

- Market Size (2026)
- USD 3.7 Bn
- Forecast (2036)
- USD 6.2 Bn
- CAGR (2026 to 2036)
- 5.3%
How big is Sports Drink Market in 2026?
Sales in the sports drink market are projected to grow at 5.3% CAGR, with the market size rising from USD 3.5 billion in 2025 to USD 3.7 billion in 2026 and reaching USD 6.2 billion by 2036.
Balancing rapid intestinal fluid uptake against the metallic astringency of concentrated sodium and potassium salts has long complicated commercial sports beverage production. Endurance runners and industrial field crews need hypotonic and isotonic fluids that restore plasma volume without causing stomach heaviness during heat exertion. In March 2025, National Institutes of Health dietary supplement guidance confirmed that balanced sodium and potassium replenishment prevents cellular cramping during prolonged sweat loss [1]. According to Future Market Insights analysis, global sports drink revenue rises from USD 3.5 billion in 2025 to USD 3.7 billion in 2026 and reaches USD 6.2 billion by 2036 at a 5.3% CAGR, adding USD 2.5 billion while Flavored / Botanical Infusion leads variety demand at 39.3%.
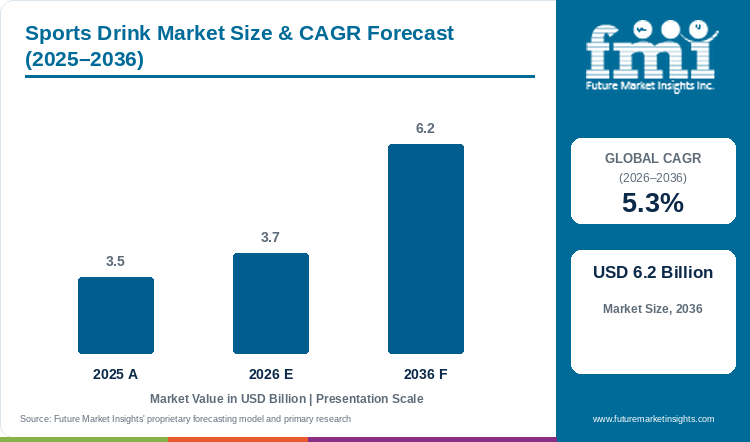
Key Market Trends & Insights
- By product variety / flavor: Flavored and botanical infusion led with a share of 39.3% in 2026, as tart citrus and berry acids mask the salty aftertaste of dissolved sodium electrolytes.
- By packaging format: Slim aluminum cans accounted for 35.2% of demand in 2026 because thin-wall metal chills rapidly in gym coolers and enters municipal recycling streams cleanly.
- By distribution channel: With a 39.8% share in 2026, supermarkets and hypermarkets led the category through refrigerated endcap displays and weekend multi-pack promotions.
Regional Highlights
- Fastest-growing evaluated country: South Korea, at 6.5% CAGR from 2026 to 2036.
- By country: Japan at 5.9%, Germany at 5.5%, the USA at 5.1%, and France at 4.7% follow, while Switzerland records the lowest evaluated CAGR at 4.2%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Sports Drink Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 3.5 billion |
| Estimated Market Size in 2026 | USD 3.7 billion |
| Projected Market Size by 2036 | USD 6.2 billion |
| CAGR, 2026 to 2036 | 5.3% |
| Added Revenue, 2026 to 2036 | USD 2.5 billion |
Tiered sugar-excise brackets in France and Germany contrast sharply with mandatory summer workplace heatstroke hydration programs across Japan and South Korea, forcing beverage brands to localize carbohydrate and sodium ratios by jurisdiction. Bottling plants in North America and Europe also navigate strict regulatory lines separating everyday thirst quenchers from liquid dietary supplements. Updated August 2025 industry guidance from the U.S. Food and Drug Administration clarified the boundary between liquid dietary supplements and conventional beverages based on container volume, osmolality, and nutrient claims [2]. Contract packers are therefore recalibrating inline blending skids with natural high-intensity sweeteners so finished drinks preserve rapid gastric emptying without incurring municipal soda tariffs.
Isotonic Formulation and Osmolality Operational Metrics
Table 2: Isotonic Formulation and Osmolality Operational Metrics for the Sports Drink Market (USD billion and operational parameters), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 3.5 | 3.7 | 6.2 |
| Commercial hydration liquid volume (billion liters) | 2.4 | 2.5 | 4.1 |
| Target osmolality range in finished beverage (mOsm/kg) | 270 to 330 | 275 to 325 | 280 to 310 |
| Sodium concentration in standard formulation (mg/100ml) | 40 to 65 | 42 to 68 | 45 to 70 |
Formulation note: Osmolality and sodium concentration ranges reflect commercial quality-control tolerances across high-speed isotonic bottling and contract canning lines.
Facility Capital Expenditure & Canning Yardstick Metrics
High-speed beverage plants rely on reverse-osmosis water polishing and automated mineral-dosing skids so batch conductivity never drifts outside isotonic specifications. Dissolving sodium citrate, potassium chloride, and magnesium salts alongside botanical extracts requires heated agitation tanks that prevent crystal precipitation during cold filling. Because grocery buyers are expanding shelf space for zero-sugar beverages, regional co-packers are installing rotary counter-pressure can fillers and inline laser seamers capable of running 1,200 slim cans per minute.
Table 3: Facility Capital Expenditure and Processing Yardstick Metrics for the Sports Drink Market (USD and units), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Operational sports drink bottling plants globally (units) | 420 | 450 | 720 |
| High-speed beverage blending skid outlay (USD million) | 1.4 to 2.2 | 1.5 to 2.4 | 2.2 to 3.4 |
| Rotary can filling and seaming line spend (USD million) | 2.8 to 4.2 | 3.0 to 4.5 | 4.2 to 6.2 |
| Osmolality and mineral density assay cost per batch (USD) | 220 to 340 | 240 to 360 | 340 to 480 |
Table 4: Facility & Operational Cost Benchmark Metrics for the Sports Drink Market (USD and percentages), mixed reporting years from 2024 to 2026
| Operational Cost Indicator | 2024 | 2025 | 2026 |
|---|---|---|---|
| Mineral electrolyte premix share of formulation cost (%) | 18.0 to 24.0 | 19.0 to 25.0 | 20.0 to 26.0 |
| Water purification and reverse osmosis outlay per ton (USD) | 14 to 22 | 15 to 24 | 16 to 25 |
| Secondary shrink-wrap multi-pack packaging cost per case (USD) | 0.32 to 0.48 | 0.34 to 0.52 | 0.36 to 0.55 |
| High-speed canning line electrical power expense per run (USD) | 180 to 250 | 190 to 265 | 200 to 280 |
Analyst Perspective
"Pairing tart botanical extracts with hypotonic mineral ratios lets beverage brands capture daily hydration occasions outside stadium sports. Co-packers still face long qualification trials to prevent acidic electrolyte brines from corroding internal aluminum can liners."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the sports drink market segmented?
The sports drink market is segmented by product variety / flavor, packaging format, distribution channel, and region. In 2026, flavored / botanical infusion is projected at 39.3%, slim aluminum cans at 35.2%, and supermarkets & hypermarkets at 39.8%.
By product variety / flavor: Flavored / Botanical Infusion, classic unflavored / traditional, and zero-sugar / sugar-free variant.
By packaging format: Slim Aluminum Cans, PET bottles, glass bottles, and aseptic paperboard cartons.
By distribution channel: Supermarkets & Hypermarkets, convenience stores & gas stations, online retail & subscription, and food service & cafes.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does Flavored / Botanical Infusion lead the product variety category?
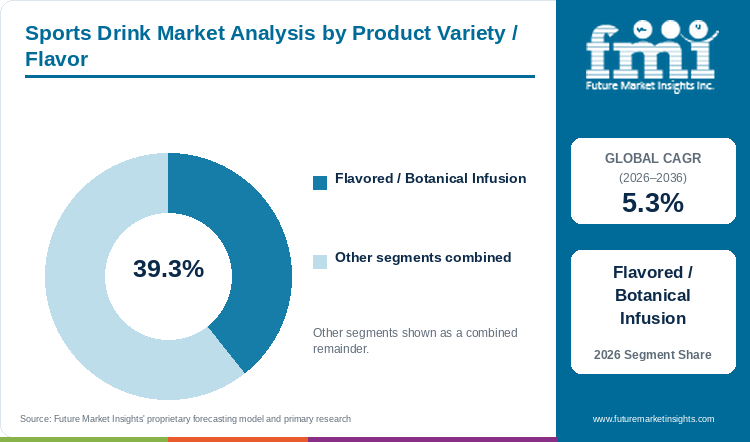
Flavored and botanical infusion is projected to account for 39.3% of product variety in 2026, supported by natural flavor masking.
Table 5: Product Variety / Flavor Share for the Sports Drink Market (percentage share), 2026
| Product Variety / Flavor | Share (2026) |
|---|---|
| Flavored / Botanical Infusion | 39.3% |
| Other Segments Combined | 60.7%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Variety / Flavor Leadership and Market Growth for the Sports Drink Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.3% |
| Leading Segment | Flavored / Botanical Infusion |
Unflavored sodium and magnesium solutions leave a sharp saline coating on the tongue that causes athletes to stop drinking before their fluid deficit is replaced. Formulators overcome this sensory barrier by dosing hibiscus, yuzu, and tart berry extracts into electrolyte hydration drinks, keeping sodium between 45 and 65 milligrams per 100 milliliters while delivering a crisp finish. Organic fruit acids stimulate salivary flow during heavy breathing, which helps marathoners and gym members drink steadily across long workouts. Beverage chemists still have to weight citrus oils with ester gums so flavor emulsions do not separate into neck rings inside clear display bottles.
- Flavored and botanical infusion accounts for 39.3% of product variety revenue in 2026, supported by natural fruit acids that neutralize mineral salt astringency.
- In October 2026, The Coca-Cola Company showcased expanded botanical and fruit-forward hydration flavors at the NACS Show to broaden convenience cooler rotation [3].
What keeps Slim Aluminum Cans ahead by packaging format?
Slim aluminum cans are estimated to capture 35.2% of packaging format demand in 2026, reflecting fast chilling and light protection.
Gym merchandising coolers and convenience store cold vaults increasingly favor 330-milliliter and 355-milliliter sleek cans because thin aluminum walls pull heat out of liquid twice as fast as thick blow-molded plastic. Double-seamed metal ends also block ultraviolet rays and oxygen ingress completely, preventing ascorbic acid and delicate berry anthocyanins from turning brown on the shelf. Co-packers are shifting high-turn hydration SKUs into recyclable aluminum cans to trim outbound truck weight and satisfy retailer circular-packaging scorecards. Because low-pH chloride brines pit bare aluminum, can suppliers must cure uniform BPA-non-intent epoxy-acrylate internal coatings prior to filling.
- Slim aluminum cans represent 35.2% of packaging format demand in 2026, reflecting rapid thermal conductivity and complete light and oxygen barrier protection.
- In June 2025, the International Council of Beverages Associations reported that lightweighted aluminum beverage cans achieved higher closed-loop recovery across metropolitan deposit systems [4].
Why do Supermarkets & Hypermarkets lead the distribution channel category?
Supermarkets and hypermarkets are anticipated to capture 39.8% of distribution channel sales in 2026, owing to multipack value pricing.
Weekly household stock-up trips for youth soccer leagues, school lunchboxes, and amateur running training keep supermarkets and hypermarkets at the center of commercial volume. National grocery chains position shrink-wrapped eight-packs and twelve-packs on pallet drops beside sports nutrition products, letting families buy isotonic bottles at a thirty-percent per-liter discount compared with gas-station singles. Endcap chiller programs tied to summer tournament broadcasts also give beverage brands immediate national trial for new zero-sugar flavors. Independent hydration brands nevertheless face steep slotting allowances and must hit weekly scan-per-store benchmarks within ninety days to avoid delisting.
- Supermarkets and hypermarkets hold 39.8% of distribution channel sales in 2026, owing to bulk multipack economics and chilled checkout placement.
- In May 2025, the British Soft Drinks Association noted that supermarket multi-pack promotions generated the largest volume share of off-premise sports hydration purchasing [5].
What are the drivers, restraints, and opportunities in the sports drink market?
Adult endurance athletics and workplace heat-safety routines elevate recurring electrolyte volume, whereas municipal sugar excise taxes and aluminum can costs compress bottling margins, and cognitive nootropic hydration blends create premium retail value.
- Driver: Growing participation in community running clubs, amateur endurance events, and occupational heat-hydration programs expands year-round electrolyte beverage consumption.
- Restraint: Municipal sugar-sweetened beverage excise taxes and synthetic food-dye compliance actions force costly recipe reformulations and batch recalls.
- Opportunity: Combining isotonic mineral electrolytes with L-theanine and plant-derived nootropics opens higher-margin daytime occasions beyond traditional stadium athletics.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Recreational half-marathons, urban cycling clubs, and occupational heat-safety rules have turned electrolyte replenishment from a weekend stadium habit into a daily weekday purchase. Construction safety managers and athletic trainers warn that drinking plain water during heavy sweating dilutes blood sodium and triggers heat exhaustion. Active commuters are therefore alternating ready-to-drink isotonic bottles with hydration supplement mixes to sustain cellular fluid balance across warm shifts. World Health Organization bulletins in September 2025 highlighted that structured physical activity and metabolic wellness programs are expanding across adult urban populations worldwide [6]. Bottlers must still balance glucose-to-sodium transport ratios so fluids cross the intestinal wall rapidly.
Risk Assessment of the Sports Drink Market: Operational and Formulation Friction
Excise taxes on sugar-sweetened beverages and state-level crackdowns on synthetic petroleum dyes are forcing legacy sports drink makers into expensive recipe overhauls. Stripping sucrose out of an isotonic formula and substituting organic stevia extracts changes liquid density, requiring food scientists to rebalance potassium and citrate salts while masking steviol bitterness. Packaging and labeling errors on synthetic colorants also expose bottlers to immediate recall costs. In October 2026, a U.S. Food and Drug Administration enforcement report documented a Class II recall of 122,000 cases of Gatorade 28-ounce bottles triggered by undeclared yellow dyes [7]. Co-packers now run optical label verification and allergen-flush cycles between every flavor changeover.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Merging hypotonic mineral hydration with nootropic amino acids such as L-theanine, citicoline, and standardized green-tea catechins is opening a profitable bridge between sports recovery and afternoon mental focus. Esports competitors, hospital shift workers, and office gym-goers increasingly reach for plant-based energy drinks and cognitive hydration cans that restore electrolytes without causing high-caffeine crash. In February 2025, PepsiCo outlined strategic beverage investments prioritizing zero-sugar functional hydration and rapid electrolyte recovery lines across North American and international markets [8]. Formulators that microencapsulate bitter nootropics so they remain optically clear in chilled cans can command thirty-percent price premiums in convenience stores.
Sports Drink Market by Country (2026 to 2036)
In the FMI report, South Korea posts the fastest expansion among the six profiled countries at a 6.5% CAGR from 2026 to 2036, whereas mature alpine demand in Switzerland progresses at 4.2% CAGR. National growth trajectories reflect how local bottlers navigate municipal sugar taxes, convenience-store cold-vault density, and public heat-stress hydration campaigns.
Table 7: Country CAGR and Primary Growth Levers for the Sports Drink Market (CAGR percentage and operational drivers), 2026 to 2036
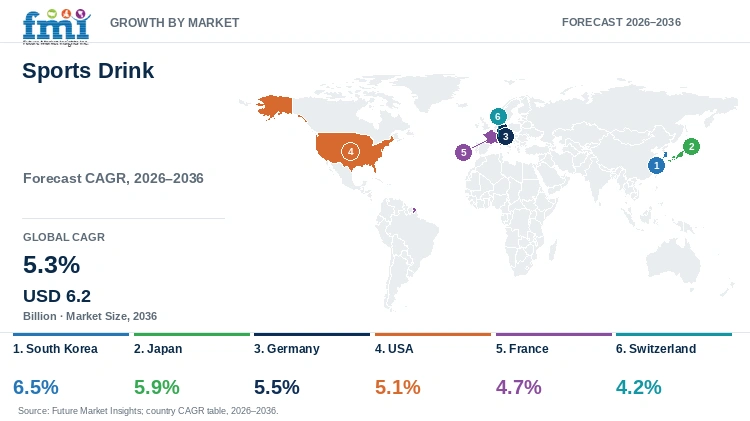
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| South Korea | 6.5% | Urban marathon club expansion and dense 24-hour convenience store chiller placement |
| Japan | 5.9% | Statutory workplace heatstroke prevention protocols and senior-friendly hypotonic drinks |
| Germany | 5.5% | Consumer migration toward bio-certified fruit spritzers and sugar-reduced isotonic blends |
| USA | 5.1% | Youth athletics volume and rapid shelf rotation into zero-sugar electrolyte cans |
| France | 4.7% | Endurance cycling culture and clean-label natural pigment formulation mandates |
| Switzerland | 4.2% | High alpine recreation spending and herbal mountain-spring isotonic positioning |
Source: Future Market Insights analysis
South Korea Sports Drink Market Outlook (2026 to 2036)
Dense 24-hour convenience store networks and evening running crews across Seoul and Busan have turned single-serve electrolyte cans into an everyday urban habit. South Korea is projected to expand at a 6.5% CAGR from 2026 to 2036, buoyed by rapid trial of zero-calorie peach and grapefruit ion drinks among young adults. Korea Food Industry Association retail tracking in October 2025 showed that domestic sales of low-sugar functional hydration beverages rose 15.0% across convenience chains [9]. Fierce cold-vault competition from ready-to-drink burdock and barley teas still limits shelf facings, so domestic bottlers co-sponsor city night marathons and bundle mobile convenience-store coupons.
Key takeaway: In South Korea, round-the-clock convenience chiller access and urban running crew sponsorships drive a 6.5% CAGR through 2036.
Japan Sports Drink Market Outlook (2026 to 2036)
Mandatory summer workplace heat-stress rules and municipal elder-care hydration alerts make ion-supply beverages a year-round staple in Japan, where the market is projected to record a 5.9% CAGR from 2026 to 2036. Rather than relying solely on school athletics, Japanese beverage makers formulate mild hypotonic liquids for outdoor construction crews and older citizens walking in humid summer weather. In August 2025, Japan's Ministry of Health, Labour and Welfare documented heightened summer heat-illness alerts that accelerated institutional procurement of oral electrolyte solutions [10]. Shrinking student cohorts cap school-club demand, prompting Otsuka and Suntory to expand household powder sachets and senior hydration jellies.
Key takeaway: In Japan, occupational heatstroke mandates and senior-friendly hypotonic jellies keep domestic demand expanding at 5.9% annually.
Germany Sports Drink Market Outlook (2026 to 2036)
German recreational cyclists and football clubs strongly favor naturally cloudy isotonic drinks and mineral-rich fruit spritzers (Apfelschorle) over neon-colored synthetic beverages, guiding the market toward a 5.5% CAGR from 2026 to 2036. German Association of the Non-Alcoholic Beverages Industry data from September 2025 showed that calorie-reduced and vitamin-fortified sports beverages recorded 9.0% annual volume growth across domestic retail channels [11]. Strict European Union health-claim rules and Germany's mandatory deposit-return system (Pfand) complicate logistics for imported bottles. Regional bottlers win supermarket contracts by certifying organic juice bases and filling standardized Pfand-compliant slim cans.
Key takeaway: In Germany, clean-label bio-isotonic fruit spritzers and Pfand-compliant reverse-vending packaging govern supermarket shelf access.
USA Sports Drink Market Outlook (2026 to 2036)
In the United States, demand for sports drinks is predicted to advance at a 5.1% CAGR through 2036 as high-school athletics, collegiate stadiums, and commercial fitness chains rotate out of high-fructose corn syrup bottles into zero-sugar cans. American shoppers increasingly scrutiny potassium-to-sodium ratios alongside natural coconut-water electrolyte blends. In January 2026, the National Institutes of Health Office of Dietary Supplements updated its clinical reference guidance on magnesium and electrolyte adequacy for physically active populations [12]. Long-haul refrigerated trucking rates and state bans on synthetic dyes still squeeze margins, leading major brands to pair localized cold-fill canning with lightweight powder sticks.
Key takeaway: In the USA, stadium and grocery conversion to dye-free, zero-sugar electrolyte cans and powder sticks underpins steady volume growth.
France Sports Drink Market Outlook (2026 to 2036)
Alpine trail running, long-distance road cycling, and regional rugby tournaments anchor French athletic hydration, with national sales forecast to rise at a 4.7% CAGR between 2026 and 2036. French endurance athletes inspect Nutri-Score badges closely and reject artificial preservatives or metallic sweetener aftertastes. French Soft Drinks Union market figures in November 2025 recorded a 10.0% retail sales increase for low-sugar isotonic and functional athletic beverages across hypermarkets [13]. Tiered national soda taxes indexed to grams of added sugar per hectoliter penalize legacy carbohydrate recipes, so domestic formulators sweeten hypotonic berry blends with beet-derived palatinose.
Key takeaway: In France, Nutri-Score visibility and tiered soda taxes push endurance hydration brands toward low-glycemic beet carbohydrates.
Switzerland Sports Drink Market Outlook (2026 to 2036)
Between 2026 and 2036, the Switzerland sports drink market is expected to progress at a 4.2% CAGR as mountaineering clubs, winter ski resorts, and corporate wellness buyers purchase alpine-positioned isotonic drinks. High disposable income allows Swiss bottlers to formulate mineral drinks using glacier spring water, edelweiss, and lemon balm extracts. Swiss Beverage Association year-end figures in December 2025 confirmed a 6.0% rise in domestic sales of vitamin-enriched and mineral isotonic beverages [14]. Elevated domestic bottling wages and a compact population limit mass-volume economies, steering local producers toward high-margin pharmacy and ski-chalet channels.
Key takeaway: In Switzerland, ski-resort and pharmacy demand for alpine herbal isotonic drinks supports premium unit margins.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the sports drink market?
PepsiCo, Inc. (Gatorade), The Coca-Cola Company (Powerade), Monster Beverage Corporation, Abbott Laboratories, BA Sports Nutrition (BodyArmor), Otsuka Pharmaceutical (Pocari Sweat), Kill Cliff, BioSteel Sports Nutrition, Roar Organic, and Suntory Beverage & Food are the notable companies in this market.
Securing refrigerated endcap space in national supermarkets requires direct-store-delivery trucking fleets and high-speed rotary canning capacity, which keeps PepsiCo and The Coca-Cola Company at the forefront of global isotonic volume. Challenger brands such as BA Sports Nutrition, BioSteel, and Roar Organic capture specialty gym and convenience cold-vault facings by formulating dye-free drinks around packaged coconut water and B-vitamin premixes. Across East Asia, Otsuka Pharmaceutical and Suntory Beverage & Food leverage clinical osmolality research and dense vending machine networks, while Abbott Laboratories supplies pharmacy-grade oral electrolyte solutions for heat-stressed workers and athletes.
- Global Isotonic & Direct-Store-Delivery Leaders: PepsiCo, Inc. (Gatorade), The Coca-Cola Company (Powerade), and Suntory Beverage & Food manage multi-continent bottling and supermarket cooler networks.
- Pharmaceutical & Clinical Hydration Specialists: Otsuka Pharmaceutical (Pocari Sweat) and Abbott Laboratories formulate precision ion-supply and rapid plasma-rehydration beverages.
- Clean-Label, Coconut-Water & Zero-Sugar Challengers: Monster Beverage Corporation, BA Sports Nutrition (BodyArmor), Kill Cliff, BioSteel Sports Nutrition, and Roar Organic target gym and convenience channels with dye-free formulas.
Competitive Benchmarking: Sports Drink Market
Table 8: Competitive Benchmarking for the Sports Drink Market (qualitative capability ratings), 2026
| Company | Isotonic Portfolio Breadth | Zero-Sugar & Clean-Label Depth | Retail & Gym Cooler Access | Geographic Reach |
|---|---|---|---|---|
| PepsiCo, Inc. (Gatorade) | High | High | High | High |
| The Coca-Cola Company (Powerade) | High | High | High | High |
| Monster Beverage Corporation | Medium | High | High | High |
| Abbott Laboratories | Medium | High | Medium | High |
| BA Sports Nutrition (BodyArmor) | High | High | High | Medium |
| Otsuka Pharmaceutical (Pocari Sweat) | High | Medium | High | High |
| Kill Cliff | Medium | High | Medium | Medium |
| BioSteel Sports Nutrition | Medium | High | Medium | Medium |
| Roar Organic | Medium | High | Medium | Medium |
| Suntory Beverage & Food | High | Medium | High | High |
Scoring basis: Companies earn a High rating in Isotonic Portfolio Breadth when they market ready-to-drink bottles, sleek cans, and powder sticks spanning hypotonic and isotonic tiers, and Medium when focused on a single format. Zero-Sugar & Clean-Label Depth is rated High where stevia, coconut water, or branched-chain amino acids anchor commercial lines without synthetic dyes. Retail & Gym Cooler Access reflects documented direct-store-delivery routes and national grocery endcap programs, while Geographic Reach distinguishes global bottling footprints from North American or regional specialists.
Key Developments in the Sports Drink Market
- In October 2026, The Coca-Cola Company unveiled new seasonal hydration and zero-sugar sports beverage extensions at the NACS Show to expand convenience store cold-vault placement [15].
- In February 2026, Otsuka Pharmaceutical commissioned its second dedicated Pocari Sweat ion-supply beverage manufacturing facility to expand aseptic bottling capacity across Asia-Pacific markets [16].
- In February 2025, PepsiCo expanded high-speed aluminum canning and zero-sugar electrolyte hydration production lines under its Gatorade portfolio to capture health-focused active consumers [17].
Key Players in the Sports Drink Market
Global Isotonic & Direct-Store-Delivery Leaders
- PepsiCo, Inc. (Gatorade)
- The Coca-Cola Company (Powerade)
- Suntory Beverage & Food
Pharmaceutical & Clinical Hydration Specialists
- Otsuka Pharmaceutical (Pocari Sweat)
- Abbott Laboratories
Clean-Label, Coconut-Water & Zero-Sugar Challengers
- Monster Beverage Corporation
- BA Sports Nutrition (BodyArmor)
- Kill Cliff
- BioSteel Sports Nutrition
- Roar Organic
Sports Drink Market - Report Scope
Table 9: Report Scope for the Sports Drink Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Variety / Flavor; Packaging Format; Distribution Channel; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial manufacturer revenue from ready-to-drink isotonic, hypotonic, and hypertonic sports beverages and electrolyte hydration drinks sold within the listed segmentation. Excludes high-caffeine energy shots, unfortified bottled water, and clinical intravenous solutions. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | South Korea, Japan, Germany, USA, France, Switzerland, and additional countries in the full report |
| Key Companies Covered | PepsiCo, Inc. (Gatorade), The Coca-Cola Company (Powerade), Monster Beverage Corporation, Abbott Laboratories, BA Sports Nutrition (BodyArmor), Otsuka Pharmaceutical (Pocari Sweat), Kill Cliff, BioSteel Sports Nutrition, Roar Organic, Suntory Beverage & Food |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Sports Drink Market - Research Methodology
Table 10: Research Methodology for the Sports Drink Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with beverage formulation scientists, bottling plant directors, sports dietitians, and supermarket category buyers across the value chain to validate osmolality standards, flavor preferences, and cooler placement trends. |
| Secondary Research | Secondary research included company annual reports, investor presentations, FDA and EFSA regulatory publications, sports medicine position stands, beverage association statistical bulletins, and publicly available trade literature. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period were developed using top-down and bottom-up models pairing commercial beverage canning and bottling output with retail scanner pricing and athletic participation trends. |
| Data Triangulation and Validation | Data is validated against macro-economic indicators, electrolyte premix shipment volumes, aluminum can consumption statistics, and historical category performance to ensure accuracy without double counting adjacent energy drink categories. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's athletic hydration econometric model, calibrating evaluated national growth rates against the 5.3% global baseline through verified fitness club memberships, endurance sports participation rates, and low-sugar electrolyte RTD shelf-space expansion. |
| Operational Benchmark Traceability | Operational benchmarks (commercial hydration liquid volume, sodium/potassium electrolyte osmolality tolerances, and high-speed rotary canning line speeds) represent modeled estimates synthesized from NIH ODS hydration data, FDA beverage guidance, WHO nutrition recommendations, and commercial sports drink brand disclosures. |
Sports Drink Market by Segments
Sports Drink Market segmented by Product Variety / Flavor:
- Flavored / Botanical Infusion
- Classic Unflavored / Traditional
- Zero-Sugar / Sugar-Free Variant
Sports Drink Market segmented by Packaging Format:
- Slim Aluminum Cans
- PET Bottles
- Glass Bottles
- Aseptic Paperboard Cartons
Sports Drink Market segmented by Distribution Channel:
- Supermarkets & Hypermarkets
- Convenience Stores & Gas Stations
- Online Retail & Subscription
- Food Service & Cafes
Sports Drink Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Western Europe
- Germany
- France
- United Kingdom
- Switzerland
- Italy
- Eastern Europe
- Poland
- Czech Republic
- East Asia
- South Korea
- Japan
- China
- South Asia and Pacific
- Australia and New Zealand
- India
- ASEAN
- Middle East and Africa
- GCC Countries
- South Africa
Research Sources and Bibliography
- [1] National Institutes of Health. (2025, March 14). Potassium and electrolyte balance in athletic fluid replacement: Health professional fact sheet. NIH Office of Dietary Supplements.
- [2] U.S. Food and Drug Administration. (2025, August 19). Guidance for industry: Distinguishing liquid dietary supplements from beverages. Center for Food Safety and Applied Nutrition.
- [3] The Coca-Cola Company. (2026, October 09). New hydration and sports beverage flavor extensions showcased at the 2026 NACS Show. Corporate Beverage Releases.
- [4] International Council of Beverages Associations. (2025, June 12). Sustainable packaging guidelines and closed-loop recycling for aluminum beverage cans. ICBA Technical Series, 15, 25-40.
- [5] British Soft Drinks Association. (2025, May 21). Functional sports hydration and off-premise supermarket multipack performance review. BSDA Annual Industry Report, 49, 12-28.
- [6] World Health Organization. (2025, September 25). Physical activity, hydration, and noncommunicable disease prevention frameworks. WHO Fact Sheets and Clinical Bulletins.
- [7] U.S. Food and Drug Administration. (2026, October 05). Class II enforcement report: Voluntary recall of 28-oz sports drink bottles over undeclared color additives. FDA Enforcement Reports.
- [8] PepsiCo, Inc. (2025, February 04). Strategic portfolio focus on zero-sugar hydration and functional electrolyte beverage platforms. PepsiCo Investor Updates.
- [9] Korea Food Industry Association. (2025, October 16). Functional beverage retail sales performance across South Korean convenience chains. KFIA Industry Reports, 18, 50-68.
- [10] Ministry of Health, Labour and Welfare. (2025, August 14). Summer heatstroke prevention survey and oral electrolyte beverage consumption statistics. MHLW Technical Bulletin, 39, 85-102.
- [11] German Association of the Non-Alcoholic Beverages Industry. (2025, September 22). Market developments in low-calorie and bio-isotonic sports drinks. WAFG Statistical Overview, 27, 44-60.
- [12] National Institutes of Health. (2026, January 06). Magnesium and dietary reference intakes for sodium and potassium in active populations. Office of Dietary Supplements Nutrient Recommendations.
- [13] French Soft Drinks Union. (2025, November 18). Boissons rafraichissantes sans alcool: Retail performance of sports hydration drinks in France. BRF Annual Report, 24, 30-48.
- [14] Swiss Beverage Association. (2025, December 09). Schweizer Getraenkeindustrie Jahresbericht: Functional and alpine isotonic beverage trends. SBA Market Intelligence, 19, 15-32.
- [15] Vending Market Watch & The Coca-Cola Company. (2026, October 09). Coca-Cola adds new flavors across sports drinks and hydration portfolios for convenience retail. Commercial Beverage Announcements.
- [16] Otsuka Pharmaceutical Co., Ltd. (2026, February 18). Commissioning of second dedicated Pocari Sweat manufacturing plant for regional aseptic supply. Otsuka Corporate Newsroom.
- [17] PepsiCo Gatorade Division. (2025, February 19). Capital expansion of high-speed aluminum canning and zero-sugar hydration blending lines. Corporate Manufacturing Releases.
- [18] BA Sports Nutrition. (2025, July 14). Rollout of BodyArmor Flash I.V. zero-sugar coconut-water electrolyte sticks and ready-to-drink bottles. BodyArmor Product Releases.
- [19] Monster Beverage Corporation. (2025, November 06). Expansion of commercial canning capacity for performance hydration and electrolyte beverage lines. Monster Corporate Filings.
- [20] Abbott Laboratories. (2026, March 24). Clinical validation and retail pharmacy expansion for adult rapid electrolyte rehydration solutions. Abbott Nutrition Releases.
- [21] Suntory Beverage & Food Limited. (2025, August 28). Reformulation of mineral hydration beverages for automated vending and cold-chain channels. Suntory Group News.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the sports drink market in 2026 and what is forecast for 2036?
- Why does flavored and botanical infusion lead the product variety category?
- What keeps slim aluminum cans ahead across the packaging format category?
- Why do supermarkets and hypermarkets command the largest distribution channel share?
- How do growth rates differ across South Korea, Japan, Germany, and the USA?
- Which notable companies supply isotonic and zero-sugar hydration beverages today?
- What regulatory and packaging cost pressures restrain sports drink bottling margins?
- What should retail and institutional buyers evaluate before qualifying a supplier?
Frequently Asked Questions
How big is the sports drink market in 2026, and what is forecast for 2036?
The global sports drink market is projected to reach USD 3.7 billion in 2026 and expand to USD 6.2 billion by 2036, supported by amateur endurance sports participation and workplace heat-hydration programs.
What is the CAGR for the sports drink market from 2026 to 2036?
As per FMI, the sports drink market is forecast to grow at a 5.3% CAGR from 2026 to 2036. Growth is supported by consumer transition toward zero-sugar electrolyte formulations and portable slim cans.
Which product variety segment leads the sports drink market in 2026?
Flavored and botanical infusion is projected to hold 39.3% of product variety demand in 2026. The segment benefits from natural citrus, berry, and herbal extracts that mask the salty taste of concentrated electrolytes.
Which packaging format holds the largest sports drink share in 2026?
Slim aluminum cans are estimated to account for 35.2% of packaging format demand in 2026. Demand is supported by rapid thermal chilling in gym coolers, light barrier protection, and curbside recyclability.
Which country has the fastest sports drink growth outlook through 2036?
FMI finds that South Korea is projected to register a 6.5% CAGR during the 2026 to 2036 assessment period. Expansion is underpinned by urban marathon clubs and dense 24-hour convenience store chiller distribution.
Who are the notable companies active in the sports drink market?
Notable market participants include PepsiCo, Inc. (Gatorade), The Coca-Cola Company (Powerade), Monster Beverage Corporation, Abbott Laboratories, BA Sports Nutrition (BodyArmor), Otsuka Pharmaceutical, Kill Cliff, BioSteel Sports Nutrition, Roar Organic, and Suntory Beverage & Food.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Variety / Flavor, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Variety / Flavor, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Variety / Flavor, 2026 to 2036
- Flavored / Botanical Infusion
- Classic Unflavored / Traditional
- Zero-Sugar / Sugar-Free Variant
- Y-o-Y Growth Trend Analysis By Product Variety / Flavor, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Variety / Flavor, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Slim Aluminum Cans
- PET Bottles
- Glass Bottles
- Aseptic Paperboard Cartons
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Convenience Stores & Gas Stations
- Online Retail & Subscription
- Food Service & Cafes
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Switzerland
- Italy
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- South Korea
- Japan
- China
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Australia and New Zealand
- India
- ASEAN
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- PepsiCo, Inc. (Gatorade)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- The Coca-Cola Company (Powerade)
- Monster Beverage Corporation
- Abbott Laboratories
- BA Sports Nutrition (BodyArmor)
- Otsuka Pharmaceutical (Pocari Sweat)
- Kill Cliff
- BioSteel Sports Nutrition
- Roar Organic
- Suntory Beverage & Food
- PepsiCo, Inc. (Gatorade)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


