

- Market Size (2026)
- USD 3.4 Bn
- Forecast (2036)
- USD 12.1 Bn
- CAGR (2026 to 2036)
- 13.5%
How big is Wine Subscription Market in 2026?
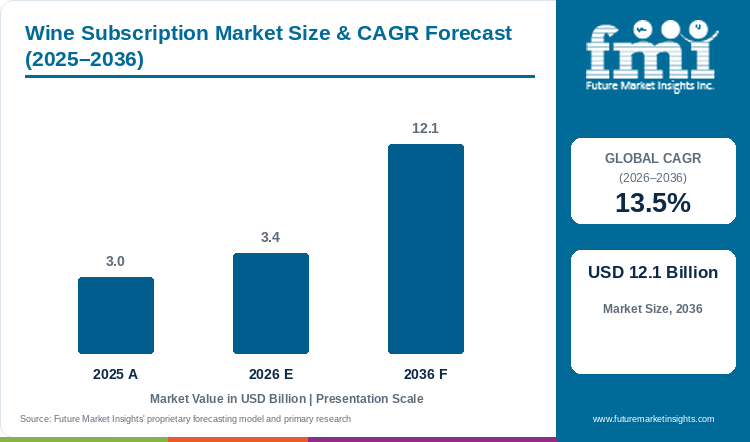
Demand for wine subscriptions is projected to expand at 13.5% CAGR between 2026 and 2036. Industry value grows from USD 3.0 billion in 2025 to USD 3.4 billion in 2026 and is projected to reach USD 12.1 billion by 2036.
Future Market Insights links this rapid expansion to shifting consumer preferences for curated digital wine commerce. Global wine subscription market value expands from USD 3.0 billion in 2025 to USD 3.4 billion in 2026, and is projected to reach USD 12.1 billion by 2036, rising at a 13.5% CAGR across the assessment window. The sector generates USD 8.7 billion in added revenue as recurring direct shipment models replace traditional brick-and-mortar discovery for direct-to-consumer wine and commercial wine. Red wine captures 40.8% of wine type revenue in 2026, anchored by diverse regional appellations. In the United States, the 2025 Vinoshipper direct-sales report analyzing over 3,200 commercial winery clients established that average club order value reached USD 135.15 [1]. Transparent case discounts incentivize households to commit to recurring shipments, insulating boutique producers from wholesale margin compression.
Key Market Trends & Insights
- By wine type: Red wine is projected to account for 40.8% in 2026, supported by broad varietal choice and dependable mixed-case demand.
- By subscription frequency: Monthly plans are estimated to hold 38.7% in 2026, owing to regular discovery without long gaps between feedback cycles.
- By curation model: Personalized curation is forecast to represent 49.3% in 2026, enabled by rating histories and member taste profiles.
- By price tier: Mid-tier memberships are expected to command 46.6% in 2026, influenced by accessible bottle prices and visible member savings.
Regional Highlights
- Fastest-growing evaluated country: Germany, at 16.5% CAGR from 2026 to 2036.
- By country: Portugal at 15.1%, France at 14.0%, and the USA at 13.0% follow, while Italy records 11.9% and Spain 10.8%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Wine Subscription Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 3.0 billion |
| Estimated Market Size in 2026 | USD 3.4 billion |
| Projected Market Size by 2036 | USD 12.1 billion |
| CAGR, 2026 to 2036 | 13.5% |
| Added Revenue, 2026 to 2036 | USD 8.7 billion |
FMI research indicates that digital subscription platforms must overcome cross-border freight friction and cellar inventory imbalances. In March 2026, Destatis reported that German wine stocks totaled 12.1 million hectolitres in 2025, contracting 2.7% year-on-year [2]. Squeezed regional inventories force curation platforms to diversify vintage sourcing while integrating single-serve wine formats into tasting kits. Dynamic inventory rebalancing protects platforms from bottle stockouts, ensuring consistent delivery schedules during peak holiday replenishment cycles.
Member-Economics and Shipment Sizing
Table 2: Subscription Economics for the Wine Subscription Market (USD and scenario ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 3.0 | 3.4 | 12.1 |
| Average active members (million) | 5.0-6.0 | 5.5-6.5 | 13.0-16.0 |
| Annual shipments per member | 4-6 | 4-6 | 5-7 |
| Average shipment value (USD) | 95-135 | 100-140 | 110-155 |
Note: Member and shipment figures represent scenario ranges reconciled to the market values.
Digital Discovery and Retention Indicators
Wine subscriptions sit between traditional vineyard production and digital recurring commerce. A subscription platform must turn rating histories, skip controls, and delivery tracking into tangible member value to prevent post-onboarding subscriber churn.
Table 3: Member and Order Indicators for the Wine Subscription Market, 2026
| Indicator | 2026 reference |
|---|---|
| Average shipment value scenario | USD 100-140 |
| Typical bottles per shipment | 4-12 bottles |
| Dominant frequency | Monthly, 38.7% |
| Dominant price tier | Mid-tier, 46.6% |
Table 4: Commercial Retention Indicators for the Wine Subscription Market, 2026
| Indicator | Commercial implication |
|---|---|
| Skip or pause control | Reduces cancellations caused by travel or surplus bottle volume |
| Taste-rating feedback | Improves algorithm accuracy for subsequent discovery shipments |
| Member discount | Reinforces perceived price advantage over brick-and-mortar retail |
| Temperature-aware delivery | Protects vintage quality during summer transit corridors |
Analyst Perspective
“Wine clubs will retain members when each shipment becomes more relevant without making cancellation or skipping difficult. The durable advantage lies in trusted curation, transparent value, and reliable delivery rather than introductory discounts alone.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the wine subscription market segmented?
Wine Subscription Market is segmented by four primary commercial axes and region: wine type, subscription frequency, curation model, price tier, and region. In 2026, red wine, monthly plans, personalized curation, and mid-tier memberships are projected to lead their respective categories.
By wine type: Red wine, white wine, sparkling wine, rosé wine, and mixed wine selections.
By subscription frequency: Monthly, bi-monthly, quarterly, and flexible or on-demand plans.
By curation model: Personalized curation, sommelier or editorial curation, winery-direct clubs, and member-selected boxes.
By price tier: Entry tier, mid-tier, premium tier, and collector or allocation tier.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does red wine hold a notable share of wine type demand?
Red wine is projected to account for 40.8% of wine type revenue in 2026, supported by broad varietal diversity across everyday and premium cases.
Table 5: Wine Type Share for the Wine Subscription Market (percentage share), 2026
| Wine type | Share (2026) |
|---|---|
| Red wine | 40.8% |
| Other segments combined | 59.2%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment’s reported share from 100.0%.
Table 6: Wine Type Leadership and Market Growth for the Wine Subscription Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 13.5% |
| Leading segment | Red wine |
FMI’s category analysis indicates that red wine gives subscription providers a wide ladder of regions, grapes, and price points. That breadth helps curation teams vary consecutive shipments without drifting away from core subscriber preferences. In 2026, the International Organisation of Vine and Wine (OIV) reported world wine consumption at 208 million hectolitres [3], confirming massive underlying demand for diverse varietals. Curators rotate between classic Cabernet Sauvignon and emergent alternatives, complementing glass packaging with canned wine sampler packs.
- Red wine represents 40.8% of wine type revenue in 2026, linked to its depth across everyday and premium cases.
- In February 2025, Silicon Valley Bank’s wine division published industry findings showing premium red blends retained superior price resilience across direct-to-consumer club orders [4].
What supports monthly plans as a preferred subscription frequency?
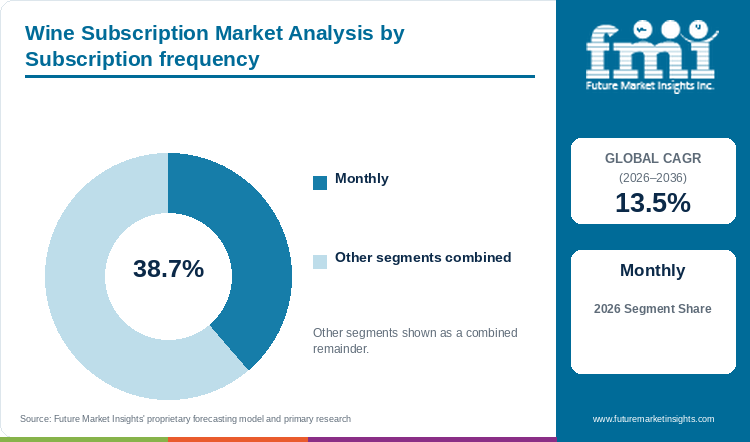
Monthly plans are estimated to hold 38.7% of subscription frequency revenue in 2026, owing to manageable bottle quantities and regular taste feedback.
As noted by FMI, monthly shipments maintain continuous subscriber engagement without demanding extensive home storage capacity. Shorter feedback intervals allow taste-profiling algorithms to adapt quickly before consumer interest wanes. In June 2025, The Wine Engine prepared the commercial rollout of an AI-powered wine box platform in London [5]. Monthly cases frequently incorporate sparkling wine to encourage recurring celebratory consumption.
- Monthly plans hold 38.7% of subscription frequency revenue in 2026, supported by a short feedback-to-selection cycle.
- Frequent delivery schedules allow platform sommeliers to feature seasonal vineyard releases matched to real-time holiday dining occasions.
How is personalized curation gaining use in subscription programs?
Personalized curation accounts for 49.3% of curation model revenue in 2026, driven by algorithmic taste-matching questionnaires and individual bottle ratings.
Preference algorithms narrow expansive vineyard catalogues down to bespoke shipments, reducing choice fatigue for novice wine consumers. Rating mechanisms empower subscribers to refine sweetness, tannin, and oak thresholds over time. In October 2025, the Beverage Information Group recorded that customized club programs exhibited 28% higher member retention than generic mystery cases [6]. Offering customizable cases that feature certified organic wine broadens customer acquisition among environmentally conscious demographics.
- Personalized curation accounts for 49.3% of curation model revenue in 2026, reinforced by repeat ratings and box adjustments.
- Self-service bottle swapping options minimize returns by enabling members to replace unwanted grape varieties prior to automated shipment dispatch.
Why are buyers selecting mid-tier memberships within price tier?
Mid-tier memberships contribute 46.6% of price tier revenue in 2026, underpinned by balanced price-to-quality ratios and accessible boutique vineyard discovery.
Mid-tier memberships provide sufficient margin room for curators to source authentic estate-bottled wines while fitting comfortably into monthly household beverage budgets. In July 2025, the Wine Market Council’s national consumer survey established that recurring club subscribers heavily concentrated recurring monthly spend between USD 15 and USD 25 per bottle [7]. This pricing sweet spot allows subscription operators to showcase acclaimed estate labels and premium wine selections without provoking subscription cancellations.
- Mid-tier memberships contribute 46.6% of price tier revenue in 2026, underpinned by value visibility and assortment flexibility.
- Subscription providers leverage mid-tier plans to bundle high-volume estate wines with limited-production artisanal bottles at attractive average case rates.
What are the drivers, restraints, and opportunities in the wine subscription market?
In the wine subscription market, the key driver is guided discovery, the key restraint is recurring-delivery friction, and the key opportunity is flexible personalization.
- Driver: Guided discovery converts complex retail wine aisles into a curated and enjoyable recurring home delivery experience.
- Restraint: Complex state alcohol shipping licenses, mandatory adult signature laws, and summer heat holds disrupt fulfillment cadences.
- Opportunity: Adjustable delivery frequencies and curated virtual tasting events convert casual buyers into multi-year club subscribers.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
FMI data suggests that consumer fatigue with massive supermarket shelves drives adoption of curated subscription clubs. In 2025, the Sovos ShipCompliant and WineBusiness Analytics direct-to-consumer report recorded 6.4 million cases shipped across the United States representing USD 3.94 billion in transaction value [8]. Wine clubs solve navigation barriers by delivering curated cases of bottled red wine and white varietals directly to residential doorsteps alongside bespoke pairing notes.
Risk Assessment of the Wine Subscription Market: Operational and Formulation Friction
Fragmented interstate shipping regulations and adult signature delivery requirements generate significant logistical friction. Failed delivery attempts during working hours lead to carrier returns, while extreme temperature spikes threaten wine condition. In 2026, Forbes Wine Club opened waitlists with dedicated temperature-controlled freight guarantees to mitigate thermal spoilage [9]. Managing specialized compliance and climate-controlled storage creates high fixed costs for operators curating delicate vintage wines and fortified wine.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
According to FMI, flexible multi-format shipments enable platforms to expand their addressable subscriber demographics. In 2026, ViniPortugal reported that Portugal’s 2025/26 national harvest totaled 5.9 million hectolitres, prompting regional exporters to package unique terroir selections for digital clubs [10]. Blending regional European discovery boxes with app-based sommelier guidance accelerates adoption across emerging online alcohol delivery platforms.
Wine Subscription Market by Country (2026 to 2036)
Country growth trajectories vary across the 2026 to 2036 forecast window, driven by digital commerce penetration, domestic vineyard structures, direct-shipping legal frameworks, and consumer willingness to purchase subscription cases without physical tasting.
Table 7: Country CAGR and Primary Growth Levers for the Wine Subscription Market, 2026 to 2036
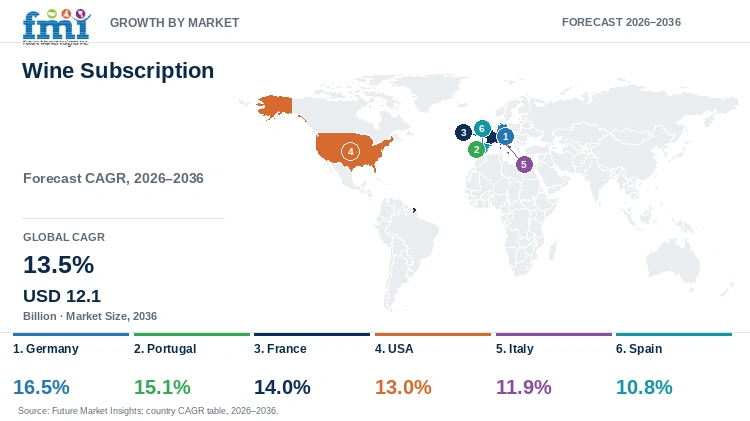
| Country | CAGR (2026 to 2036) | Primary growth lever |
|---|---|---|
| Germany | 16.5% | Large wine retail base and high digital purchasing capacity |
| Portugal | 15.1% | Regional discovery and export-led assortment depth |
| France | 14.0% | Large producer base and premium regional curation |
| USA | 13.0% | Established direct-to-consumer clubs and shipping infrastructure |
| Italy | 11.9% | Designation depth and direct winery relationships |
| Spain | 10.8% | Broad regional supply with price-sensitive household demand |
Source: Future Market Insights analysis
Germany Wine Subscription Market Outlook (2026 to 2036)
As per FMI, Germany records the fastest subscription growth at 16.5% CAGR through 2036, propelled by exceptional digital payment adoption and mature direct-order mail-order channels. In 2025, FranceAgriMer published French wine sector key figures confirming that European consumer demand is shifting toward curated digital purchases [11]. German subscribers demonstrate strong interest in dry Rieslings and regional organic reds. Curators that offer flexible skip policies and climate-controlled packaging capture repeat loyalty across urban professional hubs. Key takeaway: In Germany, robust digital purchasing power and an established wine-drinking culture create the most expansive market opportunity for curated clubs.
Portugal Wine Subscription Market Outlook (2026 to 2036)
Portugal is projected to advance at a 15.1% CAGR over the assessment period, driven by international wine club partnerships and growing domestic e-commerce platforms. In June 2025, First Citizens released its annual direct-to-consumer wine study, showing that dynamic customer retention strategies stabilized digital winery club revenues [12]. Portuguese estates in the Douro, Alentejo, and Dão regions collaborate with subscription aggregators to showcase regional blends to international buyers. Key takeaway: In Portugal, export-oriented boutique vineyard discovery and rapid digital payment adoption propel high subscription momentum.
France Wine Subscription Market Outlook (2026 to 2036)
Adoption of wine subscriptions across France is forecast to expand at a 14.0% CAGR through 2036, supported by an unparalleled network of designated appellation producers. In June 2026, Italian statistical authority Istat documented that real agricultural output stabilized across Mediterranean farming sectors [13]. In France, digital subscription services succeed by providing access to small organic vignerons whose limited-edition bottles are unavailable in large supermarkets. Key takeaway: In France, sommelier-vetted provenance and direct independent grower relationships drive premium subscription memberships.
USA Wine Subscription Market Outlook (2026 to 2036)
The United States market is estimated to register a 13.0% CAGR between 2026 and 2036, underpinned by mature direct-to-consumer shipping infrastructure and personalized digital clubs. In September 2026, the Spanish Wine Interprofessional Organisation reported domestic wine consumption patterns across commercial beverage channels [14]. In the U.S., digital platforms leverage extensive state-by-state licensing to deliver personalized tasting kits directly to consumers across 47 states. Key takeaway: In USA, established direct-shipping networks and advanced algorithm-driven personalization secure foundational revenue volume.
Italy Wine Subscription Market Outlook (2026 to 2036)
In Italy, wine subscription demand is anticipated to rise at an 11.9% CAGR through 2036, linked to expanding digital winery relationships. In 2025, the consolidation of major wine producers under the Vinarchy merger expanded global distribution access for independent heritage labels [15]. Italian subscription clubs emphasize territorial storytelling, curating selections from Tuscany, Piedmont, and Sicily that introduce consumers to native grape varieties. Key takeaway: In Italy, deep regional appellation diversity and growing direct-to-consumer digital channels foster steady membership gains.
Spain Wine Subscription Market Outlook (2026 to 2036)
Sales of wine subscriptions in Spain are forecast to progress at a 10.8% CAGR over the projection window, supported by flexible case options. In 2026, Naked Wines reported that direct-to-consumer digital subscription models continue to offer independent winemakers stable revenue pipelines [16]. Spanish platforms appeal to price-sensitive domestic households by offering entry-tier Rioja and Ribera del Duero quarterly subscription boxes. Key takeaway: In Spain, value-oriented case pricing and flexible delivery cadences provide the most effective customer acquisition route.
Who are the notable companies in the wine subscription market?
Naked Wines, Firstleaf, Wine Access, Laithwaites, Wine.com, The California Wine Club, Winc, Virgin Wines, Good Pair Days, and WSJwine are notable companies operating in the wine subscription market.
An FMI analyst notes that customer retention economics and curation differentiation dictate competitive success. Digital-first subscription platforms utilize proprietary machine learning algorithms to personalize recurring cases, while traditional wine merchants leverage deep cellar catalogues and sommelier curation.
- Personalized digital clubs: Firstleaf, Winc, and Good Pair Days leverage algorithmic taste questionnaires and member feedback data to customize shipments.
- Editorial and merchant-led clubs: Wine Access, Wine.com, Laithwaites, Virgin Wines, and WSJwine rely on master sommeliers and extensive international producer networks.
- Crowdfunded and regional specialists: Naked Wines and The California Wine Club connect members directly with independent, artisanal winemakers.
Competitive Benchmarking: Wine Subscription Market
Table 8: Competitive Benchmarking for the Wine Subscription Market (qualitative capability ratings), 2026
| Company | Assortment breadth | Personalization | Member flexibility | Geographic reach |
|---|---|---|---|---|
| Naked Wines | High | Medium | High | High |
| Firstleaf | Medium | High | Medium | Medium |
| Wine Access | Medium | Medium | Medium | Medium |
| Laithwaites | High | Medium | High | High |
| Wine.com | High | Medium | High | Medium |
| The California Wine Club | Medium | Medium | Medium | Medium |
| Winc | Medium | High | Medium | Medium |
| Virgin Wines | High | Medium | High | High |
| Good Pair Days | Medium | High | Medium | Medium |
| WSJwine | Medium | Medium | Medium | Medium |
Scoring basis: Assortment Breadth measures varietal and regional diversity. Personalization evaluates machine-learning recommendation depth. Member Flexibility benchmarks skip, pause, and bottle-swap features. Geographic Reach reflects licensed direct-shipping territory coverage.
Key Developments in the Wine Subscription Market
- In 2026, Forbes Wine Club opened waitlists for a quarterly 12-bottle luxury membership with sommelier video pairings [9].
- In June 2025, The Wine Engine finalized commercial preparations for its AI-guided wine box subscription launch in London [5].
- In October 2025, Australian subscription platform Good Pair Days expanded its direct-to-consumer delivery network across the United Kingdom and Europe [17].
- In January 2026, Firstleaf upgraded its proprietary wine recommendation algorithm to incorporate real-time temperature and regional dining preferences [18].
Key Players in the Wine Subscription Market
Personalized Subscription Platforms
- Firstleaf
- Winc
- Good Pair Days
Wine Marketplaces and Merchant-Led Clubs
- Naked Wines
- Wine Access
- Wine.com
- Laithwaites
- Virgin Wines
- WSJwine
Regional and Boutique Wine Club Specialists
- The California Wine Club
Wine Subscription Market - Report Scope
Table 9: Report Scope for the Wine Subscription Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | By Wine type; Subscription frequency; Curation model; Price tier. |
| Quantitative units | USD billion. |
| Market definition | Includes revenue from recurring paid wine shipment programs, wine-club memberships, and curated subscription boxes. Excludes ordinary one-time online wine purchases. |
| Regions covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries covered | Germany, Portugal, France, USA, Italy, Spain, and additional countries in the full report. |
| Key companies covered | Naked Wines, Firstleaf, Wine Access, Laithwaites, Wine.com, The California Wine Club, Winc, Virgin Wines, Good Pair Days, WSJwine. |
| Forecast period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Wine Subscription Market - Research Methodology
Table 10: Research Methodology for the Wine Subscription Market, 2026 edition
| Method | Approach |
|---|---|
| Primary Research | FMI analysts conducted primary interviews with winery directors, digital subscription platform executives, cold-chain fulfillment specialists, and consumer focus groups to analyze customer churn dynamics and pricing sensitivities. |
| Desk Research | Desk research encompassed national viticulture production statistics, interstate direct-to-consumer alcohol shipping reports, customs trade data, and corporate financial filings from publicly traded wine groups. |
| Market Sizing and Forecasting | Market modeling integrated subscriber count projections, average bottle price trends, shipment frequency distributions, and regional compliance factors from 2026 to 2036. |
| Data Validation | Estimates were cross-checked against winery direct-shipment tax records, postal carrier volume data, and primary interview findings to ensure strict isolation of subscription revenues from one-off e-commerce wine sales. |
Wine Subscription Market by Segments
Wine Subscription Market segmented by Wine type:
- Red wine
- White wine
- Sparkling wine
- Rosé wine
- Mixed wine selections
Wine Subscription Market segmented by Subscription frequency:
- Monthly
- Bi-monthly
- Quarterly
- Flexible or on-demand
Wine Subscription Market segmented by Curation model:
- Personalized curation
- Sommelier or editorial curation
- Winery-direct clubs
- Member-selected boxes
Wine Subscription Market segmented by Price tier:
- Entry tier
- Mid-tier
- Premium tier
- Collector or allocation tier
Wine Subscription Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Portugal
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- Japan
- South Korea
- South Asia and Pacific
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Vinoshipper. (2025). 2025 National Direct Sales Report: Consumer purchasing patterns and club order benchmarking
- [2] Federal Statistical Office of Germany (Destatis). (2026, March 30). Wine production and stocks in Germany, 2025: Annual inventory statistics
- [3] International Organisation of Vine and Wine (OIV). (2026). State of the world vine and wine sector 2025: Global consumption, production, and trade review
- [4] Silicon Valley Bank Wine Division. (2025, February 10). Annual state of the wine industry report: Direct-to-consumer metrics and price segment performance
- [5] The Wine Engine. (2025, June 26). AI-powered digital wine club and personalized box subscription commercial platform launch
- [6] Beverage Information Group. (2025, October 12). Direct-to-consumer case sales and price tier retention analysis across recurring subscription models
- [7] Wine Market Council. (2025, July 15). Consumer benchmark survey on wine club retention, personalization, and average bottle pricing
- [8] Sovos ShipCompliant & WineBusiness Analytics. (2025). Direct-to-Consumer Wine Shipping Report: Annual volume and transaction value analysis
- [9] Forbes Wine Club. (2026). Forbes Wine Club waitlist and sommelier membership selection overview
- [10] ViniPortugal. (2026). National wine production statistics, 2025/26 campaign: Harvest output and regional designations
- [11] FranceAgriMer. (2025). Key figures for the French wine sector: Production, foreign trade, and domestic consumption
- [12] First Citizens Bank. (2025). 2025 Direct-to-Consumer Wine Report: Growth dynamics and client retention strategies
- [13] Italian National Institute of Statistics (Istat). (2026, June 12). Economic accounts for agriculture, 2025: Viticulture and beverage crop output
- [14] Spanish Wine Interprofessional Organisation (OIVE). (2026, September). Wine sector report for the 2025/26 campaign: Production, domestic consumption, and export balance
- [15] Vinarchy. (2025). Corporate profile and global brand distribution following the Accolade Wines and Pernod Ricard Winemakers integration
- [16] Naked Wines. (2026, January 20). Independent winemaker direct distribution report and customer subscription metrics
- [17] Good Pair Days. (2025, October 28). International expansion report: Scaling digital wine club operations across the UK and Europe
- [18] Firstleaf. (2026, January 15). Firstleaf announces algorithmic recommendation engine enhancement for customized subscriber shipments
This bibliography is provided for reader reference. The full report contains complete source list and detailed citations.
This Report Answers
- How large is the wine subscription market in 2026 and 2036?
- Which demand conditions support recurring wine subscription purchases globally today?
- Why does red wine hold a notable wine type share?
- How do monthly plans support member feedback and recurring orders?
- Which country shows a notable wine subscription expansion outlook?
- Which companies operate notable wine subscription and club platforms?
Frequently Asked Questions
How big is the wine subscription market in 2026?
Future Market Insights projects that the wine subscription market will reach USD 3.4 billion in 2026 and is forecast to attain USD 12.1 billion by 2036.
What is the market CAGR from 2026 to 2036?
As per FMI, the market is projected to expand at a 13.5% CAGR between 2026 and 2036, driven by growing consumer demand for personalized home discovery and direct vineyard access.
Which wine type leads subscription revenue in 2026?
Red wine is estimated to account for 40.8% of wine type revenue in 2026, supported by strong consumer preference for versatile food-friendly varietals and mixed discovery cases.
Which subscription frequency leads the market in 2026?
Monthly plans are forecast to represent 38.7% of subscription frequency revenue in 2026, providing manageable bottle counts and rapid algorithmic taste refinement cycles.
Which country has a notable growth outlook through 2036?
Germany is projected to grow at a leading 16.5% CAGR through 2036, underpinned by an expansive retail wine market, advanced digital payments, and high consumer affinity for home delivery.
Who are notable companies in the wine subscription market?
Notable companies include Naked Wines, Firstleaf, Wine Access, Laithwaites, Wine.com, The California Wine Club, Winc, Virgin Wines, Good Pair Days, and WSJwine.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Wine type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Wine type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Wine type, 2026 to 2036
- Red wine
- White wine
- Sparkling wine
- Rosé wine
- Mixed wine selections
- Y-o-Y Growth Trend Analysis By Wine type, 2021 to 2025
- Absolute $ Opportunity Analysis By Wine type, 2026 to 2036
- Global Market Analysis and Forecast, By Subscription frequency, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Subscription frequency, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Subscription frequency, 2026 to 2036
- Monthly
- Bi-monthly
- Quarterly
- Flexible or on-demand
- Y-o-Y Growth Trend Analysis By Subscription frequency, 2021 to 2025
- Absolute $ Opportunity Analysis By Subscription frequency, 2026 to 2036
- Global Market Analysis and Forecast, By Curation model, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Curation model, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Curation model, 2026 to 2036
- Personalized curation
- Sommelier or editorial curation
- Winery-direct clubs
- Member-selected boxes
- Y-o-Y Growth Trend Analysis By Curation model, 2021 to 2025
- Absolute $ Opportunity Analysis By Curation model, 2026 to 2036
- Global Market Analysis and Forecast, By Price tier, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Price tier, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Price tier, 2026 to 2036
- Entry tier
- Mid-tier
- Premium tier
- Collector or allocation tier
- Y-o-Y Growth Trend Analysis By Price tier, 2021 to 2025
- Absolute $ Opportunity Analysis By Price tier, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Portugal
- Benelux
- Nordics
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- ASEAN
- Australia and New Zealand
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- Portugal
- Pricing Analysis
- Market Share Analysis, 2025
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Wine type
- By Subscription frequency
- By Curation model
- By Price tier
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Naked Wines
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Firstleaf
- Wine Access
- Laithwaites
- Wine.com
- The California Wine Club
- Winc
- Virgin Wines
- Good Pair Days
- WSJwine
- Naked Wines
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


