
- Market Size (2026)
- USD 167.3 Mn
- Forecast (2036)
- USD 283.1 Mn
- CAGR (2026 to 2036)
- 5.4%
How big is Automated CPR Device Market in 2026?
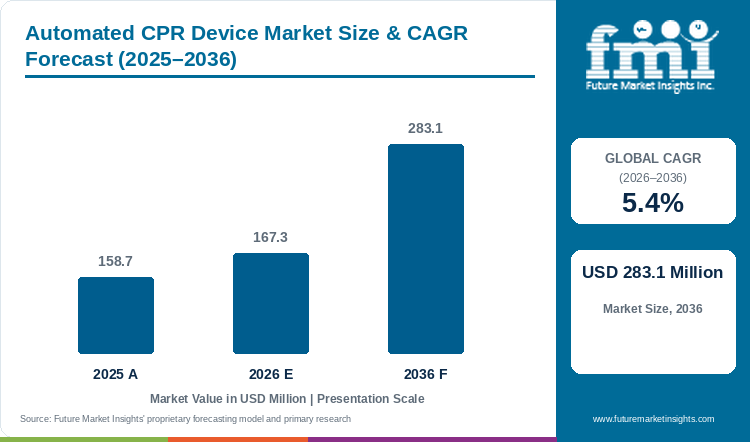
Demand is projected to expand at 5.4% CAGR from 2026 to 2036. Market value rises from USD 158.7 million in 2025 to USD 167.27 million in 2026 and USD 283.11 million by 2036.
Purchasing is concentrated on clinical settings in which a trained team has a defined reason to use mechanical chest compression, including selected transport or procedural situations. The AHA does not recommend routine mechanical-device use for adults in cardiac arrest, while UK guidance describes consideration when effective manual compression is impractical or compromises provider safety. [1][2] These limits make team preparation, fitting and service support commercially important alongside the compression mechanism. Japan's agency survey documents a substantial installed base among participating emergency organisations, creating a practical context for training and fleet support. [3] Through 2036, suppliers are likely to compete by helping eligible services deploy and maintain equipment reliably, with demand shaped by the actual protocol and operating environment. Device availability alone therefore provides a partial view of the work involved in a functioning resuscitation service.
Key Market Trends & Insights
- Selected difficult or unsafe manual-compression settings create an operational requirement.
- The absence of a routine-use recommendation limits universal adoption claims.
- Fleet support can address a defined gap between ownership and deployable equipment.
Regional Highlights
- Chinese hospital programmes considering mechanical compression during a complex resuscitation procedure need to connect the device with patient access, team responsibilities and the intended clinical protocol (FMI outlook: 8.5% CAGR, 2026 to 2036).
- UK guidance connects mechanical chest compression with situations in which high-quality manual compressions are impractical or compromise provider safety, making the intended operating environment important to procurement (FMI outlook: 5.8% CAGR, 2026 to 2036).
- Japan's national survey provides a detailed view of mechanical-compression equipment within participating emergency organisations (FMI outlook: 5.4% CAGR, 2026 to 2036).
Market Size & Forecast
Table 1: Market Size and Forecast for Automated CPR Device Market (USD million and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 market value | USD 158.7 million |
| 2026 market value | USD 167.27 million |
| 2036 market value | USD 283.11 million |
| CAGR 2026 to 2036 | 5.4% |
| Revenue increase 2026 to 2036 | USD 115.84 million |
| Market expansion 2026 to 2036 | 1.69 times |
The market covers mechanical or automated chest-compression devices and their deployment. AEDs and manual CPR training are excluded; ECMO equipment is outside the scope unless compression equipment is separately identified.
Automated external defibrillators serve a separate resuscitation function within the emergency equipment available to a prepared response team.
Clinical use boundaries alongside the installed base
Mechanical compression equipment enters a purchasing decision through the service's intended clinical protocol and deployment resources. US and UK guidance make selected use and trained fitting consequential, while Japan's agency survey describes an installed fleet with differing levels of team coverage. These conditions give maintenance, training and continuing readiness a practical role alongside the initial equipment purchase. [1][2][3]
Table 2: Industry evidence relevant to the automated cpr device market
| Indicator | Data point or observation | Market relevance | Source |
|---|---|---|---|
| Clinical guidance | AHA does not recommend routine adult mechanical CPR use | Selected-use protocols define the purchasing case | [1] |
| Deployment | UK guidance emphasises trained teams and minimal interruption | Fitting capability matters alongside equipment | [2] |
| Installed base | 650 of 695 consenting Japanese agencies owned devices | Ownership and team coverage create different support needs | [3] |
Analyst Perspective
"Mechanical compression equipment belongs within a defined selected-use protocol and a prepared team. Buyers need to assess fitting, patient access and continuing readiness together, because the purchasing decision includes training and fleet support as well as the device, while routine use remains constrained by clinical guidance."
- Anurag Sharma, Principal Consultant for Healthcare, FMI
How is the Automated CPR Device Market segmented?
The market is segmented by Product, Modality, End User, and Region.
The market is segmented by Product, Modality and End User. Product types distinguish piston-based and load-distributing-band devices, modality identifies battery-driven and electrically driven systems, and end users include hospital departments, emergency medical services and other specified care settings. Clinical use remains governed by the intended setting, relevant protocol and the trained team's ability to deploy the device appropriately.
What sustains the large product share of piston-based devices?
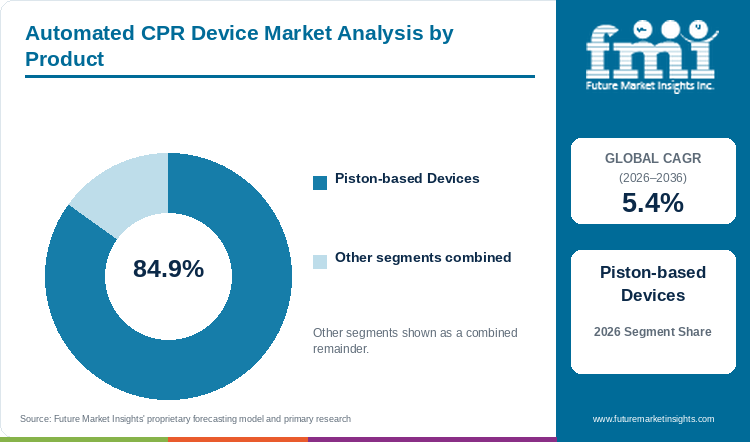
Table 3: Product Share for Automated CPR Device Market (percentage share), 2026
| Product | Estimated share (2026) |
|---|---|
| Piston-based Devices | 84.9% |
| Load-distributing Band-based Devices | 15.1% |
| Total | 100.0% |
Table 4: Segment Position and Market Growth for Automated CPR Device Market, 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.4% |
| Profiled product segment | Piston-based Devices |
Piston-based devices provide a defined mechanical compression arrangement that emergency services can evaluate within their selected-use protocols, making deployment, positioning and continuing service central to the purchasing decision. A provider needs to understand how the team fits the equipment and maintains compression continuity during that process, alongside the practical requirements for batteries, accessories and maintenance. UK guidance emphasises trained teams and minimal interruption when a mechanical device is used in an appropriate setting. [2] The estimated product share reflects the established position of this mechanism within the product mix. Suppliers can support that position through dependable equipment and training arrangements, while the clinical protocol determines when mechanical compression is appropriate.
The Piston-based Devices segment is projected to account for 84.9% of product demand in 2026.
- Piston-based Devices: 84.9% of product demand (2026 estimate), reflecting their established position within the mechanical-compression equipment mix.
- Deployment needs a trained team and attention to compression interruption, with the intended setting guiding the equipment's clinical role. [2]
Why do emergency medical services form a substantial purchasing channel?
Table 5: End User Share for Automated CPR Device Market (percentage share), 2026
| End User | Estimated share (2026) |
|---|---|
| Emergency Medical Services | 34.4% |
| Other end users | 65.6% |
| Total | 100.0% |
Emergency medical services need equipment that can be deployed within the practical constraints of transport, staffing and patient access, giving mechanical-compression devices a defined role in selected situations. The purchase includes the team's preparation and fleet support as well as the compression system, because equipment needs to remain ready for the protocol under which it is used. Japan's survey of participating fire agencies documents ownership and differing coverage across ambulance teams, illustrating the operational decisions behind this channel. [3] The estimated share reflects these emergency-service requirements, with procurement linked to actual deployment plans and maintenance capacity. Suppliers need to explain how the device and its support arrangements fit the service's operating environment.
The Emergency Medical Services segment is projected to account for 34.4% of end user demand in 2026.
- Emergency Medical Services: 34.4% of end-user demand (2026 estimate), supported by selected-use requirements within ambulance and field-response services.
- Agency ownership and team coverage describe different stages of deployment, making training and fleet readiness important to the purchasing arrangement. [3]
- Patient monitoring systems provide clinical information used by trained teams within the broader resuscitation and continuing-care environment.
What are the drivers, restraints, and opportunities in the Automated CPR Device Market?
Mechanical compression is purchased for a defined role within a trained team's resuscitation workflow. That role creates equipment demand in selected operating situations, while clinical guidance limits routine use and makes careful deployment important. Manufacturers can compete through dependable readiness, maintenance and training, with the service's actual protocol determining how the device contributes to its emergency or procedural work.
Driver
Selected emergency and procedural settings need a workable way to maintain compression when effective manual delivery is difficult or unsafe, creating a defined equipment requirement for prepared teams. UK guidance places the device within this practical context, making training and fitting part of the commercial proposition. [2] Emergency fleets also need dependable equipment availability and support across the teams designated to use it.
Restraint
Routine mechanical CPR device use is not recommended for adults in cardiac arrest under AHA guidance, limiting an unrestricted adoption argument. [1] Services therefore need to identify the intended selected-use setting and prepare a trained team, while deployment must fit the existing resuscitation workflow. These requirements can constrain purchases and make ongoing training and maintenance important alongside equipment availability.
Opportunity
Installed emergency fleets create opportunities for replacement, maintenance and training that keep equipment ready across teams and locations. Japan's agency survey documents differing levels of ambulance-team coverage among device owners, identifying an operational setting for this continuing support. [3] Suppliers can build value by fitting their equipment and service arrangements to the buyer's actual deployment plan.
Emergency medical services determine the fleet, staffing and deployment arrangements into which selected compression equipment must fit.
Which country CAGRs are profiled in the Automated CPR Device Market?
Table 6: Country CAGR Comparison for Automated CPR Device Market (CAGR percentage), 2026 to 2036
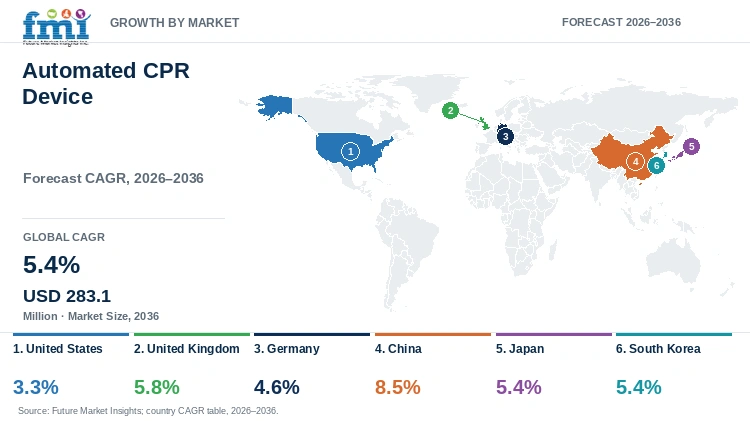
| Country | CAGR |
|---|---|
| United States | 3.3% |
| United Kingdom | 5.8% |
| Germany | 4.6% |
| China | 8.5% |
| Japan | 5.4% |
| South Korea | 5.4% |
Country-wise Analysis
United States Automated CPR Device Market Outlook (2026 to 2036)
US clinical guidance places a clear boundary around the commercial case for automated compression equipment. The AHA does not recommend routine mechanical CPR device use for adults in cardiac arrest, while allowing consideration in selected circumstances where high-quality manual compression is difficult or dangerous and interruption can be limited. [1] A service therefore needs to identify the intended setting and prepare its team before purchasing equipment for that role. Manufacturers can compete through dependable equipment and practical training, while the clinical protocol remains central to the decision about when the device is used.
United Kingdom Automated CPR Device Market Outlook (2026 to 2036)
UK guidance connects mechanical chest compression with situations in which high-quality manual compressions are impractical or compromise provider safety, making the intended operating environment important to procurement. The guidance also emphasises trained teams and minimal interruption during fitting, so the commercial requirement includes preparation and deployment capability alongside the device. [2] Suppliers need to support the equipment's readiness and the team's familiarity with its fitting process, while buyers assess maintenance, accessories and continuing training within their service. These operational requirements influence whether an installed device remains useful when the relevant clinical situation arises.
Germany Automated CPR Device Market Outlook (2026 to 2036)
German emergency fleets considering mechanical compression need a deployment plan that fits the teams, vehicles and clinical situations for which the equipment is intended. A provider may need to assess storage, access to the patient and the availability of trained staff, while continuing maintenance determines whether a device remains ready across shifts. Manufacturers can make their proposals more useful by explaining the actual device configuration, accessories and service arrangements, allowing the buyer to connect the equipment with its selected clinical protocol and practical fleet requirements.
China Automated CPR Device Market Outlook (2026 to 2036)
Chinese hospital programmes considering mechanical compression during a complex resuscitation procedure need to connect the device with patient access, team responsibilities and the intended clinical protocol. ILCOR's international consensus identifies ECMO cannulation among settings where manual compression can interfere with another potentially lifesaving procedure, providing a relevant technical consideration for such programmes. [4] Suppliers need to support the actual configuration and deployment arrangement, while the hospital maintains the wider procedural resources. Dependable readiness and fitting support contribute to the purchasing proposition within this defined clinical setting.
Japan Automated CPR Device Market Outlook (2026 to 2036)
Japan's national survey provides a detailed view of mechanical-compression equipment within participating emergency organisations. Among 695 consenting fire agencies, 650 owned an automated chest-compression device, and 445 of those owners equipped all their ambulance teams while 205 equipped some teams. [3] These findings make fleet coverage and continuing support practical purchasing questions, particularly where an organisation needs to maintain training and readiness across several teams. Suppliers need to understand the agency's actual deployment plan, because ownership of a device and routine readiness across every team represent different operational requirements.
South Korea Automated CPR Device Market Outlook (2026 to 2036)
South Korean hospital services considering automated compression need to establish the specific procedure or operating situation in which the device will be used, together with the team responsible for deployment. A clinical department may need equipment that fits limited patient access or a defined transport arrangement, while training and maintenance determine whether it remains available when required. Suppliers can strengthen the purchasing proposition through clear configuration information, dependable accessories and a service route that fits the institution's staffing. The buyer's actual protocol and deployment plan remain central to the practical value of the device.
Who are the notable companies in the Automated CPR Device Market?
Stryker; ZOLL Medical; corpuls; SCHILLER; Defibtech
Mechanical compression suppliers compete within selected clinical workflows that require prepared teams and dependable equipment readiness. Stryker, ZOLL, corpuls, SCHILLER and Defibtech occupy compression or resuscitation-equipment roles, with device configuration and deployment arrangements influencing the comparison. Fleet coverage creates continuing service requirements, while clinical protocols determine the settings in which a purchase has a useful operating role.
Competitive Benchmarking: Automated CPR Device Market
Table 7: Competitive positioning for the automated cpr device market
| Company | Positioning | Commercial distinction |
|---|---|---|
| Stryker | Mechanical chest-compression devices | Deployment workflow and fleet support |
| ZOLL Medical | Automated compression devices | Device mechanism and intended setting |
| corpuls | Mechanical CPR equipment | Team deployment and service arrangements |
| SCHILLER | Resuscitation equipment | Compression-device scope and training |
| Defibtech | Mechanical compression equipment | Specific product and operational support |
Key Developments in the Automated CPR Device Market
- The AHA's 2025 adult basic-life-support guidance retains a recommendation against routine mechanical CPR device use, placing the commercial case within selected clinical settings. [1]
- Japan's 2026 survey report documents device ownership and ambulance-team coverage among participating fire agencies, providing a view of the installed service environment. [3]
- ILCOR's 2025 ALS consensus identifies selected situations where mechanical compression can be useful, including when manual CPR interferes with ECMO cannulation, while retaining recommendations against routine replacement of manual compression. [4]
Key Players in the Automated CPR Device Market
Mechanical chest-compression devices
- Stryker
Automated compression devices
- ZOLL Medical
Mechanical CPR equipment
- corpuls
Resuscitation equipment
- SCHILLER
Mechanical compression equipment
- Defibtech
Automated CPR Device Market Report Scope
Table 8: Report Scope for Automated CPR Device Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market definition | The market covers mechanical or automated chest-compression devices and their deployment. AEDs and manual CPR training are excluded; ECMO equipment is outside the scope unless compression equipment is separately identified. |
| Quantitative units | USD million |
| Historical reference year | 2025 |
| Forecast period | 2026 to 2036 |
| Market breakdown | Product; Modality; End User; Region |
| Countries profiled | United States; United Kingdom; Germany; China; Japan; South Korea |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Key companies profiled | Stryker; ZOLL Medical; corpuls; SCHILLER; Defibtech |
Automated CPR Device Market Research Methodology
Table 9: Research Methodology for Automated CPR Device Market, 2026 edition
| Method | Approach |
|---|---|
| Market definition | The market covers mechanical or automated chest-compression devices and their deployment. AEDs and manual CPR training are excluded; ECMO equipment is outside the scope unless compression equipment is separately identified. |
| Secondary research | Public institutional reports, regulator publications, technical literature and supplier documentation provide the operating context for the market. |
| Quantitative coverage | Market values are expressed in USD million, with a 2025 base value, a 2026 estimate and a projection for 2036. |
| Segment and country assessment | Segment categories retain distinct demand measures, while each country profile is linked with its estimated CAGR for 2026 to 2036. |
| Company comparison | Representative participants are compared by the product or service offered, the customer application and the implementation requirements relevant to procurement. |
Automated CPR Device Market by Segments
Automated CPR Device Market segmented by Product:
- Piston-based Devices
- Load-distributing Band-based Devices
Automated CPR Device Market segmented by Modality:
- Battery-driven
- Electrically-driven
Automated CPR Device Market segmented by End User:
- Hospitals
- Emergency Departments
- Intensive Care Units
- Others
- Ambulatory Medical Centers
- Specialty Clinics
- Emergency Medical Services
- Ambulances
- Air Ambulances
- Independent Catheterization Labs
- Long-Term Care Centers
- Emergency Departments
Automated CPR Device Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] American Heart Association. 2025. 2025 Adult Basic Life Support Guidelines: mechanical CPR devices
- [2] Resuscitation Council UK. 2025-10-27. Adult advanced life support Guidelines 2025
- [3] Hiroshima International University / Emergency Promotion Foundation. 2026-03. Observational study of the usefulness of mechanical CPR in Japan
- [4] International Liaison Committee on Resuscitation. 2025. 2025 Consensus on Science With Treatment Recommendations: Advanced Life Support
This Report Answers
- How large is the Automated CPR Device Market in 2026?
- What is the growth outlook for the Automated CPR Device Market through 2036?
- What is the 2026 share of Piston-based Devices?
- What is the 2026 share of Emergency Medical Services?
- Which profiled market has the highest projected growth?
- Who are the notable participants in the Automated CPR Device Market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product, 2026 to 2036
- Piston-based Devices
- Load-distributing Band-based Devices
- Y-o-Y Growth Trend Analysis By Product, 2021 to 2025
- Absolute $ Opportunity Analysis By Product, 2026 to 2036
- Global Market Analysis and Forecast, By Modality, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Modality, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Modality, 2026 to 2036
- Battery-driven
- Electrically-driven
- Y-o-Y Growth Trend Analysis By Modality, 2021 to 2025
- Absolute $ Opportunity Analysis By Modality, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End User, 2026 to 2036
- Hospitals
- Emergency Departments
- Intensive Care Units
- Others
- Ambulatory Medical Centers
- Specialty Clinics
- Emergency Medical Services
- Ambulances
- Air Ambulances
- Independent Catheterization Labs
- Long-Term Care Centers
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product
- By Modality
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Modality
- By End User
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product
- By Modality
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Modality
- By End User
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Benelux
- Nordics
- By Product
- By Modality
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Modality
- By End User
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product
- By Modality
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Modality
- By End User
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product
- By Modality
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Modality
- By End User
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product
- By Modality
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Modality
- By End User
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product
- By Modality
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Modality
- By End User
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Modality
- By End User
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Modality
- By End User
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Modality
- By End User
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Modality
- By End User
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Modality
- By End User
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Modality
- By End User
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Modality
- By End User
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Modality
- By End User
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Modality
- By End User
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Modality
- By End User
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Modality
- By End User
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Modality
- By End User
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Modality
- By End User
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Modality
- By End User
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Modality
- By End User
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Modality
- By End User
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Modality
- By End User
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Modality
- By End User
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Modality
- By End User
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Modality
- By End User
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product
- By Modality
- By End User
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Stryker
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- ZOLL Medical
- corpuls
- SCHILLER
- Defibtech
- Stryker
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Product, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Modality, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 5: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by Product, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Modality, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 9: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Million) Forecast by Product, 2021 to 2036
- Table 11: Latin America Market Value (USD Million) Forecast by Modality, 2021 to 2036
- Table 12: Latin America Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 13: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Million) Forecast by Product, 2021 to 2036
- Table 15: Western Europe Market Value (USD Million) Forecast by Modality, 2021 to 2036
- Table 16: Western Europe Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Million) Forecast by Product, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Million) Forecast by Modality, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 21: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Million) Forecast by Product, 2021 to 2036
- Table 23: East Asia Market Value (USD Million) Forecast by Modality, 2021 to 2036
- Table 24: East Asia Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Million) Forecast by Product, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Million) Forecast by Modality, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Million) Forecast by Product, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Million) Forecast by Modality, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Million) Forecast by End User, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product
- Figure 6: Global Market Value Share and BPS Analysis by Modality, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Modality, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Modality
- Figure 9: Global Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End User
- Figure 12: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Product
- Figure 26: North America Market Value Share and BPS Analysis by Modality, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Modality, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Modality
- Figure 29: North America Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by End User
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Product
- Figure 36: Latin America Market Value Share and BPS Analysis by Modality, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Modality, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Modality
- Figure 39: Latin America Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by End User
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Product
- Figure 46: Western Europe Market Value Share and BPS Analysis by Modality, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Modality, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Modality
- Figure 49: Western Europe Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by End User
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Product
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Modality, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Modality, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Modality
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by End User
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Product
- Figure 66: East Asia Market Value Share and BPS Analysis by Modality, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Modality, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Modality
- Figure 69: East Asia Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by End User
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Product
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Modality, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Modality, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Modality
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by End User
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Product
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Modality, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Modality, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Modality
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by End User
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the Automated CPR Device Market in 2026?
The market is estimated at USD 167.27 million in 2026, compared with USD 158.7 million in 2025.
What is the growth outlook for the Automated CPR Device Market through 2036?
The market is projected to reach USD 283.11 million by 2036, representing a CAGR of 5.4% from 2026 to 2036.
What is the 2026 share of Piston-based Devices?
The Piston-based Devices segment is estimated to account for 84.9% of product demand in 2026. Deployment needs a trained team and attention to compression interruption, with the intended setting guiding the equipment's clinical role. [2]
What is the 2026 share of Emergency Medical Services?
The Emergency Medical Services segment is estimated to account for 34.4% of end user demand in 2026. Agency ownership and team coverage describe different stages of deployment, making training and fleet readiness important to the purchasing arrangement. [3]
Which profiled market has the highest projected growth?
China has the highest projected rate among the markets profiled, at 8.5% CAGR from 2026 to 2036.
Who are the notable participants in the Automated CPR Device Market?
Representative participants include Stryker, ZOLL Medical, corpuls, SCHILLER, Defibtech.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
