

- Market Size (2026)
- USD 444.0 Mn
- Forecast (2036)
- USD 1318.7 Mn
- CAGR (2026 to 2036)
- 11.5%
How Big is the Bakery Glazing Agents Market in 2026?
The bakery glazing agents market is estimated at USD 444.0 million in 2026.
The global bakery glazing agents market was valued at USD 398.2 million in 2025 and is estimated to reach USD 444.0 million in 2026. The market is projected to reach USD 1,318.7 million by 2036, expanding at a compound annual growth rate (CAGR) of 11.5% between 2026 and 2036. Standard grade accounted for the largest share of the Product Type breakdown, contributing 38.0% of total revenue in 2026. Demand is supported by investment from bakery ingredient suppliers. Puratos opened a dedicated US ultra-high-temperature (UHT) bakery glaze facility with a pilot line in October 2025[3], and the group reported 2025 revenue of EUR 3.6 billion, up 6.0%[5]. Egg costs also shape demand, as many glazes replace a traditional egg wash. US wholesale egg prices averaged USD 1.1 per dozen in February 2026, about 86.0% below a year earlier[7], after avian influenza losses had driven prices sharply higher. The US Department of Agriculture (USDA) expects retail egg prices to fall by 29.4% in 2026, following a 21.9% rise in 2025[8]. Lower egg prices reduce the cost advantage of egg-free glazes, so suppliers increasingly compete on consistency, handling and shelf life.
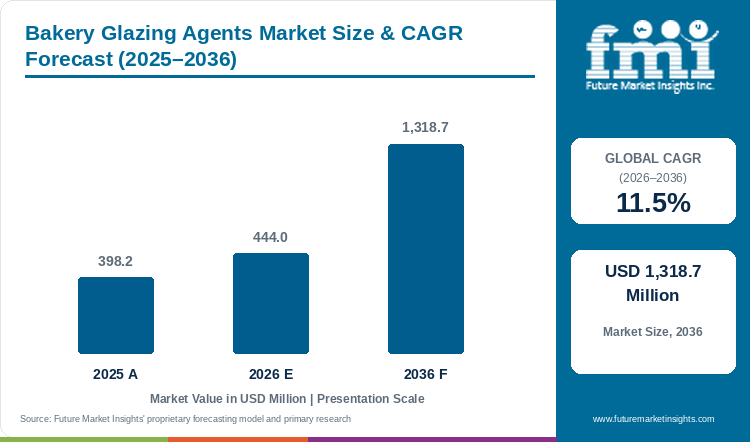
Table 1: Bakery Glazing Agents Market Size and Forecast (USD million), 2025 to 2036
| Market size and forecast | Value |
|---|---|
| 2025 market size | USD 398.2 million |
| Estimated market size in 2026 | USD 444.0 million |
| Projected market size by 2036 | USD 1,318.7 million |
| CAGR (2026-2036) | 11.5% |
| Added revenue, 2026 to 2036 | USD 874.7 million |
Key Market Trends & Insights
- By Product Type: The Standard grade segment accounted for the largest share of the Product Type breakdown in 2026, representing 38.0% of total market revenue.
- By Form: Powder / dry products held the leading market position with a share of 46.0% in 2026, with water addition and dispersion remaining part of preparation before application.
- By Application: Bread & rolls remained the largest application segment, accounting for 30.0% of the market in 2026.
Regional Highlights
- Fastest-growing country: The UAE is expected to record the highest growth rate among the eight profiled countries, with a projected CAGR of 12.8% between 2026 and 2036.
- Growth across other countries: Saudi Arabia is projected to expand at a CAGR of 12.5%, followed by South Korea at 12.2% and the USA at 11.8%. Japan is expected to register comparatively slower growth, with a CAGR of 10.5% during the forecast period.
Investment by leading suppliers is expanding glaze capacity. Puratos announced its dedicated US UHT bakery glaze facility in Pennsauken on October 28, 2025, with a pilot line linking manufacturing with application development[3]. The company reported revenue of EUR 3.6 billion in 2025, up 6.0% from the previous year, with net profit rising by more than 2.0% to EUR 130.3 million[5]. In March 2026, Puratos also agreed to acquire Dawn Foods[9]. Pilot-line capability addresses a central feature of glaze qualification, as the preparation must deliver its finish through the customer's dispensing and handling sequence, and the wider bakery ingredient system determines the surface presented to it.
Egg supply has a direct influence on demand for egg-replacing glazes. The Poultry Site reported that the US table-egg layer flock lost 151.2 million birds to highly pathogenic avian influenza (HPAI) between February 2022 and April 2026[6]. Outbreaks have since eased, with around 20.8 million birds affected in the first three months of 2026, roughly 45.0% fewer than a year earlier[7], and USDA projects 2026 table egg production at 7,827 million dozen, up 4.4%[6]. Zeelandia's Ovex range, an egg-glaze substitute, is offered as a powder mixed with water and as a ready-to-use liquid[2]. With eggs cheaper, the choice between these formats and a traditional egg wash depends more on preparation labour, storage and consistency at the applicator.
Product development is widening the range of finishes. IRCA introduced Colorglaze on June 16, 2025 for cold-process covering and decorating[4], an application route that differs from a prebake treatment in the conditions required to achieve colour and surface finish. Glaze costs are also affected by sugar, with the Food and Agriculture Organization of the United Nations (FAO) Sugar Price Index rising by 14.7% year on year in September 2026[10]. Composition accompanies the physical assessment, with FDA allergen guidance relevant to finished-food information in the USA[1], so a formula change may require a review of both the declaration and the surface after handling.
Table 2: Supporting Industry Indicators for the Bakery Glazing Agents Market, 2025 to 2026
| Indicator | Data point | Why it matters | Source |
|---|---|---|---|
| Dedicated glaze production | Puratos announced its US UHT glaze facility and pilot line in October 2025. | Dedicated capacity supports qualification for industrial finishing. | [3] |
| Supplier results | Puratos reported 2025 revenue of EUR 3.6 billion, up 6.0%, and net profit of EUR 130.3 million. | Leading suppliers are growing and investing. | [5] |
| Supplier consolidation | Puratos agreed to acquire Dawn Foods in March 2026. | Consolidation widens supplier glaze and finishing ranges. | [9] |
| HPAI losses | The US table-egg layer flock lost 151.2 million birds to HPAI between February 2022 and April 2026. | Egg shortages increased interest in egg-free glazes. | [6] |
| Egg supply recovery | USDA projects 2026 table egg production at 7,827 million dozen, up 4.4%. | Recovering supply lowers the cost of egg wash. | [6] |
| Wholesale egg prices | Large Grade A wholesale eggs averaged USD 1.1 per dozen in February 2026, about 86.0% below a year earlier. | Lower egg costs reduce the price advantage of egg replacers. | [7] |
| Retail egg price outlook | USDA expects retail egg prices to fall by 29.4% in 2026 after a 21.9% rise in 2025. | Egg price volatility affects glaze purchasing decisions. | [8] |
| Sugar prices | The FAO Sugar Price Index rose by 14.7% year on year in September 2026. | Sugar is a key input in many glazes. | [10] |
| Preparation formats | Zeelandia's Ovex is available as water-prepared powder and ready-to-use liquid. | Format choice changes mixing labour and preparation control. | [2] |
| Cold decorative range | IRCA introduced Colorglaze cold-process coloured glazes on June 16, 2025. | The range provides a route for covering and decorating without prebake application. | [4] |
Demand Intensity Analysis
A comparison of egg prices with market growth gives a measure of how the case for egg-free glazes has changed. US wholesale egg prices fell by about 86.0% between February 2025 and February 2026[7], while FMI estimates that the bakery glazing agents market grew by approximately 11.5% between 2025 and 2026. Demand for glazes continued to grow even as the cost advantage of replacing egg wash narrowed, which suggests that bakeries value consistency, food-safety handling and shelf life as well as cost.
Supplier scale provides another reference point. Puratos generated net profit of EUR 130.3 million on revenue of EUR 3.6 billion in 2025, a net margin of approximately 3.6%[5]. At these margins, input costs such as sugar, which rose by 14.7% on the FAO index[10], can have a significant effect on glaze pricing. Powder / dry, which accounted for USD 204.2 million in 2026, places dilution, dispersion and usable batch time within the customer's own operating sequence.
A similar comparison can be made between projected market growth and egg supply. FMI expects the market to grow at a CAGR of 11.5% between 2026 and 2036, compared with USDA's projected 4.4% growth in US table egg production in 2026[6]. Glaze growth is expected to come from wider use of formulated finishes in industrial baking rather than from egg shortages alone.
Segment values show where demand is concentrated. Standard grade was valued at USD 168.7 million in 2026, while Bread & rolls represented USD 133.2 million by Application and Direct to industrial bakeries held USD 213.1 million by Sales Channel. Frequent production runs connect these requirements with pack replenishment, applicator settings and the time available before wrapping. FMI projects USD 874.7 million in added revenue from 2026 to 2036, with the market reaching approximately 3.0 times its 2026 value.
Table 3: Demand Intensity Metrics for the Bakery Glazing Agents Market, 2025 to 2036
| Demand intensity metric | Value | Basis |
|---|---|---|
| FMI market growth, 2025 to 2026 | Approximately +11.5% | USD 398.2 million to USD 444.0 million. |
| US wholesale egg price change, February 2026 | Approximately -86.0% | Year-on-year change. |
| US retail egg price outlook, 2026 | -29.4% | USDA forecast. |
| US table egg production outlook, 2026 | +4.4% | USDA projection of 7,827 million dozen. |
| Puratos net margin, 2025 | Approximately 3.6% | EUR 130.3 million on EUR 3.6 billion. |
| FAO Sugar Price Index, September 2026 | +14.7% | Year-on-year change. |
| Powder / dry revenue, 2026 | USD 204.2 million | 46.0% of market revenue. |
| Direct to industrial bakeries revenue, 2026 | USD 213.1 million | 48.0% of market revenue. |
| Added revenue, 2026 to 2036 | USD 874.7 million | FMI bakery glazing agents forecast. |
| Market expansion multiple | Approximately 3.0 times | Projected 2036 market value relative to 2026. |
Analyst Perspective
"Cheaper eggs have removed the easy cost argument for egg-free glazes, so the suppliers that win will be those that prove their glaze gives the same finish on every run, through freezing and wrapping, with fewer rejected products."
- Nandini Roy Choudhury, Principal Analyst at Future Market Insights
How is the bakery glazing agents market segmented?
The bakery glazing agents market is segmented by product type, form, application, claim and sales channel. Product Type sets the grade, Form determines preparation requirements, and Application identifies the food and stage at which treatment occurs. Claim adds composition constraints, while Sales Channel governs technical coordination and replenishment.
Why does Standard grade anchor bakery glaze purchasing by Product Type?
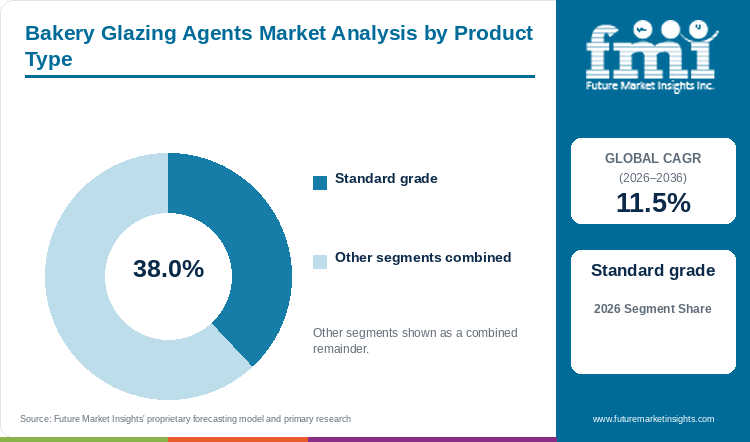
Standard grade represents 38.0% of Product Type revenue in 2026.
Standard grade glazes generated approximately USD 168.7 million in 2026, as recurring bread and pastry production needs an approved surface maintained with limited adjustment between runs. Defining coverage, colour and the condition required for handling makes that task measurable, and a trial can track dilution, application losses and items that need correction. Specialised finishes may warrant another formulation when the design calls for it, but routine work depends more on maintaining the approved reference, so the value of a standard grade appears in usable output as well as its purchase price.
- Standard grade represents 38.0% of Product Type revenue in 2026.
- Dilution, material loss and corrected items all contribute to the cost of a routine finish.
What operating choices keep Powder / dry first among glaze Forms?
Powder / dry leads Form with 46.0% of revenue in 2026.
Powder glazes generated approximately USD 204.2 million in 2026, placing control of water addition and mixing within the bakery's production sequence. Zeelandia's Ovex powder requires water, while its liquid alternative is ready to use[2]. The powder route needs a defined solids level, a mixing sequence that disperses the material consistently and a known period during which the prepared batch remains suitable for the applicator. Storage and transport advantages therefore have to be considered alongside the labour required to reproduce the mixture each time.
- Powder / dry leads Form with 46.0% of revenue in 2026.
- A defined mixing method must keep the prepared glaze suitable throughout its time in the applicator.
How do Bread & rolls drive the highest bakery glaze Application share?
Bread & rolls hold 30.0% of Application revenue in 2026.
Bread and rolls accounted for approximately USD 133.2 million in 2026, as uniform treatment matters across frequent batches. The glaze has to reach the intended area without pooling and leave a surface that can be cooled and wrapped normally. In a prebake application, the timing between proofing and the oven becomes part of the requirement. With egg prices falling by about 86.0% at wholesale in the year to February 2026[7], some bread producers may compare egg wash again with egg-free glazes, making consistent coverage and handling the key points of difference.
- Bread & rolls hold 30.0% of Application revenue in 2026.
- Cooling and wrapping show whether an even initial coating remains a usable surface.
Why does Conventional remain the leading Claim?
Conventional accounts for 55.0% of Claim revenue in 2026.
Conventional formulations held 55.0% of Claim revenue in 2026, as they allow ingredient selection to follow the bakery's required process and finished appearance. Claim-specific alternatives may narrow the ingredient choice or add documentation requirements, but every option still needs clear composition information. In the USA, the FDA's fifth-edition allergen guidance provides a reference for reviewing the finished-food label[1], which matters where a glaze replaces egg, a major allergen. Practical approval can then follow shine, coverage and colour development through cooling.
- Conventional accounts for 55.0% of Claim revenue in 2026.
- Formula changes can affect both the appearance of the glaze and finished-product information.
What makes Direct to industrial bakeries the principal Sales Channel?
Direct to industrial bakeries leads Sales Channel with 48.0% in 2026.
Direct supply to industrial bakeries accounted for approximately USD 213.1 million in 2026. Glaze flow variation affects coverage across an industrial run, and direct supply allows that behaviour to be addressed against a particular applicator and production sequence, with preparation method, operating temperature and the appearance at release agreed together. Dedicated capacity such as Puratos' Pennsauken UHT facility[3] supports this kind of relationship, while distributors remain useful where smaller requirements or mixed assortments matter more.
- Direct to industrial bakeries leads Sales Channel with 48.0% in 2026.
- The approved formulation needs to be tied to preparation temperature and applicator settings.
What are the drivers, restraints and opportunities in the bakery glazing agents market?
A dependable finishing step supports recurring bakery specifications, although a change in formulation can require a new application balance, while dedicated production and distinct finish formats widen the offer.
A dependable finishing step supports recurring bakery specifications
Glaze application forms part of the continuous sequence linking baking, cooling and packaging, and repeated correction at the finishing stage can delay it even where the initial appearance meets the specification. Preparation and delivery through the applicator matter alongside gloss or colour. The relationship with food processing equipment is direct, as spray systems, brushes and rollers do not handle the same preparation identically. Supplier investment such as Puratos' US glaze facility and pilot line[3] helps match formulations to the chosen method, allowing the bakery to repeat its visual standard at normal output.
A change in formulation can require a new application balance
Input cost volatility is a restraint. Egg prices rose by 21.9% in 2025 before an expected 29.4% fall in 2026[8], and the FAO Sugar Price Index rose by 14.7% year on year in September 2026[10], making it difficult to hold glaze prices steady. Replacement-glaze qualification also extends beyond matching the shine of the existing preparation, as different dilution or pickup may be needed and the surface may behave differently once cooled and packed. Zeelandia's powder and liquid Ovex formats show how alternatives involve different preparation work, while FDA allergen guidance makes composition review relevant to the US label[1][2].
Dedicated production and distinct finish formats widen the offer
Different glaze formats are expanding the choices available for defined finishing tasks. Puratos opened its US UHT glaze facility in October 2025[3], and its agreement to acquire Dawn Foods in March 2026[9] would bring together two large suppliers to North American bakeries. IRCA's Colorglaze introduction in June 2025 addressed cold-process coloured glazes for covering and decorating[4]. Prebake treatment, fruit surface treatment and a cold decorative layer each place different demands on preparation and use, and considering them alongside bakery coatings helps locate gloss, colour or surface protection within the product design.
Which country CAGRs are profiled in the bakery glazing agents market?
Table 4: Country growth outlook for the bakery glazing agents market
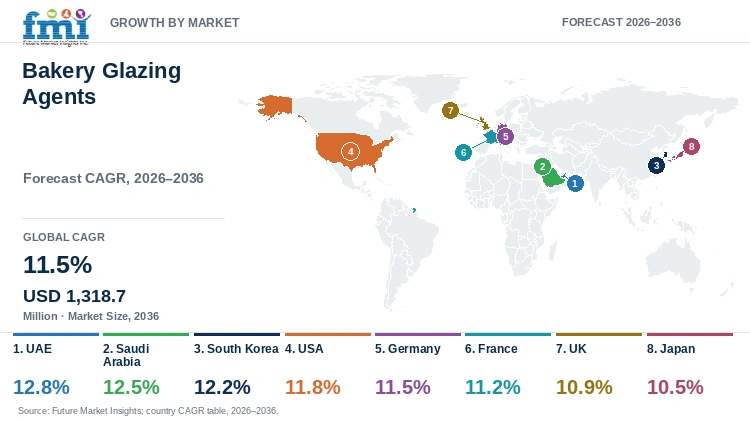
| Country | CAGR |
|---|---|
| UAE | 12.8% |
| Saudi Arabia | 12.5% |
| South Korea | 12.2% |
| USA | 11.8% |
| Germany | 11.5% |
| France | 11.2% |
| UK | 10.9% |
| Japan | 10.5% |
UAE
- The UAE is the fastest-growing market among the profiled countries, with a projected CAGR of 12.8% from 2026 to 2036. Central preparation and outlet finishing create different glaze requirements in the UAE, as a centrally mixed powder can suit controlled production, while a ready-to-use preparation may simplify work closer to service. Either route needs assessment after dispatch, transport and display, since the finish has to remain presentable beyond the point of application.
Saudi Arabia
- Saudi Arabia is forecast to grow at a CAGR of 12.5% from 2026 to 2036. Glaze left on equipment at the end of a run is part of the cost of finishing a Saudi bread or sweet-roll line, so application weight and colour need to be assessed alongside that loss and the time available before packing. When the applicator is filled repeatedly, pack format and batch preparation must also suit consumption, and observing a full run shows whether consistency changes between refills.
South Korea
- With a projected CAGR of 12.2% from 2026 to 2036, South Korea ranks third among the profiled countries. Glaze thickness and distribution determine how much surface detail remains visible on small pastries, and the intended appearance guides the choice between a cold finish and a prebake treatment. Any freezing and thawing steps belong in the trial, since the finish needs to survive the actual sequence without an added correction step before packing.
USA
- The USA market is forecast to grow at a CAGR of 11.8% from 2026 to 2036, supported by dedicated capacity such as Puratos' UHT glaze facility, opened in October 2025[3]. Egg costs have been especially volatile in the US. The layer flock lost 151.2 million birds to HPAI between February 2022 and April 2026[6], but wholesale prices fell to USD 1.1 per dozen in February 2026[7]. Egg-free glazes now need to compete on coverage, preparation labour and surface condition before wrapping, while composition must align with label requirements[1].
Germany
- Germany is projected to grow at a CAGR of 11.5% from 2026 to 2036. In German industrial applications, preparation labour and consistency over a complete shift distinguish powder glazes from ready-to-use alternatives. The comparison connects the desired surface with water addition, application weight and equipment settings. Powder storage flexibility has value when mixing remains reproducible, but cleanup and adjustments also affect usable output and need to be counted.
France
- France is projected to grow at a CAGR of 11.2% from 2026 to 2036. Shine, colour and protection are related but distinct reasons to glaze a pastry in France, and identifying the primary purpose helps separate the requirements of a baked surface from those of a cold decorative layer. The application weight must suit the product design while preserving its shape, and testing each format under its stated use conditions gives the bakery a precise finishing method.
UK
- The UK market is projected to grow at a CAGR of 10.9% from 2026 to 2036. UK production across bread, buns and pastries creates a choice between a shared glaze specification and separate preparations for distinct finishes, which affects stock, operator instructions and replenishment. Clearly differentiated formats help prevent a preparation intended for one task from being used for another, and following the surface through the normal cooling period shows whether it is ready for packing on schedule.
Japan
- Japan is expected to register the slowest growth among the profiled countries, with a forecast CAGR of 10.5% from 2026 to 2036. Folds and the base of a shaped bakery item can collect glaze, making a small coverage difference visible through an individual package, so flow characteristics and application weight need to suit the item's shape. Trials after cooling and handling establish whether the initially even finish remains so.
Who are the notable companies in the bakery glazing agents market?
Puratos; Zeelandia; IRCA Group; Bakels; Zentis
The supplier range spans different preparation and application routes. Puratos has dedicated UHT glaze production, Zeelandia supplies powder and liquid Ovex options, and IRCA offers cold-process coloured glazes[2][3][4]. Bakels and Zentis provide additional bread and pastry finishing ranges. Puratos reported revenue of EUR 3.6 billion in 2025[5] and agreed to acquire Dawn Foods in March 2026[9].
Changes in bakery mix formulation can also change the surface presented to a glaze applicator, so selection needs to account for the base recipe and finishing sequence together. A product suited to one dough or pastry requires assessment before it is carried across to another.
Competitive Benchmarking: Bakery Glazing Agents Market
Table 5: Company capabilities in the bakery glazing agents market
| Company | Product capability | Application emphasis |
|---|---|---|
| Puratos | Sunset Glaze and UHT glaze production | Prebake bakery finishing |
| Zeelandia | Ovex powder and liquid egg-glaze substitutes | Spray-applied prebake finish |
| IRCA Group | Colorglaze cold-process colored glazes | Decorative covering and glazing |
| Bakels | Hot, cold and UHT glaze ranges | Bread, pastry and confectionery finishing |
| Zentis | Fiber-free gel preparations and glazes | Post-bake pastry application |
Key Developments in the Bakery Glazing Agents Market
- In June 2025, IRCA introduced Colorglaze, a range of cold-process coloured glazes for covering and decorating[4].
- In October 2025, Puratos announced its dedicated US UHT bakery glaze facility in Pennsauken, which includes a pilot line linking production with application development[3].
- In March 2026, Puratos agreed to acquire Dawn Foods[9].
- In July 2026, Puratos was reported to have achieved 2025 revenue of EUR 3.6 billion, up 6.0%[5].
- In June 2026, The Poultry Site reported that US egg prices had fallen sharply as the flock rebuilt after HPAI losses, with USDA projecting 2026 table egg production up 4.4%[6].
Key Players in the Bakery Glazing Agents Market
- Puratos
- Zeelandia
- IRCA Group
- Bakels
- Zentis
Bakery Glazing Agents Market - Report Scope
Table 6: Report scope for the bakery glazing agents market
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Form; Application; Claim; Sales Channel |
| Quantitative Units | USD Million |
| Market Definition | Revenue from separately sold, food-grade glaze preparations used to create shine, color or a protective surface on baked goods before or after baking. Includes qualifying specialty fruit, gel and compound glazing products only when supplied for glazing; excludes finished bakery sales, unrelated fillings, general chocolate sales, bakery machines and services. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | UAE; Saudi Arabia; South Korea; USA; Germany; France; UK; Japan |
| Key Companies Profiled | Puratos; Zeelandia; IRCA Group; Bakels; Zentis |
| Forecast Period | 2026 to 2036 |
| Approach | Market assessment supported by official technical and regulatory publications, company product information and country operating conditions. |
Bakery Glazing Agents Market - Research Methodology
Table 7: Research approach for the bakery glazing agents market
| Method | Approach |
|---|---|
| Market definition | The assessment covers separately sold food-grade preparations used to glaze baked goods before or after baking, with application and ingredient revenue defined consistently. |
| Desk research | Government and regulatory publications, technical literature and official product information establish the application and supply context. |
| Commercial assessment | The analysis considers dilution, application coverage, surface appearance, preparation labor, equipment compatibility and the handling condition of the finished item. |
| Comparability | Market values, segment allocations and country growth rates use consistent units and the stated 2026 to 2036 forecast period. Company comparisons describe product roles and purchasing relevance. |
Bakery Glazing Agents Market by Segments
Product Type
- Standard grade
- Premium / specialty grade
- Organic certified
- Clean label grade
Form
- Powder / dry
- Liquid
- Paste / semi-solid
- Granules / pieces
Application
- Bread & rolls
- Cakes & muffins
- Biscuits & cookies
- Viennoiserie & pastry
- Other bakery & snacks
Claim
- Conventional
- Clean label
- Organic
- Non-GMO / identity preserved
Sales Channel
- Direct to industrial bakeries
- Ingredient distributors
- Foodservice & artisan supply
- Online B2B
Bakery Glazing Agents Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Food and Drug Administration. (2025, January). Guidance for industry: Questions and answers regarding food allergen labeling (Edition 5).
- [2] Zeelandia International. (n.d.). Ovex.
- [3] Puratos USA. (2025, October 28). UHT Glaze Facility Grand Opening.
- [4] Irca Group. (2025, June 16). Shine bright, cover right! New Colorglaze.
- [5] Neerman, P. (2026, July 13). RetailDetail. Puratos: 5 billion euros in revenue on the horizon.
- [6] Global Ag Media. (2026, June 17). The Poultry Site. US egg prices fall sharply as flock rebuilds after HPAI losses.
- [7] Wicks, N. (2026, April 8). Agri-Pulse. Egg prices avoid past spikes with fewer HPAI cases.
- [8] USDA Economic Research Service. (2026, September 25). Food price outlook: Summary findings.
- [9] Food Ingredients First. (2026, March 12). Puratos strikes deal to acquire Dawn Foods in bakery industry shakeup.
- [10] Food and Agriculture Organization of the United Nations. (2026, October 2). FAO Food Price Index.
Future Market Insights. (2026). Bakery Glazing Agents Market: Global Industry Analysis and Opportunity Assessment 2036.
This Report Answers
- What is the bakery glazing agents market value in 2026 and its forecast for 2036?
- How do surface appearance, preparation and application conditions influence glaze demand?
- Why does Standard grade lead the Product Type category?
- Why does Powder / dry lead the Form category?
- How do the profiled country growth rates differ between 2026 and 2036?
- Which companies provide prebake, post-bake and cold decorative glazes?
Frequently Asked Questions
How big is the bakery glazing agents market in 2026, and what is expected in 2036?
The market is valued at USD 444.0 million in 2026 and is expected to reach USD 1,318.7 million by 2036.
What is the bakery glazing agents market CAGR from 2026 to 2036?
The market is forecast to grow at a CAGR of 11.5% from 2026 to 2036.
Which Product Type leads the bakery glazing agents market?
Standard grade leads at 38.0% in 2026.
Which Form is largest in the bakery glazing agents market?
Powder / dry leads with 46.0% in 2026.
Which profiled countries show the highest bakery glazing agents growth rates?
The UAE leads at 12.8%, followed by Saudi Arabia at 12.5% and South Korea at 12.2% from 2026 to 2036.
Which companies participate in the bakery glazing agents market?
The report profiles Puratos, Zeelandia, IRCA Group, Bakels and Zentis, whose portfolios cover prebake finishes, cold decorative glazes and post-bake gel preparations.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Standard grade
- Premium / specialty grade
- Organic certified
- Clean label grade
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Form, 2026 to 2036
- Powder / dry
- Liquid
- Paste / semi-solid
- Granules / pieces
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- Bread & rolls
- Cakes & muffins
- Biscuits & cookies
- Viennoiserie & pastry
- Other bakery & snacks
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Claim, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Claim, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Claim, 2026 to 2036
- Conventional
- Clean label
- Organic
- Non-GMO / identity preserved
- Y-o-Y Growth Trend Analysis By Claim, 2021 to 2025
- Absolute $ Opportunity Analysis By Claim, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct to industrial bakeries
- Ingredient distributors
- Foodservice & artisan supply
- Online B2B
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- UAE
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Puratos
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Zeelandia
- IRCA Group
- Bakels
- Zentis
- Puratos
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


