
- Market Size (2026)
- USD 101.5 Mn
- Forecast (2036)
- USD 192.3 Mn
- CAGR (2026 to 2036)
- 6.6%
How Big Is the Biomaterial Market in 2026?
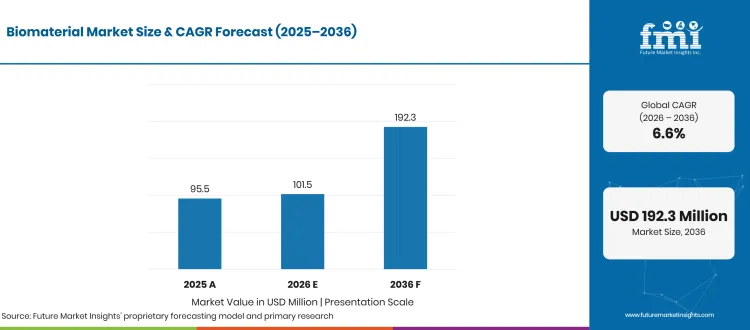
The global biomaterial market stands at USD 101.5 million in 2026, rising from USD 95.5 million in 2025, and is forecast by Future Market Insights (FMI) to reach USD 192.3 million by 2036, progressing at a 6.6% CAGR between 2026 and 2036 to deliver USD 90.8 million in incremental revenue over the 10-year forecast period.
| Market Metric | Valuation / Share / Forecast Benchmark |
|---|---|
| 2025 Market Size (Historical) | USD 95.5 million |
| 2026 Market Size (Estimated) | USD 101.5 million |
| 2036 Market Size (Projected) | USD 192.3 million |
| Compound Annual Growth Rate (2026 to 2036) | 6.6% CAGR |
| Incremental Dollar Opportunity (2026 to 2036) | USD 90.8 million |
| Dominant Material Backbone (2026 Share) | Titanium and Cobalt-Chromium Alloys (42.3% share in 2026) |
| Leading Surgical Application (2026 Share) | Orthopedic Implants and Trauma Fixation (46.1% share in 2026) |
| Leading End-User Industry (2026 Share) | Medical Device Manufacturing OEMs (74.8% share in 2026) |
| Leading Biodegradability & Fabrication (2026 Share) | Permanent Non-Resorbable Implants (58.4%) | Precision CNC Machining & Forging (51.6%) |
| Largest Country Markets (2026 Global Share) | United States (33.5%), China (15.0%), Japan (10.5%) |
| Fastest-Growing Country Markets (2026 to 2036) | South Korea (7.7% CAGR), Saudi Arabia (7.6% CAGR), China (7.4% CAGR) |
| Leading Tier-1 Companies | Evonik Industries AG, dsm-firmenich, Corbion N.V., CeramTec GmbH, Stryker, Zimmer Biomet, Medtronic |
Source: Future Market Insights analysis of the biomaterial market, 2026.
Executive Market Overview
The paperwork arrives before the part, and that is where biomaterial purchasing decisions are set. The American Academy of Orthopaedic Surgeons (March 2025) and the European Commission MDR registry (November 2025) confirm that titanium-coated PEEK and additive-manufactured trabecular titanium implants expanded 7.4% year-over-year across spinal fusion procedures, and that growth reaches the market through cleared implant systems rather than through spot material orders. North America and Europe hold 61.4% of global biomaterial consumption in 2026 on high joint replacement volumes, while expanding healthcare infrastructure across East Asia and India pulls faster procedural adoption through 2036. Contract manufacturing opportunities for specialized medical-grade titanium and polymer suppliers widen as device companies qualify second sources. The commercial question facing a supplier is how fast its documentation supports an OEM filing, and the contract value sits on that answer rather than on tonnage.
Widely used wrought titanium bars and commodity medical resins now meet tight hospital tender pricing, which caps margin on uncoated implant blanks. To lift realized value per unit, material suppliers commercialize fermentation-derived recombinant collagens, surface-bioactive coatings and medical-grade bioresorbable polymers tied to turnkey FDA Master Files. FMI projects bioresorbable polymer substrates to expand at a 10.9% CAGR through 2036, ahead of the 6.6% overall market average, as surgeons adopt degradable sutures, interference screws and drug-eluting scaffolds. Evonik Industries AG (September 2025) accelerated this shift by launching a clinical-trial-ready grade of VECOLLAN non-animal recombinant collagen for commercial medical device supply starting in 2026. Sizing covers certified implantable and tissue-contact titanium and cobalt-chromium alloys plus alumina-zirconia and hydroxyapatite bioceramics, bioabsorbable polylactide-glycolide and PEEK polymers, plus natural or recombinant collagen matrices, while excluding disposable hospital plastics, external orthotic braces and systemic pharmaceuticals.
Analyst Perspective
"Biomaterial formulators will grow revenue faster than raw tonnage by supplying additive-ready porous titanium powders, zirconia-alumina composites, and non-animal recombinant collagen backed by pre-validated ISO 10993 biological dossiers. The primary margin risk is protracted European MDR and FDA re-qualification timelines whenever an OEM modifies a resin or alloy grade."
- Anurag Sharma, Principal Consultant, Future Market Insights (FMI)
Major Market Trends and Insights
- Porous 3D-Printed Titanium and Hydrogel Hybrids Reduce Stress Shielding: Orthopedic implant engineers are replacing solid metallic stems with gyroid-lattice 3D-printed titanium structures infused with extracellular-matrix hydrogels that match cortical bone stiffness. Preclinical evaluation on bioRxiv (September 2025) shows a self-assembling peptide-hyaluronic acid hybrid scaffold inside 3D-printed porous Ti-6Al-4V calvarial implants doubled inner-core bone regeneration and lifted outer-zone bone volume to 101.0% to 106.0%, against 78.0% for inert titanium controls over eight weeks. MDPI Materials (December 2025) confirms that tailored pore geometry in titanium bone scaffolds accelerates osteoblast proliferation, the result device OEMs need before qualifying lattice feedstock.
- Non-Animal Recombinant Collagens and Self-Healing Hydrogels Replace Bovine Matrices: Medical device formulators are moving away from bovine and porcine collagen sponges toward fermentation-derived recombinant collagen and synthetic low-molecular-weight hydrogels to remove pathogen transmission risk and batch-to-batch cross-linking variability. On 16 September 2025, Evonik Industries AG (September 2025) launched clinical-grade VECOLLAN recombinant collagen for orthopedic, dental and soft-tissue scaffolds, after appointing IMCD in Evonik Industries AG (July 2025) to distribute RESOMER bioresorbable polymers across Europe. Parallel formulation research on ChemRxiv (August 2026) shows that hydroxamic-acid-functionalized hydrogelators form self-healing, cytocompatible gels at pH 9.2 for controlled active pharmaceutical ingredient delivery.
- Breakthrough Device Pathways Formalize Early Regulatory Dossier Alignment: Regulators in Europe, the United Kingdom and the United States are opening structured routes for Class III implantable devices that reward material suppliers holding complete biological evaluation master files. On 28 April 2026, the European Medicines Agency (April 2026) and the European Commission launched the European Union pilot programme for breakthrough medical devices ahead of Phase Ib opening on 1 September 2026 under proposed Article 52a of the Medical Devices Regulation. In parallel, the U.S. Food and Drug Administration (August 2026) updated its Breakthrough Devices Program guidance to streamline premarket review for novel implant substrates.
What Are the Main Drivers, Restraints, and Opportunities?
High-volume joint reconstruction, spinal fusion and dental implant procedures lift substrate consumption, while multi-year ISO 10993 biological validation and polymer degradation limits slow grade switching and leave porous trabecular metals and recombinant matrices as the growth avenues.
Driver: Rising Joint Arthroplasty, Spinal Fusion, and Dental Implant Procedure Volumes
Surgeons performing primary and revision hip and knee reconstructions require fatigue-resistant metallic stems paired with osteoconductive biocompatible materials that bond rapidly with host bone without iliac crest autograft harvesting. On 15 April 2026, Zimmer Biomet Holdings, Inc. (April 2026) received FDA 510(k) clearance for its expanded Identity and Comprehensive Reverse Shoulder systems with anatomical humeral trays and 32 mm glenospheres, and Stryker Corporation (March 2026) presented its Triathlon Gold coated femoral knee component for metal-sensitive patients plus the Triathlon Cementless 3D-printed porous titanium knee platform at the AAOS 2026 Annual Meeting. The U.S. Geological Survey (February 2026) reports Virginia specialty titanium powder capacity moving toward 1,400 metric tons per year, which gives OEMs a domestic feed for that porous demand.
Restraint: Protracted ISO 10993 Qualification, Screw Breakage in Resorbables, and Peri-Implant Inflammation
An approved implant substrate cannot be exchanged without multi-year ISO 10993 extractables testing, while biodegradable polymers and rough implant surfaces carry mechanical and immunological trade-offs. A systematic meta-analysis of four randomized controlled trials in MDPI Oral (January 2026) compared biodegradable poly-L-lactic and polyglycolic acid osteosynthesis plates with titanium fixation in mandibular fractures, with a pooled odds ratio of 0.28 and heterogeneity I2 = 66.1%, higher intraoperative screw breakage and longer operative times, plus sterile abscess risk across bone graft fixation system hardware. Epithelial testing in MDPI Dentistry Journal (January 2026) showed machined and sandblasted zirconia and titanium surfaces alter interleukin-8 (p < 0.05) and integrin expression in peri-implant oral epithelium, so committees treat a new alloy as a multi-year project.
Opportunity: Composite Bioresorbable Scaffolds and Additive Ceramic Forming
Material scientists are closing the mechanical modulus gap between degradable polymers and metals through mineralized polymer composites, surface-passivated zinc-lithium-calcium scaffolds and 3D-printed alumina-zirconia ceramics aimed at regenerative medicine and craniomaxillofacial repair. Analysis in PubMed Central (August 2025) documents that porous Zn-0.8Li-0.8Ca scaffolds with 70.0% porosity achieve a yield strength of 35.80 MPa and elastic modulus of 2.45 GPa with controlled 0.21 mm/year degradation, while photocurable methacrylated silk fibroin hydrogels at a 67.3% methacrylation rate support osteoblast mineralization. On the commercial side, CeramTec GmbH (September 2026) introduced its additive-manufactured structural medical ceramics portfolio ahead of COMPAMED 2026 in Dusseldorf, giving device OEMs a supplier to qualify for patient-specific implants.
How Is the Biomaterial Market Segmented?
The global biomaterial market is segmented by material backbone, surgical application, end-user industry, biodegradability profile, fabrication process and region, measuring certified implantable and tissue-contact substrate value at the medical device OEM and hospital procurement level.
| Segmentation Axis | Sub-Segments Covered | 2026 Leading Segment & Share | Main Growth Benchmark (2026 to 2036) |
|---|---|---|---|
| Material Backbone | Titanium & Cobalt-Chromium Alloys, Bioactive Hydroxyapatite Ceramics, Bioabsorbable Polylactic Polymers, Natural Collagen Matrix Scaffolds | Titanium & Cobalt-Chromium Alloys (42.3% revenue share) | Bioresorbable polymers expand fastest at 10.9% CAGR vs. 6.6% market average |
| Surgical Application | Orthopedic Implants & Trauma Fixation, Cardiovascular Grafts & Stents, Dental Implants & Bone Membranes, Plastic Reconstructive Surgery Matrices | Orthopedic Implants & Trauma Fixation (46.1% revenue share) | High-volume joint, spine, and trauma procedures sustain 46.1% share |
| End-User Industry | Medical Device Manufacturing OEMs, Biotechnology Regenerative Medicine Firms, Specialty Surgical Centers & Hospitals, Contract Medical Manufacturers, Academic Institutes | Medical Device Manufacturing OEMs (74.8% revenue share) | Centralized FDA Master File and EU MDR contracting anchors 74.8% share |
| Biodegradability & Fabrication | Permanent Non-Resorbable Implants, Controlled Bioresorbable Scaffolds, Surface-Bioactive Substrates | Precision CNC Machining & Forging, Additive 3D Laser Sintering, Porous Casting, Medical Extrusion | Permanent Non-Resorbable (58.4%) | Precision CNC Machining & Forging (51.6%) | Additive 3D laser sintering gains share in porous trabecular joint shells |
Source: Future Market Insights analysis of the biomaterial market, 2026.
Why Do Titanium and Cobalt-Chromium Alloys Lead by Material Backbone?
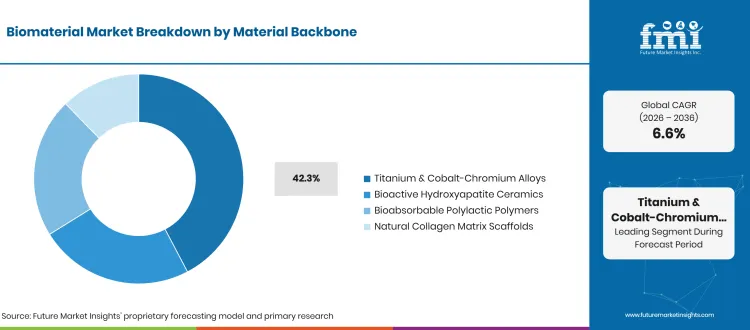
Titanium & Cobalt-Chromium Alloys lead the global biomaterial market by material backbone, capturing 42.3% of revenue in 2026. Load-bearing hip stems, knee femoral condyles, spinal pedicle screws and dental root fixtures need cyclic fatigue endurance, fracture toughness and a passive titanium-dioxide surface layer that stops fibrous encapsulation, so device OEMs buy metal against a fixed alloy and surface specification rather than on spot price. Comparative metallurgical evaluation published by the Indian Institute of Technology Roorkee in Biomedical Materials (July 2026) confirms that biodegradable magnesium alloys generate rapid hydrogen evolution and pure zinc lacks the ductility needed for heavy weight-bearing joints, while wrought Ti-6Al-4V and cobalt-chromium-molybdenum alloys paired with biocompatible polymers bearing liners sustain multi-decade gait loading. Supply chain tracking by the U.S. Geological Survey (February 2026) adds that Japan supplied 77.0% and Saudi Arabia 13.0% of U.S. titanium sponge imports, the high-purity feedstock for medical alloy conversion.
Why Do Orthopedic Implants and Trauma Fixation Lead by Surgical Application?
Orthopedic Implants & Trauma Fixation account for 46.1% of surgical application demand in 2026, anchored by global procedure volumes across total knee and hip arthroplasty, reverse shoulder reconstruction, internal trauma plating and lumbar interbody spinal fusion. Reconstructive surgeons combine porous metallic cages and biodegradable bone graft polymers with osteoinductive proteins to reach bony union without harvesting autogenous iliac crest bone, and outpatient osteoarthritis care adds non-surgical bio-implants to the same purchasing list. Regulatory approvals in 2026 reinforce this leadership. Medtronic plc (February 2026) earned FDA Premarket Approval for its INFUSE rhBMP-2 collagen bone graft in one- and two-level TLIF spine procedures from L2 to S1 with PEEK and titanium interbody cages, while Zimmer Biomet Holdings, Inc. (February 2026) cleared its G7 TM Acetabular System with Rim Fix screws for compromised acetabular bone.
Why Do Medical Device Manufacturing OEMs, Permanent Implants, and Precision CNC Machining Lead Their Categories?
Medical Device Manufacturing OEMs represent 74.8% of end-user industry revenue in 2026, Permanent Non-Resorbable Implants hold 58.4% by biodegradability profile and Precision CNC Machining & Forging commands 51.6% by fabrication process. Regulatory authorities hold the finished device OEM legally responsible for implant safety, which locks procurement teams into multi-year supply agreements for pre-certified biomaterial in surgical mesh, collagen skin matrix and metallic bar stock supported by ISO 10993 biological master files. Permanent non-resorbable substrates keep the volume majority because joint and dental prostheses must hold their structural geometry for 15 to 25 years in vivo (PubMed Central, August 2025). Five-axis Swiss CNC turning and hot forging deliver smooth bearing surfaces at scale, and additive ceramic 3D printing presented by CeramTec GmbH (September 2026) extends the same supply base for customized implants.
Biomaterial Market by Region and Country (2026 to 2036)
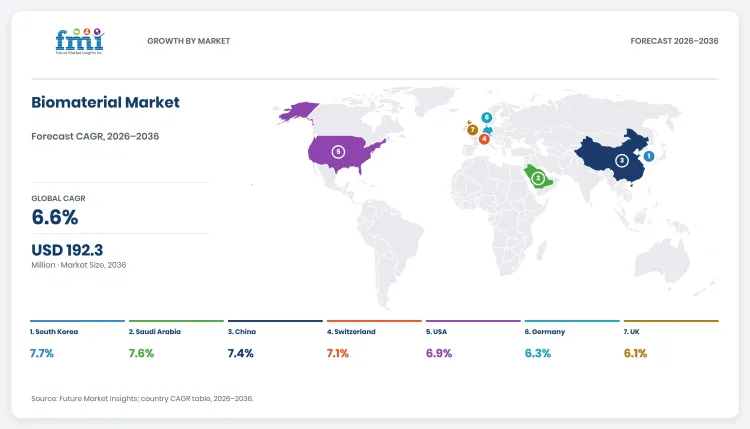
North America, East Asia and Western Europe account for the majority of global biomaterial revenue through 2036, while faster-growing Asian and Middle Eastern manufacturing hubs slowly widen their share. FMI projects the eight tracked countries in Table 3 to represent 84.0% of global revenue in 2026 at USD 85.3 million and 85.9% by 2036 at USD 165.1 million. The United States remains the largest national buyer pool, rising from USD 34.0 million in 2026 at a 33.5% global share to USD 66.2 million by 2036 at a 34.4% share and adding USD 32.2 million. Simultaneously, South Korea at a 7.7% CAGR, Saudi Arabia at 7.6% and China at 7.4% post the fastest national expansion rates as local implant assembly reduces import lead times.
| Country | 2026 Revenue | 2036 Revenue | 10-Year Addition | 2026 to 2036 CAGR | Global Share (2026 → 2036) |
|---|---|---|---|---|---|
| South Korea | USD 4.6 million | USD 9.7 million | +USD 5.1 million | 7.7% | 4.5% → 5.0% |
| Saudi Arabia | USD 1.8 million | USD 3.8 million | +USD 2.0 million | 7.6% | 1.8% → 2.0% |
| China | USD 15.2 million | USD 31.0 million | +USD 15.8 million | 7.4% | 15.0% → 16.1% |
| Switzerland | USD 3.6 million | USD 7.1 million | +USD 3.5 million | 7.1% | 3.5% → 3.7% |
| United States | USD 34.0 million | USD 66.2 million | +USD 32.2 million | 6.9% | 33.5% → 34.4% |
| Germany | USD 9.1 million | USD 16.8 million | +USD 7.7 million | 6.3% | 9.0% → 8.7% |
| United Kingdom | USD 6.3 million | USD 11.4 million | +USD 5.1 million | 6.1% | 6.2% → 5.9% |
| Japan | USD 10.7 million | USD 19.1 million | +USD 8.4 million | 6.0% | 10.5% → 9.9% |
Source: Future Market Insights analysis of the biomaterial market, 2026.
United States
At USD 34.0 million in 2026, the United States is the deepest biomaterial buying pool, expanding 1.95-fold at a 6.9% CAGR to USD 66.2 million by 2036, adding USD 32.2 million and lifting global share from 33.5% to 34.4%. Outpatient joint arthroplasty reimbursement and rapid FDA clearances for porous trabecular metals and recombinant biologics anchor domestic OEM purchasing. In February 2026, Medtronic plc (February 2026) won FDA Premarket Approval for its INFUSE collagen bone graft in TLIF spine surgery and Zimmer Biomet Holdings, Inc. (February 2026) secured FDA 510(k) clearance for its G7 TM Acetabular System, while Integra LifeSciences Holdings Corporation (November 2025) received FDA 510(k) clearance for its CUSA Clarity system in cardiac surgeries. Ambulatory surgery center joint volumes and domestic titanium powder capacity should sustain that purchasing through 2036.
China
Second in size and third in growth, China moves from USD 15.2 million in 2026 to USD 31.0 million by 2036 on a 7.4% CAGR, adding USD 15.8 million and lifting global share from 15.0% to 16.1%. National volume-based procurement tenders for orthopedic joint stems and trauma plates have cut finished device prices while driving procedure volumes and local raw-material sourcing at the same time. Trade statistics from the U.S. Geological Survey (February 2026) confirm China remains the largest titanium sponge refiner globally, and Evonik Industries AG (July 2025) operates a cleanroom device center in Shanghai to process bioresorbable polymers close to those tenders. Localization of medical-grade PLA and porous titanium implants should keep Chinese purchasing expanding through 2036.
Japan
Japanese biomaterial spend of USD 10.7 million in 2026 reaches USD 19.1 million by 2036 at a 6.0% CAGR, adding USD 8.4 million over the window as global share moderates from 10.5% to 9.9%. Super-aged demographics create steady domestic demand for cementless hip and knee bearings, dental fixtures and cell-seeded tissue scaffolds, reinforced by domestic titanium metallurgy that supplied 77.0% of U.S. titanium sponge imports per the U.S. Geological Survey (February 2026). Regulatory review records updated by the Pharmaceuticals and Medical Devices Agency, Japan (December 2025) confirm full approval for cellular scaffolds, which removes a hospital purchasing objection. Commercial scaling of PMDA-approved cellular scaffolds and pure beta-tricalcium phosphate ceramics should hold that disciplined value growth in place through 2036.
Germany
German demand of USD 9.1 million in 2026 grows to USD 16.8 million by 2036 at a 6.3% CAGR, generating USD 7.7 million in incremental revenue while global share holds near 9.0% and 8.7%. Precision surgical instrument and implant clusters in Tuttlingen, with specialty chemical and ceramic plants in Darmstadt and Plochingen, give Germany vertically integrated standing in medical PEEK, resorbable lactide polymers and alumina-zirconia hip bearings. In September 2026, CeramTec GmbH (September 2026) previewed its structural medical ceramics and ceramic 3D printing platforms ahead of COMPAMED 2026 in Dusseldorf, while Evonik Industries AG (September 2025) advanced commercial scale-up of VECOLLAN recombinant collagen. European Medicines Agency breakthrough device consultations and hybrid ceramic-polymer implants should keep German OEM order books growing through 2036.
United Kingdom
British biomaterial procurement of USD 6.3 million in 2026 is forecast to reach USD 11.4 million by 2036 at a 6.1% CAGR, adding USD 5.1 million as global share tracks from 6.2% to 5.9%. National Health Service elective orthopedic surgical hubs and private hospital networks specify hydroxyapatite-coated cementless stems and antimicrobial wound matrices that shorten post-operative ward stays. On 11 May 2026, the Medicines and Healthcare products Regulatory Agency (May 2026) opened consultation on the Medical Devices (Amendment) Regulations 2026, proposing compulsory unique device identifiers, mandatory patient implant cards and accelerated reliance access for implantable devices already cleared in Canada and the United States. Streamlined international conformity recognition and compulsory UDI traceability should favor pre-certified biomaterial suppliers in United Kingdom hospital tenders through 2036.
South Korea
South Korea runs the fastest national growth rate globally at a 7.7% CAGR, more than doubling 2.11-fold from USD 4.6 million in 2026 to USD 9.7 million by 2036, adding USD 5.1 million and lifting global share from 4.5% to 5.0%. An export-oriented titanium dental implant fixture and synthetic bone-graft industry drives growth with active hospital adoption of bioresorbable scaffolds. Materials research indexed in PubMed Central (August 2025) and MDPI Dentistry Journal (January 2026) highlights rapid Asian commercialization of sandblasted, acid-etched titanium and zirconia dental surfaces and composite hydroxyapatite bone membranes that accelerate mucosal sealing. Rising dental fixture exports across Asia-Pacific and hospital uptake of 3D-printed bioresorbable scaffolds should keep South Korea at the forefront of global biomaterial growth through 2036.
Switzerland
Swiss buying runs from USD 3.6 million in 2026 to USD 7.1 million by 2036 at a 7.1% CAGR, adding USD 3.5 million and raising Switzerland's global share from 3.5% to 3.7%. Swiss dental and trauma OEMs specialize in high-margin titanium-zirconium alloys, resorbable collagen barrier membranes and precision-machined osteosynthesis plates that are sold into export markets, so a domestic clearance raises the value of every export order. On 1 July 2026, Swissmedic (July 2026) enforced mandatory registration in the swissdamed database for all medical devices and implantable systems placed on the Swiss market, with a transition window closing on 31 December 2026. Digital traceability duties and high-value dental and trauma export orders should lock Swiss OEMs into long-term supply agreements with certified alloy and biopolymer producers through 2036.
Saudi Arabia
Saudi Arabia posts the second-fastest national expansion at a 7.6% CAGR, growing 2.11-fold from USD 1.8 million in 2026 to USD 3.8 million by 2036, adding USD 2.0 million as global share rises from 1.8% to 2.0%. Sovereign healthcare transformation initiatives under Saudi Vision 2030 are shifting hospital procurement away from imported finished implants toward domestic medical device assembly, supported by Saudi Arabia's 13.0% share of U.S. titanium sponge supply documented by the U.S. Geological Survey (February 2026). Licensing statistics from the Saudi Food and Drug Authority (July 2026) confirm that licensed factories and medical warehouses in the Kingdom grew 18.0% in 2025 to reach 9,155 facilities from 7,750 in 2024. Expanding SFDA-licensed implant plants and tertiary trauma hospital capacity should accelerate local biomaterial demand across Saudi Arabia through 2036.
Competitive Environment and Notable Companies
Notable companies operating in the global biomaterial market include Evonik Industries AG, dsm-firmenich, Corbion N.V., CeramTec GmbH, Stryker Corporation, Zimmer Biomet Holdings, Inc., Medtronic plc, Integra LifeSciences Holdings Corporation, Boston Scientific Corporation and Abbott Laboratories. Competition is tiered by value chain. Upstream specialty chemical and bioceramic producers synthesize GMP bioresorbable lactide polymers, implantable PEEK and recombinant collagen, plus alumina-zirconia ceramics. Downstream device OEMs engineer porous trabecular implants and tissue matrices around those inputs. Bargaining power sits with the OEM, which owns the device file, so suppliers compete on dossier completeness and lot consistency.
How Are Companies Positioned in the Biomaterial Market?
Upstream merchant supply is led by Evonik Industries AG with RESOMER bioresorbable polymers, VESTAKEEP PEEK and VECOLLAN recombinant collagen. Corbion N.V. supplies PURASORB polylactide and polyglycolide monomers, while dsm-firmenich supplies Dyneema Purity fibers and Bionate polycarbonate urethanes. CeramTec GmbH holds the BIOLOX delta alumina-zirconia hip bearing position. Downstream, implant leaders Zimmer Biomet Holdings, Inc., Stryker Corporation and Medtronic plc integrate porous 3D-printed titanium, elemental tantalum and rhBMP-2 collagen sponges into cleared surgical systems (Zimmer Biomet Holdings, Inc., February 2026; Medtronic plc, February 2026). Each layer sells to the layer above it, so a material breakthrough becomes revenue only after device clearance.
What Matters When a Buyer Selects a Biomaterial Supplier?
Medical device R&D and regulatory affairs directors select upstream material suppliers on complete ISO 10993 biological evaluation dossiers, FDA Type III or Type IV Master Files and European MDR Article 52a readiness (European Medicines Agency, April 2026). Buyers also weigh narrow lot-to-lot intrinsic viscosity and powder particle-size distributions. Because re-qualifying an implantable resin or alloy after a regulatory submission takes multiple years, OEMs award sole-source contracts to chemical and ceramic producers with multi-continent GMP redundancy. The buying test is simple, whether a second lot can be filed without restarting the evaluation.
Which Capabilities Distinguish Product Offers?
Product differentiation centers on non-animal recombinant purity, tailored hydrolytic resorption rates and interconnected 3D pore architectures. Evonik Industries AG distinguishes its portfolio with fermentation-derived VECOLLAN recombinant collagen that removes animal pathogen and cross-linking variability (Evonik Industries AG, September 2025), CeramTec GmbH stands out through additive 3D-printed structural medical ceramics (CeramTec GmbH, September 2026), while Zimmer Biomet Holdings, Inc. differentiates with 100.0% open-pore elemental tantalum Trabecular Metal shells (Zimmer Biomet Holdings, Inc., February 2026). Each claim is tied to a document an OEM can file, which is why specification wins over branding.
How Does Geographic Reach Affect Competition?
Upstream specialty polymer and ceramic suppliers operate global technical distribution networks to serve regional implant clusters. Evonik Industries AG partnered with IMCD in July 2025 to distribute RESOMER polymers across the European Economic Area, the United Kingdom and Switzerland while opening an ISO Class 7 medical device application center in Shanghai (Evonik Industries AG, July 2025). Medtronic plc, Stryker Corporation and Zimmer Biomet Holdings, Inc. commercialize finished implants across more than 100 countries. Local technical presence matters because a qualification question has to be answered in the buyer's own regulatory language and timeline.
| Verified Company Evidence (2025 to 2026) | Commercial Effect | Buyer Action |
|---|---|---|
| 22 September 2026: CeramTec announced its COMPAMED 2026 showcase in Dusseldorf featuring structural medical ceramics and ceramic 3D printing (CeramTec GmbH, September 2026). | Expands additive manufacturing into high-strength alumina and zirconia medical components. | Evaluate 3D-printed bioceramics for patient-specific dental and orthopedic implant designs. |
| 15 April 2026: Zimmer Biomet received FDA 510(k) clearance for expanded Identity and Comprehensive Reverse Shoulder systems, following G7 TM Acetabular clearance on 5 February 2026 (Zimmer Biomet Holdings, Inc., February & April 2026). | Broadens porous tantalum Trabecular Metal and modular titanium tray adoption in primary and revision arthroplasty. | Benchmark porous tantalum and modular titanium tray inventory for outpatient surgery centers. |
| 17 February 2026: Medtronic secured FDA Premarket Approval for INFUSE rhBMP-2 collagen bone graft in one- and two-level TLIF spine procedures with PEEK and titanium cages (Medtronic plc, February 2026). | Validates combined biologic-collagen and PEEK/titanium interbody cage utilization in lumbar spine surgery. | Align spinal cage material specifications with approved rhBMP-2 collagen carrier indications. |
| 16 September 2025: Evonik launched clinical-grade VECOLLAN fermentation-derived recombinant collagen for medical devices, after naming IMCD European RESOMER distributor in July 2025 (Evonik Industries AG, July & September 2025). | Provides a non-animal collagen alternative with reproducible batch purity and wider European polymer access. | Qualify fermentation-derived recombinant collagen to mitigate animal-tissue regulatory hurdles. |
Source: Verified corporate disclosures and Future Market Insights analysis, 2026.
| Company | Core Positioning | Verified Activity & Source Attribution |
|---|---|---|
| Evonik Industries AG | RESOMER bioresorbable polymers, VESTAKEEP implantable PEEK, and VECOLLAN recombinant collagen | Launched clinical-grade VECOLLAN recombinant collagen in September 2025 and appointed IMCD as European RESOMER distributor in July 2025 (Evonik Industries AG, July & September 2025). |
| dsm-firmenich | Dyneema Purity UHMWPE fibers, Bionate polycarbonate urethanes, and biodegradable polyester amides | Expanded biomedical polymer and drug-delivery material collaborations across orthopedic and cardiovascular device OEMs in 2025 and 2026. |
| Corbion N.V. | PURASORB medical-grade polylactide, polyglycolide, and caprolactone bioresorbable copolymers | Supplies GMP PURASORB monomers and polymers from Netherlands and US facilities for orthopedic screws, sutures, and drug delivery. |
| CeramTec GmbH | BIOLOX delta alumina-zirconia hip bearings, dental ceramic implants, and piezoceramics | Showcased structural medical ceramics and ceramic 3D printing solutions for COMPAMED 2026 in Dusseldorf (CeramTec GmbH, September 2026). |
| Zimmer Biomet Holdings, Inc. | Trabecular Metal porous tantalum shells, OsseoTi 3D porous titanium, and joint reconstruction implants | Received FDA 510(k) clearances for the G7 TM Acetabular System in February 2026 and expanded Reverse Shoulder systems in April 2026 (Zimmer Biomet Holdings, Inc., February & April 2026). |
| Medtronic plc | INFUSE rhBMP-2 absorbable collagen bone grafts, titanium and PEEK spinal cages, and vascular implants | Secured FDA Premarket Approval for INFUSE bone graft in one- and two-level TLIF spine procedures on 17 February 2026 (Medtronic plc, February 2026). |
| Stryker Corporation | Tritanium 3D-printed porous titanium cages, Triathlon knee systems, and LATERA PLLA implants | Showcased Triathlon Gold coated and Triathlon Cementless porous knee platforms at the AAOS 2026 Annual Meeting (Stryker Corporation, March 2026). |
| Integra LifeSciences Holdings Corporation | PriMatrix and Omnigraft acellular dermal and collagen regeneration matrices and surgical systems | Received FDA 510(k) clearance on 11 November 2025 for the CUSA Clarity ultrasonic surgical system in cardiac surgeries (Integra LifeSciences Holdings Corporation, November 2025). |
| Boston Scientific Corporation | Polymeric ePTFE vascular grafts, drug-eluting stent coatings, and injectable hydrogel spacers | Supplies implantable cardiovascular and peripheral vascular biomaterials across global interventional hospital centers. |
| Abbott Laboratories | Bioprosthetic pericardial heart valves, biocompatible titanium pacemaker housings, and vascular stents | Markets structural heart tissue valves and leadless cardiac rhythm implants across more than 160 countries. |
Source: Verified corporate disclosures and Future Market Insights analysis, 2026.
Biomaterial Market Report Scope and Research Methodology
FMI sizes the global biomaterial market by auditing merchant and captive supplier revenues for certified implantable and tissue-contact substrates sold to medical device OEMs, contract manufacturers, biotechnology firms and specialty surgical centers. Bottom-up volume-to-value modeling tracks medical-grade ASTM F136 titanium shipments, cobalt-chromium bar and powder shipments, ISO 6474 alumina-zirconia and hydroxyapatite ceramic volumes, GMP lactide-glycolide polymer consumption, PEEK polymer use and medical collagen matrix demand across orthopedic procedures plus dental and cardiovascular work. Country and segment estimates are cross-checked against U.S. FDA 510(k) and Premarket Approval dockets, European MDR filings and Swissmedic registrations plus USGS specialty metal trade balances, so that every segment reconciles to the global total in each forecast year. Unit conventions stay identical across the base year and the forecast window.
| Coverage Field | Report Scope |
|---|---|
| Market definition | Commercial supplier revenue from certified implantable and regenerative biomaterial substrates across metallic, ceramic, polymeric, and natural/recombinant extracellular matrices. |
| Material backbones | Titanium and Cobalt-Chromium Alloys, Bioactive Hydroxyapatite Ceramics, Bioabsorbable Polylactic Polymers, and Natural Collagen Matrix Scaffolds. |
| Surgical applications | Orthopedic Implants and Trauma Fixation, Cardiovascular Grafts and Stents, Dental Implants and Bone Membranes, and Plastic Reconstructive Surgery Matrices. |
| End-user industries | Medical Device Manufacturing OEMs, Biotechnology Regenerative Medicine Firms, Specialty Surgical Centers and Hospitals, Contract Medical Manufacturing Organizations, and Academic Research Institutes. |
| Biodegradability profiles | Permanent Non-Resorbable Implants, Controlled Bioresorbable Scaffolds, Surface-Bioactive Coated Substrates, and Stimuli-Responsive Hydrogel Matrices. |
| Fabrication processes | Precision CNC Machining and Forging, Additive 3D Laser Sintering, Porous Scaffold Casting Systems, and Medical Extrusion Compounding. |
| Materials included | Medical-grade Ti-6Al-4V, Ti-15Zr, elemental porous tantalum, CoCrMo alloys, alumina-zirconia, beta-TCP, hydroxyapatite, PLA/PGA/PLGA, PCL, implantable PEEK, and bovine/porcine/recombinant collagen. |
| Regulatory standards covered | ISO 10993 biological evaluation, ASTM F136/F75 metallic implant standards, FDA Type III/IV Master Files, EU MDR Article 52a, and Swissmedic swissdamed UDI rules. |
| Exclusions | Non-implantable disposable hospital tubing and syringes, external orthotic braces, industrial titanium pigments, and systemic pharmaceutical drugs. |
| Quantitative units | USD million for revenue valuation. |
| Value basis | Certified biomaterial substrate value counted at the medical device OEM and surgical center procurement level in each country. |
| Regions covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| National coverage | United States, China, Japan, Germany, United Kingdom, South Korea, Switzerland, and Saudi Arabia. |
| Companies covered | Evonik Industries AG, dsm-firmenich, Corbion N.V., CeramTec GmbH, Stryker Corporation, Zimmer Biomet Holdings, Inc., Medtronic plc, Integra LifeSciences Holdings Corporation, Boston Scientific Corporation, and Abbott Laboratories. |
Source: Future Market Insights analysis of the biomaterial market, 2026.
Research Sources and Bibliography
- BioRxiv. (2025, September 13). 3D-Printed Titanium Implants With Bioactive Peptide-Polysaccharide Hybrid Hydrogel for Bone Reconstruction.
- CeramTec GmbH. (2026, September 22). COMPAMED 2026: Advanced Structural Ceramics and Additive Manufacturing for Medical Equipment in Dusseldorf. https://www.ceramtec-group.com/en/news-events/news-overview/detail/compamed-2026-advanced-ceramics-for-medical-equipment
- ChemRxiv. (2026, August 18). Self-Healing Low-Molecular-Weight Hydroxamic Acid Hydrogel for Active Pharmaceutical Ingredient Formulation.
- European Medicines Agency. (2026, April 28). New Pilot to Support Development of Breakthrough Medical Devices Under Proposed EU MDR Revision. https://www.ema.europa.eu/en/news/new-pilot-support-development-breakthrough-medical-devices
- Evonik Industries AG. (2025, July 1). IMCD Becomes New European Distributor for Evonik RESOMER Medical Device Bioresorbable Polymers.
- Evonik Industries AG. (2025, September 16). Evonik Launches Recombinant Collagen VECOLLAN for Use in Clinical Medical Device Studies. https://www.evonik.com/en/news/press-releases/2025/09/evonik-launches-recombinant-collagen-vecollan-for-use-in-clinic-studies.html
- Indian Institute of Technology Roorkee in Biomedical Materials. (2026, July 16). Sustainable Metallic Biomaterials for Orthopaedic Implants: A Comprehensive Review of Biodegradable and Conventional Metals (PMID 42341830).
- Integra LifeSciences Holdings Corporation. (2025, November 11). Integra LifeSciences Receives FDA 510(k) Clearance for Use of the CUSA Clarity Ultrasonic Surgical Aspirator System for Cardiac Surgeries. https://www.integralife.com/news/fda-510k-clearance-for-cusa-clarity-ultrasonic-surgical-aspirator-system-for-cardiac-surgeries
- MDPI Dentistry Journal. (2026, January 4). Impact of Zirconia and Titanium Implant Surfaces of Different Roughness on Oral Epithelial Cells and Peri-Implant Epithelium. https://www.mdpi.com/2304-6767/14/1/30
- MDPI Materials. (2025, December 1). Advances in Titanium-Based Biomaterial for Human Bone Scaffolds: Design, Fabrication, Surface Engineering, and Biological Evaluation. https://www.mdpi.com/1996-1944/18/23/5421
- MDPI Oral. (2026, January 28). Comparison of Biodegradable Versus Titanium Fixation Systems in Mandibular Fracture Reconstruction: A Systematic Review and Meta-Analysis. https://www.mdpi.com/2673-4095/7/1/20
- Medicines and Healthcare products Regulatory Agency. (2026, May 11). MHRA Invites Views on Proposed Changes to Medical Device Regulation (Medical Devices Amendment Regulations 2026). https://www.gov.uk/government/news/mhra-invites-views-on-proposed-changes-to-medical-device-regulation
- Medtronic plc. (2026, February 17). Medtronic Announces FDA Premarket Approval of INFUSE Bone Graft for One- and Two-Level TLIF Spine Procedures. https://news.medtronic.com/2026-02-17-Medtronic-Announces-FDA-approval-of-Infuse-TM-bone-graft-for-one-and-two-level-Transforaminal-Lumbar-Interbody-Fusion-TLIF-spine-procedures
- Pharmaceuticals and Medical Devices Agency, Japan. (2025, December 8). List of Approved Regenerative Medical Products and Tissue Scaffolds in Japan. https://www.pmda.go.jp/english/review-services/reviews/approved-information/0004.html
- PubMed Central. (2025, August 9). Biodegradable Medical Implants: Reshaping Future Medical Practice Across Orthopedic and Vascular Care (PMC12462970). https://pmc.ncbi.nlm.nih.gov/articles/PMC12462970/
- Saudi Food and Drug Authority. (2026, July 23). SFDA Reports 18% Growth in Licensed Medical Device and Healthcare Factories and Warehouses Reaching 9,155 Facilities. https://oldsfda.sfda.gov.sa/en/taxonomy/term/3
- Stryker Corporation. (2026, March 3). Stryker Showcases Continued Innovation Across Orthopaedics Including Triathlon Gold and Cementless Knee Platforms at AAOS 2026. https://www.stryker.com/us/en/about/news/index.html
- Swissmedic. (2026, July 1). As of 1 July 2026, Mandatory Registration in swissdamed Applies to Medical Devices and Implantable Systems. https://www.swissmedic.ch/swissmedic/en/home/news/mitteilungen/swissdamed-registrierungspflicht.html
- U.S. Food and Drug Administration. (2026, August 31). Breakthrough Devices Program and 510(k) Premarket Notification Guidance for Medical Devices. https://www.fda.gov/medical-devices/how-study-and-market-your-device/breakthrough-devices-program
- U.S. Geological Survey. (2026, February 5). Mineral Commodity Summaries 2026: Titanium, Titanium Dioxide, and Titanium Mineral Concentrates. https://pubs.usgs.gov/periodicals/mcs2026/mcs2026-titanium.pdf
- Zimmer Biomet Holdings, Inc. (2026, February 5). Zimmer Biomet Receives FDA 510(k) Clearance for G7 TM Acetabular Hip Implant System for Challenging Primary and Revision Cases. https://hub.zimmerbiomet.com/Zimmer-Biomet-Receives-FDA-510k-Clearance-for-Hip-Implant-System-for-Challenging-Primary-and-Revision-Cases
- Zimmer Biomet Holdings, Inc. (2026, April 15). Zimmer Biomet Receives FDA 510(k) Clearance for Expanded Identity and Comprehensive Reverse Shoulder Implant Systems. https://hub.zimmerbiomet.com/Zimmer-Biomet-to-Showcase-Complete-Shoulder-Solution-Designed-to-Support-Surgeon-Flexibility
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Material Backbone, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Material Backbone, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Material Backbone, 2026 to 2036
- Titanium & Cobalt-Chromium Alloys
- Bioactive Hydroxyapatite Ceramics
- Bioabsorbable Polylactic Polymers
- Natural Collagen Matrix Scaffolds
- Y-o-Y Growth Trend Analysis By Material Backbone, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Backbone, 2026 to 2036
- Global Market Analysis and Forecast, By Surgical Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Surgical Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Surgical Application, 2026 to 2036
- Orthopedic Implants & Trauma Fixation
- Cardiovascular Grafts & Stents
- Dental Implants & Bone Membranes
- Plastic Reconstructive Surgery Matrices
- Y-o-Y Growth Trend Analysis By Surgical Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Surgical Application, 2026 to 2036
- Global Market Analysis and Forecast, By End-User Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End-User Industry, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End-User Industry, 2026 to 2036
- Medical Device Manufacturing OEMs
- Biotechnology Regenerative Medicine Firms
- Specialty Surgical Centers & Hospitals
- Contract Medical Manufacturers
- Academic Institutes
- Y-o-Y Growth Trend Analysis By End-User Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-User Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Biodegradability & Fabrication, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Biodegradability & Fabrication, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Biodegradability & Fabrication, 2026 to 2036
- Permanent Non-Resorbable Implants
- Controlled Bioresorbable Scaffolds
- Surface-Bioactive Substrates | Precision CNC Machining & Forging
- Additive 3D Laser Sintering
- Porous Casting
- Medical Extrusion
- Y-o-Y Growth Trend Analysis By Biodegradability & Fabrication, 2021 to 2025
- Absolute $ Opportunity Analysis By Biodegradability & Fabrication, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Western Europe
- East Asia
- South Asia and Pacific
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Material Backbone
- By Surgical Application
- By End-User Industry
- By Biodegradability & Fabrication
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Backbone
- By Surgical Application
- By End-User Industry
- By Biodegradability & Fabrication
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Kingdom
- Germany
- France
- By Material Backbone
- By Surgical Application
- By End-User Industry
- By Biodegradability & Fabrication
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Backbone
- By Surgical Application
- By End-User Industry
- By Biodegradability & Fabrication
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Material Backbone
- By Surgical Application
- By End-User Industry
- By Biodegradability & Fabrication
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Backbone
- By Surgical Application
- By End-User Industry
- By Biodegradability & Fabrication
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Australia
- Rest of world aggregate
- By Material Backbone
- By Surgical Application
- By End-User Industry
- By Biodegradability & Fabrication
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Backbone
- By Surgical Application
- By End-User Industry
- By Biodegradability & Fabrication
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Backbone
- By Surgical Application
- By End-User Industry
- By Biodegradability & Fabrication
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Backbone
- By Surgical Application
- By End-User Industry
- By Biodegradability & Fabrication
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Backbone
- By Surgical Application
- By End-User Industry
- By Biodegradability & Fabrication
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Backbone
- By Surgical Application
- By End-User Industry
- By Biodegradability & Fabrication
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Backbone
- By Surgical Application
- By End-User Industry
- By Biodegradability & Fabrication
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Backbone
- By Surgical Application
- By End-User Industry
- By Biodegradability & Fabrication
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Backbone
- By Surgical Application
- By End-User Industry
- By Biodegradability & Fabrication
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Backbone
- By Surgical Application
- By End-User Industry
- By Biodegradability & Fabrication
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Backbone
- By Surgical Application
- By End-User Industry
- By Biodegradability & Fabrication
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Backbone
- By Surgical Application
- By End-User Industry
- By Biodegradability & Fabrication
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Material Backbone
- By Surgical Application
- By End-User Industry
- By Biodegradability & Fabrication
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Evonik Industries AG
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- dsm-firmenich
- Corbion N.V.
- CeramTec GmbH
- Zimmer Biomet Holdings, Inc.
- Medtronic plc
- Stryker Corporation
- Integra LifeSciences Holdings Corporation
- Boston Scientific Corporation
- Abbott Laboratories
- Evonik Industries AG
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Material Backbone, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Surgical Application, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by End-User Industry, 2021 to 2036
- Table 5: Global Market Value (USD Million) Forecast by Biodegradability & Fabrication, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Material Backbone, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Surgical Application, 2021 to 2036
- Table 9: North America Market Value (USD Million) Forecast by End-User Industry, 2021 to 2036
- Table 10: North America Market Value (USD Million) Forecast by Biodegradability & Fabrication, 2021 to 2036
- Table 11: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 12: Western Europe Market Value (USD Million) Forecast by Material Backbone, 2021 to 2036
- Table 13: Western Europe Market Value (USD Million) Forecast by Surgical Application, 2021 to 2036
- Table 14: Western Europe Market Value (USD Million) Forecast by End-User Industry, 2021 to 2036
- Table 15: Western Europe Market Value (USD Million) Forecast by Biodegradability & Fabrication, 2021 to 2036
- Table 16: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 17: East Asia Market Value (USD Million) Forecast by Material Backbone, 2021 to 2036
- Table 18: East Asia Market Value (USD Million) Forecast by Surgical Application, 2021 to 2036
- Table 19: East Asia Market Value (USD Million) Forecast by End-User Industry, 2021 to 2036
- Table 20: East Asia Market Value (USD Million) Forecast by Biodegradability & Fabrication, 2021 to 2036
- Table 21: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 22: South Asia and Pacific Market Value (USD Million) Forecast by Material Backbone, 2021 to 2036
- Table 23: South Asia and Pacific Market Value (USD Million) Forecast by Surgical Application, 2021 to 2036
- Table 24: South Asia and Pacific Market Value (USD Million) Forecast by End-User Industry, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Million) Forecast by Biodegradability & Fabrication, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Material Backbone, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Material Backbone, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Material Backbone
- Figure 6: Global Market Value Share and BPS Analysis by Surgical Application, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Surgical Application, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Surgical Application
- Figure 9: Global Market Value Share and BPS Analysis by End-User Industry, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-User Industry, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-User Industry
- Figure 12: Global Market Value Share and BPS Analysis by Biodegradability & Fabrication, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Biodegradability & Fabrication, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Biodegradability & Fabrication
- Figure 15: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Material Backbone, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Material Backbone, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Material Backbone
- Figure 26: North America Market Value Share and BPS Analysis by Surgical Application, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Surgical Application, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Surgical Application
- Figure 29: North America Market Value Share and BPS Analysis by End-User Industry, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by End-User Industry, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by End-User Industry
- Figure 32: North America Market Value Share and BPS Analysis by Biodegradability & Fabrication, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Biodegradability & Fabrication, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Biodegradability & Fabrication
- Figure 35: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 36: Western Europe Market Value Share and BPS Analysis by Material Backbone, 2026 and 2036
- Figure 37: Western Europe Market Y-o-Y Growth Comparison by Material Backbone, 2026-2036
- Figure 38: Western Europe Market Attractiveness Analysis by Material Backbone
- Figure 39: Western Europe Market Value Share and BPS Analysis by Surgical Application, 2026 and 2036
- Figure 40: Western Europe Market Y-o-Y Growth Comparison by Surgical Application, 2026-2036
- Figure 41: Western Europe Market Attractiveness Analysis by Surgical Application
- Figure 42: Western Europe Market Value Share and BPS Analysis by End-User Industry, 2026 and 2036
- Figure 43: Western Europe Market Y-o-Y Growth Comparison by End-User Industry, 2026-2036
- Figure 44: Western Europe Market Attractiveness Analysis by End-User Industry
- Figure 45: Western Europe Market Value Share and BPS Analysis by Biodegradability & Fabrication, 2026 and 2036
- Figure 46: Western Europe Market Y-o-Y Growth Comparison by Biodegradability & Fabrication, 2026-2036
- Figure 47: Western Europe Market Attractiveness Analysis by Biodegradability & Fabrication
- Figure 48: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 49: East Asia Market Value Share and BPS Analysis by Material Backbone, 2026 and 2036
- Figure 50: East Asia Market Y-o-Y Growth Comparison by Material Backbone, 2026-2036
- Figure 51: East Asia Market Attractiveness Analysis by Material Backbone
- Figure 52: East Asia Market Value Share and BPS Analysis by Surgical Application, 2026 and 2036
- Figure 53: East Asia Market Y-o-Y Growth Comparison by Surgical Application, 2026-2036
- Figure 54: East Asia Market Attractiveness Analysis by Surgical Application
- Figure 55: East Asia Market Value Share and BPS Analysis by End-User Industry, 2026 and 2036
- Figure 56: East Asia Market Y-o-Y Growth Comparison by End-User Industry, 2026-2036
- Figure 57: East Asia Market Attractiveness Analysis by End-User Industry
- Figure 58: East Asia Market Value Share and BPS Analysis by Biodegradability & Fabrication, 2026 and 2036
- Figure 59: East Asia Market Y-o-Y Growth Comparison by Biodegradability & Fabrication, 2026-2036
- Figure 60: East Asia Market Attractiveness Analysis by Biodegradability & Fabrication
- Figure 61: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 62: South Asia and Pacific Market Value Share and BPS Analysis by Material Backbone, 2026 and 2036
- Figure 63: South Asia and Pacific Market Y-o-Y Growth Comparison by Material Backbone, 2026-2036
- Figure 64: South Asia and Pacific Market Attractiveness Analysis by Material Backbone
- Figure 65: South Asia and Pacific Market Value Share and BPS Analysis by Surgical Application, 2026 and 2036
- Figure 66: South Asia and Pacific Market Y-o-Y Growth Comparison by Surgical Application, 2026-2036
- Figure 67: South Asia and Pacific Market Attractiveness Analysis by Surgical Application
- Figure 68: South Asia and Pacific Market Value Share and BPS Analysis by End-User Industry, 2026 and 2036
- Figure 69: South Asia and Pacific Market Y-o-Y Growth Comparison by End-User Industry, 2026-2036
- Figure 70: South Asia and Pacific Market Attractiveness Analysis by End-User Industry
- Figure 71: South Asia and Pacific Market Value Share and BPS Analysis by Biodegradability & Fabrication, 2026 and 2036
- Figure 72: South Asia and Pacific Market Y-o-Y Growth Comparison by Biodegradability & Fabrication, 2026-2036
- Figure 73: South Asia and Pacific Market Attractiveness Analysis by Biodegradability & Fabrication
- Figure 74: Global Market - Tier Structure Analysis
- Figure 75: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the biomaterial market in 2026?
Future Market Insights estimates the global biomaterial market at USD 101.5 million in 2026, up from USD 95.5 million in 2025 across certified implantable metallic, ceramic and polymeric matrix substrates.
How fast is the biomaterial market expected to grow through 2036?
FMI projects the global biomaterial market to grow at a 6.6% CAGR from 2026 to 2036, reaching USD 192.3 million by 2036 and adding USD 90.8 million in incremental revenue.
Which material backbone segment leads the biomaterial market?
Titanium and Cobalt-Chromium Alloys lead by material backbone with 42.3% of 2026 revenue, whereas bioresorbable polymers represent the fastest-growing material class at a 10.9% CAGR through 2036.
Which surgical application segment accounts for the largest share?
Orthopedic Implants and Trauma Fixation account for 46.1% of 2026 revenue by surgical application, supported by high-volume hip and knee reconstruction procedures.
Which end-user industry and fabrication process lead the market?
Medical Device Manufacturing OEMs lead end-user industries with 74.8% of 2026 demand, while Precision CNC Machining and Forging leads fabrication processes at 51.6% share.
Which country is the largest biomaterial market globally?
The United States is the largest biomaterial market globally, capturing 33.5% of global revenue in 2026 (USD 34.0 million), followed by at 15.0% (USD 15.2 million) and Japan at 10.5% (USD 10.7 million).
Which countries are projected to grow fastest from 2026 to 2036?
South Korea (7.7% CAGR), Saudi Arabia (7.6% CAGR), and China (7.4% CAGR) are projected to record the fastest national growth rates from 2026 to 2036.
What drives demand for medical-grade biomaterials?
Demand is driven by rising orthopedic joint and spinal fusion volumes, FDA clearances for porous 3D-printed titanium and tantalum implants, and adoption of non-animal recombinant collagen scaffolds.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
