

- Market Size (2026)
- USD 3.4 Bn
- Forecast (2036)
- USD 9.6 Bn
- CAGR (2026 to 2036)
- 10.9%
How big is Cheese Alternative Market in 2026?
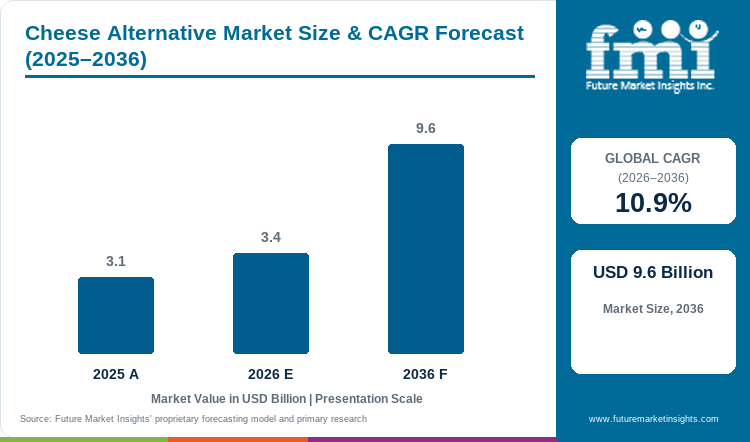
The Cheese Alternative market is valued at USD 3.4 billion in 2026 and is projected to reach USD 9.6 billion by 2036, expanding at a CAGR of 10.9% over the 2026-2036 period.
Demand for cheese alternatives is projected to expand at 10.9% CAGR between 2026 and 2036. Industry value grows from USD 3.1 billion in 2025 to USD 3.4 billion in 2026 and is projected to reach USD 9.6 billion by 2036. Retail shelves are carrying more slices, shreds, blocks, and spreads beside dairy cheese in chilled aisles. The wider choice is giving shoppers more chances to try cheese alternatives during normal grocery trips. Regular buying is harder because shoppers compare taste, melt, nutrition, and price with familiar dairy cheese. Retailers are tracking repeat sales to decide which products deserve limited refrigerated shelf space. Foodservice teams are testing the same products for melt, browning, portion size, and service speed. In May 2026, GFI reported plant-based cheese held near 1% of US cheese dollar sales during 2025. Plant-based cheese remains a small category, so brands have room to win shoppers with better flavor and value.
Country conditions are different because shoppers, retailers, and regulators face different buying rules and habits. US brands are using FDA naming guidance, so clear plant-source labels are important beside dairy cheese. In May 2026, GFI reported plant-based cheese reached 4% of US households during 2025. German retailers are placing plant-based foods beside dairy products, so shoppers compare taste and texture directly. UK households are buying large amounts of conventional cheese, which keeps the comparison with alternatives close. In September 2026, Defra reported UK households bought 129 grams of cheese per person each week for the year ending March 2025. The same official data showed purchases rose 2.9% from the previous financial year. South Korea and Japan are using food-tech programs to help new products move from trials toward business use. Across these countries, cheese alternatives need a clear meal role and dependable performance to become regular purchases.
Key Takeaways
- Better taste and melt are making cheese alternatives easier to use in familiar meals and easier to buy again.
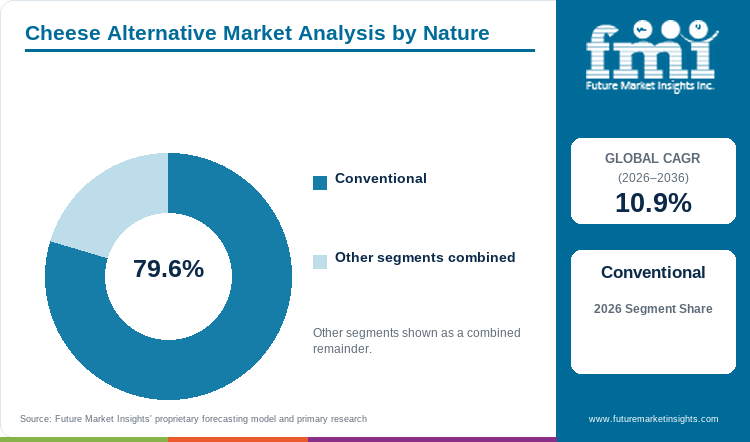
- Based on nature, conventional products are projected to account for 79.6% in 2026, supported by broader recipe choices across taste and price.
- By form, slice is forecast to represent 37.2% in 2026, influenced by fixed portions that suit sandwiches and packed lunches.
- B2C is set to lead the distribution channel with 85.2% share in 2026, reinforced by broad chilled-store access.
- Taste and melt are shaping regular buying, while nutrition and price are guiding direct comparisons with dairy cheese.
- Notable companies include Violife, Daiya Foods, Follow Your Heart, Miyoko's Creamery, Bel Group, Bute Island Foods, GoodPlanet Foods, and Treeline Cheese.
Analyst Perspective
"I expect cheese alternatives to become part of regular shopping as better melt and flavor make everyday meal swaps easier. Brands need better protein, pricing, and kitchen performance because retailers and foodservice teams are deciding which products deserve more space."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the cheese alternative market segmented?
The Cheese Alternative market is segmented four ways: by Nature, Form, Distribution Channel, and Region. Conventional products lead Nature with 79.6% of 2026 revenue, Slice leads Form with 37.2%, and B2C leads Distribution Channel with 85.2%.
The cheese alternative market uses four main axes: nature, form, distribution channel, and region. Nature separates products into conventional and organic based on sourcing rules. Form covers slice, shreds, blocks, cubes, spread, and spray across the market. Each form serves a different meal, snack, or kitchen serving need. Distribution channel separates store sales from sales to commercial kitchens. Region covers North America, Latin America, Western Europe, and Eastern Europe. East Asia, South Asia and Pacific, and Middle East and Africa complete the regional split.
Why does conventional lead the nature category?
Brands use conventional recipes because they can choose from more oils, starches, proteins, cultures, and processing aids. Product teams are using this wider choice to adjust taste, melt, nutrition, and cost for common cheese uses. Organic products serve shoppers who prefer certified ingredient sourcing standards. Organic rules narrow ingredient choice and can raise production costs for brands. Most shoppers are comparing cheese alternatives with dairy while planning normal meals. Conventional products cover more uses because brands can adjust recipes without meeting organic rules for every ingredient.
- By nature, conventional products are estimated to hold 79.6% in 2026, enabled by wider ingredient choice across recipe targets. Brands use that flexibility to adjust taste, nutrition, and price.
- Conventional makers use a wider ingredient list because every input does not need organic certification. The broader choice helps teams adjust texture, nutrition, and price for different buyers.
What keeps slice central to the form category?
Slices give shoppers ready portions for sandwiches, burgers, lunchboxes, and snacks. Households use slices without cutting or measuring portions before serving meals. Retailers place slices beside dairy cheese, so the intended use is easy to understand. Shreds and blocks are useful for cooked meals and baked dishes. Spreads work better for dips, crackers, and soft meal toppings. Slice remains familiar because it changes little about normal meal preparation.
- In 2026, slice is expected to lead form with 37.2% share, attributable to fixed portions for sandwiches and packed lunches. Ready portions reduce preparation work across sandwiches, burgers, and packed lunches.
- Households use slices for lunchboxes and simple snacks during regular meals. Brands can add flavors while keeping the portion size and handling familiar to shoppers.
Why does B2C dominate the distribution channel category?
Retail stores are the main place where shoppers find cheese alternatives during normal grocery trips. Shoppers are comparing ingredients, nutrition, price, and format while planning meals. Chilled aisles put several cheese formats in one place and make restocking easy. Restaurants are using cheese alternatives in pizza, breakfast, and sandwich meals served at scale. Kitchen teams need case sizes, melt, and browning that stay steady during busy service. Kitchen teams are checking hold times and menu costs for each use. B2C holds the larger share because stores offer more choice and easier household restocking.
- Within distribution channel, B2C is projected to hold 85.2% share in 2026, linked to chilled-store access to familiar formats. Households can compare several familiar formats during one grocery trip.
- Foodservice teams need portions and packs that suit kitchen storage, handling, and serving work. Retail packs do not meet every kitchen need because service speed and portion control differ from home use.
What are the drivers, restraints and opportunities in the cheese alternative market?
In the Cheese Alternative market, the key driver is flexitarian substitution that widens the buyer base for familiar cheese meals, the key restraint is taste and texture gaps that limit regular buying across stores and kitchens, and the key opportunity is better recipes that create room for stronger melt, protein, and foodservice performance.
- Driver: Shoppers who reduce dairy are using cheese alternatives in familiar meals without following a strict vegan diet.
- Restraint: Weak taste or texture is stopping some shoppers from buying again, while nutrition and price add more pressure.
- Opportunity: Better melt and protein are opening more meal uses, while foodservice packs are making kitchen handling easier.
Flexitarian shoppers bring cheese alternatives into more everyday meals
Many shoppers are cutting dairy without following a strict vegan diet, so cheese alternatives can enter ordinary meals. In May 2026, GFI reported 52% of US plant-based cheese buyers bought it more than once in 2025. Everyday meals are creating more purchase occasions than products aimed at strict diets. Sandwiches and pizza let shoppers compare flavor and melt with dairy in foods they already know. Pasta and snacks add more uses without changing how households cook. Cheese makers need steady flavor and texture across these meals. Mixed-diet households can buy dairy and plant-based options in the same weekly shop. Good results in familiar dishes are giving shoppers a reason to buy the product again.
Taste, texture, nutrition, and price can stop first-time buyers from returning
Problems with taste, texture, nutrition, or price are stopping some shoppers from buying again. In May 2026, GFI reported plant-based cheese dollar sales fell 10% during 2025. The same review reported unit sales fell 8% during 2025. In June 2026, GFI reported foodservice cheese alternative sales fell 15% in dollars and pounds during 2025. Falling sales show that taste and texture are not meeting enough shoppers' expectations beside dairy cheese. Protein and vitamin levels are different across products, so shoppers are checking nutrition as well. Price is important because the dairy aisle has familiar choices at many price points. Retail and foodservice products need good taste and texture at a price buyers accept.
Better melt, protein, and foodservice packs create more everyday uses
Better recipes are making cheese alternatives useful in more household meals and restaurant menus. In June 2026, GFI named taste and texture as key barriers for plant-based cheese in foodservice. Food makers are focusing product work on flavor, melt, and texture in common kitchen uses. Brands are using cultures and plant-based protein to improve texture and nutrition within familiar cheese formats. Better browning is helping pizza and baked dishes during busy service. Higher protein is giving shoppers another reason to compare alternatives with dairy. Foodservice packs are improving portion control and handling during breakfast and snack service. Brands are widening use by matching each format to a clear meal or kitchen task.
Which country CAGRs are included in the cheese alternative market?
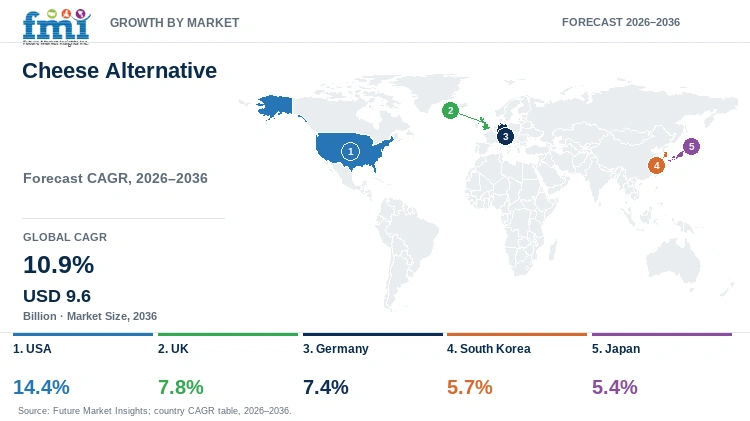
| Country | CAGR |
|---|---|
| USA | 14.4% |
| UK | 7.8% |
| Germany | 7.4% |
| South Korea | 5.7% |
| Japan | 5.4% |
How do country-level CAGRs compare in the cheese alternative market?
Cheese alternative demand is developing differently across the five countries because retail access, food rules, and meal habits differ. US and UK rules are putting more focus on naming and ingredient communication. German shoppers are comparing taste and texture closely with dairy products in stores. South Korea and Japan are using food-tech programs to move new products from trials toward business use.
- Across the USA, broad grocery access keeps attention on taste and melt across familiar cheese formats.
- UK labeling and allergen rules set clear requirements for product names and ingredient communication across plant-based cheese ranges.
- Germany places emphasis on taste and texture as shoppers compare plant-based cheese beside familiar dairy formats.
- South Korea's food-tech policy helps product testing and gives companies clearer paths from research into business planning.
- Japan favors food-tech trials that help companies test plant-derived dairy products against local meal habits.
The full report provides country-level CAGR analysis across North America, Latin America, Western Europe, and Eastern Europe. Coverage also includes East Asia, South Asia and Pacific, and the Middle East and Africa.
Country-wise Analysis
- Cheese alternative demand in the USA is forecast to rise at 14.4% CAGR over the forecast period, supported by broad grocery access. Grocery stores are giving shoppers several formats and prices to compare in one trip. FDA guidance asks makers to use clear food names and identify the main plant source. In January 2025, FDA issued draft guidance for plant-based alternatives to animal-derived foods. Clear names help shoppers understand each product beside dairy cheese. Taste and melt are important in sandwiches and other familiar meals. Price matters because dairy and plant-based products share the same chilled aisle. Brands need clear labels and reliable performance to keep shelf space.
- The UK cheese alternative market is estimated to post 7.8% CAGR over the forecast period, influenced by labeling and allergen rules. Brands are using labeling and allergen rules to keep product names and ingredient details clear. Public agencies are studying how new protein foods reach shops and restaurants. In June 2025, the Government Chemist reported rising UK interest in selling alternative proteins. The review listed shopper acceptance and food rules among the main issues for new protein foods. Cheese alternatives are competing with many dairy products in stores. Wide store access makes first trials easier, but poor taste can block another purchase. Brands need clear labels and better flavor to turn trials into regular purchases.
- Cheese alternative sales in Germany are forecast to expand at 7.4% CAGR by 2036, linked to wide store access and familiar formats. Retailers are giving shoppers familiar slices and shreds to try at home. German shoppers expect plant-based cheese to match dairy taste and texture in each format. In June 2026, GFI Europe reported plant-based cheese sales value fell 7.4% during 2025. The same source reported sales volume stayed near the prior-year level during 2025. Store access cannot offset weak flavor or texture beside dairy products. Brands need reliable melt and flavor to earn more chilled shelf space.
- Adoption of cheese alternatives in South Korea is estimated to expand at 5.7% CAGR through 2036, reinforced by national food-tech policy. Companies are using national food-tech support to move product tests toward business use. National programs include plant-based foods in wider work on new food technology. In July 2026, MAFRA published South Korea's first national food-tech plan under the Food Tech Industry Promotion Act. The plan expands testing support and helps companies plan later investment. Cheese alternatives need to suit local tastes and familiar meals. Shoppers are comparing nutrition and price during regular grocery trips. Clear serving ideas help shoppers understand how to use slices, shreds, or spreads. Brands can widen use by fitting local meals and explaining each format.
- In Japan, cheese alternative demand is predicted to advance at 5.4% CAGR through 2036, enabled by MAFF food-tech testing programs. Companies are using MAFF programs to test new foods and prepare them for sale. Plant-derived dairy is part of this wider work on product and business tests. In December 2025, MAFF opened applications for a food-tech testing and business support program. The program helps companies judge whether new foods can work in shops and restaurants. Shoppers can reject products with unfamiliar flavor or no clear role in regular meals. Japanese buyers expect useful portions and steady flavor across familiar meals. Brands can build regular use by proving each format in foods shoppers know.
Who are the notable companies in the cheese alternative market?
Notable companies in the Cheese Alternative market include Violife, Daiya Foods, Follow Your Heart, Miyoko's Creamery, Bel Group, Bute Island Foods, GoodPlanet Foods, and Treeline Cheese.
Violife, Daiya Foods, and Follow Your Heart sell familiar formats such as slices, shreds, and blocks. Miyoko's Creamery and Treeline Cheese use cultured plant milks or cashews for specialty styles. Bel Group uses known cheese brands in plant-based snacks and spreads. Bute Island Foods sells vegan cheese through its Sheese range. GoodPlanet Foods serves stores and foodservice with several dairy-free formats. Retail teams are comparing format choice with taste and melt in common meals. Foodservice teams are adding pack size, handling, and supply consistency to the same review. Store success does not guarantee that a product works in a busy kitchen.
- Violife, Daiya Foods, and Follow Your Heart sell several cheese formats for familiar home meals.
- Miyoko's Creamery and Treeline Cheese use cultured plant milks or cashews for specialty cheese styles.
- Bel Group uses known cheese brands, while Bute Island Foods and GoodPlanet Foods focus on distinct dairy-free ranges.
Competitive Benchmarking: Cheese Alternative Market
| Company | Format Breadth | Melt or Culturing Capability | Foodservice Readiness | Geographic Reach |
|---|---|---|---|---|
| Violife | High | High | High | Europe, North America, and other international markets |
| Daiya Foods | High | High | High | United States, Canada, and selected international markets |
| Follow Your Heart | High | Medium | Low | United States |
| Miyoko's Creamery | Medium | High | Medium | United States |
| Bel Group | High | Medium | High | Europe and North America |
| Bute Island Foods | Medium | Medium | High | United Kingdom with international foodservice and retail history |
| GoodPlanet Foods | Medium | Medium | High | United States |
| Treeline Cheese | High | High | Medium | United States |
The benchmarking table uses public product and foodservice evidence available through September 2026. High format breadth means a company sells several core cheese forms in its current range. Medium means the company sells a smaller range that covers normal cheese uses. High melt or culturing capability means public sources show a culturing method or tested melt performance. High foodservice readiness means the company offers dedicated foodservice products, service packs, or kitchen support. Medium means the company sells through wholesale channels but does not offer dedicated service packs. Low means public sources show retail products but no clear professional-kitchen range.
Key Developments in the Cheese Alternative Market
- In May 2025, Daiya Foods launched Pepper Jack Slices and Chipotle Cheddar Shreds in North American stores. Both products use its Oat Cream mix and bring bolder flavors to familiar formats. Slices give shoppers fixed portions for sandwiches, while shreds support melt in cooked meals.
- In January 2026, Bel Group launched plant-based Babybel Original and Barbecue in France. The five-portion pack gives shoppers a familiar snack without animal ingredients. Bel uses a known cheese brand to make the plant-based choice easy to recognize.
- In August 2025, Schuman Cheese formed GPV Foods with GoodPlanet Foods for plant-based dairy. GPV Foods combines GoodPlanet's retail reach with Vevan's foodservice and manufacturing base. The business serves store and kitchen buyers through a wider dairy-free cheese range.
Key Players in the Cheese Alternative Market
Multi-format mainstream alternatives
- Violife
- Daiya Foods
- Follow Your Heart
Cultured and artisanal cheese alternatives
- Miyoko's Creamery
- Treeline Cheese
Branded extensions and focused specialists
- Bel Group
- Bute Island Foods
- GoodPlanet Foods
Cheese Alternative Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Nature, Form, Distribution Channel, and Region |
| Quantitative Units | USD billion |
| Market Definition | Revenue from cheese alternative products sold within the stated Nature, Form, and Distribution Channel universe. Excludes conventional dairy cheese, adjacent dairy alternatives such as milk or yogurt, and downstream finished foods whose selling price includes cheese alternatives as an ingredient. Ingredient systems are excluded unless sold as a finished cheese alternative product. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Japan, USA, South Korea, UK, and Germany |
| Key Companies Profiled | Violife, Daiya Foods, Follow Your Heart, Miyoko's Creamery, Bel Group, Bute Island Foods, GoodPlanet Foods, and Treeline Cheese |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Cheese Alternative Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Cheese Alternative Market by Segments
Cheese Alternative Market segmented by Nature:
- Conventional
- Organic
Cheese Alternative Market segmented by Form:
- Slice
- Shreds
- Blocks
- Cubes
- Spread
- Spray
Cheese Alternative Market segmented by Distribution Channel:
- B2C
- B2B Foodservice
Cheese Alternative Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- U.S. Food and Drug Administration(2025, January 6).Plant-Based Milk and Animal Food Alternatives.
- The Good Food Institute (n.d.). U.S. retail market insights for the plant-based industry.
- The Good Food Institute (2026, June). U.S. foodservice market insights for plant-based foods (2021-2025).
- UK Government Chemist(2025, June 16).Quantitative review of sustainable novel food production.
- Department for Environment, Food & Rural Affairs. (2026, September 17). Family Food FYE 2025.
- UK Government (n.d.). Naming food products.
- Ministry of Agriculture, Forestry and Fisheries of Japan (n.d.). Creation of demand through new value creation.
- Ministry of Agriculture, Food and Rural Affairs of South Korea (2024, January 31). Ministry steps up efforts to revitalize the plant-based alternative food industry.
- Ministry of Agriculture, Food and Rural Affairs of South Korea (2024, December 30). Standardization work for food-tech development enters full operation.
- Ministry of Agriculture, Food and Rural Affairs of South Korea (2026, July 20). S. Korea Unveils Master Plan to Integrate Advanced Technologies into the Food Sector.
- ProVeg Deutschland (2026, January 30). Lidl × ProVeg: Gewinner des Käse-Wettbewerbs kommt in die Lidl-Regale.
- Daiya Foods (2023, December 7). Daiya’s Reformulated Cheese Products Hit Shelves.
- Daiya Foods (2025, May 14). Daiya Introduces First-to-Market Dairy-Free Cream Cheese Packets for Foodservice Operators.
- Daiya Foods (2025, June 23). Daiya Expands Dairy-Free Portfolio with Bold, Flavor-Forward Cheese Innovations: Chipotle Cheddar Shreds & Pepper Jack Slices.
- Dairy Processing (2024, June 6). Miyoko’s Creamery debuts alternative cheese spreads.
- Miyoko's Creamery (n.d.). About Us.
- Bute Island Foods (n.d.). Our Story.
- Food and Drink Technology (2024, May 1). Vegan brand Sheese re-launches with major new look and recipe.
- Bel Group (2023, April 11). Bel and Climax Foods, Inc. Announce Partnership to Innovate Cutting-edge Plant-Based Cheeses Indistinguishable from Dairy Cheeses, Powered by AI.
- Bel Group (n.d.). Proteins of the future: responsible cheese alternatives.
- FoodBev Media (2025, June 5). Bel Group to discontinue plant-based cheese brand Nurishh by end of 2025.
- Violife (n.d.). Our Story.
- Violife (n.d.). Supreme Cheddarton.
- Follow Your Heart (n.d.). Dairy Free Cheese.
- GOOD PLANeT Foods (n.d.). About Us.
- Treeline Cheese (2024, December). 2024 End of Year Letter from Founder.
- Treeline Cheese (2026, February 6). Treeline Cheese Expands Assortment at Whole Foods Market.
- Treeline Cheese (n.d.). Facts About Treeline.
- Plant Based Foods Association. (2026, June 3). Plant-Based Foods Are a Staple in American Households - Regional Data Highlights Growing Opportunity.
- The Good Food Institute. (2026, May). State of the Industry: Plant-based meat, seafood, eggs, dairy, and ingredients.
- The Good Food Institute Europe. (2026, June 9). Germany remains Europe’s leading market for plant-based foods with 3.1% growth in sales value.
- Ministry of Agriculture, Forestry and Fisheries of Japan. (2025, December 22). 令和7年度フードテックビジネス実証・実装事業の公募について.
- Bel Group. (2025, March 6). Lancement du Boursin végétal en Belgique.
- Bel Group. (2026, January 15). Babybel® innovates with two 100% plant-based recipes.
- Bel Foodservice UK. (2025, April). Nurishh Samples Terms and Conditions.
- Schuman Cheese. (2025, August 4). Schuman Cheese and GOOD PLANeT Foods Unite to Transform Plant-Based Dairy.
- Miyoko's Creamery. (2025, June 20). Sip, Savor, and Slider: Miyoko’s Creamery x Golden State Cider Collab.
- Daiya Foods. (2025, May 1). Daiya Enhances Dairy-Free Cream Cheese and Dairy-Free Deluxe Mac & Cheese with New Reformulations.
- Bel Brands Foodservice. (n.d.). Mini Babybel Plant-Based Cheese.
- GOOD PLANeT Foods. (n.d.). FOOD SERVICE.
- Treeline Cheese. (n.d.). Wholesale Inquiry.
- Flora Food Group. (2026). Annual Report 2025.
The bibliography lists the main sources used in this article. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the Cheese Alternative Market in 2026 and what is the forecast value for 2036?
- Which consumer and operating pressures support demand for cheese alternatives?
- Why does conventional lead the nature category?
- Why does slice lead the form category?
- How do growth rates differ across the USA, UK, Germany, South Korea, and Japan?
- Which companies provide relevant cheese alternative products and formats?
- What limits use, regular buying, or supplier switching in cheese alternatives?
- What should retail and foodservice buyers evaluate while buying cheese alternatives?
Frequently Asked Questions
How big is the Cheese Alternative Market in 2026, and what is forecast for 2036?
The Cheese Alternative Market is worth USD 3.4 billion in 2026. Market value is projected to reach USD 9.6 billion by 2036 as retail and foodservice use expands.
What is the CAGR for the Cheese Alternative Market from 2026 to 2036?
The Cheese Alternative Market is projected to expand at 10.9% CAGR from 2026 through 2036. Better taste and texture are supporting regular buying, while nutrition and price remain important purchase checks.
Which nature segment leads the Cheese Alternative Market?
Based on nature, conventional products are projected to account for 79.6% in 2026, supported by broader recipe options across price targets. Organic alternatives serve certified sourcing needs but use a narrower ingredient and cost range.
Which form segment leads the Cheese Alternative Market?
Within form, slice is likely to capture 37.2% share in 2026, influenced by familiar portions for sandwiches and packed lunches. Ready portions reduce preparation for sandwiches, burgers, lunchboxes, and simple snacks.
Which countries show notable growth rates in the Cheese Alternative Market?
The USA, UK, Germany, South Korea, and Japan have different forecast growth rates. Retail access, food rules, product testing, and meal habits create different local demand conditions.
Which companies are active in the Cheese Alternative Market?
Notable companies include Violife, Daiya Foods, Follow Your Heart, Miyoko's Creamery, Bel Group, Bute Island Foods, GoodPlanet Foods, and Treeline Cheese. These companies cover broad retail brands, cultured specialists, brand extensions, and focused dairy-free cheese ranges.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Nature, 2026 to 2036
- Conventional
- Organic
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form, 2026 to 2036
- Slice
- Shreds
- Blocks
- Cubes
- Spread
- Spray
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- B2C
- B2B Foodservice
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Nature
- By Form
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Form
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Nature
- By Form
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Form
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Nature
- By Form
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Form
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Nature
- By Form
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Form
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Nature
- By Form
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Form
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Nature
- By Form
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Form
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Nature
- By Form
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Form
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Nature
- By Form
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Violife
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Daiya Foods
- Follow Your Heart
- Miyoko's Creamery
- Bel Group
- Bute Island Foods
- GoodPlanet Foods
- Treeline Cheese
- Violife
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


