
- Market Size (2026)
- USD 10.8 Bn
- Forecast (2036)
- USD 35.1 Bn
- CAGR (2026 to 2036)
- 12.5%
How big is Continuous Glucose Monitoring Systems Market in 2026?
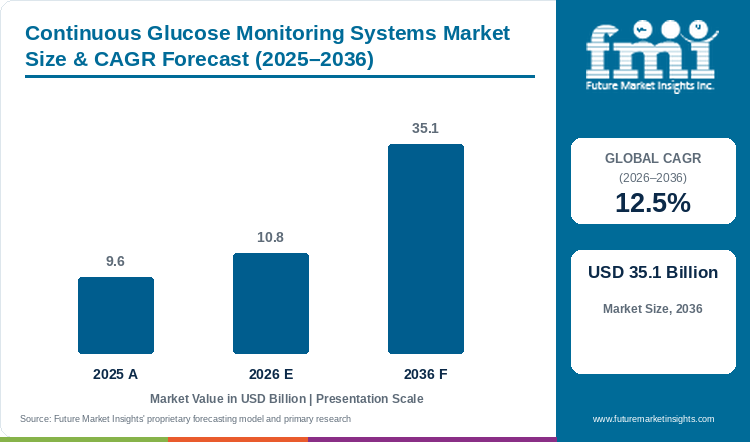
Assessed at USD 9.6 billion in 2025 and progressing to USD 10.8 billion in 2026, the continuous glucose monitoring systems market valuation is on course to reach USD 35.1 billion by 2036, supported by a forecast-period CAGR of 12.5%.
The global continuous glucose monitoring systems market was valued at USD 9.6 billion in 2025 and is estimated to reach USD 10.8 billion in 2026. The market is projected to reach USD 35.1 billion by 2036, expanding at a compound annual growth rate (CAGR) of 12.5% between 2026 and 2036. Subcutaneous disposable sensors are anticipated to capture a 58.0% share of 2026 demand, given that factory-calibrated epidermal filaments require scheduled biweekly replacement across active patient cohorts. FMI demand analysis indicates that market expansion is driven by reimbursement-unlocked buyer penetration, where public and commercial payers remove multi-injection prerequisites so basal-insulin Type 2 diabetes patients purchase continuous sensor subscriptions [1]. That recurring consumable cadence separates this industry from blood glucose monitoring devices at a 4.4% CAGR, since episodic fingerstick test strips lose prescription share whenever payers subsidize continuous interstitial telemetry. Manufacturers are also investing in extended-wear sensor platforms, as DexCom launched its FDA-cleared G7 15 Day system with an 8.0% MARD across United States durable medical equipment providers in December 2025 [2]. Endocrinology clinics and retail pharmacies renew sensor formularies on 15-day wear durability and automated insulin pump interoperability through 2036.
Key Market Trends & Insights
- By component architecture: Subcutaneous Disposable Sensors hold an estimated 58.0% share in 2026 since single-use enzymatic filaments require 24 to 36 replacement insertions per patient each year.
- By wear duration: 10 to 14 Days Wearable Sensors represent 64.0% in 2026 owing to broad regulatory clearances and established biweekly pharmacy refill packs across North America and Europe.
- By patient cohort: Type 1 Diabetes Intensive Insulin Patients account for 72.0% in 2026 given near-universal statutory reimbursement and mandatory closed-loop pump pairing across pediatric and adult clinics.
- By distribution channel: Durable Medical Equipment DME Providers secure 54.0% in 2026 supported by Medicare Part B supply allowance billing and contracted home shipment logistics.
- By connectivity integration: Standalone Smartphone-Connected CGMs command 56.0% in 2026 as direct Bluetooth Low Energy transmission to mobile apps eliminates dedicated receiver hardware.
Regional Highlights
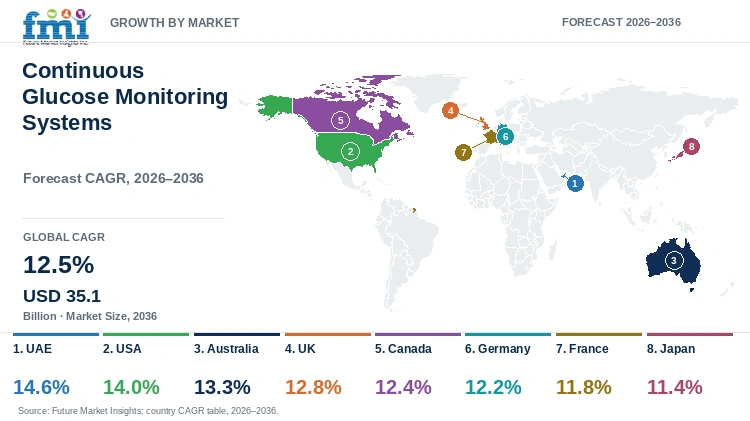
- Top national expansion: The UAE leads national growth projections at a 14.6% CAGR through 2036 under mandatory adult metabolic screening and insurance-backed sensor dispensing.
- Broader country progression: The USA tracks at a 14.0% CAGR ahead of Australia at 13.3% and the UK at 12.8%, while Canada advances at 12.4% and Germany records 12.2%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Continuous Glucose Monitoring Systems Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 9.6 billion |
| Estimated Market Size in 2026 | USD 10.8 billion |
| Projected Market Size by 2036 | USD 35.1 billion |
| CAGR, 2026 to 2036 | 12.5% |
| Added Revenue, 2026 to 2036 | USD 24.3 billion |
Outpatient endocrinology networks and primary care clinics are transitioning millions of insulin-treated and basal-treated patients from episodic capillary fingersticks to continuous interstitial glucose telemetry. Broader demand for glucose monitoring devices reflects this clinical migration toward automated trend alerts that prevent severe nocturnal hypoglycemia and emergency hospitalizations.
Active Patient Pool and Sensor Consumption Sizing
Table 2: Active Patient Pool and Sensor Consumption Sizing for the Continuous Glucose Monitoring Systems Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 9.6 | 10.8 | 35.1 |
| Active global CGM patient pool (million users) | 11.8 to 12.5 | 13.0 to 13.8 | 40.5 to 43.0 |
| Annual disposable sensors shipped (million units) | 310.0 to 330.0 | 345.0 to 365.0 | 980.0 to 1,050.0 |
| Average sensors consumed per patient-year (units) | 24.3 to 36.5 | 24.3 to 35.0 | 22.0 to 26.5 |
Operational note: Annual sensor volume ranges reflect 24.3 sensors per patient-year for 15-day wear platforms and 26.1 to 36.5 sensors per patient-year for 10-day to 14-day disposable systems.
Figures from the International Diabetes Federation in April 2025 show that 589 million adults aged 20 to 79 years live with diabetes globally, and 252 million undiagnosed adults expand the addressable monitoring pool [3]. As clinicians prescribe skin-adhered glucose patches earlier in disease management, annual disposable sensor shipments scale in lockstep with multi-year patient retention.
Per Patient Expenditure & Clinical Accuracy Benchmarks
Table 3: Annualized Per Patient Expenditure and Accuracy Benchmarks for the Continuous Glucose Monitoring Systems Market (USD and MARD percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global adult diabetes population, IDF/WHO (million) | 589.0 | 605.0 | 720.0 |
| Annual net OEM spend per active CGM patient (USD) | 790.0 to 830.0 | 800.0 to 840.0 | 820.0 to 860.0 |
| Clinical accuracy MARD benchmark range (%) | 8.0% to 10.4% | 7.8% to 9.4% | 6.5% to 8.0% |
| 14-day to 365-day extended-wear sensor share (%) | 78.0% to 82.0% | 84.0% to 88.0% | 93.0% to 96.0% |
Table 4: Institutional Reimbursement & Channel Allocation Indicators for the Continuous Glucose Monitoring Systems Market (USD billion and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 10.8 billion | 2026 global net manufacturer revenue baseline |
| U.S. diagnosed & undiagnosed diabetes pool | 40.1 million people | CDC National Diabetes Statistics Report (2026 review) |
| UK NHS T2D annual FP10 sensor tariff | GBP 780.9 to 912.5 | NHS England London CGM Implementation Tariff (2025-2026) |
| DME Provider channel revenue, 2026 | USD 5.8 billion | 54.0% distribution channel allocation |
Data from the World Health Organization in November 2026 confirms that global diabetes prevalence has reached 830 million people while 59% of adults aged 30 and older remain untreated [4]. Payers evaluating non-invasive wearable glucometers and subcutaneous sensors prioritize platforms with sub-9% MARD accuracy that qualify for automated insulin dosing without fingerstick confirmation.
Analyst Perspective
"Health systems and commercial insurers no longer evaluate continuous glucose monitors as specialty hardware reserved for brittle Type 1 diabetes; they procure 14-day and 15-day disposable sensors as preventative metabolic consumables that cut acute ketoacidosis admissions. Manufacturers that pair sub-8.5% MARD biosensors with dual ketone detection and pharmacy benefit manager formulary access will capture the basal Type 2 and over-the-counter expansion wave through 2036."
- Anurag Sharma, Principal Consultant, Future Market Insights.
How is the continuous glucose monitoring systems market segmented?
The continuous glucose monitoring systems market is segmented by component architecture, wear duration, patient cohort, distribution channel, and connectivity integration. In 2026, Subcutaneous Disposable Sensors are projected at 58.0%, 10 to 14 Days Wearable Sensors at 64.0%, Type 1 Diabetes Intensive Insulin Patients at 72.0%, Durable Medical Equipment DME Providers at 54.0%, and Standalone Smartphone-Connected CGMs at 56.0%.
By component architecture: Subcutaneous Disposable Sensors, Transmitters and Reusable Transceivers, and Handheld Readers and Mobile Smartphone Apps.
By wear duration: 10 to 14 Days Wearable Sensors, 15 Days Plus Extended Wear Sensors, and 90 to 365 Days Implantable Sensors.
By patient cohort: Type 1 Diabetes Intensive Insulin Patients, Type 2 Diabetes Basal Insulin and Oral Agents, and Gestational Diabetes and Wellness Athletes.
By distribution channel: Durable Medical Equipment DME Providers, Retail Community Pharmacies, and Hospital Outpatient Endocrinology Clinics.
By connectivity integration: Standalone Smartphone-Connected CGMs, Automated Insulin Delivery AID Pump-Integrated CGMs, and Smart Insulin Pen MDI-Connected CGMs.
Why do Subcutaneous Disposable Sensors lead the component architecture category?
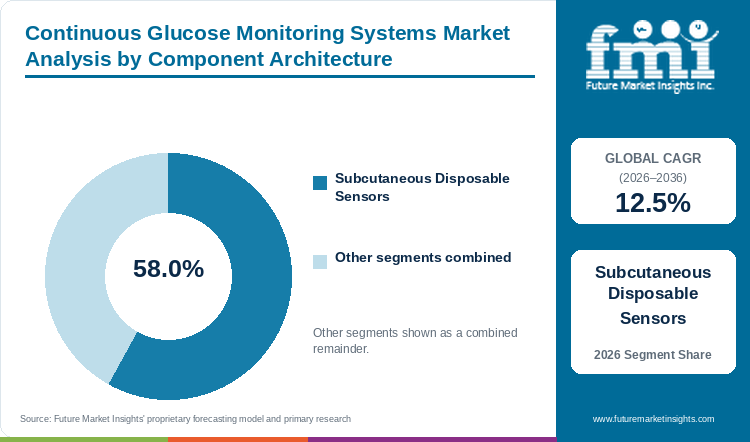
Subcutaneous Disposable Sensors hold an estimated 58.0% of component architecture demand in 2026, anchored by recurring 10-day to 15.5-day replacement schedules across active diabetes patients.
Table 5: Component Architecture Share for the Continuous Glucose Monitoring Systems Market (percentage share), 2026
| Component Architecture | Share (2026) |
|---|---|
| Subcutaneous Disposable Sensors | 58.0% |
| Other Segments Combined | 42.0%* |
| Total | 100.0% |
*Note: Remaining component architecture categories account for the balance of 2026 global continuous glucose monitoring systems demand.
Table 6: Component Architecture Leadership and Market Growth for the Continuous Glucose Monitoring Systems Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 12.5% |
| Leading Segment | Subcutaneous Disposable Sensors |
Subcutaneous disposable sensors lead commercial revenue generation since every active user must replace the sterile electrochemical filament every 10 to 15.5 days to prevent biofouling and signal drift. Demand for clinical electrochemical biosensors has accelerated as manufacturers integrate the Bluetooth transmitter and coin-cell battery directly into a single low-profile disposable housing. However, premature adhesive lifting during heavy perspiration and cutaneous isobornyl acrylate sensitivity still interrupt wear cycles for a subset of active patients.
- By component architecture, Subcutaneous Disposable Sensors are projected to account for 58.0% of category demand in 2026 since integrated all-in-one patch designs eliminate separate transmitter purchases.
- In January 2026, the American Diabetes Association updated its Standards of Care to recommend early continuous glucose sensor initiation at diagnosis while codifying interference thresholds for ascorbic acid and acetaminophen [5].
What sustains 10 to 14 Days Wearable Sensors leadership in the wear duration segment?
10 to 14 Days Wearable Sensors represent an estimated 64.0% of the wear duration category in 2026 as biweekly factory-calibrated patches dominate retail and DME prescription packs.
Ten-day to 14-day wearable sensors anchor prescription volume across North America and Europe because their biweekly replacement rhythm aligns cleanly with 28-day and 90-day pharmacy dispensing packs. A clinical review in Endocrinology and Metabolism in April 2025 reported that 14-day FreeStyle Libre 3 sensors achieve a 7.9% to 9.4% MARD while 10-day Dexcom G7 sensors record an 8.2% to 9.1% MARD [6]. Manufacturers of connected medical wearables nevertheless face growing competitive pressure from newly cleared 15-day epidermal patches and 365-day subcutaneous implants that reduce annual insertion frequency.
- Within the wear duration category, 10 to 14 Days Wearable Sensors are anticipated to capture a leading 64.0% share in 2026 owing to universal payer coding and established factory-calibrated production lines.
- Segment growth will gradually moderate over the second half of the forecast period as 15-day epidermal sensors and 365-day implantable fluorescence systems capture switches among patients seeking fewer annual skin insertions.
How do Type 1 Diabetes Intensive Insulin Patients lead the patient cohort category?
Type 1 Diabetes Intensive Insulin Patients account for an estimated 72.0% of patient cohort demand in 2026 due to universal statutory reimbursement and closed-loop insulin pump pairing.
Patients with Type 1 diabetes require continuous interstitial glucose readings and predictive low-glucose alarms every five minutes to titrate rapid-acting mealtime insulin and avoid life-threatening nocturnal hypoglycemia. Procurement of home diabetes management hardware remains heavily concentrated in this cohort because national health insurance agencies mandate continuous sensors for all pediatric and adult intensive-insulin users. Even so, alarm fatigue and high out-of-pocket copayments in underinsured markets can still slow continuous adherence among older adults.
- Type 1 Diabetes Intensive Insulin Patients are estimated to represent 72.0% of patient cohort demand in 2026 given mandatory sensor pairing with hybrid closed-loop insulin pumps.
- A November 2025 analysis of the MOBILE trial in BMJ Open Diabetes Research & Care showed that basal-insulin Type 2 diabetes patients using CGM lowered HbA1c from 9.1% to 8.0% within three months [7].
Why do Durable Medical Equipment DME Providers lead the distribution channel category?
Durable Medical Equipment DME Providers secure an estimated 54.0% of distribution channel value in 2026 through Medicare Part B supply allowances and contracted 90-day home shipments.
Durable medical equipment distributors retain the largest channel share because public payers and multi-state commercial health plans route recurring 90-day sensor and pump bundle shipments through contracted DME billing codes. At the same time, manufacturers are rapidly expanding retail pharmacy benefit manager contracts to trim prior-authorization delays from weeks to hours, as Medtronic secured United States pharmacy formulary access with Ascent Health Services and Zinc Health Services in January 2026 [8]. Strict audit documentation rules requiring six-month physician follow-up visits remain an operational hurdle for DME suppliers managing Medicare beneficiaries.
- Durable Medical Equipment DME Providers are forecast to secure 54.0% of distribution channel demand in 2026 supported by established Medicare Part B and home-delivery fulfillment contracts.
- Retail community pharmacies and direct-to-consumer e-commerce platforms are projected to gain substantial channel share through 2036 as over-the-counter biosensors and pharmacy-adjudicated prescriptions bypass traditional DME paperwork.
What gives Standalone Smartphone-Connected CGMs the leading position in connectivity integration?
Standalone Smartphone-Connected CGMs command an estimated 56.0% of connectivity integration demand in 2026 by streaming real-time Bluetooth readings directly to iOS and Android apps.
Standalone smartphone-connected systems lead adoption because patients can view real-time glucose trends and share telemetry with endocrinologists directly through iOS and Android applications without wearing an insulin pump. Direct mobile connectivity lowers upfront starter-kit costs for newly eligible Type 2 diabetes patients and wellness consumers who manage glucose through oral medications or lifestyle adjustments. Battery drain on older smartphones and operating-system update incompatibilities occasionally disrupt background Bluetooth alerts for standalone app users.
- Standalone Smartphone-Connected CGMs are expected to command 56.0% of connectivity integration demand in 2026 as mobile apps serve both multiple-daily-injection patients and over-the-counter users.
- In July 2026, Insulet Corporation launched its Omnipod 5 automated insulin delivery system and Omnipod Discover data platform in Spain with dual compatibility across Abbott and DexCom continuous glucose sensors [9].
What are the drivers, restraints, and opportunities in the continuous glucose monitoring systems market?
In the continuous glucose monitoring systems market, basal-insulin Type 2 reimbursement and closed-loop pump integration drive growth, skin adhesive detachment and sensor recalls restrain adherence, and dual glucose-ketone and hospital telemetry systems create new opportunities.
- Driver: Expanding public and commercial reimbursement for basal-insulin Type 2 diabetes patients and hybrid closed-loop pump users accelerates recurring biweekly sensor consumption.
- Restraint: Premature sensor adhesive detachment, cutaneous contact dermatitis from acrylate monomers, and lot-level sensor accuracy recalls restrain uninterrupted patient adherence.
- Opportunity: Commercializing dual glucose-ketone biosensors, 15-day to 365-day extended-wear platforms, and hospital electronic medical record telemetry creates new clinical revenue streams.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Clinical evidence proving that continuous glucose telemetry reduces all-cause mortality and cardiovascular hospitalizations is prompting payers to fund sensors across older adult and basal-insulin populations. Integration with automated insulin pumps further locks in long-term sensor reorder rates because closed-loop algorithms require uninterrupted five-minute interstitial glucose feeds to adjust basal insulin infusion. In June 2026, a Veterans Health Administration study of 8,423 older-onset Type 1 diabetes patients in Diabetes Care confirmed that initiating CGM reduced four-year all-cause mortality risk by 16% with an adjusted risk ratio of 0.84 [10]. These survival outcomes compel health ministries and private insurers to expand sensor formularies as a cost-saving preventative intervention.
Risk Assessment of the Continuous Glucose Monitoring Systems Market: Operational and Formulation Friction
Consistent sub-9% analytical accuracy across millions of mass-produced enzymatic filaments under variable skin hydration and compression conditions remains a persistent manufacturing challenge. While researchers evaluate non-invasive optical glucose monitors, commercial subcutaneous sensors still face occasional lot-level signal drift and skin irritation that trigger product replacements and regulatory scrutiny. In November 2025, the U.S. Food and Drug Administration published a medical device safety advisory after Abbott Diabetes Care initiated a voluntary correction addressing certain FreeStyle Libre 3 and FreeStyle Libre 3 Plus sensor lots exhibiting signal calibration drift [11]. Such quality events require manufacturers to invest heavily in automated inline amperometric calibration and hypoallergenic hydrocolloid adhesives.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Device manufacturers are capturing high-margin revenue avenues by extending continuous telemetry into inpatient hospital wards and connecting sensors with Bluetooth-enabled insulin pens for multiple-daily-injection users. Integration of epidermal sensors with connected smart insulin pens allows clinicians to track both dosing timestamps and glycemic excursions without requiring an expensive infusion pump. Filings in CMS MEARIS for the fiscal year 2026 cycle confirm that DexCom submitted its Breakthrough-designated G7 Hospital CGM System for New Technology Add-on Payment status across 757 inpatient diagnosis-related groups [12]. Dedicated inpatient reimbursement and over-the-counter retail distribution widen the addressable buyer base far beyond traditional outpatient endocrinology clinics.
Continuous Glucose Monitoring Systems Market by Country (2026 to 2036)
FMI country modeling indicates that the UAE leads continuous glucose monitoring systems expansion at a 14.6% CAGR through 2036 ahead of the USA at 14.0% and Australia at 13.3%. The UK follows at 12.8% and Canada tracks at 12.4%, while Germany at 12.2% and France at 11.8% outpace Japan at 11.4%.
Table 7: Country CAGR and Primary Growth Levers for the Continuous Glucose Monitoring Systems Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| UAE | 14.6% | Mandatory DHA periodic adult screening and 20.7% IDF adult diabetes prevalence |
| USA | 14.0% | Medicare LCD L33822 basal-insulin coverage, G7 15 Day launch, and OTC biosensors |
| Australia | 13.3% | Universal NDSS T1D pharmacy access and MSAC 1785 T2D subsidy evaluation |
| UK | 12.8% | NICE TA943 5-year NHS hybrid closed-loop rollout and FP10 pharmacy tariffs |
| Canada | 12.4% | Provincial public pharmacare expansion and November 2026 G7 15 Day launch |
| Germany | 12.2% | Statutory GKV Hilfsmittelverzeichnis coverage and 15-day pediatric clinical adoption |
| France | 11.8% | Universal SNDS LPPR reimbursement and 166,000+ LibreView telemonitoring users |
| Japan | 11.4% | PMDA May 2026 approval of MiniMed 780G and Simplera Sync for insulin-depleted T2D |
Source: Future Market Insights analysis
UAE Continuous Glucose Monitoring Systems Market Outlook (2026 to 2036)
Sales of continuous glucose monitors in the UAE are projected to expand at a leading 14.6% CAGR from 2026 to 2036 as mandatory preventive screening and comprehensive health insurance coverage accelerate sensor uptake. Rather than waiting for symptomatic complications, Emirati healthcare networks integrate continuous interstitial telemetry directly into Abu Dhabi and Dubai outpatient diabetes centers and Arabic-language virtual clinics. Under the Dubai Periodic Health Screening Guideline effective May 2024 for the 2026 strategy horizon, the Dubai Health Authority reported baseline adult prevalence at 13.7% diabetes and 16.2% prediabetes while mandating routine HbA1c screening across adults [13]. High summer ambient temperatures require desert-grade sweat-resistant patch adhesives to prevent premature sensor peeling during outdoor activity.
Key takeaway: In the UAE, mandatory adult metabolic screening and insurance-reimbursed virtual diabetes clinics are projected to drive leading adoption of factory-calibrated disposable sensors.
USA Continuous Glucose Monitoring Systems Market Outlook (2026 to 2036)
United States expenditure on continuous glucose monitoring systems is forecast to advance at a 14.0% CAGR between 2026 and 2036, driven by Medicare Part B basal-insulin coverage and rapid over-the-counter biosensor commercialization. American demand is uniquely shaped by dual distribution across contracted durable medical equipment suppliers and national retail pharmacy chains that fulfill 90-day sensor prescriptions with incretin therapies. The Centers for Disease Control and Prevention National Diabetes Statistics Report updated in September 2026 shows that 40.1 million Americans have diabetes and 115.2 million adults have prediabetes [14]. Prior-authorization paperwork and six-month physician visit rules still slow initial DME onboarding for rural primary care practices.
Key takeaway: In the USA, Medicare basal-insulin reimbursement and over-the-counter biosensor launches are anticipated to sustain high-volume sensor expansion across retail and DME channels.
Australia Continuous Glucose Monitoring Systems Market Outlook (2026 to 2036)
Sales of continuous glucose monitoring systems in Australia are anticipated to progress at a 13.3% CAGR through 2036 as federal health authorities evaluate expanding subsidized sensor access beyond Type 1 diabetes. Australian distribution operates through the centralized National Diabetes Services Scheme, which eliminates fragmented private insurer negotiations and streamlines community pharmacy collection nationwide. In February 2026, the Australian Medical Services Advisory Committee opened consultation on Application 1785 to evaluate subsidizing the Dexcom ONE+ system for insulin-dependent Type 2 and gestational diabetes cohorts [15]. Until formal federal Type 2 subsidy takes effect, out-of-pocket subscription costs continue to limit continuous wear among non-concessional older adults.
Key takeaway: In Australia, centralized National Diabetes Services Scheme pharmacy fulfillment and pending Type 2 diabetes subsidy expansions are expected to accelerate sensor penetration.
UK Continuous Glucose Monitoring Systems Market Outlook (2026 to 2036)
Continuous glucose monitoring systems expenditure in the UK is estimated to advance at a 12.8% CAGR from 2026 to 2036 under nationwide NHS hybrid closed-loop commissioning and primary care FP10 pharmacy prescribing. British Integrated Care Boards enforce strict cost-effectiveness tiers that favor competitively priced 10-day and 15-day factory-calibrated sensors dispensed directly through high-street community pharmacies. In May 2025, the NHS England London Diabetes Clinical Network published its Type 2 diabetes sensor implementation framework setting annual FP10 prescription tariffs at GBP 911.41 for Dexcom ONE+ and GBP 912.50 for FreeStyle Libre 2 Plus [16]. Regional variation in Integrated Care Board funding budgets nevertheless creates waiting lists for closed-loop pump pairing in several NHS trusts.
Key takeaway: In the UK, standardized NHS FP10 pharmacy tariffs and the five-year hybrid closed-loop rollout are estimated to anchor steady prescription sensor growth.
Canada Continuous Glucose Monitoring Systems Market Outlook (2026 to 2036)
Canadian demand for continuous glucose monitors is projected to record a 12.4% CAGR between 2026 and 2036 as provincial pharmacare programs widen reimbursement to basal-insulin Type 2 diabetes and extended-wear sensors launch nationwide. National market dynamics reflect a province-by-province public formulary framework across Ontario and Quebec as well as British Columbia and Alberta plus strong private employer health plan coverage. On October 28, 2026, DexCom announced that its Health Canada-authorized 15-day G7 sensor with an 8.0% MARD will launch across Canada in November 2026 with public and private insurance coverage [17]. Age-tiered prior-authorization criteria in certain Atlantic and prairie provinces still delay access for non-insulin Type 2 diabetes patients.
Key takeaway: In Canada, provincial pharmacare expansion and the November 2026 commercial rollout of 15-day wearable sensors are forecast to drive sustained adoption.
Germany Continuous Glucose Monitoring Systems Market Outlook (2026 to 2036)
Revenue from continuous glucose monitoring systems in Germany is expected to expand at a 12.2% CAGR through 2036, supported by statutory health insurance coverage under the federal Hilfsmittelverzeichnis medical aid directory. German diabetology practices emphasize rigorous clinical accuracy validation and closed-loop interoperability across pediatric and adult Disease Management Programs before prescribing new sensor architectures. In October 2026, investigators across four German pediatric centers in Ulm and Hannover published registration trial results in the Journal of Diabetes Science and Technology showing an 8.9% MARD for a 15-day sensor in youth aged 7 to 17 years [18]. Strict German statutory data-privacy regulations require local cloud server compliance before hospitals can deploy remote telemetry dashboards.
Key takeaway: In Germany, statutory GKV medical aid reimbursement and multicenter clinical validation of 15-day sensors are slated to support consistent demand growth.
France Continuous Glucose Monitoring Systems Market Outlook (2026 to 2036)
France is projected to achieve an 11.8% CAGR in the continuous glucose monitoring sector from 2026 to 2036 owing to universal national health insurance reimbursement and reimbursable remote diabetes telemonitoring programs. French endocrinologists utilize the national LPPR reimbursement list and the ETAPES digital telemonitoring framework to track ambulatory glucose profiles across large outpatient populations. In January 2025, the FACULTY study protocol in BMJ Open documented that approximately 166,000 individuals in France actively upload LibreView sensor telemetry linked to the SNDS national health database across a cohort exceeding 70,000 patients [19]. Mandatory annual physician renewal evaluations and strict CNEDiMTS price ceilings moderate average selling price expansion across French retail pharmacies.
Key takeaway: In France, universal LPPR reimbursement and cloud-connected remote telemonitoring across 166,000 active users are predicted to sustain high volume stability.
Japan Continuous Glucose Monitoring Systems Market Outlook (2026 to 2036)
Japanese spending across continuous glucose monitoring platforms is slated to expand at an 11.4% CAGR between 2026 and 2036 as regulatory clearances widen automated insulin delivery and sensor-augmented therapy into insulin-depleted Type 2 diabetes. Unlike Western retail pharmacy self-onboarding models, Japanese reimbursement under the national medical fee schedule requires hospital-based monthly physician consultations using the C150 glucose monitoring fee code. In July 2026, Japan's Pharmaceuticals and Medical Devices Agency published its May 2026 review approving Medtronic's MiniMed 780G Auto Mode with Simplera Sync sensors for Type 1 diabetes from age 2 and insulin-depleted Type 2 diabetes adults, achieving 84.9% Time in Range [20]. Frequent hospital visit requirements and demographic aging create demand for simplified, zero-calibration disposable patches.
Key takeaway: In Japan, PMDA expansion of automated insulin delivery to insulin-depleted Type 2 diabetes and hospital C150 fee reimbursement are expected to underpin steady growth.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the continuous glucose monitoring systems market?
DexCom Inc., Abbott Laboratories, Medtronic plc, Senseonics Holdings Inc., Ascensia Diabetes Care, F. Hoffmann-La Roche Ltd, Sinocare Inc., MicroTech Medical Hangzhou Co. Ltd, Nemaura Medical Inc., and Insulet Corporation represent the notable companies in the continuous glucose monitoring systems market.
Competitive positioning in the continuous glucose monitoring systems industry separates global integrated iCGM leaders, implantable and predictive AI biosensor specialists, and emerging extended-wear and tubeless AID innovators.
- Global Integrated iCGM & Biowearable Leaders: DexCom Inc. and Abbott Laboratories with Medtronic plc command global prescription volume through FDA-cleared 10-day to 15.5-day disposable sensors and closed-loop insulin pump platforms.
- Implantable & Predictive AI Biosensor Specialists: Senseonics Holdings Inc., Ascensia Diabetes Care, and F. Hoffmann-La Roche Ltd differentiate through 365-day subcutaneous fluorescence implants and AI-enabled 14-day predictive hypoglycemia platforms.
- Extended-Wear, Non-Invasive & AID Platform Innovators: Sinocare Inc. and MicroTech Medical Hangzhou Co. Ltd with Nemaura Medical Inc. and Insulet Corporation expand access through 15-day factory-calibrated patches and tubeless automated insulin pods.
Competitive Benchmarking: Continuous Glucose Monitoring Systems Market
Table 8: Competitive Benchmarking for the Continuous Glucose Monitoring Systems Market (qualitative capability ratings), 2026
| Company | Sensor Accuracy & Wear Duration | AID & Digital Interoperability | Payer & Pharmacy Access | Geographic Reach |
|---|---|---|---|---|
| DexCom Inc. | High | High | High | Global iCGM leader; G7 15 Day (8.0% MARD) in US/Canada and Stelo OTC |
| Abbott Laboratories | High | High | High | Over 8M global Libre users across 60+ countries; FDA iCGK Libre Duo 10 Day |
| Medtronic plc | High | High | High | Global MiniMed 780G and Smart MDI ecosystem with Simplera and Instinct sensors |
| Senseonics Holdings Inc. | High | Medium | Medium | US and European commercialization of Eversense 365 one-year implantable CGM |
| Ascensia Diabetes Care | Medium | Medium | Medium | Global diabetes distribution network; transitioned Eversense commercial ops in 2026 |
| F. Hoffmann-La Roche Ltd | High | Medium | High | European rollout of CE-marked 14-day AI-predictive Accu-Chek SmartGuide CGM |
| Sinocare Inc. | High | Medium | Medium | China and Europe 15-day iCan CGM expansion; US adult and pediatric ADA 2026 trials |
| MicroTech Medical Hangzhou Co. Ltd | Medium | Medium | Medium | CE-marked 15-day LinX and AiDEX CGM systems paired with Equil patch pump |
| Nemaura Medical Inc. | Low | Low | Low | Non-invasive daily-wear sugarBEAT adhesive skin patch and Miboko wellness platform |
| Insulet Corporation | High | High | High | Omnipod 5 tubeless AID system in 20+ countries compatible with Dexcom and Abbott CGMs |
Evaluation basis: Sensor Accuracy & Wear Duration evaluates published clinical MARD performance and cleared 10-day to 365-day sensor longevity, whereas AID & Digital Interoperability rates verified closed-loop pump and smartphone app integrations. Payer & Pharmacy Access measures Medicare DME, commercial PBM formulary, and national health service reimbursement coverage across major markets.
Key Developments in the Continuous Glucose Monitoring Systems Market
- Abbott Laboratories received U.S. FDA De Novo authorization on August 25, 2026 for its Libre Duo 10 Day system, establishing the first integrated continuous glucose and ketone monitoring iCGK standard for people aged 2 years and older [21].
- Senseonics Holdings Inc. initiated the European commercial launch of its CE-marked Eversense 365 one-year implantable continuous glucose monitoring system in Germany and Spain as well as Italy and Sweden on April 24, 2026 [22].
- Medtronic plc secured Medicare coverage and U.S. FDA clearance on February 2, 2026 for its MiniMed 780G automated insulin delivery system paired with the 15-day Instinct sensor made by Abbott for insulin-requiring Type 2 diabetes [23].
Key Players in the Continuous Glucose Monitoring Systems Market
Global Integrated iCGM & Biowearable Leaders
- DexCom Inc.
- Abbott Laboratories
- Medtronic plc
- Insulet Corporation
Implantable & Predictive AI Biosensor Specialists
- Senseonics Holdings Inc.
- Ascensia Diabetes Care
- F. Hoffmann-La Roche Ltd
- Sinocare Inc.
Extended-Wear & Alternative Patch Innovators
- MicroTech Medical Hangzhou Co. Ltd
- Nemaura Medical Inc.
Continuous Glucose Monitoring Systems Market - Report Scope
Table 9: Report Scope for the Continuous Glucose Monitoring Systems Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Component Architecture; Wear Duration; Patient Cohort; Distribution Channel; Connectivity Integration |
| Quantitative Units | USD Billion |
| Market Definition | Includes net manufacturer revenue from subcutaneous and implantable continuous glucose sensors, transmitters, and receivers |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | UAE, USA, Australia, UK, Canada, Germany, France, Japan, and additional regional markets |
| Key Companies Covered | DexCom Inc., Abbott Laboratories, Medtronic plc, Senseonics Holdings Inc., Ascensia Diabetes Care, Roche, Sinocare, MicroTech Medical, Nemaura Medical, Insulet Corporation |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up patient-to-sensor triangulation |
Continuous Glucose Monitoring Systems Market - Research Methodology
Table 10: Research Methodology for the Continuous Glucose Monitoring Systems Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with endocrinologists, certified diabetes care and education specialists, DME directors, and PBM formulary managers |
| Secondary Research | Analysis of FDA iCGM/iCGK clearances, CMS LCD L33822 and MEARIS filings, NICE TA943, NHS FP10 tariffs, PMDA reviews, and IDF/WHO registries |
| Market Sizing and Forecasting | Bottom-up active CGM user cohorts multiplied by annual sensor replacement frequency (24.3 to 36.5 units/year) and net realized OEM pricing |
| Country Forecasting Model | Country projections weight insulin-treated T1D/T2D prevalence, national public reimbursement eligibility, and OTC retail rollout timelines |
| Operational Benchmark Traceability | Patient pool, annual sensor shipment volumes, and MARD accuracy benchmarks in Tables 2, 3, and 4 cross-check global revenue totals |
| Data Triangulation and Validation | Revenue estimates isolate continuous interstitial glucose monitoring hardware and consumables and exclude standalone BGM strips and insulin pumps |
Continuous Glucose Monitoring Systems Market by Segments
Continuous Glucose Monitoring Systems Market segmented by Component Architecture:
- Subcutaneous Disposable Sensors
- Transmitters and Reusable Transceivers
- Handheld Readers and Mobile Smartphone Apps
- Integrated All-in-One Sensor-Transmitter Pods
Continuous Glucose Monitoring Systems Market segmented by Wear Duration:
- 10 to 14 Days Wearable Sensors
- 15 Days Plus Extended Wear Sensors
- 90 to 365 Days Implantable Sensors
- Short-Term 7-Day & Daily Wearable Patches
Continuous Glucose Monitoring Systems Market segmented by Patient Cohort:
- Type 1 Diabetes Intensive Insulin Patients
- Type 2 Diabetes Basal Insulin and Oral Agents
- Gestational Diabetes and Wellness Athletes
- Pediatric and Adolescent Diabetes Cohorts
- Hospital Inpatient Critical Care Patients
Continuous Glucose Monitoring Systems Market segmented by Distribution Channel:
- Durable Medical Equipment DME Providers
- Retail Community Pharmacies
- Hospital Outpatient Endocrinology Clinics
- Direct-to-Consumer Online & Mail-Order Pharmacies
Continuous Glucose Monitoring Systems Market segmented by Connectivity Integration:
- Standalone Smartphone-Connected CGMs
- Automated Insulin Delivery AID Pump-Integrated CGMs
- Smart Insulin Pen MDI-Connected CGMs
- Hospital EMR-Integrated Telemetry Systems
Continuous Glucose Monitoring Systems Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Centers for Medicare & Medicaid Services (CMS) (2026, February 11). Medicare Provider Compliance Tips: Glucose Monitoring Supplies (LCD L33822 and Policy Article A52464). CMS Medicare Learning Network.
- [2] DexCom, Inc. (2025, November 13). DexCom, Inc. - Dexcom G7 15 Day Continuous Glucose Monitoring System to Launch on Dec. 1 in the United States. DexCom Investor Relations.
- [3] International Diabetes Federation (IDF) (2025, April 7). Diabetes Facts and Figures: IDF Diabetes Atlas 11th Edition (2025). International Diabetes Federation.
- [4] World Health Organization (WHO) (2026, November 3). Diabetes Fact Sheet: Global Prevalence, Mortality, and Treatment Coverage. World Health Organization.
- [5] American Diabetes Association (ADA) Professional Practice Committee (2026, January 1). 7. Diabetes Technology: Standards of Care in Diabetes 2026. Diabetes Care 49(Supplement 1):S150-S165.
- [6] Kwon, S. Y., & Moon, J. S. (2025, April 8). Advances in Continuous Glucose Monitoring: Clinical Applications. Endocrinology and Metabolism (PMC12061739).
- [7] Martens, T. W., Beck, R. W., Griffen, C., et al. (2025, November 4). Rapid improvements in glycemic management with use of continuous glucose monitoring in adults with type 2 diabetes treated with basal insulin: 3-month analysis of the MOBILE study. BMJ Open Diabetes Research & Care (PMC12587997).
- [8] Medtronic plc (2026, January 7). Medtronic Diabetes Secures U.S. Pharmacy Formulary Access for MiniMed 780G System, Including Pump and New CGMs. Medtronic Newsroom.
- [9] Insulet Corporation (2026, July 6). Insulet Accelerates Global Growth with Launch of Omnipod 5 and Omnipod Discover in Spain, Expanding Access to Tubeless Diabetes Technology. Insulet Corporation Investor Relations.
- [10] Reaven, P. D., Macwan, S. A., McConeghy, K., et al. (2026, June 19). Continuous Glucose Monitoring Initiation Is Associated With Reduced Mortality in Older-Onset Type 1 Diabetes Patients. Diabetes Care 49(9):1589-1598.
- [11] U.S. Food and Drug Administration (FDA). (2025, November 24). Medical Device Recalls and Corrections: Continuous Glucose Monitoring Sensor Advisory. U.S. Food and Drug Administration.
- [12] U.S. Centers for Medicare & Medicaid Services (CMS MEARIS) (2025, October 7). Public Application Summary: Dexcom G7 Hospital Continuous Glucose Monitoring System (NTP241007GNM42). CMS MEARIS NTAP Publications.
- [13] Dubai Health Authority (DHA) (2024, May 11). Dubai Periodic Health Screening Guideline Version 1.0 (DHA/PHPD/CG-01). Government of Dubai Health Authority.
- [14] Centers for Disease Control and Prevention (CDC) (2026, September 16). National Diabetes Statistics Report: Prevalence of Diagnosed and Undiagnosed Diabetes in the United States. U.S. Department of Health and Human Services.
- [15] Australian Government Department of Health, Disability and Ageing (MSAC) (2026, February 25). MSAC Application 1785 Resubmission: Dexcom ONE+ Continuous Glucose Monitoring System for Insulin-Dependent Type 2 Diabetes. Office of Health Technology Assessment.
- [16] NHS England London Diabetes Clinical Network (2025, May 1). A Pan-London Implementation Document for Continuous Glucose Sensors for People Living with Type 2 Diabetes. NHS England.
- [17] DexCom, Inc. (2026, October 28). Dexcom G7 15 Day Continuous Glucose Monitoring System to Launch in Canada in November. DexCom, Inc. Investor Relations.
- [18] Link, M., Denzer, C., Biester, T., et al. (2026, October 14). Performance of a 15-Day Continuous Glucose Monitoring System in Children and Adolescents With Diabetes. Journal of Diabetes Science and Technology (PMC13669239).
- [19] Ajjan, R. A., Battelino, T., Seufert, J., et al. (2025, January 8). Do continuous glucose monitoring (CGM) metrics predict macrovascular and microvascular complications in diabetes? The FACULTY protocol of a retrospective real-world cohort study. BMJ Open (PMC11749619).
- [20] Pharmaceuticals and Medical Devices Agency (PMDA) Japan (2026, July 23). Review Summary: Medtronic MiniMed 700 Series Portable Insulin Infusion Pump and Simplera Sync CGM System. PMDA Japan.
- [21] Abbott Laboratories (2026, August 25). Abbott Receives FDA Authorization for World's First Dual Glucose-Ketone Sensing Technology for People with Diabetes. Abbott MediaRoom.
- [22] Senseonics Holdings, Inc. (2026, April 24). Senseonics Announces European Launch of Eversense 365, The World's First and Only One-Year CGM System. Senseonics Investor Relations.
- [23] Medtronic plc (2026, February 2). Medtronic Diabetes Expands Access to Full-Stack Insulin Delivery Solutions with Medicare Access and New FDA Clearances. Medtronic Newsroom.
- [24] Changsha Sinocare Inc. (2026, June 16). High-Performance iCan CGM System in US Adult and Pediatric Studies Presented at ADA 2026. Sinocare Inc. Corporate News.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations across all primary and secondary sources.
This Report Answers
- How large is the continuous glucose monitoring systems market in 2026 and what is forecast for 2036?
- Which basal-insulin reimbursement and closed-loop interoperability catalysts support demand for continuous glucose monitors?
- Why do Subcutaneous Disposable Sensors lead the component architecture category?
- Why do 10 to 14 Days Wearable Sensors lead the wear duration category globally?
- How do growth rates differ across the UAE and the USA compared with Australia and the UK?
- Which leading companies supply integrated iCGM patches versus implantable or predictive AI biosensors today?
- What limits sensor wear duration or causes premature detachment in the continuous glucose monitoring systems market?
- What should healthcare providers evaluate before selecting standalone versus AID-integrated continuous glucose sensors?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Component Architecture, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Component Architecture, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Component Architecture, 2026 to 2036
- Subcutaneous Disposable Sensors
- Transmitters and Reusable Transceivers
- Handheld Readers and Mobile Smartphone Apps
- Integrated All-in-One Sensor-Transmitter Pods
- Y-o-Y Growth Trend Analysis By Component Architecture, 2021 to 2025
- Absolute $ Opportunity Analysis By Component Architecture, 2026 to 2036
- Global Market Analysis and Forecast, By Wear Duration, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Wear Duration, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Wear Duration, 2026 to 2036
- 10 to 14 Days Wearable Sensors
- 15 Days Plus Extended Wear Sensors
- 90 to 365 Days Implantable Sensors
- Short-Term 7-Day & Daily Wearable Patches
- Y-o-Y Growth Trend Analysis By Wear Duration, 2021 to 2025
- Absolute $ Opportunity Analysis By Wear Duration, 2026 to 2036
- Global Market Analysis and Forecast, By Patient Cohort, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Patient Cohort, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Patient Cohort, 2026 to 2036
- Type 1 Diabetes Intensive Insulin Patients
- Type 2 Diabetes Basal Insulin and Oral Agents
- Gestational Diabetes and Wellness Athletes
- Pediatric and Adolescent Diabetes Cohorts
- Hospital Inpatient Critical Care Patients
- Y-o-Y Growth Trend Analysis By Patient Cohort, 2021 to 2025
- Absolute $ Opportunity Analysis By Patient Cohort, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Durable Medical Equipment DME Providers
- Retail Community Pharmacies
- Hospital Outpatient Endocrinology Clinics
- Direct-to-Consumer Online & Mail-Order Pharmacies
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Connectivity Integration, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Connectivity Integration, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Connectivity Integration, 2026 to 2036
- Standalone Smartphone-Connected CGMs
- Automated Insulin Delivery AID Pump-Integrated CGMs
- Smart Insulin Pen MDI-Connected CGMs
- Hospital EMR-Integrated Telemetry Systems
- Y-o-Y Growth Trend Analysis By Connectivity Integration, 2021 to 2025
- Absolute $ Opportunity Analysis By Connectivity Integration, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- By Country
- Market Attractiveness Analysis
- By Country
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- By Country
- Market Attractiveness Analysis
- By Country
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- By Country
- Market Attractiveness Analysis
- By Country
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- By Country
- Market Attractiveness Analysis
- By Country
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- By Country
- Market Attractiveness Analysis
- By Country
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- By Country
- Market Attractiveness Analysis
- By Country
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- By Country
- Market Attractiveness Analysis
- By Country
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- UAE
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Component Architecture
- By Wear Duration
- By Patient Cohort
- By Distribution Channel
- By Connectivity Integration
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- DexCom Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Abbott Laboratories
- Medtronic plc
- Senseonics Holdings Inc.
- Ascensia Diabetes Care
- F. Hoffmann-La Roche Ltd
- Sinocare Inc.
- MicroTech Medical Hangzhou Co. Ltd
- Nemaura Medical Inc.
- Insulet Corporation
- DexCom Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Component Architecture, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Wear Duration, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Patient Cohort, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Connectivity Integration, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Component Architecture, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Wear Duration, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Patient Cohort, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Connectivity Integration, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Component Architecture, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Wear Duration, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Patient Cohort, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Connectivity Integration, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Component Architecture, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Wear Duration, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Patient Cohort, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Connectivity Integration, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Component Architecture, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Wear Duration, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Patient Cohort, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Connectivity Integration, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Component Architecture, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Wear Duration, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Patient Cohort, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Connectivity Integration, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Component Architecture, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Wear Duration, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Patient Cohort, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Connectivity Integration, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Component Architecture, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Wear Duration, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Patient Cohort, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Connectivity Integration, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Component Architecture, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Component Architecture, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Component Architecture
- Figure 6: Global Market Value Share and BPS Analysis by Wear Duration, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Wear Duration, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Wear Duration
- Figure 9: Global Market Value Share and BPS Analysis by Patient Cohort, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Patient Cohort, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Patient Cohort
- Figure 12: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Distribution Channel
- Figure 15: Global Market Value Share and BPS Analysis by Connectivity Integration, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Connectivity Integration, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Connectivity Integration
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Component Architecture, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Component Architecture, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Component Architecture
- Figure 32: North America Market Value Share and BPS Analysis by Wear Duration, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Wear Duration, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Wear Duration
- Figure 35: North America Market Value Share and BPS Analysis by Patient Cohort, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Patient Cohort, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Patient Cohort
- Figure 38: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Distribution Channel
- Figure 41: North America Market Value Share and BPS Analysis by Connectivity Integration, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Connectivity Integration, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Connectivity Integration
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Component Architecture, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Component Architecture, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Component Architecture
- Figure 48: Latin America Market Value Share and BPS Analysis by Wear Duration, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Wear Duration, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Wear Duration
- Figure 51: Latin America Market Value Share and BPS Analysis by Patient Cohort, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Patient Cohort, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Patient Cohort
- Figure 54: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 57: Latin America Market Value Share and BPS Analysis by Connectivity Integration, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Connectivity Integration, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Connectivity Integration
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Component Architecture, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Component Architecture, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Component Architecture
- Figure 64: Western Europe Market Value Share and BPS Analysis by Wear Duration, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Wear Duration, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Wear Duration
- Figure 67: Western Europe Market Value Share and BPS Analysis by Patient Cohort, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Patient Cohort, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Patient Cohort
- Figure 70: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 73: Western Europe Market Value Share and BPS Analysis by Connectivity Integration, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Connectivity Integration, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Connectivity Integration
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Component Architecture, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Component Architecture, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Component Architecture
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Wear Duration, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Wear Duration, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Wear Duration
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Patient Cohort, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Patient Cohort, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Patient Cohort
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Connectivity Integration, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Connectivity Integration, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Connectivity Integration
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Component Architecture, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Component Architecture, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Component Architecture
- Figure 96: East Asia Market Value Share and BPS Analysis by Wear Duration, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Wear Duration, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Wear Duration
- Figure 99: East Asia Market Value Share and BPS Analysis by Patient Cohort, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Patient Cohort, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Patient Cohort
- Figure 102: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 105: East Asia Market Value Share and BPS Analysis by Connectivity Integration, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Connectivity Integration, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Connectivity Integration
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Component Architecture, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Component Architecture, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Component Architecture
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Wear Duration, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Wear Duration, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Wear Duration
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Patient Cohort, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Patient Cohort, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Patient Cohort
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Connectivity Integration, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Connectivity Integration, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Connectivity Integration
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Component Architecture, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Component Architecture, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Component Architecture
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Wear Duration, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Wear Duration, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Wear Duration
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Patient Cohort, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Patient Cohort, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Patient Cohort
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Connectivity Integration, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Connectivity Integration, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Connectivity Integration
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the continuous glucose monitoring systems market in 2026, and what is forecast for 2036?
FMI estimates that global continuous glucose monitoring systems valuation stood at USD 9.6 billion in 2025 and reached USD 10.8 billion in 2026. Total sector revenue is on course to hit USD 35.1 billion by 2036 as basal-insulin Type 2 diabetes and over-the-counter users adopt disposable biosensors.
What is the CAGR for the continuous glucose monitoring systems market from 2026 to 2036?
The continuous glucose monitoring systems sector is projected to expand at a 12.5% CAGR over the 2026 to 2036 window, adding USD 24.3 billion across outpatient DME and retail pharmacy channels.
Which component architecture segment leads the continuous glucose monitoring systems market?
Subcutaneous Disposable Sensors hold an estimated 58.0% of component architecture demand in 2026 since single-use enzymatic filaments require 24 to 36 replacement insertions per patient annually.
Which wear duration segment leads the continuous glucose monitoring systems market?
10 to 14 Days Wearable Sensors represent an estimated 64.0% of the wear duration category in 2026 owing to broad FDA and CE-mark clearances and standardized biweekly pharmacy refill packs.
Which country has a notable growth outlook during the assessment period?
The UAE leads national expansion projections at a 14.6% CAGR through 2036, driven by mandatory periodic adult diabetes screening and high private health insurance coverage.
Who are the key players in the market?
DexCom Inc. and Abbott Laboratories supply global demand with Medtronic plc and Senseonics Holdings Inc. plus Ascensia Diabetes Care. Additional active participants include F. Hoffmann-La Roche Ltd and Sinocare Inc., while MicroTech Medical Hangzhou Co. Ltd, Nemaura Medical Inc., and Insulet Corporation also compete.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
