

- Market Size (2026)
- USD 380.1 Mn
- Forecast (2036)
- USD 668.0 Mn
- CAGR (2026 to 2036)
- 5.8%
How big is Cornbread Market in 2026?
Starting from USD 359.3 million in 2025, the global cornbread market valuation advanced to USD 380.1 million in 2026, with projections pointing toward USD 668.0 million by 2036 at a CAGR of 5.8%.
The global cornbread market was valued at USD 359.3 million in 2025 and is estimated to reach USD 380.1 million in 2026. The market is projected to reach USD 668.0 million by 2036, expanding at a compound annual growth rate (CAGR) of 5.8% between 2026 and 2036. Classic sweet and buttermilk formats hold a projected 44.2% share of 2026 product demand, since broad household and casual-dining menu pairing moves both retail trays and foodservice pans. Demand for prepared cornbread is supported by back-of-house kitchen labor shortages, as scratch sheet-pan mixing burns skilled baker overtime and pan-scraping waste that thaw-and-serve formats eliminate outright [1]. That labor math explains why cornbread compounds slower than the packaged bread market at 9.5% CAGR, because cornbread still competes against near-zero-cost homemade mixes in its core Southern grocery aisle. The growth in foodservice adoption is also visible in product launches, as Rich Products introduced Cornbread Poppers with hot-honey filling in August 2026 to give operators a rapid oven-heated snackable side [8]. Grupo Bimbo's July 2025 commitment to remove artificial colorants across its portfolios by end-2026 also clears the reformulation path for clean-label golden cornmeal lines [21]. Operators buy the format that strips an overtime shift from the plate, and 72-hour amylopectin staling control decides who keeps the contract.
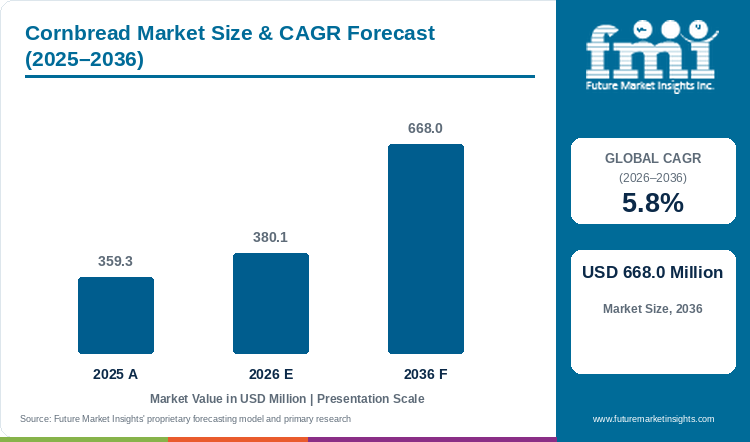
Key Market Trends & Insights
- By product type: Broad household and casual-dining menu pairing gives Classic Sweet & Buttermilk a projected 44.2% share of the product type segment in 2026.
- By format: Fresh / In-Store Bakery is expected to hold 41.8% of the format segment in 2026 through warm perimeter grocery merchandising beside hot rotisserie chicken and soup bars.
- By claim / nature: Because wheat-cornmeal blends lower ingredient cost and boost muffin crown height, Conventional formulations are estimated to represent 63.4% of the claim / nature segment in 2026.
- By packaging format: Clamshell Multipacks are anticipated to secure 38.6% of the packaging format segment in 2026 to protect friable cornmeal edges from crushing during pallet transit.
- By sales channel: Impulse cross-merchandising in perimeter bakery and deli islands places Supermarkets & Hypermarkets at a forecast 45.3% share of the sales channel segment in 2026.
Regional Highlights
- Top national expansion: Commercial turnover in the USA is forecast to grow at a 6.4% CAGR through 2036, driven by nationwide foodservice adoption of thaw-and-serve muffins and honey-filled cornbread poppers.
- Broader country progression: Demand in the UK is projected to rise at a 6.1% CAGR ahead of South Korea at 5.9% and the UAE at 5.6%, while Japan is forecast to register a 4.2% CAGR through 2036.
Market Size & Forecast
Table 1: Market Size and Forecast for the Cornbread Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 359.3 million |
| Estimated Market Size in 2026 | USD 380.1 million |
| Projected Market Size by 2036 | USD 668.0 million |
| CAGR, 2026 to 2036 | 5.8% |
| Added Revenue, 2026 to 2036 | USD 287.9 million |
Perimeter bakery department shrink caused by rapid crumb drying governs how supermarket chains source and finish commercial cornbread. Because degerminated yellow cornmeal lacks viscoelastic gluten proteins, scratch-baked sheet pans lose free moisture within 48 hours on ambient tables and force store managers to take steep evening markdowns. Retail food-market data updated by the USDA Economic Research Service in August 2026 confirm that grocery stores captured 56.2% of food-at-home sales in 2025 while warehouse clubs and supercenters held 26.4% [2]. Bakery directors across those high-volume grocery formats protect store margins by ordering frozen scoop batters and pre-baked mini-loaves and sourdough bakery items that hold frozen for 180 days and thaw in small afternoon batches.
Bakery-Output and Foodservice-Portion Sizing
Table 2: Bakery-Output and Foodservice-Portion Sizing for the Cornbread Market (USD million and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD million) | 359.3 | 380.1 | 668.0 |
| Commercial finished cornbread volume (thousand MT) | 76.8 to 79.4 | 80.0 to 82.5 | 126.5 to 130.5 |
| Portioned cornbread servings per day (million) | 3.7 to 3.9 | 3.9 to 4.1 | 6.1 to 6.4 |
| Realized wholesale price per kg (USD) | 4.50 to 4.70 | 4.58 to 4.78 | 5.10 to 5.30 |
Operational note: Daily serving ranges reflect standard 57-gram (2-ounce) mini-loaves and filled muffin portions across retail clamshell packs and institutional foodservice steam-table trays.
Preserving soft interior crumb texture across a 14-day ambient retail display window determines whether a commercial baker wins national supermarket distribution. Unlike low-moisture bakery products engineered for dry shelf stability, cornbread depends on cultured buttermilk solids and invert-syrup humectants to bind free water and stop crown cracking during pallet transit. Industrial bakeries that validate two-week ambient crumb softness command wholesale realizations of USD 4.58 to USD 4.78 per kilogram in 2026 while cutting retailer unsaleable return credits.
Per Capita & Outlet Spending Sizing
Table 3: Per Capita and Outlet Spending Indicators for the Cornbread Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Addressable retail and dining consumer base (million) | 610.0 | 622.0 | 745.0 |
| Spend per 1,000 consumers (USD) | 589.0 | 611.1 | 896.6 |
| Annual spend per stocking outlet (USD) | 2,450 to 2,750 | 2,580 to 2,890 | 4,100 to 4,550 |
| Frozen thaw-and-serve foodservice share (%) | 33.5% to 35.5% | 34.8% to 36.8% | 41.0% to 44.0% |
Table 4: Retail Bakery & Foodservice Procurement Indicators for the Cornbread Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 380.1 million | 2026 global revenue baseline |
| Supermarket bakeries & casual-dining outlets | 138,500 outlets | Global grocery in-store bakery and restaurant registry |
| Market spend per stocking outlet | USD 2,744 | Annualized finished cornbread expenditure |
| Supermarkets & hypermarkets revenue, 2026 | USD 172.2 million | 45.3% sales channel allocation |
Ticket-time compression during peak dinner shifts drives restaurant conversion from scratch cornmeal mixing to frozen thaw-and-serve foodservice cases. Broadline foodservice distributors co-deliver individually quick-frozen cornbread muffins and hot-honey poppers and par baked bread dinner rolls on consolidated cold-chain trucks. Because line cooks can finish pre-portioned cornbread in under five minutes in convection ovens with zero batter mixing, frozen thaw-and-serve foodservice share rises from 34.8%–36.8% in 2026 toward 41.0%–44.0% by 2036.
Analyst Perspective
"Commercial repeat orders in the cornbread market depend on crumb moisture survival after frozen transit and retail ambient display. Bakery manufacturers that engineer humectant-stabilized buttermilk recipes inside crush-resistant multipack clamshells and thaw-and-serve foodservice cases will capture durable grocery and restaurant contracts."
- Nandini Roy Choudhury, Principal Analyst at Future Market Insights
How is the cornbread market segmented?
The cornbread market is segmented by product type, format, claim / nature, packaging format, sales channel, and region. In 2026, Classic Sweet & Buttermilk is projected at 44.2% of the product type segment, Fresh / In-Store Bakery at 41.8% of the format segment, Conventional at 63.4% of the claim / nature segment, Clamshell Multipacks at 38.6% of the packaging format segment, and Supermarkets & Hypermarkets at 45.3% of the sales channel segment.
By product type: Classic Sweet & Buttermilk, Savory & Cheese-Stuffed, Honey-Glazed & Filled Bites, and Whole-Grain & Stone-Ground.
By format: Fresh / In-Store Bakery, Frozen Thaw-and-Serve and Frozen Par-Baked and Ambient Packaged.
By claim / nature: Conventional, Clean Label, Gluten-Free, and Organic.
By packaging format: Clamshell Multipacks, Family & Sheet Pans, Bulk Foodservice Cases, and Single-Serve Wraps.
By sales channel: Supermarkets & Hypermarkets, Foodservice Distributors, Artisan & Specialty Bakeries, and Convenience & Online Grocery.
Why does Classic Sweet & Buttermilk lead the product type segment?
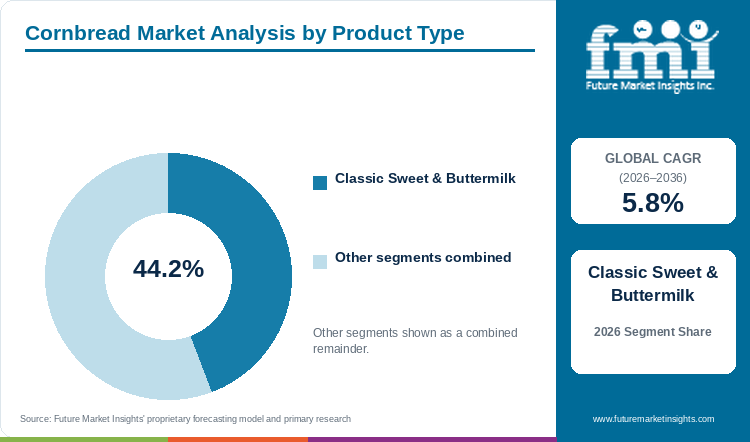
Classic Sweet & Buttermilk is projected to account for 44.2% of the product type segment in 2026 because balanced buttermilk sweetness pairs across both smokehouse platters and retail deli dinners.
Table 5: Product Type Share for the Cornbread Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Classic Sweet & Buttermilk | 44.2% |
| Other Segments Combined | 55.8% |
| Total | 100.0% |
Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type Leadership and Market Growth for the Cornbread Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.8% |
| Leading Segment | Classic Sweet & Buttermilk |
Supermarket perimeter bakeries and barbecue casual-dining chains anchor their core assortment on classic sweet and cultured-buttermilk cornbread because its golden crumb and mild lactic tang pair across all dinner occasions. Cultured buttermilk acidity tenderizes composite wheat-and-maize batters while complementing frozen dough rolls on smokehouse and chili menus.
- Classic Sweet & Buttermilk is projected to capture 44.2% of the product type segment in 2026 due to high SKU velocity across family deli meals and restaurant combo platters.
- Composite wheat-corn cake trials published in Frontiers in Nutrition in April 2026 demonstrated that 10% corn fraction incorporation raises dietary fiber from 0.58% to 2.15% and boosts iron, zinc, and magnesium while earning the highest consumer sensory acceptability score of 4.933 [3].
How does Fresh / In-Store Bakery retain leadership in the format segment?
Fresh / In-Store Bakery is expected to hold 41.8% of the format segment in 2026 through warm perimeter grocery table placement beside rotisserie chicken and soup bars.
Supermarket in-store bakeries bake or finish cornbread mini-loaves and muffins throughout the day from frozen scoop batters and quarter-sheets to capture warm-from-the-oven aroma. Merchandising freshly finished trays directly beside hot rotisserie chicken and soup bars drives impulse dinner basket additions while use yellow corn flour blends calibrated for clean, crumble-free slicing.
- Fresh / In-Store Bakery is expected to hold 41.8% of the format segment in 2026 because warm perimeter table placement commands higher retail unit pricing than ambient center-store loaves.
- Physicochemical baking trials published in Frontiers in Nutrition in June 2026 on corn-flour-substituted loaf breads confirmed that 15% corn flour replacement preserves soft crumb elasticity and consumer hedonic scores on par with 100% wheat controls [4].
Why does Conventional anchor the claim / nature segment?
Conventional formulations are estimated to represent 63.4% of the claim / nature segment in 2026 owing to composite wheat-cornmeal batter stability and mainstream retail unit pricing.
Mainstream commercial cornbread formulations blend yellow cornmeal with enriched wheat flour and whole liquid egg leavened by double-acting sodium aluminum sulfate baking powder. Because U.S. Food and Drug Administration gluten-free labeling rules under 21 CFR 101.91 require strict below-20-ppm gluten verification [5], conventional wheat-cornmeal batters avoid segregated allergen ovens and keep retail pack prices competitive with tortilla mix and dinner rolls.
- Conventional formulations are estimated to represent 63.4% of the claim / nature segment in 2026 through superior muffin crown height and lower batch ingredient cost.
- Eliminating xanthan gum binders and certified gluten-free rice-starch replacers under FDA 21 CFR 101.91 rules saves wholesale bakeries 22% to 30% in dry-ingredient batch costs [5].
What makes Clamshell Multipacks the leading packaging format segment?
Clamshell Multipacks are anticipated to capture 38.6% of the packaging format segment in 2026 by shielding friable cornmeal crowns from crushing during pallet transit.
High-cornmeal batters bake into a tender, friable crumb that fractures easily when stacked inside flexible polyethylene bags. Supermarket chains and warehouse clubs therefore mandate rigid thermoformed PET compartment clamshells holding 4 to 12 mini-loaves or muffins that protect crown edges during palletized freight and reclose tightly in household kitchens.
- Clamshell Multipacks are anticipated to account for 38.6% of the packaging format segment in 2026 via crush-resistant perimeter stacking and reclosable moisture seals.
- Extruded corn-flour research published in the Journal of the Science of Food and Agriculture in July 2026 showed that modified corn flour with a 556.89-micron particle diameter and golden yellowness (b = 32.59) achieves a 13.49 g/g water absorption index and 77% sensory acceptability in cornbread [6].
Why do Supermarkets & Hypermarkets lead the sales channel segment?
Supermarkets & Hypermarkets are forecast to generate 45.3% of the sales channel segment in 2026 via perimeter in-store bakery and prepared-deli cross-merchandising.
Perimeter cross-merchandising between prepared rotisserie meals and in-store bakery tables keeps supermarkets and hypermarkets ahead of single-channel bakeries. Full-line grocery chains position multipack cornbread clamshells directly beside hot chicken warmers and chilled deli soup islands to raise average evening basket spend. In February 2025, Flowers Foods completed its acquisition of Simple Mills to broaden its natural baking and snacking footprint across 30,000 retail grocery doors [7]. That national retail footprint enables supermarket chains to synchronize afternoon bake-off finishing with online curbside grocery pickup orders.
- Supermarkets & Hypermarkets are forecast to capture 45.3% of the sales channel segment in 2026 through private-label perimeter programs and fourth-quarter holiday display spikes.
- Flowers Foods' February 2025 acquisition of Simple Mills expanded branded specialty baking distribution across more than 30,000 supermarket and natural grocery stores in the USA [7].
What are the drivers, restraints, and opportunities in the cornbread market?
Back-of-house kitchen labor shortages and perimeter supermarket deli merchandising propel cornbread demand through 2036, whereas 72-hour amylopectin staling and wheat-egg-dairy allergen controls restrain ambient shelf life.
- Driver: Back-of-house culinary labor shortages compel restaurants and caterers to replace scratch-baked pans with frozen thaw-and-serve cornbread portions.
- Restraint: Rapid amylopectin retrogradation and strict wheat/egg/milk allergen labeling limit ambient shelf life and export turnaround.
- Opportunity: Filled cornbread bites and savory jalapeño-cheddar muffins along with cornbread burger buns unlock all-day snacking and QSR sandwich carriers.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Eliminating back-of-house batter mixing and sheet-pan portioning labor is steering quick-service and casual-dining chains toward pre-filled, bite-sized cornbread formats. Multi-unit fried-chicken and smokehouse operators require portable sides that move straight from freezer cases to convection ovens without skilled baking staff. In August 2026, Rich Products Corporation launched Cornbread Poppers featuring a sweet hot-honey flavored filling engineered for thaw-and-serve or rapid oven finishing across foodservice channels [8]. Co-distributing portioned cornbread bites and frozen baked goods trims kitchen prep waste below 2% and captures all-day snacking check add-ons.
Risk Assessment of the Cornbread Market: Operational and Formulation Friction
Rapid amylopectin starch retrogradation and multi-allergen cross-contact rules remain the primary operational restraints limiting ambient cornbread shelf life. Because maize amylose and amylopectin recrystallize quickly after cooling, untreated loaves turn dry and crumbly within 72 hours on unrefrigerated store tables. Standard cornbread batters also combine wheat gluten and whole egg and buttermilk dairy allergens, which under U.S. Food and Drug Administration food-allergen guidance updated in March 2026 require explicit label declarations and cross-contact sanitation controls [9]. Commercial plants producing frozen bakery and ambient retail loaves must therefore dose invert-syrup humectants while running segregated allergen washdowns.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Steady growth in independent restaurant traffic is opening new menu opportunities for commercial bakeries to reposition cornbread from a dinner side into an all-day sandwich carrier. Fast-casual chains are introducing scored cornbread burger buns and jalapeño-cheddar slider rolls to differentiate menus without adding back-of-house prep steps. Second-quarter fiscal 2026 earnings released by US Foods Holding Corp. in August 2026 confirmed that net sales rose 4.5% to USD 10.5 billion as independent restaurant case volume expanded 5.1% [10]. Pairing those foodservice formats with functional fiber bakery formulations that maintain six-month frozen stability helps industrial bakers win high-margin limited-time menu contracts.
Cornbread Market by Country (2026 to 2036)
International demand patterns follow the expansion of smokehouse and fried-chicken restaurant chains and frozen bake-off counters in modern supermarkets. The USA leads global growth at a 6.4% CAGR from 2026 to 2036, followed by the UK at 6.1% and South Korea at 5.9%, whereas Japan progresses at a 4.2% CAGR due to strong competition from domestic steamed corn buns.
Table 7: Country CAGR and Primary Growth Levers for the Cornbread Market (CAGR percentage and operational drivers), 2026 to 2036
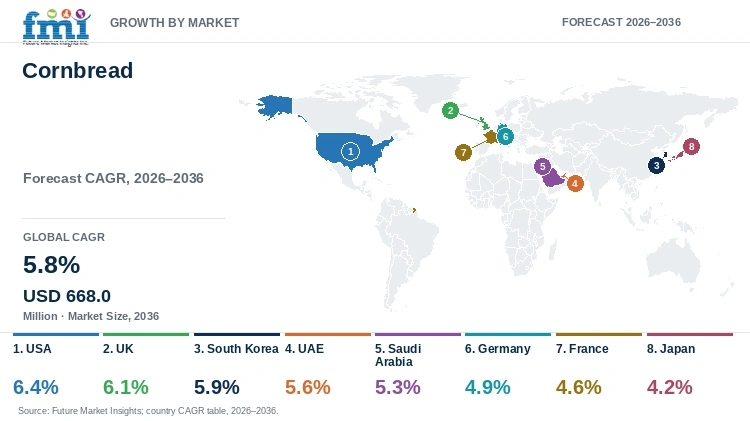
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 6.4% | USD 1.41T food-away-from-home dining and club-store multipack mini-loaf velocity |
| UK | 6.1% | Barbecue casual-dining expansion and thaw-and-serve hospitality side orders |
| South Korea | 5.9% | Convenience-store sweet-corn bakery snack rotation and imported frozen batter adoption |
| UAE | 5.6% | QSR and hotel buffet catering supported by cold-chain HRI retail and bakery imports |
| Saudi Arabia | 5.3% | Multinational chicken/barbecue QSR growth and SFDA Arabic-labeled frozen bakery supply |
| Germany | 4.9% | Supermarket bake-off counter diversification and EUR 18.7B organic store-brand demand |
| France | 4.6% | Themed casual-dining chains and EU organic gluten-free specialty bakery placement |
| Japan | 4.2% | Ready-to-eat convenience bakery demand moderated by domestic steamed corn-bun competition |
Source: Future Market Insights analysis
USA Cornbread Market Outlook (2026 to 2036)
Dedicated capital investment in automated accompaniment-bread lines and year-round barbecue foodservice demand set the USA apart from international markets and drive a leading 6.4% CAGR from 2026 to 2036. Supermarket in-store bakeries and casual-dining chains across the USA are replacing scratch sheet-pan mixing with frozen scoop batters and hot-honey cornbread bites to cut kitchen labor costs. In July 2025, Governor Brian Kemp announced that King's Hawaiian will invest USD 54 million to expand its Hall County bakery facility in Georgia with a new production line [11]. Warehouse clubs and grocery delis also cross-merchandise 12-count mini-loaf clamshells beside hot rotisserie chicken, though 72-hour ambient staling shrink still restrains unpackaged loaf formats.
Key takeaway: In the USA, high food-away-from-home spending and perimeter grocery deli cross-merchandising are projected to sustain leading demand for portioned thaw-and-serve cornbread.
UK Cornbread Market Outlook (2026 to 2036)
Rollouts of Texas-style smokehouse and rotisserie-chicken casual dining chains anchor commercial cornbread expansion in the UK, where category sales are projected to grow at a 6.1% CAGR through 2036. Unlike the USA where cornbread is a traditional household staple, demand in the UK is led by hospitality groups and supermarket meal-deal counters seeking differentiated side breads. Provisional 2025 trade statistics published by the UK Department for Environment, Food & Rural Affairs in April 2026 show that UK food and drink imports rose 6% to GBP 67.8 billion across temperature-controlled supply chains [12]. Strict prepacked-for-direct-sale allergen rules requiring bolded wheat, egg, and dairy declarations on every pack nevertheless add labeling overhead for in-store bake-off operators.
Key takeaway: In the UK, casual dining smokehouse menus and supermarket meal-accompaniment fixtures are expected to drive recurring orders for frozen thaw-and-serve cornbread portions.
South Korea Cornbread Market Outlook (2026 to 2036)
Shoppers in South Korea treat cornbread as a sweet afternoon coffee pastry rather than a savory dinner accompaniment, creating a distinct product profile across urban bakery chains. Metropolitan café franchises and convenience stores in Seoul and Busan merchandise cream-cheese and sweet-corn filled mini loaves wrapped in single-serve pillow pouches. Trade data in the May 2026 USDA Foreign Agricultural Service South Korea Food Processing Ingredients Annual report (KS2026-0013) confirm that domestic bakeries rely heavily on imported cornmeal and frozen bakery intermediates [13]. Rapid café and convenience-store menu rotation supports a 5.9% CAGR in South Korea from 2026 to 2036, though foreign-exchange swings on imported grain and butterfat periodically compress co-packer margins.
Key takeaway: In South Korea, convenience-store bakery snacking and café dessert innovation are projected to favor sweet-filled, single-serve cornbread formats.
UAE Cornbread Market Outlook (2026 to 2036)
International hotel buffet catering and Western casual-dining franchises in Dubai and Abu Dhabi drive steady institutional cornbread orders across the UAE. Because extreme outdoor heat accelerates butterfat oxidation and crumb drying during ambient delivery, hospitality commissaries rely almost entirely on imported frozen thaw-and-serve cases. Market tracking in the October 2026 USDA Foreign Agricultural Service United Arab Emirates Retail Foods Annual report confirms sustained expansion across UAE hospitality and retail foodservice channels in 2025 and 2026 [14]. Broadline distributors importing halal-certified frozen cornbread muffins in minus-18-degree-Celsius reefer containers sustain a 5.6% CAGR in the UAE through 2036, balanced against elevated cold-storage utility costs.
Key takeaway: In the UAE, expanding tourism and franchise dining are forecast to anchor HRI cold-chain imports of halal-certified frozen cornbread.
Saudi Arabia Cornbread Market Outlook (2026 to 2036)
Rapid expansion of multinational fried-chicken and barbecue quick-service franchises across Riyadh and Jeddah acts as the primary engine lifting cornbread demand in Saudi Arabia. Franchise operators bundle warm honey-glazed cornbread muffins with family chicken buckets to differentiate combo meals from flatbread competitors. Sector analysis in the August 2026 USDA Foreign Agricultural Service Saudi Arabia Retail Foods Annual report (SA2026-0013) documents continued store and foodservice outlet growth across the Kingdom [15]. Import regulations updated by the Saudi Food and Drug Authority (SFDA) in August 2026 require authenticated health certificates and Arabic allergen labels on imported bakery cases [16], supporting a 5.3% CAGR in Saudi Arabia through 2036 for compliant suppliers.
Key takeaway: In Saudi Arabia, multinational QSR chicken and barbecue chain expansion is anticipated to drive frozen cornbread imports that satisfy SFDA Arabic labeling mandates.
Germany Cornbread Market Outlook (2026 to 2036)
Deep consumer loyalty to dense rye and spelt sourdough loaves limits sweet pan cornbread in Germany, channeling commercial demand instead into savory par-baked Maisbrot and certified gluten-free organic trays. Discount and full-line supermarkets across Germany are expanding in-store bake-off stations and private-label organic bakery fixtures to capture gluten-avoidant shoppers. Retail tracking in a January 2026 USDA Foreign Agricultural Service report on Germany (GM2026-0003) shows that organic retail sales in Germany reached an estimated EUR 18.7 billion in 2025 during wider discount private-label organic assortments [17]. Supplying par-baked maize loaves that finish in eight-minute store oven cycles supports a 4.9% CAGR in Germany from 2026 to 2036, though hard-discounter price caps restrain supplier margins.
Key takeaway: In Germany, supermarket bake-off counter diversification and private-label organic store brands are estimated to support steady uptake of par-baked and gluten-free cornbread.
France Cornbread Market Outlook (2026 to 2036)
Daily household preference for crusty artisan wheat baguettes keeps cornbread a targeted specialty item in France, where commercial sales are forecast to expand at a 4.6% CAGR from 2026 to 2036. Volume in France is anchored by metropolitan burger and smokehouse bistros ordering frozen cornbread sides and supermarket sans-gluten organic bays. Market figures in the February 2025 USDA Foreign Agricultural Service report on the European Union organics sector (GM2025-0003) confirm that France ranks among the two largest organic food markets in the European Union across supermarkets and specialist bio stores [18]. Frozen bakery manufacturers therefore formulate butter-enriched par-baked cornbread fingers free from synthetic preservatives to win foodservice and bio retail listings across France.
Key takeaway: In France, burger casual dining and organic gluten-free retail fixtures are predicted to sustain targeted demand for butter-enriched par-baked cornbread.
Japan Cornbread Market Outlook (2026 to 2036)
Direct competition from domestic soft white wheat buns topped with Hokkaido sweet corn (kon-pan) and steamed corn cakes moderates commercial cornbread growth in Japan to a 4.2% CAGR through 2036. Because urban consumers in Japan reject dry or coarse cornmeal textures, traditional crumbly Southern-style cornbread struggles to earn repeat grocery purchases. Retail analysis in the November 2025 USDA Foreign Agricultural Service Japan Retail Foods Annual report (JA2025-0048) shows that retail food sales in Japan totaled USD 193 billion, with convenience stores and supermarkets prioritizing single-serve ready-to-eat items for compact households [19]. Domestic bakery co-packers in Tokyo and Osaka consequently formulate individually wrapped mini cornbread loaves with trehalose and invert syrup to preserve soft crumb moisture in chilled convenience-store displays.
Key takeaway: In Japan, single-serve convenience-store packaging and casual-dining chains are projected to guide niche adoption of moisture-stabilized portioned cornbread.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the cornbread market?
Rich Products Corporation, US Foods (Chef's Line / Metro Deli), Bake'n Joy Foods, Flowers Foods, Grupo Bimbo, King's Hawaiian, Vandemoortele, Aryzta, Lantmännen Unibake, and St Pierre Groupe are the notable companies in the cornbread market.
Competitive positioning in the cornbread market is determined by how manufacturers solve the trade-off between five-day ambient crumb softness and zero-prep kitchen convenience. Specialized foodservice producers engineer sour-cream buttermilk muffins and honey-filled poppers for restaurant commissaries and supermarket in-store bakeries. At the same time, national direct-store-delivery bread groups and international frozen bake-off platforms compete by bundling multipack cornbread clamshells with high-velocity perimeter bakery and QSR bun programs.
- Foodservice & In-Store Bakery Cornbread Specialists: Rich Products Corporation and US Foods with Bake'n Joy Foods supply finished thaw-and-serve cornbread muffins and filled poppers as well as cornbread buns.
- National Packaged & Specialty Retail Bakery Networks: Flowers Foods and Grupo Bimbo with King's Hawaiian and St Pierre Groupe operate high-velocity retail bread aisles and perimeter bakery tables.
- International Frozen & Bake-Off Bakery Platforms: Vandemoortele and Aryzta with Lantmännen Unibake deliver industrial frozen dough, par-baked bread carriers, and multi-country foodservice distribution.
Competitive Benchmarking: Cornbread Market
Table 8: Competitive Benchmarking for the Cornbread Market (qualitative capability ratings), 2026
| Company | Thaw-and-Serve Crumb Moisture Retention | In-Store & Retail Multipack Reach | Foodservice Portion & Case Customization | Geographic Reach |
|---|---|---|---|---|
| Rich Products Corporation | High | High | High | USA, Canada, and global foodservice networks |
| US Foods (Chef's Line) | High | Medium | High | USA broadline restaurant and hospitality distribution |
| Bake'n Joy Foods | High | High | High | USA in-store bakery and foodservice channels |
| Flowers Foods | High | High | Medium | USA national direct-store-delivery and retail grocery |
| Grupo Bimbo | High | High | High | Americas, Europe, and Asia packaged bakery operations |
| King's Hawaiian | High | High | Medium | USA and international sweet-baked retail channels |
| Vandemoortele | High | Medium | High | Western Europe and USA frozen bakery channels |
| Aryzta | High | Medium | High | Europe, Asia-Pacific, and QSR convenience bakery networks |
| Lantmännen Unibake | Medium | Medium | High | Nordics, Europe, and international foodservice markets |
| St Pierre Groupe | Medium | High | Medium | UK, USA, and Europe perimeter bakeries |
Capability assessment basis: Tier rankings evaluate documented humectant and freeze-thaw crumb softness retention and portion-controlled foodservice case formats.
Key Developments in the Cornbread Market
- In August 2026, Rich Products Corporation launched Cornbread Poppers with hot-honey flavored filling, offering foodservice operators a thaw-and-serve or rapid oven-heated snackable side [8].
- In February 2025, Vandemoortele acquired Italy frozen-bakery specialist Lizzi across four production plants, expanding its Europe and transatlantic artisan frozen bread and pastry manufacturing footprint [20].
- In July 2025, Grupo Bimbo announced its global commitment to remove artificial colorants across all bread and sweet-baked product portfolios by the end of 2026, accelerating clean-label golden cornmeal bakery reformulation [21].
Key Players in the Cornbread Market
Foodservice & In-Store Bakery Cornbread Specialists
- Rich Products Corporation
- US Foods (Chef's Line / Metro Deli)
- Bake'n Joy Foods
National Packaged & Specialty Retail Bakery Networks
- Flowers Foods
- Grupo Bimbo
- King's Hawaiian
- St Pierre Groupe
International Frozen & Bake-Off Bakery Platforms
- Vandemoortele
- Aryzta
- Lantmännen Unibake
Cornbread Market - Report Scope
Table 9: Report Scope for the Cornbread Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Format; Claim / Nature; Packaging Format; Sales Channel |
| Quantitative Units | USD Million |
| Market Definition | Includes commercial manufacturer and in-store bakery revenue from finished ready-to-eat, frozen thaw-and-serve, and par-baked cornbread loaves, muffins, mini-loaves, filled bites, and cornbread sandwich buns. Category Scope Note: Excludes dry yellow/white cornmeal, dry retail/foodservice cornbread baking mixes, unbaked liquid/frozen batters sold by weight, and corn tortillas. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, UK, South Korea, UAE, Saudi Arabia, Germany, France, Japan, and additional countries in the full report |
| Key Companies Covered | Rich Products Corporation, US Foods, Bake'n Joy Foods, Flowers Foods, Grupo Bimbo, King's Hawaiian, Vandemoortele, Aryzta, Lantmännen Unibake, St Pierre Groupe |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Cornbread Market - Research Methodology
Table 10: Research Methodology for the Cornbread Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with supermarket in-store bakery directors, commercial frozen-bakery R&D managers, broadline foodservice distributors, and QSR culinary buyers to validate portion weights, case pricing, and shrink rates. |
| Secondary Research | Analysis of USDA Economic Research Service food-expenditure releases, USDA Foreign Agricultural Service retail and grain annuals, FDA 21 CFR 101.91 and allergen rules, and corporate bakery expansion filings. |
| Market Sizing and Forecasting | Bottom-up daily portion volumes (57-gram equivalent units) and commercial bakery tonnage reconciled against top-down supermarket perimeter bakery and foodservice side-bread expenditure from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight food-away-from-home expenditure shares, casual-dining and QSR outlet expansion, cold-chain bake-off penetration, and statutory allergen/Arabic labeling gates across eight national markets. |
| Operational Benchmark Traceability | Finished tonnage, daily portion counts, and per-outlet spending indicators in Tables 2, 3, and 4 trace to USDA ERS food spending benchmarks, club-store multipack specifications, and broadline foodservice releases. |
| Data Triangulation and Validation | Revenue estimates are cross-checked against commercial frozen and fresh bakery case shipments while excluding dry cornmeal, dry baking mixes, unbaked batters, and tortillas to prevent category overlap. |
Cornbread Market by Segments
Cornbread Market segmented by Product Type:
- Classic Sweet & Buttermilk
- Savory & Cheese-Stuffed
- Honey-Glazed & Filled Bites
- Whole-Grain & Stone-Ground
Cornbread Market segmented by Format:
- Fresh / In-Store Bakery
- Frozen Thaw-and-Serve
- Frozen Par-Baked
- Ambient Packaged
Cornbread Market segmented by Claim / Nature:
- Conventional
- Clean Label
- Gluten-Free
- Organic
Cornbread Market segmented by Packaging Format:
- Clamshell Multipacks
- Family & Sheet Pans
- Bulk Foodservice Cases
- Single-Serve Wraps
Cornbread Market segmented by Sales Channel:
- Supermarkets & Hypermarkets
- Foodservice Distributors
- Artisan & Specialty Bakeries
- Convenience & Online Grocery
Cornbread Market by Region
- North America
- USA
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- UK
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] USDA Economic Research Service. (2026, June 11). Total U.S. food spending reached $2.51 trillion in 2025. U.S. Department of Agriculture Charts of Note.
- [2] USDA Economic Research Service. (2026, August 17). Retailing & Wholesaling - Retail Trends - Economic Research Service. U.S. Department of Agriculture Food Markets & Prices.
- [3] Nyefene, J. D., & Glago, P. (2026, April 30). Nutritional composition, sensory acceptability and shelf-life evaluation of wheat-corn chaff composite cake. Frontiers in Nutrition, 13, 1808630 (PubMed Central PMC13171324 / PMID 42146076).
- [4] Lemos, I. M. L., de Sousa, T. R., Martins, C. P. C., et al. (2026, June 12). Physicochemical and functional modifications induced by purple corn flour (Zea mays L.) and their sensory implications for loaf breads. Frontiers in Nutrition, 13, 1850874 (PubMed PMID 42370346).
- [5] U.S. Food and Drug Administration. (2026, March 17). Gluten-Free Labeling of Foods - FDA. Center for Food Safety and Applied Nutrition.
- [6] Silva, S. T. P., Magalhães, G. L., Caliari, M., & Soares Júnior, M. S. (2026, July 18). Recovered residue from corn flake processing and its application in modified flours and arepa bread. Journal of the Science of Food and Agriculture (PubMed PMID 42470219).
- [7] Flowers Foods, Inc. (2025, February 21). FLOWERS FOODS, INC. COMPLETES ACQUISITION OF SIMPLE MILLS. Flowers Foods Investor Newsroom.
- [8] Rich Products Corporation. (2026, August 24). New Rich's Filled Donut Bites: Strawberry Cheesecake & Cornbread Popper with Hot Honey Flavored Filling. Rich Products USA Foodservice Resources.
- [9] U.S. Food and Drug Administration. (2026, March 11). Food Allergies - FDA. Center for Food Safety and Applied Nutrition.
- [10] US Foods Holding Corp. (2026, August 6). US Foods Reports Second Quarter Fiscal Year 2026 Earnings. US Foods Investor Relations Newsroom.
- [11] Office of the Governor of Georgia. (2025, July 17). King's Hawaiian to Invest $54 Million in Hall County Expansion. State of Georgia Official Press Releases.
- [12] UK Department for Environment, Food & Rural Affairs. (2026, April 30). UK trade in Food, Feed and Drink, 2025 provisional - GOV.UK. GOV.UK Accredited Official Statistics.
- [13] USDA Foreign Agricultural Service. (2026, May 27). South Korea: Food Processing Ingredients Annual. Global Agricultural Information Network (GAIN Report KS2026-0013).
- [14] USDA Foreign Agricultural Service. (2026, October 19). United Arab Emirates: Retail Foods Annual. Global Agricultural Information Network (GAIN).
- [15] USDA Foreign Agricultural Service. (2026, August 31). Saudi Arabia: Retail Foods Annual. Global Agricultural Information Network (GAIN Report SA2026-0013).
- [16] Saudi Food and Drug Authority. (2026, August 21). Conditions & Requirements for Importing Food to Saudi Arabia. SFDA Official Regulations Portal.
- [17] USDA Foreign Agricultural Service. (2026, January 29). Large Retail Chains Support Record Year for German Organic Sales. Global Agricultural Information Network (GAIN Report GM2026-0003).
- [18] USDA Foreign Agricultural Service. (2025, February 7). European Union: EU Organics Market Begins to Recover. Global Agricultural Information Network (GAIN Report GM2025-0003).
- [19] USDA Foreign Agricultural Service. (2025, November 19). Japan: Retail Foods Annual | USDA Foreign Agricultural Service. Global Agricultural Information Network (GAIN Report JA2025-0048).
- [20] Vandemoortele NV. (2025, February 14). PRESS RELEASE - Vandemoortele acquires Lizzi in Italy, a specialty player in frozen Bakery. Vandemoortele Corporate Newsroom.
- [21] Grupo Bimbo, S.A.B. de C.V. (2025, July 29). We are committed to removing artificial colorants from all our products by the end of 2026. Grupo Bimbo Official Press Releases.
- [22] St Pierre Groupe. (2026, May 15). Limited-Edition Spicy Brioche Buns to Boost Category Sales. St Pierre Trade Newsroom.
- [23] ARYZTA AG. (2026, January 22). Full year 2025 targets achieved; Revenue growth & improved performance expected in 2026; New €40m bun bakery in Portugal. ARYZTA Investor Center Ad Hoc Announcements.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the cornbread market in 2026 and what is forecast for 2036?
- Which foodservice labor and retail perimeter-bakery pressures support cornbread demand?
- Why does Classic Sweet & Buttermilk lead the product type segment?
- Why does Fresh / In-Store Bakery lead the format segment globally?
- How do growth rates differ across the USA and the UK as well as South Korea and the UAE?
- Which leading companies supply finished cornbread and thaw-and-serve muffins across frozen bakery lines today?
- What limits adoption or supplier switching in the cornbread market?
- What should grocery and restaurant buyers evaluate before purchasing commercial cornbread?
Frequently Asked Questions
How big is the cornbread market in 2026, and what is forecast for 2036?
Commercial cornbread sales are projected to reach USD 380.1 million in 2026 from a 2025 baseline of USD 359.3 million. Global turnover is forecast to hit USD 668.0 million by 2036 as supermarkets and restaurant chains adopt pre-portioned loaves and filled muffin bites.
What is the CAGR for the cornbread market from 2026 to 2036?
Global revenue is forecast to advance at a 5.8% CAGR from 2026 to 2036, adding USD 287.9 million in cumulative sales across grocery in-store bakeries and foodservice distributors.
Which product type segment leads the cornbread market?
Broad menu pairing across barbecue platters and household dinners gives Classic Sweet & Buttermilk a projected 44.2% share of the product type segment in 2026.
Which format segment leads the cornbread market?
Fresh / In-Store Bakery is expected to hold 41.8% of the format segment in 2026 through perimeter bakery counter merchandising that preserves warm crust aroma and moist interior crumb.
Which country has a notable growth outlook during the assessment period?
Commercial sales in the USA are forecast to expand at a leading 6.4% CAGR through 2036, driven by USD 1.41 trillion food-away-from-home dining expenditure and rapid restaurant conversion to thaw-and-serve cornbread portions.
Who are the key players in the market?
Rich Products Corporation, US Foods (Chef's Line / Metro Deli), Bake'n Joy Foods, Flowers Foods, Grupo Bimbo, King's Hawaiian, Vandemoortele, Aryzta, Lantmännen Unibake, and St Pierre Groupe lead commercial supply across retail and foodservice bakery networks.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Classic Sweet & Buttermilk
- Savory & Cheese-Stuffed
- Honey-Glazed & Filled Bites
- Whole-Grain & Stone-Ground
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Format, 2026 to 2036
- Fresh / In-Store Bakery
- Frozen Thaw-and-Serve
- Frozen Par-Baked
- Ambient Packaged
- Y-o-Y Growth Trend Analysis By Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Format, 2026 to 2036
- Global Market Analysis and Forecast, By Claim / Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Claim / Nature, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Claim / Nature, 2026 to 2036
- Conventional
- Clean Label
- Gluten-Free
- Organic
- Y-o-Y Growth Trend Analysis By Claim / Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Claim / Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Packaging Format, 2026 to 2036
- Clamshell Multipacks
- Family & Sheet Pans
- Bulk Foodservice Cases
- Single-Serve Wraps
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Foodservice Distributors
- Artisan & Specialty Bakeries
- Convenience & Online Grocery
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- UK
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- UAE
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Format
- By Claim / Nature
- By Packaging Format
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Rich Products Corporation
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- US Foods (Chef's Line)
- Bake'n Joy Foods
- Flowers Foods
- Grupo Bimbo
- King's Hawaiian
- Vandemoortele
- Aryzta
- Lantmännen Unibake
- St Pierre Groupe
- US Foods (Chef's Line / Metro Deli)
- Rich Products Corporation
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


