

- Market Size (2026)
- USD 874.2 Mn
- Forecast (2036)
- USD 1752.1 Mn
- CAGR (2026 to 2036)
- 7.2%
How big is Focaccia Market in 2026?
The global focaccia market demonstrated steady progress from USD 812.5 million in 2025 to USD 874.2 million in 2026, building toward a targeted valuation of USD 1,752.1 million by 2036 at a CAGR of 7.2%.
Menu price inflation across fast-casual restaurants and skilled-baker shortages inside supermarket bakeries are prompting operators to replace standard pan loaves with pre-baked olive-oil focaccia carriers that command premium sandwich pricing. To serve this shift toward automated bake-off supply, in February 2026, Lantmännen Group reported close to SEK 3 billion in two-year food and grain capital investments covering European bakery acquisitions and flatbread capacity expansions [1]. Because of this foodservice and retail menu upgrade, classic rosemary commands a forecast 38.4% of 2026 product-type demand as café chains pair herb-infused multigrain and seeded loaves and savory flatbreads with hot panini presses. Category consumption trends show the global focaccia industry valuation advancing beyond its 2025 mark of USD 812.5 million to post a 2026 market size of USD 874.2 million. Between 2026 and 2036, global focaccia market value scales to a projected USD 1,752.1 million on a 7.2% CAGR, adding USD 877.9 million in ten-year expansion. However, rapid ambient staling and olive-oil migration into paperboard packs remain restraining factors that limit unrefrigerated shelf life.
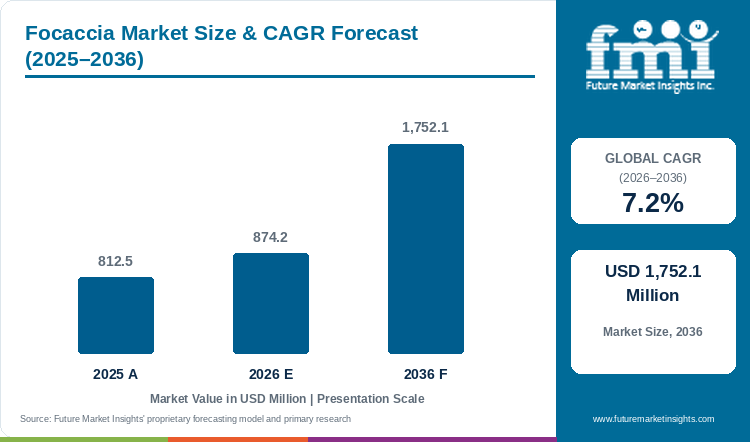
Key Market Trends & Insights
- By product type: In 2026, classic rosemary is forecast to hold a 38.4% Product Type share, linked to dual utilization as a pre-sliced sandwich carrier and warm bakery counter loaf.
- By claim / nature: In 2026, Conventional is anticipated to generate 53.6% of Claim / Nature volume, owing to high-protein wheat flour elasticity during high-hydration proofing.
- By format: Across formats, Fresh is expected to account for 29.2% in 2026, driven by crisp olive-oil crust aroma at supermarket bake-off counters.
- By packaging format: In 2026, Multipack is estimated to supply a 34.6% Packaging Format share, supported by household lunchbox portioning and twin-pack panini merchandising.
- By sales channel: In 2026, supermarkets & hypermarkets are projected to absorb a 39.4% Sales Channel share, enabled by combined in-store bakery and chilled deli fixture placement.
Regional Highlights
- North America QSR expansion: USA foodservice and grocery bakery demand leads the eight evaluated nations with an 8.1% yearly growth rate through 2036 on USD 1.41 trillion out-of-home dining.
- Europe & Asia bake-off growth: UK grocers register a 7.7% annual growth rate ahead of convenience counters in Germany (7.4%) and hospitality venues in the UAE (7.1%), while convenience stores in Japan post a 5.6% annual rate.
Market Size & Forecast
Table 1: Market Size and Forecast for the Focaccia Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 812.5 million |
| Estimated Market Size in 2026 | USD 874.2 million |
| Projected Market Size by 2036 | USD 1,752.1 million |
| CAGR, 2026 to 2036 | 7.2% |
| Added Revenue, 2026 to 2036 | USD 877.9 million |
Consumer spending growth on away-from-home lunch dining is forcing multi-unit café chains and hotel commissaries to speed up sandwich assembly without hiring back-of-house bakers. Specifically, Economic Research Service data released by the USDA in June 2026 showed that food away from home captured 56.3% of total USA food expenditures in 2025 at USD 1.41 trillion out of USD 2.51 trillion [2]. Because restaurant kitchens need zero-prep bread carriers to serve this lunch traffic, chain procurement teams contract par-baked bread carriers such as 30-by-40-centimeter sheet focaccia and pre-split sandwich squares with calibrated crumb thickness.
Commercial Bakery Output and Foodservice Carrier Sizing
Table 2: Commercial Bakery Output and Foodservice Carrier Sizing for the Focaccia Market (USD million and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD million) | 812.5 | 874.2 | 1,752.1 |
| Commercial focaccia volume (thousand MT) | 248.0 to 258.0 | 266.8 to 277.5 | 518.0 to 542.0 |
| Retail & foodservice portion volume (billion units) | 1.9 to 2.1 | 2.1 to 2.3 | 4.0 to 4.4 |
| Average wholesale realization per portion (USD) | 0.4 to 0.4 | 0.4 to 0.4 | 0.4 to 0.5 |
Operational note: Portion volume ranges reflect 110-gram to 200-gram individual retail and thaw-and-serve focaccetta units as well as 600-gram to 1,200-gram foodservice sheet slabs.
High hourly wages for night-shift scratch bakers and limited floor space inside urban grocery stores prevent most retailers from fermenting 80%-hydration focaccia doughs on site. When supermarkets attempt scratch production of olive-oil flatbreads, inconsistent proofing times lead to uneven tray heights and high day-end waste. This operational bottleneck generates strong demand for centrally baked frozen bakery items that complete bulk fermentation at the factory and finish in six minutes inside store deck ovens. In addition to this labor savings, portion-calibrated frozen slabs let store staff bake small batches matching midday customer footfall.
Per Capita & Bakery Outlet Sizing
Table 3: Per Capita and Outlet Spending Indicators for the Focaccia Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global population (billion) | 8.2 | 8.3 | 9.0 |
| Market value per 1,000 people (USD) | 99.1 | 105.3 | 194.7 |
| Annual focaccia procurement per outlet (USD) | 1,650 to 1,920 | 1,780 to 2,060 | 3,150 to 3,640 |
| Frozen & par-baked B2B contract share (%) | 56.0% to 60.0% | 58.5% to 62.5% | 68.0% to 72.0% |
Table 4: Supermarket Bakery & QSR Outlet Indicators for the Focaccia Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 874.2 million | 2026 global valuation baseline |
| Global bake-off retail & QSR outlets | 465,000 outlets | Supermarket in-store bakery & fast-casual registry |
| Average value per outlet | USD 1,880.0 | Annualized wholesale focaccia procurement |
| Supermarkets & hypermarkets allocation | USD 344.4 million | 39.4% sales-channel segment share |
Retailer delisting of artificial mould inhibitors such as calcium propionate is creating a shelf-life challenge for ambient and chilled packaged focaccia. Because high water activity and surface olive oil accelerate microbial spoilage in sealed film bags, bakers must find natural ways to extend code life across supermarket distribution centers. To solve this spoilage risk, commercial stone-hearth lines dose sourdough starter cultures into focaccia sponges so organic fermentation acids lower dough pH and inhibit mould growth naturally. However, extra-virgin olive oil price volatility still pressures wholesale contract margins.
Analyst Perspective
"Focaccia earns permanent supermarket shelf space and QSR sandwich-carrier contracts only when crumb resilience survives cold-chain distribution and rapid toaster finishing. Industrial bakers that deliver pre-sliced, portion-calibrated frozen slabs with verified allergen labeling capture multi-country foodservice rollouts."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the focaccia market segmented?
The focaccia market is segmented by product type, claim / nature, format, packaging format, and sales channel. In 2026, classic rosemary is projected at 38.4%, conventional at 53.6%, fresh at 29.2%, multipack at 34.6%, and supermarkets & hypermarkets at 39.4%.
By product type: Classic rosemary, topped (tomato, olive, onion), filled / sandwich focaccia, and mini & snacking focaccia.
By claim / nature: Conventional, clean label, organic, gluten-free, and high-protein / fortified.
By format: Fresh, frozen, ambient packaged, chilled, and par-baked / thaw-and-serve.
By packaging format: Multipack, single-serve, family / loaf pack, and bulk foodservice.
By sales channel: Supermarkets & hypermarkets, artisan & specialty bakeries, convenience & forecourt, online & DTC, and foodservice distributors.
Why does Classic rosemary lead product type demand?
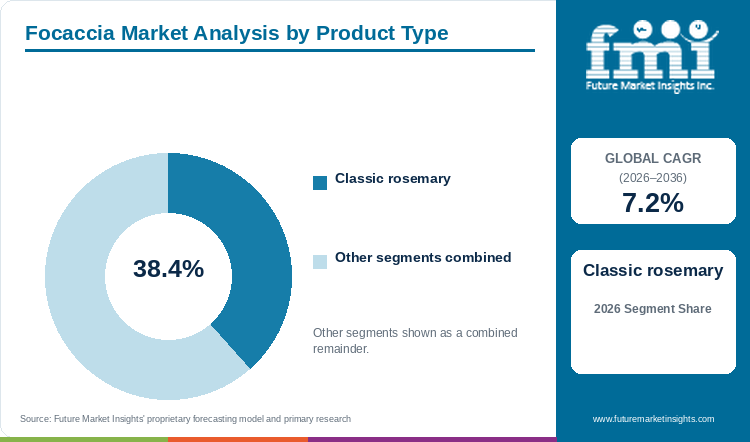
In 2026, classic rosemary is forecast to hold a 38.4% Product Type share, driven by cross-occasion versatility across sandwich and table-bread service.
Table 5: Product Type Share for the Focaccia Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Classic rosemary | 38.4% |
| Other Segments Combined | 61.6%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type Leadership and Market Growth for the Focaccia Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.2% |
| Leading Segment | Classic rosemary |
Foodservice distributors and supermarket bakery buyers aim to minimize SKU complexity by stocking one savory flatbread that works across both hot sandwich stations and dinner bread baskets. Because a sea-salt and rosemary-needle crust pairs with cured meats or soups without suffering the wet-topping spoilage seen on tomato-and-cheese slabs, high-hydration rosemary loaves baked beside clean-label bread lines achieve lower retail markdown waste.
- In 2026, classic rosemary is forecast to hold a 38.4% Product Type share, owing to lower waste rates and simpler allergen labeling than cheese- or charcuterie-topped variants.
- For instance, in October 2025, Vandemoortele's professional Banquet d'Or and Lanterna catalog documented pre-baked frozen rosemary focaccia slabs and pre-portioned focaccetta units engineered to reduce prep waste in hotel and restaurant kitchens [3].
What sustains Conventional within the claim / nature category?
In 2026, Conventional is anticipated to generate 53.6% of Claim / Nature volume, attributable to wheat-gluten gas retention in high-hydration doughs.
Automated dimpling pins and 80%-water-absorption mixing troughs subject focaccia doughs to intense mechanical stress that tears weak or gluten-free flour networks. Because conventional high-protein wheat flour provides reliable gliadin and glutenin elasticity at lower raw-material cost than certified organic grain, industrial sheet lines rely on conventional recipes for mainstream QSR and grocery contracts.
- In 2026, Conventional is anticipated to generate 53.6% of Claim / Nature volume, supported by predictable proofing tolerance and lower unit ingredient cost.
- At the same time, allergen compliance guidance updated by the USA FDA in January 2025 under Edition 5 enforces strict wheat and sesame cross-contact controls across commercial bakery plants [4].
How does Fresh retain its format advantage?
Across formats, Fresh is expected to account for 29.2% in 2026, reinforced by point-of-sale aroma and crisp crust appeal at bakery counters.
Supermarket perimeter bakeries rely on warm olive-oil aroma and crisp dimpled crusts to pull shoppers into the bakery aisle and justify higher retail prices per kilogram than bagged pan bread. Rather than mixing scratch dough in store, grocers create that fresh counter presentation by finishing par-baked frozen baked goods in deck ovens just before midday and evening shopping peaks.
- Across formats, Fresh is expected to account for 29.2% in 2026, linked to impulse basket additions at artisan bakeries and grocery bake-off fixtures.
- To support this bake-off model, in November 2025, Lantmännen Unibake's foodservice bakery portfolio highlighted how pre-sliced frozen rosemary and olive-oil focaccia sheets finish in minutes to deliver fresh-baked counter aroma and crisp crusts [5].
Why does Multipack lead packaging format?
In 2026, Multipack is estimated to supply a 34.6% Packaging Format share, enabled by pre-portioned household meal convenience.
Consumers preparing work-from-home lunches and school paninis often avoid buying large uncut 800-gram focaccia loaves because leftover portions dry out after the bag is opened. By shifting retail merchandising toward twin-packs and four-packs of pre-sliced focaccetta squares sealed inside modified-atmosphere thermoformed trays and specialty bread bags, supermarkets raise average checkout ring while reducing household bread waste.
- In 2026, Multipack is estimated to supply a 34.6% Packaging Format share, resulting from higher grocery basket value and portion-controlled home toasting.
- To illustrate this retail format shift, Vandemoortele's Lanterna brand portfolio in September 2025 documented multi-piece retail and foodservice packs of pre-sliced focaccetta and topped Ligurian-style squares designed for quick home and café toasting [6].
What keeps Supermarkets & hypermarkets ahead by sales channel?
In 2026, supermarkets & hypermarkets are projected to absorb a 39.4% Sales Channel share, associated with multi-temperature merchandising.
Unlike independent street bakeries that sell focaccia only at ambient counter temperature, supermarkets and hypermarkets cross-merchandise the product across three distinct store zones. Large grocers display warm bake-off loaves at the perimeter bakery counter, chilled filled focaccia paninis in front-of-store meal-deal coolers, and ambient multipacks in the packaged bread aisle.
- In 2026, supermarkets & hypermarkets are projected to absorb a 39.4% Sales Channel share, stemming from one-stop household grocery traffic and private-label tiering.
- In practice, economic analysis published by FranceAgriMer in July 2025 documented how retail bakery counters and boulangeries in France structure their daily bread and savory snack procurement across fresh and frozen formats [7].
What are the drivers, restraints, and opportunities in the focaccia market?
In the focaccia market, fast-casual sandwich carrier upgrades and grocery bake-off programs drive demand, whereas rapid staling and allergen labeling rules restrain small-store uptake and fully baked thaw-and-sell portions create convenience opportunities.
- Driver: Fast-casual restaurant chains and grocery delis adopt pre-sliced focaccia slabs to elevate sandwich menu pricing with minimal back-of-house prep labor.
- Restraint: Short ambient crust crispness windows and cold-chain storage fees plus strict prepacked-for-direct-sale allergen labeling elevate store waste and compliance costs.
- Opportunity: Fully baked frozen single-serve stuffed and topped focaccias with validated thaw-and-sell holding windows open forecourt and café impulse channels.
Growth Analysis and Future Potential: Fast-Casual Sandwich Carrier Premiumization
Quick-service and fast-casual café operators rely on signature savory breads to justify USD 11 to USD 15 sandwich price points during lunch and dinner dayparts. Because high-hydration focaccia retains structural integrity under hot melted cheese and marinated meats better than soft brioche buns, national chains specify pre-sliced herb and black-pepper slabs from industrial contract bakeries. For instance, in June 2025, Panera Bread launched its limited-time summer menu featuring the Steak and Mozz sandwich built on Black Pepper Focaccia across its North America bakery-cafes [8]. As a result, wholesale bakers supplying packaged bread assortments and foodservice cases capture recurring volume when slab thickness and crumb cell structure prevent sauce bleed-through.
Risk Assessment of the Focaccia Market: Day-End Staling Waste and Prepacked Allergen Compliance
Rapid starch retrogradation after bake-off and stringent store-level allergen labeling mandates represent the primary operational hurdles restricting retail margin conversion. Unwrapped fresh focaccia loses its crisp surface texture within six to eight hours on open bakery racks, while topped variants containing cheese or pesto require refrigerated holding beside refrigerated savory snacks. Specifically, in the UK, the Food Standards Agency's Prepacked for Direct Sale (PPDS) labelling guidance updated in April 2025 enforces mandatory full-ingredient labels with 14 regulated allergens emphasized on any focaccia packed on premises before customer selection [9]. Because of this compliance burden, convenience stores lacking automated label printers restrict their assortment to factory-prepacked ambient or thaw-and-sell SKUs.
Commercial Opportunity Analysis: Fully Baked Thaw-and-Sell Monoportions for Oven-Free Outlets
Coffee shops and petrol forecourts as well as railway kiosks that lack extraction hoods or deck ovens represent a major commercial opening for fully baked frozen thaw-and-serve focaccia portions. By completing stone-hearth baking and savory topping application at the central factory, industrial bakers allow small outlets to thaw individual wrapped portions at ambient or chilled temperatures and heat them in 60 seconds on a contact grill. To serve this zero-baker workflow, in November 2025, Rich Products Corporation highlighted 18-count freezer-to-oven par-baked Extra Virgin Olive Oil Artisan Focaccia slabs engineered for rapid QSR service without skilled bakers [10]. In addition, pairing long-fermented sourdough flavor systems with olive-oil emulsions enables these thaw-and-serve snacks to retain soft eating quality throughout a 48-hour display window.
Focaccia Market by Country (2026 to 2036)
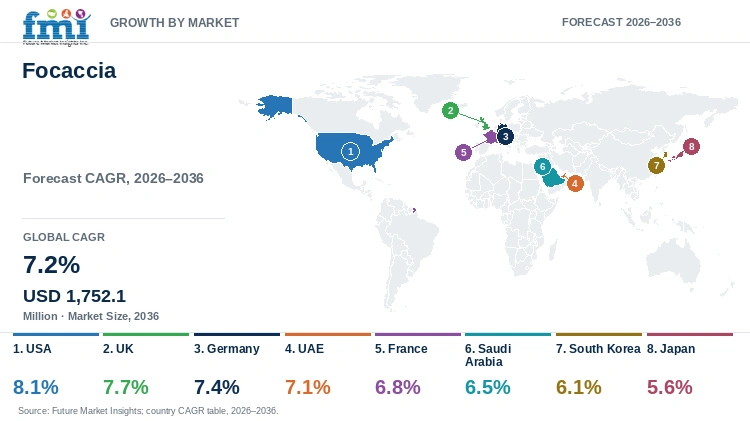
Demand patterns suggest that the USA leads the eight evaluated focaccia markets with an 8.1% CAGR through 2036. UK retail bake-off channels follow at 7.7% and convenience outlets in Germany post 7.4% ahead of Japan at 5.6%. Country performance reflects fast-casual sandwich menu penetration and supermarket in-store bake-off density.
Table 7: Country CAGR and Primary Growth Levers for the Focaccia Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 8.1% | Fast-casual sandwich carrier rollouts and USD 1.41T food-away-from-home demand |
| UK | 7.7% | Convenience-store bake-on-the-shop-floor programs and chilled meal-deal packs |
| Germany | 7.4% | Fully baked frozen 110g thaw-and-sell savory portions across EUR 18.14B bakery channels |
| UAE | 7.1% | Hotel, airport lounge, and café catering serving 19.59M international Dubai visitors |
| France | 6.8% | Boulangerie savory lunch snacking and Lanterna monoportion adoption |
| Saudi Arabia | 6.5% | Hospitality and QSR menu expansion serving 100M+ annual domestic and inbound tourists |
| South Korea | 6.1% | Urban café bakery localization and retail foodservice sandwich expansion |
| Japan | 5.6% | Compact chilled convenience-store sandwich carriers and 36.87M inbound tourist dining |
Source: Future Market Insights analysis
USA Focaccia Market Outlook (2026 to 2036)
Fast-casual bakery-café chains and supermarket perimeter deli counters drive focaccia expansion across the USA by substituting herb-baked flatbreads for commodity burger buns. Because food away from home reached USD 1.41 trillion (56.3% of total USA food expenditures) in 2025 according to the USDA Economic Research Service, restaurant operators prioritize pre-baked bread carriers that speed sandwich assembly during peak lunch rushes. For instance, in September 2025, commercial suppliers including La Brea Bakery documented par-baked quarter-sheet focaccia slabs and pre-sliced sandwich portions for national foodservice accounts [11]. Category sales across the USA are projected to advance at an 8.1% compound annual rate through 2036, although supermarket freezer slotting fees restrain smaller brands.
Key takeaway: In the USA, fast-casual sandwich menu upgrades and perimeter grocery deli programs are projected to drive bulk procurement of par-baked focaccia slabs.
UK Focaccia Market Outlook (2026 to 2036)
Supermarket lunchtime meal deals and compact bake-off ovens inside urban convenience stores across the UK are shifting savory bread demand toward pre-portioned rosemary and olive focaccia. Grocers in the UK merchandise twin-pack focaccia paninis in chilled food-to-go coolers while baking topped flatbread squares near store entrances to capture commuter footfall. Specifically, crop and milling statistics published in June 2026 by DEFRA in the UK frame domestic bakery flour sourcing and high-protein wheat import needs across commercial bread plants [12]. UK bakery revenue from focaccia is expected to climb by 7.7% annually over 2026 to 2036, reinforced by meal-deal rotation alongside strict compliance with Natasha's Law PPDS allergen labeling.
Key takeaway: In the UK, convenience-store bake-off rollouts and supermarket lunchtime meal deals are expected to sustain high-demand rotation for portioned focaccia.
Germany Focaccia Market Outlook (2026 to 2036)
Acute shortages of trained store-level bakers across railway station kiosks and petrol forecourts in Germany are accelerating adoption of zero-bake thaw-and-sell savory focaccias. Industry figures compiled in March 2026 by Germany's Bakers' Confederation (ZDB) show EUR 18.14 billion in 2025 bakery trade turnover across 8,659 enterprises where hot midday snacking drives afternoon store margins [13]. To serve outlets that lack deck ovens, in September 2026, ARYZTA Food Solutions expanded its catalog in Germany with 110-gram fully baked frozen ham and salami focaccias requiring only thawing. Commercial focaccia sales across Germany are forecast to compound at 7.4% annually through 2036, while discount grocer price caps pressure wholesale margins.
Key takeaway: In Germany, labor-saving thaw-and-sell monoportions across forecourts and chain bakery cafés are forecast to accelerate frozen topped focaccia turnover.
UAE Focaccia Market Outlook (2026 to 2036)
Record international hotel occupancy and airport lounge catering across Dubai and Abu Dhabi make the UAE the Middle East's primary foodservice import market for stone-baked frozen focaccia. Because luxury hotels and European-style cafés in the UAE serve multicultural breakfast and lunch menus without expanding kitchen baking floor space, catering buyers rely on imported par-baked rosemary and olive sheets. Tourism figures published by the Dubai Department of Economy and Tourism in February 2026 confirmed that Dubai welcomed a third consecutive record of 19.59 million international overnight visitors in 2025 [14]. Commercial focaccia procurement across the UAE is anticipated to rise by 7.1% per year through 2036, supported by minus-18-degree cold-chain logistics.
Key takeaway: In the UAE, booming international hotel occupancy and airport café catering are anticipated to fuel foodservice imports of par-baked focaccia slabs.
France Focaccia Market Outlook (2026 to 2036)
Midday competition between street boulangeries and fast-casual sandwich cafés in France is prompting bakery chains to add hot topped focaccia monoportions beside traditional jambon-beurre baguettes. Because commuters in Paris and Lyon seek warm olive-oil sandwich carriers that hold melted cheese without softening, operators stock pre-baked frozen Ligurian-style squares for two-minute panini grilling. For instance, in March 2025, Vandemoortele's Lanterna brand earned the Saveur de l'Année consumer distinction in France for its topped focaccia recipes [15]. Between 2026 and 2036, focaccia demand in France is estimated to record a 6.8% yearly rate attributable to commuter snack menu expansion, although high extra-virgin olive oil prices require strict portion control.
Key takeaway: In France, out-of-home lunch snacking growth across specialist boulangeries is estimated to support adoption of award-winning monoportion focaccias.
Saudi Arabia Focaccia Market Outlook (2026 to 2036)
Rapid rollout of specialty coffee chains, Red Sea hospitality resorts, and casual-dining districts in Riyadh and Jeddah is lifting commercial demand for standardized frozen focaccia in Saudi Arabia. Because multi-city café operators in Saudi Arabia require identical sandwich portion weights and verified halal ingredient traceability across every branch, central commissaries procure pre-sliced frozen focaccia carriers rather than baking from scratch. In June 2025, the Ministry of Tourism announced that Saudi Arabia surpassed the 100 million annual tourist mark for the second consecutive year and boosted hotel and restaurant catering demand [16]. Sales in Saudi Arabia are projected to increase by 6.5% annually over 2026 to 2036, balanced against refrigerated desert highway freight costs.
Key takeaway: In Saudi Arabia, surging tourism hospitality and multi-city café chains are projected to drive foodservice contracting for halal-certified frozen focaccia.
South Korea Focaccia Market Outlook (2026 to 2036)
Expansion of specialty espresso chains and department-store gourmet food halls across Seoul and Busan is shifting urban lunch consumption in South Korea toward hot pressed olive-oil flatbread sandwiches. Young office workers in South Korea increasingly purchase savory rosemary and sun-dried tomato focaccia paninis paired with specialty coffee as a midday meal replacement. Food retail analysis from USDA FAS economists in Seoul in October 2026 documents steady expansion in convenient meal replacements and Western-style café bakery items across South Korea [17]. Category turnover in South Korea is expected to post a 6.1% compound annual growth rate between 2026 and 2036, whereas cold-chain import tariffs on European frozen doughs encourage local co-baking.
Key takeaway: In South Korea, specialty café sandwich innovation and premium grocery deli counters are expected to expand urban demand for individual topped focaccia.
Japan Focaccia Market Outlook (2026 to 2036)
Inbound hotel breakfast buffets and nationwide convenience-store chilled sandwich shelves govern how commercial bakers formulate and portion focaccia in Japan. Because convenience retailers in Japan require single-handed savory breads that stay soft at 4-degree chilled cabinet temperatures without oozing surface oil, domestic bakeries engineer compact high-hydration focaccia buns using emulsified olive-oil doughs. Inbound tourism records from the Japan National Tourism Organization in January 2025 showed annual visitor arrivals reaching 36.87 million [18], while domestic leader Yamazaki Baking expanded its nationwide convenience and supermarket bread distribution in January 2026 [19]. Commercial focaccia sales in Japan are forecast to compound at 5.6% annually through 2036 due to compact portion engineering.
Key takeaway: In Japan, record inbound tourism catering and convenience-store chilled sandwich counters are forecast to support compact, moisture-retentive focaccia portions.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the focaccia market?
Lantmännen Unibake, Vandemoortele, ARYZTA, Europastry, Grupo Bimbo, Rich Products Corporation, La Brea Bakery (Aspire Bakeries), Flowers Foods, Warburtons, and St Pierre Groupe are the notable companies in the focaccia market.
Market competition separates into Europe frozen bake-off specialists that operate stone-hearth tunnel ovens and North America foodservice suppliers that scale pre-sliced sandwich carriers. Because grocery and café buyers want authentic open-crumb sourdough structure without store-level baking labor, leading groups are acquiring regional flatbread bakeries in Italy and Benelux.
- European Frozen Focaccia & Bake-Off Specialists: Lantmännen Unibake and Vandemoortele along with ARYZTA and Europastry supply stone-baked frozen rosemary slabs and stuffed monoportions.
- Foodservice Sandwich-Carrier & Artisan Par-Baked Platforms: Grupo Bimbo (Bimbo QSR) and Rich Products Corporation plus La Brea Bakery manufacture par-baked sheet focaccias and sliced QSR sandwich buns.
- Branded Retail & Specialty Packaged Bakery Platforms: Flowers Foods and Warburtons plus St Pierre Groupe operate high-frequency supermarket bread distribution networks and continental bakery merchandising fixtures.
Competitive Benchmarking: Focaccia Market
Table 8: Competitive Benchmarking for the Focaccia Market (qualitative capability ratings), 2026
| Company | Focaccia SKU & Recipe Depth | Frozen & Bake-Off Technology | Retail & QSR Channel Access | Geographic Reach |
|---|---|---|---|---|
| Lantmännen Unibake | High | High | High | Europe, UK, Germany, Benelux, and international foodservice |
| Vandemoortele | High | High | High | Italy, France, Western Europe retail and HoReCa |
| ARYZTA | High | High | High | Germany, UK, Switzerland, and Europe bake-off networks |
| Europastry | High | High | High | Spain, France, Europe, and Americas professional bakery |
| Grupo Bimbo | Medium | High | High | North America, Latin America, and Europe via Bimbo QSR |
| Rich Products Corporation | High | High | High | USA and global QSR and in-store bakery channels |
| La Brea Bakery (Aspire Bakeries) | High | High | High | USA foodservice and supermarket artisan bakeries |
| Flowers Foods | Medium | Medium | High | USA national grocery and foodservice channels |
| Warburtons | Medium | Medium | High | UK supermarket and convenience distribution |
| St Pierre Groupe | Medium | Medium | High | UK, USA, and Europe branded supermarket bakery aisles |
Scoring basis: Focaccia SKU & Recipe Depth evaluates documented product listings across rosemary slabs and topped focaccetta plus pre-sliced QSR buns. Frozen & Bake-Off Technology and Channel Access reflect stone-hearth par-baking and thaw-and-sell shelf stability across supermarket or fast-casual restaurant distribution.
Key Developments in the Focaccia Market
- Vandemoortele announced the acquisition of frozen-bakery specialist Lizzi S.r.l. in Italy in February 2025, adding four northern Italy manufacturing plants and the Forno della Rotonda sourdough bread and focaccia portfolio [20].
- ARYZTA Food Solutions launched fully baked frozen 110-gram Focaccia Schinken and Focaccia Salami monoportions in Germany in September 2026 to serve oven-free convenience and café counters [21].
- Europastry rolled out its Spring 2025 Cristallino high-hydration focaccia line in plain and olive or tomato variants for foodservice and bakery accounts across France and Europe in April 2025 [22].
Key Players in the Focaccia Market
European Frozen Focaccia & Bake-Off Specialists
- Lantmännen Unibake
- Vandemoortele
- ARYZTA
- Europastry
Foodservice Sandwich-Carrier & Artisan Par-Baked Platforms
- Grupo Bimbo
- Rich Products Corporation
- La Brea Bakery (Aspire Bakeries)
Branded Retail & Specialty Packaged Bakery Platforms
- Flowers Foods
- Warburtons
- St Pierre Groupe
Focaccia Market - Report Scope
Table 9: Report Scope for the Focaccia Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Claim / Nature; Format; Packaging Format; Sales Channel |
| Quantitative Units | USD Million |
| Market Definition | Commercial wholesale and retail bakery revenue from defined focaccia bread products across all specified product types, claims, formats, pack configurations, and sales channels. Includes pre-sliced focaccia sandwich carriers at the bakery-product level; excludes the assembled retail menu price of finished restaurant sandwiches, pizzas, and non-focaccia flatbreads. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, UK, Germany, UAE, France, Saudi Arabia, South Korea, Japan, and additional countries in the full report |
| Key Companies Covered | Lantmännen Unibake, Vandemoortele, ARYZTA, Europastry, Grupo Bimbo, Rich Products Corporation, La Brea Bakery (Aspire Bakeries), Flowers Foods, Warburtons, St Pierre Groupe |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Focaccia Market - Research Methodology
Table 10: Research Methodology for the Focaccia Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with supermarket in-store bakery buyers, fast-casual sandwich menu developers, frozen bake-off manufacturers, and foodservice distributors to validate case pricing and sell-through. |
| Secondary Research | Review of USDA Economic Research Service food-expenditure series, FranceAgriMer and ZDB retail statistics in Germany, UK FSA Natasha's Law PPDS rules, and professional bakery catalogs. |
| Market Sizing and Forecasting | Top-down specialty savory bread and bake-off budgets reconciled against bottom-up wholesale case volumes (110g monoportions to 1.2kg foodservice slabs) from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight food-away-from-home expenditure, convenience-store bake-off penetration, and international tourism catering throughput across eight national markets. |
| Operational Benchmark Traceability | Bakery output and outlet spending indicators in Tables 2, 3, and 4 trace to USDA ERS, FranceAgriMer, Dubai DET, Ministry of Tourism in Saudi Arabia, and JNTO hospitality benchmarks. |
| Data Triangulation and Validation | Revenue figures are cross-checked against commercial stone-hearth line capacities while excluding downstream assembled sandwich prices, pizza bases, and general white pan bread. |
Focaccia Market by Segments
Focaccia Market segmented by Product Type:
- Classic rosemary
- Topped (tomato, olive, onion)
- Filled / sandwich focaccia
- Mini & snacking focaccia
Focaccia Market segmented by Claim / Nature:
- Conventional
- Clean label
- Organic
- Gluten-free
- High-protein / fortified
Focaccia Market segmented by Format:
- Fresh
- Frozen
- Ambient packaged
- Chilled
- Par-baked / thaw-and-serve
Focaccia Market segmented by Packaging Format:
- Multipack
- Single-serve
- Family / loaf pack
- Bulk foodservice
Focaccia Market segmented by Sales Channel:
- Supermarkets & hypermarkets
- Artisan & specialty bakeries
- Convenience & forecourt
- Online & DTC
- Foodservice distributors
Focaccia Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Lantmännen Group. (2026, February 11). Strong finish and stable result for Lantmännen 2025 - all time high dividend proposed to Swedish farmers. Lantmännen Group Newsroom.
- [2] USDA Economic Research Service. (2026, June 11). Total U.S. food spending reached $2.51 trillion in 2025 | Economic Research Service. United States Department of Agriculture (USDA ERS).
- [3] Vandemoortele NV / Banquet d'Or. (2025, October 14). Lanterna - Italian Focaccia | Banquet d'Or. Vandemoortele Professional Bakery Catalog.
- [4] U.S. Food and Drug Administration (FDA). (2025, January 6). Guidance for Industry: Questions and Answers Regarding Food Allergen Labeling (Edition 5) | FDA. U.S. Department of Health and Human Services / FDA.
- [5] Lantmännen Unibake. (2025, November 12). The Bread is Your Canvas | Lantmännen Unibake. Lantmännen Unibake Foodservice Solutions.
- [6] Vandemoortele NV. (2025, September 18). Lanterna® | Vandemoortele. Vandemoortele Brand Portfolio.
- [7] FranceAgriMer. (2025, July 15). Activité hors domicile et modes d'approvisionnement des boulangeries pâtisseries | FranceAgriMer. République Française / FranceAgriMer.
- [8] Panera Bread. (2025, June 25). PANERA BREAD SAYS CIAO TO AN ITALIAN SUMMER WITH LIMITED-TIME MENU LAUNCH CELEBRATING THE FLAVORS OF ITALY | Panera Bread. Panera Bread Official Press Room.
- [9] UK Food Standards Agency (FSA). (2025, April 23). Labelling guidance for prepacked for direct sale (PPDS) food products - GOV.UK. UK Food Standards Agency Business Guidance.
- [10] Rich Products Corporation. (2025, November 5). EXTRA VIRGIN OLIVE OIL ARTISAN FOCACCIA BREAD - Rich's USA. Rich's USA Foodservice Products.
- [11] La Brea Bakery (Aspire Bakeries). (2025, September 20). 1/4 Focaccia Sheet | La Brea Bakery. La Brea Bakery Foodservice Catalog.
- [12] UK Department for Environment, Food & Rural Affairs (DEFRA). (2026, June 18). Chapter 7: Crops - GOV.UK. GOV.UK Official Agricultural Statistics.
- [13] Zentralverband des Deutschen Bäckerhandwerks e.V. (2026, March 15). Zahlen rund ums Bäckerhandwerks - Zentralverband des Deutschen Bäckerhandwerks. Deutsches Bäckerhandwerk.
- [14] Dubai Department of Economy and Tourism (DET). (2026, February 9). Dubai Welcomes 19.59 Million Visitors in Third Record Year. Government of Dubai / DET Newsroom.
- [15] Lanterna / Vandemoortele. (2025, March 10). Lanterna focaccia. Lanterna Focaccia Official Portal.
- [16] Ministry of Tourism Saudi Arabia. (2025, June 22). Ministry of Tourism Saudi Arabia. Kingdom of Saudi Arabia Ministry of Tourism.
- [17] USDA Foreign Agricultural Service. (2026, October 5). South Korea: Retail Foods Annual | USDA Foreign Agricultural Service. United States Department of Agriculture (USDA FAS).
- [18] Japan National Tourism Organization (JNTO). (2025, January 15). 訪日外客数(2025年1月発表推計値)|報道発表|JNTO(日本政府観光局). JNTO Official Press Releases.
- [19] Yamazaki Baking Co., Ltd. (2026, January 20). YAMAZAKI BAKING Co., Ltd. Yamazaki Baking Corporate Information.
- [20] Vandemoortele NV. (2025, February 14). PRESS RELEASE - Vandemoortele acquires Lizzi in Italy, a specialty player in frozen Bakery. Vandemoortele Corporate Newsroom.
- [21] ARYZTA Food Solutions GmbH. (2026, September 10). Focaccia Schinken | Internationale Snacks | Snacks | Herzhafte Backwaren | Produkte | ARYZTA Deutschland Webshop. ARYZTA Food Solutions Germany Product Catalog.
- [22] Europastry, S.A. (2025, April 15). Nouveautés Catalogue N·2 - Europastry. Europastry France Professional Catalog.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the focaccia market in 2026 and what revenue is forecast by 2036?
- Which fast-casual sandwich and grocery bake-off trends accelerate focaccia procurement?
- Why does classic rosemary lead the product type mix?
- Why does conventional wheat dough hold the largest claim / nature share?
- How do country CAGRs compare across the USA, the UK, Germany, and the UAE?
- Which commercial bakers document frozen slabs, monoportions, and QSR sandwich carriers?
- Where do day-end staling losses and Natasha's Law PPDS rules restrict store adoption?
- What thaw-and-sell holding and allergen checks should buyers complete before listing focaccia?
Frequently Asked Questions
How big is the focaccia market in 2026, and what is forecast for 2036?
Global focaccia sales advance beyond a 2025 mark of USD 812.5 million to reach an estimated USD 874.2 million in 2026. Category turnover is projected at USD 1,752.1 million by 2036 across retail bake-off and foodservice channels.
What is the CAGR for the focaccia market from 2026 to 2036?
The category is forecast to post a 7.2% compound annual growth rate across the ten-year horizon, delivering USD 877.9 million in net new annual bakery turnover.
Which product type segment leads the focaccia market?
In 2026, classic rosemary is forecast to hold a 38.4% Product Type share, supported by broad compatibility with hot panini fillings and soup-and-salad service.
Which claim / nature segment leads the focaccia market?
In 2026, Conventional is anticipated to generate 53.6% of Claim / Nature volume, linked to reliable wheat-gluten gas retention in high-hydration sheet doughs.
Which country has a notable growth outlook during the assessment period?
The USA is projected to lead evaluated country growth at an 8.1% CAGR to 2036, driven by fast-casual sandwich launches and grocery deli bake-off programs.
Who are the key players in the market?
Notable market participants include Lantmännen Unibake, Vandemoortele, ARYZTA, Europastry, Grupo Bimbo, Rich Products Corporation, La Brea Bakery (Aspire Bakeries), Flowers Foods, Warburtons, and St Pierre Groupe across wholesale and retail bakery routes.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Classic rosemary
- Topped (tomato, olive, onion)
- Filled / sandwich focaccia
- Mini & snacking focaccia
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Claim / Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Claim / Nature, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Claim / Nature, 2026 to 2036
- Conventional
- Clean label
- Organic
- Gluten-free
- High-protein / fortified
- Y-o-Y Growth Trend Analysis By Claim / Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Claim / Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Format, 2026 to 2036
- Fresh
- Frozen
- Ambient packaged
- Chilled
- Par-baked / thaw-and-serve
- Y-o-Y Growth Trend Analysis By Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Format, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Packaging Format, 2026 to 2036
- Multipack
- Single-serve
- Family / loaf pack
- Bulk foodservice
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Supermarkets & hypermarkets
- Artisan & specialty bakeries
- Convenience & forecourt
- Online & DTC
- Foodservice distributors
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- UAE
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Lantmännen Unibake
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Vandemoortele
- ARYZTA
- Europastry
- Grupo Bimbo
- Rich Products Corporation
- La Brea Bakery (Aspire Bakeries)
- Flowers Foods
- Warburtons
- St Pierre Groupe
- Lantmännen Unibake
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


