
- Market Size (2026)
- USD 560.5 Mn
- Forecast (2036)
- USD 1092.3 Mn
- CAGR (2026 to 2036)
- 6.9%
How big is Dextrin Market in 2026?
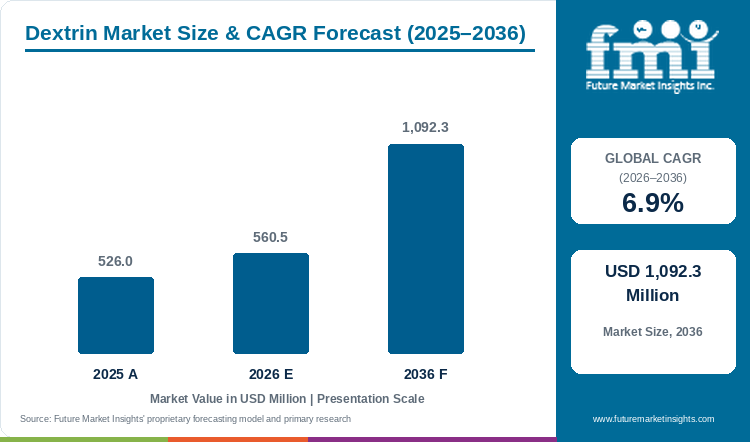
The dextrin market establishes its foundation at USD 526.0 million in 2025, advances to USD 560.5 million in 2026, and is forecast to scale to USD 1,092.3 million by 2036 at a CAGR of 6.9%.
The global dextrin market was valued at USD 526.0 million in 2025 and is estimated to reach USD 560.5 million in 2026. Overall industry valuation is projected to reach USD 1,092.3 million by 2036, expanding at a compound annual growth rate (CAGR) of 6.9% between 2026 and 2036. FMI market findings show that yellow pyrodextrin high solubility is anticipated to hold 49.8% of production modification sales in 2026, while soluble dietary prebiotic fiber supplementation is projected to capture 57.3% of application demand as food brands reformulate under front-of-pack sugar and fiber labeling mandates. The demand for dextrin is supported by clinically verified gut-microbiota fortification, with a May 2026 randomized trial in Frontiers in Nutrition proving that 15 grams per day of NUTRIOSE resistant dextrin across 124 adults selectively increased beneficial Parabacteroides bacteria [1]. That regulatory fiber-claim pull separates dextrin growth from the broader maltodextrin bulking ingredient category expanding at 5.1% CAGR, since digestible maltodextrins add glycemic calories whereas resistant dextrins enable dietary fiber declarations and industrial pyrodextrins replace synthetic packaging glues. Suppliers are consolidating carbohydrate portfolios to capture this shift, as Ingredion announced a recommended GBP 3.7 billion (USD 5.0 billion) acquisition offer for Tate & Lyle in June 2026 [2]. Beverage formulators and corrugated converters renew dextrin contracts when low-viscosity grades meet digestive tolerance ceilings and high-speed remoistenable tack targets through 2036.
Key Market Trends & Insights
- By production modification: Yellow Pyrodextrin High Solubility holds an estimated 49.8% share in 2026 since prolonged acid-catalyzed roasting generates highly branched, cold-water-soluble polymers.
- By botanical starch: Corn Starch Acid Roasting represents 53.5% in 2026 owing to abundant dent and waxy maize supply across North American, European, and Asian wet mills.
- By application: Soluble Dietary Prebiotic Fiber Supplementation accounts for 57.3% in 2026 given that alpha-1-2 and alpha-1-3 glycosidic linkages resist human digestive enzymes while maintaining clear beverage viscosity.
- By physical form: Spray-Dried and Agglomerated Powder secures 68.4% in 2026 supported by rapid dust-free dispersion in dry drink mixes and industrial adhesive kettles.
- By sales channel: Direct to Food and Packaging Manufacturers commands 62.1% in 2026 through bulk silo deliveries and custom dextrose-equivalent and viscosity qualification.
Regional Highlights
- Top national expansion: Mexico leads national growth projections at an 8.1% CAGR through 2036 under mandatory front-of-pack sugar reduction and e-commerce corrugated packaging demand.
- Broader country progression: Brazil tracks at a 7.5% CAGR ahead of the United States at 7.2% and Canada at 6.8%, while Spain advances at a 5.9% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Dextrin Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 526.0 million |
| Estimated Market Size in 2026 | USD 560.5 million |
| Projected Market Size by 2036 | USD 1,092.3 million |
| CAGR, 2026 to 2036 | 6.9% |
| Added Revenue, 2026 to 2036 | USD 531.8 million |
Bakery and snack formulators adding high levels of dietary fiber often encounter dough stiffening and loaf volume loss when insoluble bran fibers disrupt gluten hydration. In May 2026, macromolecular structural research published in MDPI Foods demonstrated that resistant dextrin forms hydrogen-bonded networks with wheat starch and gluten that preserve dough viscoelasticity and water distribution [3]. Consequently, commercial bakeries blend resistant dextrins with digestion resistant maltodextrin to achieve high-fiber front-of-pack nutrition scores without sacrificing soft crumb texture.
Treated Starch Tonnage and Prebiotic Fiber Dosing Sizing
Table 2: Treated Starch Tonnage and Prebiotic Fiber Dosing Sizing for the Dextrin Market (USD million and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global dextrin market size (USD million) | 526.0 | 560.5 | 1,092.3 |
| Commercial dextrin & resistant dextrin volume (thousand metric tons) | 365.0 to 405.0 | 388.0 to 430.0 | 715.0 to 790.0 |
| Soluble prebiotic resistant dextrin volume (thousand metric tons) | 155.0 to 172.0 | 168.0 to 186.0 | 345.0 to 382.0 |
| Industrial adhesive & coating pyrodextrin volume (thousand metric tons) | 210.0 to 233.0 | 220.0 to 244.0 | 370.0 to 408.0 |
Operational note: Treated-starch and dosing ranges reflect 1.2 to 15.0 grams per serving FDA GRAS dietary fiber clearances and 35% to 65% solids industrial pyrodextrin adhesive coatings.
Beverage, confectionery, and nutrition-bar brands require official FDA and EFSA dietary fiber recognition and high gastrointestinal tolerance before scaling soluble fiber inclusions across mass-market SKUs. Regulatory filings in the U.S. Food and Drug Administration GRAS Notice Inventory under GRN No. 1170 confirm that tapioca-derived resistant dextrin is cleared up to 15 grams per serving across baked goods and non-alcoholic beverages [4]. That broad regulatory clearance enables product developers to specify dextrin and modified starch for simultaneous sugar reduction and mouthfeel restoration.
Industrial Packaging Solids and Fiber Fortification Benchmarks
Table 3: Industrial Packaging Solids and Fiber Fortification Benchmarks for the Dextrin Market (grams and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| FDA GRAS tapioca resistant dextrin food ceiling (g/serving) | 1.2 to 15.0 | 1.2 to 15.0 | 1.2 to 15.0 |
| Clinical prebiotic microbiota modulation daily dose (g/day) | 10.0 to 15.0 | 10.0 to 15.0 | 10.0 to 20.0 |
| Industrial yellow pyrodextrin aqueous adhesive solids (% w/w) | 45.0% to 65.0% | 45.0% to 65.0% | 48.0% to 68.0% |
| Clean-label tapioca & potato dextrin share of food demand (%) | 36.0% to 40.0% | 38.0% to 42.0% | 45.0% to 50.0% |
Table 4: Institutional Regulatory and Clinical Reference Indicators for the Dextrin Market (metrics and reference basis), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Clinical prebiotic NUTRIOSE trial dose | 15 g/day across 124 adults | Frontiers in Nutrition May 2026 randomized controlled study |
| FDA GRAS tapioca resistant dextrin limit | 1.2 to 15.0 g/serving | U.S. FDA GRAS Notice Inventory GRN No. 1170 & GRN No. 1045 |
| Tate & Lyle cumulative fiber fortification | 18.3B servings (35B by 2030) | Tate & Lyle Purpose Target Release August 2026 (15g fiber equivalent) |
| Ingredion recommended offer for Tate & Lyle | GBP 3.7B (USD 5.0B) EV | Tate & Lyle and Ingredion Acquisition Announcement June 8, 2026 |
Multinational food processors are committing to measurable multi-year fiber fortification targets as public health agencies address chronic dietary fiber deficits across Western and Asian diets. Corporate sustainability disclosures published by Tate & Lyle in August 2026 document that the company delivered 18.3 billion daily 15-gram fiber-gap servings between April 2020 and March 2026 and established a new target of 35 billion servings by March 2030 while removing 12 million tonnes of sugar [5]. Food manufacturers pursuing these sugar-to-fiber replacement goals combine soluble corn and tapioca dextrins with resistant starch across everyday cereals, yogurts, and snacks.
Analyst Perspective
"Dextrin buyers operate across two distinct commercial tracks: food formulators buy non-digestible alpha-1-2 and alpha-1-3 branched dextrins for zero-viscosity fiber claims, whereas packaging converters buy yellow pyrodextrins for high-solids water-activated tack on recyclable paperboard. Wet millers that flexibly swing roasting and enzymatic hydrolysis capacity toward soluble prebiotic fibers while guaranteeing verified non-GMO crop identity will capture superior margin mix through 2036."
- Nandini Roy Choudhury,, Principal Consultant, Future Market Insights.
How is the dextrin market segmented?
The dextrin market is segmented by production modification, botanical starch, application, physical form, and sales channel. In 2026, Yellow Pyrodextrin High Solubility is projected at 49.8%, Corn Starch Acid Roasting at 53.5%, Soluble Dietary Prebiotic Fiber Supplementation at 57.3%, Spray-Dried and Agglomerated Powder at 68.4%, and Direct to Food and Packaging Manufacturers at 62.1%.
By production modification: Yellow Pyrodextrin High Solubility, White Dextrin Low Viscosity, Resistant Prebiotic Dextrin Fibersol-2, and Canary British Gum Medium Conversion.
By botanical starch: Corn Starch Acid Roasting, Potato Starch Derived Dextrin, Tapioca Starch Dextrin, and Wheat and Waxy Maize Starch Dextrin.
By application: Soluble Dietary Prebiotic Fiber Supplementation, Industrial Adhesives Corrugated Board and Envelope Gums, Bakery Glazes and Confectionery Crisp Coatings, and Pharmaceutical Tablet Binder and Encapsulation Carrier.
By physical form: Spray-Dried and Agglomerated Powder, Fine Roasted Granular Blend, Liquid Aqueous Dextrin Solution, and Instant Cold-Water Dispersible Flakes.
By sales channel: Direct to Food and Packaging Manufacturers, Specialty Carbohydrate and Chemical Distributors, Nutraceutical Contract Blenders, and Digital B2B Ingredient Supply.
Why does Yellow Pyrodextrin High Solubility lead the production modification category?
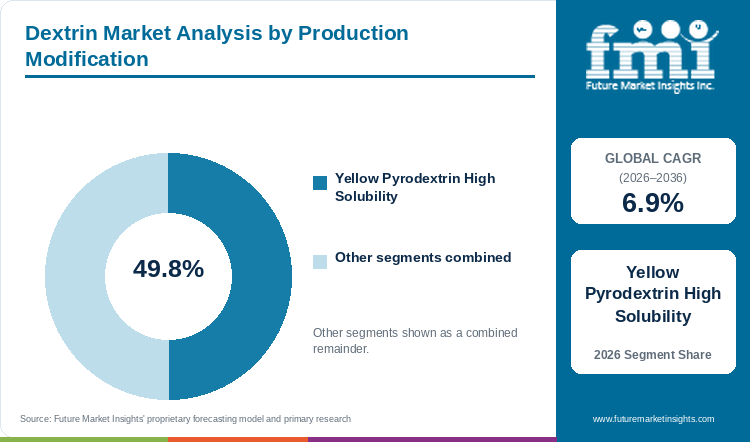
Yellow Pyrodextrin High Solubility holds an estimated 49.8% of production modification demand in 2026, anchored by nearly 100% cold-water solubility and dual use as a prebiotic-fiber precursor and packaging adhesive.
Table 5: Production Modification Share for the Dextrin Market (percentage share), 2026
| Production Modification | Share (2026) |
|---|---|
| Yellow Pyrodextrin High Solubility | 49.8% |
| Other Segments Combined | 50.2%* |
| Total | 100.0% |
*Note: Remaining production modification categories account for the balance of 2026 global dextrin demand.
Table 6: Production Modification Leadership and Market Growth for the Dextrin Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.9% |
| Leading Segment | Yellow Pyrodextrin High Solubility |
Industrial starch processors roast acidified starch at 150 to 200 degrees Celsius under dry conditions to produce yellow pyrodextrins that exhibit nearly 95% to 100% cold-water solubility and exceptionally low solution viscosity. Given that yellow pyrodextrin acts both as the primary intermediate for enzymatic resistant dextrin manufacturing and as a high-solids binder in paperboard adhesives and foundry cores, it anchors global production volume across dietary fibers and prebiotic fiber and industrial starch plants. Thermal color development and Maillard off-notes require activated-carbon refining when yellow pyrodextrin is purified into clear beverage fiber.
- Within the production modification segment, Yellow Pyrodextrin High Solubility is projected to account for a leading 49.8% share in 2026, driven by dual demand as a resistant-fiber precursor and high-solids packaging adhesive.
- In September 2026, Roquette reported 9% first-half 2026 growth and a 13.0% operating EBITDA margin, noting that strategic ramp-up in soluble food fibers and pharmaceutical excipients offset broader starch headwinds [6].
What sustains Corn Starch Acid Roasting leadership in the botanical starch segment?
Corn Starch Acid Roasting represents an estimated 53.5% of the botanical starch category in 2026, supported by large-scale maize wet-milling cost efficiency and year-round grain availability.
Integrated corn wet-milling complexes in North America and Europe supply the majority of global dextrin feedstock since dent and waxy maize offer the lowest per-ton carbohydrate cost and year-round silo storage stability. Compared with seasonal chicory root used in inulin fiber extraction or weather-sensitive European potato harvests, corn starch acid roasting provides predictable amylopectin branching for both industrial canary gums and soluble corn fibers. Financial results published by Archer Daniels Midland Company in August 2026 reflect the scale of this corn processing infrastructure, supported by multi-site capital expenditure across carbohydrate and nutrition facilities [7]. Non-GMO and allergen-free label preferences in baby food and clean-label snacks remain the main factor encouraging secondary tapioca switching.
- In 2026, Corn Starch Acid Roasting is anticipated to capture 53.5% of global botanical starch demand, reflecting entrenched wet-milling cost advantages and established FDA and EFSA regulatory approvals.
- Tapioca Starch Dextrin is forecast to record faster percentage growth through 2036 as snack and beverage brands specify grain-free, non-GMO cassava dextrins for clean-label and hypoallergenic product lines.
How does Soluble Dietary Prebiotic Fiber Supplementation lead the application category?
Soluble Dietary Prebiotic Fiber Supplementation accounts for an anticipated 57.3% of application demand in 2026, driven by front-of-pack sugar reduction, GLP-1 companion foods, and clear RTD beverage fortification.
Packaged beverage and supplement manufacturers represent the largest revenue pool for commercial dextrins since acid-roasted and amylase-refined resistant dextrins dissolve into crystal-clear, low-viscosity solutions with zero chalkiness. When formulators use insoluble fibers or high-viscosity gums, beverage mouthfeel turns slimy and extruded snacks lose crispness, a problem avoided by pairing resistant dextrin with food coating ingredients in reduced-sugar glazes and bars. High gastrointestinal tolerance up to 45 grams per day also prevents the bloating and flatulence triggered by short-chain fructo-oligosaccharides.
- By application, demand for Soluble Dietary Prebiotic Fiber Supplementation is estimated to reach 57.3% of total category share in 2026 as food brands close consumer dietary fiber gaps and replace bulk sugars.
- In January 2026, metabolic nutrition research published in Food & Function demonstrated that resistant dextrin combined with botanical extracts significantly lowers fasting blood glucose and HbA1c while enriching short-chain fatty acid-producing gut bacteria [8].
Why does Spray-Dried and Agglomerated Powder lead the physical form category?
Spray-Dried and Agglomerated Powder secures an expected 68.4% of physical form demand in 2026, supported by instant cold-water dispersion and direct-compression pharmaceutical tableting.
Food, beverage, and pharmaceutical buyers overwhelmingly specify spray-dried and fluidized-bed agglomerated dextrin powders, owing to porous micro-granules wet instantly in cold water without fish-eye clumping. Dry agglomerated powders also compress cleanly as direct-tableting excipients and protect encapsulated flavor oils from oxidation during ambient shelf storage. Corporate organizational disclosures from Roquette in May 2025 demonstrate this high-value solid excipient focus, detailing the launch of its unified Health & Pharma Solutions and Nutrition & Bioindustry Business Groups following the acquisition of Emsland Group Pharma Solutions [9].
- Strong repeat procurement across dry beverage premixes and tablet plants places Spray-Dried and Agglomerated Powder on course to hold an estimated 68.4% share of the physical form category in 2026.
- Liquid aqueous dextrin syrups retain steady industrial volume in regional corrugated box plants and bottle-labeling lines located within tanker-truck radius of wet-milling refineries.
What gives Direct to Food and Packaging Manufacturers the leading position in sales channel?
Direct to Food and Packaging Manufacturers commands a projected 62.1% of sales channel share in 2026, anchored by bulk silo contracts and application-lab viscosity calibration.
Multinational beverage bottlers, cereal makers, and corrugated packaging converters contract directly with primary starch wet millers to secure multi-thousand-ton annual volumes and customized dextrose-equivalent and molecular-weight profiles. Direct technical co-development through supplier application labs ensures that resistant dextrin grades match exact UHT pasteurization pH tolerances and that adhesive pyrodextrins match high-speed corrugator roller speeds. Smaller confectionery and foundry buyers rely on regional chemical and carbohydrate distributors for pallet-load deliveries.
- Direct to Food and Packaging Manufacturers is predicted to secure 62.1% of sales channel demand in 2026, anchored by bulk contract pricing and application-lab co-development.
- In July 2026, Ingredion presented its next-generation fiber fortification and Ask Ingredion AI formulation portal at IFT FIRST 2026 to accelerate direct R&D formulation work with food and beverage manufacturers [10].
What are the drivers, restraints, and opportunities in the dextrin market?
In the dextrin market, front-of-pack sugar and fiber labeling mandates and GLP-1 diet shifts are projected to drive adoption whereas energy-intensive thermal roasting and chromatographic refining restrain low-tier producers and biodegradable corrugated pyrodextrin glues expand industrial demand.
- Driver: Global sugar-reduction taxes, front-of-pack nutrition scoring, and GLP-1 companion diet trends compel food and beverage brands to fortify everyday products with soluble prebiotic dextrins.
- Restraint: Energy-intensive thermal acid roasting and multi-step enzymatic chromatography purification raise production costs for high-purity resistant dextrins relative to commodity native starches.
- Opportunity: Replacing petroleum-derived hot-melt packaging glues with biodegradable pyrodextrin adhesives and expanding clean-label tapioca and potato resistant dextrins open high-margin industrial and food growth.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Consumer adoption of GLP-1 weight-management medications and mandatory front-of-pack sugar warning labels are structurally shifting packaged food formulation toward high-fiber, nutrient-dense portion formats. Given that resistant dextrin provides soluble prebiotic fiber and sugar-like bulking body at 1.5 to 2.0 kilocalories per gram without altering product clarity or flavor, beverage and snack brands use it and clean-label ingredients to replace sucrose and corn syrup solids. Clinical meta-analysis data published in Nutrition Journal in March 2026 across 13 randomized controlled trials and 952 participants substantiates this nutritional demand driver, confirming that 10 grams per day of resistant dextrin significantly lowers fasting blood glucose and HOMA-IR insulin resistance [11].
Risk Assessment of the Dextrin Market: Operational and Formulation Friction
Complex thermal-acid dextrinization and chromatographic refining requirements represent the primary cost and operational hurdles restraining lower-tier starch processors in the dextrin market. Transformation of native starch into non-digestible resistant dextrin requires precise hydrochloric acid trace catalysis at elevated heating temperatures followed by enzymatic refining to remove digestible glucose and dark Maillard byproducts, while industrial adhesive grades face moisture-resistance limits compared with synthetic resins in compostable adhesives applications. Structural carbohydrate research published in the International Journal of Molecular Sciences in October 2024 demonstrates these processing trade-offs, showing that microwave-assisted acid dextrinization of potato starch achieves 74% water solubility at 20 degrees Celsius and 47% total dietary fiber content [12].
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Starch biorefiners are capturing premium margin expansion by engineering enzyme-branched resistant dextrins with ultra-high dietary fiber yields for bakery and beverage fortification and by formulating bio-based pyrodextrin gums for e-commerce paper packaging. In commercial bread and reduced-sugar beverages, pairing high-purity resistant dextrin with prebiotic ingredient blends replaces calorie-dense fats and sugars while maintaining crystal clarity and soft crumb elasticity. Bioprocessing research published in the International Journal of Biological Macromolecules in June 2025 confirms this formulation opportunity, showing that a two-hour branching enzyme treatment raises alpha-1,6 glycosidic linkage ratios to 44.11% and boosts resistant dextrin water solubility to 96.3% and dietary fiber content to 84.2% [13].
Dextrin Market by Country (2026 to 2036)
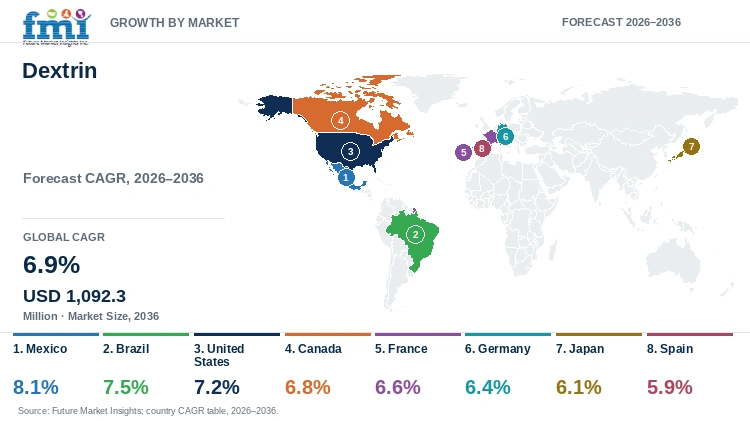
FMI country modeling indicates that Mexico leads dextrin market growth at an 8.1% CAGR through 2036 ahead of Brazil at 7.5% and the United States at 7.2%. Canada follows at a 6.8% CAGR, while Spain advances at a 5.9% CAGR.
Table 7: Country CAGR and Primary Growth Levers for the Dextrin Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Mexico | 8.1% | NOM-051 front-of-pack sugar reformulation and e-commerce corrugated adhesives |
| Brazil | 7.5% | Domestic corn and cassava wet-milling and ANVISA functional beverage fibers |
| United States | 7.2% | GLP-1 high-fiber CPG launches and Midwest soluble corn fiber biorefineries |
| Canada | 6.8% | Mandatory Jan 2026 Health Canada FOP nutrition labels and paper packaging |
| France | 6.6% | Nutri-Score food reformulation, Lestrem biorefining, and AGEC plastic bans |
| Germany | 6.4% | High-speed corrugated board adhesives and potato/wheat baking glaze dextrins |
| Japan | 6.1% | FOSHU and FFC indigestible dextrin RTD teas and glycemic-control foods |
| Spain | 5.9% | Export bakery glaze coatings and horticultural corrugated tray lamination |
Source: Future Market Insights analysis
Mexico Dextrin Market Outlook (2026 to 2036)
Demand for dextrin in Mexico is projected to expand at a leading 8.1% CAGR between 2026 and 2036 as domestic beverage bottlers, bakery groups, and maquiladora packaging plants accelerate sugar-reduction and corrugated adhesive procurement. What distinguishes Mexico from mature European markets is the strict enforcement of NOM-051 front-of-pack black octagon warning seals for excess sugar and calories, which compels soft-drink and sweet-bakery manufacturers to replace sucrose with soluble resistant dextrin fibers. April 2026 Mexico City GAIN filings confirm that domestic food processors are actively importing and sourcing functional fiber and texturizing ingredients to reformulate packaged retail foods [14]. Rapid growth in cross-border e-commerce shipping also boosts yellow dextrin case-sealing gum consumption.
Key takeaway: In Mexico, NOM-051 front-of-pack sugar reformulation and export corrugated box manufacturing are projected to drive leading national dextrin demand.
Brazil Dextrin Market Outlook (2026 to 2036)
Brazil's abundant domestic corn and cassava starch processing base and expanding functional dairy and beverage industry put national dextrin demand on a 7.5% CAGR path through 2036. Compared with starch-importing countries, Brazilian wet millers in Parana and Sao Paulo convert local maize and tapioca feedstocks into both soluble dietary fibers for ANVISA front-of-pack compliant foods and industrial pyrodextrins for agricultural export cartons. October 2026 Brasilia agricultural climate updates note that while El Nino weather patterns create regional crop cost pressures, Brazil's corn export and processing complex remains above 42 million metric tons [15]. Local food formulators actively specify tapioca and corn dextrins in powdered beverages and confectionery glazes.
Key takeaway: In Brazil, integrated domestic corn and cassava wet-milling and functional beverage reformulation are on course to sustain strong dextrin growth.
United States Dextrin Market Outlook (2026 to 2036)
The United States dextrin market is forecast to progress at a 7.2% CAGR from 2026 to 2036, anchored by GLP-1 companion food launches and Midwest soluble corn fiber fortification. What sets the United States apart from global markets is the massive scale of domestic corn wet-milling biorefineries operated by Ingredion and ADM along with Tate & Lyle and Cargill that supply patented soluble corn dextrins directly to national CPG brands. Corporate financial disclosures from Archer Daniels Midland Company in November 2026 show resilient third-quarter 2026 operating performance supported by ongoing investments in high-return Nutrition and Carbohydrate Solutions [16]. American snack and beverage makers rely on soluble dextrins to hit high-fiber and zero-sugar nutrition panels.
Key takeaway: In the United States, GLP-1 high-fiber food reformulation and domestic corn wet-milling scale are forecast to anchor steady dextrin expansion.
Canada Dextrin Market Outlook (2026 to 2036)
In Canada, dextrin adoption is estimated to grow at a 6.8% CAGR through 2036, driven by mandatory January 2026 Health Canada front-of-package nutrition symbol regulations and sustainable paper packaging mandates. In contrast to jurisdictions without dated labeling cutoffs, Canadian bakery and snack processors face immediate retail shelf pressure to lower saturated fat and sugars while boosting dietary fiber content using recognized novel fiber sources such as resistant maltodextrin and dextrin. August 2026 Ottawa industry records confirm that Health Canada's January 1, 2026 front-of-package labeling rules are accelerating functional and high-fiber ingredient procurement across Canada's food processing sector [17]. Canadian corrugated converters also use white and yellow dextrins in recyclable boxboard.
Key takeaway: In Canada, mandatory 2026 front-of-package sugar labeling and recyclable packaging standards are estimated to drive steady dextrin procurement.
France Dextrin Market Outlook (2026 to 2036)
France's position as Europe's premier starch biorefining and clinical prebiotic research hub places national dextrin demand on a projected 6.6% CAGR path over the 2026 to 2036 forecast period. What differentiates France from other Western European markets is the domestic production of wheat, maize, and pea starch derivatives led by Roquette in Lestrem as well as widespread Nutri-Score front-of-pack adoption across French supermarkets and artisan bakeries. April 2026 Paris food-processing data shows that France's 17,000 to 18,000 food processing enterprises are actively adapting recipes and packaging to meet post-inflation consumer value demands and AGEC single-use plastic reduction laws [18]. French packaging converters replace synthetic plastic coatings and glues using starch pyrodextrins while food brands dose soluble dextrin to upgrade Nutri-Score ratings.
Key takeaway: In France, Nutri-Score bakery and dairy reformulation and AGEC plastic-free packaging laws are projected to sustain solid dextrin demand.
Germany Dextrin Market Outlook (2026 to 2036)
Demand for dextrin in Germany is predicted to climb at a 6.4% CAGR between 2026 and 2036 across industrial corrugated board mills, pharmaceutical tablet excipient plants, and private-label health food manufacturers. Compared with Southern European markets, Germany features Europe's largest corrugated packaging and paper-converting engineering sector as well as major potato and wheat starch cooperatives that produce specialized white and yellow pyrodextrins for remoistenable envelope and label gums. September 2026 Berlin retail food analysis notes that German consumers strongly prioritize health-conscious products, organic options, and Nutri-Score-optimized private labels across Europe's largest retail food market [19]. German bakery and confectionery plants also apply potato dextrins for crisp pretzel and pastry glazes.
Key takeaway: In Germany, high-speed corrugated board adhesive consumption and Nutri-Score private-label food reformulation are predicted to uphold dextrin sales.
Japan Dextrin Market Outlook (2026 to 2036)
In Japan, dextrin market growth is slated to track at a 6.1% CAGR during 2026 to 2036, anchored by the country's pioneering FOSHU as well as Foods with Function Claims (FFC) indigestible dextrin beverage and supplement sector. What distinguishes Japan globally is the mainstream consumer habit of drinking clear RTD teas, coffees, and sodas fortified with 5 grams of indigestible dextrin (pioneered by Matsutani Chemical's Fibersol-2) to moderate post-meal blood triglyceride and glucose spikes. April 2026 Tokyo food-processing records confirm that health foods and soft drinks remain resilient growth segments within Japan's food manufacturing industry [20]. Japanese pharmaceutical and functional food blenders also use branched cyclodextrins and pyrodextrins as odor-masking carriers.
Key takeaway: In Japan, FOSHU and FFC indigestible-dextrin RTD beverages and glycemic-control supplements are slated to anchor consistent market growth.
Spain Dextrin Market Outlook (2026 to 2036)
Spain's expanding packaged food export sector and Mediterranean horticultural corrugated box industry place national dextrin sales on course for a 5.9% CAGR from 2026 to 2036. Rather than focusing solely on domestic retail, Spanish food processors and packaging converters use corn and potato dextrins to glaze exported bakery and confectionery products and to laminate heavy-duty corrugated produce trays for European supermarket distribution. March 2026 Madrid agricultural trade records show Spain's status as the European Union's third-largest agricultural powerhouse with rising demand for food processing ingredients [21]. Spanish sports-nutrition and clinical-nutrition packers also import soluble prebiotic dextrins for powder sachets.
Key takeaway: In Spain, export bakery glaze applications and heavy-duty horticultural corrugated packaging are on course to support steady dextrin expansion.
Full report country CAGRs cover: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Who are the notable companies in the dextrin market?
Roquette Freres SA, Ingredion Incorporated, Tate and Lyle plc, Archer Daniels Midland Company, Cargill Incorporated, Matsutani Chemical Industry Co., Ltd., Agrana Beteiligungs-AG, Emsland Group, Avebe U.A., and Grain Processing Corporation are the notable companies in the dextrin market.
Competitive positioning in the dextrin market separates vertically integrated global starch wet millers, Japanese indigestible-dextrin pioneers, and multi-ingredient nutrition and flavor formulators. Roquette Freres SA and Ingredion Incorporated lead global manufacturing of clinical resistant dextrins and pharmaceutical pyrodextrins while Tate and Lyle plc and Matsutani Chemical Industry Co., Ltd. supply soluble corn and tapioca fibers. Archer Daniels Midland Company and Cargill Incorporated operate massive North American and international corn wet-milling complexes and Grain Processing Corporation for food-grade and packaging dextrins. Meanwhile, Agrana Beteiligungs-AG and Emsland Group join Avebe U.A. in co-formulating dextrin fibers and carriers into finished bakery, beverage, and supplement systems.
- Specialty Resistant Dextrin and Starch Biorefiners: Roquette Freres SA and Ingredion Incorporated along with Tate and Lyle plc and Matsutani Chemical Industry Co., Ltd. manufacture clinically backed soluble resistant dextrins and pharmaceutical pyrodextrins.
- Global Wet-Milling and Industrial Dextrin Producers: Archer Daniels Midland Company and Cargill Incorporated along with Grain Processing Corporation and Agrana Beteiligungs-AG supply bulk corn dextrins, corrugated adhesive gums, and fortified nutrition premixes.
- Integrated Nutrition, Texture, and Flavor Formulators: Emsland Group and Avebe U.A. combine soluble dextrin carriers with spray-dried flavor encapsulants and clean-label bakery systems.
Competitive Benchmarking: Dextrin Market
Table 8: Competitive Benchmarking for the Dextrin Market (qualitative capability ratings), 2026
| Company | Prebiotic Fiber Clinical Dossier | Wet-Milling & Roasting Scale | Industrial & Packaging Adhesive Fit | Geographic Reach |
|---|---|---|---|---|
| Roquette Freres SA | High | High | High | Global maize, wheat, pea, and potato biorefineries; EUR 2,586M H1 2026 turnover across Europe, Americas, and APAC |
| Ingredion Incorporated | High | High | High | Global corn and tapioca wet-milling network; announced GBP 3.7B offer to acquire Tate & Lyle in June 2026 |
| Tate and Lyle plc | High | High | Medium | Global PROMITOR soluble fiber and mouthfeel centers; delivered 18.3B fiber servings through March 2026 |
| Archer Daniels Midland Company | High | High | High | Global Carbohydrate Solutions wet mills and Fibersol-2 joint-venture distribution network |
| Cargill Incorporated | Medium | High | High | Global corn, wheat, and tapioca starch and dextrin complexes across North America, Europe, and APAC |
| Matsutani Chemical Industry Co., Ltd. | High | Medium | Low | Japan headquarters and global Fibersol-2 indigestible dextrin clinical and patent leadership |
| Agrana Beteiligungs-AG | Medium | Unscored | Unscored | Global Taste, Texture & Health and gut-microbiome premix co-formulation centers |
| Emsland Group | Medium | Unscored | Low | Global food biosciences, flavor encapsulation, and clean-label bakery texturizing network |
| Avebe U.A. | Medium | Unscored | Unscored | Global taste modulation, bakery glaze, and nutritional beverage formulation centers across 50+ countries |
| Grain Processing Corporation | Low | High | High | North American and international MALTRIN maltodextrin and specialty corn dextrin wet-milling plants |
Evaluation basis: Prebiotic Fiber Clinical Dossier rates published randomized human trials and FDA/EFSA/FOSHU dietary fiber authorizations for resistant dextrin grades, whereas Wet-Milling & Roasting Scale measures multi-crop corn and tapioca dextrinization capacity. Industrial & Packaging Adhesive Fit assesses tailored pyrodextrin viscosity and tack grades for paperboard and foundry buyers.
Key Developments in the Dextrin Market
- Roquette launched its WELLENCE GF 1229 plant-based texture solution for gluten-free bakery on October 27, 2026 ahead of Fi Europe, expanding its specialty carbohydrate and hydrocolloid portfolio for bread volume and softness [22].
- Avebe U.A. published its clean-label and processed-food formulation framework on August 6, 2026, detailing how recognizable starch and fiber ingredients help food brands meet consumer transparency standards [23].
- Roquette announced its 2025 full-year financial results on March 19, 2026, reporting EUR 4.9 billion in turnover and EUR 612 million in full-year EBITDA driven by food specialties and pharmaceutical excipients [24].
Key Players in the Dextrin Market
Specialty Resistant Dextrin and Starch Biorefiners
- Roquette Freres SA
- Ingredion Incorporated
- Tate and Lyle plc
- Matsutani Chemical Industry Co., Ltd.
Global Wet-Milling and Industrial Dextrin Producers
- Archer Daniels Midland Company
- Cargill Incorporated
- Grain Processing Corporation
- Agrana Beteiligungs-AG
Integrated Nutrition, Texture, and Flavor Formulators
- Emsland Group
- Avebe U.A.
Dextrin Market - Report Scope
Table 9: Report Scope for the Dextrin Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Production Modification; Botanical Starch; Application; Physical Form; Sales Channel |
| Quantitative Units | USD Million |
| Market Definition | Includes commercial B2B supplier revenue from pyro-converted starch dextrins (yellow pyrodextrins, white dextrins, canary British gums) and enzymatically refined indigestible/resistant dextrins (soluble corn, tapioca, potato, and wheat dextrin fibers) used across dietary fiber fortification, industrial paper/corrugated adhesives, bakery glazes, and pharmaceutical tableting/encapsulation. Category Scope Note: Excludes standard digestible maltodextrins (DE 3 to 20), glucose/corn syrups, native unmodified starches, and cyclodextrins. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Mexico, Brazil, United States, Canada, France, Germany, Japan, Spain, and additional countries in the full report |
| Key Companies Covered | Roquette Freres SA, Ingredion Incorporated, Tate and Lyle plc, Archer Daniels Midland Company, Cargill Incorporated, Matsutani Chemical Industry Co., Ltd., Agrana Beteiligungs-AG, Emsland Group, Avebe U.A., Grain Processing Corporation |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Dextrin Market - Research Methodology
Table 10: Research Methodology for the Dextrin Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with starch wet-milling roasting engineers, CPG beverage and bakery fiber formulators, corrugated adhesive chemists, and pharmaceutical excipient buyers to validate pricing and inclusion rates. |
| Secondary Research | Analysis of U.S. FDA GRAS Notice Inventory filings (GRN 1170, GRN 1045), USDA FAS Food Processing Ingredients and Retail Foods Annual reports, peer-reviewed clinical nutrition trials, and corporate financial disclosures. |
| Market Sizing and Forecasting | Top-down parent modified starch and dietary fiber baselines reconciled against bottom-up acid-roasted pyrodextrin and resistant dextrin tonnage across food, pharma, and industrial channels from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight front-of-pack sugar/fiber labeling mandates (NOM-051, Health Canada FOP, Nutri-Score), FOSHU/FFC beverage claims, and corrugated packaging output across eight key countries. |
| Operational Benchmark Traceability | Clinical dosing, regulatory fiber limits, and M&A benchmarks in Tables 2, 3, and 4 trace to Frontiers in Nutrition May 2026, FDA GRN 1170/1045, and Ingredion/Tate & Lyle/Roquette 2026 disclosures. |
| Data Triangulation and Validation | Revenue estimates isolate thermal pyrodextrins and non-digestible resistant dextrins while strictly excluding high-DE digestible maltodextrins, native starches, and synthetic packaging resins. |
Dextrin Market by Segments
Dextrin Market segmented by Production Modification:
- Yellow Pyrodextrin High Solubility
- White Dextrin Low Viscosity
- Resistant Prebiotic Dextrin Fibersol-2
- Canary British Gum Medium Conversion
Dextrin Market segmented by Botanical Starch:
- Corn Starch Acid Roasting
- Potato Starch Derived Dextrin
- Tapioca Starch Dextrin
- Wheat and Waxy Maize Starch Dextrin
Dextrin Market segmented by Application:
- Soluble Dietary Prebiotic Fiber Supplementation
- Industrial Adhesives Corrugated Board and Envelope Gums
- Bakery Glazes and Confectionery Crisp Coatings
- Pharmaceutical Tablet Binder and Encapsulation Carrier
- Foundry Core Binding and Textile Printing
Dextrin Market segmented by Physical Form:
- Spray-Dried and Agglomerated Powder
- Fine Roasted Granular Blend
- Liquid Aqueous Dextrin Solution
- Instant Cold-Water Dispersible Flakes
Dextrin Market segmented by Sales Channel:
- Direct to Food and Packaging Manufacturers
- Specialty Carbohydrate and Chemical Distributors
- Nutraceutical Contract Blenders
- Digital B2B Ingredient Supply
Dextrin Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Perreau, C., Tomassi, D., Capronnier, O., Carton, T., Thabuis, C., & Guerin-Deremaux, L. (2026, May 19). Resistant dextrin promotes beneficial fecal bacteria in high and low fiber diet populations: a randomized, double-blinded, controlled pilot study. Frontiers in Nutrition, 13, 1810842.
- [2] Tate & Lyle PLC. (2026, June 8). Recommended Acquisition of Tate & Lyle PLC by Ingredion Incorporated. Tate & Lyle PLC Corporate Newsroom.
- [3] Sun, Y., Wang, L., Li, Y., Bai, X., Yang, R., Wang, L., & Cao, R. (2026, May 7). Molecular Interactions of Resistant Dextrin with Wheat Starch and Gluten: Structural Dynamics and Macromolecular Network Formation. Foods (MDPI), 15(10), 1620.
- [4] U.S. Food and Drug Administration. (2024, October 22). GRN No. 1170: Resistant dextrin from tapioca in powder or syrup form for dietary fiber and texturizing applications. FDA GRAS Notice Inventory.
- [5] Tate & Lyle PLC. (2026, August 26). Tate & Lyle adds new purpose target to improve everyday consumer health through fibre fortification. Tate & Lyle PLC Corporate Newsroom.
- [6] Roquette Freres SA. (2026, September 24). Strategic Transformation Supports Roquette's H1 2026 Performance. Roquette Corporate Press Releases.
- [7] Archer Daniels Midland Company. (2026, August 4). ADM Reports Second Quarter 2026 Results and Carbohydrate Solutions Outlook. ADM Corporate News Releases.
- [8] Yang, P., Zhao, Z., Liu, Y., He, J., Chen, H., Zhang, K., Wang, Y., Sun, Y., Wang, Y., Liu, Y., Duan, S., Guo, J., Zhou, Q., Zhao, L., Sang, Y., Wang, R., & Yu, S. (2026, January 26). Study on the efficacy and mechanism of resistant dextrin combined with mulberry leaf extract in ameliorating type 2 diabetes mellitus. Food & Function, 17(2), 902-916.
- [9] Roquette Freres SA. (2025, May 5). Roquette Announces a New Organization following the Acquisition of Emsland Group Pharma Solutions. Roquette Corporate Press Releases.
- [10] Ingredion Incorporated. (2026, July 6). Ingredion to Spotlight Next-Generation Solutions for Texture, Clean Labels and Positive Nutrition at IFT FIRST 2026. Ingredion Corporate Newsroom.
- [11] Chen, S., Zhang, L., Zong, A., Gan, Z., Zhang, X., Du, F., Liu, H., & Xu, T. (2026, March 5). Effects of resistant dextrin on glycemic traits: a systematic review and meta-analysis of randomized controlled trials. Nutrition Journal, 25, 45.
- [12] Kapusniak, K., Wojcik, M., Rosicka-Kaczmarek, J., Miskiewicz, K., Pacholczyk-Sienicka, B., & Juszczak, L. (2024, October 17). Molecular Structure and Properties of Resistant Dextrins from Potato Starch Prepared by Microwave Heating. International Journal of Molecular Sciences (MDPI), 25(20), 11202.
- [13] Guo, S., Han, Y., Wang, S., Liu, Y., Li, F., & Xu, H. (2025, June 24). Introduction of a branching enzyme in the preparation of resistant dextrin: Structural characterization, physicochemical, and functional properties. International Journal of Biological Macromolecules, 319(Pt 2), 145503.
- [14] USDA Foreign Agricultural Service. (2026, April 6). Mexico: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report MX2026-0022.
- [15] USDA Foreign Agricultural Service. (2026, October 13). Brazil: Bracing for Impact - How the 2026 El Nino Affects Brazil's Agriculture. U.S. Department of Agriculture GAIN Report BR2026-0040.
- [16] Archer Daniels Midland Company. (2026, November 3). ADM Reports Third Quarter 2026 Results. ADM Corporate News Releases.
- [17] USDA Foreign Agricultural Service. (2026, August 27). Canada: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report CA2026-0022.
- [18] USDA Foreign Agricultural Service. (2026, April 3). France: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report FR2026-0003.
- [19] USDA Foreign Agricultural Service. (2026, September 25). Germany: Retail Foods Annual. U.S. Department of Agriculture GAIN Report GM2026-0016.
- [20] USDA Foreign Agricultural Service. (2026, April 1). Japan: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report JA2026-0012.
- [21] USDA Foreign Agricultural Service. (2026, March 31). Spain: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report SP2026-0003.
- [22] Roquette Freres SA. (2026, October 27). Introducing a New Ingredient Solution for Gluten-Free Bakery: WELLENCE GF 1229. Roquette Corporate Press Releases.
- [23] Avebe U.A.. (2026, August 6). Beyond the Label: Why Processed Food Definitions Matter. Avebe U.A. Media Releases.
- [24] Roquette Freres SA. (2026, March 19). Roquette 2025 Full-Year Results Announcement. Roquette Corporate Press Releases.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the dextrin market in 2026 and what is forecast for 2036?
- Which front-of-pack fiber mandates and packaging adhesive trends support demand for dextrin?
- Why does Yellow Pyrodextrin High Solubility lead the production modification category?
- Why does Corn Starch Acid Roasting lead the botanical starch category globally?
- How do growth rates differ across Mexico and Brazil versus the United States and France?
- Which leading companies manufacture clinical resistant dextrins versus industrial pyrodextrins today?
- What thermal roasting and chromatographic purification costs restrain low-tier dextrin producers?
- What should food and packaging buyers evaluate before qualifying a dextrin grade?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Production Modification, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Production Modification, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Production Modification, 2026 to 2036
- Yellow Pyrodextrin High Solubility
- White Dextrin Low Viscosity
- Resistant Prebiotic Dextrin Fibersol-2
- Canary British Gum Medium Conversion
- Y-o-Y Growth Trend Analysis By Production Modification, 2021 to 2025
- Absolute $ Opportunity Analysis By Production Modification, 2026 to 2036
- Global Market Analysis and Forecast, By Botanical Starch, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Botanical Starch, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Botanical Starch, 2026 to 2036
- Corn Starch Acid Roasting
- Potato Starch Derived Dextrin
- Tapioca Starch Dextrin
- Wheat and Waxy Maize Starch Dextrin
- Y-o-Y Growth Trend Analysis By Botanical Starch, 2021 to 2025
- Absolute $ Opportunity Analysis By Botanical Starch, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- Soluble Dietary Prebiotic Fiber Supplementation
- Industrial Adhesives Corrugated Board and Envelope Gums
- Bakery Glazes and Confectionery Crisp Coatings
- Pharmaceutical Tablet Binder and Encapsulation Carrier
- Foundry Core Binding and Textile Printing
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Physical Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Physical Form, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Physical Form, 2026 to 2036
- Spray-Dried and Agglomerated Powder
- Fine Roasted Granular Blend
- Liquid Aqueous Dextrin Solution
- Instant Cold-Water Dispersible Flakes
- Y-o-Y Growth Trend Analysis By Physical Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Physical Form, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct to Food and Packaging Manufacturers
- Specialty Carbohydrate and Chemical Distributors
- Nutraceutical Contract Blenders
- Digital B2B Ingredient Supply
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Production Modification
- By Botanical Starch
- By Application
- By Physical Form
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Roquette Freres SA
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Ingredion Incorporated
- Tate and Lyle plc
- Archer Daniels Midland Company
- Cargill Incorporated
- Matsutani Chemical Industry Co., Ltd.
- Agrana Beteiligungs-AG
- Emsland Group
- Avebe U.A.
- Grain Processing Corporation
- Roquette Freres SA
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Production Modification, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Botanical Starch, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 5: Global Market Value (USD Million) Forecast by Physical Form, 2021 to 2036
- Table 6: Global Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Production Modification, 2021 to 2036
- Table 9: North America Market Value (USD Million) Forecast by Botanical Starch, 2021 to 2036
- Table 10: North America Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 11: North America Market Value (USD Million) Forecast by Physical Form, 2021 to 2036
- Table 12: North America Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 13: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Million) Forecast by Production Modification, 2021 to 2036
- Table 15: Latin America Market Value (USD Million) Forecast by Botanical Starch, 2021 to 2036
- Table 16: Latin America Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 17: Latin America Market Value (USD Million) Forecast by Physical Form, 2021 to 2036
- Table 18: Latin America Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Million) Forecast by Production Modification, 2021 to 2036
- Table 21: Western Europe Market Value (USD Million) Forecast by Botanical Starch, 2021 to 2036
- Table 22: Western Europe Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 23: Western Europe Market Value (USD Million) Forecast by Physical Form, 2021 to 2036
- Table 24: Western Europe Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Million) Forecast by Production Modification, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Million) Forecast by Botanical Starch, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Million) Forecast by Physical Form, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 31: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Million) Forecast by Production Modification, 2021 to 2036
- Table 33: East Asia Market Value (USD Million) Forecast by Botanical Starch, 2021 to 2036
- Table 34: East Asia Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 35: East Asia Market Value (USD Million) Forecast by Physical Form, 2021 to 2036
- Table 36: East Asia Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Million) Forecast by Production Modification, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Million) Forecast by Botanical Starch, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Million) Forecast by Physical Form, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Million) Forecast by Production Modification, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Million) Forecast by Botanical Starch, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Million) Forecast by Physical Form, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Production Modification, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Production Modification, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Production Modification
- Figure 6: Global Market Value Share and BPS Analysis by Botanical Starch, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Botanical Starch, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Botanical Starch
- Figure 9: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Application
- Figure 12: Global Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Physical Form
- Figure 15: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Sales Channel
- Figure 18: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Production Modification, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Production Modification, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Production Modification
- Figure 32: North America Market Value Share and BPS Analysis by Botanical Starch, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Botanical Starch, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Botanical Starch
- Figure 35: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Application
- Figure 38: North America Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Physical Form
- Figure 41: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Sales Channel
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Production Modification, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Production Modification, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Production Modification
- Figure 48: Latin America Market Value Share and BPS Analysis by Botanical Starch, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Botanical Starch, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Botanical Starch
- Figure 51: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Application
- Figure 54: Latin America Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Physical Form
- Figure 57: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Production Modification, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Production Modification, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Production Modification
- Figure 64: Western Europe Market Value Share and BPS Analysis by Botanical Starch, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Botanical Starch, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Botanical Starch
- Figure 67: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Application
- Figure 70: Western Europe Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Physical Form
- Figure 73: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Production Modification, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Production Modification, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Production Modification
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Botanical Starch, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Botanical Starch, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Botanical Starch
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Application
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Physical Form
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Production Modification, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Production Modification, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Production Modification
- Figure 96: East Asia Market Value Share and BPS Analysis by Botanical Starch, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Botanical Starch, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Botanical Starch
- Figure 99: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Application
- Figure 102: East Asia Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Physical Form
- Figure 105: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Production Modification, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Production Modification, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Production Modification
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Botanical Starch, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Botanical Starch, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Botanical Starch
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Physical Form
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Production Modification, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Production Modification, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Production Modification
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Botanical Starch, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Botanical Starch, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Botanical Starch
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Physical Form
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the dextrin market in 2026, and what is forecast for 2036?
FMI estimates that the 2025 global dextrin market size stood at USD 526.0 million before advancing to USD 560.5 million during 2026. Overall industry valuation is on course to hit USD 1,092.3 million in 2036 as food brands and packaging converters expand prebiotic fiber and bio-adhesive use.
What is the CAGR for the dextrin market from 2026 to 2036?
The dextrin sector is projected to expand at a 6.9% CAGR over the 2026 to 2036 window, adding USD 531.8 million in incremental revenue across soluble dietary fiber and industrial adhesive applications.
Which production modification segment leads the dextrin market?
Yellow Pyrodextrin High Solubility is anticipated to hold 49.8% of production modification demand in 2026 since acid-roasted thermal conversion provides both high-solids adhesive tack and resistant-fiber precursor feedstock.
Which botanical starch segment leads the dextrin market?
Corn Starch Acid Roasting represents an estimated 53.5% of the botanical starch category in 2026 owing to large-scale maize wet-milling infrastructure across North America, Europe, and Asia.
Which country has a notable growth outlook during the assessment period?
Mexico leads national expansion projections at an 8.1% CAGR through 2036, driven by NOM-051 front-of-pack sugar-reduction reformulation and cross-border e-commerce corrugated packaging demand.
Who are the key players in the market?
Major commercial suppliers include Roquette and Ingredion, while Tate & Lyle and Matsutani Chemical anchor clinical resistant dextrin production. Additional active participants include ADM and Cargill, whereas Grain Processing Corporation supplies specialty maize dextrins. Meanwhile, Agrana Beteiligungs-AG and Emsland Group in addition to Avebe U.A. complete the primary supplier landscape.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
