

- Market Size (2026)
- USD 14.5 Bn
- Forecast (2036)
- USD 21.9 Bn
- CAGR (2026 to 2036)
- 4.2%
How big is Disposable Cups Market in 2026?
Global disposable cups turnover advances at a 4.2% CAGR over the 2026 to 2036 forecast period. Worldwide foodservice cup spending climbs from USD 13.9 billion in 2025 and USD 14.5 billion in 2026 to USD 21.9 billion by 2036.
Replacing conventional polyethylene-lined paper cups and banned expanded polystyrene foam drinkware with repulpable fiber and clarified recycled-PET containers is reshaping unit economics across global foodservice beverage chains. For instance, in July 2025, Huhtamaki Oyj launched new home- and industrial-compostable paperboard cups engineered with a bio-based barrier coating that holds total plastic content below 10% [1]. Across the global beverage foodservice sector, sales stand at USD 13.9 billion in 2025 against USD 14.5 billion in 2026, with Future Market Insights projecting demand to hit USD 21.9 billion by 2036 at a 4.2% CAGR for a net gain of USD 7.4 billion. Single-Wall & Double-Wall Hot Beverage Cups anchor the product format / style hierarchy at 34.5% share in 2026 as quick-service drive-thrus convert takeaway coffee volume into repulpable commercial paper cups that pass municipal paper-mill recovery audits.
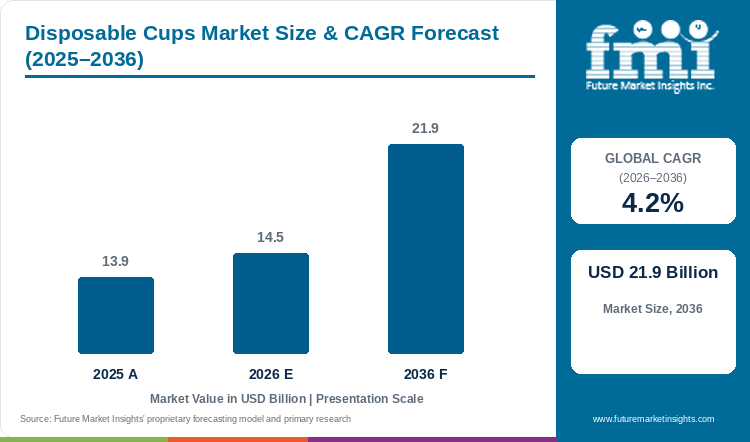
Key Market Trends & Insights
- By product format / style: Single-Wall & Double-Wall Hot Beverage Cups lead with 34.5% share in 2026 on the strength of daily commuter coffee and tea servings across café and drive-thru lanes.
- By material substrate: Virgin Chemical Kraft Pulp captures 45.0% of 2026 substrate sales due to hot-liquid food-contact hygiene regulations and ultrasonic side-seam bonding stiffness.
- By end-use application: Quick-Service Restaurants & Coffee Chains generate 31.0% of 2026 application revenue through high-speed cup dispensing and custom-printed brand promotional runs.
- By barrier / coating property: Aqueous Water-Based Barrier holds 37.2% of 2026 barrier turnover because dispersion coatings break down in standard paperboard hydrapulpers without specialized delaminating drums.
Regional Highlights
- State-level prohibitions on unrecyclable plastic-lined drinkware and high independent café density place Australia ahead of all evaluated countries at a 5.1% CAGR from 2026 to 2036.
- Tourism beverage traffic in Spain (4.7%) and VerpackG recyclability rules in Germany (4.4%) outpace konbini coffee cup demand in Japan (3.7%) and high-street takeaways in the UK (3.4%).
Market Size & Forecast
Table 1: Market Size and Forecast for the Disposable Cups Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 13.9 billion |
| Estimated Market Size in 2026 | USD 14.5 billion |
| Projected Market Size by 2036 | USD 21.9 billion |
| CAGR, 2026 to 2036 | 4.2% |
| Added Revenue, 2026 to 2036 | USD 7.4 billion |
Cup converting margins vary across national markets where municipal paper-mill repulping thresholds and mandatory dine-in reuse quotas govern foodservice procurement. Beverage chains operating in Germany and the United Kingdom are replacing conventional LDPE extrusion linings with water-based dispersion barriers and PLA barrier coated beverage board to qualify for standard paper recycling streams. In October 2025, Eurostat reported in its Packaging waste statistics release that paper and cardboard accounted for 40.4% (32.3 million tonnes) of all packaging waste generated in the European Union while plastic accounted for 19.8% (15.8 million tonnes), reinforcing regulatory pressure to keep fiber-composite cups below polymer contamination limits [2]. Therefore, multi-unit restaurant operators are consolidating cup and lid tenders around converters that provide certified chain-of-custody cupstock and repulpability certificates.
Beverage Cup Throughput and Cupstock Conversion Sizing
Table 2: Beverage Cup Throughput and Cupstock Conversion Sizing for the Disposable Cups Market (USD billion, million tonnes, and USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 (Base Estimate) | 2026 (Estimated) | 2036 (Forecast) |
|---|---|---|---|
| Market size (USD billion, FMI valuation) | 13.9 | 14.5 | 21.9 |
| Cupstock board & polymer sheet throughput (million tonnes, modeled) | 4.4 to 4.7 | 4.6 to 4.9 | 6.7 to 7.1 |
| Commercial disposable cups produced (billion units, modeled) | 385.0 to 405.0 | 400.0 to 422.0 | 575.0 to 610.0 |
| Average converter realization per 1,000 cups (USD, modeled) | 34.30 to 36.10 | 34.40 to 36.20 | 35.90 to 38.10 |
Operational traceability note: Market size reflects FMI primary and secondary triangulation while cupstock and sheet throughput and converter realization ranges represent FMI modeled operational estimates calibrated against Eurostat paperboard and plastic packaging accounts and APCO consumption datasets at an average cup weight of 10.5 to 12.0 grams.
Per Capita & Foodservice Outlet Procurement Sizing
Single-use hot and cold beverage cups remain an essential operational input for high-throughput coffee bars and drive-thru restaurant lanes as well as stadium concessions. Preventing seam wicking on hot espresso drinks and condensation buckling on iced beverages requires tight caliper control across 230 to 320 gsm cupstock board. Furthermore, foodservice buyers increasingly source cups alongside fiber-molded paper cup lids to eliminate polystyrene lid components.
Table 3: Per Capita and Converter Spending Indicators for the Disposable Cups Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 (Base Estimate) | 2026 (Estimated) | 2036 (Forecast) |
|---|---|---|---|
| World population (billion, UN demographic baseline) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD, derived ratio) | 1.69 | 1.75 | 2.45 |
| Spend per 1,000 people (USD, derived ratio) | 1,688.94 | 1,746.99 | 2,446.93 |
| Annual disposable cups per capita (units, modeled range) | 47 to 49 | 48 to 51 | 64 to 68 |
Table 4: Facility & Institutional Procurement Indicators for the Disposable Cups Market (USD and percentages), mixed reporting years from 2024 to 2026
| Metric | Value | Reference Basis & Traceability |
|---|---|---|
| Market size, 2026 | USD 14.5 billion | FMI 2026 report valuation |
| Active QSR, café & institutional beverage outlets globally | 1.45 million outlets | FMI modeled foodservice beverage outlet universe (2025 base) |
| Average annual disposable cup spend per outlet | USD 10,000 | Derived ratio of 2026 valuation to modeled active outlets |
| Quick-service restaurants & coffee chains revenue, 2026 | USD 4.50 billion | Derived from 31.0% leading end-use share of USD 14.5 billion |
Analyst Perspective
"Coffee and quick-service chains are shifting multi-year cup contracts toward aqueous-coated cupstock and clarified rPET formats that satisfy municipal recycling thresholds. Higher coating dispersion costs and ultrasonic seam-sealing adjustments still require line qualification before converters retire conventional polyethylene-lined board."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the disposable cups market segmented?
The disposable cups market is segmented by product format / style, material substrate, end-use application, barrier / coating property, and region. In 2026, Single-Wall & Double-Wall Hot Beverage Cups are projected at 34.5%, Virgin Chemical Kraft Pulp at 45.0%, Quick-Service Restaurants & Coffee Chains at 31.0%, and Aqueous Water-Based Barrier at 37.2%.
By product format / style: Single-Wall & Double-Wall Hot Beverage Cups, Thermoformed Clear Cold Drink Cups, Ripple-Wall & Insulated Jacket Cups, and Portion & Sampling Cups.
By material substrate: Virgin Chemical Kraft Pulp, Molded Bagasse & Recycled Fiber Pulp, and Thermoformed PET, rPET & Polypropylene Sheet.
By end-use application: Quick-Service Restaurants & Coffee Chains, Institutional & Workplace Foodservice, Convenience Retail & Transit Hubs, and Hospitality, Events & Cinema Concessions.
By barrier / coating property: Aqueous Water-Based Barrier, PLA & Bio-Wax Coating, and Standard Polyethylene (PE) Lined & Monomaterial Recyclable.
Why Do Single-Wall & Double-Wall Hot Beverage Cups Lead the Disposable Cups Market by Product Format / Style?
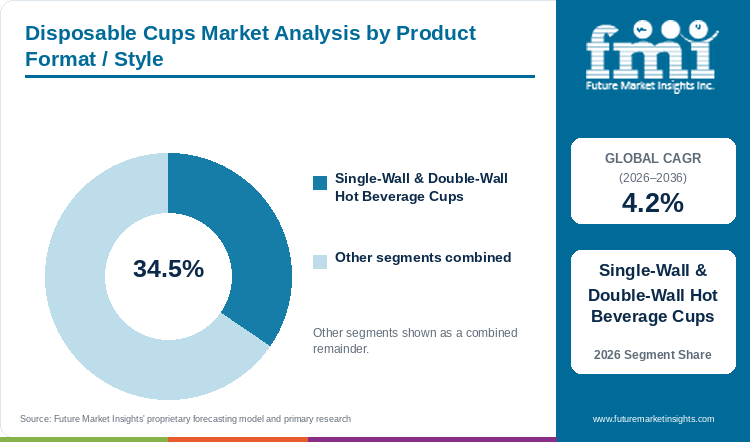
By product format / style, Single-Wall & Double-Wall Hot Beverage Cups hold 34.5% in 2026, facilitated by specialty coffee demand.
Table 5: Product Format / Style Share for the Disposable Cups Market (percentage share), 2026
| Product Format / Style | Share (2026) |
|---|---|
| Single-Wall & Double-Wall Hot Beverage Cups | 34.5% |
| Other Segments Combined | 65.5%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Format / Style Leadership and Market Growth for the Disposable Cups Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.2% |
| Leading Segment | Single-Wall & Double-Wall Hot Beverage Cups |
Single-wall and double-wall hot beverage cups capture the largest format share because commuter coffee shops and bakery cafés dispense billions of 8-ounce to 16-ounce espresso and tea servings every morning. Double-wall constructions bond an outer insulating paperboard sleeve directly over the primary cup body, which eliminates the inventory expense and counter labor of slipping separate corrugated clutches onto hot drinks. In addition to this, precision top-curl rim forming across single-serve beverage cups ensures snap-tight engagement with sip-through lids so hot liquids do not spill in vehicle cupholders. High-speed rotary cup-forming machines running at 220 to 300 cups per minute keep unit conversion costs competitive across national café tenders.
- Single-Wall & Double-Wall Hot Beverage Cups account for 34.5% of product format / style revenue in 2026 because integral insulated sleeves eliminate separate cardboard cup clutches.
- In March 2026, Huhtamaki Oyj published its Annual Report 2025 detailing high-speed rotary forming of insulated double-wall paper hot cups and fiber lids for foodservice chains [3].
What Makes Virgin Chemical Kraft Pulp Central to the Material Substrate Category?
Virgin Chemical Kraft Pulp is estimated to represent 45.0% of material substrate demand in 2026, underpinned by side-seam sealing stiffness.
Solid bleached sulfate and unbleached virgin chemical kraft pulp board dominate substrate consumption because FDA and European BfR XXXVI food-contact hygiene regulations restrict unlined mechanically recycled wastepaper from touching hot beverages. Long virgin softwood and hardwood cellulose fibers provide the wet tensile stiffness required to prevent cup sidewalls from bowing when filled with 92 degrees Celsius coffee, while short-fiber birch outer plies deliver smooth flexographic printing surfaces. Besides this, virgin kraft board forms uniform ultrasonic bottom knurls and side seams compared with brittle bagasse or molded fiber cups. Converters increasingly source FSC- and PEFC-certified virgin cupstock from integrated Nordic and North American board mills to satisfy corporate deforestation audits.
- Virgin Chemical Kraft Pulp commands 45.0% of material substrate demand in 2026 due to direct hot-beverage hygiene rules and wet ring-crush stiffness.
- In November 2025, Sonoco Products Company consolidated its consumer paperboard and rigid paper container operations under two regional geographies to streamline fiber substrate conversion [4].
Why Do Quick-Service Restaurants & Coffee Chains Anchor the End-Use Application Category?
Quick-Service Restaurants & Coffee Chains are projected to capture 31.0% of end-use application revenue in 2026, reinforced by drive-thru orders.
Global quick-service restaurant chains and specialty coffee operators anchor end-use turnover because drive-thru lanes and mobile-order pickup channels account for the majority of commercial beverage transactions. Unlike office water-cooler or hospital ward cups that prioritize plain white stock, QSR chains treat custom-printed hot and cold cups as primary brand billboards alongside fast food containers. Furthermore, rapid expansion in iced espresso and cold-foam drinks has prompted QSR chains to pair paper hot cups with crystal-clear rPET cold cups that display layered beverages. Multi-year QSR supply contracts require converters to maintain regional safety stock across dozens of distribution centers.
- Quick-Service Restaurants & Coffee Chains secure 31.0% of end-use application sales in 2026 on the strength of drive-thru traffic and seasonal iced beverage launches.
- In September 2025, Amcor plc presented lightweight recyclable beverage cups and high-speed dispensing closure solutions for foodservice and beverage brands at Drinktec [5].
What Supports Aqueous Water-Based Barrier Leadership within Barrier / Coating Property?
Aqueous Water-Based Barrier secures 37.2% of barrier / coating property demand in 2026, supported by standard paper-mill repulpability.
Aqueous dispersion barrier coatings applied inline on paperboard machines have overtaken conventional polyethylene extrusion films as the leading value segment because water-based acrylic and styrene-butadiene dispersions break down cleanly in standard paper-mill hydrapulpers. Whereas traditional 15-gram-per-square-meter LDPE linings require specialized delaminating mills and trigger high composite-packaging EPR fees, aqueous-coated cupstock achieves 90% to 95% fiber yield in mixed-paper recycling. In addition to this, aqueous coatings avoid the industrial composting infrastructure bottlenecks faced by polylactic acid linings across UV-barrier paper packaging and beverage board sectors. Optimizing ultrasonic horn pressure and dwell time ensures leak-free bottom seals on aqueous-coated cup blanks.
- Aqueous Water-Based Barrier represents 37.2% of barrier / coating property revenue in 2026 because dispersion-lined paper cups repulp in standard wastepaper mills.
- In January 2025, the European Union published Regulation (EU) 2025/40 establishing strict design-for-recycling grades that penalize non-repulpable plastic-paper composite cups [6].
What are the drivers, restraints, and opportunities in the disposable cups market?
State and national bans on expanded polystyrene foam alongside drive-thru coffee and cold-drink growth support recurring volume in the Disposable Cups Market while mandatory dine-in reuse quotas and bleached kraft pulp inflation restrain margins. Repulpable aqueous-coated and 50%-rPET cups create premium contract opportunities through 2036.
- Driver: State and municipal bans on expanded polystyrene foam cups and growing drive-thru specialty beverage sales are shifting foodservice operators into higher-value paperboard and rPET cups through 2036.
- Restraint: Mandatory reusable cup quotas for dine-in foodservice in Europe and bleached chemical kraft pulp price volatility constrain single-use volume growth and converter margins through 2036.
- Opportunity: Scaling repulpable aqueous-dispersion hot cups and clarified post-consumer rPET cold cups with fiber lids is expected to capture multi-year QSR sustainability tenders through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Legislative bans on expanded polystyrene foam drinkware and the proliferation of drive-thru coffee and smoothie chains are driving sustained value expansion across the disposable cups sector. When foodservice chains replace low-cost EPS foam cups with double-wall kraft paper cups or molded fiber containers, average converter unit revenue rises by 35% to 60% per thousand pieces. In December 2025, the Australian Packaging Covenant Organisation reported in its 2023-24 consumption and recovery release that Australia achieved a 66% recovery rate for paper and paperboard packaging while cutting problematic single-use plastics by 46% from baseline levels [7]. Foodservice operators consequently specify certified recyclable paperboard and mono-material rPET cups to meet national packaging targets.
Risk Assessment of the Disposable Cups Market: Operational and Supply Friction
Statutory reuse mandates for on-premise dining and fluctuations in bleached chemical kraft cupstock and food-grade rPET pellet prices represent the primary headwinds limiting converter margin expansion. Across Germany and France as well as several European municipalities, cafés and quick-service restaurants must offer reusable cup and takeaway container systems alongside or in place of single-use cups for dine-in orders. In March 2025, Berry Global Group announced that its reusable plastic cups were selected for the collaborative Borrow Cup returnable cup initiative in Glasgow, showing how municipal returnable schemes compete directly with single-use cups in urban centers [8]. Meanwhile, running aqueous-coated board on legacy heat-seal cup machines without ultrasonic retrofits can cause pinhole seam leaks in hot acidic coffees.
Commercial Opportunity Analysis: Differentiation and Value-Add Formats
Cup converters that combine aqueous dispersion-coated hot cups with 50% post-consumer rPET cold cups and snap-fit molded-fiber lids are winning consolidated single-vendor tenders from global QSR brands. Replacing multi-polymer cup-and-lid combinations with all-fiber hot drink assemblies or all-PET cold drink assemblies simplifies consumer disposal and lowers producer EPR fees. In April 2025, Berry Global Group announced that its Versalite insulated polypropylene hot and cold beverage cups received formal APR Design for Recyclability Recognition from the Association of Plastic Recyclers [9]. Furthermore, high-definition digital and flexographic printing across printed rigid packaging cup sleeves allows beverage chains to run localized QR-code loyalty campaigns without minimum order penalties.
Disposable Cups Market by Country (2026 to 2036)
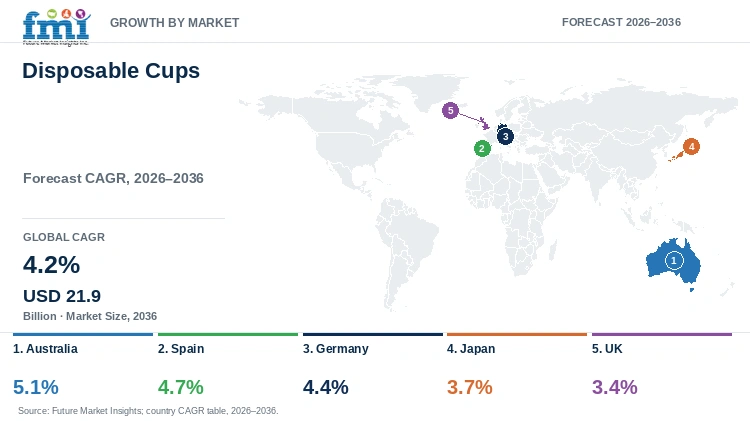
Projected growth across the five evaluated disposable cup markets spans from 3.4% CAGR in the United Kingdom to 5.1% CAGR in Australia over the 2026 to 2036 decade. National revenue performance is shaped by specialty café footfall alongside state bans on expanded polystyrene foam and mandatory paper-mill repulpability standards.
Table 7: Country CAGR and Primary Growth Levers for the Disposable Cups Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Australia | 5.1% | State single-use EPS/plastic cup bans and APCO aqueous-lined paper cup recycling expansion |
| Spain | 4.7% | Tourism hospitality takeaway beverage growth and Royal Decree 1055/2022 paper-cup recovery |
| Germany | 4.4% | VerpackG / ZSVR minimum recyclability standards and Blue Angel aqueous cup adoption |
| Japan | 3.7% | Resource Circulation Act plastic reduction targets and convenience-store counter coffee |
| UK | 3.4% | PackUK pEPR composite-cup fee modulation and high street café paper cup collection schemes |
Source: Future Market Insights analysis
Australia Disposable Cups Market Outlook (2026 to 2036)
Independent espresso bar density and state prohibitions on expanded polystyrene and unrecyclable plastic drinkware across Western Australia and New South Wales reshape Australian cup converting. In January 2026, the Australian Packaging Covenant Organisation reported under National Packaging Reform that Australia uses 1.3 million tonnes of plastic packaging annually while Extended Producer Responsibility reforms target 370,000 tonnes of landfill reduction [10]. Australian disposable cup revenues are set to advance at a 5.1% CAGR from 2026 to 2036 as roasters switch toward aqueous dispersion-coated hot cups. While local paper mills accept dispersion-lined board, converters face ocean freight delays on imported kraft cupstock. Plants in Adelaide and Melbourne therefore pair FSC virgin board with inline water-based coaters.
Key takeaway: In Australia, state single-use plastic bans and APCO packaging reforms propel café roasters toward locally converted aqueous-coated paper cups at a 5.1% CAGR.
Spain Disposable Cups Market Outlook (2026 to 2036)
Year-round coastal tourism and outdoor terrace hospitality across Madrid and Catalonia generate intense seasonal spikes in single-use cold and hot beverage service. In October 2025, Eurostat reported that European Union residents generated 35.3 kilograms of plastic packaging waste per person, while Spain enforced its EUR 0.45 per kilogram tax on non-recycled plastic packaging under Law 7/2022 [11]. Spanish foodservice cup expenditure is projected to expand at a 4.7% CAGR through 2036 under Royal Decree 1055/2022 recyclability mandates. Yet commercial uptake faces friction from the plastic tax burden on virgin thermoformed cold cups. Spanish foodservice distributors bypass this levy by procuring 50% post-consumer rPET cold cups and aqueous-coated paper cups recoverable in municipal blue bins.
Key takeaway: In Spain, record hospitality beverage volume and the EUR 0.45 per kilogram virgin plastic tax accelerate foodservice shifts toward aqueous paper and rPET cups.
Germany Disposable Cups Market Outlook (2026 to 2036)
Strict design-for-recycling fee modulation under the German Packaging Act (VerpackG) and mandatory reusable foodservice offers (Mehrwegpflicht) create Europe's most demanding cup specification regime. In August 2026, Germany's Central Agency Packaging Register (ZSVR) and the Federal Environment Agency published the updated Minimum standard for determining the recyclability of packaging, grading composite cups strictly on recoverable fiber yield [12]. German cup converter turnover will progress at a 4.4% CAGR over the 2026 to 2036 period as commuter bakery-cafés and railway kiosks serve travelers who decline deposit-return mugs. However, municipal single-use packaging taxes in cities such as Tuebingen penalize non-recyclable takeaway cups. German converters consequently supply aqueous-coated paper cups containing over 95% virgin fiber and separable K3 cardboard-plastic cups.
Key takeaway: In Germany, ZSVR minimum recyclability standards and commuter bakery demand compel converters to supply over-95%-fiber aqueous paper cups.
Japan Disposable Cups Market Outlook (2026 to 2036)
Freshly brewed counter coffee machines across 55,000 Seven-Eleven and FamilyMart as well as Lawson outlets make convenience stores the primary volume anchor for Japanese beverage cups. In August 2025, the U.S. International Trade Administration reported that Japan generated 7.69 million tons of plastic waste with 460,000 tons (6%) domestically recycled, prompting Resource Circulation Act amendments targeting 1 million tons of recycled plastic use by 2030 [13]. Japanese beverage cup sales are forecast to record a 3.7% CAGR between 2026 and 2036 as konbini chains switch from virgin plastic cups to embossed paper and rPET formats. Nonetheless, population aging and municipal burnable-waste rules cap unit growth. Japanese converters focus on insulated double-wall paper cups and biomass linings.
Key takeaway: In Japan, convenience-store counter coffee volume and Resource Circulation Act amendments drive konbini chains toward embossed paper and rPET cups.
UK Disposable Cups Market Outlook (2026 to 2036)
High-street coffee shop saturation combined with in-store fiber cup take-back bins across major British café chains shifts domestic cup demand toward circular material upgrades. In August 2026, PackUK published its 2026 to 2027 operational plan projecting GBP 1.47 billion in chargeable local authority disposal costs and introducing green-amber-red Recyclability Assessment Methodology (RAM) fee modulation [14]. British disposable cup demand is estimated to post a 3.4% CAGR from 2026 to 2036 following England's prohibition on expanded polystyrene beverage cups. The central commercial obstacle involves bring-your-own-cup discounts that trim single-use unit velocity among commuters. UK converters protect revenue by replacing amber-rated PE-lined board with green-rated aqueous dispersion cups and molded-fiber lids.
Key takeaway: In the UK, PackUK's GBP 1.47 billion pEPR operational plan and RAM fee modulation shift mature coffee-chain demand toward green-rated aqueous paper cups.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the disposable cups market?
Huhtamaki Oyj, Berry Global Group, Inc., Amcor plc, Dart Container Corporation, Pactiv Evergreen Inc., Sonoco Products Company, Georgia-Pacific LLC, and Greiner Packaging International GmbH are the notable companies in the disposable cups market.
Procurement qualification in the disposable cups market centers on whether a converter delivers high-speed rotary paper-cup forming alongside aqueous barrier coatings and thermoformed rPET cold cups at national QSR scale. Huhtamaki Oyj and Dart Container Corporation alongside Pactiv Evergreen and Georgia-Pacific (Dixie) operate large North American and European cup-forming plants supplying multi-billion-unit coffee and fast-food chains. Amcor plc and Berry Global Group lead in thermoformed polypropylene and post-consumer rPET cold drink cups paired with sip-through lids. Sonoco Products Company and Greiner Packaging specialize in recyclable paperboard containers and separable cardboard-plastic cup combinations.
- Global Foodservice Cup & Fiber Leaders: Huhtamaki Oyj, Dart Container Corporation, and Pactiv Evergreen Inc. supply high-volume hot paper cups, molded fiber lids, and cold beverage cups.
- Thermoformed Cold-Cup & Multi-Material Platforms: Amcor plc, Berry Global Group, Inc., and Georgia-Pacific LLC manufacture clarified rPET/PP cold cups and insulated Dixie hot cups.
- Recyclable Paperboard & Separable Cup Specialists: Sonoco Products Company and Greiner Packaging International GmbH engineer repulpable fiber containers and K3 cardboard-plastic cups.
Competitive Benchmarking: Disposable Cups Market
Table 8: Competitive Benchmarking for the Disposable Cups Market (qualitative capability ratings), 2026
| Company | Hot & Cold Cup Breadth | Aqueous / Bio-Barrier Tech | QSR Supply Chain Scale | Geographic Reach |
|---|---|---|---|---|
| Huhtamaki Oyj | High | High | High | High |
| Berry Global Group, Inc. | High | Medium | High | High |
| Amcor plc | High | High | High | High |
| Dart Container Corporation | High | Medium | High | Medium |
| Pactiv Evergreen Inc. | High | High | High | Medium |
| Sonoco Products Company | Medium | High | Medium | High |
| Georgia-Pacific LLC | High | High | High | Medium |
| Greiner Packaging International GmbH | Medium | High | Medium | High |
Scoring basis: Hot & Cold Cup Breadth is rated High when a supplier manufactures both rotary-formed paper hot cups and thermoformed cold drink cups across 4-ounce to 32-ounce capacities. Aqueous / Bio-Barrier Tech evaluates commercial deployment of dispersion-coated repulpable board and home-compostable PLA linings or separable cardboard-plastic sleeves. QSR Supply Chain Scale reflects multi-plant contract fulfillment for top-tier coffee and fast-food chains, while Geographic Reach tracks multi-continental versus regional plant footprints.
Key Developments in the Disposable Cups Market
- Amcor plc finalized its corporate combination with Berry Global Group in April 2025 to create a unified supplier of thermoformed rPET cold drinkware and injection-molded beverage lids [15].
- In May 2025, Dart Container Corporation earned industry sustainability recognition for expanding recyclable PET cold beverage cup and molded-fiber sip-lid lines replacing expanded polystyrene foam [16].
- Novolex and Pactiv Evergreen Inc. completed their merger in April 2025 to form a combined North American manufacturer of dispersion-coated paper hot cups and foodservice drinkware [17].
Key Players in the Disposable Cups Market
Global Foodservice Cup & Fiber Leaders
- Huhtamaki Oyj
- Dart Container Corporation
- Pactiv Evergreen Inc.
Thermoformed Cold-Cup & Multi-Material Platforms
- Amcor plc
- Berry Global Group, Inc.
- Georgia-Pacific LLC
Recyclable Paperboard & Separable Cup Specialists
- Sonoco Products Company
- Greiner Packaging International GmbH
Disposable Cups Market - Report Scope
Table 9: Report Scope for the Disposable Cups Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Format / Style; Material Substrate; End-Use Application; Barrier / Coating Property; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes converter revenue from single-use hot and cold beverage drinking cups, insulated ripple/double-wall cups, and portion cups across coated paperboard, molded fiber, and thermoformed polymers. Category Scope Note: Market valuation reflects disposable beverage and portion cups supplied to foodservice, institutional, and retail channels; folding cartons, rigid set-up boxes, corrugated shipping containers, and fresh meat trays are excluded from this market boundary. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Australia, Spain, Germany, Japan, UK, and additional countries in the full report |
| Key Companies Covered | Huhtamaki Oyj, Berry Global Group, Inc., Amcor plc, Dart Container Corporation, Pactiv Evergreen Inc., Sonoco Products Company, Georgia-Pacific LLC, Greiner Packaging International GmbH |
| Forecast Period | 2026 to 2036 (Base Year: 2025) |
| Approach | Primary interviews with cup-forming plant directors and QSR packaging procurement leads combined with Eurostat, APCO, ZSVR, and PackUK data triangulation. |
Disposable Cups Market - Research Methodology
Table 10: Research Methodology for the Disposable Cups Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews were conducted with rotary paper-cup and thermoforming plant managers, bleached kraft cupstock mill engineers, aqueous dispersion formulators, and QSR/café packaging procurement directors across Europe, North America, and Asia-Pacific. |
| Secondary Research | Desk research synthesized Eurostat packaging waste registries, APCO consumption and recovery reports, German ZSVR VerpackG standards, U.S. ITA Japan plastic circulation assessments, PackUK EPR operational plans, and corporate filings from Huhtamaki, Amcor, Berry Global, Dart Container, and Pactiv Evergreen. |
| Market Sizing and Forecasting | Bottom-up cupstock board and thermoformed sheet consumption (million tonnes) and average converter realization per 1,000 cups were reconciled against top-down QSR, coffee-chain, convenience retail, and institutional beverage servings from 2025 to 2036. |
| Data Triangulation and Validation | Revenue estimates and segment shares were cross-checked against high-speed cup-forming machine installed bases, paper-mill repulpability audit thresholds (PTS-RH 021/97 and CEPI), and EPR fee schedules to prevent double-counting with folding cartons or corrugated boxes. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's foodservice beverage packaging econometric model, calibrating evaluated national growth rates against the 4.2% global baseline through verified EPS foam and single-use plastic cup prohibitions, aqueous-coated paper cup value-mix upgrades, and commercial café/QSR outlet expansion. |
| Operational Benchmark Traceability | Operational benchmarks (cupstock board and polymer sheet throughput in million tonnes, disposable cup unit output, and converter realization per 1,000 cups) represent modeled estimates synthesized from Eurostat env_waspac datasets, APCO material factsheets, ZSVR recyclability registries, and commercial converter disclosures. |
Disposable Cups Market by Segments
Disposable Cups Market segmented by Product Format / Style:
- Single-Wall & Double-Wall Hot Beverage Cups
- Thermoformed Clear Cold Drink Cups
- Ripple-Wall & Insulated Jacket Cups
- Portion & Sampling Cups
Disposable Cups Market segmented by Material Substrate:
- Virgin Chemical Kraft Pulp
- Molded Bagasse & Recycled Fiber Pulp
- Thermoformed PET, rPET & Polypropylene Sheet
Disposable Cups Market segmented by End-Use Application:
- Quick-Service Restaurants & Coffee Chains
- Institutional & Workplace Foodservice
- Convenience Retail & Transit Hubs
- Hospitality, Events & Cinema Concessions
Disposable Cups Market segmented by Barrier / Coating Property:
- Aqueous Water-Based Barrier
- PLA & Bio-Wax Coating
- Standard Polyethylene (PE) Lined & Monomaterial Recyclable
Disposable Cups Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Western Europe
- Germany
- France
- United Kingdom
- Spain
- Italy
- Eastern Europe
- Poland
- Russia
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- Australia
- New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Israel
Research Sources and Bibliography
- [1] Huhtamaki Oyj. (2025, July 16). Huhtamaki launches new compostable ice cream cups. Huhtamaki Official Media Releases.
- [2] Eurostat. (2025, October 10). Packaging waste statistics. Statistical Office of the European Union.
- [3] Huhtamaki Oyj. (2026, March 5). Annual Report 2025. Huhtamaki Official Investor Relations.
- [4] Sonoco Products Company. (2025, November 10). Sonoco Consolidating Consumer Packaging Businesses Under Two Geographies. Sonoco Official Investor Relations.
- [5] Amcor plc. (2025, September 2). Amcor brings caps, closures and cups to Drinktec. Amcor Official Media Releases.
- [6] European Parliament and Council of the European Union. (2025, January 22). Regulation (EU) 2025/40 of the European Parliament and of the Council of 19 December 2024 on packaging and packaging waste, amending Regulation (EU) 2019/1020 and Directive (EU) 2019/904, and repealing Directive 94/62/EC. Official Journal of the European Union.
- [7] Australian Packaging Covenant Organisation (APCO). (2025, December 1). APCO Australian Packaging Consumption and Recovery Data 2023-24. Australian Packaging Covenant Organisation.
- [8] Berry Global Group, Inc. (2025, March 6). Berry's Reusable Cups Support Returnable Cup Initiative. Berry Global Official Newsroom.
- [9] Berry Global Group, Inc. (2025, April 16). Berry Global's Versalite™ Cups Receive the APR Design® for Recyclability Recognition. Berry Global Official Newsroom.
- [10] Australian Packaging Covenant Organisation (APCO). (2026, January 13). National Packaging Reform: Turning brand leadership into consistent outcomes. Australian Packaging Covenant Organisation.
- [11] Eurostat. (2025, October 22). Plastic packaging waste in the EU: 35.3 kg per person. Statistical Office of the European Union.
- [12] Zentrale Stelle Verpackungsregister (ZSVR) & Umweltbundesamt. (2026, August 31). Minimum standard for determining the recyclability of packaging. Stiftung Zentrale Stelle Verpackungsregister.
- [13] International Trade Administration (ITA). (2025, August 20). Japan Recycled Plastic Materials. U.S. Department of Commerce.
- [14] PackUK. (2026, August 10). PackUK operational plan: 2026 to 2027. GOV.UK Official Publications.
- [15] Amcor plc. (2025, April 30). Amcor completes combination with Berry Global. Amcor Official Media Releases.
- [16] Dart Container Corporation. (2025, May 12). Dart Container Earns Recognition for Sustainable Packaging. Dart Container Official Newsroom.
- [17] Novolex & Pactiv Evergreen Inc. (2025, April 1). Novolex and Pactiv Evergreen Inc. Complete Combination, Creating a Leading Manufacturer in Food, Beverage and Specialty Packaging. Novolex Official Newsroom.
- [18] Georgia-Pacific LLC. (2025, April 23). Georgia-Pacific Opens More Opportunities for Paper Cup Recycling. Georgia-Pacific Official Newsroom.
- [19] Greiner Packaging International GmbH. (2025, February 26). UK retailers choose Greiner Packaging's self-separating K3® r100 packaging. Greiner Packaging Official Press Releases.
- [20] Greiner Packaging International GmbH. (2026, January 25). Meeting America's Appetite for Convenience: Greiner Packaging enters the Ready Meal Market with K3® Cup. Greiner Packaging Official Press Releases.
- [21] Association of Plastic Recyclers (APR). (2026, June 10). New Champions Strengthen Long-Term Demand for North American PCR. Association of Plastic Recyclers.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the disposable cups market in 2026 and what is forecast for 2036?
- Which foodservice, coffee-chain, and regulatory factors support demand for disposable cups?
- Why do Single-Wall & Double-Wall Hot Beverage Cups lead the product format / style category?
- Why does Virgin Chemical Kraft Pulp lead the material substrate category globally?
- How do growth rates differ across Australia, Spain, Germany, Japan, and the UK?
- Which leading companies supply paper hot cups and thermoformed cold drink cups today?
- What limits single-use volume growth or supplier switching in the disposable cups market?
- What should QSR and café buyers evaluate before qualifying disposable cup suppliers?
Frequently Asked Questions
How big is the disposable cups market in 2026, and what is forecast for 2036?
The global disposable cups market is estimated to reach USD 14.5 billion in 2026. Revenue is projected to expand further and reach USD 21.9 billion by 2036, generating USD 7.4 billion in added value.
What CAGR is forecast for the Disposable Cups Market through 2036?
As per FMI, the disposable cups market is projected to grow at a 4.2% CAGR from 2026 to 2036. Growth is supported by drive-thru coffee and cold beverage expansion alongside higher-value aqueous-coated paper and rPET cup conversion.
Which product format / style holds a notable disposable cups demand share in 2026?
Single-Wall & Double-Wall Hot Beverage Cups are projected to hold 34.5% of product format / style demand in 2026. The segment benefits from daily hot coffee and tea consumption across QSR, café, and convenience-store chains.
Which material substrate segment holds a notable disposable cups share in 2026?
Virgin Chemical Kraft Pulp is estimated to hold 45.0% of material substrate demand in 2026. Demand is supported by FDA and European BfR food-contact hygiene rules for hot liquids and wet sidewall stiffness requirements.
Which country has a notable disposable cups expansion outlook during the forecast period?
FMI finds that Australia is projected to expand at a 5.1% CAGR during the 2026 to 2036 assessment period. Growth is supported by state-level bans on EPS foam and conventional PE-lined cups alongside high per-capita café spending.
Which companies are active in the Disposable Cups Market during 2026?
Notable companies include Huhtamaki Oyj, Berry Global Group, Inc., Amcor plc, Dart Container Corporation, Pactiv Evergreen Inc., Sonoco Products Company, Georgia-Pacific LLC, and Greiner Packaging International GmbH. These companies focus on aqueous water-based barrier coatings, high-PCR rPET cold cups, and molded-fiber sip lids.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Format / Style, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Format / Style, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Format / Style, 2026 to 2036
- Single-Wall & Double-Wall Hot Beverage Cups
- Thermoformed Clear Cold Drink Cups
- Ripple-Wall & Insulated Jacket Cups
- Portion & Sampling Cups
- Y-o-Y Growth Trend Analysis By Product Format / Style, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Format / Style, 2026 to 2036
- Global Market Analysis and Forecast, By Material Substrate, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Substrate, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Substrate, 2026 to 2036
- Virgin Chemical Kraft Pulp
- Molded Bagasse & Recycled Fiber Pulp
- Thermoformed PET, rPET & Polypropylene Sheet
- Y-o-Y Growth Trend Analysis By Material Substrate, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Substrate, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Quick-Service Restaurants & Coffee Chains
- Institutional & Workplace Foodservice
- Convenience Retail & Transit Hubs
- Hospitality, Events & Cinema Concessions
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Barrier / Coating Property, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Barrier / Coating Property, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Barrier / Coating Property, 2026 to 2036
- Aqueous Water-Based Barrier
- PLA & Bio-Wax Coating
- Standard Polyethylene (PE) Lined & Monomaterial Recyclable
- Y-o-Y Growth Trend Analysis By Barrier / Coating Property, 2021 to 2025
- Absolute $ Opportunity Analysis By Barrier / Coating Property, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Spain
- Italy
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Russia
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Australia
- New Zealand
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Israel
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Huhtamaki Oyj
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Berry Global Group, Inc.
- Amcor plc
- Dart Container Corporation
- Pactiv Evergreen Inc.
- Sonoco Products Company
- Georgia-Pacific LLC
- Greiner Packaging International GmbH
- Huhtamaki Oyj
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


