
- Market Size (2026)
- USD 3.0 Bn
- Forecast (2036)
- USD 16.2 Bn
- CAGR (2026 to 2036)
- 18.5%
How big is Electric Vehicle Reducer Market in 2026?
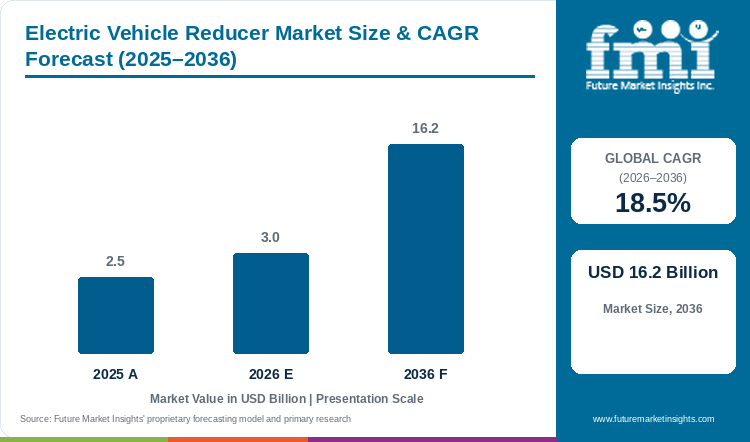
The electric vehicle reducer market is estimated at USD 2.5 billion in 2025 and is likely to reach USD 3.0 billion in 2026. Electric vehicle reducer sales are forecast to grow at an 18.5% CAGR and reach USD 16.2 billion by 2036.
Electric vehicle reducer sales, covering reduction gearboxes for electric drives, are estimated at USD 2.5 billion for 2025. The electric vehicle reducer market is expected to reach USD 3.0 billion in 2026. Across 2026 to 2036, FMI's model shows an 18.5% CAGR for electric vehicle reducer demand, with sales of USD 16.2 billion expected in 2036. Every battery electric car needs a reduction gearbox between motor and wheels, so reducer volume follows electric car output. Germany registered 88,599 battery electric cars in September 2026, 34.5% of new cars and about 95% more than a year earlier, KBA figures reported by electrive show.[1] Each of those cars meant one more reduction gear order for suppliers.
Recent supplier results are changing contract terms for carmakers. Schaeffler grew E-Mobility sales 7.7% at constant currency to EUR 2.578 billion in H1 2026, and the division still ran an EBIT margin before special items of minus 15.6%.[2] Loss-making e-drive units will press buyers for volume floors and price reopeners, so purchasing teams will trade longer awards for lower piece prices. Contract terms have become the new battleground for industry leadership. Carmakers with in-house gear shops gain room in those talks, as those shops can pull reducer work back inside when quotes rise.
Reducer makers are also moving beyond the core market of passenger cars into electric vans, buses and two-wheelers, which spreads gear-cutting capacity across more programmes.
Key Market Trends & Insights
- Compact single-stage gearboxes behind one motor make up an estimated 64.1% of product type sales in 2026, and multi-stage units about 35.9%. The Kassel plant of Volkswagen built over 850,000 electric drives in 2025, about 24% more than in 2024.[3]
- Around 68.2% of vehicle type sales in 2026 is expected from battery electric vehicles. Chinese new energy vehicle sales reached 1.643 million units in August 2026, a 60.6% share of all new vehicle sales, CAAM data reported by Gasgoo show.[4]
- Carmaker supply contracts are likely to hold 91.5% of sales channel sales in 2026, with aftermarket replacement near 8.5%.
Regional Highlights
- India leads the profiled set with a 21.4% CAGR, as electric cars and two-wheelers spread across the country.
- GCC Countries and Brazil also beat the 18.5% CAGR for the electric vehicle reducer market in the FMI outlook, and China grows close to that figure. Carmakers in Japan favour hybrids with integrated transaxles, which leaves the country at 16.4%, about two points behind the electric vehicle reducer market as a whole.
- Electric passenger vehicle retail in India rose 94.56% to 36,108 units in September 2026, an 8.5% share of the passenger vehicle market, FADA data show.[5]
Market Size & Forecast
Table 1: Market Size and Forecast for the Electric Vehicle Reducer Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 2.5 billion |
| Estimated Market Size in 2026 | USD 3.0 billion |
| Projected Market Size by 2036 | USD 16.2 billion |
| CAGR, 2026 to 2036 | 18.5% |
| Added Revenue, 2026 to 2036 | USD 13.2 billion |
| Market Expansion Multiple | 5.4x |
Reducer awards are placed two to three years before a model launches, so supplier volumes swing with each carmaker change to electric programmes. Magna grew Q2 2026 sales 3% to USD 11.0 billion against a 2% fall in global light vehicle production, and the company named North American electric vehicle programme deferrals, cancellations and volume reductions as a risk.[6] US buyers bought 262,649 electric vehicles in Q3 2026, 39.5% fewer than a year earlier after federal incentives expired, Cox Automotive estimated.[7] Each battery electric car carries one reducer per drive motor. With the battery electric vehicle market likely to expand at a 15% CAGR as cheaper battery packs reach compact models, the base of electric vehicle reducer demand keeps rising. Roughly USD 13.2 billion of extra electric vehicle reducer sales is expected in the FMI outlook by 2036, leaving the 2036 figure about 5.4 times the 2026 base. Programme cancellations in North America are the main risk to that path for suppliers with US-heavy order bases.
Supplier Restructuring, In-House Drives and Hybrid Transaxles
Tier 1 drivetrain suppliers are cutting cost after weak electric demand. ZF completed a make-or-buy review of Division E in May 2026 and kept e-motors and inverters in-house, and the 7,600 job cuts announced for the division stand.[8] FMI's analysis expects suppliers to bundle reducers with motors and inverters, as stand-alone gearbox contracts earn too little to cover development cost.
Carmakers are building more of the drive in carmaker-owned plants. Volkswagen has produced 5 million electric drive units at Győr, Kassel, Tianjin and Zuffenhausen, and Kassel has built 1 million APP550 drives.[3] AISIN, DENSO and BluE Nexus developed a two-motor hybrid drive module for the new Jeep Cherokee, with the transaxle and motors made by AISIN North Carolina.[9] Hybrid transaxles and in-house e-drives will leave independent reducer makers competing for second-source and platform-sharing work.
Table 2: Electric Car, Supplier and Drive Indicators for the Electric Vehicle Reducer Market (units, sales and margins), 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Germany BEV registrations, September 2026 | 88,599; 34.5% share | Reducer volume in the largest EU market. | [1] |
| China NEV sales, August 2026 | 1.643 million; 60.6% share | The largest base of reducer-equipped vehicles. | [4] |
| US EV sales, Q3 2026 | 262,649; down 39.5% | Programme volumes reset after incentive expiry. | [7] |
| Schaeffler E-Mobility, H1 2026 | EUR 2.578 billion; margin minus 15.6% | Supplier losses shape contract terms. | [2] |
| Volkswagen Kassel electric drives, 2025 | Over 850,000 units; up about 24% | In-house drive output keeps rising. | [3] |
| India electric PV retail, September 2026 | 36,108 units; up 94.56% | A fast-growing new reducer market. | [5] |
Analyst Perspective
“Gear sets have become the quiet bargaining chip in electric drive contracts, and I expect suppliers that sell the reducer as part of a full motor and inverter unit to hold margins best through 2036. The sharper opportunity for gear specialists lies outside passenger cars, in electric vans, buses and two-wheelers. Those programmes still buy reducers as separate parts.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the electric vehicle reducer market segmented?
The market is segmented into product type, vehicle type, sales channel, and region. Single-stage reducers are expected to lead product type with an estimated 64.1% share in 2026, and battery electric vehicles lead vehicle type with about 68.2%.
By product type: single-stage, and multi-stage.
By vehicle type: battery electric vehicles, plug-in hybrid electric vehicles, hybrid electric vehicles, and fuel cell electric vehicles.
By sales channel: OEM, and aftermarket.
By region: electric drive and gearbox programmes in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do single-stage reducers lead electric vehicle reducer sales by product type?
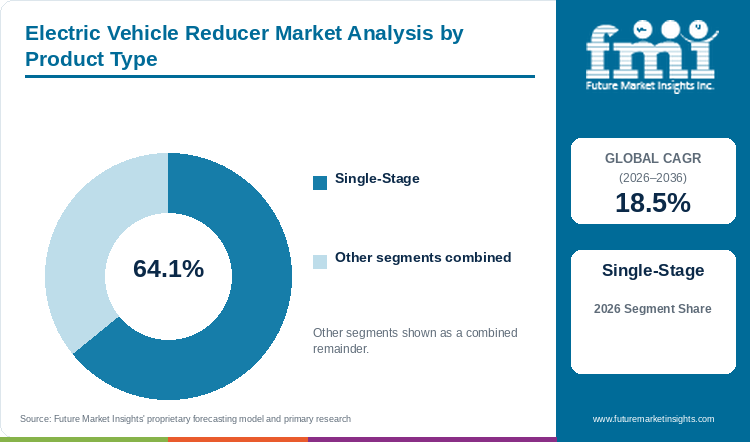
One fixed gear ratio gives single-stage reducers an estimated 64.1% of product type sales in 2026, against about 35.9% for multi-stage units.
Table 3: Product Type Share for the Electric Vehicle Reducer Market (percentage share), 2026
| Product Type | Estimated Share (2026) |
|---|---|
| Single-Stage | 64.1% |
| Multi-Stage | 35.9% |
| Total | 100.0% |
Table 4: Product Type Leadership and Market Growth for the Electric Vehicle Reducer Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 18.5% |
| Leading Segment | Single-Stage |
One fixed ratio between a high-speed motor and the wheels covers the speed range of most passenger electric cars at the lowest cost and weight. That is why single-stage reducers are expected to lead product type in 2026, with 64.1% share. Multi-stage units, an estimated 35.9%, use two gear meshes or a planetary gear set for the higher ratios of heavy SUVs, pickups, vans and buses, and cost more to machine and assemble. Drive controllers decide torque and gear protection on each unit, and a 13.5% CAGR is forecast for the powertrain domain control unit platforms market, which brings tighter software control to both reducer types. A carmaker choosing a reducer for a compact or mid-size model will keep a single fixed ratio, since a second stage adds cost with no gain in range.
- Parallel-axis helical single-stage units in front and rear e-axles make up most of the volume.
- The APP550 drive delivers up to 240 kW and 560 Nm in series production, according to a Volkswagen release of February 2026.[3]
Why do battery electric vehicles lead electric vehicle reducer sales by vehicle type?
About 68.2% of vehicle type sales in 2026 is projected for battery electric vehicles, with plug-in hybrids at about 19.4%, hybrids near 9.8% and fuel cell vehicles roughly 2.6%.
Table 5: Vehicle Type Share for the Electric Vehicle Reducer Market (percentage share), 2026
| Vehicle Type | Estimated Share (2026) |
|---|---|
| Battery Electric Vehicles | 68.2% |
| Plug-In Hybrid Electric Vehicles | 19.4% |
| Hybrid Electric Vehicles | 9.8% |
| Fuel Cell Electric Vehicles | 2.6% |
| Total | 100.0% |
Every BEV relies on a reducer to turn motor speed into wheel torque, and many dual-motor models carry two, so battery electric vehicles are forecast to lead vehicle type with 68.2% share in 2026. Plug-in hybrids, an estimated 19.4%, combine a reducer with an engine gearbox or a dedicated hybrid transmission, and growth of the multi-mode hybrid drivetrain control units market at a 7.8% CAGR points to more complex hybrid gearing. Hybrids, near 9.8%, use power-split or two-motor transaxles with built-in reduction gears, and AISIN builds such a transaxle in North Carolina for the new Jeep Cherokee.[9] Fuel cell vehicles, about 2.6%, remain a small fleet of buses and trucks. A carmaker planning a new platform will size reducer capacity to BEV output first, since each BEV carries at least one dedicated unit.
- Single-motor and dual-motor battery electric cars, vans and buses form the leading group.
- China sold 10.65 million new energy vehicles in January to August 2026, 52.4% of all vehicle sales, Gasgoo reported.[4]
Why does OEM supply lead electric vehicle reducer sales by sales channel?
OEM supply is likely to hold 91.5% of sales channel sales in 2026, and the aftermarket about 8.5%.
Table 6: Sales Channel Share for the Electric Vehicle Reducer Market (percentage share), 2026
| Sales Channel | Estimated Share (2026) |
|---|---|
| OEM | 91.5% |
| Aftermarket | 8.5% |
| Total | 100.0% |
Reducers are fitted on the assembly line as part of a sealed drive unit and carry warranties of eight years or more. In 2026, OEM supply is predicted to lead the sales channel split with 91.5% share. The aftermarket, an estimated 8.5%, covers replacement gear sets, bearings and complete units for older electric cars and fleet vehicles, and the young age of the electric fleet keeps that channel small. Magna reported Power & Vision sales of USD 4,093 million in Q2 2026, and the division includes drivetrain work for carmakers.[6] Electronics content in each drive unit keeps rising, and growth of the automotive electronics market at a 4.6% CAGR adds sensors and controllers that make repairs a dealer job. A fleet operator choosing between a new drive unit and a gear rebuild will replace the whole unit under warranty, which keeps sales in the OEM channel.
- Line-fit sales to carmakers and drive unit makers form the OEM channel.
- Electrified vehicles, including hybrids and plug-ins, made up nearly 25% of US vehicle sales in Q3 2026, Cox Automotive estimated.[7]
What are the drivers, restraints, and opportunities in the electric vehicle reducer market?
Rising electric car sales add a reducer to each new vehicle, which keeps gear set volume growing. Programme cancellations and supplier losses squeeze reducer makers, and electric vans, buses and two-wheelers open new demand outside passenger cars.
- Driver: Each new battery electric car carries at least one reducer, so gear set volume rises with every gain in electric car share.
- Restraint: Carmakers delaying or cancelling electric programmes leave suppliers with idle gear lines and unrecovered tooling, which raises the price of each remaining unit.
- Opportunity: Electric vans, buses and two-wheelers still buy reducers as separate parts, which gives gear specialists programmes outside the integrated car drive.
Electric Car Sales Add a Reducer to Every Vehicle
Adoption of electric cars converts directly into gear set orders. Germany's September 2026 registrations were 34.5% battery electric, against 19.3% a year earlier.[1] China sold 1.643 million new energy vehicles in August 2026, up 17.8% on a year earlier.[4] Rising electric share in those two markets will keep reducer lines in Europe and China running near capacity.
Programme Cancellations Leave Gear Lines Idle
Producers of reducers carry tooling and capacity for programmes that can be cut before launch. Magna named North American electric vehicle programme deferrals, cancellations and volume reductions among the risks in the July 2026 results.[6] Weaker-than-expected electric demand pushed the ZF passenger car powertrain division into the red, electrive reported in May 2026.[8] FMI's analysis treats programme timing as the main risk to supplier returns through 2036. Gear makers will ask for capacity reservation fees on new awards.
Vans, Buses and Two-Wheelers Open New Demand
Demand for reducers outside passenger cars is growing fastest in India. Electric two-wheeler retail in India rose 88.67% to 207,314 units in September 2026, and electric models made up 64.9% of three-wheeler retail.[5] Hub drives on pedal bikes use small planetary reducers, and an 8.5% CAGR forecast for the electric bike market points to another outlet for compact gear sets. FMI expects gear specialists to gain more of these programmes, since two-wheeler and bus makers rarely build drives in-house, giving stand-alone gear makers a wider opening beyond passenger cars.
Which country CAGRs are profiled in the electric vehicle reducer market?
Table 7: Country CAGR Comparison for the Electric Vehicle Reducer Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 21.4% |
| GCC Countries | 19% |
| Brazil | 18.7% |
| China | 18.3% |
| South Korea | 18.1% |
| Germany | 17.6% |
| United States | 17.2% |
| Japan | 16.4% |
How do country-level CAGRs compare in the electric vehicle reducer market?
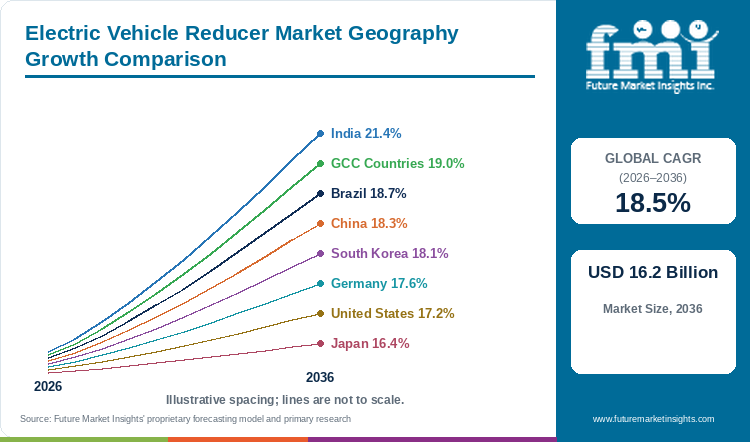
Electric passenger vehicles reached 8.5% of passenger vehicle retail in India in September 2026, up from 5.7% a year earlier.[5] A low base and rising share give India a projected 21.4% CAGR, against the 18.5% rate for the electric vehicle reducer market in FMI's model. GCC Countries come next at 19%, as Gulf governments back local electric car assembly. Imported and locally built electric cars carry Brazil to 18.7%. China grows near the electric vehicle reducer market rate, at 18.3%, from the largest electric car base. South Korea is projected at 18.1%, with suppliers chasing export orders. Germany grows at 17.6%, with carmakers building more drives in-house. After incentive expiry cut electric car sales, the United States is likely to grow at 17.2%. Hybrid-first carmakers keep Japan at 16.4%, the slowest profiled rate.
- Electric car and two-wheeler retail in India is growing at high double-digit rates.
- Gulf governments are funding local electric car assembly.
- Brazilian buyers are taking more imported electric cars.
- Chinese new energy vehicles already exceed half of new vehicle sales.
- Korean suppliers are pursuing core component orders abroad.
- German electric car registrations reached a 34.5% share in September 2026.
- US electric car sales fell after federal incentives expired.
- Japanese carmakers lean on hybrids with built-in transaxles.
Full report country CAGRs cover: Eight countries carry separate rates in the full report. India, GCC Countries and Brazil exceed the 18.5% electric vehicle reducer market CAGR, China is close to that figure, four mature markets grow more slowly, and Eastern Europe and the rest of Latin America receive regional notes.
Country-wise Analysis
India Electric Vehicle Reducer Market Outlook (2026 to 2036)
Electric two-wheeler retail in India reached 207,314 units in September 2026, 11.6% of the segment, and electric passenger vehicle retail grew 94.56% to 36,108 units, FADA data reported by Autocar Professional show.[5] Scooter, three-wheeler and car makers in India will need local gear supply as volumes rise, and a 21.4% CAGR is forecast for the country.
Key takeaway: Two-wheelers and cars together give India the steepest growth curve in the table.
GCC Countries Electric Vehicle Reducer Market Outlook (2026 to 2036)
Gulf governments are backing local electric car assembly and charging networks, and fleet buyers in Saudi Arabia and the UAE are adding electric taxis and delivery vans. Imported drive units will dominate supply at first, for a projected 19% CAGR across GCC Countries.
Key takeaway: A small base and state-backed assembly put GCC Countries above the electric vehicle reducer market rate.
Brazil Electric Vehicle Reducer Market Outlook (2026 to 2036)
Electric car sales in Brazil are rising from a small base, led by imported Chinese models and new local assembly. Reducer demand will follow local assembly plans, which supports an 18.7% CAGR in Brazil.
Key takeaway: Local assembly of electric cars sets the pace in Brazil.
China Electric Vehicle Reducer Market Outlook (2026 to 2036)
New energy vehicles made up 60.6% of Chinese vehicle sales in August 2026, and NEV production reached 1.653 million units in the month, CAAM data reported by Gasgoo show.[4] Gear makers such as Zhuzhou Gear and Tsingshan Industry supply domestic drive unit makers on short price cycles. With electric share already high, China will grow at 18.3%, close to the 18.5% CAGR for electric vehicle reducer sales.
Key takeaway: The largest electric car base keeps China near the electric vehicle reducer market rate.
South Korea Electric Vehicle Reducer Market Outlook (2026 to 2036)
Hyundai Mobis reported slightly lower electrification sales in Q2 2026 as some carmaker customers cut production, and the company received USD 740 million of core component orders from automakers in North America, Europe and Asia in the first half.[10] Korean suppliers will sell more drive parts abroad, and South Korea is predicted to grow at 18.1%.
Key takeaway: Export orders for drive parts set the outlook in South Korea.
Germany Electric Vehicle Reducer Market Outlook (2026 to 2036)
Battery electric car registrations in Germany reached 604,144 over January to September 2026, up 58.1% on the same months of 2025.[1] ZF kept e-motor and inverter production in-house after a review completed in May 2026, and job cuts at Schweinfurt and Auerbach continue.[8] Germany is projected to grow at 17.6%, as carmakers build more drives in carmaker-owned plants.
Key takeaway: Rising registrations and in-house drives shape German reducer demand.
United States Electric Vehicle Reducer Market Outlook (2026 to 2036)
US electric vehicle sales rose 6.1% from Q2 to Q3 2026, and the EV share of new vehicle sales reached about 6.4%, Cox Automotive estimated.[7] Hybrid transaxles add a second outlet, with AISIN North Carolina building the transaxle and motors for a new two-motor hybrid module.[9] Hybrids and EVs sharing programme budgets hold the United States at 17.2%.
Key takeaway: Hybrid transaxles partly offset slower EV sales in the United States.
Japan Electric Vehicle Reducer Market Outlook (2026 to 2036)
Japanese suppliers AISIN and DENSO announced in August 2026 a two-motor hybrid drive module, developed with BluE Nexus, that pairs a high-torque transaxle with a DENSO inverter.[9] Japanese carmakers will keep favouring hybrids with integrated transaxles, so demand for stand-alone EV reducers grows more slowly, at 16.4%.
Key takeaway: A hybrid-first strategy leaves Japan with the slowest profiled growth.
Who are the notable companies in the electric vehicle reducer market?
BorgWarner, ZF, Magna, Bosch, GKN Automotive, Schaeffler, AISIN, Aichi Machine Industry, HOTA Industrial, Tsingshan Industry and Zhuzhou Gear are the profiled companies.
Global drivetrain suppliers, Japanese transaxle makers and Asian gear specialists make up the profiled group, and FMI tracks eleven of them. Magna raised the 2026 adjusted EBIT margin outlook to 6.3% to 6.6% in July 2026.[6] Schaeffler confirmed 2026 sales guidance of EUR 22.5 billion to 24.5 billion in August.[2] ZF kept e-motor and inverter production after a review of Division E.[8] BorgWarner, Bosch, GKN Automotive, AISIN, Aichi Machine Industry, HOTA Industrial, Tsingshan Industry and Zhuzhou Gear complete the group.
- Global drivetrain suppliers: BorgWarner, ZF, Magna, Bosch, GKN Automotive and Schaeffler.
- Japanese transaxle and gear makers: AISIN and Aichi Machine Industry.
- Asian gear specialists: HOTA Industrial, Tsingshan Industry and Zhuzhou Gear.
Competitive Benchmarking: Electric Vehicle Reducer Market
Table 8: Competitive Benchmarking for the Electric Vehicle Reducer Market (qualitative documentation ratings), 2026
| Company | E-Drive Integration | Hybrid Transaxles | Global Plants | Recency |
|---|---|---|---|---|
| ZF | High | Medium | High | High |
| Schaeffler | High | Medium | High | High |
| Magna | Medium | Low | High | High |
| AISIN | Medium | High | High | High |
| BorgWarner | High | Low | High | Low |
Scores track how much each supplier disclosed on drive units in dated 2026 releases and results, and the scores carry no market-share meaning.
Key Developments in the Electric Vehicle Reducer Market
- On 12 October 2026, Cox Automotive estimated US electric vehicle sales of 262,649 units for Q3 2026.[7]
- On 7 October 2026, FADA data showed electric vehicle retail in India of 333,634 units for September 2026.[5]
- On 5 October 2026, KBA data showed battery electric cars at 34.5% of new car registrations in Germany.[1]
- On 10 September 2026, CAAM data showed a 60.6% new energy vehicle share in China for August 2026.[4]
- On 27 August 2026, DENSO announced a two-motor hybrid drive module developed with AISIN and BluE Nexus.[9]
- On 14 August 2026, Schaeffler confirmed the full-year 2026 forecast after the first half.[2]
- On 31 July 2026, Magna raised the 2026 outlook after second-quarter results.[6]
- On 24 July 2026, Hyundai Mobis reported second-quarter operating profit 12.1% above a year earlier.[10]
- On 19 May 2026, ZF said e-motors and inverters will stay in-house after a Division E review.[8]
- On 9 February 2026, Volkswagen reported 5 million electric drives produced.[3]
Key Players in the Electric Vehicle Reducer Market
Global Drivetrain Suppliers
- BorgWarner
- ZF
- Magna
- Bosch
- GKN Automotive
- Schaeffler
Japanese Transaxle and Gear Makers
- AISIN
- Aichi Machine Industry
Asian Gear Specialists
- HOTA Industrial
- Tsingshan Industry
- Zhuzhou Gear
Electric Vehicle Reducer Market - Report Scope
Table 9: Report Scope for the Electric Vehicle Reducer Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; vehicle type; sales channel; region |
| Quantitative units | USD billion |
| Market definition | Fixed-ratio single-stage and multi-stage reduction gearboxes fitted between the traction motor and the driven wheels of battery electric, plug-in hybrid, hybrid and fuel cell vehicles, sold to carmakers and the aftermarket. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | BorgWarner, ZF, Magna, Bosch, GKN Automotive, Schaeffler, AISIN, Aichi Machine Industry, HOTA Industrial, Tsingshan Industry, Zhuzhou Gear |
| Forecast period | 2026 to 2036 |
Electric Vehicle Reducer Market - Research Methodology
Table 10: Research Methodology for the Electric Vehicle Reducer Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Supplier and carmaker results, drive unit announcements, vehicle registration and retail data and automotive trade press from May 2025 onward. |
| Desk Research | Desk research covers electric car sales, drive unit sourcing, supplier restructuring and hybrid transaxle programmes. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 3.0 billion and an 18.5% CAGR through 2036. |
| Data Validation | Sales, registrations and margins were checked against the company, association or agency that reported them. |
Electric Vehicle Reducer Market by Segments
Electric Vehicle Reducer Market segmented by Product Type:
- Single-Stage
- Multi-Stage
Electric Vehicle Reducer Market segmented by Vehicle Type:
- Battery Electric Vehicles
- Plug-In Hybrid Electric Vehicles
- Hybrid Electric Vehicles
- Fuel Cell Electric Vehicles
Electric Vehicle Reducer Market segmented by Sales Channel:
- OEM
- Aftermarket
Electric Vehicle Reducer Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] electrive.net. (2026, October 5). Neuer Spitzenwert: Mehr als jeder dritte Neuwagen ist ein Elektroauto. https://www.electrive.net/2026/10/05/jeder-dritte-neuwagen-elektroauto/
- [2] INDUSTRIAL Production. (2026, August 14). Schaeffler confirms forecast following a stable first half of 2026. https://www.industrial-production.de/drive-technology/schaeffler-confirms-forecast-following-a-stable-first-half-of-2026.htm
- [3] Volkswagen Group. (2026, February 9). Volkswagen Group achieves global milestone with 5 million electric drives produced; APP550 sets the benchmark. https://www.volkswagen-group.com/en/press-releases/volkswagen-group-achieves-global-milestone-with-5-million-electric-drives-produced-app550-sets-the-benchmark-20166
- [4] Gasgoo. (2026, September 10). China's new energy vehicle share reaches record high of 60.6% in August 2026. https://autonews.gasgoo.com/articles/ev/2097970492295430145
- [5] Autocar Professional. (2026, October 7). Electric vehicle retail rises sharply in September 2026: FADA. https://www.autocarpro.in/news/electric-vehicle-retail-rises-sharply-in-september-2026-fada-135098
- [6] Magna International Inc. (2026, July 31). Magna announces strong second quarter results; raises outlook for 2026 (Form 6-K, Exhibit 99.1). https://www.sec.gov/Archives/edgar/data/0000749098/000110465926088923/tm2618646d1_ex99-1.htm
- [7] Cox Automotive. (2026, October 12). EV sales in the U.S. continue to rise: Q3 2026 hits highest volume in a year. https://www.coxautoinc.com/insights/q3-2026-ev-sales-report-commentary/
- [8] electrive. (2026, May 19). ZF commits to development and production of e-motors and inverters. https://www.electrive.com/2026/05/19/zf-commits-to-development-and-production-of-e-motors-and-inverters/
- [9] DENSO Corporation. (2026, August 27). Newly developed two-motor hybrid drive module adopted for STELLANTIS new Jeep Cherokee. https://www.denso.com/global/en/newsroom/news/2026/20260827-g01
- [10] Edaily. (2026, July 24). Hyundai Mobis reports increased 2Q revenue and operating profit, up 2.4% and 12.1% year-over-year. https://en.edaily.co.kr/news/eda202607245236
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the electric vehicle reducer market during 2026?
- What market size is projected by 2036?
- Which product type holds notable share?
- Which vehicle type holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Single-Stage
- Multi-Stage
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Battery Electric Vehicles
- Plug-In Hybrid Electric Vehicles
- Hybrid Electric Vehicles
- Fuel Cell Electric Vehicles
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- OEM
- Aftermarket
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- By Sales Channel
- GCC Countries
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Vehicle Type
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- ZF
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Schaeffler
- Magna
- AISIN
- BorgWarner
- Bosch
- GKN Automotive
- Aichi Machine Industry
- HOTA Industrial
- Tsingshan Industry
- Zhuzhou Gear
- ZF
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Vehicle Type
- Figure 9: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Sales Channel
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Product Type
- Figure 26: North America Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Vehicle Type
- Figure 29: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Sales Channel
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Product Type
- Figure 36: Latin America Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Vehicle Type
- Figure 39: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Product Type
- Figure 46: Western Europe Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Vehicle Type
- Figure 49: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Vehicle Type
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Product Type
- Figure 66: East Asia Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Vehicle Type
- Figure 69: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Vehicle Type
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Vehicle Type
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the electric vehicle reducer market expected in 2026?
FMI sizes 2026 electric vehicle reducer sales at USD 3.0 billion, after USD 2.5 billion in 2025. The electric vehicle reducer market is projected to reach USD 16.2 billion by 2036.
What CAGR is projected for the electric vehicle reducer market through 2036?
The FMI forecast projects electric vehicle reducer market growth at an 18.5% CAGR over the forecast years. Rising battery electric car output, with one reducer per drive motor, carries that growth.
Which product type holds a notable market share in 2026?
An estimated 64.1% share in 2026 is expected for single-stage reducers. Multi-stage units make up about 35.9%.
Which vehicle type holds a notable market share in 2026?
BEVs are projected to hold an estimated 68.2% share in 2026. Plug-in hybrids follow at about 19.4%.
Which country has a notable expansion outlook through 2036?
Fastest growth among profiled countries is projected for India, at a 21.4% CAGR. GCC Countries follow at 19%.
Who are the key companies in the electric vehicle reducer market?
BorgWarner, ZF, Magna, Bosch, GKN Automotive and Schaeffler are the profiled global drivetrain suppliers. AISIN, Aichi Machine Industry, HOTA Industrial, Tsingshan Industry and Zhuzhou Gear complete the group.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
