
- Market Size (2026)
- USD 23.4 Bn
- Forecast (2036)
- USD 54.4 Bn
- CAGR (2026 to 2036)
- 8.8%
How big is Flavored Water Market in 2026?
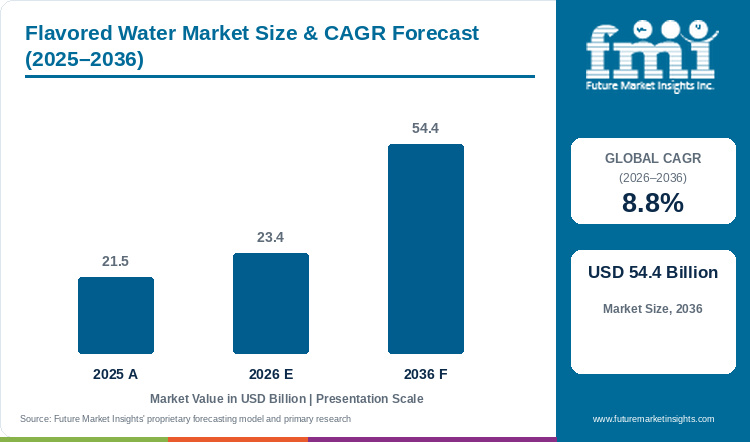
Accounting for USD 21.5 billion in 2025 and rising to USD 23.4 billion in 2026, the flavored water market is projected to expand to USD 54.4 billion by 2036, advancing at a CAGR of 8.8%.
Retail grocery shoppers, workplace cafeterias, and younger beverage consumers are actively substituting high-calorie carbonated soft drinks with unsweetened fruit-infused and botanical waters to eliminate added sugar intake. The global flavored water market was valued at USD 21.5 billion in 2025 and is estimated to reach a market size of USD 23.4 billion in 2026, before advancing to a projected valuation of USD 54.4 billion by 2036 at an 8.8% CAGR between 2026 and 2036. Still flavored water is projected to capture 58.0% of 2026 carbonation demand while zero-calorie and unsweetened formulations are anticipated to hold 52.0% by caloric profile, given that natural citrus and berry aroma extracts satisfy flavor cravings without triggering glycemic spikes or sugar-tax surcharges. This soda-replacement dynamic moves everyday flavored water faster than broader enhanced hydration drinks expanding at 4.75% in developing markets, since mainstream flavored water requires no expensive clinical dossier and prices near conventional bottled water. Industry consumption records from the International Bottled Water Association confirm this structural shift, reporting in May 2026 that packaged water remained America's top beverage choice for the tenth consecutive year with a 45.5% volume share of the refreshment beverage category in 2025 [1]. Beverage bottlers are rapidly expanding flavor lineups to capture this migration, as seen in February 2026 when Keurig Dr Pepper unveiled its 2026 refreshment and hydration portfolio expansions across retail channels [2]. FMI analysis suggests that beverage brands combining natural not-from-concentrate fruit extracts with recycled PET and sleek aluminum multipacks will lock in supermarket shelf space through 2036.
Key Market Trends & Insights
- By carbonation level: Still Flavored Water holds an estimated 58.0% share in 2026 since non-carbonated formats fit high-volume family multipacks, sports hydration, and school lunchboxes.
- By flavor profile: Citrus Lemon Lime and Grapefruit represents 36.5% in 2026 driven by natural essential-oil stability and universal palate acceptance across unsweetened waters.
- By packaging format: PET Plastic Bottles account for 64.0% in 2026 owing to resealable on-the-go closures, shatterproof portability, and lightweight 24-pack grocery handling.
- By caloric profile: Zero Calorie and Unsweetened formulations secure 52.0% in 2026 supported by national sugar-sweetened beverage levies and clean-label ingredient scrutiny.
- By distribution channel: Supermarkets and Hypermarkets command 48.5% in 2026 through chilled endcap promotions and bulk household pantry stocking.
Regional Highlights
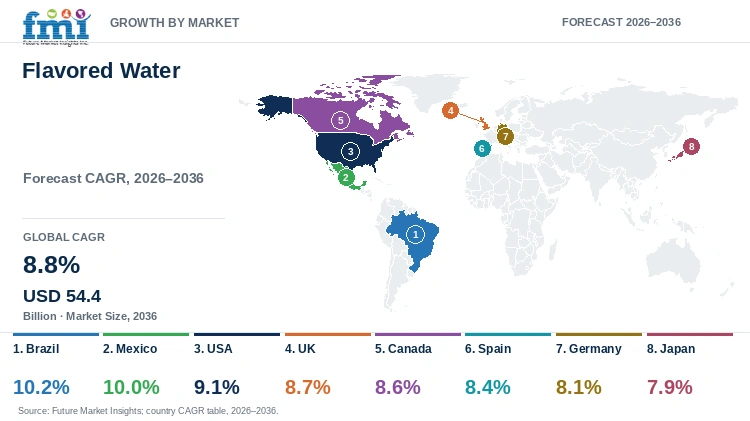
- Top national expansion: Brazil leads national growth projections at a 10.2% CAGR through 2036 supported by front-of-pack high-sugar warning labels and year-round tropical hydration demand.
- Broader country progression: Mexico tracks at a 10.0% CAGR ahead of the USA at 9.1% and the UK at 8.7%, while Japan advances at a 7.9% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Flavored Water Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 21.5 billion |
| Estimated Market Size in 2026 | USD 23.4 billion |
| Projected Market Size by 2036 | USD 54.4 billion |
| CAGR, 2026 to 2036 | 8.8% |
| Added Revenue, 2026 to 2036 | USD 31.0 billion |
Beverage formulators replacing sucrose and high-fructose corn syrup in flavored waters must preserve clean mouthfeel and satiety without triggering insulin spikes or metallic bitter aftertastes. When brands blend natural fruit aroma distillates with non-nutritive sweeteners such as stevia rebaudioside M or monk fruit extract, consumers gain sweet refreshment at near-zero caloric load. Findings from an August 2026 randomized clinical MRI study published in The American Journal of Clinical Nutrition show that 500-milliliter flavored waters sweetened with stevia or monk fruit produced zero blood insulin elevation while matching the gastric-emptying satiety of sucrose waters [3]. Consequently, beverage R&D teams pair natural botanical extracts with effervescent spring waters to convert diet-soda drinkers into daily flavored water buyers.
Packaged Hydration Volume and Container Mix Sizing
Table 2: Packaged Flavored Water Volume and Container Sizing for the Flavored Water Market (USD billion and volume ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 21.5 | 23.4 | 54.4 |
| Global commercial flavored water volume (billion liters) | 39.8 to 42.0 | 42.8 to 45.2 | 86.0 to 92.5 |
| Packaged water share of U.S. refreshment beverage volume (%, IBWA basis) | 45.5% | 46.2% | 52.0% |
| Average retail realization per liter across formats (USD) | 0.52 to 0.54 | 0.53 to 0.55 | 0.59 to 0.63 |
Operational note: Liter and container ranges reflect commercial still and sparkling flavored waters across PET, aluminum can, and glass formats.
High-speed bottling lines rely on lightweighted polyethylene terephthalate preforms and recycled resin pellets to keep multi-pack retail prices competitive against tap water filtration and carbonated soft drinks. As documented in the January 2026 Progress Report from IBWA industry analysts, single-serve PET plastic bottles account for 70% of packaged water volume while bottlers expand recycled PET inclusion to lower packaging carbon intensity [4]. Regional brands also package hospitality lines in mineral-rich glass bottles to capture restaurant table service.
Sugar-Levy Exemption & Household Hydration Spending Indicators
Table 3: Sugar-Tax Threshold and Per-Liter Realization Indicators for the Flavored Water Market (USD and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Zero-calorie & unsweetened share of total value (%) | 50.8% | 52.0% | 61.5% |
| PET plastic bottle share of flavored water revenue (%) | 64.8% | 64.0% | 58.5% |
| Recycled PET (rPET) inclusion across major EU/NA water brands (%) | 35.0% to 42.0% | 38.0% to 46.0% | 65.0% to 75.0% |
| Untaxed zero-sugar threshold under tiered SSB laws (grams sugar/100mL) | < 5.0 g | < 5.0 g | < 4.0 g |
Table 4: Caloric Profile & Channel Spending Indicators for the Flavored Water Market (USD billion and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 23.4 billion | 2026 global flavored water valuation baseline |
| Single-serve PET share of packaged water volume | 70.0% volume share | IBWA 2025/2026 Progress Report industry benchmark |
| Still Flavored Water revenue, 2026 | USD 13.6 billion | 58.0% carbonation level allocation |
| Zero Calorie and Unsweetened revenue, 2026 | USD 12.2 billion | 52.0% caloric profile allocation |
Fiscal excise taxes on sugar-sweetened drinks across more than 100 jurisdictions have fundamentally altered retail shelf economics in favor of unsweetened and zero-calorie flavored waters. In January 2026, the World Health Organization published its Global Report on the Use of Sugar-Sweetened Beverage Taxes, documenting how tiered excise duties penalize sugared sodas and create a direct price advantage for untaxed zero-sugar waters [5]. Retailers actively position zero-calorie flavored multipacks beside liquid water enhancer drops to capture price-sensitive families migrating away from taxed soft drinks.
Analyst Perspective
"Flavored water has graduated from a niche diet alternative into the primary growth engine of cold-vault beverage aisles. As front-of-pack sugar warnings and soft-drink excise levies compress traditional soda volumes, bottlers that pair real-squeezed citrus and berry essences with 100% recycled PET bottles and sleek aluminum cans will win both household pantry stock-ups and Gen Z convenience-store trips."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the flavored water market segmented?
The flavored water market is segmented by carbonation level, flavor profile, packaging format, caloric profile, and distribution channel. In 2026, Still Flavored Water is projected at 58.0%, Citrus Lemon Lime and Grapefruit at 36.5%, PET Plastic Bottles at 64.0%, Zero Calorie and Unsweetened at 52.0%, and Supermarkets and Hypermarkets at 48.5%.
By carbonation level: Still Flavored Water, and Sparkling Carbonated Flavored Water.
By flavor profile: Citrus Lemon Lime and Grapefruit, Berry Strawberry Raspberry and Blueberry, Tropical Mango Pineapple and Passionfruit, and Botanical Herbal and Floral Blends.
By packaging format: PET Plastic Bottles, Aluminum Cans, Glass Bottles, and Tetra Pak Cartons.
By caloric profile: Zero Calorie and Unsweetened, Low Calorie Stevia or Monk Fruit Sweetened, and Sugar-Sweetened Formulations.
By distribution channel: Supermarkets and Hypermarkets, Convenience Stores and Gas Stations, and Foodservice and Direct E-Commerce.
Why does Still Flavored Water lead the carbonation level category?
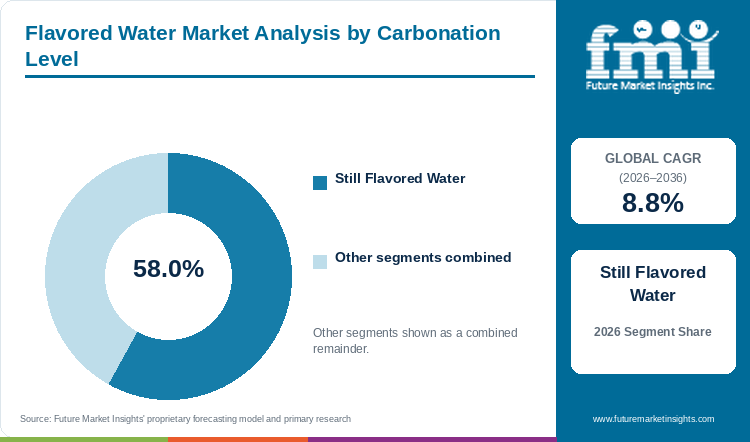
Still Flavored Water formulations hold an estimated 58.0% of carbonation level demand in 2026, anchored by high-frequency athletic, school, and household multipack hydration.
Table 5: Carbonation Level Share for the Flavored Water Market (percentage share), 2026
| Carbonation Level | Share (2026) |
|---|---|
| Still Flavored Water | 58.0% |
| Other Segments Combined | 42.0%* |
| Total | 100.0% |
*Note: Remaining carbonation level categories account for the balance of 2026 global flavored water demand.
Table 6: Carbonation Level Leadership and Market Growth for the Flavored Water Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 8.8% |
| Leading Segment | Still Flavored Water |
Still Flavored Water commands the majority of global category sales because non-carbonated fruit-infused water can be consumed rapidly during athletic workouts, school lunches, and warm-weather commutes without causing gastric carbonation fullness. While sparkling seltzers attract adult mocktail occasions, still formulations paired with vitamin-infused hydration blends anchor high-turn family multipacks and aseptic kids' lunchbox pouches, though still waters without carbonic acid require strict cold-fill or hot-fill sanitation to prevent microbial spoilage.
- Within the carbonation level segment, Still Flavored Water is projected to account for a leading 58.0% share in 2026, supported by everyday household and athletic hydration frequency.
- Longitudinal beverage sales analysis published in Nutrients in January 2026 confirmed that non-sugar-sweetened flavored waters transitioned from historical decline to statistically significant volume expansion between 2019 and 2024 as consumers exited sugared drinks [6].
What sustains Citrus Lemon Lime and Grapefruit leadership in the flavor profile segment?
Citrus Lemon Lime and Grapefruit options represent 36.5% of the flavor profile category in 2026, supported by crisp essential-oil stability and universal palate appeal.
Citrus Lemon Lime and Grapefruit formulations lead consumer repeat purchasing because cold-pressed peel essential oils and natural citric acid deliver crisp, palate-cleansing refreshment without requiring heavy sweetener masking. Compared with delicate berry or tropical esters that can oxidize during warm warehouse storage, citrus terpenes blend cleanly with both still spring water and electrolyte coconut waters. Consumer demand for transparent citrus labeling was shown in February 2026 when Spindrift Beverage Co. rolled out refreshed 2026 packaging across its sparkling water cans that explicitly names lemon, grapefruit, and blood orange extracts on the ingredient panel [7].
- In 2026, Citrus Lemon Lime and Grapefruit is anticipated to capture 36.5% of global flavor profile demand, reflecting high repeat velocity for lemon and blood orange SKUs.
- Tropical mango, passionfruit, and botanical hibiscus or cucumber-mint blends are projected to post rapid SKU additions through 2036 as Gen Z shoppers seek bold mocktail flavor variety.
How do PET Plastic Bottles lead the packaging format category?
PET Plastic Bottles account for 64.0% of packaging format value in 2026, driven by resealable portability and lightweight 24-pack grocery logistics.
PET Plastic Bottles secure the largest packaging share in flavored water because transparent, shatterproof resin allows shoppers to see clear fruit-infused liquids while screw-top closures permit multi-hour resealable consumption in cars and gym bags. While aluminum cans are expanding in sparkling 8-packs and bulk bag-in-box dispensers serve workplace cafeterias, bottle deposit laws and European recycled-content mandates require bottlers to secure food-grade recycled PET pellets at a cost premium over virgin resin.
- By packaging format, demand for PET Plastic Bottles is estimated to reach 64.0% of total category share in 2026 as grocery chains standardize 500ml and 1.5-liter shrink-wrapped multipacks.
- Large-scale circular resin execution was confirmed by Danone in October 2026 when the company reported that 96% of its water packaging is recyclable after cutting 1.5-liter bottle plastic weight by 10% and doubling recycled PET content across Evian, Volvic, and Font Vella between 2019 and 2025 [8].
Why does Zero Calorie and Unsweetened lead the caloric profile category?
Zero Calorie and Unsweetened products secure 52.0% of caloric profile value in 2026, supported by sugar-tax exemptions and metabolic health trends.
Zero Calorie and Unsweetened flavored waters flavored solely with natural fruit essence oils or trace stevia/monk fruit extracts dominate modern buyer adoption because they bypass both dietary sugar restrictions and fiscal sugar-sweetened beverage taxes. Shoppers managing weight, pre-diabetes, or GLP-1 metabolic regimens actively check nutrition panels to avoid drinks containing five or more grams of added sugar per 100 milliliters. This regulatory and dietary cutoff was highlighted in a February 2026 study in Nutrients, which documented how beverage tax reforms exempting drinks with zero added sugar or under 5 grams per 100 milliliters vs. 12.2% to 20% tax rates on higher-sugar drinks steer adult purchases toward untaxed zero-sugar flavored waters [9].
- Strict sugar-tax thresholds and clean-label diet trends place Zero Calorie and Unsweetened formulations on course to hold an estimated 52.0% share of the caloric profile category in 2026.
- Low-calorie formulations sweetened with stevia rebaudioside M and allulose will continue capturing mid-calorie juice and soda switchers through 2036 while sugar-sweetened waters lose shelf facings.
What gives Supermarkets and Hypermarkets the leading position in distribution channel?
Supermarkets and Hypermarkets command 48.5% of distribution channel share in 2026, anchored by chilled endcap promotions and weekly family stock-ups.
Supermarkets and Hypermarkets generate the largest share of global flavored water sales because multi-pack cases are bulky, heavy pantry staples that households purchase during weekly grocery trips. Modern grocery chains allocate prominent chilled checkout coolers and warm beverage-aisle endcaps to private-label and branded flavored water 12-packs, though high supermarket slotting fees and private-label price competition challenge smaller emerging brands.
- Supermarkets and Hypermarkets are predicted to secure 48.5% of distribution channel demand in 2026, anchored by promotional multi-pack pricing and wide flavor assortment.
- Consumer channel research in Keurig Dr Pepper's May 2026 State of Beverages Trend Report noted that while grocery stores anchor household stock-ups, 44% of Gen Z consumers also discover new flavored beverages via social digital channels and quick-commerce delivery [10].
What are the drivers, restraints, and opportunities in the flavored water market?
In the flavored water market, consumer substitution of sugared soft drinks and expanding national sugar-levy exemptions are projected to drive adoption while deposit-return and rPET resin costs restrain margins and functional L-theanine and vitamin waters create new growth avenues.
- Driver: Expanding national sugar-sweetened beverage excise taxes and consumer shift toward zero-sugar daily hydration drive sustained migration from sodas to flavored waters.
- Restraint: Mandatory single-use plastic deposit-return schemes, food-grade rPET resin premiums, and citrus essential-oil oxidation risks pressure bottler unit margins.
- Opportunity: Formulating L-theanine, electrolyte, and nanoemulsion vitamin-infused flavored waters in sleek aluminum cans and rPET bottles unlocks premium functional occasions.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Volume and value expansion across the flavored water industry is anchored by consumers replacing sugary afternoon sodas and high-calorie juices with crisp, aroma-driven waters that deliver sensory reward without metabolic guilt. When beverage makers tune carbonation bite and natural citrus or berry aroma release, adult shoppers treat flavored water as well as clear protein hydration drinks as an all-day lifestyle refreshment. Sensory consumer research published in Foods in May 2026 confirmed that carbonation intensity and natural fruit flavor perception are the two primary sorting criteria driving repeat consumer purchasing across carbonated and flavored refreshment drinks [11].
Risk Assessment of the Flavored Water Market: Operational and Formulation Friction
Regulatory compliance with extended producer responsibility fees, mandatory bottle deposit-return schemes, and recycled-resin quotas represents the primary cost restraint for high-volume flavored water bottlers. Because flavored water carries a lower retail price per liter than energy drinks or maternal electrolyte beverages, spikes in food-grade recycled PET pellet prices or container deposit handling fees directly compress bottler gross margins. In February 2026, the UK Government enacted The Deposit Scheme for Drinks Containers Regulations 2026, establishing statutory collection and deposit compliance obligations across single-use plastic and metal drinks containers [12].
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Beverage innovators are building higher per-liter price realization by incorporating GRAS-notified adaptogens, electrolytes, and nanoemulsion-stabilized fat-soluble vitamins into clear flavored waters without cloudiness or sediment. Formulation of zero-calorie fruit essences with cognitive relaxation ingredients such as L-theanine or botanical coconut-water blends allows brands to command premium single-serve cooler prices in convenience stores and fitness studios. Regulatory clearance for this pathway expanded on September 4, 2026 when the U.S. Food and Drug Administration issued a positive agency response letter for GRAS Notice No. GRN 001311 covering fermentation-derived L-theanine in flavored and enhanced bottled waters [13].
Flavored Water Market by Country (2026 to 2036)
FMI country modeling indicates that Brazil leads national flavored water expansion at a 10.2% CAGR through 2036, while Japan advances at a 7.9% CAGR. National growth patterns across Latin American sugar-regulated markets and East Asian vending networks depend on sugar excise laws and rPET packaging infrastructure.
Table 7: Country CAGR and Primary Growth Levers for the Flavored Water Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Brazil | 10.2% | ANVISA front-of-pack high-sugar warning labels and year-round tropical hydration demand |
| Mexico | 10.0% | Octagonal sugar warning seals, IEPS soda taxes, and Topo Chico Sabores expansion |
| USA | 9.1% | High household penetration of zero-sugar PET and aluminum can multipacks across grocery chains |
| UK | 8.7% | October 2025 HFSS retail placement bans and Soft Drinks Industry Levy reformulation incentives |
| Canada | 8.6% | Mandatory January 2026 front-of-package high-sugar nutrition symbols driving zero-sugar switches |
| Spain | 8.4% | 21% sweetened-beverage VAT differential and outdoor Mediterranean hospitality consumption |
| Germany | 8.1% | Closed-loop Pfand rPET bottle infrastructure and shift from sugary Schorle to zero-sugar aroma waters |
| Japan | 7.9% | Nationwide convenience store and vending machine velocity for transparent fruit-extract waters |
Source: Future Market Insights analysis
Brazil Flavored Water Market Outlook (2026 to 2036)
Demand for flavored water in Brazil is projected to expand at a leading 10.2% CAGR between 2026 and 2036 as ANVISA front-of-pack magnifying-glass high-sugar warning labels and tropical climate hydration needs steer urban shoppers toward zero-sugar citrus and tropical waters. What distinguishes Brazil from temperate beverage markets is year-round high ambient temperatures combined with rapid modern supermarket and cash-and-carry atacarejo expansion across Sao Paulo, Rio de Janeiro, and Minas Gerais. March 2026 GAIN attaché findings for Brazil confirm that domestic beverage processors are actively reformulating soft drinks with natural fruit extracts and non-caloric sweeteners to avoid high-sugar front-of-pack warnings [14]. High municipal water variability further reinforces packaged hydration trust.
Key takeaway: In Brazil, ANVISA front-of-pack sugar warnings and year-round tropical hydration demand are projected to drive a leading 10.2% CAGR through 2036.
Mexico Flavored Water Market Outlook (2026 to 2036)
Mexico's packaged beverage sector is experiencing rapid consumer migration from traditional sugared refrescos toward lightly flavored mineral and still waters under national octagonal warning-seal rules and IEPS sugar taxes. Consequently, national flavored water adoption in Mexico is anticipated to advance at a 10.0% CAGR through 2036 across convenience store chains and neighborhood grocery tiendas. Brand investment in Mexican heritage flavored waters was reinforced in May 2025 when The Coca-Cola Company celebrated the 130-year milestone of Monterrey-born Topo Chico while scaling Topo Chico Sabores fruit- and herbal-flavored waters bottled with partner Arca Continental [15]. Seasonal groundwater stress in northern Mexican bottling basins requires strict water-stewardship recycling in plants.
Key takeaway: In Mexico, octagonal sugar warning seals and Topo Chico Sabores expansion are anticipated to sustain a 10.0% CAGR.
USA Flavored Water Market Outlook (2026 to 2036)
Projected to expand at a 9.1% CAGR from 2026 to 2036, the USA flavored water market is driven by household pantry loading of unsweetened sparkling slim-can 8-packs and zero-sugar vitamin-enhanced PET still waters. Compared with European markets dominated by unflavored mineral water in glass, American buyers strongly favor fruit-forward berry and real-squeezed juice sparkling cans as well as zero-calorie still multipacks. October 2026 Food Price Outlook data from the USDA Economic Research Service shows that non-alcoholic beverage retail prices rose 3.8% year-on-year in September 2026 with full-year 2026 prices forecast to increase 4.4%, keeping zero-sugar flavored water multipacks an affordable daily luxury relative to coffee and soda [16]. State plastic bottle recycled-content mandates in California, Washington, and Oregon require continuous rPET procurement.
Key takeaway: In the USA, high household penetration of zero-sugar PET and aluminum can multipacks is projected to anchor a 9.1% CAGR through 2036.
UK Flavored Water Market Outlook (2026 to 2036)
In the UK, flavored water market growth is forecast to reach an 8.7% CAGR through 2036 as the Soft Drinks Industry Levy and supermarket High in Fat, Salt or Sugar placement bans push retailers to dedicate front-of-store meal-deal chillers to sugar-free flavored waters. What sets the UK apart from continental Europe is the strict regulatory restriction on promoting sugared beverages at checkout endcaps and online grocery banners. As documented in the November 2025 UK Government consultation on strengthening the Soft Drinks Industry Levy, HFSS location and advertising restrictions taking effect from October 2025 onward actively incentivize beverage makers to formulate below sugar-levy thresholds [17]. Scheduled UK deposit-return container infrastructure will require reverse-vending machine integration across supermarkets.
Key takeaway: In the UK, HFSS retail placement bans and Soft Drinks Industry Levy reformulation incentives are forecast to support an 8.7% CAGR.
Canada Flavored Water Market Outlook (2026 to 2036)
Canadian flavored water demand is estimated to progress at an 8.6% CAGR between 2026 and 2036, supported by Health Canada's mandatory January 2026 front-of-package nutrition symbol for high-sugar foods and drinks. In contrast to sugar-sweetened juice and soda categories that trigger front-of-pack warning symbols, unsweetened and stevia-sweetened flavored waters enjoy clean front labels across Ontario and Quebec grocery chains. August 2026 Toronto agricultural attaché reports confirm that Canadian beverage processors are accelerating zero-sugar natural flavor reformulations to comply with front-of-pack labeling rules [18]. Extended producer responsibility recycling fees across Canadian provinces incentivize lightweighted aluminum and rPET packs.
Key takeaway: In Canada, mandatory 2026 front-of-package sugar symbols and clean-label grocery reformulation are estimated to drive an 8.6% CAGR.
Spain Flavored Water Market Outlook (2026 to 2036)
Spanish flavored water market expansion is slated to track at an 8.4% CAGR over the 2026 to 2036 forecast period, fueled by Spain's 21% value-added tax on sweetened beverages and surging Mediterranean hospitality demand for zero-sugar lemon and botanical waters. Compared with northern European markets, Spain combines high per-capita bottled mineral water consumption with a massive outdoor terrace café and resort sector where adults actively order chilled flavored sparkling and still waters. Data from the March 2026 Madrid agricultural attaché food processing report confirms that strong tourism and hospitality foodservice activity continues to drive demand for low-calorie refreshment beverages [19]. EU single-use plastics directives requiring tethered caps on PET bottles are now fully standardized on Spanish filling lines.
Key takeaway: In Spain, the 21% sweetened-drink VAT differential and outdoor hospitality terrace consumption are slated to sustain an 8.4% CAGR.
Germany Flavored Water Market Outlook (2026 to 2036)
Deep-rooted national preference for carbonated mineral water Sprudel and natural fruit Schorle spritzers places the Germany flavored water market on course for an 8.1% CAGR from 2026 to 2036. German mineral-spring bottlers and supermarket chains are rapidly expanding zero-sugar citrus, apple-herb, and vitamin-infused still and sparkling water lines packaged in Pfand deposit-return rPET and glass bottles. Formulation research published in Frontiers in Nutrition in March 2026 demonstrated that two-stage nanoemulsion delivery systems enable clear, phase-stable multi-vitamin and natural flavor fortification in aqueous beverages without clouding transparent bottles [20]. Germany's 98%-plus Pfand return loop provides domestic bottlers with Europe's cleanest closed-loop rPET supply.
Key takeaway: In Germany, closed-loop Pfand rPET availability and consumer shift from sugary Schorle to zero-sugar aroma waters are expected to drive an 8.1% CAGR.
Japan Flavored Water Market Outlook (2026 to 2036)
Japanese flavored water market growth is predicted to advance at a 7.9% CAGR between 2026 and 2036, anchored by crystal-clear fruit-extract mineral waters sold across millions of nationwide vending machines and convenience stores. What distinguishes Japan from Western flavored water markets is the dominance of transparent natural peach, muscat grape, and lemon still waters engineered for high-turn convenience store cold vaults and bottle-to-bottle PET recycling. September 2026 Tokyo attaché retail food assessments confirm that convenience stores and automated retail channels remain primary launchpads for functional and seasonal ready-to-drink hydration products [21]. Intense weekly SKU rotation in Japanese convenience stores requires continuous seasonal flavor innovation.
Key takeaway: In Japan, nationwide vending and convenience store cold-vault velocity for transparent fruit-extract waters is predicted to generate a 7.9% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the flavored water market?
The Coca-Cola Company, PepsiCo Inc., Nestle Waters, Danone SA, Keurig Dr Pepper Inc., Spindrift Beverage Co. Inc., Talking Rain Beverage Company, Primo Brands Corporation, Suntory Beverage & Food Limited, and Hint Inc. are the notable companies in the flavored water market.
Competitive positioning across the global flavored water landscape spans multinational soft-drink and bottled-water conglomerates, regional zero-sugar refreshment leaders, and clean-label real-fruit challengers. Coca-Cola and PepsiCo coupled with Nestle Waters and Danone leverage global bottling networks and spring water heritage. Keurig Dr Pepper and Primo Brands paired with Talking Rain and Suntory anchor North American and Asian zero-sugar flavored hydration, while Spindrift and Hint lead in real-squeezed fruit and unsweetened essence niches.
- Global Multinational Beverage & Water Bottlers: The Coca-Cola Company, PepsiCo Inc., Nestle Waters, and Danone SA operate global high-speed PET and canning plants spanning Topo Chico, bubly, Maison Perrier, and Volvic lines.
- Regional Zero-Sugar & Refreshment Hydration Leaders: Keurig Dr Pepper Inc., Talking Rain Beverage Company, Primo Brands Corporation, and Suntory Beverage & Food Limited command supermarket endcaps with Sparkling Ice, Splash, and Tennensui flavored waters.
- Real-Fruit & Unsweetened Clean-Label Specialists: Spindrift Beverage Co. Inc. and Hint Inc. formulate non-concentrate squeezed fruit sparkling waters and unsweetened fruit-essence still waters free of synthetic sweeteners.
Competitive Benchmarking: Flavored Water Market
Table 8: Competitive Benchmarking for the Flavored Water Market (qualitative capability ratings), 2026
| Company | Zero-Sugar & Natural Flavor Portfolio | Cold-Vault & Multipack Distribution | rPET & Can Packaging Execution | Geographic Reach |
|---|---|---|---|---|
| The Coca-Cola Company | High | High | High | Global beverage leader; scaled Topo Chico Sabores (May 2025) and reported strong Q3 2026 zero-sugar hydration results (Oct 2026) |
| PepsiCo Inc. | High | High | High | Global beverage leader operating bubly, Propel, and LIFEWTR across retail aluminum can and rPET multipacks |
| Nestle Waters | High | High | High | Global premium water group operating Maison Perrier and Sanpellegrino; reported 3.6% H1 2026 organic growth in July 2026 |
| Danone SA | High | High | High | Global Waters leader (Volvic, Evian, Bonafont, Font Vella); achieved 96% recyclable packaging and 4.2% H1 2026 LFL growth |
| Keurig Dr Pepper Inc. | High | High | High | North American refreshment powerhouse; unveiled 2026 flavor portfolio in Feb 2026 and State of Beverages Report in May 2026 |
| Spindrift Beverage Co. Inc. | High | Medium | High | North American leader in real-squeezed NFC fruit sparkling water; rolled out updated extract-named labels in 2026 |
| Talking Rain Beverage Company | High | High | Medium | North American zero-sugar flavored water leader producing Sparkling Ice and Sparkling Ice Caffeine across grocery/convenience |
| Primo Brands Corporation | Medium | High | High | North American packaged water leader supplying Splash Refresher flavored still waters and regional spring water brands |
| Suntory Beverage & Food Limited | High | High | High | Japan, Asia-Pacific, and European leader producing Suntory Tennensui transparent flavored waters and functional hydration |
| Hint Inc. | High | Medium | Medium | U.S. specialist in unsweetened, preservative-free fruit-essence still, sparkling, and kids' box waters |
Evaluation basis: Zero-Sugar and Natural Flavor Portfolio evaluates breadth of unsweetened essence and stevia/allulose flavored water SKUs, while Cold-Vault Distribution rates supermarket endcap and vending machine reach. rPET and Can Packaging Execution measures verified recycled PET inclusion and sleek aluminum can line capacity.
Key Developments in the Flavored Water Market
- The Coca-Cola Company reported on October 27, 2026 its third-quarter 2026 financial results, highlighting continued volume and value share gains across its zero-sugar and Topo Chico flavored hydration portfolio [22].
- Danone SA announced on July 28, 2026 its first-half 2026 results with 4.2% like-for-like sales growth, supported by strong Waters division momentum across Volvic and Evian flavored and vitamin-infused lines [23].
- Nestle SA reported on July 23, 2026 its half-year 2026 financial results with 3.6% organic growth, driven by real internal growth execution across Maison Perrier and Sanpellegrino flavored sparkling waters [24].
Key Players in the Flavored Water Market
Global Multinational Beverage & Water Bottlers
- The Coca-Cola Company
- PepsiCo Inc.
- Nestle Waters
- Danone SA
Regional Zero-Sugar & Refreshment Hydration Leaders
- Keurig Dr Pepper Inc.
- The Talking Rain Beverage Company
- Primo Brands Corporation
- Suntory Beverage & Food Limited
Real-Fruit & Unsweetened Clean-Label Specialists
- Spindrift Beverage Co. Inc.
- Hint Inc.
Flavored Water Market - Report Scope
Table 9: Report Scope for the Flavored Water Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Carbonation Level; Flavor Profile; Packaging Format; Caloric Profile; Distribution Channel |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial manufacturer and bottler revenue from ready-to-drink still and sparkling waters infused with natural fruit extracts, botanical/herbal essences, or caloric/non-caloric sweeteners (zero-calorie unsweetened, stevia/monk fruit/allulose low-calorie, and lightly sugar-sweetened waters). Category Scope Note: Excludes plain unflavored bottled still/sparkling water, high-caffeine energy drinks, sports isotonic recovery drinks, 100% fruit juices, and concentrated liquid/powder water enhancers. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Brazil, Mexico, USA, UK, Canada, Spain, Germany, Japan, and additional countries in the full report |
| Key Companies Covered | The Coca-Cola Company, PepsiCo Inc., Nestle Waters, Danone SA, Keurig Dr Pepper Inc., Spindrift Beverage Co. Inc., Talking Rain Beverage Company, Primo Brands Corporation, Suntory Beverage & Food Limited, Hint Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Flavored Water Market - Research Methodology
Table 10: Research Methodology for the Flavored Water Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with beverage R&D flavorists, aseptic PET and canning plant directors, and supermarket cold-vault category managers to validate carbonation shares, sweetener splits, and per-liter pricing. |
| Secondary Research | Analysis of International Bottled Water Association (IBWA) progress reports, WHO global sugar-sweetened beverage tax registries, USDA FAS/ERS Retail Foods and Food Price Outlook bulletins, UK HM Treasury SDIL consultations, and FDA GRAS notices. |
| Market Sizing and Forecasting | Top-down global packaged water and refreshment beverage baselines reconciled against bottom-up flavored still and sparkling liter volumes (42.8B to 45.2B liters in 2026) and format-weighted retail realization from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight sugar-sweetened beverage excise rates, mandatory front-of-pack sugar warning labels, convenience store cooler penetration, and rPET deposit laws across eight countries. |
| Operational Benchmark Traceability | Volume shares, container splits, and sugar-tax thresholds in Tables 2, 3, and 4 trace to IBWA 2025/2026 Progress Report benchmarks (45.5% water share; 70% PET share), WHO 2026 SSB tax thresholds (<5g/100mL), and Danone rPET disclosures. |
| Data Triangulation and Validation | Revenue estimates isolate ready-to-drink flavored still and sparkling waters while strictly excluding plain unflavored bottled water, concentrated drops/powders, and traditional carbonated colas. |
Flavored Water Market by Segments
Flavored Water Market segmented by Carbonation Level:
- Still Flavored Water
- Carbonated Sparkling Flavored Water
- Lightly Effervescent Micro-Dosed Water
- Nitrogen-Infused Smooth Water
Flavored Water Market segmented by Flavor Profile:
- Citrus Lemon Lime and Grapefruit
- Berry Strawberry Raspberry and Blueberry
- Tropical Mango Pineapple and Passionfruit
- Botanical Herbal and Floral Blends
Flavored Water Market segmented by Packaging Format:
- PET Plastic Bottles
- Aluminum Cans
- Glass Bottles
- Tetra Pak Cartons
- Aseptic Pouches and Refillable Jugs
Flavored Water Market segmented by Caloric Profile:
- Zero Calorie and Unsweetened
- Low Calorie Stevia or Monk Fruit Sweetened
- Sugar-Sweetened Formulations
- Real-Juice Lightly Sweetened (<25 kcal)
Flavored Water Market segmented by Distribution Channel:
- Supermarkets and Hypermarkets
- Convenience Stores and Gas Stations
- On-Trade Foodservice and Vending
- Direct-to-Consumer E-Commerce
Flavored Water Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] International Bottled Water Association (IBWA). (2026, May 13). Consumers Choose Bottled Water First for the 10th Year in a Row. IBWA Official News Release.
- [2] Keurig Dr Pepper Inc. (2026, February 18). Keurig Dr Pepper Announces Flavorful New Innovation Across Its Refreshment Portfolio. Keurig Dr Pepper Corporate Newsroom.
- [3] Smeets, P. A. M., & van der Klaauw, A. (2026, August 14). Brain and physiological responses to flavored waters with different sweeteners. The American Journal of Clinical Nutrition / PubMed Central (PMC13494110).
- [4] International Bottled Water Association (IBWA). (2026, January 8). 2025 IBWA Progress Report. IBWA Annual Industry Progress Report.
- [5] World Health Organization (WHO). (2026, January 13). Global report on the use of sugar-sweetened beverage taxes, 2025. World Health Organization Publication ISBN 978-92-4-011894-2.
- [6] Backholer, K., & Peeters, A. (2026, January 15). Temporal Trends in Australian Non-Alcoholic Beverage Sales from 1997 to 2024. Nutrients, 18(2), 361 (MDPI Open Access).
- [7] Spindrift Beverage Co. Inc. (2026, February 10). The Same Spindrift You Love, Now With Refreshed Packaging. Spindrift Official Corporate Blog.
- [8] Danone SA. (2026, October 30). The benefits of water for health and nature. Danone Group Waters Sustainability Report.
- [9] Gomez, L., & Rivera, J. (2026, February 25). Consumption of Sugary Beverages by Adults Prior to Sugary Drink Tax Updates. Nutrients, 18(5), 716 (MDPI Open Access).
- [10] Keurig Dr Pepper Inc. (2026, May 6). Keurig Dr Pepper's 2026 State of Beverages Trend Report Reveals Gen Z's Drink Choice Is Now a Form of Self-Expression. Keurig Dr Pepper Corporate Release.
- [11] Kim, H. J., & Lee, S. (2026, May 28). Carbonation Perception and Texture Characteristics of Carbonated Beverages. Foods, 15(11), 2013 (MDPI Open Access).
- [12] UK Statutory Instruments. (2026, February 12). The Deposit Scheme for Drinks Containers (Wales) Regulations 2026. King's Printer of Acts of Parliament (Legislation.gov.uk).
- [13] U.S. Food and Drug Administration (FDA). (2026, September 4). GRAS Notice (GRN) 1311 Agency Response Letter. U.S. FDA Human Foods Program Docket.
- [14] USDA Foreign Agricultural Service. (2026, March 31). Brazil: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report BR2026-0011.
- [15] The Coca-Cola Company. (2025, May 15). 130 Years Young: Topo Chico Celebrates Anniversary Milestone. The Coca-Cola Company Media Center.
- [16] USDA Economic Research Service (ERS). (2026, October 23). Food Price Outlook Summary Findings. U.S. Department of Agriculture Economic Research Service.
- [17] HM Treasury & UK Department of Health and Social Care. (2025, November 25). Strengthening the Soft Drinks Industry Levy consultation. GOV.UK Official Policy Consultation.
- [18] USDA Foreign Agricultural Service. (2026, August 27). Canada: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report CA2026-0022.
- [19] USDA Foreign Agricultural Service. (2026, March 31). Spain: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report SP2026-0003.
- [20] Patel, R., & Wang, Y. (2026, March 4). A novel formulation of multi-vitamin fortified beverage with natural flavor nanoemulsion. Frontiers in Nutrition, 13, 1779711.
- [21] USDA Foreign Agricultural Service. (2026, September 28). Japan: Retail Foods Annual. U.S. Department of Agriculture GAIN Report JA2026-0056.
- [22] The Coca-Cola Company. (2026, October 27). Coca-Cola Reports Third Quarter 2026 Results and Raises Full Year Guidance. The Coca-Cola Company Media Center.
- [23] Danone SA. (2026, July 28). H1 Results 2026. Danone Corporate Press Release.
- [24] Nestle SA. (2026, July 23). Half-year results 2026: execution driving RIG. Nestle Global Media Release.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the flavored water market in 2026 and what is forecast for 2036?
- Which soda-substitution and sugar-tax regulatory pressures support demand for flavored water?
- Why does Still Flavored Water lead the carbonation level category?
- Why do Citrus Lemon Lime and Grapefruit and PET Plastic Bottles lead their categories globally?
- How do growth rates differ across Brazil, Mexico, and the UK?
- Which leading companies supply global multipack flavored waters versus real-fruit clean-label cans today?
- What plastic deposit-return and rPET resin cost pressures restrain bottler margins?
- What should beverage formulators evaluate before adding L-theanine or nanoemulsion vitamins to flavored water?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Carbonation Level, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Carbonation Level, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Carbonation Level, 2026 to 2036
- Still Flavored Water
- Carbonated Sparkling Flavored Water
- Lightly Effervescent Micro-Dosed Water
- Nitrogen-Infused Smooth Water
- Y-o-Y Growth Trend Analysis By Carbonation Level, 2021 to 2025
- Absolute $ Opportunity Analysis By Carbonation Level, 2026 to 2036
- Global Market Analysis and Forecast, By Flavor Profile, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Flavor Profile, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Flavor Profile, 2026 to 2036
- Citrus Lemon Lime and Grapefruit
- Berry Strawberry Raspberry and Blueberry
- Tropical Mango Pineapple and Passionfruit
- Botanical Herbal and Floral Blends
- Y-o-Y Growth Trend Analysis By Flavor Profile, 2021 to 2025
- Absolute $ Opportunity Analysis By Flavor Profile, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- PET Plastic Bottles
- Aluminum Cans
- Glass Bottles
- Tetra Pak Cartons
- Aseptic Pouches and Refillable Jugs
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Caloric Profile, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Caloric Profile, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Caloric Profile, 2026 to 2036
- Zero Calorie and Unsweetened
- Low Calorie Stevia or Monk Fruit Sweetened
- Sugar-Sweetened Formulations
- Real-Juice Lightly Sweetened (<25 kcal)
- Y-o-Y Growth Trend Analysis By Caloric Profile, 2021 to 2025
- Absolute $ Opportunity Analysis By Caloric Profile, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets and Hypermarkets
- Convenience Stores and Gas Stations
- On-Trade Foodservice and Vending
- Direct-to-Consumer E-Commerce
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Carbonation Level
- By Flavor Profile
- By Packaging Format
- By Caloric Profile
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- The Coca-Cola Company
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- PepsiCo Inc.
- Nestle Waters
- Danone SA
- Keurig Dr Pepper Inc.
- Spindrift Beverage Co. Inc.
- Talking Rain Beverage Company
- Primo Brands Corporation
- Suntory Beverage & Food Limited
- Hint Inc.
- The Talking Rain Beverage Company
- The Coca-Cola Company
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Carbonation Level, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Flavor Profile, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Caloric Profile, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Carbonation Level, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Flavor Profile, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Caloric Profile, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Carbonation Level, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Flavor Profile, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Caloric Profile, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Carbonation Level, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Flavor Profile, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Caloric Profile, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Carbonation Level, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Flavor Profile, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Caloric Profile, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Carbonation Level, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Flavor Profile, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Caloric Profile, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Carbonation Level, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Flavor Profile, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Caloric Profile, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Carbonation Level, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Flavor Profile, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Caloric Profile, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Carbonation Level, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Carbonation Level, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Carbonation Level
- Figure 6: Global Market Value Share and BPS Analysis by Flavor Profile, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Flavor Profile, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Flavor Profile
- Figure 9: Global Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Packaging Format
- Figure 12: Global Market Value Share and BPS Analysis by Caloric Profile, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Caloric Profile, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Caloric Profile
- Figure 15: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Distribution Channel
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Carbonation Level, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Carbonation Level, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Carbonation Level
- Figure 32: North America Market Value Share and BPS Analysis by Flavor Profile, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Flavor Profile, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Flavor Profile
- Figure 35: North America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Packaging Format
- Figure 38: North America Market Value Share and BPS Analysis by Caloric Profile, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Caloric Profile, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Caloric Profile
- Figure 41: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Distribution Channel
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Carbonation Level, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Carbonation Level, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Carbonation Level
- Figure 48: Latin America Market Value Share and BPS Analysis by Flavor Profile, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Flavor Profile, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Flavor Profile
- Figure 51: Latin America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Packaging Format
- Figure 54: Latin America Market Value Share and BPS Analysis by Caloric Profile, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Caloric Profile, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Caloric Profile
- Figure 57: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Carbonation Level, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Carbonation Level, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Carbonation Level
- Figure 64: Western Europe Market Value Share and BPS Analysis by Flavor Profile, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Flavor Profile, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Flavor Profile
- Figure 67: Western Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Packaging Format
- Figure 70: Western Europe Market Value Share and BPS Analysis by Caloric Profile, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Caloric Profile, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Caloric Profile
- Figure 73: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Carbonation Level, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Carbonation Level, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Carbonation Level
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Flavor Profile, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Flavor Profile, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Flavor Profile
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Packaging Format
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Caloric Profile, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Caloric Profile, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Caloric Profile
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Carbonation Level, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Carbonation Level, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Carbonation Level
- Figure 96: East Asia Market Value Share and BPS Analysis by Flavor Profile, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Flavor Profile, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Flavor Profile
- Figure 99: East Asia Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Packaging Format
- Figure 102: East Asia Market Value Share and BPS Analysis by Caloric Profile, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Caloric Profile, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Caloric Profile
- Figure 105: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Carbonation Level, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Carbonation Level, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Carbonation Level
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Flavor Profile, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Flavor Profile, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Flavor Profile
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Packaging Format
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Caloric Profile, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Caloric Profile, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Caloric Profile
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Carbonation Level, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Carbonation Level, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Carbonation Level
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Flavor Profile, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Flavor Profile, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Flavor Profile
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Packaging Format
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Caloric Profile, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Caloric Profile, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Caloric Profile
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the flavored water market in 2026, and what is forecast for 2036?
FMI estimates that global flavored water market size stood at USD 21.5 billion in 2025 and reached USD 23.4 billion in 2026. Overall valuation is projected to hit USD 54.4 billion by 2036.
What is the CAGR for the flavored water market from 2026 to 2036?
The global flavored water sector is forecast to expand at an 8.8% CAGR over the 2026 to 2036 assessment window, adding USD 31.0 billion in incremental market value.
Which carbonation level segment leads the flavored water market?
Still Flavored Water holds an estimated 58.0% of carbonation level demand in 2026 since non-carbonated fruit-essence waters fit everyday gym, school, and family hydration occasions.
Which packaging format segment leads the flavored water market?
PET Plastic Bottles represent 64.0% of the packaging format category in 2026 as resealable closures and shatterproof 24-packs anchor grocery and convenience store sales.
Which country has a notable growth outlook during the assessment period?
Brazil leads national expansion projections at a 10.2% CAGR through 2036, driven by ANVISA front-of-pack high-sugar warning labels and year-round tropical hydration demand.
Who are the key players in the market?
The Coca-Cola Company, PepsiCo Inc., Nestle Waters, Danone SA, Keurig Dr Pepper Inc., Spindrift Beverage Co. Inc., Talking Rain Beverage Company, Primo Brands Corporation, Suntory Beverage & Food Limited, and Hint Inc. lead commercial supply across zero-sugar still and sparkling flavored waters.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
