
- Market Size (2026)
- USD 25.1 Bn
- Forecast (2036)
- USD 42.9 Bn
- CAGR (2026 to 2036)
- 5.5%
How big is Gin Market in 2026?
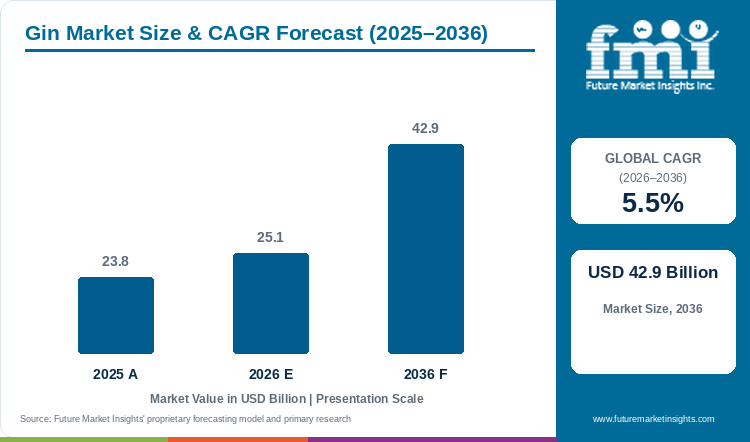
Registering a value of USD 23.8 billion in 2025, the gin market expanded to USD 25.1 billion in 2026 and is anticipated to achieve USD 42.9 billion by 2036, driven by a 5.5% CAGR.
Table 1: Market Size and Forecast for the Gin Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 23.8 billion |
| Estimated Market Size in 2026 | USD 25.1 billion |
| Projected Market Size by 2036 | USD 42.9 billion |
| CAGR, 2026 to 2036 | 5.5% |
| Added Revenue, 2026 to 2036 | USD 17.8 billion |
The global gin market was valued at USD 23.8 billion in 2025 and is estimated to reach USD 25.1 billion in 2026. The industry valuation is projected to reach USD 42.9 billion by 2036, expanding at a compound annual growth rate (CAGR) of 5.5% between 2026 and 2036. London Dry Gin is projected to hold an estimated 42.5% share of 2026 product type demand, since bartenders and retail shoppers rely on dry juniper spirits that retain crispness against tonic water. FMI analysis suggests that category revenue is driven by premium basket trade-up, where cocktail lounges and home mixologists replace economy well pours with region-specific botanical distillates. Market brief data published by the USDA Foreign Agricultural Service in September 2026 showed European national spirits retail value rising 9.3% as premiumized categories offset volume moderation. That botanical trade-up separates gin from the broader distilled spirits sector at 3.5% CAGR, given that multi-botanical gin recipes capture higher per-bottle margins than commodity white spirits. Brand owners are investing in experiential bar programs to lock in that demand, evidenced when Bacardi Limited published its 2026 Cocktail Trends Report in November 2025 showing 76% of surveyed consumers prioritize theatrical cocktail serves and 77% check ingredient origin labels. Supermarket liquor buyers and hospitality groups renew gin listings on consistent botanical terpene stability and glass bottle shelf appeal through 2036.
Key Market Trends & Insights
- By product type: London Dry Gin holds an estimated 42.5% share in 2026 since redistilled juniper-forward profiles without added post-distillation sugar anchor classic cocktail recipes.
- By price tier: Premium Gin represents an expected 46.0% share in 2026 driven by consumer trade-up toward small-batch copper-pot distillates in urban bars and retail chains.
- By distribution channel: Off-Trade Supermarkets and Specialty Liquor Stores account for a projected 58.0% in 2026 supported by household bar-cart replenishment and seasonal tasting promotions.
- By packaging format: Glass Bottles secure an anticipated 84.5% in 2026 owing to inert flint and colored glass walls that protect volatile citrus and juniper oils.
- By ABV strength: Standard 37.5% to 43.0% ABV commands an estimated 72.0% in 2026 through alignment with mandatory statutory gin proof minimums in Europe and North America.
Regional Highlights
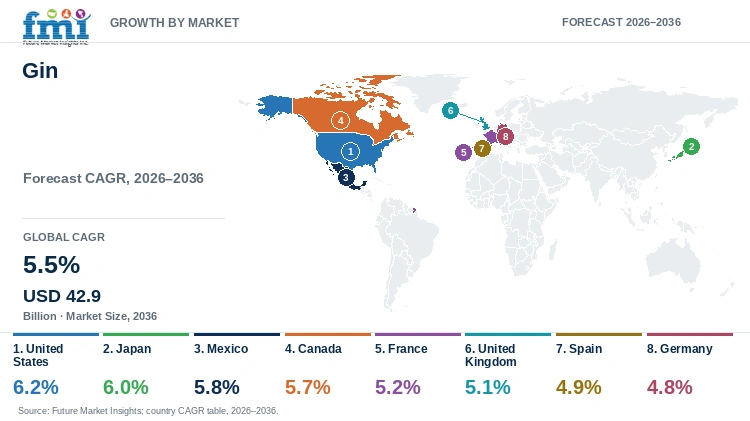
- Top national expansion: The United States leads national growth projections at a 6.2% CAGR through 2036 under supermarket spirits aisle expansion and craft botanical innovation.
- Broader country progression: Japan tracks at a 6.0% CAGR ahead of Mexico at 5.8% and Canada at 5.7%, while Germany advances at a 4.8% CAGR.
Market Size & Forecast
Commercial gin distilleries confront fluctuating alpha-pinene and nonvolatile phytochemical yields across wild-harvested European juniper berry lots that can alter batch aroma and palate profiles. When master distillers rely on uncalibrated botanical maceration, essential oil clouding known as louching occurs when chilled tonic or ice is added in hospitality service. Empirical research published by the American Chemical Society in the Journal of Agricultural and Food Chemistry in August 2026 characterized carbonic juniper berry extracts and identified deoxypodophyllotoxin as a principal active constituent modulating sensory receptor pathways. Consequently, spirits houses expanding zero-proof spirits and full-strength gin lines deploy gas-chromatography quality gates and vapor-infusion baskets to guarantee uniform aromatic cut across global bottling plants.
Case Volume and Botanical Input Sizing
Table 2: Case Volume and Botanical Input Sizing for the Gin Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 23.8 | 25.1 | 42.9 |
| Commercial distilled gin volume (million 9L cases) | 98.5 to 104.0 | 103.0 to 109.5 | 162.0 to 175.0 |
| Dried juniper & botanical input demand (thousand MT) | 41.0 to 45.5 | 43.2 to 48.0 | 68.5 to 76.0 |
| Average wholesale realization per 9L case (USD) | 228.0 to 241.0 | 232.0 to 246.0 | 248.0 to 265.0 |
Operational note: Botanical tonnage ranges apply standard 15 to 35 grams of dried juniper berries and coriander seed per liter of redistilled neutral grain spirit.
Global spirits conglomerates balance continuous column-still neutral grain spirit rectification against copper pot-still botanical redistillation to protect gross margins during warehouse inventory adjustments. As documented in a February 2026 trade briefing from the U.S. International Trade Commission, five leading international distillers held a combined USD 22.0 billion in maturing and bottled spirits inventories entering 2026 . Unaged botanical distillation allows producers of bottled cocktails and premium dry gins to turn working capital within weeks rather than tying up cash in multi-year oak barrel warehousing.
Per Capita & Hospitality Channel Sizing
Table 3: Per Capita and Hospitality Channel Spending Indicators for the Gin Market (USD and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Adult legal-drinking-age population (billion) | 5.4 | 5.5 | 6.1 |
| Annual gin spend per 1,000 legal-age adults (USD) | 4,407.4 | 4,563.6 | 7,032.8 |
| Hospitality on-trade bar pour revenue share (%) | 28.0% to 31.0% | 29.0% to 32.0% | 33.0% to 36.5% |
| Craft & super-premium botanical share of value (%) | 36.0% to 39.0% | 38.0% to 41.5% | 46.0% to 50.0% |
Table 4: Distilled Spirits Trade & Channel Spending Indicators for the Gin Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 25.1 billion | 2026 global valuation baseline |
| U.S. distilled spirits export baseline (2025) | USD 2.37 billion | DISCUS 2025 American Spirits Exports Report |
| Combined top-5 distiller aging & spirit inventory | USD 22.0 billion | USITC Executive Briefing on spirits trade |
| Off-Trade Supermarkets and Specialty Liquor Stores revenue, 2026 | USD 14.6 billion | 58.0% distribution channel allocation |
Local liquor licensing authorities and bonded warehouse removals govern direct-to-consumer event sales and retail revenue realization for craft and multinational gin labels across Europe and North America. Public licensing records issued by The Highland Council in October 2026 for Dunrobin Distillery gin market stalls illustrate how Scottish craft distillers utilize municipal occasional liquor permits to sample and sell small-batch Highland botanical gins directly to regional buyers. Distillers scaling canned cocktails and 700-milliliter glass gin SKUs calibrate bottling proof and regional distributor allocations to optimize excise duty brackets and preserve retail shelf price competitiveness.
Analyst Perspective
"Hospitality bar groups and supermarket spirits buyers do not purchase gin merely as a neutral mixer; they buy guaranteed botanical aromatic lift that survives dilution in highballs and classic cocktails. Distillers that combine vapor-infused regional botanicals with disciplined glass-bottle pricing and zero-proof brand extensions will secure permanent shelf facings through 2036."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the gin market segmented?
The gin market is segmented by product type, price tier, distribution channel, packaging format, and ABV strength. In 2026, London Dry Gin is projected at 42.5%, Premium Gin at 46.0%, Off-Trade Supermarkets and Specialty Liquor Stores at 58.0%, Glass Bottles at 84.5%, and Standard 37.5% to 43.0% ABV at 72.0%.
By product type: London Dry Gin, Plymouth Gin, Old Tom Gin, Flavored and Botanical Infused Gin, and Genever.
By price tier: Premium Gin, Super-Premium and Ultra-Premium Gin, Standard Mass-Market Gin, and Value and Economy Well Gin.
By distribution channel: Off-Trade Supermarkets and Specialty Liquor Stores, On-Trade Cocktail Bars and Fine Dining, Hotel and Resort Hospitality Venues, Direct-to-Consumer and Online Retail, and Travel Retail.
By packaging format: Glass Bottles, Aluminum Beverage Cans, Ceramic and Specialty Decanters, and Bulk Hospitality Dispensing Formats.
By ABV strength: Standard 37.5% to 43.0% ABV, Navy Strength and Overproof Above 45.0% ABV, Low-ABV Botanical Aperitifs, and Zero-Proof Distilled Botanical Alternates.
Why does London Dry Gin lead the product type category?
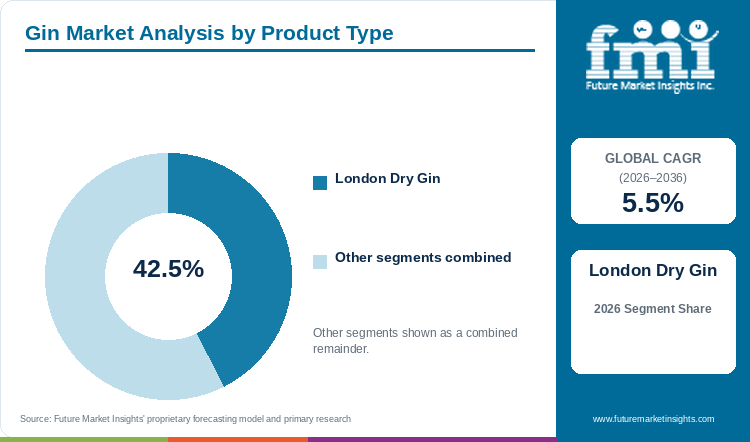
London Dry Gin holds an estimated 42.5% of product type demand in 2026, anchored by crisp juniper-forward distillation rules and universal cocktail bar pouring.
Table 5: Product Type Share for the Gin Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| London Dry Gin | 42.5% |
| Other Segments Combined | 57.5%* |
| Total | 100.0% |
*Note: Remaining product type categories account for the balance of 2026 global gin market demand.
Table 6: Product Type Leadership and Market Growth for the Gin Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.5% |
| Leading Segment | London Dry Gin |
London Dry Gin requires redistillation of ethyl alcohol of agricultural origin in the presence of natural plant botanicals with predominantly juniper flavor and a strict limit of 0.1 grams of added sweetening per liter. Beverage directors managing high-volume bar programs and ready-to-drink cocktails specify London Dry Gin since its crisp pine and citrus terpene profile cuts cleanly through quinine tonic water and dry vermouth without cloying sweetness. Seasonal fluctuations in wild Balkan and Italian juniper berry oil content still require master distillers to adjust botanical charge ratios to prevent batch variability.
- Within the product type segment, London Dry Gin is projected to account for a leading 42.5% share in 2026, driven by mandatory house-pour contracts across hotel bars and cocktail lounges.
- Export trade records published by the Distilled Spirits Council of the United States in March 2026 documented that the European Union, United Kingdom, Australia, Mexico, and Canada accounted for 72% of American spirits exports in 2025 as international buyers prioritized classic dry styles.
What sustains Premium Gin leadership in the price tier segment?
Premium Gin represents an estimated 46.0% of the price tier category in 2026, supported by hospitality cocktail menu trade-up and artisanal copper-pot botanical positioning.
Premium Gin positioned between twenty-five and forty dollars per bottle captures the sweet spot where everyday cocktail affordability meets authentic copper-pot botanical craftsmanship. While economy well labels face volume erosion from shifting drinking habits, consumers entertaining at home trade up to heritage London Dry and regional Japanese or Mediterranean botanical bottles that double as bar-cart centerpiece items next to premixed cocktail shots. In August 2025, Diageo plc reported in its Annual Report 2025 that organic net sales increased 1.7% with positive price-mix of 0.8% as consumers favored premium spirits brands across nearly 180 countries.
- In 2026, Premium Gin is anticipated to capture 46.0% of global price tier demand, reflecting strong supermarket call-brand rotation and on-trade cocktail menu callouts.
- Future segment progression shows super-premium small-batch releases expanding fastest in travel retail while mainstream premium bottles defend core grocery volume against private-label spirits.
How do Off-Trade Supermarkets and Specialty Liquor Stores lead the distribution channel category?
Off-Trade Supermarkets and Specialty Liquor Stores account for an expected 58.0% of distribution channel demand in 2026, driven by home mixology stocking and multi-brand retail aisle promotions.
Off-Trade Supermarkets and Specialty Liquor Stores provide distillers with eye-level endcap displays, cross-merchandising next to artisanal tonic waters, and multi-bottle loyalty discounts that on-premise bars cannot match on per-serving price. Shoppers replicating bar-quality cocktails at home purchase 700-milliliter and 750-milliliter bottles during weekly grocery trips, supporting cross-category sales of alcoholic flavors and citrus garnishes. Strict state liquor control monopolies and supermarket alcohol licensing caps in parts of North America and Northern Europe nevertheless require brand owners to manage complex regional distributor networks.
- By distribution channel, Off-Trade Supermarkets and Specialty Liquor Stores are estimated to reach 58.0% of total category share in 2026 as household cocktail preparation outpaces nightclub bottle service.
- Trade analysis released by spiritsEUROPE in March 2026 documented how European distillers rely on diversified retail and export distribution lanes across more than 150 international markets to offset hospitality volatility.
Why do Glass Bottles lead the packaging format category?
Glass Bottles secure a projected 84.5% of packaging format share in 2026, supported by chemical inertness that prevents terpene scalping and embossed back-bar prestige.
High-proof juniper distillates contain reactive monoterpenes including limonene, pinene, and myrcene that interact with polymeric liners if stored for extended periods in thin plastic containers. Heavy flint, emerald-green, and apothecary-style amber glass bottles provide an impermeable oxygen barrier while communicating heritage distillation quality on illuminated bar shelves. In October 2025, the European Food Safety Authority updated its Scientific Committee work programme covering safety assessments for 2,700 plant species in the Compendium of Botanicals used across beverage flavourings.
- Glass Bottles are predicted to secure 84.5% of packaging format demand in 2026, supported by zero chemical flavour scalping and harmonized 700-milliliter and 750-milliliter standard-of-fill laws.
- Distillers are simultaneously lightweighting glass bottle walls by 10% to 15% and introducing recycled cullet to lower scope-three packaging carbon emissions without sacrificing shelf presence.
What gives Standard 37.5% to 43.0% ABV the leading position in ABV strength?
Standard 37.5% to 43.0% ABV commands an anticipated 72.0% of ABV strength share in 2026, anchored by statutory spirits definitions across European Union and North American jurisdictions.
Statutory food and beverage codes in the European Union and United Kingdom mandate a minimum bottling strength of 37.5% alcohol by volume for any spirit labeled as gin, while United States federal standards require at least 40.0% alcohol by volume. Spirit rectification within the 37.5% to 43.0% ABV window keeps volatile juniper and citrus essential oils dissolved in hydro-alcoholic solution at room temperature while avoiding the punitive excise tax brackets applied to overproof spirits.
- With a projected 72.0% share of the ABV strength segment in 2026, Standard 37.5% to 43.0% ABV remains the baseline specification for multinational and craft gin labels.
- In October 2026, HM Revenue & Customs published policy paper updates confirming that United Kingdom Alcohol Duty rates will uprate by the Retail Price Index of 4.55% while expanding Small Producer Relief discounts for lower-ABV products.
What are the drivers, restraints, and opportunities in the gin market?
In the gin market, consumer trade-up toward regional botanical highballs and supermarket premix merchandising is projected to drive adoption, while alcohol excise duty upratings and juniper harvest swings restrain margins and vacuum-distilled low-ABV spirits open new moderation occasions.
- Driver: Consumer trade-up toward terroir-driven botanical gin recipes and refreshing highball serves across urban cocktail lounges and supermarket aisles accelerates repeat purchasing.
- Restraint: Inflation-linked national alcohol excise duty increases and seasonal volatility in wild juniper berry harvests compress distiller operating margins.
- Opportunity: Vacuum distillation at reduced temperatures and pressure enables low-ABV and zero-proof botanical spirits that capture adult moderation occasions.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Hospitality beverage directors and retail shoppers are shifting away from heavy, high-calorie sweet cocktails toward crisp, aromatic botanical highballs that feature regional plant provenance. Distillers differentiate their labels by vapor-infusing or macerating hand-foraged local ingredients such as Japanese yuzu peel and Scottish heather with classic juniper berries. Selection of distinctive botanical flavors allows craft and multinational brands to command premium price points on cocktail menus and luxury retail shelves. Financial disclosures released by Remy Cointreau in June 2026 showed full-year 2025-26 consolidated sales reaching EUR 935.3 million with positive organic growth supported by artisanal spirits such as The Botanist Islay Dry Gin.
Risk Assessment of the Gin Market: Operational and Formulation Friction
Higher government excise taxes on distilled spirits and elevated glass bottle energy costs represent the primary commercial hurdles restraining volume expansion in mature Western markets. When finance ministries index per-liter pure alcohol duties to inflation, retail bottle prices rise past psychological consumer thresholds and trigger distributor destocking across wholesale tiers. Producers sourcing premium spirits glass bottles and imported botanicals must also manage tariff uncertainties and warehouse inventory carrying costs. In December 2025, Brown-Forman Corporation reported in its First Half Fiscal 2026 financial release that broad-based growth of Gin Mare and agency brand distribution in Japan and Mexico helped counter distributor inventory adjustments across North American and European trade lanes.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Rotary-evaporator vacuum distillation and spinning-cone column extraction allow master distillers to capture delicate floral and citrus top notes at temperatures below 30 degrees Celsius without cooking or scorching fresh botanicals. This low-temperature processing unlocks ultra-premium regional craft editions as well as hydro-distilled zero-proof botanical spirits that replicate the bite of London Dry Gin for weeknight moderation occasions next to artisanal agave spirits. Active distillery recognition confirms this technical direction, as Suntory Holdings Limited announced in November 2025 that its Osaka Spirits & Liqueurs Craft Distillery earned the 2025 IWSC Producer Trophy for its specialized botanical maceration and distillation craftsmanship.
Gin Market by Country (2026 to 2036)
FMI country modeling indicates that the United States leads gin market expansion at a 6.2% CAGR through 2036, while Japan advances at a 6.0% CAGR and Mexico records a 5.8% CAGR. Commercial performance across North American supermarket chains, East Asian izakaya highball venues, and European aperitivo terraces depends on local botanical differentiation and excise duty rules.
Table 7: Country CAGR and Primary Growth Levers for the Gin Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| United States | 6.2% | Supermarket liquor aisle expansion and barrel-rested craft botanical gin adoption |
| Japan | 6.0% | Yuzu and Sansho pepper craft distillation and highball izakaya dining culture |
| Mexico | 5.8% | Resort hospitality cocktail programs and urban premium off-trade liquor chains |
| Canada | 5.7% | Provincial liquor board craft listings and domestic botanical micro-distilling |
| France | 5.2% | Cocktail bar mixology growth and supermarket artisanal spirits merchandising |
| United Kingdom | 5.1% | Heritage London Dry export distilling and Small Producer Relief low-ABV innovation |
| Spain | 4.9% | Balloon-glass gin-and-tonic terrace hospitality and Mediterranean citrus infusions |
| Germany | 4.8% | Black Forest herbal maceration heritage and specialty off-trade grocery retail |
Source: Future Market Insights analysis
United States Gin Market Outlook (2026 to 2036)
Demand for gin in the United States is projected to expand at a leading 6.2% CAGR between 2026 and 2036 as supermarket chains, club stores, and cocktail bars widen shelf allocations for American craft and imported botanical gins. Domestic commercial demand is driven by the rapid rise of barrel-rested American dry gins and citrus-forward botanical expressions tailored to bourbon and tequila drinkers. Industry reporting from the Distilled Spirits Council of the United States in February 2026 highlighted how premium botanical expressions and craft distillery expansions drive spirits sales across regional retail channels. Mandatory three-tier state wholesaler distribution laws still require emerging craft distilleries to partner with national liquor distributors to achieve multi-state grocery reach.
Key takeaway: In the United States, club-store spirits merchandising and citrus-forward or barrel-rested craft formulations are projected to drive leading 6.2% CAGR expansion.
Japan Gin Market Outlook (2026 to 2036)
In Japan, gin market adoption is anticipated to advance at a 6.0% CAGR from 2026 to 2036 as domestic craft distilleries infuse indigenous yuzu and gyokuro tea into grain-based distillates. Japanese izakaya dining venues serve crisp, unsweetened gin soda highballs known as Sui Gin Soda with savory meals. Annual food processing analysis from USDA FAS Tokyo attachés in April 2026 noted resilient growth in Japan's beverage categories despite broader food sector consolidation. Domestic distillers also capture high export margins as international bartenders stock Japanese craft gins on luxury back-bars.
Key takeaway: In Japan, mealtime gin-soda highball adoption and indigenous botanical distillation are anticipated to sustain a 6.0% CAGR through 2036.
Mexico Gin Market Outlook (2026 to 2036)
Sales of gin in Mexico are expected to climb at a 5.8% CAGR over the 2026 to 2036 forecast window across luxury coastal resort hospitality corridors and upscale urban cocktail lounges in Mexico City and Monterrey. While domestic spirits consumption has historically centered on agave distillates, younger Mexican legal-age consumers are adopting refreshing botanical gin-and-tonic serves during warm-weather social occasions. Exporter guide documentation released by U.S. agricultural attachés in Mexico City in July 2026 confirmed strong expansion across Mexico's modern supermarket and hotel-restaurant beverage supply chains. Ad valorem IEPS alcohol tax brackets on higher-ABV spirits remain a pricing constraint that encourages domestic bottling and premixed highball formats.
Key takeaway: In Mexico, resort hospitality cocktail programs and modern urban liquor retail are expected to support a 5.8% CAGR through 2036.
Canada Gin Market Outlook (2026 to 2036)
Projected to expand at a 5.7% CAGR between 2026 and 2036, the Canadian gin market is anchored by provincial liquor board craft spirit showcases and boreal-foraged botanical micro-distilleries across Quebec and Ontario. Canadian distribution flows through provincial crown corporations that actively promote locally distilled juniper and spruce-tip gins on dedicated retail displays. Official records released by Statistics Canada in March 2026 documented that total Canadian spirits volume stood at 177 million liters in fiscal 2024/2025, with spirits capturing 44.1% of alcohol sales in the Northwest Territories and 30.8% in British Columbia. Interprovincial shipping markups still challenge small Canadian craft distillers seeking national scale.
Key takeaway: In Canada, provincial liquor board craft promotion and boreal botanical micro-distilling are projected to sustain a 5.7% CAGR.
France Gin Market Outlook (2026 to 2036)
Procurement of gin in France is forecast to progress at a 5.2% CAGR during the 2026 to 2036 decade as Parisian cocktail bars and national hypermarket chains expand listings for domestic grape-base and Charentais pot-still artisanal gins. What sets France apart from standard grain-neutral gin markets is the utilization of Cognac wine-spirit copper alembics and regional botanicals from Provence and Corsica. Corporate regulatory filings submitted by Paris-headquartered Pernod Ricard SA in September 2026 detailed continued portfolio investment across super-premium gin and aperitif brands in European retail and hospitality channels. Strict national restrictions on alcohol advertising under France's Loi Evin require brands to rely on in-store tasting design and bartender advocacy.
Key takeaway: In France, Charentais copper-pot craft distillation and hypermarket premium spirits shelves are forecast to drive a 5.2% CAGR.
United Kingdom Gin Market Outlook (2026 to 2036)
Gin market demand in the United Kingdom is estimated to grow at a 5.1% CAGR across the 2026 to 2036 horizon, supported by the country's role as the world's largest exporter of benchmark London Dry and Scottish botanical gins. British domestic demand is shifting away from novelty sweet pink gins toward classic dry juniper expressions and vacuum-distilled low-ABV variants. Retail market analysis published by the USDA Foreign Agricultural Service in October 2026 documented that private-label products reached 52.2% of United Kingdom grocery spending in early 2026 while opportunities remained strong for differentiated premium and low-alcohol beverages. British distillers consequently focus on export market diversification and Small Producer Relief innovations to protect distillery utilization.
Key takeaway: In the United Kingdom, global London Dry export leadership and classic botanical trade-up are estimated to maintain a 5.1% CAGR.
Spain Gin Market Outlook (2026 to 2036)
In Spain, gin consumption is predicted to advance at a 4.9% CAGR between 2026 and 2036, sustained by deeply entrenched afternoon and evening Gin-Tonic terrace hospitality traditions across Madrid and Barcelona. Spanish hospitality operators differentiate their serves through large copa balloon glassware garnished with local Mediterranean lemon peel, rosemary, and cardamom pods. Market assessment data from the Madrid agricultural attaché office in July 2025 emphasized how Spain's active hotel, restaurant, and cafe sector drives high per-capita premium beverage demand with international tourism arrivals. Seasonal fluctuations in coastal tourist traffic during winter months encourage Spanish distillers to expand off-trade supermarket multipacks.
Key takeaway: In Spain, copa-glass terrace hospitality culture and Mediterranean citrus gin infusions are predicted to support a 4.9% CAGR.
Germany Gin Market Outlook (2026 to 2036)
German gin market valuation is slated to expand at a 4.8% CAGR through 2036 across specialty beverage stores and urban craft cocktail bars in Berlin, Munich, and Hamburg. Germany diverges from mass-market spirits hubs through its strong heritage of Black Forest herbal maceration, apothecary botanical recipes, and over 1,000 licensed small-scale fruit and grain distilleries. German retail sector analysis published by USDA GAIN in July 2026 confirmed that Germany's consolidated food and beverage chains demand strict sustainability credentials and recyclable glass packaging from spirit suppliers. German craft distillers compete against discounter private-label gins by emphasizing organic botanical certification and gift-ready apothecary packaging.
Key takeaway: In Germany, Black Forest botanical distilling heritage and specialty off-trade retail are slated to underpin a 4.8% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the gin market?
Diageo plc, Pernod Ricard SA, Bacardi Limited, Suntory Holdings Limited, William Grant & Sons Ltd., The Kyoto Distillery, Remy Cointreau, Campari Group, Ginebra San Miguel Inc., and Brown-Forman Corporation are the notable companies in the gin market.
Global gin competition spans multinational spirits groups, craft botanical distillers, and regional volume producers, led by Diageo plc, Pernod Ricard SA, Bacardi Limited, Suntory Holdings Limited, William Grant & Sons Ltd., The Kyoto Distillery, Remy Cointreau, Campari Group, Ginebra San Miguel Inc., and Brown-Forman Corporation.
- Global Multinational Gin Portfolio Leaders: Diageo plc, Pernod Ricard SA, Bacardi Limited, and Suntory Holdings Limited operate multi-continent distillation, bottling, and travel-retail distribution networks.
- Super-Premium and Craft Botanical Specialists: William Grant & Sons Ltd., The Kyoto Distillery, Remy Cointreau, and Campari Group engineer vapor-infused, pot-distilled, and multi-macerated artisanal gins.
- Regional Volume and Bartender-Focused Producers: Ginebra San Miguel Inc. and Brown-Forman Corporation supply high-velocity Asian gin volumes and bartender-calibrated Mediterranean and London Dry cocktail gins.
Competitive Benchmarking: Gin Market
Table 8: Competitive Benchmarking for the Gin Market (qualitative capability ratings), 2026
| Company | Botanical Distillation Depth | On-Trade Mixology Reach | Low-ABV & RTD Format Fit | Geographic Reach |
|---|---|---|---|---|
| Diageo plc | High | High | High | 180+ countries; Tanqueray, Gordon's, and Aviation Gin global network |
| Pernod Ricard SA | High | High | High | Global spirits network; Beefeater, Monkey 47, Plymouth, and Ki No Bi |
| Bacardi Limited | High | High | High | 160+ markets; vapor-infused Bombay Sapphire at Laverstoke Mill UK |
| Suntory Holdings Limited | High | High | High | Japan, North America, and Europe; Roku Japanese Craft Gin and SUI |
| William Grant & Sons Ltd. | High | High | Medium | Global luxury on-trade and duty-free; Hendrick's Gin Girvan Palace |
| The Kyoto Distillery | High | Medium | Medium | Japan and global luxury export hubs; six-element Ki No Bi dry gin |
| Remy Cointreau | High | High | Medium | Global prestige bars and retail; The Botanist 22-foraged Islay gin |
| Campari Group | Medium | High | High | Europe and Americas aperitif networks; Bulldog and Bickens London Dry |
| Ginebra San Miguel Inc. | Medium | Medium | High | Philippines and Asia-Pacific high-volume domestic and export gin |
| Brown-Forman Corporation | High | High | Medium | North America and Europe bartender networks; Fords Gin and Gin Mare |
Evaluation basis: Botanical Distillation Depth evaluates copper-pot and vapor-infusion capabilities, while On-Trade Mixology Reach rates global bartender advocacy and menu presence. Low-ABV & RTD Format Fit measures documented execution in zero-proof 0.0% distillates and ready-to-drink gin highball cans or bottles.
Key Developments in the Gin Market
- Diageo plc issued its Fiscal 27 Q1 trading statement on November 5, 2026, reporting Q1 net sales of USD 4,931 million with 1.4% organic sales growth while advancing USD 850 million in operating framework cost savings and global World Class bartender programs.
- Pernod Ricard SA announced the successful completion of its bond tender offer on October 28, 2026 to optimize its debt maturity profile following the September 2026 filing of its 2025/26 Universal Registration Document.
- Diageo plc released its 2026 Preliminary Results on August 6, 2026 for the fiscal year ended June 30, 2026, reporting USD 19.6 billion in net sales and 2.0% organic operating profit growth with operating margin expanding 116 basis points.
Key Players in the Gin Market
Global Multinational Gin Portfolio Leaders
- Diageo plc
- Pernod Ricard SA
- Bacardi Limited
- Suntory Holdings Limited
Super-Premium and Craft Botanical Specialists
- William Grant & Sons Ltd.
- The Kyoto Distillery
- Remy Cointreau
- Campari Group
Regional Volume and Bartender-Focused Producers
- Ginebra San Miguel Inc.
- Brown-Forman Corporation
Gin Market - Report Scope
Table 9: Report Scope for the Gin Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Price Tier; Distribution Channel; Packaging Format; ABV Strength |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial distiller and brand-owner revenue from juniper-predominant distilled spirits (London Dry Gin, Plymouth Gin, Old Tom Gin, Genever, and flavored or botanical-infused gin) across all price tiers and retail or hospitality channels. Category Scope Note: Excludes unflavored neutral vodka, agave tequila, oak-aged whiskies, and standalone non-alcoholic tonic water mixers. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | United States, Japan, Mexico, Canada, France, United Kingdom, Spain, Germany, and additional countries in the full report |
| Key Companies Covered | Diageo plc, Pernod Ricard SA, Bacardi Limited, Suntory Holdings Limited, William Grant & Sons Ltd., The Kyoto Distillery, Remy Cointreau, Campari Group, Ginebra San Miguel Inc., Brown-Forman Corporation |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Gin Market - Research Methodology
Table 10: Research Methodology for the Gin Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with master botanical distillers, on-trade hospitality beverage directors, supermarket spirits category buyers, and customs excise compliance managers to validate case realizations and pouring shares. |
| Secondary Research | Analysis of DISCUS American Spirits Export reports, USITC spirits import briefings, USDA FAS GAIN country reports, HM Revenue & Customs alcohol duty dossiers, Statistics Canada liquor control records, and corporate annual filings. |
| Market Sizing and Forecasting | Top-down global distilled spirits baselines reconciled against bottom-up 9-liter case shipments (103.0M to 109.5M cases in 2026) and wholesale price-tier realizations from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight legal-drinking-age demographics, hospitality cocktail bar density, supermarket off-trade licensing laws, and national alcohol excise tax structures across eight key economies. |
| Operational Benchmark Traceability | Case volume, botanical tonnage, and inventory indicators in Tables 2, 3, and 4 trace to DISCUS export series, USITC inventory audits, Statistics Canada volume tables, and spiritsEUROPE trade reviews. |
| Data Triangulation and Validation | Valuation estimates isolate juniper-distilled spirit revenues across straight bottles and brand-owned botanical variants while excluding third-party tonic mixers and non-juniper white spirits. |
Gin Market by Segments
Gin Market segmented by Product Type:
- London Dry Gin
- Plymouth Gin
- Old Tom Gin
- Flavored and Botanical Infused Gin
Gin Market segmented by Price Tier:
- Premium Gin
- Super-Premium and Ultra-Premium Gin
- Standard Mass-Market Gin
- Value and Economy Well Gin
Gin Market segmented by Distribution Channel:
- Off-Trade Supermarkets and Specialty Liquor Stores
- On-Trade Cocktail Bars and Fine Dining
- Hotel and Resort Hospitality Venues
- Direct-to-Consumer and Online Retail
- Travel Retail and Duty-Free Channels
Gin Market segmented by Packaging Format:
- Glass Bottles
- Aluminum Beverage Cans
- Ceramic and Specialty Decanters
- Bulk Hospitality Dispensing Formats
Gin Market segmented by ABV Strength:
- Standard 37.5% to 43.0% ABV
- Navy Strength and Overproof Above 45.0% ABV
- Low-ABV Botanical Aperitifs
- Zero-Proof Distilled Botanical Alternates
Gin Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- American Chemical Society. (2026, August 12). Allosteric Modulation of the CB1 Receptor by a Juniper Berry Seasoning Extract: Deoxypodophyllotoxin as the Major Active Constituent. Journal of Agricultural and Food Chemistry, 74(33), 26221.
- Bacardi Limited. (2025, November 17). Connections, Local Flavors, And Luxurious Experiences Top The 2026 Bacardi Cocktail Trends Report. Bacardi Limited News Archive.
- Brown-Forman Corporation. (2025, December 4). Brown-Forman Reports First Half Fiscal 2026 Results; Reaffirms Full Year Outlook. Brown-Forman Investor Relations.
- Diageo plc. (2025, August 14). Annual Report 2025. Diageo Investor Relations.
- Diageo plc. (2026, August 6). 2026 Preliminary Results, year ended 30 June 2026. Diageo Corporate Press Releases.
- Diageo plc. (2026, November 5). Diageo issues Fiscal 27 Q1 Trading Statement. Diageo Press Releases.
- Distilled Spirits Council of the United States. (2026, February 5). Annual Economic Briefing: U.S. Spirits Sales, Market Share, and Premium Gin Category Growth. DISCUS Industry Research.
- Distilled Spirits Council of the United States. (2026, March 12). 2025 DISCUS American Spirits Exports Report. DISCUS Economic Reports.
- Dunrobin Highland Distillery. (2024, May 15). The Story Behind Dunrobin Highland Distillery | Dunrobin Gin. Dunrobin Highland Distillery.
- European Food Safety Authority. (2025, October 18). Scientific Committee ongoing work-programme 2025-2027 for cross-cutting guidance. EFSA Technical Publications.
- HM Revenue & Customs and HM Treasury. (2026, October 29). Alcohol Duty uprating and Small Producer Relief changes. GOV.UK Policy Papers.
- Pernod Ricard SA. (2026, September 16). Filing of Pernod Ricard's 2025/26 Universal Registration Document. Pernod Ricard Regulatory Releases.
- Pernod Ricard SA. (2026, October 28). Successful tender offer for Pernod Ricard's notes. Pernod Ricard Media Room.
- Remy Cointreau Group. (2026, June 4). 2025-26 Full-year results. Remy Cointreau Financial Releases.
- spiritsEUROPE. (2026, March 22). A Spirit of Determination. spiritsEUROPE EU Trade Review 2026.
- Statistics Canada. (2026, March 5). Control and sale of alcoholic beverages and cannabis, April 1, 2024 to March 31, 2025. The Daily, Statistics Canada.
- Suntory Holdings Limited. (2025, November 14). Suntory's Osaka Spirits & Liqueurs Craft Distillery Awarded 2025 Liqueur Producer Trophy at the International Wine & Spirit Competition. Suntory Holdings News Releases.
- U.S. International Trade Commission. (2026, February 18). More for Less: U.S. Spirits Imports in 2025. USITC Executive Briefings on Trade.
- USDA Foreign Agricultural Service. (2025, July 16). Spain: Exporter Guide Annual. USDA GAIN Report SP2025-0017.
- USDA Foreign Agricultural Service. (2026, April 1). Japan: Food Processing Ingredients Annual. USDA GAIN Report JA2026-0012.
- USDA Foreign Agricultural Service. (2026, July 1). Germany: Exporter Guide Annual. USDA GAIN Report GM2026-0012.
- USDA Foreign Agricultural Service. (2026, July 7). Mexico: Exporter Guide Annual. USDA GAIN Report MX2026.
- USDA Foreign Agricultural Service. (2026, September 30). Bulgaria: Distilled Spirits Market Brief Bulgaria. USDA Foreign Agricultural Service GAIN Report.
- USDA Foreign Agricultural Service. (2026, October 1). United Kingdom: Retail Foods Annual. USDA GAIN Report UK2026.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the gin market in 2026 and what is forecast for 2036?
- Which hospitality mixology and off-trade retail shifts support demand for gin?
- Why does London Dry Gin lead the product type category?
- Why does Premium Gin lead the price tier category globally?
- How do growth rates differ across the United States, Japan, and Mexico?
- Which leading companies supply global London Dry labels versus regional craft botanical gins?
- What excise tax and juniper harvest pressures affect operating margins in the gin market?
- What should beverage buyers evaluate when selecting botanical gin and zero-proof extensions?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- London Dry Gin
- Plymouth Gin
- Old Tom Gin
- Flavored and Botanical Infused Gin
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Price Tier, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Price Tier, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Price Tier, 2026 to 2036
- Premium Gin
- Super-Premium and Ultra-Premium Gin
- Standard Mass-Market Gin
- Value and Economy Well Gin
- Y-o-Y Growth Trend Analysis By Price Tier, 2021 to 2025
- Absolute $ Opportunity Analysis By Price Tier, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Off-Trade Supermarkets and Specialty Liquor Stores
- On-Trade Cocktail Bars and Fine Dining
- Hotel and Resort Hospitality Venues
- Direct-to-Consumer and Online Retail
- Travel Retail and Duty-Free Channels
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Glass Bottles
- Aluminum Beverage Cans
- Ceramic and Specialty Decanters
- Bulk Hospitality Dispensing Formats
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By ABV Strength, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By ABV Strength, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By ABV Strength, 2026 to 2036
- Standard 37.5% to 43.0% ABV
- Navy Strength and Overproof Above 45.0% ABV
- Low-ABV Botanical Aperitifs
- Zero-Proof Distilled Botanical Alternates
- Y-o-Y Growth Trend Analysis By ABV Strength, 2021 to 2025
- Absolute $ Opportunity Analysis By ABV Strength, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Price Tier
- By Distribution Channel
- By Packaging Format
- By ABV Strength
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Diageo plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Pernod Ricard SA
- Bacardi Limited
- Suntory Holdings Limited
- William Grant & Sons Ltd.
- The Kyoto Distillery
- Remy Cointreau
- Campari Group
- Ginebra San Miguel Inc.
- Brown-Forman Corporation
- Diageo plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by ABV Strength, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by ABV Strength, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by ABV Strength, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by ABV Strength, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by ABV Strength, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by ABV Strength, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by ABV Strength, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by ABV Strength, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Price Tier
- Figure 9: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Distribution Channel
- Figure 12: Global Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Packaging Format
- Figure 15: Global Market Value Share and BPS Analysis by ABV Strength, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by ABV Strength, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by ABV Strength
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Product Type
- Figure 32: North America Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Price Tier
- Figure 35: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Distribution Channel
- Figure 38: North America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Packaging Format
- Figure 41: North America Market Value Share and BPS Analysis by ABV Strength, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by ABV Strength, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by ABV Strength
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Product Type
- Figure 48: Latin America Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Price Tier
- Figure 51: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 54: Latin America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Packaging Format
- Figure 57: Latin America Market Value Share and BPS Analysis by ABV Strength, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by ABV Strength, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by ABV Strength
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Product Type
- Figure 64: Western Europe Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Price Tier
- Figure 67: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 70: Western Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Packaging Format
- Figure 73: Western Europe Market Value Share and BPS Analysis by ABV Strength, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by ABV Strength, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by ABV Strength
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Price Tier
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Packaging Format
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by ABV Strength, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by ABV Strength, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by ABV Strength
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Product Type
- Figure 96: East Asia Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Price Tier
- Figure 99: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 102: East Asia Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Packaging Format
- Figure 105: East Asia Market Value Share and BPS Analysis by ABV Strength, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by ABV Strength, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by ABV Strength
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Price Tier
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Packaging Format
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by ABV Strength, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by ABV Strength, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by ABV Strength
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Price Tier
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Packaging Format
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by ABV Strength, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by ABV Strength, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by ABV Strength
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the gin market in 2026, and what is forecast for 2036?
FMI valuation estimates place the gin market at USD 23.8 billion in 2025 and USD 25.1 billion in 2026. Overall valuation is forecast to hit USD 42.9 billion by 2036.
What is the CAGR for the gin market from 2026 to 2036?
The gin sector is projected to expand at a 5.5% CAGR over the 2026 to 2036 forecast window, generating USD 17.8 billion in incremental revenue across retail and hospitality channels.
Which product type segment leads the gin market?
London Dry Gin is projected to hold 42.5% of product type demand in 2026 since juniper-forward redistillation without added sugar remains the primary specification for classic cocktails.
Which price tier segment leads the gin market?
Premium Gin is anticipated to represent 46.0% of the price tier category in 2026 supported by copper-pot botanical distillation and broad supermarket and bar call-brand visibility.
Which country has a notable growth outlook during the assessment period?
The United States leads national expansion projections at a 6.2% CAGR through 2036, driven by club-store and supermarket spirits merchandising and domestic craft botanical distillation.
Who are the key players in the market?
Diageo plc, Pernod Ricard SA, Bacardi Limited, Suntory Holdings Limited, William Grant & Sons Ltd., The Kyoto Distillery, Remy Cointreau, Campari Group, Ginebra San Miguel Inc., and Brown-Forman Corporation lead commercial supply across London Dry and craft botanical gin tiers.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
