

- Market Size (2026)
- USD 27.3 Bn
- Forecast (2036)
- USD 62.4 Bn
- CAGR (2026 to 2036)
- 8.6%
How big is Non-Alcoholic Beer Market in 2026?
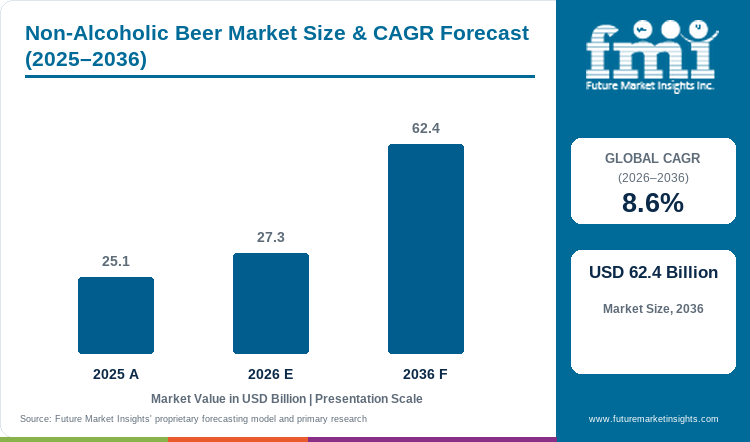
USD 27.3 Billion in 2026 and USD 62.4 Billion by 2036 at an 8.6% CAGR.
Sales of non-alcoholic beer are estimated to grow at an 8.6% CAGR from USD 27.3 Billion in 2026 to USD 62.4 Billion by 2036. The market was valued at USD 25.1 Billion in 2025. Growth is moving beyond temporary abstinence campaigns as consumers use alcohol-free beer for driving, weekday meals, sport, work-related events and mixed social occasions. The commercial test is repeat purchase: a product must preserve recognizable beer aroma, bitterness, body and carbonation while making the alcohol proposition immediately clear.
The growth mechanism differs by country. Mature beer market infrastructure gives non-alcoholic brands access to established breweries, retail shelves and hospitality accounts, but local demand still depends on style, price and occasion fit. Germany reported almost 579 million liters of non-alcoholic beer production in 2024 in a July 2025 Destatis release. These moves increase choice, which raises the importance of sensory quality and reliable availability.
Key Takeaways
- Moderation is widening the addressable occasion base because consumers can reduce alcohol exposure without leaving beer-led social settings.
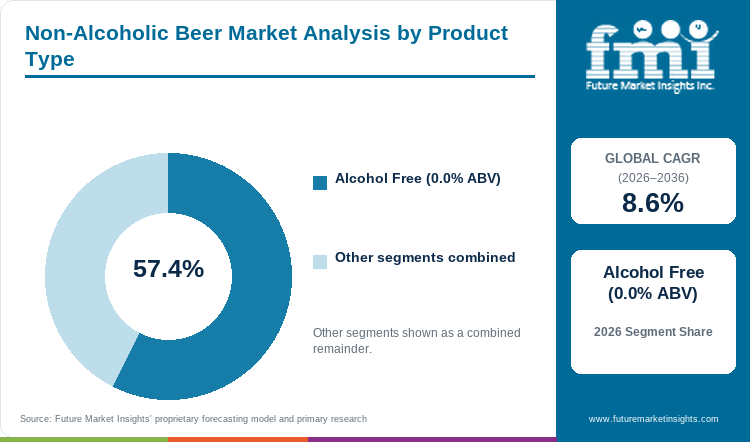
- Alcohol Free (0.0% ABV) leads Product Type with 57.4% of 2026 revenue, supported by a simple zero-alcohol proposition that is easy to communicate at shelf and in hospitality.
- Malted Grains hold 62.4% of Source revenue and Bottles hold 55.0% of Packaging revenue in 2026, reflecting continued preference for familiar brewing inputs and beer presentation.
- HoReCa leads Distribution Channel with 22.4% of 2026 revenue as draught and venue availability place alcohol-free beer in the same decision moment as standard beer.
- Sensory parity and clear alcohol-content claims remain the main qualification barriers, while the USA has the fastest profiled CAGR at 11.0% from 2026 to 2036.
- Key companies include Anheuser-Busch InBev, Heineken N.V., Carlsberg Group, Molson Coors Beverage Company, Boston Beer Company, Erdinger Weissbräu, Bitburger Braugruppe, Athletic Brewing Company, Suntory Holdings and Asahi Group Holdings.
Analyst Perspective
“Non-alcoholic beer earns repeat space when brewers make the alcohol-free choice feel like a normal beer purchase rather than a compromise. Taste, cold availability and pack recognition have to work together at the point of decision.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the non-alcoholic beer market segmented?
The Non-Alcoholic Beer Market is segmented by Product Type, Source, Packaging and Distribution Channel.
Product Type comprises Alcohol Free (0.0% ABV) and Low-Alcohol (Up to 1% ABV). Source includes Malted Grains, Berries/Apples, Grapes and Others. Packaging includes Bottles and Cans. Distribution Channel covers HoReCa, Travel Retail (Airplanes, Cruise Ships, Others), Hypermarkets/Supermarkets, Convenience Store, Online Retail, Airport Retail, Departmental Stores and Quick Service Restaurants (Sandwich Shops, Fast Casual, Coffee Shops).
Why does Alcohol Free (0.0% ABV) lead demand within the Product Type category?
Alcohol Free (0.0% ABV) gives retailers and venues a clear product promise for consumers who want beer taste without standard alcohol exposure. The segment also fits occasions where even a small amount of alcohol can be undesirable, including driving, sport and daytime social use. The challenge is to keep that certainty without flattening the beer experience. In March 2026, Heineken launched Heineken 0.0 Ultimate in the United States and Poland with zero alcohol, zero calories and zero sugar, showing how the category is adding functional cues while retaining a flagship beer identity.
- Alcohol Free (0.0% ABV) is projected to hold 57.4% of Product Type revenue in 2026, making it the leading product type.
- Zero-alcohol innovation is moving from one core lager into differentiated propositions built around calories, sugar, flavor and occasion, which broadens shelf architecture without changing the basic beer cue.
Why do Malted Grains lead demand within the Source category?
Malted Grains preserve the brewing foundation that consumers associate with beer. Malt contributes fermentable extract, body, color and flavor, so process changes used to restrict fermentation or remove alcohol must still protect the sensory cues created around that base. This matters across non-alcoholic malt beverages because buyers compare a beer-like product with established lager and ale expectations rather than with a generic soft drink. Suntory’s 2026 All-Free portfolio continues to use malt and hops to reinforce beer taste while maintaining 0.00% alcohol.
- Malted Grains lead Source with 62.4% of 2026 revenue because they support familiar beer aroma, body and bitterness across mainstream alcohol-free styles.
- Source differentiation grows when brewers move into fruit-led or hybrid propositions, but malt remains the reference base for products sold primarily on beer authenticity.
Why do Bottles lead demand within the Packaging category?
Bottles remain familiar to retail shoppers and hospitality operators because they fit established beer handling, single-serve presentation and premium merchandising. Glass also supports label-led differentiation and table service, while cans compete more strongly where portability, fast chilling and event consumption matter. The wider beer packaging landscape shows the same tension between established bottle cues and can-led convenience. Non-alcoholic suppliers therefore need pack choices that match the outlet rather than treating one format as universal.
- Bottles account for 55.0% of Packaging revenue in 2026, giving the format the leading position in the defined market.
- Pack competition is intensifying: Bitburger expanded its 0.0 portfolio in March 2026 and added sleek cans for selected fruit variants, illustrating how cans can open new occasions even while bottles retain the larger share.
Why does HoReCa lead demand within the Distribution Channel category?
HoReCa places non-alcoholic beer inside the same social decision as standard beer. Visibility on menus, in chillers or on draught reduces the need for consumers to leave the beer occasion when they choose not to drink alcohol. The channel also gives brewers a way to prove taste and serve quality before households buy the product for home use. In September 2025, Heineken reported Heineken 0.0 draught in 10,000 European outlets, with an average of 14 new taps installed per day during 2025 across key markets.
- HoReCa leads Distribution Channel with 22.4% of 2026 revenue because bars, restaurants and hospitality venues support trial within normal beer occasions.
- Draught availability can improve category visibility, but the brewer still needs account service, cold quality and sufficient throughput to keep the product fresh and commercially attractive.
What are the drivers, restraints and opportunities in the Non-Alcoholic Beer Market?
Moderation and broader social use support demand, while sensory parity and descriptor clarity constrain repeat purchase, and draught, flavor and functional innovation expand the addressable occasion base.
- Driver: Consumers increasingly use non-alcoholic beer for moderation rather than abstinence only, creating repeat occasions across meals, sports, driving and social events.
- Restraint: Brewers must reproduce beer-like aroma, body and finish while keeping alcohol-content claims accurate across markets and formats.
- Opportunity: Draught expansion, style diversification and zero-calorie or zero-sugar propositions can make non-alcoholic beer relevant to more accounts and dayparts.
Moderation turns alcohol-free beer into a substitution purchase rather than an abstinence-only product
Demand grows when the consumer still wants the ritual, taste and social signal of beer but chooses less or no alcohol for that occasion. Molson Coors said in January 2025 that Blue Moon Non-Alcoholic and Peroni 0.0 were expanding its U.S. non-alcoholic beer offer, while Carlsberg reported 11% organic volume growth in alcohol-free brews for the first half of 2026. This behavior also overlaps with the wider low-alcohol beverages market, where consumers are building more flexible drinking patterns rather than making one permanent category switch.
Taste parity and alcohol-content communication determine whether trial becomes repeat purchase
The technical burden is concentrated in flavor. Removing or preventing alcohol formation can change aroma lift, body, sweetness and finish, while very low alcohol thresholds leave little room for process variation. Athletic Brewing’s 2026 category education highlights the same commercial reality: consumers compare non-alcoholic beer against full-strength styles and expect recognizable beer character. A product that wins a moderation trial but tastes noticeably weaker can lose the next purchase even when its health or lifestyle proposition is strong.
Draught, style and functional innovation can widen the category beyond take-home lager
The strongest opportunity is not one new flavor. It is broader occasion coverage. Heineken expanded 0.0 draught to 10,000 European outlets in 2025, Athletic Brewing announced a MetLife Stadium partnership in August 2026, and Asahi continued to build 0.00% beer-like propositions in Japan. These moves reflect the broader moderation and low/no-alcohol beverage trend, where venue access, functional cues and recognizable adult-beverage presentation help normalise the choice. Suppliers can gain when they add occasions without weakening the core beer identity.
Which country CAGRs are profiled in the Non-Alcoholic Beer Market?
| Country | CAGR |
|---|---|
| USA | 11.0% |
| Japan | 10.2% |
| Germany | 9.7% |
| UK | 9.0% |
| South Korea | 8.6% |
How do country-level CAGRs compare in the Non-Alcoholic Beer Market?
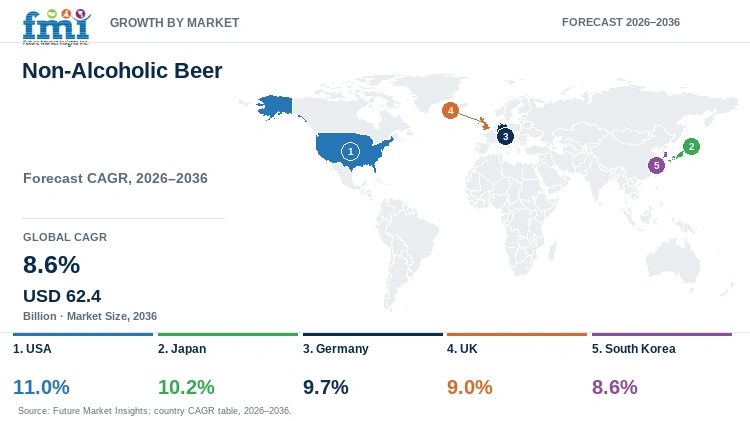
The five profiled country CAGRs span 2.4 percentage points. The USA leads the profile set at 11.0%, followed by Japan at 10.2% and Germany at 9.7%. The UK is forecast at 9.0%, while South Korea is profiled at 8.6%. The rates describe forecast growth speed from 2026 to 2036 and should not be read as a ranking of current country revenue.
- USA: Portfolio expansion by major brewers is widening access to 0.0 and craft-style non-alcoholic beer across retail and social occasions.
- Japan: Large beverage groups are treating 0.00% products as a dedicated portfolio rather than a single substitute SKU, increasing style and functional choice.
- Germany: A large established production base means competition is shifting toward beer style, flavor and pack differentiation rather than basic category introduction.
- UK: Zero duty on beer up to 1.2% ABV under the February 2026 Alcohol Duty rates supports a clear economic distinction for very low-alcohol products.
- South Korea: New 0.00% propositions are creating finer distinctions between non-alcoholic and alcohol-free products while extending convenience-channel choice.
The profile spread is relatively narrow, so execution matters as much as the headline CAGR. Brewers still need local pricing, route-to-market coverage and beer-like sensory performance before a fast-growing category converts into durable brand revenue.
Country-wise Analysis
- The USA is profiled at an 11.0% CAGR from 2026 to 2036. NIAAA reported in March 2026 that 47.5% of adults ages 18 to 25 drank alcohol in the past month during 2024, indicating that moderation products compete inside an active drinking culture rather than outside it. Heineken launched Heineken 0.0 Ultimate in the United States in March 2026, while Molson Coors continued to invest behind Blue Moon Non-Alcoholic and Peroni 0.0 through 2025. The commercial opening is therefore substitution within established beer occasions, provided taste and availability are strong enough for repeat purchase.
- Japan is forecast at a 10.2% CAGR. Suntory stated in August 2025 that it had created a dedicated Non-Alcoholic Department in Japan and was positioning non-alcoholic beverages as 0.00% adult-drinking propositions. In 2026 it refreshed the All-Free range and added further beer-taste variants. Asahi also expanded 0.00% beer-like products during 2026. The market rewards brewers that create distinct flavors and dayparts without losing the familiar beer cue.
- Germany is profiled at a 9.7% CAGR. Destatis reported in July 2025 that Germany produced almost 579 million liters of non-alcoholic beer in 2024. That scale makes the category familiar, so the next competitive step is differentiation. ERDINGER launched its first non-alcoholic Helles in 2025, and Bitburger widened its 0.0 range in March 2026. Buyers can therefore compare style, package and flavor within an already developed alcohol-free beer set.
- The UK carries a 9.0% CAGR from 2026 to 2036. HM Revenue & Customs updated Alcohol Duty rates in February 2026 with a zero duty rate for beer from 0 to 1.2% ABV. Heineken also included the UK in its 2025 0.0 draught expansion. The opportunity is strongest when compliant low- or no-alcohol products are easy to order in the same venues as standard beer, rather than requiring a separate consumption occasion.
- South Korea is profiled at an 8.6% CAGR. Oriental Brewery’s February 2026 company FAQ lists Cass 0.0, Cass Lemon Squeeze 0.0, Hoegaarden 0.0 and Cass All Zero, while the 2025 Budweiser APAC annual report described Cass All Zero as a four-zero proposition covering alcohol, sugar, calories and gluten. The market is moving toward sharper functional and alcohol-content distinctions, which raises the importance of accurate formulation and packaging communication.
Who are the notable companies in the Non-Alcoholic Beer Market?
Anheuser-Busch InBev, Heineken N.V., Carlsberg Group, Molson Coors Beverage Company, Boston Beer Company, Erdinger Weissbräu, Bitburger Braugruppe, Athletic Brewing Company, Suntory Holdings and Asahi Group Holdings are the notable companies profiled in this market.
Competition separates into scaled global brewers, dedicated non-alcoholic specialists and regional beer companies extending familiar styles into alcohol-free formats. Global brewers can use existing brands, brewery networks and distributor relationships to gain rapid shelf and venue coverage. Specialists such as Athletic Brewing Company compete through a broad non-alcoholic style range and focused brand identity. German and Japanese brewers add local style credibility, while diversified beverage groups use functional claims and broader drinking occasions to expand category reach.
- Global beer-franchise platforms: Anheuser-Busch InBev, Heineken N.V., Carlsberg Group, Molson Coors Beverage Company and Asahi Group Holdings.
- Specialist and regional beer propositions: Erdinger Weissbräu, Bitburger Braugruppe and Athletic Brewing Company.
- Diversified beverage and craft portfolios: Boston Beer Company and Suntory Holdings.
Competitive Benchmarking: Non-Alcoholic Beer Market
| Company | Documented 0.0 / NA Beer Breadth | Dedicated Process or Capacity | On-Premise / Occasion Activation | Geographic Reach |
|---|---|---|---|---|
| Anheuser-Busch InBev | High | Medium | High | Global; 2025 portfolio activity includes Corona Cero expansion and Cass All Zero in South Korea |
| Heineken N.V. | High | High | High | Global; Heineken 0.0 is sold across a wide international footprint |
| Carlsberg Group | Medium | Medium | Medium | Multi-region group with alcohol-free brews reported as a growth category in 2026 |
| Molson Coors Beverage Company | High | Medium | High | North America and Europe with Blue Moon Non-Alcoholic, Peroni 0.0 and other low/no-alcohol brands |
| Boston Beer Company | Medium | Medium | High | United States with Samuel Adams Just the Haze and sports-venue activation |
| Erdinger Weissbräu | High | High | High | Germany with international export activity and dedicated alcohol-free positioning |
| Bitburger Braugruppe | High | Medium | Medium | Germany with broad export activity and an expanded 0.0 portfolio |
| Athletic Brewing Company | High | High | High | United States with selected international distribution and dedicated non-alcoholic production |
| Suntory Holdings | High | High | Medium | Japan with All-Free and broader international non-alcoholic beverage activity |
| Asahi Group Holdings | High | High | High | Japan and Europe with Asahi Zero, Dry Zero, Super Dry 0.0 and Peroni 0.0 |
Scoring basis: Documented 0.0 / NA Beer Breadth reflects the number and variety of beer-specific non-alcoholic propositions. Dedicated Process or Capacity reflects specialist brewing, alcohol-removal or production infrastructure. On-Premise / Occasion Activation reflects draught, venue, sport or event activity tied to the category. High indicates broad documented capability, Medium indicates narrower documented capability, Low indicates a documented limitation, and Unscored means no rating is assigned for that criterion.
Key Developments in the Non-Alcoholic Beer Market
- In March 2026, Heineken N.V. launched Heineken 0.0 Ultimate in the United States and Poland. The product combines zero alcohol with zero calories and zero sugar while retaining a beer-led proposition. The launch expands the category beyond alcohol avoidance by adding functional cues for consumers who want a familiar beer brand in active and daytime occasions.
- In August 2026, Carlsberg Group reported 11% organic volume growth for alcohol-free brews in the first half of 2026. The result places alcohol-free beer among the group’s defined growth categories and shows that large brewers are managing it as a portfolio growth engine rather than a peripheral line extension.
- In March 2026, Bitburger Braugruppe expanded its alcohol-free portfolio with four new products, refreshed 0.0 packaging and sleek-can formats for selected fruit variants. The move widens style and packaging choice inside a mature German alcohol-free beer market and gives retailers more ways to merchandise the category by flavor and occasion.
Key Players in the Non-Alcoholic Beer Market
Global Brewers Extending Core Beer Franchises
- Anheuser-Busch InBev
- Heineken N.V.
- Carlsberg Group
- Molson Coors Beverage Company
- Asahi Group Holdings
Specialist and Regional Beer Producers
- Erdinger Weissbräu
- Bitburger Braugruppe
- Athletic Brewing Company
Diversified Beverage and Craft Portfolios
- Boston Beer Company
- Suntory Holdings
Non-Alcoholic Beer Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Source; Packaging; Distribution Channel |
| Quantitative Units | USD Billion |
| Market Definition | Revenue from beer-style beverages sold as non-alcoholic, alcohol-free or low-alcohol beer within the stated Product Type, Source, Packaging and Distribution Channel categories. Standard alcoholic beer and adjacent non-beer substitutes are excluded. Ingredients, brewing equipment and venue food-service revenue are outside the market boundary. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, Japan, Germany, UK, South Korea |
| Key Companies Profiled | Anheuser-Busch InBev; Heineken N.V.; Carlsberg Group; Molson Coors Beverage Company; Boston Beer Company; Erdinger Weissbräu; Bitburger Braugruppe; Athletic Brewing Company; Suntory Holdings; Asahi Group Holdings |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Non-Alcoholic Beer Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gather input from manufacturers, distributors, retailers, hospitality operators, procurement teams and subject-matter experts. Interviews examine purchasing decisions, product evaluation, adoption barriers, pricing, route-to-market requirements and expectations for sensory and commercial support. |
| Desk Research | Desk research covers government statistics, regulatory publications, trade data, industry associations, technical literature, company filings, product information and official corporate announcements relevant to the defined market. |
| Market Sizing and Forecasting | The market model combines the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation and country-level demand conditions. Forecast assumptions consider economic activity, channel development, product innovation and barriers to wider market use. |
| Data Validation | Estimates are checked against independent public indicators, company activity, trade patterns and primary research. Segment and regional estimates are reconciled before the final market total is completed. |
Non-Alcoholic Beer Market by Segments
Non-Alcoholic Beer Market segmented by Product Type:
- Alcohol Free (0.0% ABV)
- Low-Alcohol (Up to 1% ABV)
Non-Alcoholic Beer Market segmented by Source:
- Malted Grains
- Berries/Apples
- Grapes
- Others
Non-Alcoholic Beer Market segmented by Packaging:
- Bottles
- Cans
Non-Alcoholic Beer Market segmented by Distribution Channel:
- HoReCa
- Travel Retail (Airplanes, Cruise Ships, Others)
- Hypermarkets/Supermarkets
- Convenience Store
- Online Retail
- Airport Retail
- Departmental Stores
- Quick Service Restaurants (Sandwich Shops, Fast Casual, Coffee Shops)
Non-Alcoholic Beer Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- Statistisches Bundesamt. (2025, July 29). Produktion von alkoholfreiem Bier mit +96,1 % in den vergangenen zehn Jahren fast verdoppelt.
- National Institute on Alcohol Abuse and Alcoholism. (2026, March). Alcohol and Young Adults Ages 18 to 25.
- HM Revenue & Customs. (2026, February 1). Alcohol Duty rates.
- The HEINEKEN Company. (2025, September 10). HEINEKEN Expands 0.0 Draught to 10,000 Outlets Across Europe.
- The HEINEKEN Company. (2026, March 12). Heineken 0.0 unveils first zero alcohol, zero calorie, and zero sugar brew.
- Carlsberg Group. (2026, August 19). H1 2026 Financial Statement.
- Bitburger Braugruppe. (2026, March 9). Bitburger baut alkoholfreies Portfolio aus.
- Molson Coors Beverage Company. (2025, January 9). From beer to energy: checking in on Molson Coors’ non-alc portfolio.
- Molson Coors Beverage Company. (2025, May 28). From Beer to Non-Alc: How Molson Coors is preparing its above premium portfolio for summer.
- Boston Beer Company. (2025, July 11). Samuel Adams and Boston Red Sox Toast to Ten More Years of Partnership.
- ERDINGER Weissbräu. (2025). ERDINGER Brauhaus Helles Alkoholfrei launch and brewery expansion materials.
- ERDINGER Weissbräu. (2025, May). ERDINGER Alkoholfrei in new 0.5-litre can.
- Athletic Brewing Company. (2026, March 24). Non-Alcoholic Beer 101.
- Athletic Brewing Company. (2026, August 13). MetLife Stadium partnership.
- Suntory Holdings. (2025, August 8). Financial commentary for the first half of 2025.
- Suntory Holdings. (2026, January 13). All-Free brand renewal and portfolio expansion.
- Oriental Brewery. (2026, February). Company and Brand FAQ: non-alcoholic and alcohol-free beverage portfolio.
- Budweiser Brewing Company APAC Limited. (2026). Annual Report 2025.
- Asahi Breweries. (2026, August 20). Asahi Zero surpasses 200 million cumulative units and receives a product and packaging renewal.
- Asahi Breweries. (2026, February 25). Asahi Zero Ale Taste limited release.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the Non-Alcoholic Beer Market in 2026 and what value is forecast for 2036?
- Which moderation and occasion shifts are supporting demand for non-alcoholic beer?
- Why does Alcohol Free (0.0% ABV) lead the Product Type category?
- Why do Malted Grains lead the Source category?
- Why do Bottles hold the leading Packaging share?
- How do country growth rates differ across the five profiled markets?
- Which companies compete through global beer franchises, specialist non-alcoholic brewing and regional beer propositions?
- What limits repeat purchase and supplier switching in the non-alcoholic beer market?
Frequently Asked Questions
How big is the Non-Alcoholic Beer Market in 2026, and what is forecast for 2036?
The market is valued at USD 27.3 Billion in 2026 and is forecast to reach USD 62.4 Billion by 2036. The market was valued at USD 25.1 Billion in 2025.
What is the CAGR for the Non-Alcoholic Beer Market from 2026 to 2036?
The market is forecast to grow at an 8.6% CAGR from 2026 to 2036 as alcohol-free beer gains wider retail, hospitality and social-occasion coverage.
Which Product Type segment leads the Non-Alcoholic Beer Market?
Alcohol Free (0.0% ABV) leads Product Type with a 57.4% share in 2026. The segment benefits from a clear zero-alcohol proposition that fits driving, sport and daytime occasions.
Which Source segment leads the Non-Alcoholic Beer Market?
Malted Grains lead Source with a 62.4% share in 2026 because malt remains central to reproducing familiar beer aroma, body and bitterness.
Which profiled countries record the highest growth rates?
The USA has the highest profiled CAGR at 11.0% from 2026 to 2036, followed by Japan at 10.2% and Germany at 9.7%. These rates describe growth pace, not current market size.
Which companies are active in the Non-Alcoholic Beer Market?
Profiled companies include Anheuser-Busch InBev, Heineken N.V., Carlsberg Group, Molson Coors Beverage Company, Boston Beer Company, Erdinger Weissbräu, Bitburger Braugruppe, Athletic Brewing Company, Suntory Holdings and Asahi Group Holdings.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Alcohol Free (0.0% ABV)
- Low-Alcohol (Up to 1% ABV)
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source, 2026 to 2036
- Malted Grains
- Berries/Apples
- Grapes
- Others
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging, 2026 to 2036
- Bottles
- Cans
- Y-o-Y Growth Trend Analysis By Packaging, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- HoReCa
- Travel Retail (Airplanes, Cruise Ships, Others)
- Hypermarkets/Supermarkets
- Convenience Store
- Online Retail
- Airport Retail
- Departmental Stores
- Quick Service Restaurants (Sandwich Shops, Fast Casual, Coffee Shops)
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Source
- By Packaging
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Anheuser-Busch InBev
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Heineken N.V.
- Carlsberg Group
- Molson Coors Beverage Company
- Boston Beer Company
- Erdinger Weissbräu
- Bitburger Braugruppe
- Athletic Brewing Company
- Suntory Holdings
- Asahi Group Holdings
- Anheuser-Busch InBev
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


