
- Market Size (2026)
- USD 32.6 Bn
- Forecast (2036)
- USD 51.1 Bn
- CAGR (2026 to 2036)
- 4.6%
How big is Oilfield Chemical Market in 2026?
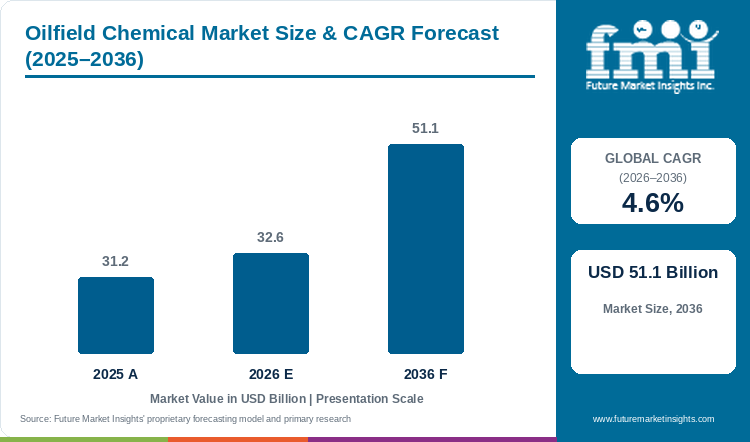
Oilfield chemical demand is on track for a 4.6% CAGR over 2026 to 2036. Industry value stands at USD 31.2 billion in 2025, moves to USD 32.6 billion in 2026, and is forecast to reach USD 51.1 billion by 2036.
The chemical consumption intensity per barrel analysis of the oilfield chemical market links chemical dosing to crude and gas output volumes, active well counts, drilling intensity and water-cut progression across operating basins. US crude oil production averaged a record 13.6 million barrels per day in 2025, up from the 2024 record of 13.2 million barrels per day, and the EIA projects output near 13.7 million barrels per day for 2026 . China's crude output reached 216.05 million metric tons in 2025, a 1.5% year-on-year increase, and natural gas output climbed 6.2% to 261.9 billion cubic meters.
Petrobras reported a record oil and gas production level in 2025 at about 2.99 million barrels of oil equivalent per day, with pre-salt fields supplying 82% of the total by the fourth quarter. Each barrel produced carries a chemical dosage across multiple treatment points, from drilling fluid additives through corrosion inhibitors in production tubing to demulsifiers at separation facilities. FMI's analysis indicates that the steady rise in global liquids output, combined with higher average water cuts in aging fields, underpins a growing chemical bill per unit of hydrocarbon delivered.
Adoption of oilfield production chemicals reflects this upstream activity. Baker Hughes reported OFSE sales of USD 3.2 billion in Q1 2026, with the segment down 7% year on year on asset dispositions. Halliburton’s Completion and Production division posted full-year 2025 revenue of USD 12.8 billion, a decline of approximately 4% from 2024. Flotek Industries raised 2026 revenue guidance to USD 360–370 million in September 2026, reflecting international chemistry revenue of approximately USD 10.6 million in the second quarter of 2026, a sequential increase of more than 450% from the first quarter, supported by activity in Saudi Arabia’s Jafurah basin. SLB completed the acquisition of ChampionX, a global provider of production chemistry and artificial lift, in July 2025, adding more than 7,000 employees to the combined chemical and digital production technology offering. Chemical suppliers with dosing expertise, field logistics and formulation breadth are expected to gain position as well complexity increases.
Key Market Trends & Insights
- Drilling and completion chemicals led application demand with 28% share in 2026, as lateral lengths in US shale basins and deepwater wells off Brazil and West Africa maintain high fluid volumes per well. Sales of drilling and completion chemicals track rig activity, and the US rig count stood at 543 in the week ending 17 April 2026, about 7% below the year-earlier level.
- By terrain type, onshore operations held an estimated 65% in 2026, according to FMI. Demand for oilfield chemicals in onshore basins follows shale drilling and EOR programmes, and China's onshore fields in Xinjiang and the Bohai Bay rim contribute to sustained inhibitor and polymer consumption.
- Inhibitors accounted for an estimated 30% of product-type demand in 2026. Key trends in oilfield chemical formulations include the shift from generic corrosion inhibitors toward application-specific blends and the growing use of oilfield stimulation chemicals such as friction reducers and breakers in unconventional wells.
Regional Highlights
- China posts the fastest profiled growth at 5.7% CAGR over 2026 to 2036.
- Brazil (5.1%) and the United States (4.8%) rank next, and New Zealand records the lowest profiled rate at 3.1%.
- US crude oil production reached a record 13.6 million barrels per day in 2025, reinforcing chemical dosage volumes across Permian, Eagle Ford and Bakken operations.
Market Size & Forecast
Table 1: Market Size and Forecast for the Oilfield Chemical Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 31.2 billion |
| Estimated Market Size in 2026 | USD 32.6 billion |
| Projected Market Size by 2036 | USD 51.1 billion |
| CAGR, 2026 to 2036 | 4.6% |
| Added Market Value, 2026 to 2036 | USD 18.5 billion |
| Market Expansion Multiple | 1.6x |
Chemical consumption intensity per barrel stands at the centre of this market's demand arithmetic. US output of 13.6 million barrels per day in 2025 consumed drilling fluids, completion brines, stimulation acids and production-phase inhibitors at each stage of the well life cycle. Nouryon opened an Innovation Center for oilfield applications in Houston in mid-2025, the company's first such facility, to develop more sustainable drilling, completion and stimulation processes, with labs covering demulsification, corrosion and scale inhibition.
Syensqo completed the sale of its Oil & Gas Business Unit, a global player in oilfield stimulation chemicals with approximately EUR 400 million in 2024 net sales, to SNF Group in January 2026 for an enterprise value of EUR 135 million. However, volatile crude prices create hesitancy in upstream capital budgets and compress chemical procurement cycles. FMI expects that the chemical intensity per barrel will rise through 2036 as wells grow longer, water cuts increase and environmental standards tighten formulation requirements, supporting the enhanced oil recovery segment in particular.
Chemical Consumption Intensity per Barrel Evidence
Under the chemical consumption intensity per barrel analysis, chemical dosage rates per barrel, drilling activity indicators and water-treatment chemical demand are assembled below.
Table 2: Chemical Consumption Intensity per Barrel Indicators for the Oilfield Chemical Market (mixed units), mixed reporting years from 2025 to 2026
| Indicator | Data Point | Significance | Source |
|---|---|---|---|
| US crude oil production, 2025 | 13.6 million barrels per day (record) | Sets the barrel base over which drilling and production chemicals are consumed | |
| China crude output, 2025 | 216.05 million metric tons, up 1.5% | Sustains onshore inhibitor and polymer volumes in the second-largest producing country | |
| Petrobras output, 2025 | 2.99 million boe/d; pre-salt 82% of Q4 total | Deepwater pre-salt wells require high-performance flow-assurance and scale-inhibition chemistries | |
| US rig count, week ending 17 April 2026 | 543 rigs (410 oil, 125 gas), down 7% year on year | Drilling activity directly scales drilling-fluid and cementing-chemical consumption | - |
| Baker Hughes OFSE sales, Q1 2026 | USD 3.2 billion, down 7% year on year | Reflects oilfield services and chemical demand trends among the largest suppliers | - |
| Flotek international chemistry sales, Q2 2026 | USD 10.6 million, up more than 450% from Q1 | Signals growing chemical dosing activity in Middle Eastern fields | - |
Analyst Perspective
"Chemical spend per barrel climbs as operators drill longer laterals, manage higher water cuts and meet stricter discharge limits. Suppliers that combine formulation science with digital dosing and field logistics will capture more of the treatment chain."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the Oilfield Chemical Market segmented?
Oilfield chemical market is segmented by three primary commercial axes and region: application, terrain type, product type, and region. In 2026, drilling and completion chemicals are projected at 28%, onshore at an estimated 65%, and inhibitors at an estimated 30%.
By application: drilling and completion chemicals, cementing chemicals, stimulation chemicals, oil production chemicals, and enhanced oil recovery (EOR) chemicals.
By terrain type: onshore and offshore.
By product type: inhibitors (scale, corrosion, paraffin), lubricants, de-emulsifiers, viscosifiers, gas well foamers, biocides, H₂S scavengers, and others.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do drilling and completion chemicals retain a notable application share?
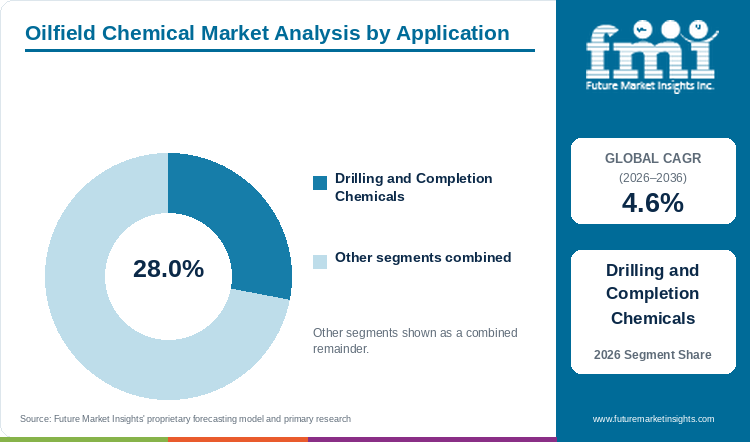
Drilling and completion chemicals hold 28% of application demand in 2026, as every well drilled and completed requires fluid systems, cement additives and completion brines.
Table 3: Application Share for the Oilfield Chemical Market (percentage share), 2026
| Application | Share (2026) |
|---|---|
| Drilling and Completion Chemicals | 28% |
| Other Segments Combined | 72%* |
| Total | 100% |
*Represents the combined share of all other application segments besides drilling and completion chemicals.
Table 4: Application Leadership and Market Growth for the Oilfield Chemical Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.6% |
| Leading Segment | Drilling and Completion Chemicals |
Drilling and completion chemicals encompass drilling fluid additives, shale inhibitors, lubricants, completion brines and wellbore-cleanup agents. In the FMI report, drilling and completion chemicals account for 28% of application demand in 2026. The US rig count averaged 543 in mid-April 2026, with oil rigs at 410 and gas rigs at 125. Chevron Phillips Chemical supplies poly-alpha-olefin and linear-alpha-olefin based drilling specialties that serve as synthetic base fluids and lubricants in high-angle wells. Under the chemical consumption intensity per barrel analysis, each horizontal shale well consumes several hundred tons of fluid over the drilling and completion cycle, and this volume scales with lateral length. FMI's oilfield production chemicals analysis covers the production-phase segment separately.
- Drilling and completion chemicals take 28% of application share in 2026 because every new well requires a fluid system tailored to the formation.
- Deepwater wells offshore Brazil, West Africa and Southeast Asia carry heavier fluid bills per well than onshore horizontals, which sustains this segment's share even as the US rig count softens.
What positions onshore as the leading terrain type?
Onshore operations represent an estimated 65% of terrain-type demand in 2026, reflecting the dominance of shale basins, conventional onshore fields and onshore EOR programmes in global chemical consumption.
Shale drilling in the Permian Basin, Eagle Ford and Bakken underpins the onshore share in North America. China's onshore activity spans mature fields in the Daqing basin and newer plays in Xinjiang, and polymer flooding and chemical EOR are widely applied across these onshore plays. Under the chemical consumption intensity per barrel analysis, onshore wells tend to have shorter individual chemical bills than deepwater offshore wells but far outnumber them. The onshore rig count in the US alone stood at more than 400 active oil rigs in April 2026.
- Onshore operations account for an estimated 65% in 2026, led by North American shale and Chinese conventional and EOR fields.
- The lower per-well chemical cost onshore is offset by higher well counts, which keeps onshore volumes ahead of offshore.
How do inhibitors lead by product type?
Inhibitors are estimated at 30% of product-type demand in 2026, covering corrosion, scale and paraffin inhibitors used across drilling, production and transportation.
Corrosion inhibitors protect downhole tubing, flowlines and processing equipment from acidic fluids, CO₂ and H₂S. Scale inhibitors prevent mineral deposition in production systems, and paraffin inhibitors keep waxy crudes flowing. BASF markets a portfolio of oilfield inhibitors, including biodegradable surfactants and low-toxicity corrosion inhibitors designed for environmentally sensitive operations. Clariant, a Swiss specialty chemical producer, supplies scale and corrosion management chemistries through its Oil Services division to operators in the North Sea and Middle East. Under FMI's analysis, inhibitor consumption intensity per barrel rises as fields age and water cuts increase, because produced water carries dissolved minerals and corrosive gases that require higher dosing rates.
- Inhibitor demand per barrel increases over a field's life as water cut rises and fluid chemistry becomes more aggressive.
- Biodegradable inhibitor formulations are gaining share in the North Sea and other regulated offshore basins.
What are the drivers, restraints, and opportunities in the Oilfield Chemical Market?
Record crude output in the United States and sustained production growth in Brazil and China pull chemical volumes higher. Oil price volatility compresses upstream capital budgets and narrows procurement windows. Biodegradable and digitally optimised chemical systems open the main commercial opportunity for formulators.
- Driver: Record US crude production and deepwater expansion in Brazil and West Africa raise barrel-weighted chemical demand.
- Restraint: Crude oil price swings and OPEC+ supply management create uncertainty in upstream spending and chemical procurement.
- Opportunity: Biodegradable formulations and AI-driven dosing systems that lower chemical waste and operating cost.
Record output and deepwater expansion
Demand for oilfield chemicals follows barrel counts. US crude oil production hit 13.6 million barrels per day in 2025, a record, and the EIA forecasts 13.7 million barrels per day for 2026. Petrobras produced a record 2.99 million barrels of oil equivalent per day in 2025, with Búzios alone exceeding 1 million barrels per day in October 2025. Pre-salt wells operate at high pressures and temperatures, and each requires a suite of flow-assurance, hydrate-inhibition and scale-control chemicals formulated for those conditions. Chemical dosing intensity in FMI's analysis for pre-salt operations exceeds onshore conventional by a multiple of the treatment points involved. The broader enhanced oil recovery chemicals segment benefits as mature basins turn to polymer and surfactant flooding to arrest decline rates.
Price volatility and budget compression
Volatile crude prices have periodically curbed drilling and exploration budgets in North America and other regions through 2025 and into 2026. The Baker Hughes US rig count declined to 543 in mid-April 2026, about 7% below the prior year. Halliburton's Completion and Production division saw revenue fall to USD 12.8 billion in 2025 from USD 13.3 billion in 2024, a measure of the spending caution that flows through to chemical orders. Operators that cut well programmes defer fluid purchases, which concentrates chemical demand into shorter windows and pressures supplier margins.
Biodegradable formulations and digital dosing
Nouryon opened the company's Houston Innovation Center in mid-2025 to develop more sustainable drilling and stimulation chemistries, including lower-toxicity demulsifiers and corrosion inhibitors. BASF's oilfield line includes biodegradable surfactants and specialty polymers designed to meet offshore discharge standards. Digital dosing systems that adjust chemical injection rates in real time based on flow, water cut and corrosion-probe data reduce both chemical waste and intervention cost. FMI expects these technologies to be a competitive differentiator through 2036, especially in regions with strict environmental oversight such as the North Sea and Australian offshore.
Which country CAGRs are profiled in the Oilfield Chemical Market?
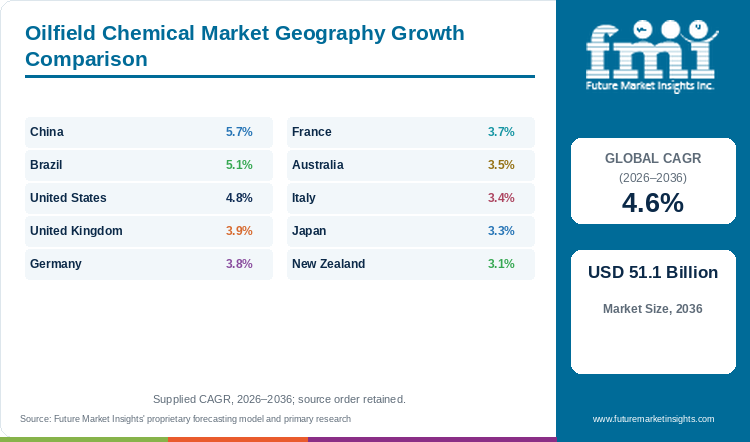
Table 5: Country CAGR Comparison for the Oilfield Chemical Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| China | 5.7% |
| Brazil | 5.1% |
| United States | 4.8% |
| United Kingdom | 3.9% |
| Germany | 3.8% |
| France | 3.7% |
| Australia | 3.5% |
| Italy | 3.4% |
| Japan | 3.3% |
| New Zealand | 3.1% |
How do country-level CAGRs compare in the oilfield chemical market?
Chemical consumption intensity per barrel analysis reveals that output volume, field maturity and offshore complexity shape the country-level growth spread. China and the United States rank at the top, with crude production records in 2025 translating directly into higher chemical dosage volumes. Brazil's chemical CAGR reflects record Petrobras deepwater pre-salt output and the high per-well chemical intensity of ultra-deepwater completions. European markets grow at moderate rates driven more by production-chemical demand from mature North Sea fields than by new drilling.
- China oilfield chemical demand follows from record crude output of 216.05 million metric tons and gas output of 261.9 billion cubic meters in 2025, both records, alongside large-scale polymer flooding in mature onshore fields.
- United States demand rests on 13.6 million barrels per day of crude production in 2025, the highest output of any country, with the Permian Basin and deepwater Gulf of Mexico as the primary chemical consumption centres.
- Brazil demand follows record Petrobras output of about 2.99 million barrels of oil equivalent per day in 2025, with pre-salt fields supplying 82% of fourth-quarter production and driving high-intensity flow-assurance and scale-inhibition chemical use.
- United Kingdom demand centres on North Sea mature-field maintenance; corrosion and scale inhibitors, demulsifiers and hydrate management chemicals dominate the chemical bill there.
- Germany serves as a formulation and export base for high-performance oilfield chemicals through BASF's oilfield chemicals business, reflecting export and R&D activity rather than measured domestic upstream chemical consumption.
- France contributes through specialty chemical R&D and export, including cementing additives and anti-scaling products, though domestic upstream activity is minimal.
- Australia draws chemical demand from offshore LNG projects in the Northwest Shelf and Browse Basin; drilling mud, cementing and stimulation chemicals are required there to meet remote operating and environmental compliance conditions.
- Italy supplies customised chemicals for Mediterranean offshore projects and North African exploration, benefiting from logistics proximity.
- Japan develops advanced materials for deepwater and unconventional applications, including paraffin inhibitors and hydrate suppressants, with digitally modelled dosing gaining adoption.
- New Zealand records the lowest profiled growth at 3.1%, with steady but limited demand concentrated on Taranaki Basin well maintenance and production optimisation.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Country-wise Analysis
- China's crude oil output reached 216.05 million metric tons in 2025, up 1.5%, and natural gas production rose 6.2% to 261.9 billion cubic meters, both records. This output growth puts the China oilfield chemical market on course for a 5.7% CAGR through 2036. Onshore EOR programmes in Daqing and Shengli, combined with offshore exploration in the South China Sea, sustain a broad chemical bill spanning polymers, surfactants and inhibitors. Energy-security mandates that favour domestic output are expected to maintain chemical procurement volumes.
- US crude output averaged 13.6 million barrels per day in 2025, and the EIA projects 13.7 million barrels per day for 2026. The United States oilfield chemical market is set for a 4.8% CAGR through 2036 on this production base. The Permian Basin, Eagle Ford and Bakken basins collectively consume large volumes of drilling fluids, friction reducers and production inhibitors. Flotek raised 2026 revenue guidance to USD 360–370 million, citing accelerating international and domestic chemistry demand. Sustained production near record levels is expected to underpin US oilfield chemical demand.
- Petrobras reported record oil and gas output of about 2.99 million barrels of oil equivalent per day in 2025, with pre-salt fields supplying 82% of the fourth-quarter total. Pre-salt wells operate at high pressure and temperature and require intensive flow-assurance, hydrate-inhibition and scale-control chemical packages, putting the Brazil oilfield chemical market on a projected 5.1% CAGR through 2036. Búzios alone exceeded 1 million barrels per day in October 2025, reinforcing deepwater chemical demand.
- North Sea operators rely on corrosion and scale inhibitors, demulsifiers and hydrate management chemicals to extend the productive life of mature offshore fields, pointing to a 3.9% CAGR for the United Kingdom oilfield chemical market through 2036. Environmental oversight under the OSPAR framework favours low-toxicity and biodegradable formulations, which steers R&D spend toward green chemistry alternatives.
- Germany oilfield chemical market is projected to grow at a 3.8% CAGR through 2036. Domestic oil and gas output is small, but BASF's oilfield chemicals business positions Germany as a formulation and export base, a measure of supply activity rather than domestic upstream consumption. Research partnerships on EOR polymers and water management chemicals add to the country's chemical contribution.
- French specialty chemical firms supply drilling fluid additives, cementing additives and anti-scaling products to international operators despite limited domestic exploration, placing the France oilfield chemical market on an estimated 3.7% CAGR through 2036. The completed transfer of Syensqo’s Oil & Gas business to SNF Group in January 2026 for approximately EUR 135 million has consolidated French oilfield stimulation chemistry under a polyacrylamide specialist.
- Australia oilfield chemical market is anticipated to record a 3.5% CAGR through 2036, driven by offshore LNG projects in the Northwest Shelf and Browse Basin that require drilling mud, cementing chemicals and stimulation additives under stringent environmental compliance standards. Lower-toxicity and biodegradable formulations are gaining preference as operators align with national offshore environmental plans.
- Mediterranean offshore projects and North African exploration support demand for high-salinity-tolerant and deepwater chemical formulations, underpinning a 3.4% CAGR forecast for the Italy oilfield chemical market through 2036. Logistics infrastructure connecting Italian ports to North African drilling sites gives local suppliers a distribution advantage.
- Offshore technology partnerships and advanced material development underpin the supply of paraffin inhibitors, hydrate suppressants and emulsion breakers for deepwater and unconventional resources, supporting a 3.3% CAGR for the Japan oilfield chemical market through 2036. Automated, digitally modelled chemical dosing is being adopted by Japanese service providers.
- New Zealand oilfield chemical market is estimated at 3.1% CAGR through 2036. Activity is concentrated in the Taranaki Basin; steady demand exists there for well-maintenance and production-optimisation chemicals, including corrosion inhibitors and scale-control agents. Marine environmental standards favour water-based and low-discharge chemical systems.
Who are the notable companies in the Oilfield Chemical Market?
Baker Hughes Company, Halliburton Company, SLB, BASF SE, Albemarle Corporation, Nouryon, Dow Inc., Flotek Industries Inc., Clariant AG, Innospec Incorporated, Chevron Phillips Chemical Company LLC, and GEO Drilling Fluids Inc. are profiled in the oilfield chemical market.
Oilfield chemical supply is divided among integrated oilfield service firms, diversified chemical producers and specialist formulators. Baker Hughes, Halliburton and SLB combine chemical technology with field services and digital platforms, which allows bundled contracts covering fluid supply, dosing and performance monitoring. BASF, Nouryon and Clariant compete on formulation science, offering inhibitors, surfactants and polymers that operators procure separately from service contracts. Flotek, Innospec and GEO Drilling Fluids focus on specific product lines or geographies.
- Integrated oilfield service providers: Baker Hughes Company, Halliburton Company, SLB.
- Diversified chemical producers: BASF SE, Nouryon, Dow Inc., Clariant AG, Albemarle Corporation.
- Specialist formulators and regional suppliers: Flotek Industries Inc., Innospec Incorporated, GEO Drilling Fluids Inc., Chevron Phillips Chemical Company LLC.
Competitive Benchmarking: Oilfield Chemical Market
Table 6: Competitive Benchmarking for the Oilfield Chemical Market (qualitative capability ratings), 2026
| Company | Formulation Breadth | Field Service Integration | Sustainability Portfolio | Reach |
|---|---|---|---|---|
| Baker Hughes Company | High | High | Medium | High |
| Halliburton Company | High | High | Medium | High |
| SLB | High | High | Medium | High |
| BASF SE | High | Low | High | High |
| Nouryon | Medium | Medium | High | Medium |
| Clariant AG | Medium | Low | High | Medium |
| Albemarle Corporation | Medium | Low | Medium | Medium |
| Flotek Industries Inc. | Medium | Medium | Medium | Medium |
| Innospec Incorporated | Medium | Medium | Low | Medium |
| Dow Inc. | High | Low | Medium | High |
| GEO Drilling Fluids Inc. | Low | Medium | Low | Low |
| Chevron Phillips Chemical Company LLC | Medium | Low | Medium | Medium |
Key Developments in the Oilfield Chemical Market
- In July 2025, SLB completed the acquisition of ChampionX, gaining a production chemistry and artificial lift platform with more than 7,000 employees, in the largest acquisition SLB has made since 2016.
- In October 2025, Syensqo agreed to sell the Oil & Gas business unit, which generated about EUR 400 million in 2024 net sales in oilfield stimulation chemicals, to SNF Group for EUR 135 million enterprise value.
- In June 2025, Nouryon opened an Innovation Center for oilfield applications in Houston, covering demulsification, corrosion and scale inhibition, and stimulation research.
- In April 2026, Baker Hughes reported Q1 2026 OFSE revenue of USD 3.2 billion and total revenue of USD 6.6 billion, with record quarterly orders of USD 4.9 billion in the company’s Industrial and Energy Technology segment.
Key Players in the Oilfield Chemical Market
Integrated Oilfield Service Providers
- Baker Hughes Company
- Halliburton Company
- SLB
Diversified Chemical Producers
- BASF SE
- Nouryon
- Dow Inc.
- Clariant AG
- Albemarle Corporation
Specialist Formulators and Regional Suppliers
- Flotek Industries Inc.
- Innospec Incorporated
- GEO Drilling Fluids Inc.
- Chevron Phillips Chemical Company LLC
Oilfield Chemical Market - Report Scope
Table 7: Report Scope for the Oilfield Chemical Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Application; terrain type; product type; region |
| Quantitative units | USD million |
| Market definition | Revenue from chemicals consumed in onshore and offshore oil and gas operations across drilling, completion, cementing, stimulation, production and enhanced oil recovery stages. Excludes refinery process chemicals, petrochemical feedstocks and general-purpose industrial chemicals not formulated for oilfield use. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; China; Brazil; United Kingdom; Germany; France; Australia; Italy; Japan; New Zealand |
| Key companies profiled | Baker Hughes Company; Halliburton Company; SLB; BASF SE; Albemarle Corporation; Nouryon; Dow Inc.; Flotek Industries Inc.; Clariant AG; Innospec Incorporated; GEO Drilling Fluids Inc.; Chevron Phillips Chemical Company LLC |
| Forecast period | 2026 to 2036 |
| Approach | A two-way bottom-up and top-down check reconciles reported operator chemical spend, supplier revenue and production throughput within the defined oilfield chemical revenue boundary. |
Oilfield Chemical Market - Research Methodology
Table 8: Research Methodology for the Oilfield Chemical Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with oilfield chemical formulators, procurement teams at E&P operators, and drilling-fluid engineers across North America, the Middle East and Asia-Pacific. |
| Desk Research | Public filings, investor presentations and annual reports from the profiled companies; government production statistics from the EIA, China NBS, Petrobras and OPEC; trade body data from the American Chemistry Council and OSPAR. |
| Market Sizing and Forecasting | Chemical intensity per barrel modelling across well stages, combined with rig-count regression and regional production forecasts. Segment shares derived from supplier product-line revenue and operator procurement data. |
| Data Validation | Cross-referencing company-reported oilfield segment revenue against top-down production-weighted chemical demand estimates. Three-way check: supplier revenue, operator spend surveys, and published production volumes. |
Oilfield Chemical Market by Segments
Oilfield Chemical Market segmented by Application:
- Drilling and Completion Chemicals
- Cementing Chemicals
- Stimulation Chemicals
- Oil Production Chemicals
- Enhanced Oil Recovery (EOR) Chemicals
Oilfield Chemical Market segmented by Terrain Type:
- Onshore
- Offshore
Oilfield Chemical Market segmented by Product Type:
- Inhibitors (Scale, Corrosion, Paraffin)
- Lubricants
- De-emulsifiers
- Viscosifiers
- Gas Well Foamers
- Biocides
- H₂S Scavengers
- Others
Oilfield Chemical Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] EIA. (2026, July). The United States produced more crude oil than any other country in 2025. https://www.eia.gov/todayinenergy/detail.php?id=67844
- [2] Hydrocarbon Processing. (2026, January). China's 2025 refinery throughput, crude and gas output hit new highs. https://hydrocarbonprocessing.com/news/2026/01/chinas-2025-refinery-throughput-crude-and-gas-output-hit-new-highs/
- [3] Datamar News. (2026, February). Petrobras sets production record and expands exports in 2025. https://datamarnews.com/noticias/petrobras-sets-production-record-and-expands-exports-in-2025/
- [4] Pipeline & Gas Journal. (2026, April 17). US rig count falls for second straight week, Baker Hughes says. https://pgjonline.com/news/2026/april/us-rig-count-falls-for-second-straight-week-baker-hughes-says
- [5] Chevron Phillips Chemical. (n.d.). Drilling specialties – high performance and value. https://www.cpchem.com/bl/drilling/en-us/pages/default.aspx
- [6] Offshore Technology. (2026, April). Baker Hughes Q1 2026 net income $930m. https://www.offshore-technology.com/news/baker-hughes-q1-2026-net-income-930m/
- [7] Business Wire. (2026, January 21). Halliburton announces fourth quarter 2025 results. https://www.businesswire.com/news/home/20260121200751/en/Halliburton-Announces-Fourth-Quarter-2025-Results
- [8] FinViz. (2026, August). Flotek raises 2026 revenue guidance to $360 million–$370 million. https://finviz.com/news/390229/flotek-raises-2026-revenue-guidance-to-360-million-370-million
- [9] SLB. (2025, July). ChampionX legacy companies. https://www.slb.com/zh-cn/legacy-companies/championx
- [10] Nouryon. (2025, June 18). Launching Innovation Center for Oilfield Solutions in Texas, US. https://www.nouryon.com/news-and-events/news-overview/2025/launching-innovation-center-for-oilfield-solutions-in-texas-us/
- [11] Chemical Engineering. (2025, October 31). Syensqo to divest Oil & Gas business to SNF Group. https://www.chemengonline.com/syensqo-to-divest-oil-gas-business-to-snf-group/
- [12] BASF. (n.d.). Oilfield chemicals – applications – production. https://energy-resources.basf.com/global/en/oilfield-chemicals/applications/production
- [13] Clariant. (n.d.). Oil Services. https://www.clariant.com/Business-Units/Care-Chemicals/Oil-Services
- [14] Hellenic Shipping News. (2025, March). Korean shipbuilders secure 3.5-year backlog as LNG and defense orders lift prices. https://www.hellenicshippingnews.com/?p=1118298
This Report Answers
- How big is the oilfield chemical market during 2026?
- What value is projected by 2036?
- Which application holds leading share?
- Which terrain type holds leading share?
- Which countries have leading growth?
- Which companies are key in the market?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Drilling and Completion Chemicals
- Cementing Chemicals
- Stimulation Chemicals
- Oil Production Chemicals
- Enhanced Oil Recovery (EOR) Chemicals
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Terrain Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Terrain Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Terrain Type, 2026 to 2036
- Onshore
- Offshore
- Y-o-Y Growth Trend Analysis By Terrain Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Terrain Type, 2026 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Inhibitors (Scale, Corrosion, Paraffin)
- Lubricants
- De-emulsifiers
- Viscosifiers
- Gas Well Foamers
- Biocides
- H₂S Scavengers
- Others
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Application
- By Terrain Type
- By Product Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Terrain Type
- By Product Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Application
- By Terrain Type
- By Product Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Terrain Type
- By Product Type
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Application
- By Terrain Type
- By Product Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Terrain Type
- By Product Type
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Application
- By Terrain Type
- By Product Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Terrain Type
- By Product Type
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Application
- By Terrain Type
- By Product Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Terrain Type
- By Product Type
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Application
- By Terrain Type
- By Product Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Terrain Type
- By Product Type
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Application
- By Terrain Type
- By Product Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Terrain Type
- By Product Type
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Terrain Type
- By Product Type
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Application
- By Terrain Type
- By Product Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Baker Hughes Company
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Halliburton Company
- SLB
- BASF SE
- Nouryon
- Clariant AG
- Albemarle Corporation
- Flotek Industries Inc.
- Innospec Incorporated
- Dow Inc.
- GEO Drilling Fluids Inc.
- Chevron Phillips Chemical Company LLC
- Baker Hughes Company
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Terrain Type, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Terrain Type, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Terrain Type, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Terrain Type, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Terrain Type, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Terrain Type, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Terrain Type, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Terrain Type, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Application
- Figure 6: Global Market Value Share and BPS Analysis by Terrain Type, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Terrain Type, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Terrain Type
- Figure 9: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Product Type
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Application
- Figure 26: North America Market Value Share and BPS Analysis by Terrain Type, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Terrain Type, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Terrain Type
- Figure 29: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Product Type
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Application
- Figure 36: Latin America Market Value Share and BPS Analysis by Terrain Type, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Terrain Type, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Terrain Type
- Figure 39: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Product Type
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Application
- Figure 46: Western Europe Market Value Share and BPS Analysis by Terrain Type, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Terrain Type, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Terrain Type
- Figure 49: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Product Type
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Application
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Terrain Type, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Terrain Type, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Terrain Type
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Application
- Figure 66: East Asia Market Value Share and BPS Analysis by Terrain Type, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Terrain Type, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Terrain Type
- Figure 69: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Product Type
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Terrain Type, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Terrain Type, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Terrain Type
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Terrain Type, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Terrain Type, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Terrain Type
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the Oilfield Chemical Market expected in 2026?
As per FMI analysis, the oilfield chemical market reaches USD 32.60 billion in 2026, advancing from USD 31.2 billion in 2025. By 2036, the market is projected at USD 51.1 billion, adding USD 18.51 billion in revenue over the forecast decade.
What CAGR is projected for the Oilfield Chemical Market through 2036?
FMI projects a 4.6% CAGR for the oilfield chemical market from 2026 to 2036. Record crude output in the US and China, deepwater expansion off Brazil and sustained EOR activity in mature fields underpin this trajectory.
Which application holds a leading market share in 2026?
Drilling and completion chemicals lead at 28% of application demand in 2026. Every well drilled and completed draws on drilling fluid additives, shale inhibitors, completion brines and wellbore-cleanup agents, and the segment scales with rig count and lateral length.
Which terrain type holds a leading share in 2026?
Onshore operations represent an estimated 65% of terrain-type demand in 2026, driven by North American shale basins, Chinese onshore conventional and EOR fields, and Middle Eastern onshore production.
Which country has a leading expansion outlook through 2036?
China posts the fastest profiled growth at 5.7% CAGR, supported by rising domestic crude and gas production, large-scale polymer flooding programmes and offshore exploration in the South China Sea.
Who are the key companies in the Oilfield Chemical Market?
Notable companies include Baker Hughes Company, Halliburton Company, SLB, BASF SE, Albemarle Corporation, Nouryon, Dow Inc., Flotek Industries Inc., Clariant AG, Innospec Incorporated, GEO Drilling Fluids Inc., and Chevron Phillips Chemical Company LLC.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
