

- Market Size (2026)
- USD 118.0 Bn
- Forecast (2036)
- USD 207.4 Bn
- CAGR (2026 to 2036)
- 5.8%
How big is Out-of-home Coffee Market in 2026?
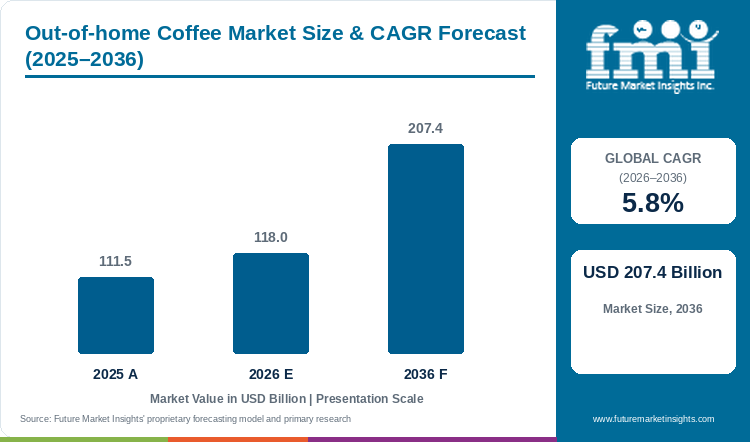
Demand for out-of-home coffee is projected to expand at 5.8% CAGR between 2026 and 2036. Industry value grows from USD 111.5 billion in 2025 to USD 118.0 billion in 2026 and is projected to reach USD 207.4 billion by 2036.
Peak morning commuter throughput at drive-thru windows and transit cafés depends on espresso extraction speed and automated milk texturing that preserve cup quality under time pressure. Industry turnover stood at USD 111.5 billion in 2025 and reaches USD 118.0 billion in 2026, according to FMI. Over the forecast decade, commercial out-of-home coffee expenditure is set to climb to USD 207.4 billion by 2036 at a 5.8% CAGR and unlock USD 89.4 billion in cumulative expansion. Corporate pantries and hotel counters dispense portioned coffee capsules to bypass manual grinding, whereas barista-pulled espresso drinks capture 49.0% of 2026 product type revenue. International Coffee Organization trade data in February 2026 confirmed that January 2026 global green bean exports rose 12.7% year-on-year to 10.85 million bags as total coffee shipments reached 12.62 million bags [1].
Key Market Trends & Insights
- By product type: Espresso-Based Drinks claim 49.0% of 2026 product type expenditure as patrons trade up from batch drip brews to iced shaken espressos and flat whites.
- By service channel: Cafés & Specialist Chains secure 47.0% of 2026 service channel turnover through dual-lane suburban drive-thrus and mobile app pre-ordering.
- By packaging format: Disposable Paper Cups represent 74.0% of 2026 serving volume because takeaway commuters rely on insulated cups lined with water-based recyclable coatings.
Regional Highlights
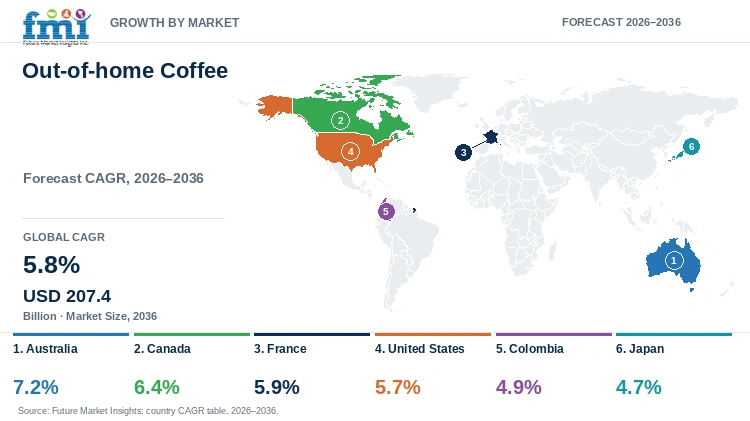
- Independent espresso bar density puts Australia ahead of all evaluated nations with a 7.2% CAGR from 2026 to 2036.
- Suburban drive-thru corridors in Canada (6.4%) and bistro terraces in France (5.9%) lead North American and European growth ahead of the United States (5.7%), whereas Colombia (4.9%) and Japan (4.7%) reflect mature urban networks.
Market Size & Forecast
Table 1: Market Size and Forecast for the Out-of-home Coffee Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 111.5 billion |
| Estimated Market Size in 2026 | USD 118.0 billion |
| Projected Market Size by 2036 | USD 207.4 billion |
| CAGR, 2026 to 2036 | 5.8% |
| Added Revenue, 2026 to 2036 | USD 89.4 billion |
High-street lease costs in Sydney and London alongside mandatory reusable dine-in tableware laws in France force café operators to engineer smaller store footprints than suburban drive-thru chains in the United States and Canada. Global coffee production for the 2026/27 marketing year is projected by the July 2026 USDA Foreign Agricultural Service circular to rise by 10.8 million bags to a record 189.7 million bags, easing spot supply bottlenecks for commercial roasters [2]. Multi-site hospitality groups are locking in medium-roast and dark-roast roasted coffee contracts while deploying super-automatic bean-to-cup machines that auto-adjust burr grind settings to humidity shifts during morning rush hours.
Store Throughput and Beverage Ticket Economics
Table 2: Store Throughput and Beverage Ticket Indicators for the Out-of-home Coffee Market (USD billion, cups, and USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 111.5 | 118.0 | 207.4 |
| Average daily cups dispensed per commercial café (cups) | 310 to 360 | 325 to 380 | 410 to 475 |
| Average out-of-home espresso beverage ticket (USD) | 4.20 to 4.85 | 4.35 to 5.05 | 5.40 to 6.30 |
| Mobile app pre-order share of chain transactions (%) | 36% to 40% | 39% to 43% | 52% to 58% |
Store economics note: Daily cup counts and ticket averages alongside digital pre-order shares summarize point-of-sale benchmarks across commercial coffeehouses and drive-thru or convenience dispense counters.
Commercial Dispensing & Per Capita Consumption Sizing
Automated grind-and-brew equipment has allowed convenience stores and highway travel plazas alongside corporate micro-markets to capture morning commuter traffic that previously belonged exclusively to full-service coffee shops. Telemetry sensors inside modern boilers and burr grinders alert regional maintenance teams before scale buildup alters extraction pressure. In addition to this, office facilities and hotel lobbies are adopting recyclable single-serve coffee containers so employees and travelers can brew fresh specialty roasts without dedicated barista staffing.
Table 3: Commercial Dispensing and Per Capita Spending Indicators for the Out-of-home Coffee Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Annual out-of-home coffee spend per capita (USD) | 13.55 | 14.22 | 23.17 |
| Annual spend per regular urban coffee commuter (USD) | 580 to 690 | 610 to 725 | 860 to 1,020 |
| Average green bean dose per double espresso shot (grams) | 16 to 18 | 17 to 19 | 18 to 20 |
Table 4: Channel and Format Revenue Concentration for the Out-of-home Coffee Market (USD billion and percentages), mixed reporting years from 2025 to 2026
| Metric | Value | Scope Reference |
|---|---|---|
| Market size, 2026 | USD 118.0 billion | 2026 market baseline |
| Espresso-based drinks revenue, 2026 | USD 57.8 billion | 49.0% product type share |
| Cafés and specialist chains revenue, 2026 | USD 55.5 billion | 47.0% service channel share |
| Disposable paper cups serving revenue, 2026 | USD 87.3 billion | 74.0% packaging format share |
Analyst Perspective
"Pressurized cold-brew taps and telemetry-linked espresso grinders cut drive-thru wait times while lifting afternoon iced beverage margins. Green Arabica price spikes and municipal single-use cup bans still force chains to redesign takeaway packaging."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the out-of-home coffee market segmented?
The out-of-home coffee market is segmented by product type, service channel, packaging format, and region. In 2026, espresso-based drinks are projected at 49.0% of product type, cafés and specialist chains at 47.0% of service channel, and disposable paper cups at 74.0% of packaging format.
Commercial foodservice coffee tracking from 2026 to 2036 covers Beverage Product Type and Service Channel alongside Packaging Format and Region. Product Type separates high-pressure espresso-based drinks from batch filter and drip brewed coffee as well as steeped cold brew and nitro draft coffee. Service Channel classifies revenue by point of sale across cafés and specialist chains alongside quick service restaurants and corporate workplaces. Packaging Format measures takeaway disposable paper cups against dine-in ceramic ware and reusable tumblers.
By product type: Espresso-Based Drinks, Filter & Drip Brewed Coffee, and Cold Brew & Nitro Draft Coffee.
By service channel: Cafés & Specialist Chains, Quick Service Restaurants (QSRs), and Workplaces & Corporate Offices.
By packaging format: Disposable Paper Cups and Reusable Mugs & Ceramic Ware.
What makes Espresso-Based Drinks central to the product type category?
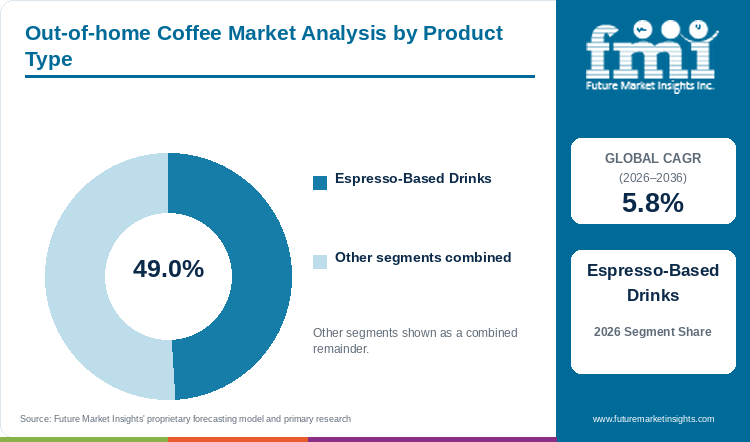
Espresso-based drinks are projected to capture 49.0% of product type demand in 2026, driven by customized milk beverages.
Table 5: Product Type Share for the Out-of-home Coffee Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Espresso-Based Drinks | 49.0% |
| Other Segments Combined | 51.0%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type Leadership and Market Growth for the Out-of-home Coffee Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.8% |
| Leading Segment | Espresso-Based Drinks |
Commercial coffee bars generate nearly half of their turnover from espresso-based drinks because high-pressure 9-bar extraction produces a concentrated crema shot that pairs well with steamed dairy milk and plant-based oat milk. Unlike basic drip coffee that consumers easily brew at home, cappuccinos and iced shaken espressos command higher ticket prices through customized milk micro-foam and cold foam toppings. Operators also formulate dairy and plant-based coffee creamer emulsions that resist curdling in acidic espresso shots. Filter and drip brewed coffee holds 31.0% share for high-speed morning batch service, while cold brew and nitro draft coffee accounts for 20.0%.
- Capturing 49.0% of product type revenue in 2026, espresso-based drinks lead commercial sales on account of higher ticket values for lattes and iced shaken espressos.
- Consumer tracking in the 2026 National Coffee Data Trends Specialty Coffee Report released in July 2026 confirmed that espresso-based and specialty iced coffee beverages remained at record consumption highs among adult coffee drinkers [3].
Why do Cafés & Specialist Chains lead the service channel category?
With an estimated 47.0% share in 2026, cafés and specialist chains lead the service channel category, underpinned by drive-thru speed.
Branded coffeehouses and independent specialty espresso bars anchor commercial distribution by combining suburban drive-thru convenience with neighborhood third-place seating. Multi-unit chains integrate smartphone order-ahead queues with dual-hopper super-automatic espresso machines so commuters can collect customized drinks in under three minutes. Furthermore, high-volume chains dose shelf-stable liquid coffee extracts into blended frappes and iced refreshers to eliminate brewing wait times during peak hours. Quick service restaurants hold 33.0% share through value breakfast combos, while workplaces and corporate offices represent 20.0% as employers upgrade pantry amenities.
- Cafés and specialist chains hold an estimated 47.0% of service channel demand in 2026, propelled by integrated loyalty apps and dedicated drive-thru pickup windows.
- Daypart performance data in the National Restaurant Association 2025 State of the Restaurant Industry Report in May 2025 indicated that drive-thru and digital order-ahead lanes generated over half of morning beverage traffic at commercial chains [4].
What keeps Disposable Paper Cups ahead by packaging format?
Disposable paper cups are set to command 74.0% of packaging format revenue in 2026, reinforced by commuter takeaway convenience.
Takeaway commuters and drive-thru motorists rely on insulated paperboard containers that protect hands from 85-degree-Celsius coffee while fitting standard vehicle cupholders. Because municipal waste regulations across Europe and North America penalize conventional polyethylene-lined cups, foodservice operators are transitioning toward aqueous dispersion-coated and PLA-lined paper cups that repulp cleanly in standard paper mills. Double-wall and ripple-wall paper constructions also eliminate separate cardboard sleeves, speeding up barista cup assembly. Reusable mugs and ceramic dine-in ware account for the remaining 26.0% share across sit-down bistros and bring-your-own-tumbler discount programs.
- Representing 74.0% of packaging format volume in 2026, disposable paper cups remain the primary container format owing to commuter takeaway habits and recyclable aqueous barrier linings.
- Audits published by the European Foodservice Packaging Association in June 2025 confirmed that aqueous-dispersion and low-plastic barrier paperboard cups exceeded 62% adoption across surveyed European café chains [5].
What are the drivers, restraints, and opportunities in the out-of-home coffee market?
Urban commuter habits and specialty iced espresso menus drive commercial sales, whereas Arabica bean volatility and barista turnover compress store margins, and mobile pre-ordering alongside cold-brew tap systems unlock throughput gains.
- Driver: Daily commuter coffee routines and strong Gen-Z demand for customized iced espresso and cold brew drinks sustain year-round store traffic through 2036.
- Restraint: Weather-driven green coffee bean price swings and high hospitality labor turnover raise operating expenses for chain and independent cafés through 2036.
- Opportunity: Smartphone order-ahead loyalty ecosystems and nitro cold-brew draft dispensers cut queue wait times and raise average ticket margins through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Afternoon iced beverage occasions and single-origin espresso upgrades have turned neighborhood coffee shops into all-day traffic destinations rather than morning-only stops. Younger beverage buyers treat iced shaken espressos and cold-foam lattes as customizable daily refreshments. Industry tracking in Allegra World Coffee Portal's Project Café Global 2026 report in December 2025 confirmed continued global outlet expansion led by iced beverage menus and drive-thru formats [6]. For batch-brewed morning filter service, chains also specify oxygen-bleached coffee filter paper that removes bitter diterpene oils while preserving clean origin aromatics.
Risk Assessment of the Out-of-home Coffee Market: Operational and Supply Friction
Erratic rainfall and frost events across Brazilian and Vietnamese coffee-growing belts expose foodservice roasters to sudden green-bean cost spikes. When futures markets surge, independent coffeehouses struggle to raise counter prices fast enough to protect gross margins. The International Coffee Organization reported in its September 2026 Coffee Market Report that the ICO Composite Indicator Price averaged 262.18 US cents per pound in September 2026 as Robusta rose to 43.1% of world output [7]. High barista turnover further strains store operations, prompting chains to stock pre-dosed Swiss-water decaffeinated coffee pucks that brew consistently without manual grinder recalibration.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Pressurized cold-brew draft towers paired with smartphone order-ahead pickup shelves let coffee chains boost peak-hour transaction capacity without expanding store square footage. Pulling nitrogen-infused cold brew from a kegged tap takes less than five seconds compared with 45 seconds for a manual espresso build. Allegra World Coffee Portal's Project Café Europe 2025 report in April 2025 documented that the European branded coffee shop market grew 4.7% to reach 51,042 outlets as operators expanded digital ordering and cold beverage bars [8]. Beverage groups also capture impulse cooler sales by stocking canned ready-to-drink coffee at checkout lanes.
Out-of-home Coffee Market by Country (2026 to 2036)
Independent espresso bar density in Australia and high-frequency drive-thru commuting in Canada lead expansion across the six profiled coffee markets. FMI projections show commercial foodservice coffee turnover advancing at a 7.2% CAGR in Australia while convenience-store-anchored Japan progresses at 4.7% through 2036. Store profitability in each jurisdiction reflects local commercial lease rates and barista wage scales alongside packaging waste legislation.
Table 7: Country CAGR and Primary Growth Levers for the Out-of-home Coffee Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Australia | 7.2% | Independent specialty café culture and high flat-white and oat-milk spend |
| Canada | 6.4% | Suburban drive-thru breakfast lanes and cold-brew summer menu expansion |
| France | 5.9% | Sidewalk bistro terrace traffic paired with urban specialty roast bars |
| United States | 5.7% | Drive-thru kiosk networks, mobile app ordering, and iced shaken espresso |
| Colombia | 4.9% | Domestic single-estate specialty coffee shops and urban coffee tourism |
| Japan | 4.7% | Automated convenience-store bean-to-cup counters and precision drip bars |
Source: Future Market Insights analysis
Australia Out-of-home Coffee Market Outlook (2026 to 2036)
Neighborhood micro-roasters and independent espresso bars shape Australia's commercial coffee landscape, where daily commuters demand barista-textured flat whites and single-origin batch brews instead of standardized international chain menus. Strong suburban café patronage across Melbourne and Sydney lifts Australian out-of-home coffee expenditure at a 7.2% CAGR through 2036. In October 2025, the Australian Specialty Coffee Association reported a 9% annual rise in specialty café turnover as domestic coffee consumption approached 2.65 million 60-kilogram bags [9]. While mandatory weekend hospitality penalty wages and metropolitan lease escalations compress full-service café margins, operators are launching compact walk-up espresso windows paired with smartphone pre-ordering and barista-grade oat and macadamia milk surcharges to protect store-level unit profitability through 2036.
Key takeaway: In Australia, independent specialty roasters pair premium flat-white and plant-milk menus with compact walk-up windows to drive a 7.2% CAGR.
Canada Out-of-home Coffee Market Outlook (2026 to 2036)
Highway commuter corridors and sub-zero winter weather make dual-lane suburban drive-thrus the primary commercial engine across Canada, linking morning brewed coffee orders directly to hot breakfast sandwich attachment. High-frequency commuter orders along provincial transit routes support a 6.4% CAGR for Canadian foodservice coffee between 2026 and 2036. In September 2025, Statistics Canada consumer price and foodservice tracking highlighted rising retail and restaurant coffee expenditure across provinces as national green and soluble coffee imports exceeded 5.05 million bags [10]. Yet commercial uptake faces friction from federal single-use plastics prohibitions and municipal cup-recycling mandates, prompting Canadian chains to roll out aqueous-lined paperboard cups and heated mobile pickup lockers alongside pressurized cold-brew tap systems across Ontario and Quebec.
Key takeaway: In Canada, high-throughput suburban drive-thru lanes and summer nitro cold-brew tap rollouts sustain a 6.4% CAGR through 2036.
France Out-of-home Coffee Market Outlook (2026 to 2036)
Sidewalk bistro terraces and railway-station brasseries anchor out-of-home coffee service in France, where traditional post-meal Robusta-blend espressos now compete alongside third-wave washed Arabica coffeehouses in Paris and Lyon. Premiumization across French brasseries and specialty coffee shops underpins a 5.9% CAGR from 2026 to 2036. Survey data from the Comité Français du Café in December 2025 documented a 10% revenue increase among urban French specialty espresso bars serving traceable single-origin shots and oat-milk lattes [11]. However, France's statutory AGEC anti-waste law banning disposable tableware for dine-in meals forces commercial chains and bistros to install high-speed under-counter dishwashers and radio-frequency-tracked reusable ceramic and tempered-glass cups while expanding afternoon iced espresso and specialty filter service.
Key takeaway: In France, urban specialty Arabica espresso bars and bistro terrace upgrades offset AGEC reusable tableware compliance costs.
United States Out-of-home Coffee Market Outlook (2026 to 2036)
Modular drive-thru-only coffee kiosks and afternoon cold-foam espresso refreshers have transformed unit economics in the United States, shifting peak store revenue away from sit-down morning drip coffee toward higher-ticket iced builds. Nationwide expansion of drive-thru lanes and cold-dispense bars keeps United States foodservice coffee growing at a 5.7% CAGR through 2036. December 2025 USDA Foreign Agricultural Service world coffee trade data confirmed that U.S. green, roasted, and soluble coffee imports exceeded 25.5 million bags supporting commercial foodservice chains [12]. Nonetheless, statutory hospitality minimum-wage hikes in California and coastal metros compel U.S. operators to install automated cold-milk and syrup dosing skids that cut drink assembly times below thirty seconds during peak rush hours.
Key takeaway: In the United States, drive-thru-only espresso kiosks and automated cold-beverage dosing skids protect store margins against rising labor costs.
Colombia Out-of-home Coffee Market Outlook (2026 to 2036)
Producer-country vertical integration sets Colombia apart from coffee-importing nations, as domestic chains and estate roasteries in Bogotá and Medellín roast high-altitude washed Arabica micro-lots directly at origin for local cafés. Urban café openings and coffee tourism across Colombia generate a projected 4.9% CAGR over the 2026 to 2036 period. In October 2026, the Federación Nacional de Cafeteros reported 2025/26 national output at 12.65 million 60-kilogram bags while domestic coffee consumption held near 2.20 million bags across expanding urban coffeehouses [13]. The central commercial obstacle involves household disposable income disparities outside major cities, prompting domestic chains such as Juan Valdez and Tostao to split formats between premium tourist origin lounges and high-turnover neighborhood bakery-cafés serving freshly pulled washed Arabica espressos.
Key takeaway: In Colombia, origin-roasted single-estate espresso lounges and affordable neighborhood bakery-cafés capture both tourist and commuter spending.
Japan Out-of-home Coffee Market Outlook (2026 to 2036)
Dense commuter rail networks and more than 55,000 convenience store counters define Japan's commercial coffee architecture, blending self-serve freshly ground bean-to-cup machines with heritage kissaten siphon salons and specialty roasteries. Steady commuter traffic across Japanese convenience counters and specialty espresso chains delivers a 4.7% CAGR through 2036. In March 2026, the All Japan Coffee Association reported resilient commercial coffee demand approaching 6.90 million 60-kilogram bags supported by 6.20 million bags of green bean imports [14]. Nevertheless, a weaker yen against dollar-denominated Arabica contracts and acute service-sector labor shortages across regional prefectures push Japanese operators to deploy cashless touch-screen espresso pods and commuter rail station lockers alongside robotic pour-over kiosks across metropolitan Tokyo and Osaka.
Key takeaway: In Japan, automated convenience-store bean-to-cup counters and unmanned espresso kiosks sustain commuter volume despite acute staffing shortages.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the out-of-home coffee market?
Starbucks Corporation, JAB Holding Company, Costa Coffee, Nestlé Professional, Dunkin' Brands, McCafé, Lavazza, and Tim Hortons are notable companies in the out-of-home coffee market.
Real estate control at high-traffic commuter intersections and proprietary mobile app ecosystems decide market share among commercial coffee operators. Starbucks and Costa Coffee alongside Dunkin' Brands and Tim Hortons run thousands of company-owned and franchised drive-thru and high-street cafés anchored by digital loyalty rewards. JAB Holding Company and McCafé capture morning breakfast traffic across multi-brand bakery-café and quick-service restaurant counters. On the B2B side, Nestlé Professional and Lavazza supply telemetry-enabled bean-to-cup machines and roasted Arabica blends alongside recyclable disposable cups to corporate offices and hospitality venues.
- Global Branded Coffeehouse Chains: Starbucks Corporation and Costa Coffee alongside Tim Hortons operate company-owned and licensed cafés with integrated mobile ordering apps.
- Quick-Service and Multi-Brand Hospitality Groups: JAB Holding Company and Dunkin' Brands alongside McCafé drive high-volume morning drive-thru and bakery-café beverage transactions.
- Commercial Roasting and B2B Foodservice Platforms: Nestlé Professional and Lavazza supply bean-to-cup machinery and specialty Arabica blends alongside automated telemetry solutions to offices and hospitality venues.
Competitive Benchmarking: Out-of-home Coffee Market
Table 8: Competitive Benchmarking for the Out-of-home Coffee Market (qualitative capability ratings), 2026
| Company | Specialty Espresso & Cold Menu Breadth | Drive-Thru & Mobile App Integration | B2B Workplace & Kiosk Reach | Geographic Reach |
|---|---|---|---|---|
| Starbucks Corporation | High | High | Medium | High |
| JAB Holding Company | High | High | Medium | High |
| Costa Coffee | High | Medium | High | High |
| Nestlé Professional | Medium | Medium | High | High |
| Dunkin' Brands | High | High | Medium | Medium |
| McCafé | Medium | High | Medium | High |
| Lavazza | High | Medium | High | High |
| Tim Hortons | Medium | High | Medium | Medium |
Capability assessment note: Table 8 evaluates each operator across four operational dimensions. High ratings in Specialty Espresso & Cold Menu Breadth and Drive-Thru & Mobile App Integration reflect nationwide nitro draft and cold-foam espresso menus paired with smartphone order-ahead execution, while B2B Workplace & Kiosk Reach tracks unattended bean-to-cup pod installations in offices and travel hubs.
Key Developments in the Out-of-home Coffee Market
- Starbucks Coffee Company expanded its seasonal espresso and cold-foam creamer lineup alongside ready-to-drink iced espresso beverages in October 2026 across commercial and retail channels [15].
- Costa Coffee announced in October 2026 a nationwide upgrade of more than 13,000 Costa Express self-serve coffee machines across convenience and forecourt locations [16].
- JAB Holding Company portfolio brands expanded automated bean-to-cup workplace and transit terminal coffee kiosks in June 2025 across North American and European commuter hubs [17].
- Nestlé Professional partnered with regional bakery chains in January 2026 to install compact super-automatic specialty espresso bars across fast-casual counters [18].
Key Players in the Out-of-home Coffee Market
Global Branded Coffeehouse Chains
- Starbucks Corporation
- Costa Coffee
- Tim Hortons
Quick-Service and Multi-Brand Hospitality Groups
- JAB Holding Company
- Dunkin' Brands
- McCafé
Commercial Roasting and B2B Foodservice Platforms
- Nestlé Professional
- Lavazza
Out-of-home Coffee Market - Report Scope
FMI scope parameters cover commercial foodservice and workplace revenue from freshly prepared out-of-home coffee beverages while excluding packaged grocery roast-and-ground or instant coffee bought for home brewing.
Table 9: Report Scope for the Out-of-home Coffee Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Service Channel; Packaging Format; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial sales of freshly prepared hot and cold coffee beverages dispensed across cafés, specialist coffee chains, quick-service restaurants, workplaces, hotels, and convenience counters. Excludes retail grocery sales of packaged coffee beans, ground coffee, and household pods consumed at home. Supply Scope Note: Market valuation reflects commercial foodservice, workplace, and hospitality beverage dispensing realization rather than at-home retail supermarket roast-and-ground or household pod expenditures. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Australia, Canada, France, United States, Colombia, Japan, and additional countries in the full report |
| Key Companies Covered | Starbucks Corporation, JAB Holding Company, Costa Coffee, Nestlé Professional, Dunkin' Brands, McCafé, Lavazza, Tim Hortons |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Out-of-home Coffee Market - Research Methodology
Table 10: Research Methodology for the Out-of-home Coffee Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with commercial coffeehouse operations directors, master roasters, commercial espresso equipment engineers, foodservice packaging suppliers, and workplace beverage managers across key regions to validate store throughput, ticket pricing, and channel trends. |
| Secondary Research | Secondary research examined International Coffee Organization (ICO) market reports, USDA Foreign Agricultural Service world coffee trade circulars, national coffee association surveys, commercial foodservice point-of-sale data, and corporate annual filings. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period combined active café and QSR outlet counts with daily cup throughput, average beverage check values, and country-level commuter and workplace consumption trends. |
| Data Triangulation and Validation | Estimates were cross-checked against commercial green coffee roasting allocations, foodservice cup shipment volumes, and public chain segment revenues to ensure accuracy without double counting retail grocery coffee sales. |
| Country Forecasting Model | Country-level CAGRs are projected via the commercial foodservice beverage econometric model, calibrating evaluated national growth rates against the 5.8% global baseline through verified specialty café and drive-thru store openings, commercial espresso and cold-dispense equipment installations, and workplace single-serve coffee contract penetration. |
| Operational Benchmark Traceability | Operational benchmarks (daily commercial café cup throughput, espresso beverage ticket averages, and green bean extraction dosing weights) represent modeled estimates synthesized from International Coffee Organization market reports, USDA FAS World Markets and Trade circulars, national coffee association surveys, and commercial foodservice operator disclosures. |
Out-of-home Coffee Market by Segments
Out-of-home Coffee Market segmented by Product Type:
- Espresso-Based Drinks
- Filter & Drip Brewed Coffee
- Cold Brew & Nitro Draft Coffee
Out-of-home Coffee Market segmented by Service Channel:
- Cafés & Specialist Chains
- Quick Service Restaurants (QSRs)
- Workplaces & Corporate Offices
Out-of-home Coffee Market segmented by Packaging Format:
- Disposable Paper Cups
- Reusable Mugs & Ceramic Ware
Out-of-home Coffee Market by Region
- North America
- United States
- Canada
- Latin America
- Colombia
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- France
- United Kingdom
- Germany
- Italy
- Spain
- Benelux
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- Japan
- China
- South Korea
- South Asia and Pacific
- Australia and New Zealand
- India
- ASEAN
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] International Coffee Organization. (2026, February 1). Coffee Market Report - February 2026: Improved supply outlook weighing down on the I-CIP (CMR-0226-E). International Coffee Organization.
- [2] U.S. Department of Agriculture, Foreign Agricultural Service. (2026, July 2). Coffee: World Markets and Trade (July 2026 Circular). United States Department of Agriculture.
- [3] National Coffee Association & Specialty Coffee Association. (2026, July 27). 2026 National Coffee Data Trends specialty coffee report. National Coffee Association.
- [4] National Restaurant Association. (2025, May 14). 2025 state of the restaurant industry report. National Restaurant Association.
- [5] European Foodservice Packaging Association. (2025, June 20). Sustainable beverage packaging and paperboard cup recycling in European foodservice. European Foodservice Packaging Association.
- [6] World Coffee Portal (Allegra Group). (2025, December 17). Project Café Global 2026. Allegra World Coffee Portal.
- [7] International Coffee Organization. (2026, September 30). Coffee Market Report - September 2026: I-CIP drops 8.7% as Brazil's record crop reaches the market (CMR-0926-E). International Coffee Organization.
- [8] World Coffee Portal (Allegra Group). (2025, April 3). Project Café Europe 2025. Allegra World Coffee Portal.
- [9] Australian Specialty Coffee Association. (2025, October 16). Australian specialty café industry and domestic coffee consumption report 2025. Australian Specialty Coffee Association.
- [10] Statistics Canada. (2025, September 18). It's costing you a latte more for that cup of coffee lately, and here's why. Government of Canada.
- [11] Comité Français du Café. (2025, December 9). Enquête nationale sur la consommation de café hors domicile en France. Comité Français du Café.
- [12] U.S. Department of Agriculture, Foreign Agricultural Service. (2025, December 18). Coffee: World Markets and Trade (December 2025 Report). United States Department of Agriculture.
- [13] Federación Nacional de Cafeteros de Colombia. (2026, October 10). Producción mensual de café en Colombia: Balance cafetero 2025/2026. Federación Nacional de Cafeteros.
- [14] All Japan Coffee Association. (2026, March 11). Japan coffee supply, demand and convenience-store consumption statistics 2025-2026. All Japan Coffee Association.
- [15] Starbucks Coffee Company. (2026, October 5). Starbucks brings holiday coffees, creamers and ready-to-drink beverages to grocery. Starbucks Stories & News.
- [16] Costa Coffee. (2026, October 13). Costa Express upgrades more than 13,000 machines in nationwide push to raise the bar for coffee on the go. Costa Coffee Newsroom.
- [17] JAB Holding Company. (2025, June 18). Portfolio update on automated bean-to-cup workplace and transit coffee concepts. JAB Holding Company.
- [18] Nestlé Professional. (2026, January 22). Nestlé Professional expands compact super-automatic specialty espresso solutions for foodservice. Nestlé Professional News.
- [19] Luigi Lavazza S.p.A. (2026, March 30). 2025 results: Lavazza Group financial results as at 31st December 2025. Lavazza Group News and Media.
- [20] Tim Hortons (Restaurant Brands International). (2026, April 9). Tim Hortons expands cold brew and dual-lane drive-thru digital menu boards across North America. Tim Hortons Newsroom.
- [21] Dunkin' (Inspire Brands). (2025, September 26). Dunkin' deploys automated beverage dispensing systems across franchised iced coffee counters. Dunkin' News & Press Releases.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the out-of-home coffee market in 2026 and what is forecast for 2036?
- Which commuter and workplace beverage trends support demand for commercial coffee service?
- What makes Espresso-Based Drinks central to the product type category?
- Why do Cafés & Specialist Chains lead the service channel category globally?
- How do growth rates differ between Australia and Canada alongside France and the United States?
- Which leading companies operate café chains and commercial bean-to-cup systems today?
- What limits store margin expansion or equipment upgrades in the out-of-home coffee market?
- What should foodservice operators evaluate before selecting commercial espresso machinery and bean suppliers?
Frequently Asked Questions
How large is the Out-of-home Coffee Market expected to be in 2026 and what is forecast for 2036?
Global sales in the out-of-home coffee market are estimated to reach USD 118.0 billion in 2026. The market is projected to expand further and reach USD 207.4 billion by 2036, supported by urban commuter traffic and iced espresso menu innovation.
What CAGR is forecast for the Out-of-home Coffee Market through 2036?
As per FMI, the out-of-home coffee market is projected to grow at a 5.8% CAGR from 2026 to 2036. Growth is supported by expanding suburban drive-thru lanes alongside mobile app pre-ordering and automated workplace espresso dispensers.
Which product type holds a notable out-of-home coffee demand share in 2026?
Espresso-Based Drinks are projected to hold 49.0% of product type demand in 2026. The segment benefits from high consumer demand for handcrafted lattes and flat whites alongside iced shaken espresso beverages.
Which service channel holds a notable out-of-home coffee share in 2026?
Cafés & Specialist Chains are estimated to account for 47.0% of service channel revenue in 2026. Demand is supported by dedicated drive-thru windows alongside digital loyalty rewards and third-place social seating.
Which country has a notable out-of-home coffee expansion outlook during the forecast period?
FMI finds that Australia is projected to expand at a 7.2% CAGR during the 2026 to 2036 assessment period. Growth is supported by a deeply established independent barista culture and high per-capita spend on specialty espresso drinks.
Which companies are active in the Out-of-home Coffee Market during 2026?
Notable companies active in the market include Starbucks Corporation, JAB Holding Company, Costa Coffee, Nestlé Professional, Dunkin' Brands, McCafé, Lavazza, and Tim Hortons. These operators focus on cold-brew tap automation and mobile pickup speed alongside recyclable cup packaging.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Espresso-Based Drinks
- Filter & Drip Brewed Coffee
- Cold Brew & Nitro Draft Coffee
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Service Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Service Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Service Channel, 2026 to 2036
- Cafés & Specialist Chains
- Quick Service Restaurants (QSRs)
- Workplaces & Corporate Offices
- Y-o-Y Growth Trend Analysis By Service Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Service Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Disposable Paper Cups
- Reusable Mugs & Ceramic Ware
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Service Channel
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Service Channel
- By Packaging Format
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Colombia
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Service Channel
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Service Channel
- By Packaging Format
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- France
- United Kingdom
- Germany
- Italy
- Spain
- Benelux
- By Product Type
- By Service Channel
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Service Channel
- By Packaging Format
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Service Channel
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Service Channel
- By Packaging Format
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- China
- South Korea
- By Product Type
- By Service Channel
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Service Channel
- By Packaging Format
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Australia and New Zealand
- India
- ASEAN
- By Product Type
- By Service Channel
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Service Channel
- By Packaging Format
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Service Channel
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Service Channel
- By Packaging Format
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- Colombia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Service Channel
- By Packaging Format
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Service Channel
- By Packaging Format
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Starbucks Corporation
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- JAB Holding Company
- Costa Coffee
- Nestlé Professional
- Dunkin' Brands
- McCafé
- Lavazza
- Tim Hortons
- Starbucks Corporation
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


