

- Market Size (2026)
- USD 7.9 Bn
- Forecast (2036)
- USD 12.7 Bn
- CAGR (2026 to 2036)
- 4.9%
How big is Overrunning Clutches Market in 2026?
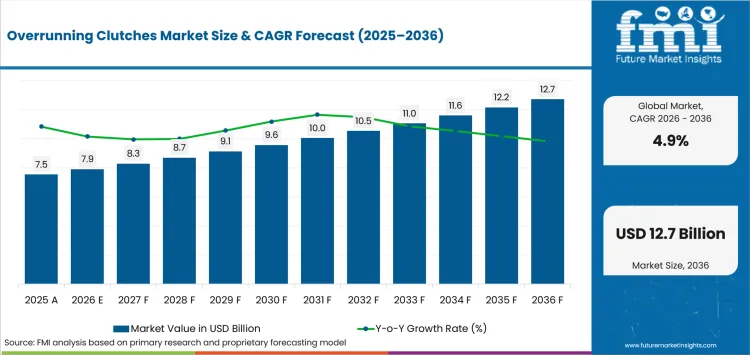
USD 7.9 billion in 2026 and USD 12.7 billion by 2036 at a 4.9% CAGR.
Demand for overrunning clutches is projected to advance at 4.9% CAGR from 2026 to 2036, reaching USD 12.7 billion from USD 7.9 billion. Steel-processing drives use passive one-direction torque control where overrunning shafts must disconnect without separate actuation. RINGSPANN documented steel-industry drive assemblies pairing freewheels with cardan shafts in September 2026, tying clutch choice to drive geometry and replacement access.
Country conditions vary because vehicle production cycles change qualification timing and replacement exposure for drivetrain components. UK Office for National Statistics data showed motor-vehicle manufacturing output increased 17.5% during the three months to January 2026. Component makers need replacement continuity during output swings while engineering teams qualify parts for new vehicle platforms.
Key Takeaways
- Vehicle starting and industrial machinery sustain demand for passive one-direction torque control that prevents reverse rotation during operation.
- By clutch type, sprag clutches are estimated to hold 32.0% in 2026 owing to compact torque density and rapid engagement.
- Starter drives are set to represent 26.0% of application demand in 2026 because automatic release protects components after engine speed increases.
- In 2026, automotive end use is projected to account for 35.0% because one-way functions remain embedded in starter and transmission architectures.
- Platform redesign and discontinued legacy freewheels can force requalification where shaft geometry or speed limits change during replacement decisions.
- Some of the key players in this market include Schaeffler AG, BorgWarner Inc., NTN Corporation, NSK Ltd., JTEKT Corporation, The Timken Company, Formsprag Clutch (Regal Rexnord), Stieber Clutch (Regal Rexnord), RINGSPANN GmbH, and SKF.
Analyst Perspective
“Commercial value depends on proving torque capacity and release behavior inside the customer’s actual drivetrain or machine. Suppliers earn repeat business by supporting qualification and replacement continuity without forcing avoidable redesign.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights
How is the overrunning clutches market segmented?
Clutch type, application, end use, sales channel and torque class define how overrunning clutches are specified, purchased and deployed.
Clutch type covers sprag clutches, roller ramp clutches, cam clutches, one-way bearing clutches and integrated overrunning units. Applications cover starter drives, conveyors - indexing, transmission systems, pulleys - accessory drives and industrial machinery. End use covers automotive, industrial machinery, mining - conveying, powersports and aerospace - defense applications with distinct operating loads. Sales channels cover OEM direct, industrial distributors, aftermarket replacement and MRO - service routes for installed equipment. Torque class covers medium duty, light duty, heavy duty and high-speed precision specifications for different load ranges.
Why do sprag clutches hold the current share position within clutch type?
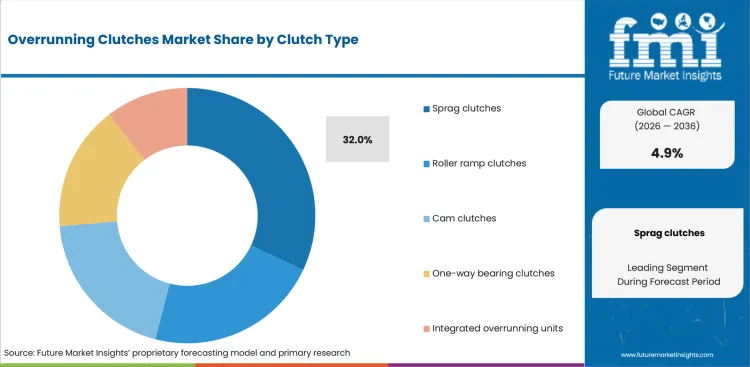
Sprag designs use wedging elements to lock quickly under torque while preserving freewheel operation after the speed relationship reverses. Their compact geometry fits clutch and brake systems that require automatic engagement without separate actuation hardware.
- By clutch type, sprag clutches are estimated to hold 32.0% in 2026 owing to compact torque density and rapid engagement.
- NSK-Warner described itself as a specialized clutch manufacturer in October 2025 while announcing an eAxle component based on its torque-transmission expertise. The development confirms continuing investment in compact rotating-system integration where one-way clutch packaging competes for limited space.
Why do starter drives hold the current share position within application?
Starter drives require automatic release after engine speed overtakes starter speed because continued coupling can damage the starting system. Packaging constraints make automotive starter systems sensitive to clutch size and repeatable engagement behavior.
- Starter drives are set to represent 26.0% of application demand in 2026 because automatic release protects components after engine speed increases.
- Council Regulation (EU) 2026/1463 set a 0% autonomous duty through 2030 for specified overrunning clutches used in passenger and commercial vehicle starter motors. The exact tariff description confirms that starter overrunning clutches remain a separately specified automotive component rather than a generic bearing function.
Why does automotive hold the current share position within end use?
Automotive programs use one-way torque control in starting and transmission-related functions where package efficiency and low drag affect the wider drivetrain. Electrified architectures change the placement of mechanical functions but continue to pressure power transmission components toward compact integration.
- In 2026, automotive end use is projected to account for 35.0% because one-way functions remain embedded in starter and transmission architectures.
- BorgWarner secured two Chinese dual-clutch programs in May 2025 and scheduled one new program for mass production by year-end. The awards confirm continuing customer investment in compact clutch modules with lower drag and controlled transmission behavior.
Why does OEM direct hold the current share position within sales channel?
Original equipment programs settle shaft geometry and operating limits before production tooling is frozen, so early engineering access reduces later redesign. Direct engagement is especially important in industrial gearbox design where adjacent bearings and housings determine the available clutch envelope.
- OEM direct is forecast to represent 42.0% in 2026 driven by application engineering that resolves geometry and qualification before production approval.
- NTN began providing data for about 6,000 bearing models to KISSsoft gearbox software in May 2025. The action illustrates how component manufacturers move engineering data into customer design tools before equipment specifications become fixed.
Why does medium duty hold the current share position within torque class?
Medium-duty units cover machinery that requires meaningful torque capacity without the size or service burden of heavy packaged freewheels. Conveyors and general machinery place many such specifications beside conveyor drive systems with recurring maintenance requirements.
- Medium duty is anticipated to represent 41.0% in 2026 because the class covers practical machinery loads without requiring oversized heavy-duty housings.
- JTEKT announced its integrated gear-bearing JIGB in April 2025 for automotive and industrial machinery applications. The development shows continuing design work around compact rotating assemblies where component size and load capacity influence medium-duty equipment specifications.
What are the drivers, restraints and opportunities in the Overrunning Clutches Market?
Automation and drivetrain investment support passive one-way torque control, while legacy-product discontinuation raises requalification work and high-speed machinery opens specialized engineering opportunities.
- Driver: Automated machinery and vehicle programs keep specifying passive engagement where reverse motion or speed mismatch must be controlled without separate actuation.
- Restraint: Legacy freewheel discontinuation can force replacement engineering because existing race geometry and speed limits may not accept a nominally similar unit.
- Opportunity: High-speed industrial systems reward suppliers that document lift-off behavior and thermal performance during prolonged freewheel operation.
Automated Motion Keeps One-Way Functions Relevant
Bulk-material and conveyor drives still need passive backstops because a stopped loaded system can run backward without mechanical restraint. RINGSPANN documented in April 2026 that cement plants use backstops on conveyors and bucket elevators plus overtaking freewheels in multi-motor drives. The same requirement keeps overrunning-clutch demand tied to industrial automation systems where electronic control does not replace reverse-motion protection during shutdowns.
Legacy Freewheel Changes Raise Requalification Costs
Machine builders face extra engineering work after a qualified freewheel family disappears because nominal dimensions do not prove interchangeability. RINGSPANN reported in June 2025 that automotive suppliers had reduced or discontinued cage-freewheel ranges used by industrial customers. Replacement programs therefore require fresh checks for race geometry, torque behavior and speed limits before maintenance teams approve a substitute during fixed shutdown windows.
High-Speed Freewheeling Supports Specialized Industrial Offers
Industrial users operating multi-motor drives need freewheels that disengage cleanly at elevated shaft speeds without excessive wear or heat. RINGSPANN introduced the FHHS series in December 2025 for speeds up to 12,000 rpm and commissioned a dedicated test bench. Suppliers can apply similar documented operating envelopes to gear motor systems and process drives where passive engagement avoids extra switching hardware.
Which country CAGRs are included in the Overrunning Clutches Market?
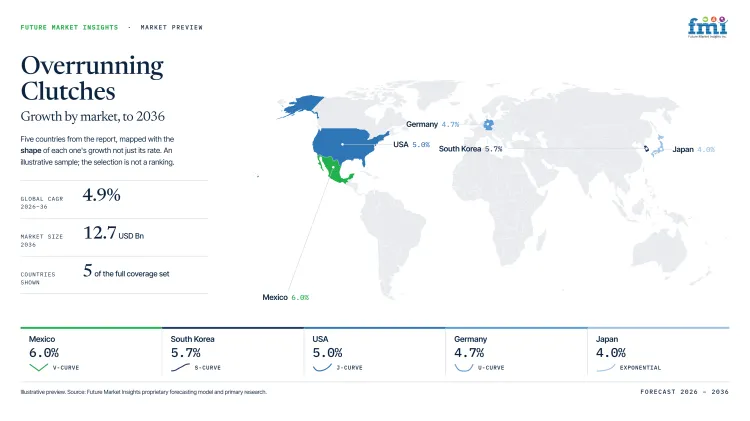
| Country | CAGR |
|---|---|
| Mexico | 6.0% |
| South Korea | 5.7% |
| Brazil | 5.3% |
| USA | 5.0% |
| Germany | 4.7% |
| France | 4.3% |
| Japan | 4.0% |
How do country-level CAGRs compare in the Overrunning Clutches Market?
Country forecasts span two percentage points from Mexico at 6.0% to Japan at 4.0% under different manufacturing conditions. Mexico and South Korea form the upper group because vehicle-program changes increase qualification work. Brazil and the USA occupy the middle, while Germany and France join Japan where mature equipment increases replacement exposure.
- Mexico’s export vehicle base rewards local engineering teams that resolve component changes without delaying production launches.
- South Korean platform redesign increases qualification work for compact drivetrain parts tied to export vehicle programs.
- Brazil’s recovering vehicle output meets financing pressure that keeps replacement continuity important for installed machinery.
- USA applications span vehicle production and industrial maintenance channels with materially different approved operating specifications.
- German electrification changes component placement while mature factories continue replacing parts inside established machinery.
- French electrified-vehicle production grows beside factories that still require replacement-compatible industrial motion components during maintenance.
- Japanese programs emphasize compactness and low rotational losses during qualification for mature production systems.
Similar CAGRs produce different conditions because production scale and qualification effort vary materially between countries.
Country-wise Analysis
- Mexico’s manufacturing base buys clutches through vehicle and machinery programs that require local engineering during component changes. Data México recorded national trade under HS 848360 for clutches and shaft couplings in second-quarter 2026, with Tamaulipas and Nuevo León reporting international sales. Demand for overrunning clutches in Mexico is forecast to expand at 6.0% CAGR from 2026 to 2036, linked to installed equipment requiring one-direction torque control. Approval still depends on verified torque and speed limits for the existing shaft and housing. Companies need local engineering plus replacement supply for material-handling systems that cannot accept lengthy redesign during planned shutdowns.
- South Korean sourcing follows export vehicle programs that change quickly as manufacturers rework electrified powertrain architectures. The Korean trade ministry reported in February 2026 that January automobile production rose 24.1% year over year and eco-friendly vehicle exports reached 92,000 units. Demand for overrunning clutches in South Korea is predicted to advance at 5.7% CAGR through 2036, tied to frequent platform engineering. Temporary line changes expose friction because newly positioned components must clear launch qualification before production resumes. Companies need compact designs and local technical response that preserve launch timing without assuming legacy one-way layouts transfer unchanged between programs.
- Brazilian vehicle plants serve domestic and export programs beside a large replacement base as ANFAVEA recorded 2.644 million vehicles produced in 2025 with exports rising 32.1%. Overrunning clutch demand in Brazil is forecast to rise at 5.3% CAGR over the forecast period, supported by renewed vehicle output and ongoing maintenance requirements. High interest rates limited a stronger domestic recovery and can delay discretionary machinery spending beyond essential replacement work. Companies need distributor coverage for replacement work and direct OEM support for new programs using conveyor belt equipment where approval depends on torque behavior instead of purchase price alone during plant outages.
- USA buyers span large vehicle programs and a broad industrial maintenance base that exposes clutch suppliers to varied operating envelopes. The Federal Reserve reported on August 18 2026 that motor vehicle assemblies averaged a 10.16 million unit annual rate during 2025. Adoption of overrunning clutches in USA is estimated to expand at 5.0% CAGR through 2036, supported by vehicle production and equipment replacement. Specification diversity remains the main commercial friction because automotive and industrial approvals use different load or speed limits. Companies need wide product coverage and engineering support that can document fit before approval in original-equipment and maintenance programs.
- German manufacturers operate a large vehicle base beside industrial automation as VDA recorded 4.15 million passenger cars produced in 2025 with electric registrations rising 50%. Overrunning clutch demand in Germany is projected to record 4.7% CAGR during the assessment period, supported by drivetrain redesign and installed machinery requirements. Passenger-car output remained 11% below 2019 and preserves replacement exposure beside newer electrified-platform investment in established manufacturing clusters. Companies need application engineering that can support newer electrified platforms without abandoning installed conveyor gearbox assets and legacy drivetrain equipment requiring dependable replacement parts during scheduled shutdowns and long-service production cycles without broader redesign work.
- French automotive manufacturing is shifting toward electrified vehicles while industrial sites maintain machinery built around established mechanical interfaces. INSEE reported on March 27 2026 that more than half of passenger cars produced in France during 2025 were fully or partly electric. Demand for overrunning clutches in France is forecast to expand at 4.3% CAGR over the forecast period, supported by platform transition beside installed-equipment replacement. Uneven factory utilization can slow qualification spending outside priority programs and delay discretionary redesign work. Companies need low-drag designs for newer drivetrains and replacement-compatible units for machinery that cannot justify broader shaft or housing redesign.
- Japanese vehicle programs place tight limits on package size and rotational losses during qualification for new and replacement drivetrain parts. METI reported in February 2026 that drive, transmission and control parts were among the main contributors to an 8.8% monthly rise in motor-vehicle industry shipments during January. Japan is estimated to post 4.0% CAGR over the forecast period, supported by selective replacement and tightly engineered drivetrain specifications. Mature installed equipment supplies recurring service work but unfamiliar one-way components can require longer review against fixed shafts and housings. Companies need low-loss designs plus dimensional support that proves interchangeability before installation under fixed production restart deadlines for conveyor gearbox assets and vehicle programs.
Who are the notable companies in the Overrunning Clutches Market?
Schaeffler AG, BorgWarner Inc., NTN Corporation, NSK Ltd., JTEKT Corporation, The Timken Company, Formsprag Clutch (Regal Rexnord), Stieber Clutch (Regal Rexnord), RINGSPANN GmbH and SKF serve relevant automotive or industrial motion applications.
NSK Ltd. and BorgWarner Inc. participate directly through NSK-Warner while Formsprag Clutch and Stieber Clutch operate as Regal Rexnord freewheel brands. RINGSPANN GmbH specializes in industrial overrunning while the remaining listed groups contribute drivetrain or adjacent motion-component roles.
- Automotive clutch participation centers on BorgWarner Inc. and NSK Ltd. through their jointly owned NSK-Warner business.
- Industrial motion coverage includes NTN Corporation and SKF with The Timken Company serving broader rotating-equipment channels.
- Industrial freewheel specialists include Formsprag Clutch and Stieber Clutch under Regal Rexnord alongside RINGSPANN GmbH.
Competitive Benchmarking: Overrunning Clutches Market
| Company | One-way clutch breadth | Automotive integration | Industrial application coverage | Geographic Reach |
|---|---|---|---|---|
| Schaeffler AG | Medium | High | Medium | Global |
| BorgWarner Inc. | High | High | Low | Global automotive network |
| NTN Corporation | Medium | Medium | Medium | Global |
| NSK Ltd. | High | High | Medium | Global |
| JTEKT Corporation | Medium | Medium | Medium | Global |
| The Timken Company | Low | Low | Medium | Global industrial network |
| Formsprag Clutch (Regal Rexnord) | High | Medium | High | Global through Regal Rexnord |
| Stieber Clutch (Regal Rexnord) | High | Low | High | Europe-centered with international distribution |
| RINGSPANN GmbH | High | Medium | High | Europe, Asia and Americas |
| SKF | Low | Medium | Medium | Global |
Benchmark ratings use documented current evidence rather than company size or reputation. One-way clutch breadth scores High for three documented architectures, Medium for two roles and Low for one narrow role. Automotive and industrial scores require direct drivetrain or overrunning evidence while Geographic Reach records the published operating footprint.
Key Developments in the Overrunning Clutches Market
- In March 2026, RINGSPANN GmbH documented a parcel-conveyor freewheel that replaced legacy band brakes with maintenance-free backstopping.
- In May 2026, BorgWarner Inc. won an Asian wet dual-clutch program for a Chinese SUV entering production during 2026.
- In April 2026, Schaeffler AG announced 2026 volume production for its MultiMode hybrid transmission serving electric and hybrid driving modes.
Key Players in the Overrunning Clutches Market
Automotive Drivetrain and Clutch Engineering
- Schaeffler AG
- BorgWarner Inc.
- NSK Ltd.
- JTEKT Corporation
Motion Component and Service Networks
- NTN Corporation
- The Timken Company
- SKF
Industrial Overrunning and Backstop Specialists
- Formsprag Clutch (Regal Rexnord)
- Stieber Clutch (Regal Rexnord)
- RINGSPANN GmbH
Overrunning Clutches Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By clutch type, application, end use, sales channel, torque class and region. |
| Quantitative Units | USD billion. |
| Market Definition | Commercial sales of overrunning clutches that transmit torque in one direction and freewheel in the opposite direction within qualified vehicle and industrial applications. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific and Middle East and Africa. |
| Countries Covered | Mexico, South Korea, Brazil, USA, Germany, France, Japan, and additional countries included in the full report. |
| Key Companies | Schaeffler AG, BorgWarner Inc., NTN Corporation, NSK Ltd., JTEKT Corporation, The Timken Company, Formsprag Clutch (Regal Rexnord), Stieber Clutch (Regal Rexnord), RINGSPANN GmbH, SKF. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Overrunning Clutches Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Overrunning Clutches Market by Segments
Overrunning Clutches Market segmented by Clutch Type:
- Sprag clutches
- Roller ramp clutches
- Cam clutches
- One-way bearing clutches
- Integrated overrunning units
Overrunning Clutches Market segmented by Application:
- Starter drives
- Conveyors - indexing
- Transmission systems
- Pulleys - accessory drives
- Industrial machinery
Overrunning Clutches Market segmented by End Use:
- Automotive
- Industrial machinery
- Mining - conveying
- Powersports
- Aerospace - defense
Overrunning Clutches Market segmented by Sales Channel:
- OEM direct
- Industrial distributors
- Aftermarket replacement
- MRO - service
Overrunning Clutches Market segmented by Torque Class:
- Medium duty
- Light duty
- Heavy duty
- High-speed precision
Overrunning Clutches Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- RINGSPANN GmbH. (2026, September 1). Many key components from a single source.
- Office for National Statistics. (2026, March 13). Index of Production, UK: January 2026.
- NSK Ltd.. (2025, October 20). NSK-Warner Introduces New Electrical Bypass Plate Delivering Both Electrical Conductivity and Space Efficiency at World-Class Levels.
- Council of the European Union. (2026, June 25). Council Regulation (EU) 2026/1463 of 25 June 2026 amending Regulation (EU) 2021/2278.
- BorgWarner Inc.. (2025, May 6). BorgWarner Secures Two Dual-Clutch Programs in China.
- NTN Corporation. (2025, May 30). NTN Begins Providing Bearing Data to “KISSsoft” a Design Analysis Software for Gearboxes.
- JTEKT Corporation. (2025, April 8). Development of JTEKT Integrated Gear Bearing (JIGB).
- RINGSPANN GmbH. (2026, April 29). From raw material extraction to bulk material.
- RINGSPANN GmbH. (2025, June 23). Identical twin for industrial drives.
- RINGSPANN GmbH. (2025, December 15). High speeds with a new test bench.
- Secretaría de Economía, Data México. (n.d.). Clutches and Shaft Couplings, Incl. Universal Joints, for Machines: Commercial exchange, international imports and exports, market and specialization. Retrieved September 14, 2026.
- Ministry of Trade, Industry and Resources, Republic of Korea. (2026, February 19). January 2026 Automobile Exports Reach $6.1 Billion, Second-Highest January on Record.
- ANFAVEA. (2026, January 15). Produção e venda de autoveículos crescem em 2025 e Anfavea projeta nova alta em 2026.
- Board of Governors of the Federal Reserve System. (2026, August 18). Industrial Production and Capacity Utilization - G.17, Table 3 Motor Vehicle Assemblies.
- German Association of the Automotive Industry (VDA). (2026, January 5). Passenger car production in 2025 slightly above previous year's level.
- INSEE. (2026, March 27). Automotive industry: production of electric vehicles at French sites is ramping up and improving the external balance.
- Ministry of Economy, Trade and Industry, Japan. (2026, February 27). 1月の鉱工業生産は、自動車工業やプラスチック製品工業などが上昇したことから、全体として前月比2.2%と、3か月ぶりの上昇。基調判断は、「一進一退」に据え置き。.
- NSK-Warner K.K. (n.d.). Corporate Profile. Retrieved September 14, 2026.
- Stieber Clutch. (n.d.). About Stieber Clutch. Retrieved September 14, 2026.
- Stieber Clutch. (n.d.). Stieber Quality. Retrieved September 14, 2026.
- RINGSPANN GmbH. (2026, March 23). Lifting and moving valuable goods safely.
- BorgWarner Inc. (2026, May 6). BorgWarner Wins Two Conquest Awards in Asia for Combustion and Hybrid Powertrain Programs.
- Schaeffler AG. (2026, April 27). Not just a bridging technology: Schaeffler offers extensive range from components to systems for all hybrid powertrains.
- BorgWarner Inc. (2026, August 4). BorgWarner Wins Major Program with Next Generation Integrated Drive Module Technology.
- NTN Corporation. (2026, August 31). NTN Develops CVJ Analysis Technology for Highly Accurate Prediction of Vehicle Vibrations.
- Schaeffler AG. (2026, September 8). Schaeffler launches major aftermarket brand transformation.
- JTEKT Corporation. (2026, August 3). Concerning Completion of the Transfer of the European Automotive Business.
- The Timken Company. (2026, March 18). Timken Broadens Automated Lubrication Systems Capabilities with Acquisition of Bijur Delimon.
- Schaeffler AG. (2026, July 8). Integrated Portfolio and Smart Solutions: Schaeffler Vehicle Lifetime Solutions paves the way for greater efficiency and reduced complexity.
- BorgWarner Inc. (2026, July 24). BorgWarner Secures Motorcycle Dual-Clutch Transmission Program in China.
- NTN Corporation. (2025, December 17). Contributing to Further Energy Efficiency of Automobiles! NTN Develops High-Accuracy Bearing Torque Calculation Method.
- NSK Ltd. (2025, March 26). NSK Develops Compact, Lightweight Deep Groove Ball Bearing for EVs: Helping to Reduce EV Drive Unit Size, Weight, and Electricity Consumption.
- JTEKT Corporation. (2025, December 1). Establishment of New Sales Bases in Vietnam to Strengthen the Aftermarket Business.
- The Timken Company. (2025, July 2). Built for Customers: Inside Timken’s Product Pipeline.
- SGS North America Inc. (2026, May 2). Certificate US97/0823.
- Regal Rexnord Corporation. (2026, February 20). Annual Report on Form 10-K for the year ended December 31, 2025.
- RINGSPANN GmbH. (2026, January 15). On course for growth with a complete range of couplings.
- SKF. (2026, February 26). SKF announces the future name of the Automotive business: SKF Vertevo.
- NSK-Warner K.K. (n.d.). Overseas Group Companies. Retrieved September 14, 2026.
- RINGSPANN GmbH. (n.d.). RINGSPANN Companies. Retrieved September 14, 2026.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- What are the 2026 and 2036 overrunning clutches market values?
- What sustains one-direction torque control?
- Why do sprag clutches hold 32.0%?
- Why do starter drives hold 26.0% application share?
- Why does automotive hold 35.0% end-use share?
- How do the seven country CAGRs compare?
- Which companies serve vehicle and industrial clutch applications?
- What delays clutch replacement qualification?
Frequently Asked Questions
How big is the Overrunning Clutches Market in 2026?
The overrunning clutches market is valued at USD 7.9 billion in 2026 and is projected to reach USD 12.7 billion by 2036. Vehicle and industrial systems support specification and replacement demand for passive one-direction torque control.
What is the CAGR of the Overrunning Clutches Market from 2026 to 2036?
The overrunning clutches market is projected to grow at a CAGR of 4.9% between 2026 and 2036. Vehicle drivetrain programs and industrial equipment support demand for passive overrunning or backstopping functions in rotating systems.
Which clutch type leads the Overrunning Clutches Market?
Sprag clutches are expected to hold 32.0% of the overrunning clutches market in 2026, attributable to compact torque density and rapid engagement. Their geometry fits vehicle and industrial packages requiring automatic switching between locked and freewheel states.
Which application leads the Overrunning Clutches Market?
Starter drives are expected to hold 26.0% of the overrunning clutches market in 2026, driven by automatic disengagement after engine speed overtakes starter speed. Automatic release protects starting components without requiring separate active switching hardware inside the qualified starter system.
Which companies are active in the Overrunning Clutches Market?
Key companies include Schaeffler AG and BorgWarner Inc. alongside NTN Corporation and NSK Ltd. as well as JTEKT Corporation and The Timken Company. Formsprag Clutch (Regal Rexnord) and Stieber Clutch (Regal Rexnord) join RINGSPANN GmbH and SKF in industrial or replacement applications.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Clutch Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Clutch Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Clutch Type, 2026 to 2036
- Sprag clutches
- Roller ramp clutches
- Cam clutches
- One-way bearing clutches
- Integrated overrunning units
- Sprag clutches
- Y-o-Y Growth Trend Analysis By Clutch Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Clutch Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Starter drives
- Conveyors/indexing
- Transmission systems
- Pulleys/accessory drives
- Industrial machinery
- Starter drives
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Automotive
- Industrial machinery
- Mining/conveying
- Powersports
- Aerospace/defense
- Automotive
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- OEM direct
- Industrial distributors
- Aftermarket replacement
- MRO/service
- OEM direct
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Torque Class, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Torque Class, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Torque Class, 2026 to 2036
- Medium duty
- Light duty
- Heavy duty
- High-speed precision
- Medium duty
- Y-o-Y Growth Trend Analysis By Torque Class, 2021 to 2025
- Absolute $ Opportunity Analysis By Torque Class, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- By Country
- Market Attractiveness Analysis
- By Country
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- By Country
- Market Attractiveness Analysis
- By Country
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- By Country
- Market Attractiveness Analysis
- By Country
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- By Country
- Market Attractiveness Analysis
- By Country
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- By Country
- Market Attractiveness Analysis
- By Country
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- By Country
- Market Attractiveness Analysis
- By Country
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- By Country
- Market Attractiveness Analysis
- By Country
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Clutch Type
- By Application
- By End Use
- By Sales Channel
- By Torque Class
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Schaeffler
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- BorgWarner
- NTN
- NSK
- JTEKT
- Timken
- Formsprag / Regal Rexnord
- Stieber Clutch
- Ringspann
- SKF
- Schaeffler
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


