

- Market Size (2026)
- USD 24.0 Bn
- Forecast (2036)
- USD 37.6 Bn
- CAGR (2026 to 2036)
- 4.6%
How big is Packing Boxes Market in 2026?
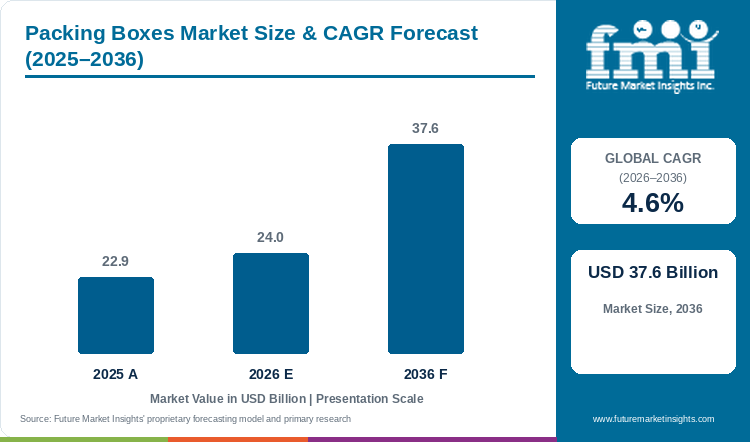
Demand for packing boxes is projected to expand at 4.6% CAGR between 2026 and 2036. Industry value grows from USD 22.9 billion in 2025 to USD 24.0 billion in 2026 and is projected to reach USD 37.6 billion by 2036.
Expanding parcel logistics and stricter corporate secondary packaging reduction goals are compelling supply chain managers to replace oversized shipping cases with right-sized cartons. Global packing boxes valuation expands from USD 22.9 billion in 2025 to USD 24.0 billion in 2026, and is projected to advance at a 4.6% CAGR through 2036 to attain USD 37.6 billion, generating USD 13.6 billion in added market opportunity. In March 2026, the U.S. Census Bureau reported that domestic annual retail e-commerce sales reached USD 1,233.7 billion in 2025, an increase of 5.4% over 2024, driving sustained baseline demand for transit shipping cases and shelf-ready displays [1]. Folding cartons and trays lead the product format category with a 32.0% share in 2026 because pre-creased flat delivery minimizes plant storage footprint prior to filling. Growth across profiled countries spans 3.7% in Canada to 5.6% in Austria, though paperboard price volatility and barrier chemistry qualification continue to shape converter gross margins.
Key Market Trends & Insights
- By product format / style: Folding cartons and trays lead with 32.0% share in 2026, supported by flat shipment and automated line erecting.
- By material substrate: Virgin chemical kraft pulp accounts for 38.5% in 2026, owing to predictable compression and burst strength.
- By end-use application: Fresh produce and meat packaging holds 36.5% in 2026, driven by cold-chain moisture and ventilation requirements.
- By barrier / coating property: Aqueous water-based barriers represent 50.7% in 2026, enabled by grease protection and repulpability compliance.
- Austria records 5.6% CAGR and Finland records 5.2% CAGR from 2026 to 2036, leading evaluated regional expansion paths.
- A few notable companies covered in the report include International Paper, Smurfit Westrock plc, Mondi plc, Graphic Packaging Holding Company, Packaging Corporation of America, Stora Enso Oyj, Mayr-Melnhof Karton AG, Oji Holdings Corporation, Rengo Co., Ltd., and Sonoco Products Company.
Regional Highlights
- Fastest-growing evaluated country: Austria, at 5.6% CAGR from 2026 to 2036.
- By country: Finland at 5.2%, Sweden at 4.8%, and the USA at 4.4% follow, while Germany records 4.0% and Canada records 3.7%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Packing Boxes Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 22.9 billion |
| Estimated Market Size in 2026 | USD 24.0 billion |
| Projected Market Size by 2036 | USD 37.6 billion |
| CAGR, 2026 to 2036 | 4.6% |
| Added Revenue, 2026 to 2036 | USD 13.6 billion |
Regional adoption develops differently across packaging formats because statutory waste targets and fiber collection efficiencies differ across markets. In January 2025, the European Parliament and Council enacted Regulation (EU) 2025/40 on packaging and packaging waste, establishing mandatory recyclability assessment protocols and maximum empty-space ratios across member states [2]. Procurement directors are auditing transit container dimensions and barrier coatings against automated sorting infrared systems, steering demand toward mono-material paper structures.
Volume and Revenue Bridge
Table 2: Revenue Bridge for the Packing Boxes Market (USD billion and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size | 22.9 | 24.0 | 37.6 |
| Index, 2025 = 100 | 100.0 | 104.8 | 164.2 |
| Forecast CAGR | - | 4.6% | 4.6% |
Calculation basis: The index applies the given market values. Index values derive from the stated market sizes for 2025, 2026, and 2036.
Per Capita and Commercial Sizing
Table 3: Per Capita Revenue Indicators for the Packing Boxes Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 2.78 | 2.89 | 4.20 |
| Spend per 1,000 people (USD) | 2,782 | 2,892 | 4,201 |
Table 4: Segment Revenue Indicators for the Packing Boxes Market (USD billion and percentages), 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 24.0 billion | Report value |
| Folding cartons and trays revenue | USD 7.7 billion | 32.0% share |
| Virgin chemical kraft pulp revenue | USD 9.2 billion | 38.5% share |
| Fresh produce and meat packaging revenue | USD 8.8 billion | 36.5% share |
Analyst Perspective
"Box procurement is shifting from raw board volume toward measured structural performance per shipment. Converters combining recyclable barrier coatings with automated right-sized box machinery will secure long-term fulfillment contracts."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the packing boxes market segmented?
The packing boxes market is segmented across four primary commercial axes and region: product format / style, material substrate, end-use application, and barrier / coating property. In 2026, folding cartons and trays are projected to hold 32.0% of product format revenue, virgin chemical kraft pulp 38.5% of material substrate, fresh produce and meat packaging 36.5% of end-use application, and aqueous water-based barriers 50.7% of barrier / coating property.
By product format / style: Folding cartons and trays, Rigid set-up boxes, Corrugated containers, Custom die-cut formats.
By material substrate: Virgin chemical kraft pulp, Recycled fluting and testliner, Barrier-coated solid bleached board, Molded fiber and specialty paperboard.
By end-use application: Fresh produce and meat packaging, Dry food and confectionery, E-commerce shipping and logistics, Consumer electronics and goods.
By barrier / coating property: Aqueous water-based barrier, PLA and bio-wax coating, Standard uncoated recyclable, Dispersion-coated grease barrier.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do Folding Cartons and Trays Lead the Product Format Category?
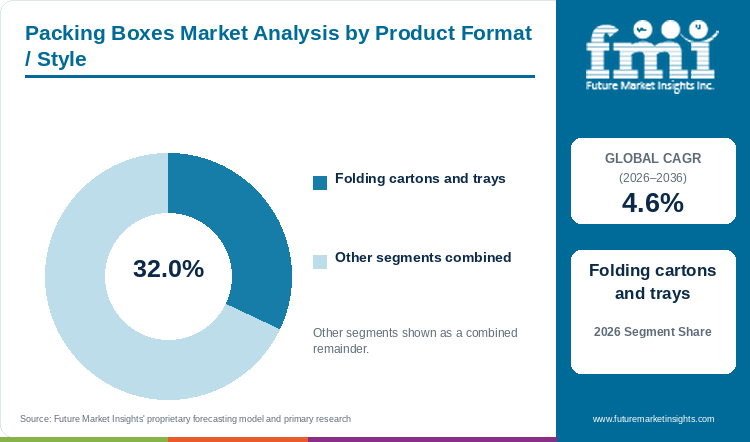
Folding cartons and trays are expected to hold 32.0% of product format revenue in 2026, supported by flat shipment logistics and automated packing line compatibility.
Table 5: Product Format Share for the Packing Boxes Market (percentage share), 2026
| Product Format / Style | Share (2026) |
|---|---|
| Folding cartons and trays | 32.0% |
| Other segments combined | 68.0%* |
| Total | 100.0% |
*Calculated as the balance after deducting the leading segment's reported share from 100.0%.
Table 6: Product Format Leadership and Market Growth for the Packing Boxes Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR | 4.6% |
| Leading segment | Folding cartons and trays |
Folding cartons and trays dominate consumer packaging formats because pre-glued blanks ship completely flat, minimizing warehouse storage volume until automated erecting machinery forms each box. Converters specializing in folding carton and paperboard packaging print high-resolution branding graphics directly onto the board surface, eliminating secondary labelling operations. In October 2025, Eurostat confirmed that paper and cardboard packaging represented 40.4% of total EU packaging waste generation, driving demand for easily recyclable cartonboard designs [3]. Food and household goods manufacturers favor folding cartons for high-speed cartoning lines operating above 300 units per minute.
- Folding cartons and trays represent 32.0% of product format / style in 2026, supported by automated packing and print quality.
- In October 2025, Eurostat reported that paper and cardboard represented 40.4% of EU packaging waste generated in 2023, making recovery compatibility a primary commercial buying condition [3].
What Supports Virgin Chemical Kraft Pulp as a Preferred Material Substrate?
Virgin chemical kraft pulp is estimated to account for 38.5% of material substrate demand in 2026, reflecting high tensile fiber strength and stacking compression resilience.
Virgin chemical kraft pulp leads substrate consumption because unbleached and bleached kraft liners maintain superior ring crush and Mullen burst strength compared to recycled fibers. In industrial kraft paper converting, virgin long softwood fibers resist tearing when creased and folded on high-speed folder-gluers. In August 2026, the U.S. Census Bureau reported second-quarter adjusted e-commerce sales of USD 340.2 billion, up 12.2% year over year, reinforcing high-compression shipping box procurement [4]. Heavy transit cases utilize virgin kraft outer plies to prevent pallet stack collapse in multi-tier warehouse storage.
- Virgin chemical kraft pulp accounts for 38.5% of material substrate in 2026, owing to predictable compression and burst strength.
- In August 2026, the U.S. Census Bureau reported USD 340.2 billion in adjusted retail e-commerce sales for the second quarter of 2026, supporting steady corrugated case demand [4].
How Does Fresh Produce and Meat Packaging Anchor End-Use Demand?
Fresh produce and meat packaging is projected to capture 36.5% of end-use demand in 2026, driven by cold-chain moisture exposure and ventilated transit requirements.
Agricultural growers and protein processors require specialized moisture-resistant corrugated boxes to transport chilled goods without wall softening. In paper-based frozen food packaging, ventilated die-cut trays allow rapid forced-air precooling and moisture drainage during refrigerated transit. In 2025, the Paperboard Packaging Council published market indicators showing cartonboard cost increases of 4.4% annually, highlighting the need for efficient material utilization [5]. Meat packers specify water-resistant adhesive bonds to ensure cartons endure wet processing floor conditions without delaminating.
- Fresh produce and meat packaging holds 36.5% of end-use application in 2026, driven by cold-chain moisture and ventilation needs.
- In 2025, the Paperboard Packaging Council reported that cartonboard costs rose 4.4% annually from 2014 to 2024, prompting converters to optimize fiber weight [5].
Why are Buyers Selecting Aqueous Water-Based Barriers within Coating Specifications?
Aqueous water-based barriers are anticipated to command 50.7% of coating demand in 2026, owing to effective grease resistance and verified paper-mill repulpability.
Packaging specifiers are actively replacing traditional polyethylene extrusion and wax coatings with water-based polymer dispersions that repulp cleanly in standard paper recycling mills. In sustainable packaging applications, aqueous barrier coatings provide oil, grease, and moisture vapor resistance while maintaining full recyclability under EN 13430 standards. In February 2025, Huhtamaki introduced its ProDairy packaging range featuring less than 10% plastic content to verify mill repulpability [6]. Commercial box converters apply aqueous dispersion coatings on flexo press units, reducing coating line turnaround times.
- Aqueous water-based barriers represent 50.7% of coating demand in 2026, enabled by grease protection and fiber-recovery compatibility.
- In February 2025, Huhtamaki launched ProDairy packaging featuring less than 10% plastic content across the range to confirm recyclability in paper streams [6].
What are the drivers, restraints, and opportunities in the packing boxes market?
In the packing boxes market, e-commerce order expansion drives case volume, raw fiber and energy price volatility squeezes converter margins, and right-sized automated box structures create substantial material savings through 2036.
- Driver: Parcel fulfillment orders and food shipments increase the recurring number of boxes required per logistics transaction.
- Restraint: Board, energy, and starch adhesive cost volatility can reset faster than contracted annual box supply agreements.
- Opportunity: Right-sized box erecting automation and recyclable barrier coatings reduce fiber consumption while protecting distribution performance.
Parcel Fulfillment Expansion Anchors Recurring Case Demand
The global proliferation of omni-channel retail distribution requires automated fulfillment centers to stock diverse case footprints to protect individual shipments. In e-commerce packaging, corrugated boxes serve as the primary protective vehicle preventing product damage during transit across parcel sorting hubs. Regional sheet plants benefit from ongoing retailer optimization of custom box dimensions, shorter turnaround fulfillment contracts, and reverse logistics returns handling.
Containerboard Price Volatility and Margin Friction Constrain Converters
Wholesale box plants operate in a capital-intensive environment where raw paperboard constitutes up to 60% of total box conversion expense. In paper and paperboard packaging, sudden shifts in energy tariffs and recovered old corrugated container collection costs quickly squeeze gross margins when contract price adjustments lag quarterly indices. Converters counter this by rationalizing board trim and downgauging fluting profiles.
Right-Sized Box Systems and Water-Based Barrier Coatings Unlock Value
Fulfillment operations are deploying automated on-demand 3D box-making equipment that cuts and creases custom corrugated cases around exact product dimensions in real time. Deploying advanced protective packaging automation eliminates internal void-fill materials and lowers dimensional parcel shipping surcharges, delivering quantifiable cost reductions for high-volume logistics shippers.
Packing Boxes Market by Country (2026 to 2036)
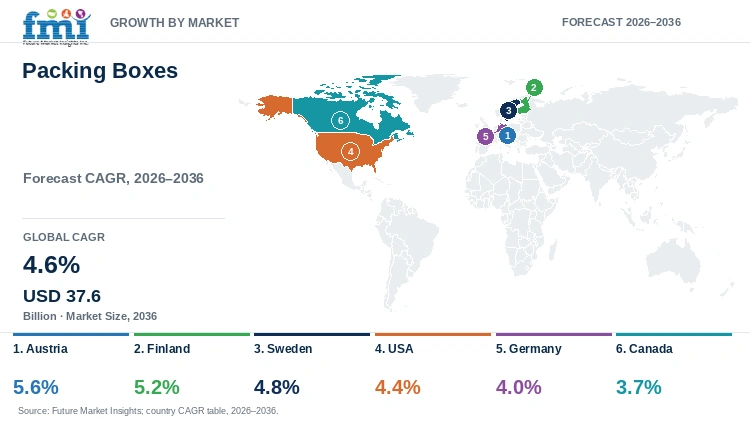
As per Future Market Insights analysis, Austria records a 5.6% CAGR and Finland records a 5.2% CAGR among the six evaluated countries, while Canada registers 3.7% CAGR over the assessment period. Commercial performance across covered countries depends on recovery infrastructure scale, parcel fulfillment growth, regional forest asset integration, and converter ability to manage automated short production runs.
Table 7: Country CAGR and Primary Growth Levers for the Packing Boxes Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Austria | 5.6% | circular material targets and export redesign |
| Finland | 5.2% | forest-products base and export conversion |
| Sweden | 4.8% | producer responsibility and plastic substitution |
| USA | 4.4% | e-commerce scale and regional sheet plants |
| Germany | 4.0% | high paper recovery and PPWR redesign |
| Canada | 3.7% | retail growth and long distribution routes |
Source: Future Market Insights analysis
Austria Packing Boxes Market Outlook (2026 to 2036)
Binding national circular economy mandates and export-oriented industrial manufacturing drive packaging redesign across Austria. In corrugated boxes, Austrian converters engineer lightweight, high-strength cases for export food and machinery sectors. In 2026, Statistics Austria published circular economy indicators showing a domestic circular material use rate of 13.8%, progressing toward the 18% national target for 2030 [7]. High energy and conversion labor expenses represent the primary operational bottleneck for domestic box plants. Converters mitigate this by deploying digital printing and standardized sheet sizes that minimize production changeover scrap.
Key takeaway: In Austria, binding circular material targets push exporters toward recyclable lightweight corrugated and cartonboard boxes.
Finland Packing Boxes Market Outlook (2026 to 2036)
Extensive forest resources and integrated pulp and paperboard mills provide Finland with direct access to high-yield chemical pulps and containerboard grades. In 2025, Statistics Finland recorded a national population of approximately 5.6 million residents, limiting domestic consumption volume [8]. Finnish packaging corporations such as Stora Enso focus on exporting high-value barrier-coated solid bleached boards and micro-flute packaging to European consumer markets. High reliance on export freight tariffs represents the main commercial friction, which mills offset through continuous fiber optimization.
Key takeaway: In Finland, forest-products integration allows domestic mills to manufacture high-yield lightweight packaging grades for European export.
Sweden Packing Boxes Market Outlook (2026 to 2036)
Stringent producer responsibility regulations and corporate plastic replacement initiatives accelerate fiber packaging adoption across Sweden. In corrugated packaging, Swedish converters collaborate with brand owners to replace single-use plastic containers with recyclable corrugated trays. In January 2025, the Swedish Environmental Protection Agency reiterated national reduction targets for single-use plastic food packaging by 2026, boosting demand for coated carton alternatives [9]. Strict repulpability testing remains a technical requirement that converters satisfy using certified water-based barrier coatings.
Key takeaway: In Sweden, statutory plastic reduction targets and producer responsibility fees reward documented fiber-box recyclability.
USA Packing Boxes Market Outlook (2026 to 2036)
Tremendous e-commerce parcel volume and nationwide food processing infrastructure establish the United States as a massive consumer of corrugated shipping cases. In commercial paper packaging, regional sheet plants supply fulfillment centers with customized RSC and die-cut containers. In 2025, the U.S. Environmental Protection Agency documented that paper and paperboard packaging represents the single largest recycled material category in municipal solid waste, confirming mature recovery networks [12]. Elevated transportation expenses for shipping empty boxes across long distances create margin friction, which converters resolve by establishing decentralized sheet plants near major logistics corridors.
Key takeaway: In the USA, extensive parcel fulfillment networks reward decentralized sheet plants that reduce empty-box freight and eliminate void fill.
Germany Packing Boxes Market Outlook (2026 to 2036)
Germany combines heavy industrial export shipping with sophisticated municipal paper recovery systems operating across all federal states. In February 2026, Destatis reported that 1.985 million tonnes of paper, paperboard, and carton packaging entered disposal channels in 2024, with 1.841 million tonnes successfully routed into industrial recycling streams [10]. High energy tariffs and strict workplace emission regulations raise converting operational expenses. Major integrated groups like Smurfit Westrock and Mondi invest in energy-efficient corrugator steam systems and mono-material water coatings to lower conversion overhead.
Key takeaway: In Germany, exceptionally high paper recycling recovery rates favor mono-material coated boxes that simplify optical waste sorting.
Canada Packing Boxes Market Outlook (2026 to 2036)
Long inter-provincial freight corridors and dispersed retail distribution hubs require Canadian corrugated containers to maintain exceptional compression strength under variable temperatures. In February 2026, Statistics Canada reported retail sales reached USD 70.0 billion in December 2025, with annual retail turnover advancing 4.0% [11]. Cold winter transit conditions cause standard adhesive bonds to embrittle. Canadian converters formulate specialized cold-resistant starches and pair heavy fluting with virgin kraft liners to guarantee box integrity across transcontinental rail distribution.
Key takeaway: In Canada, vast distribution distances and winter cold-chain conditions favor standardized heavy-duty corrugated cases that prevent pallet crushing.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the packing boxes market?
International Paper, Smurfit Westrock plc, Mondi plc, Graphic Packaging Holding Company, Packaging Corporation of America, Stora Enso Oyj, Mayr-Melnhof Karton AG, Oji Holdings Corporation, Rengo Co., Ltd., and Sonoco Products Company are significant market players in this market.
FMI research indicates that competition divides between fully integrated forest-products corporations and specialized regional converting operations. Integrated paper groups control vast timberland, containerboard mills, and corrugating plants, allowing them to optimize fiber costs across multi-country supply networks. In contrast, independent sheet plants differentiate through rapid order turnaround, custom short runs, and specialized structural design services for local e-commerce shippers.
- Integrated corrugated groups: International Paper, Smurfit Westrock, Mondi, Packaging Corporation of America, and Rengo control integrated containerboard mills and box converting assets.
- Folding-carton and paperboard specialists: Graphic Packaging Holding Company and Mayr-Melnhof Karton focus on high-graphic folding cartons for food and beverage retail.
- Fiber, tube, and specialty platforms: Stora Enso, Oji Holdings, and Sonoco deliver specialized industrial board, protective inserts, and sustainable barrier cartons.
Competitive Benchmarking: Packing Boxes Market
Table 8: Competitive Benchmarking for the Packing Boxes Market (qualitative capability ratings), 2026
| Company | Format Breadth | Fiber Integration | Food / E-commerce Access | Geographic Reach |
|---|---|---|---|---|
| International Paper | High | High | High | High |
| Smurfit Westrock plc | High | High | High | High |
| Mondi plc | High | High | High | High |
| Graphic Packaging Holding Company | High | Medium | High | Medium |
| Packaging Corporation of America | High | High | High | Medium |
| Stora Enso Oyj | High | High | High | High |
| Mayr-Melnhof Karton AG | Medium | Medium | High | Medium |
| Oji Holdings Corporation | Medium | High | Medium | High |
| Rengo Co., Ltd. | Medium | Medium | Medium | Medium |
| Sonoco Products Company | Medium | Medium | Medium | Medium |
Scoring basis: High indicates broad documented capability, current commercial activity, and multi-region manufacturing reach. Medium indicates established operational presence with focused regional strength. Ratings describe public evidence breadth and do not rank product quality or commercial market share.
Key Developments in the Packing Boxes Market
- In September 2026, Smurfit Westrock agreed to acquire CMPC's containerboard and corrugated operations in Chile for USD 420 million, adding one containerboard mill, three corrugated converting plants, and a molded tray facility [13].
- In March 2026, Smurfit Westrock completed the acquisition of Cartomanabí assets in Ecuador, adding more than 50,000 tonnes of annual corrugated containerboard capacity [14].
- In April 2025, Mondi finalized the acquisition of Schumacher Packaging's Western Europe converting operations, adding more than 1 billion square meters of box converting capacity across Germany, the UK, and Benelux [15].
Key Players in the Packing Boxes Market
Integrated Corrugated and Containerboard Groups
- International Paper
- Smurfit Westrock plc
- Mondi plc
- Packaging Corporation of America
Folding Carton and Paperboard Specialists
- Graphic Packaging Holding Company
- Mayr-Melnhof Karton AG
- Stora Enso Oyj
Regional and Industrial Paper Packaging Platforms
- Oji Holdings Corporation
- Rengo Co., Ltd.
- Sonoco Products Company
Packing Boxes Market - Report Scope
Table 9: Report Scope for the Packing Boxes Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Format / Style; Material Substrate; End-Use Application; Barrier / Coating Property |
| Quantitative Units | USD Billion |
| Market Definition | Includes supplier revenue from corrugated containers, folding cartons, rigid set-up boxes, custom die-cut boxes, and in-scope fiber formats. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Austria, Finland, Sweden, USA, Germany, Canada, and additional countries in the full report |
| Key Companies Covered | International Paper, Smurfit Westrock plc, Mondi plc, Graphic Packaging Holding Company, Packaging Corporation of America, Stora Enso Oyj, Mayr-Melnhof Karton AG, Oji Holdings Corporation, Rengo Co., Ltd., Sonoco Products Company |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with data triangulation. |
Packing Boxes Market - Research Methodology
Table 10: Research Methodology for the Packing Boxes Market, 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with manufacturers, suppliers, distributors, procurement teams, converters, end users, and industry experts to validate purchasing decisions, performance requirements, and demand conditions. |
| Secondary Research | Secondary research included annual reports, investor presentations, regulatory publications, industry associations, technical papers, trade journals, company websites, product literature, and public data. |
| Market Sizing and Forecasting | Top-down and bottom-up approaches assessed volume demand, price points, segment mix, and country adoption for 2026 to 2036. |
| Data Triangulation and Validation | Data was validated against macroeconomic indicators, packaging regulation, e-commerce activity, recovery systems, company developments, and historical trends without double counting adjacent categories. |
Segment shares and forecast estimates are proprietary analytical estimates. They are not government statistics or direct measurements of global market share.
Packing Boxes Market by Segments
Packing Boxes Market segmented by Product Format / Style:
- Folding cartons and trays
- Rigid set-up boxes
- Corrugated containers
- Custom die-cut formats
Packing Boxes Market segmented by Material Substrate:
- Virgin chemical kraft pulp
- Recycled fluting and testliner
- Barrier-coated solid bleached board
- Molded fiber and specialty paperboard
Packing Boxes Market segmented by End-Use Application:
- Fresh produce and meat packaging
- Dry food and confectionery
- E-commerce shipping and logistics
- Consumer electronics and goods
Packing Boxes Market segmented by Barrier / Coating Property:
- Aqueous water-based barrier
- PLA and bio-wax coating
- Standard uncoated recyclable
- Dispersion-coated grease barrier
Packing Boxes Market by Region
- North America
- United States
- Canada.
- Latin America
- Brazil
- Mexico
- Argentina
- Chile.
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Austria
- Finland
- Sweden.
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary.
- East Asia
- Japan
- South Korea.
- South Asia and Pacific
- ASEAN
- Australia and New Zealand.
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel.
Research Sources and Bibliography
- [1] U.S. Census Bureau. (2026, March 10). Quarterly retail e-commerce sales, fourth quarter 2025. U.S. Census Bureau.
- [2] European Parliament and Council. (2025, January 22). Regulation (EU) 2025/40 on packaging and packaging waste. EUR-Lex.
- [3] Eurostat. (2025, October 14). Packaging waste statistics: Paper and cardboard share of EU packaging waste. Eurostat.
- [4] U.S. Census Bureau. (2026, August 18). Quarterly retail e-commerce sales, second quarter 2026. U.S. Census Bureau.
- [5] Paperboard Packaging Council. (2025). Industry outlook and market data report 2025-26. Paperboard Packaging Council.
- [6] Huhtamaki Oyj. (2025, February 28). Huhtamaki launches recyclable single-coated paper cups for yogurt and dairy. Huhtamaki press release.
- [7] Statistics Austria. (2026). Circular economy and circular material use rate. Statistics Austria.
- [8] Statistics Finland. (2025). Finland in figures 2025. Statistics Finland.
- [9] Swedish Environmental Protection Agency. (2025, January 9). Support and information for producers of packaging. Swedish EPA.
- [10] Federal Statistical Office of Germany. (2026, February 23). Type, quantity and destination of disposed packaging. Destatis.
- [11] Statistics Canada. (2026, February 20). Retail trade, December 2025. Statistics Canada.
- [12] U.S. Environmental Protection Agency. (2025). Advancing sustainable materials management: Facts and figures fact sheet. U.S. EPA.
- [13] Smurfit Westrock. (2026, September 23). Agreement to acquire CMPC containerboard and corrugated business in Chile. Smurfit Westrock press release.
- [14] Smurfit Westrock. (2026, March 3). Smurfit Westrock expands its presence in Ecuador. Smurfit Westrock press release.
- [15] Mondi. (2025, April 1). Mondi completes acquisition of Schumacher Packaging Western Europe operations. Mondi press release.
- This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the packing boxes market in 2026 and 2036?
- Which demand conditions support recurring purchases of packing boxes?
- Why do folding cartons and trays lead product format demand?
- How does virgin chemical kraft pulp support box performance?
- Which country has a notable packing boxes growth outlook?
- Which companies compete in corrugated and folding-carton supply?
Frequently Asked Questions
How big is the packing boxes market in 2026, and what is forecast for 2036?
Future Market Insights estimates that the global packing boxes market will reach USD 24.0 billion in 2026 and USD 37.6 billion by 2036.
What is the CAGR for the packing boxes market from 2026 to 2036?
As per FMI, the market is projected to expand at a 4.6% CAGR over the assessment period.
Which product format leads the packing boxes market?
Folding cartons and trays are projected to hold 32.0% share in 2026, supported by flat shipment logistics and automated packing line compatibility.
Which material substrate leads the packing boxes market?
Virgin chemical kraft pulp is estimated to account for 38.5% share in 2026, driven by dependable stacking compression and burst strength.
Which country has a notable growth outlook during the assessment period?
Austria is projected to register a 5.6% CAGR from 2026 to 2036, supported by circular economy mandates and export packaging redesign.
Who are the key players in the market?
Key players include International Paper, Smurfit Westrock plc, Mondi plc, Graphic Packaging Holding Company, Packaging Corporation of America, Stora Enso Oyj, Mayr-Melnhof Karton AG, Oji Holdings Corporation, Rengo Co., Ltd., and Sonoco Products Company.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Format / Style, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Format / Style, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Format / Style, 2026 to 2036
- Folding cartons and trays
- Rigid set-up boxes
- Corrugated containers
- Custom die-cut formats
- Y-o-Y Growth Trend Analysis By Product Format / Style, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Format / Style, 2026 to 2036
- Global Market Analysis and Forecast, By Material Substrate, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Substrate, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Substrate, 2026 to 2036
- Virgin chemical kraft pulp
- Recycled fluting and testliner
- Barrier-coated solid bleached board
- Molded fiber and specialty paperboard
- Y-o-Y Growth Trend Analysis By Material Substrate, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Substrate, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Fresh produce and meat packaging
- Dry food and confectionery
- E-commerce shipping and logistics
- Consumer electronics and goods
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Barrier / Coating Property, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Barrier / Coating Property, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Barrier / Coating Property, 2026 to 2036
- Aqueous water-based barrier
- PLA and bio-wax coating
- Standard uncoated recyclable
- Dispersion-coated grease barrier
- Y-o-Y Growth Trend Analysis By Barrier / Coating Property, 2021 to 2025
- Absolute $ Opportunity Analysis By Barrier / Coating Property, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada.
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile.
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Austria
- Finland
- Sweden.
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary.
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea.
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- ASEAN
- Australia and New Zealand.
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel.
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Austria
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Finland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Sweden
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- International Paper
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Smurfit Westrock plc
- Mondi plc
- Graphic Packaging Holding Company
- Packaging Corporation of America
- Stora Enso Oyj
- Mayr-Melnhof Karton AG
- Oji Holdings Corporation
- Rengo Co., Ltd.
- Sonoco Products Company
- International Paper
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


