

- Market Size (2026)
- USD 30.2 Bn
- Forecast (2036)
- USD 54.7 Bn
- CAGR (2026 to 2036)
- 6.1%
How big is Polymer Emulsion Market in 2026?
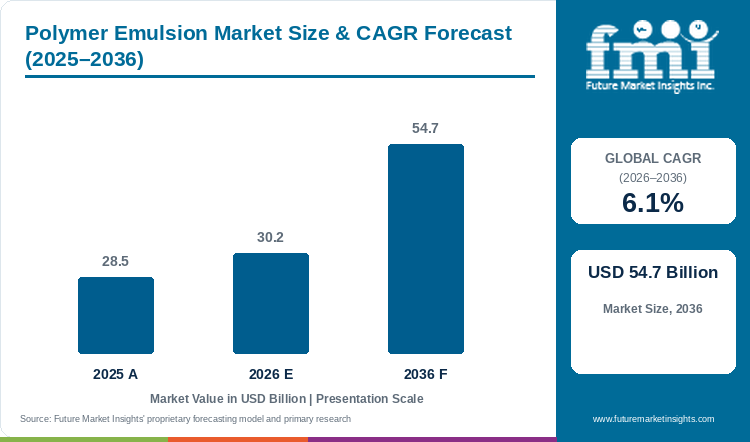
Water-based binder sales record a 6.1% CAGR between 2026 and 2036. Market size stood at USD 28.5 billion in 2025, is estimated at USD 30.2 billion in 2026 and is projected to reach USD 54.7 billion by 2036.
Sales of polymer emulsions stood at USD 28.5 billion in 2025 and are estimated at USD 30.2 billion in 2026. Market size is projected to reach USD 54.7 billion by 2036, the FMI study shows, at a 6.1% CAGR from 2026 to 2036. WACKER POLYMERS posted Q2 2026 sales of €406 million, 12 percent above Q2 2025, and named higher prices in certain cases among the reasons for stronger results.[1] Due to this, paint plants are paying more per tonne of binder in 2026. Acrylic grades already hold 44% of 2026 product sales, and paint plants are moving more formulas to acrylic binders. The acrylic emulsions market is set for a 7.7% CAGR from 2026 to 2036, above the 6.1% emulsion rate, so vinyl acetate and styrene butadiene grades will lose share. Paints and coatings take 40% of 2026 application sales, so binder price rises reach paint plants first. A requalification constraint is slowing supplier switching at paint plants, so paint makers will pick drop-in grades that run on existing coating lines. Adoption of emulsion binders in cement modifiers and waterproofing coats is pulling sales beyond traditional sources of demand, and construction uses already take an estimated 10.9% of 2026 application sales. The construction chemicals market is projected at a 5.2% CAGR from 2026 to 2036, below the 6.1% emulsion rate, so mortar and waterproofing work will add binder tonnage without leading growth. India posts the fastest country CAGR, 8.3% from 2026 to 2036, as road, rail and housing work under the National Infrastructure Pipeline adds coating and mortar volume.
Key Market Trends & Insights
- Acrylic polymer emulsions hold 44% of 2026 product sales, according to FMI’s analysis, owing to wide use in architectural and industrial coatings.
- Demand for emulsions in paints and coatings reached 40% of 2026 application sales. China put two mandatory coating standards for harmful substances into force on 1 June 2026.[2]
- Building and construction is the top end-use industry at about 38.6% (estimated), since one building uses emulsions in paint, mortar and waterproofing.
- Old reactors and long buyer approvals keep conventional emulsion polymerization at an estimated 71.8% of technology sales.
- Direct sales, near 58.3% (estimated), remain the main channel for large paint and adhesive makers.
Regional Highlights
- India leads country growth on National Infrastructure Pipeline demand, and FMI predicts an 8.3% CAGR from 2026 to 2036.
- Chinese sales follow at 7%, with the USA on 6.3% and Germany on 5.8%, and Japan is the slowest profiled country at 5.4%.
- Sika named India and Southeast Asia as standouts in Asia/Pacific in July 2026.[3]
Market Size & Forecast
Table 1: Market Size and Forecast for the Polymer Emulsion Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 28.5 billion |
| Estimated Market Size in 2026 | USD 30.2 billion |
| Projected Market Size by 2036 | USD 54.7 billion |
| CAGR, 2026 to 2036 | 6.1% |
| Added Revenue, 2026 to 2036 | USD 24.5 billion |
| Market Expansion Multiple | 1.8x |
Paint, adhesive and mortar plants buying binder for new lines and repeat batches account for the bulk of the USD 24.5 billion gain to 2036, FMI’s report shows. Coating and adhesive plants replace binders batch by batch, so volume follows paint and glue output. Furniture and joinery plants buy wood glue made with emulsion binders, so growth of the wood adhesives market adds binder orders. Resin makers and emulsion makers draw on one acrylic monomer supply, and water-based grades hold the largest share of the acrylic resin market.
Feedstock Costs and Price Pass-Through
BASF reported 2025 Dispersions & Resins sales of €4,801 million, down 6% from €5,110 million.[4] Prices in the division fell 3.1%, mainly due to lower raw material prices and a competitive environment, BASF said.[4] Volumes slipped 0.4% in the same year.[4] Prices turned in 2026. Nippon Paint said raw-material cost increases linked to Middle East conditions were offset in Q2 2026 through price pass-through and cost reductions.[5] Nippon Paint expects higher raw-material costs to weigh more in the second half of 2026.[5] Paint Stores Group prices at Sherwin-Williams rise 8% from 1 September 2026, the company announced.[6] An 8% price rise at Sherwin-Williams stores will help binder suppliers pass monomer costs to paint makers in late 2026.
Table 2: Feedstock and Pricing Indicators for the Polymer Emulsion Market (EUR, USD, JPY and percentage), 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| BASF Dispersions & Resins sales, 2025 | €4,801 million, down 6% | Lower prices cut binder sales value in 2025. | [4] |
| BASF Dispersions & Resins price effect, 2025 | Down 3.1% | Raw material declines passed to buyers. | [4] |
| WACKER POLYMERS sales, Q2 2026 | €406 million, up 12 percent | Binder sales recovered in 2026. | [1] |
| WACKER POLYMERS EBITDA, Q2 2026 | €69 million, up 74 percent | Cost savings and higher prices in certain cases. | [1] |
| Sherwin-Williams Paint Stores price increase | 8% from 1 September 2026 | Paint prices carry binder costs to end buyers. | [6] |
| Nippon Paint revenue, Q2 2026 | ¥533.4 billion, up 19.4% | Coating demand in Asia. | [5] |
| Sika construction products, H1 2026 | Up 4.1% in local currencies | Construction chemical demand for emulsion binders. | [3] |
| Henkel Adhesive Technologies, H1 2026 | Organic growth of 4.5% | Adhesive demand for emulsion binders. | [7] |
Analyst Perspective
“Distributor sales of emulsions will gain share as small formulators in India and Southeast Asia buy binders in smaller lots. I expect producers to pair direct contracts for large paint makers with distributor stock close to new construction projects. Online sample orders will shorten qualification for small buyers.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the polymer emulsion market segmented?
Five product axes and region make up the polymer emulsion market. Acrylic grades hold 44% of product sales and paints and coatings 40% of applications in 2026, and building and construction, conventional polymerization and direct sales lead the other axes on estimated shares.
By product type: acrylic, vinyl acetate, styrene butadiene, polyurethane dispersions, others.
By application type: paints and coatings, adhesives and sealants, paper and paperboard, textiles and nonwovens, construction, automotive, and others.
By end-use industry: building/construction, chemicals, automotive, packaging, textile, paper, others.
By technology: conventional, mini and micro emulsion polymerization.
By distribution channel: direct, distributor and online sales.
By region: binder demand is split across Europe (Western, Eastern), the Americas (North, Latin), Asia (East, South Asia and Pacific) and the Middle East with Africa.
Why do acrylic emulsions lead product sales?
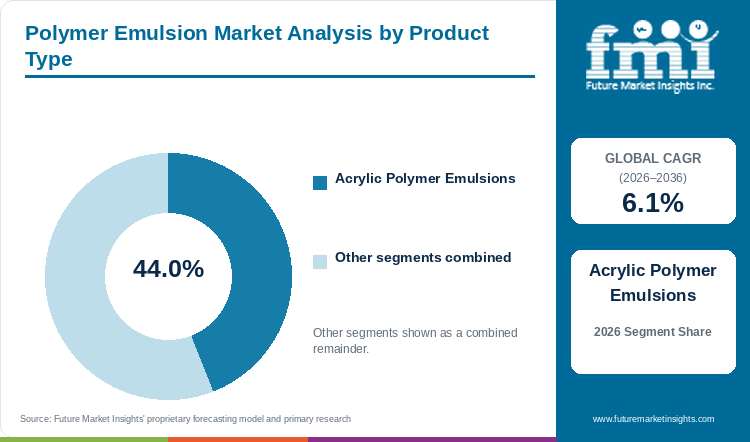
Acrylic polymer emulsions rank first among products with 44% in 2026, and second place goes to vinyl acetate grades at an estimated 23.6%.
Table 3: Product Type Share for the Polymer Emulsion Market (percentage share), 2026
| Product Type | Estimated Share (2026) |
|---|---|
| Acrylic Polymer Emulsions | 44% |
| Vinyl Acetate Polymer Emulsions | 23.6% |
| Styrene Butadiene Polymer Emulsions | 17.2% |
| Polyurethane Dispersions | 9.8% |
| Others | 5.4% |
| Total | 100.0% |
Table 4: Product Type Leadership and Market Growth for the Polymer Emulsion Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.1% |
| Leading Segment | Acrylic Polymer Emulsions |
One acrylic chemistry covers architectural paint, industrial coatings, construction and packaging adhesives, and the FMI study puts acrylic polymer emulsions first at 44% of product sales. Vinyl acetate grades, at an estimated 23.6%, cost less but lose ground on water resistance, so paint makers keep vinyl acetate for interior and economy lines. Styrene butadiene grades hold about 17.2% (estimated), as yellowing outdoors confines them mainly to paper coating, carpet backing and cement modification. Polyurethane dispersions are the costliest of the group and take near 9.8% (estimated), mostly in wood, leather and specialty coatings. Other chemistries make up the remaining 5.4% (estimated). Chinese paint makers reformulating architectural coatings for GB 30981.1-2025, in force from 1 June 2026, will order more water-based binders.[2]
- Vinyl acetate grades, near 23.6% (estimated), include polyvinyl acetate and vinyl acetate ethylene types.
Why do paints and coatings lead application sales?
Paints and coatings hold 40% of 2026 application sales, and adhesives and sealants come second at an estimated 18.7%.
Table 5: Application Type Share for the Polymer Emulsion Market (percentage share), 2026
| Application Type | Estimated Share (2026) |
|---|---|
| Paints and Coatings | 40% |
| Adhesives and Sealants | 18.7% |
| Paper and Paperboard | 11.6% |
| Construction | 10.9% |
| Textiles and Nonwovens | 8.4% |
| Automotive | 5.9% |
| Others | 4.5% |
| Total | 100.0% |
Binder makes up a large part of every can of water-based paint, and FMI estimates paints and coatings at 40% of application sales. Sherwin-Williams raised consolidated net sales 7.5% to USD 6.79 billion in Q2 2026, European Coatings reported.[6] Adhesives and sealants come second at an estimated 18.7%, as packaging and wood glue volumes are smaller than paint volumes. Paper and paperboard take about 11.6% (estimated), and falling graphic paper output caps that share. Construction uses, near 10.9% (estimated), come from mortar modifiers and waterproofing coats, a smaller tonnage than paint. Textiles and nonwovens hold about 8.4%, automotive 5.9% and other uses 4.5%, all estimated, and each of the three buys a narrow set of specialty grades.
- Henkel Packaging & Consumer Goods posted organic sales growth of 4.7% in H1 2026.[7]
Why does building and construction lead end-use industry sales?
An estimated 38.6% of 2026 end-use sales goes to building and construction, with packaging next at about 14.2%.
Table 6: End-Use Industry Share for the Polymer Emulsion Market (percentage share), 2026
| End-Use Industry | Estimated Share (2026) |
|---|---|
| Building and Construction | 38.6% |
| Packaging | 14.2% |
| Automotive | 12.1% |
| Chemicals | 10.8% |
| Paper | 9.7% |
| Textile | 8.3% |
| Others | 6.3% |
| Total | 100.0% |
Homes and offices are switching to low-odour, water-based paint, and consumer preference for such paint supports building and construction, the top end-use industry at about 38.6% (estimated). Builders also use emulsions a second time in cement modification and waterproofing. Sika reported 4.1% local-currency growth in products for the construction industry in H1 2026.[3] Packaging takes an estimated 14.2%, with the binder going mainly into carton adhesives and barrier coats. Automotive buyers, near 12.1% (estimated), purchase emulsions for interior and exterior coatings, a narrower use than building work. Chemicals hold about 10.8% (estimated) as an intermediate for formulators. Paper (9.7%), textile (8.3%) and other industries (6.3%) are all estimated and smaller, owing to mature output at paper mills and textile plants.
- Repaint work is holding up in Japan, and Nippon Paint grew Japan Q2 2026 decorative paint revenue 26.3%.[5]
Why does conventional emulsion polymerization lead technology sales?
Conventional emulsion polymerization runs at about 71.8% (estimated) in the 2026 technology split, with mini emulsion near 17.4% and micro emulsion near 10.8%.
Table 7: Technology Share for the Polymer Emulsion Market (percentage share), 2026
| Technology | Estimated Share (2026) |
|---|---|
| Conventional Emulsion Polymerization | 71.8% |
| Mini Emulsion Polymerization | 17.4% |
| Micro Emulsion Polymerization | 10.8% |
| Total | 100.0% |
Most emulsion reactors in service were built for conventional recipes, and paint buyers have approved conventional grades over many years. Conventional emulsion polymerization keeps an estimated 71.8% as a result. Mini emulsion, at about 17.4% (estimated), needs high-shear mixing before polymerization, so producers use mini emulsion for hybrid and specialty binders only. Micro emulsion, near 10.8% (estimated), needs large amounts of surfactant, which keeps micro grades in small-particle and high-purity uses.
Why do direct sales lead distribution channel sales?
Direct contracts account for about 58.3% of 2026 channel sales, with distributors at 34.2% and online orders at 7.5%, all estimated.
Table 8: Distribution Channel Share for the Polymer Emulsion Market (percentage share), 2026
| Distribution Channel | Estimated Share (2026) |
|---|---|
| Direct Sales | 58.3% |
| Distributor Sales | 34.2% |
| Online Sales | 7.5% |
| Total | 100.0% |
Large paint and adhesive makers order binder by the tanker on annual supply agreements, and direct sales hold an estimated 58.3%. Distributor sales, about 34.2% (estimated), serve formulators too small for a direct contract and buyers who need several chemistries in one delivery. Online sales stay near 7.5% (estimated), because bulk liquids need tank trucks and quality paperwork that web orders handle poorly.
- Distributor stock near new construction sites in India and Southeast Asia will shorten delivery times for small formulators.
What are the drivers, restraints, and opportunities in the polymer emulsion market?
China’s GB 30981 coating limits from 1 June 2026, repaint orders in Japan and Indian infrastructure work drive demand for polymer emulsions. Producers of polymer emulsions face certification and requalification work for each new specification.
- Driver: Coating reformulation in China under GB 30981 limits from 1 June 2026.
- Restraint: Certification and requalification effort, heaviest for smaller buyers.
- Opportunity: Drop-in acrylic grades that run on existing paint lines.
New Coating Limits in China Favour Water-Based Binders
The State Administration for Market Regulation and the Standardization Administration of China released GB 30981.1-2025 and GB 30981.2-2025 on 30 May 2025.[2] Both standards replace older limits for wall, floor, wood, vehicle and marine coatings, effective 1 June 2026.[2] Paint makers reformulating for the June 2026 limits will order more water-based acrylic and vinyl binders.
Requalification Slows Supplier Switching
Each new emulsion grade needs test work at the paint or adhesive plant before use. Price competition adds to the burden, and BASF named a competitive environment as one cause of the 3.1% price decline in Dispersions & Resins in 2025.[4] Requalification costs weigh most on smaller buyers, and suppliers with grades already approved will keep share. Adhesive and sealant formulators run the same approval steps for every new binder, so growth of the adhesives and sealants market will mostly reach suppliers with approved grades.
Drop-In Grades for Existing Coating Lines
Paint makers prefer to upgrade products without rebuilding plants. Nippon Paint reported Japan Q2 2026 decorative paint revenue up 26.3% to ¥15.6 billion on stronger sales of high-durability architectural and structural products.[5] Durable architectural paints need premium acrylic binders. Drop-in acrylic grades will gain as paint makers upgrade products on existing lines.
Which country CAGRs are profiled in the polymer emulsion market?
Table 9: Country CAGR Comparison for the Polymer Emulsion Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 8.3% |
| China | 7% |
| USA | 6.3% |
| Germany | 5.8% |
| Japan | 5.4% |
How do country-level CAGRs compare in the polymer emulsion market?
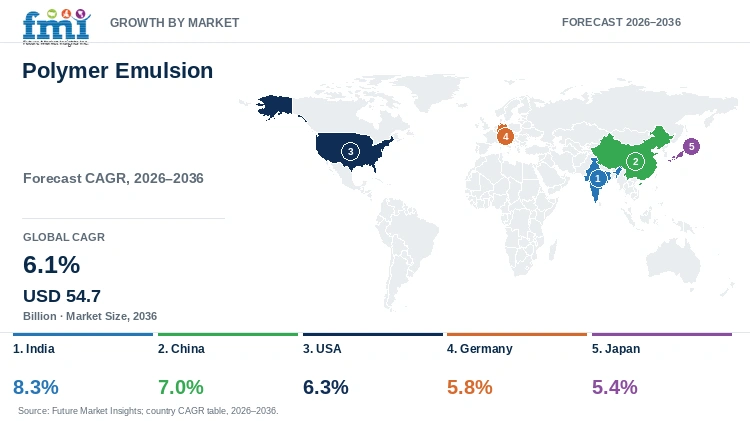
Road, rail and housing work under the National Infrastructure Pipeline drives Indian demand, and analysts at FMI see India at 8.3% from 2026 to 2036, ahead of China at 7%. US sales grow at 6.3%, close to the 6.1% global CAGR. Housing starts at a 62-year low hold Japan at 5.4%, and energy costs keep Germany at 5.8%, both under the global CAGR.
- Road, rail and housing contracts under the National Infrastructure Pipeline carry India to an 8.3% CAGR.
- Chinese paint makers are reformulating to coating limits in force since 1 June 2026, and China grows at 7%.[2]
- Sherwin-Williams Paint Stores posted 4.2% same-store growth in Q2 2026, and US demand grows at 6.3%.[6]
- Energy costs in Germany squeeze local producers, and DIN and EU performance standards set grade rules.
- Japan is the slowest profiled country at 5.4% after housing starts fell 6.5% in 2025.[8]
Full report country CAGRs cover: 30+ countries in seven emulsion regions, with history from 2021.
Country-wise Analysis
Japan Polymer Emulsion Market Outlook (2026 to 2036)
Housing starts in Japan dropped 6.5% in 2025 to 740,667 units, a 62-year low, Jiji Press reported.[8] Fewer new homes cut demand for emulsions in new-build paint and mortar. Repainting holds up better, and Nippon Paint grew Japan Q2 2026 revenue 17.9% to ¥61.6 billion.[5] Japan posts a 5.4% CAGR from 2026 to 2036, as repaint orders offset part of the fall in new-build paint demand.
Key takeaway: Japan offers repaint and high-purity grade work, and new housing will add little volume.
India Polymer Emulsion Market Outlook (2026 to 2036)
Sika named India among the Asia/Pacific standouts in H1 2026, a half in which Sika construction products grew 4.1% in local currencies.[3] Road, rail and housing projects under the National Infrastructure Pipeline need wall paint, mortar modifiers and tile adhesives made with emulsion binders. India posts an 8.3% CAGR through 2036, the top profiled rate, and local formulators will add emulsion capacity close to new road, rail and housing projects.
Key takeaway: India’s 8.3% CAGR makes the country the first target for new construction-grade emulsion capacity.
Germany Polymer Emulsion Market Outlook (2026 to 2036)
Destatis reported June 2026 new orders in the main construction industry 11.3% above June 2025 in real terms.[9] German sales grow at a 5.8% CAGR from 2026 to 2036, as the 11.3% rise in construction orders brings mortar and repaint work back to local producers.
Key takeaway: German demand recovers with construction orders, and energy costs will keep local production margins thin.
USA Polymer Emulsion Market Outlook (2026 to 2036)
Paint Stores Group net sales at Sherwin-Williams reached USD 3.89 billion in Q2 2026, a 5.1% gain, with same-store sales up 4.2%.[6] An 8% Paint Stores price rise from 1 September 2026 will pass higher binder costs to US contractors.[6] American emulsion sales post a 6.3% CAGR through 2036.
Key takeaway: Same-store paint sales up 4.2% in Q2 2026 point to steady repaint orders for US binder plants.
China Polymer Emulsion Market Outlook (2026 to 2036)
Coating reformulation is holding Chinese demand up as construction volume falls. Sika said construction activity in China fell by a double-digit percentage in H1 2026.[3] New harmful-substance limits for architectural and industrial coatings took effect on 1 June 2026.[2] China posts a 7% CAGR from 2026 to 2036, and paint makers reformulating wall, floor and wood coatings will place the new binder orders.
Key takeaway: Chinese demand shifts from new construction to compliant reformulated coatings.
Who are the notable companies in the polymer emulsion market?
BASF, Proell, SNF, Wacker Chemie, Trinseo, Celanese, Rakem Group, Arkema, Devine Chemicals Ltd and DIC supply polymer emulsions.
Demand in India and Southeast Asia stood out for Sika in July 2026, and the race to capture emerging demand there favours producers with grades already approved by global paint makers.[3] FMI groups BASF, Wacker Chemie, Rakem Group and Devine Chemicals as integrated producers. Proell, Trinseo and Arkema form the specialty supplier group, and SNF, Celanese and DIC form the regional group.
Producer results in 2025 and 2026 split by chemistry and region. BASF Dispersions & Resins sales fell 6% in 2025.[4] WACKER POLYMERS sales rose 12 percent in Q2 2026.[1] Henkel Adhesive Technologies grew organically by 4.5% in H1 2026.[7]
- Integrated producers: BASF, Wacker Chemie, Rakem Group, and Devine Chemicals Ltd.
- Specialty suppliers: Proell, Trinseo, and Arkema.
- Regional players: SNF, Celanese, and DIC.
Competitive Benchmarking: Polymer Emulsion Market
Table 10: Competitive Benchmarking for the Polymer Emulsion Market (qualitative documentation ratings), 2026
| Company | Portfolio Breadth | Qualification Depth | Supply Scale | Footprint |
|---|---|---|---|---|
| BASF | High | High | Strong | Global |
| Proell | High | High | Strong | Global |
| SNF | Medium | Medium | Moderate | Global |
| Wacker Chemie | High | Medium | Moderate | Regional |
| Trinseo | Medium | Medium | Moderate | Regional |
Portfolio and qualification run High, Medium or Low, supply scale runs Strong or Moderate, and footprint is Global or Regional.
Key Developments in the Polymer Emulsion Market
- In August 2026, Nippon Paint moved the full-year 2026 revenue forecast up to ¥2 trillion from ¥1.92 trillion.[5]
- In August 2026, Henkel reported H1 2026 Adhesive Technologies sales of €5,534 million.[7]
- In August 2026, an 8% price rise for the Sherwin-Williams Paint Stores Group was set for 1 September 2026.[6]
- In August 2026, Destatis reported June 2026 construction orders 11.3% above the prior year.[9]
- In July 2026, WACKER reported Q2 2026 Polymers sales of €406 million.[1]
- In February 2026, BASF reported 2025 Dispersions & Resins sales of €4,801 million.[4]
- In June 2025, China released GB 30981.1-2025 and GB 30981.2-2025 for coatings, effective 1 June 2026.[2]
Key Players in the Polymer Emulsion Market
Integrated Producers
- BASF
- Wacker Chemie
- Rakem Group
- Devine Chemicals Ltd
Specialty Suppliers
- Proell
- Trinseo
- Arkema
Regional Players
- SNF
- Celanese
- DIC
Polymer Emulsion Market - Report Scope
Table 11: Report Scope for the Polymer Emulsion Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; application type; end-use industry; technology; distribution channel; region |
| Quantitative units | USD billion |
| Market definition | Water-based polymer emulsions and dispersions, including acrylic, vinyl acetate, styrene butadiene and polyurethane grades, used in coatings, adhesives, paper, textiles, construction and automotive products. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | India; China; USA; Germany; Japan |
| Key companies profiled | BASF, Proell, SNF, Wacker Chemie, Trinseo, Celanese, Rakem Group, Arkema, Devine Chemicals Ltd, DIC |
| Forecast period | 2026 to 2036 |
Polymer Emulsion Market - Research Methodology
Table 12: Research Methodology for the Polymer Emulsion Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Producer and buyer results, a Chinese standards notice, construction statistics and trade press dated May 2025 or later. |
| Desk Research | Desk research covers binder prices, paint and adhesive sales, coating rules and construction activity. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base of USD 28.5 billion and the 6.1% CAGR. |
| Data Validation | Producer price effects were compared with paint maker price moves in the same period. |
Polymer Emulsion Market by Segments
Polymer Emulsion Market segmented by Product Type:
- Acrylic Polymer Emulsions
- Vinyl Acetate Polymer Emulsions
- Styrene Butadiene Polymer Emulsions
- Polyurethane Dispersions
- Others
Polymer Emulsion Market segmented by Application Type:
- Paints and Coatings
- Adhesives and Sealants
- Paper and Paperboard
- Textiles and Nonwovens
- Construction
- Automotive
- Others
Polymer Emulsion Market segmented by End-Use Industry:
- Building and Construction
- Chemicals
- Automotive
- Packaging
- Textile
- Paper
- Others
Polymer Emulsion Market segmented by Technology:
- Conventional Emulsion Polymerization
- Mini Emulsion Polymerization
- Micro Emulsion Polymerization
Polymer Emulsion Market segmented by Distribution Channel:
- Direct Sales
- Distributor Sales
- Online Sales
Polymer Emulsion Market by Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
Research Sources and Bibliography
- [1] Wacker Chemie AG. (2026, July 30). WACKER's Q2 earnings rise due to cost savings and a special effect. https://www.wacker.com/cms/media/en/documents/pressrelease-pdf/pm2026/wacker_q2_2026.pdf
- [2] CIRS Group. (2025, June 11). Two New Mandatory National Standards on Limit of Harmful Substances of Coatings Officially Implemented. https://www.cirs-group.com/en/chemicals/two-new-national-standards-on-limit-of-harmful-substances-of-coatings-officially-implemented
- [3] Sika AG. (2026, July 28). Sika delivers 4.0% local currency revenue growth and upgrades full-year growth expectations. https://www.sika.com/en/media/media-releases/2026/half-year-report-2026.html
- [4] BASF SE. (2026, February 27). BASF Report 2025, Industrial Solutions segment. https://report.basf.com/2025/en/combined-managements-report/basf-groups-business-year/segments/industrial-solutions
- [5] Painting & Coating Industry (PCI). (2026, August 10). Nippon Paint raises revenue outlook after record second quarter. https://www.pcimag.com/articles/115014-nippon-paint-raises-revenue-outlook-after-record-second-quarter
- [6] European Coatings. (2026, August 4). Sherwin-Williams reports 7.5% net sales growth in Q2 2026. https://www.european-coatings.com/news/markets-companies/sherwin-williams-reports-7-5-net-sales-growth-in-q2-2026
- [7] Henkel. (2026, August 6). Henkel delivers strong sales and earnings performance in the first half and upgrades top-line guidance for 2026. https://www.henkel.com.au/press/press-releases-and-kits/2026-08-06-henkel-delivers-strong-sales-and-earnings-performance-in-the-first-half-and-upgrades-top-line-guidance-for-2026-2217762
- [8] Nippon.com (Jiji Press). (2026, January 30). Japan Housing Starts Fall to 62-Year Low in 2025. https://www.nippon.com/en/news/yjj2026013001015
- [9] Statistisches Bundesamt (Destatis). (2026, August 25). Press release No. 304, Auftragseingang im Bauhauptgewerbe im Juni 2026. https://www.destatis.de/DE/Presse/Pressemitteilungen/2026/08/PD26_304_441.html
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- What will polymer emulsion market size be in 2026 and 2036?
- What CAGR will emulsion sales record from 2026 to 2036?
- Which product type and application will hold the largest shares?
- Which end-use industry will buy the most emulsions?
- Which countries will grow fastest?
- Which producers will shape competition through 2036?
Frequently Asked Questions
What is the size of the polymer emulsion market in 2026?
Emulsion market size is estimated at USD 30.2 billion in 2026 and will reach USD 54.7 billion in 2036, per FMI.
How fast will polymer emulsion sales grow?
A 6.1% CAGR will carry emulsion sales from 2026 to 2036. Coating reformulation in China, Indian infrastructure work and higher paint prices will add USD 24.5 billion.
Which product type will lead in 2026?
Acrylic polymer emulsions will lead with a 44% share of product sales.
Which application will buy the most emulsions?
Paints and coatings, at 40% of 2026 application sales, ahead of adhesives and sealants at an estimated 18.7%.
Which country will grow fastest through 2036?
An 8.3% CAGR will make India the fastest country in the FMI table.
Who are the main polymer emulsion producers?
BASF, Wacker Chemie, Proell, Trinseo and Arkema will compete with SNF, Celanese and DIC.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Acrylic Polymer Emulsions
- Vinyl Acetate Polymer Emulsions
- Styrene Butadiene Polymer Emulsions
- Polyurethane Dispersions
- Others
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application Type, 2026 to 2036
- Paints and Coatings
- Adhesives and Sealants
- Paper and Paperboard
- Textiles and Nonwovens
- Construction
- Automotive
- Others
- Y-o-Y Growth Trend Analysis By Application Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Application Type, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Industry, 2026 to 2036
- Building and Construction
- Chemicals
- Automotive
- Packaging
- Textile
- Paper
- Others
- Y-o-Y Growth Trend Analysis By End-Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Technology, 2026 to 2036
- Conventional Emulsion Polymerization
- Mini Emulsion Polymerization
- Micro Emulsion Polymerization
- Y-o-Y Growth Trend Analysis By Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Direct Sales
- Distributor Sales
- Online Sales
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Application Type
- By End-Use Industry
- By Technology
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application Type
- By End-Use Industry
- By Technology
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Application Type
- By End-Use Industry
- By Technology
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application Type
- By End-Use Industry
- By Technology
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Application Type
- By End-Use Industry
- By Technology
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application Type
- By End-Use Industry
- By Technology
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Application Type
- By End-Use Industry
- By Technology
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application Type
- By End-Use Industry
- By Technology
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Application Type
- By End-Use Industry
- By Technology
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application Type
- By End-Use Industry
- By Technology
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Application Type
- By End-Use Industry
- By Technology
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application Type
- By End-Use Industry
- By Technology
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Application Type
- By End-Use Industry
- By Technology
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application Type
- By End-Use Industry
- By Technology
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application Type
- By End-Use Industry
- By Technology
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application Type
- By End-Use Industry
- By Technology
- By Distribution Channel
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application Type
- By End-Use Industry
- By Technology
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application Type
- By End-Use Industry
- By Technology
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application Type
- By End-Use Industry
- By Technology
- By Distribution Channel
- India
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Application Type
- By End-Use Industry
- By Technology
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- BASF
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Proell
- SNF
- Wacker Chemie
- Trinseo
- Rakem Group
- Devine Chemicals Ltd
- Arkema
- Celanese
- DIC
- BASF
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


