
- Market Size (2026)
- USD 37.2 Bn
- Forecast (2036)
- USD 78.8 Bn
- CAGR (2026 to 2036)
- 7.8%
How big is Premium Chocolate Market in 2026?
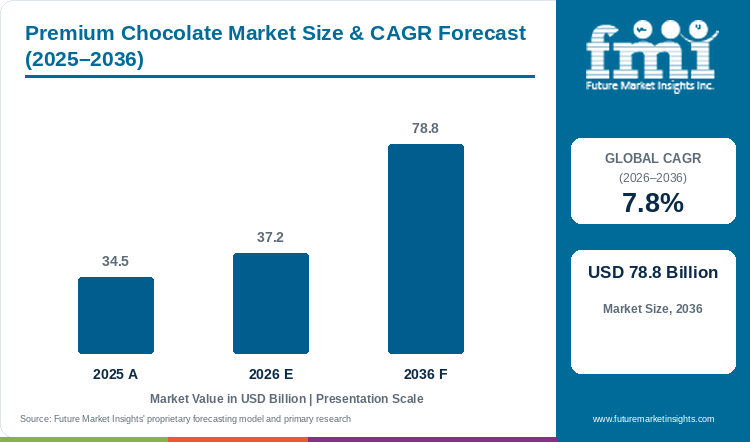
Accounting for USD 34.5 billion in 2025 and rising to USD 37.2 billion in 2026, the premium chocolate market is projected to expand to USD 78.8 billion by 2036, advancing at a CAGR of 7.8%.
The global premium chocolate market was valued at USD 34.5 billion in 2025 and is estimated to reach USD 37.2 billion in 2026. The market is projected to reach USD 78.8 billion by 2036, expanding at a compound annual growth rate (CAGR) of 7.8% between 2026 and 2036. Premium dark chocolate with 70 percent or higher cocoa solids is projected to capture a leading 52.0% share of 2026 demand, given that discerning shoppers trade up to high-cocoa, low-sugar tablets for daily mindful treating. Demand for luxury dark tablets and artisanal pralines is supported by resilient brand loyalty during periods of retail price inflation, with the National Confectioners Association reporting in its 2026 State of Treating study that U.S. confectionery retail sales reached USD 55.0 billion in 2025 as 64% of buyers chose smaller portions of their favorite brand over cheaper substitutes [1].
That price-inelastic gifting and self-reward behavior separates the sector from bulk industrial chocolate at a 4.7% CAGR, since mass bakery coatings compete on commodity fat margins whereas single-origin tablets and boxed truffles command high retail price realization per gram. Manufacturers are also investing heavily in dedicated molding and praline plants, as demonstrated in February 2026 when the Ferrero Group reported EUR 19.3 billion in 2024/2025 consolidated turnover supported by nearly EUR 1.1 billion in capital expenditures across North American and European facilities. Chocolatiers that lock in polygon-mapped deforestation-free cocoa beans and master thin-shell praline textures will capture specialty and travel-retail spending through 2036.
Key Market Trends & Insights
- By chocolate type: Premium Dark Chocolate 70 Percent Plus holds an estimated 52.0% share in 2026 since buyers prioritize flavanol-rich cacao liquor and single-estate flavor notes over sugar-heavy candy.
- By product format: Tablets and Molded Chocolate Bars represent a projected 58.0% in 2026 owing to precise score-line portioning and high-visibility origin storytelling on bar wrappers.
- By sourcing credential: Bean-to-Bar Single Origin accounts for an anticipated 48.0% in 2026 supported by farm-plot GPS polygon mapping and direct fermentation control.
- By cocoa content tier: 70 to 85 Percent Extra-Bitter formulations secure an estimated 55.0% in 2026 as adult consumers balance intense roast aroma against manageable astringency.
- By distribution channel: Specialty Chocolate Boutiques and Gifting Retail command a projected 46.0% in 2026 driven by climate-controlled praline counters, seasonal gift boxes, and airport duty-free shops.
Regional Highlights
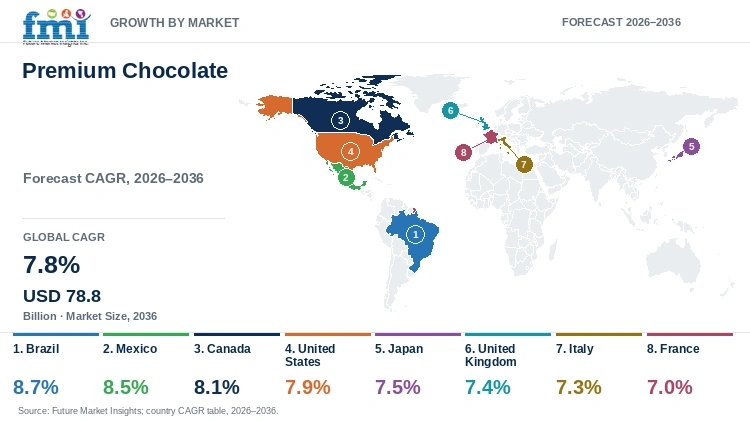
- Top national expansion: Brazil leads national growth projections at an 8.7% CAGR through 2036 under tree-to-bar Bahia and Para fine-cocoa boutiques and expanding mall gifting chains.
- Broader country progression: Mexico tracks at an 8.5% CAGR ahead of Canada at 8.1% and the United States at 7.9%, while Japan advances at 7.5%, the United Kingdom at 7.4%, and Italy at 7.3%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Premium Chocolate Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 34.5 billion |
| Estimated Market Size in 2026 | USD 37.2 billion |
| Projected Market Size by 2036 | USD 78.8 billion |
| CAGR, 2026 to 2036 | 7.8% |
| Added Revenue, 2026 to 2036 | USD 41.6 billion |
Fine-flavor chocolatiers and luxury confectionery houses operate against tight global cocoa bean balances that elevate raw cocoa liquor and fat input costs. When West African main-crop harvests fluctuate due to swollen-shoot virus or erratic El Nino rainfall, unhedged chocolate makers face steep spot-market margin compression. In August 2026, the International Cocoa Organization reported in its Volume LII Quarterly Bulletin of Cocoa Statistics that world gross cocoa production reached 4.733 million metric tons in 2024/25 while global grindings declined 3.3% to 4.649 million metric tons, leaving a narrow 37,000-metric-ton surplus and a 28.2% stocks-to-grindings ratio. Consequently, luxury brands secure direct multi-year contracts for pure cocoa butter and single-origin liquor to insulate retail tablet pricing from futures exchange volatility.
Fine Cocoa Grindings and Couverture Sizing
Table 2: Fine Cocoa Grindings and Couverture Sizing for the Premium Chocolate Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 34.5 | 37.2 | 78.8 |
| World cocoa bean grindings (million metric tons, ICCO basis) | 4.65 | 4.70 to 4.78 | 5.50 to 5.85 |
| Fine-flavor & traceable single-origin cocoa volume (thousand MT) | 520.0 to 560.0 | 555.0 to 600.0 | 1,050.0 to 1,180.0 |
| Average cocoa solids content in premium dark tablets (%) | 70.0% to 85.0% | 70.0% to 85.0% | 72.0% to 88.0% |
Operational note: Global cocoa bean grindings and fine-flavor origin shares trace to International Cocoa Organization (ICCO) quarterly bulletins and European/U.S. standard-of-identity cocoa solids thresholds.
Adult confectionery buyers are shifting away from high-sugar countlines toward multi-sensory dark tablets, pistachio-kunafa and yuzu fillings, and clean-label ingredient decks. According to Barry Callebaut AG's Top Chocolate Confectionery Trends 2026 & Beyond report released in February 2026 under its Future of Taste framework, consumers increasingly demand cleaner ingredient profiles, richer sensory experiences, and purpose-driven formats that justify premium price points. Artisanal patisseries and boutique chocolatiers therefore specify single-estate chocolate couverture with calibrated three-drop to five-drop fluidity to mold thin-walled filled bonbons.
Per Capita & Specialty Boutique Line Sizing
Table 3: Per Capita and Specialty Boutique Spending Indicators for the Premium Chocolate Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Global premium chocolate spend per capita (USD) | 4.2 | 4.5 | 8.8 |
| U.S. chocolate & cocoa exports (USD billion, USDA FAS BICO) | 2.67 | 2.85 to 2.95 | 4.60 to 5.10 |
| Certified traceable & polygon-mapped cocoa share in premium (%) | 64.0% to 68.0% | 68.0% to 73.0% | 90.0% to 95.0% |
Table 4: Fine Confectionery & Channel Spending Indicators for the Premium Chocolate Market (USD billion and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 37.2 billion | 2026 global revenue baseline |
| World gross cocoa production, 2024/25 | 4.733 million MT | ICCO August 2026 Quarterly Bulletin (4.649M MT grindings; 28.2% stocks-to-grindings) |
| U.S. confectionery retail sales, 2025 | USD 55.0 billion | NCA State of Treating 2026 (64% of buyers stick with favorite brand when money is tight) |
| Tablets and Molded Chocolate Bars revenue, 2026 | USD 21.6 billion | 58.0% product format allocation |
Exporting fine chocolate tablets and cocoa liquor into the European Union now requires farm-level geolocation polygon coordinates proving zero post-2020 forest degradation. In July 2026, the European Commission adopted a Delegated Act and Information System Implementing Act to support EU Deforestation Regulation (EUDR) compliance ahead of its end-of-December 2026 application. Suppliers processing cocoa derivatives and single-origin couverture consequently integrate satellite polygon verification directly into their cooperative purchasing ledgers.
Analyst Perspective
"Elevated cocoa bean prices have split the confectionery aisle in two: mass candy bars lose volume when prices rise, while 70% dark single-origin tablets and luxury gift boxes retain pricing power. Chocolatiers that combine polygon-traced cacao estates with multi-textured praline craftsmanship will capture the bulk of industry profit pool expansion through 2036."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Premium Chocolate Market segmented?
The premium chocolate market is segmented by chocolate type, product format, sourcing credential, cocoa content tier, and distribution channel. In 2026, Premium Dark Chocolate 70 Percent Plus is projected at 52.0%, Tablets and Molded Chocolate Bars at 58.0%, Bean-to-Bar Single Origin at 48.0%, 70 to 85 Percent Extra-Bitter at 55.0%, and Specialty Chocolate Boutiques and Gifting Retail at 46.0%.
By chocolate type: Premium Dark Chocolate 70 Percent Plus, Artisanal Milk Chocolate, Single-Origin White Chocolate, and Flavored and Infill Pralines.
By product format: Tablets and Molded Chocolate Bars, Boxed Assortments and Truffles, Bite-Sized Pralines and Batons, and Luxury Seasonal Gift Hampers.
By sourcing credential: Bean-to-Bar Single Origin, Fairtrade and Rainforest Alliance Certified, Organic and Direct Trade Cocoa, and Conventional Fine Flavor.
By cocoa content tier: 70 to 85 Percent Extra-Bitter, 55 to 69 Percent Balanced Dark, 35 to 54 Percent High-Cocoa Milk, and Under 35 Percent Cocoa Butter White and Blonde.
By distribution channel: Specialty Chocolate Boutiques and Gifting Retail, Premium Supermarkets and Gourmet Grocers, Travel Retail and Airport Duty-Free, and Direct-to-Consumer Online Gifting.
Why does Premium Dark Chocolate 70 Percent Plus lead the chocolate type category?
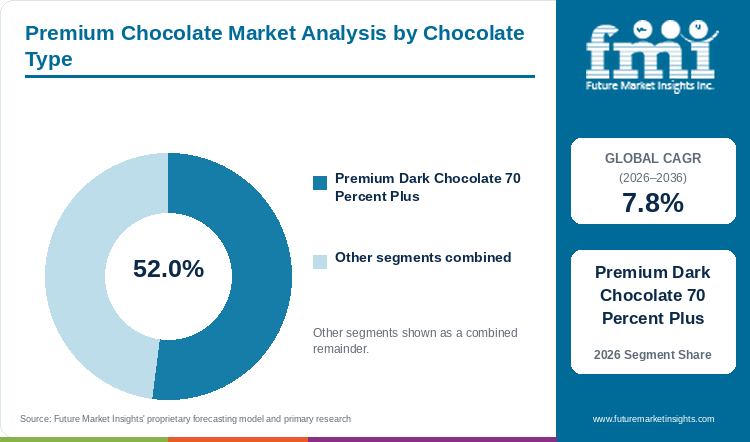
Premium Dark Chocolate 70 Percent Plus holds an estimated 52.0% of chocolate type demand in 2026, anchored by high cacao-solid purity, flavanol content, and clean-label ingredient lists.
Table 5: Chocolate Type Share for the Premium Chocolate Market (percentage share), 2026
| Chocolate Type | Share (2026) |
|---|---|
| Premium Dark Chocolate 70 Percent Plus | 52.0% |
| Other Segments Combined | 48.0%* |
| Total | 100.0% |
*Note: Remaining chocolate type categories account for the balance of 2026 global premium chocolate demand.
Table 6: Chocolate Type Leadership and Market Growth for the Premium Chocolate Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.8% |
| Leading Segment | Premium Dark Chocolate 70 Percent Plus |
Premium Dark Chocolate 70 Percent Plus leads global value because high non-fat cocoa solids and pure cocoa butter showcase estate-specific fruit, floral, and roasted-nut flavor precursors developed during wooden-box fermentation. Connoisseurs and health-conscious buyers favor 70% and higher dark recipes containing minimal cane sugar and zero dairy allergens, often paired with roasted hazelnuts, sea salt, or chocolate inclusions and decorations. Financial disclosures from Chocoladefabriken Lindt & Sprungli AG in July 2026 confirm that strong brand equity across Excellence dark tablets and Lindor lines drove 4.3% organic sales growth and an 11.2% operating EBIT margin across global retail and boutique channels in the first half of 2026. High cocoa-solid inclusion rates (70% to 90% by weight) nonetheless expose dark chocolate makers to steeper raw bean cost swings than milk or filled confectionery.
- Within the chocolate type segment, Premium Dark Chocolate 70 Percent Plus is projected to account for a leading 52.0% share in 2026, driven by clean-label two-ingredient recipes and flavanol-linked wellness positioning.
- While high-cocoa dark chocolate maintains category leadership through 2036, artisanal high-cocoa milk chocolate (40% to 50% cacao) and pistachio- or fruit-filled pralines are anticipated to expand rapidly among younger Millennial and Gen Z shoppers.
What sustains Tablets and Molded Chocolate Bars leadership in the product format segment?
Tablets and Molded Chocolate Bars represent a projected 58.0% of the product format category in 2026, supported by scored portion control, ambient stability, and origin wrapper storytelling.
Tablets and Molded Chocolate Bars ranging from 70-gram craft origin slabs to 100-gram scored tasting bars dominate retail volume because flat molded geometry maximizes glossy temper snap, aroma release, and shelf-facing brand visibility. Unlike hand-piped truffles that require chilled humidity cabinets or defatted cocoa powder beverage mixes, foil- and paper-wrapped tablets achieve twelve-to-eighteen-month ambient stability while costing less to package per gram. Even so, thin-bar molding lines require precise Form V beta-crystal tempering control to prevent gray fat bloom during summer parcel shipping.
- In 2026, Tablets and Molded Chocolate Bars are anticipated to capture 58.0% of global product format demand, reflecting everyday self-treating convenience and broad gourmet grocery distribution.
- Quarterly financial filings from The Hershey Company in October 2026 illustrate how core molded bar and seasonal assortment pricing supported a 3.0% rise in third-quarter 2026 consolidated net sales and a 1,090-basis-point adjusted gross margin recovery to 42.7%.
How does Bean-to-Bar Single Origin lead the sourcing credential category?
Bean-to-Bar Single Origin lines account for an anticipated 48.0% of sourcing credential volume in 2026, driven by GPS polygon farm traceability and estate-specific fermentation.
Bean-to-Bar Single Origin chocolates crafted from specific cacao regions in Madagascar, Ecuador, Peru, Ghana, and Cote d'Ivoire lead sourcing credentials because buyers pay a premium for verifiable terroir and farm-level story transparency. Craft roasters and luxury pastry chefs pairing organic cocoa with single-plantation provenance control every step from post-harvest fermentation to stone melangeur conching. Corporate traceability disclosures from Valrhona SAS in May 2025 substantiate this model, confirming that 100% of its partner cocoa plots of all sizes are GPS polygon-mapped against 20-year forest cover maps under contracts averaging 8.5 years that increase partner cocoa farmer incomes by more than twofold to sevenfold per hectare. Single-origin dependence can still create vintage-to-vintage flavor variation when localized weather alters bean acidity.
- By sourcing credential, demand for Bean-to-Bar Single Origin chocolate is estimated to reach 48.0% of total category share in 2026, supported by satellite plot traceability and estate-specific tasting profiles.
- Fairtrade, Rainforest Alliance, and organic direct-trade credentials are projected to grow in tandem through 2036 as European supermarkets mandate dual sustainability and living-income verification on all premium confectionery shelves.
Why does 70 to 85 Percent Extra-Bitter lead the cocoa content tier category?
70 to 85 Percent Extra-Bitter formulations secure an estimated 55.0% of cocoa content tier value in 2026, balancing rich cacao polyphenol intensity with smooth cocoa-butter melt.
Formulations in the 70 to 85 Percent Extra-Bitter tier represent the commercial sweet spot of the dark chocolate spectrum, delivering concentrated cacao polyphenols and complex roast notes without the chalky dryness of 90% and higher bars. Food scientists and master chocolatiers carefully adjust conching temperatures and cocoa butter ratios in 70% to 85% recipes so the bar melts smoothly at human body temperature (34 to 37 degrees Celsius). In warm tropical distribution corridors across Latin America and Asia, high-cocoa bars still require specialized fat-crystal stabilization to prevent softening.
- Consistent repeat purchasing by dark-chocolate enthusiasts places 70 to 85 Percent Extra-Bitter recipes on course to hold an estimated 55.0% share of the cocoa content tier category in 2026.
- Laboratory research published in Food Chemistry in August 2026 demonstrated that formulating dark chocolate with ternary blends of 70% cocoa butter, 10% to 20% mango kernel fat stearin, and 10% to 20% soybean oil-based structured fat raises solid fat content at 35 degrees Celsius and improves heat stability.
What gives Specialty Chocolate Boutiques and Gifting Retail the leading position in distribution channel?
Specialty Chocolate Boutiques and Gifting Retail command a projected 46.0% of distribution channel share in 2026, anchored by climate-controlled praline counters and seasonal gift ballotins.
Specialty Chocolate Boutiques and Gifting Retail including brand-owned flagship stores, luxury department store food halls, and artisanal chocolateries capture the largest channel value by offering temperature-controlled ballotin gift boxes, seasonal hampers, and personalized ribbon wrapping. Ethical sourcing credentials strengthen boutique brand equity, as Fairtrade International reported in June 2026 that 15 commercial cocoa partners now pay Living Income Reference Prices while certified producer organizations generated record Fairtrade Premium community investments across the 2021 to 2025 strategy cycle. High urban flagship retail rents and seasonal staffing spikes around Valentine's Day, Easter, and Christmas remain key overhead challenges for boutique operators.
- Specialty Chocolate Boutiques and Gifting Retail are predicted to secure 46.0% of distribution channel demand in 2026, anchored by high average transaction values and corporate and holiday gifting traditions.
- Direct-to-consumer cold-pack e-commerce and international airport travel retail are forecast to post rapid channel gains through 2036 as luxury chocolatiers expand insulated express shipping and duty-free boutique counters.
What are the drivers, restraints, and opportunities in the Premium Chocolate Market?
In the premium chocolate market, flavanol-linked dark chocolate trade-up and luxury seasonal gifting are projected to drive adoption, while elevated cocoa butter prices and cadmium/EUDR compliance restrain margins and botanical/savory inclusions unlock new demand.
- Driver: Consumer trade-up toward flavanol-rich 70% and higher dark chocolate, seasonal luxury gifting traditions, and verified single-origin bean-to-bar craftsmanship drive sustained value expansion.
- Restraint: Elevated cocoa bean and cocoa butter costs, strict European Union cadmium limits in South American fine cacao, and mandatory EUDR geolocation compliance restrain processor margins.
- Opportunity: Multi-sensory Asian and botanical flavor inclusions, caramelized blonde and ruby chocolate formats, and heat-stable tropical couverture unlock new regional buyer cohorts.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Health-conscious adults and luxury gifting shoppers are driving a structural trade-up from sugar-dense mass confectionery toward high-cocoa dark tablets and artisanal pralines that offer documented bioactive flavanol benefits and transparent origin credentials. Rather than consuming large quantities of compound candy, buyers purchase scored 70%-to-85% dark bars and single-estate tasting squares as part of a daily wellness and cognitive-health routine alongside specialty formats such as caramelized white chocolate. A GRADE-assessed systematic review and meta-analysis published in Nutrition Reviews in August 2026 across 16 randomized controlled trials and 2,847 participants confirmed that chronic dark chocolate or cocoa intake providing at least 500 milligrams of cocoa flavanols per day for 8 weeks or longer significantly improved Trail Making Test executive function and verbal fluency scores. This convergence of clinical wellness validation and luxury gifting prestige continues expanding premium unit values through 2036.
Risk Assessment of the Premium Chocolate Market: Operational and Formulation Friction
Natural soil cadmium accumulation in fine-flavor Latin American cacao estates alongside volatile cocoa butter ratios and strict European regulatory ceilings represent the primary operational hurdles restraining single-origin chocolate producers. Unlike West African bulk Amelonado cocoa that converts easily into standard compound chocolate or mass milk bars, fine Criollo and Trinitario beans grown in young volcanic South American soils frequently absorb elevated trace cadmium averaging 1.39 mg/kg compared with 0.09 mg/kg in West Africa. In February 2025, agricultural scientists reporting in the journal Agriculture highlighted that European Commission Regulation (EU) No. 488/2014 caps cadmium in chocolate at 0.10 to 0.80 milligrams per kilogram of dry matter, compelling single-origin makers to apply zinc/lime soil amendments or low-accumulator rootstocks. Combined with multi-year highs in cocoa butter pricing, these analytical testing and parcel-segregation requirements raise batch qualification costs for small bean-to-bar roasters.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Chocolatiers and gourmet brands are unlocking new demand avenues by pairing single-origin dark chocolate with fermented Asian botanicals, savory umami textures, and lower-sweetness clean-label inclusions while exploring partial carob-based cocoa replacers in adjacent bakery fillings. Younger Gen Z and Millennial buyers actively seek adventurous flavor pairings such as matcha, yuzu, black sesame, and fermented marine or botanical infusions that turn a standard chocolate tablet into a culinary tasting experience. Sensory research published in the journal Foods in June 2026 across 83 consumers demonstrated that enriching 54.5% Callebaut dark chocolate with Aspergillus oryzae-fermented laver (Porphyra umbilicalis) significantly increased flavor liking (6.5 vs. 5.7) and overall acceptance (6.6 vs. 5.7) over unfermented seaweed. Launching limited-edition seasonal origin bars and bite-sized botanical pralines allows premium brands to command higher per-kilogram margins without diluting flagship heritage recipes.
Premium Chocolate Market by Country (2026 to 2036)
FMI country modeling indicates that Brazil leads premium chocolate expansion at an 8.7% CAGR through 2036, while France advances at a 7.0% CAGR. Commercial growth across Latin American tree-to-bar origin retail networks, North American specialty grocery and gifting channels, and European and Japanese master chocolatier markets reflects local cacao origin pride, gifting rituals, and boutique store expansion.
Table 7: Country CAGR and Primary Growth Levers for the Premium Chocolate Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Brazil | 8.7% | Bahia and Para tree-to-bar fine-cocoa boutiques and Ferrero's Bold Snacks acquisition |
| Mexico | 8.5% | Ancestral Tabasco/Chiapas criollo craft roasters and luxury resort/department-store retail |
| Canada | 8.1% | USD 1,508M #1 U.S. chocolate export destination and high Fairtrade dark-tablet affinity |
| United States | 7.9% | USD 55B confectionery baseline, +12.7% H1 2026 Lindt North America growth, and natural grocery bars |
| Japan | 7.5% | Depachika Valentine/White Day self-gifting salons and Lindt Tokyo Style matcha innovation |
| United Kingdom | 7.4% | High-street cacao boutiques, Fairtrade retail charters, and HFSS shift to 70%+ dark bars |
| Italy | 7.3% | Lindt's new Italian Choco Wafer factory (operational 2027) and Piedmontese gianduja heritage |
| France | 7.0% | 20.4% specialized food and commercial artisan retail share and MOF dark degustation culture |
Source: Future Market Insights analysis
Brazil Premium Chocolate Market Outlook (2026 to 2036)
Demand for premium chocolate in Brazil is projected to expand at a leading 8.7% CAGR between 2026 and 2036 as domestic tree-to-bar chocolatiers and monobrand mall boutiques convert fine Bahia and Para cacao into high-value tablets and gift assortments. What distinguishes Brazil from import-dependent chocolate markets is the rapid rise of domestic fine-cocoa origin designations (such as Sul da Bahia and Transamazonica) alongside vast franchised specialty chocolate store networks during Easter and Christmas gifting peaks. Global confectionery groups are also investing directly in Brazilian manufacturing, evidenced on March 18, 2026 when the Ferrero Group signed an agreement to acquire Brazilian premium protein snack company Bold Snacks and its Divinópolis factory in Minas Gerais, with approximately 300 employees expected to join Ferrero Brazil [14]. High ambient tropical temperatures across Brazilian distribution routes nevertheless require refrigerated retail display cases and heat-tolerant cocoa butter tempering.
Key takeaway: In Brazil, domestic Bahia and Para tree-to-bar origin boutiques and multinational M&A investments are projected to drive a leading 8.7% CAGR.
Mexico Premium Chocolate Market Outlook (2026 to 2036)
Mexico's premium chocolate market is anticipated to advance at an 8.5% CAGR from 2026 to 2036, supported by ancestral Tabasco and Chiapas criollo cacao heritage, luxury tourism retail, and expanding gourmet department-store counters. Compared with mass domestic table-chocolate disks used for hot beverages, premium demand in Mexico centers on 70% and higher single-estate dark bars, artisanal bonbons, and imported European gift boxes sold in Mexico City, Monterrey, and Cancun resort corridors. According to the April 2026 USDA Foreign Agricultural Service Mexico Food Processing Ingredients Annual, Mexico's 13th-largest global economy recorded all-time-high agricultural and food-processing ingredient imports in 2025 with rising commercial demand for tree nuts, dairy solids, and gourmet confectionery inputs. Domestic cacao harvest deficits and NOM-051 warning-label compliance remain key operational considerations for premium brands formulating low-sugar dark tablets.
Key takeaway: In Mexico, ancestral criollo cacao craft chocolateries and luxury department-store gifting are anticipated to sustain an 8.5% CAGR.
Canada Premium Chocolate Market Outlook (2026 to 2036)
In Canada, premium chocolate sales are forecast to grow at an 8.1% CAGR over the 2026 to 2036 forecast period across specialty grocers, bilingual seasonal gifting boutiques, and domestic bean-to-bar roasters. Canada stands out in North America for its high per capita consumption of European-style dark tablets and Fairtrade-certified organic chocolate bars alongside large domestic confectionery manufacturing hubs in Ontario and Quebec. In August 2025, the USDA Foreign Agricultural Service Canada Exporter Guide Annual confirmed that Canada remains the top international destination for U.S. consumer-oriented agricultural products, accounting for roughly 25% of total U.S. consumer-oriented exports. Strict Canadian bilingual labeling rules and rising cocoa butter import costs compel domestic chocolatiers to lock in long-term hedged couverture supply.
Key takeaway: In Canada, strong European dark-tablet affinity and cross-border confectionery manufacturing scale are forecast to drive an 8.1% CAGR.
United States Premium Chocolate Market Outlook (2026 to 2036)
Commercial demand for premium chocolate in the United States is estimated to progress at a 7.9% CAGR between 2026 and 2036 across natural supermarket chains, specialty gifting boutiques, and direct-to-consumer cold-chain e-commerce. What sets the United States apart from traditional European praline markets is the scale of its craft bean-to-bar movement paired with nationwide natural grocery planograms dedicated to 70%-to-85% organic and Regenerative Organic dark tablets. Official trade records published in the USDA Foreign Agricultural Service Chocolate and Cocoa Products 2025 Export Highlights documented that U.S. chocolate and cocoa product exports rose 11% in 2025 to an all-time record high led by a 23% surge in shipments to Canada and a 6% increase to Mexico. California Proposition 65 lead and cadmium notification thresholds require U.S. premium dark chocolate brands to test every imported fine-cocoa lot prior to roasting.
Key takeaway: In the United States, record 11% chocolate export growth and natural grocery dark-bar planograms are estimated to support a 7.9% CAGR.
Japan Premium Chocolate Market Outlook (2026 to 2036)
Japan's premium chocolate market is projected to expand at a 7.5% CAGR through 2036, anchored by prestigious department-store (depachika) chocolate salons, high-polyphenol functional dark chocolate habits, and artisanal bean-to-bar craftsmanship. Rather than treating chocolate solely as a casual snack, Japanese shoppers drive massive seasonal gifting surges during Valentine's Day and White Day (increasingly focused on jibun-choco self-reward boxes) while buying 72%-to-86% cacao pouches daily for cardiovascular wellness. In November 2025, the USDA Foreign Agricultural Service Japan Retail Foods Annual highlighted that Japan's retail food sector expanded steadily across supermarkets, 24-hour convenience stores, and luxury department-store food halls. Weakness in the Japanese yen against the U.S. dollar and Swiss franc has increased landed costs for imported European pralines, encouraging domestic production of single-origin tablets.
Key takeaway: In Japan, depachika luxury self-gifting salons and daily high-polyphenol dark chocolate consumption are projected to sustain a 7.5% CAGR.
United Kingdom Premium Chocolate Market Outlook (2026 to 2036)
Sales of premium chocolate in the United Kingdom are slated to advance at a 7.4% CAGR from 2026 to 2036 across monobrand high-street boutiques, supermarket finest-tier private labels, and subscription tasting clubs. The United Kingdom diverges from continental Europe through its rapid adoption of direct-to-consumer velvetiser drinking chocolate, ethical Fairtrade supermarket charters, and innovative dark-milk (45% to 55% cocoa) bars. According to the March 2026 USDA Foreign Agricultural Service United Kingdom Food Processing Ingredients Annual, food and drink form the United Kingdom's largest manufacturing sector as new advertising and HFSS regulatory restrictions compel confectionery brands to re-engineer formulations and packaging. Because HFSS rules restrict end-aisle promotions on high-sugar confectionery, British retailers allocate prime display space to 70% and higher dark chocolate and portion-controlled luxury gifting boxes.
Key takeaway: In the United Kingdom, high-street cacao boutiques, Fairtrade retail charters, and HFSS dark-chocolate shifts are slated to drive a 7.4% CAGR.
Italy Premium Chocolate Market Outlook (2026 to 2036)
In Italy, premium chocolate demand is anticipated to grow at a 7.3% CAGR over the 2026 to 2036 horizon, supported by historic Piedmontese gianduja and hazelnut praline craftsmanship, Modica IGP stone-ground chocolate, and luxury travel retail. Italian consumption centers on artisanal pasticcerie, specialty gourmet shops, and flagship boutiques in Milan, Turin, Rome, and Florence that pair roasted IGP Piedmont hazelnuts and Sicilian pistachios with extra-dark couverture. In July 2026, Chocoladefabriken Lindt & Sprungli AG announced in its Half-Year 2026 Results presentation that following highly successful pilot launches in Italy and the United Kingdom, it is constructing a dedicated Lindt Choco Wafer production facility at its site in Italy scheduled to become operational by 2027. Hot Mediterranean summers from May through September cause Italian grocers to scale back unrefrigerated praline facings seasonally, shifting summer demand toward gelato-paired chocolate wafers.
Key takeaway: In Italy, Lindt's new Italian Choco Wafer factory investment and Piedmontese gianduja heritage are anticipated to support a 7.3% CAGR.
France Premium Chocolate Market Outlook (2026 to 2036)
French demand for premium chocolate is predicted to progress at a 7.0% CAGR between 2026 and 2036 across the world's densest network of Meilleurs Ouvriers de France (MOF) chocolatiers, gourmet patisseries, and dark-chocolate supermarket aisles. Unlike Anglo-Saxon markets where milk chocolate historically dominated, French adult consumers strongly favor 70%-to-85% degustation dark tablets and single-plantation ganache assortments during Easter, Christmas, and dinner-party gifting. In September 2026, the USDA Foreign Agricultural Service France Retail Foods Annual documented that specialized food stores and commercial artisans accounted for 20.4% of French food retail sales alongside 58.6% in general food retailers as consumer inflation moderated to 0.9%. Sharp increases in French retail cocoa and chocolate price indices between 2024 and 2026 have prompted chocolatiers to introduce smaller 50-gram tasting tablets and 6-piece ballotin gift boxes.
Key takeaway: In France, a 20.4% specialized food and commercial artisan retail share and dark-tablet tasting culture are predicted to sustain a 7.0% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Premium Chocolate Market?
Chocoladefabriken Lindt & Sprungli AG, Ferrero International SA, Mondelez International, Inc., Godiva Chocolatier Inc., The Hershey Company, Valrhona SAS, Neuhaus NV, Barry Callebaut AG, Puratos Group NV, and Olam Food Ingredients are the notable companies in the premium chocolate market.
Competitive positioning in the premium chocolate industry spans global luxury tablet and boxed-praline leaders, heritage Belgian and French artisanal chocolatiers, and vertically integrated B2B fine-couverture and cocoa processors. Chocoladefabriken Lindt & Sprungli AG, Ferrero International SA, Mondelez International, Inc., and The Hershey Company scale global dark tablets, seasonal gift boxes, and organic craft brands across retail and travel channels. Godiva Chocolatier Inc., Valrhona SAS, and Neuhaus NV anchor boutique Belgian pralines and chef-grade single-estate couverture, while Barry Callebaut AG, Puratos Group NV, and Olam Food Ingredients supply traceable fine-flavor beans, liquor, and couverture.
- Global Branded Premium Tablet and Boxed Gifting Leaders: Ferrero International SA, Chocoladefabriken Lindt & Sprungli AG, The Hershey Company, and Mondelez International, Inc. supply dark tablets and seasonal ballotins.
- Boutique Belgian Praline and Chef Couverture Houses: Godiva Chocolatier Inc., Valrhona SAS, and Neuhaus NV operate luxury monobrand boutiques and supply polygon-traced single-origin couverture to fine pastry chefs.
- Vertically Integrated Fine Cocoa and Couverture Processors: Barry Callebaut AG, Puratos Group NV, and Olam Food Ingredients manage origin fermentation, EUDR-compliant bean sourcing, and professional chocolate couverture plants.
Competitive Benchmarking: Premium Chocolate Market
Table 8: Competitive Benchmarking for the Premium Chocolate Market (qualitative capability ratings), 2026
| Company | Single-Origin & EUDR Traceability | Molding & Praline Craftsmanship | Boutique & Gifting Channel Reach | Geographic Reach |
|---|---|---|---|---|
| Chocoladefabriken Lindt & Sprungli | High | High | High | Global network (CHF 2.33B H1 2026 sales, +4.3% OSG); new Italian Choco Wafer factory |
| Ferrero International SA | High | High | High | 170+ countries, 36 plants, EUR 19.3B FY24/25 turnover; Rocher, Thorntons, Bold Snacks |
| Mondelez International, Inc. | High | High | High | 150+ countries (USD 38.5B FY25; USD 9.97B Q3 26); ~100% Cocoa Life across 257,000+ farmers |
| Godiva Chocolatier Inc. | Medium | High | High | Global boutiques, department stores, and grocery gifting aisles across Americas, Europe, Asia |
| The Hershey Company | High | High | Medium | North America and international (USD 3.28B Q3 2026, 42.7% adj. gross margin); Lily's, dark lines |
| Valrhona SAS | High | High | High | B-Corp certified French single-origin couverture leader; 100% GPS polygon-mapped plots |
| Neuhaus NV | High | High | High | Inventor of the Belgian praline and ballotin box; Brussels ateliers and global travel retail |
| Barry Callebaut AG | High | High | Medium | Global B2B chocolate and single-origin couverture leader; Future of Taste 2026 framework |
| Puratos Group NV | High | High | Medium | 100+ countries; Belcolade real Belgian chocolate and Cacao-Trace fermented single-origin lines |
| Olam Food Ingredients (ofi) | High | Medium | Medium | Global origin cocoa bean, single-origin liquor, and natural/alkalized cocoa butter supplier |
Key Developments in the Premium Chocolate Market
In October 2026, Chocoladefabriken Lindt & Sprüngli AG announced the departure of Group CEO Adalbert Lechner and initiated a formal search for a successor expected to be appointed in the second quarter of 2027. The Board stated that new operational leadership is required to return the group to consistent, strong growth across all global markets following a year of volume pressure driven by groupwide price increases of 11.8% [25].
In October 2026, The Hershey Company reported third-quarter 2026 financial results, with consolidated net sales increasing 3.0% to USD 3,275.5 million. Adjusted gross margin recovered 1,090 basis points to 42.7%, driven by net price realization, lower net commodity costs, and productivity program savings [26].
In March 2026, Ferrero Group signed an agreement to acquire Bold Snacks, a leading Brazilian premium protein snack company. As part of the transaction, Ferrero will take over Bold Snacks’ office and factory in Divinópolis, Minas Gerais, with approximately 300 employees expected to join Ferrero Brazil, marking the group’s first entry into the better-for-you snacking segment in South America [27].
Key Players in the Premium Chocolate Market
Global Branded Premium Tablet and Boxed Gifting Leaders
- Chocoladefabriken Lindt & Sprungli AG
- Ferrero International SA
- Mondelez International, Inc.
- The Hershey Company
Boutique Belgian Praline and Chef Couverture Houses
- Godiva Chocolatier Inc.
- Valrhona SAS
- Neuhaus NV
- Barry Callebaut AG
Vertically Integrated Fine Cocoa and Couverture Processors
- Puratos Group NV
- Olam Food Ingredients
Premium Chocolate Market - Report Scope
Table 9: Report Scope for the Premium Chocolate Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Chocolate Type; Product Format; Sourcing Credential; Cocoa Content Tier; Distribution Channel |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial retail, boutique, travel-retail, and foodservice sales of premium dark chocolate (70%+ and 55%-69% cacao), artisanal high-cocoa milk chocolate, single-origin pure-cocoa-butter white and blonde chocolate, and filled pralines, truffles, and seasonal gift ballotins formulated exclusively with pure cocoa butter. Category Scope Note: Excludes mass-market compound chocolate formulated with palm or lauric vegetable fat substitutes, non-chocolate sugar candy, and unrefined bulk cocoa beans. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Brazil, Mexico, Canada, United States, Japan, United Kingdom, Italy, France, and additional countries in the full report |
| Key Companies Covered | Chocoladefabriken Lindt & Sprungli AG, Ferrero International SA, Mondelez International, Inc., Godiva Chocolatier Inc., The Hershey Company, Valrhona SAS, Neuhaus NV, Barry Callebaut AG, Puratos Group NV, Olam Food Ingredients |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Premium Chocolate Market - Research Methodology
Table 10: Research Methodology for the Premium Chocolate Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with master chocolatiers, bean-to-bar cocoa roasters, EUDR geolocation compliance officers, and luxury department-store and travel-retail confectionery buyers to validate price realization and cocoa-solid specifications. |
| Secondary Research | Analysis of International Cocoa Organization (ICCO) Quarterly Bulletins of Cocoa Statistics, National Confectioners Association State of Treating 2026 data, European Commission EUDR notices, USDA FAS GAIN reports, and corporate financial filings. |
| Market Sizing and Forecasting | Top-down global chocolate confectionery retail baselines reconciled against bottom-up fine-flavor cocoa bean grindings (4.65M MT total world grindings), pure-cocoa-butter couverture shipments, and monobrand boutique sales from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight domestic fine-cacao origin production, seasonal gifting expenditure, HFSS and NOM-051 sugar regulations, and cadmium/EUDR traceability rules across eight national markets. |
| Operational Benchmark Traceability | Cocoa bean grindings, fine-flavor tonnage, and trade indicators in Tables 2, 3, and 4 trace to ICCO August 2026 statistics, NCA 2026 State of Treating retail figures, and USDA FAS BICO HS-10 export data. |
| Data Triangulation and Validation | Revenue estimates isolate pure-cocoa-butter premium tablets, pralines, truffles, and artisanal couverture while strictly excluding lauric compound coatings and mass-market sugar confectionery. |
Premium Chocolate Market by Segments
Premium Chocolate Market segmented by Chocolate Type:
- Premium Dark Chocolate 70 Percent Plus
- Artisanal Milk Chocolate
- Single-Origin White Chocolate
- Flavored and Infill Pralines
Premium Chocolate Market segmented by Product Format:
- Tablets and Molded Chocolate Bars
- Boxed Assortments and Truffles
- Bite-Sized Pralines and Batons
- Luxury Seasonal Gift Hampers
Premium Chocolate Market segmented by Sourcing Credential:
- Bean-to-Bar Single Origin
- Fairtrade and Rainforest Alliance Certified
- Organic and Direct Trade Cocoa
- Conventional Fine Flavor
- Single-Estate Vintage Cacao (Sourcing Sub-Segment)
Premium Chocolate Market segmented by Cocoa Content Tier:
- 70 to 85 Percent Extra-Bitter
- 55 to 69 Percent Balanced Dark
- 35 to 54 Percent High-Cocoa Milk
- Under 35 Percent Cocoa Butter White and Blonde
Premium Chocolate Market segmented by Distribution Channel:
- Specialty Chocolate Boutiques and Gifting Retail
- Premium Supermarkets and Gourmet Grocers
- Travel Retail and Airport Duty-Free
- Direct-to-Consumer Online Gifting
Premium Chocolate Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] National Confectioners Association. (2026, March 15). State of Treating 2026. National Confectioners Association Sweet Insights.
- [2] Ferrero International SA. (2026, February 6). Ferrero Group Reports Consolidated Financial Statements for the 2024/2025 Financial Year. Ferrero Group Corporate Newsroom.
- [3] International Cocoa Organization. (2026, August 31). August 2026 Quarterly Bulletin of Cocoa Statistics. International Cocoa Organization Secretariat (Volume LII, Issue No. 3).
- [4] Barry Callebaut AG. (2026, February 3). Barry Callebaut releases 'Top Chocolate Confectionery Trends 2026 & Beyond' report. Barry Callebaut Group Media Releases.
- [5] European Commission Directorate-General for Environment. (2026, July 13). Commission updates product scope and tools to support EUDR. European Commission Environment News.
- [6] Chocoladefabriken Lindt & Sprungli AG. (2026, July 21). Half-Year Report 2026. Chocoladefabriken Lindt & Sprungli AG Investor Relations.
- [7] The Hershey Company. (2026, October 29). Hershey Reports Third-Quarter 2026 Financial Results. The Hershey Company Corporate Newsroom.
- [8] Valrhona SAS. (2025, May 23). From producer to maker: 100% traced, fair-trade cocoa. Valrhona Corporate Sustainability News.
- [9] Aondoakaa, I. P., Martini, S., & Akoh, C. C. (2026, August 27). Development of heat-stable dark chocolate using ternary blends of cocoa butter, mango kernel fat stearin, and soybean oil-based structured fat. Food Chemistry, 527, 150926 (PubMed PMID 42667775).
- [10] Fairtrade International. (2026, June 11). Fairtrade International highlights growing business commitment to living incomes and future vision in 2025 Annual Report. Fairtrade International Press Centre.
- [11] Arabpour, Z., Arabpour, Z., & Jazayeri, S. (2026, August 25). Effect of Chronic Dark Chocolate or Cocoa Intake on Cognitive Function: A Grading of Recommendations Assessment, Development, and Evaluation (GRADE)-Assessed Systematic Review and Meta-Analysis of Randomized Controlled Trials. Nutrition Reviews, nuaf286 (PubMed PMID 42641106).
- [12] Garcia Porras, G. A., Santos, J. A. d., Carvalho, M. R. d., Pinzon-Sandoval, E. H., Pereira, A. A. S., & Guilherme, L. R. G. (2025, February 19). Addressing Cadmium in Cacao Farmland: A Path to Safer, Sustainable Chocolate. Agriculture, 15(4), 433.
- [13] Adams, Z., & McSweeney, M. B. (2026, June 6). Enhancing Dark Chocolate with Fermented Laver (Porphyra umbilicalis): Effects on Sensory Characteristics and Consumer Acceptance. Foods, 15(12), 2047.
- [14] Ferrero International SA. (2026, March 18). Ferrero Group acquires Bold Snacks, a leading Brazilian protein snack company. Ferrero Group Corporate Newsroom.
- [15] USDA Foreign Agricultural Service. (2026, April 6). Mexico: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report MX2026-0022.
- [16] USDA Foreign Agricultural Service. (2025, August 1). Canada: Exporter Guide Annual. U.S. Department of Agriculture GAIN Report CA2025-0024.
- [17] USDA Foreign Agricultural Service. (2026, February 10). Chocolate and Cocoa Products 2025 Export Highlights. U.S. Department of Agriculture Foreign Agricultural Service (BICO HS-10).
- [18] USDA Foreign Agricultural Service. (2025, November 19). Japan: Retail Foods Annual. U.S. Department of Agriculture GAIN Report JA2025-0048.
- [19] USDA Foreign Agricultural Service. (2026, March 24). United Kingdom: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report UK2026-0008.
- [20] Chocoladefabriken Lindt & Sprungli AG. (2026, July 21). Transcript of Webcast Presentation on Tuesday 21 July 2026: Lindt & Sprungli Half-Year 2026 Results. Chocoladefabriken Lindt & Sprungli AG Investor Relations.
- [21] USDA Foreign Agricultural Service. (2026, September 30). France: Retail Foods Annual. U.S. Department of Agriculture GAIN Report FR2026-0010.
- [22] Mondelez International, Inc. (2026, October 29). Mondelez International Reports Q3 2026 Results. Mondelez International Investor Relations.
- [23] Rainforest Alliance. (2026, June 24). Explore our 2025 Cocoa Certification Data Report. Rainforest Alliance Certification Reports.
- [24] Mondelez International, Inc. (2026, April 15). Mondelez International Announces 2025 Sustainability Milestones. Mondelez International Investor Relations.
- [25] Chocoladefabriken Lindt & Sprüngli AG. (2026, October 19). Leadership change at CEO level. Lindt & Sprüngli Investor Relations. https://live.deutsche-boerse.com/news/Lindt---Spruengli-announces-leadership-changes-87b0bdb3-539d-40d5-857a-e25851985415[
- 26] The Hershey Company. (2026, October 29). Hershey Reports Third-Quarter 2026 Financial Results. The Hershey Company Corporate Newsroom. https://www.sec.gov/Archives/edgar/data/0000047111/000162828026068046/exhibit991_2026xq3.htm
- [27] Ferrero Group. (2026, March 18). Ferrero Group acquires Bold Snacks, a leading Brazilian protein snack company. Ferrero Group Corporate Newsroom. https://www.prnewswire.co.uk/news-releases/ferrero-group-acquires-bold-snacks-a-leading-brazilian-protein-snack-company-302717441.html
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the premium chocolate market in 2026 and what is forecast for 2036?
- Which flavanol-wellness and luxury gifting habits support demand for premium chocolate?
- Why does Premium Dark Chocolate 70 Percent Plus lead the chocolate type category?
- Why do Tablets and Molded Chocolate Bars lead the product format category globally?
- How do growth rates differ across Brazil, Mexico, Canada, the United States, and Japan?
- Which leading companies operate monobrand praline boutiques versus fine-cocoa processors today?
- What limits single-origin cacao supply or raises cadmium and EUDR compliance costs?
- What should specialty retailers evaluate before qualifying bean-to-bar chocolate suppliers?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Chocolate Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Chocolate Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Chocolate Type, 2026 to 2036
- Premium Dark Chocolate 70 Percent Plus
- Artisanal Milk Chocolate
- Single-Origin White Chocolate
- Flavored and Infill Pralines
- Y-o-Y Growth Trend Analysis By Chocolate Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Chocolate Type, 2026 to 2036
- Global Market Analysis and Forecast, By Product Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Format, 2026 to 2036
- Tablets and Molded Chocolate Bars
- Boxed Assortments and Truffles
- Bite-Sized Pralines and Batons
- Luxury Seasonal Gift Hampers
- Y-o-Y Growth Trend Analysis By Product Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Format, 2026 to 2036
- Global Market Analysis and Forecast, By Sourcing Credential, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sourcing Credential, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sourcing Credential, 2026 to 2036
- Bean-to-Bar Single Origin
- Fairtrade and Rainforest Alliance Certified
- Organic and Direct Trade Cocoa
- Conventional Fine Flavor
- Single-Estate Vintage Cacao (Sourcing Sub-Segment)
- Y-o-Y Growth Trend Analysis By Sourcing Credential, 2021 to 2025
- Absolute $ Opportunity Analysis By Sourcing Credential, 2026 to 2036
- Global Market Analysis and Forecast, By Cocoa Content Tier, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Cocoa Content Tier, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Cocoa Content Tier, 2026 to 2036
- 70 to 85 Percent Extra-Bitter
- 55 to 69 Percent Balanced Dark
- 35 to 54 Percent High-Cocoa Milk
- Under 35 Percent Cocoa Butter White and Blonde
- Y-o-Y Growth Trend Analysis By Cocoa Content Tier, 2021 to 2025
- Absolute $ Opportunity Analysis By Cocoa Content Tier, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Specialty Chocolate Boutiques and Gifting Retail
- Premium Supermarkets and Gourmet Grocers
- Travel Retail and Airport Duty-Free
- Direct-to-Consumer Online Gifting
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Chocolate Type
- By Product Format
- By Sourcing Credential
- By Cocoa Content Tier
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Chocoladefabriken Lindt & Sprungli
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Ferrero International SA
- Mondelez International, Inc.
- Godiva Chocolatier Inc.
- The Hershey Company
- Valrhona SAS
- Neuhaus NV
- Barry Callebaut AG
- Puratos Group NV
- Olam Food Ingredients (ofi)
- Chocoladefabriken Lindt & Sprungli AG
- Olam Food Ingredients
- Chocoladefabriken Lindt & Sprungli
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Chocolate Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Sourcing Credential, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Cocoa Content Tier, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Chocolate Type, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Sourcing Credential, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Cocoa Content Tier, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Chocolate Type, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Sourcing Credential, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Cocoa Content Tier, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Chocolate Type, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Sourcing Credential, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Cocoa Content Tier, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Chocolate Type, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Sourcing Credential, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Cocoa Content Tier, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Chocolate Type, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Sourcing Credential, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Cocoa Content Tier, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Chocolate Type, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Sourcing Credential, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Cocoa Content Tier, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Chocolate Type, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Sourcing Credential, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Cocoa Content Tier, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Chocolate Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Chocolate Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Chocolate Type
- Figure 6: Global Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Product Format
- Figure 9: Global Market Value Share and BPS Analysis by Sourcing Credential, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Sourcing Credential, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Sourcing Credential
- Figure 12: Global Market Value Share and BPS Analysis by Cocoa Content Tier, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Cocoa Content Tier, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Cocoa Content Tier
- Figure 15: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Distribution Channel
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Chocolate Type, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Chocolate Type, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Chocolate Type
- Figure 32: North America Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Product Format
- Figure 35: North America Market Value Share and BPS Analysis by Sourcing Credential, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Sourcing Credential, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Sourcing Credential
- Figure 38: North America Market Value Share and BPS Analysis by Cocoa Content Tier, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Cocoa Content Tier, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Cocoa Content Tier
- Figure 41: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Distribution Channel
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Chocolate Type, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Chocolate Type, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Chocolate Type
- Figure 48: Latin America Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Product Format
- Figure 51: Latin America Market Value Share and BPS Analysis by Sourcing Credential, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Sourcing Credential, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Sourcing Credential
- Figure 54: Latin America Market Value Share and BPS Analysis by Cocoa Content Tier, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Cocoa Content Tier, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Cocoa Content Tier
- Figure 57: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Chocolate Type, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Chocolate Type, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Chocolate Type
- Figure 64: Western Europe Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Product Format
- Figure 67: Western Europe Market Value Share and BPS Analysis by Sourcing Credential, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Sourcing Credential, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Sourcing Credential
- Figure 70: Western Europe Market Value Share and BPS Analysis by Cocoa Content Tier, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Cocoa Content Tier, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Cocoa Content Tier
- Figure 73: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Chocolate Type, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Chocolate Type, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Chocolate Type
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Product Format
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Sourcing Credential, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Sourcing Credential, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Sourcing Credential
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Cocoa Content Tier, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Cocoa Content Tier, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Cocoa Content Tier
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Chocolate Type, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Chocolate Type, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Chocolate Type
- Figure 96: East Asia Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Product Format
- Figure 99: East Asia Market Value Share and BPS Analysis by Sourcing Credential, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Sourcing Credential, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Sourcing Credential
- Figure 102: East Asia Market Value Share and BPS Analysis by Cocoa Content Tier, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Cocoa Content Tier, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Cocoa Content Tier
- Figure 105: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Chocolate Type, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Chocolate Type, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Chocolate Type
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Product Format
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Sourcing Credential, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Sourcing Credential, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Sourcing Credential
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Cocoa Content Tier, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Cocoa Content Tier, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Cocoa Content Tier
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Chocolate Type, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Chocolate Type, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Chocolate Type
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Product Format
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Sourcing Credential, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Sourcing Credential, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Sourcing Credential
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Cocoa Content Tier, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Cocoa Content Tier, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Cocoa Content Tier
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Premium Chocolate Market in 2026, and what is forecast for 2036?
FMI estimates that global premium chocolate revenue stood at USD 34.5 billion in 2025 and reaches USD 37.2 billion in 2026, scaling to USD 78.8 billion by 2036 across gourmet channels.
What is the CAGR for the Premium Chocolate Market from 2026 to 2036?
The premium chocolate sector is projected to expand at a 7.8% CAGR over the 2026 to 2036 window, adding USD 41.6 billion across specialty boutiques, gourmet supermarkets, and travel retail.
Which chocolate type segment leads the Premium Chocolate Market?
Premium Dark Chocolate 70 Percent Plus is projected to hold 52.0% of chocolate type demand in 2026 since buyers value high cacao-solid purity, flavanol antioxidants, and lower sugar content.
Which product format segment leads the Premium Chocolate Market?
Tablets and Molded Chocolate Bars are anticipated to represent 58.0% of the product format category in 2026 owing to convenient scored portioning and ambient shelf stability.
Which country has a notable growth outlook during the assessment period?
Brazil leads national expansion projections at an 8.7% CAGR through 2036, driven by domestic Bahia and Para tree-to-bar fine-cocoa boutiques and monobrand gifting stores.
Who are the key players in the market?
Chocoladefabriken Lindt & Sprungli AG, Ferrero International SA, Mondelez International, Inc., and The Hershey Company lead branded tablets and seasonal assortments, while Godiva, Valrhona SAS, and Neuhaus NV anchor luxury boutiques and Barry Callebaut AG, Puratos Group NV, and ofi supply couverture.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
