

- Market Size (2026)
- USD 19.5 Bn
- Forecast (2036)
- USD 30.3 Bn
- CAGR (2026 to 2036)
- 4.5%
How big is Printing Machinery Market in 2026?
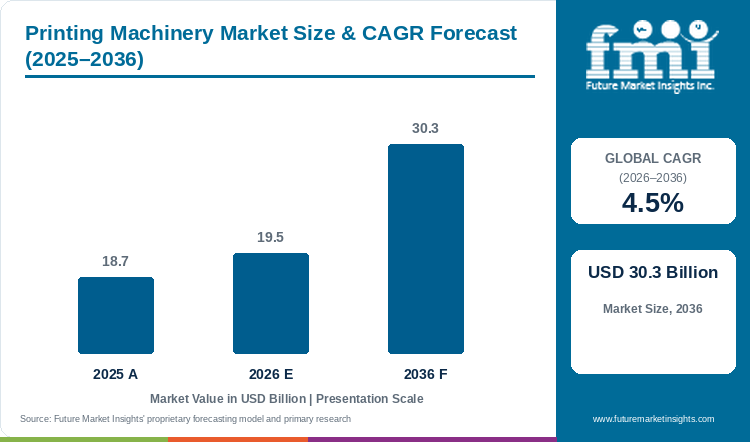
The printing machinery is forecast to register a CAGR of 4.5% through 2036. Revenue increases from USD 18.7 billion in 2025 to USD 19.5 billion in 2026 before reaching USD 30.3 billion by 2036.
Shrinking packaging run lengths and mandatory item-level barcode serialization are forcing commercial converters to retire manual mechanical presses in favor of servo-driven equipment that completes plate and ink changeovers in minutes. Global printing machinery expenditure progresses from a 2025 baseline of USD 18.7 billion to USD 19.5 billion in 2026, with FMI forecasting 2036 equipment revenue of USD 30.3 billion at 4.5% annual compounding and USD 10.8 billion in net value creation. Substrate shifts from rigid plastics to printed paperboard reinforce machinery orders, as Eurostat packaging waste statistics updated in October 2025 confirmed that paper and cardboard accounted for 40.4% of the 79.7 million tonnes of packaging waste generated across the European Union [1]. Fully Automatic High-Speed Web & Sheet-Fed Presses lead press configurations at 54.3% of 2026 expenditure because inline spectrophotometers and automated plate loaders minimize substrate spoilage during frequent artwork switches. Five-country growth rates through 2036 start at 3.6% in France and peak at 5.5% in Italy as packaging converters weigh high press capital outlays against acute shortages of experienced pressroom operators.
Key Market Trends & Insights
- By press configuration: Servo-synchronized plate loaders and closed-loop color cameras give Fully Automatic High-Speed Web & Sheet-Fed Presses 54.3% of 2026 machinery expenditure across large folding-carton and flexible-packaging plants.
- By printing technology: Flexographic & Offset Lithography Press Systems secure 37.7% of 2026 technology turnover as central-impression flexo webs and B1 sheet-fed litho presses deliver low unit costs on medium-to-long packaging runs.
- By end-use industry: Frequent seasonal artwork updates and mandatory nutrition and allergen panels position Food & Beverage Packaging & Labels as the largest end-use buyer at 40.7% of 2026 demand.
Regional Highlights
- Fastest national machinery market: Italy records a 5.5% compound annual rate through 2036 thanks to Transition 5.0 capital tax credits and concentrated flexographic and gravure press manufacturing in Lombardy and Piedmont.
- Broader country performance: Labor-saving pressroom automation drives a 5.0% CAGR in Japan alongside pharmaceutical serialization upgrades at 4.7% in Switzerland, while cosmetics carton embellishment in South Korea (4.0%) and mineral-oil-free packaging retrofits in France (3.6%) round out the profiled economies.
Market Size & Forecast
Table 1: Market Size and Forecast for the Printing Machinery Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 18.7 billion |
| Estimated Market Size in 2026 | USD 19.5 billion |
| Projected Market Size by 2036 | USD 30.3 billion |
| CAGR, 2026 to 2036 | 4.5% |
| Added Revenue, 2026 to 2036 | USD 10.8 billion |
Retail point-of-sale barcode standards are accelerating hybrid press installations across global label and carton plants. Under the GS1 Sunrise 2027 initiative documented in March 2025, retail checkout scanners worldwide are transitioning to read two-dimensional DataMatrix and QR codes that carry dynamic batch numbers and expiration dates alongside allergen links on every package [2]. Printing unique variable-data 2D symbols at speeds above 150 meters per minute requires converters to mount piezoelectric drop-on-demand inkjet bars directly onto flexographic and offset frames, stimulating demand across H:digital printing and H:industrial inkjet printers.
Installed Press Fleet and Makeready Productivity Economics
Table 2: Commercial Press Fleet Shipments and Makeready Efficiency Indicators for the Printing Machinery Market (USD billion, units, and minutes), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global printing machinery market size (USD billion, FMI model) | 18.7 | 19.5 | 30.3 |
| Annual industrial press installations (thousand units, VDMA/METI) | 28.4 to 30.2 | 29.5 to 31.4 | 42.0 to 45.5 |
| Average automated offset/flexo job makeready time (minutes, Fogra) | 4.5 to 6.5 | 4.2 to 6.0 | 2.0 to 3.5 |
| Packaging & label share of total press capital spend (%, modeled) | 64.0 to 67.0 | 65.5 to 68.5 | 74.0 to 78.0 |
Methodology note: Press shipment and makeready benchmarks for 2025 and 2026 draw on VDMA printing machinery statistics and Fogra ProcessStandard ISO 12647 guidelines [19] alongside Koenig & Bauer and Heidelberger Druckmaschinen technical releases.
Press Speed, Substrate Waste & Converter Throughput Benchmarks
Contemporary packaging and commercial printing presses combine servo-driven gearless mandrels and inline camera register inspection with electron-beam or UV-LED curing lamps. Automating plate mounting and blanket washing reduces job changeover waste from more than 300 sheets to fewer than 40 sheets on B1 folding-carton lines. Pressroom productivity data in Tables 3 and 4 reflect Koenig & Bauer order intake disclosures [20] and European Printing Ink Association food-contact GMP standards [21].
Table 3: Global Per Capita and Converter Capital Expenditure Indicators for the Printing Machinery Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion, UN/World Bank baseline) | 8.23 | 8.30 | 8.95 |
| Printing machinery spend per capita (USD, FMI derived) | 2.27 | 2.35 | 3.39 |
| Spend per 1,000 inhabitants (USD, FMI derived) | 2,272.2 | 2,349.4 | 3,385.5 |
| Average capex per B1 8-color packaging press (USD million, OEM basis) | 2.6 to 3.8 | 2.7 to 3.9 | 3.2 to 4.6 |
Table 4: Press Line Speed & Operating Benchmarks for the Printing Machinery Market (USD, sheets/meters per hour, and percentages), mixed reporting years from 2025 to 2026
| Metric | Value | Source / Operational Basis |
|---|---|---|
| Market size, 2026 | USD 19.5 billion | FMI global new press and inline unit baseline |
| Flagship B1 sheet-fed offset press speed | 18,000 to 21,000 sheets/hr | HEIDELBERG & Koenig & Bauer Rapida specs |
| Wide-web CI flexographic press speed | 500 to 800 m/min | Windmöller & Hölscher & Bobst web specs |
| Food & Beverage Packaging revenue, 2026 | USD 7.9 billion | 40.7% leading end-use industry share |
Analyst Perspective
"Packaging converters are prioritizing autonomous press workflows that eliminate manual register setup as skilled press operators retire. Equipment builders must still prove that hybrid digital-analog lines can handle thin mono-material films without web distortion."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the printing machinery market segmented?
The printing machinery market is segmented by press configuration, printing technology, end-use industry, and region. In 2026, Fully Automatic High-Speed Web & Sheet-Fed Presses are projected at 54.3%, Flexographic & Offset Lithography Press Systems at 37.7%, and Food & Beverage Packaging & Labels at 40.7%.
By press configuration: Fully Automatic High-Speed Web & Sheet-Fed Presses, Hybrid Inline Flexo-Digital Converting Presses, and Narrow-Web Modular Label & Specialty Presses.
By printing technology: Flexographic & Offset Lithography Press Systems, High-Speed Production Inkjet & Electrophotographic Digital Presses, and Rotogravure & Screen Printing Machinery.
By end-use industry: Food & Beverage Packaging & Labels, Pharmaceutical & Healthcare Serialization Packaging, Personal Care, Cosmetics & Folding Cartons, and Commercial Publishing & Industrial Graphics.
Why Do Fully Automatic High-Speed Web & Sheet-Fed Presses Lead by Press Configuration?
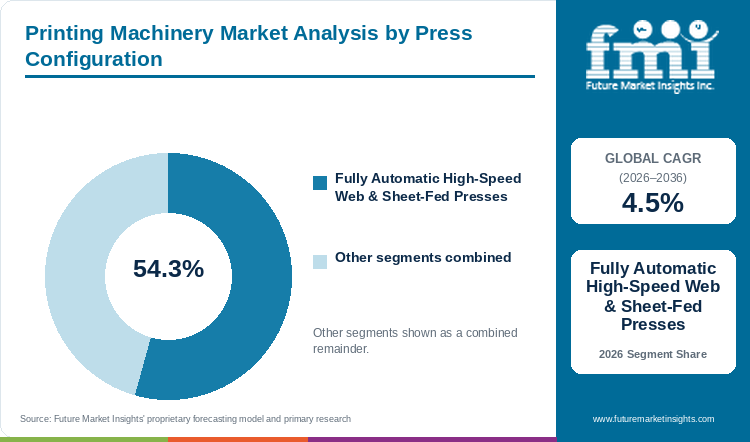
With 54.3% share in 2026, Fully Automatic High-Speed Web & Sheet-Fed Presses lead press configuration, driven by autonomous makeready workflows.
Table 5: Press Configuration Share for the Printing Machinery Market (percentage share), 2026
| Press Configuration | Share (2026) |
|---|---|
| Fully Automatic High-Speed Web & Sheet-Fed Presses | 54.3% |
| Other Segments Combined | 45.7%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Press Configuration Leadership and Market Growth for the Printing Machinery Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.5% |
| Leading Segment | Fully Automatic High-Speed Web & Sheet-Fed Presses |
Fully Automatic High-Speed Web & Sheet-Fed Presses command 54.3% of 2026 press configuration expenditure because folding-carton and flexible-pouch plants rely on simultaneous plate-cylinder loading and inline closed-loop spectrophotometry to keep overall equipment effectiveness high across short SKU runs. Koenig & Bauer AG documented in September 2026 that Australian print group IVE commissioned an eight-color Rapida 106 X sheet-fed offset press operating at 20,000 sheets per hour with inline coating to consolidate commercial and packaging production. Parallel upgrades in H:flexographic printing machines reinforce this shift toward autonomous pressrooms.
- Fully Automatic High-Speed Web & Sheet-Fed Presses represent 54.3% of press configuration revenue in 2026, underpinned by automated plate changing and closed-loop inline defect inspection.
- In September 2026, Koenig & Bauer AG commissioned a 20,000-sheet-per-hour Rapida 106 X fully automatic sheet-fed offset press at IVE Group to accelerate commercial and folding-carton packaging production [3].
What Makes Flexographic & Offset Lithography Press Systems Central to Printing Technology?
Flexographic & Offset Lithography Press Systems are estimated to represent 37.7% of printing technology in 2026, enabled by multi-substrate efficiency.
Flexographic & Offset Lithography Press Systems account for 37.7% of 2026 printing technology revenue as sheet-fed offset dominates folding cartons and central-impression flexography anchors wide-web polyethylene and polypropylene pouch converting. Windmöller & Hölscher KG showcased its updated ALPHAFLEX central-impression flexographic press and VAREX II extrusion systems in October 2025 to help converters print recyclable mono-material barrier films at high registration accuracy. Concurrently, H:digital textile printing and single-pass corrugated inkjet represent the fastest-growing technology tiers.
- Flexographic & Offset Lithography Press Systems hold 37.7% of printing technology demand in 2026, reflecting unmatched ink laydown speed and low plate cost across flexible films and paperboard cartons.
- In October 2025, Windmöller & Hölscher KG presented its ALPHAFLEX central-impression flexographic press at K 2025, featuring automated impression setting and high-efficiency drying for flexible packaging [4].
Why Does Food & Beverage Packaging & Labels Anchor the End-Use Industry Category?
By end-use industry, Food & Beverage Packaging & Labels is projected at 40.7% in 2026, owing to recurring grocery labeling.
Food & Beverage Packaging & Labels captures 40.7% of 2026 end-use demand because grocery brands rely on high-impact shelf graphics and multi-language allergen tables alongside scannable serialization codes across every carton and bottle label. The American Forest & Paper Association reported in January 2026 that U.S. containerboard production remained resilient through Q4 2025 as box plants invested in high-graphics post-print flexo and digital folder-gluers. Demand across H:packaging machinery and H:label printing machines scales alongside these food-contact packaging lines.
- Food & Beverage Packaging & Labels accounts for 40.7% of end-use industry revenue in 2026, sustained by non-discretionary grocery consumption and mandatory nutrition and traceability labeling.
- In January 2026, the American Forest & Paper Association reported that U.S. containerboard and boxboard mills finished Q4 2025 with operating rates above 91%, sustaining substrate supply for food and beverage carton printers [5].
What are the drivers, restraints, and opportunities in the printing machinery market?
In the Printing Machinery Market, plastic-to-paperboard packaging transitions and SKU versioning drive press investments, high capital financing costs and press-operator shortages restrain replacements, and industrial single-pass inkjet integration creates growth opportunities through 2036.
- Driver: Brand owners replacing rigid plastics with printed folding cartons and mono-material flexible films are driving converter investments in automated multi-color packaging presses through 2036.
- Restraint: Multi-million-dollar capital outlays for wide-web and B1 presses combined with acute shortages of experienced press machinists delay equipment replacement among mid-sized printers through 2036.
- Opportunity: Integrating single-pass water-based inkjet and hybrid flexo-digital print bars allows converters to produce zero-plate short runs and variable 2D serialization profitably through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Brand-owner migration from multi-layer plastic laminates toward recyclable folding cartons and mono-material paper wraps compels converters to install heavy-duty sheet-fed offset and wide-web water-based flexo presses. In February 2026, Pro Carton published its 2025 Carbon Footprint Study confirming an 8% reduction in European cartonboard cradle-to-gate fossil emissions across 70 production sites [6]. This verified sustainability advantage is accelerating food and personal-care carton press orders alongside H:rotogravure printing machine upgrades.
Risk Assessment of the Printing Machinery Market: Operational and Supply Friction
Multi-million-dollar capital outlays for B1 sheet-fed and wide-web central-impression presses lengthen converter investment payback periods when industrial interest rates and factory power tariffs rise. VDMA Printing and Paper Technology industry assessments in 2026 note that geopolitical trade friction and cautious European capital goods financing have prompted commercial publication printers to defer full press replacements in favor of control-system retrofits [7].
Commercial Opportunity Analysis: Differentiation and Value-Add Formats
Press manufacturers are capturing recurring lifecycle revenue by bundling single-pass industrial inkjet systems with AI-driven workflow software and automated plate-to-unit logistics. In September 2026, Heidelberger Druckmaschinen AG announced that Austrian commercial printer Klampfer Druck invested in a Jetfire 50 B3 industrial inkjet system integrated via the Prinect workflow to produce short-run jobs profitably alongside sheet-fed offset [8]. Expansion in H:commercial printing and H:printing inks supports these hybrid press deployments.
Printing Machinery Market by Country (2026 to 2036)
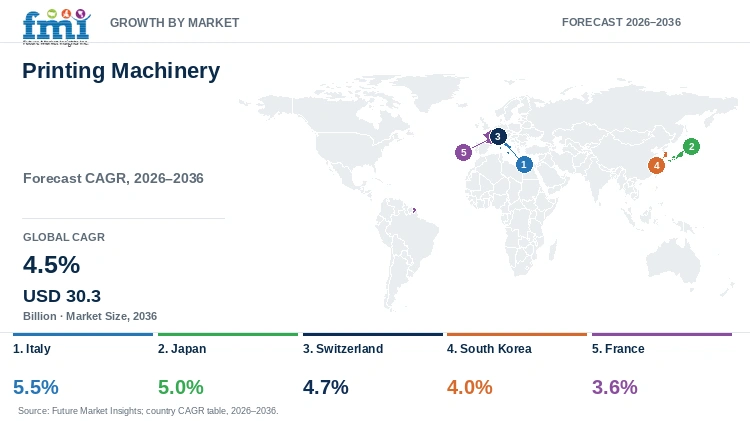
Capital equipment budgets in the printing machinery sector reflect domestic packaging-machinery engineering clusters and print-shop labor demographics alongside national food-contact ink regulations. Evaluated country trajectories over the next decade span 3.6% in France to 5.5% in Italy.
Table 7: Country CAGR and Primary Growth Levers for the Printing Machinery Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Italy | 5.5% | Rotogravure, flexo, and converting machinery export cluster and Transition 5.0 tax credits |
| Japan | 5.0% | Precision inkjet printhead and offset press engineering alongside compact food-pack automation |
| Switzerland | 4.7% | Pharmaceutical blister, security, and luxury folding-carton inline converting machinery |
| South Korea | 4.0% | K-beauty cosmetics carton finishing and electronics specialty film/label printing |
| France | 3.6% | Decree 2025-1081 EPR compliance and mineral-oil-free ink retrofits across wine/luxury packs |
Source: Future Market Insights analysis
Italy Printing Machinery Market Outlook (2026 to 2036)
Concentrated machinery engineering districts across Piedmont and Lombardy alongside Emilia-Romagna make Italy Europe's foremost producer and domestic testbed for rotogravure and central-impression flexographic presses. Italian industrial production advanced 0.6% during January 2026 with machinery and equipment manufacturing recording positive momentum in the March 2026 Italian National Institute of Statistics (Istat) release [9] across northern industrial provinces. Italian printing machinery sales are poised for 5.5% compound annual expansion through 2036 while Transition 5.0 tax credits subsidize energy-efficient press replacements across pasta and pharmaceutical packaging converters. However, Italian converters face commercial friction from high solvent-recovery thermal oxidizer operating costs and rising regional electricity tariffs on legacy gravure lines.
Key takeaway: In Italy, a globally competitive flexographic and gravure machinery cluster paired with Transition 5.0 tax incentives drives a 5.5% CAGR through 2036.
Japan Printing Machinery Market Outlook (2026 to 2036)
Acute shortages of younger pressroom machinists combined with ultra-fast SKU rotation in convenience-store food and beverage packaging compel Japanese printing companies to prioritize autonomous makeready and single-pass digital presses. March 2026 industrial production indices from Tokyo's economic ministry showed Japan's production machinery output advancing 3.1% in January 2026 [10] as domestic factories invested heavily in labor-saving automation equipment. Pressroom capital expenditure in Japan is expected to post a 5.0% compound annual gain over the 2026 to 2036 window thanks to domestic piezoelectric inkjet head and B1 offset robotics leadership from Komori and Fujifilm alongside Canon. Contraction in domestic newspaper and book circulation nevertheless dampens web-offset publication press demand.
Key takeaway: In Japan, print-shop labor deficits and high-frequency convenience food packaging accelerate converter investment in autonomous offset and single-pass inkjet presses.
Switzerland Printing Machinery Market Outlook (2026 to 2036)
High concentration of multinational pharmaceutical headquarters in Basel and luxury watch and confectionery brands across Geneva and Zurich creates specialized demand for zero-defect inline serialization and micro-optic security printing. Swiss secondary-sector industrial output increased 2.1% year-over-year during the final quarter of 2025 according to May 2026 Federal Statistical Office INDPAU data [11], underpinned by precision machinery and pharmaceutical export activity. Swiss printing press investments are projected to increase at a 4.7% yearly pace through 2036 as Bobst Group SA and Gallus supply automated multi-process converting lines for high-margin healthcare cartons. Nonetheless, a strong Swiss franc and high domestic machinist wages push standard commercial brochures to neighboring German print shops.
Key takeaway: In Switzerland, zero-defect pharmaceutical serialization and luxury packaging standards anchor demand for high-precision inline printing and die-cutting systems.
South Korea Printing Machinery Market Outlook (2026 to 2036)
Export-oriented K-beauty cosmetics brands and semiconductor-display component makers require intricate cold-foil and holographic cast-and-cure presses alongside cleanroom precision coating systems across South Korea. Technology-intensive manufacturing and digital hardware exports remained primary growth engines across East Asian industrial economies in the May 2026 UNCTAD Data Hub assessment [12], supporting capital investment across Korean specialty folding-carton and functional-film converters around Seoul and Gyeonggi-do. South Korean printing equipment turnover is forecast to register 4.0% annual growth from 2026 to 2036 on strong domestic orders for multi-coater UV-LED offset presses. While specialty cosmetics packaging upgrades remain brisk, domestic commercial printers face sluggish publication demand and high import financing costs on European machinery.
Key takeaway: In South Korea, export cosmetics carton embellishment and electronics film converting drive investments in multi-coater UV-LED offset and digital label presses.
France Printing Machinery Market Outlook (2026 to 2036)
Strict national prohibitions on mineral-oil printing inks alongside mandatory extended producer responsibility packaging rules accelerate pressroom modernization across French food and luxury cosmetics converters. Légifrance published Décret n° 2025-1081 on November 17, 2025 to align French packaging waste and recyclability enforcement with updated European circularity mandates [13], compelling converters to retrofit presses for vegetable-oil and electron-beam low-migration ink systems. French converter spending on printing machinery is estimated to grow at 3.6% annually over the next decade as wine-label and luxury folding-carton plants upgrade equipment across Nouvelle-Aquitaine and Auvergne-Rhône-Alpes. The central commercial obstacle involves ongoing closures of traditional commercial catalog and retail-flyer web-offset plants following France's opt-in advertising mail rules.
Key takeaway: In France, mineral-oil ink bans and Décret n° 2025-1081 packaging rules redirect converter capital expenditure from publication web lines to low-migration packaging presses.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the printing machinery market?
Heidelberger Druckmaschinen AG, Koenig & Bauer AG, Komori Corporation, Bobst Group SA, HP Inc., Fujifilm Holdings Corporation, Canon Inc., and Windmöller & Hölscher KG are the notable companies in this market.
Supplier competition in the printing machinery industry centers on autonomous makeready speed and inline spectrophotometric color control alongside hybrid digital-analog integration. European and Japanese sheet-fed and web press engineering leaders including Heidelberger Druckmaschinen AG and Koenig & Bauer AG alongside Bobst Group SA and Komori Corporation dominate high-tonnage folding-carton and flexible-packaging machinery. Simultaneously, digital production press pioneers led by HP Inc. and Fujifilm Holdings Corporation alongside Canon Inc. capture expanding share in short-run labels and variable-data cartons.
- Sheet-Fed Offset & Integrated Packaging Press Leaders: Heidelberger Druckmaschinen AG and Koenig & Bauer AG alongside Komori Corporation supply high-speed B1 and large-format lithographic presses with inline coating and autonomous plate-changing robotics.
- Web-Fed Flexible Packaging & Inline Converting Specialists: Bobst Group SA and Windmöller & Hölscher KG engineer wide-web central-impression flexographic and rotogravure lines alongside inline folding-carton die-cutters.
- Digital Inkjet & Liquid/Dry Toner Production Press Innovators: HP Inc. (HP Indigo & PageWide) and Fujifilm Holdings Corporation (Jet Press & Revoria) alongside Canon Inc. lead plate-free digital packaging and commercial press installations.
Competitive Benchmarking: Printing Machinery Market
Table 8: Competitive Benchmarking for the Printing Machinery Market (qualitative capability ratings), 2026
| Company | Offset & Flexo Press Breadth | Digital Inkjet & Hybrid Integration | Autonomous Workflow Software | Geographic Reach |
|---|---|---|---|---|
| Heidelberger Druckmaschinen AG | High | High | High | High |
| Koenig & Bauer AG | High | High | High | High |
| Komori Corporation | High | Medium | High | High |
| Bobst Group SA | High | High | High | High |
| HP Inc. | Medium | High | High | High |
| Fujifilm Holdings Corporation | Medium | High | High | High |
| Canon Inc. | Medium | High | High | High |
| Windmöller & Hölscher KG | High | Medium | High | High |
Assessment framework: Offset & Flexo Press Breadth evaluates documented manufacturing of heavy sheet-fed lithographic and central-impression flexo alongside gravure web platforms. Digital & Hybrid Inkjet Capability measures single-pass piezoelectric inkjet and liquid-electrophotography press speeds. Workflow Automation & Inline Inspection reflects closed-loop inline spectrophotometry and prepress job queuing alongside cloud connectivity.
Key Developments in the Printing Machinery Market
- In July 2026, Komori Europe announced that UK commercial and packaging printer Selsey Press installed an advanced Komori Lithrone G37P perfecting offset press with LED-UV curing to eliminate sheet-drying bottlenecks [14].
- In June 2026, Bobst Group SA launched its BOBST Connect Tool Management cloud platform to synchronize die-cutting tooling and gravure/flexo cylinder tracking alongside predictive maintenance across global packaging plants [15].
- In July 2025, FUJIFILM Business Innovation Corp. expanded its digital production portfolio with white and metallic silver specialty toners for the Revoria Press EC2100S and SC285S platforms [16].
- In March 2024 and May 2025, HP Inc. introduced its automated HP Indigo 120K and 18K B2 digital presses [17] while Canon Europe completed the first EMEA installations of its varioPRINT iX1700 sheetfed inkjet press [18].
Key Players in the Printing Machinery Market
Sheet-Fed Offset and Hybrid Packaging Press Builders
- Heidelberger Druckmaschinen AG
- Koenig & Bauer AG
- Komori Corporation
Flexible Packaging, Gravure, and Inline Converting Specialists
- Bobst Group SA
- Windmöller & Hölscher KG
Production Digital Inkjet and Electrophotography Leaders
- HP Inc.
- Fujifilm Holdings Corporation
- Canon Inc.
Printing Machinery Market - Report Scope
Table 9: Report Scope for the Printing Machinery Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Press Configuration; Printing Technology; End-Use Industry; Region |
| Quantitative Units | USD Billion |
| Market Definition | Covers manufacturer revenue from commercial and industrial printing presses (offset lithography, flexography, rotogravure, screen, and production digital inkjet/toner) and press-integrated inline coating/curing units. Category Scope Note: Market valuation reflects capital equipment sales and factory-bundled inline print modules; standalone office/home desktop printers, aftermarket printing inks/plates sold separately, and unprinted filling/sealing packaging machines are excluded. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Italy, Japan, Switzerland, South Korea, France, and additional countries in the full report |
| Key Companies Covered | Heidelberger Druckmaschinen AG, Koenig & Bauer AG, Komori Corporation, Bobst Group SA, HP Inc., Fujifilm Holdings Corporation, Canon Inc., Windmöller & Hölscher KG |
| Forecast Period | 2026 to 2036 (Base Year: 2025) |
| Approach | Primary and secondary research with top-down and bottom-up press shipment triangulation. |
Printing Machinery Market - Research Methodology
Table 10: Research Methodology for the Printing Machinery Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with press engineering directors, folding-carton and flexible-packaging converters, commercial print executives, printhead OEMs, and workflow automation specialists. |
| Secondary Research | Secondary research incorporated data from Eurostat, Istat, METI Japan, Swiss Federal Statistical Office (FSO), Légifrance, VDMA, GS1, Fogra, Pro Carton, and audited annual reports of press manufacturers. |
| Market Sizing and Forecasting | Market sizing reconciled annual unit shipments and average selling prices across sheet-fed offset, CI/inline flexo, rotogravure, and production digital presses from 2026 to 2036. |
| Data Triangulation and Validation | Estimates were cross-checked against packaging substrate consumption (containerboard, boxboard, flexible films), manufacturer order backlogs, and industrial capital expenditure indices. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's capital equipment and graphic arts econometric model, calibrating evaluated national growth rates against the 4.5% global baseline through verified packaging converter capex, machinery export backlogs, and statutory food-contact/EPR labeling mandates. |
| Operational Benchmark Traceability | Operational benchmarks (annual industrial press installations, automated makeready minutes, and sheet/web line speeds) represent modeled estimates synthesized from VDMA/ACIMGA machinery registries, METI production surveys, Fogra ISO 12647 standards, and press OEM technical disclosures. |
Printing Machinery Market by Segments
Printing Machinery Market segmented by Press Configuration:
- Fully Automatic High-Speed Web & Sheet-Fed Presses
- Hybrid Inline Flexo-Digital Converting Presses
- Narrow-Web Modular Label & Specialty Presses
Printing Machinery Market segmented by Printing Technology:
- Flexographic & Offset Lithography Press Systems
- High-Speed Production Inkjet & Electrophotographic Digital Presses
- Rotogravure & Screen Printing Machinery
Printing Machinery Market segmented by End-Use Industry:
- Food & Beverage Packaging & Labels
- Pharmaceutical & Healthcare Serialization Packaging
- Personal Care, Cosmetics & Folding Cartons
- Commercial Publishing & Industrial Graphics
Printing Machinery Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Eurostat. (2025, October 10). Packaging waste statistics. European Commission.
- [2] GS1 AISBL. (2025, March 18). 2D Barcodes at Retail Point-of-Sale: Sunrise 2027. GS1 Global Office.
- [3] Koenig & Bauer AG. (2026, September 23). 20,000 sheets/h: IVE Group Accelerates Commercial and Packaging Printing with Rapida 106 X from Koenig & Bauer. Koenig & Bauer AG.
- [4] Windmöller & Hölscher KG. (2025, October 15). K 2025 - Windmöller & Hölscher presents VAREX II and ALPHAFLEX. Windmöller & Hölscher KG.
- [5] American Forest & Paper Association (AF&PA). (2026, January 30). AF&PA Releases Q4 2025 Containerboard Quarterly Report. American Forest & Paper Association.
- [6] Pro Carton. (2026, February 18). Pro Carton releases their Carbon Footprint Study 2025. Pro Carton.
- [7] VDMA. (2026, April 14). Printing and Paper Technology. VDMA.
- [8] Heidelberger Druckmaschinen AG. (2026, September 24). Klampfer Druck boosts competitiveness with Jetfire 50 digital printing system from HEIDELBERG. Heidelberger Druckmaschinen AG.
- [9] Italian National Institute of Statistics (Istat). (2026, March 13). Industrial production – January 2026. Istituto Nazionale di Statistica.
- [10] Ministry of Economy, Trade and Industry (METI). (2026, March 19). Indices of Industrial Production: Revised Report for January 2026. Ministry of Economy, Trade and Industry.
- [11] Federal Statistical Office (FSO). (2026, May 21). Secondary sector: Production, Orders and Turnover Statistics (INDPAU). Swiss Confederation Federal Statistical Office.
- [12] UNCTAD Data Hub. (2026, May 21). Digital economy and technology - Data Insights. United Nations Conference on Trade and Development.
- [13] Légifrance. (2025, November 17). Décret n° 2025-1081 du 17 novembre 2025 relatif aux emballages ainsi qu'aux déchets d'emballages. Journal Officiel de la République Française.
- [14] Komori Europe. (2026, July 6). Selsey Press invests in one of Europe's most advanced printing presses. Komori Corporation.
- [15] Bobst Group SA. (2026, June 15). Everything's connected: BOBST announces latest innovations and Tool Management. Bobst Group SA.
- [16] FUJIFILM Business Innovation Corp. (2025, July 10). FUJIFILM Business Innovation Expands Colour Capabilities with the Launch of White and Silver Toners for Revoria Press EC2100S and Revoria Press SC285S. FUJIFILM Holdings Corporation.
- [17] HP Inc. (2024, March 24). HP Sets New Industry Standard in Digital Printing with Advanced Automation and AI. HP Inc.
- [18] Canon Europe. (2025, May 14). Canon Europe announces the first two installations of the Canon varioPRINT iX1700 sheetfed inkjet press in EMEA. Canon Inc.
- [19] Fogra Research Institute for Media Technologies. (2026, February 11). Certification according to PSO (ISO 12647). Fogra Research Institute for Media Technologies.
- [20] Koenig & Bauer AG. (2025, May 22). Positive Outlook for Koenig & Bauer: Successful Results After China Print and Stable Order Intake. Koenig & Bauer AG.
- [21] European Printing Ink Association (EuPIA). (2025, November 5). Good Manufacturing Practice (GMP) Printing Inks for Food Contact Materials. European Printing Ink Association.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the printing machinery market in 2026 and what is forecast for 2036?
- Which packaging, labeling, and traceability factors support demand for printing machinery?
- Why do Fully Automatic High-Speed Web & Sheet-Fed Presses lead the press configuration category?
- Why do Flexographic & Offset Lithography Press Systems lead the printing technology category globally?
- How do growth rates differ across Italy, Japan, Switzerland, South Korea, and France?
- Which leading companies supply offset and flexographic alongside gravure and digital printing presses today?
- What limits press replacement cycles or supplier switching in the printing machinery market?
- What should converters evaluate before purchasing a commercial or packaging printing press?
Frequently Asked Questions
How big is the printing machinery market in 2026, and what is forecast for 2036?
The global printing machinery market is estimated to reach USD 19.5 billion in 2026. Revenue is projected to expand further and reach USD 30.3 billion by 2036, driven by automated folding-carton and label press upgrades.
What CAGR is forecast for the Printing Machinery Market through 2036?
As per FMI, the printing machinery market is projected to grow at a 4.5% CAGR from 2026 to 2036. Growth is supported by shorter packaging SKU print runs, plastic-to-paperboard substitution, and inline digital serialization.
Which press configuration holds a notable printing machinery demand share in 2026?
Fully Automatic High-Speed Web & Sheet-Fed Presses are projected to hold 54.3% of press configuration demand in 2026. The segment leads because simultaneous plate changing and inline spectrophotometry minimize makeready waste between short packaging jobs.
Which printing technology segment holds a notable printing machinery share in 2026?
Flexographic & Offset Lithography Press Systems will hold 37.7% of printing technology demand in 2026. Demand is supported by high-speed wide-web flexible film printing and low unit cost across medium-to-long folding carton runs.
Which country has a notable printing machinery expansion outlook during the forecast period?
FMI finds that Italy is projected to expand at a 5.5% CAGR during the 2026 to 2036 assessment period. Growth is supported by its world-leading flexo and gravure presses alongside converting machinery export cluster and Transition 5.0 capital tax incentives.
Which companies are active in the Printing Machinery Market during 2026?
Notable companies include Heidelberger Druckmaschinen AG, Koenig & Bauer AG, Komori Corporation, Bobst Group SA, HP Inc., Fujifilm Holdings Corporation, Canon Inc., and Windmöller & Hölscher KG. These manufacturers focus on autonomous push-to-stop makeready and low-migration curing systems.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Press Configuration, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Press Configuration, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Press Configuration, 2026 to 2036
- Fully Automatic High-Speed Web & Sheet-Fed Presses
- Hybrid Inline Flexo-Digital Converting Presses
- Narrow-Web Modular Label & Specialty Presses
- Y-o-Y Growth Trend Analysis By Press Configuration, 2021 to 2025
- Absolute $ Opportunity Analysis By Press Configuration, 2026 to 2036
- Global Market Analysis and Forecast, By Printing Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Printing Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Printing Technology, 2026 to 2036
- Flexographic & Offset Lithography Press Systems
- High-Speed Production Inkjet & Electrophotographic Digital Presses
- Rotogravure & Screen Printing Machinery
- Y-o-Y Growth Trend Analysis By Printing Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Printing Technology, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Industry, 2026 to 2036
- Food & Beverage Packaging & Labels
- Pharmaceutical & Healthcare Serialization Packaging
- Personal Care, Cosmetics & Folding Cartons
- Commercial Publishing & Industrial Graphics
- Y-o-Y Growth Trend Analysis By End-Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Press Configuration
- By Printing Technology
- By End-Use Industry
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Heidelberger Druckmaschinen AG
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Koenig & Bauer AG
- Komori Corporation
- Bobst Group SA
- HP Inc.
- Fujifilm Holdings Corporation
- Canon Inc.
- Windmöller & Hölscher KG
- Heidelberger Druckmaschinen AG
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


