
- Market Size (2026)
- USD 61.5 Bn
- Forecast (2036)
- USD 134.0 Bn
- CAGR (2026 to 2036)
- 8.1%
How big is Probiotic Drink Market in 2026?
Global demand for probiotic drinks is set to expand at 8.1% CAGR between 2026 and 2036, with the market size rising from USD 56.9 billion in 2025 to USD 61.5 billion in 2026 and reaching USD 134.0 billion by 2036.
Demand in the probiotic drink market is expanding at an 8.1% CAGR from 2026 to 2036 as beverage formulators pair live lactic acid and spore-forming cultures with low-sugar fruit and botanical infusions for daily digestive wellness. According to Future Market Insights analysis, global industry valuation rises from USD 56.9 billion in 2025 to USD 61.5 billion in 2026 and reaches USD 134.0 billion by 2036, generating USD 72.5 billion in added revenue. Consumers substituting sugary carbonated sodas with live-culture refreshments require verified colony-forming unit counts at shelf expiry. In May 2026, the International Scientific Association for Probiotics and Prebiotics published its consensus statement defining evidence-based gut health markers for microbial foods and beverages [1]. Flavored / Botanical Infusion holds 53.1% share in 2026, while country growth spans 6.5% in Germany to 9.9% in the UK.
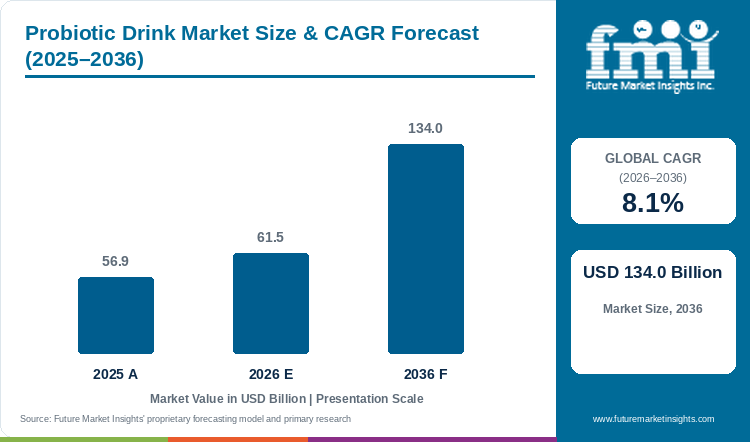
Key Market Trends & Insights
- By product variety / flavor: Flavored / Botanical Infusion accounted for 53.1% of demand in 2026, because ginger, berry, and citrus extracts mask lactic and acetic fermentation sourness [3].
- By packaging format: With a 29.0% share in 2026, Slim Aluminum Cans led the category, as hermetic double-seamed lids block ultraviolet light and retain carbonation in sparkling gut-health sodas.
- By distribution channel: Supermarkets & Hypermarkets held the leading share of 33.6% in 2026, underpinned by multi-deck chilled grab-and-go bays stocking fermented foods and beverages for weekly household grocery trips.
Regional Highlights
- Fastest-growing evaluated country: UK, at 9.9% CAGR from 2026 to 2036.
- By country: The USA at 9.1%, Canada at 8.4%, South Korea at 7.8%, and Japan at 7.1% follow, while Germany records the lowest evaluated CAGR at 6.5%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Probiotic Drink Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 56.9 billion |
| Estimated Market Size in 2026 | USD 61.5 billion |
| Projected Market Size by 2036 | USD 134.0 billion |
| CAGR, 2026 to 2036 | 8.1% |
| Added Revenue, 2026 to 2036 | USD 72.5 billion |
Japanese and South Korean dairies distribute miniature fermented milk shots through daily doorstep and convenience channels, while UK and U.S. bottlers are scaling ambient-stable functional sodas in slim cans. Commercial beverage plants must prevent post-bottling over-acidification and live cell die-off across both refrigerated and ambient distribution chains. In March 2025, the National Institutes of Health Office of Dietary Supplements updated its clinical probiotic guidance, emphasizing that digestive and immune benefits are strain-specific and require guaranteed viable counts through shelf expiry [2]. As a result, beverage makers are adopting microencapsulated probiotic ingredients and inline aseptic dosing skids so live cultures survive low-pH fruit and tea matrices.
Microbial Fermentation and Culture Viability Operational Metrics
Table 2: Microbial Fermentation and Culture Viability Operational Metrics for the Probiotic Drink Market (USD billion and operational parameters), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 56.9 | 61.5 | 134.0 |
| Commercial probiotic beverage volume (billion liters) | 18.2 | 19.8 | 41.5 |
| Target colony forming units per serving (billion CFU) | 1.0 to 5.0 | 1.2 to 6.0 | 2.0 to 10.0 |
| Bacterial survival rate through gastric simulant (percentage) | 65.0 to 78.0 | 68.0 to 82.0 | 80.0 to 92.0 |
Reported liter volumes span cultured dairy shot plants, milk and water kefir dairies, and kombucha and functional soda canneries worldwide. Labeled colony forming unit counts are verified at product expiry using flow cytometry and selective agar plate enumeration.
Facility Capital Expenditure & Brewing Yardstick Metrics
Bottling live fermented beverages at commercial speed requires arresting acid fermentation at an exact target pH so sealed cans and bottles do not referment or bulge on grocery shelves. When beverage plants formulate low-sugar sparkling kefirs and kombucha teas, sterile inline dosing skids meter freeze-dried cultures and gut health ingredients downstream of pasteurization. Supermarket chain audits for viable cell counts and sub-0.5% alcohol compliance are driving brewery investments in seed bioreactors, cold-fill canning lines, and automated flow cytometers.
Table 3: Facility Capital Expenditure and Processing Yardstick Metrics for the Probiotic Drink Market (USD and units), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Commercial probiotic beverage bottling plants (units) | 1,850 | 1,980 | 3,400 |
| Sterile seed bioreactor spend per facility (USD thousand) | 380 to 520 | 410 to 550 | 580 to 790 |
| Cold-fill aseptic canning line outlay (USD million) | 2.4 to 3.6 | 2.6 to 3.9 | 3.8 to 5.4 |
| Strain viability and flow cytometry audit per batch (USD) | 280 to 420 | 300 to 450 | 420 to 610 |
Table 4: Facility & Operational Cost Benchmark Indicators for the Probiotic Drink Market (USD and percentages), mixed reporting years from 2024 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 61.5 billion | Report value |
| Freeze-dried starter culture share of beverage cost | 13.5% to 18.0% | 2026 bottler operating range |
| Fermentation thermal control power outlay per batch | USD 92 to 128 | Commercial brewery benchmark |
| Supermarkets & hypermarkets revenue, 2026 | USD 20.7 billion | 33.6% share |
Analyst Perspective
"Heat-tolerant spore-forming strains and inline aseptic dosing let beverage makers launch shelf-stable probiotic sodas and sparkling waters outside the chilled dairy aisle. Strict regulatory scrutiny on strain-specific health claims and cold-chain energy costs for live dairy shots still require rigorous shelf-life validation before national retail rollouts."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the probiotic drink market segmented?
The probiotic drink market is segmented by product variety / flavor, packaging format, distribution channel, and region. In 2026, Flavored / Botanical Infusion is projected at 53.1%, Slim Aluminum Cans at 29.0%, and Supermarkets & Hypermarkets at 33.6%.
By product variety / flavor: Flavored / Botanical Infusion, Classic Unflavored / Traditional, and Zero-Sugar / Sugar-Free Variant.
By packaging format: Slim Aluminum Cans, PET Bottles, Glass Bottles, and Aseptic Paperboard Cartons.
By distribution channel: Supermarkets & Hypermarkets, Convenience Stores & Gas Stations, Online Retail & Subscription, and Food Service & Cafes.
Why does Flavored / Botanical Infusion lead the product variety / flavor category?
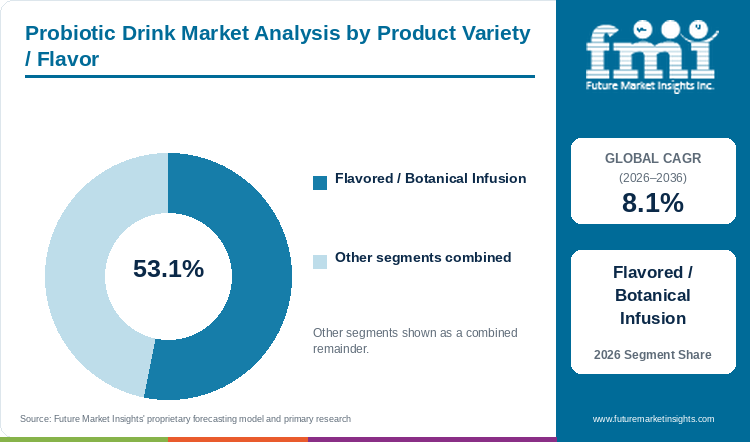
Flavored / Botanical Infusion is expected to account for 53.1% of product variety / flavor revenue in 2026, supported by organic acid masking.
Table 5: Product Variety / Flavor Share for the Probiotic Drink Market (percentage share), 2026
| Product Variety / Flavor | Share (2026) |
|---|---|
| Flavored / Botanical Infusion | 53.1% |
| Other Segments Combined | 46.9%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Variety / Flavor Leadership and Market Growth for the Probiotic Drink Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 8.1% |
| Leading Segment | Flavored / Botanical Infusion |
Unflavored lactic and acetic fermentations produce sharp vinegar or sour-milk notes that limit repeat daily drinking among mainstream soft-drink switchers. Blending cold-pressed ginger, hibiscus, mango, and berry extracts into cultured kefir and sparkling kombucha tea balances tart organic acids without relying on heavy cane sugar. Natural botanical flavor masking widens appeal among office workers and younger shoppers seeking gut-friendly afternoon refreshments. Microbiologists still screen essential oil and polyphenol additions carefully so antimicrobial plant compounds do not reduce live bacterial counts during storage.
- Flavored / Botanical Infusion is projected to hold 53.1% of product variety / flavor demand in 2026, supported by high palate acceptance among consumers switching from conventional soft drinks.
- In February 2026, Lifeway Foods showcased new fruit-forward and botanical cultured kefir beverage innovations at Natural Products Expo West to expand mainstream daily occasions [4].
What keeps Slim Aluminum Cans ahead by packaging format?
Slim Aluminum Cans are estimated to represent 29.0% of the packaging format category in 2026, reflecting ultraviolet barrier protection and portability.
Opaque metal walls block ultraviolet light and oxygen ingress that otherwise degrade light-sensitive probiotic strains packaged in clear plastic or glass. Bottlers of sparkling fermented beverages and low-calorie functional beverages specify polymer-lined 250-milliliter and 330-milliliter slim cans to hold internal carbonation pressure while cutting outbound freight weight compared with glass bottles. Slim cans also chill rapidly in convenience-store open coolers and fit standard vending tracks. Packaging engineers must select epoxy-free internal liners so low-pH organic acids do not corrode the aluminum wall over a 9-month to 12-month shelf life.
- Slim Aluminum Cans capture 29.0% of packaging format demand in 2026, reflecting total light blocking, high municipal recycling rates, and lower freight breakage than glass.
- In October 2025, the British Soft Drinks Association documented expanding adoption of recyclable slim aluminum cans across functional and fermented sparkling drink launches in UK retail [5].
Why do Supermarkets & Hypermarkets define the largest distribution channel?
Supermarkets & Hypermarkets are set to command 33.6% of distribution channel sales in 2026, reinforced by chilled functional beverage aisle expansion.
Continuous multi-deck refrigeration and high weekly household foot traffic make supermarkets and hypermarkets the primary volume channel for perishable multi-pack probiotic shots and kefirs. National grocery chains place chilled probiotic yogurt and drinkable yogurt multi-packs alongside kombucha and prebiotic-probiotic sodas in dedicated digestive-wellness bays. Supermarket loyalty-card promotions and 4-pack or 8-pack family cartons help brands convert first-time buyers into routine weekly shoppers. Emerging beverage makers still face steep chilled slotting fees and strict minimum velocity hurdles before grocery category managers grant permanent national shelf space.
- Supermarkets & Hypermarkets account for 33.6% of distribution channel revenue in 2026, reinforced by cold-chain display reliability and multi-pack household purchasing.
- In May 2026, Lifeway Foods reported that expanded placement across national supermarket chains helped lift annual net sales to USD 212.5 million during the prior fiscal year [6].
What are the drivers, restraints, and opportunities in the probiotic drink market?
Microbiome wellness and soda-substitution habits elevate drink volume, whereas cold-chain distribution costs and live-cell die-off limit reach, and ambient spore-forming synbiotic cans unlock new channels.
- Driver: Consumer substitution of high-sugar soft drinks with live-culture digestive and immune support beverages drives recurring daily unit volume through 2036.
- Restraint: Continuous 2 to 8 degree Celsius cold-chain requirements for vegetative dairy and kombucha strains raise freight costs and trigger refermentation spoilage during thermal excursions.
- Opportunity: Pairing heat-resistant spore-forming Bacillus strains with soluble prebiotic fibers enables ambient-stable cans that penetrate convenience, vending, and e-commerce channels.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Mainstream beverage shoppers are actively replacing high-fructose carbonated soft drinks and sugary juices with fermented dairy shots, water kefirs, and low-sugar probiotic sodas that support daily gut barrier and immune function. Rather than treating probiotics as occasional capsule supplements taken during illness, households now buy multi-pack cultured drinks as everyday breakfast and lunch refreshments. Clinical visibility around the gut-microbiome axis is pulling probiotic beverages into mainstream grocery baskets. In May 2026, a Nature Reviews Gastroenterology & Hepatology consensus publication indexed in PubMed established standardized clinical and physiological criteria for gut health maintenance through dietary microbes [7]. Beverage brands must print exact strain designations and end-of-shelf-life CFU counts on labels to win dietitian and consumer trust.
Risk Assessment of the Probiotic Drink Market: Operational and Formulation Friction
Vegetative Lactobacillus and Bifidobacterium strains experience rapid cellular stress when exposed to pH levels below 4.2, dissolved oxygen, or warehouse temperature spikes above 8 degrees Celsius. Unpasteurized kombucha and kefir also continue fermenting residual sugars if cold-chain trucks warm during summer transit, causing excess carbonation, cap leakage, or alcohol drift above 0.5% ABV. In February 2025, European Food Safety Authority scientific guidance reiterated strict characterization and viable-count stability requirements for microorganisms submitted under gut-health nutrition dossiers [8]. High refrigerated freight surcharges and short 45-day to 60-day shelf windows force retailers to mark down slow-moving SKUs.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Dormant spore-forming strains such as Bacillus coagulans and Bacillus subtilis remain protected inside a natural protein coat during tunnel pasteurization, room-temperature warehousing, and stomach acid transit, germinating only when they reach the small intestine. Formulators are combining these heat-tolerant spores with soluble prebiotic fiber to launch ambient-stable synbiotic products in slim aluminum cans. In March 2025, Lallemand Health Solutions and beverage partners advanced commercial three-strain and spore-stabilized synbiotic beverage formulations designed for room-temperature distribution [9]. Because ambient probiotic sodas and sparkling waters require zero refrigerated trucking or chilled store cabinets, brands can place them in workplace vending machines, gym coolers, and parcel e-commerce boxes.
Probiotic Drink Market by Country (2026 to 2036)
Front-of-store meal-deal chillers and sugar-levy reformulation push the UK to a 9.9% CAGR between 2026 and 2036, ahead of the USA at 9.1% and Canada at 8.4%. In East Asia and continental Europe, South Korea registers 7.8%, Japan posts 7.1%, and Germany grows at 6.5% CAGR.
Table 7: Country CAGR and Primary Growth Levers for the Probiotic Drink Market (CAGR percentage and operational drivers), 2026 to 2036
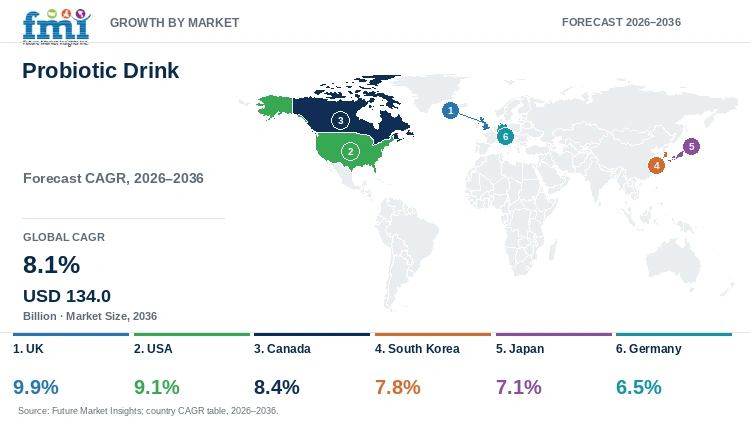
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| UK | 9.9% | Supermarket meal-deal kombucha and kefir bays and Soft Drinks Industry Levy sugar reformulation |
| USA | 9.1% | Mainstream grocery functional soda sets and high-protein cultured kefir expansion |
| Canada | 8.4% | Health Canada probiotic strain monograph clarity and dairy-free fermented drinks |
| South Korea | 7.8% | Convenience-store digestive and skin-axis dairy shots and home delivery networks |
| Japan | 7.1% | FOSHU and Function Claim lactic-acid bacteria shots for sleep, stress, and immunity |
| Germany | 6.5% | Organic bio-supermarket water kefir and clean-label cultured buttermilk demand |
Source: Future Market Insights analysis
UK Probiotic Drink Market Outlook (2026 to 2036)
British supermarkets have integrated single-serve kombucha cans, kefir smoothies, and daily gut shots directly into front-of-store lunchtime meal-deal chillers, accelerating trial among office workers and commuters. By 2036, the UK is projected to grow at 9.9% CAGR, supported by consumer avoidance of high-sugar carbonated drinks under the UK Soft Drinks Industry Levy. In June 2025, UK Food Standards Agency consumer tracking surveys documented rising public adoption of live microbial beverages and fermented dairy drinks for everyday digestive maintenance [10]. However, UK advertising rules strictly prohibit unverified probiotic therapeutic claims on front-of-pack labels. British beverage makers overcome this labeling hurdle by pairing live cultures with small doses of calcium or vitamin C, which carry approved digestive-enzyme and immune health claims.
Key takeaway: In the UK, supermarket lunchtime meal-deal placement and sugar-tax-driven soda substitution propel the fastest growth rate among the evaluated countries.
USA Probiotic Drink Market Outlook (2026 to 2036)
In the USA, demand for probiotic drinks is predicted to advance at 9.1% CAGR through 2036, driven by national grocery chains dedicating full refrigerated and ambient doors to functional gut sodas, kefirs, and kombucha. American shoppers increasingly select low-calorie sparkling cans fortified with Bacillus spores alongside high-protein cultured kefir bottles that support both microbiome balance and satiety. In September 2026, USDA Economic Research Service food outlook data noted resilient domestic fluid dairy and cultured beverage output supporting value-added dairy processing [11]. Even so, class-action litigation targeting unsubstantiated gut-health claims and cold-chain LTL trucking costs across long interstate routes pressure smaller brands. U.S. bottlers mitigate risk by using clinically studied spore strains and co-packing near regional grocery distribution centers.
Key takeaway: In the USA, mainstream supermarket functional-soda sets and high-protein cultured kefir lines drive large-scale commercial expansion.
Canada Probiotic Drink Market Outlook (2026 to 2036)
Canada provides beverage formulators with a clear regulatory pathway through Health Canada's probiotic monograph, which permits non-strain-specific digestive flora claims for eligible bacterial species at 1 billion CFU per serving. The Canada probiotic drink sector is projected to record 8.4% CAGR during the assessment period, underpinned by strong retail sales of organic kombucha, oat-based probiotic drinks, and fermented milk kefir across Ontario, Quebec, and British Columbia. In November 2025, Canadian Health Food Association retail tracking showed that digestive-wellness drinks ranked among the fastest-turning refrigerated beverage categories in natural and conventional grocers [12]. Still, sub-zero winter temperatures across transcontinental highway routes risk freezing live bottles in transit. Canadian distributors protect live cell viability by utilizing heated insulated trailers and regional cold-storage cross-docking.
Key takeaway: In Canada, transparent Health Canada probiotic labeling rules and strong organic grocery distribution support steady long-term growth.
South Korea Probiotic Drink Market Outlook (2026 to 2036)
South Korean consumers view fermented lactic-acid beverages as an extension of traditional fermented food culture, buying dual-chamber probiotic shots and drinkable yogurts daily through convenience stores and doorstep delivery networks. Sales of probiotic drinks in South Korea are forecast to expand at 7.8% CAGR through 2036, aided by Ministry of Food and Drug Safety health-functional food certifications for patented domestic Lactobacillus strains. In August 2025, the Korea Functional Beverage Industry Association reported that retail sales of functional fermented milk and plant probiotic drinks rose 14.0% year-on-year on strong demand for dual digestive and liver-care or skin-hydration shots [13]. Intense price promotions among domestic dairy chaebols squeeze margins on basic yogurt shots, prompting Korean producers to launch premium dual-cap bottle formats.
Key takeaway: In South Korea, ubiquitous convenience-store distribution and dual-function digestive and beauty probiotic shots sustain rapid category turnover.
Japan Probiotic Drink Market Outlook (2026 to 2036)
Japan is the foundational market for commercial lactic-acid bacteria beverages, supported by nationwide home-delivery networks and regulatory frameworks including Foods for Specified Health Uses (FOSHU) and Foods with Function Claims (FFC). Between 2026 and 2036, the Japan market is expected to progress at 7.1% CAGR, driven by high-density probiotic shots clinically positioned for sleep quality, stress relief via the gut-brain axis, and winter immune defense. In September 2025, the Japan Health and Nutrition Food Association confirmed that lactic-acid bacteria beverages remained the top-selling FFC beverage subcategory across Japanese supermarkets and vending channels [14]. Because an aging and declining total population limits volume growth in standard family cartons, Japanese dairy leaders focus on high-margin 65-milliliter to 100-milliliter daily functional bottles.
Key takeaway: In Japan, FFC-certified gut-brain axis shots and established household delivery systems drive consistent value expansion across adult and senior cohorts.
Germany Probiotic Drink Market Outlook (2026 to 2036)
German shoppers favor clean-label cultured milk kefir, organic bread-drink ferments, and low-sugar water kefir sold through bio-supermarkets and discounter chilled bays, which is why Germany is estimated to post 6.5% CAGR over the forecast period. In January 2026, inspection findings from the Bavarian State Office for Health and Food Safety underscored strict German enforcement of viable microbial counts and European Union health-claim rules across microbial supplements and fortified drinks [15]. Because German regulators prohibit use of the word probiotic as a standalone health claim on food labels unless paired with an authorized European Commission claim, marketers cannot rely on aggressive medicinal slogans. Domestic dairies and organic brewers overcome this restriction by emphasizing traditional live fermentation, Bio-Siegel organic certification, and returnable deposit packaging.
Key takeaway: In Germany, strong organic retail channels and consumer appreciation for traditional live-cultured kefir and kombucha support steady growth under strict labeling rules.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the probiotic drink market?
Danone S.A., Yakult Honsha Co., Ltd., PepsiCo (KeVita), Lifeway Foods, Inc., BioGaia AB, Probi AB, Novonesis, GoodBelly (NextFoods), Chobani LLC, and Harmless Harvest are the notable companies in this market.
Probiotic beverage makers compete on strain-level clinical evidence, aseptic cold-fill bottling speed, and chilled grocery door placement. Danone S.A., Yakult Honsha Co., Ltd., Lifeway Foods, Inc., and Chobani LLC run high-volume dairy fermentation plants that supply daily shots, milk kefirs, and drinkable yogurts across supermarket chains. PepsiCo (KeVita), GoodBelly (NextFoods), and Harmless Harvest brew organic kombuchas, probiotic fruit juices, and cultured coconut drinks for natural and mainstream grocers. Upstream, Novonesis, BioGaia AB, and Probi AB isolate and freeze-dry patented bacterial strains for licensing to beverage bottlers. Supermarket category managers verify end-of-shelf-life CFU counts and sugar levels before granting chiller space.
- Global Cultured Dairy and Shot Leaders: Danone S.A., Yakult Honsha Co., Ltd., Lifeway Foods, Inc., and Chobani LLC produce high-volume fermented dairy shots, drinkable yogurts, and milk kefirs.
- Functional Kombucha, Juice, and Plant-Based Drink Makers: PepsiCo (KeVita), GoodBelly (NextFoods), and Harmless Harvest formulate organic kombuchas, probiotic fruit juices, and cultured coconut beverages.
- Clinically Validated Strain and Biosolutions Suppliers: Novonesis, BioGaia AB, and Probi AB supply patented probiotic cultures, spore formers, and starter systems to commercial beverage processors.
Competitive Benchmarking: Probiotic Drink Market
Table 8: Competitive Benchmarking for the Probiotic Drink Market (qualitative capability ratings), 2026
| Company | Fermented Beverage Breadth | Clinical Strain Documentation | Cold-Chain & Ambient Reach | Geographic Reach |
|---|---|---|---|---|
| Danone S.A. | High | High | High | High |
| Yakult Honsha Co., Ltd. | Medium | High | High | High |
| PepsiCo (KeVita) | High | Medium | High | Medium |
| Lifeway Foods, Inc. | High | Medium | High | Medium |
| BioGaia AB | Medium | High | Medium | High |
| Probi AB | Medium | High | Medium | High |
| Novonesis | High | High | High | High |
| GoodBelly (NextFoods) | Medium | High | Medium | Medium |
| Chobani LLC | High | Medium | High | Medium |
| Harmless Harvest | Medium | Medium | Medium | Medium |
Scoring basis: Benchmark ratings evaluate documented strain science and bottling distribution across fermented drink categories. Fermented Beverage Breadth separates multi-format portfolios spanning shots, kefirs, kombuchas, and plant drinks from single-line producers. Clinical Strain Documentation reflects peer-reviewed human trials on proprietary strains such as L. casei Shirota, L. plantarum 299v, and L. reuteri Protectis, while Cold-Chain & Ambient Reach and Geographic Reach measure refrigerated fleet coverage and international market presence.
Key Developments in the Probiotic Drink Market
- In May 2026, Lifeway Foods reported record annual net sales of USD 212.5 million following expanded U.S. retail distribution of its cultured probiotic kefir and drinkable dairy lines [16].
- In February 2026, Lifeway Foods unveiled Muscle Mates functional probiotic dairy beverages at Natural Products Expo West, combining live kefir cultures with 20 grams of protein and creatine [17].
- In September 2025, the International Scientific Association for Probiotics and Prebiotics updated its clinical and regulatory resource framework on postbiotics and live microbial beverages [18].
Key Players in the Probiotic Drink Market
Global Cultured Dairy and Shot Leaders
- Danone S.A.
- Yakult Honsha Co., Ltd.
- Lifeway Foods, Inc.
- Chobani LLC
Functional Kombucha, Juice, and Plant-Based Drink Makers
- PepsiCo (KeVita)
- GoodBelly (NextFoods)
- Harmless Harvest
Clinically Validated Strain and Biosolutions Suppliers
- Novonesis
- BioGaia AB
- Probi AB
Probiotic Drink Market - Report Scope
Table 9: Report Scope for the Probiotic Drink Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Variety / Flavor; Packaging Format; Distribution Channel; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes manufacturer revenue from ready-to-drink probiotic beverages containing live bacteria or yeast cultures (fermented dairy shots, drinkable yogurts, milk and water kefirs, kombuchas, probiotic juices, and spore-fortified functional sodas and waters) sold within the listed segmentation. Excludes spoonable cup yogurts, dry capsule/tablet supplements, and unfermented prebiotic-only sodas without live cultures. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | UK, USA, Canada, South Korea, Japan, Germany, and additional countries in the full report |
| Key Companies Covered | Danone S.A., Yakult Honsha Co., Ltd., PepsiCo (KeVita), Lifeway Foods, Inc., BioGaia AB, Probi AB, Novonesis, GoodBelly (NextFoods), Chobani LLC, Harmless Harvest |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Probiotic Drink Market - Research Methodology
Table 10: Research Methodology for the Probiotic Drink Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with industrial microbiologists, fermentation brewmasters, aseptic beverage bottling directors, and supermarket chilled-category buyers across the value chain to validate CFU survival protocols, packaging formats, and retail velocity. |
| Secondary Research | Secondary research included International Scientific Association for Probiotics and Prebiotics consensus papers, regulatory health-claim registers, company annual reports, investor releases, and retail beverage scanner datasets. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period were developed using top-down commercial fermented beverage output and starter culture shipments paired with bottom-up retail channel sales tracking. |
| Data Triangulation and Validation | Data is validated against national cultured dairy and functional soft-drink production statistics, slim-can packaging volumes, and household panel data to ensure accuracy without double counting spoonable dairy. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's functional beverage econometric model, calibrating evaluated national growth rates against the 8.1% global baseline through verified digestive wellness retail spend, probiotic drinkable yogurt adoption, and refrigerated cold-chain distribution density. |
| Operational Benchmark Traceability | Operational benchmarks (commercial probiotic beverage volume, live CFU strain viability retention rates, and high-speed aseptic bottling line speeds) represent modeled estimates synthesized from ISAPP consensus bulletins, NIH ODS probiotic data, and commercial dairy beverage brand disclosures. |
Probiotic Drink Market by Segments
Probiotic Drink Market segmented by Product Variety / Flavor:
- Flavored / Botanical Infusion
- Classic Unflavored / Traditional
- Zero-Sugar / Sugar-Free Variant
Probiotic Drink Market segmented by Packaging Format:
- Slim Aluminum Cans
- PET Bottles
- Glass Bottles
- Aseptic Paperboard Cartons
Probiotic Drink Market segmented by Distribution Channel:
- Supermarkets & Hypermarkets
- Convenience Stores & Gas Stations
- Online Retail & Subscription
- Food Service & Cafes
Probiotic Drink Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Colombia
- Argentina
- Chile
- Western Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- Japan
- South Korea
- China
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] International Scientific Association for Probiotics and Prebiotics. (2026, May 06). Consensus statement on the definition and scope of gut health for microbial foods and beverages. ISAPP Consensus Statement on Gut Health.
- [2] National Institutes of Health Office of Dietary Supplements. (2025, March 25). Probiotics: Clinical mechanisms, strain specificity, and viable enumeration in dietary and food products. NIH Office of Dietary Supplements Fact Sheet.
- [3] International Probiotics Association. (2025, July 18). Global market overview: Organic acid masking and strain survival in functional probiotic beverages. IPA Technical Review No. 37.
- [4] Lifeway Foods, Inc. (2026, February 27). Lifeway Foods celebrates 40 years of kefir leadership with new fruit and botanical cultured dairy innovations at Expo West 2026. Lifeway Corporate Press Releases.
- [5] British Soft Drinks Association. (2025, October 14). Annual UK soft drinks industry review: Growth in slim-can functional and fermented beverages. BSDA Market Intelligence, 19, 44-62.
- [6] Fast Company & Lifeway Foods, Inc. (2026, May 29). Lifeway Foods reports record USD 212.5 million annual net sales on supermarket kefir expansion. Commercial Beverage Industry Reports.
- [7] Marco, M. L., Sanders, M. E., & ISAPP Expert Panel. (2026, May 15). The International Scientific Association for Probiotics and Prebiotics consensus statement on the definition and scope of gut health. Nature Reviews Gastroenterology & Hepatology, 23(5), 280-296.
- [8] European Food Safety Authority. (2025, February 12). Scientific guidance on microbial strain characterization and shelf-life viability requirements for gut-flora claims. EFSA Journal, 23(2), 8820.
- [9] Lallemand Health Solutions. (2025, March 19). Commercial launch of multi-strain and spore-forming synbiotic beverage concepts for ambient stability. Lallemand Corporate Releases.
- [10] UK Food Standards Agency. (2025, June 24). Consumer attitudes to novel foods and live microbial fermented beverage products in the United Kingdom. FSA Research Series No. 104.
- [11] United States Department of Agriculture. (2026, September 25). U.S. dairy herd expansion and cultured fluid beverage output outlook for 2026. USDA Economic Research Service Dairy & Beverage Outlook.
- [12] Canadian Health Food Association. (2025, November 18). Consumer health and natural fermented beverage retail velocity trends in Canada. CHFA Industry Report, 28, 50-68.
- [13] Korea Functional Beverage Industry Association. (2025, August 22). Retail market trends in Korean ready-to-drink fermented milk and dual-function probiotic shots. KFBIA Statistical Review, 16, 75-92.
- [14] Japan Health and Nutrition Food Association (JHNFA). (2025, September 15). Foods with Function Claims (FFC) and FOSHU market developments: Lactic-acid bacteria drinks for sleep and immunity. JHNFA Annual Bulletin, 42, 110-128.
- [15] Bavarian State Office for Health and Food Safety (LGL). (2026, January 20). Regulatory inspection findings on microbial viability and health claims in fermented drinks and supplements. LGL Annual Food Control Reports.
- [16] Lifeway Foods Investor Relations. (2026, May 29). Full-year fiscal performance and national supermarket distribution expansion for Lifeway Kefir. Corporate Financial Filings.
- [17] Lifeway Foods, Inc. (2026, February 27). Lifeway unveils Muscle Mates functional probiotic dairy drinks with 20g protein and creatine at Expo West 2026. PR Newswire Corporate Releases.
- [18] International Scientific Association for Probiotics and Prebiotics. (2025, September 19). Expert consensus document on the definition and commercial scope of postbiotics and fermented matrices. ISAPP Scientific Publications.
- [19] Danone S.A. (2025, November 06). Modernization of cold-fill aseptic bottling lines for Actimel and cultured dairy drinks across European plants. Danone Corporate Communications.
- [20] Yakult Honsha Co., Ltd. (2025, October 21). International expansion of Yakult 1000 and high-density Shirota strain fermented milk drinks. Yakult Investor Releases.
- [21] Probi AB & Symrise. (2026, January 14). Clinical beverage formulation partnership for Lactiplantibacillus plantarum 299v in fruit and oat drinks. Probi Corporate Press Room.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the probiotic drink market in 2026 and what is forecast for 2036?
- Which microbiome wellness and sugar-reduction pressures support demand for probiotic drinks?
- Why does Flavored / Botanical Infusion lead the product variety / flavor category?
- Why do Slim Aluminum Cans lead single-serve packaging growth globally?
- How do growth rates differ across the UK, the USA, Canada, South Korea, Japan, and Germany?
- Which leading companies supply cultured dairy shots, kombuchas, and probiotic strains today?
- What cold-chain and strain viability factors limit margin expansion in the probiotic drink market?
- What should grocery and beverage buyers evaluate before qualifying a probiotic drink supplier?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Variety / Flavor, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Variety / Flavor, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Variety / Flavor, 2026 to 2036
- Flavored / Botanical Infusion
- Classic Unflavored / Traditional
- Zero-Sugar / Sugar-Free Variant
- Y-o-Y Growth Trend Analysis By Product Variety / Flavor, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Variety / Flavor, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Slim Aluminum Cans
- PET Bottles
- Glass Bottles
- Aseptic Paperboard Cartons
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Convenience Stores & Gas Stations
- Online Retail & Subscription
- Food Service & Cafes
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Colombia
- Argentina
- Chile
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Benelux
- Nordics
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- China
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Danone S.A.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Yakult Honsha Co., Ltd.
- PepsiCo (KeVita)
- Lifeway Foods, Inc.
- BioGaia AB
- Probi AB
- Novonesis
- GoodBelly (NextFoods)
- Chobani LLC
- Harmless Harvest
- Danone S.A.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Variety / Flavor, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Product Variety / Flavor, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Product Variety / Flavor, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Product Variety / Flavor, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Product Variety / Flavor, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Product Variety / Flavor, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Product Variety / Flavor, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Product Variety / Flavor, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Variety / Flavor, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Variety / Flavor, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Variety / Flavor
- Figure 6: Global Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Packaging Format
- Figure 9: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Distribution Channel
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Product Variety / Flavor, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Product Variety / Flavor, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Product Variety / Flavor
- Figure 26: North America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Packaging Format
- Figure 29: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Distribution Channel
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Product Variety / Flavor, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Product Variety / Flavor, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Product Variety / Flavor
- Figure 36: Latin America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Packaging Format
- Figure 39: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Product Variety / Flavor, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Product Variety / Flavor, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Product Variety / Flavor
- Figure 46: Western Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Packaging Format
- Figure 49: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Product Variety / Flavor, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Product Variety / Flavor, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Product Variety / Flavor
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Packaging Format
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Product Variety / Flavor, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Product Variety / Flavor, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Product Variety / Flavor
- Figure 66: East Asia Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Packaging Format
- Figure 69: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Product Variety / Flavor, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Variety / Flavor, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Product Variety / Flavor
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Packaging Format
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Product Variety / Flavor, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Product Variety / Flavor, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Product Variety / Flavor
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Packaging Format
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the Probiotic Drink Market expected to be in 2026?
The global probiotic drink market is estimated to reach USD 61.5 billion in 2026. Market revenue is projected to expand further and reach USD 134.0 billion by 2036, supported by daily digestive and immune wellness routines.
What CAGR is forecast for the Probiotic Drink Market through 2036?
As per FMI, the probiotic drink market is projected to expand at an 8.1% CAGR from 2026 to 2036. Growth is underpinned by low-sugar kombucha, kefir, and spore-fortified functional soda adoption.
Which flavor variety holds the leading share in the probiotic drink market in 2026?
Flavored / Botanical Infusion is projected to hold 53.1% of product variety / flavor demand in 2026. The segment benefits from natural fruit, ginger, and hibiscus extracts that balance fermentation acidity.
Which distribution channel accounts for the largest share in 2026?
Supermarkets & Hypermarkets is estimated to account for 33.6% of distribution channel revenue in 2026. Demand is supported by dedicated chilled functional-beverage bays and weekly household multi-pack purchases.
Which country has the highest growth outlook during the 2026 to 2036 assessment period?
FMI finds that the UK is projected to register a 9.9% CAGR from 2026 to 2036. Expansion is driven by front-of-store lunchtime meal-deal placement and consumer migration away from sugary soft drinks.
Which companies are active in the Probiotic Drink Market during 2026?
Notable companies active in the market include Danone S.A., Yakult Honsha Co., Ltd., PepsiCo (KeVita), Lifeway Foods, Inc., BioGaia AB, Probi AB, Novonesis, GoodBelly (NextFoods), Chobani LLC, and Harmless Harvest. These participants focus on clinically documented strains, cold-fill aseptic canning, and low-sugar botanical recipes.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
