
- Market Size (2026)
- USD 1.9 Bn
- Forecast (2036)
- USD 3.8 Bn
- CAGR (2026 to 2036)
- 7.2%
How big is Progesterone Market in 2026?
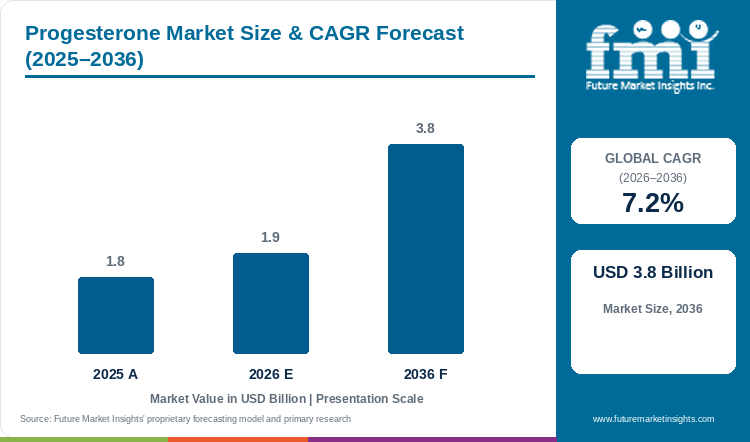
With a valuation of USD 1.8 billion in 2025 and moving to USD 1.9 billion in 2026, the progesterone market is positioned to attain USD 3.8 billion by 2036, exhibiting a CAGR of 7.2%.
Table 1: Market Size and Forecast for the Progesterone Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 1.8 billion |
| Estimated Market Size in 2026 | USD 1.9 billion |
| Projected Market Size by 2036 | USD 3.8 billion |
| CAGR, 2026 to 2036 | 7.2% |
| Added Revenue, 2026 to 2036 | USD 1.9 billion |
The global progesterone market was valued at USD 1.8 billion in 2025 and is estimated to reach USD 1.9 billion in 2026. The market is projected to reach USD 3.8 billion by 2036, expanding at a compound annual growth rate (CAGR) of 7.2% between 2026 and 2036. Micronized Natural Progesterone USP commands an anticipated 57.2% share of 2026 demand, given that reproductive endocrinologists and menopause specialists prefer bioidentical steroid structures that avoid the androgenic and glucocorticoid off-target effects of older synthetic progestins. Formulation trend analysis by FMI indicates that prescription volume is driven by rising maternal age at first childbirth and frozen-thawed embryo transfer protocols that require exogenous luteal hormone supplementation for ten to twelve weeks per cycle. Demand for standardized luteal and endocrine prescribing is supported by the World Health Organization first global guideline on infertility issued in November 2025, which established 40 clinical recommendations to integrate fertility care into national health financing for the one in six people of reproductive age affected globally. That fertility-driven cycle intensity distinguishes the category from broader hormone replacement therapy at a 5.2% CAGR, since each assisted conception patient consumes two to three daily doses across multi-week luteal protocols. Active corporate investment backs this expansion, evidenced when Ferring signed a USD 1.38 billion agreement in October 2026 to acquire Gameto and integrate cell-engineered maturation with its global luteal support platform. Sustained revenue growth through 2036 hinges on public insurance reimbursement for assisted reproduction cycles and patient-friendly vaginal and aqueous subcutaneous dosage formats.
Key Market Trends & Insights
- By chemical formulation: Micronized Natural Progesterone USP holds an estimated 57.2% share in 2026 since bioidentical progesterone avoids synthetic progestin metabolic side effects during pregnancy and menopause.
- By delivery route: Oral Soft Gelatin Capsules represent an estimated 35.9% in 2026 driven by high patient convenience across endometrial protection and luteal regimens.
- By clinical application: Assisted Reproductive Technology Luteal Support accounts for an anticipated 39.7% in 2026 owing to rising frozen embryo transfer volumes requiring exogenous corpus luteum replacement.
- By source synthesis: Diosgenin Semisynthetic Plant Extraction secures a projected 68.4% in 2026 supported by established Marker degradation steroid manufacturing in Europe and Asia.
- By distribution channel: Fertility Clinics and Hospital Pharmacies command an estimated 46.8% in 2026 through protocol-bundled dispensing during oocyte retrieval and embryo transfer.
Regional Highlights
- Top national expansion: The United States leads national growth projections at a 7.8% CAGR through 2036 under expanding employer fertility benefits and rising maternal conception ages above 30 years.
- Broader country progression: South Korea tracks at a 7.6% CAGR ahead of Saudi Arabia at 7.4% and the United Kingdom at 7.1%, while Germany advances at a 5.9% CAGR.
Market Size & Forecast
Controlled ovarian stimulation and GnRH agonist or antagonist triggers during in vitro fertilization suppress endogenous luteinizing hormone pulsatility, creating an iatrogenic luteal phase defect that prevents embryo implantation without external hormone supplementation. Per U.S. FDA prescribing documentation for Endometrin updated in 2026, patients undergoing assisted reproductive technology require 100 mg vaginal progesterone inserts two or three times daily starting the day after oocyte retrieval for up to 10 weeks . Consequently, reproductive clinics expanding in vitro fertilization capacity generate predictable multi-box progesterone prescriptions on every initiated transfer cycle.
ART Cycle Volume and Luteal Dosing Sizing
Table 2: ART Cycle Volume and Active Steroid Sizing for the Progesterone Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 1.8 | 1.9 | 3.8 |
| Global assisted reproductive technology treatment cycles (million) | 3.6 to 3.9 | 3.9 to 4.2 | 7.4 to 8.1 |
| Frozen embryo transfer share of total ART cycles (%) | 46.0% to 52.0% | 48.0% to 55.0% | 64.0% to 70.0% |
| Active micronized progesterone & progestin API volume (metric tons) | 410 to 445 | 438 to 475 | 860 to 935 |
Operational note: Dosing ranges reflect standard 200 to 600 mg/day micronized vaginal or oral progesterone and 20 to 30 mg/day oral dydrogesterone across luteal and menopausal regimens.
Oral administration of crystalline progesterone suffers from extensive hepatic first-pass metabolism where plasma half-life averages 16.8 hours with wide inter-patient variability. In April 2026, the World Health Organization Prequalification Team published bioequivalence design guidance for progesterone vaginal rings, confirming that vaginal mucosal delivery bypasses gastrointestinal and hepatic first-pass clearance to achieve peak plasma concentrations within one to three days. Hospital obstetric units managing preterm birth prevention and management and luteal support routinely specify micronized vaginal inserts, bioadhesive gels, and sustained rings to maintain stable uterine tissue concentrations.
Reproductive Clinic & Formulation Channel Sizing
Table 3: Reproductive Clinic and Formulation Spending Indicators for the Progesterone Market (USD and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Micronized Natural Progesterone USP share (%) | 56.5% | 57.2% | 63.4% |
| Fertility clinics & hospital pharmacies revenue (USD billion) | 0.84 | 0.89 | 1.78 |
| Average luteal phase progesterone spend per ART cycle (USD) | 185 to 260 | 190 to 270 | 225 to 315 |
| Vaginal & subcutaneous aqueous luteal administration share (%) | 51.0% to 55.0% | 52.5% to 56.8% | 61.0% to 66.0% |
Table 4: Clinical Channel & Institutional Reference Indicators for the Progesterone Market (USD billion and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 1.9 billion | 2026 global pharmaceutical revenue baseline |
| Global reproductive-age infertility prevalence | 1 in 6 adults (17.5%) | WHO First Global Guideline on Infertility (November 2025) |
| UK licensed clinic treatment & storage cycles | 100,300 cycles | HFEA Fertility Sector Report 2025/26 (October 2026) |
| Fertility Clinics and Hospital Pharmacies revenue, 2026 | USD 0.89 billion | 46.8% distribution channel allocation |
Frozen embryo transfer cycles performed in programmed artificial endometrial cycles lack a functional corpus luteum entirely, requiring high-dose exogenous progesterone until the luteo-placental shift occurs between gestational weeks seven and twelve. In April 2026, Organon Canada published the updated Product Monograph for Utrogestan 200 mg micronized progesterone soft gelatin capsules, specifying a 600 mg daily divided dosage from the day of embryo transfer through at least the seventh to twelfth week of pregnancy. Fertility pharmacy networks supplying infertility drugs consequently bundle multi-blister micronized softgels with gonadotropin stimulation kits.
Analyst Perspective
"Progesterone demand is structurally decoupled from general pharmaceutical volume since programmed frozen embryo transfers and midlife estradiol replacement both mandate concomitant progestogen coverage. Manufacturers that eliminate painful intramuscular oil injections via high-bioavailability vaginal inserts, aqueous subcutaneous solutions, and oral retroprogesterone tablets are positioned to capture clinic protocol share through 2036."
- Anurag Sharma, Principal Consultant, Future Market Insights.
How is the progesterone market segmented?
The progesterone market is segmented by chemical formulation, delivery route, clinical application, source synthesis, and distribution channel. In 2026, Micronized Natural Progesterone USP is projected at 57.2%, Oral Soft Gelatin Capsules at 35.9%, Assisted Reproductive Technology Luteal Support at 39.7%, Diosgenin Semisynthetic Plant Extraction at 68.4%, and Fertility Clinics and Hospital Pharmacies at 46.8%.
By chemical formulation: Micronized Natural Progesterone USP, Retroprogesterone Dydrogesterone Derivatives, Medroxyprogesterone Acetate Esters and Norethindrone and Levonorgestrel Progestins.
By delivery route: Oral Soft Gelatin Capsules, Vaginal Micronized Gels and Inserts, Intramuscular Oil Injection Solutions and Subcutaneous Aqueous Injections.
By clinical application: Assisted Reproductive Technology Luteal Support, Menopausal Hormone Replacement Therapy, Recurrent Preterm Birth Prevention and Secondary Amenorrhea Management as well as Dysfunctional Uterine Bleeding Control.
By source synthesis: Diosgenin Semisynthetic Plant Extraction, Stigmasterol Soy Sterol Bioconversion, Microbial Fermentation Steroid Intermediates and Fully Synthetic Progestogen Synthesis.
By distribution channel: Fertility Clinics and Hospital Pharmacies, Retail Community Pharmacies, Specialty Reproductive Mail-Order Pharmacies and Telehealth Women Health Dispensaries.
Why does Micronized Natural Progesterone USP lead the chemical formulation category?
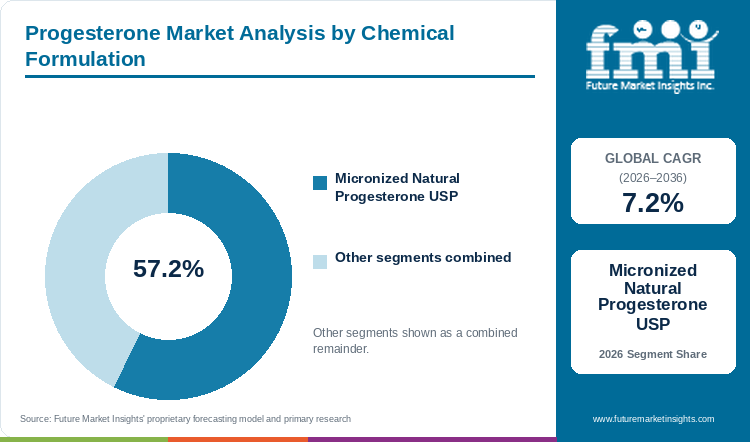
Micronized Natural Progesterone USP holds an estimated 57.2% of chemical formulation demand in 2026, anchored by bioidentical receptor specificity across luteal and menopausal care.
Table 5: Chemical Formulation Share for the Progesterone Market (percentage share), 2026
| Chemical Formulation | Share (2026) |
|---|---|
| Micronized Natural Progesterone USP | 57.2% |
| Other Segments Combined | 42.8%* |
| Total | 100.0% |
*Note: Remaining chemical formulation categories account for the balance of 2026 global progesterone demand.
Table 6: Chemical Formulation Leadership and Market Growth for the Progesterone Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.2% |
| Leading Segment | Micronized Natural Progesterone USP |
Micronized Natural Progesterone USP milled to particle diameters below 10 micrometers and suspended in arachis or sunflower oil with soybean lecithin matches endogenous human corpus luteum hormone molecularly. Medical societies in North America and Europe recommend bioidentical micronized progesterone over androgenic synthetic progestins in combined hormone replacement therapy and IVF luteal support due to lower breast mitotic stimulation and neutral high-density lipoprotein impact. Formulators rely on specialized softgel capsules and vaginal inserts to stabilize the lipophilic steroid suspension. Clinical research published in Biomedicines in October 2025 comparing luteal support protocols across assisted reproductive technology cycles confirmed that standardized micronized progesterone maintains endometrial secretory transformation and live-birth rates comparable to parenteral regimens.
- Within the chemical formulation segment, Micronized Natural Progesterone USP is projected to account for a leading 57.2% share in 2026, driven by clinical guideline preference for bioidentical hormone safety in pregnancy and menopause.
- Segment competition through 2036 is anticipated to intensify in East Asia and Europe where oral retroprogesterone dydrogesterone tablets offer three-times-daily oral dosing without vaginal discharge.
What sustains Oral Soft Gelatin Capsules leadership in the delivery route segment?
Oral Soft Gelatin Capsules represent an estimated 35.9% of the delivery route category in 2026, supported by non-invasive daily dosing convenience.
Hermetically sealed 100 mg and 200 mg Oral Soft Gelatin Capsules containing micronized progesterone in oil suspension serve as the workhorse prescription format across menopausal endometrial protection, secondary amenorrhea, and dual-route luteal protocols. Oral capsules avoid the sterile needle anxiety and sterile abscess risks of intramuscular sesame-oil injections as well as the local perineal irritation reported with multi-daily vaginal pessaries. Prescribers managing menopause treatment routinely pair bedtime oral micronized progesterone capsules with transdermal estradiol to prevent endometrial hyperplasia while leveraging mild neurosteroid allopregnanolone sedation to improve sleep quality.
- In 2026, Oral Soft Gelatin Capsules are anticipated to capture 35.9% of global delivery route demand, reflecting broad retail pharmacy availability and high patient adherence across long-term therapy.
- In April 2026, a clinical investigation in Frontiers in Endocrinology evaluated oral dydrogesterone and micronized progesterone regimens across assisted reproduction cohorts, confirming high patient satisfaction with oral administration routes.
How does Assisted Reproductive Technology Luteal Support lead the clinical application category?
Assisted Reproductive Technology Luteal Support accounts for an anticipated 39.7% of clinical application demand in 2026, driven by programmed frozen embryo transfer growth.
Every fresh and frozen-thawed embryo transfer cycle requires intensive luteal phase progesterone supplementation to induce decidualization of the endometrium, suppress uterine myometrial contractility, and modulate maternal-fetal immune tolerance. Higher prevalence of polycystic ovary syndrome and endometriosis treatment as well as delayed childbearing has expanded annual global fertility clinic volumes and shifted practice toward freeze-all vitrification cycles that rely entirely on exogenous hormone replacement. In October 2026, the UK fertility regulator HFEA reported in its 2025/26 fertility sector audit that UK licensed clinics performed approximately 83,100 treatment cycles and 17,200 egg and embryo storage cycles.
- By clinical application, demand for Assisted Reproductive Technology Luteal Support is estimated to reach 39.7% of total category share in 2026 as frozen embryo transfers require 10 to 12 weeks of continuous multi-daily dosing.
- High out-of-pocket cycle costs in under-insured markets remain the primary adoption barrier, though expanding statutory fertility coverage in East Asia and Europe is broadening treated patient access.
Why does Diosgenin Semisynthetic Plant Extraction lead the source synthesis category?
Diosgenin Semisynthetic Plant Extraction secures a projected 68.4% of source synthesis share in 2026, supported by high-yield Marker degradation steroid chemistry.
Industrial active pharmaceutical ingredient synthesis of progesterone USP relies predominantly on the Marker degradation of diosgenin extracted from Dioscorea tubers cultivated in China, Mexico, and India. Diosgenin provides a chiral steroid nucleus with the exact stereochemistry required for five-step conversion into pregnenolone and progesterone at high multi-ton batch yields. Environmental wastewater regulations around chromic acid oxidation in Chinese diosgenin plants create periodic raw-material cost swings, prompting API producers to qualify cleaner catalytic oxidation and soy stigmasterol bioconversion routes.
- Diosgenin Semisynthetic Plant Extraction is predicted to secure 68.4% of source synthesis demand in 2026, supported by established Drug Master File registrations across European and North American generic formulators.
- In October 2025, the U.S. Food and Drug Administration issued revised product-specific bioequivalence guidance PSG_022057 for 100 mg progesterone vaginal inserts, standardizing physicochemical particle-size and in vitro dissolution criteria for generic API qualifiers.
What gives Fertility Clinics and Hospital Pharmacies the leading position in distribution channel?
Fertility Clinics and Hospital Pharmacies command an estimated 46.8% of distribution channel share in 2026, anchored by cycle-synchronized luteal dispensing.
Reproductive endocrinology centers and hospital obstetric pharmacies control initiation prescriptions for luteal support inserts, intramuscular progesterone-in-oil vials, and high-risk preterm birth prophylaxis. Given that luteal progesterone timing must synchronize within hours of oocyte retrieval or progesterone-start day in programmed frozen embryo transfers, fertility clinics dispense starter and maintenance packs directly through captive clinic pharmacies. In April 2026, Swiss specialty leader Ferring and Gallup launched the Global Fertility Monitor across 70 countries to track clinical and socioeconomic barriers shaping patient entry into reproductive care centers.
- Projected to hold a 46.8% share of the distribution channel segment in 2026, Fertility Clinics and Hospital Pharmacies anchor high-value luteal and obstetric injectable fulfillment.
- Over the 2026 to 2036 forecast window, digital menopause platforms and specialty fertility mail-order couriers are expected to capture a growing share of maintenance refills.
What are the drivers, restraints, and opportunities in the progesterone market?
In the progesterone market, rising IVF frozen embryo transfers and bioidentical hormone replacement are projected to drive adoption, while hepatic first-pass clearance and oil-injection pain restrain conventional routes and aqueous subcutaneous formulations open new growth.
- Driver: Expanding assisted reproductive technology cycle volumes and rising frozen-thawed embryo transfer protocols mandate high-dose multi-week luteal progesterone supplementation.
- Restraint: Extensive hepatic first-pass metabolism in oral crystalline forms, vaginal discharge from pessaries, and bone mineral density warnings on depot synthetic progestins limit adherence.
- Opportunity: Aqueous cyclodextrin-complexed subcutaneous progesterone injections and once-weekly vaginal rings create high-margin convenience upgrades for fertility clinics.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Delayed maternal age at first pregnancy and the global clinical transition from fresh embryo transfers to vitrified-warmed frozen embryo transfers are propelling sustained volume growth in the progesterone market. In programmed artificial frozen embryo transfer cycles, ovulation is pharmacologically suppressed, meaning the patient produces zero endogenous corpus luteum progesterone and depends on daily exogenous dosing through the first trimester. While progestin-containing contraceptives deliver microgram daily doses to suppress ovulation, luteal support regimens require 200 mg to 800 mg of micronized progesterone daily. Clinical evidence published in the Journal of Clinical Medicine in May 2025 comparing oral dydrogesterone and vaginal progesterone across programmed embryo transfer cohorts confirmed that optimized luteal rescue and dual-route protocols significantly improve ongoing pregnancy rates.
Risk Assessment of the Progesterone Market: Operational and Formulation Friction
Route-specific tolerability friction and long-term synthetic progestin safety warnings represent the primary clinical restraints moderating patient persistence across progesterone and progestin therapies. Intramuscular progesterone-in-oil injections cause local injection-site pain and sterile abscesses, vaginal micronized capsules cause daily discharge and irritation, and depot medroxyprogesterone acetate carries regulatory bone-loss warnings. Per Pfizer prescribing labeling for Depo-Provera CI 150 mg intramuscular suspension updated in late 2025, adolescents using depot medroxyprogesterone acetate for two years experienced mean bone mineral density reductions of 4.3% at the total hip and 4.2% at the femoral neck. Clinicians managing long-term hormonal contraception and endometriosis consequently monitor treatment duration and switch patients toward lower-risk bioidentical or localized delivery options.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Pharmaceutical formulators open substantial commercial growth avenues by replacing painful oil-based intramuscular injections and messy thrice-daily vaginal inserts with water-soluble hydroxypropyl-beta-cyclodextrin subcutaneous progesterone injections and sustained-release vaginal rings. National demographic pressures are also prompting governments to subsidize fertility preservation and luteal medications as well as fertility supplements as birth rates decline below replacement thresholds. In June 2025, the United Nations Population Fund State of World Population report documented that financial and healthcare access barriers prevent millions of adults across declining-fertility nations from realizing their desired family size. Suppliers that pair subsidized public tender pricing with painless self-injected subcutaneous aqueous progesterone capture high repeat clinic adoption through 2036.
Progesterone Market by Country (2026 to 2036)
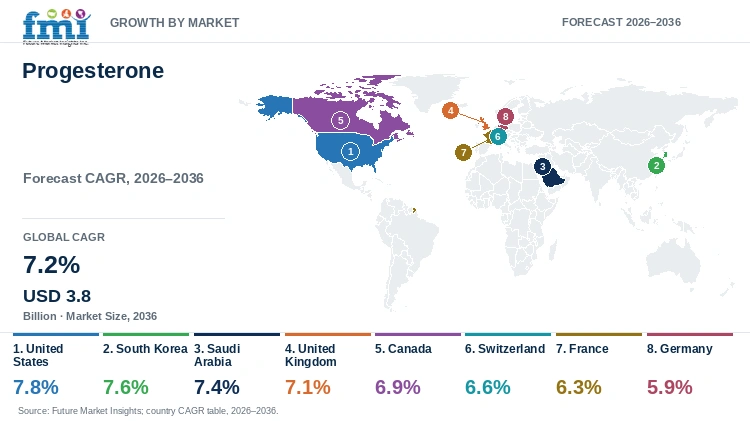
Long-term forecast modeling at FMI points to the United States leading progesterone market expansion at a 7.8% CAGR through 2036, while Germany advances at a 5.9% CAGR. National growth trajectories reflect maternal age distributions at first birth, public insurance reimbursement for in vitro fertilization cycles, and menopausal hormone replacement prescribing guidelines.
Table 7: Country CAGR and Primary Growth Levers for the Progesterone Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| United States | 7.8% | Rising birth rates in mothers aged 30-44 (CDC 2025) and employer IVF benefit expansion |
| South Korea | 7.6% | National IVF reimbursement expansion countering a 0.80 total fertility rate |
| Saudi Arabia | 7.4% | Vision 2030 maternal health investments (SAR 124B) and private IVF clinic growth |
| United Kingdom | 7.1% | 48% frozen embryo transfer share across 83,100 HFEA cycles and NICE miscarriage guidance |
| Canada | 6.9% | Record 31.9-year mean maternal age and provincial IVF tax credits and Utrogestan protocols |
| Switzerland | 6.6% | Single-embryo transfer precision (97.8% singleton IVF births) and specialist fertility centers |
| France | 6.3% | Full statutory reimbursement for up to 4 ART cycles and bioidentical HRT preference |
| Germany | 5.9% | Demographic pressure from 1.32 fertility rate and Kinderwunsch clinic luteal protocols |
Source: Future Market Insights analysis
United States Progesterone Market Outlook (2026 to 2036)
Demand for progesterone in the United States is projected to expand at a leading 7.8% CAGR between 2026 and 2036 as corporate employer fertility benefits and delayed maternal childbearing drive record assisted reproductive technology cycle volumes. Domestic commercial demand is driven by the high share of preimplantation genetic testing and frozen embryo transfer cycles that require 10 to 12 weeks of intensive vaginal and intramuscular progesterone supplementation. Official birth records published by the Centers for Disease Control and Prevention in October 2026 confirm this demographic shift, documenting 3,612,012 U.S. births in 2025 where birth rates fell for women under 30 but rose 3% to 96.3 per 1,000 for women aged 30 to 34 and rose 2% for ages 35 to 39. Pharmacy compounding competition and variable state IVF insurance mandates remain the primary commercial hurdles.
Key takeaway: In the United States, rising maternal birth rates among women aged 30 to 44 and high frozen embryo transfer shares are projected to drive a 7.8% CAGR.
South Korea Progesterone Market Outlook (2026 to 2036)
South Korea's municipal and national health authorities have expanded statutory copay subsidies for in vitro fertilization and luteal phase medications to counter the world's lowest national fertility rate. Consequently, progesterone demand in South Korea is anticipated to advance at a 7.6% CAGR through 2036, outpacing European markets as government-funded fertility clinics in Seoul and Gyeonggi province lift cycle caps for married and unmarried women. Comparative demographic records released by Statistics Canada in September 2026 highlighted that South Korea recorded a total fertility rate of 0.80 children per woman in 2025, the lowest among 20 high-income nations. Strict National Health Insurance drug price ceilings nevertheless pressure unit margins for imported vaginal gels.
Key takeaway: In South Korea, expanded national IVF reimbursement subsidies responding to a 0.80 fertility rate are anticipated to propel a 7.6% CAGR through 2036.
Saudi Arabia Progesterone Market Outlook (2026 to 2036)
Private women's health hospitals and maternal-fetal medicine centers under Vision 2030 are accelerating prescription progesterone uptake across Saudi Arabia. Healthcare procurement tracking at FMI finds that the Saudi Arabia progesterone market is estimated to grow at a 7.4% CAGR over the 2026 to 2036 forecast period, supported by high clinical utilization in recurrent miscarriage prevention and assisted conception. In February 2026, the Saudi Ministry of Health released its 2025 Health Sector Annual Report documenting SAR 124 billion in healthcare transformation investments and a 40% reduction in chronic non-communicable mortality as life expectancy reached 79.7 years. Reliance on imported finished softgels and cold-chain logistics across desert corridors remains a local supply-chain consideration.
Key takeaway: In Saudi Arabia, Vision 2030 maternal health investments and private IVF hospital expansion are estimated to sustain a 7.4% CAGR.
United Kingdom Progesterone Market Outlook (2026 to 2036)
In the United Kingdom, market growth is forecast to reach a 7.1% CAGR through 2036, anchored by National Institute for Health and Care Excellence guidelines recommending vaginal micronized progesterone for women with early pregnancy bleeding and prior miscarriage as well as growing private IVF cycles. UK patients frequently self-fund frozen embryo transfer cycles at HFEA-licensed clinics when local NHS Integrated Care Boards restrict cycle allowances. In June 2026, the UK Human Fertilisation and Embryology Authority announced that annual UK IVF patient numbers tripled over 30 years to 53,000 patients, with frozen embryo transfers reaching 48% of all cycles while NHS-funded share declined to 28%. Regional NHS formulary disparities remain a local access hurdle.
Key takeaway: In the United Kingdom, a 48% frozen embryo transfer share across 53,000 annual IVF patients and NICE miscarriage guidelines are forecast to drive a 7.1% CAGR.
Canada Progesterone Market Outlook (2026 to 2036)
Prescription demand for progesterone in Canada is slated to progress at a 6.9% CAGR between 2026 and 2036 as provincial tax credits and public fertility funding programs expand across Ontario, Quebec, and British Columbia. What sets Canada apart is its record-high average maternal age at childbirth, which increases clinical reliance on assisted conception and micronized vaginal progesterone luteal protocols. In April 2026, Organon Canada updated its clinical patient dosing documentation for Utrogestan 200 mg vaginal soft capsules to support standardized three-times-daily luteal administration across Canadian fertility centers. Provincial formulary prior-authorization requirements for branded vaginal inserts still encourage generic oral softgel substitution in cost-sensitive plans.
Key takeaway: In Canada, rising maternal childbirth age above 31.9 years and provincial IVF funding programs are slated to support a 6.9% CAGR.
Switzerland Progesterone Market Outlook (2026 to 2036)
Switzerland combines high per-capita out-of-pocket spending on advanced reproductive medicine with domestic pharmaceutical headquarters expertise in peptide and steroid reproductive therapies. Sales of progesterone in Switzerland are expected to rise at a 6.6% CAGR from 2026 to 2036 across specialized fertility clinics in Zurich, Geneva, and Basel. National demographic tables from the Swiss Federal Statistical Office in September 2026 tracking demographic indicators through 2025 confirm sustained maternal age advancement and single-embryo transfer standardization that reduces multiple births to 2.2% of IVF deliveries. Lack of mandatory basic health insurance coverage for full IVF cycles beyond intrauterine insemination restrains total domestic cycle volume.
Key takeaway: In Switzerland, high single-embryo transfer precision and premium subcutaneous and vaginal luteal prescribing are expected to maintain a 6.6% CAGR.
France Progesterone Market Outlook (2026 to 2036)
France provides full statutory National Health Insurance reimbursement for up to four assisted reproductive technology cycles per pregnancy plus Europe's highest historical preference for bioidentical micronized progesterone in menopause care. Consequently, the French progesterone market is projected to grow at a 6.3% CAGR through 2036 as public and private fertility centers process expanded oocyte preservation and transfer queues following the bioethics law expansion. In July 2026, the French national statistics bureau INSEE reported 643,905 births in France in 2025, noting that childbirth postponement among women born after 1985 continues to elevate demand for medical reproductive support after age 35. Strict statutory CEPS price controls compress per-box manufacturer realizations.
Key takeaway: In France, full statutory reimbursement for four ART cycles and widespread bioidentical hormone prescribing are projected to yield a 6.3% CAGR.
Germany Progesterone Market Outlook (2026 to 2036)
German progesterone expenditure is predicted to advance at a 5.9% CAGR between 2026 and 2036 across outpatient gynecological practices and university Kinderwunsch fertility centers. German statutory health insurance funds typically reimburse 50% of approved IVF treatment costs for up to three cycles, creating moderate out-of-pocket co-payments that temper cycle growth during economic slowdowns. In July 2026, the German Federal Statistical Office Destatis reported that Germany's total fertility rate declined to 1.32 children per woman in 2025, intensifying federal policy debate over expanding statutory reproductive medicine subsidies.
Key takeaway: In Germany, demographic pressure from a 1.32 fertility rate and expanding gynecological menopause prescribing are predicted to sustain a 5.9% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the progesterone market?
Besins Healthcare, Ferring Pharmaceuticals, Organon & Co., Pfizer Inc., AbbVie Inc., Bayer AG, Sandoz Group AG, Teva Pharmaceutical Industries Ltd., Lupin Limited, and Viatris Inc. are the notable companies in the progesterone market.
Competitive positioning in the progesterone industry separates dedicated reproductive and bioidentical hormone specialists, global women's health pharmaceutical innovators, and high-volume generic steroid and softgel manufacturers. Besins and Ferring as well as Organon and AbbVie anchor branded micronized progesterone softgels, vaginal luteal inserts, and bioadhesive gels across fertility clinics. Pfizer and Bayer supply injectable and oral synthetic progestin franchises. Sandoz, Teva, Lupin and Viatris scale generic oral capsules and vaginal preparations.
- Dedicated Reproductive and Bioidentical Hormone Leaders: Besins Healthcare, Ferring, Organon and AbbVie commercialize branded Utrogestan and Endometrin formulations tailored to IVF luteal support and menopausal endometrial protection.
- Global Women's Health and Progestin Innovators: Pfizer Inc. and Bayer AG manufacture hospital intramuscular and subcutaneous medroxyprogesterone suspensions, oral progestins, and endocrine therapies across global gynecology networks.
- Generic Steroid and Softgel Capsule Manufacturers: Sandoz, Teva, Lupin and Viatris produce bioequivalent micronized progesterone soft gelatin capsules and sterile oil injections.
Competitive Benchmarking: Progesterone Market
Table 8: Competitive Benchmarking for the Progesterone Market (qualitative capability ratings), 2026
| Company | Micronized & Bioidentical Depth | ART Luteal Clinic Reach | Global Women's Health Scale | Geographic Reach |
|---|---|---|---|---|
| Besins Healthcare | High | High | High | Global bioidentical hormone specialist; Utrogestan and Progestogel across 100+ countries |
| Ferring Pharmaceuticals | High | High | High | Global reproductive medicine leader; Endometrin, Lutinus, and USD 1.38B Gameto agreement in Oct 2026 |
| Organon & Co. | High | High | High | Global women's health company; Canadian Utrogestan monograph update in April 2026 |
| Pfizer Inc. | Medium | Medium | High | Global sterile injectable and hospital network; Depo-Provera, Sayana Press, and Provera |
| AbbVie Inc. | High | High | High | North American and global endocrine reach; Prometrium capsules and Crinone 8% vaginal gel |
| Bayer AG | Medium | Medium | High | Global women's healthcare leader; launched Menopause Advocacy and Policy Alliance in Oct 2026 |
| Sandoz Group AG | High | Medium | High | Global generic pharmaceutical leader; micronized progesterone softgels across Europe and US |
| Teva Pharmaceutical Industries Ltd. | High | Medium | High | Global generic and women's health portfolio; bioequivalent progesterone capsules and injectables |
| Lupin Limited | Medium | Medium | High | North America, India, and APAC women's health generics and oral hormonal formulations |
| Viatris Inc. | Medium | Medium | High | Global retail and hospital generic distribution; oral dydrogesterone and micronized softgels |
Evaluation basis: Micronized & Bioidentical Depth evaluates documented particle-size control and softgel/vaginal encapsulation of natural progesterone USP, while ART Luteal Clinic Reach measures direct protocol integration across IVF centers. Global Women's Health Scale rates geographic regulatory registrations and menopausal/obstetric pharmacy distribution.
Key Developments in the Progesterone Market
- Bayer AG launched the global Menopause Advocacy and Policy Alliance on October 2, 2026 at the 2026 IMS Congress to expand coordinated clinical guidelines and workplace policy for midlife hormonal care across 12 countries.
- In April 2025, the UK Medicines and Healthcare products Regulatory Agency issued regulatory notice EL(25)A/13 for Utrogestan Vaginal 200 mg progesterone capsules to standardize milligram carton overlabeling across UK pharmacy wholesalers.
- Organon & Co. presented new real-world health-economic and patient-access research across its women's reproductive and endocrine portfolio at the ISPOR 2026 conference on May 15, 2026.
Key Players in the Progesterone Market
Dedicated Reproductive and Bioidentical Hormone Leaders
- Besins Healthcare
- Saint-Prex Ferring Pharmaceuticals
- Organon & Co.
- AbbVie Inc.
Global Women's Health and Progestin Innovators
- Pfizer Inc.
- Bayer AG
- Generic Steroid and Softgel Capsule Manufacturers
- Sandoz Group AG
Teva Pharmaceutical Industries Ltd.
- Lupin Limited
- Viatris Inc.
Progesterone Market - Report Scope
Table 9: Report Scope for the Progesterone Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Chemical Formulation; Delivery Route; Clinical Application; Source Synthesis; Distribution Channel |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial pharmaceutical manufacturer revenue from prescription natural micronized progesterone USP and therapeutic synthetic progestins (dydrogesterone, medroxyprogesterone acetate, norethindrone, levonorgestrel) across oral softgels, vaginal gels/inserts/rings, and intramuscular/subcutaneous injections. Category Scope Note: Excludes non-hormonal copper IUDs, gonadotropin stimulation drugs, and over-the-counter herbal supplements. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | United States, South Korea, Saudi Arabia, United Kingdom, Canada, Switzerland, France, Germany, and additional countries in the full report |
| Key Companies Covered | Besins Healthcare, Ferring Pharmaceuticals, Organon & Co., Pfizer Inc., AbbVie Inc., Bayer AG, Sandoz Group AG, Teva Pharmaceutical Industries Ltd., Lupin Limited, Viatris Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Progesterone Market - Research Methodology
Table 10: Research Methodology for the Progesterone Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with reproductive endocrinology clinic directors, hospital obstetric pharmacists, softgel encapsulation engineers, and steroid API procurement managers. |
| Secondary Research | Analysis of WHO infertility and prequalification guidelines, U.S. FDA Drugs@FDA and PSG_022057 dockets, HFEA UK fertility sector audits, CDC NCHS, Statistics Canada, INSEE, Destatis, and FSO Switzerland birth records. |
| Market Sizing and Forecasting | Top-down global endocrine and fertility drug baselines reconciled against bottom-up ART treatment cycles (3.9M to 4.2M cycles in 2026) and menopausal HRT prescription cohorts from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight maternal age at childbirth, frozen embryo transfer shares, and public IVF reimbursement coverage across eight national markets. |
| Operational Benchmark Traceability | Cycle, dosage, and channel indicators in Tables 2, 3, and 4 trace to FDA Endometrin and Organon Utrogestan labeling, WHO Prequalification ring studies, and HFEA 2025/26 national cycle audits. |
| Data Triangulation and Validation | Revenue estimates isolate active progesterone and therapeutic progestin drug formulations while strictly excluding non-participating life-science conglomerates, laboratory incubators, and diagnostic test kits. |
Progesterone Market by Segments
Progesterone Market segmented by Chemical Formulation:
- Micronized Natural Progesterone USP
- Retroprogesterone Dydrogesterone Derivatives
- Medroxyprogesterone Acetate Esters
- Norethindrone and Levonorgestrel Progestins
Progesterone Market segmented by Delivery Route:
- Oral Soft Gelatin Capsules
- Vaginal Micronized Gels and Inserts
- Intramuscular Oil Injection Solutions
- Subcutaneous Aqueous Injections
Progesterone Market segmented by Clinical Application:
- Assisted Reproductive Technology Luteal Support
- Menopausal Hormone Replacement Therapy
- Recurrent Preterm Birth Prevention
- Secondary Amenorrhea Management
- Dysfunctional Uterine Bleeding Control
Progesterone Market segmented by Source Synthesis:
- Diosgenin Semisynthetic Plant Extraction
- Stigmasterol Soy Sterol Bioconversion
- Microbial Fermentation Steroid Intermediates
- Fully Synthetic Progestogen Synthesis
Progesterone Market segmented by Distribution Channel:
- Fertility Clinics and Hospital Pharmacies
- Retail Community Pharmacies
- Specialty Reproductive Mail-Order Pharmacies
- Telehealth Women Health Dispensaries
Progesterone Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- Al-Mansoor, H., & Clinical Obstetrics Network. (2025, May 7). Oral dydrogesterone versus vaginal progesterone for luteal phase support in programmed embryo transfer cycles. Journal of Clinical Medicine (MDPI), 14(9), 3238.
- Bayer AG. (2026, October 2). Bayer launches new Menopause Advocacy and Policy (MAP) Alliance at International Menopause Society Congress 2026. Bayer Corporate Media Releases.
- Centers for Disease Control and Prevention. (2026, October 21). Births in the United States, 2025: National Vital Statistics System maternal age and fertility data brief. CDC NCHS Data Brief No. 571.
- Ferring Pharmaceuticals. (2026, April 16). Ferring Pharmaceuticals and Gallup announce landmark 70-country global public attitudes study on fertility and family-building. Ferring Corporate Announcements.
- Ferring Pharmaceuticals. (2026, October 27). Ferring Pharmaceuticals and Gameto sign agreement for proposed acquisition to advance reproductive medicine. Ferring Global Press Releases.
- Human Fertilisation and Embryology Authority. (2026, June 16). Number of IVF patients triples in 30 years with frozen embryo transfers reaching 48% of UK cycles. HFEA UK Regulatory Press Releases.
- Human Fertilisation and Embryology Authority. (2026, October 15). The fertility sector 2025/26: UK national audit of 83,100 treatment cycles and 137 licensed clinics. HFEA United Kingdom Official Publications.
- Institut national de la statistique et des etudes economiques. (2026, July 6). Births in 2025 and maternal age postponement trends across France (643,905 live births). INSEE Focus No. 383.
- Kovacs, P., & Reproductive Endocrinology Group. (2025, October 13). Comparison of different progesterone protocols for luteal support in assisted reproductive technology. Biomedicines (MDPI), 13(10), 2487.
- Medicines and Healthcare products Regulatory Agency. (2025, April 1). Utrogestan Vaginal 200 mg Capsules (progesterone) PLPI 45396/0316 pharmacy and wholesaler regulatory notice EL(25)A/13. GOV.UK Medicines and Healthcare products Regulatory Agency.
- Ministry of Health Saudi Arabia. (2026, February 15). Ministry of Health releases the 2025 Health Sector Annual Report with SAR 124 billion in health transformation initiatives. Kingdom of Saudi Arabia MOH Media Center.
- Organon & Co. (2026, May 15). Organon presents new health-economic research on women's health access and value at ISPOR 2026. Organon Media Relations.
- Organon Canada Inc. (2026, April 2). Utrogestan (micronized progesterone 200 mg soft gelatin capsules) Product Monograph for luteal phase support. Organon Official Product Monographs.
- Organon Canada Inc. (2026, April 2). Utrogestan 200 mg vaginal soft capsule patient medication and dosing schedule monograph. Organon Canada Regulatory Filings.
- Pfizer Inc. (2025, November 12). Depo-Provera CI (medroxyprogesterone acetate injectable suspension 150 mg) prescribing and bone mineral density labeling. Pfizer Official Medical Labeling.
- Statistisches Bundesamt (Destatis). (2026, July 1). Total fertility rate in Germany drops to 1.32 children per woman in 2025 demographic release. Destatis Press Release PE26_230_12.
- Statistics Canada. (2026, September 23). The Daily: Fertility and maternal age indicators across Canada and selected OECD countries including South Korea, 2025. Statistics Canada Official Release 260923e.
- Swiss Federal Statistical Office. (2026, September 24). Live births per month, total fertility rate, and average age of mother in Switzerland through 2025. FSO Switzerland Vital Statistics px-x-0102020204_111.
- United Nations Population Fund. (2025, June 10). The real fertility crisis: The pursuit of reproductive agency in a changing world (2025 State of World Population). UNFPA Global Population Publications.
- U.S. Food and Drug Administration. (2025, October 15). Product-specific draft guidance on progesterone vaginal insert 100 mg bioequivalence studies. FDA Office of Generic Drugs PSG_022057.
- U.S. Food and Drug Administration. (2026, March 10). Endometrin (progesterone) vaginal insert 100 mg prescribing information for assisted reproductive technology luteal support. FDA Drugs@FDA Official Labeling.
- World Health Organization. (2025, November 28). WHO issues first global guideline on infertility with 40 evidence-based clinical recommendations. WHO News Releases.
- World Health Organization Prequalification Team. (2026, April 26). Notes on the design of bioequivalence study: Progesterone vaginal ring pharmacokinetics and LLOQ guidance. WHO Prequalification Medicines Guidance.
- Zhang, W., & Reproductive Medicine Consortium. (2026, April 16). Dydrogesterone versus micronized vaginal progesterone for luteal phase support in assisted reproductive technology. Frontiers in Endocrinology, 17, 1785932.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the progesterone market in 2026 and what is forecast for 2036?
- Which assisted reproductive technology and frozen embryo transfer trends support demand for progesterone?
- Why does Micronized Natural Progesterone USP lead the chemical formulation category?
- Why do Oral Soft Gelatin Capsules lead the delivery route category globally?
- How do growth rates differ across the United States, South Korea and Saudi Arabia?
- Which leading companies supply branded IVF luteal inserts versus generic oral softgel capsules today?
- What first-pass metabolism and tolerability hurdles affect delivery route selection in the progesterone market?
- What should fertility clinic directors evaluate when comparing vaginal inserts, oral dydrogesterone, and aqueous subcutaneous progesterone?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Chemical Formulation, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Chemical Formulation, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Chemical Formulation, 2026 to 2036
- Micronized Natural Progesterone USP
- Retroprogesterone Dydrogesterone Derivatives
- Medroxyprogesterone Acetate Esters
- Norethindrone and Levonorgestrel Progestins
- Y-o-Y Growth Trend Analysis By Chemical Formulation, 2021 to 2025
- Absolute $ Opportunity Analysis By Chemical Formulation, 2026 to 2036
- Global Market Analysis and Forecast, By Delivery Route, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Delivery Route, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Delivery Route, 2026 to 2036
- Oral Soft Gelatin Capsules
- Vaginal Micronized Gels and Inserts
- Intramuscular Oil Injection Solutions
- Subcutaneous Aqueous Injections
- Y-o-Y Growth Trend Analysis By Delivery Route, 2021 to 2025
- Absolute $ Opportunity Analysis By Delivery Route, 2026 to 2036
- Global Market Analysis and Forecast, By Clinical Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Clinical Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Clinical Application, 2026 to 2036
- Assisted Reproductive Technology Luteal Support
- Menopausal Hormone Replacement Therapy
- Recurrent Preterm Birth Prevention
- Secondary Amenorrhea Management
- Dysfunctional Uterine Bleeding Control
- Y-o-Y Growth Trend Analysis By Clinical Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Clinical Application, 2026 to 2036
- Global Market Analysis and Forecast, By Source Synthesis, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source Synthesis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source Synthesis, 2026 to 2036
- Diosgenin Semisynthetic Plant Extraction
- Stigmasterol Soy Sterol Bioconversion
- Microbial Fermentation Steroid Intermediates
- Fully Synthetic Progestogen Synthesis
- Y-o-Y Growth Trend Analysis By Source Synthesis, 2021 to 2025
- Absolute $ Opportunity Analysis By Source Synthesis, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Fertility Clinics and Hospital Pharmacies
- Retail Community Pharmacies
- Specialty Reproductive Mail-Order Pharmacies
- Telehealth Women Health Dispensaries
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Chemical Formulation
- By Delivery Route
- By Clinical Application
- By Source Synthesis
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Besins Healthcare
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Ferring Pharmaceuticals
- Organon & Co.
- Pfizer Inc.
- AbbVie Inc.
- Bayer AG
- Sandoz Group AG
- Teva Pharmaceutical Industries Ltd.
- Lupin Limited
- Viatris Inc.
- Saint-Prex Ferring Pharmaceuticals
- Generic Steroid and Softgel Capsule Manufacturers
- Besins Healthcare
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Chemical Formulation, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Delivery Route, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Clinical Application, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Source Synthesis, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Chemical Formulation, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Delivery Route, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Clinical Application, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Source Synthesis, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Chemical Formulation, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Delivery Route, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Clinical Application, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Source Synthesis, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Chemical Formulation, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Delivery Route, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Clinical Application, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Source Synthesis, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Chemical Formulation, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Delivery Route, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Clinical Application, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Source Synthesis, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Chemical Formulation, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Delivery Route, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Clinical Application, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Source Synthesis, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Chemical Formulation, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Delivery Route, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Clinical Application, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Source Synthesis, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Chemical Formulation, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Delivery Route, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Clinical Application, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Source Synthesis, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Chemical Formulation, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Chemical Formulation, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Chemical Formulation
- Figure 6: Global Market Value Share and BPS Analysis by Delivery Route, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Delivery Route, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Delivery Route
- Figure 9: Global Market Value Share and BPS Analysis by Clinical Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Clinical Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Clinical Application
- Figure 12: Global Market Value Share and BPS Analysis by Source Synthesis, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Source Synthesis, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Source Synthesis
- Figure 15: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Distribution Channel
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Chemical Formulation, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Chemical Formulation, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Chemical Formulation
- Figure 32: North America Market Value Share and BPS Analysis by Delivery Route, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Delivery Route, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Delivery Route
- Figure 35: North America Market Value Share and BPS Analysis by Clinical Application, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Clinical Application, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Clinical Application
- Figure 38: North America Market Value Share and BPS Analysis by Source Synthesis, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Source Synthesis, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Source Synthesis
- Figure 41: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Distribution Channel
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Chemical Formulation, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Chemical Formulation, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Chemical Formulation
- Figure 48: Latin America Market Value Share and BPS Analysis by Delivery Route, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Delivery Route, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Delivery Route
- Figure 51: Latin America Market Value Share and BPS Analysis by Clinical Application, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Clinical Application, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Clinical Application
- Figure 54: Latin America Market Value Share and BPS Analysis by Source Synthesis, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Source Synthesis, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Source Synthesis
- Figure 57: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Chemical Formulation, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Chemical Formulation, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Chemical Formulation
- Figure 64: Western Europe Market Value Share and BPS Analysis by Delivery Route, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Delivery Route, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Delivery Route
- Figure 67: Western Europe Market Value Share and BPS Analysis by Clinical Application, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Clinical Application, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Clinical Application
- Figure 70: Western Europe Market Value Share and BPS Analysis by Source Synthesis, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Source Synthesis, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Source Synthesis
- Figure 73: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Chemical Formulation, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Chemical Formulation, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Chemical Formulation
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Delivery Route, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Delivery Route, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Delivery Route
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Clinical Application, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Clinical Application, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Clinical Application
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Source Synthesis, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Source Synthesis, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Source Synthesis
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Chemical Formulation, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Chemical Formulation, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Chemical Formulation
- Figure 96: East Asia Market Value Share and BPS Analysis by Delivery Route, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Delivery Route, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Delivery Route
- Figure 99: East Asia Market Value Share and BPS Analysis by Clinical Application, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Clinical Application, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Clinical Application
- Figure 102: East Asia Market Value Share and BPS Analysis by Source Synthesis, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Source Synthesis, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Source Synthesis
- Figure 105: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Chemical Formulation, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Chemical Formulation, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Chemical Formulation
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Delivery Route, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Delivery Route, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Delivery Route
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Clinical Application, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Clinical Application, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Clinical Application
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Source Synthesis, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Source Synthesis, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Source Synthesis
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Chemical Formulation, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Chemical Formulation, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Chemical Formulation
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Delivery Route, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Delivery Route, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Delivery Route
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Clinical Application, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Clinical Application, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Clinical Application
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Source Synthesis, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Source Synthesis, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Source Synthesis
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the progesterone market in 2026, and what is forecast for 2036?
FMI estimates that global progesterone valuation stood at USD 1.8 billion in 2025 and reached USD 1.9 billion in 2026, with demand forecast to hit USD 3.8 billion by 2036.
What is the CAGR for the progesterone market from 2026 to 2036?
The progesterone sector is projected to expand at a 7.2% CAGR over the 2026 to 2036 window, adding USD 1.9 billion in incremental revenue across reproductive and gynecological pharmacy channels.
Which chemical formulation segment leads the progesterone market?
Micronized Natural Progesterone USP holds an estimated 57.2% of chemical formulation demand in 2026 since bioidentical steroid structure avoids androgenic side effects in pregnancy and menopause.
Which delivery route segment leads the progesterone market?
Oral Soft Gelatin Capsules represent an estimated 35.9% of the delivery route category in 2026 driven by simple daily administration across endometrial protection and luteal support.
Which country has a notable growth outlook during the assessment period?
The United States leads national expansion projections at a 7.8% CAGR through 2036, supported by rising birth rates among women aged 30 to 44 and expanding employer fertility benefits.
Who are the key players in the market?
Besins Healthcare, Ferring Pharmaceuticals, Organon & Co. and AbbVie lead branded reproductive and bioidentical progesterone formulations. Pfizer and Bayer plus Sandoz, Teva, Lupin and Viatris supply progestin injectables and generic softgels.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
