
- Market Size (2026)
- USD 14.5 Bn
- Forecast (2036)
- USD 33.2 Bn
- CAGR (2026 to 2036)
- 8.6%
How big is Menopause Treatment Market in 2026?
Accounting for USD 13.4 billion in 2025 and rising to USD 14.5 billion in 2026, the menopause treatment market is projected to expand to USD 33.2 billion by 2036, advancing at a CAGR of 8.6%.
The global menopause treatment market recorded a value of USD 13.4 billion in 2025 and is estimated to reach USD 14.5 billion in 2026, with market valuation projected to reach USD 33.2 billion by 2036 at a CAGR of 8.6%. According to FMI, this 8.6% growth rate outpaces the mature endocrine hormone replacement therapy baseline as newly approved non-hormonal neurokinin blockers bring estrogen-contraindicated women into prescription care. Hormone replacement therapy estrogen, progesterone and tibolone holds 62.4% of therapy class value in 2026 as gynecologists prescribe bioidentical estradiol for vasomotor relief and bone protection. The demand for midlife hormone prescribing is supported by a November 2025 Women's Health Initiative analysis of 27,347 women in JAMA Internal Medicine confirming 41% vasomotor relief in ages 50 to 59 with neutral cardiovascular risk [1]. However, six-month refill drop-offs and liver testing rules restrain persistence, so growth through 2036 depends on telehealth follow-up.
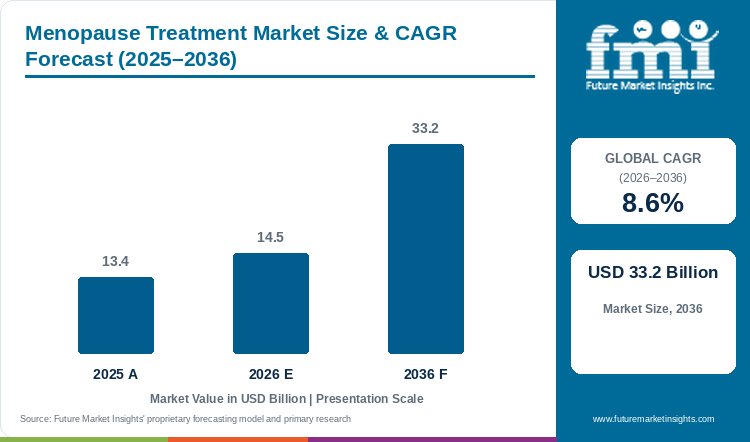
Key Market Trends & Insights
- By therapy class: By therapy class, hormone replacement therapy estrogen, progesterone and tibolone is projected to capture 62.4% in 2026, driven by first-line medical society guideline endorsement.
- By route of administration: Within route of administration, oral tablets and micronized capsules is estimated to command 58.8% in 2026, supported by once-daily dosing convenience and broad formulary coverage.
- By target symptom: Based on target symptom, vasomotor hot flashes and night sweats is expected to hold 51.3% in 2026, underpinned by acute sleep disruption and daytime flushing consultations.
- By distribution channel: By distribution channel, retail and digital women's telehealth pharmacies is forecast to generate 63.9% in 2026, enabled by subscription mail-order refills and virtual menopause clinics.
Regional Highlights
- Asia-Pacific and U.S. expansion: Australia paces tracked national markets at a 6.6% CAGR through 2036 under Pharmaceutical Benefits Scheme transdermal listings, while the United States advances at 5.4%.
- European and Japanese progression: The United Kingdom is forecast to grow at a 5.3% CAGR followed by Germany at 5.0%, whereas Japan progresses at a 4.8% annual rate.
Market Size & Forecast
Table 1: Market Size and Forecast for the Menopause Treatment Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 13.4 billion |
| Estimated Market Size in 2026 | USD 14.5 billion |
| Projected Market Size by 2036 | USD 33.2 billion |
| CAGR, 2026 to 2036 | 8.6% |
| Added Value, 2026 to 2036 | USD 18.7 billion |
The expansion in menopause prescription demand varies across health systems, with Australia growing at a 6.6% CAGR under public transdermal subsidies while Japan advances at 4.8%. According to a July 2025 Climacteric cohort study across the USA and Western Europe, 75.0% to 88.0% of women stopped hormone therapy within six months [2], prompting clinics to use digital women's health platforms for dose titration.
Symptomatic Cohort and Prescription-Regimen Sizing
Table 2: Symptomatic Cohort and Prescription-Regimen Sizing for the Menopause Treatment Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 13.4 | 14.5 | 33.2 |
| Symptomatic postmenopausal women in care (million) | 42.0 to 46.5 | 43.5 to 48.2 | 58.0 to 64.5 |
| Active annual treatment regimens (million) | 8.4 to 9.5 | 8.8 to 10.0 | 14.2 to 16.0 |
| Annualized treatment outlay per active patient (USD) | 84.0 to 95.0 | 84.4 to 95.9 | 90.9 to 102.5 |
Operational note: Cohort ranges reflect symptomatic perimenopausal and postmenopausal women aged 45 to 64 seeking prescription hormone, non-hormonal neurokinin, or standardized botanical therapy across tracked health systems.
Higher demand for safe hot-flash relief among breast cancer survivors and women with blood-clot risks is driving adoption of non-estrogen oral therapies. For instance, a March 2025 pooled analysis of 1,022 women in Current Medical Research and Opinion showed fezolinetant 45 mg cut daily moderate-to-severe vasomotor episodes by 2.55 versus placebo at Week 12 [3].
Per Capita & Gynecology Clinic Sizing
Table 3: Per Capita and Gynecology Clinic Allocation Indicators for the Menopause Treatment Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World female population aged 45 to 64 (billion) | 0.94 | 0.96 | 1.12 |
| Market value per 1,000 women aged 45 to 64 (USD) | 14,255.3 | 15,104.2 | 29,642.9 |
| Annual valuation per menopause clinic (USD) | 14,200 to 16,800 | 14,900 to 17,600 | 23,500 to 27,800 |
| Retail & telehealth pharmacy share (%) | 62.5% to 64.0% | 63.2% to 64.6% | 67.5% to 70.0% |
Table 4: Gynecology Clinic & Channel Allocation Indicators for the Menopause Treatment Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 14.5 billion | 2026 global market valuation baseline |
| OB/GYN & menopause clinics globally | 52,000 | Global outpatient gynecology & midlife clinic registry |
| Market value per clinic | USD 16,225 | Annualized prescribed and OTC menopause valuation |
| Retail & digital telehealth allocation, 2026 | USD 9.3 billion | 63.9% distribution channel segment allocation |
Wider awareness of midlife urogenital and skin changes is encouraging women to combine prescription vasomotor therapy with targeted supportive care. Retail pharmacies are therefore pairing prescription estradiol patches with menopausal skin care formulations and women's health supplements to increase recurring monthly basket orders.
Analyst Perspective
"Bioidentical 17-beta estradiol and micronized progesterone remain the clinical foundation while neurokinin antagonists open hormone-contraindicated patient cohorts. Brands integrating telehealth prescribing with localized vaginal and transdermal delivery will lead growth through 2036."
- Anurag Sharma, Principal Consultant, Future Market Insights.
How is the menopause treatment market segmented?
The menopause treatment market is segmented by four primary commercial axes and region: therapy class, route of administration, target symptom, and distribution channel. In 2026, hormone replacement therapy estrogen, progesterone and tibolone is projected at 62.4%, oral tablets and micronized capsules at 58.8%, vasomotor hot flashes and night sweats at 51.3%, and retail and digital women's telehealth pharmacies at 63.9%.
By therapy class: hormone replacement therapy estrogen, progesterone & tibolone, non-hormonal NK3 receptor antagonists fezolinetant, SSRIs & gabapentinoids, and phytoestrogen & standardized black cohosh/soy isoflavone OTC.
By route of administration: oral tablets & micronized capsules, transdermal estradiol patches, gels & sprays, and vaginal rings, creams & low-dose inserts.
By target symptom: vasomotor hot flashes & night sweats, vulvovaginal atrophy / genitourinary syndrome, and postmenopausal osteoporosis prevention.
By distribution channel: retail & digital women's telehealth pharmacies and hospital & OB/GYN clinic pharmacies.
Why does hormone replacement therapy account for a notable share of demand?
Hormone replacement therapy estrogen, progesterone and tibolone is projected to hold 62.4% share in 2026, supported by consensus guidelines.
Table 5: Therapy Class Share for the Menopause Treatment Market (percentage share), 2026
| Therapy Class | Share (2026) |
|---|---|
| Hormone Replacement Therapy Estrogen, Progesterone & Tibolone | 62.4% |
| Other Segments Combined | 37.6%* |
| Total | 100.0% |
*Note: Remaining therapy class categories sum to 100.0% of 2026 menopause treatment market value.
Table 6: Therapy Class Leadership and Market Growth for the Menopause Treatment Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 8.6% |
| Leading Segment | Hormone Replacement Therapy Estrogen, Progesterone & Tibolone |
In the FMI report, estrogen and progestogen replacement remains the foundational pharmacotherapy by simultaneously resolving vasomotor flushing and urogenital atrophy and bone loss [4]. Consumer health brands also formulate standardized menopause active ingredients and standardized soy isoflavone extracts for mild perimenopausal symptom relief.
- By therapy class, hormone replacement therapy estrogen, progesterone and tibolone is estimated to hold 62.4% in 2026, underpinned by initiation within 10 years of menopause onset [5] [4].
- In March 2025, a 90-day randomized double-blind trial of 96 postmenopausal women in the European Journal of Nutrition showed that combined black cohosh and soy isoflavones with flaxseed lignans reduced total Menopause Rating Scale scores by 48.0% [6].
What supports oral tablets as a preferred choice in administration route?
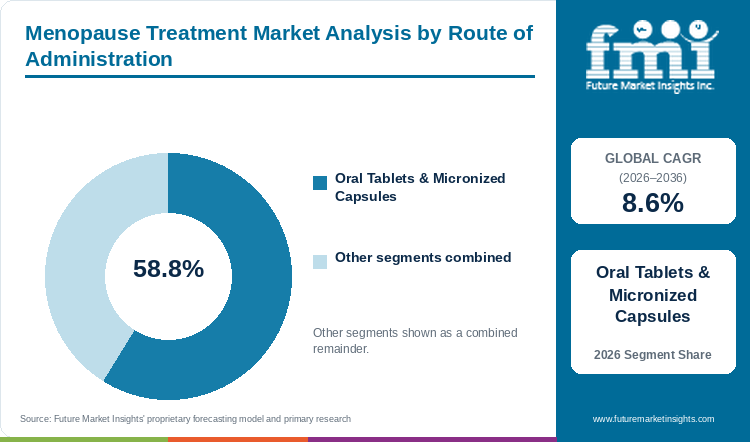
By route of administration, oral tablets and micronized capsules is estimated to hold 58.8% in 2026, owing to daily dosing.
Once-daily oral tablets and soft micronized progesterone capsules capture the largest share of administration value through straightforward adherence and commercial scaling of oral fezolinetant and elinzanetant [7] [8]. For localized urogenital care without systemic hormone elevation, gynecologists prescribe intravaginal hormone inserts and low-dose estradiol rings and creams.
- In 2026, oral tablets and micronized capsules is expected to lead route of administration with 58.8% share, reinforced by convenient dosing across hormonal and neurokinin classes.
- In July 2025, a systematic review and meta-analysis of 118,659 breast cancer survivors in Revista Brasileira de Ginecologia e Obstetricia confirmed that localized vaginal estrogen therapy did not increase breast cancer recurrence (RR 0.87) and correlated with lower all-cause mortality (RR 0.80) [9].
How is vasomotor symptom care gaining use across target symptom applications?
By target symptom, vasomotor hot flashes and night sweats is forecast to represent 51.3% in 2026, driven by sleep disruption.
Moderate-to-severe vasomotor symptoms affect up to 80% of menopausal women and trigger initial medical consultations and prescription onboarding. When patients present with concurrent dyspareunia or bone loss, clinicians add vulvovaginal inflammatory treatments and postmenopausal osteoporosis medications to long-term care plans.
- Vasomotor hot flashes and night sweats is likely to capture 51.3% share in 2026, attributable to rapid reductions in daily flushing frequency anchoring patient willingness to pay.
- In October 2025, Astellas Pharma presented real-world Phase IV OPTION-VMS data across 998 U.S. women showing that Veozah (fezolinetant) improved vasomotor bother, actigraphy sleep wakefulness, and workplace productivity by Week 4 through Week 12 [10].
Why are buyers selecting telehealth pharmacies for products within distribution channel?
Retail and digital women's telehealth pharmacies is likely to capture 63.9% share in 2026, enabled by virtual clinic refills.
Community retail chains and specialized women's telehealth platforms lead menopause prescription fulfillment as chronic hormone patches and non-prescription menopause supplements rely on recurring 90-day home refills. Virtual menopause clinics connect underserved regional patients with certified menopause practitioners who prescribe bioidentical estradiol and non-hormonal neurokinin blockers.
- The distribution channel category is forecast to be led by retail and digital women's telehealth pharmacies at 63.9% share in 2026, linked to discrete home shipping and automated refill adherence.
- An October 2025 meta-analysis of 47 randomized controlled trials across 2,657 postmenopausal women in Menopause confirmed that standardized soy isoflavones dispensed across retail channels reduced vaginal dryness (SMD -1.147) and improved vaginal maturation values [11].
Which market conditions keep non-hormonal antagonists relevant within therapy class?
Within therapy class, non-hormonal NK3 receptor antagonists is projected to expand through 2036, driven by estrogen-contraindicated patient demand.
Selective neurokinin 3 and dual NK1/NK3 receptor antagonists modulate kisspeptin-neurokinin B-dynorphin neurons in the hypothalamic thermoregulatory center without stimulating breast or endometrial estrogen receptors. Oncology survivorship clinics and gynecologists prescribe oral fezolinetant and elinzanetant for women with prior breast malignancy or thromboembolism history.
- Non-hormonal neurokinin antagonists expand prescription capture among symptomatic women who previously relied on unstandardized over-the-counter botanicals.
- In July 2025, a clinical review in Annals of Medicine and Surgery detailed how FDA-approved Veozah (fezolinetant) across the SKYLIGHT clinical trials provides a targeted non-hormonal option for moderate-to-severe vasomotor symptoms [7].
What are the drivers, restraints, and opportunities in the menopause treatment market?
In the menopause treatment market, the key driver is non-hormonal NK3 and transdermal MHT adoption, the key restraint is high six-month discontinuation, and the key opportunity is non-estrogen urogenital therapy.
- Driver: Regulatory approvals of fezolinetant and elinzanetant and updated transdermal MHT safety evidence expand treated patient pools.
- Restraint: Patient anxiety over venous thromboembolism and hepatic transaminase monitoring requirements drive 75% to 88% six-month discontinuation.
- Opportunity: Selective non-estrogen vaginal therapies for genitourinary syndrome and integrated postmenopausal musculoskeletal clinics open undertreated cohorts.
Growth Analysis and Demand Catalysts
Updated medical society guidelines and new non-hormonal tablet launches are major factors driving prescription demand in the menopause market. According to the April 2025 International Menopause Society World Congress consensus in Climacteric, hormone replacement therapy remains the most effective treatment for hot flashes and bone loss while non-hormonal NK3 blockers provide a proven option for women who cannot take estrogen [4]. FMI research indicates that clear clinical guidance reduces doctor hesitation and brings more midlife women into treatment. Manufacturers are also updating vaginal estrogen labels to support long-term maintenance use. For instance, in April 2025, Pfizer updated Premarin Vaginal Cream prescribing rules to validate twice-weekly 0.5-gram dosing that reduced painful intercourse scores by 1.55 versus 0.62 on placebo [12].
Risk Assessment and Operational Restraints
Patient concerns over blood-clot risks and mandatory liver blood tests for non-hormonal pills are key restraining factors hindering long-term treatment adoption. According to the July 2026 multi-country WARMER survey of 1,465 postmenopausal women in The Patient, five-year blood-clot risk was the single largest factor (26.4% to 28.4% importance) influencing whether women start therapy [13]. Fear of side effects causes many patients to stop filling oral hormone prescriptions when irregular bleeding or breast tenderness occurs. In addition to this, a May 2025 Harvard Medical School review in the International Journal of Molecular Sciences noted that starting oral estrogen more than 10 years after menopause raises vascular risk compared with skin patches, which limits oral tablet prescribing in older women [5].
Commercial Opportunity and Format Differentiation
Higher demand for non-estrogen vaginal treatments and midlife bone protection is creating new growth avenues for drugmakers serving breast cancer survivors and aging women. For instance, in March 2026, a randomized trial of 115 postmenopausal women in the European Journal of Cancer showed that once-weekly 20 mg vaginal tamoxifen helped 68.6% of estrogen-contraindicated women relieve vaginal atrophy symptoms at three months versus 9.1% on placebo [14]. Non-estrogen vaginal inserts allow oncology clinics to treat chronic urogenital symptoms safely. Besides this, wider screening for age-related bone and muscle loss is supporting long-term therapy demand. In September 2026, an American Society for Bone and Mineral Research report in the Journal of Bone and Mineral Research supported combined osteoporosis and menopause care [15].
Menopause Treatment Market by Country (2026 to 2036)
As per FMI, national menopause treatment demand diverges between rapid Pharmaceutical Benefits Scheme transdermal expansion in Australia and emerging non-hormonal neurokinin adoption in Japan. Public subsidy updates for body-identical estradiol, regulatory clearances of fezolinetant and elinzanetant, and telehealth clinic reach govern country growth rates through 2036.
Table 7: Country CAGR and Primary Growth Levers for the Menopause Treatment Market (CAGR percentage and operational drivers), 2026 to 2036
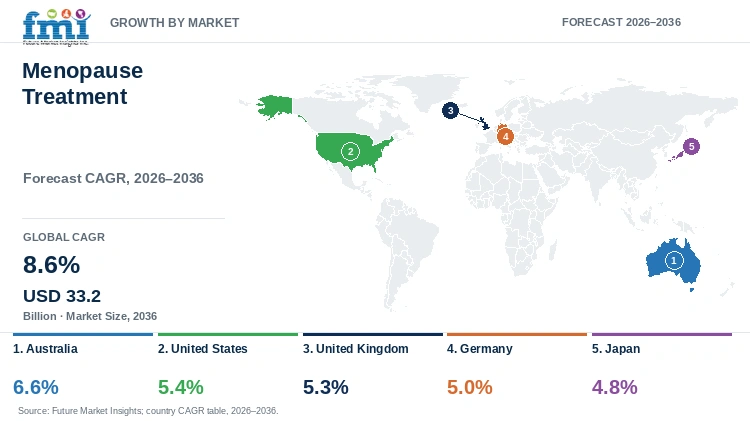
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Australia | 6.6% | PBS transdermal MHT dispensing growth (+5.89%/yr) and closing the 77.5% untreated VMS gap |
| United States | 5.4% | FDA approvals of Veozah and Lynkuet and employer-sponsored telehealth menopause benefits |
| United Kingdom | 5.3% | NHS Hormone Replacement Therapy Prescription Prepayment Certificates and specialist menopause clinics |
| Germany | 5.0% | High gynecologist HRT prescribing share (92.6% of treated women) and S3 guideline adherence |
| Japan | 4.8% | Positive Phase 3 STARLIGHT 2 fezolinetant results and Kampo / transdermal estradiol integration |
Source: Future Market Insights analysis
Australia Menopause Treatment Market Outlook (2026 to 2036)
Federal parliamentary menopause inquiries, updated Pharmaceutical Benefits Scheme subsidies, and general practitioner clinical training are closing longstanding treatment gaps across Australia. A December 2025 Australian Midlife Years Study of 8,086 women aged 40 to 69 in Climacteric revealed that while 10.8% of postmenopausal women used MHT overall, only 22.5% of symptomatic women with vasomotor symptoms received MHT, leaving 77.5% untreated [16]. By 2036, Australia is projected to grow at 6.6% CAGR, driven by PBS subsidy expansion for body-identical hormones. An April 2026 Australian PBS dispensing analysis in the Australian and New Zealand Journal of Obstetrics and Gynaecology documented 5.89% annual growth in transdermal MHT and 10.22% annual growth in intrauterine MHT among women aged 45 to 64 [17].
Key takeaway: In Australia, rapid PBS transdermal and intrauterine MHT growth and clinical outreach to the 77.5% untreated symptomatic cohort drive a 6.6% CAGR.
United States Menopause Treatment Market Outlook (2026 to 2036)
Broad commercial insurance coverage and expanding virtual menopause clinics make the United States the largest national market for prescription midlife care. The demand for non-hormonal prescriptions is supported by U.S. FDA approval of Astellas Pharma's Veozah [7] and Bayer's October 2025 FDA clearance of dual NK1/NK3 blocker Lynkuet across 1,420 women in the Phase 3 OASIS trials for moderate-to-severe hot flashes [8]. United States's menopause treatment outlook is anticipated to advance at 5.4% CAGR over the assessment period, underpinned by non-hormonal NK3 and telehealth onboarding. Payer prior-authorization step edits still require generic transdermal or oral trials first, so manufacturers fund copay assistance cards and workplace productivity registries [10].
Key takeaway: In the United States, commercial scaling of Veozah and Lynkuet and digital telehealth fulfillment drives a 5.4% CAGR through 2036.
United Kingdom Menopause Treatment Market Outlook (2026 to 2036)
Intermittent pharmacy stockouts of transdermal estradiol gels and sprays have challenged National Health Service prescribing across the United Kingdom following workplace menopause awareness campaigns. In the July 2025 multi-country Climacteric cohort study of 214,374 UK women experiencing natural menopause, hormone therapy accounted for 41.1% of treated patients while non-hormonal prescriptions represented 50.8% [2]. Menopause treatment demand in the United Kingdom is forecast to rise at 5.3% CAGR over the forecast period, supported by NHS HRT Prescription Prepayment Certificates. Strict NICE cost-effectiveness rules still limit first-line branded neurokinin prescribing across public NHS clinics, which prompts Astellas and Bayer to focus commercial outreach on private women's health clinics and breast cancer survivors who cannot use estrogen.
Key takeaway: In the United Kingdom, NHS HRT prepayment certificates and expanding transdermal estradiol supply sustain a 5.3% compound annual growth rate.
Germany Menopause Treatment Market Outlook (2026 to 2036)
Strong office-based gynecologist prescribing and widespread pharmacy counter access to standardized herbal remedies support steady demand for menopause treatments across Germany. According to the July 2025 Climacteric cohort study of 124,542 German menopausal women, hormone therapy accounted for 92.6% of treated patients, although six-month treatment drop-out reached 82.0% [2]. High early drop-out rates are encouraging German gynecologists to switch patients from oral pills to better-tolerated skin gels. Adoption of menopause treatments in Germany is estimated to expand at 5.0% CAGR through 2036, reinforced by S3 guideline transdermal estradiol conversion. Statutory health insurance reference pricing penalizes undifferentiated oral hormones, compelling manufacturers to supply metered-dose transdermal estradiol gels and micronized progesterone capsules and dual NK1/NK3 tablets.
Key takeaway: In Germany, strong office-based gynecologist hormone prescribing and transdermal estradiol conversion support a 5.0% CAGR through 2036.
Japan Menopause Treatment Market Outlook (2026 to 2036)
Cultural preference for traditional Kampo herbal formulations and clinical caution regarding breast and thrombotic safety have historically kept systemic hormone replacement uptake near 2% in Japan. In May 2026, Japanese Phase II STARLIGHT patient-reported outcome data across 36 centers in Climacteric showed rapid improvements in sleep disturbance and menopause-specific quality of life with fezolinetant[18]. The Japan menopause treatment sector is projected to record 4.8% CAGR during the assessment period, owing to non-hormonal NK3 receptor antagonist onboarding. Astellas Pharma announced positive topline Phase 3 STARLIGHT 2 results in 410 Japanese women in February 2026 meeting the Week 8 primary endpoint for both 30 mg and 45 mg doses [19].
Key takeaway: In Japan, positive Phase 3 STARLIGHT 2 fezolinetant results open non-hormonal prescription adoption and support a 4.8% annual growth rate.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the menopause treatment market?
Astellas Pharma Inc., Bayer AG, Pfizer Inc., Theramex HQ UK Ltd., Novo Nordisk A/S, and Noven Pharmaceuticals Inc. are the notable companies in the menopause treatment market.
As per the analysis from FMI, the menopause treatment market is moderately concentrated in patented non-hormonal neurokinin antagonists while fragmenting across generic oral and transdermal hormone suppliers. Major manufacturers compete through Phase 3 vasomotor sleep outcomes, low-irritancy transdermal matrix engineering, and direct telehealth pharmacy fulfillment partnerships.
- Non-Hormonal Neurokinin Antagonist Innovators: Astellas Pharma Inc. and Bayer AG lead first-in-class NK3 (Veozah) and dual NK1/NK3 (Lynkuet) oral non-hormonal vasomotor therapy across global formularies.
- Global Endocrine and Vaginal Estrogen Leaders: Pfizer Inc. and Novo Nordisk A/S supply foundational conjugated estrogens, estradiol tablets, and vaginal hormone delivery systems across hospital and retail pharmacies.
- Dedicated Women's Health & Transdermal Specialists: Theramex HQ UK Ltd. and Noven Pharmaceuticals Inc. focus on body-identical micronized progesterone and transdermal estradiol delivery systems and low-dose paroxetine.
Competitive Benchmarking Menopause Treatment Market
Table 8: Competitive Benchmarking for the Menopause Treatment Market (qualitative capability ratings), 2026
| Company | Hormonal / Non-Hormonal Breadth | Transdermal & Vaginal Depth | Telehealth / Retail Access | Geographic Reach |
|---|---|---|---|---|
| Astellas Pharma Inc. | Medium | Low | High | High |
| Bayer AG | High | Medium | High | High |
| Pfizer Inc. | High | High | High | High |
| Theramex HQ UK Ltd. | High | High | High | Medium |
| Novo Nordisk A/S | Medium | High | High | High |
| Noven Pharmaceuticals Inc. | Medium | High | High | Medium |
Evaluation basis: Capability tiers evaluate commercialized portfolio breadth across systemic hormone therapy and non-hormonal NK3 antagonists and transdermal and vaginal delivery engineering.
Key Developments in the Menopause Treatment Market
- In February 2026, Astellas Pharma Inc. announced positive topline Phase 3 STARLIGHT 2 clinical trial results for once-daily fezolinetant (30 mg and 45 mg) in 410 Japanese women with moderate-to-severe vasomotor symptoms, building on approvals across 45 countries [19].
- In February 2026, Novo Nordisk A/S reported in its 2025 Annual Report that annual net receipts increased 10% at constant exchange rates while expanding global active pharmaceutical ingredient and fill-finish manufacturing capacity [20].
- In October 2025, Bayer AG won U.S. FDA marketing clearance for Lynkuet (elinzanetant), the first dual neurokinin 1 and 3 (NK1 and NK3) receptor antagonist for moderate-to-severe hot flashes based on the Phase 3 OASIS clinical program [8].
- In September 2025, Theramex HQ UK Ltd. launched the Menopausa HUB specialist gynecologist training program and Sisthers digital patient platform, supporting more than 6 million women across 57 countries [21].
Key Players in the Menopause Treatment Market
Non-Hormonal Neurokinin & Endocrine Leaders
- Astellas Pharma Inc.
- Bayer AG
Multinational Hormone Replacement Platforms
- Pfizer Inc.
- Novo Nordisk A/S
Dedicated Women's Health & Transdermal Specialists
- Theramex HQ UK Ltd.
- Noven Pharmaceuticals Inc.
Menopause Treatment Market Report Scope
Table 9: Report Scope for the Menopause Treatment Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Therapy Class, Route of Administration, Target Symptom, Distribution Channel |
| Quantitative Units | USD Billion |
| Market Definition | Includes prescription systemic and local hormone replacement therapies (estrogens, progestogens, combinations, tibolone, DHEA, ospemifene), non-hormonal neurokinin antagonists (fezolinetant, elinzanetant) and low-dose SSRI/gabapentinoid VMS therapies, and standardized over-the-counter phytoestrogen (black cohosh, soy isoflavone) menopause preparations. Category Scope Note Excludes general cosmetic anti-aging creams, non-specific calcium/vitamin D supplements, and surgical gynecology devices. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa |
| Countries Covered | Australia, United States, United Kingdom, Germany, Japan, and additional national markets in the full report |
| Key Companies Covered | Astellas Pharma Inc., Bayer AG, Pfizer Inc., Theramex HQ UK Ltd., Novo Nordisk A/S, Noven Pharmaceuticals Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. Segment shares and forecast estimates are FMI proprietary analytical estimates. |
Menopause Treatment Market Research Methodology
Table 10: Research Methodology for the Menopause Treatment Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with manufacturers, suppliers, distributors, reproductive endocrinologists, gynecologists, and telehealth pharmacy managers across the value chain to validate market trends, therapy persistence protocols, demand dynamics, and purchasing decisions. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements reviewed for relevance and consistency with the defined market scope. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 forecast period were developed using top-down and bottom-up approaches to assess symptomatic patient volume, six-month persistence rates, and telehealth adoption trends. |
| Data Validation | Data is validated against macro-economic indicators, menopausal demographic cohorts, regulatory reimbursement frameworks, and historical trend analysis to ensure accuracy without double counting off-label antidepressant volume. |
Menopause Treatment Market by Segments
Menopause Treatment Market segmented by Therapy Class:
- Hormone Replacement Therapy Estrogen, Progesterone & Tibolone
- Non-Hormonal NK3 Receptor Antagonists Fezolinetant, SSRIs & Gabapentinoids
- Phytoestrogen & Standardized Black Cohosh/Soy Isoflavone OTC
Menopause Treatment Market segmented by Route of Administration:
- Oral Tablets & Micronized Capsules
- Transdermal Estradiol Patches, Gels & Sprays
- Vaginal Rings, Creams & Low-Dose Inserts
Menopause Treatment Market segmented by Target Symptom:
- Vasomotor Hot Flashes & Night Sweats
- Vulvovaginal Atrophy / Genitourinary Syndrome
- Postmenopausal Osteoporosis Prevention
Menopause Treatment Market segmented by Distribution Channel:
- Retail & Digital Women's Telehealth Pharmacies
- Hospital & OB/GYN Clinic Pharmacies
Menopause Treatment Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Rossouw, J. E., Aragaki, A. K., Manson, J. A. E., Szmuilowicz, E. D., Harrington, L. B., Johnson, K. C., et al. (2025, November 1). Menopausal Hormone Therapy and Cardiovascular Diseases in Women With Vasomotor Symptoms: A Secondary Analysis of the Women's Health Initiative Randomized Clinical Trials. JAMA Internal Medicine, 185(11), 1330-1339 (PubMed PMID 40952729).
- [2] Saadedine, M., Banks, V., Dinkel-Keuthage, C., Caetano, C., Argyriou, G., Moeller, C., et al. (2025, July 30). Treatments in women experiencing natural menopause: a cohort study from the USA, the UK and Germany. Climacteric, 29(1), 121-128 (PubMed PMID 40735862).
- [3] Santoro, N., Neal-Perry, G., Stute, P., Blogg, M., Mancuso, S., Morga, A., Ottery, F. D., & Siddiqui, E. (2025, March 5). Fezolinetant effect on vasomotor symptoms due to menopause in women unsuitable for hormone therapy. Current Medical Research and Opinion, 41(2), 375-384 (PubMed PMID 40044127).
- [4] Simon, J. A., Davis, S. R., Lindén Hirschberg, A., Kiesel, L., de Melo Pompei, L., Reginster, J.-Y., Simoncini, T., & Hillard, T. (2025, April 1). State of the art in menopause: current best practice approaches from the IMS World Congress 2024, Melbourne. Climacteric, 28(2), 98-103 (PubMed PMID 39928407).
- [5] Xia, W., & Khalil, R. A. (2025, May 24). Hormone Replacement Therapy and Cardiovascular Health in Postmenopausal Women. International Journal of Molecular Sciences, 26(11), 5078 (PubMed PMID 40507889).
- [6] Pokushalov, E., Ponomarenko, A., Garcia, C., Kasimova, L., Pak, I., Shrainer, E., et al. (2025, March 25). Assessing the combined effects of Black Cohosh, Soy Isoflavones, and SDG Lignans on menopausal symptoms: a randomized, double-blind, placebo-controlled clinical trial. European Journal of Nutrition, 64(3), 138 (PubMed PMID 40131516).
- [7] Elendu, C., Okahia, T. W., Blewusi, G. S., Meduoye, O. O. M., Ogelle, E. C., Egbo, A. R., et al. (2025, July 30). FDA approves Veozah (Fezolinetant) for menopausal symptoms: a new nonhormonal option. Annals of Medicine and Surgery (London), 87(9), 5373-5377 (PubMed PMID 40901162).
- [8] Bayer AG. (2025, October 24). U.S. approval of a new hormone-free treatment option for moderate to severe vasomotor symptoms due to menopause. Bayer Global Newsroom.
- [9] Santos, G. M. L., Magalhães, A. O., Teichmann, P. D. V., & Wender, M. C. O. (2025, July 15). Vaginal estrogen therapy for treatment of menopausal genitourinary syndrome among breast cancer survivors: a systematic review and meta-analysis. Revista Brasileira de Ginecologia e Obstetricia, 47, e-rbgo46 (PubMed PMID 40673012).
- [10] Astellas Pharma Inc. (2025, October 22). Astellas Presents Preliminary Real-World VEOZAH (fezolinetant) Data From OPTION-VMS Phase IV Observational Study. Astellas Newsroom.
- [11] Na Takuathung, M., Inpan, R., Yaja, K., Ruansit, W., Teekachunhatean, S., & Koonrungsesomboon, N. (2025, October 21). Isoflavones improve vaginal atrophy, skin health, and sex-related hormones in postmenopausal women: a systematic review and meta-analysis of randomized controlled trials. Menopause (PubMed PMID 41117624).
- [12] Pfizer Inc. (2025, April 15). PREMARIN (conjugated estrogens) Vaginal Cream Full Prescribing Information. Pfizer Labeling.
- [13] Heidenreich, S., Simoncini, T., Cutts, K., Krucien, N., Kim, J., Todorova, L., Walker, J., Kristjansson, C., & Hillard, T. (2026, July 15). Women's Treatment Preferences for Moderate to Severe Vasomotor Symptoms Associated with Menopause: Insights from the WARMER Study. The Patient (Patient-Centered Outcomes Research) (PubMed PMID 42458154).
- [14] Nyback, S., Sundström Poromaa, I., Lindman, H., Lindén Hirschberg, A., Kopp Kallner, H., Wikman, A., & Kunovac Kallak, T. (2026, March 11). Vaginal tamoxifen as a potential treatment option for vaginal atrophy symptoms in postmenopausal women who cannot use estrogen. European Journal of Cancer, 236, 116261 (PubMed PMID 41643515).
- [15] Matthews, M., Cooper, R., Dallas, S. L., Khosla, S., Lengyel, K., Nizar, N., et al. (2026, September 24). Women's musculoskeletal health: insights from the 2024 National Academies of Sciences, Engineering, and Medicine report on chronic conditions. Journal of Bone and Mineral Research, 41(10), 1045-1055 (PubMed PMID 42315116).
- [16] Grant, J., Bond, M., Islam, R. M., & Davis, S. R. (2025, December 15). Prevalence of menopausal hormone therapy usage in symptomatic postmenopausal women in Australia. Climacteric, 29(2), 210-217 (PubMed PMID 41396000).
- [17] Risni, H. W., Wei, L., Hickey, M., Grzeskowiak, L., Ilomäki, J., & Brauer, R. (2026, April 15). Trends in Government-Subsidised Menopausal Hormone Therapy Dispensing in Australia Between 2014 and 2023. Australian and New Zealand Journal of Obstetrics and Gynaecology, 66(2), e70135 (PubMed PMID 42032843).
- [18] Takamatsu, K., Miki, T., Miyazaki, K., Hashimoto, A., Morga, A., & Wang, X. (2026, May 20). Patient-reported outcome data from a randomized phase II study (STARLIGHT) of fezolinetant in women in Japan with vasomotor symptoms associated with menopause. Climacteric, 1-8 (PubMed PMID 42159172).
- [19] Astellas Pharma Inc. (2026, February 3). Phase 3 Trial of Fezolinetant in Japan Shows Topline Results for Treatment of Vasomotor Symptoms (VMS) Associated with Menopause. Astellas Newsroom.
- [20] Novo Nordisk A/S. (2026, February 3). Novo Nordisk Annual Report 2025: Financial Performance. Novo Nordisk Investor Relations.
- [21] Theramex HQ UK Ltd. (2025, September 11). Menopausa: Il Ginecologo Come Primo Alleato Della Donna In Menopausa, Ma Serve Piu Formazione Tra Gli Specialisti. Theramex Newsroom.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the menopause treatment market in 2026 and 2036?
- Which clinical studies support demand for menopause treatments through 2036?
- Why does hormone replacement therapy lead the therapy class in 2026?
- Why do oral tablets lead the route of administration category globally?
- How do growth rates differ across Australia, the USA, and Europe?
- Which notable companies supply hormone replacement and non-hormonal neurokinin therapies?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Therapy Class, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Therapy Class, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Therapy Class, 2026 to 2036
- Hormone Replacement Therapy Estrogen, Progesterone & Tibolone
- Non-Hormonal NK3 Receptor Antagonists Fezolinetant, SSRIs & Gabapentinoids
- Phytoestrogen & Standardized Black Cohosh/Soy Isoflavone OTC
- Y-o-Y Growth Trend Analysis By Therapy Class, 2021 to 2025
- Absolute $ Opportunity Analysis By Therapy Class, 2026 to 2036
- Global Market Analysis and Forecast, By Route of Administration, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Route of Administration, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Route of Administration, 2026 to 2036
- Oral Tablets & Micronized Capsules
- Transdermal Estradiol Patches, Gels & Sprays
- Vaginal Rings, Creams & Low-Dose Inserts
- Y-o-Y Growth Trend Analysis By Route of Administration, 2021 to 2025
- Absolute $ Opportunity Analysis By Route of Administration, 2026 to 2036
- Global Market Analysis and Forecast, By Target Symptom, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Target Symptom, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Target Symptom, 2026 to 2036
- Vasomotor Hot Flashes & Night Sweats
- Vulvovaginal Atrophy / Genitourinary Syndrome
- Postmenopausal Osteoporosis Prevention
- Y-o-Y Growth Trend Analysis By Target Symptom, 2021 to 2025
- Absolute $ Opportunity Analysis By Target Symptom, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Retail & Digital Women's Telehealth Pharmacies
- Hospital & OB/GYN Clinic Pharmacies
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Therapy Class
- By Route of Administration
- By Target Symptom
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Astellas Pharma Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Bayer AG
- Pfizer Inc.
- Theramex HQ UK Ltd.
- Novo Nordisk A/S
- Noven Pharmaceuticals Inc.
- Astellas Pharma Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Therapy Class, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Target Symptom, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Therapy Class, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Target Symptom, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Therapy Class, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Target Symptom, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Therapy Class, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Target Symptom, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Therapy Class, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by Target Symptom, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Therapy Class, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by Target Symptom, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Therapy Class, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by Target Symptom, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by Therapy Class, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by Target Symptom, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Therapy Class, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Therapy Class, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Therapy Class
- Figure 6: Global Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Route of Administration
- Figure 9: Global Market Value Share and BPS Analysis by Target Symptom, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Target Symptom, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Target Symptom
- Figure 12: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Distribution Channel
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Therapy Class, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Therapy Class, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Therapy Class
- Figure 29: North America Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Route of Administration
- Figure 32: North America Market Value Share and BPS Analysis by Target Symptom, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Target Symptom, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Target Symptom
- Figure 35: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Distribution Channel
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Therapy Class, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Therapy Class, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Therapy Class
- Figure 42: Latin America Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Route of Administration
- Figure 45: Latin America Market Value Share and BPS Analysis by Target Symptom, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Target Symptom, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Target Symptom
- Figure 48: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Therapy Class, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Therapy Class, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Therapy Class
- Figure 55: Western Europe Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Route of Administration
- Figure 58: Western Europe Market Value Share and BPS Analysis by Target Symptom, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by Target Symptom, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by Target Symptom
- Figure 61: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Therapy Class, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Therapy Class, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Therapy Class
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Route of Administration
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by Target Symptom, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by Target Symptom, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by Target Symptom
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Therapy Class, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Therapy Class, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Therapy Class
- Figure 81: East Asia Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Route of Administration
- Figure 84: East Asia Market Value Share and BPS Analysis by Target Symptom, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by Target Symptom, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by Target Symptom
- Figure 87: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Therapy Class, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Therapy Class, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Therapy Class
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Route of Administration
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by Target Symptom, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by Target Symptom, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by Target Symptom
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Therapy Class, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Therapy Class, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Therapy Class
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Route of Administration
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by Target Symptom, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by Target Symptom, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by Target Symptom
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the menopause treatment market in 2026, and what is forecast for 2036?
As noted by FMI, global menopause treatment market value is estimated to reach USD 14.5 billion in 2026 from USD 13.4 billion in 2025 and is anticipated to reach USD 33.2 billion by 2036.
What is the CAGR for the menopause treatment market from 2026 to 2036?
An FMI analyst notes that the market is projected to expand at a 8.6% compound annual growth rate between 2026 and 2036, adding USD 18.7 billion in valuation.
Which therapy class segment leads the menopause treatment market?
Hormone replacement therapy estrogen, progesterone and tibolone is projected to capture 62.4% of therapy class demand in 2026 as bioidentical hormones relieve vasomotor symptoms and protect bone density.
Which route of administration segment leads the menopause treatment market?
Oral tablets and micronized capsules is estimated to secure 58.8% of the route of administration category in 2026 due to daily dosing convenience across micronized hormones and oral NK3 antagonists.
Which country has a notable growth outlook during the assessment period?
Australia is projected to record a 6.6% CAGR through 2036, supported by expanding Pharmaceutical Benefits Scheme transdermal MHT listings and rising treatment capture among symptomatic women.
Who are the notable companies in the market?
Astellas Pharma Inc., Bayer AG, Pfizer Inc., Theramex HQ UK Ltd., Novo Nordisk A/S, and Noven Pharmaceuticals Inc. are the notable companies operating in the market.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
