
- Market Size (2026)
- USD 316.3 Bn
- Forecast (2036)
- USD 628.0 Bn
- CAGR (2026 to 2036)
- 7.1%
How big is Water Treatment System Market in 2026?
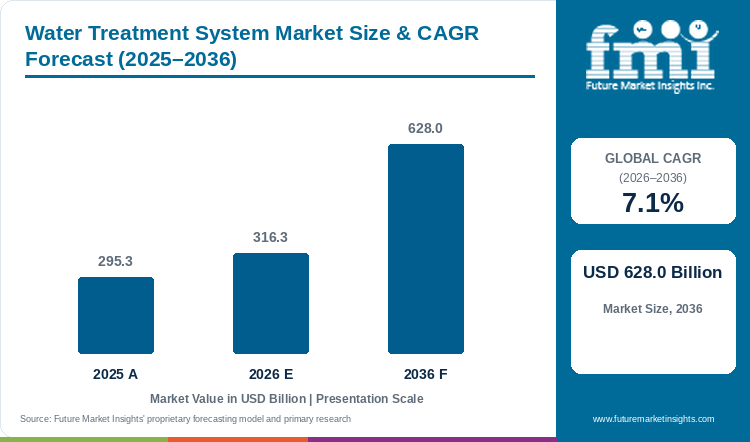
Starting from USD 295.3 billion in 2025, the water treatment system market valuation advanced to USD 316.3 billion in 2026, with projections pointing toward USD 628.0 billion by 2036 at a CAGR of 7.1%.
As per FMI estimates, the global water treatment system market size rose from USD 295.3 billion in 2025 to USD 316.3 billion in 2026 and is forecast to attain USD 628.0 billion by 2036 at a 7.1% annual growth rate. This 7.1% annual expansion across complete municipal and industrial treatment systems is more measured than the 10.2% CAGR recorded for specialized water desalination and purification equipment because full-plant utility contracts include long-lifecycle civil clarification basins and fast-growing membrane skids. Demand is driven by municipal drinking water authorities (40.4% end-user share) and industrial semiconductor and chemical plants adopting Reverse Osmosis Systems (35.2% technology share) to meet strict perfluoroalkyl and wastewater reuse mandates. The growth in membrane system adoption is supported by new chlorine-tolerant membrane designs that reduce premature module replacement costs. According to a January 2026 Water Research study, surface-engineered polyamide reverse osmosis membranes achieved 6.01 L/m2/h/bar water flow and 98.50% salt rejection even after heavy chlorine exposure[1]. However, high desalination pump electricity consumption and membrane biofouling costs remain major restraining factors for municipal utility budgets. Even so, system sales continue to scale where utilities and industrial plants sign multi-year service agreements that guarantee treated water quality and lower kilowatt-hour operating costs.
Key Market Trends & Insights
- By technology: Reverse osmosis systems capture 35.2% in 2026 through high dissolved-solids rejection across desalination and industrial reuse skids.
- By end user: Municipal water authorities command 40.4% in 2026 while public utilities replace aging drinking water filtration basins.
- By installation: Point-of-entry systems account for 56.4% in 2026 since main intake skids protect entire plant distribution loops.
- By equipment class: Membrane modules and skids hold 41.8% in 2026 under recurring spiral-wound element replacement cycles.
- By contract structure: Multi-year frame and service-level agreements secure 54.5% in 2026 via bundled chemical and membrane maintenance.
Regional Highlights
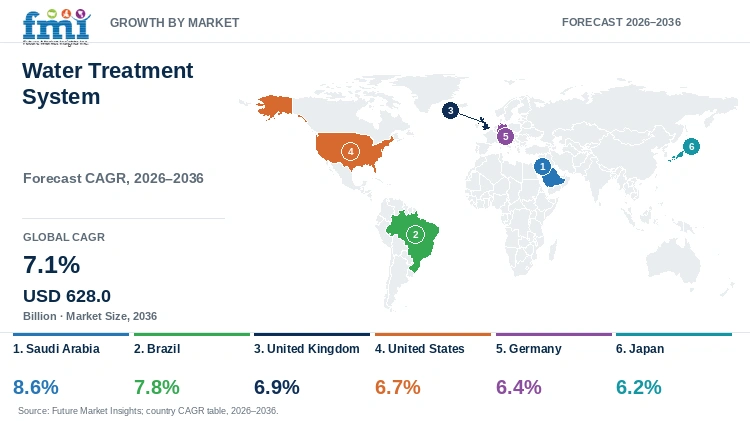
- Top national expansion: Saudi Arabia leads national expansion at an 8.6% CAGR through 2036 under giga-project seawater desalination tenders.
- Broader country progression: Brazil advances at a 7.8% CAGR ahead of the United Kingdom at 6.9% and the United States at 6.7% through 2036.
Market Size & Forecast
Table 1: Market Size and Forecast for the Water Treatment System Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 295.3 billion |
| Estimated Market Size in 2026 | USD 316.3 billion |
| Projected Market Size by 2036 | USD 628.0 billion |
| CAGR, 2026 to 2036 | 7.1% |
| Added Value, 2026 to 2036 | USD 311.7 billion |
Municipal water utilities and industrial facility operators are shifting capital spending from standalone filtration tanks toward modular membrane skids covered by multi-year maintenance contracts. According to a July 2025 Membranes industry review, desalination and water reuse plants retire more than 2 million reverse osmosis membrane modules each year, while recycling spent modules into secondary filtration units cuts disposal impact by 27%[2]. Utility procurement directors therefore specify standardized water treatment equipment skids that bundle scheduled cartridge replacement with predictable operating expenses.
Installed Treatment Capacity and Module Sizing
Table 2: Installed Treatment Capacity and Module Sizing for the Water Treatment System Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 295.3 | 316.3 | 628.0 |
| Active RO membrane modules installed (million) | 14.2 to 16.5 | 15.1 to 17.6 | 26.0 to 30.5 |
| End-of-life RO modules generated per year (million) | 2.0 to 2.2 | 2.1 to 2.4 | 3.6 to 4.2 |
| Average municipal membrane flux (L/m2/h) | 18.0 to 24.0 | 19.0 to 25.0 | 24.0 to 32.0 |
Operational note: Capacity and module ranges align municipal desalination and industrial reuse installations against documented membrane element replacement rates.
Rising freshwater withdrawal fees and strict industrial wastewater discharge limits are compelling chemical, food processing, and power plants to recycle process water on site. Plant engineers install automated pretreatment filters ahead of high-pressure reverse osmosis skids to prevent mineral scaling and unplanned production downtime. Industrial buyers increasingly source pre-assembled water desalination equipment packages that cut on-site construction time and guarantee treated water purity.
Utility Capex & Industrial Plant Sizing
Table 3: Utility and Industrial Plant Allocation Indicators for the Water Treatment System Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Market value per capita (USD) | 36.0 | 38.1 | 69.8 |
| Municipal authority segment value (USD billion) | 119.3 | 127.8 | 253.7 |
| Multi-year SLA contract share (%) | 53.8% | 54.5% | 58.2% |
Table 4: Municipal and Industrial Facility Indicators for the Water Treatment System Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 316.3 billion | 2026 global market value baseline |
| Municipal Water Authorities value, 2026 | USD 127.8 billion | 40.4% end-user segment allocation |
| Reverse Osmosis Systems value, 2026 | USD 111.3 billion | 35.2% technology segment allocation |
| Point-of-Entry Systems value, 2026 | USD 178.4 billion | 56.4% installation segment allocation |
Rapid expansion of domestic semiconductor wafer fabs, battery plants, and hyperscale data centers is creating strong commercial demand for ultrapure water polishing loops and brine concentration systems. To minimize liquid waste disposal fees and cut pump electricity bills, turnkey engineering contractors pair modular water treatment trains with isobaric energy-recovery devices across industrial parks.
Analyst Perspective
"Municipal utility directors and industrial plant managers prioritize membrane skids that cut kilowatt-hour consumption per cubic meter and resist chlorine biofouling. Suppliers that bundle direct EPC turnkey delivery with multi-year service-level agreements win long-term municipal desalination and industrial reuse tenders."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the water treatment system market segmented?
The water treatment system market spans technology, end user, installation, equipment class, contract structure, sales channel, and lifecycle stage. In 2026, reverse osmosis systems capture 35.2%, municipal water authorities 40.4%, point-of-entry systems 56.4%, membrane modules and skids 41.8%, and multi-year frame agreements 54.5%.
By technology: Reverse osmosis systems and ultrafiltration and microfiltration join UV and ozone disinfection with ion exchange and conventional clarification.
By end user: Municipal water authorities and industrial process plants join commercial buildings and residential point-of-entry and point-of-use buyers.
By installation: Point-of-entry systems and point-of-use systems cover centralized intake skids and terminal dispensing taps.
By equipment class: Membrane modules and skids join pumps and dosing skids and filtration vessels and media across plant capital budgets.
By contract structure: Multi-year frame and service-level agreements and spot equipment capex govern direct OEM EPC contracts (59.3%) and greenfield installations (55.6%).
Why do reverse osmosis systems account for a notable share of technology demand?
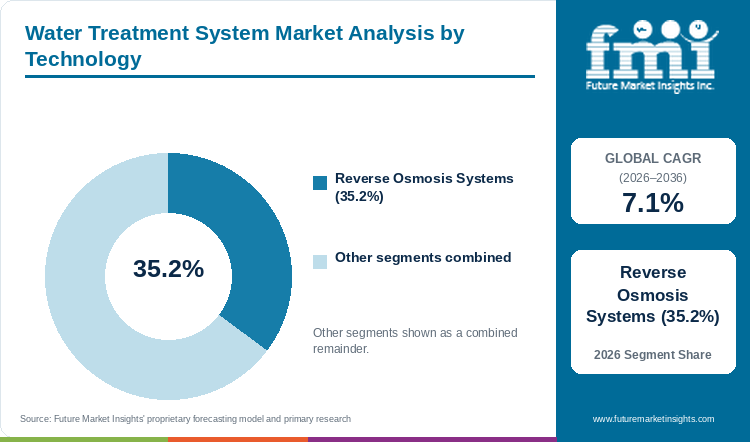
Based on technology, reverse osmosis systems is projected to account for 35.2% in 2026, driven by high monovalent salt rejection.
Table 5: Technology Share for the Water Treatment System Market (percentage share), 2026
| Technology | Share (2026) |
|---|---|
| Reverse Osmosis Systems | 35.2% |
| Other Technologies Combined (UF/MF, UV/Ozone, Ion Exchange, Clarification) | 64.8%* |
| Total | 100.0% |
*Note: Remaining technology categories sum to 100.0% of 2026 system installations.
Table 6: Technology Leadership and Market Growth for the Water Treatment System Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.1% |
| Leading Segment | Reverse Osmosis Systems (35.2% in 2026) |
FMI's segment analysis indicates that Reverse Osmosis Systems lead technology sales because high-pressure membrane skids remove dissolved salts, heavy metals, and trace industrial chemicals within a compact plant footprint. Municipal and industrial buyers pair reverse osmosis units with upstream ultrafiltration membranes to trap suspended silt and extend downstream membrane life.
- Reverse osmosis systems secure 35.2% of 2026 technology demand by delivering 98.5% salt rejection across desalination and ultrapure water lines.
- A July 2025 Membranes study showed 5 kDa UF pretreatment ahead of 32 bar RO achieved 28% recovery below 0.5 mS/cm [3].
What supports municipal water authorities as a preferred buyer in end user demand?
By end user, municipal water authorities is estimated to hold 40.4% in 2026, owing to statutory drinking water purification rules.
Municipal Water Authorities represent the largest customer group as city utilities upgrade aging sand filtration plants to meet binding drinking water quality rules and urban potable reuse targets. Public water districts combine high-efficiency reverse osmosis pumps with energy-recovery turbines to keep municipal electricity bills within approved ratepayer tariffs.
- Municipal water authorities command 40.4% of 2026 end user market value as cities upgrade potable treatment plants and potable reuse basins.
- A January 2026 Journal of Hazardous Materials study showed pressurized PVDF ultrafiltration with ozonation cut fouling resistance 41% versus submerged units [4].
How are point-of-entry systems gaining use across applications in the installation category?
In 2026, point-of-entry systems is expected to lead installation with 56.4% share, supported by centralized utility and factory intake treatment.
Point-of-Entry Systems capture the majority of installation spending because treating raw water at the main plant intake protects entire facility piping networks, boilers, and cooling towers from scale damage. Industrial plant managers pair centralized intake skids with membrane filter press solutions to dewater treatment sludge and lower hauling costs.
- Point-of-entry systems hold 56.4% of 2026 installation demand since main header treatment protects downstream piping and process heat exchangers.
- A January 2026 Environmental Pollution study found pre-ozonation before chlorination raised trihalomethanes from 8.1 to 14.5 ug/L, which favors UV [5].
Why are buyers selecting membrane modules and skids within the equipment class category?
By equipment class, membrane modules and skids is forecast to represent 41.8% in 2026, underpinned by recurring element replacement cycles.
Membrane Modules and Skids generate the largest equipment revenue stream because spiral-wound reverse osmosis and ultrafiltration cartridges require scheduled replacement every three to seven years. Water treatment plants also integrate water treatment ozone generator units ahead of membrane racks to oxidize organic contaminants and maintain steady water throughput.
- Membrane modules and skids account for 41.8% of 2026 equipment class value through combined greenfield skid assembly and recurring element replacement.
- A March 2026 Membranes review of 108 industrial wastewater studies confirmed hybrid membrane-ion exchange trains raise contaminant removal by 15% to 25% [6].
Which market conditions keep multi-year frame agreements relevant within contract structure?
Multi-year frame and service-level agreements are likely to capture 54.5% share in 2026, linked to bundled chemical and membrane maintenance.
Multi-Year Frame and Service-Level Agreements dominate contract structures because utilities and factories prefer shifting membrane cleaning risk and water-quality compliance guarantees to specialized equipment vendors. Turnkey EPC contractors capturing 59.3% of channel sales and greenfield projects holding 55.6% of lifecycle demand bundle automated hydraulic dosing pump skids into these long-term service contracts.
- Multi-year frame agreements capture 54.5% of 2026 contract value since utilities bundle membrane replacement and antiscalants into predictable opex budgets.
- A February 2026 Water Research study found carbon filter aging from 3.5 to 10 years cut cytotoxicity abatement below 10% [7].
What are the drivers, restraints, and opportunities in the water treatment system market?
In the water treatment system market, municipal micropollutant rules and industrial reuse mandates expand membrane skid orders whereas desalination electricity costs restrain capex and 120-bar brine concentration modules create retrofit opportunities.
- Driver: Stricter municipal drinking water regulations and industrial zero-liquid-discharge mandates compel utilities and factories to install multi-stage membrane treatment skids.
- Restraint: High kilowatt-hour electricity demand in seawater desalination and irreversible membrane biofouling inflate operating costs across municipal utilities.
- Opportunity: Chlorine-resistant polyamide membranes and high-pressure minimal-liquid-discharge skids create high-margin retrofit demand across chemical and semiconductor plants.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Tightening municipal drinking water contaminant limits and mandatory industrial wastewater recycling rules are the primary catalysts driving orders for multi-stage water treatment systems. Cities and industrial parks can no longer rely on basic settling tanks when regulations require removal of trace pharmaceuticals and industrial solvents before water reuse. An FMI analyst notes that worsening urban water scarcity is boosting turnkey EPC contract awards and demand for wastewater treatment aerators in biological treatment basins. A January 2026 Journal of Hazardous Materials study showed that activated sludge biological treatment with membrane filtration removed over 80% of micropollutants for agricultural reuse [8]. To avoid discharge penalties and secure reliable process water supplies, municipal authorities and industrial plants are signing multi-year contracts for integrated membrane treatment skids.
Risk Assessment of the Water Treatment System Market: Operational and Fouling Constraints
High desalination electricity consumption and progressive membrane fouling remain the main commercial barriers delaying capital approval for large water treatment projects. Over multi-year operating cycles, mineral scaling and bacterial biofilm growth clog membrane pores and increase the pumping pressure required to push water through filtration modules. For instance, a June 2026 Membranes 11-year operational audit of 120 microfiltration modules at a municipal drinking water plant found that water permeability dropped 86.4% and forced complete module replacement [9]. Municipal finance boards therefore require vendors to complete multi-month pilot testing and provide energy-consumption warranties before awarding greenfield plant contracts. When industrial plants compare high-pressure brine concentrators against basic chemical clarifiers, high industrial electricity rates create strong buyer pushback against energy-intensive desalination trains.
Commercial Opportunity Analysis: High-Recovery Brine Concentration and Catalytic Membranes
Equipment suppliers are unlocking high-margin revenue opportunities by commercializing high-pressure brine concentration skids and durable catalytic membranes for zero-liquid-discharge industrial plants. Standard reverse osmosis systems stop working above 75 grams per liter of dissolved salt, which previously forced chemical and mining companies to install expensive thermal steam evaporators. According to a March 2026 Water Research study, catalytic ceramic ozone membranes accelerated industrial pollutant breakdown 29-fold while resisting chemical wear [10]. Pairing durable ceramic pre-filters with ultra-high-pressure reverse osmosis elements prevents organic fouling and allows factories to concentrate salty wastewater streams at a fraction of thermal evaporation costs. Vendors that bundle 120-bar brine concentration skids with cloud-based pressure sensors and automated chemical dosing contracts are capturing lucrative retrofit orders across chemical, power, and microelectronics plants.
Water Treatment System Market by Country (2026 to 2036)
According to FMI, Saudi Arabia leads national water treatment system growth at an 8.6% CAGR through 2036, while Japan rises 6.2%. Capital equipment awards across Middle Eastern desalination corridors and Latin American sanitation concessions depend on sovereign utility tenders and industrial water reuse mandates.
Table 7: Country CAGR and Primary Growth Levers for the Water Treatment System Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Saudi Arabia | 8.6% | Sovereign seawater reverse osmosis desalination tenders and Vision 2030 industrial water reuse mandates |
| Brazil | 7.8% | Universal sanitation concession tenders under the Legal Sanitation Framework and mining effluent treatment |
| United Kingdom | 6.9% | Ofwat AMP8 utility investment cycle targeting storm-overflow abatement and tertiary phosphorus removal |
| United States | 6.7% | Enforceable EPA drinking water PFAS limits and semiconductor fab ultrapure water treatment loops |
| Germany | 6.4% | Fourth-stage municipal wastewater micropollutant ozonation-ultrafiltration upgrades and closed-loop chemical parks |
| Japan | 6.2% | Semiconductor wafer fab ultrapure water polishing loops and seismic-resilient municipal plant retrofits |
Source: Future Market Insights analysis
Saudi Arabia Water Treatment System Market Outlook (2026 to 2036)
Extreme desert aridity and the absence of permanent rivers make Saudi Arabia the world's most desalination-dependent water market and distinguish it from temperate freshwater utilities. Coastal municipalities and new industrial cities rely on mega-scale seawater reverse osmosis plants to supply household and industrial water. According to December 2025 Saudi Water Authority sector documentation, national desalination upgrades prioritize replacement of legacy thermal plants with low-energy reverse osmosis membrane facilities across the Kingdom [11]. Water treatment system demand in Saudi Arabia is forecast to rise at an 8.6% CAGR through 2036, propelled by Vision 2030 independent water tenders. Because high seawater salinity accelerates membrane biofouling, EPC contractors pair reverse osmosis trains with dissolved-air flotation and ultrafiltration pretreatment skids.
Key takeaway: In Saudi Arabia, giga-project seawater reverse osmosis tenders and Vision 2030 water reuse mandates anchor greenfield EPC turnkey contract awards.
Brazil Water Treatment System Market Outlook (2026 to 2036)
According to a January 2026 Environmental Research study, self-cleaning reinforced filtration membranes reduced organic fouling from 75% to 20% while removing 98.1% of manganese and 97.4% of copper at low operating pressure [12]. That low-pressure filtration performance directly addresses industrial mining wastewater and municipal river clarification needs across Brazil. The Brazil water treatment system sector is projected to record a 7.8% CAGR during the assessment period, driven by private utility auctions under the Legal Sanitation Framework. Concessionaires are purchasing modular ultrafiltration skids to meet statutory targets for universal drinking water coverage by 2033. Because high tariffs inflate imported pump costs, global water OEMs are expanding local skid assembly in Sao Paulo.
Key takeaway: In Brazil, private municipal sanitation concessions and industrial mining effluent rules drive multi-year procurement of modular filtration and desalination skids.
United Kingdom Water Treatment System Market Outlook (2026 to 2036)
Five-year regulatory capital cycles under the Ofwat Asset Management Plan 8 from 2025 to 2030 govern water utility procurement across England and Wales. That statutory investment structure sets the United Kingdom apart from decentralized municipal water markets across continental Europe and North America. Regional water and sewerage companies face binding targets to eliminate storm overflows and strip phosphorus from wastewater outfalls. A February 2026 Science Bulletin study showed self-floating photo-Fenton catalytic membranes sustain continuous hydrogen peroxide generation and organic pollutant degradation in wastewater [13]. In the United Kingdom, demand for water treatment systems is predicted to advance at 6.9% CAGR through 2036, reinforced by UV and membrane retrofits. Civil engineering bottlenecks still delay greenfield builds, so utilities favor containerized membrane skids.
Key takeaway: In the United Kingdom, Ofwat AMP8 utility investment programs and strict nutrient-neutrality discharge rules sustain tertiary membrane and disinfection skid upgrades.
United States Water Treatment System Market Outlook (2026 to 2036)
Per March 2026 U.S. EPA guidance, high-pressure reverse osmosis and anion exchange with granular activated carbon remove regulated drinking water contaminants [14]. Municipal water districts and domestic semiconductor wafer fabs across Arizona, Texas, and Ohio are accelerating capital orders for multi-stage membrane and ion-exchange polishing skids. The United States is estimated to post 6.7% CAGR over the forecast period, underpinned by federal Drinking Water State Revolving Fund allocations. Industrial ultrapure water loop construction across domestic microelectronics and battery plants further expands high-purity skid procurement across regional water basins. Certified operator shortages across smaller water systems still slow complex skid adoption, so municipal utilities sign multi-year OEM remote monitoring agreements.
Key takeaway: In the United States, federal PFAS drinking water compliance deadlines and semiconductor fab construction drive procurement of reverse osmosis and ion-exchange skids.
Germany Water Treatment System Market Outlook (2026 to 2036)
Mandatory fourth-stage micropollutant removal at municipal wastewater plants under the revised European Union Urban Wastewater Directive distinguishes Germany from standard municipal filtration markets. Zero-effluent water recycling loops across integrated chemical complexes along the Rhine and Ruhr rivers further boost industrial orders for high-recovery membrane skids. A May 2026 Membranes study confirmed that multi-layer composite filtration membranes rapidly strip pharmaceutical antibiotic residues from hospital and industrial wastewater streams [15]. Adoption of water treatment systems in Germany is estimated to expand at a 6.4% CAGR through 2036, supported by municipal ozone and ultrafiltration plant upgrades. High industrial electricity tariffs lead factory engineers to install low-energy reverse osmosis skids.
Key takeaway: In Germany, fourth-stage municipal micropollutant filtration mandates and closed-loop chemical park recycling sustain demand for ozone and membrane retrofit skids.
Japan Water Treatment System Market Outlook (2026 to 2036)
Aging municipal water workforces and rapid expansion of domestic logic and memory semiconductor wafer fabs in Kyushu and Hokkaido shape demand across Japan. A November 2025 Scientific Reports study documented carbon footprints of 3.258 kg CO2-eq/m3 for seawater RO and 2.868 kg/m3 for brackish plants [16]. That lifecycle study also recorded 3.083 kg CO2-eq/m3 for municipal and industrial reclaimed water reuse plants across coastal cities. Revenue from water treatment system sales in Japan is projected to rise at 6.2% CAGR over the assessment period, attributable to wafer fab loops. Shrinking rural tax bases still restrict greenfield utility capex, so Kurita Water Industries supplies cloud-monitored ion-exchange and membrane service contracts.
Key takeaway: In Japan, semiconductor fab ultrapure water investments and municipal seismic-resilience retrofits sustain demand for high-selectivity reverse osmosis and ion-exchange systems.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the water treatment system market?
Veolia Environnement S.A. and Xylem Inc. join Ecolab Inc., Pentair plc, Kurita Water Industries Ltd., DuPont de Nemours Inc., and Culligan International Company as notable companies.
In the FMI report, supplier shares in water treatment systems are moderately concentrated across turnkey desalination EPCs and fragmented among regional skid assemblers. Multinational water engineering groups execute turnkey municipal desalination and industrial reuse plants under multi-year operating contracts. Membrane and filtration component specialists supply spiral-wound polyamide elements and digital water quality monitoring skids across international distributor networks.
- Turnkey Water & Utility Engineering Leaders: Veolia Environnement S.A. and Xylem Inc. deliver integrated municipal desalination plants, membrane bioreactors, and digital utility pumping networks.
- Industrial Water & Process Treatment Specialists: Ecolab Inc. and Kurita Water Industries Ltd. supply automated boiler and ultrapure water treatment skids under multi-year service agreements.
- Membrane, Filtration & Point-of-Entry Platforms: DuPont de Nemours Inc. and Pentair plc join Culligan International Company in supplying reverse osmosis membranes, filtration vessels, and commercial point-of-entry systems.
Competitive Benchmarking: Water Treatment System Market
Table 8: Competitive Benchmarking for the Water Treatment System Market (qualitative capability ratings), 2026
| Company | Membrane & Skid Breadth | Turnkey EPC & SLA Depth | Municipal / Industrial Access | Geographic Reach |
|---|---|---|---|---|
| Veolia Environnement S.A. | High | High | High | High |
| Xylem Inc. | High | High | High | High |
| Ecolab Inc. | Medium | High | High | High |
| Pentair plc | High | Medium | High | High |
| Kurita Water Industries Ltd. | High | High | High | Medium |
| DuPont de Nemours Inc. | High | Medium | High | High |
| Culligan International Company | High | Medium | High | High |
Scoring basis: Capability tiers evaluate documented technology breadth across reverse osmosis and ultrafiltration as well as UV/ozone and turnkey EPC execution capacity. Contract service and geographic ratings reflect verified multi-year industrial service agreements and multinational utility installed bases.
Key Developments in the Water Treatment System Market
- In July 2026, Xylem Inc. reported Q2 2026 orders up 42% to USD 3.1 billion and raised 2026 revenue guidance to USD 9.2 billion [17].
- In July 2026, Ecolab Inc. reported Q2 2026 adjusted diluted EPS up 11% to USD 2.09 on strong industrial water and data-center demand [18].
- In April 2026, DuPont de Nemours Inc. expanded its FilmTec Fortilife portfolio with XC220 (83 bar) and XC-Max UHP (120 bar) membranes [19].
Key Players in the Water Treatment System Market
Turnkey Water & Utility Engineering Leaders
- Veolia Environnement S.A.
- Xylem Inc.
Industrial Water & Process Treatment Specialists
- Ecolab Inc.
- Kurita Water Industries Ltd.
Membrane, Filtration & Point-of-Entry Platforms
- Pentair plc and Culligan International Company
- DuPont de Nemours Inc.
Water Treatment System Market - Report Scope
Table 9: Report Scope for the Water Treatment System Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Technology, End User, Installation, Equipment Class, Contract Structure, Sales and Procurement Channel, and Project Lifecycle Stage |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial supplier value from reverse osmosis, ultrafiltration, microfiltration, UV/ozone disinfection, ion exchange, and conventional clarification skids, modules, and multi-year SLA contracts. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa |
| Countries Covered | Saudi Arabia, Brazil, United Kingdom, United States, Germany, Japan, and additional countries in the full report |
| Key Companies Covered | Veolia Environnement S.A., Xylem Inc., Ecolab Inc., Pentair plc, Kurita Water Industries Ltd., DuPont de Nemours Inc., and Culligan International Company |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Water Treatment System Market - Research Methodology
Table 10: Research Methodology for the Water Treatment System Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with manufacturers, EPC contractors, distributors, municipal utility directors, industrial process engineers, and subject-matter experts across the value chain to validate membrane trends, contaminant rules, demand dynamics, and purchasing decisions. |
| Secondary Research | Secondary research included company annual reports, investor presentations, regulatory publications, industry associations, technical papers, trade journals, company websites, product literature, and other publicly available sources relevant to the water treatment system market. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 forecast period were developed using top-down and bottom-up approaches to assess module volume demand, skid price points, and utility adoption trends. |
| Data Triangulation and Validation | Data is validated against macro-economic indicators, municipal desalination and industrial reuse drivers, regulatory limits, and historical trend analysis to maintain accuracy without double counting adjacent categories. |
Water Treatment System Market by Segments
Water Treatment System Market segmented by Technology:
- Reverse Osmosis Systems (35.2%)
- Ultrafiltration and Microfiltration
- UV and Ozone Disinfection
- Ion Exchange, Softening, and Conventional Clarification
Water Treatment System Market segmented by End User:
- Municipal Water Authorities (40.4%)
- Industrial Process Plants
- Commercial Buildings and Residential Point-of-Entry / Point-of-Use
Water Treatment System Market segmented by Installation:
- Point-of-Entry Systems (56.4%)
- Point-of-Use Systems
- Centralized Utility & Industrial Intake Skids
Water Treatment System Market segmented by Equipment Class:
- Membrane Modules and Skids (41.8%)
- Pumps and Dosing Skids
- Filtration Vessels and Media
- Auxiliary Disinfection and Clarifier Hardware
Water Treatment System Market segmented by Contract Structure, Channel & Lifecycle:
- Multi-Year Frame and Service-Level Agreements (54.5%)
- Spot Equipment and Project-Specific Capex
- Direct OEM and EPC Turnkey Contracts (59.3%)
- Authorized Industrial Distributors and System Integrators
- Greenfield Capacity (55.6%) and Brownfield Retrofit / MRO Replacement
Water Treatment System Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Pan, Z., Geng, G., Yu, S., Lu, H., Liu, M., Wu, D., & Gao, C. (2026, January 15). Highly selective and chlorine-resistant polyamide reverse osmosis membranes for advanced water treatment via Fenton-assisted aromatic amine surface engineering. Water Research, 289(Pt A), 124828 (PubMed PMID 41130170).
- [2] Somrani, A., Abohelal, K., & Pontie, M. (2025, July 21). A Mini Review of Reused End-of-Life Reverse Osmosis (EoL RO) Membranes. Membranes, 15(7), 217 (PMCID PMC12300567).
- [3] Ahmed, A. E. G., Jordan, C., Walcher, E., Kuloglija, S., Turetschek, R., Lozar, A., Tomasetig, D., & Harasek, M. (2025, July 12). Membrane Processes for Remediating Water from Sugar Production By-Product Stream. Membranes, 15(7), 207 (PMCID PMC12297894).
- [4] He, H., Wang, K., Wang, X., Huang, X., Wang, X., Zhu, H., et al. (2026, January 1). Pressurized cell-side feeding versus submerged PVDF ultrafiltration reactor for in-situ ozonation: A comparative pilot scale study. Journal of Hazardous Materials, 501, 140975 (PubMed PMID 41468815).
- [5] Elsharkawy, K., & Liu, C. (2026, January 1). Effect of oxidative treatment on the formation of disinfection byproducts from tire wear particles upon water chlorination. Environmental Pollution, 388, 127375 (PubMed PMID 41232661).
- [6] Al Saadi, A. S., Al-Yahmadi, I., Zein, S. H., Rajamohan, N., Al-Busaidi, I. K., Al-Rashdi, N., et al. (2026, March 31). Advanced Membrane Technologies and Hybrid Treatment Systems for Sustainable Removal of Naturally Occurring Radioactive Materials from Industrial Wastewater. Membranes, 16(4), 125 (PubMed PMID 42042984).
- [7] Liu, H., Hu, C., & Liu, C. (2026, February 15). Effect of media age on cytotoxicity of drinking water treated by biological activated carbon filters and chlorine disinfection. Water Research, 290, 125090 (PubMed PMID 41371070).
- [8] Ibrahim, F. G. G., Torre, R. M., Coy, A. M. B., Hernandez, F., & Crespo, I. d. G. (2026, January 1). Performance comparison of microalgae-based and activated sludge with membrane filtration (AS-MBR) for emerging contaminant removal and wastewater reuse. Journal of Hazardous Materials, 501, 140553 (PubMed PMID 41349304).
- [9] Kabsch-Korbutowicz, M., Wolska, M., & Solipiwko-Piescik, A. (2026, June 20). Full-Scale Microfiltration for Drinking Water: A Long-Term Performance Analysis. Membranes, 16(6), 212 (PMCID PMC13304411).
- [10] Zhang, M., Wang, J., Wang, Y., Zhang, W., Guo, Z., Xu, D., Tang, X., Bai, L., & Liang, H. (2026, March 1). Direct electron transfer for catalytic ozonation with Mn3Al2(SiO4)3 ceramic membranes to achieve rapid water purification. Water Research, 291, 125147 (PubMed PMID 41412028).
- [11] Saudi Water Authority. (2025, December 15). A Comprehensive Report on Water Desalination Sector. Saudi Water Authority (SWA).
- [12] Morsy, A., Hatem, N., Ewais, H. A., Mohamed, S., Morsy, A., Fathi, H., Tarek, A., & Nassef, E. (2026, January 1). High-performance self-cleaning cellulose acetate membranes reinforced with nanochitosan for heavy metal removal. Environmental Research, 288(Pt 1), 123197 (PubMed PMID 41167321).
- [13] Cao, J., Zhang, W., Lv, W., Zhu, M., Liang, L., Liang, Z., Liu, Q., Jiang, Y., & Xing, M. (2026, February 15). Electron transfer-mediated enhanced sustained degradation of refractory high ionization potential organic pollutants via a self-floating photo-fenton membrane. Science Bulletin, 71(3), 577 to 586 (PubMed PMID 41530042).
- [14] U.S. Environmental Protection Agency. (2026, March 23). Overview of Drinking Water Treatment Technologies. U.S. Environmental Protection Agency.
- [15] Shi, Z., Sun, X., Ren, J., Xu, W., Guo, Q., Chen, Y., Lin, Z., Tian, Y., & Zhang, J. (2026, May 20). Structural Design of PES-CS-MMT Composite Membrane by Layer-by-Layer Self-Assembly for the Removal of Antibiotic Wastewater. Membranes, 16(5), 180 (PubMed PMID 42188455).
- [16] Zhang, M., Yu, S., Shi, C., Wang, H., & Chang, N. (2025, November 19). Carbon footprint analysis and carbon neutrality potential of desalination by reverse osmosis for different applications basd on life cycle assessment method. Scientific Reports, 15, 40842 (PMCID PMC12630984).
- [17] Xylem Inc. (2026, July 30). Xylem Reports Second Quarter 2026 Results. Xylem Inc.
- [18] Ecolab Inc. (2026, July 28). Ecolab Delivers Accelerated Sales Growth and Double-Digit EPS Growth. Ecolab Media Center.
- [19] DuPont de Nemours, Inc. (2026, April 9). DuPont Expands FilmTec Fortilife Portfolio for Advanced ZLD/MLD and resource recovery applications. DuPont Newsroom.
- [20] Veolia Environnement S.A. (2026, February 26). Full year 2025 results of the Group. Veolia Environnement S.A.
- [21] Pentair plc. (2026, February 3). Pentair Reports Strong Fourth Quarter and Full Year 2025 Results. Pentair Investor Relations.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the water treatment system market in 2026 and what is forecast for 2036?
- Which municipal and industrial compliance pressures support demand for water treatment systems?
- Why do Reverse Osmosis Systems lead the technology category?
- Why do Municipal Water Authorities lead the end user category globally?
- How do growth rates differ across Saudi Arabia, Brazil, the UK, and the USA?
- Which leading companies supply membrane skids and turnkey water treatment systems today?
- What limits adoption or project execution in the water treatment system market?
- What should buyers evaluate before procuring a commercial water treatment system?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Technology, 2026 to 2036
- Reverse Osmosis Systems (35.2%)
- Ultrafiltration and Microfiltration
- UV and Ozone Disinfection
- Ion Exchange, Softening, and Conventional Clarification
- Y-o-Y Growth Trend Analysis By Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Technology, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End User, 2026 to 2036
- Municipal Water Authorities (40.4%)
- Industrial Process Plants
- Commercial Buildings and Residential Point-of-Entry / Point-of-Use
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Installation, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Installation, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Installation, 2026 to 2036
- Point-of-Entry Systems (56.4%)
- Point-of-Use Systems
- Centralized Utility & Industrial Intake Skids
- Y-o-Y Growth Trend Analysis By Installation, 2021 to 2025
- Absolute $ Opportunity Analysis By Installation, 2026 to 2036
- Global Market Analysis and Forecast, By Equipment Class, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Equipment Class, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Equipment Class, 2026 to 2036
- Membrane Modules and Skids (41.8%)
- Pumps and Dosing Skids
- Filtration Vessels and Media
- Auxiliary Disinfection and Clarifier Hardware
- Y-o-Y Growth Trend Analysis By Equipment Class, 2021 to 2025
- Absolute $ Opportunity Analysis By Equipment Class, 2026 to 2036
- Global Market Analysis and Forecast, By Contract Structure, Channel & Lifecycle, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Contract Structure, Channel & Lifecycle, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Contract Structure, Channel & Lifecycle, 2026 to 2036
- Multi-Year Frame and Service-Level Agreements (54.5%)
- Spot Equipment and Project-Specific Capex
- Direct OEM and EPC Turnkey Contracts (59.3%)
- Authorized Industrial Distributors and System Integrators
- Greenfield Capacity (55.6%) and Brownfield Retrofit / MRO Replacement
- Y-o-Y Growth Trend Analysis By Contract Structure, Channel & Lifecycle, 2021 to 2025
- Absolute $ Opportunity Analysis By Contract Structure, Channel & Lifecycle, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Technology
- By End User
- By Installation
- By Equipment Class
- By Contract Structure, Channel & Lifecycle
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Veolia Environnement S.A.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Xylem Inc.
- Ecolab Inc.
- Pentair plc
- Kurita Water Industries Ltd.
- DuPont de Nemours Inc.
- Culligan International Company
- Pentair plc and Culligan International Company
- Veolia Environnement S.A.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Installation, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Equipment Class, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Contract Structure, Channel & Lifecycle, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Installation, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Equipment Class, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Contract Structure, Channel & Lifecycle, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Installation, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Equipment Class, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Contract Structure, Channel & Lifecycle, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Installation, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Equipment Class, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Contract Structure, Channel & Lifecycle, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Installation, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Equipment Class, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Contract Structure, Channel & Lifecycle, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Installation, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Equipment Class, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Contract Structure, Channel & Lifecycle, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Installation, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Equipment Class, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Contract Structure, Channel & Lifecycle, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Installation, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Equipment Class, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Contract Structure, Channel & Lifecycle, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Technology
- Figure 6: Global Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by End User
- Figure 9: Global Market Value Share and BPS Analysis by Installation, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Installation, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Installation
- Figure 12: Global Market Value Share and BPS Analysis by Equipment Class, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Equipment Class, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Equipment Class
- Figure 15: Global Market Value Share and BPS Analysis by Contract Structure, Channel & Lifecycle, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Contract Structure, Channel & Lifecycle, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Contract Structure, Channel & Lifecycle
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Technology
- Figure 32: North America Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by End User
- Figure 35: North America Market Value Share and BPS Analysis by Installation, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Installation, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Installation
- Figure 38: North America Market Value Share and BPS Analysis by Equipment Class, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Equipment Class, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Equipment Class
- Figure 41: North America Market Value Share and BPS Analysis by Contract Structure, Channel & Lifecycle, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Contract Structure, Channel & Lifecycle, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Contract Structure, Channel & Lifecycle
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Technology
- Figure 48: Latin America Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by End User
- Figure 51: Latin America Market Value Share and BPS Analysis by Installation, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Installation, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Installation
- Figure 54: Latin America Market Value Share and BPS Analysis by Equipment Class, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Equipment Class, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Equipment Class
- Figure 57: Latin America Market Value Share and BPS Analysis by Contract Structure, Channel & Lifecycle, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Contract Structure, Channel & Lifecycle, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Contract Structure, Channel & Lifecycle
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Technology
- Figure 64: Western Europe Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by End User
- Figure 67: Western Europe Market Value Share and BPS Analysis by Installation, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Installation, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Installation
- Figure 70: Western Europe Market Value Share and BPS Analysis by Equipment Class, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Equipment Class, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Equipment Class
- Figure 73: Western Europe Market Value Share and BPS Analysis by Contract Structure, Channel & Lifecycle, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Contract Structure, Channel & Lifecycle, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Contract Structure, Channel & Lifecycle
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Technology
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by End User
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Installation, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Installation, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Installation
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Equipment Class, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Equipment Class, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Equipment Class
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Contract Structure, Channel & Lifecycle, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Contract Structure, Channel & Lifecycle, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Contract Structure, Channel & Lifecycle
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Technology
- Figure 96: East Asia Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by End User
- Figure 99: East Asia Market Value Share and BPS Analysis by Installation, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Installation, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Installation
- Figure 102: East Asia Market Value Share and BPS Analysis by Equipment Class, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Equipment Class, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Equipment Class
- Figure 105: East Asia Market Value Share and BPS Analysis by Contract Structure, Channel & Lifecycle, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Contract Structure, Channel & Lifecycle, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Contract Structure, Channel & Lifecycle
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Technology
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by End User
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Installation, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Installation, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Installation
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Equipment Class, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Equipment Class, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Equipment Class
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Contract Structure, Channel & Lifecycle, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Contract Structure, Channel & Lifecycle, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Contract Structure, Channel & Lifecycle
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Technology
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by End User
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Installation, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Installation, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Installation
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Equipment Class, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Equipment Class, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Equipment Class
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Contract Structure, Channel & Lifecycle, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Contract Structure, Channel & Lifecycle, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Contract Structure, Channel & Lifecycle
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the water treatment system market in 2026, and what is forecast for 2036?
FMI research indicates that global water treatment system market size reaches USD 316.3 billion in 2026 from USD 295.3 billion in 2025. Global equipment and service valuation is forecast to attain USD 628.0 billion by 2036 across utilities.
What is the CAGR for the water treatment system market from 2026 to 2036?
FMI data suggests a 7.1% compound annual growth rate between 2026 and 2036 across global purification systems. That ten-year expansion adds USD 311.7 billion in annual category value for suppliers.
Which technology segment leads the water treatment system market?
Reverse osmosis systems capture 35.2% of technology demand in 2026 since high-rejection polyamide membranes remove dissolved salts and trace micropollutants.
Which end user segment leads the water treatment system market?
Municipal water authorities secure 40.4% of 2026 end user demand while public utilities upgrade drinking water and potable reuse plants.
Which country has a notable growth outlook during the assessment period?
Saudi Arabia leads national growth at an 8.6% CAGR through 2036 under sovereign seawater desalination tenders and industrial water reuse mandates.
Who are the key players in the market?
Veolia Environnement S.A. and Xylem Inc. lead system supply while Ecolab Inc. and Pentair plc expand industrial skids. Kurita Water Industries Ltd. and DuPont de Nemours Inc. also compete with Culligan International Company across global tenders.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
