
- Market Size (2026)
- USD 16.5 Bn
- Forecast (2036)
- USD 25.9 Bn
- CAGR (2026 to 2036)
- 4.6%
How big is Sludge Treatment Chemicals Market in 2026?
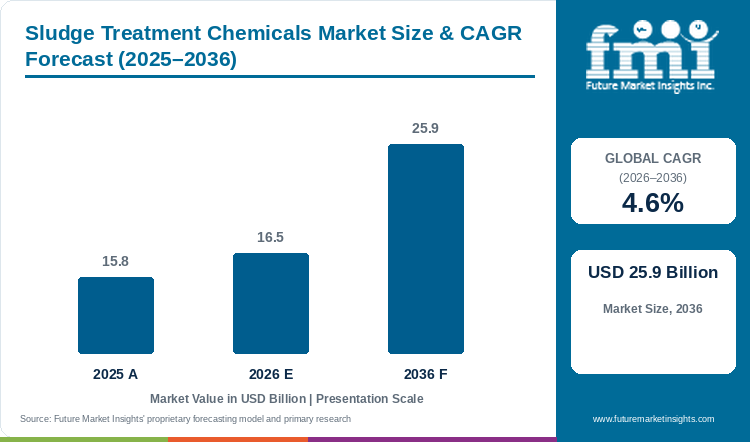
The sludge treatment chemicals market is estimated at USD 15.8 billion in 2025 and is projected to reach USD 16.5 billion in 2026. Demand for sludge treatment chemicals is expected to grow at a CAGR of 4.6% and reach USD 25.9 billion by 2036.
Sludge treatment chemicals market share is weighted toward municipal sewage works, which are likely to account for 57.3% of 2026 demand. For the sludge treatment chemicals market, the 2025 figure is estimated at USD 15.8 billion, and utilities renewing dewatering contracts are expected to raise sales to USD 16.5 billion in 2026. FMI's forecast puts the sludge treatment chemicals market at USD 25.9 billion by 2036 on a 4.6% CAGR. Utilities now judge a dewatering programme by cake weight, since each tonne of water pressed out cuts haulage fees. Toronto Water asked council in July 2026 to add CAD 5.69 million to an SNF Canada polymer contract for sludge thickening and dewatering, noting that trialling another product would mean shutting down a line.[1]
Demand intensity analysis puts dewatering at the top, as polymer goes onto every batch of digested sludge ahead of the centrifuge. Flocculants, at an expected 52.4% of 2026 product type sales, are bought by the tonne under term contracts, and coagulants follow at an estimated 31.7%. Paper and pulp mills, near 9.6% of end use, run the next heaviest programmes on fibre sludge.
For buyers, dose per dry tonne sets the annual bill. Drier cake for furnaces and fertiliser plants is opening a new outlet for cake-conditioning polymer at incinerator-fed works.
Key Market Trends & Insights
- Cationic polyacrylamide binds the fine solids in digested sludge, giving flocculants an expected 52.4% of product type sales in 2026. Coagulant purchases are estimated near 31.7%, with disinfectants and additives close to 15.9%.
- Every town plant produces sludge on every day of operation, which leaves municipal works likely to hold 57.3% of end use demand in 2026 and paper and pulp mills about 9.6%. Korea Environment Corporation plans a 61,000-ton-per-day underground sewage plant in Gwacheon, due in 2031, Herald Business reported in July 2026.[2]
Regional Highlights
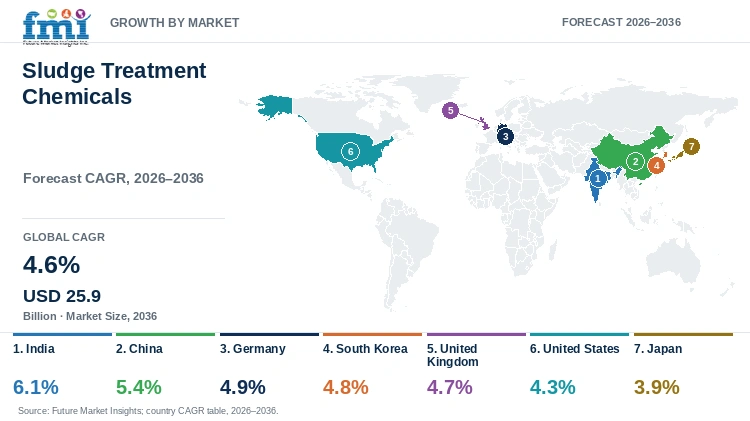
- India's 6.1% is the quickest pace in the country table, running 1.5 percentage points over the market rate of 4.6% as AMRUT sewage plants enter service and start producing cake.
- China follows on 5.4% as county plants add dewatering. Phosphorus rules keep Germany on 4.9%. South Korea follows on 4.8%, and the United Kingdom, on 4.7%, completes a tight middle group shaped by plant renewal and disposal reform. The United States is projected at 4.3%, and Japan, on 3.9%, has the lowest rate in the table as sewage flows decline.
- Sewage plants in India with about 31,885 MLD of installed capacity generate nearly 8,000 tonnes of dried sludge daily, according to a parliamentary committee report presented on 4 August 2026.[3]
Market Size & Forecast
Table 1: Market Size and Forecast for the Sludge Treatment Chemicals Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 15.8 billion |
| Estimated Market Size in 2026 | USD 16.5 billion |
| Projected Market Size by 2036 | USD 25.9 billion |
| CAGR, 2026 to 2036 | 4.6% |
| Added Revenue, 2026 to 2036 | USD 9.4 billion |
| Market Expansion Multiple | 1.6x |
Demand for sludge treatment chemicals follows the dry tonnes that sewage works and factories send to the press, so volume grows with each new sewer connection and digester. SNF Holding Company applied an energy-related price increase of 10% to 20% to orders shipping in the United States from 1 April 2026.[4] Anaerobic digesters stabilise most municipal sludge before dewatering, and the biogas market is projected to grow at an 8.1% CAGR as utilities sell gas from those tanks, adding digested sludge that calls for high-charge polymer. On FMI's forecast, about USD 9.4 billion of new sales are expected between 2026 and 2036, leaving the sludge treatment chemicals market 1.6 times larger by 2036. Slower approval of land spreading is the near-term risk, as plants without a disposal outlet store cake and dose less.
Disposal Rules, Phosphorus Recovery and Polymer Prices
Disposal routes are tightening on both sides of the Atlantic. The US EPA released draft guidance on 1 July 2026 with voluntary steps to reduce risk from PFOA and PFOS in sewage sludge and biosolids, and comments closed on 5 October 2026.[5] In England, Defra opened a consultation in January 2026 on options that include revoking the 1989 sludge-in-agriculture regulations and moving sludge under environmental permitting, Water Magazine reported.[6] Works facing tighter spreading terms will press cake drier and dose more conditioning polymer per tonne.
Phosphorus recovery is opening a second disposal path. Klärschlamm-Verwertung Rheinland is building a mono-incineration plant at Hürth-Knapsack with a capacity of 180,000 tonnes, and two water associations will supply up to 148,000 tonnes of dewatered sludge in each year from 2029, EUWID reported in May 2026.[7] Eight prefectural and municipal governments in Japan ran 11 phosphorus recovery facilities at the end of fiscal 2025, Jiji Press reported.[8] Furnace and fertiliser routes both need consistent cake, which favours suppliers with on-site trial teams.
Table 2: Disposal, Recovery and Price Indicators for the Sludge Treatment Chemicals Market (capacity, contracts and price changes), 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| SNF Canada polymer contract, Highland Creek, July 2026 | Raised from CAD 19.7 million to CAD 25.4 million | Thickening and dewatering polymer locked in for the contract term | [1] |
| SNF Holding Company price increase, from 1 April 2026 | 10% to 20%, energy related | Higher polymer cost per dry tonne | [4] |
| US EPA draft biosolids guidance, 1 July 2026 | Voluntary PFOA and PFOS risk-reduction steps | Pressure on land application outlets | [5] |
| Defra sludge consultation, January 2026 | Options include moving sludge under environmental permitting | Tighter cake quality rules in England | [6] |
| Hürth-Knapsack mono-incineration, May 2026 | 180,000 tonnes capacity; completion planned for 2028 | Drier cake for thermal treatment | [7] |
| Japan phosphorus recovery, end of fiscal 2025 | 11 facilities run by eight governments | Sludge reused as fertiliser | [8] |
| India sewage plants, August 2026 | About 31,885 MLD installed; nearly 8,000 tonnes of dried sludge daily | Large municipal dewatering base | [3] |
Analyst Perspective
“I expect cake dryness and polymer kilograms per dry tonne to decide most sludge chemical contracts through 2036, as haulage and incineration fees now weigh heavier on utility budgets than the chemical invoice. Suppliers that run trials on the plant's own centrifuge and hold price through energy shocks will keep municipal accounts for a full contract cycle.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the sludge treatment chemicals market segmented?
The market is segmented into product type, end use industry, and region. Flocculants are expected to lead product type with 52.4% share in 2026, and municipal works lead end use industry with 57.3%.
By product type: flocculants (cationic and anionic), coagulants (organic and inorganic), and disinfectants and additives (anti-foulants, anti-foamers and activated carbon).
By end use industry: municipal, paper and pulp, food and beverage, oil and gas, metal processing, chemical and fertilizer, automotive, and others.
By region: sewage works, mills and process plants in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do flocculants lead sludge treatment chemicals sales by product type?
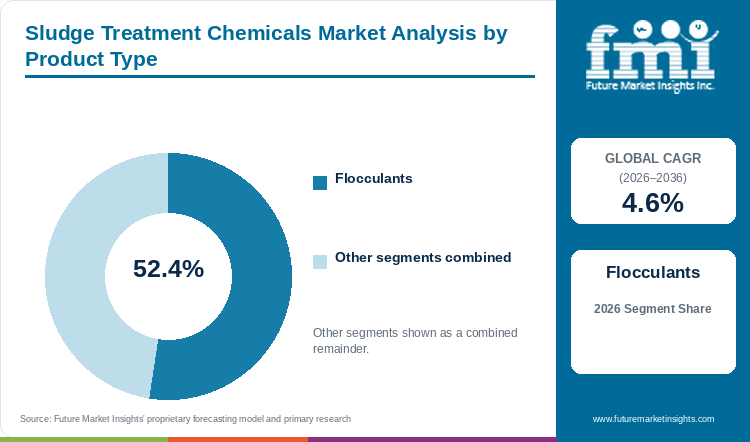
Flocculants are expected to lead product type sales with 52.4% share in 2026, against an estimated 31.7% for coagulants and 15.9% for disinfectants and additives.
Table 3: Product Type Share for the Sludge Treatment Chemicals Market (percentage share), 2026
| Product Type | Estimated Share (2026) |
|---|---|
| Flocculants | 52.4% |
| Coagulants | 31.7% |
| Disinfectants and Additives | 15.9% |
| Total | 100.0% |
Table 4: Product Type Leadership and Market Growth for the Sludge Treatment Chemicals Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.6% |
| Leading Segment | Flocculants |
A 52.4% share in 2026 is expected to put flocculants first in product type. Cationic polyacrylamide bridges the fine, negatively charged particles in digested sludge into flocs that release water in a centrifuge or belt press, and no other product class does that job at such low doses. Coagulants, an estimated 31.7%, neutralise charge and bind phosphorus, and ferric and aluminium salts add mass to the cake, so works dose them ahead of the polymer as a partner product. Disinfectants and additives, near 15.9%, cover anti-foamers for digesters, anti-foulants for presses and activated carbon for odour, and each is bought in small lots to fix a specific fault. The SNF price increase of 10% to 20% reached polymer buyers first in April 2026.[4] Works managers comparing these segments will keep the flocculant budget fixed and trim additive orders when prices rise.
- Cationic grades for digested municipal sludge and anionic grades for mineral-rich industrial sludge form the flocculant range.
- Toronto Water raised the SNF Canada polymer contract from CAD 19.7 million to CAD 25.4 million, according to a council report dated 6 July 2026.[1]
Why do municipal works lead sludge treatment chemicals sales by end use industry?
Municipal works are projected to lead end use industry sales with 57.3% share in 2026, ahead of paper and pulp at an estimated 9.6% and food and beverage at about 8.4%.
Table 5: End Use Industry Share for the Sludge Treatment Chemicals Market (percentage share), 2026
| End Use Industry | Estimated Share (2026) |
|---|---|
| Municipal | 57.3% |
| Paper and Pulp | 9.6% |
| Food and Beverage | 8.4% |
| Oil and Gas | 7.1% |
| Chemical and Fertilizer | 6.5% |
| Metal Processing | 5.2% |
| Automotive | 2.4% |
| Others | 3.5% |
| Total | 100.0% |
Municipal works, at 57.3% share in 2026, are projected to lead end use, as tenders run three to five years and dosing never stops. Paper and pulp, about 9.6%, treats fibre and filler sludge at the mill, and closures of older machines cap growth there. Food and beverage, 8.4%, handles fat-rich sludge from dairies and breweries that needs a coagulant step first. Oil and gas, 7.1%, and chemical and fertilizer plants, 6.5%, dose oily and saline sludges in smaller, project-led volumes. Metal processing, 5.2%, automotive, 2.4%, and other users, 3.5%, buy for hydroxide and paint sludge. Sewage plants in India alone generate nearly 8,000 tonnes of dried sludge each day.[3] As utilities add treatment stages, the water and wastewater treatment chemicals market is forecast to grow at a CAGR of 4.6%, keeping coagulant and polymer orders inside the same city tenders.
- Activated sludge works, digester-equipped plants and small package plants form the municipal base.
- The KRW 224.9 billion Gwacheon project includes a 75-ton integrated biogas facility, Herald Business reported on 1 July 2026.[2]
What are the drivers, restraints, and opportunities in the sludge treatment chemicals market?
Wider sewer coverage and new digesters keep demand for sludge treatment chemicals recurring. Energy-linked polymer prices strain utility budgets, and incineration and phosphorus recovery routes add new dosing points.
- Driver: Each new sewer connection sends more solids to a treatment works, and every added tonne of sludge needs polymer and coagulant before haulage.
- Restraint: Polyacrylamide and metal salt prices move with energy and feedstock costs, and fixed municipal tenders leave suppliers and utilities disputing who absorbs the gap.
- Opportunity: Mono-incineration and phosphorus recovery plants need dry, uniform cake, which rewards suppliers able to tune polymer to each feed.
Sewer Coverage Adds Dewatering Load
Orders for sludge treatment chemicals rise with the share of homes connected to a treatment works. Under AMRUT 2.0, 658 MLD of the 6,815 MLD of treatment capacity taken up was operational, the Standing Committee on Housing and Urban Affairs noted in August 2026.[3] The Gwacheon plant will treat 61,000 tons of sewage per day once complete in 2031.[2] Each plant that moves from construction into service becomes a polymer buyer for the life of the works.
Energy-Linked Prices Strain Utility Budgets
Polymer buyers face feedstock costs that move faster than municipal budgets. SNF Holding Company cited raw material costs and the Middle East situation for the increase announced in March 2026.[4] Toronto Water reported that testing a new polymer at Highland Creek would require shutting down a line, which leaves little room to switch supplier when prices rise.[1] FMI analysis shows utilities absorbing these increases in the short run and asking for dose-based pricing at the next tender.
Incineration and Phosphorus Recovery Open New Dosing Points
Growth of the sludge treatment chemicals market will come from works that burn or mine sludge instead of spreading cake on farmland. The Hürth-Knapsack plant is scheduled for completion in 2028, and phosphorus recovery becomes mandatory in Germany from 2029.[7] Tokyo plans nationwide distribution of fertiliser made from recovered phosphorus from fiscal 2026, working with Zen-Noh.[8] Suppliers that guarantee cake dryness for furnace feed will hold these new accounts.
Which country CAGRs are profiled in the sludge treatment chemicals market?
Table 6: Country CAGR Comparison for the Sludge Treatment Chemicals Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 6.1% |
| China | 5.4% |
| Germany | 4.9% |
| South Korea | 4.8% |
| United Kingdom | 4.7% |
| United States | 4.3% |
| Japan | 3.9% |
How do country-level CAGRs compare in the sludge treatment chemicals market?
Indian cities are bringing AMRUT sewage plants into service, and installed capacity of about 31,885 MLD already yields close to 8,000 tonnes of dried sludge each day.[3] India is expected to grow at 6.1%, and China follows on 5.4% as county-level plants add thickening and dewatering. FMI's forecast puts Germany at 4.9% as the 2029 phosphorus rule moves sludge to mono-incineration, three tenths above the market rate of 4.6%. Plant renewal in South Korea and stricter spreading rules in the United Kingdom keep both close behind, on 4.8% and 4.7%. Mature networks with flat or shrinking sewage flows hold the United States to 4.3% and Japan to 3.9%.
- AMRUT 2.0 sewage plants entering service in India add new dewatering lines.
- County and rural sewage plants in China are fitting sludge thickening and dewatering.
- German utilities are preparing sludge for mono-incineration ahead of the 2029 phosphorus rule.
- Underground sewage plants with biogas units are replacing older works in South Korean cities.
- Defra's review of sludge spreading rules puts cake quality under closer scrutiny in the United Kingdom.
- PFAS guidance for biosolids is shaping disposal choices at US treatment works.
- Japanese cities are recovering phosphorus from sludge as sewage volumes decline.
Full report country CAGRs cover: seven profiled countries, with India and China ahead on new sewage capacity, Germany, South Korea and the United Kingdom within 0.3 points of the 4.6% global figure, and the United States and Japan below the line; other standard countries are grouped by region.
Country-wise Analysis
India Sludge Treatment Chemicals Market Outlook (2026 to 2036)
Sludge volumes in India are rising faster than disposal options. Sewage plants with about 31,885 MLD of installed capacity generate nearly 8,000 tonnes of dried sludge daily, and the parliamentary committee asked for a framework on recovery technologies, safe-reuse standards and end-use markets.[3] On FMI's forecast, demand for sludge treatment chemicals in India will grow at 6.1%, as each commissioned plant adds a polymer contract.
Key takeaway: New sewage plants turn into steady polymer buyers in India.
China Sludge Treatment Chemicals Market Outlook (2026 to 2036)
County towns and rural districts in China are adding sewage plants that ship cake to landfill, incinerators and brick kilns. Local polyacrylamide makers supply most commodity grades at low prices, so global suppliers compete on service at large city works. Chinese county plants are expected to keep demand for sludge treatment chemicals rising at 5.4% through 2036.
Key takeaway: Plant build-out and local polymer supply shape China.
Germany Sludge Treatment Chemicals Market Outlook (2026 to 2036)
Klärschlamm-Verwertung Rheinland, formed by Erftverband, Wasserverband Eifel-Rur and RWE Power, is building a 180,000-tonne mono-incineration plant at Hürth-Knapsack for completion in 2028.[7] Sludge for such furnaces needs dewatering to a stable dry solids level, and German utilities are tightening polymer specifications to match. Those specifications are expected to hold growth in Germany at 4.9% for sludge treatment chemicals.
Key takeaway: Phosphorus recovery rules push German cake specifications higher.
South Korea Sludge Treatment Chemicals Market Outlook (2026 to 2036)
Korea Environment Corporation awarded the KRW 224.9 billion Gwacheon sewage project to a consortium led by Kumho Engineering & Construction, with a 61,000-ton-per-day underground plant and a 75-ton biogas facility due in 2031.[2] Digester-equipped plants of this type produce sludge that needs high-charge cationic polymer. South Korea is forecast at 4.8%.
Key takeaway: Underground plants with digesters raise polymer needs in South Korea.
United Kingdom Sludge Treatment Chemicals Market Outlook (2026 to 2036)
Most sewage sludge from water companies in England is recycled to land, and Defra's January 2026 consultation weighed revoking the 1989 regulations in favour of environmental permitting.[6] Water companies preparing for tighter permits are reviewing digestion, drying and polymer programmes. The United Kingdom is projected at 4.7%.
Key takeaway: Permitting reform keeps cake quality under review in the United Kingdom.
United States Sludge Treatment Chemicals Market Outlook (2026 to 2036)
US treatment works face questions over PFAS in biosolids, and the EPA's July 2026 draft guidance gave operators, farmers and states voluntary risk-reduction steps.[5] SNF Holding Company raised US prices by 10% to 20% from April 2026.[4] FMI analysis gives the United States a 4.3% CAGR, under the market rate of 4.6%, with growth led by plant upgrades and drier cake for landfill and thermal routes.
Key takeaway: Biosolids rules and polymer prices set the US outlook.
Japan Sludge Treatment Chemicals Market Outlook (2026 to 2036)
Japan relies on imports for almost all phosphorus, and Tokyo began recovering phosphorus from sludge at the Sunamachi Water Reclamation Center in January 2024, producing about 70 tons of phosphorus each year.[8] FMI expects shrinking sewage flows to hold Japan at 3.9%, though recovery projects add demand for consistent dewatering.
Key takeaway: Recovery projects offset falling sewage volumes in Japan.
Who are the notable companies in the sludge treatment chemicals market?
SNF Group, Kemira, BASF, Ecolab, Veolia, Suez, Kurita Water Industries, Buckman, Feralco, ChemTreat, Solenis, Accepta and Thermax are the profiled companies.
Thirteen companies are profiled by FMI across polymer and coagulant production, water treatment service and regional supply. SNF Group is the documented polymer supplier at Toronto's Highland Creek plant. The city raised that contract to CAD 25.4 million in July 2026.[1] SNF Holding Company also set a 10% to 20% energy-related price increase in the United States from April 2026.[4] Kemira, BASF and Feralco supply polymer and metal salt coagulants, and Ecolab, Veolia, Suez, Kurita Water Industries, Solenis, ChemTreat and Buckman sell treatment programmes with on-site service.
- Polymer and metal salt producers: SNF Group, Kemira, BASF and Feralco.
- Water treatment service groups: Ecolab, Veolia, Suez, Kurita Water Industries, Solenis, ChemTreat and Buckman.
- Regional suppliers: Accepta and Thermax.
Competitive Benchmarking: Sludge Treatment Chemicals Market
Table 7: Competitive Benchmarking for the Sludge Treatment Chemicals Market (qualitative documentation ratings), 2026
| Company | Polymer Supply | Coagulant Supply | On-site Service | Recency |
|---|---|---|---|---|
| SNF Group | High | Medium | Medium | High |
| Kemira | High | High | Medium | Medium |
| BASF | Medium | Low | Low | Medium |
| Feralco | Low | High | Low | Low |
| Kurita Water Industries | Medium | Medium | High | Medium |
Ratings grade the dated 2026 contract and company evidence found for each column, with no link to sales share.
Key Developments in the Sludge Treatment Chemicals Market
- On 4 August 2026, the Standing Committee on Housing and Urban Affairs presented a report noting nearly 8,000 tonnes of dried sludge generated daily by Indian sewage plants.[3]
- On 6 July 2026, Toronto Water recommended raising the SNF Canada polymer contract for Highland Creek to CAD 25.4 million.[1]
- On 1 July 2026, the US EPA released draft guidance for reducing risk from PFOA and PFOS in biosolids.[5]
- On 1 July 2026, Herald Business reported the KRW 224.9 billion Gwacheon sewage plant award by Korea Environment Corporation.[2]
- On 21 May 2026, EUWID reported that the furnace hall for the second line at Hürth-Knapsack was structurally complete.[7]
- On 9 May 2026, Jiji Press reported 11 phosphorus recovery facilities at Japanese local governments.[8]
- On 17 March 2026, SNF Holding Company announced an energy-related price increase of 10% to 20%.[4]
- On 28 January 2026, Water Magazine reported a Defra consultation on reform of sewage sludge regulation in England.[6]
Key Players in the Sludge Treatment Chemicals Market
Polymer and Metal Salt Producers
- SNF Group
- Kemira
- BASF
- Feralco
Water Treatment Service Groups
- Ecolab
- Veolia
- Suez
- Kurita Water Industries
- Solenis
- ChemTreat
- Buckman
Regional Suppliers
- Accepta
- Thermax
Sludge Treatment Chemicals Market - Report Scope
Table 8: Report Scope for the Sludge Treatment Chemicals Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; end use industry; region |
| Quantitative units | USD billion |
| Market definition | Flocculants, coagulants, disinfectants and process additives dosed to thicken, condition, dewater, stabilise or deodorise sludge from municipal sewage works and industrial effluent plants. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | SNF Group, Kemira, BASF, Ecolab, Veolia, Suez, Kurita Water Industries, Buckman, Feralco, ChemTreat, Solenis, Accepta, Thermax |
| Forecast period | 2026 to 2036 |
Sludge Treatment Chemicals Market - Research Methodology
Table 9: Research Methodology for the Sludge Treatment Chemicals Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Municipal council reports, environmental regulator releases, parliamentary committee summaries, producer price notices and water trade press from January 2026 onward. |
| Desk Research | Desk research covers dewatering practice, biosolids disposal rules, mono-incineration, phosphorus recovery and polymer pricing. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 16.5 billion and the 4.6% CAGR for 2026 to 2036. |
| Data Validation | Contract values, capacities and price changes were checked against the council report, regulator page or article that first carried them. |
Sludge Treatment Chemicals Market by Segments
Sludge Treatment Chemicals Market segmented by Product Type:
- Flocculants
- Coagulants
- Disinfectants and Additives
Sludge Treatment Chemicals Market segmented by End Use Industry:
- Municipal
- Paper and Pulp
- Food and Beverage
- Oil and Gas
- Metal Processing
- Chemical and Fertilizer
- Automotive
- Others
Sludge Treatment Chemicals Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] City of Toronto, Toronto Water and Purchasing and Materials Management. (2026, July 6). Amendments to Contracts for Biosolids Haulage and Polymer Supply (General Government Committee report). https://www.toronto.ca/legdocs/mmis/2026/gg/bgrd/backgroundfile-289097.pdf
- [2] Herald Business. (2026, July 1). Project to handle increased wastewater from Gwacheon and Gwacheon Juam public housing district developments. https://biz.heraldcorp.com/article/10794121
- [3] PRS Legislative Research. (2026, August 4). Review of Sewerage and Septage Coverage in Cities under AMRUT and AMRUT 2.0 (Standing Committee report summary). https://prsindia.org/policy/report-summaries/review-of-sewerage-and-septage-coverage-in-cities-under-amrut-amrut-2-0
- [4] SNF Holding Company. (2026, March 17). SNFHC Announces Energy-Related Price Increase. https://www.snf.com/media/global-communication/snfhc-price-increase/
- [5] U.S. Environmental Protection Agency. (2026, July 1). Draft Guidance for Reducing Risk from Perfluorooctanoic Acid (PFOA) and Perfluorooctane Sulfonic Acid (PFOS) in Biosolids. https://www.epa.gov/biosolids/draft-guidance-reducing-risk-perfluorooctanoic-acid-pfoa-and-perfluorooctane-sulfonic
- [6] Water Magazine. (2026, January 28). Defra consults on major overhaul of sewage sludge regulation. https://www.watermagazine.co.uk/2026/01/28/defra-consults-on-major-overhaul-of-sewage-sludge-regulation/
- [7] EUWID Recycling und Entsorgung. (2026, May 21). Klärschlamm-Monoverbrennung in Hürth-Knapsack erreicht nächste Bauphase. https://www.euwid-recycling.de/news/wirtschaft/klaerschlamm-monoverbrennung-in-huerth-knapsack-erreicht-naechste-bauphase-210526/
- [8] Jiji Press via Adnkronos. (2026, May 9). Japan Local Govts Recover Phosphorus from Sewage Sludge. https://english.adnkronos.com/2026/05/09/japan-local-govts-recover-phosphorus-from-sewage-sludge/
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the sludge treatment chemicals market during 2026?
- What market size is projected by 2036?
- Which product type holds notable share?
- Which end use industry holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Flocculants
- Coagulants
- Disinfectants and Additives
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use Industry, 2026 to 2036
- Municipal
- Paper and Pulp
- Food and Beverage
- Oil and Gas
- Metal Processing
- Chemical and Fertilizer
- Automotive
- Others
- Y-o-Y Growth Trend Analysis By End Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By End Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use Industry
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By End Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use Industry
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By End Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use Industry
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By End Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use Industry
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By End Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use Industry
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By End Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use Industry
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By End Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use Industry
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Industry
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Industry
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Industry
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Industry
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Industry
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Industry
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Industry
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Industry
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Industry
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Industry
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Industry
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Industry
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Industry
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Industry
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Industry
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Industry
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Industry
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Industry
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Industry
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Industry
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By End Use Industry
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- SNF Group
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Kemira
- BASF
- Feralco
- Kurita Water Industries
- Ecolab
- Veolia
- Suez
- Solenis
- ChemTreat
- Buckman
- Accepta
- Thermax
- SNF Group
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by End Use Industry, 2021 to 2036
- Table 4: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by End Use Industry, 2021 to 2036
- Table 7: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by End Use Industry, 2021 to 2036
- Table 10: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 11: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 12: Western Europe Market Value (USD Billion) Forecast by End Use Industry, 2021 to 2036
- Table 13: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 15: Eastern Europe Market Value (USD Billion) Forecast by End Use Industry, 2021 to 2036
- Table 16: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 18: East Asia Market Value (USD Billion) Forecast by End Use Industry, 2021 to 2036
- Table 19: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 21: South Asia and Pacific Market Value (USD Billion) Forecast by End Use Industry, 2021 to 2036
- Table 22: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 23: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 24: Middle East and Africa Market Value (USD Billion) Forecast by End Use Industry, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by End Use Industry, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by End Use Industry, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by End Use Industry
- Figure 9: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Region
- Figure 12: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 13: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 14: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 15: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 20: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 21: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 22: North America Market Attractiveness Analysis by Product Type
- Figure 23: North America Market Value Share and BPS Analysis by End Use Industry, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by End Use Industry, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by End Use Industry
- Figure 26: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 27: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 28: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 29: Latin America Market Attractiveness Analysis by Product Type
- Figure 30: Latin America Market Value Share and BPS Analysis by End Use Industry, 2026 and 2036
- Figure 31: Latin America Market Y-o-Y Growth Comparison by End Use Industry, 2026-2036
- Figure 32: Latin America Market Attractiveness Analysis by End Use Industry
- Figure 33: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 34: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 35: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 36: Western Europe Market Attractiveness Analysis by Product Type
- Figure 37: Western Europe Market Value Share and BPS Analysis by End Use Industry, 2026 and 2036
- Figure 38: Western Europe Market Y-o-Y Growth Comparison by End Use Industry, 2026-2036
- Figure 39: Western Europe Market Attractiveness Analysis by End Use Industry
- Figure 40: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 41: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 42: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 43: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 44: Eastern Europe Market Value Share and BPS Analysis by End Use Industry, 2026 and 2036
- Figure 45: Eastern Europe Market Y-o-Y Growth Comparison by End Use Industry, 2026-2036
- Figure 46: Eastern Europe Market Attractiveness Analysis by End Use Industry
- Figure 47: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 48: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 49: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 50: East Asia Market Attractiveness Analysis by Product Type
- Figure 51: East Asia Market Value Share and BPS Analysis by End Use Industry, 2026 and 2036
- Figure 52: East Asia Market Y-o-Y Growth Comparison by End Use Industry, 2026-2036
- Figure 53: East Asia Market Attractiveness Analysis by End Use Industry
- Figure 54: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 55: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 56: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 57: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 58: South Asia and Pacific Market Value Share and BPS Analysis by End Use Industry, 2026 and 2036
- Figure 59: South Asia and Pacific Market Y-o-Y Growth Comparison by End Use Industry, 2026-2036
- Figure 60: South Asia and Pacific Market Attractiveness Analysis by End Use Industry
- Figure 61: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 62: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 63: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 64: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 65: Middle East and Africa Market Value Share and BPS Analysis by End Use Industry, 2026 and 2036
- Figure 66: Middle East and Africa Market Y-o-Y Growth Comparison by End Use Industry, 2026-2036
- Figure 67: Middle East and Africa Market Attractiveness Analysis by End Use Industry
- Figure 68: Global Market - Tier Structure Analysis
- Figure 69: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the sludge treatment chemicals market expected in 2026?
FMI estimates the sludge treatment chemicals market at USD 16.5 billion in 2026, up from USD 15.8 billion in 2025. By 2036, the sludge treatment chemicals market is projected to reach USD 25.9 billion.
What CAGR is projected for the sludge treatment chemicals market through 2036?
The sludge treatment chemicals market is expected to grow at a 4.6% CAGR from 2026 to 2036. New sewer connections, digesters and drier cake for incineration support that growth.
Which product type holds a notable market share in 2026?
Flocculants are expected to lead with 52.4% share in 2026. Coagulants follow at an estimated 31.7%.
Which end use industry holds a notable market share in 2026?
Municipal works are projected to lead with 57.3% share in 2026. Paper and pulp mills follow at about 9.6%.
Which country has a notable expansion outlook through 2036?
India is first in FMI's country table at a 6.1% CAGR. China follows at 5.4%.
Who are the key companies in the sludge treatment chemicals market?
SNF Group, Kemira, BASF and Feralco lead the polymer and coagulant producers. Ecolab, Veolia, Suez, Kurita Water Industries, Solenis, ChemTreat, Buckman, Accepta and Thermax complete the profiled companies.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
