
- Market Size (2026)
- USD 52.1 Bn
- Forecast (2036)
- USD 96.9 Bn
- CAGR (2026 to 2036)
- 6.4%
How big is Water Treatment Polymers Market in 2026?
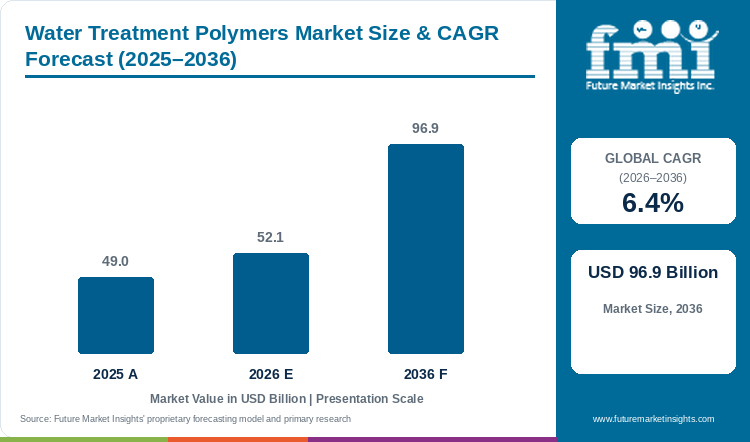
The water treatment polymers market is estimated at USD 49.0 billion in 2025 and is expected to reach USD 52.1 billion in 2026. At a 6.4% CAGR across the forecast period, sales of water treatment polymers are projected to reach USD 96.9 billion by 2036.
Demand for water treatment polymers will grow at a 6.4% CAGR through the decade, with the water treatment polymers market estimated at USD 49.0 billion in 2025, expected at USD 52.1 billion in 2026 and projected at USD 96.9 billion in 2036. Polyacrylamide makers are shipping more tonnes into municipal and industrial plants at lower unit prices. SNF reported 9.1% volume growth and a 5.5% price decline in the first quarter of 2026.[1] Treatment plants are therefore getting more flocculant per contract, and operators are adding dosing points at clarifiers and belt presses.
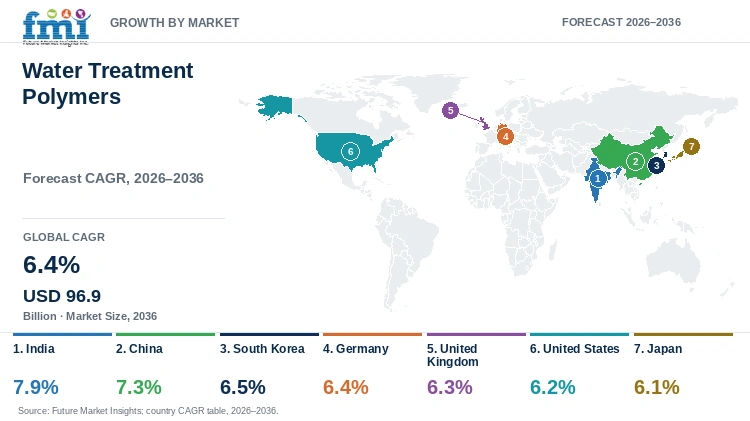
Through 2036, South Korea is predicted to outpace Japan, at 6.5% against 6.1% on a CAGR basis. The Korean environment ministry proposed KRW 1,268.6 billion for new sewage treatment plants inside a KRW 7.3 trillion water budget for 2026, the largest ever.[2] Every new Korean plant orders cationic polymer for sludge dewatering from start-up. Japanese utilities are putting more money into corroded sewer pipe, so polymer orders in Japan follow existing plant flows.
Polyacrylamides are likely to hold 47.6% of product sales in 2026, and municipality buyers 52.4% of end use, FMI analysts expect. Water reuse permits are widening the buyer pool to food, chip and refinery plants that now dose polymer ahead of membranes.
Key Market Trends & Insights
- Ahead of polyacrylates at an estimated 21.8%, cationic and anionic polyacrylamides will hold 47.6% of product type sales in 2026. SNF said in May 2026 that selling price increases were already in place in all regions after the closure of the Strait of Hormuz.[1]
- Clarification, sedimentation and filter polishing give the water treatment stage an estimated 44.7% of 2026 application demand, with sludge treatment near 36.2% and preliminary treatment at 19.1%.
- Within end use, municipality buyers are projected to account for 52.4% in 2026 and industrial plants for about 33.9%. Veralto said demand stayed strong across industrial water treatment in the second quarter of 2026.[3]
Regional Highlights
- Ganga basin sewage plants put India at 7.9% in FMI's outlook, faster than the market average of 6.4%.
- China comes next on 7.3% as coastal cities extend sewer networks. South Korea (6.5%) and Germany (6.4%) stay close to the global figure, with the United Kingdom (6.3%) and the United States (6.2%) a fraction lower. Pipe repair holds Japan to 6.1%, the lowest rate here.
- Spill events from storm overflows in England fell 35% to 291,492 in 2025, Environment Agency data published in March 2026 show.[4]
Market Size & Forecast
Table 1: Market Size and Forecast for the Water Treatment Polymers Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 49.0 billion |
| Estimated Market Size in 2026 | USD 52.1 billion |
| Projected Market Size by 2036 | USD 96.9 billion |
| CAGR, 2026 to 2036 | 6.4% |
| Added Revenue, 2026 to 2036 | USD 44.8 billion |
| Market Expansion Multiple | 1.9x |
Sales of water treatment polymers move with treated flow, as plants dose flocculant and coagulant aid in proportion to the litres passing each clarifier and press. Veralto reported 5.7% core sales growth in Water Quality for April to June 2026, with municipal demand for water analytics described as steady.[3] Federal support is thinner in the United States, and the FY2026 Clean Water SRF base appropriation fell to USD 746.1 million from USD 1,638.9 million.[5] Utilities usually tender polymer and metal salts together, and the water and wastewater treatment chemicals market is predicted to rise by 4.6% on a CAGR basis, so polymers are expected to gain share of each treatment chemical budget. FMI's outlook adds USD 44.8 billion to sales of water treatment polymers by 2036, close to 1.9 times the 2026 level. Feedstock cost is the main near-term risk, as acrylamide and acrylic acid follow propylene and energy prices.
Sewer Renewal, Overflow Storage and Regional Polymer Supply
Network renewal is changing what utilities fund first. Japan's infrastructure ministry classed 748 km of the 4,692 km of large sewer pipe inspected as needing countermeasures in April 2026.[6] In England, monitoring data have supported GBP 10.2 billion of storm overflow upgrades within GBP 104 billion of water investment over five years.[4] Overflow storage and pipe repair come first, and plant chemistry contracts grow once the added flow reaches the works.
Polyacrylamide supply is moving closer to Gulf and South Asian buyers. SNF Oman began local polymer processing in January 2026 at about 6,000 tonnes per year and plans more than 10,000 tonnes of added output in Salalah, mainly for oil and gas and the wider region.[7] Namami Gange had created 4,263 MLD of sewage treatment capacity in India by June 2026, with 6,610 MLD sanctioned.[8] Regional reactors shorten lead times for utilities that once imported emulsion and powder grades from Europe.
Table 2: Polymer Supply, Funding and Capacity Indicators for the Water Treatment Polymers Market (volumes, budgets and capacity), 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| SNF volume and price, Q1 2026 | Volume up 9.1%; price down 5.5% | Polyacrylamide tonnes rising | [1] |
| SNF Asia Pacific share of sales, Q1 2026 | 25.9%, from 24.3% | Growth moving to Asia | [1] |
| Veralto Water Quality core sales, Q2 2026 | Up 5.7% | Industrial water treatment demand | [3] |
| US Clean Water SRF base, FY2026 | USD 746.1 million; USD 1,638.9 million in FY2025 | Less federal plant funding | [5] |
| Korea sewage treatment plant budget, 2026 plan | KRW 1,268.6 billion | New plants needing polymer | [2] |
| England storm overflow spill events, 2025 | 291,492; down 35% | Upgrade pressure on utilities | [4] |
| Namami Gange STP capacity, June 2026 | 4,263 MLD created; 6,610 MLD sanctioned | Clarifier and press dosing in India | [8] |
Analyst Perspective
“I expect cationic polyacrylamide for sludge dewatering to be the fastest-moving product line, as every new sewage plant in Asia buys a dewatering grade from the first week of operation. Buyers now judge suppliers on dry solids at the press and on how quickly a jar test becomes a dosing change, and I see producers with local emulsion plants keeping those accounts for years.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the water treatment polymers market segmented?
The market is segmented into product type, application, end use, and region. Polyacrylamides are expected to lead product type with 47.6% share in 2026, and municipality leads end use with 52.4%.
By product type: polyacrylamides, polyacrylates, quaternary ammonium polymers, and polyamines.
By application: preliminary treatment, water treatment, and sludge treatment.
By end use: residential buildings, commercial buildings, municipality, and industrial.
By region: utilities and industrial plants in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do polyacrylamides lead water treatment polymers sales by product type?
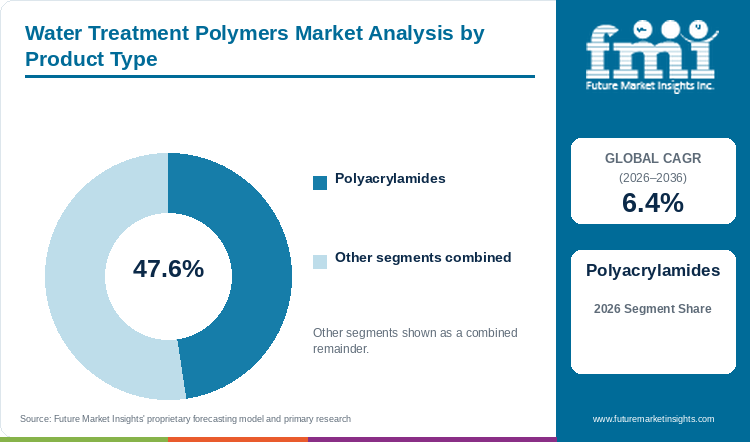
Polyacrylamides are expected to lead product type sales with 47.6% share in 2026, against an estimated 21.8% for polyacrylates, 17.3% for quaternary ammonium polymers and 13.3% for polyamines.
Table 3: Product Type Share for the Water Treatment Polymers Market (percentage share), 2026
| Product Type | Estimated Share (2026) |
|---|---|
| Polyacrylamides | 47.6% |
| Polyacrylates | 21.8% |
| Quaternary Ammonium Polymers | 17.3% |
| Polyamines | 13.3% |
| Total | 100.0% |
Table 4: Product Type Leadership and Market Growth for the Water Treatment Polymers Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.4% |
| Leading Segment | Polyacrylamides |
With charge and chain length tuned to each sludge, polyacrylamides are predicted to lead with a 47.6% share in 2026. Polyacrylates, an estimated 21.8%, are short-chain dispersants that keep scale off boilers and membranes, so polyacrylates never compete for clarifier or press dosing. Quaternary ammonium polymers such as polyDADMAC, about 17.3%, act as primary coagulants in drinking water, and utilities pair them with a polyacrylamide flocculant instead of replacing one with the other. Polyamines, near 13.3%, cost less per tonne but build small floc, which limits them to colour and turbidity removal in river water. Paper, mining and oilfield buyers use the same acrylamide chemistry, and growth of the polyacrylamide market keeps producers running large reactors that also make water grades. Operators choose polyacrylamide when cake dryness sets disposal cost, and add polyamine or polyDADMAC when raw water turbidity sets the dose.
- Cationic emulsions for dewatering, anionic powders for clarification and nonionic grades for mine water make up most polyacrylamide volume.
- SNF Oman plans more than 10,000 tonnes per year of added polymer output in Salalah, with the second phase due in the fourth quarter of 2026.[7]
Why does water treatment lead water treatment polymers sales by application?
Water treatment is likely to lead application sales with 44.7% share in 2026, with sludge treatment at about 36.2% and preliminary treatment at roughly 19.1%.
Table 5: Application Share for the Water Treatment Polymers Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| Water Treatment | 44.7% |
| Sludge Treatment | 36.2% |
| Preliminary Treatment | 19.1% |
| Total | 100.0% |
Primary clarification, secondary sedimentation and tertiary filtration dose polymer on every litre of flow, so water treatment is likely to lead applications at 44.7% in 2026. Sludge treatment, an estimated 36.2%, needs the highest dose per tonne of solids, but sludge is a small fraction of plant flow. Preliminary treatment, about 19.1%, covers screening, grit and oil removal, and many works dose there only at peak load or for industrial influent. Projected at a 4.6% CAGR, the sludge treatment chemicals market follows new dewatering press installations, which keeps the sludge share moving slowly. Monitoring data in England have supported GBP 10.2 billion of storm overflow upgrades.[4] Storm water held in new tanks returns to the works for clarification once flows fall, so the main polymer budget will stay at the clarifier.
- Coagulant aids for primary tanks, settling aids for secondary clarifiers and filter aids for tertiary polishing make up this stage.
- NBM&CW reported in August 2026 that 146 of the 219 sanctioned Namami Gange sewerage projects were complete.[8]
Why does municipality lead water treatment polymers sales by end use?
Municipality is projected to lead end use sales with 52.4% share in 2026, ahead of industrial plants at an estimated 33.9%, commercial buildings at 8.6% and residential buildings at 5.1%.
Table 6: End Use Share for the Water Treatment Polymers Market (percentage share), 2026
| End Use | Estimated Share (2026) |
|---|---|
| Municipality | 52.4% |
| Industrial | 33.9% |
| Commercial Buildings | 8.6% |
| Residential Buildings | 5.1% |
| Total | 100.0% |
City works treat sewage and drinking water around the clock under discharge permits, and municipality buyers will lead with a 52.4% share of end use in 2026. Industrial plants, an estimated 33.9%, dose polymer for process water, effluent and boiler make-up, but many recycle water internally and order smaller tonnages per site. Commercial buildings, about 8.6%, need scale and corrosion programmes for cooling towers and pools, so dispersant polymers dominate there. Residential buildings, near 5.1%, use polymer mostly in packaged sewage units and softeners. Reuse plants run membranes that need antiscalant dosing, with the membrane chemicals market on a 6.1% CAGR forecast, close to the polymer rate. Municipal tenders will remain the largest contracts, and industrial accounts will pay more per kilogram for tailored grades.
- Sewage works, drinking water plants and sludge centres run by cities form the municipal base.
- Every storm overflow in England now has an event duration monitor fitted, the Environment Agency said in March 2026.[4]
What are the drivers, restraints, and opportunities in the water treatment polymers market?
Rising treated flows at city works and stricter discharge permits keep demand for water treatment polymers recurring. Feedstock price swings and thinner public funding squeeze buyers and suppliers, and reuse plants and new sewage capacity in Asia open fresh accounts.
- Driver: Each new sewage plant and storm tank adds flow that has to be clarified and dewatered, which turns a capital project into a permanent polymer contract.
- Restraint: Acrylamide and acrylic acid follow propylene and energy prices, and fixed annual tenders leave suppliers carrying cost changes until the next award.
- Opportunity: Reuse schemes in food, electronics and refining need cleaner pretreatment ahead of membranes, which rewards suppliers able to tune polymer charge to each effluent.
New Treatment Capacity Becomes Recurring Polymer Volume
Growth of the water treatment polymers market follows the number of treatment lines in service, as dosing runs whenever a plant receives flow. The National Mission for Clean Ganga commissioned 25 sewage treatment plants in 2025.[8] South Korea set aside KRW 1,268.6 billion for sewage treatment plant installation in the 2026 budget plan.[2] Each commissioned line becomes a polymer tender that renews for the life of the plant.
Feedstock Swings and Public Budgets Squeeze Margins
Feedstock costs for producers of water treatment polymers change faster than annual contracts can follow. SNF said in May 2026 that the company was watching raw material markets after the Strait of Hormuz closure and had raised selling prices in all regions.[1] Congress set the FY2026 Clean Water SRF base 54% below the FY2025 level.[5] Buyers on fixed tenders will see surcharges at renewal, and smaller utilities may trim dose rates to stay within budget.
Reuse Plants and Asian Sewage Works Add Accounts
Adoption potential for water treatment polymers is highest at plants that recycle effluent. Veralto reported strong demand across industrial water treatment in the second quarter of 2026 and raised full-year core sales growth guidance to 4% to 4.5%.[3] Industrial reuse needs low-turbidity feed ahead of membranes, and suppliers with jar-testing teams on site will secure those accounts.
Which country CAGRs are profiled in the water treatment polymers market?
Table 7: Country CAGR Comparison for the Water Treatment Polymers Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 7.9% |
| China | 7.3% |
| South Korea | 6.5% |
| Germany | 6.4% |
| United Kingdom | 6.3% |
| United States | 6.2% |
| Japan | 6.1% |
How do country-level CAGRs compare in the water treatment polymers market?
Cities along the Ganga basin in India are commissioning sewage plants faster than any other profiled market, with 25 plants started in 2025.[8] Per FMI's country model, India is projected at 7.9%, and China follows at 7.3% as municipal sewer networks extend. South Korea, at 6.5%, is the one high-income market above the 6.4% global rate, helped by the largest water budget on file. Germany matches the global figure as large works prepare fourth-stage treatment, and the United Kingdom, at 6.3%, is a fraction lower. The United States holds 6.2% on a large installed base with less federal funding, and Japan is last in the country ranking at 6.1%.
- Sewage plants commissioned along the Ganga basin carry polymer orders in India.
- Wider sewer networks in Chinese cities send more flow to treatment works.
- New sewage plants funded in the 2026 budget add dewatering lines in South Korea.
- German utilities are planning fourth-stage treatment ahead of the 2027 transposition date.
- Storm overflow upgrades push more storm flow through British works.
- Industrial water treatment programmes offset tighter federal plant funding in the United States.
- Sewer pipe repair comes ahead of new treatment plants in Japan.
Full report country CAGRs cover: the seven rates in the table, led by India at 7.9% and ending with Japan at 6.1%, along with every other country in the standard regional list.
Country-wise Analysis
India Water Treatment Polymers Market Outlook (2026 to 2036)
Demand for water treatment polymers in India is predicted to grow by 7.9% on a CAGR basis, the top rate in this report. The National Mission for Clean Ganga had 6,610 MLD of capacity sanctioned across 219 sewerage projects and commissioned common effluent treatment plants at Mathura and Jajmau.[8] Buckman and Atul agreed in August 2025 to form a joint venture that will make water treatment chemicals in India for domestic demand and import substitution.[9] Each sewage plant buys coagulant aid for clarifiers and cationic polymer for sludge presses, and local production will shorten supply to those plants.
Key takeaway: Ganga basin plants and local production anchor polymer growth in India.
China Water Treatment Polymers Market Outlook (2026 to 2036)
FMI analysts expect China to grow at 7.3%, as city sewer extensions raise flow at existing works. SNF's Asia Pacific business rose to 25.9% of group sales in the first quarter of 2026, from 24.3% in the first quarter of 2025.[1] Domestic polyacrylamide makers supply most commodity grades in China, so imported products compete on specialty cationic emulsions.
Key takeaway: Network growth and local supply shape China.
South Korea Water Treatment Polymers Market Outlook (2026 to 2036)
South Korean utilities are funding new plants, and the national CAGR is forecast at 6.5%. The 2026 budget plan includes KRW 203.7 billion for algal bloom pollution source management, 19.6% more than before, and KRW 1.1 billion for PFAS monitoring at water treatment plants.[2] Nutrient control upstream of drinking water intakes adds coagulation steps at river-fed plants.
Key takeaway: Budget-backed plant building keeps South Korea above the global rate.
Germany Water Treatment Polymers Market Outlook (2026 to 2036)
Germany is forecast to grow at 6.4%, in step with the water treatment polymers market. The Landkreistag Baden-Württemberg expects about EUR 9 billion of fourth-stage treatment costs in Germany by 2045 and wants producers of micropollutants to pay, under an EU directive due for transposition by 31 July 2027.[10] Powdered activated carbon stages need polymer-aided settling and filtration to keep carbon fines out of the effluent.
Key takeaway: Fourth-stage planning holds Germany level with the global rate.
United Kingdom Water Treatment Polymers Market Outlook (2026 to 2036)
Storm overflow work gives the United Kingdom a 6.3% CAGR, per FMI's country model. The Environment Agency linked the 35% fall in 2025 spill events largely to drier weather and pointed to GBP 104 billion of water infrastructure investment over five years.[4] Larger storm tanks and treatment upgrades will send more flow through clarifiers at English works.
Key takeaway: Overflow upgrades sustain dosing in the United Kingdom.
United States Water Treatment Polymers Market Outlook (2026 to 2036)
Demand for water treatment polymers in the United States is projected to increase at a 6.2% CAGR. Congress cut the FY2026 Clean Water SRF base to USD 746.1 million and added USD 892.8 million of community project funding.[5] Veralto described municipal demand for water analytics as steady in the second quarter of 2026.[3] Utilities will pay for polymer from operating budgets and look for lower dose rates per million gallons.
Key takeaway: Operating budgets set the pace in the United States.
Japan Water Treatment Polymers Market Outlook (2026 to 2036)
Japan has the lowest profiled rate, 6.1% in FMI's projection. The infrastructure ministry found 748 km of large sewer pipe in need of countermeasures and asked 383 municipalities and operators to act quickly, Jiji Press reported in April 2026.[6] Repair crews and budgets will go to pipes first, and plant polymer volumes will follow a shrinking population.
Key takeaway: Pipe repair ahead of plant growth slows Japan.
Who are the notable companies in the water treatment polymers market?
SNF, Kemira, Solenis, Ecolab, Veolia, Kurita Water Industries, Veralto, Buckman, BASF, Dow, Thermax, Chembond Chemicals and Aries Chemical are the profiled companies.
FMI's company coverage spans polyacrylamide producers, water service groups and specialty chemical makers. SNF, a polyacrylamide specialist, reported first-quarter 2026 sales of EUR 1,198 million, 2.3% lower in euros as currency and price offset volume gains.[1] Water Quality core sales at Veralto rose 5.7% in the June quarter, and reported segment sales rose 10.1%.[3] Kemira, Solenis, Ecolab, Veolia, Kurita Water Industries, Buckman, BASF, Dow, Thermax, Chembond Chemicals and Aries Chemical complete the group.
- Polyacrylamide producers: SNF, Kemira and Solenis.
- Field dosing and analytics providers: Buckman, Kurita Water Industries, Veolia, Ecolab and Veralto.
- Specialty and regional chemical makers: BASF, Dow, Thermax, Chembond Chemicals and Aries Chemical.
Competitive Benchmarking: Water Treatment Polymers Market
Table 8: Competitive Benchmarking for the Water Treatment Polymers Market (qualitative documentation ratings), 2026
| Company | Polyacrylamide Range | Service Coverage | Regional Capacity | Recency |
|---|---|---|---|---|
| SNF | High | Medium | High | High |
| Veralto | Low | High | Medium | High |
| Kemira | High | Medium | High | Medium |
| Solenis | High | High | Medium | Medium |
| Buckman | Medium | High | Medium | High |
Each rating draws on dated 2025 and 2026 disclosures and published product ranges, and none implies market share.
Key Developments in the Water Treatment Polymers Market
- On 7 August 2026, NBM&CW reported that Namami Gange had created 4,263 MLD of sewage treatment capacity by June 2026.[8]
- On 28 July 2026, Veralto raised full-year 2026 core sales growth guidance to 4% to 4.5%.[3]
- On 24 May 2026, SNF Oman announced more than USD 100 million of polymer investment in Salalah.[7]
- On 20 May 2026, SNF reported EBITDA of EUR 206 million for January to March, a 17.2% margin.[1]
- On 19 May 2026, the Landkreistag Baden-Württemberg called for producer responsibility to fund fourth-stage treatment.[10]
- On 21 April 2026, Japan's infrastructure ministry flagged 748 km of sewer pipe for countermeasures.[6]
- On 26 March 2026, the Environment Agency reported 291,492 storm overflow spill events in England for 2025.[4]
- On 19 March 2026, the Congressional Research Service listed a FY2026 Clean Water SRF base of USD 746.1 million.[5]
Key Players in the Water Treatment Polymers Market
Polyacrylamide Producers
- SNF
- Kemira
- Solenis
Field Dosing and Analytics Providers
- Buckman
- Kurita Water Industries
- Veolia
- Ecolab
- Veralto
Specialty and Regional Chemical Makers
- BASF
- Dow
- Thermax
- Chembond Chemicals
- Aries Chemical
Water Treatment Polymers Market - Report Scope
Table 9: Report Scope for the Water Treatment Polymers Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; application; end use; region |
| Quantitative units | USD billion |
| Market definition | Synthetic polymers dosed into drinking water, wastewater, process water and sludge to coagulate, flocculate, disperse or condition solids, covering polyacrylamides, polyacrylates, quaternary ammonium polymers and polyamines. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | SNF, Kemira, Solenis, Ecolab, Veolia, Kurita Water Industries, Veralto, Buckman, BASF, Dow, Thermax, Chembond Chemicals, Aries Chemical |
| Forecast period | 2026 to 2036 |
Water Treatment Polymers Market - Research Methodology
Table 10: Research Methodology for the Water Treatment Polymers Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Polymer producer results, water service company filings, government budget and regulator releases and trade press from May 2025 onward. |
| Desk Research | Desk research covers polyacrylamide supply, sewage plant building, storm overflow upgrades, sewer renewal and public water funding. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 52.1 billion and the 6.4% CAGR for 2026 to 2036. |
| Data Validation | Volume, budget and capacity figures were checked against the release, ministry document or article that first published them. |
Water Treatment Polymers Market by Segments
Water Treatment Polymers Market segmented by Product Type:
- Polyacrylamides
- Polyacrylates
- Quaternary Ammonium Polymers
- Polyamines
Water Treatment Polymers Market segmented by Application:
- Preliminary Treatment
- Water Treatment
- Sludge Treatment
Water Treatment Polymers Market segmented by End Use:
- Residential Buildings
- Commercial Buildings
- Municipality
- Industrial
Water Treatment Polymers Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] SNF Group. (2026, May 20). SNF Group First Quarter 2026 Press Release. https://www.snf.com/wp-content/uploads/2026/06/SNF-Group-First-Quarter-2026-Press-Release.pdf
- [2] Asia Economy. (2025, September 2). Ministry of Environment proposes 15.9 trillion won budget for next year; water management budget 7.3 trillion won, largest ever. https://view.asiae.co.kr/article/2025090211244387312
- [3] Veralto Corporation. (2026, July 28). Veralto Reports Second Quarter 2026 Results (Form 8-K, Exhibit 99.1). https://www.sec.gov/Archives/edgar/data/0001967680/000196768026000043/vlto-20260728xex991.htm
- [4] Environment Agency, Department for Environment, Food and Rural Affairs. (2026, March 26). Fewer and shorter storm overflow spills in 2025, new monitoring data shows. https://www.gov.uk/government/news/fewer-and-shorter-storm-overflow-spills-in-2025-new-monitoring-data-shows
- [5] Congressional Research Service. (2026, March 19). FY2026 Appropriations for U.S. Environmental Protection Agency (EPA) Water Infrastructure Programs (IF13177). https://www.everycrsreport.com/files/2026-03-19_IF13177_2f2cb0f041c5ca151414082c02ef89d673dedea0.html
- [6] Nippon.com (Jiji Press). (2026, April 21). 748 km of Japan's Sewers Classified as Requiring Action. https://www.nippon.com/en/news/yjj2026042100297/
- [7] Muscat Daily. (2026, May 24). SNF Oman announces major investment in polymer manufacturing plant in Salalah. https://www.muscatdaily.com/2026/05/24/snf-oman-announces-major-investment-in-polymer-manufacturing-plain-in-salalah/
- [8] NBM&CW. (2026, August 7). Namami Gange Creates 4,263 MLD Sewage Treatment Capacity; 25 STPs Commissioned in 2025. https://www.nbmcw.com/news/infra-development/namami-gange-creates-4-263-mld-sewage-treatment-capacity-25-stps-commissioned-in-2025.html
- [9] Buckman. (2025, August 12). Buckman and Atul Announce Joint Venture to Provide Advanced Water Treatment Solutions in India and Sri Lanka. https://www.buckman.com/news/buckman-and-atul-joint-venture/
- [10] Landkreistag Baden-Württemberg. (2026, May 19). Herstellerverantwortung in der Kommunalabwasserrichtlinie darf nicht zulasten der Bürgerinnen und Bürger verwässert werden (Medieninformation). https://www.landkreistag-bw.de/fileadmin/user_upload/PDFs/Aktuell/Medieninformationen/MI_2026-05-19.pdf
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the water treatment polymers market during 2026?
- What market size is projected by 2036?
- Which product type holds notable share?
- Which application holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Polyacrylamides
- Polyacrylates
- Quaternary Ammonium Polymers
- Polyamines
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Preliminary Treatment
- Water Treatment
- Sludge Treatment
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Residential Buildings
- Commercial Buildings
- Municipality
- Industrial
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Application
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By End Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Application
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By End Use
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Application
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By End Use
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Application
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By End Use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Application
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By End Use
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Application
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By End Use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Application
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By End Use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Application
- By End Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- SNF
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Veralto
- Kemira
- Solenis
- Buckman
- Kurita Water Industries
- Veolia
- Ecolab
- BASF
- Dow
- Thermax
- Chembond Chemicals
- Aries Chemical
- SNF
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by End Use, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Application
- Figure 9: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End Use
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Product Type
- Figure 26: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Application
- Figure 29: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by End Use
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Product Type
- Figure 36: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Application
- Figure 39: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by End Use
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Product Type
- Figure 46: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Application
- Figure 49: Western Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by End Use
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Application
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by End Use
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Product Type
- Figure 66: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Application
- Figure 69: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by End Use
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by End Use
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by End Use
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the water treatment polymers market expected in 2026?
FMI puts the water treatment polymers market at USD 52.1 billion in 2026, up from USD 49.0 billion in 2025. By 2036, sales of water treatment polymers are projected to reach USD 96.9 billion.
What CAGR is projected for the water treatment polymers market through 2036?
The water treatment polymers market is expected to grow at a 6.4% CAGR from 2026 to 2036. New sewage capacity, storm flow treatment and industrial reuse carry that growth.
Which product type holds a notable market share in 2026?
Polyacrylamides are expected to lead with 47.6% share in 2026. Polyacrylates follow at an estimated 21.8%.
Which application holds a notable market share in 2026?
Water treatment is likely to lead with 44.7% share in 2026. Sludge treatment is estimated at 36.2%.
Which country has a notable expansion outlook through 2036?
India is first in FMI's country table with a 7.9% CAGR. China follows at 7.3%.
Who are the key companies in the water treatment polymers market?
SNF, Kemira and Solenis lead polyacrylamide supply, and Ecolab, Veolia, Kurita Water Industries, Veralto and Buckman run treatment programmes. BASF, Dow, Thermax, Chembond Chemicals and Aries Chemical complete the profiled companies.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
