

- Market Size (2026)
- USD 8075.5 Mn
- Forecast (2036)
- USD 14058.7 Mn
- CAGR (2026 to 2036)
- 5.7%
How big is Prosthetics and Orthotics Market in 2026?
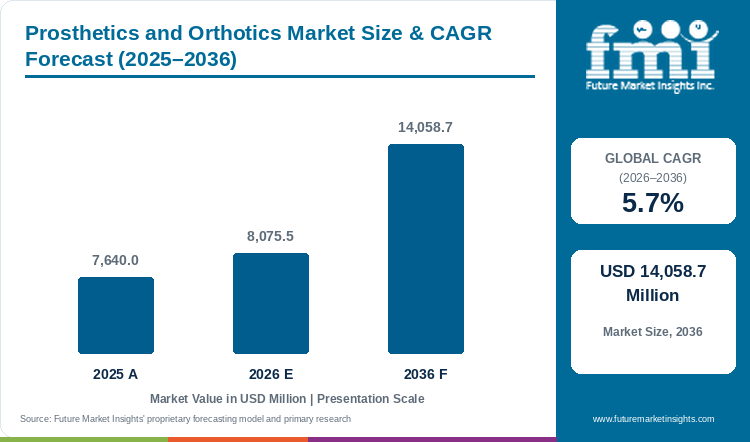
Demand is projected to expand at 5.7% CAGR from 2026 to 2036. Market value rises from USD 7,640 million in 2025 to USD 8,075.53 million in 2026 and USD 14,058.71 million by 2036.
The market is estimated at USD 8075.53 million in 2026 and projected to reach USD 14058.7 million by 2036, at a CAGR of 5.7% from 2026 to 2036. Prostheses replace a missing body part, while orthoses support or influence the function of an existing limb or body region, giving the market a broad set of clinical and everyday uses. [1] Within orthopedic prosthetics and related services, the selected component is only one part of a fitted device that must suit the individual. Orthotics hold the larger profiled type share, while prosthetic clinics remain an important setting for assessment, fitting and continuing support. WHO emphasizes access to qualified personnel and links with rehabilitation, and NHS England's current service specification places prosthetic care within an all-age rehabilitation pathway. [1][2] US coverage guidance similarly connects lower-limb device supply with clinical and functional documentation. [3] These conditions make the care service commercially significant alongside the product. Advanced technologies, including microprocessor-controlled orthoses, add options for appropriate users, while comfort, training and the ability to return for adjustments influence daily use. [4] Growth therefore follows both the need for mobility support and the capacity of services to provide suitable devices and maintain them as individual requirements change.
Key Market Trends & Insights
- Device selection increasingly brings product capabilities together with specialist assessment and follow-up, reflecting the importance of fitting within a usable mobility solution. [1][2]
- Microprocessor-controlled orthoses add technology options to the support provided by a brace, with clinical suitability and training remaining relevant to individual use. [4]
- Published service frameworks emphasize continuing access and qualified personnel, making the rehabilitation pathway important alongside the availability of components and materials. [1][2]
Regional Highlights
- US lower-limb prosthetic supply is linked to clinical and functional documentation, giving the assessment and fitting service a defined role in coverage. [3]
- NHS England’s updated all-age specification places prosthetic provision within rehabilitation, with assessment and continuing care relevant to the service pathway. [2]
- Japan and South Korea combine aging-related support needs with interest in advanced devices, creating demand across orthotic and prosthetic applications.
Market Size & Forecast
Table 1: Market Size and Forecast for Prosthetics and Orthotics Market (USD million and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 market value | USD 7,640 million |
| 2026 market value | USD 8,075.53 million |
| 2036 market value | USD 14,058.71 million |
| CAGR 2026 to 2036 | 5.7% |
| Revenue increase 2026 to 2036 | USD 5,983.18 million |
| Market expansion 2026 to 2036 | 1.74 times |
The projected 5.7% CAGR from 2026 to 2036 reflects continuing needs for mobility, physical support and devices adapted to individual function. Access to physiotherapy equipment can support the rehabilitation work surrounding a fitted mobility device, alongside the clinical assessment and training required for use. Suppliers can expand through suitable components and constructive relationships with fitting services, with access to later adjustments influencing whether the device remains useful as the person's activities or physical condition change over time. [1][2][3][4]
How do care pathways influence the value of prosthetic and orthotic devices?
WHO describes prosthetics and orthotics as services requiring qualified teams and continuing access alongside suitable products. NHS England's current specification provides an all-age rehabilitation framework, while CMS guidance connects lower-limb prosthetic coverage with clinical and functional requirements. These sources explain why assessment, fitting and follow-up are commercially significant alongside the device's technical characteristics. [1][2][3]
Table 2: Industry evidence relevant to the prosthetics and orthotics market
| Indicator | Data point or observation | Market relevance | Source |
|---|---|---|---|
| Service provision | WHO links devices with qualified personnel and continuing access | Fitting and follow-up affect practical availability | [1] |
| English care pathway | The May 2025 specification covers all-age amputee rehabilitation | Product provision sits within a continuing clinical service | [2] |
| US coverage | CMS guidance links supply with clinical need and functional assessment | Documentation and prescription influence purchasing | [3] |
Analyst Perspective
"Manufacturers with stronger clinic integration are expected to gain advantage as rehabilitation moves toward outcome-based care."
- Sudip Saha, Principal Consultant for Healthcare, FMI
How is the Prosthetics and Orthotics Market segmented?
The market is segmented by Type, Selected End-User Setting, and Region.
The market covers manufacturer revenue from prosthetic and orthotic devices and components, with separately billed clinical assessment, fitting, rehabilitation and follow-up services excluded. Prosthetics and orthotics form the two product types, while the selected end-user setting profile measures purchases associated with prosthetic clinics against total global device-market revenue. Clinical services remain relevant to product selection and continuing use without being added to device revenue.
Why does the Orthotics segment hold a strong position within the type category?
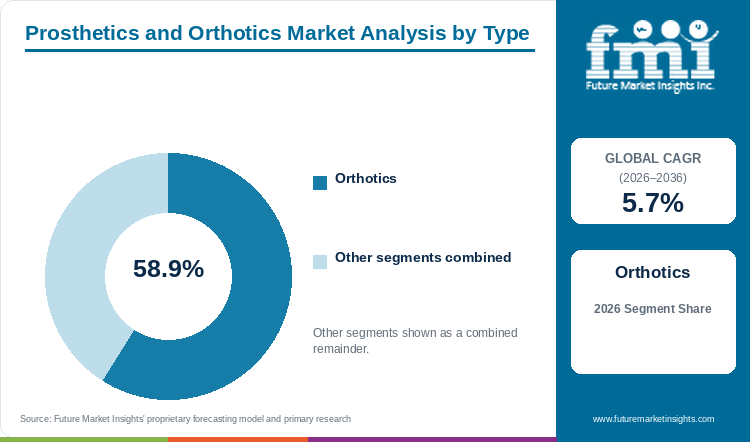
The Orthotics segment is projected to account for 58.9% of type demand in 2026.
Table 3: Type Share for Prosthetics and Orthotics Market (percentage share), 2026
| Type | Estimated share (2026) |
|---|---|
| Orthotics | 58.9% |
| Prosthetics | 41.1% |
| Total | 100.0% |
Table 4: Segment Position and Market Growth for Prosthetics and Orthotics Market, 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.7% |
| Profiled type segment | Orthotics |
Orthotics address a wide range of support needs through braces, splints and related devices that influence movement or stabilize a body region. This breadth supports the segment's projected type share, because demand can arise from several musculoskeletal and neurological conditions rather than from limb loss alone. [1] The selected product needs to suit the person's function, comfort and ordinary activities, with fitting and later review important to practical use. Technology can extend the available options, as illustrated by a microprocessor-controlled orthosis such as C-Brace, while the appropriate choice remains individual. [4] Demand consequently depends on clinical access and the range of products a service can provide, with replacement and adjustment forming part of continuing care as needs change over time. [1]
- The Orthotics segment is projected to account for 58.9% of type demand in 2026, reflecting the broad use of supportive devices across musculoskeletal and neurological conditions affecting movement and stability.
- Clinical assessment, fitting and review determine how a brace or other orthosis supports the person’s activities within their everyday environment. [1][4]
Why do prosthetic clinics account for a substantial share of market revenue?
Prosthetic clinics are projected to account for 42.3% of total global prosthetics and orthotics market revenue in 2026.
Table 5: Selected End-User Setting Share for Prosthetics and Orthotics Market (percentage share), 2026
| Selected End-User Setting | Estimated share of total market revenue (2026) |
|---|---|
| Prosthetic Clinics | 42.3% |
| Other purchasing settings | 57.7% |
| Total | 100.0% |
Prosthetic clinics bring specialist assessment and fitting together around a person who needs a device adapted to their body and activities. Their projected share of total global prosthetics and orthotics market revenue reflects the purchases associated with that setting, including the selection of components, socket or interface requirements and the training needed for practical use. A manufacturer's product specification becomes useful through this clinical process, because a technically capable component still needs to work within a complete fitted prosthesis. WHO emphasizes qualified personnel and continuing service access, while NHS England places prosthetic provision within rehabilitation. [1][2] Clinics therefore influence both the initial purchase and later adjustments, giving suppliers a reason to support clinical teams with suitable product options and the information required to maintain the device as the user's needs evolve. [3][4]
- Prosthetic clinics are projected to account for 42.3% of total global prosthetics and orthotics market revenue in 2026, as specialist teams connect device and component selection with individual fitting requirements.
- Continuing access to the clinic allows adjustments and reassessment when fit, activity or physical condition changes after the initial device is supplied. [1][2]
What are the drivers, restraints, and opportunities in the Prosthetics and Orthotics Market?
A fitted device needs to remain useful as the person’s activities, fit or physical condition change, making later access to skilled care part of its practical value. Manufacturers and clinical services therefore share an ongoing relationship around components, adjustments and training, with service capacity influencing how widely suitable technology can be provided and maintained. [1][2][3][4]
Driver
Mobility and physical-support needs arising from long-term conditions, injury and limb loss sustain demand for devices adapted to individual function. [1] Orthopedic prosthetic accessories contribute to the complete fitted device through interfaces and components that need to suit the person’s body and activities. The market’s growth depends on services that can connect those product options with clinical assessment and maintain access to fitting, training and later adjustments. Qualified staff and continuing care therefore influence how effectively available technology can address the demand for mobility and support. [2][3][4]
Restraint
The cost of a device is accompanied by the need for qualified assessment, fitting and continuing support, making access a service-capacity issue as well as a purchasing issue. WHO identifies workforce and financing barriers within prosthetic and orthotic provision, which can limit the number of people receiving suitable care. [1] Advanced components can add further training and maintenance requirements, so a service must consider whether it can sustain the selected device over the person's period of use. [2][3][4]
Opportunity
Manufacturers can improve the connection between product options and clinical fitting, helping services provide devices matched to the person's activities and ability to use them. [1][4] Orthopedic braces and supports need suitable geometry and comfort as part of that fitting process, creating a role for practical customization. Opportunities also include clearer component information and support for follow-up, allowing clinics to maintain a device when the user's requirements change throughout the period of care. [2]
Which country CAGRs are profiled in the Prosthetics and Orthotics Market?
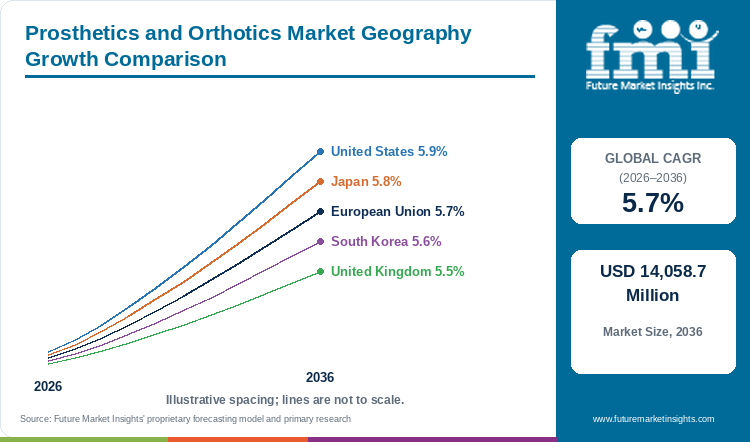
Table 6: Country CAGR Comparison for Prosthetics and Orthotics Market (CAGR percentage), 2026 to 2036
| Country | CAGR | Forecast period |
|---|---|---|
| United States | 5.9% | 2026 to 2036 |
| United Kingdom | 5.5% | 2026 to 2036 |
| European Union | 5.7% | 2026 to 2036 |
| Japan | 5.8% | 2026 to 2036 |
| South Korea | 5.6% | 2026 to 2036 |
Country-wise Analysis
United States Prosthetics and Orthotics Market Outlook (2026 to 2036)
US lower-limb prosthetic purchasing is influenced by Medicare's coverage and documentation requirements, which connect the selected device with the patient's clinical need and functional assessment. [3] This gives the fitting service an important role in describing what a person needs to do and in maintaining the records supporting the prescription. The market is projected at 5.9% CAGR from 2026 to 2036. Advanced components can add options, but the complete prosthesis still needs a suitable fit and alignment, followed by training and review as the person's needs change. [1][4] Manufacturers and clinics consequently operate within the same care pathway, with the commercial relationship extending beyond the initial component purchase to the expertise and follow-up needed for everyday use.
United Kingdom Prosthetics and Orthotics Market Outlook (2026 to 2036)
NHS England's May 2025 service specification places prosthetics within an all-age amputee rehabilitation service, giving the UK profile a clear emphasis on assessment, function and continuing care. [2] Children and adults can need different forms of support, while a change in activity, fit or physical condition can require another review. Forecast demand expands at 5.5% CAGR from 2026 to 2036. For suppliers, the relevant purchasing context therefore includes the clinical team and the service that will support the person after fitting, rather than the component alone. [1] A prosthesis or orthosis becomes useful through its relationship with the individual's daily tasks, making suitable product options, access to fitting expertise and a practical route to follow-up important throughout the care pathway.
European Union Prosthetics and Orthotics Market Outlook (2026 to 2036)
The European Union profile covers a group of markets with established rehabilitation and specialist device-manufacturing capabilities, while the route to a fitted product varies across local health services. Orthotic bracing and prosthetic components address different mobility and functional needs, making clinical assessment central to the selection. The combined-market outlook projects 5.7% CAGR from 2026 to 2036. Microprocessor-controlled orthoses such as Ottobock's C-Brace illustrate one technology option within that wider product field, with suitability depending on the person's requirements and the fitting service around the device. [4] WHO's service framework reinforces the importance of qualified personnel and continuing access, giving manufacturers and clinics a shared task in supporting use beyond the initial supply of a product. [1]
Japan Prosthetics and Orthotics Market Outlook (2026 to 2036)
Japan's older population and continuing need for musculoskeletal support create a demand setting in which ease of use and everyday mobility are important to orthotic selection. A device may need to fit an established routine at home and in the community, with comfort and the ability to attend follow-up affecting its practical use. The market is projected at 5.8% CAGR from 2026 to 2036. Prosthetic users can have different requirements, including component selection and training matched to their activities, so the clinical service needs a range of suitable options. [1] Technology adds choices, but the relationship between the person, the fitted device and continuing rehabilitation remains central to purchasing, including when a changing condition requires adjustment or replacement. [4]
South Korea Prosthetics and Orthotics Market Outlook (2026 to 2036)
South Korean demand combines interest in advanced mobility devices with a broader requirement for orthotic support as long-term health conditions affect movement. That combination creates different purchasing tasks, from selecting a brace for a defined support need to fitting a prosthesis that a person can use in daily life. The projected outlook is 5.6% CAGR from 2026 to 2036. Components with sensors or powered functions can extend the options available to a clinical team, while assessment and training determine which option is appropriate for an individual. [1][4] Suppliers consequently need to work with fitting and rehabilitation services that can translate product capabilities into a usable device, with adjustment and follow-up remaining relevant after the initial purchase.
Who are the notable companies in the Prosthetics and Orthotics Market?
Ottobock; Össur; Blatchford; Hanger; Bauerfeind
Ottobock, Össur, Blatchford and Bauerfeind represent different product portfolios across prosthetic components and orthotic support, while Hanger adds a clinical-service role to the comparison. [4] These participants occupy related positions along the route from component supply to a fitted device. Buyers can therefore compare the relevant product function and the support available to the clinical team, with service access and suitability for the individual influencing the practical use of the technology. [1][2][3]
Competitive Benchmarking: Prosthetics and Orthotics Market
Table 7: Competitive positioning for the prosthetics and orthotics market
| Company | Positioning | Commercial distinction |
|---|---|---|
| Ottobock | Prosthetic and orthotic technologies | C-Brace illustrates its microprocessor-controlled orthotic offering alongside a wider mobility-device portfolio. [4] |
| Össur | Prosthetic components and bracing | Supplies prosthetic and non-invasive orthopedic products for mobility and support. |
| Blatchford | Lower-limb prosthetics | Provides prosthetic components and systems with associated clinical support. |
| Hanger | Clinical prosthetic and orthotic services | Delivers assessment, fitting and related patient-care services. |
| Bauerfeind | Orthotic supports and bracing | Provides orthopedic supports and orthoses for defined musculoskeletal needs. |
Key Developments in the Prosthetics and Orthotics Market
- NHS England published its revised all-age amputee rehabilitation and prosthetics specification in May 2025, replacing the earlier service framework and clarifying the care pathway. [2]
- Ottobock currently documents C-Brace as a microprocessor-controlled stance and swing phase control orthosis, illustrating continuing technology development within the orthotic category. [4]
- WHO continues to provide its prosthetics and orthotics service standards and assessment resources, emphasizing personnel, products and service provision alongside policy and financing. [1]
Key Players in the Prosthetics and Orthotics Market
Prosthetic and orthotic technologies
- Ottobock
Prosthetic components and bracing
- Össur
Lower-limb prosthetics
- Blatchford
Clinical prosthetic and orthotic services
- Hanger
Orthotic supports and bracing
- Bauerfeind
Prosthetics and Orthotics Market - Report Scope
Table 8: Report Scope for Prosthetics and Orthotics Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market | Prosthetics and Orthotics Market |
| Revenue boundary | Manufacturer revenue from prosthetic and orthotic devices and components; separately billed clinical assessment, fitting, rehabilitation and follow-up services are excluded. |
| Currency and unit | USD million; market revenue |
| Historical reference year | 2025 |
| Base year | 2026 |
| Forecast period | 2026 to 2036 |
| Segmentation | Type; selected end-user setting measured against total global market revenue |
| Country profiles | United States; United Kingdom; European Union; Japan; South Korea |
| Competitive coverage | Ottobock; Össur; Blatchford; Hanger; Bauerfeind |
| Geographic coverage | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East & Africa |
Prosthetics and Orthotics Market - Research Methodology
Table 9: Research Methodology for Prosthetics and Orthotics Market, 2026 edition
| Method | Approach |
|---|---|
| Market definition | The market covers prosthetic and orthotic products and their stated commercial care settings, distinguishing replacement of a missing body part from support of an existing one. |
| Desk research | Published FMI market data, official institutional material and direct manufacturer documentation form the research base. |
| Segment assessment | The type assessment distinguishes prosthetics and orthotics, while the prosthetic-clinic profile examines specialist fitting and continuing care as a documented end-user setting. |
| Country assessment | Country profiles examine the local care, purchasing or operating conditions relevant to demand, with growth periods aligned to 2026-2036. |
| Competitive comparison | Documented offerings and commercial roles support comparison of the named companies, without assigning unsupported performance ratings. |
| Forecast assessment | Historical reference values, forecast endpoints and growth expectations are assessed consistently within the stated currency, units and market boundary. |
Prosthetics and Orthotics Market by Segments
Prosthetics and Orthotics Market segmented by Type:
- Prosthetics
- Orthotics
Prosthetics and Orthotics Market segmented by Selected End-User Setting:
- Prosthetic Clinics
Prosthetics and Orthotics Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] World Health Organization. Accessed 15 October 2026. Strengthening prosthetics and orthotics services
- [2] NHS England. Accessed 15 October 2026. Amputee rehabilitation and prosthetics service specification
- [3] Centers for Medicare & Medicaid Services. Accessed 15 October 2026. Lower limb prostheses coverage information
- [4] Ottobock. Accessed 15 October 2026. C-Brace mechatronic orthosis
This Report Answers
- How big is the prosthetics and orthotics market in 2026?
- What is the outlook for the prosthetics and orthotics market through 2036?
- Which type category is profiled?
- Which countries are included in the growth comparison?
- Which companies are profiled?
Frequently Asked Questions
How big is the prosthetics and orthotics market in 2026?
The market is estimated at USD 8075.53 million in 2026, compared with USD 7640 million in 2025.
What is the outlook for the prosthetics and orthotics market through 2036?
Demand is projected to reach USD 14058.7 million by 2036, with 5.7% CAGR from 2026 to 2036.
Which type category is profiled?
The Orthotics segment is projected to hold 58.9% of type demand in 2026.
Which countries are included in the growth comparison?
The comparison covers United States, United Kingdom, European Union, Japan, South Korea, with country or regional-market CAGRs for 2026–2036.
Which companies are profiled?
The report profiles Ottobock, Össur, Blatchford, Hanger, Bauerfeind and compares their relevant products or services.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Type, 2026 to 2036
- Prosthetics
- Orthotics
- Y-o-Y Growth Trend Analysis By Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Type, 2026 to 2036
- Global Market Analysis and Forecast, By Selected End-User Setting, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Selected End-User Setting, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Selected End-User Setting, 2026 to 2036
- Prosthetic Clinics
- Y-o-Y Growth Trend Analysis By Selected End-User Setting, 2021 to 2025
- Absolute $ Opportunity Analysis By Selected End-User Setting, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Type
- By Selected End-User Setting
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Selected End-User Setting
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Chile
- Rest of Latin America
- By Type
- By Selected End-User Setting
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Selected End-User Setting
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Type
- By Selected End-User Setting
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Selected End-User Setting
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Type
- By Selected End-User Setting
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Selected End-User Setting
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Type
- By Selected End-User Setting
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Selected End-User Setting
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Type
- By Selected End-User Setting
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Selected End-User Setting
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Turkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Type
- By Selected End-User Setting
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Selected End-User Setting
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- European Union
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Selected End-User Setting
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Type
- By Selected End-User Setting
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Ottobock
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Össur
- Blatchford
- Hanger
- Bauerfeind
- Ottobock
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


