
- Market Size (2026)
- USD 6.5 Bn
- Forecast (2036)
- USD 15.1 Bn
- CAGR (2026 to 2036)
- 8.8%
How big is Resistant Starch Market in 2026?
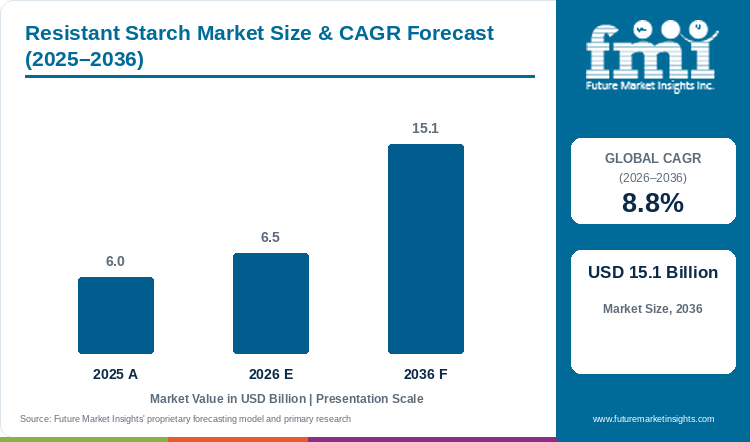
Demand for resistant starch is projected to expand at 8.8% CAGR between 2026 and 2036. Industry value grows from USD 6.0 billion in 2025 to USD 6.5 billion in 2026 and is projected to reach USD 15.1 billion by 2036.
Increasing use of fiber ingredients in regular food products is driving the resistant starch market. The market is valued at USD 6.5 billion in 2026, increasing from USD 6.0 billion in 2025, and is expected to reach USD 15.1 billion by 2036. Resistant starch is being increasingly used in bakery products, snacks, cereals, beverages, specialized nutrition and selected animal nutrition products. The ability of resistant starch to increase fiber content without making major changes in taste and texture is increasing its adoption among food manufacturers. In August 2025, Ingredion updated the HI-MAIZE 260 product data sheet with a minimum of 53% total dietary fiber on a dry basis[1]. This helps food manufacturers compare the ingredient specification with the fiber retained in the final product after heating and other processing conditions.
As per FMI’s proprietary survey, ingredient buyers sourcing resistant starch select suppliers primarily on the basis of post-processing fiber retention data rather than raw ingredient specification alone, with suppliers offering process-validated documentation holding a stronger share of trial-to-order conversions in North America and Western Europe compared with other regions. Consumption patterns diverge across key geographies, with Japan anticipated to grow at 11.4% CAGR through 2036, while the USA is projected to expand at 11.0% CAGR. This divergence is likely reinforced by the regulatory classification of specific resistant starch types as dietary fiber in these markets, which shortens the documentation pathway for qualifying formulations. Suppliers providing post-process fiber retention data and local labeling support are expected to convert trials into recurring orders at a higher rate during the forecast period.
Key Takeaways of Resistant Starch Market
- Demand is supported by reformulation that raises dietary fiber while preserving familiar texture and normal production routes.
- Based on nature, conventional material is projected to account for 80.5% in 2026, owing to established sourcing and standardized documentation.
- By type, type 3 is estimated to hold 34.9% in 2026, supported by retrogradation in familiar thermal processes.
- In 2026, cereals and grains are expected to lead source demand with 41.6% share, driven by commercial maize and wheat formats.
- Japan is projected at 11.4% CAGR through 2036, while the USA is forecast at 11.0% through separate nutrition and labeling routes.
- Notable companies in the resistant starch market include Ingredion Incorporated, Tate & Lyle PLC, Cargill, Incorporated, Archer Daniels Midland Company, Roquette Freres, MGP Ingredients, Inc., Emsland Group, AGRANA Beteiligungs AG, and KMC Amba.
Analyst Perspective
“Demand will move toward grades that retain measured fiber after processing. Over the years of analysis, I can say that suppliers with application evidence are likely to convert more trials into regular purchasing.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Resistant Starch Market segmented?
Resistant starch market is segmented by four primary commercial axes and region: nature, type, source, application, and region. Conventional material is estimated at 80.5%, type 3 at 34.9%, and cereals and grains at 41.6% in 2026.
- By nature: Conventional and Organic.
- By type: Type 3, Type 4, Type 2, Type 1, and Type 5.
- By source: Cereals & Grains, Fruits and Vegetables, and Other Crops.
- By application: Food (Bakery & Confectionery, Snacks & Convenience Food, Beverages, Sauces, Dressing and Condiment, Dairy & Frozen Desserts, Meat & Poultry Products, Baby Food), Animal Nutrition, Sports Nutrition, and Others.
- By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
What keeps Conventional central to the Nature category?
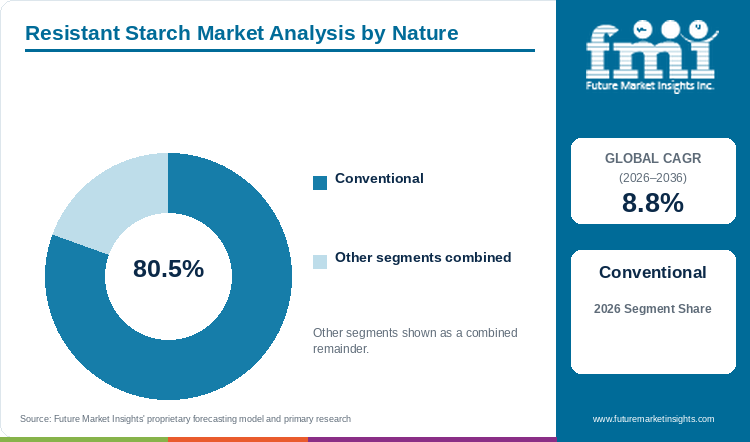
Based on nature, conventional resistant starch is projected to account for 80.5% in 2026, owing to established supply and fewer certification constraints.
Conventional resistant starch is produced through established cereal and tuber processing routes and is widely available for large volume food production. Food manufacturers generally check cost, supply availability and repeat performance before using an ingredient across several production batches. Organic resistant starch can support clean label ingredients and certified product ranges. The limited certified raw materials and chain-of-custody requirements increase the complexity. Due to easier sourcing and predictable specification, Conventional resistant starch is expected to remain the prominent nature segment during the forecast period.
- Conventional resistant starch is projected to hold 80.5% share in 2026, due to mature sourcing and lower certification requirements when compared with Organic material.
- Ingredion Incorporated offers resistant starch products such as HI-MAIZE 260, NOVELOSE 3490 and VERSAFIBE for food formulations. Availability of different commercial grades is supporting manufacturers that require established ingredients for regular production.
Why does Type 3 hold the leading position in the Type category?
By type, type 3 is estimated to hold 34.9% in 2026, supported by retrogradation during familiar cooking and cooling processes.
Type 3 resistant starch is formed when cooked starch is cooled and the gelatinized starch chains associate again. This process is also referred to as retrogradation. Type 3 is gaining preference as it can be developed through the cooking and cooling steps already used in several functional food and starch-based products.
- Type 3 is estimated to account for 34.9% share in 2026, owing to its formation through familiar cooking and cooling processes.
- A March 2024 Frontiers review identifies Type 3 as the main resistant starch form in processed food[2]. Therefore, control over the thermal process is important for maintaining Type 3 consistency.
What makes Cereals & Grains the principal Source category?
In 2026, cereals and grains are expected to lead source demand with 41.6% share, driven by commercial maize and wheat formats.
Cereals and grains have established milling, starch extraction and flour handling infrastructure, which supports their use as a source of resistant starch. High-amylose maize provides a concentrated resistant fraction, while resistant wheat starch can be used in bread and other flour-based products with limited changes in taste and texture.
- Cereals & Grains are projected to hold 41.6% share in 2026, supported by high-amylose maize and resistant wheat formats used in commercial food manufacturing.
- MGP Ingredients, Inc. offers Fibersym RW, an RS4 resistant wheat starch with at least 90% total dietary fiber on dry basis. The product shows the use of cereal-derived resistant starch in high-fiber food formulation.
Why does Food lead the Application category?
By application, food is forecast to represent 23.3% in 2026, influenced by bakery, snack, cereal, and convenience-food reformulation.
Food is the leading application as resistant starch can be used in products that consumers already purchase, including bakery, snacks, cereals and convenience food. It can replace a part of flour or conventional starch and raise fiber content without requiring a separate finished product. Neutral taste and controlled water binding are also supporting its use where manufacturers want to limit changes in texture. Cargill documents ActiStar for bakery and convenience food, while Roquette lists bakery, snacks and specialized nutrition among the applications for its high-amylose maize starch.
- Food is forecast to hold 23.3% share in 2026, owing to wider use of resistant starch in bakery, snacks, cereals and convenience-food reformulation.
- In October 2024, Archer Daniels Midland Company introduced more than 25 GLP-1 supportive food and supplement concepts, which included resistant tapioca starch[3]. This indicates the increasing use of resistant starch in targeted nutrition formulations.
What are the drivers, restraints, and opportunities in the Resistant Starch Market?
In the resistant starch market, the key driver is fiber-focused reformulation, the key restraint is process-dependent retention, and the key opportunity is novel source and application development.
- Driver: Food manufacturers can raise fiber and moderate digestible carbohydrate exposure by replacing part of conventional flour or starch with resistant starch.
- Restraint: Heating, moisture and formulation conditions can alter resistant-starch content, so buyers must validate performance after processing.
- Opportunity: Suppliers can expand revenue by tailoring resistant starch to new botanical sources, food formats and animal nutrition uses.
Fiber Targets Support Reformulation Demand
Fiber targets create a direct reformulation route. Food makers can compare raw ingredient specifications with finished-product results after baking or extrusion. The grade becomes commercially useful when measured fiber remains high enough for the intended recipe and declaration. This aligns with broader commercial adoption across personalized nutrition and fortified functional food products.
Processing Variations Delay Product Validation
Processing can change the resistant fraction before a product reaches the shelf. Heat, moisture, shear, cooling, and storage do not affect every starch type in the same way. Buyers therefore test the finished recipe rather than relying only on the incoming specification. Longer validation can delay launch and remove recipes that fail texture or fiber targets.
Novel Botanical Sources Open Formulation Opportunities
New source and application work can widen the addressable recipe set. In January 2026, Roquette published controlled-recipe research on native pea starch and glycemic response[4]. The work does not establish a resistant-starch market outcome by itself, but it supports development around slower-digesting pulse starch platforms. The analysis projects more opportunity where suppliers match source chemistry with the buyer’s process and documentation needs.
Which country CAGRs are profiled in the resistant starch market?
The profiled country CAGRs cover the 2026 to 2036 forecast period.
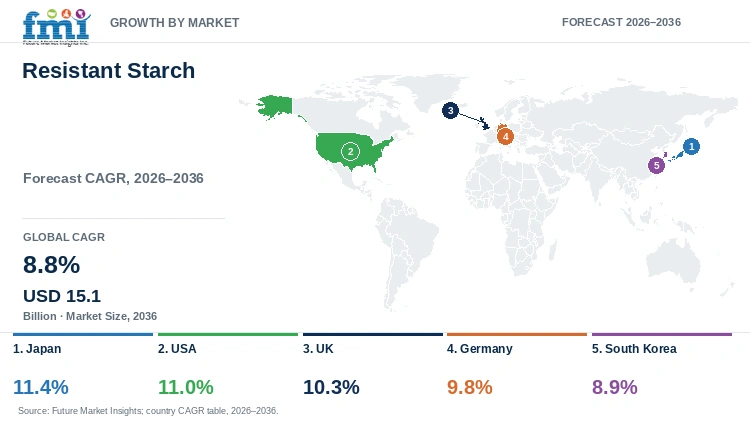
| Country | CAGR |
|---|---|
| Japan | 11.4% |
| USA | 11.0% |
| UK | 10.3% |
| Germany | 9.8% |
| South Korea | 8.9% |
How do country-level CAGRs compare in the resistant starch market?
Country outlooks remain positive but follow different commercial routes. Japan is supported by fiber-focused nutrition guidance, while the USA benefits from a more explicit labeling path for specified resistant starches.
- Japan: National nutrition guidance keeps dietary fiber adequacy visible, while local commercialization depends on formats that suit established food-processing practices.
- USA: FDA treatment of specific resistant starches as dietary fiber provides a clearer labeling route for qualified formulations.
- UK: Public dietary guidance supports fiber intake, but food makers still need acceptable texture and processing cost in mass-market products.
- Germany: A documented fiber-intake gap coexists with a strong starch-manufacturing base, supporting reformulation opportunities with tight technical specifications.
- South Korea: Recent national diet-quality data point to weak scores for mixed grains and other recommended food groups, creating a nutrition context for grain and fiber reformulation.
- Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Country-wise Analysis
- Japan's resistant starch market is anticipated to expand at 11.4% CAGR during 2026 to 2036. The Dietary Reference Intakes for Japanese, 2025, published in October 2024, includes age and sex specific fiber goals and discusses an adult ideal intake of at least 25 grams per day[5]. This guidance does not measure the demand for resistant starch, however, it keeps fiber intake visible among food manufacturers. Adoption will depend on resistant starch grades that suit Japanese food texture, taste and processing practices. Suppliers with post-process fiber data and suitable labeling records are expected to gain better opportunities in the country.
- Resistant starch demand in the USA is forecast to rise at 11.0% CAGR over the forecast period, enabled by a clearer regulatory route for specified fibers. In July 2024, FDA updated its questions and answers guidance identifying high amylose starch, or RS2, and cross-linked phosphorylated RS4 among fibers considered for the dietary-fiber definition[6]. The agency also describes enforcement discretion for qualifying declarations before rulemaking is complete. That position gives ingredient vendors a defined documentation path, but it does not remove finished-product substantiation. Formulators must confirm the exact ingredient, use level, process survival, and label treatment. The USA therefore offers a broad food-development base where regulatory clarity can shorten screening, while recipe evidence still decides whether a trial becomes a recurring order.
- The UK resistant starch market is projected to grow at 10.3% CAGR through 2036. In June 2025, the UK Office for Health Improvement and Disparities published the National Diet and Nutrition Survey report, showing that adult fiber intake remains significantly below the recommended 30 grams per day[7]. Public nutrition guidance is supporting review of fiber content in bread, cereals, snacks and convenience food. Resistant starch can be used when it raises measured fiber without creating unacceptable change in taste, dough handling or processing cost. Manufacturers also need to follow the permitted claim route for the final recipe. Suppliers offering bakery and snack application data are likely to support faster scale-up in the country.
- Germany is projected to record 9.8% CAGR during the assessment period, supported by a visible fiber intake gap and local starch processing capability. The 15th DGE-Nutrition Report published in 2024 by the German Nutrition Society reinforces an adult reference intake of at least 30 grams of fiber per day, while average population intake remains substantially lower[8]. The presence of starch manufacturers and application laboratories is supporting trials in bakery, cereals and prepared food. However, buyers will continue to compare source traceability, post-process fiber and technical support before approving an ingredient.
- Adoption of resistant starch in South Korea is estimated to expand at 8.9% CAGR through 2036, supported by attention to diet quality and grain-based foods. In August 2026, the Korea Disease Control and Prevention Agency reported an adult Diet Quality Index score of 58.6 using 2022 to 2024 data[9]. Mixed grains were among the weaker components in the agency’s assessment. The figure does not measure ingredient demand, but it gives food developers a current nutrition context for grain and fiber reformulation. Local acceptance still depends on taste, texture, preparation habits, and labeling treatment. Suppliers need to show that the selected starch survives the intended process and fits familiar products before wider purchasing develops.
Who are the notable companies in the resistant starch market?
Ingredion Incorporated, Tate & Lyle PLC, Cargill, Incorporated, Archer Daniels Midland Company, Roquette Freres, MGP Ingredients, Inc., Emsland Group, AGRANA Beteiligungs AG, , and KMC Amba are the notable companies profiled in this market.
Competition is moderately fragmented between direct resistant-starch suppliers and broader starch or fiber companies. Ingredion, ADM, Cargill, Roquette, MGP Ingredients, and KMC publish product or application evidence tied to resistant starch. Other companies compete through starch processing, fiber formulation, source access, or regional technical support. Buyers compare resistant content, botanical source, recipe performance, documentation, and supply reach before approving a grade. FMI identifies qualification evidence as the main difference between a company with general starch capability and a supplier ready for recurring resistant-starch orders.
- Direct resistant-starch ingredient platforms: Ingredion Incorporated, Cargill, Incorporated, Archer Daniels Midland Company, Roquette Freres, and MGP Ingredients, Inc.
- Broader starch and fiber formulation platforms: Tate & Lyle PLC, Emsland Group, and AGRANA Beteiligungs AG. Current resistant-starch product evidence is limited for the latter two.
Competitive Benchmarking: Resistant Starch Market
| Company | Direct RS Product Depth | Source / Type Coverage | Application & Qualification Support | Geographic Reach |
|---|---|---|---|---|
| Ingredion Incorporated | High | High | High | High |
| Tate & Lyle PLC | Low | Low | High | High |
| Cargill, Incorporated | Medium | Low | Medium | High |
| Archer Daniels Midland Company | Medium | Medium | High | High |
| Roquette Freres | Medium | Medium | Medium | High |
| MGP Ingredients, Inc. | Medium | Medium | High | Low |
| Emsland Group | Low | Low | Medium | Medium |
| AGRANA Beteiligungs AG | Low | Low | Medium | Medium |
| KMC Amba | Medium | Medium | Medium | High |
Scoring is based on publicly available product and application evidence. Direct RS Product Depth is High where several dedicated resistant starch products are documented, Medium where at least one current product is verified and Low where the current offer is limited. Source / Type Coverage considers the number of verified botanical sources or resistant starch types. Application & Qualification Support considers formulation, processing and claim related evidence. Geographic Reach considers the regions where product support and supply are documented.
Key Developments in the Resistant Starch Market
- In August 2025, Ingredion Incorporated updated the HI-MAIZE 260 product data sheet. It lists minimum 53% total dietary fiber on a dry basis and a shelf life of 24 months.
- In March 2025, KMC Amba announced a EUR 40 million (approximately USD 43 million) investment for expansion of its Brande granules factory, with completion expected in autumn 2026 [10]. The expansion supports wider potato ingredient capacity and is not limited only to ReStarch.
- In January 2026, Roquette Freres published a technical resource on native pea starch and a controlled-recipe glycemic-response study. The study supports development around slowly digestible and resistant starch fractions, but it does not establish a market share outcome.
Key Players in the Resistant Starch Market
Direct Resistant-Starch Ingredient Platforms
- Ingredion Incorporated
- Cargill, Incorporated
- Archer Daniels Midland Company
- Roquette Freres
- MGP Ingredients, Inc.
Broader Starch and Fiber Formulation Platforms
- Tate & Lyle PLC
- Emsland Group
- AGRANA Beteiligungs AG
Specialized Trait and Animal-Nutrition Positions
- KMC Amba
Resistant Starch Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Nature, Type, Source, Application |
| Quantitative Units | USD Billion |
| Market Definition | Revenue from resistant starch ingredients sold across the defined Nature, Type, Source and Application categories. Downstream finished-product revenue is excluded. Adjacent or substitute starch and fiber revenue is excluded. For blends, only attributable resistant-starch ingredient value is included when it can be separated from other components. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, UK, Germany, Japan, South Korea |
| Key Companies Profiled | Ingredion Incorporated, Tate & Lyle PLC, Cargill, Incorporated, Archer Daniels Midland Company, Roquette Freres, MGP Ingredients, Inc., Emsland Group, AGRANA Beteiligungs AG, KMC Amba |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Resistant Starch Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments and findings from primary interviews. Validation also tested whether products, services, applications and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Segment shares and forecast values are FMI proprietary analytical estimates. They are not government statistics or direct measurements of global market share.
Resistant Starch Market by Segments
Resistant Starch Market segmented by Nature:
- Conventional
- Organic
Resistant Starch Market segmented by Type:
- Type 3
- Type 4
- Type 2
- Type 1
- Type 5
Resistant Starch Market segmented by Source:
- Cereals & Grains
- Fruits and Vegetables
- Other Crops
Resistant Starch Market segmented by Application:
- Food
- Animal nutrition
- Other
- Beverages
- Snacks & Convenience Food
- Sports nutrition
- Bakery & Confectionery
- Sauces, dressing and Condiment
- Dairy & Frozen Desserts
- Meat & Poultry Products
- Baby Food
Resistant Starch Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Ingredion Incorporated. (2025, August 19). HI-MAIZE 260 resistant starch product data sheet.
- [2] Baptista, N. T. et al. (2024, March 20). Harnessing the power of resistant starch: a narrative review of its health impact and processing challenges. Frontiers in Nutrition.
- [3] Archer Daniels Midland Company. (2024, October 16). ADM Unveils GLP-1 Supportive Solutions Backed by Proprietary Insights.
- [4] Roquette Freres. (2026, January 19). Slow digestible starch in native pea starch lowers glycemic response with no adverse effects on gastrointestinal symptoms in healthy adults.
- [5] Ministry of Health, Labour and Welfare, Japan. (2024, October). Dietary Reference Intakes for Japanese, 2025.
- [6] U.S. Food and Drug Administration. (2024, July 25). Questions and Answers on Dietary Fiber.
- [7] Office for Health Improvement and Disparities. (2025, June 11). National Diet and Nutrition Survey 2019 to 2023: report.
- [8] Deutsche Gesellschaft für Ernährung. (2024). 15. DGE-Ernährungsbericht.
- [9] Korea Disease Control and Prevention Agency. (2026, August 4).
- [10] KMC Amba. (2025, March 27). Increased Customer Demand Drives EUR 40 Million Granules Investment at KMC.
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the Resistant Starch Market during 2026?
- What value is the Resistant Starch Market projected by 2036?
- Which nature segment holds notable Resistant Starch Market share?
- Which type segment holds notable Resistant Starch Market share?
- Which country has notable Resistant Starch Market growth?
- Which companies are notable in the Resistant Starch Market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Nature, 2026 to 2036
- Conventional
- Organic
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Type, 2026 to 2036
- Type 3
- Type 4
- Type 2
- Type 1
- Type 5
- Y-o-Y Growth Trend Analysis By Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Type, 2026 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source, 2026 to 2036
- Cereals & Grains
- Fruits and Vegetables
- Other Crops
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Food
- Animal nutrition
- Other
- Beverages
- Snacks & Convenience Food
- Sports nutrition
- Bakery & Confectionery
- Sauces, dressing and Condiment
- Dairy & Frozen Desserts
- Meat & Poultry Products
- Baby Food
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Nature
- By Type
- By Source
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Type
- By Source
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Nature
- By Type
- By Source
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Type
- By Source
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Nature
- By Type
- By Source
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Type
- By Source
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Nature
- By Type
- By Source
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Type
- By Source
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Nature
- By Type
- By Source
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Type
- By Source
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Nature
- By Type
- By Source
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Type
- By Source
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Nature
- By Type
- By Source
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Type
- By Source
- By Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Type
- By Source
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Type
- By Source
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Type
- By Source
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Type
- By Source
- By Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Type
- By Source
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Type
- By Source
- By Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Type
- By Source
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Type
- By Source
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Type
- By Source
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Type
- By Source
- By Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Type
- By Source
- By Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Type
- By Source
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Type
- By Source
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Type
- By Source
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Type
- By Source
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Type
- By Source
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Type
- By Source
- By Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Type
- By Source
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Type
- By Source
- By Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Nature
- By Type
- By Source
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Ingredion Incorporated
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Tate & Lyle PLC
- Cargill, Incorporated
- Archer Daniels Midland Company
- Roquette Freres
- MGP Ingredients, Inc.
- Emsland Group
- AGRANA Beteiligungs AG
- KMC Amba
- Ingredion Incorporated
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Nature
- Figure 6: Global Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Type
- Figure 9: Global Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Source
- Figure 12: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Application
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Nature
- Figure 29: North America Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Type
- Figure 32: North America Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Source
- Figure 35: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Application
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Nature
- Figure 42: Latin America Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Type
- Figure 45: Latin America Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Source
- Figure 48: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Application
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Nature
- Figure 55: Western Europe Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Type
- Figure 58: Western Europe Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by Source
- Figure 61: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Application
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Nature
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Type
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by Source
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Application
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Nature
- Figure 81: East Asia Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Type
- Figure 84: East Asia Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by Source
- Figure 87: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Application
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Nature
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Type
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by Source
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Nature
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Type
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by Source
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the Resistant Starch Market expected to be in 2026?
Future Market Insights estimates that the resistant starch market will reach USD 6.5 billion in 2026. The market is projected to expand further and reach USD 15.1 billion by 2036.
What CAGR is forecast for the Resistant Starch Market through 2036?
As per FMI, the resistant starch market is projected to grow at an 8.8% CAGR from 2026 to 2036. Growth is supported by fiber-focused reformulation and broader use in food and nutrition.
Which nature segment holds a notable resistant starch demand share in 2026?
Future Market Insights projects conventional resistant starch to hold 80.5% of nature demand in 2026. The segment benefits from established supply, mature sourcing, and lower certification requirements compared with organic material.
Which type segment holds a notable resistant starch share in 2026?
FMI finds that type 3 will hold 34.9% of type demand in 2026. Demand is supported by retrogradation during familiar cooking and cooling processes.
Which country has a notable resistant starch expansion outlook during the forecast period?
Future Market Insights predicts Japan to expand at an 11.4% CAGR during the 2026 to 2036 assessment period. Growth is supported by fiber-focused nutrition guidance and demand for documented formulation performance.
Which companies are active in the Resistant Starch Market during 2026?
As per FMI analysis, notable companies include Ingredion Incorporated, Tate & Lyle PLC, Cargill, ADM, Roquette Freres, MGP Ingredients, Emsland Group, AGRANA, Arcadia Biosciences, and KMC Amba. These companies are focusing on resistant-starch products, application support, source platforms, and regional supply.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
