
- Market Size (2026)
- USD 112.0 Bn
- Forecast (2036)
- USD 175.6 Bn
- CAGR (2026 to 2036)
- 4.6%
How big is Rigid Food Packaging Market in 2026?
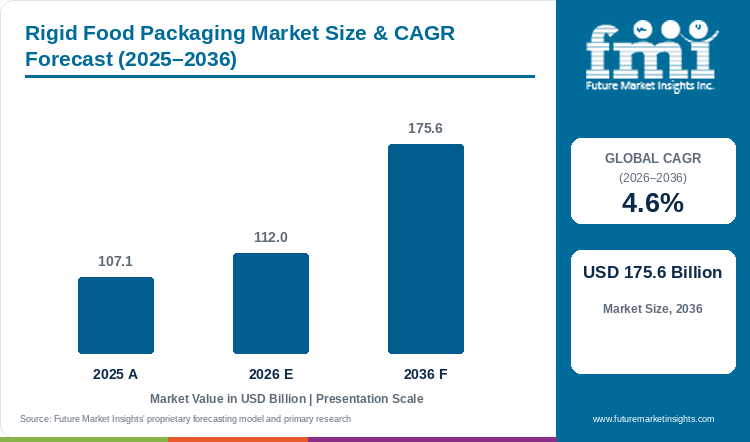
Sales in the rigid food packaging market are projected to grow at 4.6% CAGR, with the market size rising from USD 107.1 billion in 2025 to USD 112.0 billion in 2026 and reaching USD 175.6 billion by 2036.
Supermarket commissary kitchens and fresh protein packers face strict refrigerated shelf-life targets, which requires rigid food packaging that resists stacking crush loads and seals hermetically at high filling speeds. According to FMI, global rigid food packaging market valuation rises from USD 107.1 billion in 2025 to USD 112.0 billion in 2026 and is projected to reach USD 175.6 billion by 2036, expanding at a 4.6% CAGR from 2026 to 2036 and generating USD 63.6 billion in added revenue. In October 2026, the United States Food and Drug Administration updated its inventory of effective post-consumer recycled plastic food-contact notifications, reflecting expanding decontamination capacity for food-grade rPET and rPP resins [1].
Rigid Containers & Bottles hold 53.4% of packaging format demand in 2026 because precision-formed rims and rigid sidewalls support high-speed lidding film sealing and tamper-evident closures. However, issues such as food-grade recycled resin price premiums and strict plastic packaging taxes continue to challenge converter margins.
Key Market Trends & Insights
- By packaging format: Rigid Containers & Bottles led with 53.4% share in 2026, supported by high line denesting speeds, stackable retail display geometry, and hermetic heat-seal flange stability.
- By material substrate: Recycled Paperboard accounted for 43.5% in 2026, reflecting supermarket brand transitions from virgin plastic punnets to barrier-coated paperboard trays and folding meal sleeves.
- By end-use sector: Food & Beverage held 31.9% of revenue in 2026, underpinned by high-volume packaging of chilled ready-to-eat entrees, dairy yogurts, fresh meat, and takeout meal orders.
Regional Highlights
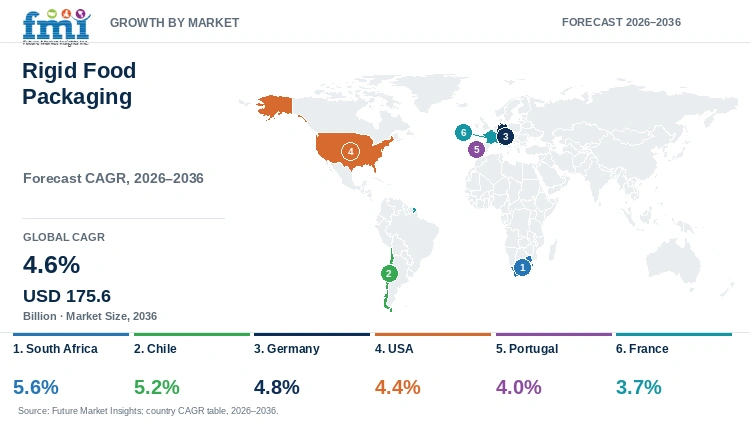
- Fastest-growing evaluated country: South Africa, at 5.6% CAGR from 2026 to 2036.
- By country: Chile at 5.2%, Germany at 4.8%, and the USA at 4.4% follow, while France records the lowest evaluated CAGR at 3.7%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Rigid Food Packaging Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 107.1 billion |
| Estimated Market Size in 2026 | USD 112.0 billion |
| Projected Market Size by 2036 | USD 175.6 billion |
| CAGR, 2026 to 2036 | 4.6% |
| Added Revenue, 2026 to 2036 | USD 63.6 billion |
Commercial conditions differ across evaluated countries owing to statutory recycled-content quotas, deposit-return infrastructure, and cold-chain retail penetration. FMI research indicates that commercial food processors are replacing multi-polymer laminates with mono-material rigid food containers and crystalline PET dual-ovenable trays and containers that move directly from blast freezers into domestic ovens. In May 2026, the European Food Safety Authority updated its safety evaluation procedures for mechanical and super-clean plastic recycling processes used in direct food-contact trays [2]. Thermoformers must therefore maintain strict batch traceability and solid-state polycondensation decontamination logs to qualify for European and North American grocery tenders.
Thermoforming Operating Metrics and Cavity Tooling Sizing
Table 2: Thermoformer Operating Metrics and Cavity Tooling Parameters for the Rigid Food Packaging Market (USD billion and operational metrics), mixed historical and forecast years from 2025 to 2036
| Operating Parameter | 2025 | 2026 | 2036 |
|---|---|---|---|
| Baseline Global Market Valuation (USD billion) | 107.1 | 112.0 | 175.6 |
| Global Rigid Food Container Output (Billion Units) | 485.0 | 508.0 | 785.0 |
| Average Thermoformer Forming Speed (Cycles per Minute) | 24.5 | 26.0 | 38.0 |
| Post-Consumer Recycled Polymer Blend Share (%) | 36.5% | 39.8% | 72.0% |
Resin Conversion Economics & Barrier Performance Sizing
Rigid food trays and tubs have gained wide adoption across meat, dairy, and convenience meal plants because dimensional stability prevents line jams on high-speed automated filling and check-weighing conveyors. Managing converter operating margins requires balancing food-grade rPET and polypropylene resin costs against cycle speed and scrap trim recovery. Replacing heavy injection-molded tubs with thin-wall pre-formed food trays reduces polymer gram weight per pack while maintaining top-load crush resistance inside supermarket display cases.
Table 3: Production Economics and Polymer Resin Processing Metrics for the Rigid Food Packaging Market (USD and percentages), mixed historical and forecast years from 2025 to 2036
| Economic Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Average Rigid Container Conversion Cost per Metric Ton (USD) | 1,420.0 | 1,385.0 | 1,110.0 |
| Polymer & Fiber Feedstock Share of Total Container Cost (%) | 56.5% | 54.8% | 42.5% |
| Decontaminated Food-Grade rPET Price Parity to Virgin (%) | 108.5% | 104.0% | 89.5% |
| Thin-Wall Injection-Molded Tub Share (%) | 28.0% | 31.5% | 63.5% |
Table 4: Facility Converting Footprint and Segment Revenue Indicators for the Rigid Food Packaging Market (USD billion, units, and percentages), mixed reporting years from 2024 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 112.0 billion | Report value |
| Automated multi-cavity thermoforming lines | 3,260 active lines | 2026 industry estimate |
| Rigid Containers & Bottles revenue, 2026 | USD 59.8 billion | 53.4% share |
| Recycled Paperboard substrate revenue, 2026 | USD 48.7 billion | 43.5% share |
Analyst Perspective
"Closed-loop tray-to-tray rPET decontamination and peelable paperboard barrier liners give food processors circular packaging that runs on existing sealing lines. Food-contact migration testing and volatile food-grade rPET flake prices still delay full conversion across cost-sensitive grocery categories."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Rigid Food Packaging Market segmented?
The rigid food packaging market is segmented by packaging format, material substrate, end-use sector, and region.
By packaging format: Rigid containers & bottles, flexible wraps & bags, and secondary bulk packaging.
By material substrate: Recycled paperboard, thermoplastic polymers, sustainable plant fibers, and specialty alloys.
By end-use sector: Food & beverage, pharmaceuticals & healthcare, personal care & homecare, and industrial manufacturing.
Why do Rigid Containers & Bottles lead the packaging format category?
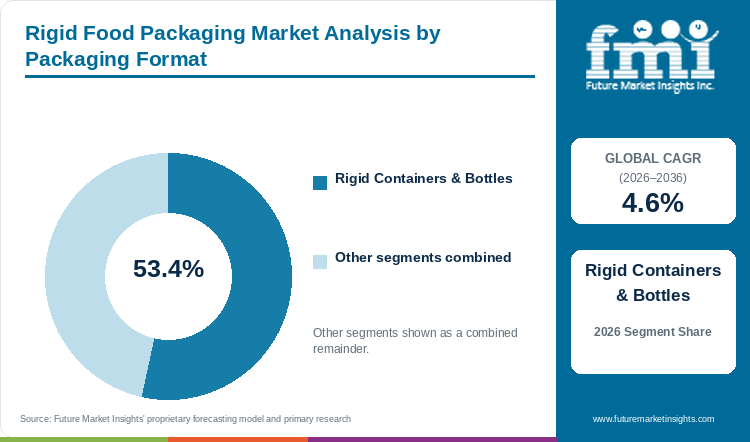
Rigid Containers & Bottles are projected to hold 53.4% of packaging format demand in 2026, facilitated by automated tray denesting.
Table 5: Packaging Format Share for the Rigid Food Packaging Market (percentage share), 2026
| Packaging Format | Share (2026) |
|---|---|
| Rigid Containers & Bottles | 53.4% |
| Other Segments Combined | 46.6%* |
| Total | 100.0% |
Table 6: Packaging Format Leadership and Market Growth for the Rigid Food Packaging Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.6% |
| Leading Segment | Rigid Containers & Bottles |
Prepared meal manufacturers, dairy plants, and meat processors rely on rigid containers and bottles because flat, dimensionally stable sealing flanges are essential for maintaining vacuum and modified-atmosphere gas flushes at 120 packs per minute. Unlike flexible pouches that can wrinkle across the seal bar or slump on chilled supermarket shelves, thermoformed barrier trays and thin-wall injection-molded tubs protect delicate food portions from mechanical crushing while offering consumers a convenient dish for microwave or oven reheating. Plant engineers verify lug denesting clearance and lidding film peel force before qualifying new container tooling.
- Rigid Containers & Bottles are projected to account for 53.4% of packaging format revenue in 2026, facilitated by hermetic flange sealing and tamper-evident rim designs.
- In June 2025, the Society of Plastics Engineers documented that servo-driven plug-assist thermoforming reduced corner wall thinning by 19% in deep-draw rigid food trays [3].
What makes Recycled Paperboard central to the material substrate category?
Recycled paperboard is expected to retain 43.5% of the material substrate category in 2026, linked to recyclable hybrid tray adoption.
Supermarket private-label brands and frozen entree producers are shifting toward recycled paperboard substrates because pressed paperboard trays and outer sleeves reduce plastic weight by up to 80% while providing a stiff, high-visibility printing surface. By laminating a micro-thin removable polymer film or applying biofilm-coated paperboard dispersion barriers onto clay-coated recycled boxboard, converters manufacture refrigerated meat, cheese, and ready-meal trays that resist grease and moisture penetration in cold storage. After consumption, shoppers peel the thin barrier liner away and place the paperboard base directly into household paper recycling streams. Converters must control board moisture content to prevent warping during tray pressing.
- Recycled paperboard is estimated to hold 43.5% of material substrate demand in 2026, supported by lower plastic packaging tax exposure and high shelf branding appeal.
- In July 2025, the European Committee for Standardization updated EN 1186 food-contact migration test protocols for barrier-lined paperboard and polymer food articles [4].
How does Food & Beverage anchor the end-use sector category?
Food & beverage is anticipated to account for 31.9% of end-use sector demand in 2026, stemming from chilled convenience meal turnover.
Chilled ready-meals, fresh cut fruit, yogurt multipacks, and portioned poultry generate the core volume base for rigid packaging because urban households increasingly favor grab-and-go retail entrees and restaurant delivery over scratch cooking. Dairy and deli brands mold polypropylene tubs decorated with fused in-mold label graphics that resist refrigeration condensate while eliminating separate adhesive label stocks. At the same time, meat and seafood packers integrate modified atmosphere packaging systems that flush rigid barrier trays with nitrogen and carbon dioxide mixes, extending retail case life from four days to over two weeks without freezing.
- Food & beverage is projected to capture 31.9% of end-use sector revenue in 2026, underpinned by modified-atmosphere meat packing and single-serve dairy consumption.
- In August 2025, the Journal of Food Engineering reported that high-barrier modified-atmosphere rigid trays reduced retail fresh meat spoilage waste by 27% across supermarket trials [5].
What are the drivers, restraints, and opportunities in the Rigid Food Packaging Market?
Chilled ready-meal demand and retail food-waste reduction targets drive high-barrier rigid tray consumption, whereas virgin plastic taxes and food-grade rPET premiums restrain converter margins, and closed-loop tray-to-tray recycling creates long-term growth opportunities.
- Driver:Expanding supermarket ready-meal counters and quick-service food delivery require crush-resistant, hermetic rigid trays that extend refrigerated shelf life.
- Restraint:Thermoformers face rising virgin plastic packaging levies and price premiums for FDA- and EFSA-compliant decontaminated post-consumer recycled resins.
- Opportunity:Investing in optical flake sorting and closed-loop tray-to-tray rPET decontamination allows converters to secure multi-year circular supply contracts with grocery chains.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Supermarket chains and central commissary kitchens are expanding chilled chef-prepared meal programs and pre-portioned protein lines to capture time-pressed urban shoppers while cutting store-level butcher and deli labor costs. Delivering a twenty-one-day refrigerated shelf life without chemical preservatives requires rigid trays with oxygen transmission rates below 0.05 cubic centimeters per pack per day. Food brands are simultaneously adopting food-grade recycled PET packaging and tamper-evident disposable food containers so that deli salads, cut fruit, and hot takeout meals arrive intact across third-party delivery networks. In September 2025, the Plastics Industry Association documented a 16% increase in North American food-contact rPET thermoforming sheet consumption [6]. Suppliers must guarantee crystal clarity and drop-impact toughness at freezer temperatures.
Risk Assessment of the Rigid Food Packaging Market: Operational and Formulation Friction
Regulatory taxes on unrecycled plastic packaging and tight supplies of food-contact approved recycled polypropylene and PET resins create substantial cost friction for rigid packaging converters. Under the European Union Packaging and Packaging Waste Regulation (EU) 2025/40, contact-sensitive PET food packaging must incorporate mandatory minimum post-consumer recycled content quotas, while multi-layer trays containing polyvinylidene chloride (PVDC) or non-separable mixed resins face severe eco-modulated EPR fee penalties [7]. Because beverage bottle manufacturers compete aggressively for clear post-consumer PET bale supplies, thermoformers often pay a premium for food-grade rPET pellets while grocery retailers resist unit tray price increases.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Rigid packaging manufacturers are unlocking structural cost and sustainability advantages by building dedicated tray-to-tray mechanical and super-clean recycling lines that process post-consumer household food trays rather than expensive beverage bottle flakes. Historically, post-consumer PET food trays went to incineration or downcycling because multi-layer barrier adhesives and colored trays contaminated bottle-to-bottle wash lines. In October 2025, the Waste and Resources Action Programme (WRAP) demonstrated that near-infrared optical flake sorting combined with hot caustic delaminating washes recovered clear food-contact rPET from mixed household tray bales at commercial yields exceeding 82% [8]. Thermoformers also mold micro-capillary dimples into mono-material meat tray bases to trap purge liquid without unrecyclable cellulose soaker pads.
Rigid Food Packaging Market by Country (2026 to 2036)
As per FMI, South Africa represents the fastest-growing rigid food packaging market among the six evaluated countries at a 5.6% CAGR from 2026 to 2036, while France records the slowest expansion at 3.7% CAGR. Across all evaluated economies, converter growth depends on how effectively plants secure food-grade decontaminated rPET supplies, engineer mono-material barrier structures, and serve modern supermarket cold-chain logistics.
Table 7: Country CAGR and Primary Growth Levers for the Rigid Food Packaging Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| South Africa | 5.6% | Rapid supermarket cold-chain expansion, urban ready-meal adoption, and ventilated export fruit punnets |
| Chile | 5.2% | High-volume fresh cherry, blueberry, and salmon fillet exports requiring rigid clamshells and MAP trays |
| Germany | 4.8% | VerpackG circularity rules driving mono-material PP and closed-loop rPET deli and meat trays |
| USA | 4.4% | Large-scale retail prepared meal consumption, FDA-cleared rPET clamshells, and takeout delivery containers |
| Portugal | 4.0% | Modernization of export seafood canning, retort barrier cups, and greenhouse berry punnet packaging |
| France | 3.7% | AGEC single-use plastic reduction mandates accelerating peelable paperboard-liner hybrid charcuterie and cheese trays |
Source: Future Market Insights analysis
South Africa Rigid Food Packaging Market Outlook (2026 to 2036)
Expanding formal supermarket cold-chain networks across urban Gauteng and the Western Cape alongside export deciduous fruit and table grape packing propel South Africa at a projected 5.6% CAGR from 2026 to 2036. Major grocery chains including Woolworths, Shoprite Checkers, and Pick n Pay have expanded chilled prepared meal counters and pre-packed butcher meats, while export packhouses require millions of ventilated rPET punnets for European supermarket buyers. In November 2025, Packaging SA reported that domestic extruders increased food-contact bottle-to-tray rPET capacity by 18% to meet statutory extended producer responsibility targets and UK/EU importer rules [9]. Because municipal power interruptions can disrupt retail refrigeration cabinets, local converters engineer high-barrier lidded trays with superior seal integrity.
Key takeaway:In South Africa, formal supermarket cold-chain growth and European export fruit compliance drive strong demand for food-grade rPET punnets and barrier meal trays.
Chile Rigid Food Packaging Market Outlook (2026 to 2036)
Export-driven counter-seasonal berry, cherry, and aquaculture salmon packing defines the rigid food packaging market in Chile, supporting a projected 5.2% CAGR through 2036. Unlike domestic-focused grocery markets, Chilean food processors ship fresh blueberries, cherries, and chilled salmon fillets across multi-week Pacific and Atlantic maritime routes where high crush strength and precise vent-hole geometry are essential to prevent condensation mold. In December 2025, OECD extended producer responsibility assessments noted that Chile Ley REP recycling quotas prompted fruit and seafood exporters to standardize clear mono-material rPET clamshells and recyclable MAP salmon trays [10]. High seasonal peak demand between November and February requires local thermoformers to maintain large buffer sheet inventories.
Key takeaway:In Chile, counter-seasonal fresh berry and salmon export logistics sustain high-volume demand for ventilated rPET clamshells and high-barrier modified-atmosphere trays.
Germany Rigid Food Packaging Market Outlook (2026 to 2036)
Strict eco-modulated Duales System recycling fees under the German Packaging Act (VerpackG) and high discount-supermarket private-label volume shape Germany, which is forecast to grow at a 4.8% CAGR from 2026 to 2036. Major retail chains such as Aldi, Lidl, Edeka, and Rewe mandate that meat, poultry, cheese, and deli salad trays achieve high recyclability ratings under Central Agency Packaging Register (ZSVR) minimum standards. In January 2026, the German Packaging Institute (dvi) documented rapid retail conversion from multi-layer PS/EVOH/PE trays to mono-material polypropylene and 80% paperboard-liner hybrid trays across chilled self-service cases [11]. Converters operating in Germany must eliminate carbon-black pigments and non-washable adhesives so trays sort cleanly in near-infrared yellow-bag recycling plants.
Key takeaway:In Germany, strict ZSVR recyclability standards and discount grocery specifications accelerate converter shifts toward mono-material PP, tray-to-tray rPET, and separable paperboard trays.
USA Rigid Food Packaging Market Outlook (2026 to 2036)
The United States anchors global rigid food packaging revenue and is projected to expand at a 4.4% CAGR through 2036, supported by high per-capita consumption of refrigerated ready-meals, club-store rotisserie and deli packs, and single-serve dairy tubs. In March 2025, the U.S. Food and Drug Administration updated its chemistry considerations guidance for post-consumer recycled plastics in food packaging, facilitating broader brand adoption of super-clean rPET thermoformed clamshells and salad bowls [12]. However, converters face diverging state-level mandates—including California SB 54 source-reduction and recyclability rules and Washington and New Jersey recycled-content minimums—alongside tight foodservice labor budgets. Domestic suppliers differentiate by engineering dual-ovenable CPET entrees and snap-lock tamper-evident delivery containers that eliminate manual shrink-banding.
Key takeaway:In the USA, high supermarket deli and ready-meal volume combined with state EPR and recycled-content laws sustain investment in FDA-cleared rPET thermoforming and dual-ovenable trays.
Portugal Rigid Food Packaging Market Outlook (2026 to 2036)
Portugal is projected to advance at a 4.0% CAGR between 2026 and 2036, driven by its export-oriented preserved seafood industry, olive oil and dairy processing, and expanding greenhouse berry cultivation in the Alentejo and Algarve regions. In March 2026, the Portuguese Packaging Association (Embaltec) reported that domestic fish processors and fresh produce cooperatives increased orders for easy-peel lacquered aluminum tins, autoclave-stable barrier plastic cups, and ventilated rPET berry punnets by 11% for intra-European export [13]. Because a large share of Portuguese packaged food is sold into French, Spanish, and British supermarket chains, local converters must certify EU 2025/40 PPWR compliance while managing high industrial electricity tariffs in thermoforming and metal-stamping plants.
Key takeaway:In Portugal, export seafood canning modernization and Southern European greenhouse fruit production support steady demand for retortable barrier containers and rPET punnets.
France Rigid Food Packaging Market Outlook (2026 to 2036)
Binding single-use plastic reduction targets under the French Anti-Waste for a Circular Economy (AGEC) law and strict ban rules on plastic packaging for unprocessed fresh fruits and vegetables under 1.5 kilograms govern France, where the market is projected to grow at a 3.7% CAGR through 2036. In April 2026, the Institut National de l Origine et de la Qualite (INAO) highlighted that French PDO cheese, charcuterie, and pâté producers increasingly adopted pressed cellulose trays with ultra-thin peelable barrier films to preserve traditional moisture and aroma profiles while cutting plastic weight [14]. Because French consumers and Citeo eco-modulation fees penalize non-recyclable polystyrene yogurt pots and PVC blisters, domestic converters are retooling lines for mono-material PET, PP, and molded fiber dairy and gastronomy packs.
Key takeaway:In France, AGEC plastic reduction mandates and Citeo eco-modulation fees compel food processors to replace legacy polystyrene pots with fiber-based hybrid trays and mono-material rPET.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Rigid Food Packaging Market?
Amcor plc, Sealed Air Corporation, Silgan Holdings Inc., Pactiv Evergreen Inc., Sonoco Products Company, Winpak Ltd., and Faerch A/S are the significant market players in this market.
FMI data suggests that competition divides between global multi-resin rigid packaging conglomerates and specialized high-barrier food tray thermoformers. Multinational converters including Amcor plc, and Silgan Holdings Inc. operate high-cavitation injection molding, blow molding, and thermoforming networks serving global dairy, beverage, and processed food brands. Meanwhile, specialized tray innovators such as Faerch A/S, Sealed Air Corporation, and Winpak Ltd. focus on modified-atmosphere meat trays, dual-ovenable CPET ready-meal dishes, and integrated tray-to-tray rPET recycling plants. Food procurement teams select suppliers based on FDA/EFSA food-contact compliance, oxygen barrier ratings, and line sealing speed.
- Global Rigid Packaging Conglomerates: Amcor plc, and Silgan Holdings Inc. manufacture injection-molded tubs, rigid bottles, closures, and thermoformed food containers across multiple continents.
- Specialized Fresh Food & MAP Tray Leaders: Sealed Air Corporation, Faerch A/S, and Winpak Ltd. engineer high-barrier modified-atmosphere protein trays, dual-ovenable CPET dishes, and circular tray-to-tray rPET solutions.
- Paperboard & Composite Rigid Food Pack Innovators: Sonoco Products Company and Pactiv Evergreen Inc. supply rigid paperboard canisters, barrier-lined pressed paperboard trays, and fresh foodservice containers.
Competitive Benchmarking: Rigid Food Packaging Market
Table 8: Competitive Benchmarking for the Rigid Food Packaging Market (qualitative capability ratings), 2026
| Company | Multi-Cavity Forming Capacity | Food-Grade rPET Decontamination | High-Barrier MAP & CPET Depth | Geographic Reach |
|---|---|---|---|---|
| Amcor plc | High | High | High | High |
| Sealed Air Corporation | High | Medium | High | High |
| Silgan Holdings Inc. | High | Medium | High | Medium |
| Pactiv Evergreen Inc. | High | High | Medium | Medium |
| Sonoco Products Company | High | High | High | High |
| Winpak Ltd. | High | Medium | High | Medium |
| Faerch A/S | High | High | High | Medium |
Key Developments in the Rigid Food Packaging Market
- In June 2025, Amcor plc expanded post-consumer recycled packaging production capabilities at its Nicholasville, Kentucky facility. The investment supports flexible PCR content options up to 100% for rigid food packaging, helping brands comply with state-level minimum recycled-content mandates across the United States.
- In January 2026, Faerch’s Cirrec recycling facility increased tray-based rPET pellet supply capacity to up to 27,000 tonnes per annum for internal Faerch Group use. The expansion supports Faerch’s target of integrating 25 to 30% tray rPET content across its rigid food packaging range by 2026.
- In April 2026, Faerch and Norwegian seafood company Norfersk scaled commercial use of 70% tray-to-tray recycled PET meat trays using CIRPET+, Faerch’s next-generation tray rPET material. The milestone is supported by the first third-party-verified tray-to-tray rPET emission factor formally published in the global Sphera database.
Key Players in the Rigid Food Packaging Market
Global Rigid Packaging Conglomerates
- Amcor plc
- Silgan Holdings Inc.
Specialized Fresh Food & MAP Tray Leaders
- Sealed Air Corporation
- Faerch A/S
- Winpak Ltd.
Paperboard & Composite Rigid Food Pack Innovators
- Sonoco Products Company
- Pactiv Evergreen Inc.
Rigid Food Packaging Market - Report Scope
Table 9: Report Scope for the Rigid Food Packaging Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Packaging Format; Material Substrate; End-Use Sector; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes converter revenue from rigid thermoformed food trays, clamshells, thin-wall injection-molded tubs, pots, rigid food bottles, jars, cans, and barrier-lined pressed paperboard food containers. Excludes flexible stand-up pouches, rollstock wrapping films, and beverage bottles. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | South Africa, Chile, Germany, USA, Portugal, France, and additional countries in the full report |
| Key Companies Covered | Amcor plc, Sealed Air Corporation, Silgan Holdings Inc., Pactiv Evergreen Inc., Sonoco Products Company, Winpak Ltd., Faerch A/S |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Rigid Food Packaging Market - Research Methodology
Table 10: Research Methodology for the Rigid Food Packaging Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with thermoforming and injection-molding plant directors, food-contact polymer scientists, supermarket packaging buyers, and meat and dairy processing engineers to validate resin blends, barrier performance, and tray pricing. |
| Secondary Research | Secondary research included corporate annual filings, investor presentations, FDA and EFSA food-contact recycling clearances, European Union PPWR directives, packaging engineering journals, and publicly available trade statistics. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 assessment period were developed using top-down and bottom-up approaches to evaluate rigid container unit shipments, resin and paperboard tonnage, and average converter selling prices. |
| Data Triangulation and Validation | Data is validated against retail packaged food sales, cold-chain meat and produce output, food-grade rPET decontamination capacities, and historical converter revenues to ensure high accuracy without double counting flexible lidding films. |
Rigid Food Packaging Market by Segments
Rigid Food Packaging Market segmented by Packaging Format:
- Rigid Containers & Bottles
- Flexible Wraps & Bags
- Secondary Bulk Packaging
Rigid Food Packaging Market segmented by Material Substrate:
- Recycled Paperboard
- Thermoplastic Polymers
- Sustainable Plant Fibers
- Specialty Alloys
Rigid Food Packaging Market segmented by End-Use Sector:
- Food & Beverage
- Pharmaceuticals & Healthcare
- Personal Care & Homecare
- Industrial Manufacturing
Rigid Food Packaging Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Portugal
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] United States Food and Drug Administration (FDA). (2026, October 06). Submissions on Post-Consumer Recycled (PCR) Plastics for Food-Contact Articles and Chemistry Considerations. FDA CFSAN Inventory.
- [2] European Food Safety Authority (EFSA). (2026, May 06). Plastic Recycling Process Application Procedure and Safety Assessment for Food Contact Materials. EFSA Official Regulatory Guidance.
- [3] Society of Plastics Engineers (SPE). (2025, June 22). Advancements in servo-driven multi-cavity thermoforming and corner wall thickness control. SPE ANTEC Conference Proceedings, 44(2), 118-129.
- [4] European Committee for Standardization (CEN). (2025, July 28). Materials and articles in contact with foodstuffs: Plastics and barrier-lined paperboard migration test methods. CEN Standards, EN 1186:2025.
- [5] Journal of Food Engineering. (2025, August 20). Gas barrier performance and retail shelf-life extension of modified-atmosphere rigid meat packaging. JFE Academic Articles, 370, 111950.
- [6] Plastics Industry Association (PLASTICS). (2025, September 24). Economic analysis of food-contact post-consumer recycled PET sheet supply in North America. PLASTICS Market Briefings, 2025-09.
- [7] European Commission Directorate-General for Environment. (2025, February 11). Regulation (EU) 2025/40 on Packaging and Packaging Waste: Mandatory Recycled Content Quotas for Contact-Sensitive Plastic Packaging. European Union Official Environment Portal.
- [8] Waste and Resources Action Programme (WRAP). (2025, October 18). Circularity pathways and optical sorting yields for post-consumer PET food trays and pots. WRAP Technical Studies, 2025-10.
- [9] Packaging Association of South Africa (Packaging SA). (2025, November 22). Annual food packaging review and bottle-to-tray rPET extended producer responsibility performance. Packaging SA Bulletins, 2025-11.
- [10] Organisation for Economic Co-operation and Development (OECD). (2025, December 18). Extended producer responsibility and export food packaging standardization in Latin America. OECD Environment Policy Papers, No. 42.
- [11] German Packaging Institute (dvi). (2026, January 20). Retail conversion to mono-material polypropylene and paperboard-liner hybrid trays under VerpackG. dvi Industry Reports, 2026-01.
- [12] United States Food and Drug Administration (FDA). (2025, March 18). Guidance for Industry: Use of Recycled Plastics in Food Packaging: Chemistry Considerations. U.S. Department of Health and Human Services.
- [13] Portuguese Packaging Association (Embaltec). (2026, March 22). Portuguese preserved seafood and greenhouse fruit rigid packaging export dynamics. Embaltec Sector Reports, 2026-03.
- [14] Institut National de l'Origine et de la Qualité (INAO). (2026, April 18). Packaging and preservation standards for Protected Denomination of Origin cheese and charcuterie in France. INAO Regulatory Papers, 2026-04.
- [15] Amcor plc. (2025, February 24). Commercial introduction of recycle-ready high-rPET thermoformed food containers and dairy tubs. Amcor Corporate Announcements.
- [17] Faerch A/S. (2025, October 22). Operational commissioning of expanded industrial tray-to-tray circular rPET food packaging recycling line. Faerch Technical Briefings.
- [18] Sealed Air Corporation. (2026, January 26). Launch of CRYOVAC brand non-PVDC high-barrier modified-atmosphere rigid meat trays. Sealed Air Product Announcements.
- [19] Sonoco Products Company. (2026, March 14). Modernization of recyclable rigid paperboard food canister and barrier tray manufacturing complexes. Sonoco Investor Disclosures.
- [20] Winpak Ltd. (2026, April 09). Commercial rollout of high-barrier dual-ovenable polypropylene and CPET ready-meal trays in North America. Winpak Product Releases.
- [21] Pactiv Evergreen Inc. (2025, May 19). Expansion of post-consumer recycled PET tamper-evident deli and bakery clamshell lines. Pactiv Evergreen Corporate News.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the rigid food packaging market in 2026 and what is forecast for 2036?
- Which ready-meal shelf-life and food-safety pressures support demand for rigid food packaging?
- Why do Rigid Containers & Bottles lead the packaging format category?
- Why does recycled paperboard hold a major share in the material substrate category?
- How do growth rates prominently differ across South Africa, Chile, Germany, and the USA?
- Which leading companies manufacture thermoformed trays, tubs, and rigid food containers today?
- What limits adoption or converter margin expansion in the rigid food packaging market?
- What should food processors evaluate deeply before qualifying a rigid packaging supplier?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Rigid Containers & Bottles
- Flexible Wraps & Bags
- Secondary Bulk Packaging
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Material Substrate, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Substrate, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Substrate, 2026 to 2036
- Recycled Paperboard
- Thermoplastic Polymers
- Sustainable Plant Fibers
- Specialty Alloys
- Y-o-Y Growth Trend Analysis By Material Substrate, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Substrate, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Sector, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Sector, 2026 to 2036
- Food & Beverage
- Pharmaceuticals & Healthcare
- Personal Care & Homecare
- Industrial Manufacturing
- Y-o-Y Growth Trend Analysis By End-Use Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Portugal
- Benelux
- Nordics
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Portugal
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Amcor plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Sealed Air Corporation
- Silgan Holdings Inc.
- Pactiv Evergreen Inc.
- Sonoco Products Company
- Winpak Ltd.
- Faerch A/S
- Amcor plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Packaging Format
- Figure 6: Global Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Material Substrate
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Sector
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Packaging Format
- Figure 26: North America Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Material Substrate
- Figure 29: North America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by End-Use Sector
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Packaging Format
- Figure 36: Latin America Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Material Substrate
- Figure 39: Latin America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by End-Use Sector
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Packaging Format
- Figure 46: Western Europe Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Material Substrate
- Figure 49: Western Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by End-Use Sector
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Packaging Format
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Material Substrate
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by End-Use Sector
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Packaging Format
- Figure 66: East Asia Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Material Substrate
- Figure 69: East Asia Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by End-Use Sector
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Packaging Format
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Material Substrate
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by End-Use Sector
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Packaging Format
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Material Substrate
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by End-Use Sector
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the rigid food packaging market in 2026, and what is forecast for 2036?
The global rigid food packaging market is projected to reach USD 112.0 billion in 2026. Industry valuation is forecast to reach USD 175.6 billion by 2036, supported by chilled ready-meal demand and fresh produce distribution.
What is the CAGR for the rigid food packaging market from 2026 to 2036?
As per FMI, the rigid food packaging market is projected to expand at a 4.6% CAGR from 2026 to 2036. Growth is underpinned by high-speed modified-atmosphere meat packing and rising adoption of dual-ovenable convenience meal trays.
Which packaging format segment leads the rigid food packaging market?
Rigid Containers & Bottles hold 53.4% share of packaging format demand in 2026. The segment leads because rigid sidewalls and flat sealing rims enable rapid automated tray denesting, hermetic lidding seals, and crush-free retail stacking.
Which material substrate segment holds a major share in the rigid food packaging market?
Recycled paperboard accounts for 43.5% of material substrate demand in 2026. Demand is driven by supermarket conversion to pressed paperboard trays with peelable barrier liners that reduce plastic tax exposure and enter household paper recycling.
Which country has a notable growth outlook during the assessment period?
FMI finds that South Africa is projected to register a 5.6% CAGR from 2026 to 2036. Expansion is supported by formal supermarket cold-chain rollout, urban ready-meal purchasing, and ventilated rPET fruit export punnets.
Who are the key players in the market?
Notable market participants include Amcor plc, Berry Global Group Inc., Sealed Air Corporation, Silgan Holdings Inc., Pactiv Evergreen Inc., Sonoco Products Company, Winpak Ltd., and Faerch A/S. These companies focus on food-grade rPET decontamination, mono-material barrier trays, and thin-wall injection molding.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
