
- Market Size (2026)
- USD 593.8 Mn
- Forecast (2036)
- USD 845.7 Mn
- CAGR (2026 to 2036)
- 3.6%
How big is the Sea Salt Market in 2026?
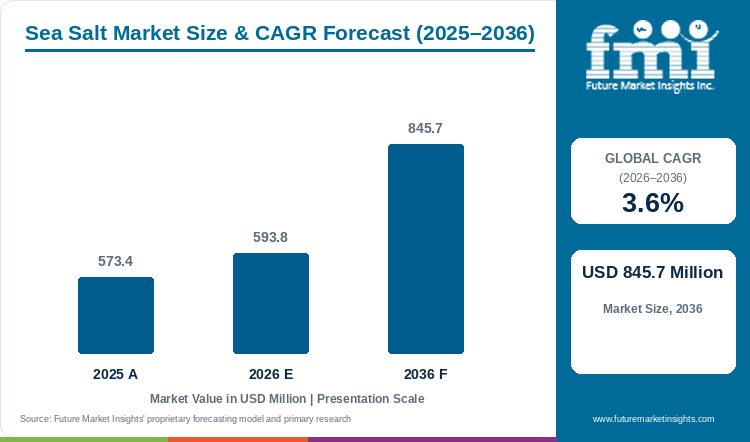
The Sea Salt Market is projected to reach USD 845.7 million by 2036, growing at a 3.6% CAGR from 2026 to 2036. FMI estimates the market at USD 593.8 million in 2026, after it was valued at USD 573.4 million in 2025. Sea salt is a small slice of the wider salt trade. Its value grows with food manufacturing and premium retail packs, not with tonnage. Health guidance on sodium limits volume growth in developed markets.
Import dependence differs widely across the profiled markets, and the figures below cover all salt types. Overseas-origin salt made up 89.2% of Japan's supply in fiscal 2025. China imported 12.9 million tonnes of salt in 2025, down 8.1%. The United States met 31% of apparent consumption through net imports in 2025. Mexico, Chile and Canada supplied 70% of US imports from 2021 to 2024. Australia and Chile held about 19% and 15% of world salt trade in 2024. Asian import demand is mostly industrial, so food-grade sea salt earns its margin from grade and packaging, not tonnage.
Key Market Trends & Insights
- Supply is concentrating in a few exporting regions: India accounted for nearly 29.0% of world salt trade in 2024, with China taking more than half of its shipments. Buyers in Asia therefore depend on Indian and Australian solar supply, so freight and harvest weather have become pricing factors.
- Branded salt is growing faster than the commodity. Tata Consumer Products reported that its salt business grew 14.0% in fiscal 2026 with double-digit volume growth. That business spans several salt types, so the figure is broader context for sea salt. Scale brands that sell refined and speciality lines are gaining share from loose and unbranded salt.
- Sodium policy is pushing food makers toward lower-salt recipes and products tracked in the low sodium sea salt market. The FDA draft guidance of 15 August 2024 sets sodium targets for 163 food categories. They would lower US intake to about 2,750 mg a day from about 3,400 mg. The guidance was still a draft when the FDA published a related final rule on 13 October 2026.
Regional Highlights
- In Asia Pacific, trade lanes are shifting as China's domestic production covers more of its needs: imports of crude salt fell 34.2% in December 2025, and sea salt supplies a large share of China's raw salt output, which keeps domestic evaporation capacity large.
- In North America, solar salt is a niche within a large salt industry. The USGS estimated US salt production at 40 million tons in 2025, with salt in brine at 44.0%. Because most American demand is met from brine and rock salt, sea salt sells mainly as a premium food product.
Sea Salt Market Size and Forecast
Table 1: Sea Salt Market Size and Forecast
| Market size and forecast | Value |
|---|---|
| Market size in 2025 | USD 573.4 million |
| Estimated market size in 2026 | USD 593.8 million |
| Projected market size by 2036 | USD 845.7 million |
| CAGR from 2026 to 2036 | 3.6% |
Source: Future Market Insights analysis of the sea salt market, 2026.
Analyst Perspective
“Food manufacturers buy sea salt for taste and label appeal, while households pay more for named origins and flake or coarse grades. Producers with their own solar pans and refining can hold margins when freight and packaging costs rise, but weather during the harvest season remains the main supply risk, because a wet season cuts the volume available for the year.”
- Nandini Roy Choudhury, Principal Analyst at Future Market Insights
How is the Sea Salt Market segmented?
- By end use: Food and Beverage, HoReCa, Agriculture, Animal Feed, Cosmetics and Personal Care.
- By production method: Solar evaporation, Mechanical and vacuum evaporation, Other methods.
- By packaging: Bags, Pouches, Sacks, Shakers, Glass Jars.
- By region: North America, Latin America, Europe, East Asia, South Asia, Oceania, Middle East and Africa.
Why does Food and Beverage lead by End Use in the Sea Salt Market in 2026?
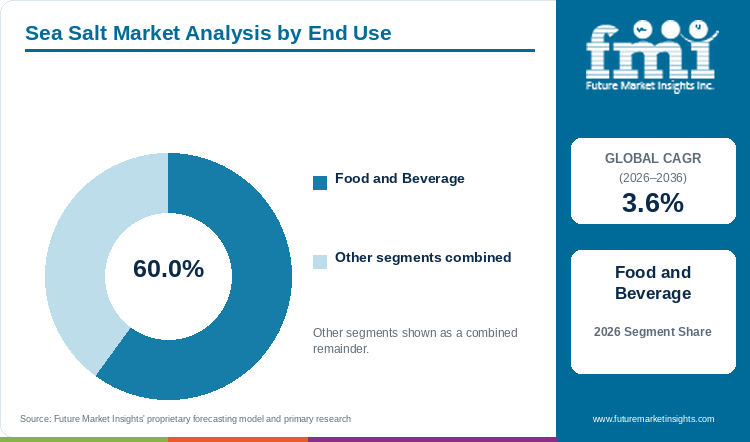
Food and Beverage holds 60.0% of the Sea Salt Market by end use in 2026.
Food makers use salt in every savoury product, and household cooking sits inside this group. Dietary guidance caps use, and the German Nutrition Society gives a reference value of up to 6 grams a day. Volume per person is therefore capped, so growth comes from more consumers and from premium grades. HoReCa, agriculture, animal feed and cosmetics together hold the remaining 40.0%. Manufacturers can reformulate processed food toward the FDA draft goal of about 2,750 mg of sodium a day. Finishing salts for restaurants and home cooks are used in small amounts and are less exposed.
Table 2: End Use, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Food and Beverage | 60.0% |
| All Other Segments Combined Share | 40.0% |
Source: Future Market Insights analysis of the sea salt market, 2026.
Why does Solar evaporation lead by Production Method in the Sea Salt Market in 2026?
Solar evaporation holds 80.0% of the Sea Salt Market by production method in 2026.
Large coastal producing regions rely on sun and wind to concentrate seawater. That method has the lowest energy cost per tonne and ties sea salt to the solar salt market. India is forecast to produce about 35.8 million tonnes of salt in 2025 and to export about 18.4 million tonnes. Mechanical evaporation and other methods hold the remaining 20.0%. Solar output is limited to arid coasts. In the United States, solar salt was only 9.0% of 2025 salt output. That USGS category also includes lake operations in Utah. Producers in humid or cold regions use heated evaporation, which costs more per tonne but gives a steady supply all year.
Table 3: Production Method, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Solar evaporation | 80.0% |
| All Other Segments Combined Share | 20.0% |
Source: Future Market Insights analysis of the sea salt market, 2026.
Why do Bags lead by Packaging in the Sea Salt Market in 2026?
Bags hold 35.0% of the Sea Salt Market by packaging in 2026.
Bags are the cheapest pack per kilo and fit both retail and small food-service orders. Salt is a low-price staple, and freight is a large part of delivered cost. The seawater-fed Price field in South Australia packs retail sizes, 10 kg and 25 kg bags, and bulk bags. Pouches, sacks, shakers and glass jars together hold the remaining 65.0%. Jars and shakers carry the highest price per kilo and serve gourmet and gift buyers. Sacks serve food manufacturers and farms that buy in bulk.
Table 4: Packaging, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Bags | 35.0% |
| All Other Segments Combined Share | 65.0% |
Source: Future Market Insights analysis of the sea salt market, 2026.
What are the key drivers, restraints and opportunities?
Driver
Branded salt growth in India. Packed and branded salt is expanding with household income. A leading brand reported salt revenue growth of 14.0% across its range in fiscal 2026. Export contracts support steady demand for solar-produced salt.
Strong export demand for finishing salt. Maldon Salt reports increased demand for its flakes, particularly from export markets, and says demand still exceeds its output.
Restraint
Sodium reduction policy. Public health bodies urge consumers and food makers to use less salt, which shapes the salt content reduction ingredients market. FDA draft sodium targets and the German salt reference value both limit volume growth in mature markets.
Slow demand in Japan. Japan is a large importer but a flat market. Total salt demand was 7.8 million tonnes in fiscal 2025, down from 9.5 million in fiscal 1997. Food manufacturing accounts for only 8.3% of that demand. A shrinking population and import dependence keep growth near zero.
Opportunity
Premium finishing and flavoured salts. Salt added at the table is the smaller share of intake. More than 70% of US sodium comes from processed, packaged and prepared foods. Gourmet flakes and flavoured blends use small amounts of salt, so they face less pressure from sodium targets.
Supply chain integration. Producers that own pans, refining and packing can serve brand owners directly. Cheetham Salt operates 6 solar fields and 4 refineries in Australia. Its Price site supplies food manufacturing, retail, export food markets and animal feed. Owners of integrated capacity capture more of the margin between raw and packed salt.
Sea Salt Market by Country (2026 to 2036)
Table 5: Sea Salt Market Country Growth Forecast
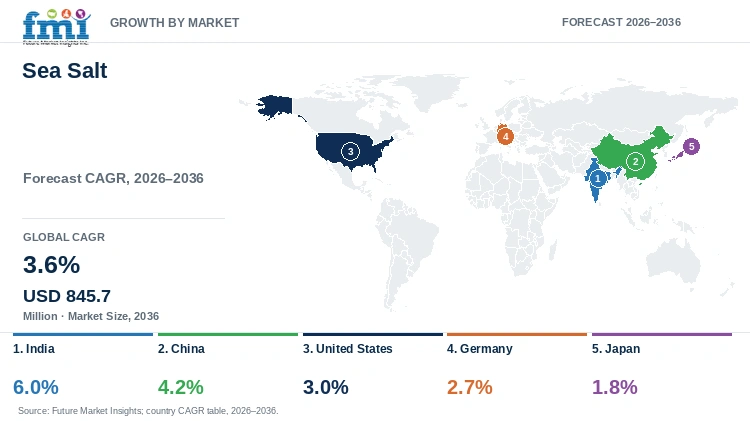
| Country | CAGR, 2026 to 2036 |
|---|---|
| India | 6.0% |
| China | 4.2% |
| United States | 3.0% |
| Germany | 2.7% |
| Japan | 1.8% |
Source: Future Market Insights analysis of the sea salt market, 2026.
India
India is the fastest-growing profiled market, as its exports rose 11.7% in the first seven months of 2025 and branded packed salt is gaining share at home. Both trends support a 6.0% CAGR from 2026 to 2036.
Cost and scale explain India's lead in the group. Sea salt makes up about 80% of Indian output. Gujarat supplied 85.6% of the national total in fiscal 2021 to 2022. One dry season therefore moves national supply, as output rose 10.1% to 33.7 million tonnes in 2024. Exports of 17.3 million tonnes accounted for 51% of that output. Solar evaporation keeps unit costs among the lowest worldwide. Ports are similarly concentrated, since Kandla loaded 7.6 of the 9.8 million tonnes exported in January to July 2025.
India is a net exporter. China received 5.55 million tonnes of Indian salt in January to July 2025, up 12.1%. Industry accounts for over 60% of consumption, so the 6.3 million tonne edible requirement is the smaller base. Iodised capacity reached 21.9 million tonnes by 2022, well above that requirement. A national iodisation programme under the Salt Commissioner shapes the packed segment, whereas Germany leaves iodisation voluntary. Raw solar salt flows to Chinese industrial buyers, while packed iodised grades serve Indian households.
China
China relies on sea salt for 43.0% of raw salt output, behind well and rock salt at 46.0%. Imports of crude salt have fallen as domestic supply covers more demand. Rising food spending supports a 4.2% CAGR from 2026 to 2036, held back by large domestic supply.
Scale and cost set China's position in the group. USGS estimates 2025 output at 56 million tonnes, or 20.7% of the 270 million tonnes produced worldwide. Raw salt output fell 3.2% to 49.85 million tonnes in 2022. Weak chemical demand and heavy imports cut prices, so sea and lake salt producers limited shipments. Average sea salt cost rose USD 2.9 per tonne between 2021 and 2023, mainly on labour.
China is both a large importer and a growing exporter. Imports fell 8.1% to 12.9 million tonnes in 2025, and Australia supplied 21.2% of them. Exports rose 43.6% to 0.95 million tonnes, and Japan took 53.6% of the volume. That was 509,000 tonnes of crude salt. Food use faces a ceiling, since the 2025 to 2030 nutrition guideline targets 5 g of salt a day. Growth therefore rests on import displacement and exports, not on food volume. Imports remain about 14 times the volume of exports, so China is still a net importer of salt. Overseas suppliers face a smaller import market as domestic supply grows.
United States
The United States is a mature market where FDA draft voluntary sodium targets encourage processors to use less salt. Sea salt therefore grows as a premium segment. Premium retail packs support a 3.0% CAGR from 2026 to 2036.
Pricing and product mix explain the US position. USGS reports 2025 average values of USD 150 per tonne for solar salt and USD 54 for rock salt. Vacuum and open pan salt sells at USD 260, and salt in brine at USD 11. Solar salt was 9% of the 39 million tonnes sold or used, and that USGS category includes Utah lake operations. Between 2021 and 2025, solar salt fell 2.3% and vacuum and open pan salt rose 27.6%. Sea salt therefore gains value through grade and pack size, because bulk solar pricing has not risen.
Domestic solar facilities sit in six states from California to Oklahoma. Net imports met 31% of US apparent consumption of all salt in 2025. Mexico, Chile and Canada supplied 70% of imports from 2021 to 2024. Those figures cover every salt type, so they show supply exposure, not sea salt demand. From 14 December 2026 an FDA final rule lets makers of standardized foods use salt substitutes to cut sodium. Food-grade salt suppliers to those makers may therefore lose part of their volume.
Germany
German buyers follow health guidance closely, and the German Nutrition Society has called for lower salt in processed food. Demand for sea salt comes mainly from gourmet and home cooking. Premium use offsets lower intake, which supports a 2.7% CAGR from 2026 to 2036.
Germany grows slowly because most salt enters the diet through processed food. Processed foods and meals eaten out supply most dietary salt. Bread, meat, sausage and cheese contribute the most. Salt added at the table is a small share of intake. The DEGS health survey puts mean daily intake at 10.0 g for men and 8.4 g for women. About 80% of men and 70% of women exceed the 6 g reference value. Half of men exceed 10 g a day. Sea salt therefore competes only for the household and finishing share of demand.
Iodine guidance narrows that share further, since DGE advises iodised and fluoridated salt. It notes that untreated sea salt contains only slightly more iodine than untreated table salt. The food ministry runs an iodised salt campaign because 32% of adults face a higher risk of iodine shortfall. Iodisation is voluntary, and iodised salt appears in only 9% of bread products and 34% of sausages in 2025. Salt content has been mandatory on food labels since December 2016. A sea salt supplier therefore competes on taste and origin, not on iodine content.
Japan
Japanese salt demand slipped 0.4% to 7.8 million tonnes in fiscal 2025. That is 18.0% below the fiscal 1997 level of 9.5 million tonnes. A flat food market and import dependence limit growth to a 1.8% CAGR from 2026 to 2036. Value growth therefore depends on gourmet and artisan lines.
Climate and import structure hold Japan's growth below the other profiled markets. Japan has no salt lakes or rock salt, and rainfall and humidity make solar evaporation unsuitable. Domestic salt therefore comes from seawater concentrated in salt fields or by ion-exchange membranes and then boiled down. Domestic output was 836,000 tonnes in fiscal 2025, 37% below the 1997 level of 1.33 million tonnes. Imported solar salt is also dissolved and recrystallised in Japan, so local refiners depend on overseas supply.
Food is a small segment of Japanese salt demand. Food manufacturing uses 646,000 tonnes, or 8.3% of demand. Households use 107,000 tonnes, or 1.4%. Sea salt for food therefore competes in a segment below a tenth of national volume. Australia shipped 1.7 million tonnes to Japan in January to July 2025 and India 0.6 million tonnes, up 37.9%. China shipped 509,000 tonnes of crude salt to Japan in 2025. Overseas sources supply 89.2% of Japanese salt, so food buyers depend on import contracts and local refiners.
Who are the notable companies in the Sea Salt Market?
Notable companies in the Sea Salt Market include Tata Consumer, Cheetham Salt and Maldon Salt.
Origin separates the suppliers in this market. A supplier counts only where its salt comes from seawater evaporated in solar fields or heated pans. A sea salt label on rock, well or lake salt does not qualify. Ownership of the pans and refining then sets grade range and pack sizes.
Tata Consumer Products sells Tata Salt Iodised Crystal Salt, which it describes as sea-sourced and solar evaporated. Its range also includes rock salt and black salt, so its salt revenue is broader context for this market. Salt revenue grew 14.0% in fiscal 2026 and crossed INR 4,000 crore, with double-digit volume growth. The company calls Tata Salt India's largest salt brand.
Cheetham Salt operates 6 solar fields and 4 refineries in Australia. Its Price site on St Vincent's Gulf has a seawater-fed solar field and began operating in 1919. The site supplies food, retail and export customers as well as animal feed and industrial users. Bajool in Queensland adds two seawater-fed fields and a refinery. Its Sea Lake and Lochiel sites produce lake salt, which falls outside this report.
Maldon Salt draws seawater from the Blackwater Estuary and evaporates brine in salt pans over flames to make flakes. A third production building at Longwick Farm was recently completed and takes the site to 72 pans. The company says demand, particularly from export markets, still exceeds its output.
Key Developments in the Sea Salt Market
- In February 2026, Tata Consumer Products Limited formalized a technology transfer with the Council of Scientific and Industrial Research National Institute for Interdisciplinary Science and Technology to develop low-sodium salt formulations for its salt category. The collaboration supports the company’s science-led innovation agenda for the salt segment and targets health-conscious consumers across its core markets [20].
- In November 2025, Maldon Salt Ltd launched Maldon Pepper Sea Salt in 488 Morrisons stores across the United Kingdom and on Morrisons’ online platform. The product blends the company’s hand-harvested sea salt flakes from the Blackwater Estuary with Tellicherry black peppercorns and pink peppercorns, presented in a 50g recyclable tub [21].
Key Players in the Sea Salt Market
- Tata Consumer Products Limited
- Cheetham Salt
- Maldon Salt Limited
Sea Salt Market Report Scope
Table 6: Sea Salt Market Report Scope
| Coverage field | Report scope |
|---|---|
| Market definition | Salt produced from seawater by solar or mechanical evaporation and sold as food, feed, cosmetic and agricultural salt at manufacturer selling prices. Origin decides inclusion: rock, well, brine and lake salt are excluded even when sold under a sea salt label. Industrial, deicing and chemical-grade salt is excluded. |
| End Use | Food and Beverage; HoReCa; Agriculture; Animal Feed; Cosmetics and Personal Care |
| Production Method | Solar evaporation; Mechanical and vacuum evaporation; Other methods |
| Packaging | Bags; Pouches; Sacks; Shakers; Glass Jars |
| Regions and profiled countries | North America, Latin America, Europe, East Asia, South Asia, Oceania, Middle East and Africa. Profiled countries: India, China, United States, Germany, Japan |
| Companies covered | Tata Consumer Products Limited; Cheetham Salt; Maldon Salt Limited |
| Quantitative Units | USD million |
Sea Salt Market by Segments
Sea Salt Market segmented by End Use:
- Food and Beverage
- HoReCa
- Agriculture
- Animal Feed
- Cosmetics and Personal Care
Sea Salt Market segmented by Production Method:
- Solar evaporation
- Mechanical and vacuum evaporation
- Other methods
Sea Salt Market segmented by Packaging:
- Bags
- Pouches
- Sacks
- Shakers
- Glass Jars
Sea Salt Market by Region
- North America
- Latin America
- Europe
- East Asia
- South Asia
- Oceania
- Middle East
- Africa
- India
- China
- United States
- Germany
- Japan
Research Sources and Bibliography
- [1] U.S. Food and Drug Administration. (2024, August 15). Sodium Reduction in the Food Supply. https://www.fda.gov/food/nutrition-food-labeling-and-critical-foods/sodium-reduction-food-supply
- [2] Breakwave Advisors. (2025, August 26). Indian Salt Across Asian Waters. https://www.breakwaveadvisors.com/insights/2025/8/26/indian-salt-across-asian-waters
- [3] Tata Consumer Products Limited. (2026, June). AGM Presentation for FY 2025-26. https://www.tataconsumer.com/sites/g/files/gfwrlq316/files/2026-06/TCPL-AGM-PRESENTATION-FOR-FY-2025-26.pdf
- [4] Bloomin Global. (2026). China's crude salt imports fall 34.2% in December 2025. https://www.bloominglobal.com/media/detail/chinas-crude-salt-imports-fall-342-in-december-2025
- [5] SMM. SMM exclusive study on China raw salt market and its energy consumption. https://news.metal.com/newscontent/102355461/smm-exclusive-study-on-china-raw-salt-market-and-its-energy-consumption
- [6] U.S. Geological Survey. (2026, February). Mineral Commodity Summaries 2026: Salt. https://pubs.usgs.gov/periodicals/mcs2026/mcs2026-salt.pdf
- [7] Tata Consumer Products Limited. (2026, May). Results for the Quarter and Year ended 31st March 2026. https://www.tataconsumer.com/news/results-quarter-and-year-ended-31st-march-2026
- [8] Indian Bureau of Mines. (2024, March). Indian Minerals Yearbook 2022: Salt (advance release). https://ibm.gov.in/writereaddata/files/17125772176613dac1f2662Salt_2022.pdf
- [9] The Salt Industry Center of Japan. (2026). State of Salt Demand and Supply in Japan, fiscal 2025 (Ministry of Finance, Record of Demand and Supply of Salt). https://www.shiojigyo.com/english/upload/demandandsupply2025.pdf
- [10] The Salt Industry Center of Japan. (2026, accessed November 5). Salt production method. https://www.shiojigyo.com/english/method/
- [11] Deutsche Gesellschaft fuer Ernaehrung. (2023, October 1). FAQ Speisesalz. https://www.dge.de/gesunde-ernaehrung/faq/speisesalz/
- [12] Bundesministerium fuer Landwirtschaft, Ernaehrung und Heimat. (2026, July 30). Wenn Salz, dann Jodsalz. https://www.bmleh.de/DE/themen/ernaehrung/gesunde-ernaehrung/jodsalz-landingpage/jodsalz-landingpage_node.html
- [13] National Health Commission of China. (2025, March 21). Guideline aims to promote balanced nutrition, healthier lifestyles. https://en.nhc.gov.cn/2025-03/21/c_86413.htm
- [14] Food and Drug Administration. (2026, October 13). Use of Salt Substitutes To Reduce the Sodium Content in Standardized Foods (final rule, 91 FR 65040). Federal Register. https://www.federalregister.gov/documents/2026/10/13/2026-20848/use-of-salt-substitutes-to-reduce-the-sodium-content-in-standardized-foods
- [15] Cheetham Salt. Sites and locations. https://www.cheethamsalt.com.au/sites-locations
- [16] Essex County News. (2026, July 20). Maldon Salt looks to expand production side to meet demand. https://www.essexcountynews.co.uk/news/26289956.maldon-salt-looks-expand-production-side-meet-demand/
- [17] Maldon District Council. (2026, July 10). Weekly list of planning applications, week 28 (application 26/00423/FUL). https://www.maldon.gov.uk/download/downloads/id/20268/weekly_list_we_10_july_2026.pdf
- [18] Maldon Salt. (2022). A guide to sea salt: how it's made and where it comes from. https://maldonsalt.com/a-guide-to-sea-salt-how-its-made-and-where-it-comes-from/
- [19] Tata Consumer Products. Tata Salt product range. https://www.tataconsumer.com/brands/foods/tata-salt
- [20] Tata World. (2026, February 18). Tata Consumer Products collaborates with CSIR-NIIST to advance science-backed food and beverage innovations. https://www.tataworld.com/news/openinside/tata-consumer-products-csir-niist-food-beverage-innovations
- [21] Maldon Salt Ltd. (2025, November 3). Introducing Maldon Pepper Sea Salt: A Bold New Flavour. https://maldonsalt.com/?p=10384
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End Use, 2026 to 2036
- Food and Beverage
- HoReCa
- Agriculture
- Animal Feed
- Cosmetics and Personal Care
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Production Method, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Production Method, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Production Method, 2026 to 2036
- Solar evaporation
- Mechanical and vacuum evaporation
- Other methods
- Y-o-Y Growth Trend Analysis By Production Method, 2021 to 2025
- Absolute $ Opportunity Analysis By Production Method, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Packaging, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Packaging, 2026 to 2036
- Bags
- Pouches
- Sacks
- Shakers
- Glass Jars
- Y-o-Y Growth Trend Analysis By Packaging, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Europe
- East Asia
- South Asia
- Oceania
- Middle East
- Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By End Use
- By Production Method
- By Packaging
- Market Attractiveness Analysis
- By Country
- By End Use
- By Production Method
- By Packaging
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By End Use
- By Production Method
- By Packaging
- Market Attractiveness Analysis
- By Country
- By End Use
- By Production Method
- By Packaging
- Key Takeaways
- Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By End Use
- By Production Method
- By Packaging
- Market Attractiveness Analysis
- By Country
- By End Use
- By Production Method
- By Packaging
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By End Use
- By Production Method
- By Packaging
- Market Attractiveness Analysis
- By Country
- By End Use
- By Production Method
- By Packaging
- Key Takeaways
- South Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By End Use
- By Production Method
- By Packaging
- Market Attractiveness Analysis
- By Country
- By End Use
- By Production Method
- By Packaging
- Key Takeaways
- Oceania Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By End Use
- By Production Method
- By Packaging
- Market Attractiveness Analysis
- By Country
- By End Use
- By Production Method
- By Packaging
- Key Takeaways
- Middle East Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By End Use
- By Production Method
- By Packaging
- Market Attractiveness Analysis
- By Country
- By End Use
- By Production Method
- By Packaging
- Key Takeaways
- Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- China
- United States
- Germany
- Japan
- By End Use
- By Production Method
- By Packaging
- By Country
- Market Attractiveness Analysis
- By Country
- By End Use
- By Production Method
- By Packaging
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By End Use
- By Production Method
- By Packaging
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By End Use
- By Production Method
- By Packaging
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By End Use
- By Production Method
- By Packaging
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By End Use
- By Production Method
- By Packaging
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By End Use
- By Production Method
- By Packaging
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By End Use
- By Production Method
- By Packaging
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Tata Consumer Products Limited
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Cheetham Salt
- Maldon Salt Limited
- Tata Consumer Products Limited
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Production Method, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by Packaging, 2021 to 2036
- Table 5: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Production Method, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Packaging, 2021 to 2036
- Table 9: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 11: Latin America Market Value (USD Million) Forecast by Production Method, 2021 to 2036
- Table 12: Latin America Market Value (USD Million) Forecast by Packaging, 2021 to 2036
- Table 13: Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Europe Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 15: Europe Market Value (USD Million) Forecast by Production Method, 2021 to 2036
- Table 16: Europe Market Value (USD Million) Forecast by Packaging, 2021 to 2036
- Table 17: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 18: East Asia Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 19: East Asia Market Value (USD Million) Forecast by Production Method, 2021 to 2036
- Table 20: East Asia Market Value (USD Million) Forecast by Packaging, 2021 to 2036
- Table 21: South Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 22: South Asia Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 23: South Asia Market Value (USD Million) Forecast by Production Method, 2021 to 2036
- Table 24: South Asia Market Value (USD Million) Forecast by Packaging, 2021 to 2036
- Table 25: Oceania Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: Oceania Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 27: Oceania Market Value (USD Million) Forecast by Production Method, 2021 to 2036
- Table 28: Oceania Market Value (USD Million) Forecast by Packaging, 2021 to 2036
- Table 29: Middle East Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 30: Middle East Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 31: Middle East Market Value (USD Million) Forecast by Production Method, 2021 to 2036
- Table 32: Middle East Market Value (USD Million) Forecast by Packaging, 2021 to 2036
- Table 33: Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 34: Africa Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 35: Africa Market Value (USD Million) Forecast by Production Method, 2021 to 2036
- Table 36: Africa Market Value (USD Million) Forecast by Packaging, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by End Use
- Figure 6: Global Market Value Share and BPS Analysis by Production Method, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Production Method, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Production Method
- Figure 9: Global Market Value Share and BPS Analysis by Packaging, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Packaging, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Packaging
- Figure 12: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: South Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Oceania Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 24: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 25: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 26: North America Market Attractiveness Analysis by End Use
- Figure 27: North America Market Value Share and BPS Analysis by Production Method, 2026 and 2036
- Figure 28: North America Market Y-o-Y Growth Comparison by Production Method, 2026-2036
- Figure 29: North America Market Attractiveness Analysis by Production Method
- Figure 30: North America Market Value Share and BPS Analysis by Packaging, 2026 and 2036
- Figure 31: North America Market Y-o-Y Growth Comparison by Packaging, 2026-2036
- Figure 32: North America Market Attractiveness Analysis by Packaging
- Figure 33: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 34: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 35: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 36: Latin America Market Attractiveness Analysis by End Use
- Figure 37: Latin America Market Value Share and BPS Analysis by Production Method, 2026 and 2036
- Figure 38: Latin America Market Y-o-Y Growth Comparison by Production Method, 2026-2036
- Figure 39: Latin America Market Attractiveness Analysis by Production Method
- Figure 40: Latin America Market Value Share and BPS Analysis by Packaging, 2026 and 2036
- Figure 41: Latin America Market Y-o-Y Growth Comparison by Packaging, 2026-2036
- Figure 42: Latin America Market Attractiveness Analysis by Packaging
- Figure 43: Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 44: Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 45: Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 46: Europe Market Attractiveness Analysis by End Use
- Figure 47: Europe Market Value Share and BPS Analysis by Production Method, 2026 and 2036
- Figure 48: Europe Market Y-o-Y Growth Comparison by Production Method, 2026-2036
- Figure 49: Europe Market Attractiveness Analysis by Production Method
- Figure 50: Europe Market Value Share and BPS Analysis by Packaging, 2026 and 2036
- Figure 51: Europe Market Y-o-Y Growth Comparison by Packaging, 2026-2036
- Figure 52: Europe Market Attractiveness Analysis by Packaging
- Figure 53: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 54: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 55: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 56: East Asia Market Attractiveness Analysis by End Use
- Figure 57: East Asia Market Value Share and BPS Analysis by Production Method, 2026 and 2036
- Figure 58: East Asia Market Y-o-Y Growth Comparison by Production Method, 2026-2036
- Figure 59: East Asia Market Attractiveness Analysis by Production Method
- Figure 60: East Asia Market Value Share and BPS Analysis by Packaging, 2026 and 2036
- Figure 61: East Asia Market Y-o-Y Growth Comparison by Packaging, 2026-2036
- Figure 62: East Asia Market Attractiveness Analysis by Packaging
- Figure 63: South Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 64: South Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 65: South Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 66: South Asia Market Attractiveness Analysis by End Use
- Figure 67: South Asia Market Value Share and BPS Analysis by Production Method, 2026 and 2036
- Figure 68: South Asia Market Y-o-Y Growth Comparison by Production Method, 2026-2036
- Figure 69: South Asia Market Attractiveness Analysis by Production Method
- Figure 70: South Asia Market Value Share and BPS Analysis by Packaging, 2026 and 2036
- Figure 71: South Asia Market Y-o-Y Growth Comparison by Packaging, 2026-2036
- Figure 72: South Asia Market Attractiveness Analysis by Packaging
- Figure 73: Oceania Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 74: Oceania Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 75: Oceania Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 76: Oceania Market Attractiveness Analysis by End Use
- Figure 77: Oceania Market Value Share and BPS Analysis by Production Method, 2026 and 2036
- Figure 78: Oceania Market Y-o-Y Growth Comparison by Production Method, 2026-2036
- Figure 79: Oceania Market Attractiveness Analysis by Production Method
- Figure 80: Oceania Market Value Share and BPS Analysis by Packaging, 2026 and 2036
- Figure 81: Oceania Market Y-o-Y Growth Comparison by Packaging, 2026-2036
- Figure 82: Oceania Market Attractiveness Analysis by Packaging
- Figure 83: Middle East Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 84: Middle East Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 85: Middle East Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 86: Middle East Market Attractiveness Analysis by End Use
- Figure 87: Middle East Market Value Share and BPS Analysis by Production Method, 2026 and 2036
- Figure 88: Middle East Market Y-o-Y Growth Comparison by Production Method, 2026-2036
- Figure 89: Middle East Market Attractiveness Analysis by Production Method
- Figure 90: Middle East Market Value Share and BPS Analysis by Packaging, 2026 and 2036
- Figure 91: Middle East Market Y-o-Y Growth Comparison by Packaging, 2026-2036
- Figure 92: Middle East Market Attractiveness Analysis by Packaging
- Figure 93: Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 94: Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 95: Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 96: Africa Market Attractiveness Analysis by End Use
- Figure 97: Africa Market Value Share and BPS Analysis by Production Method, 2026 and 2036
- Figure 98: Africa Market Y-o-Y Growth Comparison by Production Method, 2026-2036
- Figure 99: Africa Market Attractiveness Analysis by Production Method
- Figure 100: Africa Market Value Share and BPS Analysis by Packaging, 2026 and 2036
- Figure 101: Africa Market Y-o-Y Growth Comparison by Packaging, 2026-2036
- Figure 102: Africa Market Attractiveness Analysis by Packaging
- Figure 103: Global Market - Tier Structure Analysis
- Figure 104: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Sea Salt Market in 2026?
FMI estimates the market at USD 593.8 million in 2026, up from USD 573.4 million in 2025. It is forecast to reach USD 845.7 million by 2036 at a 3.6% CAGR.
Which end use leads the Sea Salt Market in 2026?
Food and Beverage leads by end use with 60.0% in 2026. HoReCa, agriculture, animal feed and cosmetics together hold 40.0%.
Which production method leads?
Solar evaporation leads with 80.0% of value in 2026, because sun and wind give the lowest energy cost per tonne for coastal producers.
Which country is forecast to grow fastest through 2036?
India has the highest forecast CAGR among the profiled countries at 6.0% during 2026 to 2036, followed by China at 4.2%.
How does sodium policy affect sea salt demand?
Policy limits volume but not premium value. FDA draft targets across 163 food categories would lower US sodium intake to about 2,750 mg a day [1]. The German Nutrition Society gives a reference value of up to 6 grams of salt a day [11]. Finishing salts are used in small amounts and are less exposed.
Which companies are covered in the Sea Salt Market?
Tata Consumer Products, Cheetham Salt and Maldon Salt are profiled.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
