
- Market Size (2026)
- USD 56.30 Bn
- Forecast (2036)
- USD 113.90 Bn
- CAGR (2026 to 2036)
- 7.3%
How big is Sparkling Bottled Water Market in 2026?
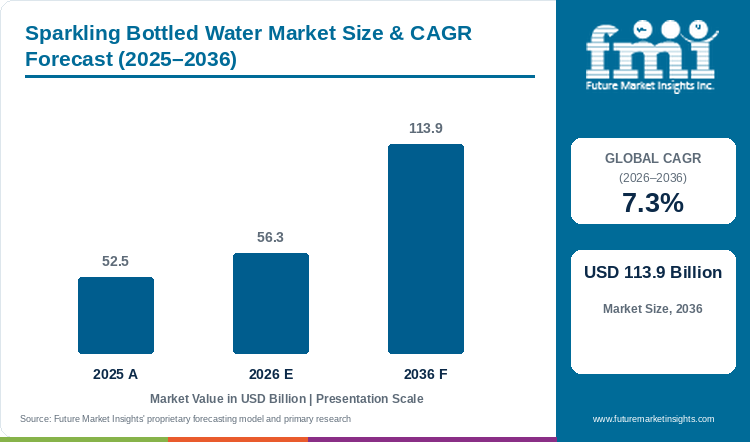
Sparkling bottled water market size climbs from USD 52.47 billion in 2025 to USD 56.30 billion in 2026, and FMI forecasts a 7.3% CAGR that lifts the total to USD 113.90 billion by 2036.
At a 7.3% annual pace, the FMI forecast takes the market from USD 52.47 billion (2025) through USD 56.30 billion (2026) to USD 113.90 billion (2036). Flavored variants lead with 58.6% in 2026, as brands borrow fruit and mocktail profiles from the wider flavored water range. Producer results for the first half of 2026 point to value growth led by price and premium mix. Nestlé Waters & Premium Beverages posted 5.1% organic growth in the first half, and in the second quarter pricing of 4.4% contributed twice the 2.2% real internal growth, with S.Pellegrino water rising at a high single-digit rate. Danone posted total group sales of EUR 13,936 million in H1 2026, up 3.6% like-for-like in EMEA in the second quarter on a strong start to summer led by Volvic, a still-water brand, making this a still-water-led proxy for category momentum rather than direct sparkling-water evidence . FMI attributes the gap to premiumization and flavor innovation, which are expected to keep lifting average selling prices and mix faster than category-wide volume growth through 2036.
Brand owners are restructuring portfolios and ownership around premium water. Nestlé agreed in July 2026 to place S.Pellegrino, Perrier, Acqua Panna and Pure Life in Peranel, a 50:50 joint venture with Platinum Equity valued at USD 5.6 billion, with closing expected in the first half of 2027. Primo Brands lifted premium water net sales to USD 114.2 million in the second quarter of 2026 from USD 87.5 million a year earlier, through a portfolio that includes Saratoga and Mountain Valley, and raised full-year net sales growth guidance to 2% to 4%. Supply reliability has also become a differentiator: problems at the Topo Chico plant in Mexico led Coca-Cola to pause production, leaving glass-bottled Topo Chico mineral water short in the US from February 2026 until a phased return began in Texas in October 2026. Brand owners with control over source access, bottle supply and premium pricing are positioned to capture a larger part of the USD 57.60 billion added between 2026 and 2036.
Key Market Trends & Insights
- Flavored sparkling water held 58.6% of 2026 product type demand. Sparkling Ice, the largest flavored brand, recorded more than USD 971 million in sales and an 18% share of flavored sparkling water, though sales eased 4% year on year to early November 2025.
- Multipack formats such as the 8-pack of 12-ounce bubly cans PepsiCo released at US retailers in September 2026 support hypermarket and supermarket demand, which held 47.9% of channel sales in 2026.
- Glass bottles accounted for 41.3% of 2026 packaging value, a position tied to imported mineral brands and table service. The 2026 Topo Chico shortage affected only glass-bottled mineral water, as flavored sparkling water from the brand stayed on shelf.
- Medium and high carbonation levels dominate in Germany, accounting for more than 70% of 2026 mineral water sales there.
Regional Highlights
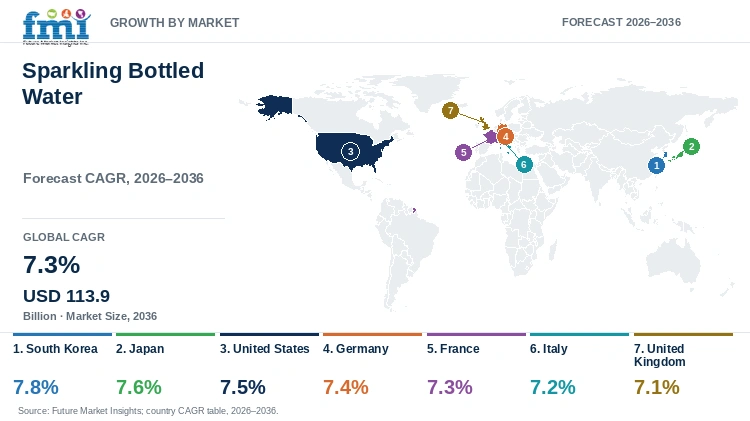
- South Korea tops the profiled countries with 7.8% annual growth over 2026 to 2036.
- Japan comes next at 7.6%, with US growth close behind at 7.5%; Britain, at 7.1%, sits at the bottom of the set.
- South Korea began requiring label-free bottled water from 1 January 2026, with product details moved to caps or QR codes. This rule covers bottled water broadly, including still water, rather than sparkling water specifically.
Market Size & Forecast
Table 1: Market Size and Forecast for the Sparkling Bottled Water Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 52.47 billion |
| Estimated Market Size in 2026 | USD 56.30 billion |
| Projected Market Size by 2036 | USD 113.90 billion |
| CAGR, 2026 to 2036 | 7.3% |
| Added Value, 2026 to 2036 | USD 57.60 billion |
| Market Expansion Multiple | 2.0x |
Flavor and format extensions keep supplying new listings. Talking Rain added four Sparkling Ice x LIFE SAVERS flavors in January 2026 in a 17-ounce slim bottle, starting with Kroger, Publix and Amazon ahead of a wider spring rollout. Danone extended evian lightly sparkling water to France by mid-2026 after launches in the United Kingdom and the United States. Sanpellegrino and Maison Perrier posted strong double-digit growth in the first half of 2026, helped by Sanpellegrino CIAO! and ZERO and Maison Perrier's probiotic French Kiss. The bottled water shelf space remains the base on which sparkling SKUs compete for facings. National Beverage's fiscal 2026 net sales slipped to USD 1,180.6 million from USD 1,201.4 million in a 53-week prior year, with case volume down 6.7%. Premium imports and functional extensions are set to expand faster than mainstream flavored cans through the forecast period.
Producer Results and Packaging Rules
Six indicators from 2025 and 2026 combine producer results with packaging rules that will govern bottle and can supply in the profiled markets.
Table 2: Producer Results and Packaging Rule Indicators for the Sparkling Bottled Water Market (mixed units), mixed reporting years from 2025 to 2026
| Indicator | Data Point | Significance | Source |
|---|---|---|---|
| Nestlé Waters & Premium Beverages, H1 2026 | 5.1% organic growth; UTOP margin 9.5% | Premium mineral brands grow on price and mix | - |
| Danone Waters, H1 2026 | EUR 2,525 million, up 3.6% like-for-like; margin 13.3% | European summer demand lifts water profitability | - |
| US sparkling water category, 52 weeks to 28 Oct 2025 | Up 2.5%; Spindrift up 30% | Growth concentrates in fruit-led challenger brands | - |
| German mineral water, 2025 | Just under 10.2 billion litres, up 2.4%; flavored up 18% | Carbonated mineral water remains Europe's largest volume pool | - |
| EU PPWR, applying from 12 Aug 2026 | 90% separate collection of plastic bottles and metal cans by 2029 | Deposit systems become standard for PET and can formats | |
| UK deposit return scheme | Starts 1 Oct 2027 for PET, aluminium and steel containers of 150 ml to 3 litres | Adds producer fees and labelling for PET and can SKUs |
Analyst Perspective
“Sparkling water value is shifting toward brands that own the source and the bottle supply, as the Topo Chico interruption and the Perrier authorisation review showed in 2025 and 2026. Deposit and recycled-content rules in Europe, Britain and Korea will add cost to PET and cans first, which gives returnable glass and premium mineral brands a firmer pricing base through 2036.”
- Rahul Pandita, Principal Consultant, Future Market Insights.
How is the Sparkling Bottled Water Market segmented?
Sparkling bottled water market is segmented by six primary commercial axes and region: product type, distribution channel, packaging type, carbonation level, end use, price range, and region. In 2026, flavored is projected at 58.6%, hypermarket and supermarket at 47.9%, and glass bottles at 41.3%.
By product type: flavored, unflavored, and functional.
By distribution channel: hypermarket and supermarket, convenience stores, independent grocery stores, specialty stores, online retail, and others (vending and HoReCa).
By packaging type: glass bottles, PET bottles, cans, and cartons and other formats.
By carbonation level: high, medium, and low.
By end use: household consumption, foodservice and hospitality, and institutional buyers.
By price range: premium, mid range, and economy.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does flavored sparkling water hold the leading product type share?
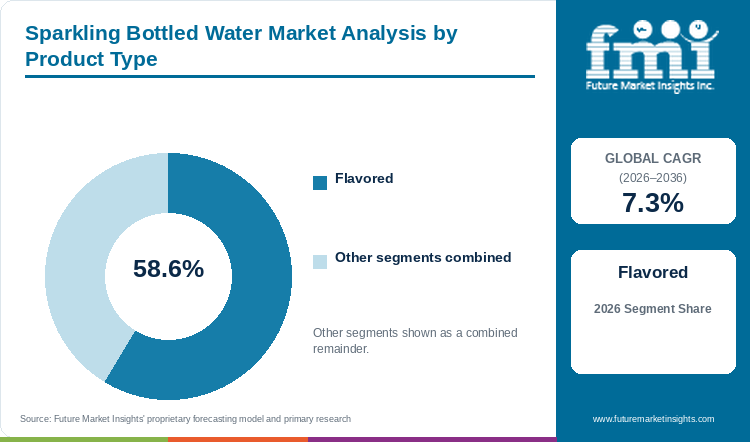
Flavored sparkling water takes 58.6% of 2026 product type value, as zero-sugar fruit and mocktail profiles recruit soda and juice drinkers.
Table 3: Product Type Share for the Sparkling Bottled Water Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Flavored | 58.6% |
| Other Segments Combined | 41.4%* |
| Total | 100.0% |
*Reflects the balance remaining after the leading segment's reported share of 100.0%.
Table 4: Product Type Leadership and Market Growth for the Sparkling Bottled Water Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.3% |
| Leading Segment | Flavored |
In the FMI report, flavored variants make up 58.6% of product type demand in 2026, with functional SKUs classified separately whenever vitamins, electrolytes or probiotics are added. PepsiCo released bubly Berry Sparkle Sangria and Paradise Paloma nationwide in September 2026, with the release noting that almost half of Americans are trying to drink less. German flavored mineral water sales rose 18% in 2025, against 2.4% for mineral water as a whole. Brands moving into added electrolytes and probiotics are likely to draw on functional water positioning as the flavored base matures. This global average blends markets where flavored cans lead, such as the United States, with Europe's much larger unflavored mineral water volumes, so country-level flavored shares vary widely around this figure.
- Flavored sparkling water accounts for 58.6% share in 2026, led by limited-edition and licensed flavor drops.
- Talking Rain's LIFE SAVERS range and PepsiCo's mocktail-style bubly flavors both entered US retail in 2026.
Why do hypermarkets and supermarkets carry the largest channel share?
Hypermarkets and supermarkets hold 47.9% of distribution channel demand in 2026; multipacks and variety packs anchor weekly grocery baskets there.
As per FMI, hypermarkets and supermarkets represent 47.9% of channel sales in 2026. New flavors often open in grocery first, and the Sparkling Ice x LIFE SAVERS range started at Kroger and Publix in January 2026, with major retailers and select convenience stores to follow in spring. Online retail is a smaller route, though Hint sells a 12-pack of Sparkling with Electrolytes cans at USD 12.99 through the brand's own website.
- Variety packs and 8 to 12-can multipacks keep grocery at 47.9% of 2026 demand.
- Direct-to-consumer sales give smaller functional brands a test channel before grocery listing.
Why do glass bottles retain the largest packaging share?
Glass bottles carry 41.3% of 2026 packaging value, backed by imported mineral brands, restaurant service and returnable systems.
Glass represents 41.3% of packaging value in 2026 in the FMI estimate, with the heaviest weight in European mineral water and premium foodservice. That share rests on a small number of sources, and problems at the Topo Chico plant in Mexico caused a US shortage of glass bottles from February 2026. In France, the Gard prefecture authorised only two of Perrier's five Vergèze boreholes for natural mineral water in December 2025, under weekly microbiological monitoring. Producers balancing glass with lighter formats will continue to source from the glass bottles supply base as PET and cans absorb most deposit obligations. In the United States, flavored sparkling water is sold mostly in cans and PET bottles, so this global glass share is driven mainly by European mineral water and imported premium brands rather than the US flavored segment.
- Glass bottles account for 41.3% share in 2026, concentrated in premium and HoReCa sales.
- The UK deposit return scheme lists PET, aluminium and steel containers, leaving glass outside the listed materials.
What are the drivers, restraints, and opportunities in the Sparkling Bottled Water Market?
In the sparkling bottled water market, zero-sugar flavor launches and premium mineral pricing drive value, source access, plant reliability and packaging compliance costs restrain supply, and functional sparkling formats offer the principal commercial opportunity.
- Driver: Zero-sugar flavor launches and price-led growth in premium mineral brands.
- Restraint: Source authorisations, plant outages and new deposit and recycled-content obligations.
- Opportunity: Sparkling water with electrolytes, probiotics and other functional additions.
Premium mineral pricing and flavor launches lift value
Nestlé's second-quarter 2026 water growth of 6.6% combined 4.4% pricing with 2.2% real internal growth, led by North America, key international brands and warm European weather. Danone's group recurring operating margin reached 13.3% in the first half of 2026, an improvement of 12 basis points year on year. Price-led premium growth is set to keep value expansion ahead of volume across the forecast decade.
Source access and packaging rules restrain supply
Natural mineral water labels require regulator approval of each source, and Perrier's December 2025 order closed three Vergèze boreholes and requires a stability report within two years. The EU Packaging and Packaging Waste Regulation, applying from 12 August 2026, requires deposit return schemes for plastic beverage bottles and cans by 2029 unless member states reach set collection rates, and plastic packaging faces recycled-content targets of 10% to 35% by 2030. South Korean producers using more than 5,000 tons of PET a year include at least 10% recycled plastic from 2026. Compliance costs are set to fall most heavily on brands sourcing PET bottles for single-serve and multipack sparkling formats.
Functional sparkling formats open new demand
Hint updated the Sparkling with Electrolytes line in May 2026 with four flavors in carbonated cans free of sugar and sweeteners. Maison Perrier's probiotic French Kiss formed part of the strong double-digit growth Nestlé reported for Sanpellegrino and Maison Perrier in the first half of 2026. Electrolyte and probiotic claims link the category to electrolyte drinks occasions such as exercise and recovery, a path toward a larger functional share by 2036.
Which country CAGRs are profiled in the Sparkling Bottled Water Market?
Table 5: Country CAGR Comparison for the Sparkling Bottled Water Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| South Korea | 7.8% |
| Japan | 7.6% |
| United States | 7.5% |
| Germany | 7.4% |
| France | 7.3% |
| Italy | 7.2% |
| United Kingdom | 7.1% |
How do country-level CAGRs compare in the Sparkling Bottled Water market?
The seven profiled rates fall within a 0.7-point band. South Korea (7.8%) and Japan (7.6%) lead on convenience-store distribution and new unsweetened formats, the United States (7.5%) relies on flavored can brands, Germany (7.4%), France (7.3%) and Italy (7.2%) expand from large mineral water bases, and the United Kingdom (7.1%) adds deposit-scheme packaging cost.
- South Korea is moving bottled water to label-free PET.
- Japan's water makers are extending carbonated lines into unsweetened fruit flavors.
- The United States leans on challenger brands such as Spindrift for growth.
- Germany, France and Italy apply new EU collection and recycled-content targets.
- The United Kingdom faces a 2027 deposit scheme and a lower sugar levy threshold.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Country-wise Analysis
- South Korea leads the profiled set with a 7.8% CAGR to 2036. Bottled water became label-free in manufacturing and distribution from 1 January 2026, with online and bundled sales converting first and single bottles in stores given a one-year transition; the government expects 2,270 metric tons a year less label plastic, based on 5.2 billion bottles made in 2024. From the same year, producers using over 5,000 tons of PET annually include at least 10% recycled plastic. These rules apply to bottled water broadly, including still water, rather than sparkling water specifically.
- Japan's sparkling bottled water sales are anticipated to expand at 7.6% a year through 2036. Domestic production and imports of mineral water (a still-water-led category figure used here as a directional proxy, not sparkling-specific) reached a record JPY 505.37 billion in 2025, up 3.1%. Asahi launched a grapefruit sparkling squash under the Wilkinson carbonated water brand in March 2026, aimed at drinkers of sweetened carbonated beverages.
- In the United States, FMI estimates growth at 7.5% CAGR through 2036, led by flavored cans. Spindrift sales rose 30% and volume 27.3% in the 52 weeks to 28 October 2025, as Sparkling Ice eased 4%. Primo Brands' premium water sales, which include Saratoga and Mountain Valley, grew to USD 114.2 million in the second quarter of 2026.
- Germany is forecast to expand at 7.4% CAGR between 2026 and 2036. Germany sold just under 10.2 billion litres of mineral and medicinal water in 2025, with per capita use up to 128.8 litres. PPWR obligations for 90% separate collection of plastic bottles and metal cans by 2029 started to apply on 12 August 2026.
- France is projected to grow at 7.3% CAGR through 2036. France's mineral water heritage brands support premium glass-bottle demand, and the same PPWR collection and recycled-content targets apply to French producers from August 2026.
- Italy is estimated to expand at 7.2% CAGR through 2036. Italy's large glass-bottled mineral water base continues to anchor foodservice and retail demand, with PPWR packaging obligations phasing in alongside the rest of the EU.
- The United Kingdom records the lowest profiled rate, at 7.1% CAGR through 2036. The deposit return scheme for England and Northern Ireland begins on 1 October 2027. HMRC confirmed in July 2026 that the Soft Drinks Industry Levy lower threshold falls from 5 grams to 4.5 grams of sugar per 100 ml from 1 January 2028, leaving zero-sugar flavored sparkling water below the threshold.
Who are the notable companies in the Sparkling Bottled Water market?
FMI profiles Nestlé Waters & Premium Beverages, Danone, The Coca-Cola Company (Topo Chico), PepsiCo (bubly), Primo Brands, National Beverage Corp. (LaCroix), Talking Rain Beverage Company, Spindrift Beverage Co., Polar Beverages, and Hint Inc.
Global water groups own the mineral sources and glass-heavy imports; US specialists compete through flavored cans and slim bottles. Ownership has changed in the past two years, with BlueTriton and Primo Water combined as Primo Brands in November 2024 and Gryphon Investors acquiring a majority stake in Spindrift in early 2025, with founder Bill Creelman retaining a significant equity stake and moving to a board chair role . Coca-Cola cut US distribution of AHA to focused channels from 2024, kept Canadian sales, and pointed to Topo Chico for sparkling water growth.
- Global water and beverage groups: Nestlé Waters & Premium Beverages, Danone, The Coca-Cola Company (Topo Chico), PepsiCo (bubly).
- North American bottled water group: Primo Brands.
- Flavored sparkling water specialists: National Beverage Corp. (LaCroix), Talking Rain Beverage Company, Spindrift Beverage Co., Polar Beverages, Hint Inc.
- Asia-Pacific sparkling water leaders: Lotte Chilsung Trevi, Asahi Wilkinson.
Competitive Benchmarking: Sparkling Bottled Water Market
Table 6: Competitive Benchmarking for the Sparkling Bottled Water Market (qualitative capability ratings), 2026
| Company | Flavored Range | Mineral and Unflavored | Functional | Reach |
|---|---|---|---|---|
| Nestlé Waters & Premium Beverages | High | High | Medium | High |
| Danone | Low | High | Low | High |
| The Coca-Cola Company (Topo Chico) | Medium | High | Low | Medium |
| PepsiCo (bubly) | High | Low | Low | Medium |
| Primo Brands | Medium | Medium | Low | Medium |
| National Beverage Corp. (LaCroix) | High | Low | Low | Medium |
| Talking Rain Beverage Company | High | Low | Low | Medium |
| Spindrift Beverage Co. | High | Low | Low | Medium |
| Polar Beverages | Medium | Low | Low | Low |
| Hint Inc. | Medium | Low | Medium | Low |
High reflects wide published documentation, Medium reflects limited published documentation, and Low reflects less direct published documentation. Ratings do not indicate product quality, market share or company rank.
Key Developments in the Sparkling Bottled Water Market
- In October 2026, Coca-Cola began a phased return of Topo Chico glass-bottled mineral water in Texas, with more states planned in 2027.
- In September 2026, PepsiCo launched two limited-edition bubly flavors in 8-packs of 12-ounce cans across US retailers.
- In July 2026, Nestlé and Platinum Equity agreed to form Peranel, a water and premium beverage joint venture with an enterprise value of USD 5.6 billion.
- In May 2026, Hint refreshed the Sparkling with Electrolytes cans with four new flavors.
Key Players in the Sparkling Bottled Water Market
Global Water and Beverage Groups
- Nestlé Waters & Premium Beverages
- Danone
- The Coca-Cola Company (Topo Chico)
- PepsiCo (bubly)
North American Bottled Water Group
- Primo Brands
Asia-Pacific Sparkling Water Leaders
- Lotte Chilsung Trevi
- Asahi Wilkinson
Flavored Sparkling Water Specialists
- National Beverage Corp. (LaCroix)
- Talking Rain Beverage Company
- Spindrift Beverage Co.
- Polar Beverages
- Hint Inc.
Sparkling Bottled Water Market - Report Scope
Table 7: Report Scope for the Sparkling Bottled Water Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; distribution channel; packaging type; carbonation level; end use; price range; region |
| Quantitative units | USD billion |
| Market definition | Retail and foodservice revenue from sealed, ready-to-drink carbonated water, including naturally sparkling and carbonated mineral water, carbonated spring or purified water, unsweetened or zero and low-sugar flavored sparkling water, and sparkling water with added functional ingredients, packed in glass, PET, cans or cartons; branded and private label products are included. Excludes sweetened carbonated soft drinks, tonic and mixers, hard seltzers, home carbonation machines and syrups, and bulk-dispensed soda water. Functional products are classified as functional whether or not flavored. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | South Korea; Japan; United States; European Union; United Kingdom |
| Key companies profiled | Nestlé Waters & Premium Beverages; Danone; The Coca-Cola Company (Topo Chico); PepsiCo (bubly); Primo Brands; National Beverage Corp. (LaCroix); Talking Rain Beverage Company; Spindrift Beverage Co.; Polar Beverages; Hint Inc. |
| Forecast period | 2026 to 2036 |
| Approach | Bottom-up volume data and top-down estimates were cross-checked to reconcile producer water segment results, retail scan data and national mineral water statistics within the defined revenue boundary. |
Sparkling Bottled Water Market - Research Methodology
Table 8: Research Methodology for the Sparkling Bottled Water Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Interviews with bottlers, brand owners, packaging suppliers, retail buyers and foodservice distributors. |
| Desk Research | Review of company results, trade association statistics, packaging and deposit regulations, and retail scan reports. |
| Market Sizing and Forecasting | Country-level value modelling by product type, channel and packaging, adjusted for pricing and regulatory changes. |
| Data Validation | Triangulation of model outputs against producer disclosures and national statistics, with analyst review of outliers. |
Sparkling Bottled Water Market by Segments
Sparkling Bottled Water Market segmented by Product Type:
- Flavored
- Unflavored
- Functional
Sparkling Bottled Water Market segmented by Distribution Channel:
- Hypermarket and Supermarket
- Convenience Stores
- Independent Grocery Stores
- Specialty Stores
- Online Retail
- Others (Vending and HoReCa)
Sparkling Bottled Water Market segmented by Packaging Type:
- Glass Bottles
- PET Bottles
- Cans
- Cartons and Other Formats
Sparkling Bottled Water Market segmented by Carbonation Level:
- High
- Medium
- Low
Sparkling Bottled Water Market segmented by End Use:
- Household Consumption
- Foodservice and Hospitality
- Institutional Buyers
Sparkling Bottled Water Market segmented by Price Range:
- Premium
- Mid Range
- Economy
Sparkling Bottled Water Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Nestlé S.A. (2026, July 23). Nestlé half-year results 2026.
- [2] Danone. (2026, July 29). Danone: Strong Q2 performance and solid H1 results, demonstrating the relevance of our health-focused portfolio.
- [3] BevNET. (2025, December 11). Fizz Factor: How soda's resurgence is helping bring flavor, focus to sparkling water.
- [4] Tageskarte. (2026, January 27). Verbraucher greifen häufiger zu Mineralwasser.
- [5] PepsiCo. (2026, September 8). bubly sparkling water stirs up two new mocktail-inspired flavors for a limited time only this fall.
- [6] Packaging Insights. (2025, December 16). South Korea mandates label-free bottled water by 2026.
- [7] International Business Times Australia. (2026, July 3). National Beverage stock jumps on special dividend as LaCroix maker reports fiscal 2026 results.
- [8] European Commission. (2024). Regulation (EU) 2025/[PPWR number] on packaging and packaging waste. Official Journal of the European Union.
[9] GOV.UK. (2025, January 27). Deposit Return Scheme: drinks producer and retailer responsibilities. - [10] Talking Rain Beverage Company. (2026, January 27). Sparkling Ice x LIFE SAVERS collab brings four new candy-inspired flavors.
- [11] Hint Inc. (2026, May 1). Hint evolves Sparkling with Electrolytes lineup with new flavor portfolio.
- [12] KTTC / CNN Newsource. (2026, October 2). Topo Chico water in glass bottles returning to store shelves in the US.
- [13] L'Info Durable / AFP. (2025, December 19). Perrier autorisé à continuer à produire de "l'eau minérale naturelle" à Vergèze (Gard).
- [14] HM Revenue & Customs. (2026, July 13). Changes to the Soft Drinks Industry Levy: policy paper.
- [15] PE Hub. (2025, January 14). Gryphon Investors to acquire Spindrift Beverage Co.
- [16] Platinum Equity. (2026, July 23). Platinum Equity and Nestlé to create Peranel, a $5.6 billion leader in water and premium beverages.
- [17] Primo Brands Corporation. (2026, August 5). Primo Brands reports 2026 second quarter results (Form 8-K, Exhibit 99.1).
- [18] Danone. (2026, July). Shareholders' letter, July 2026.
- [19] National Beverage Corp. (2026, July 1). National Beverage Corp. celebrates America with special cash dividend and reports FY 2026 results (Form 8-K, Exhibit).
- [20] Nissyoku Shimbun. (2026, June 3). Mineral water and carbonated water feature: Asahi Beverages aims to create an unsweetened fruit water category.
- [21] Primo Brands Corporation. (2024, November 8). Primo Brands Corporation announces successful completion of merger of Primo Water and BlueTriton Brands (Form 8-K, Exhibit 99.1).
- [22] Food Dive. (2023, October 9). Coca-Cola to sharply cut distribution of Aha sparkling water as sales decline.
- [23] The Boston Globe. (2026, April 9). Polar Seltzer is releasing three limited edition summer flavors and bringing back a few favorites.
This Report Answers
- How big is the sparkling bottled water market during 2026?
- What value is projected by 2036?
- Which product type holds notable share?
- Which distribution channel holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Flavored
- Unflavored
- Functional
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Hypermarket and Supermarket
- Convenience Stores
- Independent Grocery Stores
- Specialty Stores
- Online Retail
- Others (Vending and HoReCa)
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Type, 2026 to 2036
- Glass Bottles
- PET Bottles
- Cans
- Cartons and Other Formats
- Y-o-Y Growth Trend Analysis By Packaging Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Type, 2026 to 2036
- Global Market Analysis and Forecast, By Carbonation Level, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Carbonation Level, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Carbonation Level, 2026 to 2036
- High
- Medium
- Low
- Y-o-Y Growth Trend Analysis By Carbonation Level, 2021 to 2025
- Absolute $ Opportunity Analysis By Carbonation Level, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Household Consumption
- Foodservice and Hospitality
- Institutional Buyers
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Price Range, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Price Range, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Price Range, 2026 to 2036
- Premium
- Mid Range
- Economy
- Y-o-Y Growth Trend Analysis By Price Range, 2021 to 2025
- Absolute $ Opportunity Analysis By Price Range, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Carbonation Level
- By End Use
- By Price Range
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Nestlé Waters & Premium Beverages
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Danone
- The Coca-Cola Company (Topo Chico)
- PepsiCo (bubly)
- Primo Brands
- National Beverage Corp. (LaCroix)
- Talking Rain Beverage Company
- Spindrift Beverage Co.
- Polar Beverages
- Hint Inc.
- Lotte Chilsung Trevi
- Asahi Wilkinson
- Nestlé Waters & Premium Beverages
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Packaging Type, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Carbonation Level, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 7: Global Market Value (USD Billion) Forecast by Price Range, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Packaging Type, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Carbonation Level, 2021 to 2036
- Table 13: North America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 14: North America Market Value (USD Billion) Forecast by Price Range, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Packaging Type, 2021 to 2036
- Table 19: Latin America Market Value (USD Billion) Forecast by Carbonation Level, 2021 to 2036
- Table 20: Latin America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 21: Latin America Market Value (USD Billion) Forecast by Price Range, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 25: Western Europe Market Value (USD Billion) Forecast by Packaging Type, 2021 to 2036
- Table 26: Western Europe Market Value (USD Billion) Forecast by Carbonation Level, 2021 to 2036
- Table 27: Western Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 28: Western Europe Market Value (USD Billion) Forecast by Price Range, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 31: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 32: Eastern Europe Market Value (USD Billion) Forecast by Packaging Type, 2021 to 2036
- Table 33: Eastern Europe Market Value (USD Billion) Forecast by Carbonation Level, 2021 to 2036
- Table 34: Eastern Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 35: Eastern Europe Market Value (USD Billion) Forecast by Price Range, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 38: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 39: East Asia Market Value (USD Billion) Forecast by Packaging Type, 2021 to 2036
- Table 40: East Asia Market Value (USD Billion) Forecast by Carbonation Level, 2021 to 2036
- Table 41: East Asia Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 42: East Asia Market Value (USD Billion) Forecast by Price Range, 2021 to 2036
- Table 43: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 45: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 46: South Asia and Pacific Market Value (USD Billion) Forecast by Packaging Type, 2021 to 2036
- Table 47: South Asia and Pacific Market Value (USD Billion) Forecast by Carbonation Level, 2021 to 2036
- Table 48: South Asia and Pacific Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 49: South Asia and Pacific Market Value (USD Billion) Forecast by Price Range, 2021 to 2036
- Table 50: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 51: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 52: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 53: Middle East and Africa Market Value (USD Billion) Forecast by Packaging Type, 2021 to 2036
- Table 54: Middle East and Africa Market Value (USD Billion) Forecast by Carbonation Level, 2021 to 2036
- Table 55: Middle East and Africa Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 56: Middle East and Africa Market Value (USD Billion) Forecast by Price Range, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Distribution Channel
- Figure 9: Global Market Value Share and BPS Analysis by Packaging Type, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Packaging Type, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Packaging Type
- Figure 12: Global Market Value Share and BPS Analysis by Carbonation Level, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Carbonation Level, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Carbonation Level
- Figure 15: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by End Use
- Figure 18: Global Market Value Share and BPS Analysis by Price Range, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Price Range, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Price Range
- Figure 21: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 22: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 23: Global Market Attractiveness Analysis by Region
- Figure 24: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 29: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 30: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 31: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 32: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Product Type
- Figure 35: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Distribution Channel
- Figure 38: North America Market Value Share and BPS Analysis by Packaging Type, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Packaging Type, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Packaging Type
- Figure 41: North America Market Value Share and BPS Analysis by Carbonation Level, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Carbonation Level, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Carbonation Level
- Figure 44: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 45: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 46: North America Market Attractiveness Analysis by End Use
- Figure 47: North America Market Value Share and BPS Analysis by Price Range, 2026 and 2036
- Figure 48: North America Market Y-o-Y Growth Comparison by Price Range, 2026-2036
- Figure 49: North America Market Attractiveness Analysis by Price Range
- Figure 50: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 51: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Product Type
- Figure 54: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 57: Latin America Market Value Share and BPS Analysis by Packaging Type, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Packaging Type, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Packaging Type
- Figure 60: Latin America Market Value Share and BPS Analysis by Carbonation Level, 2026 and 2036
- Figure 61: Latin America Market Y-o-Y Growth Comparison by Carbonation Level, 2026-2036
- Figure 62: Latin America Market Attractiveness Analysis by Carbonation Level
- Figure 63: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 64: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 65: Latin America Market Attractiveness Analysis by End Use
- Figure 66: Latin America Market Value Share and BPS Analysis by Price Range, 2026 and 2036
- Figure 67: Latin America Market Y-o-Y Growth Comparison by Price Range, 2026-2036
- Figure 68: Latin America Market Attractiveness Analysis by Price Range
- Figure 69: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 70: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Product Type
- Figure 73: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 76: Western Europe Market Value Share and BPS Analysis by Packaging Type, 2026 and 2036
- Figure 77: Western Europe Market Y-o-Y Growth Comparison by Packaging Type, 2026-2036
- Figure 78: Western Europe Market Attractiveness Analysis by Packaging Type
- Figure 79: Western Europe Market Value Share and BPS Analysis by Carbonation Level, 2026 and 2036
- Figure 80: Western Europe Market Y-o-Y Growth Comparison by Carbonation Level, 2026-2036
- Figure 81: Western Europe Market Attractiveness Analysis by Carbonation Level
- Figure 82: Western Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 83: Western Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 84: Western Europe Market Attractiveness Analysis by End Use
- Figure 85: Western Europe Market Value Share and BPS Analysis by Price Range, 2026 and 2036
- Figure 86: Western Europe Market Y-o-Y Growth Comparison by Price Range, 2026-2036
- Figure 87: Western Europe Market Attractiveness Analysis by Price Range
- Figure 88: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 92: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 93: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 94: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 95: Eastern Europe Market Value Share and BPS Analysis by Packaging Type, 2026 and 2036
- Figure 96: Eastern Europe Market Y-o-Y Growth Comparison by Packaging Type, 2026-2036
- Figure 97: Eastern Europe Market Attractiveness Analysis by Packaging Type
- Figure 98: Eastern Europe Market Value Share and BPS Analysis by Carbonation Level, 2026 and 2036
- Figure 99: Eastern Europe Market Y-o-Y Growth Comparison by Carbonation Level, 2026-2036
- Figure 100: Eastern Europe Market Attractiveness Analysis by Carbonation Level
- Figure 101: Eastern Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 102: Eastern Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 103: Eastern Europe Market Attractiveness Analysis by End Use
- Figure 104: Eastern Europe Market Value Share and BPS Analysis by Price Range, 2026 and 2036
- Figure 105: Eastern Europe Market Y-o-Y Growth Comparison by Price Range, 2026-2036
- Figure 106: Eastern Europe Market Attractiveness Analysis by Price Range
- Figure 107: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 108: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 109: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 110: East Asia Market Attractiveness Analysis by Product Type
- Figure 111: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 112: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 113: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 114: East Asia Market Value Share and BPS Analysis by Packaging Type, 2026 and 2036
- Figure 115: East Asia Market Y-o-Y Growth Comparison by Packaging Type, 2026-2036
- Figure 116: East Asia Market Attractiveness Analysis by Packaging Type
- Figure 117: East Asia Market Value Share and BPS Analysis by Carbonation Level, 2026 and 2036
- Figure 118: East Asia Market Y-o-Y Growth Comparison by Carbonation Level, 2026-2036
- Figure 119: East Asia Market Attractiveness Analysis by Carbonation Level
- Figure 120: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 121: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 122: East Asia Market Attractiveness Analysis by End Use
- Figure 123: East Asia Market Value Share and BPS Analysis by Price Range, 2026 and 2036
- Figure 124: East Asia Market Y-o-Y Growth Comparison by Price Range, 2026-2036
- Figure 125: East Asia Market Attractiveness Analysis by Price Range
- Figure 126: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 127: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 128: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 129: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 130: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 131: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 132: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 133: South Asia and Pacific Market Value Share and BPS Analysis by Packaging Type, 2026 and 2036
- Figure 134: South Asia and Pacific Market Y-o-Y Growth Comparison by Packaging Type, 2026-2036
- Figure 135: South Asia and Pacific Market Attractiveness Analysis by Packaging Type
- Figure 136: South Asia and Pacific Market Value Share and BPS Analysis by Carbonation Level, 2026 and 2036
- Figure 137: South Asia and Pacific Market Y-o-Y Growth Comparison by Carbonation Level, 2026-2036
- Figure 138: South Asia and Pacific Market Attractiveness Analysis by Carbonation Level
- Figure 139: South Asia and Pacific Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 140: South Asia and Pacific Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 141: South Asia and Pacific Market Attractiveness Analysis by End Use
- Figure 142: South Asia and Pacific Market Value Share and BPS Analysis by Price Range, 2026 and 2036
- Figure 143: South Asia and Pacific Market Y-o-Y Growth Comparison by Price Range, 2026-2036
- Figure 144: South Asia and Pacific Market Attractiveness Analysis by Price Range
- Figure 145: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 146: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 147: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 148: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 149: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 150: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 151: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 152: Middle East and Africa Market Value Share and BPS Analysis by Packaging Type, 2026 and 2036
- Figure 153: Middle East and Africa Market Y-o-Y Growth Comparison by Packaging Type, 2026-2036
- Figure 154: Middle East and Africa Market Attractiveness Analysis by Packaging Type
- Figure 155: Middle East and Africa Market Value Share and BPS Analysis by Carbonation Level, 2026 and 2036
- Figure 156: Middle East and Africa Market Y-o-Y Growth Comparison by Carbonation Level, 2026-2036
- Figure 157: Middle East and Africa Market Attractiveness Analysis by Carbonation Level
- Figure 158: Middle East and Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 159: Middle East and Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 160: Middle East and Africa Market Attractiveness Analysis by End Use
- Figure 161: Middle East and Africa Market Value Share and BPS Analysis by Price Range, 2026 and 2036
- Figure 162: Middle East and Africa Market Y-o-Y Growth Comparison by Price Range, 2026-2036
- Figure 163: Middle East and Africa Market Attractiveness Analysis by Price Range
- Figure 164: Global Market - Tier Structure Analysis
- Figure 165: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the sparkling bottled water market expected in 2026?
FMI's 2026 estimate is USD 56.30 billion, compared with USD 52.47 billion for 2025, and the forecast reaches USD 113.90 billion by 2036, roughly twice the 2026 level.
What CAGR is projected for the sparkling bottled water market through 2036?
The FMI forecast carries a 7.3% CAGR for 2026 to 2036. Price and premium mix lead the growth, as Nestlé's second-quarter 2026 water pricing of 4.4% ran at twice the real internal growth rate. This rate sits above most single-country category growth rates, reflecting continued premiumization and flavor innovation rather than volume growth alone.
Which product type holds a notable market share in 2026?
Flavored sparkling water, with 58.6% of product type demand in 2026. Unflavored and functional variants share the remaining 41.4%.
Which distribution channel holds a notable share in 2026?
Hypermarkets and supermarkets, at 47.9% of 2026 channel demand, followed by convenience stores, online retail and other routes.
Which country has a notable expansion outlook through 2036?
South Korea, at 7.8% CAGR, leads ahead of Japan at 7.6%. Korea's switch to label-free bottles and the 10% recycled PET rule for large producers both took effect in 2026, under bottled-water-wide rules rather than sparkling-specific measures.
Who are the key companies in the sparkling bottled water market?
Notable companies include Nestlé Waters & Premium Beverages, Danone, The Coca-Cola Company (Topo Chico), PepsiCo (bubly), Primo Brands, National Beverage Corp. (LaCroix), Talking Rain Beverage Company, Spindrift Beverage Co., Polar Beverages, Hint Inc., Lotte Chilsung Trevi, and Asahi Wilkinson.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
