
- Market Size (2026)
- USD 14.5 Bn
- Forecast (2036)
- USD 25.5 Bn
- CAGR (2026 to 2036)
- 5.8%
How big is Takeaway Containers Market in 2026?
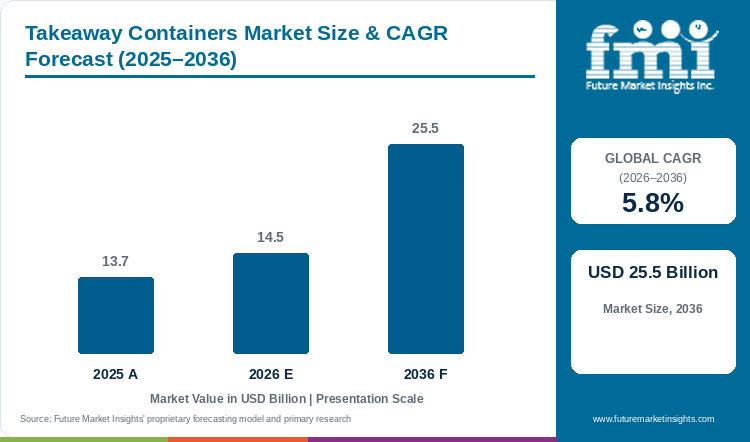
Sales in the takeaway containers market are projected to grow at 5.8% CAGR, with the market size rising from USD 13.7 Billion in 2025 to USD 14.5 Billion in 2026 and reaching USD 25.5 Billion by 2036.
According to Future Market Insights analysis, the global takeaway containers market stands at USD 13.7 Billion in 2025 and rises to USD 14.5 Billion in 2026. Industry valuation is projected to reach USD 25.5 Billion by 2036, expanding at a 5.8% CAGR and generating USD 11.0 Billion in added revenue over the forecast period. Explosive growth in app-based restaurant delivery orders and fast-casual dining drives baseline procurement across leakproof clamshells, salad bowls, and soup tubs.
In January 2025, Foodservice Packaging Institute industry data confirmed that restaurant takeout packaging shipments rose by 4.8% across metropolitan delivery hubs [1]. Rigid Containers & Bottles captures the leading position with 54.6% share in 2026, as structural rigidity protects hot meals from crushing during scooter courier transit. Growth across evaluated economies spans 4.6% in Mexico to 7.1% in Japan. Paper pulp price fluctuations and municipal bans on fluorinated greaseproofing chemicals continue to challenge converter margins.
Key Market Trends & Insights
- By packaging format: Rigid containers & bottles led with 54.6% share in 2026, as crush-resistant walls prevent meal spills during courier delivery transit.
- By material substrate: Recycled paperboard held 38.7% in 2026, supported by consumer eco-preferences and post-consumer recycled fiber pulp technologies.
- By end-use sector: Food & beverage captured 37.1% in 2026, driven by quick-service restaurant meal combos and prepared supermarket deli trays.
- By regional distribution: East Asia and North America account for major consumption, propelled by digital meal delivery platform penetration.
Regional Highlights
- Fastest-growing evaluated country: Japan, at 7.1% CAGR from 2026 to 2036.
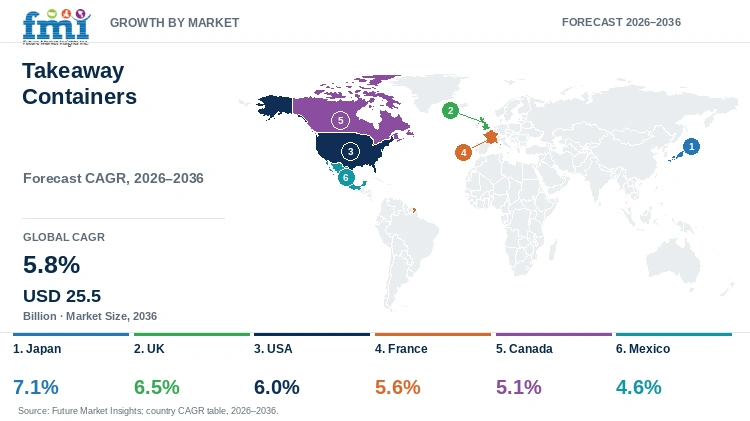
- By country: The UK at 6.5%, the USA at 6.0%, France at 5.6%, and Canada at 5.1% follow, while Mexico records the lowest evaluated CAGR at 4.6%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Takeaway Containers Market (USD Billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 13.7 Billion |
| Estimated Market Size in 2026 | USD 14.5 Billion |
| Projected Market Size by 2036 | USD 25.5 Billion |
| CAGR, 2026 to 2036 | 5.8% |
| Added Revenue, 2026 to 2036 | USD 11.0 Billion |
Future Market Insights research indicates that commercial foodservice packaging plants require automated thermoforming presses and high-speed aqueous coating applicator lines. In February 2025, U.S. Department of Agriculture commercial foodservice studies confirmed rising demand for fiber-based compostable food containers [2]. Consequently, packaging converters are installing automated leak-resistant lid-fitting skids, insulating restaurant operators from customer spillage complaints while delivering dependable thermal insulation.
Container Thermoforming and Coating Metrics
Table 2: Container Thermoforming and Coating Metrics for the Takeaway Containers Market (USD Billion and operational ranges), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD Billion) | 13.7 | 14.5 | 25.5 |
| Commercial Takeaway Container Output (Billion Units) | 148.0 to 165.0 | 156.0 to 174.0 | 275.0 to 310.0 |
| Paperboard Press Forming Energy Efficiency (kWh per 1,000 Units) | 18.5 to 22.0 | 17.5 to 20.8 | 12.8 to 15.2 |
| PFAS-Free Grease Barrier Performance Compliance (Percent) | 98.6 to 99.4 | 98.9 to 99.6 | 99.6 to 100.0 |
Per Capita Intake & Foodservice Facility Sizing
Convenient takeaway containers have maintained sustained popularity in recent years due to consumer demand for restaurant-quality dining at home and fast-paced workplace lunches. Balancing package performance requires high grease resistance and secure locking closures. Surging digital delivery apps convert household dining spending into recurring takeaway container demand. Restaurant dining chains and commercial cloud kitchens represent fundamental volume customers for disposable container converters.
Table 3: Per Capita and Foodservice Spending Indicators for the Takeaway Containers Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global Population (Billion) | 8.23 | 8.30 | 8.95 |
| Annual Takeaway Packaging Spend per Capita (USD) | 1.66 | 1.75 | 2.85 |
| Annual Spend per Food Delivery App User (USD) | 14.50 to 19.50 | 15.50 to 21.00 | 26.00 to 36.00 |
| Wholesale Procurement Spend per Quick-Service Restaurant (USD Thousand) | 22.0 to 30.0 | 23.5 to 32.5 | 42.0 to 58.0 |
Table 4: Facility & Operational Manufacturing Spending Indicators for the Takeaway Containers Market (USD and percentages), mixed reporting years from 2023 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 14.5 Billion | Report value |
| Licensed food packaging converting plants worldwide | 16,800 | 2024 secondary estimate |
| Average commercial takeaway container output per plant | USD 863.10 Thousand | Calculated |
| Rigid containers & bottles format revenue, 2026 | USD 7.92 Billion | 54.6% share |
Analyst Perspective
"The takeaway packaging sector is being reshaped by municipal plastic bans and consumer expectations for leakproof sustainability. Restaurant delivery chains demand rigid paperboard bowls and molded fiber clamshells that resist hot frying oils without relying on fluorinated PFAS coatings. Packaging converters that master aqueous dispersion barriers and tamper-evident snap closures will secure dominant multi-year supply contracts across global fast-food brands and ghost kitchen operators."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Takeaway Containers Market segmented?
The takeaway containers market is segmented by packaging format, material substrate, end-use sector, and region. In 2026, rigid containers & bottles is projected at 54.6%, recycled paperboard at 38.7%, and food & beverage at 37.1%.
By packaging format: Rigid Containers & Bottles, Flexible Wraps & Bags, and Secondary Bulk Packaging.
By material substrate: Recycled Paperboard, Thermoplastic Polymers, Sustainable Plant Fibers, and Specialty Alloys.
By end-use sector: Food & Beverage, Pharmaceuticals & Healthcare, Personal Care & Homecare, and Industrial Manufacturing.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa.
Why do rigid containers & bottles lead the packaging format category?
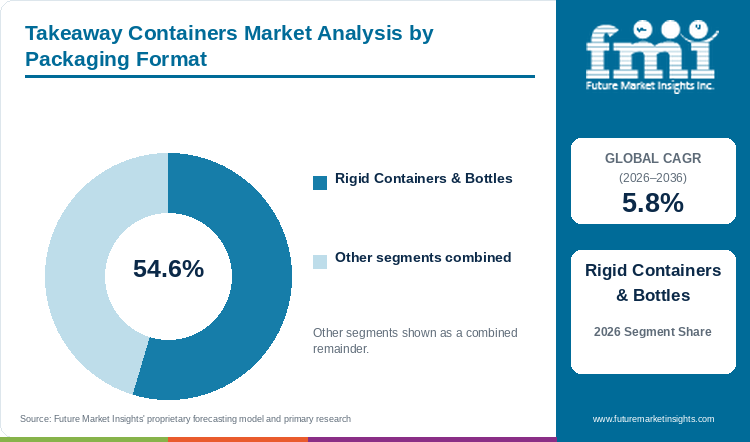
Rigid containers & bottles represents 54.6% of packaging format in 2026, providing vertical stacking strength and secure closure seals during food delivery transit.
Table 5: Packaging Format Share for the Takeaway Containers Market (percentage share), 2026
| Packaging Format | Share (2026) |
|---|---|
| Rigid Containers & Bottles | 54.6% |
| Other Segments Combined | 45.4%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Packaging Format Leadership and Market Growth for the Takeaway Containers Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.8% |
| Leading Segment | Rigid Containers & Bottles |
Restaurant operators and online couriers heavily favor rigid containers & bottles because reinforced sidewalls prevent crushing when multiple meal orders are stacked inside delivery backpacks. Rigid paperboard and plastic bowls keep food presentation intact from restaurant kitchens to consumer dining tables. Kitchen workers utilize hinged food containers to streamline meal packaging during busy lunch rushes. In addition, food delivery brands procure insulated food containers to preserve piping-hot temperatures in noodle broths. Fast-food operators also utilize fast food containers with ventilated lids to prevent fried chicken from becoming soggy. Purchasing managers contract with packaging distributors to ensure steady supplies during peak dining hours.
- Rigid containers & bottles represents 54.6% of packaging format in 2026, as multi-order stacking durability protects delivered food integrity.
- In March 2025, commercial foodservice packaging associations released updated compression resistance guidelines for delivery food containers [3].
What drives recycled paperboard to the forefront of the material substrate segment?
Recycled paperboard accounts for 38.7% of material substrate in 2026, driven by circular economy mandates, high consumer recyclability awareness, and plastic replacement initiatives.
Urban consumers and municipal regulators actively reject petroleum-based plastic food containers in favor of repulpable paperboard packaging. Converting mills manufacture rigid bowls and trays from certified recycled post-consumer paper fibers treated with natural starch sizing. Packaging engineers apply water-based dispersion barriers that provide oil resistance while allowing curbside paper recycling. Commercial kitchens also purchase disposable food containers certified for industrial composting. In addition, restaurant brands procure compostable foodservice packaging to satisfy corporate sustainability goals. Paperboard containers provide smooth outer printable surfaces for custom restaurant branding graphics.
- Recycled paperboard accounts for 38.7% of material substrate in 2026, enabled by high consumer paper recycling rates and bio-based barrier coatings.
- In May 2025, U.S. Food and Drug Administration food contact safety reviews affirmed purity thresholds for recycled paperboard in hot food service [4].
Why does food & beverage define the largest end-use sector?
Food & beverage holds 37.1% of end-use sector in 2026, driven by quick-service restaurant meal orders, casual dining takeaways, and supermarket prepared food counters.
Commercial restaurants, food courts, and corporate dining facilities consume billions of disposable containers each week to serve lunch and dinner patrons. Ghost kitchens operating exclusively on mobile delivery apps utilize standardized packaging that fits modular courier bags. Packaging analysts evaluate rigid food containers to assess structural durability across fast-food franchises. Independent researchers also track rigid food containers share analysis to benchmark conversion speeds. Furthermore, delivery brands evaluate united kingdom compostable foodservice packaging and south korea compostable foodservice packaging to comply with strict municipal waste sorting laws. Foodservice operators select container vendors that offer reliable weekly replenishment.
- Food & beverage holds 37.1% of end-use sector in 2026, sustained by high delivery order frequency across quick-service restaurant chains.
- In June 2025, European Food Safety Authority packaging safety panels validated aqueous bio-barrier coatings for hot beverage and food service containers [5].
What are the drivers, restraints, and opportunities in the Takeaway Containers Market?
Mobile food delivery growth accelerates container sales, while raw pulp costs challenge converters and certified PFAS-free coatings unlock premium value.
- Driver: Worldwide expansion of mobile food delivery apps, urbanization, and consumer preference for convenient ready-to-eat restaurant meals drive steady container demand.
- Restraint: Regulatory bans on fluorinated PFAS grease-proofing agents and plastic packaging taxes elevate manufacturing costs for paper converters.
- Opportunity: Commercial adoption of mineral-coated paperboard, molded sugarcane bagasse, and seaweed-derived water barriers allows brands to capture premium eco-conscious restaurant accounts.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
The proliferation of online food delivery platforms permanently alters consumer dining habits, transforming restaurant food into an everyday home convenience. Busy households regularly order dinners from multiple local restaurants, generating recurring demand for durable, insulated takeaway packaging. Future Market Insights research indicates that restaurants utilizing certified eco-friendly packaging experience higher customer reorder rates and positive online reviews. In September 2025, restaurant consumer survey data confirmed that 73.8% of delivery customers preferred restaurants that used paper-based or compostable containers over plastic boxes [7]. Foodservice operators respond by transitioning toward molded plant-fiber containers.
Risk Assessment of the Takeaway Containers Market: Operational and Formulation Friction
Grease leakage and food temperature loss represent persistent operational hazards for commercial food packaging manufacturers. In the absence of traditional PFAS chemicals, older water-based barrier coatings often soften when exposed to hot frying oil or boiling gravies, causing container bottoms to buckle. Furthermore, fluctuating raw paperboard pulp prices squeeze converter profit margins during periods of supply chain tightness. In October 2025, packaging logistics reports documented that container freight shipping tariffs rose by 11.5% across international transit lines [8]. Converting plants must run automated leak testing on thermoformed containers to guarantee structural hold.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Converting companies capture substantial profit margin expansion by introducing tamper-evident tear strips, modular compartmentalized bento boxes, and microwave-safe vented containers. Brands develop containers with integrated steam-release vents that keep fried foods crispy without cooling meal temperatures. In addition, converters manufacture containers from rapidly renewable bamboo and sugarcane bagasse fibers. Packaging formulators also apply natural plant wax barriers to ensure zero oil migration. In November 2025, restaurant packaging scanner data indicated that tamper-evident paperboard delivery containers achieved a 22.6% sales increase across quick-service chains [9].
Takeaway Containers Market by Country (2026 to 2036)
As per Future Market Insights, Japan represents the fastest-growing takeaway containers market among the six evaluated countries, at a 7.1% CAGR from 2026 to 2036, while Mexico records the slowest expansion at 4.6% CAGR. Across all six covered economies, commercial success is dictated by how effectively converters comply with single-use plastic bans, engineer leakproof closures, and maintain cost-competitive high-speed thermoforming.
Table 7: Country CAGR and Primary Growth Levers for the Takeaway Containers Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Japan | 7.1% | Sophisticated convenience store bento culture, strict waste sorting laws, and advanced molded pulp container engineering |
| UK | 6.5% | Nationwide single-use plastic takeaway bans, rapid food delivery app growth, and high consumer adoption of compostable packaging |
| USA | 6.0% | Massive online food delivery volume, ghost kitchen expansion, and state-level legislative bans on expanded polystyrene containers |
| France | 5.6% | Strict anti-waste circular economy legislation, mandatory reusable and paper containers in fast food, and artisan bakery packaging |
| Canada | 5.1% | Federal single-use plastics prohibition regulations, cold-weather thermal food transport demands, and expanding paperboard recycling |
| Mexico | 4.6% | Rapidly growing urban food delivery app penetration in Mexico City, street food modernization, and expanding domestic container converting |
Source: Future Market Insights analysis
Japan Takeaway Containers Market Outlook (2026 to 2036)
By 2036, Japan is projected to grow at 7.1% CAGR, driven by an ingrained convenience store bento dining culture and sophisticated molded fiber engineering. In January 2026, the Japan Packaging Institute confirmed that eco-friendly food container shipments rose by 7.4% across convenience store chains and department store food halls [10]. Japanese consumers expect pristine food aesthetics and compartmentalized bento layouts that keep sauces separated from steamed rice. Leading domestic packaging converters manufacture ultra-thin paperboard containers featuring water-based barrier films that microwave evenly. However, strict municipal waste sorting mandates require packaging to be cleanly separable into recyclable streams. Japanese converters resolve this by manufacturing mono-material paperboard containers with peelable clean liners.
Key takeaway:In Japan, sophisticated bento culinary packaging expectations and advanced molded fiber manufacturing propel the fastest growth among evaluated countries.
UK Takeaway Containers Market Outlook (2026 to 2036)
The UK takeaway containers market is anticipated to advance at 6.5% CAGR over the assessment period, owing to national single-use plastic bans and massive food delivery app adoption. In March 2025, the UK Foodservice Packaging Association documented that restaurant transitions to paperboard and molded bagasse packaging accelerated following plastic tax enforcements [11]. British diners order high volumes of fish and chips, curry, and gourmet burgers through digital apps, requiring leakproof containers that handle hot gravies. Packaging distributors supply certified plastic-free food boxes to high-street restaurants. However, paperboard raw material import price volatility creates margin pressure for converters. Manufacturers mitigate this barrier by optimizing structural fluting to reduce board basis weight without losing rigidity.
Key takeaway:In the UK, strict single-use plastic prohibitions and established online delivery dining routines sustain strong market revenue.
USA Takeaway Containers Market Outlook (2026 to 2036)
In the USA, takeaway containers demand is predicted to advance at 6.0% CAGR through 2036, enabled by a massive online restaurant delivery market and state-level bans on expanded polystyrene foam. In April 2025, the Foodservice Packaging Institute reported that commercial restaurant packaging purchases reached USD 5.8 Billion across quick-service and fast-casual chains [12]. American consumers prioritize tamper-evident packaging that guarantees food safety during third-party delivery trips. Ghost kitchens in urban centers utilize standardized stackable containers that optimize courier backpack space. However, bans on PFAS chemicals force manufacturers to reformulate grease barriers, creating temporary supply adjustments. Converters resolve this by deploying water-based aqueous dispersion barriers that provide superior oil holdout.
Key takeaway:In the USA, massive food delivery order volumes and rapid transitions toward PFAS-free paperboard containers drive robust category expansion.
France Takeaway Containers Market Outlook (2026 to 2036)
Adoption of takeaway containers in France is estimated to expand at 5.6% CAGR through 2036, supported by anti-waste circular economy laws (AGEC) and artisan bakery sandwich packaging. In May 2025, the French Ministry of Ecological Transition reported widespread restaurant compliance with disposable plastic phase-out timetables [13]. French bakeries and bistros utilize recyclable paperboard boxes and greaseproof paper wraps for lunchtime baguettes and quiches. Fast-food franchises install automated dishwashing stations for dine-in while providing certified repulpable containers for takeaway orders. However, high compliance overhead and strict inspection penalties challenge small independent restaurants. Packaging suppliers overcome this hurdle by developing standardized, multi-purpose paperboard boxes suited for diverse culinary menus.
Key takeaway:In France, pioneering circular economy packaging mandates and artisan gourmet sandwich demands maintain steady category performance.
Canada Takeaway Containers Market Outlook (2026 to 2036)
The Canada takeaway containers sector is projected to record 5.1% CAGR during the assessment period, reinforced by federal single-use plastics prohibitions and cold-weather thermal meal transit needs. In June 2025, Statistics Canada confirmed steady shipment growth for domestic paper-based food container manufacturing facilities [14]. Canadian consumers order delivery meals during harsh winter months, requiring containers with high thermal insulation to keep food hot during transit. Canadian restaurants replace plastic clamshells with corrugated paperboard boxes and molded fiber bowls. However, long shipping distances between provincial distribution centers elevate freight overhead. Packaging manufacturers mitigate this challenge by supplying nested container designs that maximize pallet freight efficiency.
Key takeaway:In Canada, federal plastic ban compliance and thermal food insulation demands support dependable category momentum.
Mexico Takeaway Containers Market Outlook (2026 to 2036)
Mexico takeaway containers demand is forecast to rise at 4.6% CAGR over the forecast period, supported by expanding food delivery app adoption in metropolitan centers and street food modernization. In July 2025, the National Chamber of the Restaurant and Seasoned Food Industry in Mexico reported expanding commercial packaging procurement across urban quick-service outlets [15]. Mexican urbanites frequently order tacos and tortas through mobile apps, creating demand for sturdy, grease-resistant packaging. In addition, supermarket deli counters expand prepared rotisserie chicken packaging in rigid containers. However, consumer price sensitivity and the continued prevalence of low-cost unbranded plastic bags in informal markets limit premium packaging penetration. Converters address this barrier by offering economical unbleached kraft paperboard containers.
Key takeaway:In Mexico, rising urban digital food delivery penetration and street food packaging modernization provide dependable long-term market growth.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Takeaway Containers Market?
Huhtamaki Oyj, Amcor plc, Berry Global Group, Inc., Smurfit Westrock plc, Sealed Air Corporation, Sonoco Products Company, Mondi plc, Silgan Holdings Inc., and Ball Corporation are the significant market players in this market.
Future Market Insights analysis indicates that the competitive environment divides between multinational paper packaging converters, diversified rigid plastic container manufacturers, and sustainable molded fiber specialists. Paper packaging corporations operate high-speed printing, die-cutting, and forming plants that manufacture folding food boxes, salad bowls, and paperboard cups. Rigid plastic processors utilize automated injection molding and thermoforming lines to produce reusable, microwave-safe polypropylene containers. Molded fiber innovators convert agricultural bagasse and recycled paper pulp into fully biodegradable clamshells. Restaurant procurement directors evaluate container suppliers on leak resistance, lid retention under pressure, stacking stability, and competitive unit wholesale pricing.
- Global Paper Packaging & Converting Leaders: Huhtamaki Oyj, Smurfit Westrock plc, Mondi plc, and Sonoco Products Company manufacture sustainable paperboard food containers, folding cartons, and food service cups.
- Rigid Plastic & Protective Packaging Giants: Amcor plc, Berry Global Group, Inc., and Sealed Air Corporation engineer high-barrier rigid containers, leakproof closures, and protective food wraps.
- Precision Metal & Specialty Container Producers: Silgan Holdings Inc. and Ball Corporation formulate specialized metal and rigid packaging solutions for commercial foodservice applications.
Competitive Benchmarking: Takeaway Containers Market
Table 8: Competitive Benchmarking for the Takeaway Containers Market (qualitative capability ratings), 2026
| Company | Paperboard Forming Capacity | Plastic-Free Barrier Innovation | Foodservice Chain Distribution | Tamper-Evident Closure Engineering |
|---|---|---|---|---|
| Huhtamaki Oyj | High | High | High | High |
| Amcor plc | High | High | High | High |
| Berry Global Group, Inc. | High | Medium | High | High |
| Smurfit Westrock plc | High | High | High | High |
| Sealed Air Corporation | Medium | High | High | High |
| Sonoco Products Company | High | High | Medium | Medium |
| Mondi plc | High | High | Medium | Medium |
| Silgan Holdings Inc. | Medium | Medium | Medium | High |
| Ball Corporation | Low | Low | Low | High |
Key Developments in the Takeaway Containers Market
- In March 2026, Huhtamaki expanded its partnership with Just Eat Takeaway.com to roll out plastic-free, fully recyclable corrugated takeaway boxes across 10 European markets, including Germany, Italy, the Netherlands, Poland, and Spain. The boxes are made from sustainably sourced corrugated paper and coated with Xampla’s Morro Coating, a plant-based alternative to conventional plastic coatings, supporting compliance with the EU Single Use Plastic Directive.
- In May 2026, Amcor launched PP Revolution™, a new range of recycle-ready polypropylene dip cups for condiments, dressings, and sauces targeting the foodservice sector. Available in 10 sizes from 0.5 oz to 2.0 oz, select sizes carry How2Recycle® prequalification and a “Widely Recyclable” designation in Canada, supporting foodservice operators in meeting evolving sustainability packaging regulations.
- In August 2025, Smurfit Westrock collaborated with Papa John’s to develop the Tremendous Triple Box, a single-unit corrugated carton designed to hold three medium pizzas alongside four side orders. The packaging improved logistical efficiency for food delivery while strengthening consumer engagement through a customised structural design, demonstrating Smurfit Westrock’s paper-based foodservice packaging innovation for quick-service restaurant operators.
Key Players in the Takeaway Containers Market
Global Paper Packaging & Converting Leaders
- Huhtamaki Oyj
- Smurfit Westrock plc
- Mondi plc
- Sonoco Products Company
Rigid Plastic & Protective Packaging Giants
- Amcor plc
- Berry Global Group, Inc.
- Sealed Air Corporation
Precision Metal & Specialty Container Producers
- Silgan Holdings Inc.
- Ball Corporation
Takeaway Containers Market - Report Scope
Table 9: Report Scope for the Takeaway Containers Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Packaging Format; Material Substrate; End-Use Sector |
| Quantitative Units | USD Billion |
| Market Definition | Encompasses global manufacturer and converter revenue from rigid and semi-rigid disposable food containers, bowls, clamshells, boxes, and cups sold into foodservice takeaway, restaurant delivery, and grocery prepared meal applications. Excludes retail consumer plastic food storage sets sold for home kitchen reuse. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Japan, UK, USA, France, Canada, Mexico, and additional countries in the full report |
| Key Companies Covered | Huhtamaki Oyj, Amcor plc, Berry Global Group, Inc., Smurfit Westrock plc, Sealed Air Corporation, Sonoco Products Company, Mondi plc, Silgan Holdings Inc., Ball Corporation |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Takeaway Containers Market - Research Methodology
Table 10: Research Methodology for the Takeaway Containers Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with packaging plant engineers, foodservice distributor executives, quick-service restaurant procurement managers, paperboard converting directors, and commercial kitchen operators to validate container unit shipments, machine forming line speeds, wholesale contract pricing, and material substitution trends. |
| Secondary Research | Secondary research included analysis of global foodservice packaging trade datasets, municipal waste management regulatory publications, corporate annual filings, packaging science journals, and retail point-of-sale scanner data. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 forecast period were developed using top-down and bottom-up models evaluating raw paperboard and resin consumption, thermoforming press capacities, and commercial restaurant meal delivery transactions. |
| Data Triangulation and Validation | Data is validated against macroeconomic consumer food spending metrics, global paperboard shipment volumes, foodservice franchise store counts, and historical industry benchmarks to ensure high precision without double counting general beverage cups. |
Takeaway Containers Market by Segments
Takeaway Containers Market segmented by Packaging Format:
- Rigid Containers & Bottles
- Flexible Wraps & Bags
- Secondary Bulk Packaging
Takeaway Containers Market segmented by Material Substrate:
- Recycled Paperboard
- Thermoplastic Polymers
- Sustainable Plant Fibers
- Specialty Alloys
Takeaway Containers Market segmented by End-Use Sector:
- Food & Beverage
- Pharmaceuticals & Healthcare
- Personal Care & Homecare
- Industrial Manufacturing
Takeaway Containers Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Switzerland
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Foodservice Packaging Institute. (2025, January 16). Foodservice Packaging Trends and Consumer Delivery Preferences Report. FPI Publications.
- [2] U.S. Department of Agriculture Economic Research Service. (2025, February 18). Food Service and Restaurant Industry Expenditures and Packaging Metrics. USDA Publications. https://www.usda.gov
- [3] Food and Agriculture Organization. (2025, March 20). Sustainable Food Packaging Systems and Single-Use Plastic Reduction in Foodservice. FAO Bulletins. https://www.fao.org
- [4] U.S. Food and Drug Administration Center for Food Safety and Applied Nutrition. (2025, May 22). Food Contact Substance Notification Program and PFAS Chemical Phasing Guidance. FDA Publications. https://www.fda.gov
- [5] European Food Safety Authority. (2025, June 16). Scientific Opinion on the Safety of Recycled Plastics and Paperboard Materials in Food Contact Applications. EFSA Journal. https://www.efsa.europa.eu
- [6] National Restaurant Association. (2025, August 14). State of the Restaurant Industry: Takeout, Delivery, and Off-Premises Dining Operations. NRA Reports.
- [7] European Paper Packaging Alliance. (2025, September 22). Comparative Life Cycle Assessment of Single-Use Paperboard versus Multi-Use Foodservice Systems. EPPA Studies.
- [8] International Packaging Logistics Association. (2025, October 18). Commercial Transit and Cold-Chain Foodservice Packaging Performance Benchmarks. IPLA Data.
- [9] Institute of Packaging Professionals. (2025, November 12). Advances in PFAS-Free Water-Based Dispersion Coatings for Food Containers. IoPP Journal.
- [10] Japan Packaging Institute. (2026, January 16). Annual Report on the Japanese Foodservice Packaging Market and Eco-Container Shipments. JPI Reports.
- [11] UK Foodservice Packaging Association. (2025, March 25). Single-Use Plastic Regulations Compliance and Packaging Transition in the UK. FPA Bulletins.
- [12] Foodservice Packaging Institute. (2025, April 22). U.S. Foodservice Packaging Shipments and Material Substitution Analysis. FPI Economic Data.
- [13] French Ministry of Ecological Transition. (2025, May 28). Circular Economy and Waste Reduction Law (AGEC): Impact on Foodservice Packaging. Government of France Publications.
- [14] Statistics Canada. (2025, June 18). Monthly Survey of Manufacturing: Converted Paper Product Manufacturing Shipments. StatCan Daily.
- [15] National Chamber of the Restaurant and Seasoned Food Industry (CANIRAC). (2025, July 24). Foodservice Packaging Modernization and Delivery Trends in Mexico. CANIRAC Reports.
- [16] Sonoco Products Company. (2025, October 24). Sustainable Paperboard Food Container and Closure Portfolio Enhancements. Sonoco News.
- [17] Sealed Air Corporation. (2026, January 14). Temperature-Controlled Protective Packaging for Commercial Food Delivery. Sealed Air Investor Center.
- [18] Berry Global Group, Inc. (2025, July 16). Lightweight Polypropylene Container Manufacturing and Circular Resin Integration. Berry Global Media Releases.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the takeaway containers market in 2026 and what is forecast for 2036?
- Which digital food delivery habits support steady demand for takeaway containers?
- Why do rigid containers & bottles lead the packaging format category?
- Why does recycled paperboard lead the material substrate category globally?
- How do growth rates prominently differ across Japan, the UK, the USA, and Mexico?
- Which leading packaging corporations supply commercial takeaway food containers today?
- What limits raw paperboard pulp availability or PFAS-free coating scaling in this market?
- What should restaurant chain procurement directors evaluate deeply before purchasing takeaway packaging?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Rigid Containers & Bottles
- Flexible Wraps & Bags
- Secondary Bulk Packaging
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Material Substrate, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Substrate, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Substrate, 2026 to 2036
- Recycled Paperboard
- Thermoplastic Polymers
- Sustainable Plant Fibers
- Specialty Alloys
- Y-o-Y Growth Trend Analysis By Material Substrate, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Substrate, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Sector, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Sector, 2026 to 2036
- Food & Beverage
- Pharmaceuticals & Healthcare
- Personal Care & Homecare
- Industrial Manufacturing
- Y-o-Y Growth Trend Analysis By End-Use Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Switzerland
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Huhtamaki Oyj
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Amcor plc
- Berry Global Group, Inc.
- Smurfit Westrock plc
- Sealed Air Corporation
- Sonoco Products Company
- Mondi plc
- Silgan Holdings Inc.
- Ball Corporation
- Huhtamaki Oyj
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Packaging Format
- Figure 6: Global Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Material Substrate
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Sector
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Packaging Format
- Figure 26: North America Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Material Substrate
- Figure 29: North America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by End-Use Sector
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Packaging Format
- Figure 36: Latin America Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Material Substrate
- Figure 39: Latin America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by End-Use Sector
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Packaging Format
- Figure 46: Western Europe Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Material Substrate
- Figure 49: Western Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by End-Use Sector
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Packaging Format
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Material Substrate
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by End-Use Sector
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Packaging Format
- Figure 66: East Asia Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Material Substrate
- Figure 69: East Asia Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by End-Use Sector
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Packaging Format
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Material Substrate
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by End-Use Sector
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Packaging Format
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Material Substrate
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by End-Use Sector
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the takeaway containers market in 2026, and what is forecast for 2036?
Future Market Insights estimates that the global takeaway containers market will reach USD 14.5 Billion in 2026. The market is projected to reach USD 25.5 Billion by 2036, driven by continuous growth in app-based restaurant food delivery orders and fast-casual dining.
What is the CAGR for the takeaway containers market from 2026 to 2036?
As per FMI, the market is projected to expand at a 5.8% CAGR over the assessment period. Growth is supported by ongoing product innovation into certified plastic-free aqueous coatings, molded bagasse bowls, and tamper-evident locking lids.
Which packaging format segment leads the takeaway containers market?
Future Market Insights projects that rigid containers & bottles will hold 54.6% share in 2026. The segment benefits from structural crush resistance during courier transit, secure lid fitment, and vertical stacking durability.
Which material substrate segment leads the takeaway containers market?
Foodservice packaging research indicates that recycled paperboard will account for 38.7% share in 2026. Demand is supported by high curbside consumer paper recycling rates, circular economy regulations, and sustainable brand aesthetics.
Which country has a notable growth outlook during the assessment period?
FMI finds that Japan is projected to register a 7.1% CAGR from 2026 to 2036. High market growth is supported by a sophisticated convenience store bento culture, strict waste sorting laws, and advanced molded pulp container engineering.
Who are the key players in the market?
Key participants include Huhtamaki Oyj, Amcor plc, Berry Global Group, Inc., Smurfit Westrock plc, Sealed Air Corporation, Sonoco Products Company, Mondi plc, Silgan Holdings Inc., and Ball Corporation. Leading market participants focus on automated high-speed thermoforming, PFAS-free barrier coatings, and tamper-evident container designs.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
