
- Market Size (2026)
- USD 154.9 Mn
- Forecast (2036)
- USD 5385.8 Mn
- CAGR (2026 to 2036)
- 42.6%
How big is TV White Space Spectrum Market in 2026?
The global TV white space spectrum market is estimated at USD 108.6 million in 2025 and is expected to reach USD 154.9 million in 2026. Over 2026 to 2036, sales of TV white space equipment and services are likely to grow at a CAGR of 42.6% and reach USD 5,385.8 million. According to FMI analysis, radios are expected to hold the largest share, at 49.3% of 2026 component sales.
Adoption of shared spectrum is drawing more attention from regulators. This is visible in the 2026 DSA Global Summit, which the Dynamic Spectrum Alliance held in London in October 2026 under the theme of dynamic spectrum access and AI [1]. Greater regulatory interest in sharing improves the case for database-managed access to unused TV channels. Demand for TV white space links from rural operators is rising, since cheap long-range wireless can reach scattered homes. For instance, about 2.2 billion people remained offline in 2025, and only 58% of rural residents used the Internet against 85% in urban areas [2]. Sales of white space radios also have wide room to grow, as over three billion people remain unconnected according to GSMA [3]. FMI analysis shows that rural access gaps of this size will keep low-cost radios at the centre of connectivity plans.
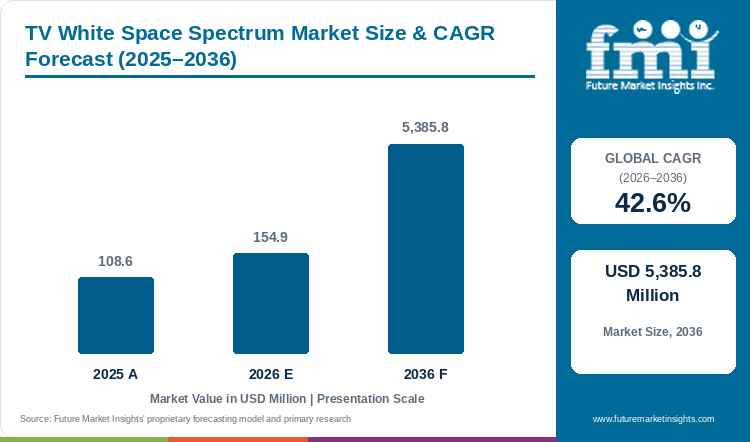
Table 1: TV White Space Spectrum Market Size and Forecast (USD million), 2025 to 2036
| Market size and forecast | Value |
|---|---|
| 2025 market size | USD 108.6 million |
| Estimated market size in 2026 | USD 154.9 million |
| Projected market size by 2036 | USD 5,385.8 million |
| CAGR (2026 to 2036) | 42.6% |
| Added sales, 2026 to 2036 | USD 5,230.9 million |
Key Market Trends & Insights
- By component: Radios account for 49.3% of 2026 component sales, as every link needs a base station and customer unit tuned to the UHF band, ahead of antennas, backhaul, power and cabling.
- By software and services: Software is set to capture 52.7% of the software and services segment in 2026, since geolocation databases and network management tools decide which channels each device may use.
- By device: Fixed devices lead with an estimated 63.5% share in 2026, as rural broadband links use rooftop customer units and tower-mounted base stations.
Regional Highlights
- Fastest-growing country: South Korea holds the highest rate in the profiled set, a 42.6% CAGR over 2026 to 2036 that equals the global pace, as safety and sensor networks in mountain areas use these long-range links.
- Growth across other countries: The United States is projected at 42.5% and India at 42.4%, as rural and tribal providers and village broadband schemes buy long-range links. Japan (42.3%), Canada (42%) and South Africa (41.9%) follow closely, with demand coming from disaster networks, remote communities and rural schools. Dense fibre leaves the United Kingdom with the lowest rate, a 41.8% CAGR.
Rural networks need radio signals that travel far, but at remote sites a reliable power supply matters as much as signal range. More than 240 million people joined the online population in 2025, but 96% of the offline population lives in low- and middle-income countries [2]. Hence, most new users will live far from fibre, which favours long-range wireless links. Power is the second constraint at remote sites, as more than 666 million people still had no electricity in 2023 [4]. Base stations in such areas need solar panels and batteries, which raises the share of power supplies in each project. Suppliers that sell radios together with solar power kits gain an edge in rural tenders.
How mobile operators make money shapes demand for rural links. GSMA put the economic value of mobile at USD 7.6 trillion in 2025, equal to 6.4% of global GDP [3]. Operators earn most of that value in cities, which leaves little reason to build costly rural towers. Prices of Internet access add pressure, as access is unaffordable in around 60% of low- and middle-income countries [2]. Accordingly, low-cost TV white space links appeal to community networks, utilities and local providers. The cost of connecting each home remains the deciding factor in every project.
Popularity of broadcast TV, along with regulation, shapes how many channels stay unused. Broadcast TV viewing in the United Kingdom fell 4% in 2024 to 2 hours 24 minutes per day, and broadcast content made up 56% of in-home viewing [5]. As a result, debate over the future of broadcast channels is growing, and the outcome could raise or cut the spectrum left free. Spectrum protection works against wider sharing, as ITU and WMO called in September 2026 for protection of radio spectrum used for weather, climate and water services [6]. The two bodies also said demand for wireless communications continues to grow, so interference rules for shared bands are likely to tighten. Accurate spectrum databases will become a selling point for white space vendors.
Table 2: Supporting Industry Indicators for the TV White Space Spectrum Market, 2023 to 2026
| Indicator | Data point | Why it matters | Source |
|---|---|---|---|
| Offline population | About 2.2 billion people offline in 2025, down from a revised 2.3 billion in 2024 | Large pool of homes for long-range links | [2] |
| Rural and urban gap | 58% of rural residents online against 85% in urban areas (2025) | Rural areas are the core TV white space use case | [2] |
| Unconnected people | Over three billion people remain unconnected; usage gap almost 10 times the coverage gap (March 2026) | Affordable access matters as much as coverage | [3] |
| Mobile economic value | USD 7.6 trillion in 2025, 6.4% of global GDP | Scale of the industry that TV white space complements | [3] |
| Electricity access gap | Over 666 million people without electricity in 2023 | Remote sites need off-grid power supplies | [4] |
| Solar capacity | Solar reached 1,865 GW in 2024, over three-quarters of renewable additions | Low-cost solar powers remote base stations | [7] |
| Broadcast TV viewing | UK broadcast viewing fell 4% in 2024 to 2 hours 24 minutes per day | Falling linear viewing reopens debate on UHF use | [5] |
| Spectrum protection | ITU and WMO call to protect weather and climate spectrum (September 2026) | Interference rules tighten for shared bands | [6] |
| Submarine cables | Submarine cables carry more than 99% of data traffic (July 2026) | Backhaul depends on resilient international links | [8] |
| Dynamic spectrum policy | DSA Global Summit in London focused on dynamic spectrum access and AI, with Ofcom, FCC and ICASA (October 2026) | Regulators are exploring wider spectrum sharing | [1] |
Demand Intensity Analysis
The number of people offline gives the most direct outside measure for the estimate. About 2.2 billion people remained offline in 2025, according to ITU [2]. The market is estimated at USD 108.6 million in 2025, or roughly USD 0.049 per offline person. Many offline people live in areas better served by mobile or satellite, so the ratio overstates the reach of TV white space. Even so, the very low value per person shows how early the technology still is in rural networks.
The mobile industry provides a broad, sector-wide comparison for the estimate. GSMA estimated the economic value of mobile at USD 7.6 trillion in 2025 and counted over three billion people still unconnected [3]. At USD 108.6 million, the market equals about 0.0014% of that value, or about USD 0.036 per unconnected person. The GSMA figure covers the whole mobile industry, beyond equipment sales, so the ratio is only a rough guide. The comparison still confirms that TV white space is a small add-on to mobile networks.
User growth on the Internet gives a yardstick for the 42.6% CAGR. More than 240 million people joined the online population in 2025, against a revised 5.8 billion users in 2024 [2]. That equals growth of about 4.1%, far below the 42.6% CAGR for 2026 to 2036. To close that gap, market value per new Internet user would need to rise by about 36.9% a year. The forecast thus assumes rural projects move from small trials to large rollouts, helped by policy support and cheaper devices.
Table 3: Demand Intensity Metrics for the TV White Space Spectrum Market, 2024 and 2025 Data Against 2025 Market Values
| Demand intensity metric | Value | Basis |
|---|---|---|
| Offline population, 2025 | About 2.2 billion | International Telecommunication Union, 2025 estimate |
| Market value per offline person | USD 0.049 | Calculated from ITU 2025 offline population and the 2025 market value |
| Economic value of mobile, 2025 | USD 7.6 trillion | GSMA, March 2026 |
| Market value as a share of mobile economic value | 0.0014% | Calculated from GSMA figures and the 2025 market value |
| People still unconnected | Over three billion | GSMA, March 2026 |
| Market value per unconnected person | USD 0.036 | Calculated from GSMA figures and the 2025 market value |
| People joining the online population, 2025 | More than 240 million | International Telecommunication Union, 2025 estimate |
| Online population growth, 2025 | 4.1% | Calculated from ITU 2025 additions and the revised 2024 user base |
| Implied annual growth in value per newly connected user | 36.9% | Calculated from the 42.6% CAGR and ITU online population growth |
Analyst Perspective
“TV white space has spent a decade in trials, but the economics now favour larger rollouts. Rural providers need long-range links that cost less than fibre or towers, and regulators are warming to sharing managed by databases. Vendors that bundle radios, spectrum databases and solar power into one package will turn pilots into national rollouts.”
- Sudip saha, Principal Consultant, Future Market Insights.
How is the TV white space spectrum market segmented?
The market is segmented into component, software and services, device, end-use application, and region. Radios are expected to lead component with 49.3% share in 2026, and software leads software and services with an estimated 52.7%.
By component: radios, antennas, backhaul and services, power supplies, and cables.
By software and services: software and services.
By device: fixed and portable TV white space devices.
By end-use application: rural internet access, urban connectivity, smart grid networks, IoT and M2M, emergency and public safety, transportation and logistics, and vehicle broadband access.
By region: rural operators, utilities and public agencies across North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do radios lead by component?
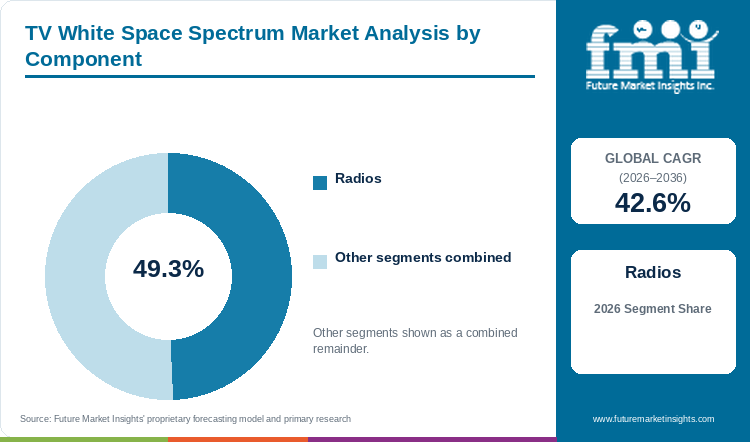
Radios are expected to lead component sales with 49.3% share in 2026, ahead of antennas at an estimated 17.6% and backhaul and services near 13.4%.
Table 4: Component Share for the TV White Space Spectrum Market (percentage share), 2026
| Component | Estimated Share (2026) |
|---|---|
| Radios | 49.3% |
| Antennas | 17.6% |
| Backhaul and Services | 13.4% |
| Power Supplies | 10.8% |
| Cables | 8.9% |
| Total | 100.0% |
Table 5: Component Leadership and Market Growth for the TV White Space Spectrum Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 42.6% |
| Leading Segment | Radios |
Radios lead, as each network needs base station radios and home units that tune to free broadcast channels. FMI puts radios at 49.3% of 2026 sales, with antennas at 17.6%, backhaul and services at 13.4%, power supplies at 10.8% and cables at 8.9%. Supply of power matters more at sites with no grid, and solar reached 1,865 GW of installed capacity in 2024 [7]. Cheap solar panels make remote base stations affordable, which supports the power supply share. Other rural technologies are also growing, and the fixed wireless access market is projected to grow at a 13.4% CAGR from 2025 to 2035. Radios are likely to keep the lead as more units are sold each year.
- Base station radios, home units and mesh nodes make up the radio segment.
- Backhaul links connect rural radios to the wider Internet, and submarine cables carry more than 99% of data traffic, ITU said in July 2026 [8]. Reliable international links therefore support every rural white space network.
Why does software lead by software and services?
Software is expected to lead the software and services segment with 52.7% share in 2026, ahead of services at an estimated 47.3%.
Table 6: Software and Services Share for the TV White Space Spectrum Market (percentage share), 2026
| Software and Services | Estimated Share (2026) |
|---|---|
| Software | 52.7% |
| Services | 47.3% |
| Total | 100.0% |
Software holds 52.7% of 2026 sales in this segment, since location databases and network tools decide which channels each device may use. Services, at about 47.3%, cover planning, installation and maintenance for rural operators. Popularity of database tools is rising as regulators study spectrum sharing. The 2026 DSA Global Summit covered dynamic spectrum access, AI and spectrum sharing in the upper 6 GHz band [1]. Sharing rules of this kind raise demand for software that assigns channels automatically. The shift to software-based networks adds to the trend, as the network function virtualization market is projected at a 24.9% CAGR from 2025 to 2035. Software is likely to keep a slim lead through 2036.
- Location databases, channel planning tools and network management software make up the software segment.
- Spectrum demand keeps rising, and ITU and WMO said in September 2026 that demand for wireless communications, satellite services and environmental data continues to grow [6]. Rising demand increases the value of software that avoids interference.
Why do fixed devices lead by device?
Fixed TV white space devices are expected to lead device sales with 63.5% share in 2026, ahead of portable devices at an estimated 36.5%.
Table 7: Device Share for the TV White Space Spectrum Market (percentage share), 2026
| Device | Estimated Share (2026) |
|---|---|
| Fixed TV White Space Devices | 63.5% |
| Portable TV White Space Devices | 36.5% |
| Total | 100.0% |
Sales of fixed devices account for about 63.5% of the 2026 total, as rural broadband relies on base stations on towers and units on rooftops. Use of portable devices, which make up about 36.5% of sales, centres on sensors, vehicles and temporary sites. Strong rural demand keeps fixed devices in the lead, since only 58% of rural residents were online in 2025, against 85% in urban areas [2]. Closing that gap needs permanent links to homes and schools, which favours fixed equipment. High-altitude platforms compete for the same users, and the high altitude aeronautical platform stations market is projected to reach USD 17.9 billion by 2035. FMI expects portable devices to gain share as IoT uses grow.
- Base stations, rooftop customer units and fixed IoT gateways form the fixed device segment.
- Poor access to electricity limits fixed rural sites, and 85% of the 666 million people without electricity live in sub-Saharan Africa [4]. Fixed devices sold into such areas increasingly ship with solar kits.
Why does rural internet access lead by end-use application?
Rural internet access is expected to lead end-use application sales with 34.2% share in 2026, ahead of urban connectivity at an estimated 14.6% and smart grid networks near 12.3%.
Table 8: End-use Application Share for the TV White Space Spectrum Market (percentage share), 2026
| End-use Application | Estimated Share (2026) |
|---|---|
| Rural Internet Access | 34.2% |
| Urban Connectivity | 14.6% |
| Smart Grid Networks | 12.3% |
| IoT and M2M | 11.8% |
| Emergency and Public Safety | 10.4% |
| Transportation and Logistics | 9.1% |
| Vehicle Broadband Access | 7.6% |
| Total | 100.0% |
Rural internet access leads with 34.2% of 2026 sales, as long-range broadcast-band signals reach farms and villages that fibre and towers skip. Urban connectivity holds 14.6%, smart grid networks 12.3%, IoT and M2M 11.8%, emergency and public safety 10.4%, transportation and logistics 9.1% and vehicle broadband 7.6%. Consumer preference for cheap shared links grows as Internet access is unaffordable in around 60% of low- and middle-income countries, ITU reported in November 2025 [2]. Low-cost shared links therefore suit community networks better than costly mobile plans. Laser links serve busier sites, and the free-space optics communication market is forecast to rise from USD 1.5 billion in 2026 to USD 5.8 billion by 2036. FMI expects rural access to keep the lead through 2036.
- Village broadband, school connectivity and farm networks make up rural internet access.
- Mobile coverage leaves a large usage gap, and GSMA said the usage gap is almost 10 times larger than the coverage gap [3]. Cheaper rural links can turn people who have signal but no service into users.
What are the drivers, restraints, and opportunities in the TV white space spectrum market?
Key drivers of the TV white space spectrum market include rural internet gaps and the need for cheap long-range links. Few device choices and doubts over future access to broadcast channels hold back investment. Sensor networks and smart grids open new projects for white space vendors.
- Driver: Rural communities beyond fibre and towers need affordable broadband, so operators use long-range links on unused broadcast channels.
- Restraint: A small range of devices and doubts over future access to broadcast channels make operators wary of large investments.
- Opportunity: Utilities, farms and transport operators need wide-area links for sensors and meters, which opens demand beyond home broadband.
Rural Connectivity Gaps Drive Long-Range Links
The size of the rural gap sets demand for TV white space equipment. About 2.2 billion people remained offline in 2025, and 96% of them live in low- and middle-income countries [2]. Large offline populations in poorer countries favour technologies that cost little per square kilometre covered. FMI views rural access as the main driver through 2036. Public funding schemes will decide how fast networks roll out.
Device Ecosystem and Spectrum Uncertainty Slow Investment
A limited device range remains the main restraint, since few vendors produce certified white space radios at volume. Doubt over the future of the broadcast band adds to the caution. In the United Kingdom, broadcast TV viewing fell 4% in 2024, and young adults watched only 17 minutes of live TV a day [5]. Falling viewing invites plans to reassign broadcast spectrum, which could shrink the white space available. Clear long-term rules will be needed before operators commit to national networks. Mobile video adds to the debate, and the mobile TV market is projected to grow at an 8% CAGR from 2025 to 2035.
IoT and Smart Grid Uses Open New Projects
Machine links will drive more of the growth of the TV white space spectrum market, since sensors and meters need wide coverage but little data. Mobile networks are moving to 5G, and GSMA expects 57% of all mobile connections to run on 5G by 2030 [3]. Rural sensors rarely justify 5G sites, which leaves room for white space links in farms and grids. Utilities with remote substations are early buyers, and vendors offering sensor-ready radios will capture these projects first.
Which country CAGRs are profiled in the TV white space spectrum market?
Table 9: Country CAGR Comparison for the TV White Space Spectrum Market (CAGR percentage), 2026 to 2036
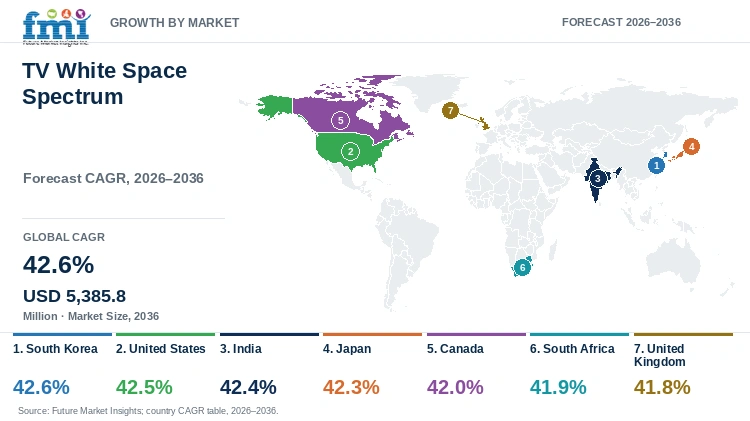
| Country | CAGR |
|---|---|
| South Korea | 42.6% |
| United States | 42.5% |
| India | 42.4% |
| Japan | 42.3% |
| Canada | 42% |
| South Africa | 41.9% |
| United Kingdom | 41.8% |
How do country-level CAGRs compare in the TV white space spectrum market?
South Korea ranks first in the FMI country table at 42.6%, level with the global CAGR, as safety and sensor networks adopt white space. The United States comes next on 42.5% with rural and tribal providers, and India on 42.4% with village broadband schemes. Japan (42.3%), Canada (42%) and South Africa (41.9%) form a tight middle group. The United Kingdom is lowest at 41.8%, given dense fibre and mobile coverage. A spread of only 0.8 points shows that equipment cost and rules, more than geography, set the pace in every profiled country.
- South Korea uses white space mainly for public safety and sensors in hilly areas, since dense mobile coverage already serves homes. Vendors with rugged, sensor-ready radios benefit most from this use.
- In the United States, rural providers and tribal networks use white space in areas with costly towers, so suppliers with FCC-certified radios hold an advantage.
- Village broadband programmes in India need links that reach beyond fibre points, so low-cost white space radios gain a role. Vendors that assemble radios locally gain an edge on price.
- Japanese networks focus on disaster communications and local area links, which steers vendors toward emergency-ready products.
- Remote northern and Indigenous communities in Canada lack fibre, and long-range links offer a cheaper path. Vendors with equipment built for cold climates are best placed.
- South Africa combines wide rural areas with an active regulator, which gives suppliers a test ground for licensed white space services.
- Dense fibre and mobile coverage limit white space to niche rural uses in the United Kingdom, which keeps growth the slowest.
Full report country CAGRs cover: seven profiled rates between 41.8% in the United Kingdom and 42.6% in South Korea, alongside regional tables for every other standard country.
Country-wise Analysis
South Korea TV White Space Spectrum Market Outlook (2026 to 2036)
South Korea has near-universal mobile and fibre coverage, so white space serves special uses such as safety networks. Public safety networks and sensors in mountain areas are the main applications. No other profiled country matches the Korean growth rate, a CAGR of 42.6%.
Key takeaway: In South Korea, public safety agencies and sensor network operators will buy white space radios for hilly areas that mobile networks cover poorly.
United States TV White Space Spectrum Market Outlook (2026 to 2036)
US rural and tribal providers use white space radios to reach homes in areas with costly towers. The FCC joined other regulators at the 2026 DSA Global Summit focused on dynamic spectrum access [1]. Use of database-managed access to unused channels is gaining support as regulators continue to show interest. US white space sales are forecast to grow at a 42.5% CAGR as rural funds flow. Public funding for rural broadband will set the pace of US rollouts.
Key takeaway: US rural and tribal providers will keep buying white space radios as public broadband funds and regulator support make long-range links affordable.
India TV White Space Spectrum Market Outlook (2026 to 2036)
India has many villages beyond the reach of fibre and profitable towers. Demand for long-range links is strong, as white space can carry broadband from fibre points to groups of homes and schools. Indian deployments are set to grow at a 42.4% CAGR, close to the global figure.
Key takeaway: Demand for white space links in India will come from village broadband schemes that need low-cost connections beyond the reach of fibre.
Japan TV White Space Spectrum Market Outlook (2026 to 2036)
In Japan, white space use centres on disaster communications and local broadcast services. Dense networks limit consumer broadband use, so Japanese sales are expected to rise at a 42.3% CAGR, slightly under the global rate.
Key takeaway: Japanese local governments will buy white space equipment mainly for disaster communications, as dense mobile networks already serve most homes.
Canada TV White Space Spectrum Market Outlook (2026 to 2036)
Canada has vast rural and northern areas with scattered homes, which drives adoption of long-range links. Long-range links lower the cost of reaching these communities compared with fibre. Canada's white space sales are set for 42% annual growth.
Key takeaway: Canadian providers serving remote northern and Indigenous communities will choose long-range white space links as fibre costs too much there.
South Africa TV White Space Spectrum Market Outlook (2026 to 2036)
South African regulators are active in spectrum sharing debates. ICASA joined the 2026 DSA Global Summit in London alongside Ofcom and the FCC [1]. Active regulators of this kind help set clear rules for shared spectrum. The forecast for South Africa is a 41.9% CAGR over the decade. Rural schools and clinics are likely to be the first paying users.
Key takeaway: Rural schools and clinics in South Africa are likely to be early buyers of white space services as the regulator works on shared spectrum rules.
United Kingdom TV White Space Spectrum Market Outlook (2026 to 2036)
The United Kingdom pioneered database-managed white space access, but dense coverage limits demand. Broadcast viewing fell 4% in 2024, which keeps debate over UHF spectrum use alive [5]. Uncertainty over the band slows investment, and British demand is projected at a 41.8% CAGR, the lowest in the table. Niche rural and maritime links will carry most of that demand.
Key takeaway: With fibre and mobile coverage already dense, UK buyers will use white space only for niche rural and maritime links, keeping growth the slowest.
Who are the notable companies in the TV white space spectrum market?
Radio makers, database operators and sponsors covered here are Microsoft, Carlson Wireless Technologies, Adaptrum, Broadcom, Aviacomm, Nominet, 6Harmonics, Alphabet (Google) and RED Technologies.
Top companies operating in the TV white space spectrum market are technology sponsors, radio makers and database operators, and FMI sees complete rural packages as the main competitive advantage. Rural buyers need affordable equipment, since Internet access is unaffordable in around 60% of low- and middle-income countries [2]. Price pressure of this kind favours vendors with low-cost radios and simple installation. Database operators compete on accuracy and approvals, and regulators from Europe, the Americas, Africa and Asia met at the 2026 DSA Global Summit to discuss dynamic spectrum access [1]. Closer contact among regulators favours vendors certified in several countries. Competition through 2036 will turn on device cost, database approvals and partnerships with rural operators.
- Technology sponsors: Microsoft and Alphabet (Google).
- Radio and chipset makers: Carlson Wireless Technologies, Adaptrum, Broadcom, Aviacomm and 6Harmonics.
- Database operators and specialists: RED Technologies and Nominet, whose white space database business RED Technologies acquired.
Competitive Benchmarking: TV White Space Spectrum Market
Table 10: Competitive Benchmarking for the TV White Space Spectrum Market (qualitative ratings), 2026
| Company | Radio Portfolio | Spectrum Database | Rural Partnerships | Recent Activity |
|---|---|---|---|---|
| Microsoft | Low | Medium | High | Medium |
| Carlson Wireless Technologies | High | Low | Medium | Medium |
| Adaptrum | High | Medium | Medium | Low |
| Nominet | Low | High | Low | Low |
| 6Harmonics | High | Low | Medium | Low |
| RED Technologies | Medium | High | Low | Low |
Ratings compare the companies on radio portfolio, spectrum database, rural partnerships and recent activity.
Key Developments in the TV White Space Spectrum Market
- The Dynamic Spectrum Alliance closed the 2026 DSA Global Summit in London in October 2026, with dynamic spectrum access and AI as the theme [1]. Regulators are paying more attention to ways of sharing spectrum.
- In September 2026, ITU and WMO called for protection of spectrum for weather, climate and water services and released a joint handbook on spectrum use [6]. Devices that use shared bands will face closer checks on interference.
- In July 2026, the International Advisory Body on Submarine Cable Resilience approved a final report [8]. Stronger international links support rural networks that depend on distant gateways.
- GSMA opened MWC26 on 2 March 2026 with figures showing over three billion people still unconnected [3]. The size of the gap keeps other access technologies on the policy agenda.
- On 17 November 2025, ITU reported that about 6 billion people were online in 2025 and 2.2 billion remained offline [2]. Rural and low-income areas remain the main target for new links.
- Ofcom reported in July 2025 that UK broadcast TV viewing fell 4% in 2024 [5]. Debate over the future of broadcast spectrum is gaining pace as a result.
Key Players in the TV White Space Spectrum Market
Technology Sponsors
- Microsoft
- Alphabet (Google)
Radio and Chipset Makers
- Carlson Wireless Technologies
- Adaptrum
- Broadcom
- Aviacomm
- 6Harmonics
Database Operators and Specialists
- Nominet
- RED Technologies
TV White Space Spectrum Market - Report Scope
Table 11: Report Scope for the TV White Space Spectrum Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Component; software and services; device; end-use application; region |
| Quantitative units | USD million |
| Market definition | Equipment, software and services that use unused television broadcast channels for wireless broadband and machine communications under database-controlled access. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | India; South Africa; Canada; South Korea; United States; Japan; United Kingdom |
| Key companies profiled | Microsoft, Carlson Wireless Technologies, Adaptrum, Broadcom, Aviacomm, Nominet, 6Harmonics, Alphabet (Google), RED Technologies |
| Forecast period | 2026 to 2036 |
TV White Space Spectrum Market - Research Methodology
Table 12: Research Methodology for the TV White Space Spectrum Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Company results, industry associations, government statistics and trade publications. |
| Desk Research | Coverage spans rural connectivity, spectrum policy, broadcasting trends, off-grid power and IoT networks. |
| Market Sizing | Market value covers equipment, software and services across components, devices, applications and regions. |
| Data Validation | Figures are cross-checked across company, industry and government sources. |
TV White Space Spectrum Market by Segments
TV White Space Spectrum Market segmented by Component:
- Radios
- Antennas
- Backhaul and Services
- Power Supplies
- Cables
TV White Space Spectrum Market segmented by Software and Services:
- Software
- Services
TV White Space Spectrum Market segmented by Device:
- Fixed TV White Space Devices
- Portable TV White Space Devices
TV White Space Spectrum Market segmented by End-use Application:
- Rural Internet Access
- Urban Connectivity
- Smart Grid Networks
- IoT and M2M
- Emergency and Public Safety
- Transportation and Logistics
- Vehicle Broadband Access
TV White Space Spectrum Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Dynamic Spectrum Alliance. (2026, October 25). Thank you, London: the 2026 DSA Global Summit wraps up. https://www.dynamicspectrumalliance.org/2026-dsa-global-summit-recap/
- [2] International Telecommunication Union. (2025, November 17). Global number of Internet users increases, but disparities deepen key digital divides. https://www.itu.int/en/mediacentre/Pages/PR-2025-11-17-Facts-and-Figures.aspx
- [3] GSMA. (2026, March 2). MWC26 Barcelona opens with call to complete 5G, rise to AI challenges, and strengthen digital safety. https://www.bolsamania.com/nota-de-prensa/mercados/mwc26-barcelona-opens-with-call-to-complete-5g-rise-to-ai-challenges-and-strengthen-digital-safety--21892452.html
- [4] International Energy Agency. (2025, June 25). Energy access improving, but international financial support still needed to boost progress and address disparities. https://www.iea.org/news/energy-access-improving-but-international-financial-support-still-needed-to-boost-progress-and-address-disparities
- [5] Ofcom. (2025, July 30). Tuning into YouTube: UK's media habits revealed. https://www.ofcom.org.uk/media-use-and-attitudes/media-habits-adults/tuning-into-youtube-uks-media-habits-revealed
- [6] International Telecommunication Union. (2026, September 28). ITU and WMO call to protect radio spectrum for weather, climate and water services. https://www.itu.int/en/mediacentre/Pages/PR-2026-09-28-ITU-WMO-radio-spectrum-protection.aspx
- [7] International Renewable Energy Agency. (2025, March 26). Record-Breaking Annual Growth in Renewable Power Capacity. https://www.irena.org/News/pressreleases/2025/Mar/Record-Breaking-Annual-Growth-in-Renewable-Power-Capacity
- [8] International Telecommunication Union. (2026, July 10). International Advisory Body approves landmark report to strengthen submarine cable resilience. https://www.itu.int/en/mediacentre/Pages/PR-2026-07-10-Submarine-cable-resilience-report.aspx
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the TV white space spectrum market during 2026?
- What market size is projected by 2036?
- Which component holds notable share?
- Which device type holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Component, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Component, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Component, 2026 to 2036
- Radios
- Antennas
- Backhaul and Services
- Power Supplies
- Cables
- Y-o-Y Growth Trend Analysis By Component, 2021 to 2025
- Absolute $ Opportunity Analysis By Component, 2026 to 2036
- Global Market Analysis and Forecast, By Software and Services, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Software and Services, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Software and Services, 2026 to 2036
- Software
- Services
- Y-o-Y Growth Trend Analysis By Software and Services, 2021 to 2025
- Absolute $ Opportunity Analysis By Software and Services, 2026 to 2036
- Global Market Analysis and Forecast, By Device, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Device, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Device, 2026 to 2036
- Fixed TV White Space Devices
- Portable TV White Space Devices
- Y-o-Y Growth Trend Analysis By Device, 2021 to 2025
- Absolute $ Opportunity Analysis By Device, 2026 to 2036
- Global Market Analysis and Forecast, By End-use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End-use Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End-use Application, 2026 to 2036
- Rural Internet Access
- Urban Connectivity
- Smart Grid Networks
- IoT and M2M
- Emergency and Public Safety
- Transportation and Logistics
- Vehicle Broadband Access
- Y-o-Y Growth Trend Analysis By End-use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Component
- By Software and Services
- By Device
- By End-use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Software and Services
- By Device
- By End-use Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Component
- By Software and Services
- By Device
- By End-use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Software and Services
- By Device
- By End-use Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Component
- By Software and Services
- By Device
- By End-use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Software and Services
- By Device
- By End-use Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Component
- By Software and Services
- By Device
- By End-use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Software and Services
- By Device
- By End-use Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Component
- By Software and Services
- By Device
- By End-use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Software and Services
- By Device
- By End-use Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Component
- By Software and Services
- By Device
- By End-use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Software and Services
- By Device
- By End-use Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Component
- By Software and Services
- By Device
- By End-use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Software and Services
- By Device
- By End-use Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Software and Services
- By Device
- By End-use Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Software and Services
- By Device
- By End-use Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Software and Services
- By Device
- By End-use Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Software and Services
- By Device
- By End-use Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Software and Services
- By Device
- By End-use Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Software and Services
- By Device
- By End-use Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Software and Services
- By Device
- By End-use Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Software and Services
- By Device
- By End-use Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Software and Services
- By Device
- By End-use Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Software and Services
- By Device
- By End-use Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Software and Services
- By Device
- By End-use Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Software and Services
- By Device
- By End-use Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Software and Services
- By Device
- By End-use Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Software and Services
- By Device
- By End-use Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Software and Services
- By Device
- By End-use Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Software and Services
- By Device
- By End-use Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Software and Services
- By Device
- By End-use Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Software and Services
- By Device
- By End-use Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Software and Services
- By Device
- By End-use Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Software and Services
- By Device
- By End-use Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Component
- By Software and Services
- By Device
- By End-use Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Microsoft
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Carlson Wireless Technologies
- Adaptrum
- Nominet
- 6Harmonics
- RED Technologies
- Alphabet (Google)
- Broadcom
- Aviacomm
- Microsoft
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Software and Services, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by Device, 2021 to 2036
- Table 5: Global Market Value (USD Million) Forecast by End-use Application, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Software and Services, 2021 to 2036
- Table 9: North America Market Value (USD Million) Forecast by Device, 2021 to 2036
- Table 10: North America Market Value (USD Million) Forecast by End-use Application, 2021 to 2036
- Table 11: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 13: Latin America Market Value (USD Million) Forecast by Software and Services, 2021 to 2036
- Table 14: Latin America Market Value (USD Million) Forecast by Device, 2021 to 2036
- Table 15: Latin America Market Value (USD Million) Forecast by End-use Application, 2021 to 2036
- Table 16: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 18: Western Europe Market Value (USD Million) Forecast by Software and Services, 2021 to 2036
- Table 19: Western Europe Market Value (USD Million) Forecast by Device, 2021 to 2036
- Table 20: Western Europe Market Value (USD Million) Forecast by End-use Application, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Million) Forecast by Software and Services, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Million) Forecast by Device, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Million) Forecast by End-use Application, 2021 to 2036
- Table 26: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 28: East Asia Market Value (USD Million) Forecast by Software and Services, 2021 to 2036
- Table 29: East Asia Market Value (USD Million) Forecast by Device, 2021 to 2036
- Table 30: East Asia Market Value (USD Million) Forecast by End-use Application, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Million) Forecast by Software and Services, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Million) Forecast by Device, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Million) Forecast by End-use Application, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Million) Forecast by Software and Services, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Million) Forecast by Device, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Million) Forecast by End-use Application, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Component
- Figure 6: Global Market Value Share and BPS Analysis by Software and Services, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Software and Services, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Software and Services
- Figure 9: Global Market Value Share and BPS Analysis by Device, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Device, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Device
- Figure 12: Global Market Value Share and BPS Analysis by End-use Application, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by End-use Application, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by End-use Application
- Figure 15: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Component
- Figure 29: North America Market Value Share and BPS Analysis by Software and Services, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Software and Services, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Software and Services
- Figure 32: North America Market Value Share and BPS Analysis by Device, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Device, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Device
- Figure 35: North America Market Value Share and BPS Analysis by End-use Application, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by End-use Application, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by End-use Application
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Component
- Figure 42: Latin America Market Value Share and BPS Analysis by Software and Services, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Software and Services, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Software and Services
- Figure 45: Latin America Market Value Share and BPS Analysis by Device, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Device, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Device
- Figure 48: Latin America Market Value Share and BPS Analysis by End-use Application, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by End-use Application, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by End-use Application
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Component
- Figure 55: Western Europe Market Value Share and BPS Analysis by Software and Services, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Software and Services, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Software and Services
- Figure 58: Western Europe Market Value Share and BPS Analysis by Device, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by Device, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by Device
- Figure 61: Western Europe Market Value Share and BPS Analysis by End-use Application, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by End-use Application, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by End-use Application
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Component
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Software and Services, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Software and Services, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Software and Services
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by Device, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by Device, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by Device
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by End-use Application, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by End-use Application, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by End-use Application
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Component
- Figure 81: East Asia Market Value Share and BPS Analysis by Software and Services, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Software and Services, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Software and Services
- Figure 84: East Asia Market Value Share and BPS Analysis by Device, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by Device, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by Device
- Figure 87: East Asia Market Value Share and BPS Analysis by End-use Application, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by End-use Application, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by End-use Application
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Component
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Software and Services, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Software and Services, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Software and Services
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by Device, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by Device, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by Device
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by End-use Application, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by End-use Application, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by End-use Application
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Component
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Software and Services, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Software and Services, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Software and Services
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by Device, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by Device, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by Device
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by End-use Application, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by End-use Application, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by End-use Application
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the TV white space spectrum market expected in 2026?
The TV white space spectrum market is expected to reach USD 154.9 million in 2026, up from an estimated USD 108.6 million in 2025, FMI estimates, as rural operators move from pilots to paid deployments.
What CAGR is projected for the TV white space spectrum market through 2036?
A 42.6% CAGR is projected through 2036, taking the market to USD 5,385.8 million, since large rural populations still lack affordable broadband.
Which component holds a notable market share in 2026?
Radios are expected to hold 49.3% share in 2026, as every link needs base stations and customer units. Antennas follow at about 17.6%.
Which device type holds a notable market share in 2026?
Fixed devices are expected to lead with 63.5%, given rooftop and tower installations in rural networks. Portable devices hold about 36.5%.
Which country has a notable expansion outlook through 2036?
South Korea leads the FMI country outlook at a 42.6% CAGR, given public safety and IoT networks in mountain areas. The United States is next at 42.5%.
Who are the key companies in the TV white space spectrum market?
Microsoft and Alphabet sponsor rural white space projects, and Carlson Wireless Technologies, Adaptrum, Broadcom, Aviacomm and 6Harmonics supply radios and chipsets. RED Technologies, which acquired the Nominet spectrum database business, runs spectrum databases approved by national regulators.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
