

- Market Size (2026)
- USD 3.2 Bn
- Forecast (2036)
- USD 5.8 Bn
- CAGR (2026 to 2036)
- 6.2%
How big is the Vegetable Powders Market in 2026?
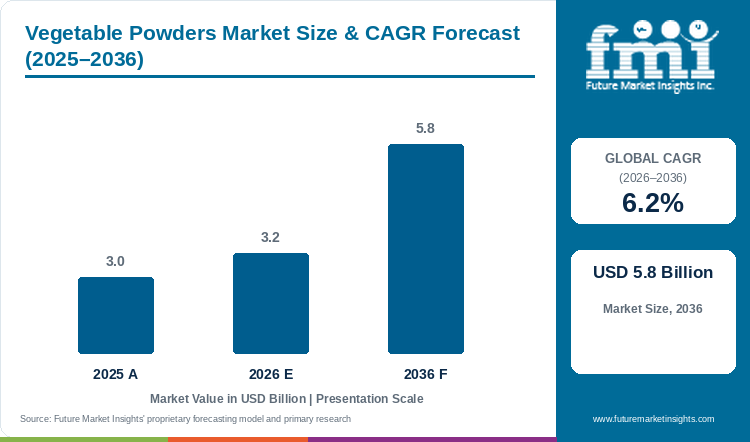
Demand for vegetable powders is projected to expand at 6.2% CAGR between 2026 and 2036. Industry value grows from USD 3.0 billion in 2025 to USD 3.2 billion in 2026 and is projected to reach USD 5.8 billion by 2036.
Future Market Insights links this expansion to the transition away from perishable raw crops toward standardized dehydrated ingredients. Global vegetable powders market valuation grows from USD 3.0 billion in 2025 to USD 3.2 billion in 2026, and is projected to reach USD 5.8 billion by 2036, rising at a 6.2% CAGR between 2026 and 2036. The forecast expansion adds USD 2.6 billion in incremental revenue as food plants integrate dehydrated vegetables and fruit powders into dry culinary mixes. Fine powder and micronized crystals lead the form category with 37.5% share in 2026, providing rapid rehydration across high-speed packaging lines. In September 2026, the U.S. Department of Agriculture Economic Research Service reported that domestic vegetable and pulse farm cash receipts reached an annual average of USD 24.2 billion [1]. The deep agricultural base secures diversified crop streams for commercial dehydrators, insulating manufacturers from localized harvest deficits.
Key Market Trends & Insights
- By form: Fine powder and micronized crystals led the market with a share of 37.5% in 2026, supported by rapid dissolution and consistent dispersion across dry mixes.
- By source: Conventional farm source accounted for 49.2% of demand in 2026, driven by broad harvest availability and commercial pricing across high-volume food processing.
- By application: Dietary supplements and nutraceuticals represented 29.6% of revenue in 2026, enabled by compact dosing and growing consumer demand for whole-food botanical fortification.
- By sales channel: B2B direct industrial food manufacturers held the leading share of 46.0% in 2026, reinforced by strict technical specification auditing and scheduled bulk procurement contracts.
Regional Highlights
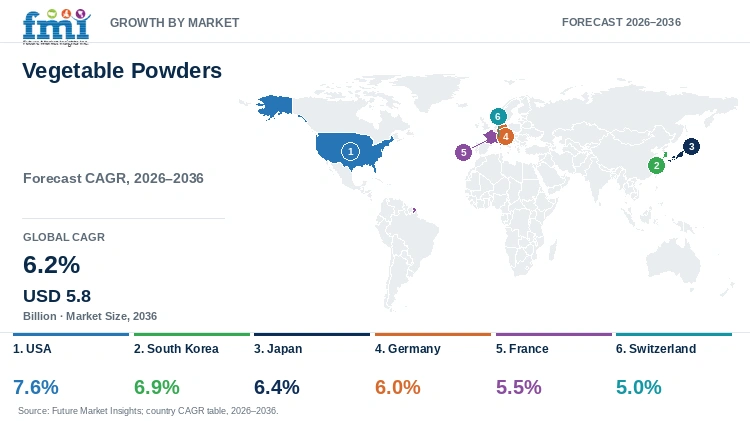
- Fastest-growing evaluated country: USA, at 7.6% CAGR from 2026 to 2036.
- By country: South Korea at 6.9%, Japan at 6.4%, and Germany at 6.0% follow, while Switzerland records the lowest evaluated CAGR at 5.0%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Vegetable Powders Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 3.0 billion |
| Estimated Market Size in 2026 | USD 3.2 billion |
| Projected Market Size by 2036 | USD 5.8 billion |
| CAGR, 2026 to 2036 | 6.2% |
| Added Revenue, 2026 to 2036 | USD 2.6 billion |
FMI research indicates that industrial processors require verifiable particle sizing and microbial stability before approving spray-dried or drum-dried inputs. Commercial food brands are incorporating clean-label ingredients into prepared meal kits to eliminate artificial flavorings. In September 2025, USDA ERS published comprehensive vegetable utilization datasets documenting that processing crop utilization expanded across canned, frozen, and dehydrated categories to meet institutional catering schedules [2]. Technical powder specifications allow processors to maintain standardized nutritional profiles and batch colors without cold-chain storage dependencies, accelerating adoption across commercial bakeries and sauce compounders.
Crop Processing and Dehydration Sizing
Table 2: Vegetable Crop Dehydration and Processing Volume Indicators for the Vegetable Powders Market (thousand metric tons and percentages), mixed reporting years from 2024 to 2026
| Metric | 2024 | 2025 | 2026 |
|---|---|---|---|
| Fresh vegetable harvest intake (thousand MT) | 14,250 | 14,800 | 15,350 |
| Processing and dehydration volume (thousand MT) | 2,850 | 3,100 | 3,380 |
| Dehydration conversion yield (%) | 8.2% to 11.5% | 8.4% to 11.8% | 8.5% to 12.0% |
| Industrial powder output (thousand MT) | 255.0 | 280.5 | 312.0 |
Per Capita & Food Processing Sizing
Commercial food compounders are replacing perishable leafy vegetables and root crops with spray-dried and freeze-dried vegetable powders to streamline inventory management. Growing demand for functional food premixes accelerates bulk powder procurement across convenience food manufacturers.
Table 3: Per Capita and Food Processing Utilization Indicators for the Vegetable Powders Market (USD and kilograms), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global consumer population (billion) | 8.23 | 8.30 | 8.95 |
| Annual powder spend per capita (USD) | 0.36 | 0.39 | 0.65 |
| Annual consumption per industrial user (MT) | 42.5 | 45.8 | 68.2 |
| Commercial adoption rate (%) | 24.5% | 25.8% | 36.2% |
Table 4: Industrial Formulation and Application Sizing Indicators for the Vegetable Powders Market (USD million and percentages), mixed reporting years from 2024 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 3.2 billion | Report value |
| Dietary supplements demand value, 2026 | USD 947.2 million | 29.6% share |
| Conventional farm input share, 2026 | USD 1,574.4 million | 49.2% share |
| B2B direct procurement share, 2026 | USD 1,472.0 million | 46.0% share |
Analyst Perspective
“Powder suppliers will gain repeat industrial orders when crop identity, particle size, and rehydration remain consistent. Buyers will also ask for clearer proof of origin as organic and functional claims expand.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Vegetable Powders Market segmented?
Vegetable Powders Market is segmented by four primary commercial axes and region: form, source, application, sales channel, and region. Fine powder, conventional farm source, dietary supplements, and B2B direct industrial sales are projected to hold 37.5%, 49.2%, 29.6%, and 46.0% shares in 2026.
By form: fine powder and micronized crystals; liquid extract and tincture; standardized granules and pellets.
By source: conventional farm source; certified organic and non-GMO; fermentation or bio-synthesized.
By application: dietary supplements and nutraceuticals; functional food and beverages; cosmetics and topical personal care; animal nutrition.
By sales channel: B2B direct industrial food manufacturers; retail packaged health stores; online DTC brands.
By region: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Why do fine powders retain broad use in industrial formulations?
Fine powder and micronized crystals are projected to account for 37.5% of form revenue in 2026, supported by precise dosing across automated dry-blending lines.
Table 5: Form Share for the Vegetable Powders Market (percentage share), 2026
| Form | Share (2026) |
|---|---|
| Fine powder and micronized crystals | 37.5% |
| Other Segments Combined | 62.5%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment’s reported share from 100.0%.
Table 6: Form Leadership and Market Growth for the Vegetable Powders Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.2% |
| Leading Segment | Fine powder and micronized crystals |
FMI’s segment analysis indicates that fine particles disperse through dry premixes, capsules, instant beverages, and seasoning systems without a separate extraction step. Milling also lets processors set mesh size around customer filling, blending, or rehydration processes. Commercial compounders rely on fine powders to incorporate essential vegetable micronutrients without altering finished recipe textures. In February 2026, USDA NASS released its annual vegetables summary tracking industrial processing and dehydration allocations across commercial beet, carrot, and broccoli acreage [3]. Precise pulverization enables stable suspension within functional beverages and powdered food ingredients.
- The 37.5% share follows broad compatibility with dry manufacturing lines and measured additions.
- In November 2025, USDA Agricultural Marketing Service recorded steady commercial wholesale demand for dehydrated vegetable flake and powder grades across major industrial packaging hubs [4].
What keeps conventional farm source relevant for vegetable powders?
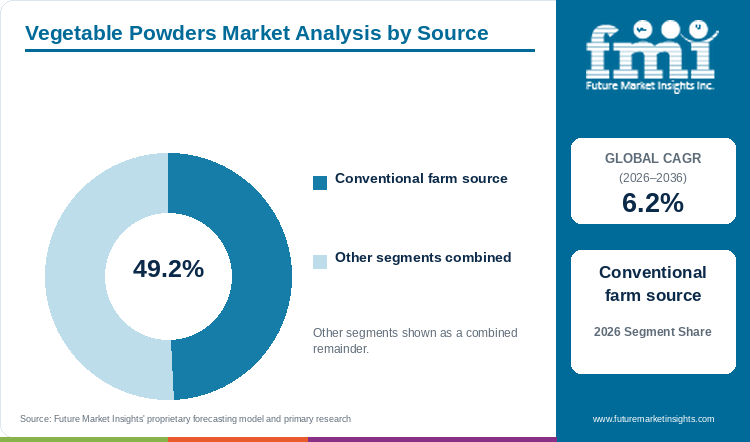
Conventional farm material is estimated to hold 49.2% of source revenue in 2026, owing to broader crop availability and established grower contracts.
As noted by FMI, conventional agriculture provides the necessary volume scale for high-capacity dehydration plants. Sourcing from conventional farms gives processors access to larger harvest pools and multi-year supply contracts. The route suits high-volume soups, sauces, seasonings, and plant-based foods where verified technical specifications take precedence over organic certification. In October 2026, South Korea’s Ministry of Food and Drug Safety updated its functional food database to incorporate standardized botanical raw material monographs [5]. Large farm partnerships protect ingredient processors from seasonal harvest shortages.
- The 49.2% share is supported by larger procurement pools and established crop handling.
- In February 2026, IFF highlighted continued capital investment in industrial taste and botanical processing facilities to support global food manufacturing partnerships [6].
How are supplements supporting vegetable powder application demand?
Dietary supplements and nutraceuticals are forecast to represent 29.6% of application revenue in 2026, driven by consumer demand for compact daily botanical nutrition.
Powder formats allow supplement manufacturers to pack dense phytonutrients into capsules, tablets, and powdered drink mixes without the physical bulk of fresh vegetables. Shifting wellness preferences encourage consumers to seek out daily green blends that support digestive vitality. Incorporating vegetable powders into specialized dietary supplements satisfies strict clean-label requirements while preserving natural vitamin and mineral content.
- The 29.6% share follows surging demand for concentrated daily servings and customized botanical blend flexibility.
- Commercial supplement brands increasingly formulate multi-vegetable greens powders with guaranteed antioxidant and polyphenol concentrations.
Why do direct industrial sales remain central to market access?
B2B direct industrial sales are set to capture 46.0% of sales channel revenue in 2026, underpinned by technical specification compliance and custom batch blending.
Industrial food manufacturers require direct technical relationships with ingredient suppliers to verify microbial testing, moisture controls, and mesh uniformity. Supplying certified bulk powders directly to commercial plants simplifies formulation audits while supporting tailored recipe development. Direct supply agreements facilitate seamless integration into commercial bakery lines and savory food premixes.
- The 46.0% share reflects stringent qualification audits and multi-year procurement contracts that cannot be executed through general retail.
- Direct supplier relationships enable processors to deliver customized batch grinds and certified microbiological lot analyses.
What drives, restrains, and opens opportunity in the Vegetable Powders Market?
In the vegetable powders market, the key driver is shelf-stable formulation, the key restraint is crop variability, and the key opportunity is certified sourcing.
- Driver: Manufacturers can replace perishable fresh material with measured dry ingredients that store and dose more easily across processing lines.
- Restraint: Crop color, flavor, moisture, and agricultural residue profiles can vary by harvest season, extending qualification trials.
- Opportunity: Organic and traceable powders can enter premium product categories where transparent agricultural origins influence consumer purchasing.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
FMI data suggests that commercial food makers are increasingly replacing raw produce with dehydrated powders to eliminate cold-chain refrigeration costs and minimize food waste. In October 2025, Roquette introduced AMYSTA L 123, utilizing advanced spray drying and thermal treatment to enhance soluble plant ingredient functionality across powdered foods [7]. The same commercial logic encourages processors to adopt shelf-stable vegetable powders that blend smoothly into dry instant soups and packaged functional foods.
Risk Assessment of the Vegetable Powders Market: Operational and Formulation Friction
Raw agricultural variations directly impact the color intensity, bulk density, and hydration rate of dehydrated powders. Processors must execute extensive analytical batch testing to maintain uniform color profiles in finished consumer goods. In June 2026, the European Commission released its annual monitoring report showing that organic agri-food import volumes reached 2.98 million tonnes amid tightening pesticide screening standards [8]. Stringent import testing creates delivery lead-time risks for manufacturers relying on foreign botanical stocks to formulate natural food colors.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
According to FMI, expanding certified organic farming creates high-margin openings for traceable single-origin vegetable powders. In December 2025, the USDA Foreign Agricultural Service documented sustained cross-border demand for dehydrated plant inputs carrying third-party non-GMO and organic verifications [9]. Clean agricultural documentation enables ingredient companies to command premium pricing from European and North American processors formulating certified organic foods.
Vegetable Powders Market by Country (2026 to 2036)
Country growth dynamics differ through 2036 as agricultural processing capabilities, dietary supplement consumption, and organic verification standards vary across profiled economies. North America and Western Europe emphasize traceable sourcing, while East Asia expands functional health food formulations.
Table 7: Country CAGR and Primary Growth Levers for the Vegetable Powders Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 7.6% | Large commercial vegetable dehydration infrastructure and dietary supplement manufacturing |
| South Korea | 6.9% | Health functional food statutory registration and daily green wellness drink adoption |
| Japan | 6.4% | Structured processed food manufacturing and rigorous organic JAS agricultural grading |
| Germany | 6.0% | National organic agricultural expansion strategy and clean-label soup compounding |
| France | 5.5% | Extensive organic certified farmland and culinary sauce reformulation requirements |
| Switzerland | 5.0% | High vegetable import dependence and preference for verifiable farm origin documentation |
Source: Future Market Insights analysis
USA Vegetable Powders Market Outlook (2026 to 2036)
As per FMI, the United States leads the profiled group with an anticipated 7.6% CAGR through 2036, propelled by a highly developed vegetable processing sector and expansive nutraceutical manufacturing. In August 2026, South Korea’s Ministry of Food and Drug Safety reported total health functional food sector production valued at approximately USD 3.0 billion after currency conversion [10], demonstrating that industrialized nutrition channels provide durable volume demand for botanical powders. In the domestic U.S. market, commercial processors direct surplus harvests into continuous dehydrators, ensuring predictable ingredient supply for packaged soups, dressings, and nutritional drink mixes. Key takeaway: In USA, large-scale domestic agricultural infrastructure and established contract supplement packaging underpin rapid market expansion.
South Korea Vegetable Powders Market Outlook (2026 to 2036)
Vegetable powder adoption in South Korea is forecast to advance at a 6.9% CAGR over the assessment window, supported by statutory Health Functional Food approval pathways. In December 2025, Japan’s Agriculture and Livestock Industries Corporation published its vegetable statistical yearbook documenting that commercial food processing accounts for over 30% of total domestic vegetable consumption [11]. Korean health brands capitalize on similar dietary trends by blending green vegetable powders into portable single-serve sachets for busy urban consumers. Suppliers that secure local ingredient safety approvals can establish recurring supply relationships with major domestic pharmaceutical and retail health chains. Key takeaway: In South Korea, formal health functional food ingredient recognition drives commercial volume uptake.
Japan Vegetable Powders Market Outlook (2026 to 2036)
The Japanese vegetable powders sector is estimated to expand at a 6.4% CAGR between 2026 and 2036, anchored by advanced instant food processing and exacting ingredient specifications. In September 2025, the European Environment Agency reported that Germany’s organic agricultural land share expanded to 9.8% under structured sustainability mandates [12]. In Japan, buyers apply equally rigorous quality benchmarks, requiring suppliers to document precise particle size distributions and minimal thermal discoloration. Processors incorporate finely milled pumpkin, spinach, and sweet potato powders into bakery items, ramen broths, and infant foods. Key takeaway: In Japan, uncompromising sensory standards and demand for natural food coloring drive premium powder procurement.
Germany Vegetable Powders Market Outlook (2026 to 2036)
Germany vegetable powder sales are projected to grow at a 6.0% CAGR over the forecast period, underpinned by national organic farming expansion and strict clean-label manufacturing. In September 2026, Eurostat released organic farming statistics confirming that French organic agricultural land area expanded to 2.88 million hectares [13], reflecting broader European transitions toward certified agricultural production. German food compounders leverage expanding certified harvests to formulate organic dry seasonings and dehydrated vegetable broths. Processors separate suppliers based on heavy-metal testing documentation and traceability rather than commodity price alone. Key takeaway: In Germany, stringent organic compliance and industrial soup manufacturing support consistent powder demand.
France Vegetable Powders Market Outlook (2026 to 2036)
Sales of vegetable powders in France are forecast to advance at a 5.5% CAGR through 2036, influenced by culinary heritage and demand for natural flavor enhancers. In October 2025, the Swiss Federal Statistical Office published food supply balance sheets showing domestic agriculture fulfilled 53.7% of national food requirements while vegetables reached 43.6% [14]. French culinary compounders similarly balance local farm output against imported specialty powders to produce dehydrated culinary stocks, savory pastry fillings, and gourmet sauces. Manufacturers demand gentle drying techniques that preserve natural aromas and volatile flavor compounds. Key takeaway: In France, culinary application requirements and natural flavor preservation dictate supplier selection.
Switzerland Vegetable Powders Market Outlook (2026 to 2036)
The Switzerland vegetable powders market is expected to record a 5.0% CAGR through 2036, characterized by high import reliance and premium quality standards. In February 2026, Roquette launched NUTRALYS Pea 850F to address sensory neutrality in powdered nutritional blends [15]. Swiss food processors utilize similar advanced neutral botanical powders to formulate medical foods and premium sports nutrition drinks. Slower volume growth is offset by high average unit prices and demand for certified pesticide-free documentation. Key takeaway: In Switzerland, high purchasing power and stringent Swiss-GAP traceability standards support stable high-value demand.
Who are the notable companies in the Vegetable Powders Market?
Notable companies include dsm-firmenich, International Flavors & Fragrances, Givaudan, Roquette, ADM, Cargill, Bunge Global, and Kerry Group.
An FMI analyst notes that broad ingredient conglomerates compete directly with specialized botanical processors by offering integrated formulation and flavor-masking capabilities. Large agricultural corporations control upstream crop origination and bulk dehydration infrastructure, while sensory and nutrition houses develop high-value encapsulated powders for dietary supplements.
- Nutrition and sensory platforms: dsm-firmenich, IFF, Givaudan, and Kerry Group combine botanical extraction with flavor modulation and clinical nutrition formulation.
- Plant ingredient specialists: Roquette develops functional plant-based proteins, starches, and soluble botanical systems used alongside vegetable powders.
- Agricultural processors: ADM, Cargill, and Bunge Global leverage global grain and vegetable origination networks to deliver high-capacity industrial dehydration.
Competitive Benchmarking: Vegetable Powders Market
Table 8: Competitive Benchmarking for the Vegetable Powders Market (qualitative capability ratings), 2026
| Company | Portfolio breadth | Application support | Geographic reach | Current activity |
|---|---|---|---|---|
| dsm-firmenich | High | High | High | High |
| IFF | High | High | High | High |
| Givaudan | High | High | High | High |
| Roquette | High | High | High | High |
| ADM | High | Medium | High | Medium |
| Cargill | High | Medium | High | Medium |
| Bunge Global | High | Medium | High | Medium |
| Kerry Group | High | High | High | High |
Scoring basis: Portfolio Breadth benchmarks the variety of dehydrated vegetables, mesh options, and organic grades offered. Application Support evaluates pilot plant testing and custom recipe assistance. Geographic Reach measures global distribution depots. Current Activity benchmarks recent plant expansions and novel product introductions.
Key Developments in the Vegetable Powders Market
- In May 2026, IFF entered into a binding agreement to sell its Food Ingredients division to CVC in a transaction valued at approximately USD 4.3 billion [16].
- In August 2025, IFF launched POWERFRESH ACE 2000, deploying targeted enzyme technology to extend industrial bakery freshness and softness for up to 34 days [17].
- In February 2026, Roquette introduced NUTRALYS Pea 850F, engineered to provide neutral sensory performance in dry powdered nutrition formulations [18].
- In October 2025, Roquette rolled out AMYSTA L 123 soluble pea starch, improving cold-water solubility and flowability in powdered beverage and dried soup formulations [7].
Key Players in the Vegetable Powders Market
Nutrition, Taste, and Formulation Platforms
- dsm-firmenich
- International Flavors & Fragrances (IFF)
- Givaudan
- Kerry Group
Plant-Based Ingredient Systems and Agricultural Processors
- Roquette
- ADM
- Cargill
- Bunge Global
Vegetable Powders Market - Report Scope
Table 9: Report Scope for the Vegetable Powders Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | By Form, Source, Application, Sales Channel, and Region. |
| Quantitative Units | USD billion. |
| Market Definition | Revenue includes supplier sales of vegetable powders, flakes, and micronized crystals derived from culinary vegetables. Revenue excludes fresh, frozen, canned, and whole dried vegetables not milled or formulated as powder. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | USA, South Korea, Japan, Germany, France, Switzerland, and additional countries in the full report. |
| Key Companies Covered | dsm-firmenich, IFF, Givaudan, Roquette, ADM, Cargill, Bunge Global, Kerry Group. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Vegetable Powders Market - Research Methodology
Table 10: Research Methodology for the Vegetable Powders Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Analysts gathered input from vegetable processors, food manufacturers, nutraceutical compounders, and ingredient procurement directors. Interviews examined crop intake pricing, dehydration energy costs, mesh size requirements, and commercial approval hurdles. |
| Desk Research | Desk research evaluated agricultural ministry harvest records, national export databases, food safety authority guidelines, company financial disclosures, and industrial dehydration patent filings. Sources were reviewed for date recency and methodological validity. |
| Market Sizing and Forecasting | Market sizing reconciled baseline values with agricultural acreage trends, dehydration facility capacities, end-use formulation inclusion rates, and country macroeconomic indicators from 2026 to 2036. |
| Data Validation | Estimates were cross-checked against independent trade statistics, corporate revenue reports, and primary interview findings. Overlapping revenues from un-milled produce and adjacent fruit ingredients were excluded. |
Vegetable Powders Market by Segments
Form
- Fine powder and micronized crystals
- Liquid extract and tincture
- Standardized granules and pellets
Source
- Conventional farm source
- Certified organic and non-GMO
- Fermentation or bio-synthesized
Application
- Dietary supplements and nutraceuticals
- Functional food and beverages
- Cosmetics and topical personal care
- Animal nutrition
Sales Channel
- B2B direct industrial food manufacturers
- Retail packaged health stores
- Online DTC brands
Vegetable Powders Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Switzerland
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Department of Agriculture, Economic Research Service. (2026, September 11). Vegetables and pulses: Farm cash receipts and commodity baseline analysis
- [2] U.S. Department of Agriculture, Economic Research Service. (2025, September 22). Vegetables and pulses data on commercial processing and dehydration utilization
- [3] U.S. Department of Agriculture, National Agricultural Statistics Service. (2026, February 12). Vegetables 2025 summary: Production, acreage, and processing utilization
- [4] U.S. Department of Agriculture, Agricultural Marketing Service. (2025, November 18). National organic and conventional wholesale vegetable ingredient pricing summary
- [5] Ministry of Food and Drug Safety, Republic of Korea. (2026, October 8). Health functional food raw material recognition and production status
- [6] International Flavors & Fragrances. (2026, February 11). IFF reports fourth quarter and full year 2025 results and strategic investments
- [7] Roquette. (2025, October 31). AMYSTA L 123: Label-friendly soluble pea starch for powdered food systems
- [8] European Commission. (2026, June). EU imports of organic agri-food products: Key developments and quality monitoring in 2025
- [9] U.S. Department of Agriculture, Foreign Agricultural Service. (2025, December 15). Global agricultural trade patterns in dried and dehydrated botanical commodities
- [10] Ministry of Food and Drug Safety, Republic of Korea. (2026, August 3). Annual statistical yearbook on health functional food manufacturing output
- [11] Agriculture and Livestock Industries Corporation. (2025, December). Vegetable statistical yearbook: Commercial consumption, processing and trade in Japan
- [12] European Environment Agency. (2025, September 28). Area under organic farming in Germany: Ecological agricultural progress report
- [13] Eurostat. (2026, September 28). Developments in organic farming and certified agricultural land across the European Union
- [14] Swiss Federal Statistical Office. (2025, October 14). The food supply chain: Pocket statistics on domestic agricultural production
- [15] Roquette. (2026, February 10). Roquette introduces NUTRALYS Pea 850F with neutral taste profile for powder formulations
- [16] International Flavors & Fragrances. (2026, May 29). IFF enters into agreement to sell its Food Ingredients business to CVC for USD 4.3 billion
- [17] International Flavors & Fragrances. (2025, August 20). IFF commercializes POWERFRESH ACE 2000 enzyme technology for extended bakery freshness
- [18] Roquette. (2026, February 18). NUTRALYS plant protein innovation for high-solubility ready-to-mix nutrition applications
This bibliography is provided for reader reference. The full report contains complete source list and detailed citations.
This Report Answers
- What is the estimated size of the Vegetable Powders Market in 2026?
- What revenue is the Vegetable Powders Market projected to reach by 2036?
- Which form holds the notable Vegetable Powders Market share in 2026?
- Which sales channel holds the notable Vegetable Powders Market share?
- Which countries have notable Vegetable Powders Market growth outlooks by 2036?
- Which companies are notable in the Vegetable Powders Market today?
Frequently Asked Questions
How large is the Vegetable Powders Market in 2026?
Future Market Insights projects that the vegetable powders market will reach USD 3.2 billion in 2026 and is forecast to attain USD 5.8 billion by 2036.
What is the Vegetable Powders Market CAGR through 2036?
As per FMI, the vegetable powders market is projected to expand at a 6.2% CAGR between 2026 and 2036, driven by rising demand for shelf-stable food formulations and clean-label dietary supplements.
Which form has a notable share in 2026?
Fine powder and micronized crystals are estimated to account for 37.5% of form revenue in 2026, supported by rapid solubility, uniform batch mixing, and precise automated dosing.
Which application has a notable share in 2026?
Dietary supplements and nutraceuticals are forecast to represent 29.6% of application revenue in 2026, reflecting strong consumer adoption of daily botanical nutrition and powdered greens.
Which country shows a notable expansion outlook?
The United States is projected to grow at a leading 7.6% CAGR through 2036, underpinned by an expansive vegetable farming infrastructure and high commercial supplement manufacturing capacity.
Which companies are notable in the Vegetable Powders Market?
Notable companies include dsm-firmenich, International Flavors & Fragrances, Givaudan, Roquette, ADM, Cargill, Bunge Global, and Kerry Group.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form, 2026 to 2036
- Fine powder and micronized crystals
- Liquid extract and tincture
- Standardized granules and pellets
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source, 2026 to 2036
- Conventional farm source
- Certified organic and non-GMO
- Fermentation or bio-synthesized
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Dietary supplements and nutraceuticals
- Functional food and beverages
- Cosmetics and topical personal care
- Animal nutrition
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- B2B direct industrial food manufacturers
- Retail packaged health stores
- Online DTC brands
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Form
- By Source
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Source
- By Application
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Form
- By Source
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Source
- By Application
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Switzerland
- Benelux
- Nordics
- By Form
- By Source
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Source
- By Application
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Form
- By Source
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Source
- By Application
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Form
- By Source
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Source
- By Application
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Form
- By Source
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Source
- By Application
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Form
- By Source
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Source
- By Application
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Application
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Application
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Application
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Application
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Application
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Application
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Application
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Application
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Application
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Application
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Application
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Application
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Application
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Application
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Application
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Application
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Application
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Application
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Application
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Application
- By Sales Channel
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Application
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Form
- By Source
- By Application
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- dsm-firmenich
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- IFF
- Givaudan
- Roquette
- ADM
- Cargill
- Bunge Global
- Kerry Group
- International Flavors & Fragrances (IFF)
- dsm-firmenich
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


