

- Market Size (2026)
- USD 11.2 Bn
- Forecast (2036)
- USD 22.2 Bn
- CAGR (2026 to 2036)
- 7.1%
How big is Food Premix Market in 2026?
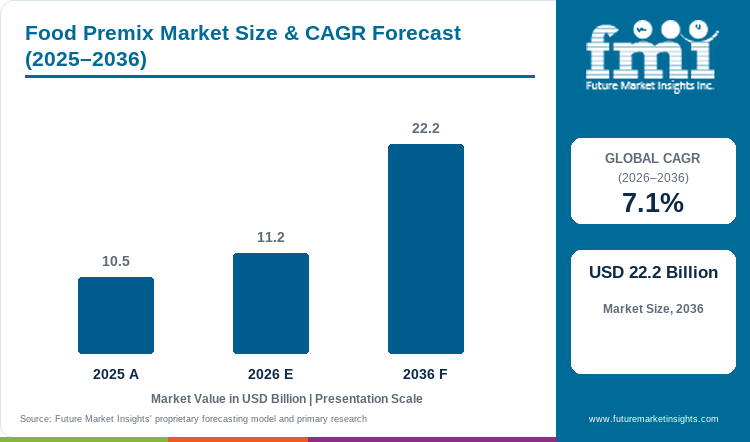
USD 11.2 billion in 2026 and USD 22.2 billion by 2036, expanding at 7.1% CAGR.
Demand for food premix is projected to expand at 7.1% CAGR between 2026 and 2036. Valuation rises from USD 10.5 billion in 2025 to USD 11.2 billion in 2026 and reaches USD 22.2 billion by 2036. Manufacturers are consolidating micronutrient dosing into controlled blends that simplify repeat production and reduce handling complexity. WHO published guidance in October 2025 on vitamin A and D fortification of edible oils and fats. The guidance ties premix formulation to defined nutrient levels and specified food vehicles used in public-health programs. Qualified blends retain repeat business when nutrient potency and dispersion remain consistent through routine commercial production.
Country demand separates according to how national rules convert nutrition policy into manufacturing work. The United Kingdom requires 0.25 mg folic acid per 100 g of non-wholemeal common wheat flour from 13 December 2026. Brazil closed a separate supplement-notification transition under RDC 843/2024 on 1 September 2026. The UK rule creates scheduled flour reformulation and dosing validation before the compliance date. Brazil places greater weight on notification records and traceability requirements for affected supplement products. These differences change qualification timing even when manufacturers use similar vitamin and mineral premix functions.
Key Takeaways of Food Premix Market
- Micronutrient fortification and targeted nutrition keep premix specifications inside repeat food and supplement manufacturing programs that require controlled dosing.
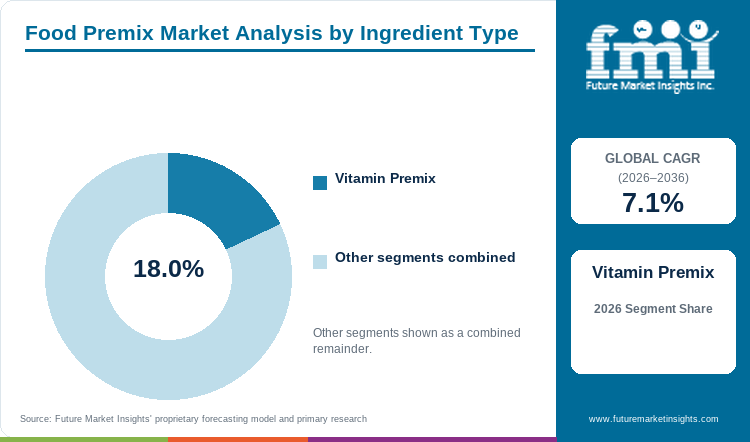
- Vitamin premix is projected to account for 18.0% of ingredient type demand in 2026, driven by the need for reliable distribution of low-dose vitamins inside finished formulas.
- Powder is estimated to hold 82.0% of form demand in 2026, owing to dry lines that meter one stable blend through existing batching systems.
- Premix blends - direct-to-consumer solutions are expected to lead product type with 93.0% share in 2026, attributable to consolidated inputs that reduce separate qualification steps.
- Country-specific permitted nutrient forms and stability requirements can lengthen formulation approval before a customer changes an established premix specification.
- The profiled company set includes Glanbia plc and Archer-Daniels-Midland Company as active nutrition suppliers. dsm-firmenich AG and Hexagon Nutrition Limited also operate within the defined food premix supply boundary. The set also contains Jubilant Ingrevia Limited plus Fenchem Biotek Ltd. alongside Prinova Group LLC and Barentz International B.V. Sudeep Pharma Limited and SternVitamin GmbH & Co. KG complete the ten-company set used across the competitive sections.
Analyst Perspective
"Food premix buyers rarely change a qualified formula for ingredient price alone because dosing accuracy and legal fit carry operational risk. Suppliers gain durable accounts when formulation support and dependable supply reduce the work required to keep each customer recipe compliant."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the food premix market segmented?
Ingredient Type, Form, Product Type, Application, and Region
The food premix market is segmented by ingredient type, form, product type, application, and region. Ingredient type covers Vitamin Premix, Amino Acids Premixes, Omega 3 Fatty Acids, Mineral Premix, Probiotics, Proteins, Enzymes, Prebiotics, Nucleotides Premixes, and Flavors. Form covers Powder and Liquid. Product type includes Premix Blends - Direct-to-Consumer Solutions and Drum to Hopper Formulations. Application covers Food Sector, Dietary Supplements, and Pharma OTC Drugs.
How does vitamin premix control low-dose distribution during repeat food fortification?
Low-dose vitamins become harder to distribute uniformly when a plant meters several active ingredients separately. A preblended carrier reduces weighing variation inside food fortification programs that specify nutrient levels by vehicle. WHO published guidance in October 2025 on vitamin A and D fortification of edible oils and fats. The guidance connects nutrient delivery with defined food vehicles and program design rather than isolated vitamin addition. Qualified vitamin premixes retain repeat use when potency and dispersion remain consistent through the customer process.
- Vitamin premix is projected to hold 18.0% within ingredient type in 2026, supported by controlled low-dose addition across recurring fortification and supplement formulas.
- Food manufacturers retain a qualified vitamin blend when batch uniformity and documented nutrient forms remain stable through routine production and release testing.
How does powder support controlled metering across dry food premix lines?
Powder blends support dry dosing systems because one formulated input replaces several micronutrients with different flow properties. The same handling requirement applies to vitamin premix programs that distribute small active doses through larger carrier volumes.ADM describes its dry blends for human nutrition as formulated systems that consolidate functional ingredients into one standardized input, reducing the number of items to purchase, control, and store while simplifying addition into the production process. Food premix customers are comparing flow behavior and segregation control before approving powder blends for routine commercial batches.
- Powder is forecast to represent 82.0% of form demand in 2026, shaped by familiar storage and metering routines across dry batching systems.
- Dry premix suppliers need flow control and segregation management because physical instability can undermine nutrient uniformity even when the chemical specification is correct.
Why do consolidated premix blends reduce qualification work for nutrition manufacturers?
A consolidated premix lets a customer qualify one formulated input instead of coordinating several nutrient materials and records. This model matters in nutraceutical ingredients programs that combine vitamins with minerals or other functional components. Fenchem lists FenMix Vitamin Premix as a tailor-made food and beverage formulation for customers needing a customized nutrient input. One-step blends retain value when compatibility and documentation remain controlled inside the intended finished-product process.
- Premix blends - direct-to-consumer solutions are likely to capture 93.0% within product type in 2026, influenced by customers consolidating ingredient qualification into one formulated input.
- One-step solutions retain value when suppliers manage ingredient compatibility and documentation without shifting unresolved stability work back to the customer plant.
How does the food sector convert fortification rules into repeat premix orders?
Food manufacturing consumes premix during every production run once a nutrient formula becomes part of a standardized recipe. The same repeat-use mechanism applies across fortified food categories that require defined nutrient addition during routine processing. UK government guidance requires 0.25 mg folic acid per 100 g of non-wholemeal common wheat flour from 13 December 2026. The requirement creates scheduled dosing work for flour producers rather than an optional nutrition claim. Premix suppliers retain these accounts when dispersion and documentation stay consistent through recurring milling operations.
- The food sector is set to lead the application category with 69.0% share in 2026, reinforced by repeat premix consumption in qualified production recipes.
- Food applications reward suppliers that protect taste and processing stability while maintaining the nutrient level specified for the finished product.
What are the drivers, restraints and opportunities in the Food Premix Market?
Fortification requirements expand repeat premix use, regulatory qualification slows supplier changes, and application-specific formulation services can shorten commercialization work.
- Driver: Fortification rules and targeted nutrition programs place measured vitamins and minerals into recurring manufacturing specifications that require controlled blending.
- Restraint: Permitted nutrient forms and dose limits differ by jurisdiction, which can extend reformulation and documentation before a replacement premix is accepted.
- Opportunity: Suppliers can win more formulation work by delivering validated one-step blends that reduce plant handling and customer development time.
Fortification programs convert nutrient policy into recurring formulation work
Fortification programs convert nutrition policy into repeat ingredient specifications when nutrient addition becomes mandatory or programmatic. The food fortifying agents category follows this conversion because mills and food plants must dose defined nutrients into recurring production. The Food Fortification Initiative reports that 94 countries mandate fortification of at least one industrially milled cereal grain, reflecting continued legislative expansion since its founding in 2002. Those rules turn micronutrient addition from an optional formulation choice into repeat process control for covered foods. Premix demand is supported by customers that need consistent nutrient concentration without weighing each low-dose vitamin or mineral separately.
Regulatory differences make formula substitution a controlled change
Premix substitution becomes a controlled change when a replacement blend uses a different nutrient form or alters the permitted amount. The same constraint affects mineral fortification because legal limits can change by intended use and finished-food category. Germany's BfR proposed updated maximum iodine levels for foods and food supplements in December 2025. The agency also advised against general iodine addition to most foods despite documented intake gaps. Buyers are reviewing dose design and intended use before approving a different blend for commercial production. Qualification work can delay supplier changes even after plant trials confirm acceptable processing performance. The regulatory hurdle centers on legal fit rather than on blending capability or plant performance alone.
Application support can move formulation work upstream to the premix supplier
Application support can move formulation work upstream when a nutrition product combines several active ingredients with different stability and labeling requirements. Dietary supplements create this need because brands must coordinate dose design with format and national rules before commercial release. Prinova announced in April 2026 that it would present new Vitafoods Europe concepts combining functional ingredients across gut health and other wellness applications. That development illustrates a route from ingredient selection into formulation and manufacturable product concepts.
Which country CAGRs are profiled in the Food Premix Market?
| Country | CAGR |
|---|---|
| Italy | 11.0% |
| Spain | 10.0% |
| France | 9.0% |
| UK | 8.0% |
| Germany | 7.0% |
| USA | 6.0% |
| Canada | 5.0% |
| Brazil | 4.0% |
How do country-level CAGRs compare in the Food Premix Market?
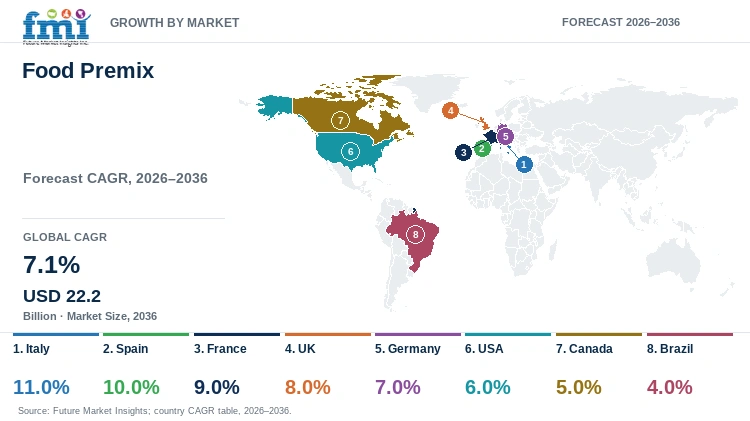
Italy, Spain and France form the upper forecast band at 9.0% to 11.0% CAGR. The UK and Germany occupy the middle forecast range between the upper and lower groups. The USA, Canada and Brazil form the lower forecast band within this eight-country comparison. These rates compare growth pace only and do not establish current country revenue or supplier scale.
- Italy requires national notification for supplements and foods with added vitamins or minerals, so compliant formulation and label documentation become part of pre-commercialization planning.
- In Spain, permitted vitamin and mineral forms plus defined nutrient thresholds keep dose design inside the formulation brief before packaging and commercial positioning are fixed.
- France combines widespread supplement use with active safety oversight and gives nutrition brands a strong reason to prioritize traceable ingredient selection and disciplined dose design.
- The UK folic-acid requirement gives flour producers a fixed implementation date and puts dosing validation ahead of the December 2026 compliance point.
- Germany places strong emphasis on conservative iodine intake guidance and prioritizes targeted nutrient formulations that fit defined uses over broad enrichment of general foods.
- The USA's large supplement user base supports varied nutrition formats, while repeat manufacturing depends on documented dose control and traceable blend quality.
- Canada's supplemented-food rules move composition and labeling review earlier in product development and limit late formula changes before commercial production.
- Brazil's national notification framework ties supplement regularization to composition and traceability requirements and rewards suppliers whose premix documentation fits the current filing process.
Comparable CAGRs can therefore produce different selling conditions because each country changes qualification work through a different national rule or use pattern. The full report provides country-level CAGR analysis across North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
Country-wise Analysis
- Food supplement entry in Italy requires national notification before first commercialization and added-vitamin foods also pass through the same notification system. Italy is projected to grow at 11.0% CAGR through 2036, supported by a documented notification route that links formula and label preparation before commercialization. The Ministry of Health updated its NSIS notification guidance in February 2025 and requires submission of the product label for covered foods. Premix suppliers therefore need formulas that match the intended nutrient forms before customers file their labels. Growth converts into repeat orders most easily when suppliers can support dose design and documentation without forcing a late reformulation.
- Spanish fortified-food formulation starts with permitted nutrient forms and minimum amounts that determine whether a nutrition position can be supported. Food premix demand in Spain is forecast to rise at 10.0% CAGR over the forecast period, driven by continued vitamin and mineral use within defined composition and claim rules. AESAN states that added nutrients must use authorized forms and generally reach defined significant amounts for relevant nutrition claims. Those thresholds make formula math part of the commercial brief before packaging and launch decisions are fixed. Premix suppliers can shorten redesign work when they translate the target claim into a stable dose that remains compliant in the finished product.
- French supplement demand operates beside active national safety oversight rather than an unrestricted wellness channel. France's food premix outlook is anticipated to advance at 9.0% CAGR over the assessment period, attributable to established supplement use under active safety oversight. ANSES stated in March 2025 that one in four French people consumes food supplements and warned that serious adverse effects can occur. The channel therefore rewards traceable ingredient selection and disciplined dose design instead of broad formulation claims. Suppliers serving the adjacent nutraceuticals category can compete more effectively when technical records make each nutrient decision clear to the finished-product brand.
- The United Kingdom is moving a national flour rule from policy into plant implementation during the forecast opening years. Adoption of food premix in the United Kingdom is estimated to expand at 8.0% CAGR through 2036, reinforced by mandatory folic-acid addition that moves flour producers into scheduled validation work. Government guidance requires 0.25 mg folic acid per 100 g of non-wholemeal common wheat flour from 13 December 2026. Millers therefore need dosing systems and premix specifications that deliver the required addition without disrupting established flour quality controls. Suppliers that understand industrial dispersion and compliance documentation can convert the mandate into recurring flour-premix orders after customer validation.
- German food and supplement formulation balances nutrient need with cautious national intake recommendations for selected micronutrients. The German food premix sector is projected to record 7.0% CAGR during the assessment period, influenced by targeted nutrition applications operating within conservative national dose guidance. BfR reported in December 2025 that iodine intake was below the estimated average requirement for about one-third of adults and just under 45% of children and adolescents. The agency still advised against general iodine addition to most foods under its updated national assessment. Premix suppliers must deliver application-specific formulations that address a defined nutrition requirement without moving customers beyond accepted use conditions.
- The United States combines a broad supplement user base with manufacturers that require repeatable quality records for ingredient systems. USA food premix demand is predicted to advance at 6.0% CAGR through 2036, aided by a broad supplement user base and continued use of multi-ingredient nutrition blends. CDC reported in May 2026 that 60.2% of adults used a dietary supplement during the August 2021 to August 2023 survey period. The scale supports many product formats without removing the need for dose control and traceability. Suppliers active in probiotic strains and micronutrients can win repeat work when one qualified blend reduces separate material handling at the customer plant.
- Canada now operates under a clear compliance point for supplemented foods and a standardized set of composition and label requirements. Canada is estimated to post 5.0% CAGR over the forecast period, shaped by supplemented-food rules that move composition and labeling review earlier. Health Canada stated in its 2025-26 plan that all supplemented foods must meet the new composition and labeling requirements from 1 January 2026. Ingredient levels can also trigger specific finished-label cautions that affect formulation approval before commercial production. Premix suppliers serving prebiotic ingredient and vitamin programs need to coordinate dose design with the finished-food category before commercial production commitments are locked.
- Brazil now routes affected supplement products through a national notification framework that places traceability beside composition and labeling. Food premix sales in Brazil are forecast to expand at 4.0% CAGR by 2036, reinforced by supplier documentation upgrades under the completed national notification transition that links composition and traceability requirements before continued regularization. ANVISA closed the RDC 843/2024 transition on 1 September 2026 and required covered supplements to complete notification for continued regularization. The agency also directed companies to review product composition and traceability under the current rules. Premix suppliers can reduce customer rework when their documentation matches the notification file and the blend remains stable for the declared shelf life.
Who are the notable companies in the Food Premix Market?
Glanbia plc, Archer-Daniels-Midland Company, dsm-firmenich AG, Hexagon Nutrition Limited, Jubilant Ingrevia Limited, Fenchem Biotek Ltd., Prinova Group LLC, Barentz International B.V., Sudeep Pharma Limited, and SternVitamin GmbH & Co. KG are notable companies serving food premix applications.
Competition separates dedicated custom-premix manufacturers from broader nutrition ingredient groups that offer integrated formulation capability. Formulation distributors with application laboratories provide a third commercial route for customers needing technical support. Entry requires repeatable blending control plus regulatory support because customers qualify composition and manufacturing execution together. Dependable sourcing also limits entry because customers expect consistent ingredient availability during repeat production.
- Dedicated premix platforms include Glanbia plc and dsm-firmenich AG with documented formulation and manufacturing operations. Hexagon Nutrition Limited and Prinova Group LLC also operate documented premix platforms with commercial application support. Sudeep Pharma Limited and SternVitamin GmbH & Co. KG complete the dedicated premix platform group with specialized nutrition capabilities.
- Broader nutrition systems are represented by Archer-Daniels-Midland Company and Jubilant Ingrevia Limited through ingredient integration and formulated nutrition capabilities.
- Fenchem Biotek Ltd. and Barentz International B.V. add sourcing and formulation networks that support custom blends for food and nutrition programs.
Competitive Benchmarking: Food Premix Market
| Company | Custom Premix Formulation | Multi-Format Application Support | Ingredient Integration & Supply | Geographic Reach |
|---|---|---|---|---|
| Glanbia plc | High | High | High | Global |
| Archer-Daniels-Midland Company | Medium | Medium | High | Global |
| dsm-firmenich AG | High | High | High | Global |
| Hexagon Nutrition Limited | High | High | Medium | 70+ countries |
| Jubilant Ingrevia Limited | Medium | Medium | High | India with international customers |
| Fenchem Biotek Ltd. | Medium | Medium | High | 11-office global network |
| Prinova Group LLC | High | High | High | North America, Europe, Latin America |
| Barentz International B.V. | Medium | High | High | Americas, EMEA, Asia-Pacific |
| Sudeep Pharma Limited | High | High | High | India, Europe, and international exports |
| SternVitamin GmbH & Co. KG | High | High | High | 63-country sales network |
Scoring basis: High requires broad documented capability in the stated criterion and Medium reflects a narrower verified offering. Low identifies a documented limitation or a single operating route within the stated benchmark criterion. Geographic reach remains descriptive and follows current public company evidence for each profiled operating network.
Key Developments in the Food Premix Market
- In May 2026, SternVitamin showcased its SternVita Longevity micronutrient premix at Vitafoods Europe for adult healthy-aging applications.
- In February 2026, Sudeep Pharma reported customer approval from a leading infant-nutrition company for a vitamin and mineral blend.
- In January 2026, Hexagon Nutrition began full-scale availability of its licensed PFH-VAP stable vitamin A fortificant for commercial food fortification.
Key Players in the Food Premix Market
Dedicated Premix Manufacturing Platforms
- Glanbia plc
- dsm-firmenich AG
- Hexagon Nutrition Limited
- Prinova Group LLC
- Sudeep Pharma Limited
- SternVitamin GmbH & Co. KG
Integrated Nutrition Ingredient Systems
- Archer-Daniels-Midland Company
- Jubilant Ingrevia Limited
Specialty Sourcing and Formulation Networks
- Fenchem Biotek Ltd.
- Barentz International B.V.
Food Premix Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By ingredient type, form, product type, application, and region. |
| Quantitative Units | USD billion. |
| Market Definition | Commercial premixed blends of vitamins, minerals, amino acids, probiotics, proteins, enzymes, prebiotics, nucleotides, flavors, and related nutrition ingredients supplied for food, supplement, and OTC applications. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | Italy, Spain, France, UK, Germany, USA, Canada, Brazil, and 20+ countries included in the full report. |
| Key Companies Profiled | Glanbia plc, Archer-Daniels-Midland Company, dsm-firmenich AG, Hexagon Nutrition Limited, Jubilant Ingrevia Limited, Fenchem Biotek Ltd., Prinova Group LLC, Barentz International B.V., Sudeep Pharma Limited, and SternVitamin GmbH & Co. KG. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Food Premix Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Food Premix Market by Segments
Food Premix Market segmented by Ingredient Type:
- Vitamin Premix
- Amino Acids Premixes
- Omega 3 Fatty Acids
- Mineral Premix
- Probiotics
- Proteins
- Enzymes
- Prebiotics
- Nucleotides Premixes
- Flavors
Food Premix Market segmented by Form:
- Powder
- Liquid
Food Premix Market segmented by Product Type:
- Premix Blends - Direct-to-Consumer Solutions
- Drum to Hopper Formulations
Food Premix Market segmented by Application:
- Food Sector
- Dietary Supplements
- Pharma OTC Drugs
Food Premix Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- World Health Organization. (2025, October 24). WHO guideline on fortification of edible oils and fats with vitamins A and D for public health.
- UK Department for Environment, Food & Rural Affairs. (2026). Bread and flour: labelling and composition.
- Agência Nacional de Vigilância Sanitária. (2026, September 1). Anvisa alerta e orienta sobre o prazo de adequação às regras de regularização de alimentos.
- Food Fortification Initiative. Global progress: Mandatory cereal grain fortification legislation.
- Archer-Daniels-Midland Company. (2026). Dry ingredient blends.
- Bundesinstitut für Risikobewertung. (2025, December 19). Update (2025): maximum levels proposed for iodine in foods, including food supplements.
- Prinova Group LLC. (2026, April 20). Prinova showcases everyday wellness solutions at Vitafoods Europe.
- Ministero della Salute. (2025, February 27). FAQ - Alimenti soggetti a notifica attraverso NSIS.
- Agencia Española de Seguridad Alimentaria y Nutrición. (2025). Programa 7: Notificación, etiquetado y composición de complementos alimenticios.
- Agence nationale de sécurité sanitaire de l’alimentation, de l’environnement et du travail. (2025, March 25). Le vrai du faux des compléments alimentaires.
- National Center for Health Statistics. (2026, May). Dietary Supplement Use: United States, August 2021-August 2023.
- Health Canada. (2025). Health Canada 2025-26 Departmental Plan.
- Canadian Food Inspection Agency. (2026, April 1). Labelling requirements for supplemented foods.
- SternVitamin GmbH & Co. KG. (2026, May). SternVita Longevity premix solution showcased at Vitafoods Europe 2026.
- Sudeep Pharma Limited. (2026, February 9). Earnings call transcript: customer approval for vitamin and mineral blend in infant nutrition.
- Hexagon Nutrition Limited. (2026). Strategy & Vision 2030.
- Glanbia plc. (2026, February 25). Full Year 2025 Results.
- dsm-firmenich. (2026, March 11). dsm-firmenich completes $10m upgrade on Schenectady (US) site.
- Jubilant Ingrevia Limited. (2026, May 26). Q4 FY26 press release.
- Archer-Daniels-Midland Company. (2026, May 20). ADM advances protein innovation with new ingredient solutions.
- Fenchem Biotek Ltd. (2026, May 5). Vitafoods Europe 2026.
- Fenchem Biotek Ltd. (2026). FenMix Vitamin Premix.
- Barentz. (2026, April 30). Barentz is showcasing global nutraceutical expertise and private label solutions at Vitafoods.
- Barentz North America. (2026). Human Nutrition Lab Capabilities.
- Glanbia plc. (2026, July 6). Inside Glanbia innovation: Where science, flavour and formulation come together.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the food premix market in 2026 and 2036?
- Which operating conditions convert food premix specifications into repeat customer orders?
- Why does vitamin premix hold the selected ingredient type share in 2026?
- Why is powder projected to account for most form demand in 2026?
- How do national fortification and supplement rules change qualification work among profiled countries?
- Which country CAGRs are included in the 2026 to 2036 comparison?
- How are current food premix companies positioned against formulation and application-support criteria?
- Which recent company actions changed premix capacity or regional customer access?
Frequently Asked Questions
How big is the Food Premix Market in 2026?
The food premix market is valued at USD 11.2 billion in 2026 and is projected to reach USD 22.2 billion by 2036. Repeat demand comes from formulations that use one qualified blend for controlled nutrient dosing.
What is the CAGR of the Food Premix Market from 2026 to 2036?
The food premix market is projected to expand at 7.1% CAGR between 2026 and 2036. Growth depends on recurring fortification and nutrition programs that keep micronutrient specifications inside commercial recipes.
Which form leads the Food Premix Market?
The powder segment is expected to hold 82.0% of form demand in 2026 because dry manufacturing lines can meter one controlled blend efficiently. Flow behavior and segregation control still determine whether a supplier remains qualified for recurring commercial production.
Which countries have the higher CAGRs in the profiled Food Premix Market?
Italy is projected at 11.0% CAGR followed by Spain at 10.0% and France at 9.0% through 2036. Their growth paths differ because national notification and nutrient-use conditions change formulation work in each country.
Which companies are active in the Food Premix Market?
Key companies include Glanbia plc and Archer-Daniels-Midland Company alongside dsm-firmenich AG and Hexagon Nutrition Limited. Jubilant Ingrevia Limited and Fenchem Biotek Ltd. are also active alongside Prinova Group LLC and Barentz International B.V. Sudeep Pharma Limited and SternVitamin GmbH & Co. KG complete the profiled company set used throughout the report. The group spans dedicated premix manufacturing plus integrated nutrition ingredients and formulation distribution services.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Ingredient Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Ingredient Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Ingredient Type, 2026 to 2036
- Vitamin Premix
- Amino Acids Premixes
- Omega 3 Fatty Acids
- Mineral Premix
- Probiotics
- Proteins
- Enzymes
- Prebiotics
- Nucleotides Premixes
- Flavors
- Y-o-Y Growth Trend Analysis By Ingredient Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Ingredient Type, 2026 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form, 2026 to 2036
- Powder
- Liquid
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Premix Blends - Direct-to-Consumer Solutions
- Drum to Hopper Formulations
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Food Sector
- Dietary Supplements
- Pharma OTC Drugs
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Ingredient Type
- By Form
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Ingredient Type
- By Form
- By Product Type
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Ingredient Type
- By Form
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Ingredient Type
- By Form
- By Product Type
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Ingredient Type
- By Form
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Ingredient Type
- By Form
- By Product Type
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Ingredient Type
- By Form
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Ingredient Type
- By Form
- By Product Type
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Ingredient Type
- By Form
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Ingredient Type
- By Form
- By Product Type
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Ingredient Type
- By Form
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Ingredient Type
- By Form
- By Product Type
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Ingredient Type
- By Form
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Ingredient Type
- By Form
- By Product Type
- By Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Type
- By Form
- By Product Type
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Type
- By Form
- By Product Type
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Type
- By Form
- By Product Type
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Type
- By Form
- By Product Type
- By Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Type
- By Form
- By Product Type
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Type
- By Form
- By Product Type
- By Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Type
- By Form
- By Product Type
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Type
- By Form
- By Product Type
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Type
- By Form
- By Product Type
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Type
- By Form
- By Product Type
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Type
- By Form
- By Product Type
- By Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Type
- By Form
- By Product Type
- By Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Type
- By Form
- By Product Type
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Type
- By Form
- By Product Type
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Type
- By Form
- By Product Type
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Type
- By Form
- By Product Type
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Type
- By Form
- By Product Type
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Type
- By Form
- By Product Type
- By Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Type
- By Form
- By Product Type
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Type
- By Form
- By Product Type
- By Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Ingredient Type
- By Form
- By Product Type
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Glanbia plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Archer-Daniels-Midland Company
- dsm-firmenich AG
- Hexagon Nutrition Limited
- Jubilant Ingrevia Limited
- Fenchem Biotek Ltd.
- Prinova Group LLC
- Barentz International B.V.
- Sudeep Pharma Limited
- SternVitamin GmbH & Co. KG
- Glanbia plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


