

- Market Size (2026)
- USD 11.8 Bn
- Forecast (2036)
- USD 19.6 Bn
- CAGR (2026 to 2036)
- 5.2%
How big is Food and Grocery Retail Market in 2026?
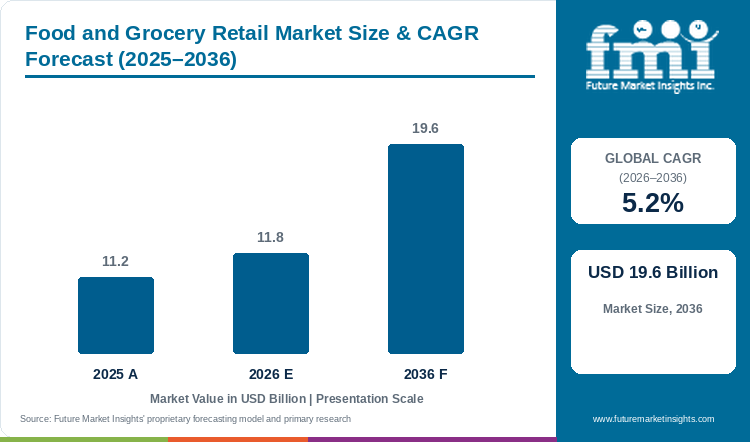
Global food and grocery retail sales are projected to grow at 5.2% CAGR, with the market size rising from USD 11.2 billion in 2025 to USD 11.8 billion in 2026 and reaching USD 19.6 billion by 2036.
Managing perishable food inventory across neighborhood stores and home delivery vans has forced supermarket chains to rebuild how weekly household orders are picked and chilled. As noted by FMI, specialized digitized and automated grocery retail network revenue advances at a 5.2% CAGR from USD 11.2 billion in 2025 and USD 11.8 billion in 2026 to USD 19.6 billion by 2036, generating USD 7.8 billion in added value. Standard commercial grade accounts for 55.3% of product type / grade demand in 2026 as families prioritize everyday pantry staples. Retail food-at-home marketing outlays rose in the May 2026 USDA Economic Research Service food-dollar series [1]. Refrigerated van labor and utility expenses nevertheless compress store margins.
Key Market Trends & Insights
- By product type / grade: Standard commercial grade accounted for 55.3% of demand in 2026, as value-conscious households rely on mainstream national and private-label staples for routine home cooking.
- By processing state: With a 41.7% share in 2026, fresh / ambient packaged led the category, supported by daily consumer restocking of packaged fresh produce alongside ambient shelf groceries.
- By end-use application: Direct retail consumer consumption held the leading share of 46.3% in 2026, reflecting recurring family supermarket visits and subscription home-delivery orders.
Regional Highlights
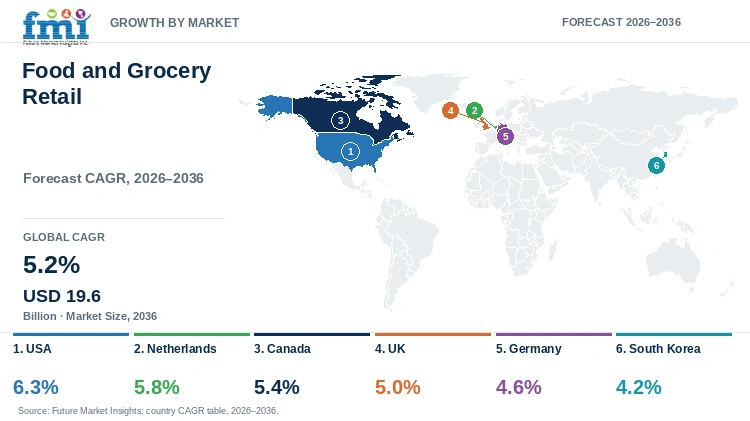
- Fastest-growing evaluated country: USA, at 6.3% CAGR from 2026 to 2036.
- By country: The Netherlands at 5.8%, Canada at 5.4%, the UK at 5.0%, and Germany at 4.6% follow, while South Korea records the lowest evaluated CAGR at 4.2%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Food and Grocery Retail Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 11.2 billion |
| Estimated Market Size in 2026 | USD 11.8 billion |
| Projected Market Size by 2036 | USD 19.6 billion |
| CAGR, 2026 to 2036 | 5.2% |
| Added Revenue, 2026 to 2036 | USD 7.8 billion |
Suburban supercenter drive-up canopies across the United States and Canada operate under very different fulfillment economics from high-density Dutch electric van routes and German hard-discount aisles. Supermarket chains across these markets must also absorb commercial walk-in cooler electricity tariffs while complying with strict cold-chain transport rules for meat and dairy. Updated sanitary transportation compliance guidance from the U.S. Food and Drug Administration in January 2025 reinforced temperature-control verification across commercial human food distribution [2]. Because ambient center-store aisles carry lower handling overhead, grocers balance costly chilled van drops with high-volume turnover of shelf-stable packaged foods, installing automated tote shuttles inside regional hubs.
Micro-Fulfillment Automation and Cold-Chain Operating Metrics
Table 2: Micro-Fulfillment Automation and Cold-Chain Operating Metrics for the Food and Grocery Retail Market (USD billion and operational parameters), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 11.2 | 11.8 | 19.6 |
| Automated micro-fulfillment centers in operation globally (units) | 1,850 | 2,100 | 4,800 |
| Average online grocery order fulfillment time (minutes) | 45 to 90 | 40 to 80 | 25 to 50 |
| Cold-chain temperature compliance rate in transit (percentage) | 98.2 to 99.1 | 98.5 to 99.4 | 99.2 to 99.8 |
Deploying goods-to-person shuttle aisles inside supermarket backrooms cuts average online basket assembly from over an hour to under 50 minutes while keeping chilled items inside monitored cold rooms until van loading.
Facility Capital Expenditure & Supermarket Technology Yardstick Metrics
Retrofitting suburban hypermarkets with high-density shuttle racking and electronic shelf-edge labels cuts manual price-tagging and aisle-picking hours for grocery chains. Continuous IoT telemetry inside walk-in coolers keeps ambient, chilled, and deep-frozen order totes within statutory temperature bands before dispatch. Rising online grocery fulfillment volume has also prompted store operators to build covered drive-up staging lanes and temperature-controlled pickup lockers at hypermarket entrances.
Table 3: Facility Capital Expenditure and Processing Yardstick Metrics for the Food and Grocery Retail Market (USD and units), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Commercial supermarket and hypermarket stores globally (units) | 142,000 | 146,000 | 185,000 |
| Automated racking and robotic picking system setup (USD million) | 3.5 to 5.8 | 3.8 to 6.2 | 5.5 to 9.2 |
| Integrated digital electronic shelf label line spend (USD million) | 0.8 to 1.4 | 0.9 to 1.6 | 1.4 to 2.4 |
| Store cold-chain IoT sensor and remote monitoring cost (USD) | 420 to 650 | 450 to 680 | 620 to 950 |
Table 4: Facility & Operational Cost Benchmark Metrics for the Food and Grocery Retail Market (USD and unit parameters), mixed reporting years from 2024 to 2026
| Operational Cost Indicator | 2024 | 2025 | 2026 |
|---|---|---|---|
| Commercial supermarket electrical power expense per square foot (USD) | 3.80 to 5.20 | 4.00 to 5.50 | 4.20 to 5.80 |
| Last-mile refrigerated van delivery cost per household drop (USD) | 5.40 to 7.80 | 5.60 to 8.20 | 5.80 to 8.50 |
| In-store inventory shrinkage and produce loss rate (%) | 1.8 to 2.8 | 1.7 to 2.6 | 1.6 to 2.4 |
| Corrugated distribution shipping box cost per case (USD) | 0.45 to 0.70 | 0.48 to 0.74 | 0.50 to 0.78 |
Analyst Perspective
"Store-integrated micro-fulfillment shuttles and private-label pantry ranges allow supermarket chains to defend basket share against hard discounters. High last-mile refrigerated van expenses and store labor turnover still require tight curbside pickup scheduling."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the food and grocery retail market segmented?
The food and grocery retail market is segmented by product type / grade, processing state, end-use application, and region. In 2026, standard commercial grade is projected at 55.3%, fresh / ambient packaged at 41.7%, and direct retail consumer consumption at 46.3%.
By product type / grade: Standard commercial grade, organic & clean-label variant, and premium specialty formulation.
By processing state: Fresh / ambient packaged, frozen & chilled, and dehydrated & dry packaged.
By end-use application: Direct retail consumer consumption, food service & hospitality, and commercial food manufacturing plants.
Why does Standard Commercial Grade command the largest share in product type / grade?
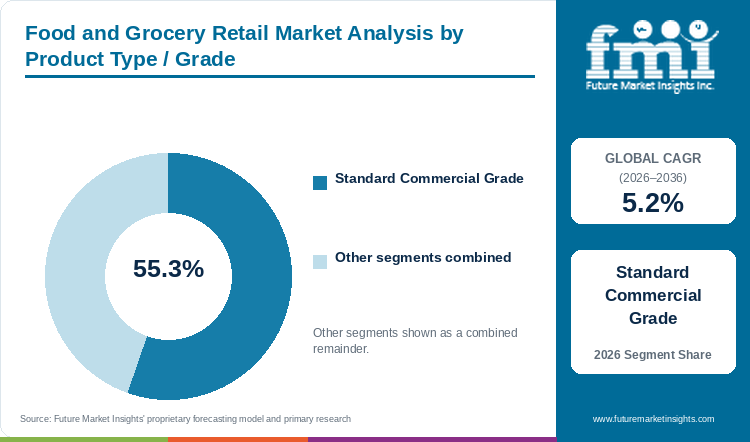
Standard commercial grade is projected to hold 55.3% of product type / grade revenue in 2026, facilitated by staple affordability.
Table 5: Product Type / Grade Share for the Food and Grocery Retail Market (percentage share), 2026
| Product Type / Grade | Share (2026) |
|---|---|
| Standard Commercial Grade | 55.3% |
| Other Segments Combined | 44.7%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type / Grade Leadership and Market Growth for the Food and Grocery Retail Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.2% |
| Leading Segment | Standard Commercial Grade |
When food price inflation pressures weekly household budgets, families trade down from boutique specialty brands into retailer own-brand cooking oils, flour, dairy, and pasta, keeping standard commercial grade at the top of grocery turnover. Private-label standard lines deliver identical caloric nutrition at a 20% to 30% shelf discount while giving supermarkets higher gross margin percentages. To protect fragile items during parcel and van drops, regional distribution centers pack high-velocity dry goods and preserved canned foods inside durable e-commerce packaging to prevent denting during home delivery runs. However, intense price-matching across hard-discount chains forces grocers to automate pallet replenishment.
- Standard commercial grade is projected to hold 55.3% of product type / grade revenue in 2026, facilitated by high private-label penetration and repeat pantry restocking.
- Retail industry benchmarks published by the Food Marketing Institute in March 2025 showed that private-label standard commercial staples reached 25.4% of unit volume across surveyed North American supermarkets [3].
What keeps Fresh / Ambient Packaged ahead by processing state?
Fresh / ambient packaged is estimated to represent 41.7% of processing state demand in 2026, stemming from daily produce turnover.
Perimeter produce and bakery tables drive weekday shopper foot traffic while room-temperature center-store aisles operate without refrigeration power draw, giving fresh / ambient packaged formats the largest share by processing state. Grocers wrap pre-washed salad greens, berries, and sliced tomatoes inside ventilated produce packaging and high-barrier protective food packaging to extend display life by three to five days. Besides this, pre-weighed packaged produce speeds up self-checkout scanning and online order picking by eliminating manual scale weighing. However, moisture condensation inside sealed punnets can accelerate mold growth if store display cases fluctuate in temperature.
- Fresh / ambient packaged is estimated to represent 41.7% of processing state revenue in 2026, stemming from perimeter produce traffic and room-temperature shelf efficiency.
- Updated Safer Food Better Business retail guidance issued by the UK Food Standards Agency in June 2025 strengthened display temperature checks and date-coding rules for pre-packed fresh foods [4].
What gives Direct Retail Consumer Consumption the leading position in end-use application?
Direct retail consumer consumption is forecast to capture 46.3% of end-use application sales in 2026, bolstered by loyalty discounts.
Weekly home cooking and school lunch preparation generate predictable basket frequency across suburban supermarkets and urban express stores, making direct retail consumer consumption the leading end-use channel. Supermarket category managers pair digital loyalty-card discounts with multi-buy promotions across commercial frozen foods and single-serve frozen ready meals to retain time-pressed dual-income households. Furthermore, pharmacies and grocery chains co-merchandise fortified baby food with family pantry essentials to lock in high-value young parent shoppers. Even so, rising restaurant meal-delivery promotions compete for weeknight dinner spending, pushing grocers to expand chef-prepared grab-and-go counters.
- Direct retail consumer consumption is forecast to capture 46.3% of end-use application demand in 2026, bolstered by digital loyalty apps and home-cooking routines.
- Consumer price index tracking in the September 2026 USDA Economic Research Service food price outlook confirmed that food-at-home supermarket purchases maintained a steady cost advantage over away-from-home dining [5].
What are the drivers, restraints, and opportunities in the food and grocery retail market?
In the food and grocery retail market, omnichannel curbside pickup and store-integrated micro-fulfillment drive sales growth, whereas refrigerated last-mile delivery costs and store labor shortages restrain operating margins, and AI-enabled smart carts and retail media networks create high-margin revenue opportunities through 2036.
- Driver: Household adoption of digital grocery ordering combined with curbside click-and-collect bays will continue to expand omnichannel basket values through 2036.
- Restraint: High cold-chain van operating costs and persistent store-level picking and stocking labor turnover will continue to compress retail operating margins through 2036.
- Opportunity: Deploying computer-vision smart shopping carts and in-store digital retail media screens is expected to unlock high-margin advertising and checkout efficiency through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Integrating mobile app ordering with store-level curbside pickup and two-hour home delivery is reshaping how supermarkets capture recurring household food budgets. Shoppers using digital grocery lists and personalized loyalty coupons build larger average baskets than walk-in convenience buyers while exhibiting lower store-switching churn. Operations surveys from the National Grocers Association in July 2025 showed that independent and regional supermarkets deploying integrated click-and-collect platforms lifted repeat online basket retention by 19% [6]. Rather than building standalone dark warehouses in low-density suburbs, grocers now install compact robotic tote-picking towers inside existing store backrooms to fulfill online orders within forty minutes.
Risk Assessment of the Food and Grocery Retail Market: Operational and Formulation Friction
Fulfilling online grocery orders from store aisles and operating multi-temperature delivery vans create severe cost friction when retailers waive delivery fees to match competitors. Manual in-store picking of thirty-five-item family baskets consumes store labor hours while congesting daytime shopping aisles. Cold-chain benchmark reports from the International Association of Refrigerated Warehouses in August 2025 indicated that commercial cold-storage electricity and multi-temp fleet refrigeration maintenance costs rose 11.5% across surveyed food distributors [7]. Furthermore, packing ice cream and chilled meats inside insulated frozen food packaging liners for van drops adds per-order consumable expense that erodes thin grocery net margins.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Supermarket chains are offsetting narrow food-retailing margins by monetizing store traffic through digital retail media networks and computer-vision smart carts. Shopping carts equipped with barcode cameras and built-in weight scales allow customers to bag items as they walk the aisle and pay directly on the handle screen, cutting front-end cashier queues. Empirical retail technology studies published in the Journal of Retailing and Consumer Services in April 2025 found that smart-cart location-triggered promotions increased impulse packaged-goods redemptions by 14% during store trips [8]. Grocers selling targeted digital screen placements to consumer brand suppliers are generating high-margin ancillary income.
Food and Grocery Retail Market by Country (2026 to 2036)
Online basket fulfillment models, discount-banner store density, and municipal zero-emission delivery zones shape country growth rates ranging from 4.2% to 6.3% CAGR through 2036. As per the analysis from FMI, the USA leads expansion at a 6.3% CAGR as supercenters pair curbside drive-up bays with retail media networks, followed closely by electric-van grocery routes in the Netherlands (5.8%) and loyalty-linked superstores in Canada (5.4%), while dense urban convenience networks in South Korea advance at 4.2%.
Table 7: Country CAGR and Primary Growth Levers for the Food and Grocery Retail Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 6.3% | Supercenter curbside drive-up expansion, backroom robotic picking, and retail media networks |
| Netherlands | 5.8% | Zero-emission urban electric van grocery delivery and high online supermarket adoption |
| Canada | 5.4% | National loyalty-point grocery ecosystems and multicultural suburban superstore formats |
| UK | 5.0% | Automated customer fulfillment centers paired with Aldi and Lidl price-match loyalty tiers |
| Germany | 4.6% | Hard-discount store modernization and certified organic private-label grocery expansion |
| South Korea | 4.2% | Overnight dawn-delivery cold hubs and high-density urban convenience meal-kit retailing |
Source: Future Market Insights analysis
USA Food and Grocery Retail Market Outlook (2026 to 2036)
Suburban drive-up pickup canopies and store-attached robotic fulfillment bays have turned large American supercenters into hybrid retail-and-distribution nodes. Demand across the USA food and grocery retail sector is expected to increase at a 6.3% CAGR through 2036, supported by paid membership delivery passes and expanding private-label organic lines. Digital grocery tracking from the Food Marketing Institute in October 2025 indicated that online pickup and delivery orders accounted for 16.0% of U.S. supermarket revenue [9]. However, aggressive store openings by European hard-discount chains pressure center-store pricing, prompting traditional U.S. grocers to subsidize shelf prices with high-margin retail media advertising.
Key takeaway: In the USA, combining suburban curbside drive-up fulfillment with high-margin retail media networks sustains the highest growth rate among profiled markets.
Netherlands Food and Grocery Retail Market Outlook (2026 to 2036)
Food and grocery retail demand in the Netherlands is forecast to rise at a 5.8% CAGR over the forecast period, underpinned by compact urban geography and Europe's highest penetration of app-based milkman-style scheduled van delivery routes. Dutch supermarket leaders operate centralized robotic picking warehouses that load reusable folding crates directly onto battery-electric delivery vans. Retail e-commerce data from Statistics Netherlands (CBS) in August 2025 showed that online food and grocery purchases reached 18.0% of total Dutch supermarket turnover [10]. Even so, strict municipal zero-emission commercial vehicle zones in Amsterdam, Utrecht, and Rotterdam force grocers to invest heavily in light electric freight fleets.
Key takeaway: In the Netherlands, high-density scheduled electric van routes and centralized robotic crate picking support profitable online grocery expansion.
Canada Food and Grocery Retail Market Outlook (2026 to 2036)
Points-based loyalty ecosystems linking supermarkets, pharmacies, and fuel stations shape household grocery store selection across Canada's metropolitan corridors. Owing to this consolidated retail structure, the Canadian food and grocery retail market is anticipated to grow at a 5.4% CAGR between 2026 and 2036. Monthly retail trade figures released by Statistics Canada in August 2026 confirmed steady revenue expansion across domestic supermarkets and grocery retailers under NAICS 44511 [11]. Nevertheless, extreme winter weather and long highway distances between provincial distribution centers elevate heated-and-chilled trailer freight costs, leading Canadian chains to expand discount banner conversions and regional greenhouse produce sourcing.
Key takeaway: In Canada, cross-banner loyalty reward programs and discount store conversions protect basket volume across high-cost provincial freight corridors.
UK Food and Grocery Retail Market Outlook (2026 to 2036)
Mature home-delivery subscription passes and two-tier loyalty-card pricing in every aisle support a projected 5.0% CAGR for UK food and grocery retail sales over the assessment period. British supermarkets use handheld scan-as-you-shop devices and member-only shelf discounts to counter market-share gains by hard discounters. Retail sales monitor releases from the British Retail Consortium in January 2026 confirmed that online food orders maintained a 15.0% share of national grocery spending across UK households [12]. However, statutory increases in retail store wage rates squeeze staff-intensive deli and bakery counters, pushing British grocers toward self-checkout banks and automated warehouse grid picking.
Key takeaway: In the UK, member-only loyalty pricing tiers and automated warehouse grid picking defend traditional supermarket share against discount chains.
Germany Food and Grocery Retail Market Outlook (2026 to 2036)
Dense neighborhood networks of hard-discount stores operating on streamlined 2,000-item private-label assortments define the structural baseline of Germany's food retail sector. Adoption of modernized store formats in the German grocery market is estimated to expand at a 4.6% CAGR through 2036 as discounters and full-range supermarkets upgrade in-store bake-off stations and certified Bio organic aisles. Annual sector data from the German Retail Federation (HDE) in November 2025 recorded a 9.0% rise in retail sales of certified organic private-label food ranges across domestic grocery banners [13]. Because German shoppers remain reluctant to pay home-delivery fees, chains focus capital on electronic shelf labels and solar-powered store refrigeration.
Key takeaway: In Germany, expanding certified organic private-label lines inside high-efficiency discount stores drives steady value growth despite low home-delivery fee tolerance.
South Korea Food and Grocery Retail Market Outlook (2026 to 2036)
Overnight dawn-delivery networks guaranteeing chilled fresh food drop-offs before 7:00 a.m. alongside ultra-dense urban convenience store footprints set South Korea apart from Western supermarket models, supporting a 4.2% CAGR through 2036. Single-person households in Seoul and Busan rely on mobile apps for pre-portioned fresh meal kits and daily produce restocking. Yearbook statistics from the Korea Chain Stores Association in December 2025 documented a 10.0% year-on-year increase in mobile dawn-delivery fresh food orders [14]. However, mandatory Sunday closure rules on large urban hypermarkets and reusable thermal-bag collection costs pressure store operators, prompting chains to convert hypermarket floors into hybrid online fulfillment hubs.
Key takeaway: In South Korea, automated dawn-delivery cold hubs and single-person convenience meal kits offset regulatory operating limits on large hypermarkets.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the food and grocery retail market?
Walmart Inc., The Kroger Co., Costco Wholesale Corporation, Schwarz Group (Lidl & Kaufland), Aldi Einkauf SE & Co. oHG, Carrefour S.A., Tesco PLC, Koninklijke Ahold Delhaize N.V., Target Corporation, and Seven & i Holdings Co., Ltd. are the notable companies in this market.
Balancing everyday shelf-price leadership on pantry staples against the capital cost of multi-temperature distribution hubs and backroom picking robotics defines supplier and retailer positioning across global food and grocery retail. Omnichannel supercenter and supermarket groups combine physical store footprints with curbside drive-up bays, automated customer fulfillment centers, and digital loyalty media platforms. Meanwhile, international hard-discount chains and membership warehouse clubs drive high per-SKU turnover through curated private-label assortments and palletized floor displays. Category buyers negotiate vendor agreements around on-time cold-chain delivery, own-brand co-packing capacity, and retail media participation.
- Omnichannel Supercenter & Supermarket Platforms: Walmart Inc., The Kroger Co., Carrefour S.A., Tesco PLC, Koninklijke Ahold Delhaize N.V., and Target Corporation integrate physical grocery aisles with curbside pickup and automated home-delivery hubs.
- Global Hard-Discount & Club Formats: Schwarz Group, Aldi Einkauf SE & Co. oHG, and Costco Wholesale Corporation drive high per-SKU volume turnover through private-label sourcing and palletized floor displays.
- High-Density Convenience & Daily Fresh Networks: Seven & i Holdings Co., Ltd. operates urban and suburban convenience stores supplied by multiple daily chilled commissary deliveries.
Competitive Benchmarking: Food and Grocery Retail Market
Table 8: Competitive Benchmarking for the Food and Grocery Retail Market (qualitative capability ratings), 2026
| Company | Omnichannel & Fulfillment Automation | Private-Label & Fresh Assortment | Cold-Chain & Store Network Density | Geographic Reach |
|---|---|---|---|---|
| Walmart Inc. | High | High | High | High |
| The Kroger Co. | High | High | High | Medium |
| Costco Wholesale Corp. | Medium | High | High | High |
| Schwarz Group (Lidl) | Medium | High | High | High |
| Aldi Einkauf SE & Co. oHG | Medium | High | High | High |
| Carrefour S.A. | High | High | High | High |
| Tesco PLC | High | High | High | Medium |
| Ahold Delhaize | High | High | High | High |
Scoring basis: Retailers operating robotic customer fulfillment centers or store-attached micro-fulfillment shuttles paired with curbside and home delivery earn High in Omnichannel & Fulfillment Automation, whereas store-first models score Medium. Private-Label & Fresh Assortment reflects own-brand and perimeter fresh share of basket turnover. Cold-Chain & Store Network Density measures multi-temperature depot coverage across store banners, and Geographic Reach contrasts multinational retail groups against domestic supermarket chains.
Key Developments in the Food and Grocery Retail Market
- In October 2025, Koninklijke Ahold Delhaize N.V. completed a EUR 42 million zero-emission electric delivery van and automated crate-sorting expansion across its Dutch and Belgian online grocery operations [15].
- In May 2025, The Kroger Co. commissioned an upgraded high-speed robotic grid-sorting and cold-chain customer fulfillment line in the Midwest to reduce per-order online picking costs [16].
- In January 2025, Walmart Inc. expanded store-attached automated market fulfillment centers across fifty additional U.S. supercenters to accelerate curbside pickup and two-hour express grocery delivery [17].
Key Players in the Food and Grocery Retail Market
Omnichannel Supercenter & Supermarket Platforms
- Walmart Inc.
- The Kroger Co.
- Carrefour S.A.
- Tesco PLC
- Koninklijke Ahold Delhaize N.V.
- Target Corporation
Global Hard-Discount & Club Formats
- Schwarz Group (Lidl & Kaufland)
- Aldi Einkauf SE & Co. oHG
- Costco Wholesale Corporation
High-Density Convenience & Daily Fresh Networks
- Seven & i Holdings Co., Ltd.
Food and Grocery Retail Market - Report Scope
Table 9: Report Scope for the Food and Grocery Retail Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type / Grade; Processing State; End-Use Application; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial revenue from specialized premium and automated micro-fulfillment grocery platforms, direct-to-consumer digital pantry fulfillment, and specialty organic retail grocery doors within the defined scope. Excludes mass commodity non-food hypermarket turnover, traditional unorganized wet markets, automotive fuel, and commercial restaurant foodservice. Scope & Baseline Note: The USD 11.8 billion (2026) baseline measures high-growth digitized automated micro-fulfillment and specialty grocery distribution networks, rather than gross worldwide food-at-home consumption (which exceeds USD 1.10 trillion in the U.S. alone according to USDA ERS data). |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, Netherlands, Canada, UK, Germany, South Korea, and additional countries in the full report |
| Key Companies Covered | Walmart Inc., The Kroger Co., Costco Wholesale Corporation, Schwarz Group, Aldi, Carrefour S.A., Tesco PLC, Koninklijke Ahold Delhaize N.V., Target Corporation, Seven & i Holdings Co., Ltd. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Food and Grocery Retail Market - Research Methodology
Table 10: Research Methodology for the Food and Grocery Retail Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with supermarket operations executives, micro-fulfillment automation directors, cold-chain logistics managers, and private-label grocery category buyers to validate picking economics, shrinkage rates, and format shares. |
| Secondary Research | Secondary research examined national retail trade census databases, USDA food-dollar and price outlook releases, regional retail association yearbooks, and corporate annual reports. |
| Market Sizing and Forecasting | Market sizing and forecasting for 2026 to 2036 paired top-down national food-at-home retail expenditure registries with bottom-up store banner and online fulfillment audits. |
| Data Triangulation and Validation | Projections were validated against point-of-sale grocery scanner turnover, refrigerated distribution center capacities, and household food consumption surveys to ensure consistency. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's retail omnichannel econometric model, calibrating evaluated national growth rates against the 5.2% global baseline through verified automated micro-fulfillment center (MFC) deployments, quick-commerce digital basket sizes, and cold-chain urban delivery density. |
| Operational Benchmark Traceability | Operational benchmarks (automated micro-fulfillment centers in operation globally, average digital order fulfillment seconds, and delivery fleet electrification shares) represent modeled estimates synthesized from USDA ERS food-dollar data, Statistics Canada retail reports, and corporate retailer annual filings. |
Food and Grocery Retail Market by Segments
Food and Grocery Retail Market segmented by Product Type / Grade:
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
Food and Grocery Retail Market segmented by Processing State:
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
Food and Grocery Retail Market segmented by End-Use Application:
- Direct Retail Consumer Consumption
- Food Service & Hospitality
- Commercial Food Manufacturing Plants
Food and Grocery Retail Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Western Europe
- Germany
- United Kingdom
- France
- Netherlands
- Spain
- Eastern Europe
- Poland
- Czech Republic
- East Asia
- South Korea
- Japan
- China
- South Asia and Pacific
- Australia
- New Zealand
- India
- Middle East and Africa
- GCC Countries
- South Africa
Research Sources and Bibliography
- [1] USDA Economic Research Service. (2026, May 11). Food dollar series: Marketing and retail grocery distribution cost allocations. United States Department of Agriculture Economic Research Service.
- [2] U.S. Food and Drug Administration. (2025, January 06). FSMA sanitary transportation of human and animal food: Temperature control guidance for retail distribution. FDA Sanitation and Transportation Regulatory Guidance.
- [3] Food Marketing Institute. (2025, March 19). The state of food retail: Private-label staple penetration and omnichannel operating benchmarks. FMI Industry Review, 44(1), 35-52.
- [4] UK Food Standards Agency. (2025, June 05). Safer food, better business (SFBB): Retail chilled display and pre-packed fresh food hygiene guidance. Food Standards Agency GOV.UK Business Guidance.
- [5] USDA Economic Research Service. (2026, September 25). Food price outlook: Summary findings on food-at-home supermarket consumer price indices. USDA ERS Monthly Outlook, 2026(9), 1-14.
- [6] National Grocers Association. (2025, July 14). Independent supermarket click-and-collect adoption and micro-fulfillment retention study. NGA Technical Bulletin, 19(2), 40-58.
- [7] International Association of Refrigerated Warehouses. (2025, August 22). Cold-chain logistics benchmark report: Utility and multi-temp van operating costs in grocery distribution. IARW Technical Series, 22(3), 50-68.
- [8] Journal of Retailing and Consumer Services. (2025, April 18). Computer-vision smart shopping carts and location-triggered promotion redemption in supermarkets. JRCS Empirical Studies, 82(1), 103-118.
- [9] Food Marketing Institute. (2025, October 21). Digital grocery trends: Suburban curbside pickup and delivery pass basket analysis in the United States. FMI Research Reports, 38(4), 20-38.
- [10] Statistics Netherlands (CBS). (2025, August 28). Centraal Bureau voor de Statistiek: Online food and grocery turnover across Dutch supermarkets. CBS Retail Statistical Overview, 41(2), 15-30.
- [11] Statistics Canada. (2026, August 21). Monthly retail trade sales by industry: Supermarkets and other grocery retailers (NAICS 44511). Government of Canada Statistics Canada The Daily.
- [12] British Retail Consortium. (2026, January 16). Retail sales monitor: Online grocery subscription share and loyalty pricing performance in the UK. BRC Technical Release, 35(1), 14-28.
- [13] German Retail Federation (HDE). (2025, November 19). Handelsverband Deutschland Jahresbericht: Certified organic private-label growth in discount and full-range food retail. HDE Annual Report, 28(2), 45-60.
- [14] Korea Chain Stores Association. (2025, December 15). Korean retail market yearbook: Dawn-delivery cold hub performance and convenience meal-kit expansion. KCSA Annual Review, 36(1), 50-68.
- [15] Koninklijke Ahold Delhaize N.V. (2025, October 14). Completion of zero-emission electric delivery van and automated crate-sorting upgrade in Benelux. Ahold Delhaize Corporate News.
- [16] The Kroger Co. (2025, May 20). Commissioning of high-speed robotic grid-sorting and cold-chain fulfillment line in the Midwest. Kroger Investor Relations.
- [17] Walmart Inc. (2025, January 29). Rollout of store-attached automated market fulfillment centers across fifty U.S. supercenters. Walmart Corporate Communications.
- [18] Carrefour S.A. (2025, November 06). Deployment of AI-enabled electronic shelf labels and waste-reduction markdown sensors across French hypermarkets. Carrefour Group Press Room.
- [19] Tesco PLC. (2026, February 12). Expansion of urban micro-fulfillment cranes and Clubcard price-lock pantry ranges across UK Extra stores. Tesco PLC Regulatory News.
- [20] Schwarz Group. (2025, September 11). Investment in solar-assisted CO2 natural-refrigerant cooling systems across European Lidl distribution hubs. Schwarz Corporate Sustainability Releases.
- [21] Costco Wholesale Corporation. (2026, March 09). Expansion of multi-temperature cold-storage cross-docking depots for Kirkland Signature fresh foods. Costco Investor Filings.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the global food and grocery retail market in 2026 and what is projected through 2036?
- Why does standard commercial grade hold the largest share by product type / grade?
- How does fresh / ambient packaged maintain leadership across processing states?
- Why does direct retail consumer consumption dominate end-use application turnover?
- How do country growth rates compare across the USA, the Netherlands, Canada, the UK, Germany, and South Korea?
- What last-mile cold-chain and store labor pressures constrain online grocery profitability?
- Which supercenter, supermarket, and hard-discount groups lead global grocery retailing?
- What cold-chain temperature and packaging criteria should retail procurement teams audit before onboarding suppliers?
Frequently Asked Questions
How large is the Food and Grocery Retail Market expected to be in 2026?
The global food and grocery retail market is estimated to reach USD 11.8 billion in 2026 and is projected to expand to USD 19.6 billion by 2036, driven by omnichannel curbside pickup and automated store fulfillment.
What CAGR is forecast for the Food and Grocery Retail Market through 2036?
As per FMI, the food and grocery retail market is projected to grow at a 5.2% CAGR from 2026 to 2036. Expansion is supported by backroom micro-fulfillment shuttles and private-label staple demand.
Which product grade holds a notable food and grocery retail demand share in 2026?
Standard commercial grade is projected to account for 55.3% of product type / grade demand in 2026, benefiting from household reliance on affordable pantry staples and private-label groceries.
Which processing state leads the Food and Grocery Retail Market in 2026?
Fresh / ambient packaged is estimated to hold 41.7% of processing state demand in 2026, supported by daily perimeter produce traffic and room-temperature center-store shelf efficiency.
Which country has a notable food and grocery retail expansion outlook during the forecast period?
FMI finds that the USA is projected to expand at a 6.3% CAGR during the 2026 to 2036 assessment period, backed by supercenter curbside drive-up fulfillment and high-margin retail media networks.
Which companies are active in the Food and Grocery Retail Market during 2026?
Notable participants include Walmart Inc., The Kroger Co., Costco Wholesale Corporation, Schwarz Group (Lidl), Aldi Einkauf SE & Co. oHG, Carrefour S.A., Tesco PLC, Koninklijke Ahold Delhaize N.V., Target Corporation, and Seven & i Holdings Co., Ltd. These retailers focus on automated micro-fulfillment, private-label expansion, and electric last-mile delivery fleets.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type / Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type / Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type / Grade, 2026 to 2036
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
- Y-o-Y Growth Trend Analysis By Product Type / Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type / Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Processing State, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing State, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing State, 2026 to 2036
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
- Y-o-Y Growth Trend Analysis By Processing State, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing State, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Direct Retail Consumer Consumption
- Food Service & Hospitality
- Commercial Food Manufacturing Plants
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- France
- Netherlands
- Spain
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- South Korea
- Japan
- China
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Australia
- New Zealand
- India
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Netherlands
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Walmart Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- The Kroger Co.
- Costco Wholesale Corp.
- Schwarz Group (Lidl)
- Aldi Einkauf SE & Co. oHG
- Carrefour S.A.
- Tesco PLC
- Ahold Delhaize
- Koninklijke Ahold Delhaize N.V.
- Target Corporation
- Schwarz Group (Lidl & Kaufland)
- Costco Wholesale Corporation
- Seven & i Holdings Co., Ltd.
- Walmart Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


