
- Market Size (2026)
- USD 194.2 Bn
- Forecast (2036)
- USD 653.6 Bn
- CAGR (2026 to 2036)
- 12.9%
How big is the Vertical Market Software Market in 2026?
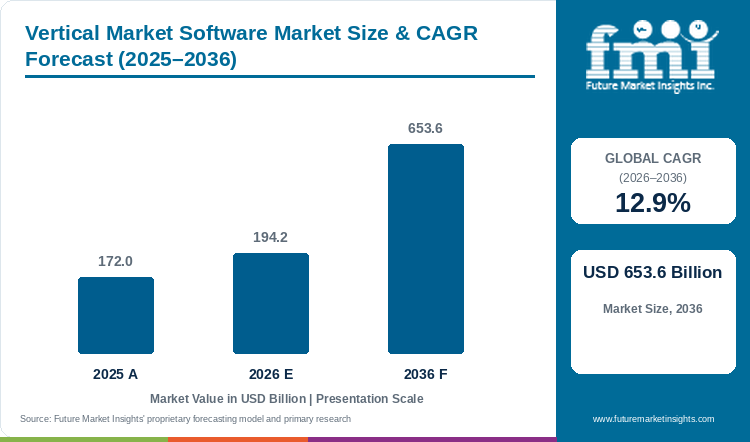
Demand is projected to expand at 12.9% CAGR from 2026 to 2036. Market value rises from USD 172 billion in 2025 to USD 194.2 billion in 2026 and USD 653.6 billion by 2036.
FMI values the vertical market software market at USD 194.2 billion in 2026 compared with an estimated USD 172 billion in 2025, with sales forecast to reach USD 653.6 billion by 2036, growing at a 12.9% CAGR. [1] Unlike horizontal software that serves generic business functions, vertical market software is engineered to handle the highly specific operational, regulatory, and data workflows of distinct industries. A bank and a healthcare payer require entirely different records, permissions, and decision workflows, even when both purchase software through a similar cloud deployment model.
For large enterprises, which command a dominant 58.3% share of the market, the primary challenge lies in connecting these specialized sector systems with existing business units and legacy information architecture. This reality makes rigorous migration planning and reliable application programming interfaces central to the total cost and ultimate usefulness of the implementation. Inconsistent legacy identifiers or outdated data formats can create massive operational friction beyond the initial license purchase. Consequently, product evaluation must rely on representative data records and a clear understanding of the exceptions encountered in daily use.
Key Market Trends and Insights
- Banking software accounts for 18.2% of the software type category in 2026, reflecting the dedicated systems required for financial transactions, customer records and reliable daily reconciliation.
- Large enterprises hold 58.3% of enterprise size demand in 2026, reflecting the integration and coordination required across several systems, business units and industry-specific operating workflows.
- Sector-specific interfaces shape software evaluation because the records, permissions and exceptions used by a buyer can determine practical workflow fit beyond a generic count of product features.
Regional Highlights
- Fastest-growing profiled market: Australia at 16.4% CAGR from 2026 to 2036.
- Financial and healthcare buyers need different data and service obligations despite both using cloud software.
Market Size and Forecast
Table 1: Market size and forecast for the vertical market software market in USD billion and percentage
| Metric | Value |
|---|---|
| 2025 market size | USD 172 billion |
| Estimated market size in 2026 | USD 194.2 billion |
| Projected market size by 2036 | USD 653.6 billion |
| CAGR 2026 to 2036 | 12.9% |
| Added revenue 2026 to 2036 | USD 459.4 billion |
| Market expansion multiple | 3.4x |
Enterprise resource planning links core business records and processes. Vertical software builds on this work with sector-specific transactions and permissions, while migration and integration remain part of implementation.
Sector Workflow and Regulatory Evidence
Banking resilience requirements and US payer interoperability rules address the operating needs of their respective sectors. [2][3]
Table 2: Evidence and adoption indicators for the vertical market software market
| Indicator | Data point or finding | Commercial relevance | Source |
|---|---|---|---|
| EU finance | DORA applied from 17 January 2025 | Creates a resilience qualification context | [2] |
| ICT providers | Third-party risk remains part of the financial entity's responsibility | Affects vendor contracts and oversight | [2] |
| US impacted payers | CMS rule specifies interoperability APIs | Defines a healthcare integration requirement | [3] |
Analyst Perspective
"Industry software needs to reflect the records and decisions people actually use, including the exceptions that make a workflow difficult. A strong demonstration should therefore show more than a feature list: it should connect representative transactions with a credible migration and interface plan. Buyers can judge implementation value more clearly when the supplier explains how existing records will remain usable and which responsibilities continue after the system goes live."
- Sudip Saha, Principal Consultant, FMI
How is the Vertical Market Software Market segmented?
The market is segmented by region; software type; deployment; enterprise size.
By software type: Banking; Healthcare; Retail; Manufacturing; Other industry software.
By deployment: Cloud; On-premises; Hybrid.
By enterprise size: Large enterprises; Small and medium enterprises.
Why does banking software lead demand within the software type category?
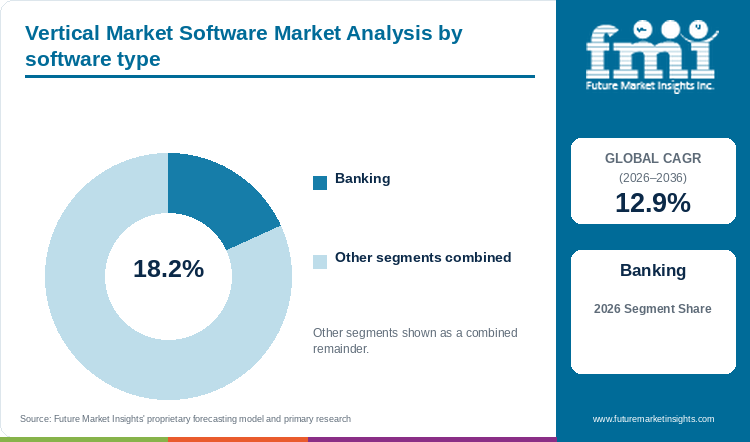
The banking software segment accounts for 18.2% of software type demand in 2026.
Banking software leads the software type category because financial institutions rely on accurate customer records and transactions within systems that support daily reliability and reconciliation. These workflows require permissions and interfaces suited to banking operations, while relevant EU financial buyers also consider DORA’s ICT-risk and third-party requirements. Revenue management software addresses related pricing and billing work, although a banking platform must fit the institution’s complete operating process. The leading position therefore reflects sector-specific functionality and the integration needed to keep records and decisions consistent across connected systems. [2]
- Banking software accounts for 18.2% of the software type category in 2026, reflecting the dedicated systems required for financial transactions, customer records and reliable daily reconciliation.
- Financial buyers should qualify banking systems against their actual transactions and interfaces, with relevant EU entities considering ICT resilience and third-party arrangements alongside the software’s operational functionality. [2]
Table 3: Leading software type share for the vertical market software market
| Software type | Share in 2026 |
|---|---|
| Banking software | 18.2% |
| Other segments combined | 81.8% |
| Total | 100.0% |
Why do large enterprises lead demand within the enterprise size category?
The large enterprises segment accounts for 58.3% of enterprise size demand in 2026.
Large enterprises lead enterprise size demand because several business units and existing systems must work with sector-specific records and permissions within a coordinated organization. The implementation burden extends beyond the software license to migration, data mapping and dependable interfaces, with exceptions requiring a clear operating response. Computer-aided facility management supports property operations within these wider environments, while industry applications manage their own specialized transactions. The segment’s share reflects the breadth of coordination involved, and buyers need to define integration responsibilities before comparing proposals intended for enterprise-wide use.
- Large enterprises hold 58.3% of enterprise size demand in 2026, reflecting the integration and coordination required across several systems, business units and industry-specific operating workflows.
- Enterprise buyers need a migration plan that preserves usable records and reliable interfaces, because implementation work determines how effectively a sector platform connects with the organization’s continuing operations.
What are the drivers restraints and opportunities in the Vertical Market Software Market?
- Industry-specific transactions and records support software demand because banks, payers and other sector buyers need systems that represent their operating decisions, reducing manual work where the platform handles both routine processing and relevant exceptions.
- Legacy identifiers and inconsistent record formats create a migration burden because conversion must preserve continuing operations, making integration planning and implementation responsibilities essential when buyers compare the cost of competing software licenses.
- Defined regulatory interfaces create focused upgrade opportunities, including the APIs required for impacted payers under the CMS rule, with the commercial task limited to the organizations and data exchanges covered by that requirement. [3]
Industry workflows create specific software requirements
Banks and payers use different records and decisions, making sector software useful where it represents the buyer’s actual process and handles the exceptions encountered during daily operations.
Migration creates a substantial implementation burden
Converting inconsistent legacy identifiers and record formats requires planning to preserve operations, with poorly defined integration work capable of reducing the purchasing advantage of a lower software license price.
Required interfaces create focused upgrade work
CMS’s interoperability rule gives suppliers a defined API task for impacted payers within its stated scope, while an automotive dealer management system illustrates a separate sector workflow whose representative records and exceptions also need demonstration during qualification. [3]
Which country CAGRs are profiled in the Vertical Market Software Market?
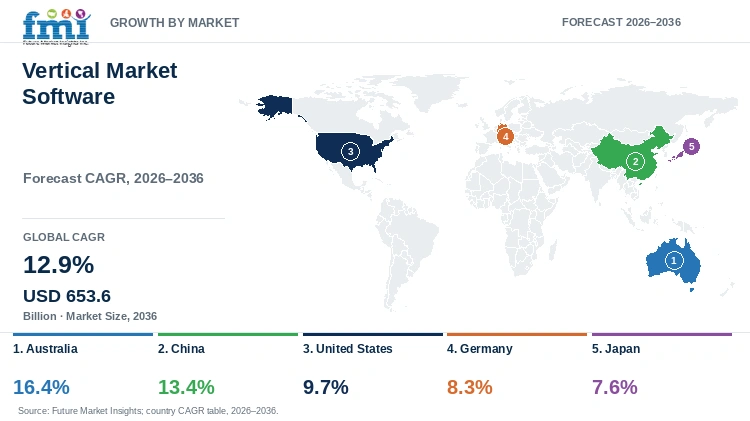
Table 5: Country CAGR comparison for the vertical market software market
| Country | CAGR 2026 to 2036 |
|---|---|
| Australia | 16.4% |
| China | 13.4% |
| United States | 9.7% |
| Germany | 8.3% |
| Japan | 7.6% |
Country-wise Analysis
Australia
Industry systems serving Australian buyers must strictly align with national data sovereignty mandates and sector specific compliance frameworks. In the financial sector, the Australian Prudential Regulation Authority enforces strict standards regarding information security and third party outsourcing, requiring vertical software to demonstrate robust local data handling. Similarly, healthcare software must integrate seamlessly with the Australian Digital Health Agency national infrastructure while complying with the Privacy Act 1988. Because these regulatory environments are highly localized, implementation partners play a critical role in navigating compliance audits and making the license fully operational. The Australian vertical market software market is projected to expand at a 16.4% CAGR from 2026 to 2036, as buyers assess delivery capability alongside sector-specific requirements.
China
Complex enterprise environments in China require careful permission structures and rigorous data mapping to comply with the national Data Security Law and the Personal Information Protection Law. The Cyberspace Administration of China mandates strict security assessments for cross border data transfers and enforces detailed data classification standards across critical industries. Consequently, vertical market software must undergo representative exception testing to ensure that sensitive operational records remain localized and properly governed before any platform expansion. The China vertical market software market is projected to expand at a 13.4% CAGR from 2026 to 2036, with permission design and representative testing forming part of deployment planning.
United States
The Centers for Medicare and Medicaid Services enforce strict interoperability mandates that create defined technical work for impacted United States payers. Regulations such as the Interoperability and Patient Access Final Rule require affected health plans to build and maintain standardized application programming interfaces using Fast Healthcare Interoperability Resources protocols. Software suppliers must design interfaces that meet these precise data exchange rules while simultaneously maintaining compliance with the Health Insurance Portability and Accountability Act. The United States vertical market software market is projected to expand at a 9.7% CAGR from 2026 to 2036, while buyers prioritize compatibility between sector systems and records exchanged with operating partners.
Germany
The European Union Digital Operational Resilience Act provides relevant financial entities in Germany with a comprehensive information and communication technology risk framework. Alongside this, the German Federal Financial Supervisory Authority enforces rigorous supervisory guidelines regarding information technology outsourcing and minimum requirements for risk management. Banking software qualification processes must therefore evaluate operational resilience, incident reporting capabilities, and third party contractual arrangements alongside core functionality. The Germany vertical market software market is projected to expand at an 8.3% CAGR from 2026 to 2036, as buyers connect software qualification with the resilience of daily operations.
Japan
Deeply entrenched legacy systems make record and interface migration a substantial purchasing decision in Japan. The Ministry of Economy, Trade and Industry and the Financial Services Agency actively promote the modernization of core infrastructure to mitigate the severe operational risks associated with aging mainframe environments. Software suppliers must guarantee absolute data continuity and strict adherence to the Act on the Protection of Personal Information during these complex transitions. The Japan vertical market software market is projected to expand at a 7.6% CAGR from 2026 to 2036, as buyers plan record migration around continuity of daily work and responsibility for stored information.
Who are the notable companies in the Vertical Market Software Market?
Notable companies include Temenos; Oracle; SAP; Microsoft; Salesforce
Competitive Benchmarking
Table 6: Competitive positioning for the vertical market software market
| Company or institution | Positioning | Evidence or purchasing distinction |
|---|---|---|
| Temenos | Banking-specific systems | Sector workflow position |
| Oracle | Enterprise and industry applications | Integration across several systems |
| SAP | Enterprise industry workflows | Data and implementation position |
| Microsoft | Industry cloud and enterprise software | Industry cloud architecture combines enterprise applications with industry-specific components. [4] |
| Salesforce | Industry-specific business applications | Offers purpose-built industry applications and workflows for sectors including financial services, healthcare and manufacturing. [5] |
Key Developments in the Vertical Market Software Market
- DORA began applying to relevant EU financial entities in January 2025, establishing an ICT-risk framework that gives banking-software buyers a defined context for evaluating operational resilience and third-party technology arrangements alongside functionality. [2]
- CMS’s Interoperability and Prior Authorization Final Rule defines APIs for impacted payers, giving healthcare software suppliers a specific data-exchange task while retaining the rule’s stated organizational coverage and requirements for the relevant interfaces. [3]
Key Players in the Vertical Market Software Market
Temenos; Oracle; SAP; Microsoft; Salesforce; Infor.
Vertical Market Software Market Report Scope
Table 7: Report coverage for the vertical market software market
| Coverage field | Report scope |
|---|---|
| Market breakdown | Software type; Deployment; Enterprise size; region |
| Quantitative units | USD billion |
| Market definition | Software configured for defined industry processes. General-purpose productivity tools are excluded unless revenue is attributable to the vertical product. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries profiled | Australia; China; United States; Germany; Japan |
| Key companies profiled | Temenos; Oracle; SAP; Microsoft; Salesforce; Infor |
| Forecast period | 2026 to 2036 |
Vertical Market Software Market Research Methodology
Table 8: Research methods for the vertical market software market
| Method | Approach |
|---|---|
| Market coverage | Industry-specific software across banking, healthcare, retail, manufacturing and other sectors, with cloud, on-premises and hybrid deployment considered within the enterprise environment. |
| Public industry evidence | DORA information, CMS interoperability guidance and company application documentation. |
| Operating and technical context | Sector workflows, ICT resilience and defined payer data-exchange requirements. |
| Product and service assessment | Record migration, permission mapping, operational exceptions and interfaces connecting existing systems. |
| Supplier research | Official company disclosures establish documented products, services and participation roles. |
| Country and segment analysis | Examine local operating conditions and the purchasing requirements of each market category. |
| Interpretation of industry indicators | Requirements for relevant EU financial entities from the US payer organizations covered by the CMS rule, reflecting the different operating and regulatory boundaries of each sector. |
Vertical Market Software Market by Segments
By software type
- Banking
- Healthcare
- Retail
- Manufacturing
- Other industry software
By deployment
- Cloud
- On-premises
- Hybrid
By enterprise size
- Large enterprises
- Small and medium enterprises
Vertical Market Software Market by Region
- North America
- USA
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- UK
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Future Market Insights. Published outlook accessed 12 October 2026. Vertical Market Software Market.
- [2] European Union. Regulation (EU) 2022/2554 of the European Parliament and of the Council on digital operational resilience for the financial sector (DORA). Official Journal of the European Union, 27 December 2022. Accessed October 2026.
- [3] Centers for Medicare and Medicaid Services. 2024 final rule accessed October 2026. CMS Interoperability and Prior Authorization Final Rule CMS-0057-F.
- [4] Microsoft. Well-Architected for Industry overview. Accessed 13 October 2026.
- [5] Salesforce. Salesforce for Industries. Accessed 13 October 2026.
This Report Answers
- How big is the vertical market software market in 2026?
- What market value is projected by 2036?
- Which software type segment leads demand?
- Which other commercial categories shape the market?
- Which countries have the fastest profiled growth?
- Which companies and institutions participate in the market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By software type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By software type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By software type, 2026 to 2036
- Banking
- Healthcare
- Retail
- Manufacturing
- Other industry software
- Y-o-Y Growth Trend Analysis By software type, 2021 to 2025
- Absolute $ Opportunity Analysis By software type, 2026 to 2036
- Global Market Analysis and Forecast, By deployment, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By deployment, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By deployment, 2026 to 2036
- Cloud
- On-premises
- Hybrid
- Y-o-Y Growth Trend Analysis By deployment, 2021 to 2025
- Absolute $ Opportunity Analysis By deployment, 2026 to 2036
- Global Market Analysis and Forecast, By enterprise size, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By enterprise size, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By enterprise size, 2026 to 2036
- Large enterprises
- Small and medium enterprises
- Y-o-Y Growth Trend Analysis By enterprise size, 2021 to 2025
- Absolute $ Opportunity Analysis By enterprise size, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By software type
- By deployment
- By enterprise size
- By Country
- Market Attractiveness Analysis
- By Country
- By software type
- By deployment
- By enterprise size
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By software type
- By deployment
- By enterprise size
- By Country
- Market Attractiveness Analysis
- By Country
- By software type
- By deployment
- By enterprise size
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- UK
- Italy
- Spain
- Benelux
- Nordics
- By software type
- By deployment
- By enterprise size
- By Country
- Market Attractiveness Analysis
- By Country
- By software type
- By deployment
- By enterprise size
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By software type
- By deployment
- By enterprise size
- By Country
- Market Attractiveness Analysis
- By Country
- By software type
- By deployment
- By enterprise size
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By software type
- By deployment
- By enterprise size
- By Country
- Market Attractiveness Analysis
- By Country
- By software type
- By deployment
- By enterprise size
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By software type
- By deployment
- By enterprise size
- By Country
- Market Attractiveness Analysis
- By Country
- By software type
- By deployment
- By enterprise size
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC countries
- South Africa
- Türkiye
- Israel
- By software type
- By deployment
- By enterprise size
- By Country
- Market Attractiveness Analysis
- By Country
- By software type
- By deployment
- By enterprise size
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By software type
- By deployment
- By enterprise size
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By software type
- By deployment
- By enterprise size
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By software type
- By deployment
- By enterprise size
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By software type
- By deployment
- By enterprise size
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By software type
- By deployment
- By enterprise size
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By software type
- By deployment
- By enterprise size
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By software type
- By deployment
- By enterprise size
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By software type
- By deployment
- By enterprise size
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By software type
- By deployment
- By enterprise size
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By software type
- By deployment
- By enterprise size
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By software type
- By deployment
- By enterprise size
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By software type
- By deployment
- By enterprise size
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By software type
- By deployment
- By enterprise size
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By software type
- By deployment
- By enterprise size
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By software type
- By deployment
- By enterprise size
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By software type
- By deployment
- By enterprise size
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By software type
- By deployment
- By enterprise size
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By software type
- By deployment
- By enterprise size
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By software type
- By deployment
- By enterprise size
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By software type
- By deployment
- By enterprise size
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By software type
- By deployment
- By enterprise size
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By software type
- By deployment
- By enterprise size
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Temenos
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Oracle
- SAP
- Microsoft
- Salesforce
- Temenos
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by software type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by deployment, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by enterprise size, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by software type, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by deployment, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by enterprise size, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by software type, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by deployment, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by enterprise size, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by software type, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by deployment, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by enterprise size, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by software type, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by deployment, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by enterprise size, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by software type, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by deployment, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by enterprise size, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by software type, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by deployment, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by enterprise size, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by software type, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by deployment, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by enterprise size, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by software type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by software type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by software type
- Figure 6: Global Market Value Share and BPS Analysis by deployment, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by deployment, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by deployment
- Figure 9: Global Market Value Share and BPS Analysis by enterprise size, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by enterprise size, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by enterprise size
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by software type, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by software type, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by software type
- Figure 26: North America Market Value Share and BPS Analysis by deployment, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by deployment, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by deployment
- Figure 29: North America Market Value Share and BPS Analysis by enterprise size, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by enterprise size, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by enterprise size
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by software type, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by software type, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by software type
- Figure 36: Latin America Market Value Share and BPS Analysis by deployment, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by deployment, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by deployment
- Figure 39: Latin America Market Value Share and BPS Analysis by enterprise size, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by enterprise size, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by enterprise size
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by software type, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by software type, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by software type
- Figure 46: Western Europe Market Value Share and BPS Analysis by deployment, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by deployment, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by deployment
- Figure 49: Western Europe Market Value Share and BPS Analysis by enterprise size, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by enterprise size, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by enterprise size
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by software type, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by software type, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by software type
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by deployment, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by deployment, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by deployment
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by enterprise size, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by enterprise size, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by enterprise size
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by software type, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by software type, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by software type
- Figure 66: East Asia Market Value Share and BPS Analysis by deployment, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by deployment, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by deployment
- Figure 69: East Asia Market Value Share and BPS Analysis by enterprise size, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by enterprise size, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by enterprise size
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by software type, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by software type, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by software type
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by deployment, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by deployment, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by deployment
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by enterprise size, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by enterprise size, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by enterprise size
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by software type, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by software type, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by software type
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by deployment, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by deployment, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by deployment
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by enterprise size, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by enterprise size, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by enterprise size
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the vertical market software market in 2026?
FMI estimates market value at USD 194.2 billion in 2026, compared with an estimated USD 172.01 billion in 2025. [1]
What value and CAGR are projected through 2036?
Market value is projected to reach USD 653.6 billion by 2036 at a 12.9% CAGR from 2026 to 2036. [1]
Which software type segment leads in 2026?
Banking software accounts for 18.2% of this category. [1]
What is the report segmentation?
Software type; Deployment; Enterprise size, and region.
Which profiled market records the highest CAGR?
Australia has the highest profiled rate at 16.4% from 2026 to 2036. [1]
Who are the key participants?
Temenos; Oracle; SAP; Microsoft; Salesforce; Infor.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
