

- Market Size (2026)
- USD 312.0 Mn
- Forecast (2036)
- USD 831.6 Mn
- CAGR (2026 to 2036)
- 10.3%
How big is Active Ideal Diode Controllers Market in 2026?
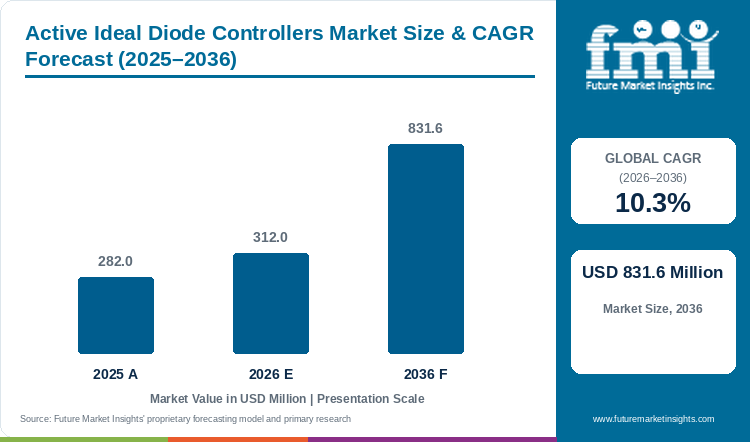
Active ideal diode controllers industry valuation moved beyond USD 282.0 million in 2025 to register USD 312.0 million in 2026, and is slated to post USD 831.6 million in 2036 at a CAGR of 10.3%.
Efforts to cut wasted heat inside sealed automotive computers and high-power data center racks are prompting hardware engineers to replace traditional rectifier diodes with active ideal diode controller chips. Technical analysis published by SAE International in June 2025 on 48-volt vehicle electrical systems shows that shifting higher-power automotive loads onto 48-volt buses requires low-loss reverse-battery protection to eliminate bulky aluminum heatsinks [1]. Sealed vehicle computers and high-current server racks cannot tolerate the heat of passive diodes. Because pairing a charge-pump controller with an external transistor cuts forward voltage drop by more than 90%, the Floating Charge-Pump Controller segment captures 64.5% of topology demand in 2026 and grows faster than general power management integrated circuits. Industry valuation for the active ideal diode controllers market moved beyond USD 282.0 million in 2025 to register USD 312.0 million in 2026, and FMI anticipates USD 831.6 million in 2036 via a 10.3% CAGR, adding USD 519.6 million over the ten-year period. Still, the extra component cost of pairing each controller with a rugged external transistor able to survive high-voltage battery spikes slows adoption in budget passenger cars.
Key Market Trends & Insights
- By gate drive topology: The Floating Charge-Pump Controller category captures 64.5% in 2026 because linear gate-servo regulation eliminates reverse shoot-through during 100 kHz AC alternator ripple.
- By voltage rating: 65V through 100V Automotive commands 59.2% in 2026 as 12V load-dump clamps and 48V mild-hybrid and zonal buses require wide transient standoff margins.
- By package type: Wettable-Flank QFN concentrates 56.4% in 2026 because automotive Tier-1 SMT lines mandate automated optical inspection of solder fillets.
- By end-use system: Automotive Zonal & ADAS generates 54.6% in 2026 whereas 48V AI Rack OR-ing climbs fastest at a CAGR of 11.2% inside 1MW server power shelves.
- By sales channel: Direct OEM & Tier-1 Supply secures 67.4% in 2026 under multi-year AEC-Q100 ASIL-D wafer allocation contracts.
Regional Highlights
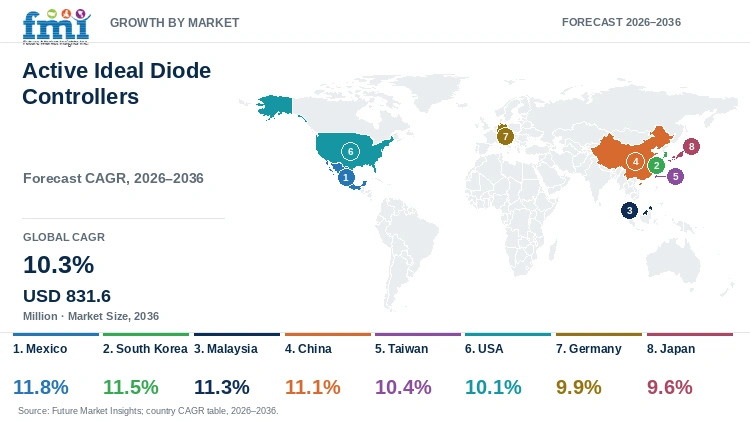
- Nearshore zonal & PSU corridors: Mexico heads geographic growth at a CAGR of 11.8% through 2036 ahead of South Korea at 11.5% and Malaysia at 11.3% as zonal ECU and server PSU assembly scales.
- Major EV & server ecosystems: China posts a CAGR of 11.1% while Taiwan achieves 10.4% and the USA logs 10.1% compared with Germany at 9.9%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Active Ideal Diode Controllers Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 282.0 million |
| Estimated Market Size in 2026 | USD 312.0 million |
| Projected Market Size by 2036 | USD 831.6 million |
| CAGR, 2026 to 2036 | 10.3% |
| Added Valuation, 2026 to 2036 | USD 519.6 million |
Deletion of extruded aluminum heatsinks inside sealed automotive ADAS enclosures and prevention of 600A busbar backfeed inside 1MW AI server racks have turned active ideal diode controllers into a high-growth power category. Substitution of passive Schottky rectifier diodes with a linear-servo charge-pump controller and external N-MOSFET cuts forward voltage drop from 500 mV to 20 mV across 20A to 200A rails. Texas Instruments' July 2026 second-quarter report documenting USD 5,463.0 million in quarterly sales (+23.0% year-on-year) demonstrated sustained industrial and automotive orders for 300mm BCD power-path controllers [2]. Accordingly, global controller billings are projected to grow from a 2026 base of USD 312.0 million toward a 2036 figure of USD 831.6 million at a CAGR of 10.3%.
Zonal ECU & Server Power Shelf Socket Sizing
Table 2: Global Active Ideal Diode Controller Unit Shipments and Blended ASP (million units and USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Annual Ideal Diode Controller IC Shipments (Million Units) | 306.5 | 331.9 | 792.0 |
| Blended Average Selling Price (USD per Controller IC) | USD 0.92 | USD 0.94 | USD 1.05 |
| AEC-Q100 65V to 100V Dual-Channel Controller ASP (USD) | USD 1.48 | USD 1.55 | USD 1.78 |
| xEV Zonal ECU & ORv3 Power Shelf Attach Rate (%) | 62.0% | 69.5% | 88.5% |
Operational note: Socket shipments exclude the companion external N-channel power MOSFET (USD 0.45 to USD 1.80 BOM) and count 6 to 14 ideal diode controller ICs per zonal vehicle and 6 to 12 controllers per 48V ORv3 power shelf.
Controller average selling prices climb from USD 0.92 for 2025 toward USD 1.05 in 2036 as 65V through 100V automotive ASIL-D devices scale across centralized vehicle power boxes and data center battery backup systems. Dual-MOSFET back-to-back load-disconnect controllers command 2.2x higher ASPs by combining reverse-polarity blocking with active inrush slew control.
Thermal Dissipation Savings & Controller Die Economics
Table 3: Thermal Loss Reduction and Reverse Turn-Off Performance vs. Passive Schottky Diodes (millivolts and watts), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Forward Conduction Drop at 50A Continuous Load (mV) | 48 mV | 44 mV | 32 mV |
| Conduction Power Dissipation at 50A vs 25.0W Schottky (Watts) | 2.40 W | 2.20 W | 1.60 W |
| Reverse-Current Comparator Turn-Off Response (Microseconds) | 0.65 µs | 0.50 µs | 0.30 µs |
| Controller Sockets per Zonal Software-Defined Vehicle (Units) | 6.5 | 8.2 | 14.0 |
Table 4: Manufacturing Cost Structure and High-Voltage BCD Wafer Economics for Active Ideal Diode Controllers (USD million and percentage share), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 312.0 million | 2026 global controller IC valuation baseline |
| High-Voltage 65V to 100V BCD Controller Die | 38.5% of unit cost | Floating charge-pump & reverse-battery wells |
| Automotive Wettable-Flank QFN / SOT-23 Package | 17.5% of unit cost | AOI-inspectable automotive surface-mount package |
| AEC-Q100 Tri-Temp Probe & ISO 16750-2 Validation | 44.0% of unit cost | Grade-0/1 wafer probe, HV isolation & ASIL-D IP |
High-standoff 65V through 100V BCD wafer processing and 3-temperature AEC-Q100 probe testing represent 53.5% of manufacturing cost, positioning vertically integrated 300mm fabs ahead of fabless challengers. Each controller is co-qualified with companion discrete power MOSFET transistors to guarantee zero reverse shoot-through during 250-nanosecond short-circuit turn-off.
Analyst Perspective
"Above 15 amps, passive Schottky diodes turn into board heaters; an active ideal diode controller driving a sub-milliohm MOSFET removes 22 watts of heat from a sealed zonal ECU and pays for itself in deleted aluminum heatsink mass alone."
- Sudip Saha, Co-founder, FMI
How is the active ideal diode controllers market segmented?
The active ideal diode controllers market is segmented by gate drive topology, voltage rating, package type, end-use system, and sales channel. In 2026, the Floating Charge-Pump Controller segment stands at 64.5% and 65V to 100V Automotive reaches 59.2%, whereas Wettable-Flank QFN holds 56.4% and Automotive Zonal & ADAS accounts for 54.6%.
By gate drive topology: the Floating Charge-Pump Controller, Back-to-Back Load-Disconnect, Monolithic Smart Bypass, and Dual-Channel OR-ing Controller.
By voltage rating: 65V through 100V Automotive, Under-40V Server & Industrial, and Over-100V High-Voltage.
By package type: Wettable-Flank QFN, Compact SOT-23 & WSON, TO-263 Solar Bypass, and Leaded MSOP & TSSOP.
By end-use system: Automotive Zonal & ADAS, 48V AI Rack OR-ing, Solar Smart Junction Boxes, and Industrial Microgrid Rectifiers.
By sales channel: Direct OEM & Tier-1 Supply, Authorized Component Fulfillment, Zonal ECU Contract Manufacturers, and Power Module Integrators.
Why does Floating Charge-Pump Controller lead the gate drive topology category?
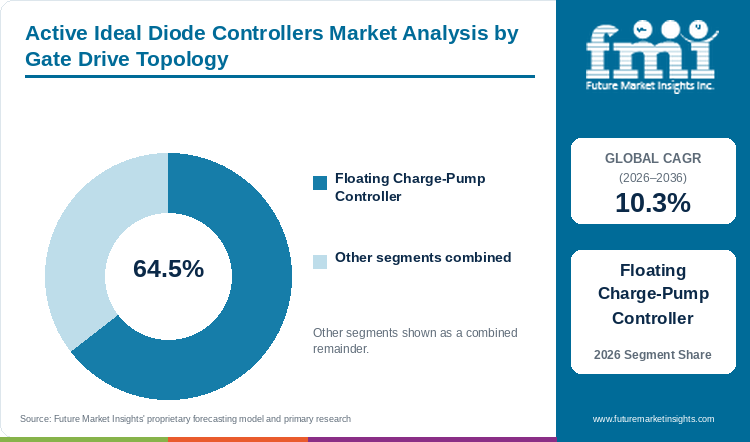
The Floating Charge-Pump Controller category heads gate drive topology volume by securing 64.5% during 2026 (reaching USD 201.2 million) and progressing at a CAGR of 10.7% through 2036.
Table 5: Gate Drive Topology Share for the Active Ideal Diode Controllers Market (percentage share), 2026
| Gate Drive Topology | Share (2026) |
|---|---|
| Floating Charge-Pump Controller | 64.5% |
| Other Segments Combined | 35.5%* |
| Total | 100.0% |
*Note: Back-to-Back Load-Disconnect and Monolithic Smart Bypass with Dual-Channel OR-ing Controller complete 100.0% of 2026 demand.
Table 6: Gate Drive Topology Leadership and Market Growth for the Active Ideal Diode Controllers Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 10.3% |
| Leading Segment | Floating Charge-Pump Controller |
An internal floating charge pump that regulates forward anode-to-cathode drop at 15 mV to 20 mV across a single external N-channel MOSFET keeps the gate partially biased under light loads so the transistor turns off in under 300 nanoseconds upon reverse fault detection. Unlike comparator-only high-speed gate driver ICs that chatter during 100 kHz alternator ripple, linear gate-servo controllers pass ISO 16750-2 superimposed AC tests with zero reverse shoot-through.
- The Floating Charge-Pump Controller segment holds 64.5% of 2026 gate drive topology demand (reaching USD 201.2 million) and progresses at a CAGR of 10.7% through 2036.
- Product releases from Vishay Intertechnology in May 2025 introduced the SiEH4800EW 80V TrenchFET Gen IV MOSFET in a bond-wireless PowerPAK 8x8SW package with 0.88 milliohm RDS(on) to pair with active charge-pump OR-ing controllers up to 608A [3].
Why do 65V to 100V Automotive controllers define the largest voltage rating segment?
Automotive 65V through 100V controllers represent 59.2% within 2026 voltage rating demand (reaching USD 184.7 million) while growing at a CAGR of 11.0% through 2036.
Even in a nominal 12V passenger car, unfiltered inductive kicks and central load-dump clamps reach 35V to 58V, while 48V mild-hybrid and zonal electric buses require 70V to 100V anode-to-cathode breakdown ratings and -65V reverse-battery immunity. High-voltage BCD charge pumps protect downstream automotive integrated power modules across dual 12V/48V vehicle trunks.
- 65V through 100V Automotive represents 59.2% within 2026 voltage rating demand (reaching USD 184.7 million) and grows at a CAGR of 11.0% through 2036.
- June 2026 automotive product releases from ROHM Co., Ltd. introduced the AG16xFNxx series 80V and 120A copper-clip AEC-Q101 MOSFETs featuring 3.2 milliohm maximum RDS(on) to pair with 65V through 100V ideal diode controllers in 48V systems [4].
What keeps Wettable-Flank QFN ahead by package type?
Wettable-Flank QFN packages command 56.4% of 2026 package type shipments (totaling USD 176.0 million) and climb at a CAGR of 10.6% through 2036.
Automotive Tier-1 surface-mount assembly lines require step-cut wettable-flank QFN packages so automated optical inspection (AOI) cameras can verify solder meniscus formation on every pin without expensive X-ray screening. Thermally improved wettable-flank pads also dissipate charge-pump gate-drive heat beside power discrete semiconductors and modules inside sealed ADAS domain controllers.
- Wettable-Flank QFN commands 56.4% of 2026 package type shipments (totaling USD 176.0 million), outpacing Compact SOT-23 & WSON and TO-263 Solar Bypass.
- October 2026 quarterly financial statements from Nexperia recorded Q3 2026 sales of USD 389.0 million (+9.3% sequentially) across its AEC-Q100 wettable-flank power protection and clip-bond package factories [5].
Why does Automotive Zonal & ADAS lead the end-use system category?
Automotive Zonal & ADAS systems capture 54.6% within 2026 end-use system valuation (equaling USD 170.4 million) and expand at a CAGR of 10.9% through 2036.
Software-defined vehicles replace centralized relay boxes with four to six zonal gateways and electric power-steering ECUs, multiplying reverse-polarity and dual-battery OR-ing inputs to 8 to 16 controller sockets per vehicle. Meanwhile, 48V AI Rack OR-ing (28.9% share) logs the fastest 11.2% yearly expansion across Open Rack v3 power shelves that feed high-density server compute blades.
- Automotive Zonal & ADAS captures 54.6% within 2026 end-use system valuation (equaling USD 170.4 million) and expands at a CAGR of 10.9% through 2036.
- Twenty-two summit tracks announced by the Open Compute Project Foundation during September 2026 covered 48V Open Rack v3 power shelves and high-current busbar protection [6].
What gives Direct OEM & Tier-1 Supply the leading position in sales channel?
Long-term automotive and hyperscale supply contracts give Direct OEM & Tier-1 Supply 67.4% of 2026 channel demand (USD 210.3 million) at a CAGR of 10.6% through 2036.
Automotive Tier-1 zonal module builders and hyperscale ORv3 server power-shelf manufacturers procure 67.4% of active ideal diode controllers under direct multi-year supply contracts with 300mm high-voltage analog producers. Direct factory partnership locks in ISO 26262 ASIL-D safety documentation and companion wide-SOA MOSFET reference validation.
- Direct OEM & Tier-1 Supply secures 67.4% of 2026 sales channel billings (reaching USD 210.3 million), while authorized component fulfillment and zonal contract assemblers with module integrators represent 32.6%.
- Audited FY2025 annual reports filed with the SEC by Diodes Incorporated during February 2026 highlighted automotive and industrial demand across its AP74700Q AEC-Q100 65V ideal diode controller portfolio [7].
What are the drivers, restraints, and opportunities in the active ideal diode controllers market?
Market expansion is driven by 91.2% conduction heat reduction in sealed automotive ECUs and 48V ORv3 AI server busbars, restrained by external wide-SOA MOSFET BOM costs under clamped load dump, and accelerated by smart solar PV bypass boxes.
- Driver: 91.2% conduction heat reduction at 50A loads inside sealed automotive ECUs and 48V ORv3 AI server busbars compels engineers to replace passive Schottky diodes with active controllers.
- Restraint: High bill-of-materials cost of companion wide-SOA external N-channel MOSFETs required to survive clamped inductive load-dump transients restrains economy-car adoption.
- Opportunity: Monolithic and co-packaged smart solar PV junction-box bypass diodes expand at an 11.0% CAGR to eliminate partial-shading thermal runaway in 700W bifacial panels.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Consolidation of centralized vehicle fuse-and-relay boxes into zonal body control units and high-compute ADAS domain controllers multiplies high-current battery input stages across passenger cars. Onsemi confirmed this commercial shift in August 2026 when second-quarter sales reached USD 1,604.0 million on zonal architecture wins for the Rivian R2 platform and doubling AI data center power billings [8]. Every ECU tied to 12V/48V vehicle trunks and automotive battery management systems must survive reverse-polarity jump-starts (-14V to -65V) and ISO 16750-2 superimposed AC ripple up to 6V peak-to-peak at 50 Hz to 200 kHz.
Risk Assessment of the Active Ideal Diode Controllers Market: Operational and Engineering Friction
The high bill-of-materials cost of wide Safe Operating Area (SOA) external N-channel MOSFETs and transient voltage suppression clamps during inductive load-dump events represents the primary restraint on active ideal diode controller adoption. Peer-reviewed power converter analysis published in Scientific Reports in May 2025 confirmed that high-voltage transient standoff and non-ideal conduction losses directly govern semiconductor switch cost across high-gain power stages [9]. When a back-to-back load-disconnect controller opens an inductive 48V automotive feed under a 120A short-circuit fault, the companion MOSFET must absorb clamped avalanche energy in linear mode without thermal breakdown ahead of standalone DC-DC power converters.
Commercial Opportunity Analysis: Architecture Differentiation and Value-Add Formats
Power semiconductor suppliers open substantial volume upside by extending active ideal diode controllers into smart solar photovoltaic junction boxes and 48V telecom microgrids with bundled controller-plus-MOSFET reference pairs. Deep-learning fault classification research in solar photovoltaic systems published in July 2026 documented module-level protection gaps under partial shading that accelerate smart bypass diode adoption [10]. When partial shading from tree limbs or soiling activates one bypass substring on a 700W bifacial solar module paired with battery management systems, replacing passive Schottky bypass diodes (0.55V drop) with smart ideal bypass diodes (0.04V drop) prevents junction-box potting degradation.
Active Ideal Diode Controllers Market by Country (2026 to 2036)
Nearshore automotive electronics and server power-shelf factories position Mexico as the fastest-growing country for active ideal diode controllers at a CAGR of 11.8% through 2036, whereas Japan records a CAGR of 9.6%. Global demand tracks nearshore automotive zonal ECU and 48V AI server power-shelf assembly in North America and Asia and 48V vehicle architecture and solar PV engineering in Europe.
Table 7: Country CAGR and Primary Growth Levers for the Active Ideal Diode Controllers Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Mexico | 11.8% | Automotive Zonal ECUs & 48V AI Server Power Shelf Assembly |
| South Korea | 11.5% | 48V xEV Zonal Body/ADAS & High-Density Server PSUs |
| Malaysia | 11.3% | AEC-Q100 Wettable-Flank Packaging & Solar PV Junction Boxes |
| China | 11.1% | EV Zonal E/E Architectures, 48V Cloud Racks & Solar PV |
| Taiwan | 10.4% | Hyperscale 48V ORv3 AI Server Power Shelf ODM Manufacturing |
| USA | 10.1% | Hyperscale 48V AI Rack Shelves & Domestic EV Zonal Design-In |
| Germany | 9.9% | Premium OEM 12V/48V Zonal & ISO 16750-2 Qualification |
| Japan | 9.6% | HEV/BEV Zero-Defect Power Control & Industrial Robotics |
Source: Future Market Insights analysis
Mexico Active Ideal Diode Controllers Market Outlook (2026 to 2036)
Nearshore electronics manufacturing campuses across Monterrey and Ciudad Juárez operate both automotive zonal body-control module lines and 48V artificial intelligence server power-shelf assembly corridors for North American customers. Diodes Incorporated's May 2026 first-quarter financial release highlighted expanding automotive and industrial protection IC shipments into North American Tier-1 and server power-supply assembly plants [11]. Under regional rules of origin, Tier-1 mobility plants in Nuevo León and server rectifier ODMs in Guadalajara propel Mexico at a world-leading CAGR of 11.8% across 2026 to 2036. High-volume dual-voltage power distribution module exports sustain controller procurement, although customs delays on Asian wafer imports and industrial substation grid bottlenecks moderate near-term surface-mount capacity expansion.
Key takeaway: In Mexico, nearshore automotive zonal ECU plants in Monterrey and 48V AI server PSU factories in Juárez drive top-ranked demand.
South Korea Active Ideal Diode Controllers Market Outlook (2026 to 2036)
What distinguishes South Korea from other Asian markets is its rapid standardization of 48V mild-hybrid and zonal electrical architectures across domestic export electric vehicle platforms in Ulsan and Gyeonggi-do. Full-year financial results released by Monolithic Power Systems in February 2026 documented a 43.1% jump in FY2025 Automotive revenue to USD 592.5 million and a 46.0% surge in Storage and Computing power solutions [12]. Controller shipments across South Korea climb at a CAGR of 11.5% from 2026 to 2036 across automotive reverse-polarity inputs and active battery disconnect units. Domestic Tier-1 automotive groups qualify 65V and 100V back-to-back load-disconnect controllers ahead of ADAS domain computers to pass ISO 16750-2 ripple tests, though export tariff uncertainty tempers quarterly build schedules.
Key takeaway: In South Korea, rapid adoption of 48V zonal vehicle architectures and ADAS domain controllers sustains 11.5% annual growth.
Malaysia Active Ideal Diode Controllers Market Outlook (2026 to 2036)
Automotive semiconductor assembly and test plants in Penang and Kulim package a large share of global AEC-Q100 wettable-flank ideal diode controllers and copper-clip power MOSFETs shipped to Tier-1 mobility accounts. Photovoltaic hardware-in-the-loop emulation research published in MethodsX in March 2026 demonstrated that low-drop active bypass switching prevents thermal hot-spotting across shaded solar substrings, supporting smart junction-box manufacturing in Kulim and Cyberjaya [13]. Active ideal diode controller demand across Malaysia registers a CAGR of 11.3% from 2026 through 2036 across automotive and solar accounts. Backend wafer-sort and wettable-flank QFN assembly expansions reinforce export throughput, although intense competition for skilled test technicians in Penang raises cleanroom packaging labor costs.
Key takeaway: In Malaysia, Penang and Kulim combine automotive AEC-Q100 power IC packaging with solar PV smart junction-box manufacturing.
China Active Ideal Diode Controllers Market Outlook (2026 to 2036)
Software-defined electric vehicle manufacturers in Shenzhen and Shanghai lead global unit production of centralized zonal electrical architectures that embed 10 to 16 active ideal diode controllers per passenger car. High-efficiency power conversion research published in Nature Communications in August 2026 highlighted how low-loss active rectification stages minimize conduction heat across dense power supplies manufactured in Dongguan and Suzhou [14]. Controller procurement across China posts a CAGR of 11.1% through 2036 as domestic cloud data centers and electric mobility platforms scale 48V power shelves and zonal gateways. Domestic production of 3.3 kW and 5.5 kW server rectifiers and bifacial photovoltaic junction boxes sustains massive unit volume, even as solar module price competition pressures smart bypass margins.
Key takeaway: In China, software-defined EV zonal gateways and solar junction-box factories anchor scale.
Taiwan Active Ideal Diode Controllers Market Outlook (2026 to 2036)
Power supply original design manufacturers in New Taipei and Taoyuan produce over 70% of world 48V Open Compute Project ORv3 AI server power shelves and battery backup units. August 2026 annual financial statements from Alpha and Omega Semiconductor Limited posting USD 678.9 million for fiscal 2026 reflected rising AI server and data center power protection deliveries to Taiwanese ODMs [15]. Every 18 kW to 33 kW power shelf manufactured for hyperscale AI clusters embeds six to twelve active ideal diode OR-ing controllers, propelling Taiwan at a CAGR of 10.4% through 2036. Domestic power supply ODMs also integrate 65V charge-pump controllers across industrial DIN-rail rectifiers, though tight 300mm BCD wafer allocations during peak AI rack build cycles constrain spot supply.
Key takeaway: In Taiwan, hyperscale 48V ORv3 AI server power-shelf ODM assembly anchors a 10.4% CAGR through 2036.
USA Active Ideal Diode Controllers Market Outlook (2026 to 2036)
Open Compute Project 1MW AI server racks deployed across Virginia and Texas require high-speed active OR-ing controllers across every 48V rectifier and lithium-ion battery backup shelf to prevent busbar collapse during short-circuit faults. November 2025 product launches by ROHM Co., Ltd. unveiling compact 5x6mm wide-SOA hot-swap and OR-ing MOSFETs for AI servers showed how companion power stages pair with active ideal diode controllers inside cloud racks [16]. Hyperscale 48V AI data center buildouts and domestic electric vehicle zonal body-controller engineering propel the USA at a CAGR of 10.1% from 2026 through 2036. Domestic design-ins across electric pickup and SUV zonal platforms reinforce high-ASP controller demand, though grid interconnect queue delays on utility solar projects moderate photovoltaic bypass orders.
Key takeaway: In the USA, 48V ORv3 AI rack power shelves and domestic EV zonal platforms drive high-ASP controller demand.
Germany Active Ideal Diode Controllers Market Outlook (2026 to 2036)
Automakers and Tier-1 system integrators in Munich and Stuttgart authored the foundational LV124 and ISO 16750-2 electrical standards that govern 12V and 48V reverse-polarity and AC ripple immunity across global vehicle platforms. Automotive architecture disclosures from STMicroelectronics in September 2025 detailed how European software-defined vehicles replace centralized relay boxes with smart zonal power distribution and active reverse-battery protection [17]. Controller shipments in Germany climb at a CAGR of 9.9% through 2036 due to domestic premium vehicle transitions toward 48V mild-hybrid and zonal body control units. Rooftop solar installations across Bavaria also adopt monolithic smart bypass diodes to curb partial-shading energy losses, although slow domestic EV unit production growth moderates near-term automotive assembly volume.
Key takeaway: In Germany, LV148 and ISO 16750-2 automotive 48V qualification standards and commercial PV safety rules sustain high-value procurement.
Japan Active Ideal Diode Controllers Market Outlook (2026 to 2036)
Hybrid-electric and battery-electric vehicle OEMs in Toyota City and Yokohama enforce stringent AEC-Q100 and AEC-Q101 zero-defect reliability rules across 12V auxiliary and 48V electric turbocharger and active stabilizer bars. ROHM Co., Ltd. joined the October 2026 NVIDIA MGX partner ceremony at the 2026 OCP Global Summit to present Japanese 48V server and AI rack power-stage adoption with automotive protection lines [18]. Active ideal diode controller billings in Japan grow at a CAGR of 9.6% through 2036 as industrial robotics and semiconductor tool builders in Osaka and Kyoto embed dual-input 24V/48V servo power rails. Domestic wide-SOA MOSFET and controller innovation supports high-reliability design-ins, though land constraints limit utility-scale ground-mounted photovoltaic bypass module demand across domestic solar installations.
Key takeaway: In Japan, zero-defect 48V automotive protection requirements and domestic wide-SOA MOSFET innovation support steady 9.6% growth.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the active ideal diode controllers market?
Analog Devices, Inc.; Texas Instruments Incorporated; Infineon Technologies AG; Nexperia B.V.; STMicroelectronics N.V.; onsemi; ROHM Co., Ltd.; and Monolithic Power Systems, Inc. are the notable companies in the active ideal diode controllers market.
High-voltage automotive analog IC producers and vertically integrated MOSFET-plus-controller suppliers anchor the active ideal diode controllers market, with the top five companies capturing nearly four-fifths of 2026 global billings across automotive zonal and server OR-ing accounts.
- Tier 1 High-Voltage Linear-Servo Controller Leaders (50.0% Category Share): Texas Instruments holding 27.5% and Analog Devices holding 22.5% dominate automotive 65V through 100V charge-pump controllers with ISO 16750-2 AC ripple immunity.
- Tier 2 Vertically Integrated Controller + MOSFET Suppliers (29.5% Combined Share): Nexperia (11.5%) and onsemi (9.5%) with Diodes Incorporated (8.5%) bundle ideal diode controllers with proprietary copper-clip 40V to 100V MOSFETs.
- Tier 3 Automotive Wide-SOA & Industrial Specialists (20.5% Combined Share): STMicroelectronics and ROHM with Monolithic Power Systems and Infineon supply companion wide-SOA MOSFETs and smart 48V protection controllers.
Competitive Benchmarking: Active Ideal Diode Controllers Market
Table 8: Competitive Benchmarking for the Active Ideal Diode Controllers Market (qualitative capability ratings), 2026
| Company | 65V to 100V Linear-Servo IP | 48V Zonal & ORv3 Design-In | Companion Wide-SOA FETs | Geographic Reach |
|---|---|---|---|---|
| Analog Devices, Inc. | High | High | Medium | High |
| Texas Instruments Inc. | High | High | Medium | High |
| Infineon Technologies AG | High | High | High | High |
| Nexperia B.V. | Medium | High | High | High |
| STMicroelectronics N.V. | Medium | High | High | High |
| onsemi | High | High | High | High |
| ROHM Co., Ltd. | Medium | Medium | High | High |
| Monolithic Power Systems | High | High | Medium | High |
Scoring basis: Supplier capability grades and share estimates draw upon audited 2025 and 2026 automotive and industrial analog filings plus ORv3 48V power-shelf approved vendor lists.
Key Developments in the Active Ideal Diode Controllers Market
- ROHM Co., Ltd. launched the AEC-Q101 100V and 120A RS4P063BPHZG MOSFET in an HPLF5060 package in September 2026 with 5x higher safe operating area tolerance for automotive battery cutoff and ideal-diode load-disconnect circuits [19].
- Infineon Technologies AG expanded its Power PROFET + 24/48V smart power distribution switch family in March 2025 to replace mechanical relays and passive rectifiers across 48V automotive zonal architectures [20].
- During August 2026, Analog Devices, Inc. disclosed USD 533.5 million in third-quarter fiscal 2026 research and development outlays supporting high-voltage LTC and LT ideal diode controllers [21].
Key Players in the Active Ideal Diode Controllers Market
Tier 1 Automotive & Hyperscale Ideal Diode Controller Leaders
- Analog Devices, Inc.
- Texas Instruments Incorporated
- Infineon Technologies AG
Tier 2 Vertically Integrated Controller & Companion MOSFET Leaders
- Nexperia B.V.
- STMicroelectronics N.V.
- onsemi
Tier 3 Wide-SOA Automotive & AI Server Protection Specialists
- ROHM Co., Ltd.
- Monolithic Power Systems, Inc.
Active Ideal Diode Controllers Market - Report Scope
Table 9: Report Scope for the Active Ideal Diode Controllers Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Gate Drive Topology; Voltage Rating; Package Type; End-Use System; Sales Channel |
| Quantitative Units | USD Million |
| Market Definition | Includes mixed-signal active ideal diode controller ICs (floating charge-pump and back-to-back load-disconnect controllers) and monolithic smart solar PV bypass diodes. Category Scope Note: Excludes standalone discrete external power MOSFET revenue, monolithic low-current dual-input power multiplexers, and passive Schottky diodes. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Mexico, South Korea, Malaysia, China, Taiwan, USA, Germany, Japan, and additional countries in the full report |
| Key Companies Covered | Analog Devices, Inc.; Texas Instruments Incorporated; Infineon Technologies AG; Nexperia B.V.; STMicroelectronics N.V.; onsemi; ROHM Co., Ltd.; Monolithic Power Systems, Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down parent PMIC market cap checks and bottom-up zonal ECU, 48V server shelf, and solar PV socket triangulation. |
Active Ideal Diode Controllers Market - Research Methodology
Table 10: Research Methodology for the Active Ideal Diode Controllers Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with automotive Tier-1 zonal power-net architects, hyperscale 48V ORv3 PSU engineers, solar junction-box designers, and 300mm BCD analog product directors to validate socket counts and ASPs. |
| Secondary Research | Analysis of SEC Form 10-K/10-Q filings (Analog Devices, TI, onsemi, MPS, Diodes, Vishay), ISO 16750-2 and LV124/LV148 automotive standards, SAE 48V reports, and OCP ORv3 specifications. |
| Market Sizing and Forecasting | Top-down parent Power Management Integrated Circuit Market (USD 35,300.0 million in 2026; active ideal diode controller share = 0.88%) models reconciled against bottom-up zonal vehicle, 48V AI rack, and smart PV module builds from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight nearshore automotive zonal ECU assembly, 48V server power-shelf ODM production, AEC-Q100 OSAT packaging, and utility solar installations across eight national markets. |
| Operational Benchmark Traceability | Unit shipment, ASP, conduction loss (2.2W vs 25.0W at 50A), and BCD wafer cost indicators in Tables 2, 3, and 4 trace to Vishay and ROHM MOSFET data, SAE 48V benchmarks, and ADI/TI disclosures. |
| Data Triangulation and Validation | Demand estimates isolate controller IC and monolithic smart bypass billings without double counting standalone external power MOSFETs or low-current power multiplexers. |
Active Ideal Diode Controllers Market by Segments
Active Ideal Diode Controllers Market segmented by Gate Drive Topology:
- Floating Charge-Pump Controller
- Back-to-Back Load-Disconnect
- Monolithic Smart Bypass
- Dual-Channel OR-ing Controller
Active Ideal Diode Controllers Market segmented by Voltage Rating:
- 65V to 100V Automotive
- Under-40V Server & Industrial
- Over-100V High-Voltage
Active Ideal Diode Controllers Market segmented by Package Type:
- Wettable-Flank QFN
- Compact SOT-23 & WSON
- TO-263 Solar Bypass
- Leaded MSOP & TSSOP
Active Ideal Diode Controllers Market segmented by End-Use System:
- Automotive Zonal & ADAS
- 48V AI Rack OR-ing
- Solar Smart Junction Boxes
- Industrial Microgrid Rectifiers
Active Ideal Diode Controllers Market segmented by Sales Channel:
- Direct OEM & Tier-1 Supply
- Authorized Electronics Distribution
- Contract EMS & ODM
- Power Module Integrators
Active Ideal Diode Controllers Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Green, G. (2025, June 12). SAE-MA-07610: 48V is coming, and not just for EVs. SAE International Automotive Engineering.
- [2] Texas Instruments Incorporated. (2026, July 22). TI reports second quarter 2026 financial results and shareholder returns. Texas Instruments Newsroom.
- [3] Vishay Intertechnology, Inc. (2025, May 21). Vishay Unveils High-Efficiency 80 V MOSFET in Compact PowerPAK® 8x8SW Package (SiEH4800EW). Vishay Company Press Releases.
- [4] ROHM Co., Ltd. (2026, June 17). ROHM Launches AG16xFNxx Series MOSFETs for Automotive 48V Power Supply Systems. ROHM Newsroom.
- [5] Nexperia B.V. (2026, October 27). Nexperia builds momentum with continued growth in Q3 2026. Nexperia Newsroom.
- [6] Open Compute Project Foundation. (2026, September 30). Explore 22 Tracks at the 2026 OCP Global Summit. Open Compute Project News.
- [7] Diodes Incorporated. (2026, February 12). Form 10-K Annual Report for the Fiscal Year Ended December 31, 2025. U.S. Securities and Exchange Commission EDGAR.
- [8] onsemi. (2026, August 3). onsemi Reports Second Quarter 2026 Results. onsemi Newsroom.
- [9] Hasan Babayi Nozadian, M., et al. (2025, May 12). Impact of the non-ideal condition in the analysis of high voltage gain switched impedance inverter with cost perspectives. Scientific Reports, 15(1), 16444 (PMC12069717).
- [10] Vignesh, V., Senthil Kumar, R., & Suganeshwari, G. (2026, July 23). Hybrid fuzzy C-means and deep learning framework for intelligent fault classification in solar PV systems. Frontiers in Artificial Intelligence, 9, 1881404 (PMC13442526).
- [11] Diodes Incorporated. (2026, May 7). Diodes Incorporated Reports First Quarter 2026 Financial Results. Diodes Investor Relations.
- [12] Monolithic Power Systems, Inc. (2026, February 5). Monolithic Power Systems Announces Results for the Fourth Quarter and Year Ended December 31, 2025 and an Increase in Quarterly Cash Dividend. Monolithic Power Systems Investor Relations.
- [13] Nguyen, H. P., & Nguyen, T. T. (2026, March 10). Design methodology for a photovoltaic emulator based on power hardware-in-the-loop with Opal-RT simulator. MethodsX, 17, 104119 (PMC13571559).
- [14] Ko, J. Y., et al. (2026, August 7). A hybrid piezoelectric resonator-based DC-DC converter. Nature Communications, 17(1), 4054 (PMC13139477).
- [15] Alpha and Omega Semiconductor Limited. (2026, August 12). Alpha and Omega Semiconductor Reports Financial Results for Fiscal Fourth Quarter and Fiscal Year Ended June 30, 2026. AOS Investor Relations.
- [16] ROHM Co., Ltd. (2025, November 25). ROHM launches wide SOA MOSFET for AI servers in compact 5x6mm package. ROHM Newsroom.
- [17] STMicroelectronics N.V. (2025, September 19). STMicroelectronics and the Transformation of the Automotive Industry. STMicroelectronics Media Center.
- [18] ROHM Co., Ltd. (2026, October 16). ROHM Participates in NVIDIA MGX Ecosystem Ceremony at OCP Global Summit 2026. ROHM Newsroom.
- [19] ROHM Co., Ltd. (2026, September 15). ROHM Launches a MOSFET with Industry-Leading Wide-SOA for Automotive Safety Functions and Protection Circuits. ROHM Newsroom.
- [20] Infineon Technologies AG. (2025, March 31). Power PROFET™ + 24/48V smart power switch family with highest energy efficiency for automotive power distribution. Infineon Technology News.
- [21] Analog Devices, Inc. (2026, August 18). Form 10-Q Quarterly Report for the Quarterly Period Ended August 1, 2026. U.S. Securities and Exchange Commission EDGAR.
- [22] ROHM Co., Ltd. (2026, May 21). ROHM Launches ESD Protection Diodes for High-Speed Interfaces Exceeding 10 Gbps. ROHM Newsroom.
- [23] Texas Instruments Incorporated. (2026, October 21). TI reports third quarter 2026 financial results and shareholder returns. Texas Instruments Newsroom.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the global active ideal diode controllers market in 2025, 2026, and 2036, and what is the 10-year CAGR?
- How much conduction heat does an active ideal diode controller plus 0.88 mOhm MOSFET eliminate at a 50A load compared with a Schottky diode?
- Why does ISO 16750-2 superimposed AC alternator ripple require a linear gate-servo charge-pump architecture?
- Why do 65V to 100V Automotive controllers command 59.2% of global market value in 2026?
- Why does Mexico record the fastest country-level CAGR (11.8%) between 2026 and 2036?
- Why is 48V AI Rack OR-ing the fastest-growing end-use system through 2036?
- What drives adoption of Monolithic Smart Bypass diodes inside solar photovoltaic junction boxes?
- How does the active ideal diode controller IC market boundary exclude standalone external discrete MOSFET revenue?
Frequently Asked Questions
What is the size of the global active ideal diode controllers market in 2025, 2026, and 2036?
Total industry valuation for active ideal diode controllers moved from a 2025 baseline of USD 282.0 million to USD 312.0 million in 2026, with FMI projecting USD 831.6 million by 2036 on a 10.3% CAGR.
How much power loss does an active ideal diode controller save compared with a passive Schottky diode?
At a 50A continuous load current, replacing a 0.50V passive Schottky diode (25.0W heat loss) with an active ideal diode controller driving a 0.88 mOhm external N-channel MOSFET lowers forward voltage to 44 mV and cuts heat dissipation by 91.2% to 2.2W.
Why does the Floating Charge-Pump Controller segment hold the largest share in 2026?
The Floating Charge-Pump Controller segment secures 64.5% of 2026 demand (USD 201.2 million) because a compact 6-pin or 8-pin IC drives a single external high-side N-channel MOSFET across unidirectional automotive reverse-polarity and server OR-ing sockets.
Why do 65V to 100V Automotive controllers outsell Under-40V devices?
Automotive 65V to 100V controllers account for 59.2% of 2026 market value (USD 184.7 million) because both 12V/24V load-dump transients and 48V mild-hybrid or zonal board-nets require 65V to 100V standoff ratings and AEC-Q100 qualification.
Why is 48V AI Rack OR-ing the fastest-growing end-use system?
Server 48V AI Rack OR-ing billings grow at an 11.2% CAGR from USD 90.2 million in 2026 to USD 261.2 million by 2036 across 1MW Open Compute Project server racks where 48V distribution cuts current 4x and I²R losses 16x.
What drives adoption of Monolithic Smart Bypass Diodes in solar PV panels?
Solar equipment outages reached 4.47% and caused USD 4,600.0 million in annual revenue losses (with shading and diode faults cutting output by 5% to 10% in Germany and Japan), prompting photovoltaic makers to replace hot Schottky diodes with low-drop smart bypass switches.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Gate Drive Topology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Gate Drive Topology, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Gate Drive Topology, 2026 to 2036
- Floating Charge-Pump Controller
- Back-to-Back Load-Disconnect
- Monolithic Smart Bypass
- Dual-Channel OR-ing Controller
- Y-o-Y Growth Trend Analysis By Gate Drive Topology, 2021 to 2025
- Absolute $ Opportunity Analysis By Gate Drive Topology, 2026 to 2036
- Global Market Analysis and Forecast, By Voltage Rating, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Voltage Rating, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Voltage Rating, 2026 to 2036
- 65V to 100V Automotive
- Under-40V Server & Industrial
- Over-100V High-Voltage
- Y-o-Y Growth Trend Analysis By Voltage Rating, 2021 to 2025
- Absolute $ Opportunity Analysis By Voltage Rating, 2026 to 2036
- Global Market Analysis and Forecast, By Package Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Package Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Package Type, 2026 to 2036
- Wettable-Flank QFN
- Compact SOT-23 & WSON
- TO-263 Solar Bypass
- Leaded MSOP & TSSOP
- Y-o-Y Growth Trend Analysis By Package Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Package Type, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use System, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End-Use System, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End-Use System, 2026 to 2036
- Automotive Zonal & ADAS
- 48V AI Rack OR-ing
- Solar Smart Junction Boxes
- Industrial Microgrid Rectifiers
- Y-o-Y Growth Trend Analysis By End-Use System, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use System, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct OEM & Tier-1 Supply
- Authorized Electronics Distribution
- Contract EMS & ODM
- Power Module Integrators
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Malaysia
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Taiwan
- Pricing Analysis
- Market Share Analysis, 2025
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Gate Drive Topology
- By Voltage Rating
- By Package Type
- By End-Use System
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Analog Devices, Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Texas Instruments Inc.
- Infineon Technologies AG
- Nexperia B.V.
- STMicroelectronics N.V.
- onsemi
- ROHM Co., Ltd.
- Monolithic Power Systems
- Texas Instruments Incorporated
- Analog Devices, Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


