
- Market Size (2026)
- USD 1.5 Bn
- Forecast (2036)
- USD 18.2 Bn
- CAGR (2026 to 2036)
- 28.5%
How big is Application Programming Interface (API) Security Market in 2026?
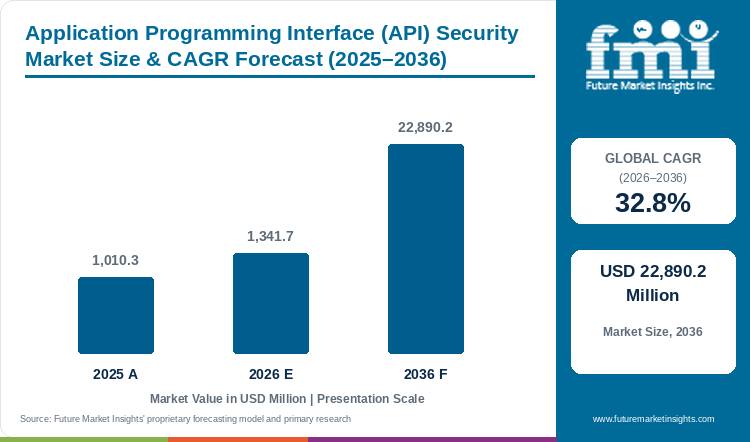
Assessed at USD 1.2 billion in 2025 and progressing to USD 1.5 billion in 2026, the application programming interface (API) security market valuation is on course to reach USD 18.2 billion by 2036, supported by a forecast-period CAGR of 28.5%.
Table 1: Market Size and Forecast for the Application Programming Interface (API) Security Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 1.2 billion |
| Estimated Market Size in 2026 | USD 1.5 billion |
| Projected Market Size by 2036 | USD 18.2 billion |
| CAGR, 2026 to 2036 | 28.5% |
| Added Revenue, 2026 to 2036 | USD 16.7 billion |
The global application programming interface (API) security market was valued at USD 1.2 billion in 2025 and is estimated to reach USD 1.5 billion in 2026. Total industry valuation is projected to reach USD 18.2 billion by 2036, expanding at a compound annual growth rate (CAGR) of 28.5% between 2026 and 2036. API Discovery and Inventory Platforms capture an estimated 44.0% share of 2026 component demand, given that security officers cannot govern microservices or partner gateways without continuous automated endpoint discovery. FMI demand analysis indicates that enterprise buyers are purchasing runtime behavioral inspection per thousand calls at a rapid clip as autonomous software agents and payment microservices multiply exposed data interfaces. This architecture-driven purchasing cycle separates the sector from zero trust security platforms expanding at a 15.1% CAGR, since workforce access licenses track employee headcount whereas API protection contracts scale with machine-to-machine transaction volume. Demand for dedicated interface defense is supported by threat telemetry from Akamai Technologies, which reported in March 2026 that 87% of surveyed organizations experienced an API security incident in 2025 as daily attacks rose 113% year over year. Security vendors are investing heavily in automated governance to capture this enterprise spend, seen when Salt Security reached 100 pre-built governance policies in July 2026 after launching Salt Code in June 2026 to inspect AI-generated software interfaces. Enterprise security architects renew multi-year platform subscriptions when behavioral telemetry stops object-level token abuse without adding latency to customer checkout traffic through 2036.
Key Market Trends & Insights
- By component solution: API Discovery and Inventory Platforms hold an estimated 44.0% share in 2026 since continuous traffic inspection uncovers rogue and zombie endpoints across distributed cloud environments.
- By deployment mode: Cloud-Native SaaS Solutions represent an estimated 68.0% share in 2026 given that elastic cloud telemetry engines analyze billions of gateway calls without on-premises hardware bottlenecks.
- By industry vertical: Financial Services and Open Banking secures an estimated 52.0% share in 2026 driven by mandatory open-banking payment interfaces and real-time fraud monitoring audits.
- By threat focus: Broken Object Authorization Protection accounts for an estimated 48.0% share in 2026 owing to attackers manipulating resource identifiers inside valid session tokens to extract records.
- By enterprise size: Large Enterprise Organizations command an estimated 64.0% share in 2026 through multi-cloud microservice estates that exceed thousands of internal and third-party application endpoints.
Regional Highlights
- Top national expansion: Australia leads national growth projections at an estimated 30.6% CAGR through 2036 under Consumer Data Right open-banking mandates and critical infrastructure defense rules.
- Broader country progression: Canada tracks at an estimated 29.8% CAGR ahead of the United Kingdom at 29.6% and the United States at 28.9%, while Germany advances at 27.6% and Japan records 26.4%.
Market Size & Forecast
Financial institutions, digital retailers, and healthcare networks confront rapid growth in machine-to-machine microservice traffic that bypasses traditional perimeter firewalls. When application developers push weekly code updates without standardized gateway catalogs, undocumented endpoints remain exposed to automated credential stuffing and unauthorized object scraping. As documented in the NIST Special Publication 800-228 Guidelines for API Protection for Cloud-Native Systems updated in March 2026, enterprises must enforce mutual TLS authentication and token validation across first-party and third-party facade APIs to stop lateral data breaches. Consequently, enterprise procurement teams bundle automated posture discovery with cloud workload protection suites to verify every internal and external call before granting database access.
Enterprise API Endpoint Inventory & Traffic Inspection Sizing
Table 2: Enterprise API Endpoint Inventory and Traffic Inspection Sizing for the Application Programming Interface (API) Security Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 1.2 | 1.5 | 18.2 |
| Monitored enterprise production APIs globally (million endpoints) | 145.0 to 165.0 | 185.0 to 210.0 | 1,420.0 to 1,650.0 |
| Inspected enterprise API traffic volume (trillion calls/year) | 42.0 to 48.0 | 58.0 to 66.0 | 680.0 to 790.0 |
| Annual security spend per 1,000 monitored APIs (USD) | 7,250 to 8,200 | 7,150 to 8,100 | 11,000 to 12,800 |
Operational note: Monitored enterprise API endpoint ranges reflect active internal and public REST, GraphQL, and gRPC interfaces under continuous posture and runtime telemetry governance.
High-volume banking and retail platforms require continuous schema validation and behavioral anomaly baselines so legitimate customer bursts are separated from automated scraping bots. Security operations centers pair out-of-band traffic mirroring with automated bot security tools to block token harvesting without slowing gateway response times. Empirical findings published by F5 in its May 2026 State of Application Strategy Report substantiate this operational shift, confirming that 78% of enterprises now run artificial intelligence inference as a core production workload connected through hybrid multicloud APIs. This expansion in automated model-to-database queries compels infrastructure buyers to upgrade annual inspection capacity.
Enterprise Security Spend & Incident Cost Indicators
Table 3: Enterprise API Security Spend and Breach Mitigation Indicators for the Application Programming Interface (API) Security Market (USD and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Surveyed enterprises experiencing API security incidents (%) | 84.0% to 87.0% | 85.0% to 88.0% | 62.0% to 68.0% |
| Enterprises running production AI inference via APIs (%) | 61.0% to 68.0% | 75.0% to 78.0% | 94.0% to 97.0% |
| Annual API security spend per large enterprise (USD thousand) | 145.0 to 180.0 | 175.0 to 220.0 | 620.0 to 780.0 |
| Cloud-Native SaaS deployment share (%) | 65.0% to 67.0% | 67.0% to 69.0% | 78.0% to 82.0% |
Table 4: Enterprise Deployment & Vertical Spending Indicators for the Application Programming Interface (API) Security Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 1.5 billion | 2026 global enterprise API security baseline |
| Organizations reporting API security incidents in 2025 | 87.0% | Akamai 2026 State of the Internet Apps & APIs Report |
| Daily API attack volume growth (YoY) | 113.0% | Akamai global edge telemetry benchmark |
| Financial Services and Open Banking revenue, 2026 | USD 0.78 billion | 52.0% industry vertical allocation under open-banking rules |
Migration from static web application signature rules to runtime behavioral protection requires correlating user identity context with backend data permissions. Security engineering teams integrate out-of-band telemetry collectors with identity and access management systems so compromised session tokens are revoked before bulk records leave the server. Threat telemetry released by Fortinet in its 2026 Global Threat Landscape Report reinforces this procurement priority, documenting a 25.49% year-over-year rise in global exploitation attempts and 7,831 confirmed ransomware victims where stolen identity credentials drove cloud exposure.
Analyst Perspective
"Enterprise security leaders no longer buy API security as a static gateway add-on; they buy continuous behavioral discovery and real-time object authorization across thousands of changing microservices. Vendors that combine zero-latency runtime blocking with developer shift-left schema audits will capture multi-year enterprise consolidation contracts through 2036."
- Sudip Saha, Principal Consultant, Future Market Insights.
How is the application programming interface (API) security market segmented?
The application programming interface (API) security market is segmented by component solution, deployment mode, industry vertical, threat focus, and enterprise size. In 2026, API Discovery and Inventory Platforms are projected at 44.0%, Cloud-Native SaaS Solutions at 68.0%, Financial Services and Open Banking at 52.0%, Broken Object Authorization Protection at 48.0%, and Large Enterprise Organizations at 64.0%.
By component solution: API Discovery and Inventory Platforms, API Vulnerability and Posture Management, API Runtime Threat Protection and API Gateway WAF Modules.
By deployment mode: Cloud-Native SaaS Solutions, On-Premises Hybrid Deployments, Containerized Kubernetes Mesh Sidecars and Sovereign Cloud Appliances.
By industry vertical: Financial Services and Open Banking, Healthcare Electronic Health Records, Retail and Digital Marketplaces, Telecommunications and Cloud Providers, and Government Public Sector Portals.
By threat focus: Broken Object Authorization Protection, Data Exfiltration and PII Prevention, Automated Bot Scraping Defense and Credential Token Hijacking Mitigation.
By enterprise size: Large Enterprise Organizations, Small and Medium-Sized Enterprises, Regulated Public Institutions and Digital-Native Startups.
Why do API Discovery and Inventory Platforms lead the component solution category?
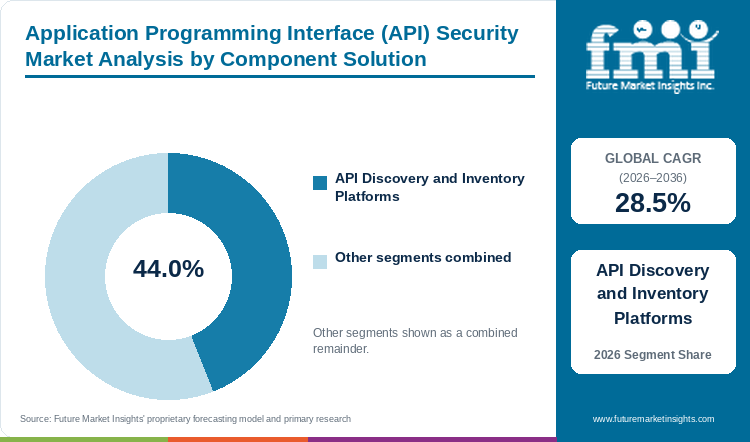
API Discovery and Inventory Platforms hold an estimated 44.0% of component solution demand in 2026, anchored by automated shadow and zombie endpoint detection across multi-cloud gateways.
Table 5: Component Solution Share for the Application Programming Interface (API) Security Market (percentage share), 2026
| Component Solution | Share (2026) |
|---|---|
| API Discovery and Inventory Platforms | 44.0% |
| Other Segments Combined | 56.0%* |
| Total | 100.0% |
*Note: Remaining component solution categories account for the balance of 2026 global application programming interface (API) security demand.
Table 6: Component Solution Leadership and Market Growth for the Application Programming Interface (API) Security Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 28.5% |
| Leading Segment | API Discovery and Inventory Platforms |
API Discovery and Inventory Platforms form the foundational purchase for enterprise security teams since rapid CI/CD software releases continuously generate undocumented shadow, deprecated, and orphan endpoints. Without an automated inventory that maps sensitive data flows across gateways and service meshes, security architects cannot configure network security firewall appliances or runtime access policies accurately. Production telemetry published by Salt Security in its 2H 2026 State of AI and API Security Report confirms this visibility gap, showing that 86.4% of surveyed organizations deploy autonomous agents while 54.3% discovered or suspected shadow Model Context Protocol servers exposing backend interfaces.
- Within the component solution segment, API Discovery and Inventory Platforms are projected to account for a leading 44.0% share in 2026, driven by mandatory endpoint cataloging before runtime policy enforcement.
- Adoption of standalone discovery tools faces rising competition from unified platforms that merge pre-production OpenAPI schema testing with live runtime blocking in a single license.
What sustains Cloud-Native SaaS Solutions leadership in the deployment mode segment?
Cloud-Native SaaS Solutions represent an estimated 68.0% of the deployment mode category in 2026, supported by agentless cloud gateway telemetry and elastic machine-learning anomaly detection.
Cloud-Native SaaS Solutions dominate enterprise procurement since analyzing multi-gigabit call streams for subtle behavioral anomalies requires elastic cloud machine-learning clusters rather than fixed on-premises appliances. Multi-cloud enterprises connect out-of-band sensors from AWS, Azure, and Google Cloud gateways directly into vendor SaaS control planes paired with cloud data encryption solutions without deploying inline proxy hardware that could introduce network latency. High-security defense and sovereign banking buyers still retain hybrid on-premises collectors where national data residency laws restrict external metadata transfer.
- In 2026, Cloud-Native SaaS Solutions are anticipated to capture 68.0% of global deployment mode demand, reflecting buyer preference for agentless cloud connectors and elastic threat correlation.
- Product updates released by Harness in January 2026 demonstrated how cloud-hosted semantic analysis achieves 98.7% accuracy in automated endpoint naming and vulnerability detection across distributed software pipelines.
Why does Financial Services and Open Banking lead the industry vertical category?
Financial Services and Open Banking secures an estimated 52.0% of industry vertical value in 2026, supported by mandatory open-banking payment rails and real-time account-takeover defense.
Financial Services and Open Banking institutions anchor global vertical spending since retail banks and payment processors expose high-value account initiation and balance-check interfaces to third-party aggregators every second. A single unauthenticated endpoint or broken token check in an open-banking gateway triggers immediate financial theft and severe central-bank compliance penalties. Financial security teams pair dedicated posture engines with managed DDoS protection services to maintain continuous payment availability during volumetric credential-stuffing campaigns, though complex legacy mainframe integrations can slow deployment cycles.
- Strong repeat ordering across banking and payment processors places Financial Services and Open Banking on course to hold an estimated 52.0% share of the industry vertical category in 2026.
- Industry survey findings from Traceable AI's Global State of API Security study confirm that 16% of large digital enterprises manage more than 2,500 active APIs while 26% face regulatory compliance struggles after breaches.
How does Broken Object Authorization Protection lead the threat focus category?
Broken Object Authorization Protection accounts for an estimated 48.0% of threat focus spending in 2026, driven by stateful object-ownership verification across authenticated REST and GraphQL sessions.
Broken Object Authorization Protection represents the top threat priority for application security buyers given that object-level flaws allow an authenticated user to swap resource identifiers in a call and read thousands of unauthorized customer records. Standard signature-based web firewalls fail to detect BOLA attacks since each malicious request carries a valid session token and conforms to normal HTTP syntax. Security teams consequently deploy stateful behavioral engines with cloud encryption software to verify object ownership on every read and write request. Academic security research published on arXiv in July 2026 with the AuthProbe multi-identity testing framework demonstrated how automated specification-driven probing uncovers object-level vulnerabilities across complex production REST endpoints without server source-code access.
- By threat focus, demand for Broken Object Authorization Protection is estimated to reach 48.0% of total category share in 2026 as enterprises prioritize object-level permission checks.
- Over the forecast period, buyer spending is expected to expand toward combined BOLA and function-level authorization defenses as multi-agent workflows chain internal microservices together.
What gives Large Enterprise Organizations the leading position in enterprise size?
Large Enterprise Organizations command an estimated 64.0% of enterprise size share in 2026, anchored by multi-cloud microservice estates and centralized DevSecOps governance contracts.
Large Enterprise Organizations account for the majority of commercial contract value given that multinational corporations operate hundreds of independent development squads that publish thousands of internal, partner, and customer-facing endpoints across hybrid clouds. Decentralized software deployment creates severe governance blind spots when business units acquire external SaaS connectors without central security review, prompting chief information security officers to standardize enterprise-wide protection suites with managed encryption services. Survey data published by Harness in September 2026 indicates that 61% of new enterprise applications are now artificial-intelligence-powered while 48% of technology leaders cite security threats as a top barrier to production deployment.
- Large Enterprise Organizations are predicted to secure 64.0% of enterprise size demand in 2026, supported by multi-year enterprise license agreements covering global microservice estates.
- Small and medium-sized enterprises are projected to adopt bundled gateway security modules at a faster rate after 2028 as cloud providers embed automated discovery into standard tier subscriptions.
What are the drivers, restraints, and opportunities in the application programming interface (API) security market?
In the application programming interface (API) security market, microservice proliferation and agentic AI tool connectivity are projected to drive adoption whereas SOC alert fatigue and inline latency concerns restrain uncalibrated blocking and kernel-level eBPF telemetry opens DevSecOps expansion.
- Driver: Rapid enterprise adoption of microservices, open-banking payment rails, and autonomous AI agents multiplies exposed endpoints that require continuous behavioral runtime protection.
- Restraint: Severe shortages of skilled application security engineers and high false-positive alert volumes from uncalibrated anomaly rules slow full-blocking enforcement in production.
- Opportunity: Embedding kernel-level eBPF telemetry and automated shift-left OpenAPI schema governance into developer pipelines opens new recurring subscription revenue across cloud-native enterprises.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Enterprise transition toward microservice architectures and agentic artificial intelligence workflows is compelling technology buyers to expand dedicated interface security budgets through 2036. When enterprises connect large language models and external partner apps directly to core customer databases via REST and GraphQL interfaces, traditional perimeter firewalls cannot inspect business-logic abuse inside encrypted traffic. Deployment of specialized discovery and behavioral threat engines within enterprise cyber defense infrastructure enables security teams to detect unauthorized token replay in real time. Adversarial research published by Cequence Security in 2026 on Agentic Zero Trust demonstrated that token isolation weaknesses appear in 73% of assessed production AI deployments with 492 unauthenticated Model Context Protocol servers exposed to the internet, confirming why enterprises are accelerating runtime procurement.
Risk Assessment of the Application Programming Interface (API) Security Market: Operational and Formulation Friction
Alert fatigue inside understaffed security operations centers and latency concerns during inline traffic inspection represent the primary operational hurdles restraining aggressive blocking-mode deployments. Unlike deterministic signature rules that block known SQL injection strings, behavioral anomaly models require baseline training windows to distinguish legitimate holiday shopping spikes from automated scraping attacks. Academic vulnerability studies released in July 2025 examining zero-trust BOLA detection confirmed that manually labeling authorization rules across hundreds of REST resource operations is error-prone and leads to high false-positive rates when application schemas change rapidly. Consequently, many enterprise buyers keep newly installed security tools in passive monitoring mode for months before authorizing automated session termination.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Security software vendors are capturing high-margin expansion contracts by embedding Extended Berkeley Packet Filter (eBPF) kernel sensors and automated token-lifecycle auditing into unified posture platforms. By capturing telemetry directly at the Linux kernel and container service-mesh layer without sidecar proxy overhead, vendors eliminate deployment friction for cloud platform engineers. Production telemetry published by Imperva in its August 2026 API Security Token and Authentication Risk Report across 1,104 customer environments and 32,725 live endpoints reveals that nearly 40% of enterprise APIs face multiple token and authentication risks. Suppliers that pair frictionless eBPF runtime sensors with automated JSON Web Token validation create new demand avenues across DevSecOps engineering budgets.
Application Programming Interface (API) Security Market by Country (2026 to 2036)
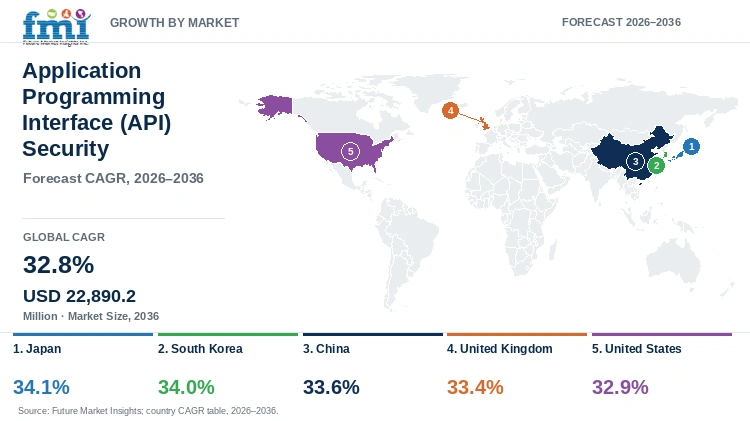
FMI country modeling indicates that Australia leads global expansion at an estimated 30.6% CAGR through 2036, while Canada advances at 29.8% and the United Kingdom tracks at 29.6%. National adoption rates reflect open-banking regulatory deadlines, federal zero-trust cloud mandates, and domestic financial and retail traffic density.
Table 7: Country CAGR and Primary Growth Levers for the Application Programming Interface (API) Security Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Australia | 30.6% | Consumer Data Right open-banking expansion and ASD critical infrastructure cyber rules |
| Canada | 29.8% | Federal consumer-driven banking framework rollout and cloud threat resilience mandates |
| United Kingdom | 29.6% | Commercial Variable Recurring Payment APIs and FCA open-banking regulatory framework |
| United States | 28.9% | CISA cloud-native API protection guidelines and fortune-scale AI microservice governance |
| Germany | 27.6% | BSI C5:2026 cloud compliance catalog and BaFin banking interface security audits |
| France | 27.4% | ENISA NIS2 supply-chain directives and sovereign cloud Kubernetes API modernization |
| South Korea | 26.8% | MyData financial super-app API aggregation and high-throughput mobile bot mitigation |
| Japan | 26.4% | IPA organizational security threat countermeasures and megabank microservice migration |
Source: Future Market Insights analysis
Australia Application Programming Interface (API) Security Market Outlook (2026 to 2036)
Demand for API security solutions in Australia is projected to expand at a leading 30.6% CAGR between 2026 and 2036 as banks, energy retailers, and telecommunications carriers comply with mandatory Consumer Data Right data-sharing endpoints. Domestic commercial demand is driven by the statutory enforcement of the Security of Critical Infrastructure Act combined with mandatory real-time availability and breach reporting across eleven regulated sectors. Official incident records from the Australian Signals Directorate's Annual Cyber Threat Report 2025-26 confirm this pressure, documenting over 1,500 cyber security incidents handled and more than 4,400 malicious activity notifications issued to Australian entities. Local enterprises prioritize cloud-native SaaS discovery platforms to govern third-party fintech and utility data-sharing connections.
Key takeaway: In Australia, statutory Consumer Data Right endpoint expansion and critical infrastructure cyber resilience mandates are projected to drive leading adoption of cloud-native discovery and runtime protection.
Canada Application Programming Interface (API) Security Market Outlook (2026 to 2036)
Canada's financial services and federal public service sectors are scaling secure data-sharing gateways across Toronto, Montreal, and Vancouver cloud corridors. Consequently, national API protection adoption is anticipated to advance at a 29.8% CAGR through 2036, outpacing mature global averages due to federally supervised open-banking accreditation rules. Intelligence findings in the Canadian Centre for Cyber Security's National Cyber Threat Assessment 2025-2026 substantiate this spending surge, warning that vendor concentration and dual-use cloud services expose Canadian critical infrastructure to automated state and criminal exploitation. Canadian banks and insurance carriers require bilingual compliance reporting and strict object-level authorization verification before onboarding fintech partners.
Key takeaway: In Canada, federal consumer-driven banking implementation and critical infrastructure threat directives are anticipated to sustain rapid procurement of runtime security platforms.
United Kingdom Application Programming Interface (API) Security Market Outlook (2026 to 2036)
In the United Kingdom, market growth is forecast to reach a 29.6% CAGR from 2026 to 2036, anchored by Europe's largest open-banking payment network and commercial Variable Recurring Payments rollout. British retail banks and e-commerce merchants process millions of instant account-to-account calls daily. Regulatory updates published by the UK Financial Conduct Authority in December 2025 confirm that 31 financial firms formed the UK Payments Initiative to launch commercial Variable Recurring Payment interfaces in 2026 ahead of long-term statutory open-banking legislation. British banking security teams prioritize real-time behavioral anomaly detection to protect high-frequency payment initiation gateways.
Key takeaway: In the United Kingdom, commercial Variable Recurring Payment scaling and FCA open-banking governance are forecast to accelerate enterprise investment in behavioral threat mitigation.
United States Application Programming Interface (API) Security Market Outlook (2026 to 2036)
Commercial API security expenditure in the United States is estimated to progress at a 28.9% CAGR between 2026 and 2036 across hyperscale cloud enterprises, healthcare clearinghouses, and federal agencies. What sets the United States apart from other regional markets is the concentration of fortune-scale multi-cloud microservice estates and aggressive federal zero-trust acquisition mandates. Federal guidance issued by the Cybersecurity and Infrastructure Security Agency in July 2026 establishing the 2026 Minimum Elements for a Software Bill of Materials (SBOM) compels American cloud SaaS and AI software suppliers to document and audit every exposed application interface. U.S. buyers lead global adoption of agentic AI governance policies and kernel-level eBPF runtime collectors.
Key takeaway: In the United States, federal CISA zero-trust directives and dense enterprise AI microservice deployments are estimated to anchor high-value multi-year protection contracts.
Germany Application Programming Interface (API) Security Market Outlook (2026 to 2036)
National regulatory mandates governing cloud sovereignty and automotive connected-factory interfaces in Germany are reshaping how domestic enterprises procure application security software. FMI country modeling indicates that API security market growth in Germany is slated to track at a 27.6% CAGR over the 2026 to 2036 forecast period. In March 2026, the German Federal Office for Information Security (BSI) finalized its revised Cloud Computing Compliance Criteria Catalogue (C5:2026), establishing updated audit requirements for cloud service interfaces and enterprise SaaS workloads across Cybernation Germany. German automotive manufacturers and Frankfurt banking groups require strict EU data residency where telemetry logs remain inside European cloud zones.
Key takeaway: In Germany, BSI C5:2026 cloud audit compliance and industrial automotive integration are slated to drive steady enterprise procurement of sovereign-ready posture platforms.
France Application Programming Interface (API) Security Market Outlook (2026 to 2036)
France's banking, telecommunications, and luxury retail sectors are consolidating fragmented gateway defenses into unified cloud application protection architectures. Demand for enterprise API security in France is likely to increase at a 27.4% CAGR through 2036, diverging from broader European averages due to stringent national SecNumCloud qualification standards and rapid generative AI adoption across Paris enterprise hubs. Threat intelligence released by the European Union Agency for Cybersecurity (ENISA) in its September 2026 Threat Landscape report confirms that expanding digital supply-chain dependencies and AI-assisted DDoS campaigns require heightened interface vigilance across EU member states. French enterprises favor hybrid Kubernetes sidecar and sovereign cloud SaaS deployments.
Key takeaway: In France, ENISA NIS2 supply-chain resilience rules and enterprise cloud modernization are likely to sustain strong demand for containerized and cloud-native security.
South Korea Application Programming Interface (API) Security Market Outlook (2026 to 2036)
South Korea's financial super-apps, semiconductor manufacturers, and public digital platforms operate some of Asia's highest-density mobile transaction environments. Procurement of API protection software in South Korea is predicted to advance at a 26.8% CAGR between 2026 and 2036 as financial groups expand MyData cross-industry sharing and replace legacy perimeter controls. Empirical threat data from Imperva's April 2026 Bad Bot Report confirms why high-throughput mobile platforms invest in automated defense, showing that automated bot traffic hit 53% of all web traffic with 27% of bot attacks targeting API endpoints. Domestic conglomerate buyers prioritize low-latency inline gateway modules paired with automated BOLA and bot-scraping protection.
Key takeaway: In South Korea, high-density MyData financial super-app traffic and mobile commerce automation are predicted to fuel enterprise upgrades to automated vulnerability and runtime defense.
Japan Application Programming Interface (API) Security Market Outlook (2026 to 2036)
Japanese megabanks, insurance groups, and industrial electronics exporters are modernizing monolithic mainframe applications into cloud-connected microservice architectures. Consequently, API security software sales in Japan are expected to grow at a 26.4% CAGR from 2026 to 2036 as enterprise security divisions address supply-chain and remote-access interface exposures. In January 2026, Japan's Information-technology Promotion Agency (IPA) published its Information Security 10 Major Threats 2026 report, ranking supply-chain vulnerabilities and targeted system exploitation among the top organizational threats requiring systematic defense. Japanese enterprise buyers rely heavily on managed security service partners to calibrate anomaly baselines.
Key takeaway: In Japan, IPA organizational threat countermeasures and banking microservice migration are expected to drive long-term adoption of managed and cloud-native security solutions.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the application programming interface (API) security market?
Salt Security, Inc., Akamai Technologies, Inc. (Noname Security), Traceable AI, Inc. (Harness), Cequence Security, Inc., Imperva, Inc. (Thales Group), Palo Alto Networks, Inc., F5, Inc., Cloudflare, Inc., CrowdStrike Holdings, Inc., and Fortinet, Inc. are the notable companies in the application programming interface (API) security market.
Competitive positioning in the API protection sector divides into dedicated discovery and runtime posture specialists, integrated edge WAF and application delivery vendors, and broad cloud workload security suites. Salt Security and Akamai Technologies focus on deep behavioral telemetry and BOLA prevention paired with Traceable AI and Cequence Security. Imperva and Palo Alto Networks embed discovery and bot mitigation directly into global edge gateways while F5 and Cloudflare scale inline traffic scrubbing and CrowdStrike Holdings and Fortinet integrate posture governance into cloud platforms.
- Dedicated API Discovery and Runtime Posture Specialists: Salt Security, Akamai Technologies, Traceable AI and Cequence Security engineer behavioral graph engines that catalog shadow endpoints and block object-level authorization abuse.
- Integrated Application Delivery and Edge Security Providers: Imperva, Palo Alto Networks, F5 and Cloudflare combine inline edge gateways and automated schema validation across global points of presence.
- Cloud Workload and Extended Threat Protection Suites: CrowdStrike Holdings and Fortinet unify code-to-cloud application security posture management with runtime container and identity threat response.
Competitive Benchmarking: Application Programming Interface (API) Security Market
Table 8: Competitive Benchmarking for the Application Programming Interface (API) Security Market (qualitative capability ratings), 2026
| Company | Deep Behavioral API Discovery | Runtime BOLA & Bot Mitigation | Shift-Left DevSecOps Fit | Geographic Reach |
|---|---|---|---|---|
| Salt Security, Inc. | High | High | High | Global SaaS cloud regions; launched Salt Code in June 2026 and 100 Policy Hub rules in July 2026 |
| Akamai Technologies, Inc. (Noname Security) | High | High | High | Global edge CDN network across 130+ countries integrated with Noname API security |
| Traceable AI, Inc. (Harness) | High | High | High | North America, Europe, and APAC DevSecOps and runtime API intelligence via Harness platform |
| Cequence Security, Inc. | High | High | Medium | Global Unified API Protection and Agentic Zero Trust MCP security across enterprise clouds |
| Imperva, Inc. (Thales Group) | Medium | High | Medium | Global Thales cyber security channel pairing Imperva WAF Gateway with Luna HSM security |
| Palo Alto Networks, Inc. | High | High | High | Global Prisma Cloud and Strata enterprise footprint; launched Idira identity platform in May 2026 |
| F5, Inc. | High | High | High | Global Distributed Cloud API Security and BIG-IP footprint across hybrid multicloud enterprises |
| Cloudflare, Inc. | Medium | High | Medium | Global 300+ city edge network delivering inline API Gateway schema validation and WAF scrubbing |
| CrowdStrike Holdings, Inc. | Medium | Medium | High | Global Falcon Cloud Security CNAPP; partnered with Lovable in November 2026 for AI app security |
| Fortinet, Inc. | Medium | High | Medium | Global FortiWeb and FortiCNAPP enterprise channel across North America, EMEA, and APAC |
Evaluation basis: Deep Behavioral API Discovery rates automated cataloging of shadow, zombie, and agentic MCP endpoints across multi-cloud traffic. Runtime BOLA and Bot Mitigation evaluates stateful session-level authorization checking and automated scraping defense, while Shift-Left DevSecOps Fit measures pre-production OpenAPI schema auditing and CI/CD pull-request integration.
Key Developments in the Application Programming Interface (API) Security Market
- CrowdStrike Holdings announced a strategic partnership with Lovable on November 3, 2026 to secure AI-built applications and govern exposed application interfaces from initial code generation through cloud runtime.
- Palo Alto Networks introduced its Idira next-generation identity and agentic security platform on May 12, 2026 to govern machine identities and AI-connected enterprise interfaces.
- UK Department for Science, Innovation and Technology and security partners reinforced enterprise interface defense priorities on April 30, 2026 as Imperva and Thales expanded integrated WAF and Luna HSM gateway protection.
Key Players in the Application Programming Interface (API) Security Market
Dedicated API Discovery and Runtime Posture Specialists
- Salt Security, Inc.
- Akamai Technologies, Inc. (Noname Security)
- Traceable AI, Inc. (Harness)
- Cequence Security, Inc.
Integrated Application Delivery and Edge Security Providers
- Imperva, Inc. (Thales Group)
- Palo Alto Networks, Inc.
- F5, Inc.
- Cloudflare, Inc.
Cloud Workload and Extended Threat Protection Suites
- CrowdStrike Holdings, Inc.
- Fortinet, Inc.
Application Programming Interface (API) Security Market - Report Scope
Table 9: Report Scope for the Application Programming Interface (API) Security Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Component Solution; Deployment Mode; Industry Vertical; Threat Focus; Enterprise Size |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial enterprise software and SaaS subscription revenue from dedicated API discovery and inventory mapping platforms, API posture governance and pre-production vulnerability testing tools, runtime behavioral API threat protection and BOLA mitigation engines, and the attributable API security module value within cloud WAF and API gateway suites. Category Scope Note: Excludes general-purpose network firewalls, standalone CDN content caching bandwidth, and basic workforce multi-factor login directories. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Australia, Canada, United Kingdom, United States, Germany, France, South Korea, Japan, and additional countries in the full report |
| Key Companies Covered | Salt Security, Inc., Akamai Technologies, Inc. (Noname Security), Traceable AI, Inc. (Harness), Cequence Security, Inc., Imperva, Inc. (Thales Group), Palo Alto Networks, Inc., F5, Inc., Cloudflare, Inc., CrowdStrike Holdings, Inc., Fortinet, Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Application Programming Interface (API) Security Market - Research Methodology
Table 10: Research Methodology for the Application Programming Interface (API) Security Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with enterprise chief information security officers, financial open-banking API architects, cloud DevSecOps directors, and API security product managers to validate endpoint counts and per-call licensing tiers. |
| Secondary Research | Analysis of NIST Special Publication 800-228 cloud-native API protection guidelines, OWASP API Security Testing Framework standards, UK FCA and GOV.UK cyber breach surveys, ASD and Canadian Cyber Centre threat reports, and arXiv BOLA vulnerability studies. |
| Market Sizing and Forecasting | Top-down application and cloud security baselines reconciled against bottom-up monitored enterprise production API endpoints (185M to 210M in 2026) and annual SaaS posture and runtime inspection contract values from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight open-banking regulatory mandates, multi-cloud microservice penetration, production AI agent deployment rates, and sovereign cloud compliance frameworks across eight countries. |
| Operational Benchmark Traceability | Endpoint inventory and breach indicators in Tables 2, 3, and 4 trace to Akamai 2026 State of the Internet telemetry, F5 2026 State of Application Strategy benchmarks, Salt Labs production telemetry, and Fortinet 2026 Global Threat Landscape data. |
| Data Triangulation and Validation | Revenue figures isolate automated API discovery, schema posture management, and behavioral runtime BOLA/bot defense while excluding commodity DDoS bandwidth, legacy network appliances, and general API management developer portals. |
Application Programming Interface (API) Security Market by Segments
Application Programming Interface (API) Security Market segmented by Component Solution:
- API Discovery and Inventory Platforms
- API Vulnerability and Posture Management
- API Runtime Threat Protection
- API Gateway WAF Modules
Application Programming Interface (API) Security Market segmented by Deployment Mode:
- Cloud-Native SaaS Solutions
- On-Premises Hybrid Deployments
- Containerized Kubernetes Mesh Sidecars
- Sovereign Cloud Appliances
Application Programming Interface (API) Security Market segmented by Industry Vertical:
- Financial Services and Open Banking
- Healthcare Electronic Health Records
- Retail and Digital Marketplaces
- Telecommunications and Cloud Providers
- Government Public Sector Portals
Application Programming Interface (API) Security Market segmented by Threat Focus:
- Broken Object Authorization Protection
- Data Exfiltration and PII Prevention
- Automated Bot Scraping Defense
- Credential Token Hijacking Mitigation
Application Programming Interface (API) Security Market segmented by Enterprise Size:
- Large Enterprise Organizations
- Small and Medium-Sized Enterprises
- Regulated Public Institutions
- Digital-Native Startups
Application Programming Interface (API) Security Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- Akamai Technologies, Inc. (2026, March 17). AI Transformation at Risk: APIs Emerge as the Primary Attack Surface, Akamai Research Finds. Akamai Newsroom.
- Australian Signals Directorate (ASD). (2026, October 14). ASD Annual Cyber Threat Report 2025-26. Australian Cyber Security Centre.
- Canadian Centre for Cyber Security. (2025, October 30). National Cyber Threat Assessment 2025-2026. Communications Security Establishment Canada.
- Cequence Security, Inc. (2026, May 18). Agentic AI Zero Trust: Extending the Zero Trust Security Architecture to Autonomous AI Systems. Cequence CQ Prime Threat Research.
- Chandramouli, R., & Butcher, Z. (2026, March 13). NIST Special Publication 800-228: Guidelines for API Protection for Cloud-Native Systems. National Institute of Standards and Technology (NIST).
- CrowdStrike Holdings, Inc. (2026, November 3). CrowdStrike and Lovable Partner to Secure AI-Built Applications. CrowdStrike Press Releases.
- Cybersecurity and Infrastructure Security Agency (CISA). (2026, July 29). 2026 Minimum Elements for a Software Bill of Materials (SBOM). U.S. Department of Homeland Security CISA.
- Department for Science, Innovation and Technology (DSIT). (2026, April 30). Cyber Security Breaches Survey 2025/2026. GOV.UK Official Statistics.
- European Union Agency for Cybersecurity (ENISA). (2026, September 22). ENISA Threat Landscape 2026: Exploring the Evolution of Digital Dependencies and Cyber Resilience. European Union Agency for Cybersecurity.
- F5, Inc. (2026, May 5). AI Has Left the Lab: F5 Report Reveals 78% of Enterprises Now Run AI Inference as a Core Operation. F5 Newsroom.
- Federal Office for Information Security (BSI). (2026, March 31). Cloud Computing Compliance Criteria Catalogue (C5:2026) Revision. Bundesamt für Sicherheit in der Informationstechnik.
- Financial Conduct Authority (FCA). (2025, December 16). Open Banking: A Year of Progress and Variable Recurring Payments Rollout. UK Financial Conduct Authority.
- Fortinet, Inc. (2026, April 15). The Fortinet 2026 Global Threat Landscape Report Reveals a Surge in AI-Enabled Cybercrime. Fortinet Newsroom.
- Harness Inc. (2026, January 29). Harness AI January 2026 Updates: Human-Aware SRE and Smarter API and Application Security. Harness Engineering Blog.
- Harness Inc. (2026, September 25). Best AI Security Solutions in 2026: An Enterprise Buyer's Guide. Harness Security Research.
- Imperva, Inc. (Thales Group). (2026, August 13). Imperva API Security Token & Authentication Risk Report: Nearly 40% of APIs Face Multiple Authentication Risks. Imperva Thales Security Blog.
- Imperva Threat Research. (2026, April 29). Bad Bot Report 2026: Bots in the Agentic Age. Imperva Cyber Threat Research.
- Information-technology Promotion Agency, Japan (IPA). (2026, January 29). Information Security 10 Major Threats 2026 for Organizations. Information-technology Promotion Agency, Japan.
- Palo Alto Networks, Inc. (2026, May 12). Palo Alto Networks Introduces Idira: The Next-Generation Identity Security Platform Built for the AI Enterprise. Palo Alto Networks Press Room.
- Research Contributors. (2026, July 22). AuthProbe: Specification-Driven, Multi-Identity Detection of Broken Object-Level Authorization. arXiv Open-Access Archive.
- Salt Labs. (2026, August 12). The State of AI and API Security 2H 2026 Report. Salt Security Research.
- Salt Security, Inc. (2026, July 20). Salt Security Reaches 100 Pre-Built Policies in Policy Hub, Setting New Standard for Agentic AI Governance. Salt Security Press Releases.
- Security Systems Research Group. (2025, July 3). Rethinking Broken Object Level Authorization Attacks Under Zero-Trust API Architectures. arXiv Computer Science Repository.
- Traceable AI & Ponemon Institute. (2025, January 15). 2025 Global State of API Security Report. Traceable AI Research.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the application programming interface (API) security market in 2026 and what is forecast for 2036?
- Which microservice proliferation and AI agent connectivity pressures support demand for API security?
- Why do API Discovery and Inventory Platforms lead the component solution category?
- Why do Cloud-Native SaaS Solutions lead the deployment mode category globally?
- How do growth rates differ across Australia, Canada, and the United Kingdom?
- Which leading companies supply dedicated API posture platforms versus integrated edge WAF gateways today?
- What limits inline blocking enforcement or causes alert fatigue in the API security market?
- What should enterprise security architects evaluate before selecting an out-of-band or inline API protection platform?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Component Solution, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Component Solution, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Component Solution, 2026 to 2036
- API Discovery and Inventory Platforms
- API Vulnerability and Posture Management
- API Runtime Threat Protection
- API Gateway WAF Modules
- Y-o-Y Growth Trend Analysis By Component Solution, 2021 to 2025
- Absolute $ Opportunity Analysis By Component Solution, 2026 to 2036
- Global Market Analysis and Forecast, By Deployment Mode, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Deployment Mode, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Deployment Mode, 2026 to 2036
- Cloud-Native SaaS Solutions
- On-Premises Hybrid Deployments
- Containerized Kubernetes Mesh Sidecars
- Sovereign Cloud Appliances
- Y-o-Y Growth Trend Analysis By Deployment Mode, 2021 to 2025
- Absolute $ Opportunity Analysis By Deployment Mode, 2026 to 2036
- Global Market Analysis and Forecast, By Industry Vertical, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Industry Vertical, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Industry Vertical, 2026 to 2036
- Financial Services and Open Banking
- Healthcare Electronic Health Records
- Retail and Digital Marketplaces
- Telecommunications and Cloud Providers
- Government Public Sector Portals
- Y-o-Y Growth Trend Analysis By Industry Vertical, 2021 to 2025
- Absolute $ Opportunity Analysis By Industry Vertical, 2026 to 2036
- Global Market Analysis and Forecast, By Threat Focus, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Threat Focus, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Threat Focus, 2026 to 2036
- Broken Object Authorization Protection
- Data Exfiltration and PII Prevention
- Automated Bot Scraping Defense
- Credential Token Hijacking Mitigation
- Y-o-Y Growth Trend Analysis By Threat Focus, 2021 to 2025
- Absolute $ Opportunity Analysis By Threat Focus, 2026 to 2036
- Global Market Analysis and Forecast, By Enterprise Size, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Enterprise Size, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Enterprise Size, 2026 to 2036
- Large Enterprise Organizations
- Small and Medium-Sized Enterprises
- Regulated Public Institutions
- Digital-Native Startups
- Y-o-Y Growth Trend Analysis By Enterprise Size, 2021 to 2025
- Absolute $ Opportunity Analysis By Enterprise Size, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- By Country
- Market Attractiveness Analysis
- By Country
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- By Country
- Market Attractiveness Analysis
- By Country
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- By Country
- Market Attractiveness Analysis
- By Country
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- By Country
- Market Attractiveness Analysis
- By Country
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- By Country
- Market Attractiveness Analysis
- By Country
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- By Country
- Market Attractiveness Analysis
- By Country
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- By Country
- Market Attractiveness Analysis
- By Country
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Component Solution
- By Deployment Mode
- By Industry Vertical
- By Threat Focus
- By Enterprise Size
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Salt Security, Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Akamai Technologies, Inc. (Noname Security)
- Traceable AI, Inc. (Harness)
- Cequence Security, Inc.
- Imperva, Inc. (Thales Group)
- Palo Alto Networks, Inc.
- F5, Inc.
- Cloudflare, Inc.
- CrowdStrike Holdings, Inc.
- Fortinet, Inc.
- Salt Security, Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Component Solution, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Industry Vertical, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Threat Focus, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Enterprise Size, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Component Solution, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Industry Vertical, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Threat Focus, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Enterprise Size, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Component Solution, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Industry Vertical, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Threat Focus, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Enterprise Size, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Component Solution, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Industry Vertical, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Threat Focus, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Enterprise Size, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Component Solution, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Industry Vertical, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Threat Focus, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Enterprise Size, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Component Solution, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Industry Vertical, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Threat Focus, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Enterprise Size, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Component Solution, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Industry Vertical, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Threat Focus, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Enterprise Size, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Component Solution, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Industry Vertical, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Threat Focus, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Enterprise Size, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Component Solution, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Component Solution, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Component Solution
- Figure 6: Global Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Deployment Mode
- Figure 9: Global Market Value Share and BPS Analysis by Industry Vertical, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Industry Vertical, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Industry Vertical
- Figure 12: Global Market Value Share and BPS Analysis by Threat Focus, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Threat Focus, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Threat Focus
- Figure 15: Global Market Value Share and BPS Analysis by Enterprise Size, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Enterprise Size, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Enterprise Size
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Component Solution, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Component Solution, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Component Solution
- Figure 32: North America Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Deployment Mode
- Figure 35: North America Market Value Share and BPS Analysis by Industry Vertical, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Industry Vertical, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Industry Vertical
- Figure 38: North America Market Value Share and BPS Analysis by Threat Focus, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Threat Focus, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Threat Focus
- Figure 41: North America Market Value Share and BPS Analysis by Enterprise Size, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Enterprise Size, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Enterprise Size
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Component Solution, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Component Solution, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Component Solution
- Figure 48: Latin America Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Deployment Mode
- Figure 51: Latin America Market Value Share and BPS Analysis by Industry Vertical, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Industry Vertical, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Industry Vertical
- Figure 54: Latin America Market Value Share and BPS Analysis by Threat Focus, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Threat Focus, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Threat Focus
- Figure 57: Latin America Market Value Share and BPS Analysis by Enterprise Size, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Enterprise Size, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Enterprise Size
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Component Solution, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Component Solution, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Component Solution
- Figure 64: Western Europe Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Deployment Mode
- Figure 67: Western Europe Market Value Share and BPS Analysis by Industry Vertical, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Industry Vertical, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Industry Vertical
- Figure 70: Western Europe Market Value Share and BPS Analysis by Threat Focus, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Threat Focus, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Threat Focus
- Figure 73: Western Europe Market Value Share and BPS Analysis by Enterprise Size, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Enterprise Size, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Enterprise Size
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Component Solution, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Component Solution, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Component Solution
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Deployment Mode
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Industry Vertical, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Industry Vertical, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Industry Vertical
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Threat Focus, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Threat Focus, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Threat Focus
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Enterprise Size, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Enterprise Size, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Enterprise Size
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Component Solution, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Component Solution, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Component Solution
- Figure 96: East Asia Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Deployment Mode
- Figure 99: East Asia Market Value Share and BPS Analysis by Industry Vertical, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Industry Vertical, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Industry Vertical
- Figure 102: East Asia Market Value Share and BPS Analysis by Threat Focus, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Threat Focus, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Threat Focus
- Figure 105: East Asia Market Value Share and BPS Analysis by Enterprise Size, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Enterprise Size, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Enterprise Size
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Component Solution, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Component Solution, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Component Solution
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Deployment Mode
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Industry Vertical, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Industry Vertical, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Industry Vertical
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Threat Focus, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Threat Focus, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Threat Focus
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Enterprise Size, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Enterprise Size, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Enterprise Size
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Component Solution, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Component Solution, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Component Solution
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Deployment Mode
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Industry Vertical, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Industry Vertical, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Industry Vertical
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Threat Focus, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Threat Focus, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Threat Focus
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Enterprise Size, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Enterprise Size, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Enterprise Size
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the application programming interface (API) security market in 2026, and what is forecast for 2036?
FMI estimates that the global API security market size stood at USD 1.2 billion in 2025 and reached USD 1.5 billion in 2026. Valuation is projected to hit USD 18.2 billion by 2036.
What is the CAGR for the application programming interface (API) security market from 2026 to 2036?
The application programming interface (API) security sector is projected to expand at a 28.5% CAGR over the 2026 to 2036 window, generating USD 16.7 billion in incremental revenue across global enterprise accounts.
Which component solution segment leads the application programming interface (API) security market?
API Discovery and Inventory Platforms hold an estimated 44.0% of component solution demand in 2026 since continuous traffic inspection is required to catalog undocumented shadow and zombie endpoints.
Which deployment mode segment leads the application programming interface (API) security market?
Cloud-Native SaaS Solutions represent an estimated 68.0% of the deployment mode category in 2026 given that elastic cloud analytics engines correlate multi-gigabit gateway telemetry without hardware bottlenecks.
Which country has a notable growth outlook during the assessment period?
Australia leads national expansion projections at an estimated 30.6% CAGR through 2036, driven by statutory Consumer Data Right open-banking APIs and critical infrastructure cyber defense rules.
Who are the key players in the market?
Salt Security, Akamai Technologies, Traceable AI and Cequence Security lead posture supply. Imperva, Palo Alto Networks and F5 deliver edge protection. Cloudflare, CrowdStrike Holdings and Fortinet secure cloud workloads.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
