

- Market Size (2026)
- USD 6.0 Bn
- Forecast (2036)
- USD 9.4 Bn
- CAGR (2026 to 2036)
- 4.6%
How big is Automotive Tinting Film Market in 2026?
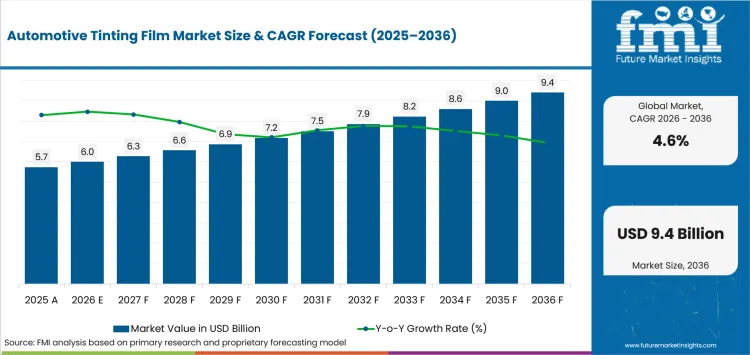
USD 6.0 billion in 2026 and USD 9.4 billion by 2036 at a 4.6% CAGR.
Demand for automotive tinting film is projected to expand at 4.6% CAGR between 2026 and 2036, increasing valuation from USD 6.0 billion in 2026 to USD 9.4 billion by 2036. Purchase conversion depends on cabin heat reduction, UV control and glare management that can be delivered without pushing the finished glass below local visible-light-transmission requirements.
Applied film gives vehicle owners and dealers a retrofit route without replacing glazing. The Skin Cancer Foundation noted in July 2026 that most side and rear glass plus sunroofs are tempered and may leave occupants exposed to UVA, while the UK requires at least 75% light transmission through the front windscreen and 70% through front side windows. These operating conditions make optical performance, legal fit and installer measurement central to repeat demand.
Key Takeaways of Automotive Tinting Film Market
- Cabin heat and UV control support repeat retrofit demand when film performance can be demonstrated on the finished vehicle glass.
- Dyed film is projected at 27.0% of film-type demand in 2026, while Solar Control is estimated at 42.0% by application.
- Passenger Cars are forecast at 72.0% by vehicle type in 2026, with Aftermarket installation estimated at 76.0%.
- Side Windows are projected at 44.0% by window location in 2026.
- Visible-light-transmission rules and discretionary accessory spending can delay adoption even when heat and UV benefits are understood.
- Eastman Chemical Company, 3M Company, Compagnie de Saint-Gobain, LINTEC Corporation, Garware Hi-Tech Films Limited, Madico, Inc., NEXFIL Co., Ltd., XPEL, Inc. and Avery Dennison Corporation serve the market through film technology or installer-facing channels.
Analyst Perspective
"Revenue capture depends on proving film performance on the actual vehicle glass while reducing compliance and installation risk. High-VLT solar-control films can widen the usable product range, but installer education and light-transmission measurement remain essential when buyers compare premium products."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights
How is the Automotive Tinting Film Market segmented?
The automotive tinting film market is segmented by film type, application, vehicle type, installation, window location and region.
Automotive tinting film is segmented by film type, application, vehicle type, installation, window location and region. Film Type covers dyed, metalized, carbon, ceramic and hybrid or other constructions. Application includes solar control, privacy, safety and security, anti-glare, and decorative or other uses. Vehicle Type separates passenger cars from LCVs, HCVs and other vehicles. Installation distinguishes aftermarket from OEM or factory-fitted demand, while Window Location covers side windows, rear windows, windshields and sunroofs.
Why does Solar Control account for 42.0% of the Application category?
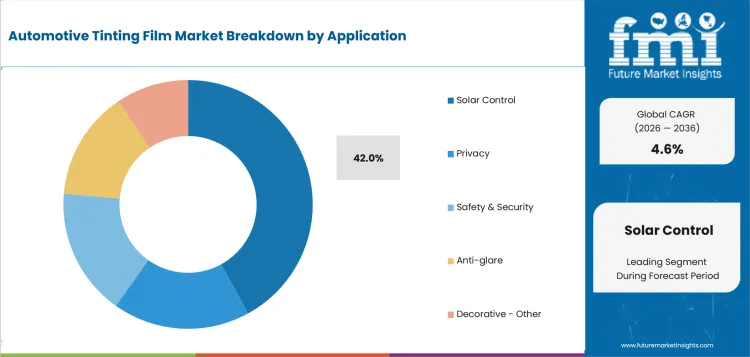
Solar control addresses a practical reason to add film to vehicle glazing by reducing solar energy reaching occupants and interior surfaces. Heat rejection can be combined with glare and UV reduction, allowing suppliers to sell functional performance without relying on very dark tint.
- Solar Control holds 42.0% of the Application category in 2026 because cabin heat and solar-load management create a recurring reason to fit automotive film.
- Garware Hi-Tech Films stated in June 2025 that its safety-glazing film combined light-transmission requirements with heat and UV management, showing how solar control can be packaged with compliance-oriented positioning.
What makes Dyed central to the Film Type category?
Dyed film serves buyers that primarily want shade, privacy or appearance at an accessible price. The construction is familiar to tint installers and supports multiple darkness levels without moving every customer into ceramic or multilayer products, although premium architectures can offer stronger infrared management and color stability.
- Dyed accounts for 27.0% of the Film Type category in 2026, reflecting its role in price-sensitive vehicle tinting and appearance-led purchases.
- LINTEC reported in 2024 that it added a highly transparent WINCOS automotive film with strong near-infrared control, illustrating the performance alternatives available above the price-led dyed tier.
How do Passenger Cars define the Vehicle Type category?
Passenger cars concentrate owner-driven and dealer-driven accessory spending because occupants experience side-window solar load at close range and can make comfort or appearance decisions outside formal fleet procurement. The in-use car population also supports retrofits after the original vehicle sale.
- Passenger Cars account for 72.0% of the Vehicle Type category in 2026 because personal vehicles concentrate comfort, privacy and styling purchases.
- The UK Department for Transport reported in April 2026 that 34.5 million road-using cars were licensed at the end of 2025, illustrating the installed base that can support accessory retrofits.
What supports Aftermarket demand in the Installation category?
Tinting is suited to retrofit because film can be applied to existing windows without replacing the glazing system. Independent installers and dealership accessory departments can sell across new and used vehicles while selecting shades according to the applicable window rules.
- Aftermarket accounts for 76.0% of the Installation category in 2026 because applied film can be fitted across vehicles already in service.
- Eastman reported in January 2026 that performance-film volume was affected by weak discretionary spending in the automotive accessories aftermarket, linking film demand directly to retrofit spending conditions.
What drives Side Windows in the Window Location category?
Side windows combine a large glazed area with direct occupant exposure, supporting solar-control, glare, privacy and appearance use cases. Front and rear side windows can also face different legal requirements, so suppliers need shade ranges that preserve permitted light transmission where rules apply.
- Side Windows hold 44.0% of the Window Location category in 2026 because they combine frequent occupant exposure with multiple functional uses.
- The Skin Cancer Foundation noted in July 2026 that most side and rear glazing plus sunroofs are tempered and may allow UVA exposure, reinforcing the protective use case for side-window film.
What are the drivers, restraints and opportunities in the Automotive Tinting Film Market?
Comfort-led solar and UV control supports demand, while visible-light-transmission compliance and discretionary spending constrain conversion as high-VLT non-metal films create additional compliant use cases.
- Driver: Cabin heat, UV exposure and glare sustain functional demand for automotive window film.
- Restraint: Visible-light-transmission rules, enforcement variation and discretionary accessory budgets can delay or prevent installation.
- Opportunity: High-VLT ceramic and multilayer films can deliver solar performance without relying on very dark tint or conductive metal layers.
Demand starts with exposure through vehicle glazing. Styling can support the purchase, while heat, UV and glare remain the functional triggers. In July 2026, the Skin Cancer Foundation explained that laminated windshields block nearly all UV while most tempered side and rear glass plus sunroofs can allow UVA exposure. Solar-control film gives owners a retrofit method to reduce that exposure and address heat and glare, allowing installers to sell measurable comfort and UV performance to buyers who prefer lighter shades.
The binding friction appears at the final installation decision. Window-tint rules differ by country and can also vary below the national level, so the same film can be acceptable on one window and unlawful on another. The UK specifies minimum light transmission for front glazing, while China applies a high-transmission threshold in the driver-view area. Eastman also linked lower performance-film volume to weak discretionary automotive-accessory spending in January 2026, showing that technical benefit does not remove budget sensitivity.
A commercial opening exists for performance that does not depend on extreme darkness. LINTEC reported in 2024 that it added a highly transparent WINCOS automotive film intended to reduce near-infrared energy while remaining suitable for windshield use. Similar ceramic and multilayer architectures can support heat and UV management where darker tint would narrow legal or customer fit, but suppliers still need clear VLT data and trained installer networks.
Which country CAGRs are profiled in the Automotive Tinting Film Market?
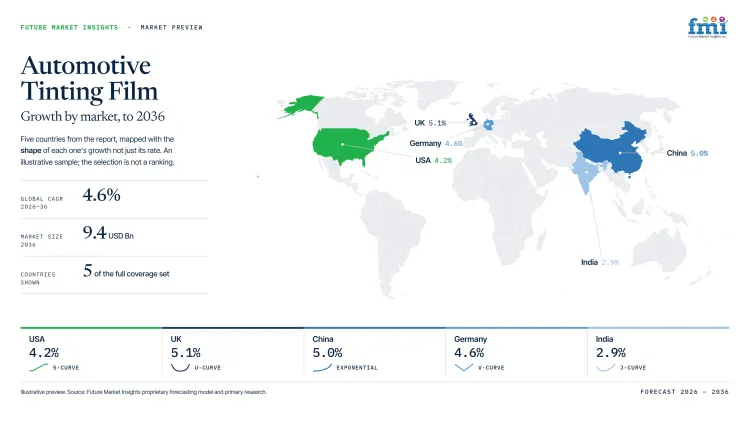
| Country | CAGR |
|---|---|
| USA | 4.2% |
| China | 5.0% |
| India | 2.9% |
| Germany | 4.6% |
| UK | 5.1% |
| Japan | 3.7% |
| Brazil | 4.9% |
How do country-level CAGRs compare in the Automotive Tinting Film Market?
The seven country CAGRs span 2.2 percentage points across different vehicle bases, tint rules and installer channels. The spacing compares expected expansion and does not represent current revenue scale, so market entry decisions still depend on local light-transmission requirements and route-to-market conditions.
- The UK records 5.1% CAGR, 0.1 percentage point above China, supported by a large in-use car base while front-glazing light-transmission limits shape product choice.
- China records 5.0%, 0.1 percentage point above Brazil, with local channel control and high-transmission requirements in the driver-view area influencing compliant product ranges.
- Brazil records 4.9%, 0.3 percentage point above Germany, as solar-control demand operates alongside installed-glass measurement requirements.
- Germany records 4.6%, 0.4 percentage point above the USA, with professional accessory channels and vehicle-approval documentation affecting conversion.
- The USA records 4.2%, 0.5 percentage point above Japan, while state-level tint rules require suppliers and installers to manage shade selection by jurisdiction and window position.
- Japan records 3.7%, 0.8 percentage point above India, with inspection enforcement encouraging high-VLT products and final-transmission verification.
- India records 2.9%, with compliance interpretation and price sensitivity narrowing retrofit conversion even as authorized channels emphasize certified glazing solutions.
Comparable CAGRs can produce different market entry conditions. The full report provides country-level CAGR analysis across North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
Country-wise Analysis
- USA automotive tinting film demand is supported by independent tint shops, dealership accessory programs and a large in-use vehicle base. The market is forecast to rise at 4.2% CAGR from 2026 to 2036. XPEL announced an approximately USD 110 million manufacturing and supply-chain investment in May 2026, while state-level tint rules continue to make shade selection and final VLT verification important for installers.
- China combines distributor and dealer channels with increasing direct local control by international film suppliers. Demand is forecast to expand at 5.0% CAGR from 2026 to 2036. Driver-view glazing requirements call for high light transmission and restrict mirrored reflective sunshade film, so suppliers need non-mirrored ranges and disciplined installation standards.
- India relies on dealer accessory programs and local retrofit shops where compliance confidence can be as important as price. Demand is forecast to rise at 2.9% CAGR from 2026 to 2036. A September 2024 Kerala High Court judgment addressed amended safety-glazing rules, reinforcing the need for certified products, installer documentation and measured light transmission without relying on broad legality claims.
- Germany is served through professional accessory and specialist channels where product approvals and documentation influence buyer confidence. Demand is forecast to expand at 4.6% CAGR from 2026 to 2036. The Kraftfahrt-Bundesamt reported 3.41 million newly registered motor vehicles for 2025, while glazing-location rules continue to shape the usable tint range.
- UK demand benefits from specialist installers and an aging car parc that supports retrofit purchases. The market is forecast to grow at 5.1% CAGR from 2026 to 2036. The Department for Transport reported 42.3 million licensed vehicles at the end of 2025, while front windscreens and front side windows must retain at least 75% and 70% light transmission respectively.
- Japan favors technically documented products and installers that can demonstrate inspection compliance. Demand is forecast to rise at 3.7% CAGR from 2026 to 2036. A transport-ministry enforcement campaign in 2025 reiterated a 70% light-transmission requirement for film on specified front glazing, supporting demand for high-VLT heat-control products.
- Brazil offers a practical solar-control use case through aftermarket channels, but compliance is assessed on the finished glazing. Demand is forecast to expand at 4.9% CAGR from 2026 to 2036. CONTRAN Resolution 960 provides a 70% light-transmission minimum for glazing areas considered indispensable to driving visibility and includes provisions for measurement.
Who are the notable companies in the Automotive Tinting Film Market?
Eastman Chemical Company, 3M Company, Compagnie de Saint-Gobain, LINTEC Corporation, Garware Hi-Tech Films Limited, Madico, Inc., NEXFIL Co., Ltd., XPEL, Inc. and Avery Dennison Corporation are notable companies serving the automotive tinting film market.
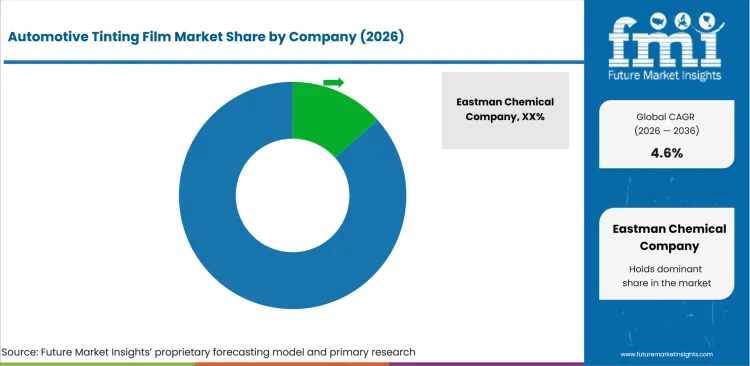
Competition is shaped by film architecture, channel access and installer support. Materials-backed platforms connect automotive tint with broader coating, adhesive or specialty-film capabilities, while specialist manufacturers focus on window-film engineering. Dealer- and distribution-led suppliers place more emphasis on automotive assortments and local installation access. Across these groups, solar and infrared performance must still be balanced with optical quality and light-transmission compliance.
- Eastman Chemical Company, 3M Company, Compagnie de Saint-Gobain and Avery Dennison Corporation combine automotive film portfolios with broader materials or specialty-film capabilities.
- LINTEC Corporation, Garware Hi-Tech Films Limited and Madico, Inc. compete through focused window-film manufacturing and solar-control product engineering.
- NEXFIL Co., Ltd. and XPEL, Inc. pair automotive tint ranges with installer, dealer or distributor access that supports local conversion.
Competitive Benchmarking: Automotive Tinting Film Market
| Company | Solar / IR Film Architecture | High-VLT & Signal-Compatible Range | Installer / Dealer Enablement | Geographic Reach |
|---|---|---|---|---|
| Eastman Chemical Company | High | High | High | North America, Europe, Asia-Pacific and other international markets |
| 3M Company | High | High | High | International commercial markets |
| Compagnie de Saint-Gobain | High | High | Medium | North America, Europe, Asia-Pacific and other Solar Gard markets |
| LINTEC Corporation | High | High | Medium | Japan and international markets |
| Garware Hi-Tech Films Limited | High | High | Medium | India and export markets across multiple regions |
| Madico, Inc. | High | High | High | North America with international distribution |
| NEXFIL Co., Ltd. | High | High | Medium | South Korea, North America and export markets |
| XPEL, Inc. | High | High | High | North America, Europe, China and other Asia-Pacific markets |
| Avery Dennison Corporation | Medium | Medium | Medium | North America, Europe and Asia through Hanita window-film channels |
Scoring basis: Solar / IR Film Architecture measures documented automotive film constructions aimed at heat or infrared control. High-VLT & Signal-Compatible Range measures public evidence of lighter-transmission options and non-metal or signal-compatible products for compliance-sensitive installations. Installer / Dealer Enablement measures documented training and dealer networks, as well as distribution support or other resources that help convert film into a consistent installation. High indicates broad documented capability against the criterion, Medium indicates narrower public evidence, and unavailable public information is left unscored. Geographic Reach records active markets documented by official sources and does not represent each company’s complete corporate footprint.
Key Developments in the Automotive Tinting Film Market
- In May 2026, XPEL, Inc. announced an approximately USD 110 million investment in manufacturing and supply-chain capability, including a four-building San Antonio site totaling approximately 435,000 square feet and acquisition of a manufacturing facility in China.
- In January 2026, Madico, Inc. completed its acquisition of Johnson Laminating & Coating and Johnson Window Films, assuming manufacturing, sales and customer-service responsibilities while retaining the Johnson brand under Madico ownership.
- In June 2025, Garware Hi-Tech Films Limited published safety-glazing film guidance focused on India’s CMVR environment, combining light-transmission requirements with heat management and use through authorized installers with measurement tools.
Key Players in the Automotive Tinting Film Market
Materials-Backed Performance Film Platforms
- Eastman Chemical Company
- 3M Company
- Compagnie de Saint-Gobain
- Avery Dennison Corporation
Specialist Window Film Manufacturers
- LINTEC Corporation
- Garware Hi-Tech Films Limited
- Madico, Inc.
Dealer- and Distribution-Led Automotive Film Specialists
- NEXFIL Co., Ltd.
- XPEL, Inc.
Automotive Tinting Film Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By film type, application, vehicle type, installation, window location and region. |
| Quantitative Units | USD billion. |
| Market Definition | Revenue includes the product value of automotive tinting film sold for application to vehicle glazing across the stated segmentation. It excludes vehicle glass, factory privacy glass without applied film, installation labor, architectural film, windshield-protection film, paint-protection film, vehicle wraps, coatings and downstream vehicle revenue. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | USA, China, India, Germany, UK, Japan, Brazil, and 20+ countries included in the full report. |
| Key Companies Profiled | Eastman Chemical Company, 3M Company, Compagnie de Saint-Gobain, LINTEC Corporation, Garware Hi-Tech Films Limited, Madico, Inc., NEXFIL Co., Ltd., XPEL, Inc. and Avery Dennison Corporation. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Automotive Tinting Film Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from film manufacturers, distributors, installers, dealership accessory teams, fleet or vehicle buyers and subject-matter experts. Interviews examined film architecture, VLT compliance, realized pricing, channel mix, installation practice, replacement behavior and purchase criteria. |
| Desk Research | Desk research covered vehicle-glazing and tint regulation, national vehicle statistics, technical literature, standards, company filings, product information and official corporate announcements. Sources were reviewed for relevance, publication date and consistency with the defined market scope. |
| Market Sizing and Forecasting | The market model combined the baseline value with price and volume relationships, aftermarket and OEM activity, installed vehicle indicators, product mix, country conditions and channel dynamics. Forecast assumptions considered adoption pace, regulation, vehicle mix, product substitution and supplier capacity. |
| Data Validation | Estimates were checked against multiple independent indicators, including regulation, country statistics, company activity and technical evidence. Adjacent categories such as vehicle glass, architectural film, windshield-protection film, paint-protection film, wraps, coatings, installation labor and downstream vehicle revenue were excluded to reduce double counting. |
Automotive Tinting Film Market by Segments
Automotive Tinting Film Market segmented by Film Type:
- Dyed
- Metalized
- Carbon
- Ceramic
- Hybrid / Other
Automotive Tinting Film Market segmented by Application:
- Solar Control
- Privacy
- Safety & Security
- Anti-glare
- Decorative / Other
Automotive Tinting Film Market segmented by Vehicle Type:
- Passenger Cars
- LCVs
- HCVs
- Other Vehicles
Automotive Tinting Film Market segmented by Installation:
- Aftermarket
- OEM / Factory-fitted
Automotive Tinting Film Market segmented by Window Location:
- Side Windows
- Rear Window
- Windshield
- Sunroof
Automotive Tinting Film Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- National Highway Traffic Safety Administration. Federal Motor Vehicle Safety Standard No. 205, Glazing Materials.
- UK Government. Tinted vehicle windows: the law.
- UK Department for Transport. (2026, April 29). Vehicle licensing statistics, United Kingdom: 2025.
- Kraftfahrt-Bundesamt. (2026, January 6). Fahrzeugzulassungen im Dezember 2025 - Jahresbilanz.
- Standardization Administration of China. (2017). GB 7258-2017: Technical Specifications for Safety of Power-driven Vehicles Operating on Roads.
- Supreme Court of India. (2012, August 3). Avishek Goenka v. Union of India & Anr., W.P. (C) No. 265 of 2011.
- High Court of Kerala. (2024, September 10). M/s. George & Sons & Anr. v. Union of India & Ors.
- Ministry of Land, Infrastructure, Transport and Tourism, Hokuriku-Shinetsu District Transport Bureau. (2025, May 30). June enforcement campaign against illegally modified vehicles.
- Conselho Nacional de Trânsito. (2022, May 17). Resolução CONTRAN Nº 960.
- Skin Cancer Foundation. (2026, July 2). Ask the Expert: Car Window Tint for UV Protection.
- XPEL, Inc. (2026, May 19). XPEL Announces Approximately USD 110 Million Manufacturing and Supply Chain Investment.
- Eastman Chemical Company. (2026, January 29). Fourth-Quarter and Full-Year 2025 Financial Results.
- Madico, Inc. (2026, January 21). Madico to Acquire Johnson Window Films.
- Garware Hi-Tech Films Limited. (2025, June 20). CMVR Guidelines for Car Window Films.
- LINTEC Corporation. (2024). LINTEC Integrated Report 2024: Window Film for Buildings and Automobiles.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the Automotive Tinting Film Market in 2026 and 2036?
- Which operating conditions support demand for automotive tinting film across retrofit channels?
- How do film construction and solar-control requirements shape segment demand?
- Why do passenger-car and aftermarket purchases account for a substantial part of market activity?
- How do window-location and sales-channel choices affect installation requirements?
- How do country growth rates interact with visible-light-transmission rules and vehicle-base conditions?
- Which companies serve materials-backed, specialist-manufacturing or installer-facing roles?
- What should buyers evaluate before selecting automotive tinting film for a vehicle?
Frequently Asked Questions
How big is the Automotive Tinting Film Market in 2026?
USD 6.0 billion represents the automotive tinting film market value in 2026. Demand is projected to reach USD 9.4 billion by 2036 as solar-control and UV-management use cases support retrofit purchasing within local glazing rules.
What is the CAGR of the Automotive Tinting Film Market from 2026 to 2036?
A 4.6% CAGR is projected for the automotive tinting film market between 2026 and 2036. Growth depends on installer access and product performance, while visible-light-transmission rules and discretionary accessory budgets affect conversion across countries.
Which application segment is projected to account for 42.0% of the Automotive Tinting Film Market?
Solar Control is projected to account for 42.0% of application demand in 2026. Heat rejection can be combined with UV and glare management, giving buyers a functional reason to install film without depending on a very dark appearance.
How much will the Automotive Tinting Film Market add between 2026 and 2036?
USD 3.4 billion is expected to be added to the automotive tinting film market between 2026 and 2036. The increase depends on retrofit demand, compliant product ranges and installer networks that can verify final glazing performance.
Which companies are active in the Automotive Tinting Film Market?
Ten companies active in the automotive tinting film market include Eastman Chemical Company, 3M Company, Compagnie de Saint-Gobain, LINTEC Corporation, Garware Hi-Tech Films Limited, Madico, Inc., Johnson Window Films, Inc., NEXFIL Co., Ltd., XPEL, Inc. and Avery Dennison Corporation. Their roles span film technology and manufacturing through installer-facing distribution.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Film Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Film Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Film Type, 2026 to 2036
- Dyed
- Metalized
- Carbon
- Ceramic
- Hybrid - Other
- Dyed
- Y-o-Y Growth Trend Analysis By Film Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Film Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Solar Control
- Privacy
- Safety & Security
- Anti-glare
- Decorative - Other
- Solar Control
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Passenger Cars
- LCVs
- HCVs
- Other Vehicles
- Passenger Cars
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis and Forecast, By Installation, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Installation, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Installation, 2026 to 2036
- Aftermarket
- OEM - Factory-fitted
- Aftermarket
- Y-o-Y Growth Trend Analysis By Installation, 2021 to 2025
- Absolute $ Opportunity Analysis By Installation, 2026 to 2036
- Global Market Analysis and Forecast, By Window Location, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Window Location, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Window Location, 2026 to 2036
- Side Windows
- Rear Window
- Windshield
- Sunroof
- Side Windows
- Y-o-Y Growth Trend Analysis By Window Location, 2021 to 2025
- Absolute $ Opportunity Analysis By Window Location, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- By Country
- Market Attractiveness Analysis
- By Country
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- By Country
- Market Attractiveness Analysis
- By Country
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- By Country
- Market Attractiveness Analysis
- By Country
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- By Country
- Market Attractiveness Analysis
- By Country
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- By Country
- Market Attractiveness Analysis
- By Country
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- By Country
- Market Attractiveness Analysis
- By Country
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- By Country
- Market Attractiveness Analysis
- By Country
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Window Location
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Eastman Chemical Company
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- 3M Company
- Saint-Gobain S.A.
- Lintec Corporation
- Garware Hi-Tech Films Limited
- Madico, Inc.
- Nexfil Co., Ltd.
- XPEL, Inc.
- Avery Dennison Corporation
- Eastman Chemical Company
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


