

- Market Size (2026)
- USD 6.2 Bn
- Forecast (2036)
- USD 10.8 Bn
- CAGR (2026 to 2036)
- 5.6%
How big is Collagen Market in 2026?
USD 6.2 billion in 2026 and USD 10.8 billion by 2036 at a 5.6% CAGR.
Collagen demand is projected to push valuation from USD 6.2 billion in 2026 to USD 10.8 billion by 2036 at 5.6% CAGR. Ingredient revenue grows where peptide powders fit familiar dietary supplement formats and give manufacturers a protein-led position consumers already recognize. IFIC reported in July 2025 that 70% of Americans were trying to consume protein. That figure measures protein interest instead of collagen purchasing, but it widens the audience for collagen powders used in daily nutrition formats.
Country rules change how fast interest becomes a marketed collagen supplement and a repeat ingredient order. Destatis reported in March 2025 that 21% of Germans aged 16 to 74 bought medicines or supplements online during 2024. That share rose from 16% in 2021 and gives Germany a measurable digital route for nutraceutical applications. Japan places more work upstream in function-claim evidence and analytical methods, so comparable growth does not imply comparable launch cost.
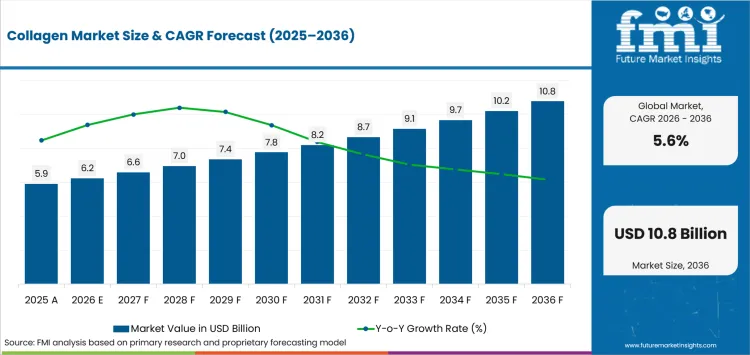
Key Takeaways of Collagen Market
- Supplement brands are extending collagen peptides into nutrition and beauty formats that fit familiar dosing routines and repeat purchasing.
- By form, nutraceuticalus is estimated to hold 24.6% in 2026 owing to flexible dosing options and widely used supplement manufacturing routes.
- In 2026, animal based collagen is expected to lead collagen type with 41.1% share because bovine and porcine feedstocks support commercial-scale processing.
- Based on ingredient type, collagen hydrolysate peptides are projected to account for 66.7% in 2026 due to solubility and broad formulation compatibility.
- Claims restrictions and incomplete manufacturing records can delay launches even after a collagen ingredient passes basic formulation and sensory evaluation.
- Some of the key players in this market include Darling Ingredients Inc., GELITA AG, Nitta Gelatin Inc., Symrise AG, dsm-firmenich, PB Leiner, Lapi Gelatine S.p.A., and CollPlant Biotechnologies Ltd.
Analyst Perspective
"Collagen economics depend on source identity and peptide behavior surviving formulation review before a brand books production. A specification that clears solubility plus documentation review can transfer between powder and gummy programs with less repeat qualification."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Collagen Market segmented?
The collagen market is segmented by form, collagen type, ingredient type, sales channel and region.
Form includes nutraceuticalus, food and beverage, powder, powder1, cosmetics and personal care, tablet pills, liquid and gummies. Collagen type includes animal based collagen, type I, type III, plant based collagen, type II, grain, legumes and vegan collagen. Ingredient type includes collagen hydrolysate peptides, plant yeast and bacteria, gelatin and native. Sales channel includes business to business sales, retail sales, store based retail, online retail, drug stores pharmacy, hypermarkets supermarkets, specialty stores and health and wellness stores.
Why does Animal based collagen lead the Collagen type category?
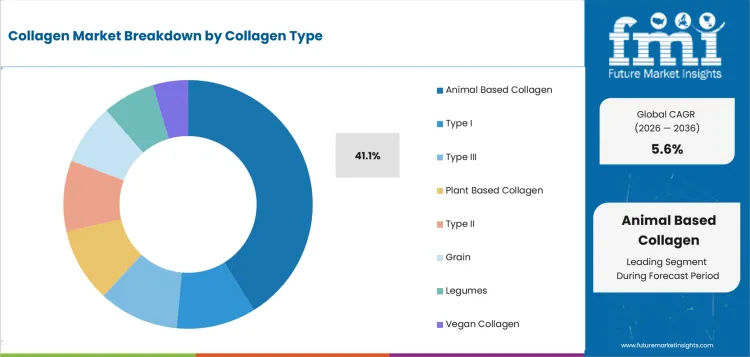
Animal based collagen uses bovine, porcine and fish raw materials already processed through industrial extraction and hydrolysis systems. Marine collagen sources widen source choice, but each origin still requires traceability and sensory review for the intended formula.
- In 2026, animal based collagen is expected to lead collagen type with 41.1% share because commercial bovine and porcine feedstocks support large-scale processing.
- Darling Ingredients announced on April 24 2025 that Rousselot's Peptan peptides received Upcycled Certified status for bovine and porcine production. The certification gives manufacturers a documented sourcing attribute before they qualify animal-derived collagen for supplement and functional-food programs.
What makes Nutraceuticalus central to the Form category?
Nutraceuticalus concentrates collagen demand in formats that let brands control dose before choosing the final consumer presentation. The same ingredient dossier can support several collagen peptide formulations if source identity and peptide specifications stay unchanged during commercial scale-up and routine contract manufacturing.
- By form, nutraceuticalus is estimated to hold 24.6% in 2026 owing to flexible dosing and widely used supplement manufacturing routes.
- The UK Food Standards Agency stated in January 2026 that millions of people regularly take food supplements. That audience gives collagen formulators a familiar purchasing context without removing product-specific evidence and claims review.
How do Collagen hydrolysate peptides shape the Ingredient type category?
Hydrolysis reduces larger collagen proteins into smaller fractions that disperse more easily in powders and liquids. Formulators compare molecular profile, solubility and sensory behavior before transferring one peptide specification into contracted production for protein hydrolysate ingredients.
- Based on ingredient type, collagen hydrolysate peptides are projected to account for 66.7% in 2026 due to high solubility and broad formulation compatibility.
- Japan's Consumer Affairs Agency said in October 2025 that it reviewed analytical methods for 98 Foods with Function Claims filings and requested added material for 69. The review makes analytical-method documentation commercially relevant for hydrolysate manufacturers supporting function-claim products.
What supports Business to business sales within the Sales channel category?
Business to business sales capture collagen value before downstream branding because manufacturers qualify source, solubility and sensory performance at ingredient level. Direct technical exchange is especially important for functional beverage formulations and gummy programs, since small formulation changes can affect scale-up and repeat ordering.
- By sales channel, business to business sales are forecast to represent 35.0% in 2026 attributable to direct specification work and repeat ingredient contracts.
- Lapi Gelatine and Juncà Gelatines expanded their Asian commercial presence in September 2025 with their first joint Bangkok exhibition following an earlier Seoul event. The expansion gave regional formulators direct technical access before committing to qualification work.
What are the drivers, restraints and opportunities in the Collagen Market?
Existing supplement routines lift peptide use, documentation failures delay repeat production and regional technical support can shorten specialized program lead times.
- Driver: Compact collagen formats let brands place defined peptide doses into supplement routines already used for protein and beauty products.
- Restraint: Missing specifications or unsupported claims can stop repeat production even after a collagen formula performs correctly during scale-up.
- Opportunity: Regional storage and technical support can shorten supply lead times for recombinant collagen programs that already meet development requirements.
Compact formats widen collagen use
Compact collagen formats widen the number of supplement routines that one peptide specification can serve without changing the ingredient itself. NIH entered an on-market quick-dissolve collagen peptide powder into the DSLD on June 25 2025. The label records a 12 gram bovine collagen serving in powder form, giving sports nutrition formats a documented commercial example without proving that every user prefers fast-dissolving delivery.
Manufacturing records set the commercial floor
Commercial manufacturing becomes a market restraint if missing records can interrupt release after a formula has cleared scale-up. The FDA warned Hearthy Foods in February 2026 that its collagen supplements lacked required finished-product and component specifications plus complete manufacturing records. A contract manufacturer facing those gaps must complete corrective work before repeat powder or capsule production can become routine.
Regional distribution shortens supply lead times
Specialized collagen programs become easier to schedule after development teams can receive material under controlled storage with complete documentation. CollPlant disclosed in March 2026 that its October 2025 USA logistics partnership gave rhCollagen and BioInk programs cGMP storage and clinical-supply distribution. The USA depot reduces physical supply friction without changing the regulatory and clinical work required before routine commercial use.
Which country CAGRs are profiled in the Collagen Market?
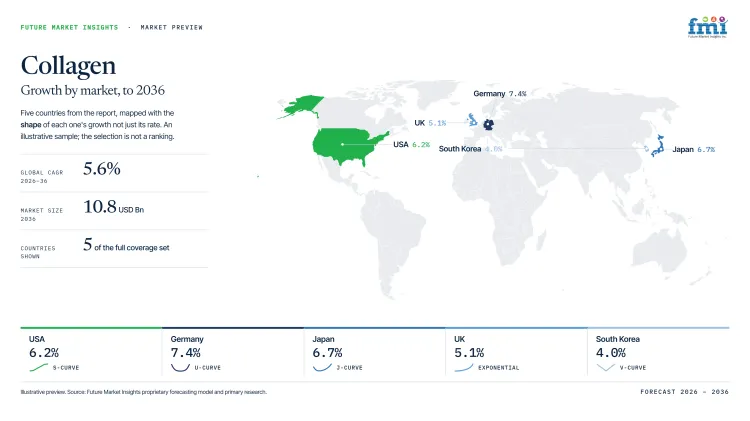
| Country | CAGR |
|---|---|
| Germany | 7.4% |
| Japan | 6.7% |
| USA | 6.2% |
| Netherlands | 5.7% |
| UK | 5.1% |
| Australia | 4.4% |
| South Korea | 4.0% |
How do country-level CAGRs compare in the Collagen Market?
The country outlooks spans 3.4 percentage points from Germany at 7.4% to South Korea at 4.0%. Germany and Japan form the upper group while the USA and Netherlands occupy the middle. The UK, Australia and South Korea grow more slowly because claims systems and supplement-channel maturity change launch economics.
- Germany uses pharmacies and online retail to extend collagen availability beyond beauty stores.
- Japan favors ingestible formats in convenience and drugstore channels after evidence review.
- USA private-label manufacturing lets brands test collagen powders without owning dedicated filling assets.
- Netherlands distribution uses EU logistics and dense parcel networks serving neighboring markets.
- UK pharmacies and online retailers provide mature routes for repeat collagen purchasing.
- Australia’s established supplement use gives collagen brands a broad consumer route without removing listed-medicine claim requirements.
- South Korean functional-food claims put regulatory review ahead of scale-up for collagen peptide programs.
Comparable rates therefore conceal different launch costs and operating demands in each market. The full report provides country-level CAGR analysis across North America, Latin America, Europe, East Asia, South Asia, Oceania and the Middle East and Africa.
Country-wise Analysis
- German collagen supplements enter a market with mature pharmacy and online channels, but notification does not give a brand premarket approval. BfR reported in June 2025 that more than three quarters of surveyed respondents had taken a food supplement during the previous twelve months. Germany is estimated to post 7.4% CAGR over the forecast period, attributable to broad supplement use and specialist retail. Contract manufacturers can turn that audience into powder or capsule orders once formula documentation is complete. Brands still need defensible composition and claims files before they commit national advertising spend or expand beauty-from-within ranges through major German retail groups.
- Japanese collagen brands using Foods with Function Claims must keep ingredient identity and analytical methods aligned with the evidence filed before national retail sale locally. The Consumer Affairs Agency disclosed in June 2026 that 11 of 500 sampled functional foods fell below filed ingredient levels and five were withdrawn nationally. Adoption of collagen in Japan is estimated to expand at 6.7% CAGR through 2036, aided by a national claims route already used for collagen-related functional ingredients. Pharmacy and e-commerce channels give compliant products wide retail access even as post-market sampling raises the cost of weak batch controls after launch nationally.
- USA collagen powders move quickly through contract manufacturing and online retail because brands can launch without owning dedicated extraction or filling assets themselves. NIH entered an on-market bovine collagen peptide powder into the DSLD on March 25 2025 with a 20 gram serving and 18 grams of protein per daily serving. Collagen sales in the USA are forecast to expand at 6.2% CAGR by 2036, propelled by mature supplement retail and broad private-label capacity for branded programs. That infrastructure lets brands test powder and capsule programs rapidly, but FDA inspection can interrupt repeat production if records or specifications fail CGMP review.
- Dutch collagen commerce relies heavily on digital sales, and NVWA found in August 2025 that 25 of 30 collagen-supplement websites used unlawful health or medical claims. The Netherlands collagen sector is projected to record 5.7% CAGR during the assessment period, given efficient parcel networks and access to neighboring EU member markets. Online sales let small brands reach national customers before they secure broad pharmacy or specialty-store distribution, lowering the inventory needed for initial local market entry. NVWA enforcement leaves little room for unsupported promotional copy, so formal legal review must precede paid media or influencer campaigns that depend on health claims.
- UK collagen importers serving supplement channels must match animal-origin paperwork to the exact source route before material reaches contract packers and retailers. Defra and the Animal and Plant Health Agency kept separate certificates for collagen, raw materials and USA-origin collagen on a page updated April 30 2025. UK collagen demand is forecast to rise at 5.1% CAGR over the forecast period, tied to mature pharmacies and online supplement retail. Domestic channel access is therefore less difficult than border documentation for animal-derived material used by supplement brands. Exporters using the wrong certificate can delay inbound ingredients, so source-route control becomes a practical scheduling constraint before formulation work or production booking starts.
- Australia's collagen opportunity sits inside an established supplement routine rather than depending on first-time consumer exposure to ingestible nutrition. ABS reported in September 2025 that 33.6% of Australians used a dietary supplement during 2023, equal to 8.5 million people. That installed consumption base gives collagen brands a ready channel for powders and other daily formats without building supplement behavior from zero. Australian collagen demand is projected to advance at 4.4% CAGR through 2036 as peptide products compete for repeat wellness spending. Orders still depend on listed-medicine rules and substantiated claims when brands move from general protein positioning into specific health benefits.
- South Korean collagen demand depends heavily on whether new functionality claims clear national ingredient review before brands commit formulation work. MFDS reported in November 2025 that low-molecular collagen peptide functionality gained approval during a committee review covering ten agenda items. That decision gives qualified peptide suppliers a clearer route into functional-food concepts that need an accepted claim basis before launch. Collagen sales in South Korea are projected to rise at 4.0% CAGR through 2036 as approved claims convert into branded supplement programs. Commercial use remains tied to source records and local specifications because claim approval does not remove ingredient qualification requirements.
Who are the notable companies in the Collagen Market?
Darling Ingredients Inc.; GELITA AG; Nitta Gelatin Inc.; Symrise AG; dsm-firmenich; PB Leiner; Lapi Gelatine S.p.A.; CollPlant Biotechnologies Ltd.
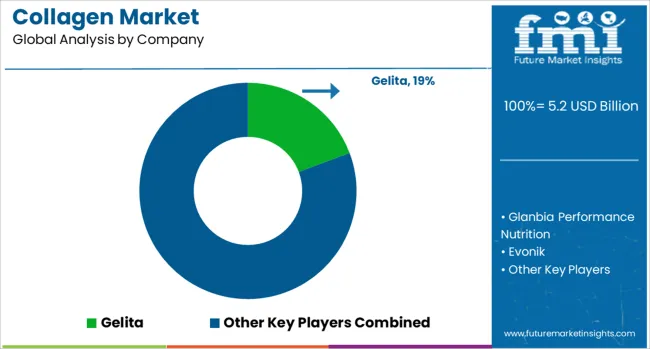
Competition separates integrated gelatin and peptide manufacturing from formulation platforms and recombinant collagen programs. Gelatin applications still reward scale because food and pharmaceutical customers qualify source and processing consistency before repeat ingredient contracts. Bioactive peptides raise the value of application evidence in anti-aging formulations and nutrition programs. CollPlant competes on non-animal rhCollagen for biomedical development, where material identity and controlled supply can outweigh commodity scale.
- Darling Ingredients Inc., GELITA AG and Nitta Gelatin Inc. pair industrial collagen processing with application support for several end-use groups.
- Symrise AG and dsm-firmenich extend collagen into nutrition and beauty programs through formulation partnerships and existing customer channels.
- PB Leiner and Lapi Gelatine S.p.A. supply gelatin and collagen peptides to international ingredient customers. CollPlant Biotechnologies Ltd. concentrates on recombinant collagen for medical development programs that require non-animal material and controlled supply. Marine collagen products add another source route for specialists without removing traceability or specification work during formulation qualification.
Competitive Benchmarking: Collagen Market
| Company | Collagen Portfolio Breadth | Source and Process Control | Application Support Depth | Geographic Reach |
|---|---|---|---|---|
| Darling Ingredients Inc. | High | High | High | Global |
| GELITA AG | High | High | High | Global |
| Nitta Gelatin Inc. | High | High | High | North America, Asia and international sales |
| Symrise AG | Medium | Medium | High | Global |
| dsm-firmenich | Medium | High | High | Global |
| PB Leiner | High | High | High | Europe, Americas and Asia |
| Lapi Gelatine S.p.A. | Medium | High | Medium | Europe and expanding Asia presence |
| CollPlant Biotechnologies Ltd. | Low | High | Medium | North America, Europe and selected Asia markets |
Scoring basis: High portfolio breadth requires at least three documented collagen or gelatin platforms, Medium requires two and Low identifies one. High process control requires owned manufacturing plus multiple source or production routes, Medium reflects one controlled route and Low reflects partner-led access. High application support requires at least three documented end-use groups, Medium requires two and Low identifies one. Geographic reach records documented commercial regions and does not rank company reputation or overall market share.
Key Developments in the Collagen Market
- In February 2026, CollPlant Biotechnologies Ltd. launched BioFlex as a ready-to-print rhCollagen kit for Digital Light Processing 3D bioprinting applications.
- In September 2025, Darling Ingredients Inc. announced patents in Europe, Japan and China for Rousselot's Colartix collagen peptide and chondroitin sulfate matrix.
- In February 2025, Symrise AG partnered with Hofseth BioCare to extend salmon proteins and collagens into human-health and pet-nutrition channels.
Key Players in the Collagen Market
Integrated Gelatin and Collagen Peptide Producers
- Darling Ingredients Inc.
- GELITA AG
- Nitta Gelatin Inc.
- PB Leiner
- Lapi Gelatine S.p.A.
Formulation and Health Ingredient Platforms
- Symrise AG
- dsm-firmenich
Recombinant Collagen Specialists
- CollPlant Biotechnologies Ltd.
Collagen Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By form, collagen type, ingredient type, sales channel and region. |
| Quantitative Units | USD Billion. |
| Market Definition | Commercial collagen ingredients including animal-derived collagen, hydrolyzed peptides, gelatin, native collagen and alternative collagen categories sold into food, supplement, beauty and related applications. |
| Regions Covered | North America, Latin America, Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | Germany, Japan, USA, Netherlands, UK, Australia, and South Korea, and 20+ countries included in the full report. |
| Key Companies Profiled | Darling Ingredients Inc., GELITA AG, Nitta Gelatin Inc., Symrise AG, dsm-firmenich, PB Leiner, Lapi Gelatine S.p.A., CollPlant Biotechnologies Ltd. |
| Forecast Period | Base 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Collagen Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Collagen Market by Segments
Collagen Market segmented by Form:
- Nutraceuticalus
- Food and Beverage
- Powder
- Powder1
- Cosmetics and Personal Care
- Tablet Pills
- Liquid
- Gummies
Collagen Market segmented by Collagen Type:
- Animal Based Collagen
- Type I
- Type III
- Plant Based Collagen
- Type II
- Grain
- Legumes
- Vegan Collagen
Collagen Market segmented by Ingredient Type:
- Collagen Hydrolysate Peptides
- Plant Yeast and Bacteria
- Gelatin
- Native
Collagen Market segmented by Sales Channel:
- Business to Business Sales
- Retail Sales
- Store based Retail
- Online Retail
- Drug stores Pharmacy
- Hypermarkets Supermarkets
- Specialty Stores
- Health and wellness Stores
Collagen Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- International Food Information Council. (2025, July 30). Time To Flex: Bridging The Protein Knowledge Action Gap.
- Statistisches Bundesamt. (2025, March 11). 21 % der 16- bis 74-Jährigen kaufen Arzneimittel oder Nahrungsergänzungsmittel online.
- Food Standards Agency. (2026, January 20). New year, new guidance: FSA helps consumers navigate food supplements safely.
- Darling Ingredients Inc.. (2025, April 24). Rousselot granted Upcycled Certified® status for Peptan® collagen peptides range.
- Consumer Affairs Agency, Japan. (2025, October 14).
- Lapi Gelatine S.p.A.. (2025, September 22). Vitafoods & Food Ingredients Asia 2025: First Joint Booth for Lapi Gelatine and Juncà Gelatines in Asia.
- National Institutes of Health, Office of Dietary Supplements. (2025, June 25). Quick Dissolve Collagen Peptides Unflavored (Label).
- USA Food and Drug Administration. (2026, February 10). Hearthy Foods, Inc. - 712415 - 02/10/2026.
- CollPlant Biotechnologies Ltd.. (2026, March 26). 20-F: Annual and transition report of foreign private issuers.
- German Federal Institute for Risk Assessment. (2025, June 17). Zwischen Hype und Halbwissen: Häufige Irrtümer rund um Nahrungsergänzungsmittel.
- Consumer Affairs Agency, Japan. (2026, June 9).
- National Institutes of Health, Office of Dietary Supplements. (2025, March 25). Collagen Peptides Unflavored (Label).
- Netherlands Food and Consumer Product Safety Authority. (2025, August 11). Ruim 80% webshops misleidt consument met collageenclaims.
- Department for Environment, Food & Rural Affairs and Animal and Plant Health Agency. (2025, April 30). Gelatine and collagen intended for human consumption: model health certificates.
- CollPlant Biotechnologies Ltd.. (2026, February 23). CollPlant Elevates rhCollagen 3D Bioprinting Portfolio with Launch of Ready-to-Print BioFlex.
- Darling Ingredients Inc.. (2025, September 2). Rousselot receives European, Japanese and Chinese patents for Colartix®, a unique hydrolyzed cartilage matrix with science on joint discomfort relief.
- Symrise AG. (2025, February 21). Symrise accelerates in Human Health and Pet Nutrition through a strategic partnership with HBC.
- Darling Ingredients Inc.. (2025, December 10). Darling Ingredients and Tessenderlo Group sign a definitive agreement to form new company to accelerate growth in attractive collagen-based health, wellness and nutrition sector.
- CollPlant Biotechnologies Ltd.. (2025, June 9). COLLPLANT BROADENS ITS COLLABORATION WITH STEMCELL TECHNOLOGIES.
- BASF SE. (2026, June 30). BASF and Bota Biosciences Introduce Bio-Identical Collagen III Powered by AI.
- Evonik Industries AG. (2025, September 16). Evonik launches recombinant collagen VECOLLAN® for use in clinical studies.
- Brenntag SE. (2025, July 1). Brenntag Nutrition signs distribution agreement with Genu-in for collagen peptides and gelatin solution in Asia Pacific.
- Darling Ingredients Inc.. (2026, June 3). Darling Ingredients’ Health Brand Rousselot Receives USA Patent for Nextida® GC, the First Collagen Peptide Composition Supporting Blood Glucose Regulation.
- GELITA AG. (2026, March 3). GELITA and Black Drop Join Forces for Bioink Development.
- Nitta Gelatin NA Inc.. (2025, February 2). Nitta Gelatin India Announces Production Expansion.
- Symrise AG. (2026, March 17). Symrise establishes a new Care & Wellness Division.
- dsm-firmenich. (2025, October 14). dsm-firmenich and Jellice Sign MOU to Jointly Develop Premium Collagen Formulations.
- Tessenderlo Group. (2026, June 15). PB Leiner acquiring remaining minority stake in Brazilian joint venture and closing of the CINIS Fertilizer AB asset transfer agreement within Tessenderlo Kerley International.
- Lapi Gelatine S.p.A.. (2025, January 21). Lapi Gelatine renews ASC Certification. Reinforcing our commitment to Responsible Aquaculture.
- CollPlant Biotechnologies Ltd.. (2025, February 12). CollPlant Biotechnologies Provides a Corporate Update.
- Australian Bureau of Statistics. (2025, September 5). Dietary supplements, 2023.
- Ministry of Food and Drug Safety, Republic of Korea. (2025, November 5). 196th Health Functional Food Review Committee Meeting Results.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the collagen market in 2026 and what value is forecast by 2036?
- Which operating conditions support collagen demand in supplement and beauty applications?
- Why does nutraceuticalus hold 24.6% of the form category in 2026?
- Why does animal based collagen account for 41.1% of the collagen type category in 2026?
- How do collagen hydrolysate peptides shape ingredient purchasing and formulation decisions?
- How do country growth rates differ among Germany, Japan, USA, Netherlands and UK?
- Which companies supply collagen peptides, gelatin, formulation support or recombinant collagen platforms?
- Which quality and claims requirements can delay collagen commercialization?
Frequently Asked Questions
How big is the Collagen Market in 2026?
The collagen market is valued at USD 6.2 billion in 2026 and is projected to reach USD 10.8 billion by 2036. Supplement brands are broadening peptide use in nutrition and beauty formats that fit familiar daily routines.
What is the CAGR of the Collagen Market from 2026 to 2036?
The collagen market is projected to grow at a CAGR of 5.6% between 2026 and 2036. Expansion is supported by wider peptide use in supplements plus application support that lowers repeat formulation work.
Which ingredient type leads the Collagen Market?
The collagen hydrolysate peptides segment is expected to hold 66.7% of the collagen market in 2026, driven by high solubility and broad formulation compatibility. Hydrolysis also lets manufacturers set peptide specifications before choosing the finished product format.
Which form leads the Collagen Market?
The nutraceuticalus segment is estimated to hold 24.6% of the collagen market by form in 2026, attributable to flexible dosing and widely used supplement manufacturing routes. Brands can use one qualified collagen specification in powders, tablets, gummies and liquids.
How much value will the Collagen Market add between 2026 and 2036?
The collagen market is expected to add USD 4.6 billion in value between 2026 and 2036. Added value comes from wider peptide use in supplement and beauty formats plus biomedical demand for specialized collagen materials.
Which countries are projected to record the highest growth in the Collagen Market?
Germany is projected to grow at 7.4% CAGR, followed by Japan at 6.7% and the USA at 6.2% through 2036. Their growth routes differ because retail access, claims systems and manufacturing infrastructure impose different launch requirements.
Which companies are active in the Collagen Market?
Key companies operating in the collagen market include Darling Ingredients Inc., GELITA AG, Nitta Gelatin Inc., Symrise AG, dsm-firmenich, PB Leiner, Lapi Gelatine S.p.A., and CollPlant Biotechnologies Ltd. These companies compete on extraction control, peptide processing, formulation support and recombinant collagen production for defined applications.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form, 2026 to 2036
- Nutraceuticalus
- Food and Beverage
- Powder
- Powder1
- Cosmetics and Personal Care
- Tablet Pills
- Liquid
- Gummies
- Nutraceuticalus
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Collagen Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Collagen Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Collagen Type, 2026 to 2036
- Animal Based Collagen
- Type I
- Type III
- Plant Based Collagen
- Type II
- Grain
- Legumes
- Vegan Collagen
- Animal Based Collagen
- Y-o-Y Growth Trend Analysis By Collagen Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Collagen Type, 2026 to 2036
- Global Market Analysis and Forecast, By Ingredient Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Ingredient Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Ingredient Type, 2026 to 2036
- Collagen Hydrolysate Peptides
- Plant Yeast and Bacteria
- Gelatin
- Native
- Collagen Hydrolysate Peptides
- Y-o-Y Growth Trend Analysis By Ingredient Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Ingredient Type, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Business to Business Sales
- Retail Sales
- Store based Retail
- Online Retail
- Drug stores Pharmacy
- Hypermarkets Supermarkets
- Specialty Stores
- Health and wellness Stores
- Business to Business Sales
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Form
- By Collagen Type
- By Ingredient Type
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Symrise AG
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- DSM-Firmenich
- FrieslandCampina Ingredients
- Corbion N.V.
- Givaudan SA
- Chr. Hansen Holding A/S
- BASF SE
- Darling Ingredients Inc.
- Symrise AG
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


