
- Market Size (2026)
- USD 457.2 Bn
- Forecast (2036)
- USD 737.1 Bn
- CAGR (2026 to 2036)
- 4.9%
How big is the Construction Aggregates Market in 2026?
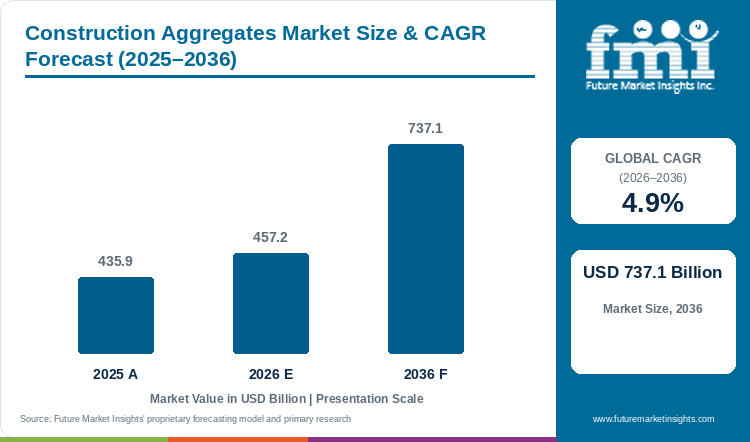
Road, concrete and foundation work is expected to bring the Construction Aggregates Market to USD 737.1 billion by 2036. FMI places 2026 revenue at USD 457.2 billion, with a 4.9% CAGR across 2026 to 2036. The market was valued at USD 435.9 billion in 2025. Crushed Stone holds 46.0% by product type in 2026. Infrastructure accounts for 40.0% by application, and Natural Aggregates represent 92.0% by source in FMI's 2026 assessment.
Road programmes and large civil works set the pace of purchasing. The U.S. Geological Survey recorded about 1.5 billion tonnes of crushed stone worth USD 27.0 billion in 2025. About 72.0% of it was used as construction aggregate. Aggregates Europe collated production of 4,226 million tonnes across 42 European countries in 2024. In South Korea, the Ministry of Data and Statistics reported a 15.9% annual rise in civil engineering work completed for September 2026.
Permitting is the main brake on supply. The U.S. Geological Survey expects zoning limits to move new quarries farther from large population centres and raise urban prices. Heidelberg Materials shows one response. In February 2026 it agreed to buy Maas Group's 40 Australian quarries and over 350 million tonnes of reserves for an enterprise value of AUD 1.7 billion. Completion was expected in the second half of 2026 subject to regulatory approvals. The purchase adds reserves to one network but does not prove rising demand.
Key Market Trends & Insights
- Price is doing more work than volume for large producers. Vulcan Materials' aggregates shipments slipped 3.0% to 62.7 million tons in the September quarter of 2026. Its freight-adjusted price still rose 4.0% to USD 22.8 per ton. Amrize sold 40.1 million tons over the same three months at USD 14.8 per ton, a price rise of 6.6%. Buyers should expect annual price letters even in flat-volume years.
- Reserve purchases are replacing greenfield quarries as the growth route. Martin Marietta completed an asset exchange with QUIKRETE in February 2026 that added aggregates operations producing about 20 million tons a year, then bought New Frontier Materials in May 2026 with over 8 million tons of annual output. The U.S. Geological Survey expects local zoning to move new quarries farther from cities. Permitted reserves near demand therefore carry a premium.
- Recycled and secondary material is becoming a measurable supply line in dense markets. The Mineral Products Association estimates that recycled and secondary sources supplied more than 70 million tonnes in 2024. That was almost one third of Great Britain's aggregates. Aggregates Europe recorded 256 million tonnes of recycled aggregates across 42 countries in 2024. Urban contractors can qualify these grades for fill and sub-base and cut haul distance.
Regional Highlights
- In North America, publicly funded work is holding up demand while housing stays weak. Cemex increased its US aggregates volumes by 4.0% in the third quarter of 2026 and said demand was driven mainly by infrastructure, with residential construction constrained by affordability. Amrize said federally funded multi-year projects partly offset weather losses in the same period. The U.S. Geological Survey notes that federal highway funding under the 2021 law expires at the end of fiscal 2026.
- In Europe, civil engineering is outperforming building work. Eurostat reported EU construction output 2.6% above August 2025 levels in August 2026, with civil engineering up 2.8% and buildings down 4.1%. Aggregates Europe estimates annual demand at about 3 billion tonnes across 15,000 mostly small companies. Producers are consolidating around road programmes. Heidelberg Materials agreed in October 2026 to buy NCC's Swedish and Norwegian aggregates and asphalt operations for about SEK 5.5 billion. The business includes 106 aggregate sites and 44 hot-mix asphalt plants.
Construction Aggregates Market Size and Forecast
Table 1: Construction Aggregates Market Size and Forecast
| Market size and forecast | Value |
|---|---|
| Market size in 2025 | USD 435.9 billion |
| Estimated market size in 2026 | USD 457.2 billion |
| Projected market size by 2036 | USD 737.1 billion |
| CAGR from 2026 to 2036 | 4.9% |
Source: Future Market Insights analysis of the construction aggregates market, 2026.
Analyst Perspective
“Contractors buy aggregates against an approved grading and a delivered cost per tonne, and they rarely change a source once a mix design has passed testing. Suppliers separate themselves through permitted reserves close to the job, a fleet that can meet paving crews on schedule and the ability to bundle asphalt or ready-mixed concrete from the same site. The qualification risk lies in the material itself because a shift in rock type or a contaminated recycled load can fail an abrasion or alkali test and stall a programme until a new source is approved.”
- Nikhil Kaitwade, Principal Consultant, FMI
How is the Construction Aggregates Market segmented?
- By product type: Crushed Stone, Sand, Gravel, and Other Aggregates.
- By application: Infrastructure, Residential Construction, Non-residential Construction, and Other Applications.
- By source: Natural Aggregates and Recycled and Secondary Aggregates.
- By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does Crushed Stone lead by Product Type in the Construction Aggregates Market in 2026?
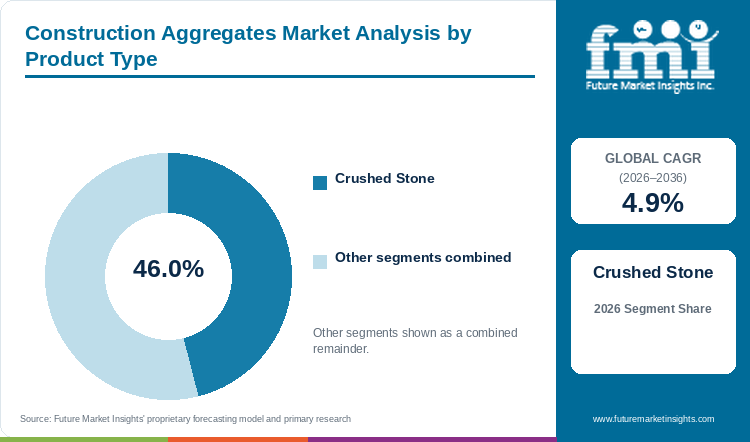
Crushed Stone holds 46.0% of the Construction Aggregates Market by product type in 2026.
Hard rock earns the lead because it serves the most demanding uses and achieves the higher price. The U.S. Geological Survey reported 2025 crushed stone output of about 1.5 billion tonnes against 870 million tonnes of construction sand and gravel. Crushed stone had an average unit value of USD 18.5 per tonne in 2025, while sand and gravel averaged USD 14.5. About 72.0% of crushed stone went to construction aggregate, mostly for road building and maintenance. Specified road base and asphalt stone must be crushed from rock, so natural gravel cannot be used for that work.
Europe shows the same balance. Aggregates Europe recorded 2,116 million tonnes of crushed rock against 1,714 million tonnes of sand and gravel across 42 countries in 2024. Limestone and dolomite made up about 70.0% of United States crushed stone output in 2025. Rock type decides crushing energy and screen wear, which is why producers protect reserves of proven stone.
Sand, Gravel and Other Aggregates together hold the remaining 54.0% by product type. Sand demand follows concrete and mortar volumes. The U.S. Geological Survey found that 42.0% of construction sand and gravel went into portland cement concrete in 2025 and 20.0% into road base. Sand and gravel pits are often closer to housing sites than hard-rock quarries, which keeps their haul costs low.
Table 2: Product Type, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Crushed Stone | 46.0% |
| All Other Segments Combined Share | 54.0% |
Source: Future Market Insights analysis of the construction aggregates market, 2026.
Why does Infrastructure lead by Application in the Construction Aggregates Market in 2026?
Infrastructure accounts for 40.0% of the Construction Aggregates Market by application in 2026.
Roads, rail and water works consume stone in volumes that no single building can match. Martin Marietta attributed its 2.3% organic shipment growth in the second quarter of 2026 to infrastructure and heavy non-residential demand. Vulcan Materials states that about 40.0% to 55.0% of its aggregates shipments have historically gone into publicly funded construction. Cemex named infrastructure as the main driver of its US demand for July to September 2026. Public contracts are also multi-year, which gives quarries a schedule to plan around.
Public spending is holding where housing has slipped. In Great Britain, the Mineral Products Association reported that infrastructure-linked demand proved more resilient in the first half of 2026 while mortar sales fell to a two-year low. Korean civil engineering output for September 2026 was 15.9% higher than a year before, against a 7.7% drop in building work. Stone for paving is assessed separately in FMI's road aggregates market study.
Residential Construction, Non-residential Construction and Other Applications together represent the remaining 60.0%. Building demand is more dispersed and stops faster when starts are deferred. Amrize reported that weather cut its cement and aggregates volumes over July to September 2026 while public multi-year projects held up. Housing recovery would add sand and concrete stone to that base.
Table 3: Application, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Infrastructure | 40.0% |
| All Other Segments Combined Share | 60.0% |
Source: Future Market Insights analysis of the construction aggregates market, 2026.
Why do Natural Aggregates lead by Source in the Construction Aggregates Market in 2026?
Natural Aggregates represent 92.0% of the Construction Aggregates Market by source in 2026 in FMI's 2026 assessment.
Quarried rock and dredged sand still supply almost all tonnage because specifications favour them. Aggregates Europe recorded 256 million tonnes of recycled aggregates and 65 million tonnes of manufactured aggregates against 3,905 million tonnes of crushed rock, sand, gravel and marine material across 42 countries in 2024. United States recycled material counted in crushed stone statistics was 37 million tonnes in 2025, against 1.5 billion tonnes of primary output. The U.S. Geological Survey adds that the share of total aggregate supplied by recycled materials remained very small in 2025. Recycled grades also sell at lower prices, which lowers their revenue share further.
Recycled and Secondary Aggregates hold the remaining 8.0% by source. Their weight is highest in dense markets with demolition feedstock. British recycled and secondary supply exceeded 70 million tonnes in 2024 by the Mineral Products Association's estimate, close to a third of the market. The association also notes that its recycling figures rest on a government-backed survey from almost two decades ago. Feedstock flows for this route are covered in the construction waste market.
Table 4: Source, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Natural Aggregates | 92.0% |
| All Other Segments Combined Share | 8.0% |
Source: Future Market Insights analysis of the construction aggregates market, 2026.
What are the key drivers restraints and opportunities?
Aggregates revenue follows the tonnage of concrete and pavement laid within trucking distance of a permitted site. The same local economics that reward a well-placed quarry make distant reserves hard to sell.
Driver
Public road and civil budgets keep orders flowing when private building slows. The U.S. Geological Survey records USD 56.8 billion authorised for Federal-Aid Highway Programs in fiscal 2026. New Zealand's National Infrastructure Pipeline projected NZD 18.6 billion of spending in the 12 months from July 2026, with transport accounting for NZD 9.6 billion of that total. Japan's Ministry of Land, Infrastructure, Transport and Tourism expects civil engineering investment of JPY 28.5 trillion in fiscal 2026, up 1.8%. Each programme converts into graded stone orders once contracts are let.
Restraint
Haul cost and permitting limit how far a quarry can reach. Vulcan Materials' freight-adjusted unit cash cost climbed 7.0% over July to September 2026, and the rise was 3.0% once higher diesel is stripped out. The U.S. Geological Survey expects local zoning and land-development constraints to cause regional shortages and above-average price increases in urban areas. British producers were mothballing sites and deferring investment after a fourth year of falling demand in 2025, according to the Mineral Products Association. Mothballed capacity takes time and money to restart.
Opportunity
Integrated supply of aggregates with asphalt or concrete wins tenders that stone alone cannot. Heidelberg Materials' agreed purchase of NCC's Nordic operations pairs 106 aggregate sites with 44 hot-mix asphalt plants. Its Maas Group agreement in Australia pairs 40 quarries with 22 ready-mixed concrete plants. Producers that can supply a paving crew and a concrete pour from one network reduce the buyer's logistics risk. Concrete demand itself is tracked in the ready-mix concrete market. The gain depends on local permits and on keeping downstream plants supplied from the same reserves.
How do permitting rules and public funding decisions affect construction aggregates supply?
Quarry permits set the geography of supply. The U.S. Geological Survey reports that producers continued to address permitting and zoning issues and environmental restrictions in 2025. It expects new quarries to be sited farther from large population centres as a result. Heidelberg Materials' Australian acquisition needs approval from the Australian Competition and Consumer Commission and the Foreign Investment Review Board before it can close. Its NCC purchase in Sweden and Norway is also subject to approval by the relevant authorities.
Funding rules decide the timing of orders. The United States highway authorisation under the 2021 law expires at the end of fiscal 2026. The Mineral Products Association cited the cancellation of further major road schemes in Great Britain as a source of uncertainty in 2026. Korean public construction orders were 5.4% lower in September 2026 than a year earlier, while private orders jumped 62.1%. Producers that track budget cycles can position stockpiles before contracts are let.
What limits reliable construction aggregates supply and quality?
Transport sets the practical radius of each site. Vulcan Materials separates its freight-adjusted price from delivered cost, and diesel drove most of the 7.0% rise in its unit cash cost in the latest quarter. The U.S. Geological Survey expects prices to rise most in and near metropolitan areas where reserves are scarce. Buyers in those cities face a choice between longer hauls and recycled grades.
Capacity follows confidence. British heavyside materials demand was heading for a fifth straight annual fall in 2026 in the Mineral Products Association's October outlook, with no growth seen in 2027 and recovery unlikely before 2028. Its chief executive said there was currently zero confidence to invest in people, sites or equipment for the future. Quality control adds a second limit. Limestone and dolomite made up about 70.0% of United States crushed stone output in 2025, and rock type decides which asphalt and concrete mixes a quarry can serve. A change of pit requires new test approvals before deliveries can start.
Where can producers win additional business?
Producers can grow through bolt-on reserves, recycled grades and downstream products. Rogers Group announced an agreement in March 2026 to buy Rockydale Quarries, adding ten Virginia locations to its network. Amrize completed its purchase of Rapid Redi-Mix in Dallas-Fort Worth during the third quarter of 2026 and said its recent acquisitions were exceeding expectations. In Britain, recycled and secondary material already meets close to a third of demand. Admixtures that let concrete producers use manufactured sand are covered in the construction chemicals market. Each route needs its own pricing so that recycled grades do not undercut specified stone from the same yard.
Construction Aggregates Market by Country (2026 to 2036)
Table 5: Construction Aggregates Market Country Growth Forecast
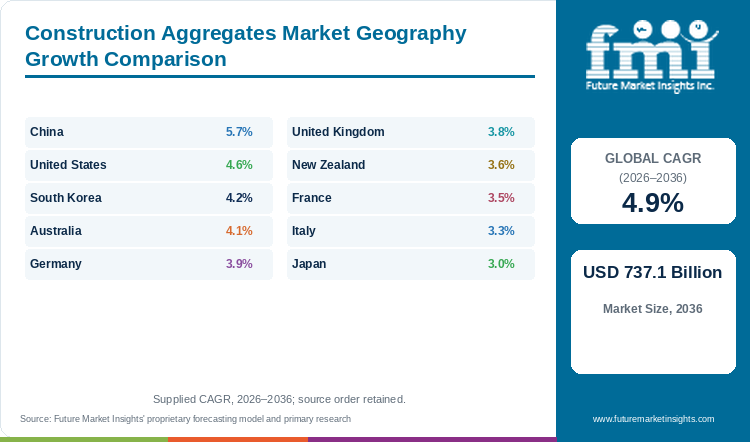
| Country | CAGR, 2026 to 2036 |
|---|---|
| China | 5.7% |
| United States | 4.6% |
| South Korea | 4.2% |
| Australia | 4.1% |
| Germany | 3.9% |
| United Kingdom | 3.8% |
| New Zealand | 3.6% |
| France | 3.5% |
| Italy | 3.3% |
| Japan | 3.0% |
Source: Future Market Insights analysis of the construction aggregates market, 2026.
China
China enters the forecast period from a depressed base in both housing and public works. Real estate development investment came to CNY 5,336.4 billion over January to September 2026, a fall of 20.6% on the prior-year period. Floor space of newly started buildings fell 24.9% over the same nine months. Fixed asset investment fell 7.2%, with infrastructure investment down 4.2% and road transportation investment down 9.9%. Cement output of 144.0 million tonnes in September 2026 was 5.3% lower than a year earlier.
That base matters for the outlook. Aggregate tonnage in 2026 remains well below the levels that quarries and sand plants were built to serve, so recovery can raise sales without new capacity. Starting from this trough gives China the fastest rate in the profiled group, with revenue compounding at 5.7% a year between 2026 and 2036. Public works are not yet a cushion. Road investment fell 9.9% and water conservancy investment fell 14.4% in the first nine months, both worse than total infrastructure.
Suppliers should not read the forecast as a return to the apartment boom. Residential investment fell 20.5% and residential floor space sold fell 13.8% in the first nine months of 2026. Quarries tied to provincial road and water schemes will see orders first once those budgets restart. Plants that served speculative housing in smaller cities face a longer wait. Pricing power will depend on how many sand and stone permits provincial authorities renew during the downturn, since idle capacity usually returns before new sites are approved.
United States
Supply in the United States is spread across about 1,400 companies running 3,500 crushed stone quarries and 3,400 companies running 6,500 sand and gravel pits. Output was about 1.5 billion tonnes of crushed stone and 870 million tonnes of sand and gravel in 2025. Producer value was USD 27.0 billion for crushed stone and USD 12.6 billion for sand and gravel. Shipments were flat to slightly lower, yet the average unit value of crushed stone rose from USD 17.5 to USD 18.5 per tonne.
Public money is the stabiliser. Highway construction spending in the first eight months of 2025 was 25.0% below the same period of 2024, but third-quarter crushed stone shipments rose 7.0% year on year. Between 40.0% and 55.0% of Vulcan's aggregates have historically ended up in public projects such as highways and airports. Cemex grew US aggregate sales volume by 4.0% in its latest quarter on infrastructure demand while housing stayed constrained.
Consolidation and pricing shape the US outlook, which FMI sets at 4.6% compound annual growth across 2026 to 2036. Martin Marietta added about 20 million tons of annual aggregates output through its QUIKRETE exchange and over 8 million tons through New Frontier Materials in 2026. Vulcan completed two bolt-on purchases in Tennessee and southern Ohio in the third quarter and plans mid- to high-single-digit price gains for 2027. The risk to watch is the September 2026 expiry of the current federal highway authorisation. A funding lapse would delay lettings in the states most dependent on federal money.
South Korea
Korean quarries are watching a wide split between orders and site activity. Orders received in September 2026 were 49.8% above the same month of 2025, and civil engineering orders climbed 84.5%. Yet the real value of work done sat 1.6% under its September 2025 level, even after a 5.8% gain on August. Orders become stone demand only after design approval and groundworks begin.
The mix within those figures favours aggregates. Civil engineering output was up 15.9% on the year while building work fell 7.7%. Civil projects use more base stone and ballast per won of contract value than apartment towers. The private sector is funding the upturn, with private orders up 62.1% and public orders down 5.4%. Private clients tend to award in bursts, so quarries need the fleet flexibility to serve several sites at once.
As that backlog turns into site work, Korean aggregates revenue can compound at 4.2% a year from 2026 to 2036. The country's metropolitan corridors already have dense supply, so growth will come from transport upgrades and utility works where civil orders have already been placed. Producers that can deliver compactable sub-base and ready-mixed coarse material on short notice will be first in line for the new work. If private orders cool before public budgets step back in, quarries would be left with capacity opened for projects that slip into later years.
Australia
Australian quarrying is being reshaped by one large transaction. In February 2026 Heidelberg Materials signed up to buy the construction materials arm of Maas Group in New South Wales, Queensland and Victoria. The assets comprise 40 quarries with reserves of over 350 million tonnes and 22 ready-mixed concrete plants. Two asphalt operations and a recycling site are included at an enterprise value of AUD 1.7 billion. Completion was expected in the second half of 2026 subject to competition and foreign investment approvals.
Demand is split between building and engineering cycles. The Australian Bureau of Statistics reported total construction work done of AUD 82.5 billion in the June quarter of 2026, down 2.1% on the quarter but 2.7% higher than a year earlier. Building work rose 1.3% to AUD 45.8 billion while engineering work fell 6.0% to AUD 36.7 billion. Residential building grew 9.1% year on year. Housing therefore drove the quarter while civil work paused.
Reserve access along the eastern seaboard explains why Australia has a 4.1% CAGR from 2026 to 2036 in FMI's assessment. Growth corridors around Sydney, Brisbane and Melbourne need long-life quarries within trucking range. The Maas reserves are located in those three states. An engineering recovery would add volume on top of the housing base. The qualification for buyers is that integration of 40 quarries into a new owner takes time, and supply contracts signed with Maas will be reviewed as the deal completes.
Germany
German demand moves with housing permits and public works orders. The Federal Statistical Office reported 169,400 dwellings approved in the first eight months of 2026, a rise of 12.1% on the same period of 2025. Permits for multi-family buildings rose 14.5% to 90,600. August alone brought 20,600 approvals, up 6.8%. Permits precede foundations by months, so sand and concrete stone orders follow later.
Civil engineering is the softer side. Destatis data show real orders in the main construction trades down 9.2% in July 2026 against June and 1.9% against July 2025. Civil engineering orders were 2.2% lower than a year before. Real turnover still rose 4.6% on the year in July. Eurostat measured German construction output 10.5% higher in August 2026 than twelve months earlier. The industry association MIRO estimates annual demand for natural stone, sand, gravel and quartz sand at around 500 million tonnes.
Permit growth of this size helps explain why German demand is modelled to rise at a 3.9% CAGR over 2026 to 2036. Sand and gravel suppliers near the large cities benefit first because multi-family housing is concentrated there. Civil contractors will need base stone as road and rail orders recover from the July dip. The restraint is distance, since many German pits are inland and serve a short radius. Producers close to metropolitan redevelopment can hold prices, while remote sites compete on freight and face thinner margins.
United Kingdom
Britain's aggregates producers are rebuilding from historic lows. Concrete, aggregates and asphalt demand fell in 2025 for the fourth year running, and aggregates sales dropped 1.6% according to the Mineral Products Association. Between the first and second quarters of 2026 crushed rock sales fell 3.3% and sand and gravel fell 1.6%. Asphalt rose 2.0% over the same period. The association attributed stable crushed rock volumes in the first half to local road maintenance activity.
The association now expects a fifth year of decline in 2026, no growth in 2027 and a meaningful recovery not before 2028. Infrastructure projects such as HS2, Sizewell C, offshore wind and grid connections are supporting demand but cannot offset weak housebuilding. Recycled and secondary sources added more than 70 million tonnes in 2024, which the association counts as almost a third of the market.
A 3.8% CAGR for the United Kingdom across 2026 to 2036 therefore rests on recovery from a low base and not on a strong current market. Energy generation and water projects are expected to support activity in the East of England, Wales and Scotland. The commercial problem is capacity. Sites have already been mothballed and investment deferred during the downturn. Producers that keep permitted capacity open through 2027 will be positioned when housing and road schemes return. Buyers should expect tighter local supply in regions where quarries have closed.
New Zealand
New Zealand has a funded pipeline and a volatile housing signal. The National Infrastructure Pipeline reached NZD 290.0 billion of initiatives in June 2026, with NZD 18.6 billion of projected spending in the 12 months from July 2026. Transport accounts for NZD 9.6 billion or 46.0% of that spending. Water projects add NZD 4.7 billion. Roads and water networks are the most aggregate-intensive categories in that list.
Housing is less steady. New dwelling consents dropped 7.9% in September 2026 on a seasonally adjusted basis, reversing a 5.3% gain in August according to Stats NZ. Fletcher Building saw volumes recover gradually in the six months to June 2026 but does not expect a meaningful pick-up in underlying volumes before calendar 2027. Its continuing operations earned NZD 414.0 million of EBIT before significant items in fiscal 2026, a group figure that spans more than aggregates.
New Zealand's outlook of 3.6% annual growth from 2026 to 2036 leans on the transport programme more than on housing. Quarry operators near Auckland and Canterbury serve both, and they will need to balance contract paving orders against intermittent subdivision work. Haul distance into Auckland is the main cost variable for suppliers there. Recycled concrete from demolition can shorten hauls into the city, though specification limits its use to fill and sub-base. Producers with consented reserves and rail or barge access will hold the advantage.
France
French construction output is contracting faster than the European average. INSEE data placed the June to August 2026 total 5.0% under the matching period a year before. Civil engineering was 8.2% lower on the same basis, although it rose 1.2% in August alone. Eurostat's August 2026 release showed France with the largest annual fall among member states, at 7.8%.
Producers are reshaping their networks in response. Cemex entered exclusive negotiations in 2026 to sell certain concrete and aggregates operations in south-east France to Vicat, subject to employee consultation and regulatory approval. Cemex also reported aggregates volumes in its Europe, Middle East and Africa region down 8.0% in the third quarter of 2026 with prices up 7.0% in dollar terms. Volume is being traded for price across the region.
Against that backdrop, the French forecast of 3.5% a year through 2026 to 2036 assumes civil engineering orders return gradually before any rebound in housing. Road rehabilitation and municipal works remain the steadiest outlets for graded stone. Sand demand from concrete producers will stay soft until building starts recover. Producers with short-haul access to Lyon, Marseille and the Paris region can protect margins through consistent grading and delivery discipline. Ownership changes in the south-east will also alter which supplier serves which contractor.
Italy
Italian output is slipping after a firm start to 2026. The seasonally adjusted ISTAT construction index lost 2.9% between July and August 2026. The calendar-adjusted index was 2.2% below August 2025. Output in the three months to August was 3.2% lower than the previous three months. For the first eight months of 2026 the index was still 1.2% higher than a year earlier. Raw output in August even rose 2.3% on the year, helped by one extra working day. Buyers reading monthly headlines should check which adjustment the figure uses before changing call-off volumes.
Eurostat placed Italy among the largest monthly decreases in August 2026 at 2.9%. Italian demand for aggregates follows road rehabilitation and building renovation more than large new programmes. Mountain terrain and dense settlement lengthen hauls and raise delivered costs. Alluvial pit quality also differs from valley to valley, so washing and screening capacity decides which uses a producer can serve.
Italy ranks second from the bottom of the profiled group, with growth of 3.3% a year modelled for 2026 to 2036. The cumulative gain through August 2026 shows activity still above the prior year even as the monthly trend turned down. Transport rehabilitation contracts will be the main source of graded stone demand. Crushed demolition concrete can win sub-base work once its grading passes the tender tests. Producers should plan for uneven monthly offtake and keep stockpiles sized to contract schedules instead of national statistics.
Japan
Japanese aggregates demand is tied to a mature investment cycle. MLIT, the national construction ministry, expects nominal construction investment to grow 2.9% to JPY 81.5 trillion in fiscal 2026. Government investment of JPY 26.6 trillion is expected to grow 0.6% while private investment of JPY 54.9 trillion grows 4.1%. Civil engineering investment of JPY 28.5 trillion is expected to rise 1.8%, slower than the 3.5% gain in building.
Those splits explain the lowest rate in the group, a 3.0% CAGR for Japan from 2026 to 2036 in FMI's assessment. Growth in nominal investment is partly price, and public civil budgets are close to flat in real terms. Stone demand therefore comes from renewal of roads, ports and flood defences instead of network expansion. Orders are frequent but small, and each delivery point may need a tightly graded asphalt stone.
The commercial advantage lies in logistics and certification. Urban haul routes are constrained, so suppliers to Tokyo and Osaka compete on delivery scheduling as much as on price. Concrete for high-durability structures faces alkali reactivity testing that limits substitution among sources. Producers that hold approved status with major contractors and can meet night-time delivery windows will keep their volumes. Private building investment growing faster than public works means that housing and commercial contractors will set the pace of sand and concrete stone demand through the forecast period.
Who are the notable companies in the Construction Aggregates Market?
Vulcan Materials, Martin Marietta, Heidelberg Materials and CRH show the main competitive positions in this market. Vulcan runs an aggregates-led model in the United States and moved 62.7 million tons in its September quarter at a freight-adjusted price of USD 22.8 per ton. Martin Marietta shipped 61.6 million tons in the second quarter of 2026 and has added reserves through the QUIKRETE exchange, New Frontier Materials and the Lhoist North America combination completed in August 2026. Both companies price aggregates separately from freight.
Heidelberg Materials is buying integrated networks. Its 2026 agreements cover 40 quarries and 22 concrete plants in Australia and 106 aggregate sites with 44 asphalt plants in Sweden and Norway. It also completed the purchase of BURNCO Rock Products' main assets in Canada on 1 April 2026. CRH reported USD 1.4 billion spent on 17 acquisitions year to date with its second-quarter 2026 results and agreed to buy Arcosa for USD 8.5 billion, subject to approvals.
The remaining players occupy distinct territories. Amrize became an independent North American company after Holcim completed its spin-off in June 2025, and its aggregates sales reached 40.1 million tons for July to September 2026. Holcim now operates in 45 markets across Europe, Latin America and Asia, Middle East and Africa. Cemex is trimming its portfolio, with concrete and recycled concrete assets sold in Atlanta and negotiations to sell south-east French operations to Vicat. Rogers Group serves 13 states from quarries, asphalt plants and sales yards. Fletcher Building returned to profit in fiscal 2026 and said its core manufacturing divisions performed well in a difficult trading environment. Buyers should compare delivered cost, reserve life and downstream integration before company size.
Key Developments in the Construction Aggregates Market
- On 3 March 2026, Rogers Group announced an agreement to acquire Rockydale Quarries Corporation of Roanoke, Virginia, with ten locations including B&S Contracting, and closing was expected on 10 April 2026.
- On 15 May 2026, Martin Marietta completed the acquisition of New Frontier Materials, an aggregates business in the greater St. Louis area producing over 8 million tons a year.
- On 7 October 2026, Heidelberg Materials signed a binding agreement to acquire NCC's Swedish and Norwegian aggregates and asphalt operations, covering 106 aggregate sites and 44 hot-mix asphalt plants, for about SEK 5.5 billion subject to approvals.
Key Players in the Construction Aggregates Market
- Heidelberg Materials AG
- Vulcan Materials Company
- Martin Marietta Materials, Inc.
- CRH plc
- Holcim Ltd
- Amrize Ltd
- Cemex, S.A.B. de C.V.
- Rogers Group, Inc.
- Fletcher Building Limited
Construction Aggregates Market Report Scope
Table 6: Construction Aggregates Market Report Scope
| Coverage field | Report scope |
|---|---|
| Market definition | Revenue from the production and sale of crushed stone, sand, gravel and recycled or secondary aggregates for construction use. Cement, ready-mixed concrete and asphalt sold as finished products are excluded. |
| Product Type | Crushed Stone; Sand; Gravel; Other Aggregates |
| Application | Infrastructure; Residential Construction; Non-residential Construction; Other Applications |
| Source | Natural Aggregates; Recycled and Secondary Aggregates |
| Regions covered | East Asia, South Asia and Pacific, Western and Eastern Europe, North America, Latin America, and the Middle East and Africa |
| Profiled markets | Australia, China, France, Germany, Italy, Japan, New Zealand, South Korea, United Kingdom, United States |
| Companies covered | Heidelberg Materials AG; Vulcan Materials Company; Martin Marietta Materials, Inc.; CRH plc; Holcim Ltd; Amrize Ltd; Cemex, S.A.B. de C.V.; Rogers Group, Inc.; Fletcher Building Limited |
| Analytical subjects | Reserve access and permitting, delivered cost and freight, public funding cycles, integration with asphalt and concrete, recycled supply |
| Quantitative Units | USD billion |
Source: Future Market Insights analysis of the construction aggregates market, 2026.
Construction Aggregates Market Research Methodology
The construction aggregates assessment draws on national mineral statistics, trade association sales surveys, construction output indices and producer disclosures. FMI measures annual revenue earned by producers from the sale of crushed stone, sand, gravel and recycled or secondary aggregates. Segment values are classified by product type, application and source. Country forecasts reflect local construction activity, public funding, reserve access and freight economics over the same 2026 to 2036 period. Tonnage, unit value and revenue are reviewed as separate measures.
Construction Aggregates Market by Segments
Construction Aggregates Market segmented by Product Type:
- Crushed Stone
- Sand
- Gravel
- Other Aggregates
Construction Aggregates Market segmented by Application:
- Infrastructure
- Residential Construction
- Non-residential Construction
- Other Applications
Construction Aggregates Market segmented by Source:
- Natural Aggregates
- Recycled and Secondary Aggregates
Construction Aggregates Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Geological Survey. (2026, February). Mineral Commodity Summaries 2026: Stone (Crushed). U.S. Department of the Interior.
- [2] U.S. Geological Survey. (2026, February). Mineral Commodity Summaries 2026: Sand and Gravel (Construction). U.S. Department of the Interior. https://pubs.usgs.gov/periodicals/mcs2026/mcs2026-sand-gravel.pdf
- [3] Vulcan Materials Company. (2026, October 29). Vulcan Reports Third Quarter 2026 Results. Form 8-K Exhibit 99.1, U.S. Securities and Exchange Commission. https://www.sec.gov/Archives/edgar/data/1396009/000114036126041095/0001140361-26-041095.txt
- [4] Vulcan Materials Company. (2026). Form 10-Q for the quarter ended September 30, 2026. U.S. Securities and Exchange Commission. https://www.sec.gov/Archives/edgar/data/0001396009/000162828026068102/vmc-20260930.htm
- [5] Martin Marietta Materials, Inc. (2026, July 30). Martin Marietta Reports Second-Quarter 2026 Results. https://ir.martinmarietta.com/news-releases/news-release-details/martin-marietta-reports-second-quarter-2026-results
- [6] Martin Marietta Materials, Inc. (2026). Form 10-Q for the quarter ended June 30, 2026. U.S. Securities and Exchange Commission. https://www.sec.gov/Archives/edgar/data/0000916076/000119312526326001/mlm-20260630.htm
- [7] Martin Marietta Materials, Inc. (2026, August 24). Martin Marietta Completes Combination With Lhoist North America. https://ir.martinmarietta.com/news-releases/news-release-details/martin-marietta-completes-combination-lhoist-north-america
- [8] Heidelberg Materials AG. (2026, February 5). Accelerating growth: Heidelberg Materials expands footprint in core market Australia by acquiring Maas Group's construction materials business. https://www.heidelbergmaterials.com/en/pr-2026-02-05
- [9] Heidelberg Materials AG. (2026, October 7). Accelerating growth in core markets: Heidelberg Materials expands footprint in Sweden and Norway by acquiring NCC's Industry business area. https://www.heidelbergmaterials.com/en/pr-2026-10-07
- [10] Heidelberg Materials AG. (2026, July 30). Heidelberg Materials with strong growth in the second quarter. https://www.heidelbergmaterials.com/en/pr-2026-07-30
- [11] CRH plc. (2026, July 30). CRH Reports Second Quarter 2026 Results. https://www.crh.com/media/press-releases/2026/crh-reports-second-quarter-2026-results/
- [12] Holcim Ltd. (2025, June 23). Holcim completes spin-off of North America business. https://www.holcim.com/media/media-releases/holcim-completes-spin-off-of-north-america-business
- [13] Amrize Ltd. (2026, October 28). Amrize Reports Third Quarter 2026 Results. Form 8-K Exhibit 99.1, U.S. Securities and Exchange Commission. https://www.sec.gov/Archives/edgar/data/0002035989/000203598926000087/amrizeq32026pressrelease.htm
- [14] Cemex, S.A.B. de C.V. (2026, October 26). Resultados del tercer trimestre 2026. Bolsa Mexicana de Valores. https://www.bmv.com.mx/docs-pub/eventemi/eventemi_1597618_1.pdf
- [15] Rogers Group, Inc. (2026, March 3). Rogers Group, Inc. Announces Agreement to Acquire Rockydale Quarries Corporation. https://rogersgroupincint.com/rogers-group-inc-announces-agreement-to-acquire-rockydale-quarries-corporation/
- [16] Rogers Group, Inc. (2026). Company overview, accessed 3 November 2026. https://rogersgroupincint.com/
- [17] Fletcher Building Limited. (2026, August 19). Fletcher Building returns to profit: EBIT up 26%. https://fletcherbuilding.com/news/fletcher-building-returns-to-profit-ebi-up-26
- [18] Mineral Products Association. (2026, February 2). Four years of decline in British construction demand threatens jobs and future capacity, warns MPA. https://mineralproducts.org/News/2026/release02.aspx
- [19] Mineral Products Association. (2026, August 3). Housing downturn deepens as concrete and mortar slump. https://mineralproducts.org/News/2026/release20.aspx
- [20] Mineral Products Association. (2026, September 29). Defra must commission new survey on recycling in construction: new report.
- [21] Mineral Products Association. (2026, October 20). Recovery delayed to 2028: new report on regional construction markets in Great Britain. https://mineralproducts.org/News/2026/release28.aspx
- [22] Aggregates Europe (UEPG). (2026). Figures: European aggregates production data 2024.
- [23] Aggregates Europe (UEPG). (2026). Facts about the European aggregates industry, accessed 3 November 2026. https://www.aggregates-europe.eu/facts-figures/facts/
- [24] Eurostat. (2026, October 20). Production in construction up by 1.8% in the euro area and by 2.0% in the EU: August 2026. https://ec.europa.eu/eurostat/web/products-euro-indicators/w/4-20102026-ap
- [25] National Bureau of Statistics of China. (2026, October 20). Investment in Real Estate Development from January to September 2026.
- [26] National Bureau of Statistics of China. (2026, October 20). Investment in Fixed Assets from January to September 2026. https://www.stats.gov.cn/english/PressRelease/202610/t20261020_1965664.html
- [27] National Bureau of Statistics of China. (2026, October 20). Industrial Production Operation in September 2026. https://www.stats.gov.cn/english/PressRelease/202610/t20261020_1965665.html
- [28] Australian Bureau of Statistics. (2026, August 26). Construction Work Done, Australia, Preliminary: June 2026. https://www.abs.gov.au/statistics/industry/building-and-construction/construction-work-done-australia-preliminary/latest-release
- [29] Stats NZ. (2026). Building consents issued: September 2026. https://www.stats.govt.nz/information-releases/building-consents-issued-September-2026/
- [30] New Zealand Infrastructure Commission, Te Waihanga. (2026, August). Pipeline snapshot: April to June 2026. https://tewaihanga.govt.nz/the-pipeline/pipeline-snapshot
- [31] Statistisches Bundesamt (Destatis). (2026, October 16). Baugenehmigungen für Wohnungen im August 2026. Pressemitteilung Nr. 370. https://www.destatis.de/DE/Presse/Pressemitteilungen/2026/10/PD26_370_3111.html
- [32] Statistisches Bundesamt (Destatis). (2026, September 25). Auftragseingang im Bauhauptgewerbe im Juli 2026. Pressemitteilung Nr. 338. https://www.destatis.de/DE/Presse/Pressemitteilungen/2026/09/PD26_338_441.html
- [33] Bundesverband Mineralische Rohstoffe e.V. (MIRO). (2026). Mineralische Rohstoffe, accessed 3 November 2026. https://www.bv-miro.org/
- [34] INSEE. (2026, October 6). In August 2026, manufacturing output bounced back partially. Informations rapides No. 245. https://www.insee.fr/en/statistiques/9068858
- [35] ISTAT. (2026, October 20). Production in the construction sector: August 2026. https://www.istat.it/en/?p=137981
- [36] Ministry of Data and Statistics, Republic of Korea. (2026, October 30). Monthly Industrial Statistics: September 2026. https://mods.go.kr/boardDownload.es?bid=11721&list_no=447746&seq=1
- [37] Ministry of Land, Infrastructure, Transport and Tourism, Japan. (2026, August 31). Reiwa 8 nendo (FY2026) kensetsu toshi mitoshi: gaiyo (Construction investment outlook, summary). https://www.mlit.go.jp/report/press/content/002018692.pdf
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Crushed Stone
- Sand
- Gravel
- Other Aggregates
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Infrastructure
- Residential Construction
- Non-residential Construction
- Other Applications
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source, 2026 to 2036
- Natural Aggregates
- Recycled and Secondary Aggregates
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Source
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Source
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Source
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Source
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Source
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Source
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Source
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Application
- By Source
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Vulcan Materials Company
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Martin Marietta Materials, Inc.
- Heidelberg Materials AG
- CRH plc
- Amrize Ltd
- Cemex, S.A.B. de C.V.
- Holcim Ltd
- Rogers Group, Inc.
- Fletcher Building Limited
- Vulcan Materials Company
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by Source, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Application
- Figure 9: Global Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Source
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Product Type
- Figure 26: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Application
- Figure 29: North America Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Source
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Product Type
- Figure 36: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Application
- Figure 39: Latin America Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Source
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Product Type
- Figure 46: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Application
- Figure 49: Western Europe Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Source
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Application
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Source
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Product Type
- Figure 66: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Application
- Figure 69: East Asia Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Source
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Source
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Source
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Construction Aggregates Market in 2026?
FMI estimates the market at USD 457.2 billion in 2026, up from USD 435.9 billion in 2025. It is forecast to reach USD 737.1 billion by 2036 at a 4.9% CAGR.
Which product type leads the Construction Aggregates Market in 2026?
Crushed Stone leads by product type with 46.0% in 2026. Sand, Gravel and Other Aggregates together hold 54.0%.
Which application and source lead in 2026?
Infrastructure holds 40.0% by application. Natural Aggregates hold 92.0% by source in FMI's 2026 assessment, with Recycled and Secondary Aggregates at 8.0%.
Which country is forecast to grow fastest through 2036?
China has the highest forecast CAGR at 5.7% during 2026 to 2036, followed by the United States at 4.6%. These are FMI forecasts and are not rates reported by the cited public bodies.
How does freight affect aggregates pricing?
Producers quote a freight-adjusted price separate from delivery. Vulcan Materials reported a freight-adjusted price of USD 22.8 per ton in the third quarter of 2026 while its unit cash cost rose 7.0%, with diesel the main driver [3].
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
