

- Market Size (2026)
- USD 25.1 Bn
- Forecast (2036)
- USD 37.4 Bn
- CAGR (2026 to 2036)
- 4.1%
How big is Construction Equipment Maintenance and Repair Market in 2026?
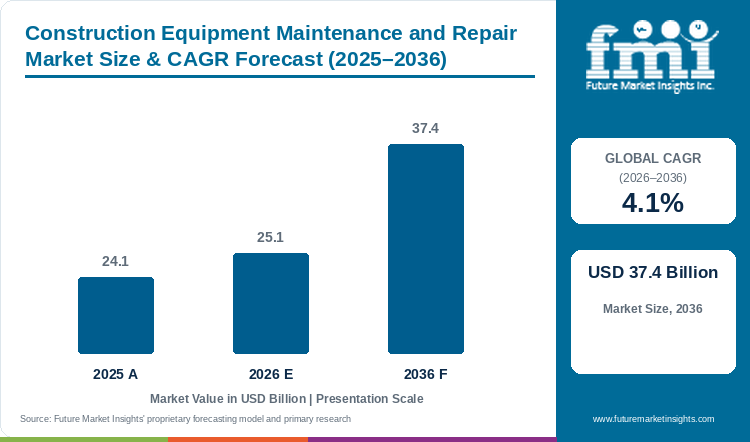
Construction equipment maintenance and repair sales will expand at a 4.1% CAGR from 2026 to 2036. Market size stood at USD 24.1 billion in 2025, is estimated at USD 25.1 billion in 2026 and is projected to reach USD 37.4 billion by 2036.
Maintenance and repair market size for construction equipment stood at USD 24.1 billion in 2025 and is estimated at USD 25.1 billion in 2026. Analysts at FMI see sales reaching USD 37.4 billion by 2036 on a 4.1% CAGR from 2026 to 2036. Key trends in equipment service point to longer machine shifts in North America and Indonesia. Komatsu machines in North America ran an average of 69.9 hours in August 2026, up 2.3% on August 2025, and Indonesian fleets averaged 212.7 hours.[1] Demand intensity follows those hours, because every extra shift brings oil, filter and wear-part changes forward.
Demand for service is heaviest on loaders, at 31% of 2026 vehicle sales, and authorized service centers handle 44% of the work on warranty and fault-code access. Japanese fleets ran fewer hours, at 49.3 in August 2026, down 1.3%.[1] Oil and filter visits on Japanese machines will therefore come at longer intervals than on North American fleets.
Each compact track loader or backhoe sold joins the installed base, and the compact construction equipment market grows at a 3.1% CAGR from 2026 to 2036, so service volume keeps rising as rental and contractor machines age. Buckets and breakers wear on the same machines, and the construction equipment attachments market posts a 4.6% CAGR over the same years, so worn teeth and cutting edges will add to the parts bill on each service visit. EU Stage V emission limits for non-road diesel engines are raising the bar for service shops, since compliant machines carry exhaust aftertreatment units that need diagnostic tools. Due to this, dealer workshops with those tools will take most aftertreatment repairs in Europe. Service sales will also spread from established markets to emerging growth opportunities, as high-hour Indonesian fleets reach overhaul intervals sooner than European ones.
Key Market Trends & Insights
- Parts carry an estimated 58.4% of 2026 component sales, since a rebuilt pump or undercarriage bills far above an oil change, and consumables take about 41.6%.
- Caterpillar agreed in September 2026 to buy the Fabick Cat dealership, with 37 locations.[2] Aftermarket outlets still handle an estimated 46.3% of 2026 channel sales.
- Loader fleets log the most hours on road and quarry jobs, giving loaders 31% of 2026 sales and a 4.3% CAGR from 2026 to 2036.
- Fleet owners with machines under warranty call dealers first, so authorized centers hold 44% of 2026 sales on a 4.2% CAGR from 2026 to 2036.
- Bundled repair and maintenance contracts form an estimated 67.5% of 2026 service type sales.
Regional Highlights
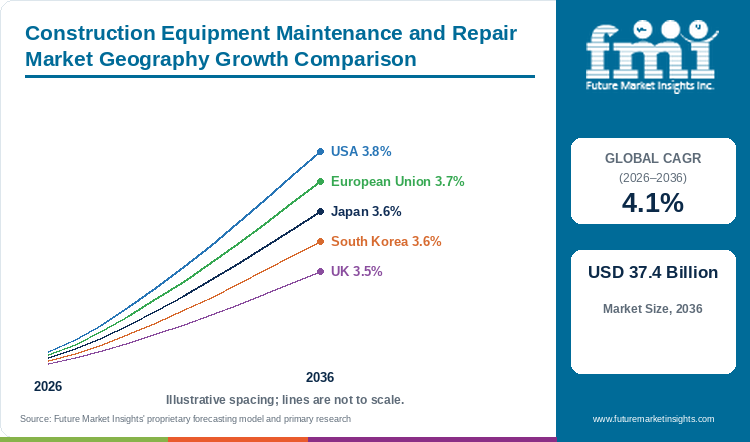
- U.S. service sales grow at a 3.8% CAGR from 2026 to 2036, the top rate among the five profiled markets.
- The EU follows on 3.7%, Japan and South Korea share 3.6%, and the UK posts 3.5%.
- U.S. construction put in place came to $2,203.1 billion for August 2026, seasonally adjusted and annualised, the Census Bureau said.[3]
Market Size & Forecast
Table 1: Market Size and Forecast for the Construction Equipment Maintenance and Repair Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 24.1 billion |
| Estimated Market Size in 2026 | USD 25.1 billion |
| Projected Market Size by 2036 | USD 37.4 billion |
| CAGR, 2026 to 2036 | 4.1% |
| Added Revenue, 2026 to 2036 | USD 12.3 billion |
| Market Expansion Multiple | 1.5x |
Infrastructure work, rental fleets and predictive tools will add USD 12.3 billion by 2036. FMI links growth to heavy machinery use on infrastructure projects, rental services and predictive maintenance technology. Telematics units on connected machines report faults and engine hours to the dealer. Each smart machine sold adds a unit to the dealer fault feed, so growth of the smart construction equipment market will widen the base of remotely monitored fleets. Dealers with access to fault codes will schedule repairs before breakdowns stop a job.
Machine Hours, Dealer Networks and Technician Supply
Dealer capacity and technician training both drew Caterpillar money within six weeks in 2026. Caterpillar agreed on 29 September 2026 to acquire John Fabick Tractor Company, a Cat dealer with 37 locations across parts of Missouri and Illinois, all of Wisconsin and the Upper Peninsula of Michigan.[2] Mobile heavy equipment mechanics held 180,300 jobs in the USA in 2025, at a median pay of $65,510 in May 2025, the BLS reported.[4] Caterpillar allocated up to $3 million in Arkansas in August 2026 under a five-year, $100 million workforce initiative for manufacturing and industry technician roles.[5] The FMI study puts authorized service centers at 44% of 2026 sales, so dealer bench strength decides the destination of most repair work.
Komatsu machines in Indonesia averaged 212.7 hours in August 2026, against 65.7 hours in Europe and 49.3 hours in Japan.[1] Caterpillar and FieldAI named autonomous inspections and jobsite digital twins as early applications of a September 2026 collaboration.[6] High-hour fleets will buy overhaul packages first.
Table 2: Machine Hours, Dealer and Workforce Indicators for the Construction Equipment Maintenance and Repair Market (hours, counts and USD), mixed reporting years from 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Komatsu average hours, North America, August 2026 | 69.9 hours; up 2.3% | More hours bring service intervals forward. | [1] |
| Komatsu average hours, Europe, August 2026 | 65.7 hours; up 2.7% | European fleets ran harder in 2026. | [1] |
| Komatsu average hours, Japan, August 2026 | 49.3 hours; down 1.3% | Lower use stretches Japanese service cycles. | [1] |
| Komatsu average hours, Indonesia, August 2026 | 212.7 hours; up 3.3% | High-hour fleets wear parts fastest. | [1] |
| U.S. construction put in place, August 2026 | $2,203.1 billion annual rate | Construction volume sets machine use. | [3] |
| U.S. mobile heavy equipment mechanics, 2025 | 180,300 jobs; $65,510 median pay | Technician supply limits service capacity. | [4] |
| Fabick Cat dealership deal, September 2026 | 37 locations | A maker takes direct control of a dealer network. | [2] |
| Caterpillar workforce initiative, August 2026 | Up to $3 million in Arkansas; $100 million program | Training adds technicians over five years. | [5] |
| UK construction output, three months to July 2026 | Down 0.5% | Slower UK work trims machine hours. | [7] |
Analyst Perspective
“The technician bench is the risk I am watching most closely, because U.S. dealers are adding locations and compact machines and training programs add mechanics only slowly. A short bench will stretch repair queues on loader and dozer fleets tied to infrastructure jobs. I expect fleets to reward dealers with hour-based contracts and trained staff, and to move work to independent shops once response times slip.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the construction equipment maintenance and repair market segmented?
Five service axes and region split the market. Loaders lead the vehicle axis at 31%, authorized service centers lead providers at 44%, and parts lead components at an estimated 58.4% in 2026.
By component: consumable and parts.
By sales channel: OEM, OES, and after market.
By vehicle: dozer, loaders, graders, scrapers, backhoe loaders, and compactors.
By service provider: authorized service center, third-party service center, and independent service center.
By service type: repair and maintenance, and service only.
By region: four groups of blocks, with Middle East and Africa as one block, the Americas split into North America and Latin America, Europe split into Western Europe and Eastern Europe, and Asia split into East Asia and South Asia Pacific.
Why do loaders lead vehicle sales?
Loaders account for 31% of 2026 vehicle sales, and dozers follow at an estimated 18.6%.
Table 3: Vehicle Share for the Construction Equipment Maintenance and Repair Market (percentage share), 2026
| Vehicle | Estimated Share (2026) |
|---|---|
| Loaders | 31% |
| Dozer | 18.6% |
| Backhoe Loaders | 17.2% |
| Compactors | 13.4% |
| Graders | 11.5% |
| Scrapers | 8.3% |
| Total | 100.0% |
Table 4: Vehicle Leadership and Market Growth for the Construction Equipment Maintenance and Repair Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.1% |
| Leading Segment | Loaders |
Road crews, quarries and material yards all run loaders, so loader fleets log the most hours, and as per FMI's analysis loaders take 31% of 2026 vehicle sales on a 4.3% CAGR from 2026 to 2036. Dozers, an estimated 18.6%, need costly undercarriage and track rebuilds and run in smaller fleets. Backhoe loaders (about 17.2%) are lighter machines with shorter service lists. Compactors hold near 13.4% and carry few wear parts beyond drums and engines. Graders, at about 11.5%, work mainly on road jobs, and scrapers, close to 8.3%, serve large earthmoving sites only. Caterpillar plans a new Sanford, North Carolina, facility for compact track loaders and telehandlers under a $1 billion investment announced in September 2026.[8] More compact track loaders in rental fleets will add loader service volume. Wheel loaders need tyres, bucket edges and hydraulic hoses replaced on a cycle, so each unit added through growth of the wheel loader market brings recurring parts orders.
Why do authorized service centers lead service provider sales?
Authorized service centers handle 44% of 2026 service provider sales, ahead of third-party centers at about 32.7% (estimated).
Table 5: Service Provider Share for the Construction Equipment Maintenance and Repair Market (percentage share), 2026
| Service Provider | Estimated Share (2026) |
|---|---|
| Authorized Service Center | 44% |
| Third-Party Service Center | 32.7% |
| Independent Service Center | 23.3% |
| Total | 100.0% |
Owners of machines under warranty bring the work to the dealer, since fault codes and warranty claims run through the authorized network. FMI's report shows authorized service centers at 44% of service provider sales in 2026, with a 4.2% CAGR from 2026 to 2036. Third-party centers (an estimated 32.7%) compete on labour rates for mixed fleets, and independent shops (about 23.3%) serve older, out-of-warranty machines with less access to diagnostic software.
- Caterpillar said the Fabick deal aims to strengthen the customer experience across the service territory.[2]
- The Fabick deal was expected to close within 30 days of the September 2026 announcement.[2]
Why do parts lead component sales?
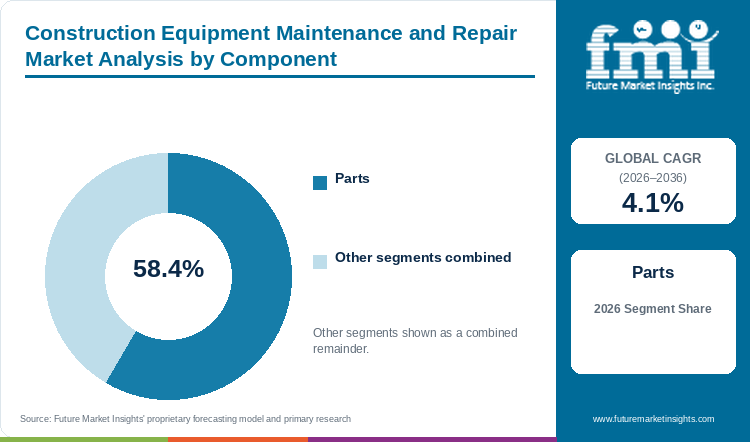
Parts carry an estimated 58.4% of 2026 component sales, and consumables about 41.6%.
Table 6: Component Share for the Construction Equipment Maintenance and Repair Market (percentage share), 2026
| Component | Estimated Share (2026) |
|---|---|
| Parts | 58.4% |
| Consumable | 41.6% |
| Total | 100.0% |
Komatsu Europe hours rose 2.7% in August 2026 against August 2025, and every extra hour wears pins, bushings and cutting edges.[1] Parts bring in an estimated 58.4% of 2026 component sales, because a rebuilt pump or undercarriage bills far above an oil and filter visit. Consumables, at about 41.6%, sell more often in smaller tickets. Every loader bucket in service needs new cutting edges and teeth on a regular cycle, and growth of the loader bucket market will put those wear parts on more dealer orders.
- Indonesian Komatsu fleets ran 212.7 hours in August 2026, up 3.3%.[1]
Why does the aftermarket lead sales channel sales?
The aftermarket accounts for an estimated 46.3% of 2026 sales channel sales, with OEM channels at about 31.2%.
Table 7: Sales Channel Share for the Construction Equipment Maintenance and Repair Market (percentage share), 2026
| Sales Channel | Estimated Share (2026) |
|---|---|
| After Market | 46.3% |
| OEM | 31.2% |
| OES | 22.5% |
| Total | 100.0% |
Brand and age make no difference to an aftermarket supplier, so aftermarket outlets take an estimated 46.3% of 2026 channel sales across mixed fleets. OEM channels, about 31.2%, sell at dealer prices and mostly to owners of newer machines. OES, near 22.5%, carries maker-approved parts through independent outlets with a narrower range. U.S. nonresidential construction came to $773.0 billion on a seasonally adjusted annual basis in August 2026, and highway construction stood at $150.6 billion.[3] Highway contractors keep older dozers and graders on those jobs, and aftermarket parts will cover most repair bills on such machines.
Why do repair and maintenance packages lead service type sales?
Repair and maintenance packages make up an estimated 67.5% of 2026 service type sales, and service only work about 32.5%.
Table 8: Service Type Share for the Construction Equipment Maintenance and Repair Market (percentage share), 2026
| Service Type | Estimated Share (2026) |
|---|---|
| Repair and Maintenance | 67.5% |
| Service Only | 32.5% |
| Total | 100.0% |
Fleet managers prefer one contract for planned service and breakdown repair, and bundled repair and maintenance contracts reach about 67.5% of the 2026 service type split by estimate. Service only work, at about 32.5%, covers scheduled oil, filter and inspection visits on small contractor fleets that pay by the visit.
- Caterpillar and FieldAI named digital twins of jobsites and equipment as an early application in September 2026, which will feed condition data into bundled contracts.[6]
- FieldAI has deployments across hundreds of sites and has raised over $400 million, Caterpillar said.[6]
What are the drivers, restraints, and opportunities in the construction equipment maintenance and repair market?
Growth of the construction equipment maintenance and repair market follows machine hours on infrastructure, rental and nonresidential jobs. High service costs, mechanic shortages and the cost of IoT monitoring slow adoption of planned maintenance.
- Driver: Infrastructure work, rental fleets and telematics-based predictive maintenance.
- Restraint: High maintenance cost, harsh site conditions and too few trained mechanics.
- Opportunity: Autonomous inspections, digital twins and dealer-owned service networks.
Public Works and Nonresidential Jobs Keep Machines Running
Public road and utility jobs are keeping U.S. machines working as total construction dips year on year. U.S. construction totalled $2,203.1 billion for August 2026 on a seasonally adjusted annualised basis, 0.9% above July and 1.7% below August 2025.[3] Public construction accounted for $547.8 billion of the August figure.[3] The updated report by FMI finds that infrastructure investment and rising equipment use drive service sales. Contractors on those public jobs will keep oil, filter and undercarriage work on schedule through 2036.
Mechanic Shortages Raise Labour Cost per Repair
Heavy vehicle and mobile equipment technicians earned a median $63,850 in May 2025, the BLS reported.[4] Key challenges in the construction equipment maintenance and repair market include labour shortages, high maintenance costs and harsh operating environments. Shops short of mechanics will raise labour rates and lengthen repair queues.
Autonomous Inspection and Digital Twins Open Condition-Based Service
Caterpillar and FieldAI are combining operational data with robot foundation models for autonomous inspections across complex sites, Caterpillar said on 2 September 2026.[6] Robots and twins flag wear before failure, and dealers will sell condition-based contracts to mining and quarry fleets first.
Which country CAGRs are profiled in the construction equipment maintenance and repair market?
Table 9: Country CAGR Comparison for the Construction Equipment Maintenance and Repair Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| USA | 3.8% |
| European Union | 3.7% |
| Japan | 3.6% |
| South Korea | 3.6% |
| UK | 3.5% |
How do country-level CAGRs compare in the construction equipment maintenance and repair market?
American fleets stay on the job owing to construction volume, which reached a $2,203.1 billion annual rate in August 2026.[3] FMI predicts that the USA will lead the five profiled markets at a 3.8% CAGR from 2026 to 2036, with the EU at 3.7%, Japan and South Korea at 3.6% and the UK at 3.5%. Every profiled rate is below the 4.1% global CAGR, and China, Germany and India rank among the top contributors to global sales.
- Public construction ran at a $547.8 billion annual rate in August 2026, keeping U.S. road and utility fleets on regular service.[3]
- European Komatsu machines ran 2.7% more hours in August 2026, and each extra hour brings EU wear-part orders forward.[1]
- Japan grows at 3.6% on inspection and retrofit jobs, since Komtrax hours there fell 1.3% in August 2026.[1]
- Smart infrastructure programs tie Korean service to AI-based predictive maintenance.
- GB construction output fell 0.5% across May to July 2026, and the UK posts the lowest profiled rate at 3.5%.[7]
Full report country CAGRs cover: seven regional blocks plus country detail for China, Germany and India, which rank among the top contributors to global sales.
Country-wise Analysis
USA Construction Equipment Maintenance and Repair Market Outlook (2026 to 2036)
Caterpillar made Arkansas the fifth allocation of the workforce program in August 2026, with up to $3 million.[5] The country employed 180,300 mobile heavy equipment mechanics in 2025.[4] Dealer ownership also changed in the Midwest after Caterpillar agreed in September 2026 to buy Fabick, a Cat dealer covering all of Wisconsin and parts of Missouri, Illinois and Michigan.[2] Safety and emission rules will keep inspection visits frequent, and the USA posts a 3.8% CAGR from 2026 to 2036, the highest of the profiled markets.
Key takeaway: Maker-owned dealers and trained mechanics will decide U.S. service capacity through 2036.
European Union Construction Equipment Maintenance and Repair Market Outlook (2026 to 2036)
Key takeaway: EU service growth will favour shops trained on electric and hybrid drivetrains.
Electric and hybrid machines are entering EU fleets with urban projects, and service shops will need battery and high-voltage training. Komatsu equipment in Europe averaged 65.7 hours in August 2026, up 2.7% on August 2025.[1] Sales grow at a 3.7% CAGR from 2026 to 2036.
Japan Construction Equipment Maintenance and Repair Market Outlook (2026 to 2036)
Machine hours in Japan averaged 49.3 in August 2026 on Komtrax data, down 1.3%, and the Japanese data population changed from April 2026 after 3G communication services ended.[1] Fewer hours will stretch service intervals, so inspection robots and seismic retrofit work on ageing, earthquake-exposed infrastructure will carry new service demand at a 3.6% CAGR from 2026 to 2036.
Key takeaway: Japanese demand comes from inspection and retrofit programs. Machine hours add little to the 3.6% CAGR.
South Korea Construction Equipment Maintenance and Repair Market Outlook (2026 to 2036)
Korean contractors will fit sensors to existing fleets to qualify for smart city work, as South Korea invests in smart infrastructure and AI-based predictive maintenance. Growth matches Japan at a 3.6% CAGR from 2026 to 2036.
Key takeaway: Korean service sales will move toward remote monitoring and AI fault prediction.
UK Construction Equipment Maintenance and Repair Market Outlook (2026 to 2036)
Total construction output in Great Britain fell 0.5% across May to July 2026, and new work fell 0.4%, the ONS reported.[7] Lower new work trims machine hours on UK sites. Smart city and sustainability projects will keep UK sales growing at 3.5% from 2026 to 2036, the lowest profiled rate.
Key takeaway: UK service providers will chase retrofit and sustainability projects during the 2026 slowdown in new work.
Who are the notable companies in the construction equipment maintenance and repair market?
Notable organisations include Caterpillar Inc., John Fabick Tractor Company, Komatsu Ltd. and FieldAI, along with RPM Machinery and fleet software providers Fleetio and Tenna.
Caterpillar is moving from production capacity to commercial scale in service, pairing a $1 billion compact equipment plant in Sanford with direct ownership of a large dealer network.[8] The Fabick purchase moves 37 dealer locations under Caterpillar ownership.[2] Caterpillar describes itself as the leading maker of construction and mining equipment, with one of the largest independent dealer networks.[6] Komatsu publishes monthly Komtrax hour data from remote monitoring of Komatsu machines.[1]
Fleet software firms compete on scheduling and uptime data. Fleetio reports that construction companies with data-driven service schedules record higher equipment availability, FMI's report notes. Tenna reported in 2024 on GPS telematics adoption for logging operating hours and maintenance compliance.
- Equipment makers and dealers: Caterpillar Inc., John Fabick Tractor Company, and Komatsu Ltd.
- Maintenance planning and fleet software firms: RPM Machinery, Fleetio, and Tenna.
- Technology partners: FieldAI.
Competitive Benchmarking: Construction Equipment Maintenance and Repair Market
Table 10: Competitive Benchmarking for the Construction Equipment Maintenance and Repair Market (qualitative documentation ratings), 2026
| Company | Dealer Network | Usage Data | Workforce Programs | Recency |
|---|---|---|---|---|
| Caterpillar Inc. | High | Medium | High | High |
| Komatsu Ltd. | Low | High | Low | High |
| John Fabick Tractor Company | High | Low | Low | High |
| FieldAI | Low | Medium | Low | High |
Dated release and filing counts per column set the marks, so a Low mark signals thin records and says nothing about share.
Key Developments in the Construction Equipment Maintenance and Repair Market
- In October 2026, the Census Bureau reported U.S. construction put in place at a $2,203.1 billion annual rate for August 2026.[3]
- In September 2026, Caterpillar announced about $1 billion for a new compact equipment plant in Sanford, North Carolina.[8]
- In September 2026, Caterpillar agreed to acquire the Fabick Cat dealership.[2]
- In September 2026, Komatsu updated Komtrax machine hour data through August 2026.[1]
- In September 2026, Caterpillar and FieldAI announced a physical AI and autonomy collaboration.[6]
- In September 2026, the ONS reported GB construction output down 0.5% across May to July 2026.[7]
- In August 2026, the BLS updated the outlook for heavy vehicle and mobile equipment service technicians.[4]
- In August 2026, Caterpillar extended the workforce initiative to Arkansas.[5]
Key Players in the Construction Equipment Maintenance and Repair Market
Equipment Makers and Dealers
- Caterpillar Inc.
- John Fabick Tractor Company
- Komatsu Ltd.
Maintenance Planning, Telematics and Technology Firms
- RPM Machinery
- Fleetio
- Tenna
- FieldAI
Construction Equipment Maintenance and Repair Market - Report Scope
Table 11: Report Scope for the Construction Equipment Maintenance and Repair Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Component; sales channel; vehicle; service provider; service type; region |
| Quantitative units | USD billion |
| Market definition | Maintenance, repair, parts and consumables for dozers, loaders, graders, scrapers, backhoe loaders and compactors, supplied through OEM, OES and aftermarket channels by authorized, third-party and independent service centers. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia Pacific; Middle East and Africa |
| Countries profiled | USA; UK; European Union; Japan; South Korea |
| Key organisations profiled | Caterpillar Inc., John Fabick Tractor Company, Komatsu Ltd., RPM Machinery, Fleetio, Tenna, FieldAI |
| Forecast period | 2026 to 2036 |
Construction Equipment Maintenance and Repair Market - Research Methodology
Table 12: Research Methodology for the Construction Equipment Maintenance and Repair Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Equipment maker releases, machine usage data, national statistics offices and labour statistics dated May 2025 or later. |
| Desk Research | Desk research covers machine operating hours, dealer ownership, technician supply and construction activity. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base of USD 24.1 billion and the 4.1% CAGR. |
| Data Validation | Hour and output data were matched to the publishing company or statistics office for the same month. |
Construction Equipment Maintenance and Repair Market by Segments
Construction Equipment Maintenance and Repair Market segmented by Component:
- Consumable
- Parts
Construction Equipment Maintenance and Repair Market segmented by Sales Channel:
- OEM
- OES
- After Market
Construction Equipment Maintenance and Repair Market segmented by Vehicle:
- Dozer
- Loaders
- Graders
- Scrapers
- Backhoe Loaders
- Compactors
Construction Equipment Maintenance and Repair Market segmented by Service Provider:
- Authorized Service Center
- Third-Party Service Center
- Independent Service Center
Construction Equipment Maintenance and Repair Market segmented by Service Type:
- Repair and Maintenance
- Service Only
Construction Equipment Maintenance and Repair Market by Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia Pacific
- Middle East and Africa
Research Sources and Bibliography
- [1] Komatsu Ltd. (2026, September 29). Monthly Komtrax data (up through Aug 2026). https://www.komatsu.jp/en/-/media/home/ir/library/demand-orders/en/komtrax_e.pdf
- [2] Caterpillar Inc. (2026, September 29). Caterpillar Inc. Enters into Agreement to Acquire Fabick Cat Dealership. https://www.caterpillar.com/en/news/corporate-press-releases/h/caterpillar-inc-enters-into-agreement-to-acquire-fabick-cat-dealership.html
- [3] U.S. Census Bureau. (2026, October 1). Monthly Construction Spending, August 2026. https://www.census.gov/construction/c30/current/index.html
- [4] U.S. Bureau of Labor Statistics. (2026, August 27). Heavy Vehicle and Mobile Equipment Service Technicians, Occupational Outlook Handbook. https://www.bls.gov/ooh/installation-maintenance-and-repair/heavy-vehicle-and-mobile-equipment-service-technicians.htm
- [5] Caterpillar Inc. (2026, August 17). Caterpillar Expands Workforce Initiative to Arkansas. https://www.caterpillar.com/en/news/corporate-press-releases/h/arkansas-workforce-investment.html
- [6] Caterpillar Inc. (2026, September 2). Caterpillar and FieldAI Advance AI-Powered Industrial Innovation. https://www.caterpillar.com/en/news/corporate-press-releases/h/caterpillar-and-fieldai-advance-ai-powered-industrial-innovation.html
- [7] Office for National Statistics. (2026, September 11). Construction output in Great Britain: July 2026. https://www.ons.gov.uk/businessindustryandtrade/constructionindustry/bulletins/constructionoutputingreatbritain/latest
- [8] Caterpillar Inc. (2026, September 30). Caterpillar to Expand Cat Compact Manufacturing in North Carolina. https://www.caterpillar.com/en/news/corporate-press-releases/h/caterpillar-to-invest-one-billion-in-north-carolina-to-expand-cat-compact-manufacturing-capacity.html
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- What will construction equipment maintenance and repair sales reach in 2026 and 2036?
- What CAGR will the market post from 2026 to 2036?
- Which vehicle and service provider will hold the largest shares?
- Will parts or consumables carry more sales?
- Which profiled country will grow fastest?
- Which equipment makers, dealers and software firms will shape service competition?
Frequently Asked Questions
What is the size of the construction equipment maintenance and repair market in 2026?
Market size in 2026 will be USD 25.1 billion. FMI projects USD 37.4 billion for 2036.
What growth rate is expected for equipment maintenance and repair?
Service sales will rise at a 4.1% CAGR between 2026 and 2036, with infrastructure jobs and rental fleets adding most of the USD 12.3 billion gain.
Which vehicle type will generate the most service sales?
Loader service will generate 31% of 2026 vehicle sales and grow at a 4.3% CAGR from 2026 to 2036.
Which service provider will hold the largest share?
FMI gives authorized service centers a 44% share in 2026, on warranty and fault-code access.
Which profiled country will grow fastest?
U.S. service sales will grow fastest of the five profiled markets, at a 3.8% CAGR from 2026 to 2036.
Which organisations will shape service competition?
Caterpillar, Komatsu and dealers like Fabick will shape dealer service, and Fleetio and Tenna will shape fleet software.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Component, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Component, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Component, 2026 to 2036
- Consumable
- Parts
- Y-o-Y Growth Trend Analysis By Component, 2021 to 2025
- Absolute $ Opportunity Analysis By Component, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- OEM
- OES
- After Market
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vehicle, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vehicle, 2026 to 2036
- Dozer
- Loaders
- Graders
- Scrapers
- Backhoe Loaders
- Compactors
- Y-o-Y Growth Trend Analysis By Vehicle, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle, 2026 to 2036
- Global Market Analysis and Forecast, By Service Provider, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Service Provider, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Service Provider, 2026 to 2036
- Authorized Service Center
- Third-Party Service Center
- Independent Service Center
- Y-o-Y Growth Trend Analysis By Service Provider, 2021 to 2025
- Absolute $ Opportunity Analysis By Service Provider, 2026 to 2036
- Global Market Analysis and Forecast, By Service Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Service Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Service Type, 2026 to 2036
- Repair and Maintenance
- Service Only
- Y-o-Y Growth Trend Analysis By Service Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Service Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Component
- By Sales Channel
- By Vehicle
- By Service Provider
- By Service Type
- Market Attractiveness Analysis
- By Country
- By Component
- By Sales Channel
- By Vehicle
- By Service Provider
- By Service Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Component
- By Sales Channel
- By Vehicle
- By Service Provider
- By Service Type
- Market Attractiveness Analysis
- By Country
- By Component
- By Sales Channel
- By Vehicle
- By Service Provider
- By Service Type
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Component
- By Sales Channel
- By Vehicle
- By Service Provider
- By Service Type
- Market Attractiveness Analysis
- By Country
- By Component
- By Sales Channel
- By Vehicle
- By Service Provider
- By Service Type
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Component
- By Sales Channel
- By Vehicle
- By Service Provider
- By Service Type
- Market Attractiveness Analysis
- By Country
- By Component
- By Sales Channel
- By Vehicle
- By Service Provider
- By Service Type
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- South Asia Pacific
- By Component
- By Sales Channel
- By Vehicle
- By Service Provider
- By Service Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Sales Channel
- By Vehicle
- By Service Provider
- By Service Type
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Component
- By Sales Channel
- By Vehicle
- By Service Provider
- By Service Type
- Market Attractiveness Analysis
- By Country
- By Component
- By Sales Channel
- By Vehicle
- By Service Provider
- By Service Type
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Sales Channel
- By Vehicle
- By Service Provider
- By Service Type
- European Union
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Sales Channel
- By Vehicle
- By Service Provider
- By Service Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Sales Channel
- By Vehicle
- By Service Provider
- By Service Type
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Sales Channel
- By Vehicle
- By Service Provider
- By Service Type
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Sales Channel
- By Vehicle
- By Service Provider
- By Service Type
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Component
- By Sales Channel
- By Vehicle
- By Service Provider
- By Service Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Caterpillar Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Komatsu Ltd.
- John Fabick Tractor Company
- FieldAI
- RPM Machinery
- Fleetio
- Tenna
- Caterpillar Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


