

- Market Size (2026)
- USD 23.0 Bn
- Forecast (2036)
- USD 43.2 Bn
- CAGR (2026 to 2036)
- 6.5%
How big is Environment Testing, Inspection and Certification Market in 2026?
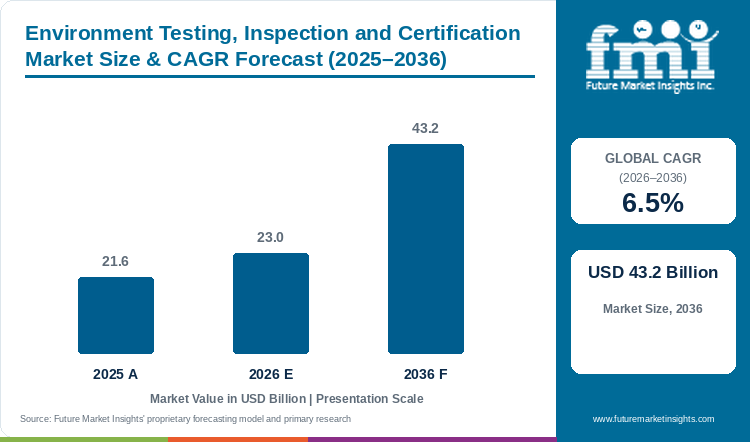
The forecast outlook projects USD 23.00 billion in 2026 and USD 43.18 billion in 2036 at 6.5% annual growth. FMI publishes USD 21.6 billion for 2025 and USD 38 billion for 2035.
The global environment testing, inspection and certification market covers services commissioned by industrial, public-sector and other customers to assess environmental samples and conditions. From a published value of USD 21.6 billion in 2025, the forecast outlook projects USD 23.00 billion in 2026 and USD 43.18 billion by 2036 at a CAGR of 6.5% over 2026 to 2036. The separately published 2035 endpoint is USD 38 billion. Testing is projected to account for 45.0% of the projected 2026 service breakdown, while water testing is projected to represent 40.0% of the separate sample-type breakdown, making analytical work central to the market's recurring monitoring and investigation contracts.
Monitoring obligations, industrial operations and development projects generate demand for measurements that support compliance and operational decisions. The technical scope extends from field collection to interpretation: EPA's September 2025 PFAS guidance addresses the sampling and analysis chain, while England's July 2025 MCERTS water-testing revision refines laboratory quality provisions. [1][2] Emerging measurement tasks add further requirements. JRC's August 2025 report examines practical considerations for microplastics analysis in drinking water, and OECD's July 2026 methods explorer helps identify analytical approaches by substance and environmental medium. [3][4] These developments favour coordination between sampling, method competence and reporting.
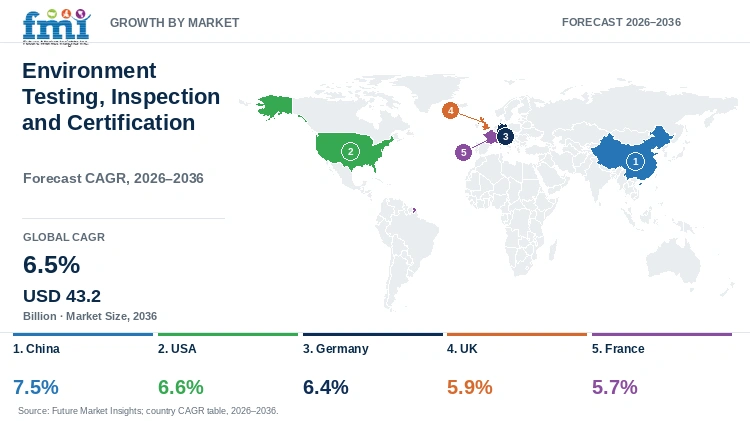
China leads the five profiled markets at a CAGR of 7.5%, followed by the United States at 6.6% and Germany at 6.4%. The United Kingdom and France are estimated at 5.9% and 5.7%, respectively. These projected rates cover 2026 to 2036. Customer requirements vary between recurring industrial or utility monitoring, project assessments and investigations that may need additional sampling as results emerge.
SGS SA, Intertek Group, Bureau Veritas, Eurofins Scientific and ALS Ltd are representative competitors across environmental assurance and laboratory services. Differentiation rests on the relevant analytical and inspection scope, sample logistics, turnaround and reports suited to the client's question. Multi-site contracts also require consistent data delivery while retaining each location's sample and regulatory requirements. Providers able to coordinate fieldwork, laboratory capacity and useful interpretation can address a broader share of the assignment.
Key Market Trends & Insights
- Sampling and sample acceptance form part of the service specification, as EPA's updated 2025 PFAS guidance illustrates. [1]
- England's July 2025 MCERTS revision addresses specific quality-control and calibration provisions for water testing. [2]
- Microplastics analysis brings method and interpretation questions alongside conventional contaminant testing. [3]
Regional Highlights
- China has the highest profiled country CAGR, 7.5%, in the 2026 to 2036 forecast.
- The USA and Germany follow at 6.6% and 6.4% respectively for 2026 to 2036.
- OECD's July 2026 methods explorer brings together environmental analytical-method information from Canada, Japan and the USA. [4]
Market Size & Forecast
Table 1: Market Size and Forecast for Environment Testing, Inspection and Certification Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| Published 2025 market value | USD 21.6 billion |
| Projected 2026 market value | USD 23.00 billion |
| Published 2035 market value | USD 38 billion |
| Projected 2036 market value | USD 43.18 billion |
| Forecast CAGR, 2026 to 2036 | 6.5% |
| Projected increase, 2026 to 2036 | USD 20.18 billion |
Demand reaches service providers through recurring monitoring contracts, individual investigations and site or project assessments. These orders have different economics. A routine programme can plan sample collection and laboratory capacity across the year, whereas an unexpected contamination investigation may require rapid mobilisation and a wider range of analyses. Providers compete on their ability to deliver the relevant accredited scope, reliable sample handling and reports that answer the client's actual compliance or operational question.
Environmental assignments form one part of a broader assurance-services industry. The Testing, Inspection and Certification Market provides related coverage of that wider purchasing environment.
The analytical method and sample chain shape the service purchased
Testing revenue depends on more than the number of samples delivered to a laboratory. The same sample may require several analytes, preparation steps and quality-control checks, while a poorly collected sample may need to be collected again. Buyers therefore need to define the measurement objective before comparing quotations. Public method guidance also helps explain why a provider qualified for one sample matrix or technique may need additional work before accepting another. The current sources cover drinking water, effluent and broader environmental media; their scopes differ and should remain visible in the purchasing specification.
Table 2: Industry evidence relevant to the environment testing, inspection and certification market
| Indicator | Data point or observation | Market relevance | Source |
|---|---|---|---|
| PFAS sample chain | EPA updated its collection and analysis guidance in September 2025. | Sampling and laboratory acceptance are connected parts of the contracted service. | [1] |
| Effluent laboratory quality | MCERTS water-testing standard updated on 31 July 2025. | A method-specific quality system matters alongside test price and turnaround. | [2] |
| Microplastics methodology | JRC published practical considerations on 25 August 2025. | Method selection and limitations affect how drinking-water results are interpreted. | [3] |
| Methods discovery | OECD updated AMSEM in July 2026. | Buyers can identify methods associated with particular substances and environmental media. | [4] |
Analyst Perspective
“A laboratory network becomes commercially useful when it can supply the method, sample logistics and reporting scope the customer actually needs. Buyers have a clearer basis for choosing a provider when field and laboratory responsibilities are explicit and analytical limitations are explained before the assignment begins.”
- Nikhil Kaitwade, Principal Analyst at Future Market Insights
A useful contract specifies the sample, analytical scope and intended use of the result, then assigns responsibility for collection, transport and reporting.
How is the Environment Testing, Inspection and Certification Market segmented?
The market is segmented by Product Type, End User, Sample Type, Test Type, and Region.
Service type distinguishes testing, inspection and certification. Sample type describes the material being assessed, while test type identifies what is measured. These views overlap commercially but are separate market breakdowns. Water testing can include chemical, physical and biological measurements; it does not represent an additional share to be added to the testing-service percentage. The two quantitative profiles below retain a projected 2026 reference year. The scope also includes the industries commissioning the service, from agriculture and construction to government institutions and manufacturing.
Why is Testing projected to account for 45.0% of product type demand in 2026?
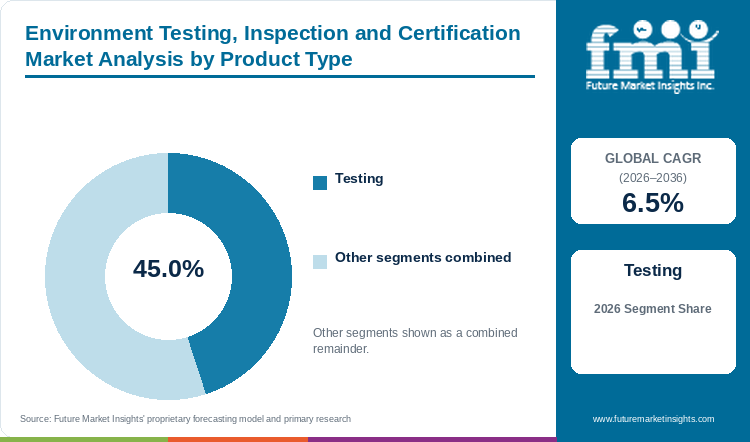
Table 3: Product Type Share for Environment Testing, Inspection and Certification Market (percentage share), 2026
| Product Type | Projected share (2026) |
|---|---|
| Testing | 45.0% |
| Other services | 55.0% |
| Total | 100.0% |
Table 4: Segment Position and Market Growth for Environment Testing, Inspection and Certification Market, 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.5% |
| Profiled product type segment | Testing |
A customer commissions testing to obtain a measured result for a defined substance, property or organism. The projected 2026 service breakdown assigns 45% to testing, ahead of inspection and certification. That position reflects a wide range of assignments, including scheduled monitoring and investigations into a specific environmental problem. The commercial specification needs to state the sample matrix, analytes, reporting limits and intended use of the results. A low headline price is less useful if the offered scope omits preparation or reporting work required by the customer. England's July 2025 MCERTS update shows that laboratory quality provisions continue to be refined. [2] Providers can distinguish an offer through the relevant technical scope and a clear responsibility for each stage of the assignment.
The Testing segment is projected to account for 45.0% of product type demand in 2026.
- Testing is projected to account for 45% of the product-type breakdown in 2026; other services together account for 55%.
- Testing, inspection and certification are separate services, even when one contract includes all three.
Why is Water Testing projected to account for 40.0% of sample type demand in 2026?
Table 5: Sample Type Share for Environment Testing, Inspection and Certification Market (percentage share), 2026
| Sample Type | Projected share (2026) |
|---|---|
| Water Testing | 40.0% |
| Other sample types | 60.0% |
| Total | 100.0% |
Water testing is projected to represent 40% of the projected 2026 sample-type breakdown. Utilities, industrial operators and other clients need different measurements depending on whether they are assessing drinking water, an effluent discharge or another water source. The sample matrix therefore determines which analytical capability is relevant. An emerging contaminant can also require collection practices that differ from the customer's established routine. EPA's 2025 PFAS guidance provides a concrete example of why contamination control and receipt checks matter before an instrument produces a result. [1] A provider that can explain the complete service, including collection arrangements and the treatment of an unsuitable sample, gives the purchaser a firmer basis for comparing bids and planning the monitoring programme.
The Water Testing segment is projected to account for 40.0% of sample type demand in 2026.
- Water testing is projected to hold 40% of the sample-type breakdown in 2026; other sample types together represent 60%.
- Drinking-water and effluent assignments require matrix-specific methods and a clear reporting purpose.
- Land investigations require sample-specific measurement and interpretation. The Soil Testing Market offers related coverage of that distinct set of customer needs.
What are the drivers, restraints, and opportunities in the Environment Testing, Inspection and Certification Market?
Recurring monitoring supports demand; method and sample requirements limit substitution; providers can strengthen their offer by coordinating fieldwork, analysis and interpretation.
Driver
Monitoring obligations and operational decisions create recurring demand for environmental measurements. Utilities need evidence about water quality, industrial sites need information about their releases, and project owners need to assess environmental conditions before or during development. Each assignment turns into a specific collection and testing scope. The quality of the evidence matters because a result may determine whether the client undertakes further investigation or corrective work. EPA's PFAS guidance illustrates that the service extends across field sampling and laboratory procedures. [1] Providers able to coordinate these tasks can compete for a larger portion of the assignment, particularly where a customer would otherwise manage several contractors.
Restraint
A laboratory cannot assume that an established capability covers every new analyte and sample matrix. Method development, competence assessment, reference materials and quality-control work can require time and investment before a service becomes routinely available. The buyer faces a related constraint: specifications from different jurisdictions or sample types may not be interchangeable. These differences complicate multinational contracts and can limit the immediate substitution of one laboratory for another. Transport arrangements and the condition of a sample on receipt also affect whether the analysis can proceed. The practical consequence is that capacity measured simply as sample throughput may overstate the capacity available for a particular customer's work.
Opportunity
Providers can make emerging analytical services easier to buy by explaining their scope and limitations in plain terms. JRC's 2025 microplastics report sets out practical considerations for a drinking-water methodology, while OECD's methods explorer helps users locate approaches relevant to substances and sample media. [3][4] These resources support a more informed specification; they do not themselves certify a laboratory or establish a universal method for every application. The opportunity lies in connecting a customer's monitoring objective with a defensible collection, analysis and reporting service. Clear reporting also helps the client decide when a result supports action and when further sampling or a different method is needed.
Industrial customers may combine measurement with equipment changes to manage emissions. The Industrial Air Filtration Market covers adjacent equipment purchases, separate from the laboratory-services contract.
Which country CAGRs are profiled in the Environment Testing, Inspection and Certification Market?
Table 6: Country CAGR Comparison for Environment Testing, Inspection and Certification Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| China | 7.5% |
| USA | 6.6% |
| Germany | 6.4% |
| UK | 5.9% |
| France | 5.7% |
Country-wise Analysis
China Environment Testing, Inspection and Certification Market Outlook (2026 to 2036)
China's broad industrial and urban customer base creates several distinct buying situations for environmental services. A manufacturing site may need recurring release monitoring, while a development project may commission a defined investigation of land or water conditions. The country's CAGR is projected at 7.5% for 2026 to 2036, the highest of the five profiles presented here. That estimate covers the market rather than the performance of every laboratory technique. For service providers, the commercial task is to match a customer's location, sample matrix and reporting requirement with appropriate field and laboratory capacity. A national account can require consistent data delivery across facilities without assuming that every site needs the same analytical package or sampling frequency.
USA Environment Testing, Inspection and Certification Market Outlook (2026 to 2036)
Drinking-water assignments show how closely US testing demand can depend on the details of the contracted method. EPA's updated 2025 PFAS guidance covers the collection and analysis chain, making the interaction between the sampler and laboratory relevant to service acceptance. [1] Industrial, construction and public-sector clients bring different monitoring questions and reporting arrangements. A provider bidding across those customer groups needs to distinguish its technical scope from its geographic reach. Buyers can then assess whether the proposed locations, collection arrangements and turnaround commitments suit the actual assignment, rather than treating a broad national laboratory network as proof of every required capability.
Germany Environment Testing, Inspection and Certification Market Outlook (2026 to 2036)
Environmental testing in Germany serves customers whose decisions span industrial operation, infrastructure development and resource management. Within that outlook, a customer's measurement question determines whether the order requires routine chemistry, specialist analysis or a wider inspection and certification programme. JRC's 2025 work on drinking-water microplastics provides relevant European methodological context, without representing a German market-size measure. [3] Providers can use technical clarity to support a bid: the report should make the method, sample scope and result limitations understandable to the client. A contract covering several sites also needs consistent reporting fields, so the customer can compare results without losing the context of individual locations.
UK Environment Testing, Inspection and Certification Market Outlook (2026 to 2036)
England's MCERTS standard gives a specific example of the quality requirements behind environmental water-testing work in the UK. Its July 2025 update covers several laboratory quality provisions. [2] Providers therefore need to distinguish the requirements applying to a particular assignment from the scope of the overall market. An effluent-monitoring customer, for example, needs an appropriate sampling and analysis service with usable records and dependable turnaround. A broader environmental assessment may involve additional fieldwork and interpretation. Commercial proposals become easier to assess when these tasks are priced and described clearly rather than compressed into one undifferentiated service label.
France Environment Testing, Inspection and Certification Market Outlook (2026 to 2036)
A project owner in France may purchase environmental services at several stages, from an initial assessment through construction monitoring and later operation. Those stages create different sample volumes, deadlines and reporting needs. The growth estimate does not imply identical demand for all test types or customer groups. Laboratories and inspection providers need to identify the assignments for which their technical scope and mobilisation capacity fit the customer's programme. For recurring contracts, reliable collection schedules and consistent reporting can matter alongside analytical price. For a one-off investigation, the ability to define the question and explain the meaning of the result may have greater influence on the purchase decision.
Who are the notable companies in the Environment Testing, Inspection and Certification Market?
SGS SA; Intertek Group; Bureau Veritas; Eurofins Scientific; ALS Ltd
SGS SA, Intertek Group, Bureau Veritas, Eurofins Scientific and ALS Ltd are representative participants in the published market coverage. Their relevant capabilities differ by service and location, so the comparison should begin with an equivalent customer requirement. A laboratory analysis contract is different from an assignment that also includes field sampling, inspection or certification. A large corporate network may provide access to several capabilities, but the customer still needs confirmation that the proposed location and team cover the required work.
Competitive Benchmarking: Environment Testing, Inspection and Certification Market
Table 7: Competitive positioning for the environment testing, inspection and certification market
| Company | Positioning | Buyer comparison focus |
|---|---|---|
| SGS SA | Environmental TIC services | Compare relevant service scope and reporting across the proposed sites. |
| Intertek Group | Environmental testing and inspection | Specify fieldwork, analysis and interpretation responsibilities separately. |
| Bureau Veritas | Environmental assurance and inspection | Assess the inspection scope and evidence required for the assignment. |
| Eurofins Scientific | Environmental laboratory analysis | Match sample matrices and analytes with the laboratory scope offered. |
| ALS Ltd | Environmental laboratory and analytical services | Review sample logistics, analytical scope and turnaround commitments. |
Key Developments in the Environment Testing, Inspection and Certification Market
- EPA updated its PFAS collection and analysis guidance in September 2025. [1]
- The Environment Agency revised its MCERTS water-testing standard on 31 July 2025. [2]
- JRC published its microplastics practical-considerations report on 25 August 2025. [3]
Key Players in the Environment Testing, Inspection and Certification Market
Environmental TIC services
- SGS SA
Environmental testing and inspection
- Intertek Group
Environmental assurance and inspection
- Bureau Veritas
Environmental laboratory analysis
- Eurofins Scientific
Environmental laboratory and analytical services
- ALS Ltd
Environment Testing, Inspection and Certification Market Report Scope
Table 8: Report Scope for Environment Testing, Inspection and Certification Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market coverage | Environmental testing, inspection and certification for industrial, public-sector and other customers. |
| Units | USD billion and percentage |
| Published quantitative reference | 2025 market baseline and 2035 published endpoint |
| Forecast outlook | 2026 to 2036 projections |
| Market breakdown | Product Type; End User; Sample Type; Test Type |
| Segment reference year | 2026 projected |
| Country comparison period | 2026 to 2036 |
| Representative companies | SGS SA; Intertek Group; Bureau Veritas; Eurofins Scientific; ALS Ltd |
Environment Testing, Inspection and Certification Market Research Methodology
Table 9: Research Methodology for Environment Testing, Inspection and Certification Market, 2026 edition
| Method | Approach |
|---|---|
| Market estimates | FMI supplies the published baseline, endpoint and market growth estimate. |
| Forecast outlook | The market is forecast at USD 23.00 billion in 2026 and USD 43.18 billion in 2036, with a CAGR of 6.5%. |
| Share comparisons | Testing and water-testing shares describe separate projected 2026 breakdowns. |
| Country comparison | Country CAGRs are projected over 2026 to 2036. |
| Public evidence | Dated EPA, Environment Agency, JRC and OECD material supports the method and procurement discussion. |
| Company assessment | Representative participants are compared using buyer service requirements. |
Environment Testing, Inspection and Certification Market by Segments
Environment Testing, Inspection and Certification Market segmented by Product Type:
- Testing
- Inspection
- Certification
Environment Testing, Inspection and Certification Market segmented by End User:
- Agriculture industry
- Construction industry
- Government institutes
- R&D laboratories
- Industrial product manufacturers
- Other end users
Environment Testing, Inspection and Certification Market segmented by Sample Type:
- Water testing
- Air testing
- Soil testing
- Building materials
- Waste testing
- Fuel/oil testing
Environment Testing, Inspection and Certification Market segmented by Test Type:
- Toxins
- Chemicals
- Pathogens
- Physical properties
- Metals
- Organic matter
- Nutrients/elements/minerals
- Inorganics
- pH test
- Other types
Environment Testing, Inspection and Certification Market by Region
- North America
- United States
- Canada
- Mexico
- Latin America
- Brazil
- Argentina
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Eastern Europe
- Poland
- Czech Republic
- Romania
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia
- New Zealand
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
Research Sources and Bibliography
- [1] US Environmental Protection Agency. Updated September 2025. Requirements and Best Practices for the Collection and Analysis of Samples for the PFAS National Primary Drinking Water Regulation
- [2] Environment Agency. Updated 31 July 2025. MCERTS: performance standard for organisations undertaking sampling and chemical testing of water
- [3] European Commission Joint Research Centre. 25 August 2025. Analysing microplastics in drinking water: Practical considerations
- [4] OECD. Updated July 2026. Analytical Methods for Substances in Environmental Media (AMSEM) Explorer for Chemicals
This Report Answers
- How big is the market in the 2026 outlook?
- What is the projected market size in 2036?
- Which service leads the projected breakdown?
- Which sample type has the largest projected share?
- Which country has the highest profiled CAGR?
- Do the country rates describe the global forecast period?
Frequently Asked Questions
What is the estimated market size in 2026?
The forecast outlook projects USD 23.00 billion for 2026, compared with the published 2025 baseline of USD 21.6 billion.
What is the projected market size in 2036?
The forecast is USD 43.18 billion in 2036 at a 6.5% forecast CAGR. The separately published FMI endpoint is USD 38 billion for 2035.
Which service leads the projected breakdown?
Testing is projected to account for 45% of the product-type breakdown in 2026.
Which sample type has the largest projected share?
Water testing is projected to hold 40% of the sample-type breakdown in 2026.
Which country has the highest profiled CAGR?
China has the highest CAGR among these five profiles, at 7.5% for 2026 to 2036.
Do the country rates describe the global forecast period?
Yes. The country CAGRs are projected for 2026 to 2036, matching the global forecast period.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Testing
- Inspection
- Certification
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End User, 2026 to 2036
- Agriculture industry
- Construction industry
- Government institutes
- R&D laboratories
- Industrial product manufacturers
- Other end users
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Sample Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sample Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sample Type, 2026 to 2036
- Water testing
- Air testing
- Soil testing
- Building materials
- Waste testing
- Fuel/oil testing
- Y-o-Y Growth Trend Analysis By Sample Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Sample Type, 2026 to 2036
- Global Market Analysis and Forecast, By Test Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Test Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Test Type, 2026 to 2036
- Toxins
- Chemicals
- Pathogens
- Physical properties
- Metals
- Organic matter
- Nutrients/elements/minerals
- Inorganics
- pH test
- Other types
- Y-o-Y Growth Trend Analysis By Test Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Test Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Product Type
- By End User
- By Sample Type
- By Test Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End User
- By Sample Type
- By Test Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Argentina
- By Product Type
- By End User
- By Sample Type
- By Test Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End User
- By Sample Type
- By Test Type
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- By Product Type
- By End User
- By Sample Type
- By Test Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End User
- By Sample Type
- By Test Type
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- By Product Type
- By End User
- By Sample Type
- By Test Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End User
- By Sample Type
- By Test Type
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By End User
- By Sample Type
- By Test Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End User
- By Sample Type
- By Test Type
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia
- New Zealand
- By Product Type
- By End User
- By Sample Type
- By Test Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End User
- By Sample Type
- By Test Type
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Saudi Arabia
- United Arab Emirates
- South Africa
- By Product Type
- By End User
- By Sample Type
- By Test Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End User
- By Sample Type
- By Test Type
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- By Sample Type
- By Test Type
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- By Sample Type
- By Test Type
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- By Sample Type
- By Test Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- By Sample Type
- By Test Type
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- By Sample Type
- By Test Type
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- By Sample Type
- By Test Type
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- By Sample Type
- By Test Type
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- By Sample Type
- By Test Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- By Sample Type
- By Test Type
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- By Sample Type
- By Test Type
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- By Sample Type
- By Test Type
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- By Sample Type
- By Test Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- By Sample Type
- By Test Type
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- By Sample Type
- By Test Type
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- By Sample Type
- By Test Type
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- By Sample Type
- By Test Type
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By End User
- By Sample Type
- By Test Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- SGS SA
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Intertek Group
- Bureau Veritas
- Eurofins Scientific
- ALS Ltd
- SGS SA
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


