
- Market Size (2026)
- USD 652.5 Bn
- Forecast (2036)
- USD 1179.6 Bn
- CAGR (2026 to 2036)
- 6.1%
How big is Fermented Food and Beverage Market in 2026?
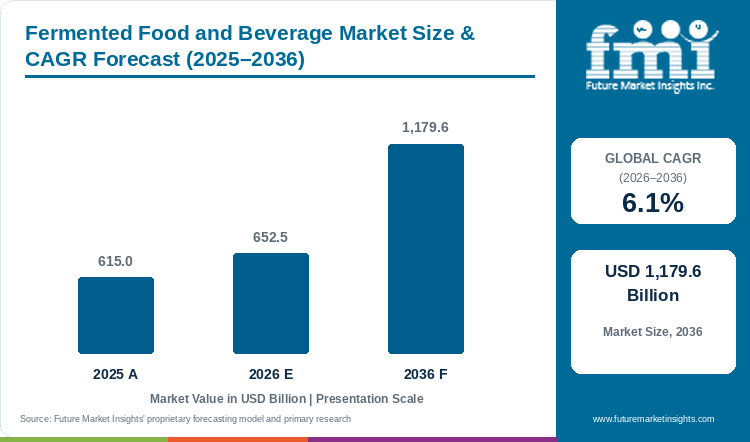
Worldwide fermented food and beverage industry valuation stands at USD 615.0 billion for 2025 and reaches USD 652.5 billion during 2026, with a projected 6.1% CAGR lifting total market size to USD 1,179.6 billion by 2036.
Heavy reliance on ultra-processed meals and frequent antibiotic courses has disrupted intestinal flora across urban populations, prompting households to incorporate live cultured foods into daily meal routines. A May 2025 clinical review published in Foods reported that consuming 300 milliliters of kefir daily for three weeks reduced fecal Escherichia coli counts by 40% and lowered serum zonulin by 18% in adults while water kefir fermentation generated 48.3 millimolar acetate within six hours. Backed by this clinical shift toward food-based gut modulation, Fermented Dairy is projected to claim 45.3% of 2026 product category valuation across processors formulating cultured probiotic yogurts. According to FMI, worldwide fermented food and beverage valuation climbs from a 2025 baseline of USD 615.0 billion to USD 652.5 billion during 2026, and a projected 6.1% CAGR brings 2036 market size to USD 1,179.6 billion for an absolute ten-year expansion of USD 527.1 billion. Even so, strict cold-chain electricity overhead and post-acidification spoilage during warm-weather transit continue to restrain margin expansion across emerging retail corridors.
Key Market Trends & Insights
- By product category: Fermented Dairy is projected to claim 45.3% for 2026 because casein and whey buffers protect live probiotic cells against gastric acid.
- By microbial starter: Lactic Acid Bacteria is estimated to command 41.7% during 2026 owing to predictable acidification kinetics and bacteriocin synthesis.
- By distribution channel: Supermarkets & Hypermarkets are expected to account for 43.9% in 2026 driven by multi-deck chilled dairy cases and weekly family grocery trips.
- By health positioning: Gut Microbiome & Live Probiotic is forecast to secure 47.7% throughout 2026 attributed to documented strain-level digestive and immune claims.
- By packaging format: Glass Bottles & Jars are anticipated to reach 49.3% across 2026 supported by zero oxygen permeation and chemical inertness under low pH.
- By storage requirement: Refrigerated Cold-Chain 2°C to 6°C is slated to hold 62.9% in 2026 since chilled holding arrests yeast over-carbonation and preserves viable colony counts.
- By consumption channel: At-Home Retail Grocery is predicted to generate 65.1% for 2026 enabled by multi-serve family tubs and morning breakfast consumption habits.
Regional Highlights
- East Asian and Latin American acceleration: South Korea is projected to pace national expansion at a 7.2% CAGR through 2036 ahead of Brazil at 6.9% as packaged kimchi exports and drinkable yogurt distribution scale.
- North American and European progression: The USA is expected to advance at a 5.6% annual rate through 2036 ahead of Germany (5.3%) and Japan (5.1%) on account of high-protein skyr and functional lactobacillus drink adoption.
Market Size & Forecast
Table 1: Global Fermented Food and Beverage Market Valuation Trajectory (USD billion and compound annual growth), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 615.0 billion |
| Estimated Market Size in 2026 | USD 652.5 billion |
| Projected Market Size by 2036 | USD 1,179.6 billion |
| CAGR, 2026 to 2036 | 6.1% |
| Added Market Value, 2026 to 2036 | USD 527.1 billion |
Multinational dairy and beverage groups are shifting capital toward high-protein cultured lines and clinically validated gut-health drinks to protect retail shelf margins. In February 2026, Danone S.A. reported full-year 2025 consolidated turnover of EUR 27,283 million with 4.5% like-for-like growth led by Essential Dairy and Plant-Based volume gains across Activia and YoPRO. Consequently, commercial dairies are expanding single-serve fermented kefir beverages that deliver twelve live probiotic strains per bottle without artificial thickeners. Formulators that lock in proprietary culture libraries and automated cold-fill lines are well placed to secure nationwide grocery contracts.
Bioreactor Fermentation Throughput and Viable-Cell Sizing
Table 2: Bioreactor Throughput and Viable-Culture Sizing for the Fermented Food and Beverage Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 615.0 | 652.5 | 1,179.6 |
| Commercial fermented food and drink output (million metric tons) | 198.0 to 214.0 | 208.0 to 225.0 | 335.0 to 365.0 |
| Inoculated starter culture volume (thousand metric tons) | 420.0 to 465.0 | 445.0 to 492.0 | 740.0 to 820.0 |
| Minimum retail shelf-end probiotic density (log CFU per gram or mL) | 7.0 to 8.0 | 7.5 to 8.5 | 8.0 to 9.5 |
Operational note: Output ranges reconcile commercial dairy and plant fermentation tonnage against standard 10^7 to 10^9 CFU per gram live-culture viability thresholds at retail expiration.
Industrial fermentation plants depend on phage-resistant freeze-dried inoculants to keep vat acidification times consistent across 50,000-liter stainless-steel tanks. In addition to this, quality assurance teams procure commercial starter cultures with verified bile-salt hydrolase activity so ingested strains survive stomach transit.
Per Capita & Retail Cold-Chain Sizing
Table 3: Household Chiller Allocation and Per-Capita Metrics in the Fermented Food and Beverage Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Annual market value per capita (USD) | 75.0 | 78.6 | 131.1 |
| Annual fermented food valuation per household (USD) | 265.0 to 295.0 | 278.0 to 310.0 | 430.0 to 485.0 |
| Chilled 2°C to 6°C display allocation in grocery (%) | 61.0% to 63.5% | 62.0% to 64.0% | 65.0% to 68.0% |
Table 4: Cultured Dairy and Cold-Chain Valuation Splits in the Fermented Food and Beverage Market (USD and share percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 652.5 billion | 2026 global fermented category valuation baseline |
| Fermented dairy category valuation, 2026 | USD 295.6 billion | 45.3% product category segment allocation |
| Refrigerated cold-chain valuation, 2026 | USD 410.4 billion | 62.9% storage requirement segment allocation |
| At-home retail grocery valuation, 2026 | USD 424.8 billion | 65.1% consumption channel segment allocation |
Supermarket category buyers dedicate prime eye-level chilled shelving to multi-pack probiotic shots and low-sugar fermented teas that drive high weekly basket frequency. Because household shoppers increasingly compare live colony counts on front-of-pack labels, beverage brands pair spoonable dairy tubs with functional probiotic drinks across neighborhood grocery chains.
Analyst Perspective
"Food and beverage processors that pair genomic strain selection with automated cold-chain packaging are capturing multi-year supermarket shelf allocations. High refrigerated freight rates and strict national probiotic health-claim rules still require disciplined formulation control."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the fermented food and beverage market segmented?
The fermented food and beverage market is segmented by product category, microbial starter, distribution channel, health positioning, packaging format, storage requirement, consumption channel, and region. In 2026, Fermented Dairy is projected at 45.3%, Lactic Acid Bacteria at 41.7%, Supermarkets & Hypermarkets at 43.9%, Gut Microbiome & Live Probiotic at 47.7%, Glass Bottles & Jars at 49.3%, Refrigerated Cold-Chain 2°C to 6°C at 62.9%, and At-Home Retail Grocery at 65.1%.
By product category: Fermented Dairy, Fermented Beverages, Fermented Soy & Legumes, and Fermented Vegetables & Sourdough.
By microbial starter: Lactic Acid Bacteria, Saccharomyces & Specialty Yeasts, and Aspergillus Koji & Mixed SCOBY Cultures.
By distribution channel: Supermarkets & Hypermarkets, Health & Natural Food Stores, and Online Retail & Foodservice.
By health positioning: Gut Microbiome & Live Probiotic, Naturally Low-Sugar & Organic Acid, High-Protein & Bioavailable Amino Acid, and Clean-Label Artisanal & Heritage.
By packaging format: Glass Bottles & Jars, HDPE & PET Chilled Tubs and Bottles, Sleek Aluminum Cans, and Flexible Vacuum Pouches & Wraps.
By storage requirement: Refrigerated Cold-Chain 2°C to 6°C, and Ambient Shelf-Stable Pasteurized.
By consumption channel: At-Home Retail Grocery, and On-Premise Restaurants, Cafes & Taprooms.
Why does Fermented Dairy lead the product category?
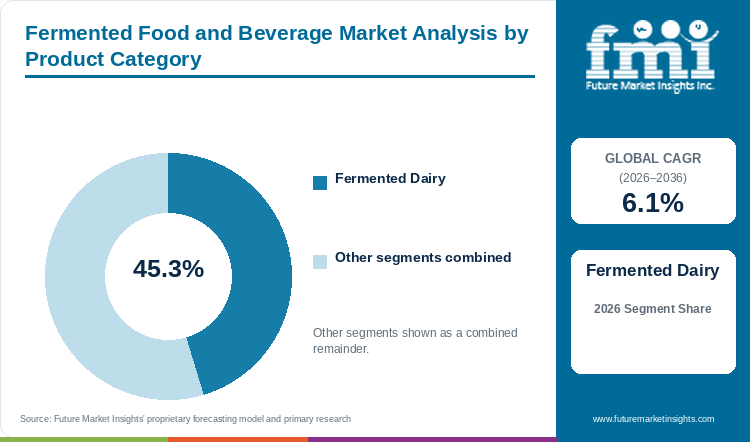
Fermented Dairy is projected to claim 45.3% of product category valuation in 2026, supported by casein buffering.
Table 5: Product Category Allocation in the Fermented Food and Beverage Market (percentage share), 2026
| Product Category | Share (2026) |
|---|---|
| Fermented Dairy | 45.3% |
| Other Segments Combined | 54.7%* |
| Total | 100.0% |
*Note: Remaining product category segments sum to 100.0% of 2026 market valuation.
Table 6: Leading Product Category and Ten-Year Compound Pace in the Fermented Food and Beverage Market (segment and CAGR), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.1% |
| Leading Segment | Fermented Dairy |
Milk proteins and milk fat globule membranes naturally shield live bacterial cultures against low stomach pH while releasing bioactive tripeptides during vat incubation. Whereas fermented vegetables and artisanal sourdough breads serve specific meal courses, spoonable yogurts and drinkable kefirs fit daily breakfast and snacking occasions across all age groups.
- Fermented Dairy is projected to hold 45.3% of product category market size during 2026 due to universal household familiarity and dense calcium delivery.
- In February 2026, Nestlé S.A. documented in its 2025 Annual Review that consolidated sales totaled CHF 89.5 billion with Milk Products and Ice Cream contributing 10.8% across 185 countries.
How do Lactic Acid Bacteria maintain top share among microbial starters?
Lactic Acid Bacteria is estimated to command 41.7% of microbial starter market size for 2026, driven by homofermentative acidification.
Commercial dairies and vegetable fermenters rely on Lactobacillus and Streptococcus thermophilus strains because rapid lactic acid output drops substrate pH below 4.5 to block pathogen growth. Unlike wild yeast or mold fermentations that require weeks of curing, selected lactic acid bacteria strains complete vat coagulation within four to eight hours while synthesizing exopolysaccharides that prevent whey separation.
- Lactic Acid Bacteria is estimated to generate 41.7% of the microbial starter segment in 2026 owing to broad regulatory clearance and repeatable texture control.
- In December 2025, Yakult Honsha Co., Ltd. reported that global daily consumption of dairy products fermented with Lacticaseibacillus paracasei strain Shirota reached roughly 38.00 million bottles across 40 countries and regions.
What keeps Supermarkets & Hypermarkets first in distribution channels?
Supermarkets & Hypermarkets are expected to account for 43.9% of distribution channel market size in 2026, backed by cold-aisle capacity.
Large-format grocery chains operate continuous glass-door refrigeration aisles capable of displaying hundreds of cultured dairy and chilled kimchi SKUs side by side. Value-conscious families prefer buying multi-pack fermented dairy tubs and condiment jars during weekly supermarket runs rather than paying single-item delivery fees online.
- Supermarkets & Hypermarkets are expected to claim 43.9% of distribution channel valuation during 2026 since high-turnover grocery chillers minimize cold-chain dwell time.
- In September 2026, USDA Economic Research Service food price data showed that August 2026 supermarket grocery prices increased 2.2% over the prior year versus 3.4% for restaurant meals, reinforcing at-home grocery shopping.
Why does Gut Microbiome & Live Probiotic anchor health positioning?
Gut Microbiome & Live Probiotic is forecast to secure 47.7% of health positioning valuation during 2026, attributed to strain-level claims.
Retail shoppers actively scan front-of-pack panels for verified colony-forming-unit counts and named Bifidobacterium or Lactobacillus strains that relieve bloating and support mucosal immunity. Beverage makers formulating brewed kombucha teas and multi-strain kefirs command price premiums of 25% to 40% over unfermented juices by guaranteeing live cultures through expiration.
- Gut Microbiome & Live Probiotic is forecast to reach 47.7% of health positioning market value in 2026 aided by gastroenterologist dietary recommendations.
- In November 2025, Lifeway Foods Inc. reported record third-quarter 2025 net sales of USD 57.1 million (up 24.0% year-on-year) across its 12-strain probiotic kefir portfolio as household penetration of gut-health dairy drinks expanded nationwide.
What gives Glass Bottles & Jars the largest share of packaging formats?
Glass Bottles & Jars are anticipated to reach 49.3% of packaging format market size in 2026, enabled by gas-barrier inertness.
Organic acids and dissolved carbon dioxide in kombucha or pickled vegetables can leach monomers from thin plastic walls when oxygen permeates polymer containers. Impermeable returnable glass bottles and jars block oxygen ingress completely while withstanding internal carbonation pressure from secondary yeast fermentation.
- Glass Bottles & Jars are anticipated to hold 49.3% of packaging format valuation during 2026 fueled by zero flavor scalping and curb-side glass recyclability.
- In August 2025, Kikkoman Corporation reported first-quarter fiscal 2026 consolidated revenue of JPY 175,660 million and business profit of JPY 19,532 million across its global brewed soy sauce and food operations packaged in glass dispensers and bottles.
Why does Refrigerated Cold-Chain 2°C to 6°C dominate storage requirements?
Refrigerated Cold-Chain 2°C to 6°C is slated to hold 62.9% of storage requirement valuation in 2026, owing to thermal metabolic dormancy.
Unpasteurized fermented foods contain metabolically active bacteria and yeasts that continue consuming residual sugars if exposed to ambient room temperatures, which causes container swelling and rapid probiotic die-off. Strict 2°C to 6°C distribution inside insulated cold-chain packaging systems keeps live microbes dormant so flavor and colony counts remain stable for 30 to 90 days.
- Refrigerated Cold-Chain 2°C to 6°C is slated to command 62.9% of storage requirement market size for 2026 because heat pasteurization destroys live probiotic claim eligibility.
- In March 2026, CJ CheilJedang Corp. reported full-year 2025 consolidated sales of KRW 27,342.6 billion supported by chilled Bibigo fermented kimchi and refrigerated culinary exports across North America and Asia.
How does At-Home Retail Grocery stay ahead in consumption channels?
At-Home Retail Grocery is predicted to command 65.1% of consumption channel valuation in 2026, guided by daily breakfast routines.
Clinical gut-microbiome benefits require consistent daily ingestion over four to twelve weeks, making domestic refrigerators the primary venue for cultured dairy and fermented vegetables. Multi-serve 500-gram to 1-kilogram retail tubs reduce per-serving cost by more than half when compared with on-premise cafe parfaits or taproom kombucha pours.
- At-Home Retail Grocery is predicted to secure 65.1% of consumption channel market value during 2026 on account of recurring morning and evening household dining habits.
- In May 2026, Lifeway Foods, Inc. filed its first-quarter 2026 Form 8-K release reporting record quarterly net sales of USD 63.0 million (up 36.7% year-on-year) driven by at-home grocery demand for Lifeway Kefir and high-protein Farmer Cheese.
What are the drivers, restraints, and opportunities in the fermented food and beverage market?
Across the fermented food and beverage market, clinical gut-microbiome awareness and GLP-1 high-protein nutrition are projected to expand retail volume whereas cold-chain energy costs restrain rural reach and precision postbiotic fermentation creates margin opportunities.
- Driver: Mainstream clinical adoption of probiotic and high-protein fermented foods for digestive health and lean muscle retention fuels weekly supermarket replenishment.
- Restraint: Continuous 2°C to 6°C refrigeration energy overhead and live-yeast CO2 refermentation risks elevate spoilage write-offs across long-distance transit.
- Opportunity: Genomic starter screening and precision postbiotic fortification allow processors to launch low-sugar functional drinks with verified shelf stability.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Primary-care physicians and dietitians increasingly recommend live fermented dairy and vegetable matrices to counteract antibiotic-associated dysbiosis and support satiety among patients using GLP-1 weight-management therapies. Strained Greek yogurts and fortified probiotic milk shots deliver 15 to 20 grams of bioavailable protein together with billions of live lactic acid bacteria in compact servings. During December 2025, Yakult Honsha Co., Ltd. released its 2025 annual corporate review showing how its flagship Yakult 1000 series delivers 100 billion Lacticaseibacillus paracasei strain Shirota cells per 100-milliliter bottle to relieve temporary mental stress and improve sleep quality. Supermarket chains consequently expand chilled functional dairy doors to capture recurring household wellness budgets.
Risk Assessment of the Fermented Food and Beverage Market: Operational and Formulation Friction
Strict maintenance of live microbial counts between 10^7 and 10^9 CFU per gram without exceeding legal alcohol limits or rupturing seals poses a persistent technical hurdle for commercial beverage and condiment plants. Wait-time temperature excursions in delivery trucks can push natural kombucha ethanol above the 0.5% non-alcoholic threshold while causing sour whey syneresis in yogurt cups. In February 2026, Danone S.A. filed its 2025 Universal Registration Document on its Regulated Information portal detailing how cold-chain logistics inflation and national health-claim substantiation standards remain key operational risk factors across dairy markets. Smaller craft fermenters without automated tunnel pasteurizers or micro-filtration lines face high retail spoilage chargebacks.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Biotechnology-guided starter screening is opening high-margin opportunities in precision postbiotics and gas-absorber-equipped pouches for traditional fermented kimchi and miso. By pairing homofermentative lactic starters with heat-stabilized postbiotic metabolites, manufacturers can extend ambient and chilled shelf life while preserving tight-junction barrier benefits. In September 2026, Danone S.A. and its Biotech Open Platform partners inaugurated a EUR 20 million-plus industrial biotechnology facility with 15 cubic meters of fermentation capacity in Clermont-Ferrand, France to scale precision fermentation processes across Europe. Processors that validate strain-specific metabolic outcomes in human trials can command preferred pharmacy and grocery placement.
Fermented Food and Beverage Market by Country (2026 to 2036)
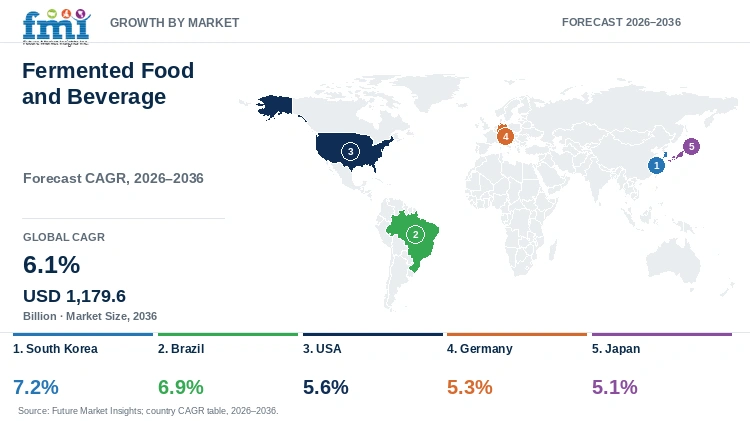
South Korea is projected to pace national fermented food and beverage valuation at a 7.2% CAGR through 2036, followed closely by Brazil at 6.9%.
FMI country modeling places South Korea at the front of national fermented food and beverage expansion with a 7.2% CAGR through 2036 ahead of Brazil (6.9%) and the USA (5.6%), whilst Germany records 5.3% and Japan posts 5.1%. Export-oriented packaged kimchi and jang paste automation in East Asia as well as high-protein cultured dairy expansion across the Americas and Europe govern country-level trajectories.
Table 7: National Fermented Food and Beverage Market Compound Growth Rates and Core Demand Catalysts, 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| South Korea | 7.2% | Packaged kimchi export scaling, patented Leuconostoc starters, and MFDS functional probiotic drinks |
| Brazil | 6.9% | Expanding supermarket chilled dairy penetration and tropical fruit kefir and drinkable yogurt adoption |
| USA | 5.6% | High-protein Greek yogurt and skyr capacity expansion paired with retail kefir and kombucha growth |
| Germany | 5.3% | Industrial quark and kefir dairy processing combined with organic sauerkraut and sourdough retail demand |
| Japan | 5.1% | Foods with Function Claims (FFC) probiotic dairy shots and automated koji soy and miso brewing |
Source: Future Market Insights analysis
South Korea Fermented Food and Beverage Market Outlook (2026 to 2036)
South Korea anchors East Asian growth because single-person urban households increasingly replace home autumn kimjang preparation with factory-fermented pouch kimchi and Ministry of Food and Drug Safety certified probiotic dairy shots. In August 2026, CJ CheilJedang Corp. published its second-quarter 2026 business results on its investor portal documenting expanded overseas K-food sales led by chilled Bibigo kimchi and fermented condiments across North America and Europe. Fermented food and beverage valuation in South Korea is projected to climb at a 7.2% CAGR through 2036 as processors deploy patented Leuconostoc mesenteroides starters and one-way CO2 degassing valves. Elevated napa cabbage farm prices still pressure domestic margins, prompting automated cold-storage cabbage reserves.
Key takeaway: In South Korea, commercial replacement of home kimchi making and export pouch packaging are projected to fuel the strongest national valuation gains.
Brazil Fermented Food and Beverage Market Outlook (2026 to 2036)
Wider middle-class access to modern cold-chain hypermarkets and cash-and-carry atacarejo stores is accelerating drinkable yogurt and fruit-infused kefir consumption across Brazil. In October 2026, FAS attaché analysts in Brasilia examined how 2026 El Niño weather patterns across southern and central Brazil affect domestic grain and dairy feed processing costs. Brazil's fermented food and beverage market value is expected to expand at a 6.9% compound annual pace through 2036 as multinational and regional dairies localize zero-lactose probiotic smoothies in 170-gram and 900-gram HDPE bottles. High refrigerated highway freight costs across interior states nonetheless encourage processors to co-locate fermentation plants near São Paulo and Minas Gerais.
Key takeaway: In Brazil, modern atacarejo chiller expansion and lactose-free drinkable probiotic dairy lines are expected to sustain rapid national volume growth.
USA Fermented Food and Beverage Market Outlook (2026 to 2036)
Strong retail demand for zero-sugar strained Greek yogurt together with 12-strain drinkable kefir positions the United States as the largest national revenue center for fermented foods and beverages. In February 2025, GT's Living Foods LLC marked 30 years of raw organic fermentation by supplying over 100 million bottles annually of unpasteurized kombucha and living coconut yogurt across U.S. grocery chains. Fermented food and beverage market size across the USA is anticipated to advance at a 5.6% annual rate through 2036 as consumers using metabolic therapies prioritize protein-dense, gut-friendly snacks. Strict FDA probiotic labeling enforcement still requires commercial brands to verify live colony survival through printed expiration dates.
Key takeaway: In the USA, high-protein cultured dairy expansion and mainstream supermarket adoption of drinkable kefir are anticipated to support billions in new valuation.
Germany Fermented Food and Beverage Market Outlook (2026 to 2036)
Germany combines Europe's largest industrial quark and kefir dairy processing infrastructure with deep household consumption of lactic-fermented sauerkraut and rye sourdough bread. During June 2026, European dairy economists at the USDA Foreign Agricultural Service reported in the European Union Dairy and Products Semi-annual bulletin that 2026 EU milk output is forecast at 152.8 million metric tons while cultured dairy and cheese processing reaches 11 million metric tons led by German dairies. The fermented food and beverage market value in Germany is forecast to rise at a 5.3% CAGR from 2026 to 2036 as discount and supermarket chains expand organic bio-certified chilled doors. Even so, reusable Pfand glass bottle logistics add recurring compliance costs for regional suppliers.
Key takeaway: In Germany, entrenched per-capita quark and kefir consumption paired with organic fermented vegetable demand is forecast to support steady market growth.
Japan Fermented Food and Beverage Market Outlook (2026 to 2036)
Japan's Consumer Affairs Agency Foods with Function Claims (FFC) framework and traditional washoku reliance on Aspergillus oryzae koji fermentation create a mature, innovation-driven domestic marketplace. In July 2026, Kikkoman Corporation released its Fiscal 2026 Factbook detailing domestic and overseas naturally brewed soy sauce and fermented condiment performance. Japan's fermented food and beverage industry size is slated to register a 5.1% yearly growth pace through 2036 as seniors and office workers purchase daily probiotic dairy bottles claimed to improve sleep quality and enteric immunity. Demographic contraction in rural Japanese prefectures still compels domestic brewers to focus new product launches on high-value functional single-serve bottle formats.
Key takeaway: In Japan, Foods with Function Claims probiotic dairy drinks and precision koji brewing are slated to sustain high-margin per-capita valuation.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the fermented food and beverage market?
Danone S.A., Nestlé S.A., Yakult Honsha Co., Ltd., Chobani, LLC, CJ CheilJedang Corp., Kikkoman Corporation, GT's Living Foods LLC, and Lifeway Foods, Inc. are the notable companies in the fermented food and beverage market.
FMI analysis indicates that competitive positioning across fermented foods and beverages hinges on proprietary microbial strain banks and refrigerated grocery distribution scale. Multinational dairy and probiotic leaders including Danone S.A. and Yakult Honsha together with Nestlé S.A. operate global cold-chain networks and clinically studied Lactobacillus and Bifidobacterium portfolios. High-growth cultured dairy and Asian fermentation specialists led by Chobani LLC and CJ CheilJedang Corp. as well as Kikkoman Corporation scale strained Greek yogurt and naturally brewed soy condiments across retail and foodservice channels. Meanwhile, GT's Living Foods LLC and Lifeway Foods Inc. anchor North American raw kombucha and drinkable probiotic kefir categories.
- Global Probiotic Dairy & Nutrition Platforms: Danone S.A. and Yakult Honsha Co., Ltd. together with Nestlé S.A. manage multi-continent dairy fermentation plants and clinically substantiated probiotic strain libraries.
- Strained Dairy & Asian Koji/Kimchi Leaders: Chobani, LLC and CJ CheilJedang Corp. along with Kikkoman Corporation lead high-protein cultured dairy and Aspergillus-brewed soy condiments.
- Specialty Kombucha & Kefir Beverage Innovators: GT's Living Foods LLC and Lifeway Foods, Inc. specialize in raw organic SCOBY-fermented kombucha and 12-strain refrigerated kefir beverages.
Competitive Benchmarking: Fermented Food and Beverage Market
Table 8: Supplier Capability Matrix for the Fermented Food and Beverage Market (qualitative ratings), 2026
| Company | Microbial Strain IP & R&D | Fermentation Category Breadth | Cold-Chain Retail Reach | Geographic Reach |
|---|---|---|---|---|
| Danone S.A. | High | High | High | High |
| Nestlé S.A. | High | High | High | High |
| Yakult Honsha Co., Ltd. | High | Medium | High | High |
| Chobani, LLC | Medium | High | High | Medium |
| CJ CheilJedang Corp. | High | High | High | High |
| Kikkoman Corporation | High | Medium | High | High |
| GT's Living Foods LLC | Medium | Medium | High | Medium |
| Lifeway Foods, Inc. | High | Medium | High | Medium |
Evaluation basis: Capability tiers assess proprietary lactic acid bacteria and koji culture collections as well as bioreactor scale and verified probiotic survival through shelf expiration. Cold-chain retail and geographic ratings reflect direct supermarket chiller distribution and multi-region manufacturing footprints.
Key Developments in the Fermented Food and Beverage Market
- Lifeway Foods, Inc. announced in August 2026 its highest quarterly net sales in company history during the second quarter of 2026 driven by sustained retail velocity for Lifeway Kefir and ProBugs.
- In July 2026, French dairy group Danone S.A. achieved 4.2% second-quarter like-for-like sales expansion as volume-mix gains in Activia gut-health yogurts and Actimel probiotic shots accelerated across Europe and North America.
- CJ CheilJedang Corp. expanded its North American fermented K-food and chilled Bibigo kimchi sampling footprint at KCON LA in August 2026 to accelerate U.S. mainstream grocery distribution.
Key Players in the Fermented Food and Beverage Market
Global Probiotic Dairy & Nutrition Platforms
- Danone S.A.
- Nestlé S.A.
- Yakult Honsha Co., Ltd.
Strained Dairy & Asian Koji/Kimchi Leaders
- Chobani, LLC
- CJ CheilJedang Corp.
- Kikkoman Corporation
Specialty Kombucha & Kefir Beverage Innovators
- GT's Living Foods LLC
- Lifeway Foods, Inc.
Fermented Food and Beverage Market - Report Scope
Table 9: Fermented Food and Beverage Market Coverage Parameters and Definitions, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Category; Microbial Starter; Distribution Channel; Health Positioning; Packaging Format; Storage Requirement; Consumption Channel; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial manufacturer and processor market value from finished foods and non-alcoholic beverages produced via controlled microbial fermentation (cultured dairy yogurt, kefir, skyr, kombucha, water kefir, fermented soy sauce, miso, tempeh, natto, kimchi, sauerkraut, and sourdough bakery goods). Category Scope Note: Excludes alcoholic beer, wine, and distilled spirits, unfermented sweet milk, standalone probiotic dietary supplement capsules/tablets, and bulk B2B starter culture powders sold separately. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | South Korea, Brazil, USA, Germany, Japan, and additional countries in the full report |
| Key Companies Covered | Danone S.A., Nestlé S.A., Yakult Honsha Co., Ltd., Chobani, LLC, CJ CheilJedang Corp., Kikkoman Corporation, GT's Living Foods LLC, Lifeway Foods, Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Fermented Food and Beverage Market - Research Methodology
Table 10: Primary and Secondary Triangulation Protocol for the Fermented Food and Beverage Market, 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with dairy fermentation plant directors, microbial culture geneticists, supermarket cold-chain category buyers, and beverage quality-assurance managers across North America, Europe, East Asia, and Latin America. |
| Secondary Research | Analysis of corporate annual reports and SEC filings (Danone, Nestlé, Yakult Honsha, Lifeway Foods, Kikkoman, CJ CheilJedang), PubMed Central clinical microbiome trials, and USDA ERS/FAS statistical bulletins. |
| Market Sizing and Forecasting | Top-down fermented food and non-alcoholic beverage division valuations reconciled against bottom-up supermarket cold-chain scanner volumes and per-capita consumption from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight chilled grocery door expansion, national functional food claim approvals (such as Japan FFC and South Korea MFDS), and household probiotic penetration across five major markets. |
| Operational Benchmark Traceability | Bioreactor throughput, viable CFU density, and household valuation indicators in Tables 2, 3, and 4 trace to PubMed Central clinical kefir trials, Yakult daily bottle disclosures, and USDA food-at-home indices. |
| Data Triangulation and Validation | Demand estimates are cross-checked against commercial dairy, soy, and vegetable fermentation tonnage without double counting alcoholic beverages, probiotic pills, or raw starter culture ingredients. |
Fermented Food and Beverage Market by Segments
Fermented Food and Beverage Market segmented by Product Category:
- Fermented Dairy
- Fermented Beverages
- Fermented Soy & Legumes
- Fermented Vegetables & Sourdough
Fermented Food and Beverage Market segmented by Microbial Starter:
- Lactic Acid Bacteria
- Saccharomyces & Specialty Yeasts
- Aspergillus Koji & Mixed SCOBY Cultures
Fermented Food and Beverage Market segmented by Distribution Channel:
- Supermarkets & Hypermarkets
- Health & Natural Food Stores
- Online Retail & Foodservice
Fermented Food and Beverage Market segmented by Health Positioning:
- Gut Microbiome & Live Probiotic
- Naturally Low-Sugar & Organic Acid
- High-Protein & Bioavailable Amino Acid
- Clean-Label Artisanal & Heritage
Fermented Food and Beverage Market segmented by Packaging Format:
- Glass Bottles & Jars
- HDPE & PET Chilled Tubs and Bottles
- Sleek Aluminum Cans
- Flexible Vacuum Pouches & Wraps
Fermented Food and Beverage Market segmented by Storage Requirement:
- Refrigerated Cold-Chain 2°C to 6°C
- Ambient Shelf-Stable Pasteurized
Fermented Food and Beverage Market segmented by Consumption Channel:
- At-Home Retail Grocery
- On-Premise Restaurants, Cafes & Taprooms
Fermented Food and Beverage Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- South Korea
- Japan
- China
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Gao, Y., Liu, Y., Ma, T., Liang, Q., Sun, J., Wu, X., Song, Y., Nie, H., Huang, J., & Mu, G. (2025, May 29). Fermented Dairy Products as Precision Modulators of Gut Microbiota and Host Health: Mechanistic Insights, Clinical Evidence, and Future Directions. Foods, 14(11), 1946 (PubMed Central PMCID PMC12154003).
- [2] Danone S.A. (2026, February 19). 2025: Another year of strong delivery - Danone. Danone Group Newsroom.
- [3] Nestlé S.A. (2026, February 19). Nestlé - Annual Review 2025. Nestlé S.A. Investor Relations.
- [4] Yakult Honsha Co., Ltd. (2025, December 15). Everything about Yakult|For Investors. Yakult Honsha Co., Ltd. Investor Relations.
- [5] Economic Research Service (ERS). (2026, September 25). Food Price Outlook - Summary Findings | Economic Research Service. U.S. Department of Agriculture.
- [6] Lifeway Foods, Inc. (2025, November 12). Lifeway Foods Delivers Record Q3 2025 Net Sales and Strong Net Income Growth Continuing Kefir Category Dominance. Lifeway Foods, Inc. Investor Relations.
- [7] Kikkoman Corporation. (2025, August 05). Kikkoman Corporation Flash Report for 1Q Fiscal 2026 (IFRS). Kikkoman Corporation Financial Library.
- [8] CJ CheilJedang Corp. (2026, March 20). Financial Highlights | CJ Cheiljedang - CJ제일제당. CJ CheilJedang Corp. Investor Relations.
- [9] Lifeway Foods, Inc. (2026, May 14). Lifeway Foods® Announces Record-Breaking Results for the First Quarter Ended March 31, 2026. U.S. Securities and Exchange Commission (Form 8-K Exhibit 99.1).
- [10] Yakult Honsha Co., Ltd. (2025, December 15). Integrated Report - 2025. Yakult Honsha Co., Ltd. IR Library.
- [11] Danone S.A. (2026, February 25). Regulated information | Danone Group. Danone Group Investors (2025 Universal Registration Document).
- [12] Danone S.A. (2026, September 29). BIOP 2026 - Danone. Danone Group Newsroom.
- [13] CJ CheilJedang Corp. (2026, August 11). Quarterly Results | CJ Cheiljedang - CJ제일제당. CJ CheilJedang Corp. IR Library (2026 2Q Business Result).
- [14] USDA Foreign Agricultural Service. (2026, October 13). Brazil: Bracing for Impact - How the 2026 El Nino Affects Brazil's Agriculture. U.S. Department of Agriculture GAIN.
- [15] GT's Living Foods LLC. (2025, February 18). GT's Living Foods Celebrates 30 Years as the Pioneer of Real Kombucha. GT's Living Foods Official Newsroom.
- [16] USDA Foreign Agricultural Service. (2026, June 05). European Union: Dairy and Products Semi-annual | USDA Foreign Agricultural Service. U.S. Department of Agriculture GAIN (Report E42026-0043).
- [17] Kikkoman Corporation. (2026, July 15). Fact Book | Kikkoman Corporation. Kikkoman Corporation Investor Relations (Factbook Fiscal 2026).
- [18] Lifeway Foods, Inc. (2026, August 13). Lifeway Foods® Delivers Highest Quarterly Net Sales in Company History, Extending Record Growth in Second Quarter 2026 - Lifeway Kefir. Lifeway Foods, Inc. Press Releases.
- [19] Danone S.A. (2026, July 28). H1 Results 2026 - Danone. Danone Group Newsroom.
- [20] CJ CheilJedang Corp. (2026, August 18). bibigo™ Brought Flavors of Korean Food to Life at KCON LA 2026. CJ CheilJedang Corp. Newsroom.
- [21] Nestlé S.A. (2026, February 19). Full-year results 2025 | Nestlé Global. Nestlé S.A. Media Relations.
- [22] Kikkoman Corporation. (2026, April 24). Flash Report Fiscal 2026 | Kikkoman Corporation. Kikkoman Corporation IR Library.
- [23] Yakult Honsha Co., Ltd. (2026, May 12). Financial Report|For Investors|Yakult. Yakult Honsha Co., Ltd. Investor Relations.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the fermented food and beverage market in 2026 and what is forecast for 2036?
- Which clinical gut-health and protein trends support demand for fermented foods and beverages?
- Why does Fermented Dairy lead the product category segment?
- Why does Lactic Acid Bacteria lead the microbial starter category globally?
- How do growth rates differ across South Korea, Brazil, the USA, Germany, and Japan?
- Which leading processors manufacture and supply fermented foods and beverages today?
- What limits shelf-life extension or distribution scaling in the fermented food and beverage market?
- What should grocery buyers evaluate before sourcing commercial fermented foods and beverages?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Category, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Category, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Category, 2026 to 2036
- Fermented Dairy
- Fermented Beverages
- Fermented Soy & Legumes
- Fermented Vegetables & Sourdough
- Y-o-Y Growth Trend Analysis By Product Category, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Category, 2026 to 2036
- Global Market Analysis and Forecast, By Microbial Starter, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Microbial Starter, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Microbial Starter, 2026 to 2036
- Lactic Acid Bacteria
- Saccharomyces & Specialty Yeasts
- Aspergillus Koji & Mixed SCOBY Cultures
- Y-o-Y Growth Trend Analysis By Microbial Starter, 2021 to 2025
- Absolute $ Opportunity Analysis By Microbial Starter, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Health & Natural Food Stores
- Online Retail & Foodservice
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Health Positioning, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Health Positioning, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Health Positioning, 2026 to 2036
- Gut Microbiome & Live Probiotic
- Naturally Low-Sugar & Organic Acid
- High-Protein & Bioavailable Amino Acid
- Clean-Label Artisanal & Heritage
- Y-o-Y Growth Trend Analysis By Health Positioning, 2021 to 2025
- Absolute $ Opportunity Analysis By Health Positioning, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Glass Bottles & Jars
- HDPE & PET Chilled Tubs and Bottles
- Sleek Aluminum Cans
- Flexible Vacuum Pouches & Wraps
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Storage Requirement, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Storage Requirement, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Storage Requirement, 2026 to 2036
- Refrigerated Cold-Chain 2°C to 6°C
- Ambient Shelf-Stable Pasteurized
- Y-o-Y Growth Trend Analysis By Storage Requirement, 2021 to 2025
- Absolute $ Opportunity Analysis By Storage Requirement, 2026 to 2036
- Global Market Analysis and Forecast, By Consumption Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Consumption Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Consumption Channel, 2026 to 2036
- At-Home Retail Grocery
- On-Premise Restaurants, Cafes & Taprooms
- Y-o-Y Growth Trend Analysis By Consumption Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Consumption Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- South Korea
- Japan
- China
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Category
- By Microbial Starter
- By Distribution Channel
- By Health Positioning
- By Packaging Format
- By Storage Requirement
- By Consumption Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Danone S.A.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Nestlé S.A.
- Yakult Honsha Co., Ltd.
- Chobani, LLC
- CJ CheilJedang Corp.
- Kikkoman Corporation
- GT's Living Foods LLC
- Lifeway Foods, Inc.
- Danone S.A.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Microbial Starter, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Health Positioning, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 7: Global Market Value (USD Billion) Forecast by Storage Requirement, 2021 to 2036
- Table 8: Global Market Value (USD Billion) Forecast by Consumption Channel, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Microbial Starter, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 13: North America Market Value (USD Billion) Forecast by Health Positioning, 2021 to 2036
- Table 14: North America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 15: North America Market Value (USD Billion) Forecast by Storage Requirement, 2021 to 2036
- Table 16: North America Market Value (USD Billion) Forecast by Consumption Channel, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 19: Latin America Market Value (USD Billion) Forecast by Microbial Starter, 2021 to 2036
- Table 20: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 21: Latin America Market Value (USD Billion) Forecast by Health Positioning, 2021 to 2036
- Table 22: Latin America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 23: Latin America Market Value (USD Billion) Forecast by Storage Requirement, 2021 to 2036
- Table 24: Latin America Market Value (USD Billion) Forecast by Consumption Channel, 2021 to 2036
- Table 25: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Western Europe Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 27: Western Europe Market Value (USD Billion) Forecast by Microbial Starter, 2021 to 2036
- Table 28: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 29: Western Europe Market Value (USD Billion) Forecast by Health Positioning, 2021 to 2036
- Table 30: Western Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 31: Western Europe Market Value (USD Billion) Forecast by Storage Requirement, 2021 to 2036
- Table 32: Western Europe Market Value (USD Billion) Forecast by Consumption Channel, 2021 to 2036
- Table 33: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 34: Eastern Europe Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 35: Eastern Europe Market Value (USD Billion) Forecast by Microbial Starter, 2021 to 2036
- Table 36: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 37: Eastern Europe Market Value (USD Billion) Forecast by Health Positioning, 2021 to 2036
- Table 38: Eastern Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 39: Eastern Europe Market Value (USD Billion) Forecast by Storage Requirement, 2021 to 2036
- Table 40: Eastern Europe Market Value (USD Billion) Forecast by Consumption Channel, 2021 to 2036
- Table 41: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 42: East Asia Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 43: East Asia Market Value (USD Billion) Forecast by Microbial Starter, 2021 to 2036
- Table 44: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 45: East Asia Market Value (USD Billion) Forecast by Health Positioning, 2021 to 2036
- Table 46: East Asia Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 47: East Asia Market Value (USD Billion) Forecast by Storage Requirement, 2021 to 2036
- Table 48: East Asia Market Value (USD Billion) Forecast by Consumption Channel, 2021 to 2036
- Table 49: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 50: South Asia and Pacific Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 51: South Asia and Pacific Market Value (USD Billion) Forecast by Microbial Starter, 2021 to 2036
- Table 52: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 53: South Asia and Pacific Market Value (USD Billion) Forecast by Health Positioning, 2021 to 2036
- Table 54: South Asia and Pacific Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 55: South Asia and Pacific Market Value (USD Billion) Forecast by Storage Requirement, 2021 to 2036
- Table 56: South Asia and Pacific Market Value (USD Billion) Forecast by Consumption Channel, 2021 to 2036
- Table 57: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 58: Middle East and Africa Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 59: Middle East and Africa Market Value (USD Billion) Forecast by Microbial Starter, 2021 to 2036
- Table 60: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 61: Middle East and Africa Market Value (USD Billion) Forecast by Health Positioning, 2021 to 2036
- Table 62: Middle East and Africa Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 63: Middle East and Africa Market Value (USD Billion) Forecast by Storage Requirement, 2021 to 2036
- Table 64: Middle East and Africa Market Value (USD Billion) Forecast by Consumption Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Category
- Figure 6: Global Market Value Share and BPS Analysis by Microbial Starter, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Microbial Starter, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Microbial Starter
- Figure 9: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Distribution Channel
- Figure 12: Global Market Value Share and BPS Analysis by Health Positioning, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Health Positioning, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Health Positioning
- Figure 15: Global Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Packaging Format
- Figure 18: Global Market Value Share and BPS Analysis by Storage Requirement, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Storage Requirement, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Storage Requirement
- Figure 21: Global Market Value Share and BPS Analysis by Consumption Channel, 2026 and 2036
- Figure 22: Global Market Y-o-Y Growth Comparison by Consumption Channel, 2026-2036
- Figure 23: Global Market Attractiveness Analysis by Consumption Channel
- Figure 24: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 25: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 26: Global Market Attractiveness Analysis by Region
- Figure 27: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 29: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 30: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 31: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 32: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 33: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 34: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 35: North America Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Product Category
- Figure 38: North America Market Value Share and BPS Analysis by Microbial Starter, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Microbial Starter, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Microbial Starter
- Figure 41: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Distribution Channel
- Figure 44: North America Market Value Share and BPS Analysis by Health Positioning, 2026 and 2036
- Figure 45: North America Market Y-o-Y Growth Comparison by Health Positioning, 2026-2036
- Figure 46: North America Market Attractiveness Analysis by Health Positioning
- Figure 47: North America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 48: North America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 49: North America Market Attractiveness Analysis by Packaging Format
- Figure 50: North America Market Value Share and BPS Analysis by Storage Requirement, 2026 and 2036
- Figure 51: North America Market Y-o-Y Growth Comparison by Storage Requirement, 2026-2036
- Figure 52: North America Market Attractiveness Analysis by Storage Requirement
- Figure 53: North America Market Value Share and BPS Analysis by Consumption Channel, 2026 and 2036
- Figure 54: North America Market Y-o-Y Growth Comparison by Consumption Channel, 2026-2036
- Figure 55: North America Market Attractiveness Analysis by Consumption Channel
- Figure 56: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 57: Latin America Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Product Category
- Figure 60: Latin America Market Value Share and BPS Analysis by Microbial Starter, 2026 and 2036
- Figure 61: Latin America Market Y-o-Y Growth Comparison by Microbial Starter, 2026-2036
- Figure 62: Latin America Market Attractiveness Analysis by Microbial Starter
- Figure 63: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 64: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 65: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 66: Latin America Market Value Share and BPS Analysis by Health Positioning, 2026 and 2036
- Figure 67: Latin America Market Y-o-Y Growth Comparison by Health Positioning, 2026-2036
- Figure 68: Latin America Market Attractiveness Analysis by Health Positioning
- Figure 69: Latin America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 70: Latin America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 71: Latin America Market Attractiveness Analysis by Packaging Format
- Figure 72: Latin America Market Value Share and BPS Analysis by Storage Requirement, 2026 and 2036
- Figure 73: Latin America Market Y-o-Y Growth Comparison by Storage Requirement, 2026-2036
- Figure 74: Latin America Market Attractiveness Analysis by Storage Requirement
- Figure 75: Latin America Market Value Share and BPS Analysis by Consumption Channel, 2026 and 2036
- Figure 76: Latin America Market Y-o-Y Growth Comparison by Consumption Channel, 2026-2036
- Figure 77: Latin America Market Attractiveness Analysis by Consumption Channel
- Figure 78: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 79: Western Europe Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 80: Western Europe Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 81: Western Europe Market Attractiveness Analysis by Product Category
- Figure 82: Western Europe Market Value Share and BPS Analysis by Microbial Starter, 2026 and 2036
- Figure 83: Western Europe Market Y-o-Y Growth Comparison by Microbial Starter, 2026-2036
- Figure 84: Western Europe Market Attractiveness Analysis by Microbial Starter
- Figure 85: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 86: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 87: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 88: Western Europe Market Value Share and BPS Analysis by Health Positioning, 2026 and 2036
- Figure 89: Western Europe Market Y-o-Y Growth Comparison by Health Positioning, 2026-2036
- Figure 90: Western Europe Market Attractiveness Analysis by Health Positioning
- Figure 91: Western Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 92: Western Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 93: Western Europe Market Attractiveness Analysis by Packaging Format
- Figure 94: Western Europe Market Value Share and BPS Analysis by Storage Requirement, 2026 and 2036
- Figure 95: Western Europe Market Y-o-Y Growth Comparison by Storage Requirement, 2026-2036
- Figure 96: Western Europe Market Attractiveness Analysis by Storage Requirement
- Figure 97: Western Europe Market Value Share and BPS Analysis by Consumption Channel, 2026 and 2036
- Figure 98: Western Europe Market Y-o-Y Growth Comparison by Consumption Channel, 2026-2036
- Figure 99: Western Europe Market Attractiveness Analysis by Consumption Channel
- Figure 100: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 101: Eastern Europe Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 102: Eastern Europe Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 103: Eastern Europe Market Attractiveness Analysis by Product Category
- Figure 104: Eastern Europe Market Value Share and BPS Analysis by Microbial Starter, 2026 and 2036
- Figure 105: Eastern Europe Market Y-o-Y Growth Comparison by Microbial Starter, 2026-2036
- Figure 106: Eastern Europe Market Attractiveness Analysis by Microbial Starter
- Figure 107: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 108: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 109: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 110: Eastern Europe Market Value Share and BPS Analysis by Health Positioning, 2026 and 2036
- Figure 111: Eastern Europe Market Y-o-Y Growth Comparison by Health Positioning, 2026-2036
- Figure 112: Eastern Europe Market Attractiveness Analysis by Health Positioning
- Figure 113: Eastern Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 114: Eastern Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 115: Eastern Europe Market Attractiveness Analysis by Packaging Format
- Figure 116: Eastern Europe Market Value Share and BPS Analysis by Storage Requirement, 2026 and 2036
- Figure 117: Eastern Europe Market Y-o-Y Growth Comparison by Storage Requirement, 2026-2036
- Figure 118: Eastern Europe Market Attractiveness Analysis by Storage Requirement
- Figure 119: Eastern Europe Market Value Share and BPS Analysis by Consumption Channel, 2026 and 2036
- Figure 120: Eastern Europe Market Y-o-Y Growth Comparison by Consumption Channel, 2026-2036
- Figure 121: Eastern Europe Market Attractiveness Analysis by Consumption Channel
- Figure 122: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 123: East Asia Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 124: East Asia Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 125: East Asia Market Attractiveness Analysis by Product Category
- Figure 126: East Asia Market Value Share and BPS Analysis by Microbial Starter, 2026 and 2036
- Figure 127: East Asia Market Y-o-Y Growth Comparison by Microbial Starter, 2026-2036
- Figure 128: East Asia Market Attractiveness Analysis by Microbial Starter
- Figure 129: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 130: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 131: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 132: East Asia Market Value Share and BPS Analysis by Health Positioning, 2026 and 2036
- Figure 133: East Asia Market Y-o-Y Growth Comparison by Health Positioning, 2026-2036
- Figure 134: East Asia Market Attractiveness Analysis by Health Positioning
- Figure 135: East Asia Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 136: East Asia Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 137: East Asia Market Attractiveness Analysis by Packaging Format
- Figure 138: East Asia Market Value Share and BPS Analysis by Storage Requirement, 2026 and 2036
- Figure 139: East Asia Market Y-o-Y Growth Comparison by Storage Requirement, 2026-2036
- Figure 140: East Asia Market Attractiveness Analysis by Storage Requirement
- Figure 141: East Asia Market Value Share and BPS Analysis by Consumption Channel, 2026 and 2036
- Figure 142: East Asia Market Y-o-Y Growth Comparison by Consumption Channel, 2026-2036
- Figure 143: East Asia Market Attractiveness Analysis by Consumption Channel
- Figure 144: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 145: South Asia and Pacific Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 146: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 147: South Asia and Pacific Market Attractiveness Analysis by Product Category
- Figure 148: South Asia and Pacific Market Value Share and BPS Analysis by Microbial Starter, 2026 and 2036
- Figure 149: South Asia and Pacific Market Y-o-Y Growth Comparison by Microbial Starter, 2026-2036
- Figure 150: South Asia and Pacific Market Attractiveness Analysis by Microbial Starter
- Figure 151: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 152: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 153: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 154: South Asia and Pacific Market Value Share and BPS Analysis by Health Positioning, 2026 and 2036
- Figure 155: South Asia and Pacific Market Y-o-Y Growth Comparison by Health Positioning, 2026-2036
- Figure 156: South Asia and Pacific Market Attractiveness Analysis by Health Positioning
- Figure 157: South Asia and Pacific Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 158: South Asia and Pacific Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 159: South Asia and Pacific Market Attractiveness Analysis by Packaging Format
- Figure 160: South Asia and Pacific Market Value Share and BPS Analysis by Storage Requirement, 2026 and 2036
- Figure 161: South Asia and Pacific Market Y-o-Y Growth Comparison by Storage Requirement, 2026-2036
- Figure 162: South Asia and Pacific Market Attractiveness Analysis by Storage Requirement
- Figure 163: South Asia and Pacific Market Value Share and BPS Analysis by Consumption Channel, 2026 and 2036
- Figure 164: South Asia and Pacific Market Y-o-Y Growth Comparison by Consumption Channel, 2026-2036
- Figure 165: South Asia and Pacific Market Attractiveness Analysis by Consumption Channel
- Figure 166: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 167: Middle East and Africa Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 168: Middle East and Africa Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 169: Middle East and Africa Market Attractiveness Analysis by Product Category
- Figure 170: Middle East and Africa Market Value Share and BPS Analysis by Microbial Starter, 2026 and 2036
- Figure 171: Middle East and Africa Market Y-o-Y Growth Comparison by Microbial Starter, 2026-2036
- Figure 172: Middle East and Africa Market Attractiveness Analysis by Microbial Starter
- Figure 173: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 174: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 175: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 176: Middle East and Africa Market Value Share and BPS Analysis by Health Positioning, 2026 and 2036
- Figure 177: Middle East and Africa Market Y-o-Y Growth Comparison by Health Positioning, 2026-2036
- Figure 178: Middle East and Africa Market Attractiveness Analysis by Health Positioning
- Figure 179: Middle East and Africa Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 180: Middle East and Africa Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 181: Middle East and Africa Market Attractiveness Analysis by Packaging Format
- Figure 182: Middle East and Africa Market Value Share and BPS Analysis by Storage Requirement, 2026 and 2036
- Figure 183: Middle East and Africa Market Y-o-Y Growth Comparison by Storage Requirement, 2026-2036
- Figure 184: Middle East and Africa Market Attractiveness Analysis by Storage Requirement
- Figure 185: Middle East and Africa Market Value Share and BPS Analysis by Consumption Channel, 2026 and 2036
- Figure 186: Middle East and Africa Market Y-o-Y Growth Comparison by Consumption Channel, 2026-2036
- Figure 187: Middle East and Africa Market Attractiveness Analysis by Consumption Channel
- Figure 188: Global Market - Tier Structure Analysis
- Figure 189: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the fermented food and beverage market in 2026, and what is forecast for 2036?
Worldwide fermented food and beverage valuation climbs from USD 615.0 billion in 2025 to an estimated USD 652.5 billion during 2026, and FMI forecasts total market size to reach USD 1,179.6 billion by 2036 as households buy live probiotic dairy and cultured condiments.
What is the CAGR for the fermented food and beverage market from 2026 to 2036?
FMI analysts anticipate a 6.1% compound annual growth rate across the 2026 to 2036 window, which creates USD 527.1 billion in added annual market value over the decade.
Which product category segment leads the fermented food and beverage market?
Fermented Dairy is projected to claim 45.3% of product category valuation in 2026 because milk proteins buffer gastric acid and deliver dense calcium and bioactive peptides.
Which microbial starter segment leads the fermented food and beverage market?
Lactic Acid Bacteria is estimated to command 41.7% of microbial starter market size in 2026 owing to rapid homofermentative acidification and verified probiotic colonization.
Which country has a notable growth outlook during the assessment period?
South Korea is projected to pace national expansion at a 7.2% CAGR through 2036, driven by commercial pouch kimchi exports and functional probiotic beverage innovation.
Who are the key players in the market?
Danone S.A., Nestlé S.A., Yakult Honsha Co., Ltd., Chobani, LLC, CJ CheilJedang Corp., Kikkoman Corporation, GT's Living Foods LLC, and Lifeway Foods, Inc. lead commercial production across retail grocery and foodservice channels.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
