

- Market Size (2026)
- USD 29.2 Bn
- Forecast (2036)
- USD 34.1 Bn
- CAGR (2026 to 2036)
- 2.0%
How big is Food Grade Phosphate Market in 2026?
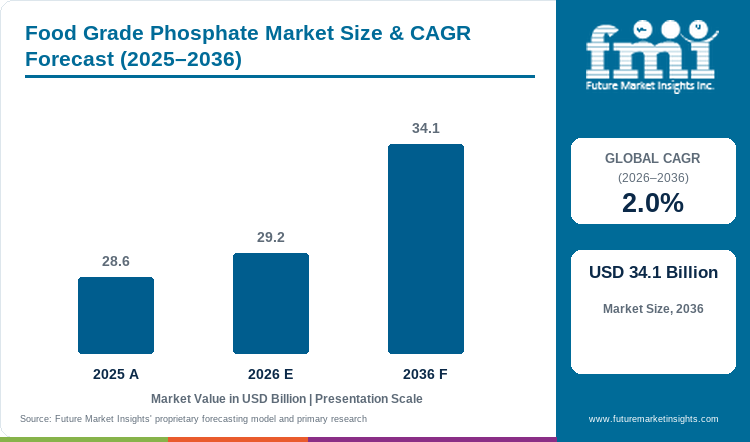
USD 29.2 Billion in 2026 and USD 34.1 Billion by 2036 at a 2.0% CAGR.
Sales of food grade phosphate are estimated to grow at a 2.0% CAGR from USD 29.2 Billion in 2026 to USD 34.1 Billion by 2036, following a market value of USD 28.6 Billion in 2025. Functional performance provides the purchasing rationale. Innophos’ October 2023 bakery work evaluated physical, sensory and microbiological shelf-life outcomes, giving bakery processors a practical basis for testing whether phosphate functionality protects saleable quality through storage.
Operating conditions determine which formulation opportunities become recurring orders. Food-grade phosphate also sits within the wider food additives landscape, where recipe function and regulatory permission have to align. The FDA’s May 2025 calcium-phosphate color authorization covers specified food uses, while the UK Food Standards Agency’s June 2026 guidance distinguishes jurisdiction-specific additive rules. Procurement teams therefore need the chosen phosphate to work in the recipe and meet the destination market’s conditions.
Key Takeaways
- Functional performance in processing and storage supports repeat purchasing when the phosphate delivers a measurable benefit in the customer’s formulation.
- Agriculture leads the Application category with a 78.0% share in 2026, while food-grade qualification remains tied to the required purity and intended use.
- Ammonium Phosphate leads the Type category with a 62.0% share in 2026, supported by documented food roles such as dough conditioning and pH control.
- Purity, dosage and permitted-use requirements can extend qualification, particularly where total dietary phosphorus exposure is part of formulation review.
- The UK records the fastest profiled CAGR at 5.0% from 2026 to 2036, followed by Germany at 4.0%.
- ICL Group Ltd., Prayon SA, Innophos Holdings Inc., Nutrien Ltd. and Aditya Birla Chemicals are the notable companies profiled in this market.
Analyst Perspective
Food grade phosphate economics are shaped by grade purity and the function required in the recipe. A phosphate used in fertilizer or feed applications does not automatically meet food specifications. In bakery, seafood and whitening applications, suppliers need specification control and application testing that match the intended food use.
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the food grade phosphate market segmented?
By Application, Type and Region.
Application comprises Agriculture, Food & Beverage, Animal Feed, Poultry, Bakery & Confectionery, Meat & Seafood, Ruminants, Dairy, Swine, Beverages, Nutrition, Frozen Food and Aqua. Type comprises Ammonium Phosphate, Sodium Phosphate, Potassium Phosphate, Calcium Phosphate and Other. Region coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
Why does Agriculture lead demand within the Application category?
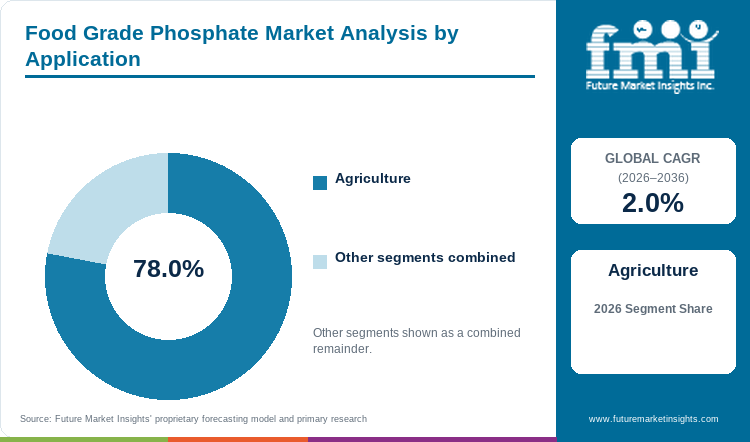
Agriculture holds the largest Application allocation at 78.0% in 2026. Its high-volume nutrient role connects phosphate demand with the broader phosphate fertilizer market, while food-grade procurement follows tighter purity, specification and intended-use requirements. Nutrien’s production guidance distinguishes fertilizer, food-grade and feed phosphate, making grade selection central to the commercial decision.
- Agriculture: 78.0% share in 2026 within the Application category.
- Food-grade orders require a specification and intended use that match the customer’s formulation rather than the broader phosphate chemistry alone.
Why does Ammonium Phosphate lead demand within the Type category?
Ammonium Phosphate connects several food-processing tasks through its chemistry. A USDA technical review describes monobasic ammonium phosphate as a dough-strengthening and pH-control substance, while ICL documents dibasic ammonium phosphate as a water-soluble yeast nutrient. In bakery formulations, phosphate selection sits alongside other bakery ingredients, so buyers compare functional performance, dose and process compatibility rather than choosing on chemical name alone.
- Ammonium Phosphate: 62.0% share in 2026 within the Type category.
- Food applications include dough conditioning, pH control and yeast nutrition, giving the type multiple formulation roles.
What are the drivers, restraints and opportunities in the Food Grade Phosphate Market?
Reproducible processing performance supports phosphate purchases, while purity and exposure constraints slow qualification and calcium-phosphate whitening creates targeted reformulation opportunities.
- Driver: Reducing processing variability and preserving saleable product quality.
- Restraint: Product qualification and exposure-aware formulation can delay adoption.
- Opportunity: Calcium-phosphate whitening in specifically authorized food categories.
Manufacturers facing product staling or unstable batter reconsider functional ingredients when process performance becomes the problem to solve. In October 2023, Innophos published bakery case studies assessing physical and sensory performance alongside microbiological outcomes. This places shelf-life performance at the center of the formulation trial and links phosphate purchasing with the broader specialty food ingredients decision set used by product-development teams.
Exposure-aware formulation constrains how far functionality can be pursued through higher dosage. EFSA’s June 2019 reassessment found that total dietary phosphorus exposure could exceed its guidance for some age groups and recommended maximum levels for phosphates in food supplements. This makes dosage justification part of formulation review alongside texture, stability and processing performance.
Whitening creates an opening beyond established leavening and moisture-management uses. In May 2025, the FDA authorized calcium phosphate as a color additive in selected categories following an Innophos petition. The order specifies identity, purity and permitted uses. Suppliers can address this opening with application-specific particle handling, appearance testing and documentation matched to the authorized food category.
Which country CAGRs are profiled in the Food Grade Phosphate Market?
The following country CAGRs cover 2026 to 2036.
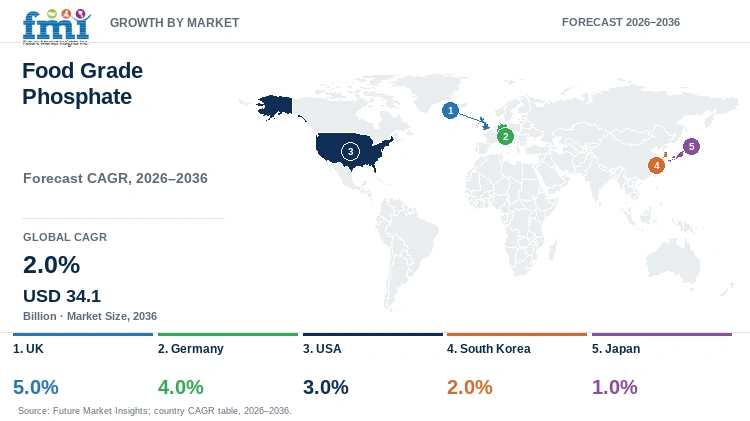
| Country | CAGR |
|---|---|
| UK | 5.0% |
| Germany | 4.0% |
| USA | 3.0% |
| South Korea | 2.0% |
| Japan | 1.0% |
How do country-level CAGRs compare in the Food Grade Phosphate Market?
The profiled forecasts are 5.0% for the UK, 4.0% for Germany, 3.0% for the USA, 2.0% for South Korea and 1.0% for Japan. The five markets span four percentage points, but their purchasing conditions differ because additive rules, exposure considerations and specification requirements are not uniform.
- UK: Destination-market additive rules make jurisdiction-specific documentation part of product qualification.
- Germany: Dietary-exposure considerations place emphasis on a defensible functional dose.
- USA: A defined color-additive route creates a specific calcium-phosphate formulation opening.
- South Korea: Local additive identity and use requirements remain central to qualification.
- Japan: Ingredient specifications and use standards remain separate purchasing checks.
Country-wise Analysis
- The UK’s 5.0% CAGR from 2026 to 2036 is the highest among the profiled countries. FSA guidance published in June 2026 explains distinct additive-rule frameworks for England and Wales versus Northern Ireland. Processors selling across jurisdictions therefore need the phosphate identity, permitted use and supporting documentation to match the destination market before reformulation moves into routine production.
- Germany carries a 4.0% CAGR from 2026 to 2036. BfR’s June 2019 communication aligns with EFSA’s phosphate assessment and highlights the possibility of guidance-value exceedances among younger consumers. This places dose justification alongside texture, stability and processing requirements when formulators assess the total phosphate contribution of a recipe.
- A 3.0% CAGR is forecast for the USA from 2026 to 2036. The FDA’s May 2025 order authorizes specified calcium-phosphate color uses and sets product specifications. This favors proposals that combine an eligible calcium-phosphate grade with performance evidence for the intended food matrix and clear documentation for the permitted application.
- South Korea carries a 2.0% CAGR from 2026 to 2036. MFDS posted an English edition of its September 2023 Food Additives Code in October 2023 and identifies the Korean text as the controlling legal reference. Suppliers therefore need current local identity and use checks for the food-grade phosphate offered to processors.
- Japan is forecast at a 1.0% CAGR from 2026 to 2036. Japan’s 2024 tenth-edition food-additive compendium separates ingredient specifications from manufacturing and use standards. Buyers evaluating imported phosphate therefore need conformity with the applicable local monograph and the intended food use before approving a formulation.
Who are the notable companies in the Food Grade Phosphate Market?
ICL Group Ltd., Prayon SA, Innophos Holdings Inc., Nutrien Ltd. and Aditya Birla Chemicals are the notable companies profiled in this market.
Competition spans finished food-phosphate ingredients, application support and upstream phosphate supply. ICL Group Ltd. combines food applications with manufacturing support. Prayon SA documents phosphate salts and purified-acid operations. Innophos Holdings Inc. and Aditya Birla Chemicals emphasize application-oriented food ingredients, while Nutrien Ltd. contributes upstream phosphate production and purified-acid supply that includes food-related uses.
- Phosphate manufacturing and food platforms: ICL Group Ltd. and Prayon SA.
- Formulation-led food ingredient specialists: Innophos Holdings Inc. and Aditya Birla Chemicals.
- Upstream phosphate supply: Nutrien Ltd.
Competitive Benchmarking: Food Grade Phosphate Market
| Company | Food application breadth | Formulation support | Phosphate conversion integration | Geographic Reach |
|---|---|---|---|---|
| ICL Group Ltd. | High | High | Medium | China: food-specialty production at Zhangjiagang. |
| Prayon SA | High | Medium | High | Belgium and France; phosphate-salt production in the USA. |
| Innophos Holdings Inc. | High | High | High | USA manufacturing; documented EC-grade supply for European customers. |
| Nutrien Ltd. | Medium | Unscored | High | USA production; purified-acid sales primarily in North America. |
| Aditya Birla Chemicals | High | High | Medium | Thailand-based business; seafood-customer engagement in India. |
Scoring basis: Food application breadth is High for documented uses across several food applications and Medium for narrower or upstream food-related coverage. Formulation support is High for documented customer formulation plus testing or dedicated development capability and Medium for application-specific solutions. Phosphate conversion integration is High for vertically integrated phosphate production or linked upstream conversion and Medium for manufacturing without equivalent integration depth. Low denotes a documented limitation.
Key Developments in the Food Grade Phosphate Market
- In November 2025, Prayon SA inaugurated a sodium hexametaphosphate production unit at Engis in Belgium. The announced investment exceeded EUR 30 million and added 10,000 tons of annual capacity for food and technical applications.
- In July 2025, Innophos Holdings Inc. announced VersaCal Bright for calcium-phosphate whitening in selected food categories following the FDA color-additive action.
- In September 2024, ICL Group Ltd. opened a food-specialty plant in the Zhangjiagang Free Trade Zone near Shanghai. The facility supports texturants and marinades for meat and seafood applications alongside local customer development.
Key Players in the Food Grade Phosphate Market
Phosphate manufacturing and food platforms
- ICL Group Ltd.
- Prayon SA
Formulation-led food ingredient specialists
- Innophos Holdings Inc.
- Aditya Birla Chemicals
Upstream phosphate supply
- Nutrien Ltd.
Food Grade Phosphate Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Application; Type; Region. |
| Quantitative Units | USD Billion |
| Market Definition | Revenue from food-grade phosphate products sold within the listed Application and Type categories is included. Finished products and substitute ingredients are excluded. Fertilizer-grade and feed-grade materials are excluded, as are upstream inputs not sold as the named product and non-phosphate portions of mixed offerings. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA; UK; Germany; Japan; South Korea |
| Key Companies Profiled | ICL Group Ltd.; Prayon SA; Innophos Holdings Inc.; Nutrien Ltd.; Aditya Birla Chemicals |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Food Grade Phosphate Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, distributors, food processors, procurement teams and subject-matter experts. Interviews examined purchasing decisions, product evaluation, adoption barriers, approval requirements, pricing considerations and expectations for technical or commercial support. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information and official corporate announcements. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation and country-level demand conditions. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments and findings from primary interviews. |
Food Grade Phosphate Market by Segments
Food Grade Phosphate Market segmented by Application:
- Agriculture
- Food & Beverage
- Animal Feed
- Poultry
- Bakery & Confectionery
- Meat & Seafood
- Ruminants
- Dairy
- Swine
- Beverages
- Nutrition
- Frozen Food
- Aqua
Food Grade Phosphate Market segmented by Type:
- Ammonium Phosphate
- Sodium Phosphate
- Potassium Phosphate
- Calcium Phosphate
- Other
Food Grade Phosphate Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- Nutrien (2023, June 23). How phosphate is produced: Behind-the-scenes look at Nutrien’s White Springs, Florida phosphate site.
- ICL Group (n.d.). Food.
- Savan Group for the USDA National Organic Program (2021, February 18). Technical Evaluation Report: Ammonia Extract, Crops.
- Innophos (2023, October 12). Innophos Releases New Whitepaper Showcasing LEVAIR® ESL.
- Innophos (n.d.). R&D Approach.
- USA Food and Drug Administration (2025, May 9). FDA Approves Three Food Colors from Natural Sources.
- USA Food and Drug Administration (2025, May 12). Listing of Color Additives Exempt From Certification; Calcium Phosphate.
- European Food Safety Authority (2019, June 12). EFSA issues new advice on phosphates.
- Food Standards Agency (2026, June 25). Approved additives and E numbers.
- German Federal Institute for Risk Assessment (2019, June 13). Intake of Phosphates: Babies, infants and children can exceed the health guidance values.
- Ministry of Food and Drug Safety, Republic of Korea (2023, October 30). Food Additives Code (#2023-60, 2023.9.20.).
- Ministry of Health, Labour and Welfare and Consumer Affairs Agency, Japan (2024). Japan’s Specifications and Standards for Food Additives, 10th edition.
- Prayon (2025, November 27). Prayon inaugurates its new SHMP production unit in Engis.
- ICL Group (2024, September 24). ICL Makes Significant Expansion in China, with Opening of New Food Specialty Plant.
- Innophos (2025, July 2). Innophos Launches Clean-Label Whitening Alternative to Titanium Dioxide.
- Prayon (2024, August 30). Prayon acquires NEI in the US, reinforcing its presence on the phosphate salts market.
- Innophos (2024, April 9). Innophos Upgrades EC Grade Calcium Phosphates Production Facility.
- Innophos (2023, April 25). Innophos Adds New Solution To Growing LEVAIR® Bakery Product Portfolio.
- Prayon (2024, March 4). Prayon introduces a low-sodium alternative for seafood.
- Aditya Birla Chemicals (n.d.). Aditya Birla Chemicals Showcases “Pearl” at the India International Seafood Show 2025.
- Innophos (2022, September 8). Innophos Launches New Baking Solutions Under LEVAIR® Brand.
- Aditya Birla Chemicals (n.d.). Phosphates.
- Nutrien (n.d.). Phosphate.
- Prayon (n.d.). Our company.
- Innophos (n.d.). Manufacturing Capabilities.
- Innophos (n.d.). Vitrafos® Sodium Hexametaphosphate (Food).
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the food grade phosphate market in 2025, 2026 and 2036?
- Which processing and storage pressures support purchases of food-grade phosphates?
- Why does Agriculture lead the Application category?
- Why does Ammonium Phosphate lead the Type category?
- How do the forecast growth rates differ across the profiled countries?
- Which companies supply finished food-phosphate ingredients or participate upstream?
- What qualification and formulation constraints can delay adoption or supplier switching?
- What should buyers verify before selecting a phosphate product for a particular food application?
Frequently Asked Questions
How big is the food grade phosphate market in 2026, and what is forecast for 2036?
The market was valued at USD 28.6 Billion in 2025, reaches USD 29.2 Billion in 2026 and is forecast at USD 34.1 Billion by 2036.
What is the food grade phosphate market CAGR from 2026 to 2036?
The market is forecast to expand at a 2.0% CAGR from 2026 to 2036.
Which Application segment leads the food grade phosphate market?
Agriculture leads the Application category with a 78.0% share in 2026.
Which Type segment leads the food grade phosphate market?
Ammonium Phosphate leads the Type category with a 62.0% share in 2026. Its documented food-processing functions include pH control, dough conditioning and yeast nutrition.
Which profiled countries have the highest food grade phosphate market growth rates?
The UK at 5.0% and Germany at 4.0% have the highest profiled CAGRs from 2026 to 2036.
Which companies are profiled in the food grade phosphate market?
The profiled companies are ICL Group Ltd., Prayon SA, Innophos Holdings Inc., Nutrien Ltd. and Aditya Birla Chemicals.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Agriculture
- Food & Beverage
- Animal Feed
- Poultry
- Bakery & Confectionery
- Meat & Seafood
- Ruminants
- Dairy
- Swine
- Beverages
- Nutrition
- Frozen Food
- Aqua
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Type, 2026 to 2036
- Ammonium Phosphate
- Sodium Phosphate
- Potassium Phosphate
- Calcium Phosphate
- Other
- Y-o-Y Growth Trend Analysis By Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Application
- By Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Application
- By Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Type
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Application
- By Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Type
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Application
- By Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Type
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Application
- By Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Type
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Application
- By Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Type
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Application
- By Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Type
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Type
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Type
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Type
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Type
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Type
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Type
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Type
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Type
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Type
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Type
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Type
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Type
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Type
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Type
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Type
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Type
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Type
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Application
- By Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- ICL Group Ltd.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Prayon SA
- Innophos Holdings Inc.
- Nutrien Ltd.
- Aditya Birla Chemicals
- ICL Group Ltd.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


