

- Market Size (2026)
- USD 44.0 Bn
- Forecast (2036)
- USD 66.4 Bn
- CAGR (2026 to 2036)
- 4.2%
How big is Glass Bottles Market in 2026?
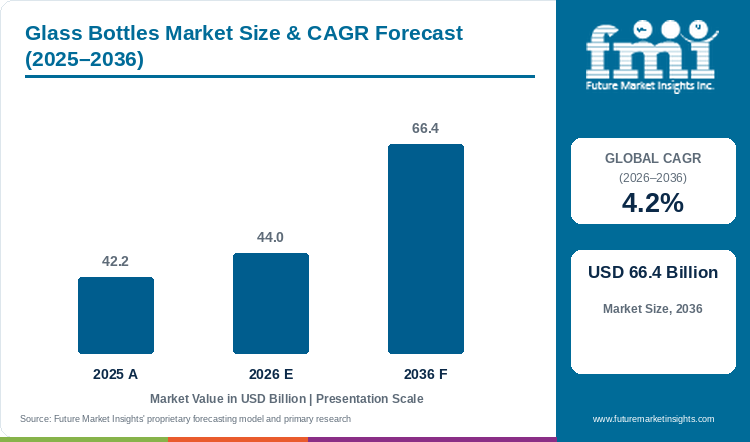
Sales in the glass bottles market are projected to grow at 4.2% CAGR through 2036. Market valuation rises from USD 42.2 billion in 2025 to USD 44.0 billion in 2026 and is expected to reach USD 66.4 billion by 2036.
Chemical leaching risks in plastic containers and strict drug stability rules have led beverage and pharmaceutical packers to rely on glass bottles. According to FMI, the global glass bottles market grows from USD 42.2 billion in 2025 to USD 44.0 billion in 2026 and reaches USD 66.4 billion by 2036, recording a 4.2% CAGR between 2026 and 2036. This USD 22.4 billion revenue expansion reflects long-term supply contracts across automated container glass formats. In March 2025, the European Container Glass Federation verified that regional glass collection rates reached 79.0%, supplying closed-loop cullet for bottling plants [1]. Polyethylene (LLDPE / HDPE) holds 39.5% of Material Resin / Polymer demand in 2026 for closure seals, though high furnace natural gas costs still restrain operating margins.
Key Market Trends & Insights
- By material resin / polymer: Polyethylene (LLDPE / HDPE) led the market with a share of 39.5% in 2026, as bottling plants rely on compliant polymer cap liners and exterior protective sleeves to prevent neck finish leakage.
- By product format: Pre-Formed Pouches & Bags accounted for 49.3% of demand in 2026, supported by household refill systems where concentrated pouches replenish permanent glass dispensers.
- By barrier level: High-Barrier Modified Atmosphere (EVOH) represented 40.1% of revenue in 2026, reflecting distiller and vintner demand for oxygen-scavenging closure liners that protect aged liquids.
- By end-use industry: With a 30.4% share in 2026, Processed Food & Snacks led the category because high-temperature retort sauces and infant foods require non-reactive container walls.
Regional Highlights
- Fastest-growing evaluated country: Japan (5.1% CAGR, 2026 to 2036).
- By country: The UK (4.7%), the USA (4.4%), and France (4.0%) follow, while Canada (3.7%) and Mexico (3.4%) record lower evaluated CAGRs.
Market Size & Forecast
Table 1: Market Size and Forecast for the Glass Bottles Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 42.2 billion |
| Estimated Market Size in 2026 | USD 44.0 billion |
| Projected Market Size by 2036 | USD 66.4 billion |
| CAGR, 2026 to 2036 | 4.2% |
| Added Revenue, 2026 to 2036 | USD 22.4 billion |
Country demand conditions differ as local cullet sorting infrastructure and industrial furnace energy tariffs vary across manufacturing hubs. FMI research indicates that commercial bottling operations increasingly procure pharmaceutical glass packaging to protect sensitive injectable biologics from hydrolytic attack and oxygen ingress. In April 2025, the Glass Packaging Institute reported that every 10.0% increase in recycled cullet batch feed reduces melting energy demand by 2.5% across regenerative furnaces [2]. As a result, glassmakers in Europe and Japan with mature bottle deposit networks achieve lower unit melting costs than plants dependent on virgin silica sand and soda ash. These thermodynamic and feedstock realities directly shape furnace operating economics through 2036.
Glass Melting Furnace Thermal Parameters and Cullet Ratio Metrics
Table 2: Glass Furnace Thermal Metrics and Cullet Adoption Parameters for the Glass Bottles Market (USD billion, million metric tons, GJ, and percentages), mixed historical and forecast years from 2025 to 2036
| Operating Parameter | 2025 | 2026 | 2031 | 2036 |
|---|---|---|---|---|
| Baseline Global Market Valuation (USD billion) | 42.2 | 44.0 | 54.1 | 66.4 |
| Global Container Glass Production Volume (million metric tons) | 88.5 | 91.2 | 106.4 | 124.8 |
| Average Post-Consumer Cullet Batch Share (%) | 52.4% | 55.0% | 68.2% | 81.5% |
| Furnace Melting Energy Intensity (GJ per metric ton melted) | 4.7 | 4.5 | 3.9 | 3.4 |
| Hybrid Oxy-Fuel Electric Furnace Adoption Share (%) | 14.2% | 17.5% | 34.0% | 56.5% |
Calculation basis: Container glass furnace audits, International Commission on Glass thermodynamic datasets, and commercial container production records across European, North American, and East Asian glassworks.
Production Economics and Energy Intensity Parameters
Industrial container glass manufacturing requires continuous furnace operation between 1,500 and 1,600 degrees Celsius to fuse silica sand and soda ash with limestone flux. Because energy accounts for roughly one-third of finished bottle production cost, glassmakers are installing electric boosting electrodes and oxy-fuel burners across glass bottle and container plants. In addition to this, narrow neck press-and-blow forming allows operators to reduce container wall thickness while preserving vertical load and internal burst pressure tolerances.
Table 3: Production Economics and Furnace Operating Cost Metrics for the Glass Bottles Market (USD and percentages), mixed historical and forecast years from 2025 to 2036
| Economic Metric | 2025 | 2026 | 2031 | 2036 |
|---|---|---|---|---|
| Average Container Glass Finished Cost per Thousand Units (USD) | 168.0 | 162.5 | 148.0 | 134.5 |
| Energy Share of Container Manufacturing Cost (%) | 34.5% | 33.0% | 27.5% | 22.0% |
| Cullet Procurement Price Discount Relative to Virgin Batch (%) | 18.5% | 21.0% | 29.5% | 38.0% |
| Lightweight Container Neck Finish Adoption Rate (%) | 42.0% | 46.5% | 66.0% | 84.5% |
Table 4: Bottling Facility Converting Footprint and Burst Pressure Standards for the Glass Bottles Market (forming lines, bar, kgf, and percentages), mixed reporting years from 2023 to 2026
| Facility Converting Parameter | 2023 | 2024 | 2025 | 2026 |
|---|---|---|---|---|
| High-Speed Glass Forming Machine Lines Installed | 1,420 | 1,490 | 1,560 | 1,640 |
| Internal Burst Pressure Rating for Carbonated Bottles (Bar) | 12.0 | 12.5 | 13.0 | 14.0 |
| Vertical Load Compression Resistance (kgf) | 850 | 880 | 920 | 960 |
| Vision-Guided Container Inspection Accuracy (%) | 99.4% | 99.6% | 99.8% | 99.9% |
Analyst Perspective
"Hybrid electric melting furnaces allow container glassmakers to cut scope-one thermal emissions while maintaining chemical inertness. High furnace rebuild capital costs still require multi-year bottling offtake agreements before plants approve full tank conversions."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the glass bottles market segmented?
The glass bottles market is segmented by material resin / polymer, product format, barrier level, and end-use industry. In 2026, Polyethylene (LLDPE / HDPE) is projected at 39.5%, Pre-Formed Pouches & Bags at 49.3%, High-Barrier Modified Atmosphere (EVOH) at 40.1%, and Processed Food & Snacks at 30.4%.
By material resin / polymer: Polyethylene (LLDPE / HDPE), polypropylene (BOPP / CPP), recycled post-consumer PET, and bio-based compostable resins.
By product format: Pre-formed pouches & bags, rollstock barrier films, and thermoformed bladders & tubes.
By barrier level: High-barrier modified atmosphere (EVOH), medium-barrier standard, and breathable micro-perforated.
By end-use industry: Processed food & snacks, beverages & spirits, and pharmaceutical & personal care.
Why does Polyethylene (LLDPE / HDPE) lead the material resin / polymer category?
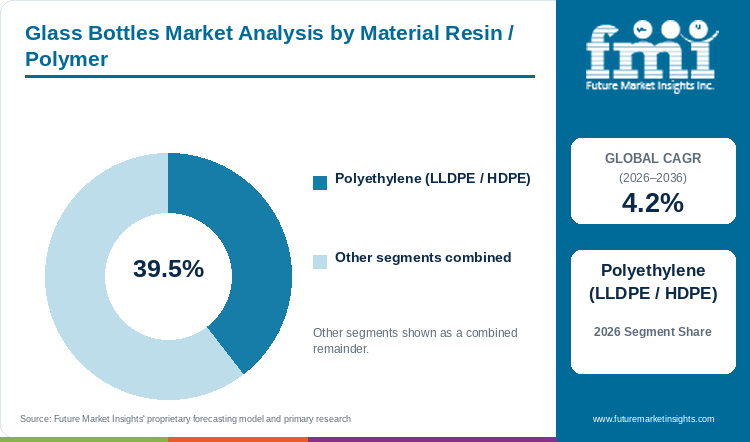
Polyethylene (LLDPE / HDPE) is expected to hold 39.5% of material resin / polymer revenue in 2026, supported by liner sealing compliance.
Table 5: Material Resin / Polymer Share for the Glass Bottles Market (percentage share), 2026
| Material Resin / Polymer | Share (2026) |
|---|---|
| Polyethylene (LLDPE / HDPE) | 39.5% |
| Other Segments Combined | 60.5%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Material Resin / Polymer Leadership and Market Growth for the Glass Bottles Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.2% |
| Leading Segment | Polyethylene (LLDPE / HDPE) |
High-speed beverage and pharmaceutical bottling lines require compliant polymer interface materials to prevent glass-to-metal contact and seal microscopic crown variations. Low-density and high-density polyethylene blends are molded into closure gaskets and protective exterior sleeves that cushion rigid glass containers against conveyor shock. When bottling plants integrate plastic caps and closures onto glass neck finishes, polyethylene liners maintain positive internal pressure without stress-cracking the glass rim. In addition to this, polyethylene shrink sleeves hold glass fragments together if a drop occurs during retail distribution. However, recyclers must separate polymer sleeves during cullet washing so residual resin does not contaminate furnace batch melts.
- Polyethylene (LLDPE / HDPE) is projected to account for 39.5% of material resin / polymer revenue in 2026, supported by widespread adoption in torque-stable bottle closure liners.
- In May 2025, the International Commission on Glass reported that polymer-cushioned neck finishes and protective sleeves reduced automated filling line bottle breakage by 18.0% [3].
What makes Pre-Formed Pouches & Bags central to the product format category?
Pre-formed pouches & bags are estimated to represent 49.3% of the product format category in 2026, reflecting household glass refill models.
Rising freight fuel tariffs and retailer scope-three emissions targets have made shipping water-heavy liquids in single-use glass across long distances increasingly expensive. To solve this cost friction without abandoning glass on the consumer shelf, personal care and beverage brands sell heavy decorative glass dispensers paired with pre-formed refill pouches. Households keep the permanent glass bottle in daily use and replenish it from lightweight flexible packs secured with specialized caps and closures. Owing to this hybrid merchandising model, brand owners retain the shelf prestige of flint and amber glass while cutting secondary distribution freight volume. Even so, pouch heat-seal integrity remains critical to prevent leakage during e-commerce parcel handling.
- Pre-formed pouches & bags are estimated to hold 49.3% of product format demand in 2026, reflecting rapid retail uptake of concentrate refill packs for permanent glass bottles.
- In June 2025, the Society of Glass Technology documented that pairing reusable household glass bottles with flexible refill pouches lowers transport mass by 60.0% across retail supply chains [4].
What keeps High-Barrier Modified Atmosphere (EVOH) ahead by barrier level?
High-barrier modified atmosphere (EVOH) is projected to capture 40.1% of barrier level demand in 2026, driven by oxygen-sensitive bottling requirements.
Although a glass bottle wall is completely impermeable to atmospheric gases, oxygen ingress frequently occurs through the microscopic gap between the bottle neck finish and the closure. Wine vintners and pharmaceutical formulators specify ethylene vinyl alcohol (EVOH) copolymer barrier liners inside screw caps and synthetic stoppers to block oxygen transmission over multi-year storage. Integrating EVOH-lined closures with durable glass packaging prevents oxidation of delicate esters in premium spirits and preserves potency in liquid medications. Furthermore, modified atmosphere nitrogen flushing during headspace capping works alongside EVOH liners to eliminate dissolved oxygen. High humidity during maritime transit can still plasticize unshielded EVOH layers, requiring multi-layer coextruded cap liners.
- High-barrier modified atmosphere (EVOH) is anticipated to contribute 40.1% of barrier level sales in 2026, driven by multi-year oxidation protection in bottled wines and biologics.
- In July 2025, the European Committee for Standardization published updated EN 14634 testing protocols governing gas-barrier closure interfaces and internal pressure resistance for glass containers [5].
Why do Processed Food & Snacks anchor the end-use industry category?
With an estimated 30.4% share in 2026, processed food & snacks lead the end-use industry category, underpinned by retort sterilization stability.
Commercial food processors packing acidic pasta sauces and infant purees face strict thermal sterilization requirements that deform standard rigid plastics. Filling lines subject sealed containers to pressurized steam retorts exceeding 120 degrees Celsius, where flint glass jars and bottles maintain exact dimensional stability and vacuum seal retention. Because glass contains no migrating monomers, parents and clean-label buyers strongly prefer transparent retail glass packaging that lets shoppers inspect food color and texture before purchase. In addition to this, wide-mouth glass bottles allow viscous condiments to dispense cleanly without chemical slip additives. However, grocery chains penalize heavy case weights, pushing food packers to qualify thin-wall narrow neck press-and-blow containers.
- Processed food & snacks are set to command 30.4% of end-use industry revenue in 2026, underpinned by high-temperature autoclave compatibility and chemical inertness.
- In August 2025, the American Society for Testing and Materials updated ASTM C147 hydrostatic pressure standards to verify thin-wall glass container durability on retort food lines [6].
What are the drivers, restraints, and opportunities in the glass bottles market?
In the Glass Bottles Market, single-use plastic penalties and pharmacopeia purity rules will continue to support demand, high furnace energy and rebuild costs will constrain margins, and lightweight narrow-neck forming is expected to expand commercial adoption through 2036.
- Driver: Extended producer responsibility fees on disposable plastics and strict USP Type I borosilicate drug rules will continue to shift beverage and medical packers toward glass through 2036.
- Restraint: Continuous 1,550-degree Celsius furnace power consumption and heavy container freight weights will continue to pressure glassmaker operating margins through 2036.
- Opportunity: Commercializing narrow neck press-and-blow lightweighting and hybrid electric melters is expected to unlock lower-emission supply contracts across food and spirits brands through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Escalating packaging waste taxes and strict pharmaceutical stability mandates are compelling brand owners to replace single-use polymer containers with recyclable glass bottles. FMI data suggests that injectable drug manufacturers are expanding long-term reservations for sterile pharmaceutical vials and borosilicate infusion bottles to prevent pH shift and silicone delamination during cold-chain storage. In September 2025, the United States Environmental Protection Agency reported that municipal recovery of glass food and beverage containers surpassed 3.1 million tons across domestic recycling programs [7]. At the same time, prestige skincare formulators are adopting custom glass cosmetic bottle designs to protect active serums from ultraviolet light. Suppliers must still prove zero glass lamellae formation before pharmaceutical quality teams approve commercial lot deliveries.
Risk Assessment of the Glass Bottles Market: Operational and Energy Friction
Continuous thermal energy consumption and periodic furnace relining costs represent the primary financial bottlenecks restricting container glass capacity expansion. Unlike plastic injection molding lines that can power down between shifts, regenerative glass tanks must hold molten batch above 1,500 degrees Celsius every hour of their ten-to-twelve-year campaign life. In October 2025, the Waste and Resources Action Programme documented that natural gas and electric melting expenses account for 33.0% of total British container glass manufacturing costs [8]. Sudden industrial power tariff spikes immediately compress plant gross margins, while unscheduled power outages risk solidifying molten glass inside the refractory tank. Consequently, glassmakers delay speculative furnace builds until beverage and healthcare buyers sign multi-year take-or-pay volume commitments.
Commercial Opportunity Analysis: Lightweighting Innovation and Electric Melters
Container glassmakers are capturing higher margins by combining narrow neck press-and-blow (NNPB) lightweighting with hybrid electric furnace conversions. Replacing blow-and-blow forming with NNPB plungers distributes molten glass evenly across the container shoulder, allowing plants to cut bottle mass by nearly one-third without losing top-load strength. In November 2025, the Glass Manufacturing Industry Council confirmed that NNPB lightweighting reduces unit bottle weight by 28.0% while preserving standard carbonated burst pressure ratings [9]. Lighter containers lower truckload fuel consumption for breweries and pharmacies ordering certified prescription bottles. Glassmakers must pair these forming upgrades with optical laser inspection cameras to reject thin-wall stress defects before palletizing.
Glass Bottles Market by Country (2026 to 2036)
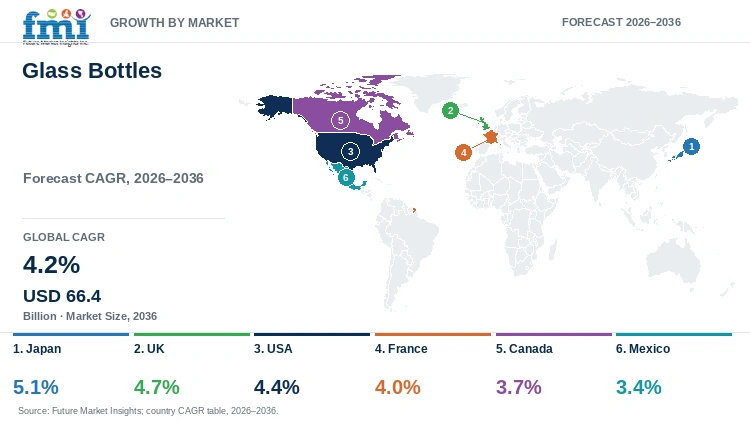
As per FMI, Japan leads evaluated country growth at a 5.1% CAGR from 2026 to 2036, whereas Mexico records the slowest evaluated trajectory at 3.4% CAGR. Across all six profiled markets, national growth rates depend on domestic cullet collection density and industrial power pricing alongside export bottling demand.
Table 7: Country CAGR and Primary Growth Levers for the Glass Bottles Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Japan | 5.1% | Municipal cullet sorting precision, ultra-lightweight sake bottles, and automated pharmaceutical vial inspection |
| UK | 4.7% | Export Scotch whisky bottling volume and digital deposit return scheme cullet recovery |
| USA | 4.4% | Domestic biologic drug reshoring, craft beverage bottling, and state extended producer responsibility laws |
| France | 4.0% | Luxury perfume flacon manufacturing in Normandy and lightweight champagne bottle adoption |
| Canada | 3.7% | Provincial deposit-return pools achieving high refillable beer and cider bottle rotation |
| Mexico | 3.4% | Appellation-protected tequila and mezcal export bottling requiring custom embossed flint glass |
Source: Future Market Insights analysis
Japan Glass Bottles Market Outlook (2026 to 2036)
Municipal waste separation rules across Japan supply domestic glassworks with exceptionally clean, color-sorted cullet that lowers furnace melting temperatures. Demand for glass bottles in Japan is forecast to rise at 5.1% CAGR over the forecast period, propelled by domestic sake brewers and pharmaceutical injectables plants. In December 2025, the Organisation for Economic Co-operation and Development reported that Japanese municipal sorting systems recover over 90.0% of post-consumer glass containers for closed-loop remelting [10]. High industrial LNG import prices still squeeze furnace operating budgets across Honshu. Domestic producers such as Nihon Yamamura Glass counter fuel costs by running ultra-lightweight NNPB forming lines and AI vision inspection for Kanto pharmaceutical clients.
Key takeaway: In Japan, disciplined municipal cullet sorting and domestic pharmaceutical vial automation sustain the fastest growth among evaluated countries.
UK Glass Bottles Market Outlook (2026 to 2036)
Export-oriented Scotch whisky and craft gin distilleries anchor British container demand, requiring heavy flint and antique-green bottles that protect brand provenance. The UK glass bottles sector is projected to record 4.7% CAGR during the assessment period, supported by distillery bottling expansion across Scotland and Northern England. In January 2026, the British Glass Manufacturers Confederation confirmed that domestic container furnaces remelted 1.8 million tonnes of recycled glass cullet during the preceding year [11]. However, UK industrial grid electricity prices remain among the highest in Western Europe, delaying full electric furnace conversions. Glassmakers are bridging this gap with oxy-fuel combustion upgrades and hospitality cullet collection contracts to stabilize unit container costs.
Key takeaway: In the UK, export spirits bottling and hospitality cullet recovery offset high industrial grid power costs.
USA Glass Bottles Market Outlook (2026 to 2036)
In the United States, demand for glass bottles is predicted to advance at 4.4% CAGR through 2036, backed by domestic biologic drug fill-finish investments and craft beverage packaging. In February 2026, the Beverage Can and Bottle Association documented a 12.0% rise in North American glass container orders across specialty beverage and healthcare accounts [12]. Unlike Western Europe, single-stream curbside recycling in many U.S. states contaminates crushed glass with paper and ceramics, forcing furnaces to haul virgin soda ash from Wyoming. To overcome cullet shortages, American container plants are investing in optical sorting hubs and modular MAGMA melters near regional wine and pharmaceutical clusters.
Key takeaway: In the USA, pharmaceutical reshoring and regional optical cullet hubs help glassmakers overcome single-stream recycling contamination.
France Glass Bottles Market Outlook (2026 to 2036)
French glassmaking is uniquely concentrated around high-margin luxury perfumery in Normandy's Glass Valley and pressurized sparkling wine bottles in Champagne and Bordeaux. Between 2026 and 2036, the France market is expected to progress at 4.0% CAGR, reinforced by nuclear-backed industrial electricity that favors electric-hybrid melting tanks. In March 2026, the Fédération du Verre reported that French glassworks supplied more than 70.0% of global luxury fragrance flacons while cutting average wine bottle weight by 14.0% [13]. Strict French AGEC anti-waste rules also mandate standardized reusable bottle washing pools for commercial restaurants. Container suppliers must balance delicate cosmetic clarity specifications against rising recycled cullet color variation.
Key takeaway: In France, luxury fragrance flacon leadership and low-carbon nuclear grid power accelerate electric furnace adoption.
Canada Glass Bottles Market Outlook (2026 to 2036)
Provincial beverage deposit systems in Ontario and Quebec alongside British Columbia operate standardized multi-trip bottle washing pools that keep glass containers in active circulation for up to fifteen fills. Sales of glass bottles in Canada are forecast to expand at 3.7% CAGR through 2036, aided by provincial extended producer responsibility fees on non-refillable plastics. In April 2026, the Packaging Association of Canada reported an 84.0% container return rate across provincial alcoholic beverage deposit networks [14]. Long winter rail hauls across provinces still add thermal shock and freight cost challenges for bottlers. Canadian beverage packers consequently specify thicker scuff-resistant sidewall coatings that survive repeated caustic bottle-washing cycles.
Key takeaway: In Canada, high-return provincial bottle deposit pools drive demand for scuff-resistant, multi-trip refillable glass containers.
Mexico Glass Bottles Market Outlook (2026 to 2036)
Appellation rules requiring 100% blue agave tequila and artisanal mezcal to be bottled within designated Mexican states create captive domestic demand for decorative flint glass. Mexico is estimated to post 3.4% CAGR over the forecast period, supported by export spirits bottling in Jalisco and high-volume domestic beer returnables. In May 2026, the Cámara Nacional de la Industria Maderera y del Envase recorded a 14.0% increase in custom-molded spirits bottle output across Mexican glass plants [15]. Cross-border natural gas pipeline constraints and water scarcity in northern industrial corridors still limit new greenfield furnace permits. Mexican glassmakers are responding by installing closed-loop water cooling towers and on-site cullet crushing lines at existing Monterey and Guadalajara complexes.
Key takeaway: In Mexico, mandatory domestic bottling rules for export tequila and mezcal sustain custom flint glass furnace utilization.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the glass bottles market?
Owens-Illinois Inc., Verallia SA, Ardagh Group S.A., Vidrala S.A., BA Glass Germany GmbH, Gerresheimer AG, Vetropack Holding Ltd., and Nihon Yamamura Glass Co. Ltd. are the notable companies in the glass bottles market.
In the FMI report, competition divides between multinational container glass groups operating high-pull beverage furnaces and specialist healthcare glassmakers producing Type I borosilicate vials. Owens-Illinois Inc. and Verallia SA alongside Ardagh Group S.A. run furnace networks near major beverage and food packers to minimize empty-bottle freight distances. Vidrala S.A. and BA Glass Germany GmbH along with Vetropack Holding Ltd. focus on regional European wine and food accounts through flexible mold changeovers and high cullet utilization. Meanwhile, Gerresheimer AG and Nihon Yamamura Glass Co. Ltd. supply cleanroom-formed pharmaceutical vials and ultra-lightweight bottles. Procurement teams qualify suppliers on internal pressure reliability and verified cullet documentation.
- Global Container Glass Conglomerates: Owens-Illinois Inc., Verallia SA, Ardagh Group S.A., and Vidrala S.A. operate multi-region regenerative and oxy-fuel furnace fleets for beverage and food brands.
- European Regional and Returnable Container Specialists: BA Glass Germany GmbH and Vetropack Holding Ltd. supply lightweight wine bottles and thermally tempered multi-trip containers.
- Healthcare and Precision Glass Formulators: Gerresheimer AG and Nihon Yamamura Glass Co. Ltd. manufacture USP Type I borosilicate vials, ampoules, and vision-inspected specialty bottles.
Competitive Benchmarking: Glass Bottles Market
Table 8: Competitive Benchmarking for the Glass Bottles Market (qualitative capability ratings), 2026
| Company | High-Speed Forming Capacity | Post-Consumer Cullet Scope | Electric Hybrid Melting | Geographic Reach |
|---|---|---|---|---|
| Owens-Illinois Inc. | High | High | High | High |
| Verallia SA | High | High | High | High |
| Ardagh Group S.A. | High | High | High | High |
| Vidrala S.A. | High | High | Medium | Medium |
| BA Glass Germany GmbH | High | High | Medium | Medium |
| Gerresheimer AG | High | Medium | High | High |
| Vetropack Holding Ltd. | Medium | High | Medium | Medium |
| Nihon Yamamura Glass Co. Ltd. | High | High | Medium | Medium |
Scoring basis: High-Speed Forming Capacity is High when a producer operates multi-section individual-section (IS) machines exceeding one billion containers annually, and Medium when focused on smaller specialty runs. Post-Consumer Cullet Scope is High when commercial furnace batches exceed 60.0% recycled glass content. Electric Hybrid Melting is High when commercial all-electric or hybrid oxy-fuel tanks are operational across printed rigid packaging networks, and Medium during pilot transition. Geographic Reach is High for multi-continental plant footprints and Medium for regional concentration.
Key Developments in the Glass Bottles Market
- In January 2026, Gerresheimer AG expanded its ready-to-use Type I borosilicate pharmaceutical vial production lines in Europe and North America. This capacity addition supplies pre-sterilized glass containers for commercial GLP-1 and biologic drug fill-finish plants [16].
- In September 2025, Ardagh Group S.A. commercialized an ultra-lightweight 330ml glass beer bottle across its European container plants. The narrow neck press-and-blow design cuts bottle mass by 15.0% while matching standard filling line drop-impact thresholds [17].
- In May 2025, Verallia SA commissioned its first commercial 100% electric glass melting furnace at its Cognac manufacturing complex in France. The electric melter reduces direct scope-one carbon dioxide emissions by 60.0% while producing flint spirits bottles [18].
- In January 2025, Owens-Illinois Inc. deployed a commercial MAGMA modular glass production line in Kentucky. The modular melter lowers furnace capital intensity and enables rapid batch changeovers for craft spirits brands [19].
Key Players in the Glass Bottles Market
Global Container Glass Conglomerates
- Owens-Illinois Inc.
- Verallia SA
- Ardagh Group S.A.
- Vidrala S.A.
European Regional and Returnable Container Specialists
- BA Glass Germany GmbH
- Vetropack Holding Ltd.
Healthcare and Precision Glass Formulators
- Gerresheimer AG
- Nihon Yamamura Glass Co. Ltd.
Glass Bottles Market - Report Scope
Table 9: Report Scope for the Glass Bottles Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Material Resin / Polymer; Product Format; Barrier Level; End-Use Industry; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes manufacturer revenue from commercial glass bottles, jars, vials, and integrated closure/refill container systems sold within the listed segmentation. Excludes flat architectural glass, fiberglass, and tableware. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Japan, UK, USA, France, Canada, Mexico, and additional countries in the full report |
| Key Companies Covered | Owens-Illinois Inc., Verallia SA, Ardagh Group S.A., Vidrala S.A., BA Glass Germany GmbH, Gerresheimer AG, Vetropack Holding Ltd., Nihon Yamamura Glass Co. Ltd. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Glass Bottles Market - Research Methodology
Table 10: Research Methodology for the Glass Bottles Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with glass furnace engineers, plant operations directors, cullet recycling processors, pharmaceutical packaging procurement leads, and beverage bottling managers to validate pull capacities, cullet ratios, and pricing. |
| Secondary Research | Secondary research examined container glass federation statistics, environmental agency recovery reports, pharmacopeia container standards, corporate annual filings, and technical glass science publications. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period combined bottom-up furnace pull capacity audits and container shipment volumes with top-down end-use beverage, food, and healthcare packaging demand. |
| Data Triangulation and Validation | Estimates were cross-checked against national glass recycling registries, industrial energy consumption benchmarks, and verified corporate segment disclosures to ensure consistency without double counting. |
Glass Bottles Market by Segments
Glass Bottles Market segmented by Material Resin / Polymer:
- Polyethylene (LLDPE / HDPE)
- Polypropylene (BOPP / CPP)
- Recycled Post-Consumer PET
- Bio-Based Compostable Resins
Glass Bottles Market segmented by Product Format:
- Pre-Formed Pouches & Bags
- Rollstock Barrier Films
- Thermoformed Bladders & Tubes
Glass Bottles Market segmented by Barrier Level:
- High-Barrier Modified Atmosphere (EVOH)
- Medium-Barrier Standard
- Breathable Micro-Perforated
Glass Bottles Market segmented by End-Use Industry:
- Processed Food & Snacks
- Beverages & Spirits
- Pharmaceutical & Personal Care
Glass Bottles Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] European Container Glass Federation (FEVE). (2025, March 18). European Container Glass Recycling Rates and Closed-Loop Circularity Statistics. FEVE Industry Reports.
- [2] Glass Packaging Institute (GPI). (2025, April 22). Glass Container Manufacturing Technical Standards and Recycling Facts. GPI Technical Bulletins.
- [3] International Commission on Glass (ICG). (2025, May 15). Advances in glass melting furnace thermal efficiency and closure interface protection. ICG Monograph Series, 44(2), 112-128.
- [4] Society of Glass Technology. (2025, June 19). Narrow neck press and blow lightweighting and hybrid refill systems in container glass production. Glass Technology: European Journal of Glass Science, 66(3), 85-94.
- [5] European Committee for Standardization. (2025, July 24). Glass packaging: Specifications for neck finishes, barrier closures, and internal pressure resistance. CEN Standards, EN 14634:2025.
- [6] American Society for Testing and Materials. (2025, August 28). Standard test methods for internal pressure and thermal shock strength of glass containers. ASTM Standards, C147-25.
- [7] United States Environmental Protection Agency. (2025, September 16). Advancing Sustainable Materials Management: Glass Material-Specific Data. EPA Annual Publications.
- [8] Waste and Resources Action Programme (WRAP). (2025, October 22). Decarbonization pathways and furnace energy cost structure for the British container glass sector. WRAP Technical Reports.
- [9] Glass Manufacturing Industry Council (GMIC). (2025, November 18). Narrow neck press-and-blow lightweighting and hybrid electric melter economics. GMIC Sector Studies.
- [10] Organisation for Economic Co-operation and Development. (2025, December 14). Extended Producer Responsibility and Economic Instruments for Packaging. OECD Environment Policy Papers.
- [11] British Glass Manufacturers Confederation. (2026, January 20). Annual container glass production, cullet remelting, and decarbonization status report. British Glass Publications, 2026-01.
- [12] Beverage Can and Bottle Association. (2026, February 16). North American beverage and pharmaceutical glass container procurement review. BCBA Annual Review, 2026-02.
- [13] Fédération du Verre. (2026, March 24). L'industrie du verre en France: Production de flacons, allègement et transition électrique. FDV Rapport Annuel, 2026-03.
- [14] Packaging Association of Canada. (2026, April 18). Provincial deposit-return container recovery and multi-trip glass pooling in Canada. PAC Technical Briefings, 2026-04.
- [15] Cámara Nacional de la Industria Maderera y del Envase. (2026, May 22). Mexican beverage packaging and appellation spirits container manufacturing overview. CNIME Informes Industriales.
- [16] Gerresheimer AG. (2026, January 15). Expansion of high-precision Type I ready-to-use borosilicate vial production lines. Corporate Investor Briefings.
- [17] Ardagh Group S.A. (2025, September 22). Commercial rollout of ultra-lightweight 330ml NNPB glass beer bottles. Corporate Media Releases.
- [18] Verallia SA. (2025, May 28). Commissioning of commercial 100% electric glass melting furnace in Cognac. Corporate Press Releases.
- [19] Owens-Illinois Inc. (2025, January 26). Commercial deployment of MAGMA modular glass melting architecture. Corporate Technology Announcements.
- [20] Vidrala S.A. (2025, August 14). Installation of optical cullet sorting automation across Iberian container glass plants. Corporate Sustainability Disclosures.
- [21] Vetropack Holding Ltd. (2025, October 19). Commercial scaling of thermally tempered reusable glass bottles for European beverage pools. Corporate Media Releases.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the glass bottles market in 2026 and what is forecast for 2036?
- Which circular packaging mandates and furnace economics shape demand for glass bottles?
- Why does Polyethylene (LLDPE / HDPE) lead the material resin / polymer category?
- Why do Pre-Formed Pouches & Bags represent the leading product format share globally?
- How do growth rates differ across Japan, the UK, the USA, and France?
- Which notable companies operate high-speed container furnaces and pharmaceutical vial lines today?
- What energy and logistics constraints limit margin expansion in the glass bottles market?
- What technical parameters should bottling procurement teams verify before qualifying a glass supplier?
Frequently Asked Questions
How big is the glass bottles market in 2026, and what is forecast for 2036?
The global glass bottles market is estimated to reach USD 44.0 billion in 2026. Revenue is projected to expand to USD 66.4 billion by 2036 as food, spirits, and pharmaceutical brands prioritize chemically inert packaging.
What is the CAGR for the glass bottles market from 2026 to 2036?
As per FMI, the market is projected to grow at a 4.2% CAGR from 2026 to 2036. Expansion is supported by closed-loop cullet recycling programs and narrow neck press-and-blow container lightweighting.
Which material resin / polymer segment leads the glass bottles market?
Polyethylene (LLDPE / HDPE) is projected to hold 39.5% of material resin / polymer demand in 2026. The segment leads because bottling lines depend on compliant polyethylene closure liners and protective shrink sleeves.
Which product format segment holds the largest share in 2026?
Pre-formed pouches and bags account for 49.3% of the product format category in 2026. Demand is driven by concentrate refill pouches that replenish reusable household glass bottles and cut shipping weight.
Which country has a notable growth outlook during the assessment period?
FMI finds that Japan is projected to register a 5.1% CAGR between 2026 and 2036. Growth is underpinned by disciplined municipal cullet sorting, lightweight sake bottling, and domestic pharmaceutical vial automation.
Who are the key players active in the glass bottles market?
Notable participants include Owens-Illinois Inc., Verallia SA, Ardagh Group S.A., Vidrala S.A., BA Glass Germany GmbH, Gerresheimer AG, Vetropack Holding Ltd., and Nihon Yamamura Glass Co. Ltd. These producers focus on electric-hybrid melting furnaces, cullet batch maximization, and thin-wall bottle forming.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Material Resin / Polymer, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Resin / Polymer, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Resin / Polymer, 2026 to 2036
- Polyethylene (LLDPE / HDPE)
- Polypropylene (BOPP / CPP)
- Recycled Post-Consumer PET
- Bio-Based Compostable Resins
- Y-o-Y Growth Trend Analysis By Material Resin / Polymer, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Resin / Polymer, 2026 to 2036
- Global Market Analysis and Forecast, By Product Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Format, 2026 to 2036
- Pre-Formed Pouches & Bags
- Rollstock Barrier Films
- Thermoformed Bladders & Tubes
- Y-o-Y Growth Trend Analysis By Product Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Format, 2026 to 2036
- Global Market Analysis and Forecast, By Barrier Level, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Barrier Level, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Barrier Level, 2026 to 2036
- High-Barrier Modified Atmosphere (EVOH)
- Medium-Barrier Standard
- Breathable Micro-Perforated
- Y-o-Y Growth Trend Analysis By Barrier Level, 2021 to 2025
- Absolute $ Opportunity Analysis By Barrier Level, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Industry, 2026 to 2036
- Processed Food & Snacks
- Beverages & Spirits
- Pharmaceutical & Personal Care
- Y-o-Y Growth Trend Analysis By End-Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Owens-Illinois Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Verallia SA
- Ardagh Group S.A.
- Vidrala S.A.
- BA Glass Germany GmbH
- Gerresheimer AG
- Vetropack Holding Ltd.
- Nihon Yamamura Glass Co. Ltd.
- Owens-Illinois Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


