
- Market Size (2026)
- USD 72.1 Bn
- Forecast (2036)
- USD 134.2 Bn
- CAGR (2026 to 2036)
- 6.4%
How big is the Waste Recycling Services Market in 2026?
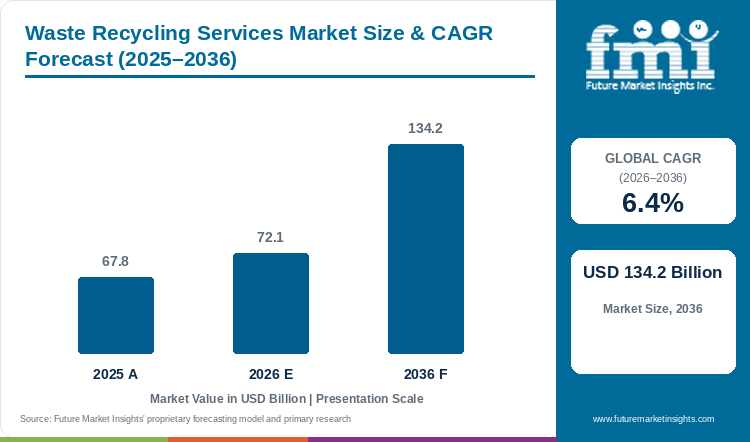
Demand for collection and processing of industrial scrap should carry the Waste Recycling Services Market to USD 134.2 billion by 2036. FMI estimates the market at USD 72.1 billion in 2026 and projects a 6.4% CAGR over the 2026 to 2036 period. The market was valued at USD 67.8 billion in 2025. Metallurgical uses hold 24.0% by application, Iron and Steel 57.0% by product type and Industrial Companies 46.0% by end use in FMI's 2026 assessment.
Public recycling targets and steel scrap demand set the pace. Eurostat reports recycling handled 42.0% of the 1,956 million tonnes of waste treated in the EU in 2024. China recovered 417 million tonnes of renewable resources in 2025. A national action plan targets 510 million tonnes a year by 2030. A provisional EU agreement of December 2025 would require new vehicles to carry 15.0% recycled plastic within six years of the rules taking effect.
Commodity prices decide how much volume turns into margin. Sims Limited reported Chinese steel exports weighed on ferrous prices in Australia and New Zealand in its 2026 financial year. Toyota Tsusho gives a qualified example of buyer interest in scrap supply. It completed the purchase of Radius Recycling in July 2025. That business processed 660,000 end-of-life vehicles in its 2024 financial year. One deal secures feedstock for one manufacturer and does not prove a market-wide wave.
Key Market Trends & Insights
- Recovered commodity prices in North America rose through 2026. WM's blended recycled commodity price was about USD 82.0 per ton in the third quarter of 2026, against about USD 68.0 per ton a year earlier. Republic Services reported USD 142.0 per ton, up USD 16.0 on the prior year. Higher prices lift processing revenue without new tonnes, which raises the value of existing sorting capacity.
- Large operators are buying regional competitors on both sides of the Atlantic. Paprec expects revenue of nearly EUR 5.0 billion by the end of 2026, subject to completion of its announced acquisitions, including Marius Pedersen's Czech and Slovak waste businesses. Republic Services invested USD 1.1 billion in acquisitions in the first nine months of 2026. Scale lowers the cost of trucks, sorting lines and compliance per tonne handled.
Regional Highlights
- Europe has the most complete recycling statistics and the firmest rules. Eurostat records that 48.0% of EU municipal waste was recycled in 2024 and that 24.0% went to landfill. The provisional end-of-life vehicle agreement of December 2025 would add producer responsibility across borders and ban exports of unroadworthy used cars five years after the rules enter into force. Processors gain a protected feedstock and a new compliance burden at the same time.
- East Asia combines very high industrial recovery with weak municipal recycling. Japan recycled 54.7% of its 367.25 million tonnes of industrial waste in the 2023 fiscal year, while its municipal recycling rate was 19.3% in the 2024 fiscal year. China's recovery of renewable resources rose 4.1% in 2025, with scrap steel above 60.0% of the volume. Service providers in the region earn most of their revenue from industrial customers.
Waste Recycling Services Market Size and Forecast
Table 1: Waste Recycling Services Market Size and Forecast
| Market size and forecast | Value |
|---|---|
| Market size in 2025 | USD 67.8 billion |
| Estimated market size in 2026 | USD 72.1 billion |
| Projected market size by 2036 | USD 134.2 billion |
| CAGR from 2026 to 2036 | 6.4% |
Source: Future Market Insights analysis of the waste recycling services market, 2026.
Analyst Perspective
“Industrial and municipal buyers award recycling contracts on price per tonne and on documented recovery rates. They also favour an operator that can handle several waste streams under one contract. Providers stand apart through sorting technology and end-market access for recovered metals and plastics. Permits for hazardous fractions add a further edge. Commodity exposure is the main qualification risk. A contract priced at one scrap or paper price can turn loss-making within a year. Buyers now ask how much of a provider's revenue is indexed to published commodity prices.”
- Nikhil Kaitwade, Principal Consultant, FMI
How is the Waste Recycling Services Market segmented?
- By application: Metallurgical, Chemical, Agriculture and Forestry, Textile, Power and Energy, and Construction Industry.
- By product type: Iron and Steel, Automotive Recycling, Battery Recycling, Compost and Food Waste, Computer and Electronics, Glass and Fiberglass, Liquids, Oils and Chemicals, Multi-Material Collection, Wastepaper, Scrap Plastic, Tire and Rubber, and Others.
- By end use: Municipal Authorities, Industrial Companies, Recycling Companies, and Commercial Establishments.
- By deployment: Centralized Recycling Facilities, Decentralized Recycling Systems, and Mobile Recycling Units.
- By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does Metallurgical lead by Application in the Waste Recycling Services Market in 2026?
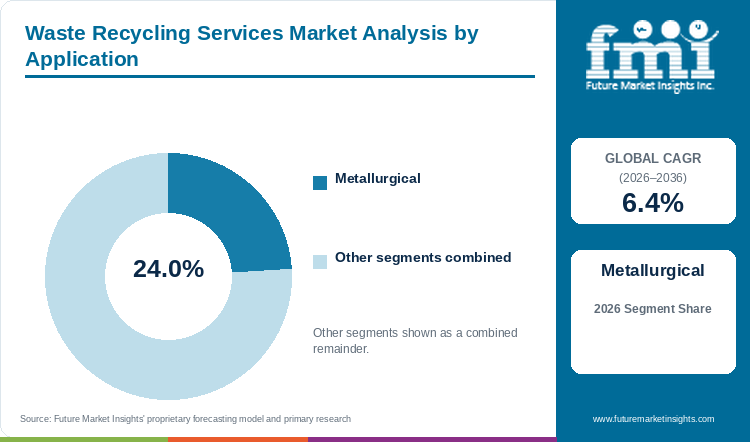
Metallurgical uses hold 24.0% of the Waste Recycling Services Market by application in 2026.
Steelmakers are the steadiest buyers of recovered material. The Bureau of International Recycling estimates global use of recycled steel at some 630 million tonnes a year. Electric arc furnaces made 71.3% of US crude steel and 90.1% of Italian crude steel in 2025. These mills run on scrap, so every tonne of ferrous waste collected has a buyer at a published price. Collection and shredding services for that scrap form part of the wider metal recycling market.
Trade flows show how far the metallurgical pull reaches. Türkiye was the largest importer of recycled steel between January and June 2025 at 9.404 million tonnes, and the EU was the largest exporter at 8.304 million tonnes. Sims' North America Metal segment lifted underlying EBIT 69.7% to AUD 135.9 million in its 2026 financial year, helped by tariffs that support US mill demand for scrap. Yards close to electric mills therefore have the shortest route to a buyer.
The other five applications together hold the remaining 76.0% by application. Demand there is less price-transparent. Japan's electricity, gas and water utilities produced 26.5% of industrial waste in the 2023 fiscal year and agriculture and forestry 22.0%. Service providers handle those streams under local contracts with few published price benchmarks.
Table 2: Application, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Metallurgical | 24.0% |
| All Other Segments Combined Share | 76.0% |
Source: Future Market Insights analysis of the waste recycling services market, 2026.
Why does Iron and Steel lead by Product Type in the Waste Recycling Services Market in 2026?
Iron and Steel accounts for 57.0% of 2026 product type value in the Waste Recycling Services Market.
Ferrous scrap is the one recovered material with a mill-ready market in every profiled country. The US Geological Survey estimates that American steelmakers and foundries consumed 57 million tons of scrap in 2025 and that domestic purchases were worth USD 19.7 billion. The composite price of No. 1 heavy melting scrap averaged USD 319.0 per ton in 2025, against USD 314.9 per ton in 2024. A processor can sell every tonne it shreds at a quoted price, which is why ferrous handling anchors yard economics.
Processing is concentrated and capital-heavy. The five leading US scrap processors handled 26 million tons at 354 facilities in 2023, and more than 280 car shredders operate in North America. Radius Recycling alone produced about 4.5 million tons of ferrous recycled products in its 2024 financial year. Sims sold 6.3 million tonnes of proprietary metal in its 2026 financial year. Exports absorb the surplus. The United States shipped 13 million tons of scrap abroad in 2025, with Türkiye accounting for 29.0% of that tonnage.
Automotive Recycling, Battery Recycling, Wastepaper, Scrap Plastic and the other product types together represent the remaining 43.0%. End-of-life vehicles feed the ferrous stream and carry rules of their own. The EU treated an estimated 4.3 million of them in 2023 at a reuse and recycling rate of 88.3%. The provisional EU agreement of December 2025 would require 15.0% recycled plastic in new vehicles within six years of the rules taking effect. Electronic scrap is gaining value. Sims Lifecycle Services raised underlying EBIT to AUD 172.7 million in its 2026 financial year on memory pricing and hyperscaler activity. Germany recycled just under 758,000 tonnes of waste electrical equipment in 2024. That stream overlaps with the e-waste management market.
Table 3: Product Type, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Iron and Steel | 57.0% |
| All Other Segments Combined Share | 43.0% |
Source: Future Market Insights analysis of the waste recycling services market, 2026.
Why do Industrial Companies lead by End Use in the Waste Recycling Services Market in 2026?
Industrial Companies hold a 46.0% share by end use in the Waste Recycling Services Market in FMI's 2026 assessment.
Industry generates far more recoverable waste than households. Eurostat attributes 8.9% of EU waste in 2024 to households. Manufacturing produced 9.9%, construction 38.2% and mining 23.9%. In England, commercial and industrial sources produced 30.8 million tonnes in 2024 and construction and demolition 118.2 million tonnes. Households produced 21.9 million tonnes. Industrial customers also sign multi-site contracts covering several streams at once. Lély Environnement collected 200,000 tonnes of commercial and industrial waste a year before Paprec bought it in February 2026.
Municipal Authorities, Commercial Establishments and Recycling Companies together account for the remaining 54.0%. Municipal work pays more per tonne but is tendered less often. SUEZ won a EUR 420.0 million twelve-year sorting and recovery contract at Calce near Perpignan during the first six months of 2026. Residential collection brought Republic Services USD 782.0 million in its September 2026 quarter. Small-container commercial customers paid it USD 1,379.0 million in the same quarter. Those municipal and commercial contracts overlap with the broader waste management market.
Table 4: End Use, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Industrial Companies | 46.0% |
| All Other Segments Combined Share | 54.0% |
Source: Future Market Insights analysis of the waste recycling services market, 2026.
What are the key drivers restraints and opportunities?
Waste recycling services earn from gate fees paid by waste producers and from the sale of recovered material. Regulation decides how much waste must be separated, and commodity markets decide what the output is worth.
Driver
Public targets are pushing separated volume into the service chain. The EU recycled 48.0% of municipal waste in 2024, and the provisional vehicle circularity deal would add recycled content duties for carmakers once adopted. China's action plan of January 2026 targets 510 million tonnes of major renewable resources recycled each year by 2030, up from 417 million tonnes in 2025. Workplaces in England with ten or more full-time equivalent staff have had to separate dry recyclables and food waste since 31 March 2025. Each rule raises the number of customers who must buy a recycling service.
Restraint
Income from recovered material moves with prices the provider does not control. Cleanaway reported that lower commodity prices and lower old corrugated cardboard prices offset part of its resource recovery growth in the 2026 financial year. Sims' ANZ Metal segment saw underlying EBIT fall 22.7% as Chinese steel exports pushed ferrous prices down. Recovered fibre prices follow the paper recycling market, which a processor cannot hedge easily. Contracts that pass price risk back to the waste producer are harder to win in competitive tenders.
Opportunity
Contracts that bundle collection with processing and guaranteed end markets offer the clearest new revenue. Republic Services' Blue Polymers venture with Ravago buys all olefins produced by its Polymer Centers, which ties plastic sorting to resin demand. SUEZ secured a ten-year EUR 460.0 million operations contract for the Milton Keynes energy recovery facility in its half-year 2026 results. Providers that can show offtake for their output can bid for longer municipal and industrial terms. Any recycled content claim should be checked against the buyer's own reporting.
How do landfill taxes and producer responsibility rules affect waste recycling services purchasing?
Disposal taxes set the price ceiling for recycling services. The UK standard rate of landfill tax rose to GBP 130.75 per tonne on 1 April 2026 and will reach GBP 136.70 per tonne in April 2027. Queensland's general levy in the metropolitan area rose from AUD 125.0 to AUD 135.0 per tonne for 2026-27. New Zealand's levy on municipal landfill climbed to NZD 70.0 per tonne in July 2026 and reaches NZD 75.0 in 2027. Every increase widens the margin a recycler can charge while still pricing below landfill.
Producer responsibility rules add customers who must pay for take-back. South Korea brought toys into its extended producer responsibility system on 1 January 2026. The provisional EU vehicle agreement would make producers financially responsible for free take-back and treatment of every end-of-life vehicle. Korea's cabinet also approved an exemption from import guarantees for ten types of circular resources on 31 March 2026, including waste paper and scrap metal. Buyers in these markets will contract with recyclers that hold the required permits and reporting systems.
What limits reliable waste recycling supply and quality?
Feedstock volume is not rising everywhere. Germany's waste generation fell 4.6% to 362.7 million tonnes in 2024 as construction waste dropped 8.1%. That total was the lowest since 2009. The number of end-of-life vehicles in the EU fell 8.6% in 2023. Household recycling in the UK was 44.5% in 2024, a slight decline on 2023. Processors built for growth in tonnes must compete for a flat or shrinking supply in several markets.
Investment in sorting technology lags demand for quality. Japan's municipal system still sends most waste to 991 incineration plants and recycles 19.3%. Without new sorting lines, output quality falls short of the specifications that steelmakers and resin producers set.
Where can waste recycling service providers win additional business?
Providers can add hazardous waste, electronic scrap and deposit container handling to existing contracts. Veolia completed its USD 3.0 billion purchase of Clean Earth in June 2026 and now runs more than 150 US locations with 33 EPA-permitted treatment facilities. Sims opened a lifecycle services facility in India and expanded into Ireland during its 2026 financial year. Each service line sells into a customer base that already has a compliance need.
Waste Recycling Services Market by Country (2026 to 2036)
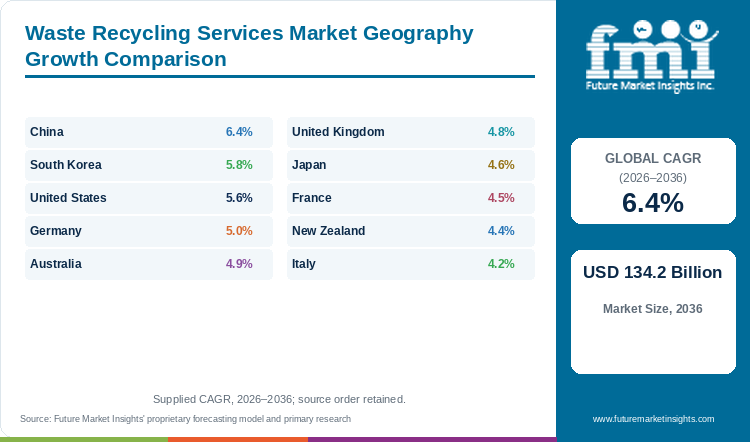
Table 5: Waste Recycling Services Market Country Growth Forecast
| Country | CAGR, 2026 to 2036 |
|---|---|
| China | 6.4% |
| South Korea | 5.8% |
| United States | 5.6% |
| Germany | 5.0% |
| Australia | 4.9% |
| United Kingdom | 4.8% |
| Japan | 4.6% |
| France | 4.5% |
| New Zealand | 4.4% |
| Italy | 4.2% |
Source: Future Market Insights analysis of the waste recycling services market, 2026.
China
China's recycling system is measured in volume. The China Materials Recycling Association counted 417 million tonnes of renewable resources recovered in 2025, a rise of 4.1%. The recovery value reached CNY 1.4 trillion. Scrap steel made up more than 60.0% of that tonnage. Waste batteries, waste tyres and scrap motor vehicles grew fastest. The association links that growth to trade-in subsidies for cars and appliances.
Policy sets the next step. The action plan issued in January 2026 by the National Development and Reform Commission and 24 other departments targets 510 million tonnes of major renewable resources recycled a year by 2030. It also calls for 4.5 billion tonnes of bulk solid waste to be used each year by the same date. Service providers that build the collection points and sorting centres for those tonnes will capture most of the growth. These targets drive the 6.4% CAGR expected for China across 2026 to 2036, the highest of the ten countries profiled.
The steel route is the limit on scrap value. Electric arc furnaces produced only 10.6% of the 960.8 million tonnes of steel China made in 2025. Recycled steel use fell 11.4% to 109.01 million tonnes in the six months to June 2025. Collection can grow faster than domestic melting demand, which would push prices down and leave recyclers holding stock. Operators that can sell non-ferrous metals, battery materials and plastics into manufacturing supply chains will depend less on steel mills. Export outlets also matter when domestic demand softens, so yards near ports hold an advantage over inland collectors.
South Korea
South Korea is widening the list of materials that must be recycled. The National Assembly passed an amendment to the Act on the Promotion of Saving and Recycling of Resources on 29 January 2026. It requires the climate and environment minister to set separate collection guidelines that local governments must follow. Toys entered the extended producer responsibility system on 1 January 2026. Both changes add streams that municipalities and producers must pay someone to collect and process.
Imports are being opened to feed processors. The cabinet approved an exemption from import guarantees for circular resources on 31 March 2026. It covers ten material types including waste paper, scrap metal and waste aluminium. Cheaper imported feedstock helps Korean plants run at full rate when domestic supply is short. Over 2026 to 2036, that regulatory widening translates into a 5.8% CAGR, second only to China in this group.
Steel demand works against that outlook for now. Korean mills used 10.242 million tonnes of recycled steel in the opening half of 2025, a fall of 11.3%. Recycled steel covered 33.4% of their output. Electric arc furnaces made 27.0% of Korea's 2025 crude steel output of 62.2 million tonnes. Scrap collectors therefore face weak domestic pull until steelmakers raise electric output. Recyclers serving electronics, packaging and battery streams will see steadier demand than ferrous yards. Firms that secure the new producer responsibility contracts early gain a reference for later tenders, and those with import licences can arbitrage between domestic and foreign feedstock.
United States
Electric arc furnaces made 71.3% of the 81.9 million tonnes of crude steel produced in the United States in 2025. That share gives domestic scrap a ready buyer. The Bureau of International Recycling recorded US recycled steel use of 26.71 million tonnes from January to June 2025 and exports of 6.0 million tonnes. Sims expects tariffs to keep protecting US mills and supporting scrap demand into its 2027 financial year.
Municipal recycling still has room to grow. The Environmental Protection Agency's latest national figures show 292.4 million tons of municipal solid waste generated in 2018, with 32.1% recycled or composted and 50.0% landfilled. Plastics were recycled at 9.0% and paper at 68.2%. Those rates leave large tonnages that private operators can target with new sorting capacity.
The two national operators are turning that volume into revenue. WM's recycling processing and sales revenue rose to USD 441.0 million in its September 2026 quarter as its blended commodity price reached about USD 82.0 per ton. Republic Services grew quarterly revenue 8.2% to USD 4,559.0 million and invested USD 1.1 billion in acquisitions in the first nine months of 2026. A 5.6% CAGR over 2026 to 2036 follows from scrap demand at electric mills and from consolidation by the two national firms. Toyota Tsusho's ownership of Radius Recycling since July 2025 adds a manufacturer with its own Oregon mill to the buyer side. Smaller haulers will keep selling to the consolidators as compliance and fleet costs rise.
Germany
German recyclers work in a market where total waste is falling. Destatis reports 362.7 million tonnes generated in 2024, down 4.6% and the lowest since 2009. Construction and demolition waste made up half of the total and fell 8.1%. Municipal waste edged up 0.8% to 49.3 million tonnes. Volume growth therefore depends on the household and commercial streams, not on building sites.
Recovery rates are already high. Germany recovered 82.0% of its waste in 2024, with 249.9 million tonnes going to material recycling. Waste electrical equipment recycling rose 1.5% to just under 758,000 tonnes at a recycling rate of 84.3%. With most waste already recovered, providers earn more from quality grades and specialised streams than from new tonnage. That structure holds the German outlook to a 5.0% CAGR over 2026 to 2036.
Scrap trade gives German yards an export outlet. Germany exported 7.6 million tonnes of ferrous scrap in 2025 and imported 3.9 million tonnes. Electric arc furnaces made 30.6% of its 34.1 million tonnes of crude steel. Domestic mills therefore consume less scrap than the country collects, so prices follow export markets. REMONDIS operates about 1,500 branches and associated companies in more than 30 countries from its German base. Groups of that size can balance weak domestic steel demand with sales abroad. Smaller yards without export logistics will struggle whenever European mill demand softens, and some will sell to the larger groups.
Australia
Australian recycling revenue is being reshaped by consolidation and levies. Cleanaway lifted net revenue 13.1% to AUD 3,736.7 million in the year to 30 June 2026. Solid Waste Services contributed AUD 2,506.4 million of that total. The acquired businesses Contract Resources and Citywide Waste added AUD 319.8 million and AUD 103.3 million of revenue. EQT Infrastructure has made a non-binding indicative proposal for the company, which says there is no certainty it will lead to a binding offer.
State levies keep raising the cost of disposal. Queensland's general levy in the metropolitan area rose from AUD 125.0 to AUD 135.0 per tonne for 2026-27, while the regional rate moved from AUD 97.0 to AUD 100.0. Higher levies make separated collection cheaper than landfill for more customer sites. That pricing pressure sustains a 4.9% CAGR for Australia in 2026 to 2036 even as commodity income weakens.
Metals and paper show that weakness. Sims' ANZ Metal underlying EBIT fell 22.7% to AUD 55.8 million as Chinese steel exports pressured ferrous prices and proprietary volumes dropped 3.6%. Cleanaway said lower old corrugated cardboard prices partly offset its resource recovery growth. Sims is building fines plants at Broadmeadows and Pinkenba to lift the value recovered from shredder residue. Providers that invest in such processing can hold margin while prices stay low. Cleanaway guides to underlying EBIT of AUD 500.0 million to AUD 530.0 million for its 2027 financial year and calls it a transitional year.
United Kingdom
British recycling rules changed for workplaces before they changed for households. Since 31 March 2025 every workplace in England with ten or more full-time equivalent staff must separate dry recyclables, food waste and residual waste. Micro-firms follow by 31 March 2027. Commercial and industrial sources generated 30.8 million tonnes in England in 2024, so the rule created a large block of new recycling customers.
Landfill tax underwrites the price of those services. The standard rate rose to GBP 130.75 per tonne on 1 April 2026 and is set at GBP 136.70 for April 2027. The lower rate more than doubled to GBP 8.65 per tonne in 2026. Operators can price collection and sorting below those figures and still win contracts. Rising disposal cost and compulsory separation at work produce a 4.8% CAGR for British recycling services in 2026 to 2036.
Household performance is flat. The UK recycled 44.5% of waste from households in 2024, down from 44.6%. England still landfilled 37.5 million tonnes, or 21.1% of treated waste. The deposit return scheme due in October 2027 will move drinks containers into a separate channel, and the UK Deposit Management Organisation, named system operator in May 2025, was also named operator for Wales on 20 August 2026. SUEZ added a ten-year contract worth EUR 460.0 million to operate the Milton Keynes energy recovery facility. Energy recovery competes with recycling for residual tonnes, which limits how far sorting revenue can rise.
Japan
Japan's industrial waste is already mostly recycled. Businesses generated 367.25 million tonnes in the 2023 fiscal year, of which 54.7% was recycled and only 2.4% went to final disposal. Electricity, gas and water utilities produced 26.5% of the total. Agriculture and forestry added 22.0% and construction 21.8%. Service growth comes from treating difficult fractions, not from diverting waste away from landfill.
Municipal waste is the opposite case. Municipal solid waste reached 38.11 million tonnes in the 2024 fiscal year, and the recycling rate was 19.3%. Japan ran 991 incineration plants at the end of March 2025 and spent JPY 2,448.9 billion on waste disposal. Incineration leaves little for recyclers, so municipal volume will stay small through the forecast period. Japan's 4.6% CAGR for 2026 to 2036 reflects the sum of these two structures.
Specialist processors are growing with industrial clients. Daiseki reports a single environment-related business segment. It posted record sales of JPY 71.8 billion in the year to February 2026, up 6.7%. It forecasts JPY 74.2 billion for the following year. Scrap steel demand is modest. Japan produced 80.7 million tonnes of crude steel in 2025 and electric furnaces made 25.8% of it. Recycled steel use fell 6.7% in the first six months of 2025. Industrial customers with liquid, chemical and oil waste offer better pricing than ferrous yards in this market. They renew contracts on treatment capability more than on price.
France
France is behind its own recycling targets. The statistics service of the ecology ministry reports that 48.0% of non-mineral and non-hazardous waste was recycled in 2022. The target was 55.0% for 2020 and 65.0% for 2025. Landfill still accounted for 20.0% of tonnages. Waste management spending reached EUR 22.0 billion in 2023. Companies paid 41.0% of it and households 35.0%, with public bodies covering 24.0%. The shortfall against targets gives public buyers a reason to tender for new sorting capacity.
Private operators are consolidating to serve those tenders. Paprec grew 2025 revenue 17.0% to EUR 3.5 billion and treated 19 million tonnes of waste. In February 2026 it bought Lély Environnement in Isère. That company collects 200,000 tonnes of commercial and industrial waste a year and runs a 75,000 tonne sorting centre. SUEZ's French waste revenue rose 2.6% between January and June 2026, and it won the EUR 420.0 million Calce sorting contract. The French outlook, a 4.5% CAGR across 2026 to 2036, rests on these tenders and on continued consolidation.
Domestic mills use only part of French scrap. France made 9.9 million tonnes of crude steel in 2025 and 36.4% of it came from electric furnaces, a small base next to Germany or Italy. French scrap therefore moves to export markets or to foreign mills within the EU. Recyclers that control sorting centres and composting sites earn steadier margins than scrap traders. Paprec's expectation that international revenue will exceed EUR 1.0 billion in 2026 also shows that French operators now look abroad for growth.
New Zealand
New Zealand uses its disposal levy as the main lever on recycling. The levy on municipal landfill rose to NZD 65.0 per tonne in July 2025, NZD 70.0 in July 2026 and will reach NZD 75.0 in July 2027. Construction and demolition fills pay NZD 40.0 per tonne from July 2026, up from NZD 30.0 two years earlier. Before the expansion the levy applied only to municipal landfills accepting household waste.
The money flows back into collection. The Ministry for the Environment expects the 2025 to 2027 increases to raise an additional NZD 171.0 million over three years, with half allocated to territorial authorities for their waste minimisation plans. Councils use that funding to buy kerbside and transfer station services from private operators. New Zealand's 4.4% CAGR across 2026 to 2036 is therefore levy-led diversion more than market pull.
Metal recovery is the weak link. New Zealand produced no crude steel from electric arc furnaces in 2025. Sims expects domestic demand to rise once the Glenbrook electric arc furnace is commissioned. Until then scrap must be exported, which ties local yards to Asian prices. Sims lists a Metal Recovery Plant in Auckland among its ANZ capital projects. That plant will lift the value recovered from shredder output before export. Small market size means a single plant or contract can move national volumes, so providers should plan around a handful of council and industrial accounts and protect those relationships through service quality.
Italy
Italy's municipal system is still improving. ISPRA reports just over 29.9 million tonnes of municipal waste in 2024, up 2.3%. Separate collection reached 67.7% and recycling 52.3%. Landfill fell to 14.8% of production. The North separates 74.2% of its waste, the Centre 63.2% and the South 60.2%. The southern shortfall is where new collection contracts will be awarded.
Costs are rising with service levels. Municipal waste management cost EUR 214.4 per inhabitant in 2024, up from EUR 197.0 the year before. Italy ran 625 operational municipal waste plants. Higher per-head spending pays for the sorting and composting capacity those plants represent. Italy grows at a 4.2% CAGR in 2026 to 2036 on southern collection growth and plant upgrades. That is the lowest rate of the profiled group, because northern regions are close to their collection limits.
Steel is Italy's strongest end market for recovered material. Electric arc furnaces produced 90.1% of Italy's 20.7 million tonne crude steel output in 2025, far above Germany at 30.6% and France at 36.4%. Italian mills therefore absorb domestic scrap and buy more from abroad. Foreign groups are entering the industrial segment. In March 2026 Paprec signed a binding agreement to acquire a majority stake in Convertini, a company based west of Milan. It treated 48,000 tonnes of non-hazardous waste in 2024. SUEZ's integration of Gruppo Ecosistem supported its hazardous waste growth in the six months to June 2026. Operators with hazardous and industrial permits will find more open demand than municipal contractors.
Who are the notable companies in the Waste Recycling Services Market?
WM, Republic Services, Veolia, SUEZ, Paprec and Sims occupy the main commercial positions in waste recycling services. WM and Republic Services combine collection networks with recycling processing in North America. WM's recycling processing and sales revenue reached USD 441.0 million over the three months to 30 September 2026. Republic Services reported USD 122.0 million from recycling processing and commodity sales in the same quarter and sells its sorted olefins to the Blue Polymers venture.
Veolia and SUEZ run municipal and industrial contracts across Europe and are pushing into hazardous waste. Veolia reported first-half 2026 revenue of EUR 22.2 billion, and its Clean Earth purchase gives it more than 150 US locations. SUEZ reported double-digit growth in hazardous waste for the same half-year and is integrating Gruppo Ecosistem in Italy. Paprec is growing through acquisitions. Its 2025 revenue rose 17.0% to EUR 3.5 billion on 19 million tonnes treated.
Metal specialists operate at the other end of the chain. Sims sold 6.3 million tonnes of proprietary metal in its 2026 financial year and lifted underlying EBIT to AUD 468.0 million. Radius Recycling is now owned by Toyota Tsusho. It feeds its own electric arc furnace in Oregon from more than 100 collection and dismantling sites. Cleanaway in Australia and Daiseki in Japan serve domestic customers from national site networks.
Key Developments in the Waste Recycling Services Market
- In June 2026, Veolia Environnement S.A. completed the acquisition of Clean Earth, Inc. from Enviri Corporation for USD 3.04 billion. The transaction doubled Veolia’s U.S. hazardous waste footprint and raised total U.S. revenue to approximately USD 6.3 billion on a pro forma basis [n].
- In January 2026, SUEZ S.A. and Banque des Territoires were jointly awarded a 12-year public service delegation contract worth nearly €420 million by Sydetom66 for waste treatment and energy recovery in Calce, near Perpignan. The contract covers the operation of the existing energy-from-waste plant at 240,000 tonnes per year, along with construction and operation of a new 40,000-tonne selective collection sorting centre [n+1].
Key Players in the Waste Recycling Services Market
- WM (Waste Management, Inc.)
- Republic Services, Inc.
- Veolia Environnement S.A.
- SUEZ S.A.
- Paprec Group
- Sims Limited
- Radius Recycling, Inc. (Toyota Tsusho Corporation)
- Cleanaway Waste Management Limited
- REMONDIS SE & Co. KG
- Daiseki Co., Ltd.
Waste Recycling Services Market Report Scope
Table 6: Waste Recycling Services Market Report Scope
| Coverage field | Report scope |
|---|---|
| Market definition | Revenue earned by service providers from the collection, sorting, processing and sale of recyclable materials recovered from industrial, commercial and municipal waste. Landfill disposal fees and energy generation revenue are excluded. |
| Application | Metallurgical; Chemical; Agriculture and Forestry; Textile; Power and Energy; Construction Industry |
| Product Type | Iron and Steel; Automotive Recycling; Battery Recycling; Compost and Food Waste; Computer and Electronics; Glass and Fiberglass; Liquids, Oils and Chemicals; Multi-Material Collection; Wastepaper; Scrap Plastic; Tire and Rubber; Others |
| End Use | Municipal Authorities; Industrial Companies; Recycling Companies; Commercial Establishments |
| Deployment | Centralized Recycling Facilities; Decentralized Recycling Systems; Mobile Recycling Units |
| Regions covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Profiled markets | China, South Korea, United States, Germany, Australia, United Kingdom, Japan, France, New Zealand, Italy |
| Companies covered | WM (Waste Management, Inc.); Republic Services, Inc.; Veolia Environnement S.A.; SUEZ S.A.; Paprec Group; Sims Limited; Radius Recycling, Inc. (Toyota Tsusho Corporation); Cleanaway Waste Management Limited; REMONDIS SE & Co. KG; Daiseki Co., Ltd. |
| Quantitative Units | USD billion |
Source: Future Market Insights analysis of the waste recycling services market, 2026.
Waste Recycling Services Market Research Methodology
The waste recycling services assessment draws on official waste statistics and landfill tax schedules as well as steel industry data and company disclosures. FMI measures annual service revenue from the collection and processing of recyclable materials and from their sale. Segment values are classified by application and product type as well as by end use and deployment. Country forecasts reflect local disposal pricing and producer responsibility rules together with steel scrap demand and operator investment over the same 2026 to 2036 period. Tonnes generated, tonnes recycled and commodity prices are reviewed as separate measures.
Waste Recycling Services Market by Segments
Waste Recycling Services Market segmented by Application:
- Metallurgical
- Chemical
- Agriculture and Forestry
- Textile
- Power and Energy
- Construction Industry
Waste Recycling Services Market segmented by Product Type:
- Iron and Steel
- Automotive Recycling
- Battery Recycling
- Compost and Food Waste
- Computer and Electronics
- Glass and Fiberglass
- Liquids, Oils and Chemicals
- Multi-Material Collection
- Wastepaper
- Scrap Plastic
- Tire and Rubber
- Others
Waste Recycling Services Market segmented by End Use:
- Municipal Authorities
- Industrial Companies
- Recycling Companies
- Commercial Establishments
Waste Recycling Services Market segmented by Deployment:
- Centralized Recycling Facilities
- Decentralized Recycling Systems
- Mobile Recycling Units
Waste Recycling Services Market by Region
- North America
- United States
- Canada
- Mexico
- Latin America
- Brazil
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East and Africa
Research Sources and Bibliography
- [1] Eurostat. (2026, October). Waste statistics. Statistics Explained.
- [2] National Development and Reform Commission, Department of Resource Conservation and Environmental Protection. (2026, April 28). (Renewable resource recovery reached 417 million tonnes last year). https://www.ndrc.gov.cn/fggz/hjyzy/zyzhlyhxhjj/202604/t20260428_1404935.html
- [3] The State Council of the People's Republic of China. (2026, January 14). China to ramp up solid waste management in green transition push. https://english.www.gov.cn/news/202601/14/content_WS6966e262c6d00ca5f9a088c8.html
- [4] Council of the European Union. (2025, December 12). Circular economy: Council and Parliament strike deal on rules for vehicle circularity and management of end-of-life vehicles.
- [5] U.S. Environmental Protection Agency. (2025, December 19, last updated). National Overview: Facts and Figures on Materials, Wastes and Recycling. https://www.epa.gov/facts-and-figures-about-materials-waste-and-recycling/national-overview-facts-and-figures-materials
- [6] WM. (2026, October 27). WM Announces Third Quarter 2026 Earnings. https://investors.wm.com/news-releases/news-release-details/wm-announces-third-quarter-2026-earnings
- [7] Republic Services, Inc. (2026, October 29). Republic Services, Inc. Reports Third Quarter 2026 Results. https://investor.republicservices.com/news-releases/news-release-details/republic-services-inc-reports-third-quarter-2026-results
- [8] Toyota Tsusho Corporation. (2025, July 11). Toyota Tsusho Completes Acquisition of All Shares of U.S.-Based Radius Recycling, Inc. https://www.toyota-tsusho.com/english/press/detail/250711_006639.html
- [9] Sims Limited. (2026, August 18). FY26 full year results announcement to the Australian Securities Exchange. https://announcements.asx.com.au/asxpdf/20260818/pdf/072vvg8t3f5p9w.pdf
- [10] Bureau of International Recycling. (2025, October 28). BIR Bangkok 2025: Ferrous Division statistics update of the 16th edition of World Steel Recycling in Figures. https://www.bir.org/news-press/press-releases/1000042491-bir-bangkok-2025-ferrous-division-statistics-update-of-the-16th-edition-of-world-steel-recycling-in-figures
- [11] World Steel Association. (2026). World Steel in Figures 2026. https://worldsteel.org/wp-content/uploads/World-Steel-in-Figures-2026.pdf
- [12] Eurostat. (2025, November). End-of-life vehicle statistics. Statistics Explained. https://ec.europa.eu/eurostat/statistics-explained/index.php?title=End-of-life_vehicle_statistics
- [13] Eurostat. (2026, January). Municipal waste statistics. Statistics Explained. https://ec.europa.eu/eurostat/statistics-explained/index.php?title=Municipal_waste_statistics
- [14] Department for Environment, Food and Rural Affairs. (2026, September 23). UK statistics on waste.
- [15] HM Revenue and Customs. (2026). Landfill Tax rates from 1 April 2013. https://www.gov.uk/government/publications/rates-and-allowances-landfill-tax/landfill-tax-rates-from-1-april-2013
- [16] Department for Environment, Food and Rural Affairs. (2025, October 3, last updated). Simpler Recycling: workplace recycling in England. https://www.gov.uk/guidance/simpler-recycling-workplace-recycling-in-england
- [17] Statistisches Bundesamt (Destatis). (2026, June 1). Erneuter Rückgang des Abfallaufkommens im Jahr 2024 (Pressemitteilung Nr. 185). https://www.destatis.de/DE/Presse/Pressemitteilungen/2026/06/PD26_185_321.html
- [18] Statistisches Bundesamt (Destatis). (2026, February 24). 1,5 % mehr recycelte Elektroaltgeräte im Jahr 2024 (Pressemitteilung Nr. 58). https://www.destatis.de/DE/Presse/Pressemitteilungen/2026/02/PD26_058_32.html
- [19] Ministry of the Environment, Japan. (2026, March 27). Municipal solid waste generation and disposal in FY2024. https://www.env.go.jp/en/press/press_01569.html
- [20] Ministry of the Environment, Japan. (2026, March 27). (Industrial waste generation and treatment, FY2023 results). https://www.env.go.jp/press/110498_00003.html
- [21] Daiseki Co., Ltd. (2026, April). Consolidated financial results for the fiscal year ended February 28, 2026. Japan Exchange Group. https://www2.jpx.co.jp/disc/97930/140120260406598778.pdf
- [22] Ministry of Climate, Energy and Environment, Republic of Korea. (2026, January 29). (Four bills including the Resources Recycling Act pass the National Assembly). KDI Economic Information and Education Center. https://eiec.kdi.re.kr/policy/materialView.do?num=276481
- [23] Ministry of Climate, Energy and Environment, Republic of Korea. (2025, December 16). (Introduction of extended producer responsibility for toys). Korea Policy Briefing. https://www.korea.kr/briefing/pressReleaseView.do?newsId=156735371
- [24] Ministry of Climate, Energy and Environment, Republic of Korea. (2026, March 31). (Exemption of import guarantees for circular resources). Korea Policy Briefing. https://www.korea.kr/briefing/pressReleaseView.do?newsId=156752082
- [25] Queensland Government. (2026, June 26, last updated). Waste disposal levy: levy rates. https://www.qld.gov.au/environment/waste-reduction-recycling/disposal-levy/about/levy-rates
- [26] Cleanaway Waste Management Limited. (2026, August 20). FY26 full year results announcement to the Australian Securities Exchange. https://announcements.asx.com.au/asxpdf/20260820/pdf/072yq2lqg3cv31.pdf
- [27] Ministry for the Environment, New Zealand. (2026). Waste disposal levy information and reporting requirements for site operators, accessed 3 November 2026. https://environment.govt.nz/what-government-is-doing/areas-of-work/waste/waste-disposal-levy/waste-disposal-levy-information-for-site-operators/
- [28] Ministry for the Environment, New Zealand. (2024). Waste disposal levy expansion, accessed 3 November 2026. https://environment.govt.nz/what-government-is-doing/areas-of-work/waste/waste-disposal-levy/expansion/
- [29] ISPRA. (2025, December). Rifiuti urbani: nel 2024 +2,3% di produzione rispetto al 2023. L'Italia differenzia di più, il sud accelera (comunicato stampa).
- [30] Service des données et études statistiques (SDES), Ministère de la Transition écologique. (2026, March 27). Gestion des déchets et économie circulaire en France: état des connaissances en 2025. https://www.statistiques.developpement-durable.gouv.fr/gestion-des-dechets-et-economie-circulaire-en-france-etat-des-connaissances-en-2025
- [31] Paprec. (2026, March 17). Paprec s'implante en Italie et vise un milliard d'euros à l'international (communiqué de presse). https://www.paprec.com/app/uploads/2026/03/17032026-paprec-resultats-et-arrivee-en-italie.pdf
- [32] Paprec. (2026, October 14). Paprec franchit le cap des 5 milliards d'euros de chiffre d'affaires (communiqué de presse). https://www.paprec.com/app/uploads/2026/10/paprec-franchit-le-cap-des-5-milliards-communique-14oct26.pdf
- [33] Paprec. (2026, February 19). Lély Environnement rejoint Paprec (communiqué de presse). https://www.paprec.com/app/uploads/2026/02/communique-lely-environnement-rejoint-paprec-19-02-2026.pdf
- [34] SUEZ. (2026, July 29). H1 2026 results (press release). https://www.suez.com/-/media/suez-global/files/publication-docs/pdf-english/finance/20260729---press-release---h1-results.pdf
- [35] Veolia. (2026, June 1). Veolia Completes Clean Earth Deal, Doubling Its U.S. Hazardous Waste Business and Expanding Its Growth Platform. https://www.veolia.com/en/our-media/press-releases/veolia-completes-clean-earth-deal-doubling-its-us-hazardous-waste-business
- [36] Veolia. (2026, July 30). Group Half-Year Financial Results 2026. https://www.veolia.com/en/our-media/press-releases/2026-first-half-results
- [37] TOMRA Systems ASA. (2026, October 23). 3rd quarter 2026 results announcement. https://media.tomra.com/download/3e5ac17acf6d11f18908cacb765c66ae
- [38] Republic Services, Inc. (2026). Form 10-Q for the quarter ended September 30, 2026. U.S. Securities and Exchange Commission. https://www.sec.gov/Archives/edgar/data/0001060391/000106039126000327/rsg-20260930.htm
- [39] REMONDIS SE & Co. KG. (2026). REMONDIS Library and company overview, accessed 3 November 2026. https://www.remondis.com/en/library/
- [40] U.S. Geological Survey. (2026, January). Iron and Steel Scrap. Mineral Commodity Summaries 2026. https://pubs.usgs.gov/periodicals/mcs2026/mcs2026-iron-steel-scrap.pdf
- [41] Enviri Corporation. (2026). Form 8-K — Completion of Clean Earth Sale. U.S. Securities and Exchange Commission. https://www.sec.gov/Archives/edgar/data/912603/000114036125025485/ef20051635_ex99-1.htm
- [42] SUEZ S.A. (2026). SUEZ confirms its position as a leading player in France in the operation of Energy-from-Waste Plants through a Major New Contract in Calce (66). https://www.suez.com/en/news/press-releases/suez-leading-france-waste-to-energy-calce
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Metallurgical
- Chemical
- Agriculture and Forestry
- Textile
- Power and Energy
- Construction Industry
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Iron and Steel
- Automotive Recycling
- Battery Recycling
- Compost and Food Waste
- Computer and Electronics
- Glass and Fiberglass
- Liquids, Oils and Chemicals
- Multi-Material Collection
- Wastepaper
- Scrap Plastic
- Tire and Rubber
- Others
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Municipal Authorities
- Industrial Companies
- Recycling Companies
- Commercial Establishments
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Deployment, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Deployment, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Deployment, 2026 to 2036
- Centralized Recycling Facilities
- Decentralized Recycling Systems
- Mobile Recycling Units
- Y-o-Y Growth Trend Analysis By Deployment, 2021 to 2025
- Absolute $ Opportunity Analysis By Deployment, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Application
- By Product Type
- By End Use
- By Deployment
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Product Type
- By End Use
- By Deployment
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Chile
- Rest of Latin America
- By Application
- By Product Type
- By End Use
- By Deployment
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Product Type
- By End Use
- By Deployment
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Application
- By Product Type
- By End Use
- By Deployment
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Product Type
- By End Use
- By Deployment
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan and Baltic
- Rest of Eastern Europe
- By Application
- By Product Type
- By End Use
- By Deployment
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Product Type
- By End Use
- By Deployment
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Application
- By Product Type
- By End Use
- By Deployment
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Product Type
- By End Use
- By Deployment
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- By Application
- By Product Type
- By End Use
- By Deployment
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Product Type
- By End Use
- By Deployment
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East and Africa
- By Application
- By Product Type
- By End Use
- By Deployment
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Product Type
- By End Use
- By Deployment
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Product Type
- By End Use
- By Deployment
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Application
- By Product Type
- By End Use
- By Deployment
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- WM (Waste Management, Inc.)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Republic Services, Inc.
- Veolia Environnement S.A.
- Paprec Group
- Sims Limited
- SUEZ S.A.
- Radius Recycling, Inc. (Toyota Tsusho Corporation)
- Cleanaway Waste Management Limited
- REMONDIS SE & Co. KG
- Daiseki Co., Ltd.
- WM (Waste Management, Inc.)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Application
- Figure 6: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Product Type
- Figure 9: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End Use
- Figure 12: Global Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Deployment
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Application
- Figure 29: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Product Type
- Figure 32: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by End Use
- Figure 35: North America Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Deployment
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Application
- Figure 42: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Product Type
- Figure 45: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by End Use
- Figure 48: Latin America Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Deployment
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Application
- Figure 55: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Product Type
- Figure 58: Western Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by End Use
- Figure 61: Western Europe Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Deployment
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Application
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by End Use
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Deployment
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Application
- Figure 81: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Product Type
- Figure 84: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by End Use
- Figure 87: East Asia Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Deployment
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by End Use
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by Deployment
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by End Use
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by Deployment
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the waste recycling services market in 2026?
FMI estimates the market at USD 72.1 billion in 2026, up from USD 67.8 billion in 2025. It is forecast to reach USD 134.2 billion by 2036 at a 6.4% CAGR.
Which application leads the waste recycling services market in 2026?
Metallurgical uses lead by application with 24.0% in 2026. The other applications together hold 76.0%.
Which product type and end use lead in 2026?
Iron and Steel holds 57.0% by product type. Industrial Companies hold 46.0% by end use in FMI's 2026 assessment.
Which country is forecast to grow fastest through 2036?
China has the highest forecast CAGR at 6.4% during 2026 to 2036, followed by South Korea at 5.8%. These are FMI forecasts and are not rates reported by the cited public bodies.
How much recycled plastic would new EU vehicles need to contain?
Under the provisional agreement reached on 12 December 2025, new vehicles would need 15.0% recycled plastic within six years and 25.0% within ten years of the rules taking effect [4]. The agreement still needs formal adoption by the Council and Parliament [4].
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
